
- Home
- »
- Plastics, Polymers & Resins
- »
-
Structural Adhesive Market Size And Share Report, 2033GVR Report cover

Structural Adhesive Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Urethane, Epoxy, Acrylic), By Technology (Water-based, Solvent-based), By Application (Transportation, Construction), By Region, And Segment Forecasts
Market Size, 2025
$23.7BMarket Estimate, 2026
$25.1BMarket Forecast, 2033
$38.7BCAGR, 2026–2033
6.4%Structural Adhesive Market Summary
The global structural adhesive market size was valued at USD 23.7 billion in 2025 and is projected to grow from USD 25.1 billion in 2026 to USD 38.7 billion by 2033, at a CAGR of 6.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 35.4% in 2025. The growth is attributable to the high demand for structural adhesives from the construction application, owing to the rising construction activities across the globe.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Epoxy segment dominated the product segment with a market share of 24.0% in 2025.
- By application: Construction segment held the largest share of 29.3% in 2025.
- By technology: Water-Based segment projected the largest share of 46.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (35.4% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 23.7 Billion
- Estimated market size in 2026: USD 25.1 Billion
- Projected market size by 2033: USD 38.7 Billion
- CAGR (2026-2033): 6.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Rapid industrialization and growth of construction and automotive industries in emerging economies such as India and China are anticipated to drive the demand for structural adhesives in the coming years. Increasing R&D initiatives and a growing preference for innovative products with high bond strength, lesser curing time, and lower toxic emissions are likely to contribute to the growth of water-based adhesives demand across the globe.Adhesive manufacturers offer more than 250,000 unique products for diverse applications. Increasing demand for low-carbon emitting and lightweight vehicles across the globe is likely to fuel the demand for adhesives in transportation applications. Additionally, increasing focus on energy efficiency, retention, and sustainable energy generation in building & construction due to the growing demand for eco-friendly materials is expected to fuel product demand in the coming years.
 To learn more about this report, Download Free Sample Report
Structural adhesives play an important role in determining the overall vehicular weight in automotive applications, leading to the reduction of carbon emissions by increasing fuel efficiency. Most mechanical fasteners and welds are increasingly being replaced by structural adhesives owing to their durability and ability to bond dissimilar substrates such as metal, wood, and plastics. Such adhesives are widely utilized in the automotive and aerospace industries, where cost and processing time are of crucial importance when selecting raw materials for production. In the automotive industry, most design decisions are driven by the total cost and durability of materials and processing operations. Increasing demand for lightweight composites and automotive components is expected to boost the growth of the market in the coming years.
The development of light commercial vehicles, innovative passenger cars, and new aircraft with high penetration of composite materials is anticipated to drive the structural adhesives industry. Automotive and aerospace are expected to remain the largest application markets for adhesives in composites over the forecast period. Other applications that require lightweight materials with high-performance benefits are also expected to drive the market. The demand for structural adhesives and composites is rising despite high competition from substitute materials, mainly in applications requiring fuel economy, high performance, weight savings, and other benefits.
The global structural adhesives industry was negatively impacted in the short term due to COVID-19, owing to its wide application in the automotive, industrial, and construction sectors. According to the National Centre of Information report published in April 2020, the automotive industry declined by almost 30% in March 2020, as compared to March 2019. The decline was witnessed due to the shutting down of automotive companies and factories.
Market Dynamics
The structural adhesive market is experiencing robust growth, driven by increasing demand for high-performance bonding solutions across the automotive, construction, aerospace, electronics, wind energy, and industrial manufacturing sectors. Structural adhesives provide superior bond strength, durability, corrosion resistance, and weight reduction compared to traditional mechanical fastening methods such as welding and riveting. Growing emphasis on lightweight materials, fuel efficiency, and sustainable manufacturing practices is further accelerating market adoption. Advancements in epoxy, polyurethane, acrylic, and methacrylate adhesive technologies are expanding their use in advanced engineering applications.
The growing adoption of lightweight materials in the automotive and aerospace sectors is a key driver of the structural adhesive market. Automakers are increasingly replacing mechanical fasteners with structural adhesives to bond aluminum, composites, and advanced plastics, reducing vehicle weight while improving structural integrity and fuel efficiency. Similarly, aircraft manufacturers use structural adhesives to assemble lightweight composite structures that enhance performance and reduce emissions. The global shift toward electric vehicles (EVs), where adhesives play a critical role in battery assembly and lightweight vehicle design, is further boosting market demand.Fluctuating prices of raw materials such as epoxy resins, acrylics, polyurethanes, and other petrochemical-based feedstock pose a significant challenge for structural adhesive manufacturers. Price volatility affects production costs and profit margins, particularly for small and medium-sized manufacturers. Structural adhesives often require thorough surface preparation, precise application, and controlled curing conditions to achieve optimal performance, increasing manufacturing complexity and operational costs. These factors may limit adoption in cost-sensitive industries.The rapid expansion of renewable energy infrastructure and advanced composite manufacturing presents significant growth opportunities for the structural adhesive market. Structural adhesives are increasingly used in wind turbine blade manufacturing, solar panel assembly, railway transportation, marine applications, and modular construction due to their excellent fatigue resistance and long-term durability. Growing investments in green infrastructure, electric mobility, and high-performance composite materials are creating new avenues for adhesive manufacturers. The development of bio-based, low-VOC, and fast-curing structural adhesives is expected to support sustainability goals and drive future market growth.
Analyst Perspective
The global structural adhesive market is positioned for steady growth, driven by increasing demand for lightweight, durable, and high-performance bonding solutions across the automotive, aerospace, construction, electronics, and industrial manufacturing sectors. Structural adhesives play a critical role in replacing traditional mechanical fastening methods by improving structural strength, reducing weight, and enhancing design flexibility. Epoxy-based structural adhesives remain the largest product segment due to their exceptional mechanical strength, chemical resistance, and widespread use in automotive assembly, aerospace components, wind energy, and infrastructure projects.
Product Insights
Epoxy segment dominated the product segment with a market share of 24.0% in 2025. Its high share is driven by the growing use of epoxy in end-use industries as a bonding agent. Epoxy structural adhesive provides strong bonding and is most versatile for many substrates. It ensures high strength toward permanent bonding applications. Epoxy is mostly used for aerospace, automotive, and industrial applications. They are vibration resistance bonds, which makes them the best glue for aluminum when utilized as an automotive structure and panel adhesive.
Urethane adhesives also present a decent growth promise owing to their application in the plastic & rubber industry. Urethanes are of two types, namely one-part and two-part urethane. Two-part urethane structural adhesives react when mixed and do not require moisture to cure. Two-part urethane adhesives offer vibration resistance and excellent impact in bonding when cured, as it is relatively flexible. Urethanes are used to bond wood, concrete, plastic, and rubber.
Cyanoacrylics are one-part products that cure very rapidly by reacting with moisture. This reaction is so quick that it requires very little clamping time. Cyanoacrylics are developed for high-strength requirements such as tight-fitting joints, small bond areas, and rapid curing applications.
Technology Insights
Water-Based segment projected the largest share of 46.8% in 2025. Its high share is driven by its growing application in providing high heat resistance. Water-based structural adhesives are in liquid form, but they become solid as the water evaporates. These adhesives are generally developed using a combination of additives, water, and polymers. Water-based adhesives offer high heat resistance. They are known for their compatibility with recyclable substrates. These adhesives have low volatile organic compound (VOC) content and are versatile and easy to clean with no odor. They can be applied on stainless steel rollers or nozzles.
Solvent-based structural adhesives are utilized in taping, medical, and packaging applications. They are the most commonly used adhesives owing to their high resistance to the impacts of the environment and their compatibility to be used with different types of substrates. Solvent-based adhesives are available in liquid form. These adhesives can be applied to both porous and non-porous surfaces, as they provide secure adhesion after the liquid evaporates while the bonding agent remains. As solvent-based adhesives are easier to apply than water-based adhesives, they are utilized in graphics and food packaging applications.
Application Insights
Construction segment held the largest share of 29.3% in 2025. Its high share is driven by the growing construction activities owing to the rapid increase in urbanization and industrial development globally. The construction industry widely utilizes structural adhesives for joining dissimilar materials such as metal, concrete, and timber. These adhesives are also used for bonding concrete to concrete, concrete to ceramic tiles, outside doors, construction panels, metal parts, and structural glass. The commonly used adhesives in the construction industry include acrylic adhesives, resin adhesives, anaerobic adhesives, and hot-melt adhesives.
Apart from construction, structural adhesives are also used in the transportation and vehicle sector as they help in making vehicles light in weight, increase durability, and make the vehicle production process faster. Commonly used adhesives for transportation vehicles include methyl methacrylate (MMA) and modified silane polymer (SMP). Structural adhesives can be utilized to assemble or seal the body of transport vehicles. In addition, they protect vehicles against water infiltration by bonding the roof of the vehicles.
 To learn more about this report, Download Free Sample Report
The furniture industry excessively utilizes structural adhesives for creating a bond between foams, plastics, metal, and fabrics. In soft furniture, adhesives keep the foam of the furniture in place. It is vital during application that the furniture glues stay on the surface, permitting strong bindings with other materials without changing the qualities of the substrates, rather than allowing them to permeate the pores of the substrate.
Structural adhesives are widely preferred in furniture applications owing to resistance to dimensional changes in wood, strong bonding capability, and moisture resistance. Widespread availability coupled with the aesthetic appeal of wood is expected to fuel furniture demand globally.
Regional Insights
Asia Pacific accounted for 35.4% of the structural adhesive market revenue in 2025, making it the largest regional market. The high demand in the Asia Pacific region is driven by the growing construction industry in countries like China, India, and Japan. According to the International Trade Administration, China has the highest urbanization rate in the world, and as the country develops as a greener economy, there will be increased opportunities for low-carbon construction such as green buildings. This is predicted to boost the growth of the construction sector in the country, thereby leading to the growth of the structural adhesives industry over the predicted years.
 To learn more about this report, Download Free Sample Report
China Structural Adhesive Market Trends
China held the highest market revenue share in Asia Pacific in 2025.
Europe is likely to offer lucrative growth opportunities for structural adhesives industry players on the account of escalating construction activities around the region, owing to the rapidly growing industrial sector coupled with a high urbanization rate. In addition, the growing transportation sector is also expected to augment the demand for structural adhesives in Europe. Factors such as congested roads and increasing volume of traffic are likely to boost the growth of the transportation industry in the region, thereby positively impacting the market in the near future.
Key Companies & Market Share Insights
The global structural adhesives industry is highly competitive on the account of the presence of multinationals like Henkel AG & Co. KGaA, 3M, HB Fuller Company, and others. These companies are heavily involved in carrying out rapid research & development activities for new product development. Growing demand for structural adhesives has also inspired new and emerging players to develop in the market. Some prominent players in the global structural adhesive market include:
-
Henkel AG & Co. KGaA
-
Dow
-
3M
-
HB Fuller Company
-
Franklin International, Inc.
-
Avery Dennison Corporation
-
Ashland Global Specialty Chemicals Inc.
-
Lord Corporation
-
Arkema S.A.
-
Scott Bader Co.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Henkel AG & Co. KGaA; Dow; 3M; H.B. Fuller Company; Avery Dennison Corporation; Arkema S.A.)
- Expand structural adhesive portfolios through continuous product innovation and sustainable formulations.
- Invest in R&D for lightweight materials, EV battery assembly, aerospace composites, and construction applications.
- Strengthening global manufacturing footprint through capacity expansions, acquisitions, and strategic partnerships.
- Develop low-VOC, fast-curing, and bio-based structural adhesives to meet evolving environmental regulations.
- Extensive global distribution networks and well-established customer relationships across multiple industries.
- Strong R&D capabilities with broad intellectual property portfolios and advanced adhesive technologies.
- Diverse product portfolios serve automotive, aerospace, electronics, construction, and industrial manufacturing.
- Strong financial resources support innovation, acquisitions, and global expansion.
- High exposure to fluctuations in petrochemical-based raw material prices.
- Significant compliance costs associated with environmental and chemical safety regulations.
- Capital-intensive manufacturing and continuous R&D investments increase operating expenses.
- Dependence on cyclical industries such as automotive, construction, and industrial manufacturing.
Emerging & Specialized Players (Franklin International, Inc.; Ashland Global Specialty Chemicals Inc.; Lord Corporation; Scott Bader Co.)
- Focus on high-performance and application-specific structural adhesive solutions for niche industrial markets.
- Strengthening customer collaboration through customized formulations and technical support.
- Expand regional manufacturing capabilities and distributor partnerships.
- Invest in specialty adhesives for composites, medical devices, renewable energy, and advanced manufacturing applications.
- High flexibility in developing customized adhesive solutions for specific customer requirements.
- Strong technical expertise and responsive customer service.
- Faster product development cycles and specialized application knowledge.
- Established presence in selected high-value industrial and specialty markets.
- Smaller global manufacturing footprint compared to multinational competitors.
- Limited financial capacity for large-scale acquisitions and capacity expansions.
- Lower global brand recognition in some regions.
- Greater dependence on regional demand and third-party distribution networks.
Structural Adhesive Market Report Scope
Report Attribute
Details
Market size in 2025
USD 23.7 Billion
Estimated market size in 2026
USD 25.1 Billion
Projected market size by 2033
USD 38.7 Billion
Growth rate
CAGR of 6.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Kilotons, Revenue in USD Billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technology, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; Italy; China; India; Japan; South Korea; Indonesia; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Henkel AG & Co. KGaA; Dow; 3M; HB Fuller Company; Franklin International, Inc.; Avery Dennison Corporation; Ashland Global Specialty Chemicals Inc.; Lord Corporation; Arkema S.A.; Scott Bader Co.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Structural Adhesive Market Report Segmentation
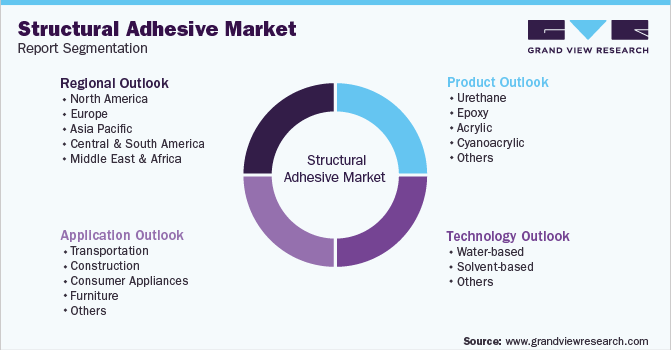
This report forecasts volume & revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global structural adhesive market report based on product, technology, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Urethane
-
Epoxy
-
Acrylic
-
Cyanoacrylic
-
Others
-
-
Technology Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Water-based
-
Solvent-based
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Transportation
-
Construction
-
Consumer Appliances
-
Furniture
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Indonesia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The Structural Adhesive Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Structural Adhesive segment quantified using the revenue-capture definitions in the table below.
Segment - Product
Revenue capture definition
Urethanes
Captures revenue generated from polyurethane-based structural adhesives used for high-strength bonding in automotive, construction, insulation panels, and industrial assembly applications.
Epoxy
Represents revenue from epoxy-based structural adhesives widely used for bonding metals, composites, and concrete in aerospace, automotive, electronics, and infrastructure applications.
Acrylic
Accounts for revenue generated from acrylic structural adhesives used for rapid bonding of metals, plastics, composites, and engineered materials across transportation, construction, and signage applications.
Cyanoacrylic
Captures revenue from cyanoacrylate structural adhesives used for instant bonding of plastics, rubber, metals, ceramics, and medical devices in industrial and consumer applications.
Others (Methacrylates, Silicone, Anaerobic)
Includes revenue generated from methacrylate, silicone, anaerobic, and other specialty structural adhesives used in demanding applications requiring high flexibility, chemical resistance, temperature stability, or thread-locking performance.
Segment - Technology
Revenue capture definition
Water-Based
Accounts for revenue generated from water-based structural adhesives formulated with low VOC content for environmentally friendly bonding applications in construction, furniture, and industrial manufacturing.
Solvent-Based
Reflects revenue from solvent-based structural adhesives that provide high bond strength, fast curing, and excellent adhesion for transportation, aerospace, construction, and heavy industrial applications.
Others
Measures revenue derived from hot-melt, reactive, UV-curable, and other advanced structural adhesive technologies designed for specialized manufacturing, electronics, medical, and high-performance industrial applications.
Segment - Application
Revenue capture definition
Transportation
Captures revenue generated from structural adhesives used in automotive, aerospace, rail, and marine applications for lightweight assembly, crash durability, vibration resistance, and composite bonding.
Construction
Represents revenue from structural adhesives utilized in commercial, residential, and infrastructure projects for bonding concrete, metals, glass, wood, composite panels, flooring, and façade systems.
Consumer Appliances
Accounts for revenue generated from structural adhesives used in the assembly of household appliances and consumer electronics, providing durable, lightweight, and vibration-resistant bonding solutions.
Furniture
Reflects revenue from structural adhesives used in the manufacturing of wood, metal, plastic, and composite furniture to improve joint strength, durability, and production efficiency.
Others (Industrial Machinery,
Medical Devices, Packaging)
Includes revenue generated from structural adhesives used in industrial equipment, medical device assembly, packaging, and other specialized applications requiring high mechanical strength, chemical resistance, and long-term reliability.
Estimation Model
Layer Name
Key Question
Description
Structural Adhesive Production Layer
What forms is the supply base?
Identify the global production capacity of structural adhesives by evaluating the manufacturing of epoxy, polyurethane, acrylic, cyanoacrylate, methacrylate, silicone, and other structural adhesive systems. The analysis includes raw material availability, resin production capacities, manufacturing technologies, formulation capabilities, and production facilities to establish the global supply base.
Application Adoption Layer
Where are structural adhesive utilized?
Estimate the distribution of structural adhesive consumption across key applications including transportation, construction, consumer appliances, furniture, industrial machinery, medical devices, packaging, and other industrial sectors by analyzing bonding requirements, manufacturing trends, and regional demand patterns.
Consumption Intensity Layer
How much structural adhesive is consumed?
Assess structural adhesive consumption across major end-use industries by evaluating production volumes of automobiles, aircraft, buildings, consumer appliances, industrial equipment, medical devices, and engineered products to estimate annual adhesive demand across key regional markets.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the sale of structural adhesives across various chemistries and technologies, including water-based, solvent-based, and other advanced formulations, supplied to OEMs, construction companies, industrial manufacturers, and component assemblers through direct sales, distributors, and integrated supply networks.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
Detailed cross-segmentation assessment evaluating the relationship between products (Urethanes, Epoxy, Acrylic, Cyanoacrylic, and Others) and application (Transportation, Construction, Consumer Appliances, Furniture, and Others). The analysis identifies product adoption trends, end-use demand patterns, technology preferences, and revenue contribution across each product–application combination.
Supports product portfolio optimization and market prioritization by identifying the most profitable product–application combinations, enabling better product development, sales strategies, and resource allocation.
Competitive Benchmarking
Comparative evaluation of leading structural adhesive manufacturers based on product portfolio, technology capabilities (Water-Based, Solvent-Based, and Others), manufacturing capacity, geographic presence, end-use industry focus, sustainability initiatives, innovation pipeline, and recent strategic developments across major regional markets.
Assists competitive intelligence and strategic decision-making by providing insights into market positioning, technological strengths, innovation capabilities, and competitive advantages.
Opportunity Assessment
Comprehensive assessment of emerging opportunities across high-growth products (Epoxy, Polyurethane, Acrylic, and specialty adhesives), advanced adhesive technologies, and expanding applications in electric vehicles, aerospace, renewable energy, construction, consumer appliances, and industrial manufacturing across key regional markets.
Helps identify high-growth product categories, technology trends, and application opportunities, supporting product innovation, capacity expansion, market entry strategies, and long-term revenue growth.
Frequently Asked Questions About This Report
Some key players operating in the structural adhesive market include The Dow Chemical Company, 3M Company, Sika AG, Henkel AG & Co., Lord Corporation, Ashland Inc., Scott Bade Company, and Ried BV.
Key factors that are driving the structural adhesive market growth include growing demand from end-use industries including construction, transportation, and furniture, and increasing composites utilization.
Asia Pacific dominated the structural adhesive market in 2025, accounting for 35.4% of the global market, driven by rapid industrialization, strong automotive manufacturing, and expanding construction activities.
The epoxy segment dominated the market in 2025 with a 24.0% revenue share, owing to its high bond strength, chemical resistance, and extensive use in automotive, aerospace, and construction applications.
The construction segment held the largest market share of 29.3% in 2025, supported by rising infrastructure development, commercial construction, and demand for durable bonding solutions.
Water based technology dominated the structural adhesive market with a share of 46.8% in 2025. This is attributable to environment-friendly and economically viable products that have wide bonding application in leather, wood, paper, and textiles.
The global structural adhesive market size was estimated at USD 23.7 billion in 2025 and is expected to reach USD 25.1 billion in 2026.
The global structural adhesive market is expected to grow at a compound annual growth rate of 6.4% from 2026 to 2033 to reach USD 38.7 billion by 2033.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


