
- Home
- »
- Plastics, Polymers & Resins
- »
-
Global Industrial Adhesives Market Size, Industry Report, 2019-2025GVR Report cover

Industrial Adhesives Market (2019 - 2025) Size, Share & Trend Analysis Report By Product (Acrylic, Polyvinyl Acetate), By Application (Automotive, Packaging), By Region, And Segment Forecasts
Industry Insights
The global industrial adhesives market size was valued at USD 47.60 billion in 2018 and is expected to grow at a CAGR of 5.9% from 2019 to 2025. The rising demand from the packaging industry and growing automobile sector especially in developing economies are expected to drive the market growth over the coming years.
Various properties of the product such as flexibility, solvent-free, lower costs, less vibration, high fatigue & thermal shock tolerance along with reduced waste and high productivity have increased its application in the automotive industry. The product is increasingly replacing conventional materials such as fasteners used indoors, hoods, deck lid flanges, roof panels, and dashboards along with other automobile components.
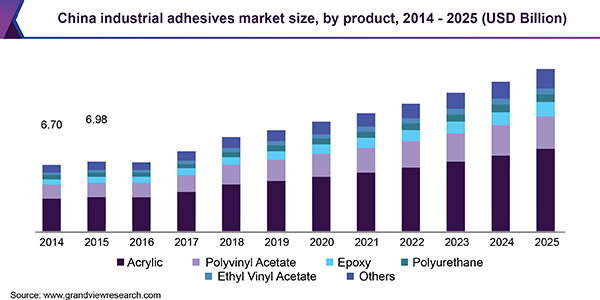 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Adhesive bonding technologies have reduced the time and costs required to bond automotive components, while ultimately reducing overall weight & fuel consumption and improving efficiency. Increasing federal & governmental regulations regarding carbon emissions are expected to further complement product applications in the automotive industry.
Increasing packaging demand from various end-use industries such as pharmaceuticals, food & beverages, and cosmetics is expected to drive market growth over the coming years. Growth of e-commerce commodities demand, in which packaging is a necessary factor, is anticipated to drive the product demand over the coming years.
The industrial adhesives market is likely to face a challenge due to volatile crude oil prices. Crude oil derivatives such as vinyl acetate monomer, polyols, toluene diisocyanate (TDI), and methylene diphenyl diisocyanate (MDI) are used in the manufacture of raw materials for industrial adhesives. The fluctuation in the price of crude oil negatively impacts the raw material costs, thus leading to the high pricing of the product. This is likely to hinder the market growth over the coming years.
Market Dynamics
The industrial adhesives market is being driven by the sustained expansion of manufacturing-intensive sectors such as packaging, automotive, electronics, construction, and woodworking. Industrial adhesives are increasingly replacing mechanical fasteners and welding processes due to their ability to improve design flexibility, reduce weight, and enhance production efficiency. Industry associations such as the World Packaging Organization (WPO) and automotive manufacturing bodies highlight the growing shift toward lightweight and high-performance bonding solutions, particularly in packaging formats and vehicle assembly lines where material efficiency and structural integrity are critical.
Industrial automation and high-speed production systems are accelerating adhesive consumption across assembly operations. Leading manufacturing companies are increasingly integrating advanced adhesive technologies such as hot-melt, epoxy, and polyurethane systems to improve cycle times and operational throughput. The rising demand for durable, lightweight, and cost-efficient bonding solutions across global supply chains continues to strengthen long-term consumption of industrial adhesives across both developed and emerging industrial economies.
A key restraint for the industrial adhesives market is the volatility in raw material costs, particularly for petrochemical-derived feedstocks such as resins, polymers, and solvents. Fluctuations in crude oil prices and supply chain disruptions directly impact adhesive formulation costs, creating pricing instability for manufacturers and end users. This cost unpredictability affects procurement planning and margin stability, especially for small and mid-sized adhesive producers operating in competitive markets.
Tightening environmental regulations governing volatile organic compound (VOC) emissions and chemical safety standards are increasing compliance burdens across the adhesives value chain. Regulatory frameworks in regions such as North America and Europe are pushing manufacturers to transition toward low-VOC, water-based, and bio-based adhesive systems, which often require higher R&D investment and reformulation costs. These compliance requirements, combined with slower adoption in cost-sensitive industries, are restraining the pace of transition in certain industrial segments.
Product Insights
Acrylics were the leading product segment accounted for a volume share of 43.5% in 2018. They are used to enhance the aesthetic appeal and improve the bonding strength of metals. Characteristics such as fast curing, acid & solvent resistant make them suitable in various end-use industries such as furniture, medical devices, and packaging.
Polyvinyl acetate is expected to register an average growth owing to its properties such as high boiling & temperature resistance. Its superior bond strength along with the improved creep resistance makes it suitable for use in the packaging industry and furniture manufacturing.
Epoxy adhesives are largely used in the automotive industry. Properties of epoxy adhesives such as durability, oil absorption capacity, good wash-out resistance, and high strength across a wide temperature range make them suitable for the automotive industry. They are majorly used in the car body owing to their high mechanical strength and adhesion to metals and heat & corrosion resistance. The aforementioned advantages of epoxy adhesives are likely to propel the product demand over the coming years.
Polyurethanes are projected to register a CAGR of 4.5%, in terms of revenue, from 2019 to 2025. They are used to bind different materials such as wood, rubber, cardboard, or glass. Increasing demand from the wood industry is anticipated to drive the market growth over the next seven years. Besides, rising construction activities globally is likely to increase its application in kitchen flooring, cupboards, and work surfaces owing to its high-fracture resistance.
Application Insights
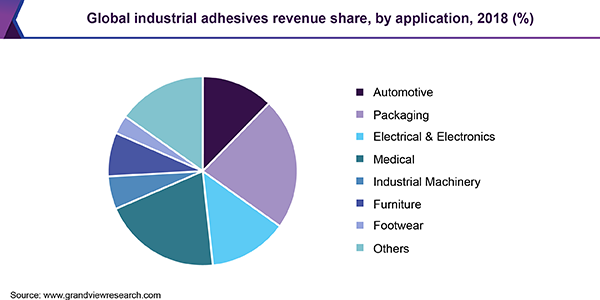
In the packaging segment, increasing the application of industrial adhesives for labeling, carton sealing, and corrugated box manufacturing has resulted in high market penetration. Moreover, rising demand for frozen goods, expanding the food & beverage industry, and flexible packaging applications are expected to provide growth opportunities. Properties such as high handling strength, superior performance under stressful conditions, and curing ability have made adhesives a popular replacement for mechanical fasteners in packaging applications.
The automotive segment is projected to grow at a CAGR of 4.7%, in terms of volume, over the forecast period. Shifting trend towards lightweight cars with streamlined modern designs to facilitate lesser wind resistance and enable high speeds is promoting adhesive applications in automobiles. Average car bodies have steel sheets with 0.6 to 0.8 mm thickness which require high strength bonding to promote maximum safety in case of accidents or mishaps. The growth is majorly driven by rising demand from the automotive industry to assemble various materials such as glass, rubber, and plastic.
 To learn more about this report, Download Free Sample Report
In the medical segment, rising prevalence of diseases and increasing geriatric population is expected to contribute to the market growth. Industrial adhesives are increasingly being used to manufacture, assemble, pack, and label medical devices and equipment. Disposable devices and reusable products such as surgical masks, gloves, catheters, syringes, and others are generally bonded using high grade, sterilized adhesives.
The footwear segment is projected to register a CAGR of 6.4%, in terms of revenue, over the forecast period. This growth is attributed to the increasing use of polyurethane adhesives owing to high adhesion and cohesion strength. Solvent-based polyurethanes along with various other adhesives such as PCP are used in the manufacture of footwear. Changing lifestyle along with rising health concerns is likely to propel the demand for designer and sports shoes, which in turn is anticipated to augment the market growth over the coming years.
Regional Insights
The Asia Pacific was the leading region and accounted for 44.9% of the overall volume in 2018. Major automotive companies have shifted their production facilities to countries such as China, India, Thailand, and Vietnam owing to cheap labor and favorable government regulations. Increasing per capita income among the middle class in countries such as China and India is anticipated to fuel automotive sales over the next seven years. These factors are expected to drive product consumption over the coming years.
The furniture market in the region is projected to grow at a rapid pace over the coming years due to rising real income of the consumer, population growth, and urbanization. The global organized furniture is anticipated to grow by 20% annually, as per the World Bank. The growth is attributed to the rapidly growing consumer markets of Asia Pacific especially in India. This is likely to propel the product demand over the coming years.
In North America, increasing demand from the packaging industry is expected to remain a key driving factor for market growth over the forecast period. Change in consumer preferences towards convenience, extended shelf life, quick-serve, and portability of products is attributable to the growth of the packaging sector, which consumes a large number of industrial adhesives. This is likely to propel the market growth over the coming years.
Europe is anticipated to register a CAGR of 4.7%, in terms of revenue, over the forecast period. The market is driven by the growing automotive industry. The automotive industry accounts for 4% of the region’s GDP. Production of motor vehicles in the region increased by 4.4% from 2014 to 2018. The rising automotive production in turn is anticipated to propel the utilization of industrial adhesives in the coming years.
Industrial Adhesives Market Share Insights
Global industrial adhesives market is widely spread with the presence of various international and local players including Henkel AG & Co., Cytec Industries Inc., Hitachi Chemical Company Ltd, Mitsubishi Chemicals Corporation, Dow Chemical Co, Bayer Product Science (Covestro), DuPont de Nemours, Inc., Adhesive Films Inc., Toyo Polymer Co. Ltd.
The market players are adopting strategies such as mergers & acquisitions, capacity expansion, and long term contracts with the end-users to increase the competitive rivalry. For instance, in January 2017, H.B. Fuller Company acquired the assets of H.E. Wisdom & Sons, Inc. and its affiliate Wisdom Adhesives Southeast, LLC, which strengthened the company’s presence in North America.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Players: Henkel AG & Co. KGaA; 3M; Sika AG; Dow Inc.; Arkema (Bostik division); Illinois Tool Works
- Focus on large-scale, diversified adhesive portfolios across automotive, construction, packaging, and electronics
- Heavy investment in R&D for high-performance, lightweight, and sustainable adhesive solutions
- Expansion through acquisitions and integration of specialty adhesive brands
- Strong global brand recognition and established customer relationships
- High R&D capabilities enabling continuous product innovation
- Diversified end-use industry exposure reducing market dependency risk
- High operational and R&D costs impacting margins
- Exposure to cyclical demand in automotive and construction sectors
- Slower agility due to large organizational structures
Emerging Players: H.B. Fuller; Avery Dennison; Ashland Global Holdings; Pidilite Industries
- Expansion into high-growth markets such as Asia-Pacific and Latin America
- Development of specialty adhesives for electronics, packaging, and flexible materials
- Focus on innovation-led growth through niche, high-margin product segments
- Higher operational flexibility compared to large, diversified conglomerates
- Strong presence in niche and fast-growing regional markets
- Faster product development cycles and customization capabilities
- Limited global manufacturing scale compared to mature leaders
- Higher dependency on regional demand fluctuations
- Lower bargaining power in raw material procurement
Report Scopes
Attribute
Details
The base year for estimation
2018
Actual estimates/Historical data
2014 - 2017
Forecast period
2019 - 2025
Market representation
Volume in Kilotons, Revenue in USD Million, and CAGR from 2019 to 2025
Regional scope
North America, Europe, Asia Pacific, Central & South America, Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, France, China, India, Japan, and Brazil
Report coverage
Revenue forecast, company share, competitive landscape, growth factors and trends
15% free customization scope (equivalent to 5 analyst working days)
If you need specific market information, which is not currently within the scope of the report, we will provide it to you as a part of customization
Segments Covered in the reportThis report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2014 to 2025. For this study, Grand View Research has segmented the global industrial adhesives market based on product, application, and region:
-
Product Outlook (Volume, Kilotons, Revenue, USD Million, 2014 - 2025)
-
Acrylic
-
Polyvinyl acetate
-
Epoxy
-
Polyurethane
-
Ethyl vinyl acetate
-
Others
-
-
Application Outlook (Volume, Kilotons, Revenue, USD Million, 2014 - 2025)
-
Automotive
-
Packaging
-
Electrical & electronics
-
Medical
-
Industrial machinery
-
Furniture
-
Footwear
-
Others
-
-
Regional Outlook (Volume, Kilotons, Revenue, USD Million, 2014 - 2025)
-
North America
-
The U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
South & Central America
-
Brazil
-
-
The Middle East and Africa
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
An integrated assessment was performed by combining product type and application demand, mapping adhesive chemistries such as epoxy in automotive and industrial machinery, EVA in packaging, and polyurethane in footwear and furniture applications. Substitution trends between performance-based and cost-driven adhesive systems were also examined.
Provided visibility into high-potential product-application intersections, enabling portfolio optimization, technology positioning, and targeted commercialization strategies across industrial end-use sectors.
Competitive Benchmarking
Key adhesive manufacturers were evaluated based on product portfolio strength across acrylic, epoxy, polyurethane, and EVA systems, R&D intensity, application specialization, sustainability initiatives, global distribution networks, and penetration across automotive, packaging, and electronics industries.
Supported identification of competitive positioning gaps, innovation leadership trends, and strategic collaboration opportunities, enabling stronger product differentiation and go-to-market planning.
Opportunity Assessment
Emerging growth avenues were evaluated across lightweight automotive bonding solutions, electronics miniaturization adhesives, sustainable water-based formulations, and high-performance structural adhesives for industrial machinery and packaging applications.
Supported identification of next-generation adhesive applications, enabling innovation roadmap development and long-term portfolio expansion across high-growth industrial sectors.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


