
- Home
- »
- Advanced Interior Materials
- »
-
Automotive Stainless Steel Tube Market Report, 2026-2033GVR Report cover

Automotive Stainless Steel Tube Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Welded Tube, Seamless Tube), By Application (Passenger Cars, Commercial Vehicles, Other Modes of Transportation), By Region, And Segment Forecasts
Market Size, 2025
$4.8BMarket Estimate, 2026
$5.0BMarket Forecast, 2033
$6.8BCAGR, 2026–2033
4.5%Automotive Stainless Steel Tube Market Summary
The global automotive stainless steel tube market size was valued at USD 4.8 billion in 2025 and is projected to grow from USD 5.0 billion in 2026 to USD 6.8 billion by 2033, at a CAGR of 4.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 53.0% in 2025. Stainless steel has become one of the primary materials in the automotive industry on account of its high strength-to-weight ratio, which helps reduce vehicle weight.
Key Market Trends & Insights
- By product: The welded tube segment accounted for approximately 92.5% of market revenue in 2025.
- By application: The commercial vehicles segment accounted for the largest revenue share of around 51.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (53.0% revenue share, 2025)
- Fastest-growing regional market: Europe (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 4.8 Billion
- Estimated market size in 2026: USD 5.0 Billion
- Projected market size by 2033: USD 6.8 Billion
- CAGR (2026-2033): 4.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Stainless steel tubes are used in diesel spark plugs, motor block reheating, diesel particulate filter systems, fuel lines, and exhaust gas recirculation systems. Good corrosion resistance & dent performance, coupled with high durability, are key factors driving its demand. Stainless steel comprises various alloying elements, such as chromium, nickel, titanium, molybdenum, and manganese, depending on the specific grade and composition. Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The presence of these elements results in higher strength and corrosion resistance in stainless steel compared to ordinary steel. Chromium, which accounts for 10% to 18% of all materials in stainless steel, increases oxidation resistance and thus corrosion resistance. Similarly, the addition of nickel, which makes up around 8% of stainless steel, helps in increasing its strength, which is important during collision and impact.
To be introduced to the market, vehicles have to undergo a variety of tests on safety, fuel efficiency, and emissions. Rigorous safety tests are conducted in which the strength of the frame of the vehicle is tested against severe impacts; failing which, the launch of the vehicle is suspended. Manufacturers are compelled to use high-strength materials, such as stainless steel tubes, which not only improve vehicle rigidity but also make them lighter, since stainless steel tubes are lighter than other materials. This, in turn, reduces vehicle curb weight, improving fuel efficiency.
Market Dynamics
The increasing implementation of stringent vehicle safety and fuel-efficiency regulations is a key market driver. The increased enforcement of stringent regulations by governments and regulatory bodies in leading automotive markets to enhance vehicle safety, emissions, and fuel efficiency is driving the adoption of high-strength, corrosion-resistant materials in the automotive sector.
The demand for stainless steel tubes is driven by their use in various vehicle parts, such as the exhaust system, fuel lines, structural components, and emission control systems, owing to their strength, heat resistance, and durability over the long term. The increasing importance of lightweight vehicle development, aimed at boosting fuel economy and complying with strict environmental regulations, will accelerate demand for innovative stainless steel tube solutions. Growth in global vehicle production and the rising need for durable auto components are expected to further drive this market.
The high cost of manufacturing automotive stainless steel tubes is a major factor restraining market growth. Manufacturing stainless steel involves high-cost raw materials such as chromium, nickel, and titanium, which significantly increase production costs compared to alternative materials like aluminum and regular steel. Changes in the price of raw materials also create cost uncertainties for manufacturers and end users.
The cost of producing stainless steel tubes is also high, as they require advanced manufacturing technologies and stringent quality control procedures. Automotive Manufacturers in cost-sensitive segments demand cheaper alternatives to remain cost-competitive. Stainless steel offers enhanced corrosion resistance and durability, but its higher initial cost might limit its use in certain segments despite its improved performance.
Increasing investments in research and development for advanced stainless steel grades present significant growth market opportunities. Manufacturers are committed to providing a second generation of stainless steel grades to help automotive manufacturers comply with changing regulations of fuel efficiency and emissions, vehicle safety, and the light-weighting trend of vehicle design.
The trend toward vehicle electrification is further favoring the market for advanced materials, which not only support harsh working environments but also enhance durability and vehicle lifespan. The demand for materials that enable innovation and sustainable practices while optimizing performance and cost-effectiveness is expected to present numerous market opportunities for the innovation of new stainless steel grades.
Analyst Perspective
The market is being shaped by the industry's focus on durability, safety, and compliance with stricter emissions and fuel-efficiency standards. Over the next decade, demand will increasingly be influenced by the changing mix of vehicle powertrains, with stainless steel tubes continuing to play a critical role in exhaust systems, fuel lines, and thermal management applications. Competitive advantage is likely to favor suppliers that can consistently meet automaker requirements for quality, precision, and long-term reliability while maintaining cost-efficient production. As vehicle manufacturers seek to simplify supply chains and reduce operational risk, procurement is expected to become more concentrated among trusted suppliers with strong engineering capabilities, established customer relationships, and the ability to support evolving vehicle platforms across global markets.
Product Insights
The welded tube segment dominated the market, accounting for approximately 92.5% of revenue in 2025. These are more readily available, resulting in a minimum waiting period and, consequently, making them cost-effective. Their wall thickness is more consistent than that of the seamless product. Besides, they can withstand extreme temperatures and pressures, making them ideal for critical automotive components such as exhaust systems. The segment is further supported by high-volume vehicle production, where manufacturers prioritize cost efficiency and reliable performance. The growing demand for durable exhaust and emission control systems is driving the adoption of welded stainless steel tubes across passenger and commercial vehicles.
The seamless tube segment is expected to grow at the fastest CAGR during the forecast period. Since there is no welding, their corrosion resistance is remarkably high. However, they are not as widely used as welded products due to their high cost. Demand for seamless tubes is expected to be driven by applications requiring superior strength, pressure resistance, and long service life under harsh operating conditions. Specialized automotive systems, where component reliability and performance are prioritized over cost, are also expected to continue to drive demand for this category of stainless steel tubes.
Application Insights
The commercial vehicles segment accounted for the largest revenue share of around 51.0% in 2025. The key factor driving the increase in demand for automotive stainless steel tubes in commercial vehicles is their widespread use. Stainless steel tubes reduce vehicle weight, optimize vehicle designs to promote safety, and increase fuel efficiency. Their benefits, such as high corrosion resistance, durability, and ability to withstand harsh operating environments, make them ideal for heavy-duty applications, including exhaust systems, fuel lines, and hydraulic systems. The segment growth is also supported by the need for lower maintenance requirements and extended vehicle service life, particularly in long-haul transportation and logistics operations.
The passenger cars segment of the stainless steel tube market is expected to grow at a significant pace over the forecast period. Stainless steel tubing possesses qualities that render it suitable for utilization in vehicle structural construction. The material is crashworthy, meaning it can protect occupants in the event of a collision. Furthermore, its lightweight construction can absorb impacts, thereby ensuring passenger safety. These characteristics are propelling its adoption in passenger vehicles.
Regional Insights
Asia Pacific automotive stainless steel tube market held the largest share of over 53.0% in 2025 and is expected to grow at the fastest CAGR during the forecast period. The region is likely to continue its dominance over the forecast period. Asia Pacific is considered one of the world's emerging regions. With fast-growing countries such as China and India, this region is expected to lead in sectors such as automotive, manufacturing, IT, telecom, and more. The automotive industry in this region is driven by rising demand for automobiles, government-backed schemes and foreign investments, innovative marketing strategies, and economic recovery.
 To learn more about this report, Download Free Sample Report
Europe Automotive Stainless Steel Tube Market Trends
The automotive stainless steel tube market in Europe is expected to grow at a notable CAGR over the forecast period. An established automotive manufacturing base, stringent governmental emission standards, and escalating demand for lightweight, fuel-efficient vehicles are key factors driving market expansion in this region. A sustained demand for automotive stainless steel tubes is evident in the region, with significant contributions from Germany, the UK, France, and Italy, driven by automotive manufacturers' enhanced investments in advanced manufacturing, the burgeoning electric mobility sector, and eco-friendly transit options.
Key Automotive Stainless Steel Tube Company Insights
Key players in the market adopt strategies such as mergers & acquisitions, expansions, new product development, agreements, collaborations & joint ventures to expand their product portfolios and geographical reach, and consequently increase their market share. The industry is highly consolidated, with both small- and large-scale manufacturers worldwide.
Key Automotive Stainless Steel Tube Companies
The following key companies have been profiled for this study on the automotive stainless steel tube market.
-
Sandvik AB
-
NIPPON STEEL CORPORATION
-
ArcelorMittal
-
thyssenKrupp AG
-
TUBACEX S.A.
-
Handytube Corporation
-
Plymouth Tube Company
-
Fischer Group of Companies
-
Maxim Tubes Company Pvt. Ltd.
-
JFE Steel Corporation
-
ChelPipe
-
Penn Stainless
-
Bri-Steel Manufacturing
-
Centravis
Recent Developments
-
In December 2025, thyssenkrupp AG Steel signed a long-term partnership agreement with TSR Group to supply TSR40 recycled steel feedstock to support its low-carbon bluemint steel production strategy.
-
In November 2025, Nippon Steel entered into a joint venture agreement with Nakayama Steel Works to form an electric arc furnace business alliance, supporting low-carbon steel production and advanced steel manufacturing capabilities.
Automotive Stainless Steel Tube Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.8 billion
Estimated market size in 2026
USD 5.0 billion
Projected market size by 2033
USD 6.8 billion
Growth rate
CAGR of 4.5% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Thailand; Indonesia; Malaysia; Australia; Brazil; Mexico
Key Companies Profiled
Sandvik AB; NIPPON STEEL CORPORATION; ArcelorMittal; thyssenKrupp AG; TUBACEX S.A.; Handytube Corporation; Plymouth Tube Company; Fscher Group of Companies; Maxim Tubes Company Pvt. Ltd.; JFE Steel Corporation; ChelPipe; Penn Stainless; Bri-Steel Manufacturing; Centravis
Customization scope
Free report customization (equivalent to up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
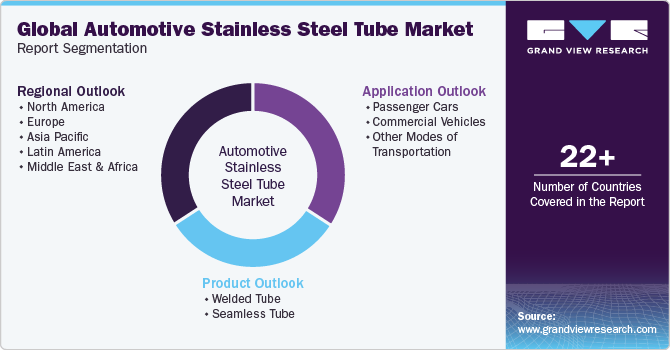
Global Automotive Stainless Steel Tube Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive stainless steel tube market based on product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilo Tons; Revenue, USD Million, 2021 - 2033)
-
Welded Tube
-
Seamless Tube
-
-
Application Outlook (Volume, Kilo Tons; Revenue, USD Million, 2021 - 2033)
-
Passenger Cars
-
Commercial Vehicles
-
Other Modes of Transportation
-
-
Regional Outlook (Volume, Kilo Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Thailand
-
Indonesia
-
Malaysia
-
Australia
-
Latin America
-
Brazil
-
Middle East & Africa
-
Frequently Asked Questions About This Report
Key players include Sandvik Group, Nippon Steel & Sumitomo Metal Corporation, ArcelorMittal, ThyssenKrupp, Tubacex, Handytube Corporation, Plymouth Tube Company, Fischer Group, Maxim Tubes Company Pvt. Ltd., JFE Steel Corporation, ChelPipe, Penn Stainless Products Inc., Bri-Steel Manufacturing, and Centravis.
Asia Pacific dominated with a 53.0% revenue share in 2025.
The global automotive stainless steel tube market size was valued at USD 4.8 billion in 2025 and is estimated at USD 5.0 billion for 2026
The global automotive stainless steel tube market is expected to grow at a CAGR of 4.5% from 2026 to 2033, reaching USD 6.8 billion
welded tube dominated the automotive stainless steel tube market with a share of 92.5% in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


