
- Home
- »
- Automotive & Transportation
- »
-
Commercial Vehicles Market Size, Share Report, 2026-2033GVR Report cover

Commercial Vehicles Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Light Commercial Vehicles (LCVs), Heavy Trucks, Buses & Coaches), By End Use (Industrial, Mining & Construction, Logistics, Passenger Transportation), By Region, And Segment Forecasts
Market Size, 2025
$1.6TMarket Estimate, 2026
$1.7TMarket Forecast, 2033
$2.2TCAGR, 2026–2033
3.5%Commercial Vehicles Market Summary
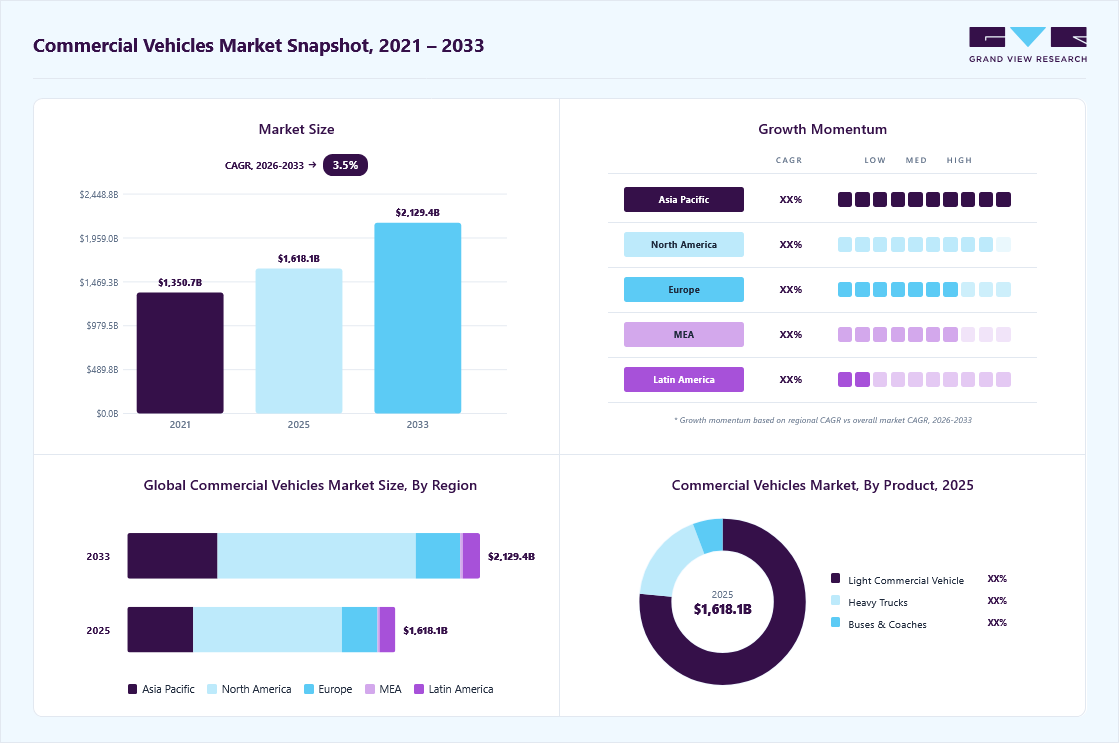
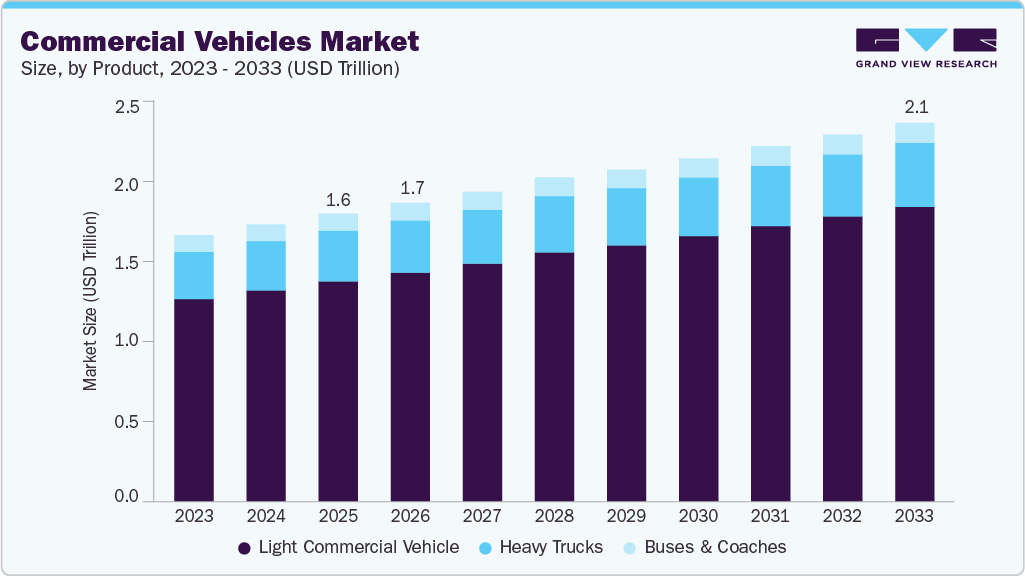
The global commercial vehicles market size was valued at USD 1.6 trillion in 2025 and is projected to grow from USD 1.7 trillion in 2026 to USD 2.2 trillion by 2033, at a CAGR of 3.5% from 2026 to 2033. The market in North America dominated with a revenue share of 55.5% in 2025. Expansion of logistics and freight transportation networks is driving the growth of the commercial vehicle market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- North America dominated the global commercial vehicles market with the largest revenue share of 55.5% in 2025.
- The commercial vehicles industry in the U.S. accounted for the largest market revenue share in North America in 2025.
- By product, the light commercial vehicles (LCVs) segment led the market with the largest revenue share of 76.4% in 2025.
- By end use, the logistics segment accounted for the largest market revenue share in 2025.
Key Market Trends & Insights
- By product: Light commercial vehicles (LCVs) segment held the largest market share of 76.4% in 2025.
- By end use: Logistics segment held the largest market share of 27.8% in 2025.
Regional Highlights
- Largest regional market: North America (55.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1.6 Trillion
- Estimated market size in 2026: USD 1.7 Trillion
- Projected market size by 2033: USD 2.2 Trillion
- CAGR (2026-2033): 3.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Rising domestic and cross-border trade, coupled with increasing movement of goods across roadways, continues to fuel demand for light, medium, and heavy commercial vehicles. The growth of organized logistics, third-party logistics providers, and cold-chain transportation has further increased fleet procurement across regions.
Rising replacement demand and ongoing fleet modernization are contributing to the growth of the commercial vehicles industry. Aging vehicle fleets are increasingly being phased out and replaced with newer models that offer improved fuel efficiency, enhanced safety systems, and compliance with evolving emission and regulatory standards. Fleet operators are prioritizing vehicles that deliver lower maintenance costs, higher reliability, and improved uptime, enabling better asset utilization and long-term profitability.
 To learn more about this report, Download Free Sample Report
The rapid growth of e-commerce and last-mile delivery services is accelerating demand for commercial vehicles, particularly light commercial vehicles. Increasing online shopping penetration, rising consumer expectations for faster and same-day deliveries, and the expansion of urban distribution networks are driving the need for efficient transportation solutions. As delivery operations become more time-sensitive and city-centric, fleet operators are investing in compact vans and pickup trucks that offer improved maneuverability, optimized payload capacity, and lower operating costs. This shift is further strengthening demand for technologically advanced, fuel-efficient, and electric-ready commercial vehicles designed specifically for last-mile logistics operations.
Rising investments in infrastructure development and construction projects are contributing to the growing demand for commercial vehicles. Governments and private sector organizations are investing heavily in highways, smart cities, industrial corridors, and urban development projects. These projects require large numbers of trucks, dump trucks, and other heavy commercial vehicles for transporting construction materials such as cement, steel, sand, and equipment. Increasing infrastructure spending across developing economies is therefore supporting the expansion of the commercial vehicles industry.
The regulatory landscape continues to exert a strong influence on market dynamics. Governments across major economies are implementing stringent emission norms, fuel-efficiency standards, and safety regulations, prompting fleet operators to upgrade existing vehicles. Policies promoting zero-emission transportation, including subsidies, tax incentives, and low-emission zones, are accelerating the adoption of electric and alternative-fuel commercial vehicles. At the same time, compliance with evolving safety standards is driving the integration of advanced braking systems, stability control, and driver monitoring technologies.
Despite growth prospects, the market faces several restraints. High upfront costs associated with electric vehicles, batteries, and advanced technologies remain a key challenge for small and mid-sized fleet operators. Volatility in raw material prices, supply-chain disruptions, and semiconductor shortages continue to impact production schedules and vehicle pricing. In addition, inadequate charging and refueling infrastructure in certain regions, along with economic uncertainty and fluctuating freight rates, may limit short-term market expansion.
Market Dynamics
Large-scale infrastructure development projects are contributing to the growth of the commercial vehicles market. Governments across both developed and developing economies are investing heavily in highways, rail corridors, airports, ports, smart cities, and industrial zones to strengthen transportation networks and economic connectivity. These projects require extensive movement of construction materials, heavy machinery, and workforce transportation, increasing the demand for heavy-duty trucks, tippers, dump trucks, and concrete mixers. Rising urban expansion and industrial construction activities are further encouraging contractors and logistics providers to expand their commercial vehicle fleets to support ongoing infrastructure operations efficiently.
Construction and mining industries are also generating strong demand for specialized commercial vehicles capable of operating in challenging environments. Rapid industrialization across Asia-Pacific, the Middle East, and Africa is accelerating investments in residential, commercial, and energy infrastructure, creating long-term opportunities for vehicle manufacturers and fleet operators. Modern commercial vehicles equipped with fuel-efficient engines, telematics systems, and higher load capacities are increasingly being preferred to improve operational productivity and reduce transportation costs. Continuous growth in public infrastructure spending and large-scale development initiatives is therefore expected to sustain strong global demand for commercial vehicles.
High initial purchase and maintenance costs are restraining the growth of the commercial vehicles market. Commercial vehicles such as heavy-duty trucks, buses, trailers, and specialized transport vehicles require significant upfront investment, making vehicle procurement challenging for small and medium-sized fleet operators. Modern commercial vehicles are increasingly equipped with advanced technologies, including telematics systems, advanced driver assistance systems (ADAS), fuel-efficient engines, emission-control technologies, and electric powertrains, which further increase vehicle prices. Financial pressure is increasingly significant in developing economies, where many transport businesses operate with limited budgets and lower profit margins, leading to delayed fleet expansion and replacement.
Operational and maintenance expenses also contribute substantially to the overall cost burden associated with commercial vehicles. Fleet owners are required to spend heavily on fuel, insurance, registration, routine servicing, tire replacement, spare parts, and repairs to ensure efficient vehicle performance and regulatory compliance. Rising labor costs and increasing complexity of technologically advanced vehicle components have further increased maintenance expenditures. Electric commercial vehicles also entail investments in charging infrastructure and battery replacement, which add to ownership costs. These high acquisition and operating expenses often discourage businesses from purchasing new commercial vehicles, thereby limiting market growth, particularly among small transportation companies and independent fleet operators.
The expansion of cold chain and refrigerated transportation is creating growth opportunities for the commercial vehicles market. Increasing demand for temperature-sensitive transportation across the food & beverage, pharmaceutical, and healthcare industries is driving the adoption of refrigerated trucks and vans. Food retailers, grocery delivery companies, and pharmaceutical distributors require reliable cold storage transportation systems to maintain product quality and comply with safety regulations during transit. Rising consumption of frozen foods, dairy products, fresh produce, and biologics is further increasing the need for advanced refrigerated commercial vehicles equipped with efficient cooling technologies and real-time temperature monitoring systems.
Growth in global pharmaceutical distribution and healthcare logistics is also strengthening demand for temperature-controlled commercial vehicles. Vaccine transportation, biopharmaceutical shipments, and medical supply distribution require strict temperature management throughout the supply chain, encouraging logistics providers to invest in specialized refrigerated fleets. Expansion of international food trade and organized retail networks in emerging economies is further supporting the development of cold chain logistics infrastructure. Commercial vehicle manufacturers are therefore focusing on developing energy-efficient refrigerated vehicles with improved insulation, telematics integration, and sustainable refrigeration systems to capitalize on the growing demand for cold chain transportation solutions.
Market Concentration & Characteristics
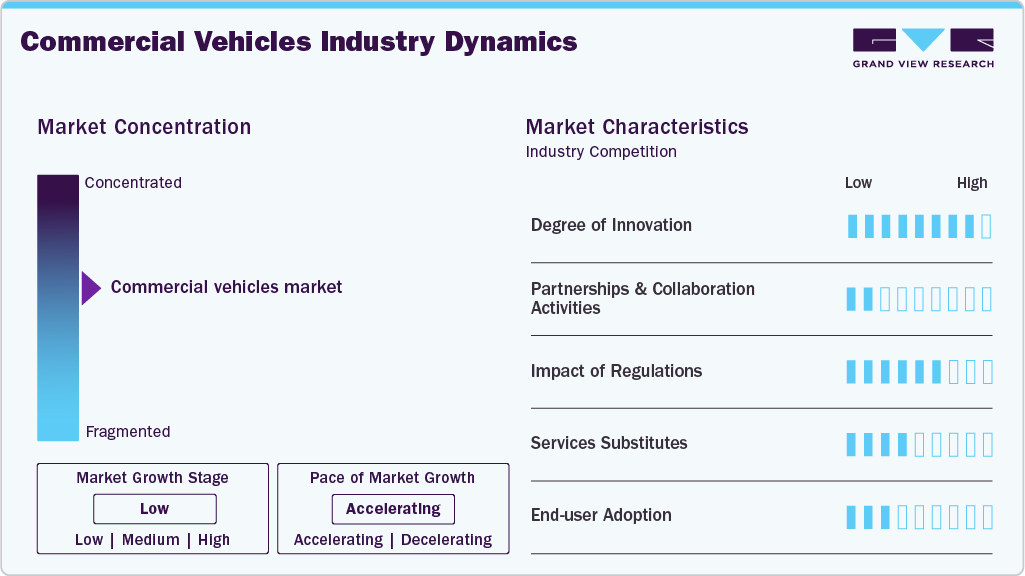
The commercial vehicles market is moderately fragmented. The market consists of several global and regional manufacturers competing across multiple vehicle segments, including heavy-duty trucks, light commercial vehicles (LCVs), buses, and electric commercial vehicles. Major multinational companies such as Daimler, Volvo, Toyota Motor Corporation, Volkswagen AG, and General Motors hold significant market shares due to their strong global presence, extensive distribution networks, advanced technologies, and diversified product portfolios. However, regional manufacturers such as Ashok Leyland, Tata Motors, Mahindra & Mahindra, Golden Dragon, and several Chinese OEMs maintain strong positions in domestic and emerging markets through competitive pricing and localized manufacturing strategies.
 To learn more about this report, Download Free Sample Report
Competition in the market remains high due to continuous technological advancements, expanding electrification initiatives, evolving emission regulations, and increasing demand from the logistics, construction, mining, and public transportation sectors. The presence of numerous domestic manufacturers, specialized vehicle producers, and new electric commercial vehicle startups further increases market fragmentation, particularly in Asia-Pacific and emerging economies. Strategic partnerships, acquisitions, product innovation, and expansion of electric and connected commercial vehicle portfolios are key competitive strategies adopted by market participants to strengthen their market positions.
Product Insights
The light commercial vehicles (LCVs) segment led the market with the largest revenue share of 76.4% in 2025 and is projected to grow at the fastest CAGR during the forecast period. The growth of light commercial vehicles is primarily driven by the rapid expansion of e-commerce, last-mile delivery services, and urban logistics networks. Increasing demand for faster deliveries, rising online retail penetration, and growth in organized retail are prompting fleet operators to deploy smaller, fuel-efficient vehicles suited to city operations. LCVs offer advantages such as lower acquisition costs, higher maneuverability, and better fuel economy, making them ideal for urban freight movement.
The heavy trucks segment is expected to grow at a significant CAGR during the forecast period. The growth of heavy trucks is driven by expanding freight transportation, infrastructure development, and industrial activity. Large-scale investments in highways, mining, ports, construction projects, and industrial corridors are increasing demand for long-haul and high-payload vehicles. Heavy trucks play a critical role in intercity and cross-border logistics, supporting manufacturing supply chains and bulk commodity movement.
End Use Insights
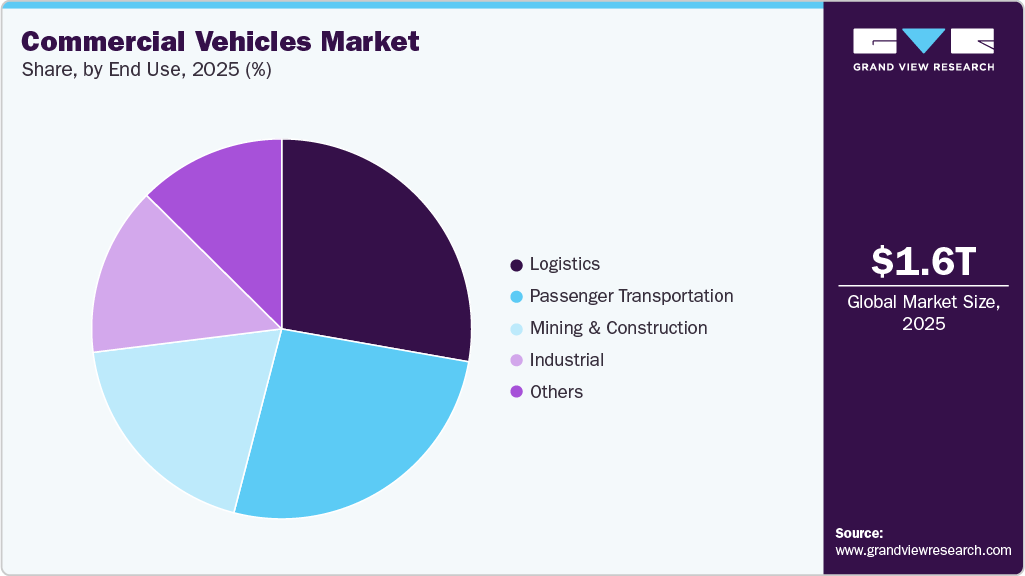
The logistics segment led the market with the largest revenue share of 27.8% in 2025 and is projected to grow at the fastest CAGR during the forecast period.The growth of commercial vehicles in logistics transportation is driven by the expansion of e-commerce, third-party logistics services, and organized supply chains. Increasing freight movement across domestic and cross-border trade routes has intensified the demand for efficient light, medium, and heavy commercial vehicles. Rising expectations for faster delivery timelines, growth in warehouse and distribution networks, and the need for cold-chain logistics are further accelerating fleet expansion.
 To learn more about this report, Download Free Sample Report
The passenger transportation segment is expected to grow at a significant CAGR during the forecast period. The passenger transportation segment is witnessing growth due to rising urbanization, population mobility, and increased demand for organized public and shared transport services. Expansion of intercity bus networks, staff transportation services, school mobility programs, and tourism-related travel is driving demand for buses and passenger carriers. Governments are increasingly investing in public transit modernization, including electric buses and low-emission fleets, to reduce congestion and environmental impact.
Regional Insights
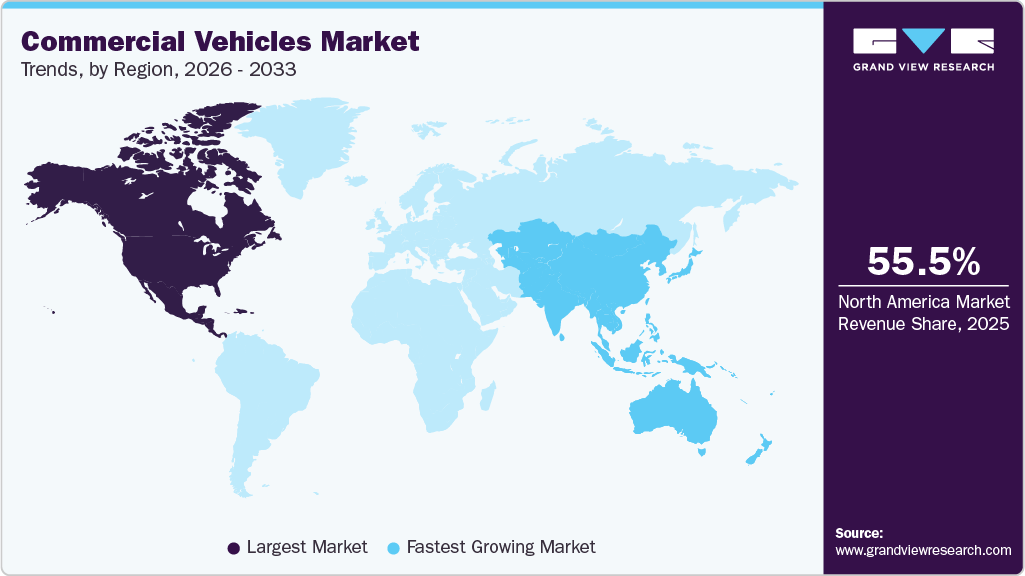
North America dominated the global commercial vehicles market with the largest revenue share of 55.5% in 2025. The North American commercial vehicles industry is characterized by strong demand from logistics, construction, and long-haul freight transportation sectors. The region benefits from a well-developed road infrastructure, high vehicle replacement rates, and steady growth in e-commerce and cross-border trade. Fleet operators are increasingly prioritizing fuel efficiency, telematics integration, and total cost of ownership optimization.
 To learn more about this report, Download Free Sample Report
U.S. Commercial Vehicles Market Trends
The commercial vehicles market in the U.S. accounted for the largest market revenue share in North America in 2025. The country represents the largest commercial vehicles industry in North America, driven by extensive freight movement, industrial activity, and last-mile delivery demand. Medium- and heavy-duty trucks dominate sales volumes, supported by strong investments in logistics fleets and infrastructure development.
Europe Commercial Vehicles Market Trends
The commercial vehicles market in Europe was identified as a lucrative region in 2025. Stringent emission regulations, strong sustainability mandates, and advanced manufacturing capabilities shape the European market. Demand is supported by intra-regional trade, modernization of transport fleets, and growing adoption of connected and automated vehicle technologies.
The UK commercial vehicles market is expected to grow rapidly in the coming years. Logistics expansion, infrastructure projects, and growing demand for urban delivery vehicles drive the market growth in the country. Light commercial vehicles account for a significant share of registrations, supported by e-commerce growth and last-mile distribution needs.
The commercial vehicles market in Germany held a substantial market share in Europe in 2025. The commercial vehicle market growth in the country is supported by its strong automotive manufacturing base and extensive freight transportation network. The country plays a central role in heavy-duty truck production and exports within the European region. Industrial output, cross-border logistics, and fleet modernization initiatives drive demand.
Asia Pacific Commercial Vehicles Market Trends
The commercial vehicles market in Asia Pacific is anticipated to grow at the fastest CAGR of 4.0% during the forecast period. The region is witnessing robust growth due to rapid urbanization, expanding industrial activity, and rising infrastructure investment. The region accounts for a significant share of global vehicle production and consumption, supported by large domestic markets and cost-competitive manufacturing.
The China commercial vehicles market held a substantial market share in the Asia Pacific in 2025. China represents the largest market in the Asia Pacific region, supported by massive logistics volumes, infrastructure development, and industrial expansion. The country dominates global production of light and heavy commercial vehicles, with strong domestic consumption.
Key Commercial Vehicles Company Insights
Some of the key companies in the commercial vehicles industry include Ashok Leyland, Daimler, Volkswagen AG, Toyota Motor Corporation, and others. Organizations are focusing on increasing customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions, and partnerships with other major companies.
-
Ashok Leyland is an automotive manufacturer headquartered in Chennai, India. The company produces a comprehensive portfolio of vehicles, including medium and heavy commercial vehicles (M&HCVs), light commercial vehicles (LCVs), buses, defence and logistics trucks, as well as industrial and marine engines and spare parts. Its products are marketed across more than 50 countries worldwide. Ashok Leyland serves a diverse customer base comprising government bodies, public transportation authorities, logistics operators, and defence organizations.
-
Daimler is a manufacturer of commercial vehicles, spanning trucks, buses, and vans across global markets. In the commercial‑vehicle market, the group’s portfolio includes strong brands such as Mercedes‑Benz Trucks, Freightliner, BharatBenz, Western Star, FUSO, Thomas Built Buses, and Setra, covering light, medium, and heavy‑duty trucks, city buses, coaches, and bus chassis. These vehicles serve long‑haul freight, construction, mining, urban logistics, and public‑transport applications, supported by tailored financial services and digital fleet solutions.
Key Commercial Vehicles Companies:
The following key companies have been profiled for this study on the commercial vehicles market.
- Ashok Leyland
- Bosch Rexroth AG
- Daimler
- Volkswagen AG
- Toyota Motor Corporation
- Mahindra and Mahindra
- TATA Motors
- AB Volvo
- Golden Dragon
- General Motors
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Daimler; Volkswagen AG; General Motors
- Mature commercial vehicle manufacturers focus on diversified product portfolios including heavy-duty trucks, light commercial vehicles (LCVs), buses, and electric commercial vehicles.
- Strong emphasis on global fleet partnerships, fuel-efficient technologies, connected vehicle solutions, and large-scale manufacturing capabilities.
- Strong global brand recognition and extensive dealership and aftersales service networks across multiple regions.
- High production capacities and established supply chain ecosystems support large-scale commercial vehicle deliveries.
- A high reliance on diesel-powered vehicle fleets creates challenges in transitioning to zero-emission mobility solutions.
- Compliance with evolving emission regulations and sustainability standards increases production and development costs.
Emerging Players: Golden Dragon; Bosch Rexroth AG
- Growing investments in electric buses, smart mobility technologies, and alternative fuel commercial vehicles to strengthen competitive positioning.
- Strong presence in fast-growing emerging economies with increasing demand for transportation and logistics infrastructure.
- Competitive pricing strategies and localized manufacturing provide advantages in price-sensitive markets.
- Limited global distribution and aftersales service networks compared to established multinational competitors.
- Dependence on regional economic conditions and infrastructure development projects may impact revenue stability.
Recent Developments
-
In March 2026, ByeTruck launched a nationwide direct-purchase platform that streamlines the sale of commercial vehicles such as semi-trucks, vans, box trucks, service utility vans, pickup trucks, buses, and entire fleets, including damaged, high-mileage, or title-impacted units, for owners and fleet managers across all 50 U.S. states. The service addresses traditional resale pain points such as lengthy listings, negotiations, inspections, and logistics by offering a simple four-step process: submit vehicle details for an instant quote, accept a competitive cash offer, handle paperwork seamlessly, and receive payment upon free nationwide pickup from hubs, job sites, or remote locations.
-
In January 2026, Tata Motors introduced a next-generation lineup of 17 commercial vehicles spanning the 7-55 tonne segment, marking one of the most extensive product launches in India’s commercial-vehicle industry. The new portfolio encompasses both diesel and electric platforms, including electric trucks marketed under the Tata Trucks.ev brand and developed on the advanced I-MOEV architecture. The rollout also features the Azura series targeting the intermediate and light commercial vehicle (ILMCV) category, along with upgraded Signa, Prima, and Ultra ranges. All models are engineered to comply with ECE R29 03 crash-safety standards while enhancing operational safety, payload capacity, fuel efficiency, and overall total cost of ownership for fleet operators.
-
In November 2025, Eicher Buses and Trucks, a business unit of VE Commercial Vehicles (VECV), launched the Eicher Pro X Diesel, a small commercial vehicle (SCV) in the 2-3.5 tonne segment that complements the previously introduced Pro X EV by offering a diesel‑powered option for customers and regions where diesel remains preferred. The Pro X Diesel is built around the new E449 diesel engine, tuned for fuel efficiency and strong performance across varied terrains, and is positioned as an “Expert” solution for fleet operators, small businesses, and first‑time buyers, with a focus on uptime, reliability, and total cost of ownership.
-
In November 2025, Volvo Trucks launched the all-new Volvo VNR in North America as its second model on a groundbreaking new platform, targeting regional and urban haul with a 90% redesign for superior versatility, safety, and efficiency. Key upgrades include enhanced aerodynamics, Eco-roll technology, and the standard next-generation D13 VGT engine, delivering up to 7.5% better fuel economy and CO2 reductions versus the prior model.
Commercial Vehicles Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.6 trillion
Estimated market size in 2026
USD 1.7 trillion
Projected market size by 2033
USD 2.2 trillion
Growth rate
CAGR of 3.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, Volume in Thousand Units and CAGR from 2026 to 2033
Report industry
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
Ashok Leyland; Bosch Rexroth AG; Daimler; Volkswagen AG; Toyota Motor Corporation; Mahindra and Mahindra; TATA Motors; AB Volvo; Golden Dragon; General Motors
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Commercial Vehicles Market Report Segmentation
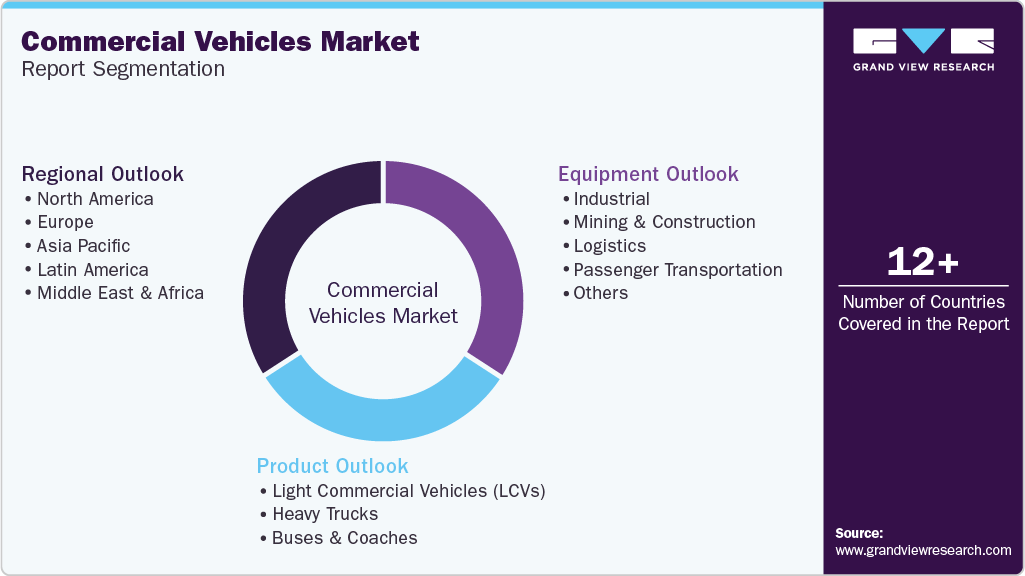
This report offers forecasts in terms of revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global commercial vehicles market report based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
Light Commercial Vehicles (LCVs)
-
Heavy Trucks
-
Buses & Coaches
-
-
End Use Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
Industrial
-
Mining & Construction
-
Logistics
-
Passenger Transportation
-
Others
-
-
Regional Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking and Market Share Analysis
- Benchmarking of key manufacturers based on product portfolio, regional presence, and strategic initiatives
- Analysis of partnerships, distribution networks, and manufacturing capabilities
- Market share assessment by vehicle type and geography
- Supported competitor tracking and strategic positioning activities
- Enabled identification of market gaps and expansion opportunities
- Assisted in evaluating competitive strengths across regional markets
Commercial Vehicle Electrification and Sustainability Assessment
- Analysis of electric commercial vehicle adoption trends and regulatory landscape
- Evaluation of charging infrastructure development and alternative fuel vehicle trends
- Identified electrification growth opportunities across commercial transport segments
- Supported strategic planning for sustainable fleet transition initiatives
Commercial Vehicle Sales Volume Assessment
- Regional and country-level sales volume analysis by vehicle category
- Segment-wise demand volume analysis across logistics, construction, mining, and public transport sectors
- Supported sales forecasting and market penetration strategies
- Enabled identification of high-demand vehicle segments
Frequently Asked Questions About This Report
The global commercial vehicles market size was estimated at USD 1.6 trillion in 2025 and is expected to reach USD 1.7 trillion in 2026.
The global commercial vehicles market is expected to grow at a compound annual growth rate of 3.5% from 2026 to 2033 to reach USD 2.2 trillion by 2033.
Some key players operating in the commercial vehicles market include Tata Motors, Volkswagen AG, Ashok Leyland, AB Volvo, and General Motors.
Key factors that are driving the commercial vehicles market growth include the rising integration of telematics services, demand for specific transport solutions by end-users, and the rising popularity of fleet sharing.
The Light Commercial Vehicles (LCVs) segment accounted for the largest revenue share of around 76% in 2025 in the commercial vehicles market.
North America dominated with a 55.5% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The logistics segment led with a 27.8% revenue share in 2025, while the passenger transportation segment is the fastest-growing.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


