
- Home
- »
- Advanced Interior Materials
- »
-
Mining Drills And Breakers Market Size Report, 2026-2033GVR Report cover

Mining Drills And Breakers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Rotary Drills, Crawler Drills, Rock Breaker, Hydraulic Breakers), By Application (Metal Mining, Mineral Mining, Coal Mining), By Region, And Segment Forecasts
Market Size, 2025
$18.4BMarket Estimate, 2026
$19.4BMarket Forecast, 2033
$30.7BCAGR, 2026–2033
6.8%Mining Drills And Breakers Market Summary
The global mining drills and breakers market size was valued at USD 18.4 billion in 2025 and is projected to grow from USD 19.4 billion in 2026 to USD 30.7 billion by 2033, growing at a CAGR of 6.8% from 2026 to 2033. Asia Pacific dominated the global market, accounting for the largest revenue share of 68.5% in 2025. The mining drills & breakers market growth is primarily driven by the increasing industrial automation and digitalization, rising demand for predictive maintenance enabled by IoT and AI, aging infrastructure requiring regular maintenance and modernization, and stricter environmental and workplace safety regulations.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Rock breaker segment accounted for the largest market share of 25.5% in 2025.
- By application: Metal mining segment led the market with a share of 40.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (68.5% revenue share in 2025)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 18.4 Billion
- Estimated market size in 2026: USD 19.4 Billion
- Projected market size by 2033: USD 30.7 Billion
- CAGR (2026-2033): 6.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growth of the mining drills and breakers market is primarily driven by the rising demand for minerals and metals across various sectors, including construction, automotive, and electronics. Rapid urbanization and industrialization worldwide have intensified the need for resources such as iron, copper, coal, and precious metals, spurring investments in mining activities.
In addition, as countries strive for resource independence, there is an increasing focus on domestic mineral production, which fuels demand for efficient and high-performing drilling and breaking equipment. Safety and productivity concerns are further encouraging mining companies to adopt advanced, automated drills and breakers that reduce manual labor and enhance operational efficiency, contributing significantly to mining drills and breakers industry growth.
 To learn more about this report, Download Free Sample Report
Governments across various regions are introducing supportive policies and incentives to boost the mining industry, which in turn positively impacts the sales of mining drills and breakers. These initiatives often include tax incentives, subsidies for local manufacturing of mining equipment, and relaxed regulations to encourage foreign investment in mining activities. For instance, governments in countries such as India, Australia, and Brazil are actively promoting mineral exploration to support economic growth, which increases the demand for advanced mining machinery. In addition, governmental emphasis on sustainable mining practices encourages the adoption of eco-friendly and energy-efficient drilling and breaking equipment, driving further the mining drills and breakers industry expansion.
The mining drills and breakers industry has significant growth opportunities, especially in emerging economies where large, untapped mineral reserves are now being explored. Countries in the Asia Pacific and Africa regions are experiencing a surge in mining activities to meet the global demand for minerals. Technological advancements, such as autonomous drilling systems and remotely operated breakers, present another growth opportunity by enabling mining companies to improve operational efficiency and safety. In addition, the push toward sustainable mining creates opportunities for eco-friendly equipment, as companies are encouraged to adopt solutions that reduce emissions and environmental impact.
Manufacturers in the mining drills and breakers market are increasingly focusing on growth strategies, such as expanding their product portfolio, investing in research and development, and forming strategic partnerships. To meet the evolving demands of the mining industry, companies are developing more efficient, durable, and technologically advanced equipment that can withstand harsh mining environments. Many manufacturers are also exploring partnerships with tech firms to incorporate AI, IoT, and automation into their machinery. In addition, some companies are expanding their reach in high-growth regions such as Asia Pacific and Latin America, where mining activities are increasing, to capture a larger market share.
Technological innovation is a key driver in the mining drills and breakers market, as advanced technologies improve equipment efficiency, safety, and environmental compliance. Innovations such as autonomous drills, GPS-guided drilling systems, and IoT-enabled equipment allow for real-time monitoring, precise operations, and predictive maintenance, reducing downtime and operational costs. The shift toward eco-friendly technology has also led to the development of electric-powered and hybrid equipment that lowers carbon emissions. These innovations are transforming traditional mining practices, helping companies meet stringent environmental standards and enhance productivity in complex mining operations, thus driving the mining drills and breakers industry.
Market Dynamics
The mining drills & breakers market is experiencing robust growth, driven by increased mineral exploration, rising demand for critical raw materials, and the modernization of mining operations worldwide. Expanding investments in surface and underground mining projects, coupled with the need for higher excavation efficiency and improved worker safety, are accelerating equipment adoption. Furthermore, advancements in automation, remote-controlled machinery, and energy-efficient drilling technologies are reshaping mining workflows, enabling operators to achieve greater productivity while optimizing operational costs.
The growing global demand for metals, minerals, and critical resources is a key driver of the mining drills and breakers market. Rising investments in infrastructure development, renewable energy projects, electric vehicles, and advanced manufacturing are increasing the need for commodities such as iron ore, copper, lithium, and other essential minerals. Mining operators are expanding exploration and extraction activities, creating sustained demand for efficient drilling and rock-breaking equipment.
Mining companies are also focusing on improving productivity and reducing operational downtime through the adoption of advanced equipment. Modern mining drills and breakers equipped with automation, remote monitoring, and improved hydraulic systems enable faster excavation, enhanced safety, and better resource utilization. These technological advancements are supporting increased equipment replacement and upgrades across mining operations.
High initial investment and operating costs associated with mining drills and breakers are a major restraint on market growth. Advanced drilling and breaking equipment requires significant capital expenditure for procurement, installation, maintenance, and training for a skilled workforce. Smaller mining operators and contractors may face challenges in adopting technologically advanced equipment due to budget limitations.
The cyclical nature of the mining industry further impacts equipment demand, as purchasing decisions are closely linked to commodity prices, mining investments, and project approvals. Periods of lower commodity demand or reduced mining activity can delay equipment upgrades and new purchases, affecting revenue growth for manufacturers and suppliers.
The increasing adoption of automation and digital technologies presents a significant opportunity for the mining drills and breakers market. Mining companies are integrating autonomous drilling systems, artificial intelligence, IoT-enabled monitoring, and data analytics to improve equipment performance, enhance worker safety, and optimize mining productivity. These technologies enable real-time equipment tracking, predictive maintenance, and improved operational decision-making.
The transition toward smart and sustainable mining is encouraging equipment manufacturers to develop electric-powered, energy-efficient, and digitally connected drilling and breaking solutions. Growing investments in mine modernization and autonomous operations are expected to create new revenue opportunities for companies offering advanced equipment, technology integration, and lifecycle support services.
Market Concentration & Characteristics
The mining drills and breakers market is moderately concentrated, comprising global mining equipment manufacturers, specialized drilling service providers, and regional equipment suppliers. The market is driven by advancements in automated drilling systems, electric and hybrid-powered equipment, hydraulic technologies, remote monitoring, telematics, and digital mine management solutions. Mergers and acquisitions remain moderate, with companies expanding capabilities through investments in automation providers, equipment technology firms, aftermarket service networks, and regional mining solution providers.
 To learn more about this report, Download Free Sample Report
Regulatory influence is moderate to high, shaped by mining safety standards, environmental regulations, emissions requirements, equipment certification standards, and operational guidelines for surface and underground mining activities. Product substitution is low, as drilling and breaking equipment are critical for mineral extraction, rock fragmentation, and mine development, with limited alternatives offering comparable performance and efficiency. Market demand is diversified across metal mining, mineral mining, and coal mining applications, supported by increasing demand for critical minerals, infrastructure development, mine modernization initiatives, and the adoption of advanced equipment technologies to improve operational efficiency and sustainability.
Analyst Perspective
The mining drills & breakers market is shifting toward automation, electrification, and digitally enabled equipment solutions as mining operators prioritize productivity, safety, and operational efficiency. Growing demand for critical minerals that support the energy transition is expected to further accelerate equipment adoption, creating favorable growth opportunities for manufacturers offering advanced drilling and breaking technologies.
Product Insights
Based on product, the rock breaker segment dominated the market with the largest revenue share of 25.5% in 2025, in the mining drills and breakers market, driven by its versatility and effectiveness in breaking large rocks into manageable sizes in mining operations. Rock breakers are essential in various mining applications, especially in secondary breaking processes, where they are used to reduce the size of oversized rocks. This segment's growth is fueled by rising mining activities globally, as companies seek to enhance productivity and minimize downtime. In addition, the adoption of automated and remotely operated rock breakers has expanded their utility, making them indispensable in harsh mining environments that prioritize safety and operational efficiency.
The hydraulic breakers segment has witnessed a CAGR of over 8% from 2025 to 2033 in the mining drills and breakers market due to the equipment's high-impact energy and efficiency in breaking hard materials. Hydraulic breakers are favored in the mining industry for their power, precision, and ability to perform in challenging conditions. They are increasingly used in both surface and underground mining, as they enhance operational productivity while reducing manual labor. The demand for environmentally friendly and energy-efficient mining equipment further drives this segment, as hydraulic breakers produce fewer emissions and operate with less noise compared to traditional explosives. In addition, advancements in hydraulic technologies have improved the durability and versatility of these breakers, contributing to their growing popularity.
Application Insights
Based on application, the metal mining segment led the market with the largest revenue share of 40.6% in 2025. The metal mining segment holds a high share in the mining drills and breakers market due to the rising demand for metals used in construction, manufacturing, and technology industries. With the global increase in urbanization and infrastructure development, the need for metals like iron, copper, and aluminum continues to rise, supporting significant investments in metal mining activities. Mining drills and breakers play a crucial role in metal extraction processes, aiding in both exploration and extraction stages. The adoption of advanced drilling and breaking technologies in metal mining further boosts this segment, as companies prioritize efficiency, safety, and cost-effectiveness in their operations.
 To learn more about this report, Download Free Sample Report
The coal mining segment is witnessing substantial growth within the mining drills and breakers market, driven by the sustained demand for coal as a primary energy source, particularly in developing economies. Despite the global shift towards renewable energy, coal remains a critical resource for electricity generation in many countries, especially in Asia Pacific. Mining drills and breakers are essential for efficient coal extraction, especially in deep and underground mining environments. Technological advancements, such as automated and remotely controlled drilling and breaking equipment, have also propelled this segment forward by improving safety and productivity in coal mining. In addition, the trend towards modernizing coal mining equipment for lower environmental impact has boosted the adoption of high-efficiency drills and breakers in this segment.
Regional Insights
The North American mining drills and breakers market will witness a CAGR of over 6% in 2025, due to the region's extensive mineral resource base, especially in the U.S. and Canada, where large mining operations require heavy-duty equipment. This region's market growth is significantly influenced by technological advancements in automation and precision in drilling and breaking equipment, improving efficiency and safety for operators. In addition, growing investments in mineral exploration and development, supported by favorable government policies, bolster the demand for advanced drills and breakers. Environmental regulations also push for efficient, less wasteful machinery, which helps drive demand for high-tech, durable, and eco-friendly equipment.
U.S. Mining Drills And Breakers Market Trends
In the United States, the mining drills and breakers market is largely driven by substantial investments in natural resource exploration and a rise in mining activities across states such as Nevada, Arizona, and Texas. The U.S. market benefits from a supportive regulatory environment and government incentives that encourage the expansion of mining operations, especially for essential minerals such as copper, lithium, and rare earth elements. Furthermore, the adoption of advanced drilling technologies, including wireless monitoring and autonomous control systems, contributes to the market's growth as companies prioritize productivity and safety.
Europe Mining Drills And Breakers Market Trends
The European mining drills and breakers market is experiencing notable growth due to an increased emphasis on sustainable mining practices. Strict environmental regulations in Europe push mining companies to adopt advanced equipment that reduces emissions and minimizes environmental impact. Countries such as Germany, Russia, and Poland are prominent contributors to this market growth, with a rising demand for minerals that support renewable energy technologies and electric vehicles. The European Union’s push for resource independence and increased domestic production of essential minerals also supports the growth mining drills and breakers industry.
The Germany mining drills and breakers market held a substantial market share in 2025 due to the country's strong mining industry, supported by technological advancements and a focus on automation to improve efficiency and safety. Rising investments in mineral exploration and infrastructure development, coupled with strict regulations promoting sustainable mining practices, drove the adoption of advanced drilling and breaking equipment. In addition, Germany's position as a manufacturing hub for high-quality machinery contributed to the mining drills and breakers industry growth.
The UK mining drills and breakers market held a substantial market share in 2025 due to increased investments in infrastructure and construction projects, driving demand for advanced mining equipment. The country's focus on sustainable mining practices and adoption of modern, energy-efficient technologies further boosted market growth. In addition, advancements in automation and the presence of established manufacturers offering innovative solutions supported the mining drills and breakers industry expansion.
Asia Pacific Mining Drills And Breakers Market Trends
Asia Pacific dominated the mining drills & breakers market, accounting for the largest revenue share of 68.5% in 2025, for mining drills and breakers, driven by rapid industrialization and urbanization in countries such as China, India, and Australia. These nations are witnessing significant investments in mining activities to meet the high demand for metals and minerals for infrastructure and manufacturing. In addition, the growth of the construction sector in this region drives demand for minerals and metals, thereby boosting the need for efficient drilling and breaking equipment. Technological advancements and an increasing focus on energy-efficient machinery also play a role in propelling the market forward.
 To learn more about this report, Download Free Sample Report
The mining drills & breakers market in the China held the largest share in the Asia Pacific region in 2025. China holds a significant share of the mining drills and breakers market due to its massive demand for raw materials to support its rapidly growing construction and industrial sectors. China is the world’s largest producer of coal and also mines a substantial amount of other minerals such as iron ore, copper, and rare earth elements. The country’s focus on modernization and upgrading mining equipment for enhanced productivity is also contributing to its significant share in the market. In addition, government support for domestic mining equipment manufacturers and subsidies for innovation plays a crucial role in this market's expansion.
India’s mining drills and breakers market is seeing rapid growth driven by an increasing demand for minerals in construction, automotive, and electronics sectors. The Indian government’s initiatives, such as “Make in India” and reforms to encourage foreign investment in mining, have boosted exploration and mining activities, particularly for coal, iron ore, and bauxite. This growth is further supported by investments in infrastructure development, which raises the demand for essential raw materials. The adoption of new drilling technologies and mechanized solutions in mining is also growing as companies focus on improving efficiency, safety, and productivity in mining operations.
Key Mining Drills And Breakers Company Insights
The major players in the market are concentrating on business strategies such as mergers, partnerships, and acquisitions for their businesses along with developing innovative mining drills and breakers to attract a larger customer base and gain a competitive edge in the market.
-
Hitachi Construction Machinery Co., Ltd. is a leading global manufacturer and supplier of construction and mining equipment, including high-quality mining drills and breakers. The company is known for its advanced technology and commitment to innovation, providing efficient, durable, and environmentally friendly machinery tailored for mining applications.
-
Komatsu Ltd. is a prominent player in the global mining equipment market, offering a wide range of mining drills and breakers designed for efficiency and sustainability. Known for its expertise in manufacturing heavy-duty machinery, Komatsu provides high-performance mining drills and breakers that are optimized for challenging mining conditions.
Key Mining Drills And Breakers Companies
The following key companies have been profiled for this study on the mining drills and breakers market.
-
Atlas Copco AB
-
Boart Longyear Ltd.
-
Cabo Drilling Corp.
-
Caterpillar, Inc.
-
Energold Drilling Corp.
-
FLSmidth & Co. A/S
-
Geodrill Limited
-
Hitachi Construction Machinery Co. Ltd
-
Komatsu Ltd.
-
Metso Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Caterpillar, Inc., Komatsu Ltd., Hitachi Construction Machinery Co. Ltd., Atlas Copco AB, Metso Corporation, FLSmidth & Co. A/S)
These players focus on strengthening their global presence through advanced equipment development, automation, digitalization, and comprehensive aftermarket service networks.
They are investing in autonomous drilling systems, remote monitoring, electric and hybrid equipment, predictive maintenance solutions, and advanced hydraulic technologies to improve productivity and reduce operating costs for mining customers.
Established players benefit from strong brand recognition, extensive global distribution networks, large installed equipment bases, and significant investments in research and development.
Their ability to provide complete mining solutions, including equipment, technology integration, spare parts, and lifecycle support, enables them to maintain strong customer relationships and compete effectively in large-scale mining projects.
Mature players face challenges related to high manufacturing costs, complex organizational structures, and slower adaptation to rapidly changing mining technologies.
Large equipment portfolios and dependence on capital-intensive mining projects can increase exposure to market cycles, commodity price fluctuations, and delayed customer investments.
Emerging & Specialized Players (Boart Longyear Ltd., Cabo Drilling Corp., Energold Drilling Corp., Geodrill Limited)
These companies focus on specialized drilling services, exploration support, contract mining solutions, and customized equipment applications.
Their strategies emphasize operational flexibility, regional expertise, rapid deployment capabilities, and cost-efficient drilling solutions for mining exploration and production activities.
Specialized players gain competitive advantages through technical expertise, strong knowledge of local mining environments, flexible service models, and the ability to support exploration and resource development projects.
Their focused approach allows them to respond quickly to customer requirements and provide customized solutions compared with larger equipment manufacturers.
These companies often have limited financial resources, smaller operational footprints, and lower brand visibility compared with global mining equipment manufacturers.
Dependence on exploration activity, commodity market conditions, and mining project investments can create revenue volatility.
Recent Development
-
In October 2023, Sandvik Mining and Rock Solutions has introduced a performance upgrade package for its 2700 series underground drills, including a single-boom jumbo, rock bolter, and top hammer production drill. This series was developed with input from the company’s Finnish, French, and Chinese teams.
-
In July 2023, Caterpillar debuted its first semi-autonomous construction equipment, the Cat 299D3 Compact Track Loader (CTL), at the Cat Trial 12 demo in Arizona. This remote-operated and semi-autonomous CTL marks a new era for construction technology.
-
In May 2024, Komatsu Ltd launched the second generation of its Z2 line of small-class underground drill and bolting equipment, featuring battery-electric models, a pumpable resin system, and improved ergonomics, expanding its hard rock mining solutions.
Mining Drills And Breakers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 18.4 billion
Estimated Market Size in 2026
USD 19.4 billion
Projected Market Size by 2033
USD 30.7 billion
Growth rate
CAGR of 6.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America, Europe, Asia Pacific, Latin America, MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, China, Japan, India, South Korea, Australia, Brazil, South Africa, Saudi Arabia, UAE
Key companies profiled
Atlas Copco AB; Boart Longyear Ltd.; Cabo Drilling Corp.; Caterpillar, Inc.; Energold Drilling Corp., FLSmidth & Co. A/S; Geodrill Limited; Hitachi Construction Machinery Co. Ltd; Komatsu Ltd.; Metso Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Mining Drills & Breakers Market Report Segmentation
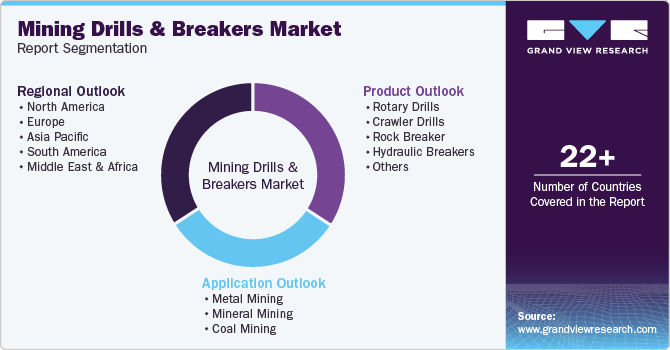
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global mining drills and breakers market report based on product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Rotary Drills
-
Crawler Drills
-
Rock Breaker
-
Hydraulic Breakers
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Metal Mining
-
Mineral Mining
-
Coal Mining
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
South America
-
Brazil
-
-
Middle East & Africa
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The mining drills and breakers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each mining drills and breakers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Rotary Drills
Revenue is generated through the sale, rental, installation, maintenance, and servicing of rotary drilling equipment used for large-scale mining operations, including blast hole drilling, exploration drilling, and rock excavation activities.
Crawler Drills
Revenue is generated through the sale, leasing, repair, maintenance, and operational support of crawler-mounted drilling machines used for surface mining, quarrying, and construction applications requiring mobility and drilling flexibility.
Rock Breaker
Revenue is generated through the supply, rental, maintenance, and replacement of rock-breaking equipment used for crushing, demolition, excavation, and breaking hard rock formations in mining and construction activities.
Hydraulic Breakers
Revenue is generated through the sale, installation, servicing, and aftermarket support of hydraulic breaker attachments used with excavators for rock fragmentation, mining excavation, quarrying, and material processing operations.
Others
Revenue is generated through the supply, maintenance, and servicing of other mining drilling and breaking equipment, including impact drills, drilling accessories, attachments, spare parts, and specialized excavation tools.
Segment - Application
Revenue capture definition
Metal Mining
Revenue is generated through the deployment, rental, maintenance, and servicing of drilling and breaking equipment used for extracting metallic ores such as iron ore, copper, gold, nickel, and other mineral resources.
Mineral Mining
Revenue is generated through the supply, operation, and maintenance of mining drills and breakers used for the extraction of non-metallic minerals such as limestone, gypsum, potash, phosphate, and industrial minerals.
Coal Mining
Revenue is generated through the sale, leasing, maintenance, and support services for drilling and breaking equipment used in coal extraction, mine development, excavation, and rock removal operations.
Estimation Model
Layer Name
Key Question
Description
Mining Equipment Technology & Manufacturing Enablement Layer
How are mining drills and breakers designed, manufactured, and optimized?
Represents the technologies, engineering capabilities, and manufacturing infrastructure that enable the development of mining, drilling, and breaking equipment. Includes equipment design engineering, hydraulic systems, drilling mechanisms, wear-resistant materials, automation technologies, electric and hybrid power systems, remote-operation capabilities, digital monitoring solutions, component manufacturing, testing facilities, and quality-assurance processes that support durable and efficient mining equipment production.
Mining Application & End-User Layer
Where are mining drills and breakers deployed and what purposes do they serve?
Represents the mining industries and operational activities where drilling and breaking equipment generate value. Key applications include metal mining, mineral mining, coal mining, quarrying, and construction-related excavation activities. These equipment solutions support exploration, mine development, blasting operations, rock fragmentation, excavation, and material extraction in both surface and underground mining.
Equipment Type, Operation & Mining Configuration Layer
How are mining drill and breaker systems structured and deployed?
Covers equipment classifications based on technology type, operating method, and mining requirements. Includes rotary drills, crawler drills, rock breakers, hydraulic breakers, and other specialized drilling and breaking equipment. The layer also includes surface and underground mining configurations, equipment attachment systems, automation levels, capacity ranges, and application-specific designs developed to meet varying geological conditions and productivity requirements.
Revenue Generation & Market Monetization Layer
How is revenue generated in the mining drills and breakers market?
Revenue is generated through the sale, rental, leasing, maintenance, repair, and aftermarket support of mining, drilling, and breaking equipment. Additional revenue streams include equipment customization, spare parts supply, component replacement, refurbishment services, technology upgrades, automation solutions, remote monitoring services, and long-term service agreements between mining equipment manufacturers, mining operators, contractors, and industrial service providers.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Sizing, Segmentation & Growth Opportunity Assessment
Assessed the global mining drills and breakers market size, historical performance, forecast growth trends, and detailed segmentation by product type (rotary drills, crawler drills, rock breakers, hydraulic breakers, and others) and application (metal mining, mineral mining, and coal mining). The analysis evaluated equipment demand drivers, adoption trends, replacement cycles, and growth opportunities across different mining operations.
Supports strategic market entry decisions, identifies high-growth equipment segments and mining applications, enables investment prioritization across drilling and breaking technologies, and assists stakeholders in developing targeted growth strategies aligned with mining industry expansion and modernization trends.
Competitive Landscape & Strategic Positioning Analysis
Benchmarked leading mining equipment manufacturers and service providers based on product portfolios, drilling and breaking technologies, equipment capabilities, automation integration, digital solutions, aftermarket services, geographic presence, partnerships, innovation initiatives, and investments in advanced technologies such as autonomous drilling, electric equipment, remote monitoring, and predictive maintenance.
Enables competitive differentiation, identifies technology and capability gaps, supports partnership and acquisition strategies, strengthens market positioning, and helps companies align product development strategies with evolving mining operator requirements for productivity, safety, and operational efficiency.
Regional Market Demand & Mining Industry Adoption Analysis
Analyzed regional market dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa by evaluating mining activity levels, mineral exploration investments, commodity demand, infrastructure development, equipment modernization initiatives, regulatory frameworks, and adoption of advanced mining technologies.
Supports geographic expansion planning, identifies high-potential mining regions, enables localization strategies, guides investments in manufacturing facilities and service networks, and improves long-term market penetration strategies across key mining markets.
Frequently Asked Questions About This Report
Some of the key players in the global mining drills & breakers market include Komatsu Ltd.; Caterpillar, Inc.; Sandvik AB; Atlas Copco AB; Doosan Corporation; Epiroc AB; and Boart Longyear Ltd.
Key factors that are driving the global mining drills & breakers market growth include technological innovations driving demand for heavy equipment and increasing mining activities across the globe
The metal mining segment led the market with a share of 40.6% in 2025.
Asia Pacific dominated the global market, accounting for the largest revenue share of 68.5% in 2025.
The U.S. held the largest market share in 2025.
Asia Pacific is expected to grow at the highest CAGR of 7.3% from 2026-2033.
The global mining drills and breakers market size was valued at USD 18,4 billion in 2025 and is estimated at USD 19.4 billion by 2026.
The rock breakers segment dominated the global mining drills & breakers market, accounting for 25.5% in 2025. This is attributable to the increasing demand for backhoe loaders and excavators, rising demand for underground mining equipment, and government initiatives supporting metal exploration in developing nations.
The global mining drills and breakers market is expected to grow at a CAGR of 6.8% from 2026 to 2033, reaching USD 30.7 billion by 2033
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


