
- Home
- »
- Advanced Interior Materials
- »
-
Rare Earth Elements Market Size Report, 2026-2033GVR Report cover

Rare Earth Elements Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Dysprosium, Neodymium), By Application (Magnets, Metallurgy), By Region (North America, Europe, APAC, Central & South America, MEA), And Segment Forecasts
Market Size, 2025
$4.2BMarket Estimate, 2026
$4.5BMarket Forecast, 2033
$8.5BCAGR, 2026–2033
9.5%Rare Earth Elements Market Summary
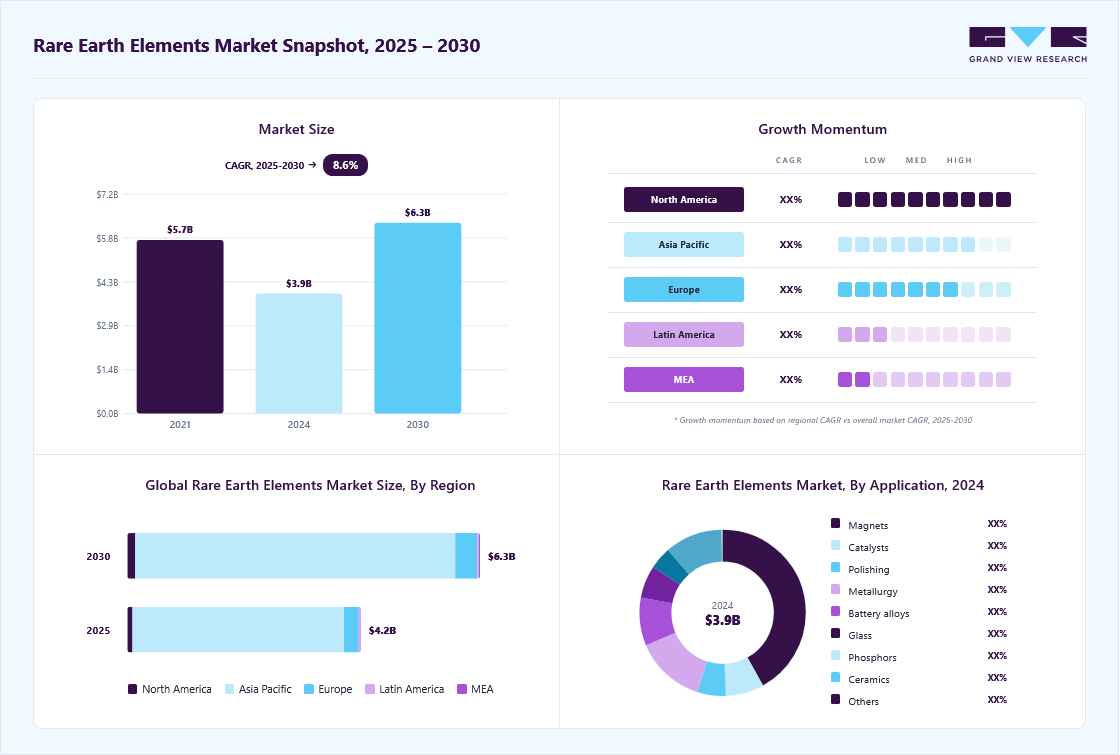
The global rare earth elements market size was valued at USD 4.2 billion in 2025 and is projected to grow from USD 4.5 billion in 2026 to USD 8.5 billion by 2033, at a CAGR of 9.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for 90.6% of revenue in 2025. The price spike in 2022, owing to the supply glut and geopolitical tensions between China and developed countries, followed by a gradual decline in prices, resulted in higher revenue gains for the market in 2022 and 2023.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Neodymium led the market with the largest revenue share of 40.8% in 2025.
- By application: Magnets segment led the market with the largest revenue share of 42.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (90.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.2 Billion
- Estimated market size in 2026: USD 4.5 Billion
- Projected market size by 2033: USD 8.5 Billion
- CAGR (2026-2033): 9.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growing demand for permanent magnets and catalysts in the automotive industry is anticipated to drive the market over the forecast period.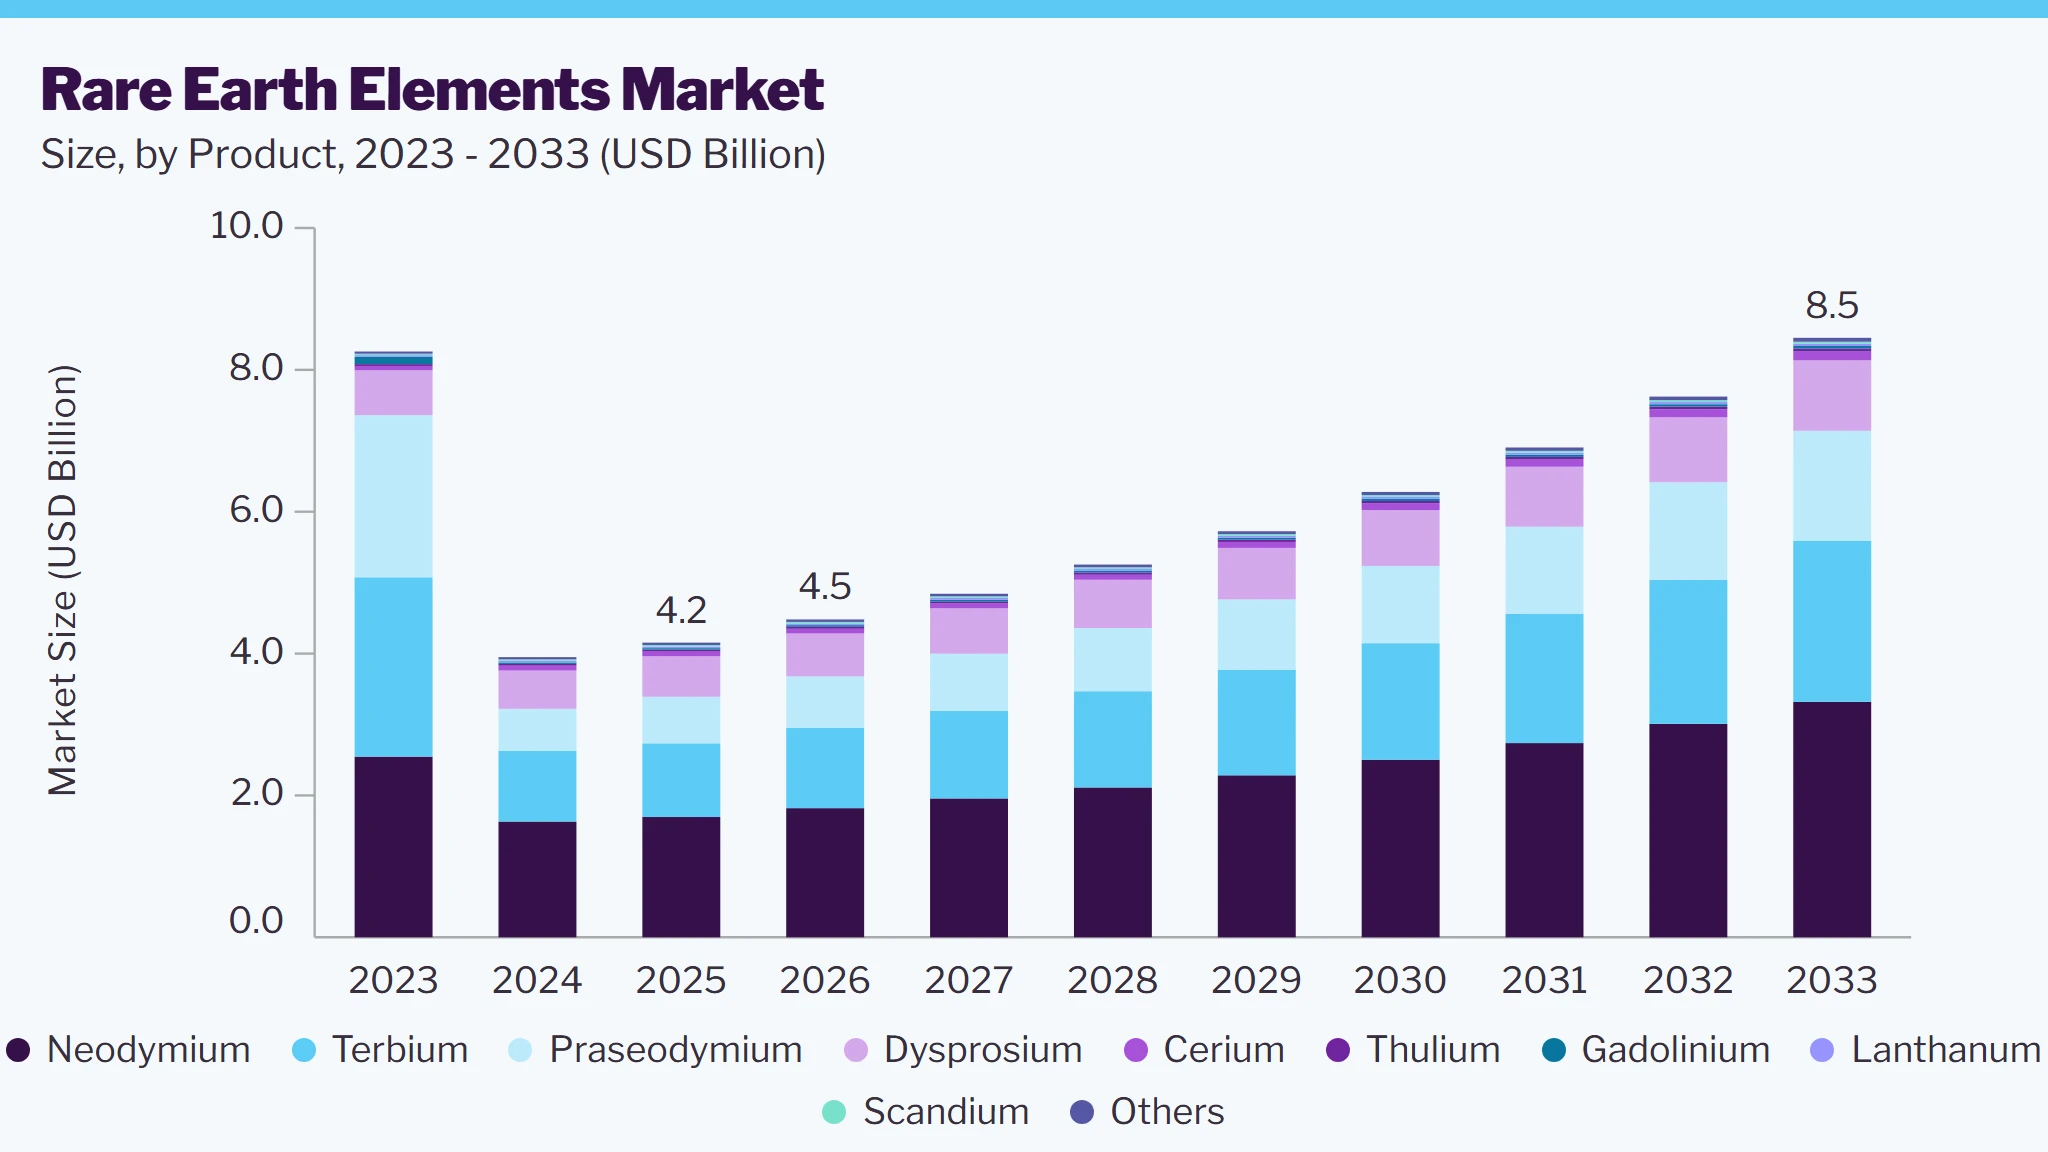 To learn more about this report, Download Free Sample Report
REEs are used to produce permanent magnets and battery alloys that are used in electric vehicle (EV) batteries, smartphones, defense technology, and other applications that require a very high strength-to-weight ratio and performance at high temperatures. For instance, neodymium- and praseodymium-based rare-earth permanent magnets are used in manufacturing EV batteries. As per the International Energy Agency (IEA), the global sales of electric vehicles (EV) were about 14.2 million in 2023, compared to 10.5 million in the previous year. Rising demand for electric vehicles to reduce CO2 emissions is expected to propel the use of permanent magnets in the production of batteries.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The rare earth elements market is experiencing steady growth due to increasing vehicle production, rising demand for lightweight automotive components, and the growing adoption of electric vehicles (EVs). Automakers are increasingly utilizing metal stamping processes to manufacture high-volume, precision-engineered components with improved strength, dimensional accuracy, and cost efficiency. Growing investments in automotive manufacturing facilities, advancements in stamping technologies, and stringent fuel-efficiency and emissions regulations are further supporting market expansion. Additionally, the increasing use of high-strength steel and aluminum in vehicle structures is driving demand for advanced metal stamping solutions across passenger and commercial vehicle segments.
The increasing focus on vehicle lightweighting is a major factor driving the rare earth elements market. Automakers are continuously seeking ways to reduce vehicle weight to improve fuel efficiency, extend EV driving range, and comply with stringent emission regulations. Metal stamping enables the mass production of lightweight, complex-shaped components using materials such as advanced high-strength steel (AHSS), aluminum, and other lightweight alloys. These stamped components are extensively used in body-in-white structures, chassis systems, doors, hoods, fenders, and structural reinforcements.
Furthermore, the growth of electric vehicle production is increasing the demand for precision-stamped battery enclosures, motor housings, structural supports, and lightweight body components. The ability of metal stamping processes to deliver high production volumes, consistent quality, and cost-effective manufacturing makes them essential to modern automotive production. As global vehicle production and electrification trends continue to expand, demand for rare earth elements is expected to remain strong throughout the forecast period.
Fluctuations in the prices of steel, aluminum, copper, and other automotive-grade metals present a significant challenge for market participants. Raw material costs account for a substantial portion of overall production expenses, and sudden price increases can adversely affect manufacturers' profitability and pricing strategies. Additionally, disruptions in global supply chains can further impact the availability and cost of metal inputs.
The rapid growth of the electric vehicle industry presents substantial opportunities for the rare earth elements market. EV manufacturers require lightweight and high-strength stamped components to improve battery efficiency, vehicle performance, and structural safety. This trend is accelerating the adoption of aluminum, advanced high-strength steel, and other lightweight materials in automotive manufacturing. In addition, advancements in hot stamping, servo stamping, and precision forming technologies are enabling manufacturers to produce increasingly complex and lightweight components with enhanced structural performance.
Analyst Perspective
The rare earth elements market is expected to witness sustained growth, driven by rising demand for permanent magnets in electric vehicles, wind turbines, and advanced electronics. Increasing investments in domestic mining, refining, recycling, and magnet manufacturing are strengthening global supply chains. At the same time, government initiatives focused on critical mineral security continue to support long-term market expansion despite challenges related to supply concentration, price volatility, and environmental regulations.
Product Insights
Based on product, Neodymium led the market with the largest revenue share of 40.8% in 2025. Neodymium was the leading segment and is anticipated to witness a CAGR of 8.1% over the forecast period. The growth in the automotive and energy industries is anticipated to drive demand. They are especially used in EVs and wind turbines, in motors and generators, and in consumer electronics. The growing demand for hybrid vehicles is expected to positively influence demand for rare earths over the forecast period.
Dysprosium is mainly used as an alloying agent in neodymium-iron-boron (Neo) permanent magnets. Neo magnets are widely used in various application industries, including transportation, power generation, aerospace & defense, medical, and industrial. Its increasing demand is expected to drive dysprosium demand over the forecast period.
Gadolinium demand is expected to be driven by the increasing demand for nuclear reactors. It is used as a neutron absorber in fresh fuel to control and regulate the reactivity of the nuclear reactor core. It is also used in alloys for producing electronic components, data storage disks, and magnets.
Praseodymium is anticipated to witness a revenue CAGR of 10.7% over the forecast period. It is used as an alloying agent with magnesium to produce high-strength metals for aircraft engines. The International Air Transport Association (IATA) announced that air traffic increased by 36.9% in 2023, as compared to 2022. Globally, traffic in 2023 was at 94.1% of pre-pandemic (2019) levels. Hence, the rebound in travel and tourism, and foreign worker participation in the global workforce, is expected to augment the demand for overseas travel and aircraft production, and positively influence praseodymium demand over the forecast period.
Application Insights
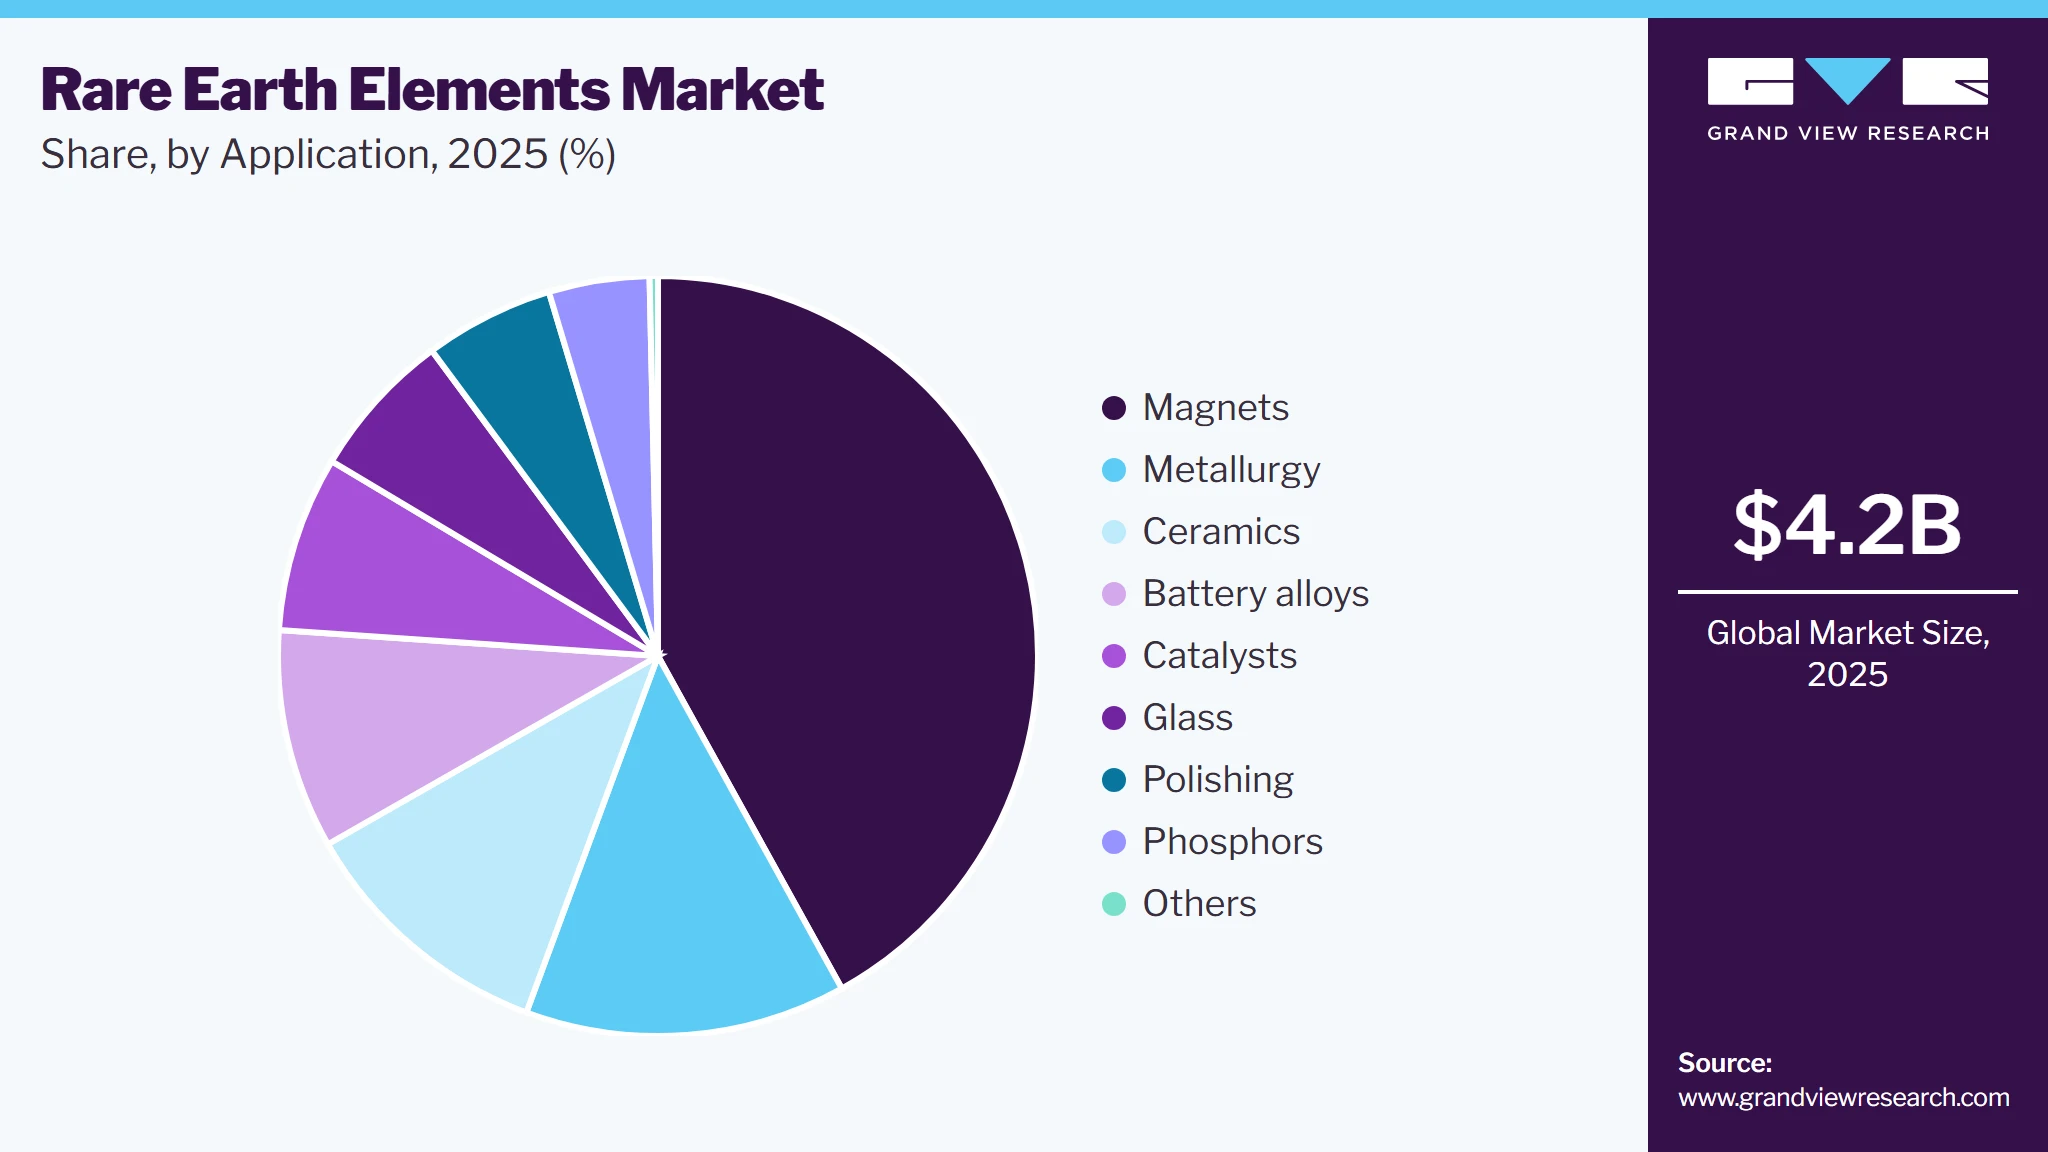
By application, the magnets segment led the market with the largest revenue share of 42.0% in 2025. Most REEs possess magnetic properties, which make them the strongest permanent magnets. Properties such as field strength, remanence, Curie temperature, energy product, and coercivity are used to compare permanent magnets.
 To learn more about this report, Download Free Sample Report
Rare earths such as samarium, neodymium, and dysprosium are important constituents of magnets. They are used in various applications such as in computer hard disk drives, linear actuators, servo motors, speakers & headphones, and sensors. The increasing demand for automobiles, turbines, and consumer electronics is anticipated to boost REE consumption over the forecast period.
Regional Insights
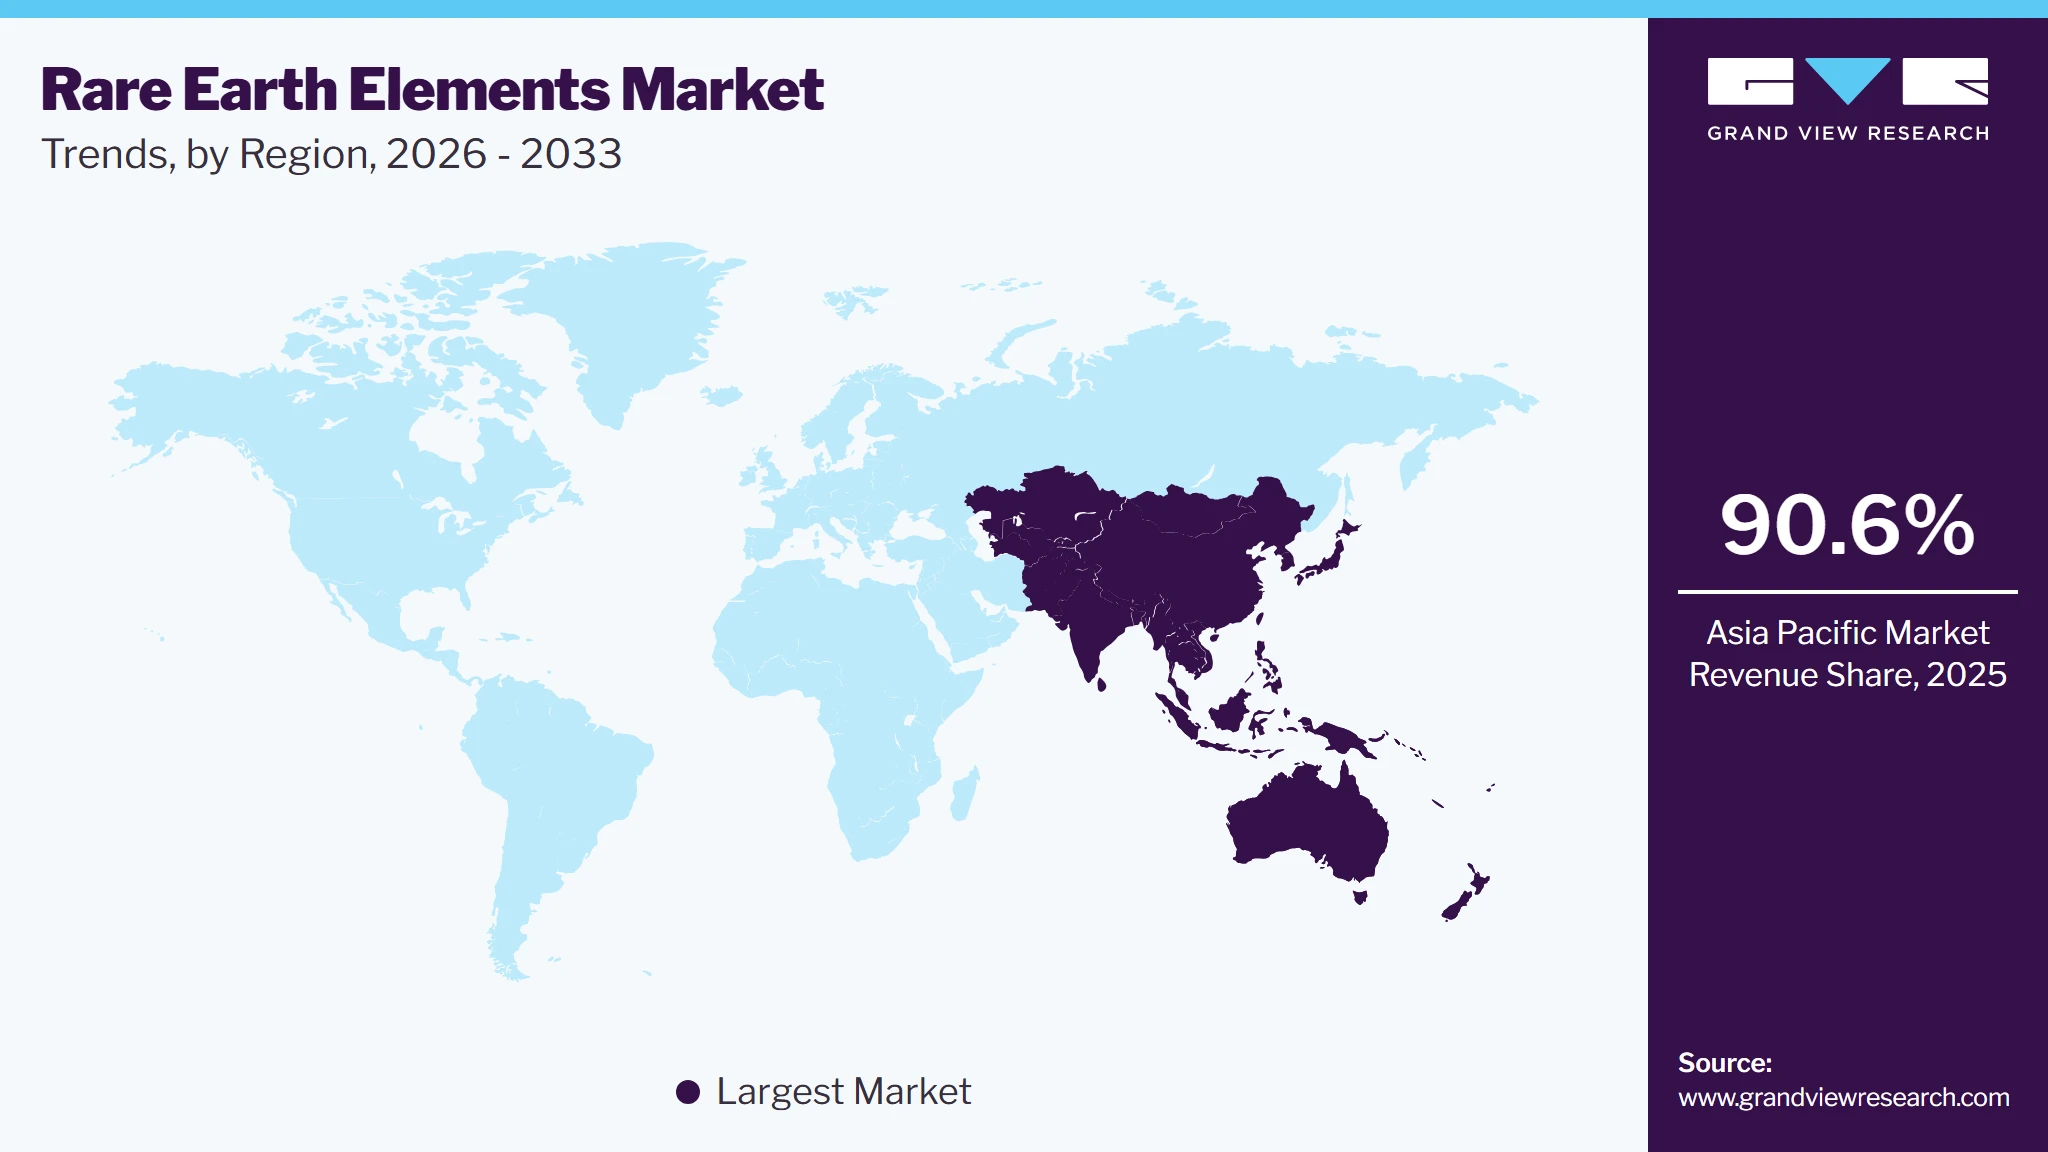
Asia Pacific dominated the rare earth elements market with the largest revenue share of 90.6% in 2025. Asia Pacific rare earth elements market is driven by the growing economy, rising disposable income, and the subsequent increase in the production of automobiles, electronics, and wind power generators in the region. Moreover, the shift of manufacturing plants across industries from high-cost developed countries to low-cost developing countries is expected to be attributed to REE demand. Additionally, rising investments in the automotive industry and the production of electric motors for EVs are also expected to boost demand.
 To learn more about this report, Download Free Sample Report
China Rare Earth Elements Market Trends
The rare earth elements market in China held the largest share in the Asia Pacific region in 2025, producing about 60% of the global output and processing nearly 90%. According to USGS, rare earth element production was 240,000 tons in 2023. In December 2023, China announced a ban on rare earth extraction and separation technologies. This comes in addition to its ongoing export restrictions on REEs. Such measures have a significant and critical impact on the world’s REE supply. Mining activities are ongoing in other parts of the world to mitigate the adverse impact of the supply shortage of this critical element group, which will eventually spike prices in the future.
Europe Rare Earth Elements Market Trends
The Europe rare earth elements market accounts for about 5% of the global production of permanent magnets, a key application of REEs. The region, however, is heavily dependent on Chinese rare earth imports. Due to the ongoing export restrictions, Europe is looking at alternative REE sources. A lot of R&D is underway to find suitable alternatives and also source REEs from sustainable mines and producers in other parts of the world.
North America Rare Earth Elements Market Trends
The rare earth elements market in North America is a frontrunner in ongoing R&D for REE substitutes. The region is also exploring alternative mining options to reduce its dependency on Chinese supply. The U.S. has witnessed a significant rise in the adoption of plug-in EVs from key players such as Tesla, Chevy, Nissan, Ford, Audi, and BMW. Thus, rising demand for EVs is expected to drive the demand for REEs over the forecast period.
Central & South America Rare Earth Elements Market Trends
Central & South America rare earth elements market has significant potential for REE production. Brazil accounts for 0.2% of global REE production. The region is yet to attract sufficient investment in the upper level of the value chain, i.e., mining and exploration, with only about 7% of the global exploration budget for REE being allocated to the region.
Middle East & Africa Rare Earth Elements Market Trends
The rare earth elements market has potential reserves of about 4 million tons, concentrated in Africa. The region has some of the highest-grade deposits in the world. Two of the deposits, Lofdal in Namibia and SKK in South Africa, have high content of critical rare earth oxides (CREO). This is a driver for value chain development in the region. Demand is low and is currently not the significant focus in the region.
Key Rare Earth Elements Company Insights
Some key players operating in the industry include Lynas Corporation Ltd. and Arafura Resources Ltd.
-
Lynas Corporation Limited, together with its subsidiaries, engages in the exploration, development, mining, and processing of rare earth elements. It was incorporated in 1983 and is headquartered in Perth, Western Australia. It undertakes exploration, development, mining, and processing activities. It is located at Mt Weld, 35km south of Laverton, Western Australia. Its concentration plant is located 1.5km from the mine site. Additionally, Lynas Malaysia is located in the Gebeng Industrial Estate near the Port of Kuantan.
-
Arafura Rare Earths Limited is an Australian mineral exploration company focusing on rare earth elements. It was incorporated in 1997 and is headquartered in Perth, Western Australia. The company's flagship project is the Nolans Rare Earths Project, located in Australia's Northern Territory.
Key Rare Earth Elements Companies:
The following key companies have been profiled for this study on the rare earth elements market.
-
Alkane Resources Ltd
-
Arafura Resources Ltd
-
Avalon Advanced Materials Inc.
-
China Northern Rare Earth (Group) High-Tech Co., Ltd.
-
Greenland Minerals Ltd
-
Hitachi Metals Ltd.
-
Iluka Resources Limited
-
Indian Rare Earth Limited
-
Lynas Corporation Ltd
-
Northern Minerals Ltd
-
Rare Element Resources Ltd.
-
Shin-Etsu Chemical Co., Ltd.
-
Ucore Rare Metals Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., China Northern Rare Earth (Group) High-Tech Co., Ltd.; Lynas Rare Earths Ltd.; Iluka Resources Limited; Proterial, Ltd.; Shin-Etsu Chemical Co., Ltd.; IREL (India) Limited)
- Operate integrated value chains encompassing rare earth mining, separation, refining, and value-added material sales to strengthen supply security.
- Continuously expand processing capacity, downstream magnet materials, and critical mineral projects to meet growing global demand.
- Build long-term commercial partnerships with automotive, renewable energy, electronics, and industrial customers to secure stable sales channels.
- Possess extensive mineral resources, advanced processing technologies, and well-established global distribution networks.
- Benefit from strong financial capabilities, technical expertise, and large-scale production infrastructure that support operational efficiency.
- Maintain diversified product portfolios and long-standing customer relationships across multiple end-use industries.
- Require substantial capital investment for mining, refining facilities, environmental compliance, and capacity expansion.
- Remain exposed to fluctuations in rare earth prices, geopolitical developments, and evolving trade regulations.
- Face lengthy project development timelines due to permitting requirements, environmental approvals, and complex processing operations.
Emerging & Regional Players (e.g., Alkane Resources Ltd.; Arafura Rare Earths Limited; Avalon Advanced Materials Inc.; Energy Transition Minerals Ltd.; Northern Minerals Limited; Rare Element Resources Ltd.; Ucore Rare Metals Inc.)
- Focus on advancing regional rare-earth mining projects and on establishing domestic processing capabilities to diversify global supply.
- Leverage strategic alliances, government funding, and technology partnerships to accelerate commercialization and infrastructure development.
- Target niche opportunities in critical minerals, recycling technologies, and localized supply chains serving high-growth industries.
- Demonstrate operational flexibility to capitalize on regional policy support and emerging market opportunities.
- Control strategically located rare earth resources that contribute to global supply diversification efforts.
- Concentrate on specialized projects that enable targeted product offerings and customer-specific supply agreements.
- Operate with relatively smaller production capacities and limited financial resources compared to global market leaders.
- Depending on external processing infrastructure or developing facilities, which can affect supply continuity and margins.
- Have a comparatively limited international customer base and market presence during the commercialization phase.
Recent Developments
-
In June 2026, Shin-Etsu Chemical confirmed its plan to build a new rare-earth refining facility in Fukui Prefecture, Japan, to strengthen raw-material security for its rare-earth magnet business. The proposed facility would be the company's first new rare-earth refining plant since 2008, with reported investment plans of at least JPY 35 billion, although the company had not finalized the investment amount or timeline. The project reflects the company's efforts to diversify rare-earth refining and magnet supply chains amid export restrictions and supply uncertainty.
-
In August 2026, Iluka reported that construction of its Eneabba rare earths refinery in Western Australia was approximately 60% complete and progressing on schedule and budget, with commissioning targeted for 2027. The company also secured its first offtake agreement covering light and heavy magnet rare-earth oxides, strengthening its long-term feedstock position. The project is intended to expand rare-earth refining capacity outside China and improve access to separated materials used in advanced manufacturing and permanent magnets
-
In April 2024, U.S.-based MP Materials received USD 58.5 million for the advance construction of the country’s first integrated rare earth magnet manufacturing facility. The plant is located in Fort Worth, Texas, and is expected to begin commercial production by late 2025.
Rare Earth Elements Report Scope
Report Attribute
Details
Market definition
The market size has been estimated based on the sales of rare earth oxides, metals, alloys, and compounds used across major applications.
Market size in 2025
USD 4.2 billion
Estimated market size in 2026
USD 4.5 billion
Projected market size by 2033
USD 8.5 billion
Growth rate
CAGR of 9.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, Volume in Tons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Germany; UK; France; China; Japan; India
Key companies profiled
Alkane Resources Ltd.; Arafura Rare Earths Limited; Avalon Advanced Materials Inc.; China Northern Rare Earth (Group) High-Tech Co., Ltd.; Energy Transition Minerals Ltd.; Proterial, Ltd.; Iluka Resources Limited; IREL (India) Limited; Lynas Rare Earths Ltd.; Northern Minerals Limited; Rare Element Resources Ltd.; Shin-Etsu Chemical Co., Ltd.; Ucore Rare Metals Inc.
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase; addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Rare Earth Elements Market Report Segmentation
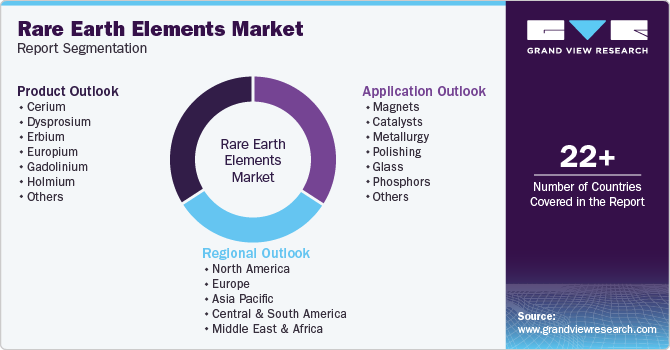
This report forecasts revenue and volume growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global rare earth elements market report based on product, application, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Tons; Revenue, USD Million; 2021 - 2033)
-
Cerium
-
Dysprosium
-
Erbium
-
Europium
-
Gadolinium
-
Holmium
-
Lanthanum
-
Lutetium
-
Neodymium
-
Praseodymium
-
Promethium
-
Samarium
-
Scandium
-
Terbium
-
Thulium
-
Ytterbium
-
Yttrium
-
-
Application Outlook (Volume, Tons; Revenue, USD Million; 2021 - 2033)
-
Magnets
-
Catalysts
-
Metallurgy
-
Polishing
-
Glass
-
Phosphors
-
Ceramics
-
Others
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Central & South America
-
Middle East & Africa
-
Research Methodology
The rare earth elements market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each rare-earth-element segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue Capture Definition
Cerium
Revenue is captured from the sales of cerium oxide, cerium metal, and cerium compounds used in catalysts, glass polishing, glass additives, metallurgy, and water treatment applications.
Dysprosium
Revenue is captured from the sales of dysprosium oxide, metal, and compounds used in high-performance permanent magnets for electric vehicles, wind turbines, industrial motors, and defense applications.
Erbium
Revenue is generated from the sale of erbium oxide, metal, and compounds used in optical fibers, lasers, specialty glass, medical devices, and photonic applications.
Europium
Revenue is captured from the sales of europium oxide and compounds used in phosphors for LED lighting, display panels, fluorescent lamps, and security applications.
Gadolinium
Revenue is captured from the sales of gadolinium oxide, metal, and compounds used in medical imaging, nuclear technologies, permanent magnets, and specialty electronics.
Holmium
Revenue is captured from the sales of holmium oxide, metal, and compounds used in lasers, magnetic materials, medical equipment, and nuclear applications.
Lanthanum
Revenue is generated from the sale of lanthanum oxide, metal, and compounds used in petroleum refining catalysts, rechargeable batteries, optical glass, ceramics, and specialty chemicals.
Lutetium
Revenue is captured from the sales of lutetium oxide, metal, and compounds used in medical imaging, radiation therapy, advanced catalysts, and scientific applications.
Neodymium
Revenue is captured from the sales of neodymium oxide, metal, alloys, and compounds used in permanent magnets for electric vehicles, wind turbines, industrial machinery, consumer electronics, and robotics.
Praseodymium
Revenue is generated from the sale of praseodymium oxide, metal, and compounds used in permanent magnets, aerospace alloys, specialty glass, ceramics, and pigments.
Promethium
Revenue is captured from the sales of promethium materials used in nuclear batteries, scientific instruments, research applications, and specialized industrial devices.
Samarium
Revenue is captured from the sales of samarium oxide, metal, alloys, and compounds used in samarium-cobalt magnets, aerospace, defense, nuclear, and catalyst applications.
Scandium
Revenue is captured from the sales of scandium oxide, metal, and alloys used in aerospace components, fuel cells, additive manufacturing, sporting goods, and defense applications.
Terbium
Revenue is captured from the sales of terbium oxide, metal, and compounds used in permanent magnets, phosphors, display technologies, lighting, and electronic devices.
Thulium
Revenue is captured from the sales of thulium oxide, metal, and compounds supplied for medical lasers, portable X-ray equipment, scientific instruments, and optical technologies.
Ytterbium
Revenue is captured from the sales of ytterbium oxide, metal, and compounds used in fiber lasers, specialty alloys, optical communications, and industrial equipment.
Yttrium
Revenue is generated from the sale of yttrium oxide, metal, and compounds used in ceramics, phosphors, superconductors, laser crystals, electronics, and medical applications.
Application
Revenue Capture Definition
Magnets
Revenue is captured from the sales of rare earth elements used in permanent magnets for electric vehicles, wind turbines, industrial motors, robotics, automation systems, and consumer electronics.
Catalysts
Revenue is generated from the sale of rare earth elements supplied for automotive catalytic converters, petroleum refining, chemical processing, and emission-control catalysts.
Metallurgy
Revenue is captured from the sales of rare earth elements used as alloying additives, grain refiners, and deoxidizing agents in steel, aluminum, magnesium, titanium, and other specialty metals.
Polishing
Revenue is generated from the sale of rare-earth polishing materials used for the precision finishing of optical lenses, semiconductor wafers, LCD panels, mirrors, and specialty glass products.
Glass
Revenue is captured from the sales of rare earth elements used in optical glass, display glass, specialty lenses, UV-resistant glass, and other high-performance glass products.
Phosphors
Revenue is captured from the sales of rare earth elements supplied for phosphors used in LED lighting, display panels, fluorescent lamps, medical imaging systems, and electronic displays.
Ceramics
Revenue is captured from the sales of rare earth elements used in advanced ceramics for electronics, industrial equipment, thermal barrier coatings, sensors, and structural components.
Others
Revenue is captured from the sales of rare earth elements used in batteries, hydrogen storage materials, aerospace, defense, healthcare, nuclear technologies, and scientific research applications.
Estimation Model
Layer Name
Key Question
Description
Demand Assessment Layer
Which industries generate demand for rare earth elements?
Market sizing begins by evaluating demand from major consuming sectors, including electric vehicles, wind energy, consumer electronics, industrial equipment, aerospace & defense, healthcare, catalysts, glass, ceramics, and metallurgy. Demand is assessed by individual rare earth element and application, considering technology penetration, production activity, and regional consumption trends to determine the overall addressable market.
Supply Chain Assessment Layer
How is market supply established?
Supply is evaluated by analyzing rare earth mining output, concentrate availability, separation and refining capacity, production of rare earth oxides, metals, and alloys, and secondary supply from recycling. The assessment also includes regional production capabilities, trade flows, inventories, and the role of miners, processors, refiners, and distributors in maintaining material availability.
Application Penetration Layer
Where are rare earth elements utilized, and to what extent?
Consumption is estimated by tracking the use of rare earth elements in permanent magnets, catalysts, metallurgy, polishing materials, phosphors, glass, ceramics, batteries, and other advanced applications. The analysis incorporates material intensity, product specifications, substitution potential, technological advancements, and end-use manufacturing trends to estimate application-wise demand.
Revenue Layer
How is the market value derived?
Market revenue is calculated from the sales of rare earth oxides, metals, alloys, compounds, and related products across global end-use industries. The valuation considers average selling prices, sales volumes, product mix, regional demand distribution, and application-wise consumption. Pricing dynamics, shifts in downstream demand, and evolving supply chain strategies are incorporated to estimate the total market value.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Trade & Critical Minerals Policy Analysis
An assessment will be carried out covering import-export regulations, tariffs, export controls, government incentives, critical mineral policies, and strategic stockpiling initiatives across major producing and consuming countries.
Will support regulatory compliance, market-entry strategies, and risk mitigation in response to evolving global trade policies.
Pricing & Supply Chain Analysis
A comprehensive analysis will be conducted covering rare earth oxide and metal pricing, mining output, refining capacity, supply-demand balance, trade flows, logistics, and the impact of geopolitical developments on the global supply chain.
Will support procurement planning, pricing strategy development, supply risk assessment, and long-term sourcing decisions.
Rare Earth Element-wise Demand & Pricing Analysis
A detailed assessment will be conducted for individual rare earth elements, including neodymium, praseodymium, dysprosium, terbium, cerium, lanthanum, yttrium, and others. The study will evaluate demand by end-use industry, pricing trends, supply availability, and future consumption outlook for each element.
Will support product portfolio optimization, pricing strategy development, and identification of the most commercially attractive rare earth elements.
Frequently Asked Questions About This Report
Asia Pacific dominated the rare earth elements market with the largest revenue share of 90.6% in 2025.
The rare earth elements market in China held the largest share in the Asia Pacific region in 2025.
North America is expected to register the fastest CAGR of 10.0% over the forecast period.
Based on applications, the magnets segment led the market with the largest revenue share of 42.0% in 2025.
The rare earth elements market size was estimated at USD 4.2 billion in 2025 and is expected to reach USD 4.5 billion in 2026.
The rare earth elements market is expected to grow at a compound annual growth rate of 9.5% from 2026 to 2033 to reach USD 8.5 billion by 2033.
Based on product, Neodymium led the market with the largest revenue share of 40.8% in 2025.
The rare earth elements market is driven by the rising demand for permanent magnets used in electric vehicles, wind turbines, consumer electronics, and other clean energy technologies.
Some of the key vendors in the global rare earth elements market are Alkane Resources Ltd., Arafura Rare Earths Limited, Avalon Advanced Materials Inc., China Northern Rare Earth (Group) High-Tech Co., Ltd., Energy Transition Minerals Ltd., Proterial, Ltd., Iluka Resources Limited, IREL (India) Limited, Lynas Rare Earths Ltd., Northern Minerals Limited, Rare Element Resources Ltd., Shin-Etsu Chemical Co., Ltd., and Ucore Rare Metals Inc.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


