
- Home
- »
- Medical Devices
- »
-
Ocular Implants Market Size & Share Report, 2026-2033GVR Report cover

Ocular Implants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Intraocular Lens, Corneal Implants), By Application (Glaucoma Surgery, Oculoplasty), By End Use (Hospitals, Specialty Eye Institutes, Clinics), By Region, And Segment Forecasts
Market Size, 2025
$16.6BMarket Estimate, 2026
$17.6BMarket Forecast, 2033
$26.3BCAGR, 2026–2033
5.9%Ocular Implants Market Size & Trends
The global ocular implants market size was valued at USD 16.6 billion in 2025 and is projected to grow from USD 17.6 billion in 2026 to USD 26.3 billion by 2033, at a CAGR of 5.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.5% in 2025. The growth is driven by several factors, such as the rising prevalence of ophthalmic disorders, the aging global population, technological advancements in implants, growing awareness of corrective eye surgeries, and rising healthcare expenditures.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Glaucoma implants segment led the market with the largest revenue share of 28.9% in 2025.
- By application: Glaucoma surgery segment led the market with the largest revenue share of 33.8% in 2025.
- By end use: Hospitals segment led the market with the largest revenue share of 42.2% in 2025.
Regional Highlights
- Largest regional market: North America (36.5% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 16.6 Billion
- Estimated market size in 2026: USD 17.6 Billion
- Projected market size by 2033: USD 26.3 Billion
- CAGR (2026-2033): 5.9%
Prism AI by Grand View Research Free to tryAsk a question about the ocular implants marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Increasing cases of diabetic retinopathy are also driving the growth of the market. According to the World Health Organization (WHO), over 2.2 billion people globally suffer from some form of near or distance vision impairment, with many of these cases linked to conditions such as cataracts and glaucoma. The increasing global prevalence of eye diseases is a significant driver of growth in the ocular implants market. For instance, according to a comprehensive study published in The Lancet Global Health, in 2020, it was estimated that 596 million individuals globally suffered from distance vision impairment, including 43 million who were classified as blind. In addition, 510 million people experienced uncorrected near vision impairment due to the lack of access to reading spectacles. A substantial majority of those affected, approximately 90%, reside in low- and middle-income countries (LMICs). By 2050, factors such as population aging, growth, and urbanization are projected to result in approximately 895 million individuals suffering from distance vision impairment, with 61 million of them expected to be blind. To learn more about this report, Download Free Sample Report
The rising prevalence of eye conditions such as cataracts, glaucoma, and age-related macular degeneration is a key driver of the ocular implants market. For instance, according to World Health Organization (WHO) cataracts are responsible for around 51% of global blindness, affecting 65.2 million people worldwide. Similarly, glaucoma is estimated to impact 80 million people globally, with this number expected to exceed 111 million by 2040. Age-related macular degeneration (AMD) affects 196 million individuals as of 2020 and is projected to rise to 288 million by 2040, particularly driven by the aging population. These growing numbers highlight the increasing demand for advanced ocular implants to restore vision and improve quality of life.
The aging global population is a significant driver of the ocular implants market as age-related eye conditions become more prevalent. For instance, according to World Health Organization (WHO), the global population aged 60 years or older was estimated at 1 billion in 2020, and is projected to nearly double to 2.1 billion by 2050. As people age, the risk of developing conditions such as cataracts, glaucoma, and macular degeneration increases, leading to a higher demand for ocular implants. For instance, over 40% of individuals aged 65 and older are affected by cataracts, and the prevalence of age-related macular degeneration rises sharply after age 50. This demographic shift is expected to significantly impact the demand for vision correction and ocular health solutions globally.
Market Dynamics
Ocular implants are gaining significant traction as they enable hospitals, specialized ophthalmology clinics, ambulatory surgery centers (ASCs), and eye surgeons to restore, preserve, and enhance visual function through advanced implantable ophthalmic technologies. These solutions encompass a broad range of products, including intraocular lenses (IOLs), glaucoma drainage implants, corneal implants, orbital implants, lacrimal implants, retinal prostheses, and other specialized ocular devices designed to address structural and functional disorders of the eye. Continuous advancements in biomaterials, foldable implant designs, hydrophobic and hydrophilic acrylic polymers, biocompatible silicone materials, premium multifocal and toric optics, sustained-release drug-eluting technologies, and minimally invasive implantation techniques have significantly improved clinical outcomes while reducing postoperative complications and enhancing long-term patient satisfaction.
The increasing incidence of ophthalmic disorders worldwide is one of the primary factors driving the growth of the ocular implants market. The rising prevalence of age-related eye diseases such as cataracts, glaucoma, age-related macular degeneration (AMD), diabetic retinopathy, corneal disorders, and retinal diseases has substantially increased the demand for implantable ophthalmic devices that can restore vision, preserve ocular function, and improve patients' quality of life. Ocular implants including intraocular lenses (IOLs), glaucoma drainage implants, corneal implants, retinal implants, and orbital implants have become integral to the long-term management of these conditions, offering durable clinical outcomes with improved visual rehabilitation. In parallel, rapid population ageing, increasing diabetes prevalence, and greater exposure to lifestyle-related risk factors are expanding the patient pool requiring advanced ophthalmic interventions, thereby supporting sustained market growth. According to the World Health Organization (WHO), at least 2.2 billion people globally live with near or distance vision impairment, and in approximately 1 billion cases, vision impairment could have been prevented or remains untreated. Cataracts account for 94 million cases of vision impairment worldwide, while glaucoma affects 7.7 million people with vision impairment and diabetic retinopathy contributes to 3.9 million cases, highlighting the substantial need for effective surgical and implant-based treatment options.
The high cost associated with advanced ocular implants and implant-based ophthalmic procedures remains a major restraint to the growth of the global ocular implants market. Although innovations such as premium intraocular lenses, glaucoma drainage implants, retinal prostheses, and bioengineered corneal implants have significantly improved visual outcomes, these products are considerably more expensive than conventional treatment alternatives. In addition to the implant cost, patients often incur expenses related to preoperative diagnostics, advanced imaging, surgical procedures, postoperative care, and long-term follow-up, increasing the overall treatment cost. In many low- and middle-income countries, limited insurance coverage and high out-of-pocket healthcare expenditure make these advanced implants inaccessible to a large proportion of patients, resulting in delayed treatment or the selection of lower-cost conventional therapies. Healthcare providers also face financial challenges in adopting advanced ocular implant technologies due to the need for specialized surgical equipment, operating microscopes, ophthalmic imaging systems, and highly trained ophthalmic surgeons.
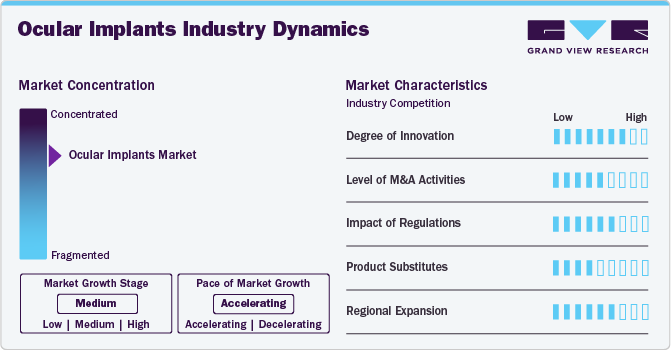
Market Concentration & Characteristics
The market is characterized by a moderate level of industry concentration, with a blend of established multinational companies and emerging players competing for market share. Major players in the market dominate through their advanced technological offerings, expansive distribution networks, and significant investments in research and development. Leading companies such as Alcon, Inc., Bausch + Lomb, Carl Zeiss AG, Johnson & Johnson Services, Inc., STAAR Surgical, MORCHER GmbH, and Glaukos Corporation are at the forefront of innovation, driving the development of cutting-edge ocular implant solutions, including intraocular lenses, glaucoma implants, and retinal prosthetics. These industry leaders benefit from strong brand recognition, extensive product portfolios, and global reach, enabling them to maintain a competitive edge. At the same time, emerging players are introducing novel technologies, focusing on specialized solutions to address unmet patient needs, contributing to the market’s dynamic growth.
The market exhibits a high degree of innovation, with continuous advancements aimed at enhancing patient outcomes and vision restoration. Innovations include the development of premium intraocular lenses (IOLs), such as ReSTOR IOL by Alcon Inc., which offer correction for cataracts and refractive errors such as presbyopia and astigmatism. Minimally invasive glaucoma surgery (MIGS) devices, such as the iStent inject by Glaukos Corporation., represent a significant rise in glaucoma management, providing effective treatment with less invasiveness. In addition, retinal prosthetics, such as the Argus II Retinal Prosthesis System, are pushing the boundaries of technology by restoring partial vision to individuals with retinitis pigmentosa. These innovations are revolutionizing ocular care, offering more precise treatments, quicker recovery times, and expanded solutions for vision impairment.
 To learn more about this report, Download Free Sample Report
The impact of regulations on the market is significant, as stringent standards ensure the safety, efficacy, and quality of these medical devices. Regulatory bodies such as the U.S. Food and Drug Administration (FDA), European Medicines Agency (EMA), and Health Canada enforce rigorous approval processes, including clinical trials and post-market surveillance, before ocular implants can be introduced to the market. These regulations ensure that products meet high safety standards and perform effectively, fostering patient trust. While these regulatory requirements can slow the time to market and increase costs for manufacturers, they also provide a framework for innovation, ensuring that only safe and reliable devices are available to consumers.
The level of mergers and acquisitions (M&A) activities in the ocular implants market has been steadily increasing as companies seek to expand their product portfolios, enter new markets, and gain access to advanced technologies. Large multinational corporations often acquire smaller, innovative firms to strengthen their R&D capabilities and broaden their offerings in areas such as glaucoma implants, retinal prosthetics, and advanced intraocular lenses. For instance, in May 2022, Alcon Inc. completed its acquisition of Aerie Pharmaceuticals, Inc., a move that strengthens Alcon's ophthalmic pharmaceutical business. The acquisition, valued at approximately USD 770 million, enables Alcon Inc. to expand its portfolio of glaucoma treatments. These M&A activities allow companies to leverage synergies, streamline production, and enhance their competitive positioning, all of which are crucial in an industry driven by technological advancements and an aging global population. In addition, M&A helps companies gain a foothold in emerging markets where the demand for ocular implants is growing rapidly.
In the market, product substitutes can impact demand, with alternatives such as glasses, contact lenses, and pharmaceutical treatments commonly used for vision correction and managing eye conditions. For instance, contact lenses can replace intraocular lenses (IOLs) for correcting refractive errors such as myopia and hyperopia. Similarly, pharmaceutical therapies for conditions such as glaucoma, such as eye drops, provide an alternative to surgical implants for managing intraocular pressure. In addition, laser eye surgeries such as LASIK offer a non-invasive alternative to IOLs for vision correction. Despite these substitutes, ocular implants remain a preferred solution, especially for cataract surgery, retinal implants, and patients who cannot use contact lenses or undergo laser treatments. The availability and affordability of these substitutes can influence demand, particularly in regions with limited access to advanced surgical care.
Regional expansion plays a crucial role in the growth of the market, with companies targeting emerging markets to meet the increasing demand for eye care solutions. For instance, in Asia-Pacific, particularly in India, Alcon Inc. has strengthened its presence by launching initiatives to enhance cataract surgery rates by providing affordable intraocular lenses (IOLs) to cater to the large aging population. In China, Johnson & Johnson Vision has expanded its footprint by establishing partnerships with local hospitals to offer advanced glaucoma implants and improve patient access to high-quality eye care. In Latin America, Bausch + Lomb has seen growth through the introduction of its iStent glaucoma implant in countries such as Brazil, addressing the rising prevalence of glaucoma with minimally invasive treatments. In Africa, where cataracts are a leading cause of blindness, MORCHER GmbH has been working with non-governmental organizations (NGOs) to distribute affordable ocular implants in countries such as Kenya, aiming to reduce the burden of vision impairment.
Analyst Perspective
The ocular implants market is positioned at the convergence of several long-term healthcare and ophthalmology industry trends, including the rising global burden of vision-threatening eye disorders, rapid population aging, and continuous innovations in implantable ophthalmic technologies. The increasing prevalence of cataracts, glaucoma, age-related macular degeneration (AMD), corneal diseases, and retinal disorders is driving sustained demand for advanced ocular implants that offer long-term vision restoration, improved disease management, and enhanced patient quality of life. Growing preference for minimally invasive ophthalmic procedures, coupled with increasing awareness regarding early diagnosis and surgical intervention, is further supporting the adoption of intraocular lenses (IOLs), glaucoma drainage implants, corneal implants, retinal prostheses, and sustained drug-delivery ocular implants across hospitals, specialty eye care centers, and ambulatory surgery centers (ASCs). Furthermore, continuous advancements in premium intraocular lens technologies, biocompatible biomaterials, extended depth-of-focus (EDOF) and trifocal IOLs, minimally invasive glaucoma implants, and biodegradable sustained-release drug implants are significantly improving surgical precision, visual outcomes, implant longevity, and post-operative patient satisfaction.
Product Insights
Based on product, the glaucoma implants segment led the market with the largest revenue share of 28.9% in 2025. This dominance is attributed to the increasing incidence of glaucoma, a condition that is one of the leading causes of blindness globally. For instance, according to the World Health Organization (WHO), glaucoma affects approximately 80 million people worldwide, and it is projected that this number is expected to rise to 112 million by 2040. The disease primarily impacts individuals over the age of 60, which is a growing demographic as the global population ages. The increasing prevalence of glaucoma is driving demand for effective treatment options, including glaucoma implants, which are designed to lower intraocular pressure and prevent optic nerve damage. In addition, the American Academy of Ophthalmology estimates that glaucoma is expected to affect 3.5 million Americans by 2025, making it a significant healthcare concern that further drives the growth of the market.
The intraocular lens segment is expected to register significant growth over the forecast period due to the rising incidence of cataracts and the increasing demand for cataract surgeries worldwide. Cataracts are a leading cause of vision impairment, particularly among the aging population, and the need for surgical intervention to replace cloudy lenses with intraocular lenses is growing. For instance, according to the American Society of Cataract and Refractive Surgery (ASCRS), more than 24 million people in the United States alone are affected by cataracts, and this number is expected to rise as the population ages. In addition, the World Health Organization (WHO) estimates that globally, more than 50 million cataract surgeries are performed each year, with intraocular lenses being the primary solution for restoring vision post-surgery. The growing preference for premium intraocular lenses, which offer benefits such as reducing the need for glasses after surgery, is also contributing to the segment’s growth.
Application Insights
Based on application, the glaucoma surgery segment led the market with the largest revenue share of 33.8% in 2025, driven by the rising prevalence of glaucoma and the increasing adoption of surgical treatments to manage intraocular pressure (IOP). Glaucoma, a leading cause of blindness, affects millions of individuals globally, particularly in aging populations. For instance, according to the World Health Organization (WHO), approximately 80 million people worldwide are affected by glaucoma, and the number is expected to rise to 112 million by 2040. The growth in glaucoma surgery is attributed to the demand for effective surgical interventions, such as trabeculectomy, tube shunts, and minimally invasive glaucoma surgeries (MIGS), which offer safer and less invasive options compared to traditional procedures. The ongoing advancements in surgical technologies and the increasing global focus on improving vision care are expected to drive continued growth in the glaucoma surgery segment.
The age-related macular degeneration segment is expected to witness exponential growth over the forecast period, driven by the increasing aging population and the rising prevalence of the condition globally. Age-related macular degeneration, a leading cause of vision loss, primarily affects individuals over the age of 50, and as the global elderly population expands, the number of cases is expected to rise. For instance, the World Health Organization estimated that the global population aged 60 and older is expected to reach 2.1 billion by 2050, nearly double the number in 2020. In the United States, the National Eye Institute reported that approximately 2.1 million people aged 50 and older are affected by age-related macular degeneration, with this number expected to increase to 5.4 million by 2050. The market for age-related macular degeneration is also being boosted by technological advancements, which are expected to expand the treatment options available. These factors are expected to significantly contribute to the exponential growth of the age-related macular degeneration segment over the forecast period.
End Use Insights
Based on end use, the hospitals segment led the market with the largest revenue share of 42.2% in 2025 of the market share, driven by the increasing demand for specialized ocular implant procedures and the growing number of patients seeking treatment for conditions such as cataracts, glaucoma, and age-related macular degeneration. Hospitals are typically the primary healthcare settings for complex eye surgeries due to their advanced infrastructure, skilled medical professionals, and access to state-of-the-art technology. For instance, in the United States, the American Academy of Ophthalmology reports that more than 4 million cataract surgeries are performed annually, the majority of which take place in hospitals. In addition, in regions such as Asia-Pacific, where the healthcare infrastructure is rapidly improving, hospitals are expected to see significant growth in ocular implant procedures, driven by the increasing prevalence of eye diseases and greater access to advanced treatment options. The concentration of advanced medical technologies, specialized surgical expertise, and patient safety protocols in hospitals are expected to continue to fuel the dominance of this segment in the ocular implants market.
 To learn more about this report, Download Free Sample Report
The specialty eye institutes segment is expected to experience significant growth during the forecast period due to the increasing demand for eye care services in remote areas and the need for specialized treatments for various eye conditions. As access to advanced eye care remains limited in many rural and underserved regions, specialty eye institutes play a crucial role in delivering high-quality care. For instance, in India, Aravind Eye Care System, one of the largest networks of eye care hospitals, serves millions of patients annually, providing affordable cataract surgeries and other treatments. Similarly, in Africa, the African Eye Institute is addressing the shortage of eye care services by offering specialized treatments and outreach programs in rural areas. In addition, the growing awareness of eye health and the increasing demand for complex procedures such as glaucoma implant surgeries and retinal implants are expected to drive the growth of these institutes. The focus of specialty eye institutes on personalized care and cutting-edge treatments, and their expansion into underserved areas is expected to significantly contribute to their growth in the ocular implants market.
Regional Insights
North America dominated the ocular implants market with the largest revenue share of 36.5% in 2025, driven by the high prevalence of eye diseases and advanced healthcare infrastructure. The region's strong market position is attributed to the increasing incidence of conditions such as cataracts, glaucoma, and age-related macular degeneration. For instance, the American Academy of Ophthalmology reports that over 24 million people in the United States are affected by cataracts, a number expected to grow as the population ages. Similarly, the Centers for Disease Control and Prevention (CDC) estimates that more than 3 million people in the U.S. have glaucoma, and this number is expected to rise in the coming decades. North America also benefits from access to state-of-the-art medical technologies, which enables the widespread adoption of advanced ocular implants. The presence of leading market players, such as Alcon, Inc., Bausch + Lomb, and Johnson & Johnson Services, Inc., further strengthens the region's market dominance.
 To learn more about this report, Download Free Sample Report
U.S. Ocular Implants Market Trends
The ocular implants market in the U.S. held the largest share in the North America region in 2025. The growth is driven by the country's aging population and the availability of cutting-edge medical technologies. With a large portion of the population aged 65 and older, the demand for treatments related to conditions like cataracts and age-related macular degeneration continues to rise. For instance, the American Academy of Ophthalmology reports that 24 million people in the U.S. are affected by cataracts, a number expected to grow as the elderly population increases. The U.S. also benefits from its strong healthcare system, offering access to the latest ocular implants and surgical options. In addition, the presence of top market players such as Alcon, Inc., Bausch + Lomb, and Johnson & Johnson Services, Inc., which are at the forefront of innovation, further drives the U.S. ocular implants market, ensuring the availability of advanced treatments and therapies for eye diseases.
Europe Ocular Implants Market Trends
The ocular implants market in Europe is experiencing significant growth, driven by factors such as an aging population, increasing awareness of eye health, and advancements in healthcare infrastructure. The region is facing a rising prevalence of conditions such as cataracts, glaucoma, and age-related macular degeneration, which are contributing to the demand for ocular implants. For instance, the European Eye Epidemiology (E3) Consortium reported that more than 50 million people in Europe are living with uncorrected vision impairment, with a substantial portion requiring advanced surgical treatments, such as intraocular lenses and retinal implants. The increasing focus on specialized eye care centers and the availability of cutting-edge medical technologies are also fueling market growth. In addition, European countries benefit from strong healthcare systems and public health initiatives that promote early detection and treatment of eye diseases, further driving the demand for ocular implants.
The UK ocular implants market is experiencing steady growth, driven by an aging population and increasing prevalence of eye conditions, such as cataracts and diabetic retinopathy. For instance, according to The Royal National Institute of Blind People, nearly 2 million people in the UK are living with sight loss, and this number is expected to rise. In addition, the UK’s strong healthcare infrastructure and the National Health Service (NHS) programs that support eye care contribute to the widespread availability of ocular implants. Advanced technologies in eye surgery and the growing adoption of intraocular lenses (IOLs) further fuel market growth.
The ocular implants market in France is expanding due to rising eye disease incidence, such as cataracts and glaucoma, among the elderly population. The French Ministry of Health reports that approximately 1.5 million people in France are affected by cataracts, with this number expected to grow as the population ages. In addition, the French healthcare system supports access to advanced eye care, with a strong emphasis on specialized eye centers and ophthalmology services. France’s adoption of cutting-edge technology in eye care and the growing number of surgeries, such as glaucoma implant surgeries, contribute significantly to the market's growth.
Germany ocular implants market is primarily driven by the increasing demand for advanced eye care technologies. Germany’s aging demographic has led to a higher incidence of age-related macular degeneration and other ophthalmic disorders. For instance, according to the German Ophthalmological Society, approximately 5 million people in Germany suffer from age-related macular degeneration, increasing the demand for ocular implants. The country's strong healthcare infrastructure, in addition to its continuous investment in medical technology, enables the widespread adoption of cutting-edge eye care treatments.
Asia Pacific Ocular Implants Market Trends
The ocular implants market in Asia-Pacific is experiencing rapid growth, primarily due to the rising prevalence of ophthalmic disorders in countries such as China, India, and Japan. For instance, India faces a high incidence of cataracts, with approximately 12 million affected people, which drives the demand for intraocular lenses. Moreover, advancements in eye surgery technologies and growing awareness about corrective eye surgeries in the region are increasing the adoption of ocular implants. Rising healthcare expenditures in countries such as China and India further support market growth by improving access to specialized eye care services.
Japan ocular implants market is benefiting from technological advancements in implants and an aging population. With one of the oldest populations globally, Japan has a growing number of people suffering from cataracts and age-related macular degeneration, leading to an increased demand for intraocular lenses and retinal implants. For instance, according to the Japan Ophthalmological Society, about 6 million people in Japan suffer from cataracts. The country’s healthcare system provides access to advanced medical technologies and high-quality ophthalmic care, supporting the growth of the ocular implants market.
The ocular implants market in China is expected to grow rapidly, driven by rising healthcare expenditures. With increasing government investment in healthcare infrastructure and access to advanced treatments, the demand for ocular implants is expanding. For instance, over 30 million people in China are affected by cataracts, as reported by the World Health Organization, contributing to the growing need for intraocular lenses. In addition, improvements in healthcare accessibility, particularly in rural areas, are expected to boost the adoption of advanced eye care technologies. The increasing affordability and availability of eye surgeries, fueled by government initiatives and rising healthcare spending, support market growth in China.
India ocular implants market is experiencing significant growth, driven by technological advancements in implants. With a large population affected by conditions such as cataracts, the introduction of innovative intraocular lenses and retinal implants is transforming treatment options in the country. For instance, 12 million people in India suffer from cataracts, creating a high demand for advanced intraocular lenses. The ongoing development of cutting-edge technologies, including more precise surgical tools and improved implant materials, is expected to drive the adoption of ocular implants across India. As a result, the market is poised for continued expansion, with increasing access to advanced eye care solutions.
Latin America Ocular Implants Market Trends
The ocular implants market in Latin America is experiencing significant growth, driven by growing awareness of corrective eye surgeries. With an increasing focus on eye health education and greater availability of information, more people in countries such as Brazil and Mexico are seeking treatments for conditions such as cataracts and glaucoma. For instance, Brazil has approximately 3.5 million people affected by cataracts, leading to a higher demand for intraocular lenses. In addition, improved public and private healthcare initiatives are making corrective eye surgeries more accessible to the population, further driving the market’s expansion in the region.
Middle East & Africa Ocular Implants Market Trends
The ocular implants market in the MEA region is growing rapidly due to the aging population and increasing healthcare investments aimed at enhancing eye care services. For instance, according to the Saudi Ophthalmological Society, cataracts are one of the leading causes of vision impairment in the country, which drives the demand for intraocular lenses. In addition, Saudi Arabia's rising healthcare expenditures support the availability of advanced medical technologies, such as glaucoma implants and retinal prosthetics, thereby contributing to the growth of the ocular implants market.
Key Ocular Implants Company Insights
The scenario in the ocular implants market is highly competitive, with key players such as Alcon, Inc., and Bausch + Lomb. and others. The major companies are undertaking various organic and inorganic strategies such as new product development, collaborations, acquisitions, mergers, and regional expansion to serve the unmet needs of their customers.
Key Ocular Implants Companies
The following key companies have been profiled for this study on the ocular implants market.
-
Alcon, Inc.
-
Bausch + Lomb.
-
Carl Zeiss AG
-
Johnson & Johnson Services, Inc.
-
STAAR SURGICAL
-
MORCHER GmbH
-
Glaukos Corporation.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Alcon, Inc., Bausch + Lomb., Carl Zeiss AG)
- Focus on expanding premium intraocular lens (IOL) portfolios, glaucoma implants, and retinal implant technologies through continuous product innovation and clinical evidence generation.
- Strengthen global distribution networks through partnerships with hospitals, ophthalmology clinics, and ambulatory surgery centers (ASCs), while pursuing regulatory approvals across major international markets.
- Strong global brand recognition, extensive surgeon loyalty, and well-established relationships with ophthalmologists and eye care institutions provide significant competitive advantages.
- Broad product portfolios covering cataract, glaucoma, corneal, and retinal implants, supported by robust R&D capabilities, long-term clinical data, and comprehensive reimbursement coverage in developed markets.
- High R&D expenditure, stringent FDA, MDR (EU), and other regulatory compliance requirements increase development costs and product launch timelines.
- Large organizational structures often result in slower commercialization of breakthrough technologies compared to smaller innovators.
Emerging Players (STAAR SURGICAL, MORCHER GmbH, Glaukos Corporation.)
- Focus on developing minimally invasive ocular implants, next-generation glaucoma drainage devices, bioengineered corneal implants, drug-eluting implants, and customized intraocular technologies targeting unmet clinical needs.
- Emphasize innovation-driven strategies through collaborations with academic institutions, research hospitals, and venture capital funding to accelerate product development.
- Faster innovation cycles enable rapid introduction of novel implant materials, minimally invasive surgical solutions, biodegradable implants, and personalized ophthalmic technologies.
- Strong flexibility in adopting advanced biomaterials, microfluidics, sustained drug delivery platforms, and digital ophthalmology integration creates technological differentiation.
- Limited financial resources, smaller commercial infrastructure, and restricted global distribution networks constrain market penetration.
- Dependence on successful clinical trial outcomes, regulatory approvals, and external funding increases commercialization risk.
Recent Developments
-
In December 2023, Glaukos Corporation. received regulatory approval for its next-generation iStent Infinite, aimed at treating glaucoma by improving intraocular pressure control. The company continues to innovate in the micro-invasive glaucoma surgery (MIGS) segment, with new implants expected to hit the market soon.
-
In August 2022, Alcon Inc. completed the acquisition of Aerie Pharmaceuticals to expand its ophthalmic pharmaceutical portfolio, strengthening its market position in advanced eye treatments, particularly for glaucoma and retinal diseases.
-
In April 2021, Bausch + Lomb. launched the ClearVisc Ophthalmic Viscosurgical Device to enhance cataract surgery outcomes. This innovation aims to improve surgical efficiency and patient safety, which is vital in the growing cataract implant segment.
Ocular Implants Market Report Scope
Report Attribute
Details
Market size in 2025
USD 16.6 billion
Estimated market size in 2026
USD 17.6 billion
Projected market size by 2033
USD 26.3 billion
Growth rate
CAGR of 5.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
Alcon, Inc., Bausch + Lomb., Carl Zeiss AG, Johnson & Johnson Services, Inc., STAAR SURGICAL, MORCHER GmbH and Glaukos Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Ocular Implants Market Report Segmentation
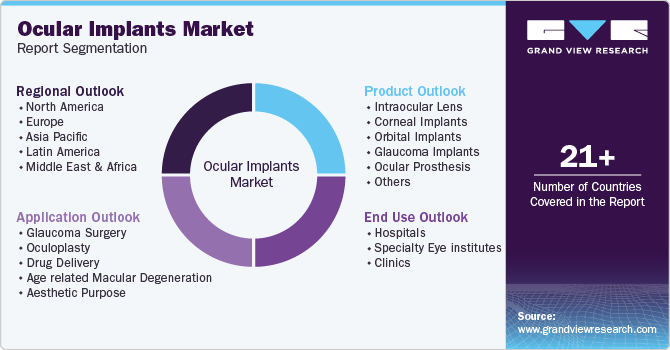
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global ocular implants market report on the basis of product, application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Intraocular Lens
-
Corneal Implants
-
Orbital Implants
-
Glaucoma Implants
-
Ocular Prosthesis
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Glaucoma Surgery
-
Oculoplasty
-
Drug Delivery
-
Age related Macular Degeneration
-
Aesthetic Purpose
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Specialty Eye institutes
-
Clinics
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The ocular implants market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each ocular implants segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Intraocular Lens
Revenue is generated through the high-volume commercial procurement of implantable optical lenses designed to replace the eye's natural crystalline lens, primarily during cataract extraction or refractive lens exchange. Manufacturers capture dominant sector value by offering a multi-tiered pricing matrix, deriving core income from standard monofocal lenses alongside premium, high-margin revenue streams from advanced technology intraocular lenses AT-IOLs, including toric, multifocal, and extended depth of focus EDOF variants that correct astigmatism and presbyopia.
Corneal Implants
Revenue flows from the commercialization of synthetic or bio-engineered corneal keratoprostheses and intracorneal ring segments ICRS utilized to treat severe corneal blindness, keratoconus, and structural thinning. Market participants generate specialized income through high-value hardware shipments and custom-engineered tissue matrices, supported by strict regulatory tissue-banking certifications and precise surgical placement tool pairings.
Orbital Implants
Revenue is captured through the production and structural delivery of sphere-based biomaterial matrices used to restore volume in the anophthalmic socket following enucleation or evisceration. Device companies monetize this segment via the sale of integrated and non-integrated orbital bodies, anchoring revenue on specialized surgical fixation accessories, wrapping meshes, and conformer kits.
Glaucoma Implants
Revenue is generated by supplying advanced fluid-drainage shunts and micro-invasive glaucoma surgery MIGS devices designed to lower elevated intraocular pressure IOP. Medtech providers leverage a high-margin, device-heavy framework, capturing consistent revenue through microscopic titanium or polymer drainage tubes, trabecular meshwork bypass stents, and specialized delivery injectors that bypass or streamline traditional filtering bleb surgeries.
Ocular Prosthesis
Revenue flows through the commercialization of custom-made or stock artificial eyes designed to aesthetically rehabilitate patients suffering from total eye loss or congenital microphthalmia. Income is driven by specialized prosthetic labs and custom ocularists who capture direct out-of-pocket or insurance-reimbursed service and hardware fees for personalized hand-painted acrylic or silicone prostheses, structural maintenance refitting loops, and regular chemical polishing kits.
Others
Revenue encompasses alternative or expanding ophthalmic implant arrays, including micro-electrode subretinal or epiretinal visual prosthetics (bionic eyes), scleral buckles for retinal detachment repair, and specialized post-trauma temporary orbital floor reconstruction plates.
Segment - Application
Revenue capture definition
Glaucoma Surgery
Revenue is generated through specialized micro-stent and aqueous shunt volume pull-through driven by the clinical demand for long-term IOP regulation. Device manufacturers capitalize on this expanding segment by shifting chronic glaucoma patients from repeating, compliance-heavy topical eye drops to definitive, single-instance surgical implant procedures.
Oculoplasty
Revenue flows from structural biomaterials, custom implants, and volume restorers used in ophthalmic plastic, reconstructive, and orbital socket salvage surgeries. Revenue capture is driven by high-complexity trauma cases, oncological eye clearances, and congenital deformity reconstructions requiring precise anatomical hardware and surgical anchoring systems.
Drug Delivery
Revenue is captured by distributing advanced micro-implants and bio-erodible polymer matrices designed to slowly release therapeutic compounds directly into the anterior or posterior chambers. Companies capture premium, ongoing pharmaceutical and medtech value by eliminating regular, invasive patient intravitreal injections in favor of multi-month, steady-state drug-eluting reservoirs.
Age related Macular Degeneration
Revenue is derived from specialized implantable optical miniatures, telescopic lens systems, and next-generation drug delivery platforms optimized to stabilize or amplify central vision for advanced AMD patients. Income is fueled by high-tier premium medical technology allocations and specialized clinical training pathways deployed across high-income geriatric patient populations.
Aesthetic Purpose
Revenue flows through private aesthetic clinic networks and direct patient-pay structures for cosmetic iris implants, custom scleral shells, and specialized orbital rim contouring plates. This out-of-pocket segment commands exceptionally premium, non-regulated pricing structures driven entirely by elective consumer cosmetic enhancement and color-modification demands.
Segment – End Use
Revenue capture definition
Hospitals
Revenue is generated through large-scale capital budget approvals, national health ministry tenders, and contract-locked group purchasing organization GPO supply setups. Enterprise device manufacturers secure massive bulk product placement by fulfilling multi-year supply chains for mainstream intraocular lenses, emergency orbital trauma hardware, and extensive perioperative surgical accessory packages used across main surgical theater units.
Specialty Eye institutes
Revenue flows via direct medical accounts, high-volume ophthalmology practice buying clusters, and dedicated outpatient vision care networks. These specialized spaces capture highly profitable revenue margins by focusing aggressively on premium AT-IOL upcharges, cutting-edge MIGS platforms, and advanced diagnostic-implant integration systems tailored to discerning, high-throughput private vision correction profiles.
Clinics
Revenue is captured through smaller-scale independent surgical suites, community eye clinics, and private ocularist offices. Income in this segment is driven by flexible, low-overhead distribution pathways, rapid-turnaround local distributor fulfillment networks, and high-frequency post-operative checkup schedules that channel patients toward localized refractive corrections and structural maintenance updates.
Estimation Model
01 – Scope Definition
02 – Build the Product Base
03 – Estimate Penetration
04 – Revenue Conversion
What is being measured in the ocular implants market?
How large is the potential patient and procedure pool for ocular implants?
What proportion of eligible ophthalmic procedures utilize ocular implants?
How are implant procedures converted into market revenue?
PROCESS STEPS
PROCESS STEPS
PROCESS STEPS
PROCESS STEPS
1. Define the scope of ocular implant product categories
1. Estimate the prevalence and incidence of ophthalmic conditions requiring implants
1. Assess implant adoption rates across different ophthalmic procedures and disease indications.
1. Collect average selling prices (ASP) for each ocular implant category across major countries and healthcare settings.
2. Segment the market by product, application, and end-user
2. Quantify annual ophthalmic surgical procedures across end user categories
2. Evaluate penetration by implant type, healthcare setting, reimbursement availability, and physician preference.
2. Estimate revenues by multiplying implant procedure volumes with average implant utilization and pricing.
3. Set Geographic Boundaries
3. Identify eligible patient populations based on disease severity, treatment guidelines, age demographics, and surgical indications.
3. Analyze technological adoption of premium intraocular lenses, minimally invasive glaucoma surgery (MIGS) implants
3. Segment revenues by product, application, and end-user
4. Align on base year & forecast horizon (2026–2033)
4. Forecast future procedure volumes
4. Measure regional differences in implant utilization
4. Validate market estimates through company financial disclosures
DATA SOURCES: ICO, AAO, ESCRS, WHO
DATA SOURCES: NHS, CMS, IAPB, National Eye Institutes, hospital procedure databases
DATA SOURCES: Primary interviews with ophthalmologists, cataract surgeons, glaucoma specialists
DATA SOURCES: Company annual reports, SEC filings, manufacturer price catalogs, distributor databases
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Key Market Player’s Market Share Analysis
Conducted a comprehensive market share assessment of the global ocular implants market, covering leading manufacturers of intraocular lenses (IOLs), glaucoma drainage implants, orbital implants, ocular prostheses, corneal implants, retinal implants, and lacrimal drainage implants. The study evaluated company-wise revenue contribution, product portfolio strength, pricing strategies, geographic presence, manufacturing capabilities, regulatory approvals, distribution networks, technological advancements, R&D investments, patent portfolios, and strategic developments including mergers & acquisitions, partnerships, collaborations, product launches, and regional expansion initiatives. Additionally, the analysis benchmarked competitors based on physician adoption, hospital procurement, procedure volume support, reimbursement coverage, and innovation pipelines to determine market leadership, competitive positioning, and future growth opportunities across major global markets.
Enables stakeholders to understand the competitive structure of the global ocular implants market, benchmark leading manufacturers, and identify market leaders based on technology, product portfolios, and commercial performance. The study supports informed strategic decisions related to portfolio expansion, pricing optimization, partnership opportunities, competitive differentiation, and investment prioritization. It also helps companies identify underserved market segments, evaluate competitor growth strategies, strengthen regional market penetration, and align future product development with evolving ophthalmic care requirements.
Macroeconomic Analysis
Conducted a detailed macroeconomic assessment of the global factors influencing the ocular implants market by evaluating healthcare expenditure, demographic trends, aging populations, prevalence of ophthalmic disorders, disposable income levels, inflationary pressures, foreign exchange fluctuations, manufacturing costs, global supply chain dynamics, trade policies, and regulatory environments. The study further assessed the impact of public and private investments in ophthalmic healthcare infrastructure, reimbursement policies, technological advancements in eye surgery, and expanding access to specialized ophthalmology services across developed and emerging economies. Additionally, the analysis examined how economic conditions influence hospital capital expenditure, ambulatory surgery center (ASC) investments, patient affordability, elective surgical procedure volumes, and long-term adoption of premium ocular implant technologies.
Enables stakeholders to evaluate macroeconomic opportunities and risks influencing demand for ocular implants across global markets. The study provides valuable insights for regional expansion planning, pricing strategies, investment prioritization, and supply chain optimization by assessing healthcare spending patterns, demographic transitions, reimbursement environments, and economic conditions. It further supports long-term business planning by identifying high-growth regions, forecasting demand shifts, mitigating operational risks arising from inflation and trade disruptions, and aligning commercial strategies with evolving global healthcare investments.
Porter Analysis
Conducted a comprehensive Porter’s Five Forces analysis to evaluate the competitive dynamics and long-term attractiveness of the global ocular implants market. The assessment analyzed supplier bargaining power by evaluating dependence on specialized biomaterials, precision manufacturing technologies, and component suppliers. Buyer bargaining power was assessed across hospitals, ophthalmology clinics, ambulatory surgery centers (ASCs), and group purchasing organizations while considering reimbursement policies and physician preferences. The study evaluated barriers to entry including stringent regulatory approvals, high R&D investments, clinical validation requirements, intellectual property protection, and manufacturing complexities. Furthermore, it assessed the threat of substitute treatment options, including pharmaceutical therapies, minimally invasive ophthalmic procedures, and emerging regenerative technologies, while examining competitive rivalry based on product innovation, pricing strategies, technological differentiation, strategic collaborations, acquisitions, and global expansion activities of major ocular implant manufacturers.
Enables stakeholders to gain a comprehensive understanding of the competitive intensity and structural attractiveness of the ocular implants market. The analysis supports strategic decision-making by identifying competitive pressures, supplier and buyer dynamics, market entry barriers, substitute technologies, and industry rivalry. It assists manufacturers in developing sustainable competitive strategies, strengthening supplier relationships, optimizing pricing models, evaluating expansion opportunities, identifying investment risks, and enhancing long-term market positioning in an increasingly innovation-driven ophthalmology industry.
Frequently Asked Questions About This Report
The global ocular implants market is expected to grow at a CAGR of 5.9% from 2026 to 2033, reaching USD 26.3 billion by 2033.
By product, the glaucoma implants segment held a leading market share of 28.9% in 2025.
Some key players operating in the ocular implants market include Bausch & Lomb, Alcon, Carl Zeiss, Johnson & Johnson, MORCHER GmbH, and STAAR surgical.
Key factors that are driving the market growth include the increasing prevalence of ophthalmic disorders such as glaucoma, scleritis, and Age-Related Macular Degeneration (AMD), higher acceptance of vision correction procedures, and technological advancements.
North America dominated the ocular implants market with a share of 36.5% in 2025. This is attributable to growing geriatric population and favorable reimbursement in the region.
Asia Pacific is the fastest-growing region over the forecast period.
By application, the age related macular degeneration segment expected to witness fastest CAGR over the forecast period.
The global ocular implants market size was valued at USD 16.6 billion in 2025 and is estimated at USD 17.6 billion for 2026.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


