
- Home
- »
- Pharmaceuticals
- »
-
Age-related Macular Degeneration Market Size Report, 2033GVR Report cover

Age-related Macular Degeneration Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Eylea, Lucentis, Beovu), By Disease (Wet AMD, Dry AMD), By Distribution Channel (Hospital Pharmacy, Retail Pharmacy, Online Pharmacy), By Region, And Segment Forecasts
Market Size, 2025
$11.6BMarket Estimate, 2026
$12.5BMarket Forecast, 2033
$22.7BCAGR, 2026–2033
9.0%Age-related Macular Degeneration Market Summary
The global age-related macular degeneration market size was valued at USD 11.6 billion in 2025 and is projected to grow from USD 12.5 billion in 2026 to USD 22.7 billion by 2033, at a CAGR of 9.0% from 2026 to 2033. The market in North America dominated with a revenue share of 53.9% in 2025. The market is driven by the increasing burden of the aging population, as AMD remains one of the leading causes of irreversible vision loss among older adults.
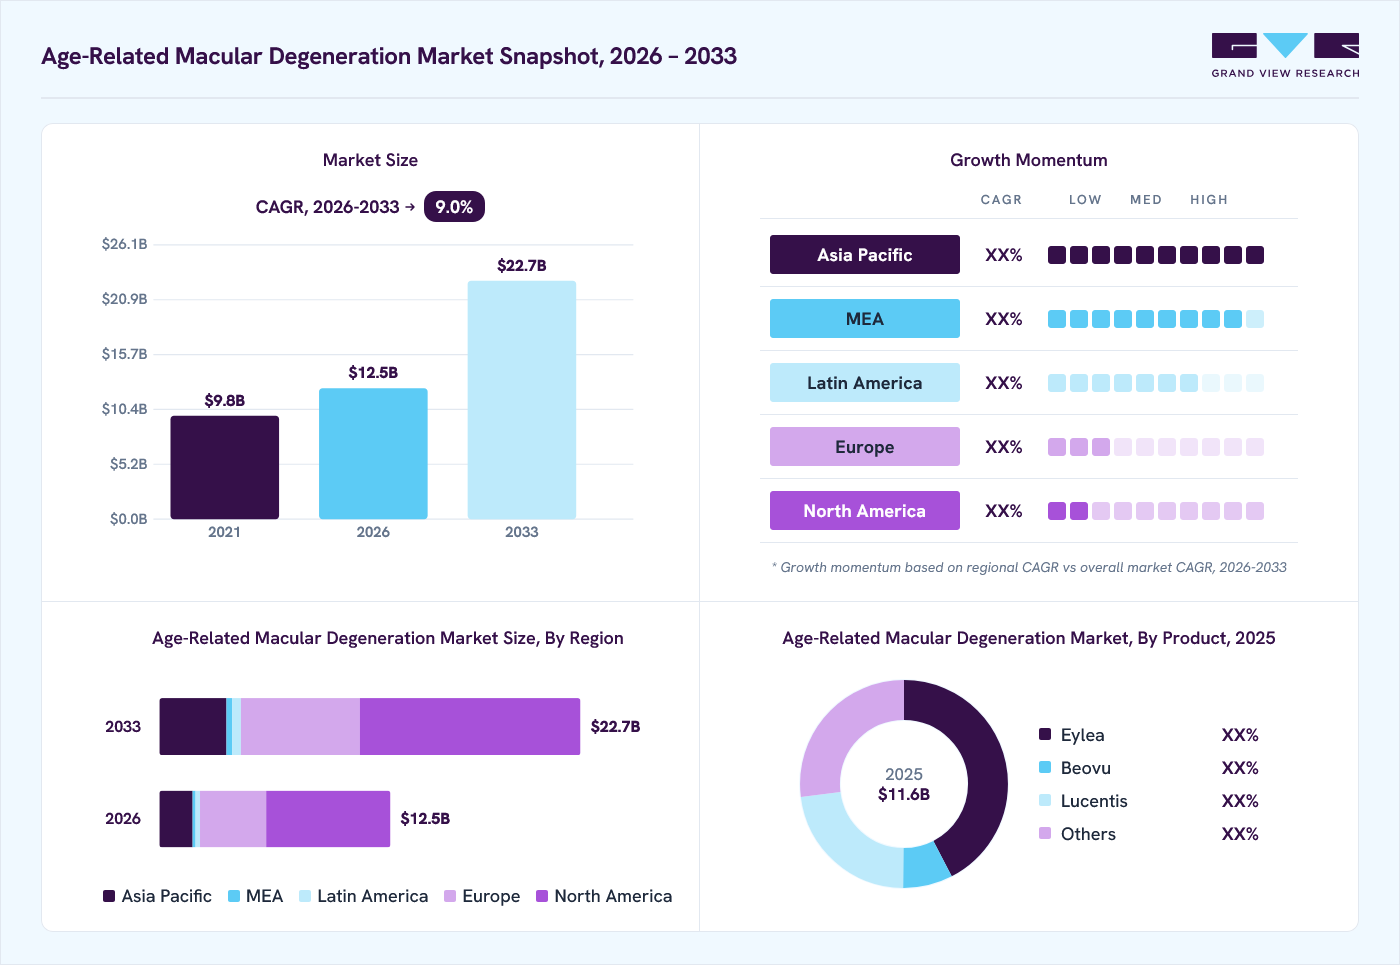 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By disease: Wet AMD segment held the largest market share of 91.0% in 2025.
- By distribution channel: Hospital pharmacy segment held the largest market share of 51.3% in 2025.
- By product: Eylea segment held the largest market share of 42.4% in 2025.
Regional Highlights
- Largest regional market: North America (53.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 11.6 Billion
- Estimated market size in 2026: USD 12.5 Billion
- Projected market size by 2033: USD 22.7 Billion
- CAGR (2026-2033): 9.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is supported by growing disease awareness, improvements in retinal imaging technologies such as optical coherence tomography (OCT), and broader access to specialist ophthalmology services, enabling earlier diagnosis and timely treatment. Anti-vascular endothelial growth factor (anti-VEGF) therapies remain the standard of care for neovascular (wet) AMD, while the introduction of complement pathway inhibitors has expanded treatment options for geographic atrophy in dry AMD. Ongoing research in sustained-release drug delivery systems, gene therapies, and novel biologics is strengthening the development pipeline and addressing the need to reduce treatment burden. At the same time, increasing healthcare expenditure, expanding retinal care infrastructure in developing countries, and the growing involvement of pharmaceutical and biotechnology companies in ophthalmology are supporting steady market growth across both developed and emerging regions.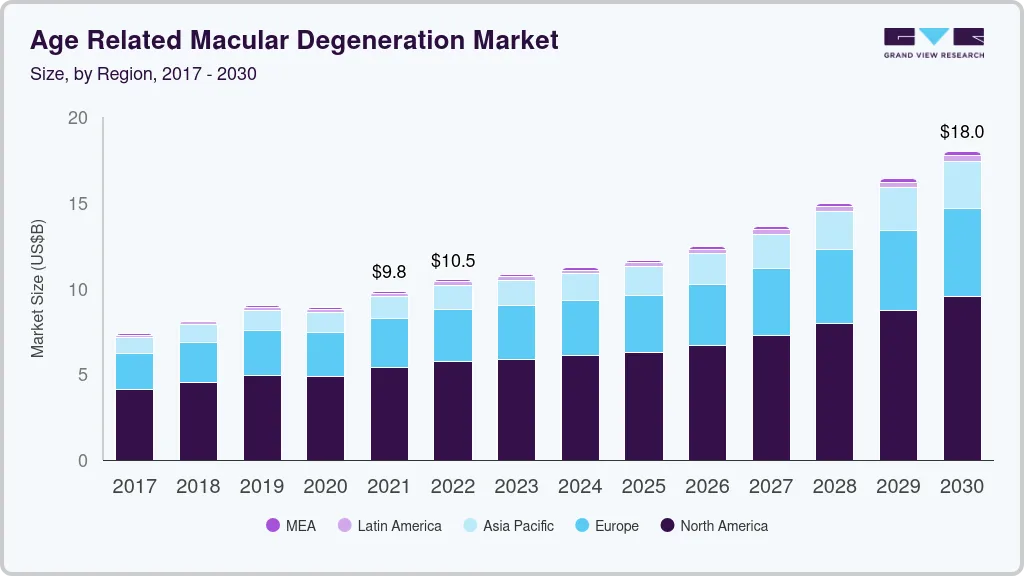 To learn more about this report, Download Free Sample Report
Market Dynamics
The market is driven by the continued expansion of approved therapies that address different stages of the disease and improve long-term disease management. Anti-vascular endothelial growth factor (anti-VEGF) therapies remain the standard of care for neovascular (wet) AMD, while complement pathway inhibitors have expanded treatment options for patients with geographic atrophy associated with dry AMD. Continued regulatory approvals across major markets are also improving patient access to advanced retinal therapies and encouraging further investment in ophthalmology research and development. For instance, in May 2025, Bayer announced that the Center for Drug Evaluation (CDE) of China's National Medical Products Administration approved aflibercept 8 mg for the treatment of neovascular (wet) age-related macular degeneration. The approval was supported by the Phase III PULSAR study, which demonstrated comparable efficacy and safety with dosing intervals of 12 weeks and 16 weeks compared with aflibercept 2 mg administered every 8 weeks, providing an option to reduce treatment frequency for eligible patients.
The long-term treatment requirements associated with age-related macular degeneration remain a key challenge for market growth. Most patients with wet AMD require repeated intravitreal injections along with regular retinal imaging and ophthalmology consultations to maintain vision. Frequent hospital visits create difficulties for elderly patients, particularly those with limited mobility, multiple chronic conditions, or dependence on caregivers for transportation. Missed appointments or treatment delays can lead to disease progression and irreversible vision loss, reducing overall treatment effectiveness. Although several newer therapies have extended dosing intervals for selected patients, regular monitoring remains necessary because disease activity varies between individuals. The treatment burden also increases demand for retinal specialists, diagnostic imaging equipment, and outpatient procedure capacity. In many developing countries, limited access to ophthalmologists and retinal care facilities further restricts timely diagnosis and treatment, slowing the adoption of advanced therapies despite the growing number of patients requiring long-term disease management.
The continued development of long-acting biologics, sustained drug-delivery systems, and gene-based therapies presents a significant market opportunity. These technologies are designed to maintain therapeutic effectiveness while reducing the frequency of intravitreal injections, addressing one of the major limitations of current treatment approaches. Ongoing research is also expanding therapeutic options for geographic atrophy and dry AMD through complement pathway modulation, regenerative medicine, and neuroprotective strategies. At the same time, increasing collaboration between biotechnology companies and established ophthalmology manufacturers is supporting clinical development and accelerating the introduction of advanced retinal therapies. Improvements in retinal imaging, earlier diagnosis, and broader access to specialist eye care are expected to increase the number of patients receiving treatment. As the global population continues to age and the prevalence of retinal disorders rises, these innovations are expected to improve long-term disease management and create opportunities for the adoption of advanced ophthalmic therapies.
Market Concentration & Characteristics
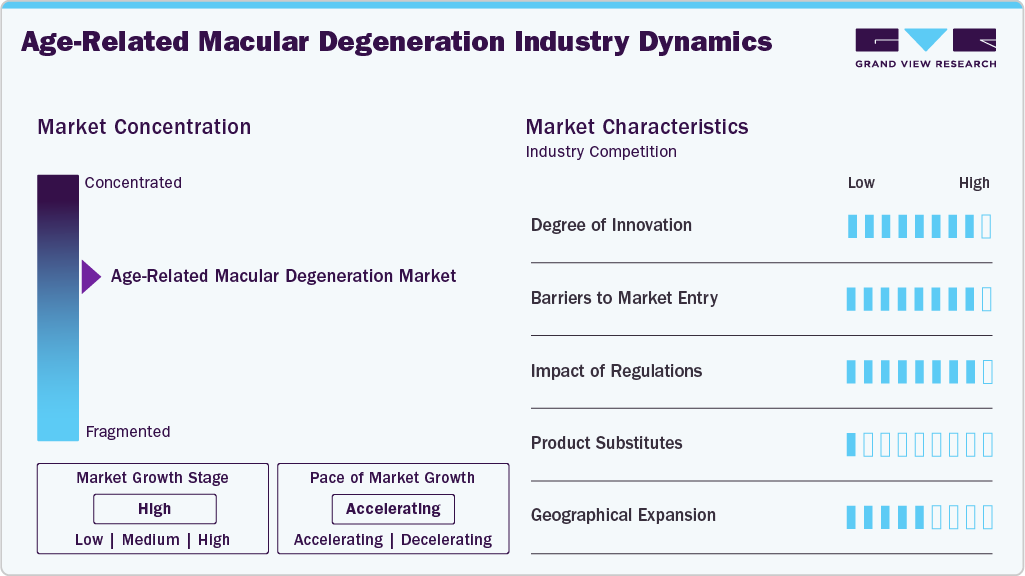
The market demonstrates a high level of innovation, driven by the development of long-acting anti-VEGF therapies, complement inhibitors for geographic atrophy, gene therapies, and sustained drug-delivery platforms. Continuous clinical research is expanding treatment options for both wet and dry AMD.
Entry barriers are high due to extensive clinical trial requirements, stringent regulatory approval processes, complex biologic manufacturing, significant research and development investments, and the need for long-term safety and efficacy data.
Regulatory authorities such as the U.S. FDA, European Commission, and other national agencies require comprehensive clinical evidence for efficacy, safety, and manufacturing quality. Post-marketing surveillance and pharmacovigilance requirements also influence product development timelines.
 To learn more about this report, Download Free Sample Report
There are limited substitutes for approved pharmacological therapies in AMD. Nutritional supplements and low-vision rehabilitation may support disease management in selected patients but cannot replace disease-modifying treatments for wet AMD or geographic atrophy.
Companies are expanding product approvals and commercial operations across Asia Pacific, Latin America, and the Middle East as retinal care infrastructure, specialist ophthalmology services, and access to advanced diagnostics continue to improve.
Analyst Perspective
The market is supported by the increasing prevalence of retinal disorders, an aging population, and continued progress in ophthalmic drug development. Anti-VEGF therapies remain the primary treatment option for wet AMD, while complement inhibitors have expanded treatment options for geographic atrophy. Pharmaceutical companies are investing in long-acting biologics, sustained drug delivery systems, gene therapies, and biosimilars to improve treatment duration and patient management. Advances in optical coherence tomography, artificial intelligence-based retinal imaging, and earlier diagnosis are supporting timely intervention. Regulatory approvals across major markets and continued clinical research are contributing to product availability and portfolio expansion. Emerging economies are also improving retinal care services through investments in healthcare infrastructure and ophthalmology centers. Competition is expected to remain focused on improving clinical outcomes, reducing treatment burden, expanding geographic reach, and developing therapies that address unmet needs across different stages of age-related macular degeneration.
Product Insights
Eylea dominated the market, with a 42.4% revenue share in 2025, owing to its established position as a standard anti-VEGF therapy for neovascular (wet) AMD and its broad adoption across major healthcare markets. The product benefits from extensive clinical evidence demonstrating sustained improvements in visual acuity and long-term disease control, making it a preferred treatment option among retinal specialists. Its availability in multiple dosing regimens, including higher-dose formulations that support extended treatment intervals for eligible patients, has reduced the frequency of intravitreal injections and improved patient adherence. Broad regulatory approvals established reimbursement coverage, and long-term physician familiarity have further strengthened its adoption across hospitals and specialty ophthalmology clinics. In addition, the increasing prevalence of age-related retinal disorders, growing access to retinal imaging technologies, and expansion of specialist eye care services continue to support the product's leading position in the global market.
The Beovu segment is projected to register the fastest CAGR of 19.4% during the forecast period, driven by increasing demand for therapies that provide effective disease control with longer dosing intervals. The product is gaining acceptance among retinal specialists because it supports individualized treatment strategies while reducing the frequency of intravitreal injections and follow-up visits for appropriate patients. Growing adoption of treat-and-extend protocols, increasing diagnosis of neovascular AMD through advanced retinal imaging, and rising awareness regarding early intervention are contributing to segment growth. Continued expansion of retinal specialty services, broader product availability across developed and emerging markets, and increasing physician confidence supported by long-term clinical evidence are expected to further strengthen adoption. As healthcare providers focus on reducing treatment burden while maintaining visual outcomes, Beovu is expected to witness steady growth throughout the forecast period.
Disease Insights
Wet AMD dominated the market, with the largest revenue share of 91.0% in 2025, driven by high treatment utilization associated with neovascular disease and the widespread adoption of anti-vascular endothelial growth factor (anti-VEGF) therapies. Patients with wet AMD require continuous disease monitoring, repeated intravitreal injections, and regular retinal imaging to maintain visual function, resulting in substantially higher treatment expenditure per patient than dry AMD. The segment also benefits from the availability of multiple approved biologic therapies, established clinical treatment guidelines, and broad reimbursement across developed healthcare markets. Increasing use of optical coherence tomography (OCT), improved access to retinal specialists, and growing adoption of treat-and-extend protocols continue to support therapy utilization. In addition, the growing elderly population and rising prevalence of neovascular AMD are driving sustained demand for long-term pharmacological management, strengthening the segment's leading position in the global market.
The dry AMD segment is projected to register the fastest CAGR of 25.3% during the forecast period, driven by the increasing availability of disease-modifying therapies for geographic atrophy and continued advances in retinal disease research. The segment is benefiting from a shift in clinical management as therapeutic options have expanded beyond nutritional supplementation and supportive care. Growing awareness regarding early diagnosis, increasing use of retinal imaging technologies, and improved identification of geographic atrophy are supporting treatment adoption across major healthcare markets. Pharmaceutical and biotechnology companies are also increasing investment in complement pathway inhibitors, gene therapies, and regenerative medicine to address the large unmet clinical need associated with dry AMD. In addition, expanding clinical research, improving physician awareness, and broader patient eligibility for newly available therapies are expected to strengthen long-term growth opportunities within the dry AMD segment.
Distribution Channel Insights
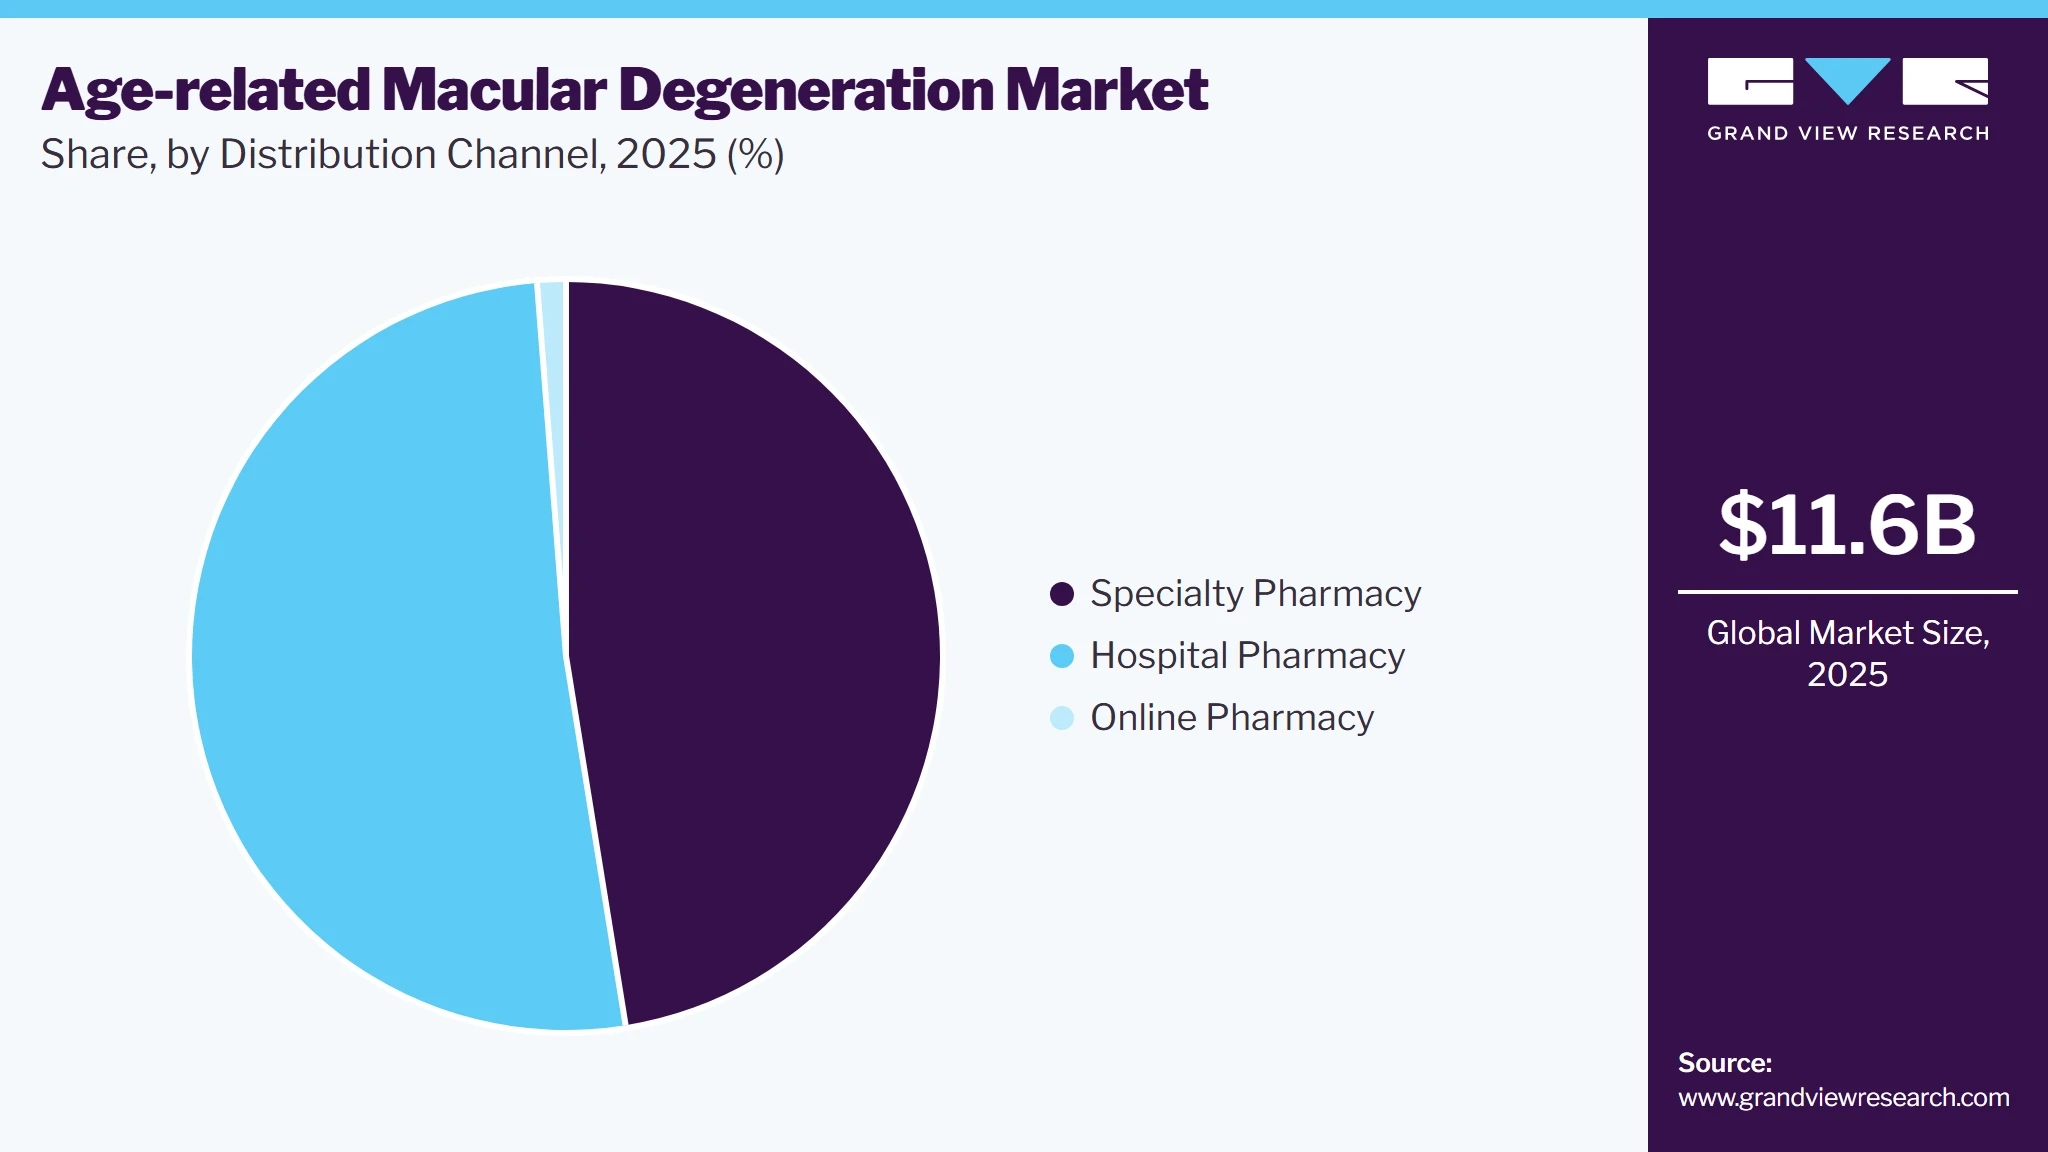
Hospital pharmacy dominated the market with the largest revenue share of 51.3% in 2025, owing to the administration requirements of intravitreal therapies, which are primarily delivered in hospital-based ophthalmology departments and retinal specialty clinics under the supervision of trained specialists. Hospital Pharmacy play a central role in the procurement, storage, preparation, and dispensing of biologic therapies, while ensuring compliance with cold-chain requirements and sterile-handling protocols. The segment also benefits from the availability of advanced retinal imaging technologies, including optical coherence tomography (OCT), which support treatment planning and disease monitoring during routine clinical visits. In addition, increasing patient preference for receiving treatment in specialized ophthalmology centers, expanding retinal care infrastructure, and the growing use of long-acting biologics continue to strengthen demand for Hospital Pharmacy. Their ability to coordinate multidisciplinary care, maintain treatment continuity, and manage complex biologic inventories further supports their leading position in the market.
 To learn more about this report, Download Free Sample Report
The specialty pharmacy segment is projected to register the fastest CAGR of 10.1% during the forecast period, driven by the growing distribution of high-value ophthalmic biologics requiring specialized storage, handling, and patient support services. Specialty pharmacies are expanding their role by assisting with reimbursement coordination, prior authorization, patient counseling, adherence monitoring, and therapy management, improving access to advanced AMD treatments. The segment is also benefiting from greater collaboration among specialty pharmacies, ophthalmologists, and other healthcare providers to ensure uninterrupted treatment and timely access to medication. Growing adoption of digital patient support platforms, remote care coordination, and specialty pharmacy management programs is further supporting segment growth. In addition, increasing demand for personalized treatment pathways and improved patient engagement is expected to strengthen the role of specialty pharmacies in the long-term management of age-related macular degeneration during the forecast period.
Regional Insights
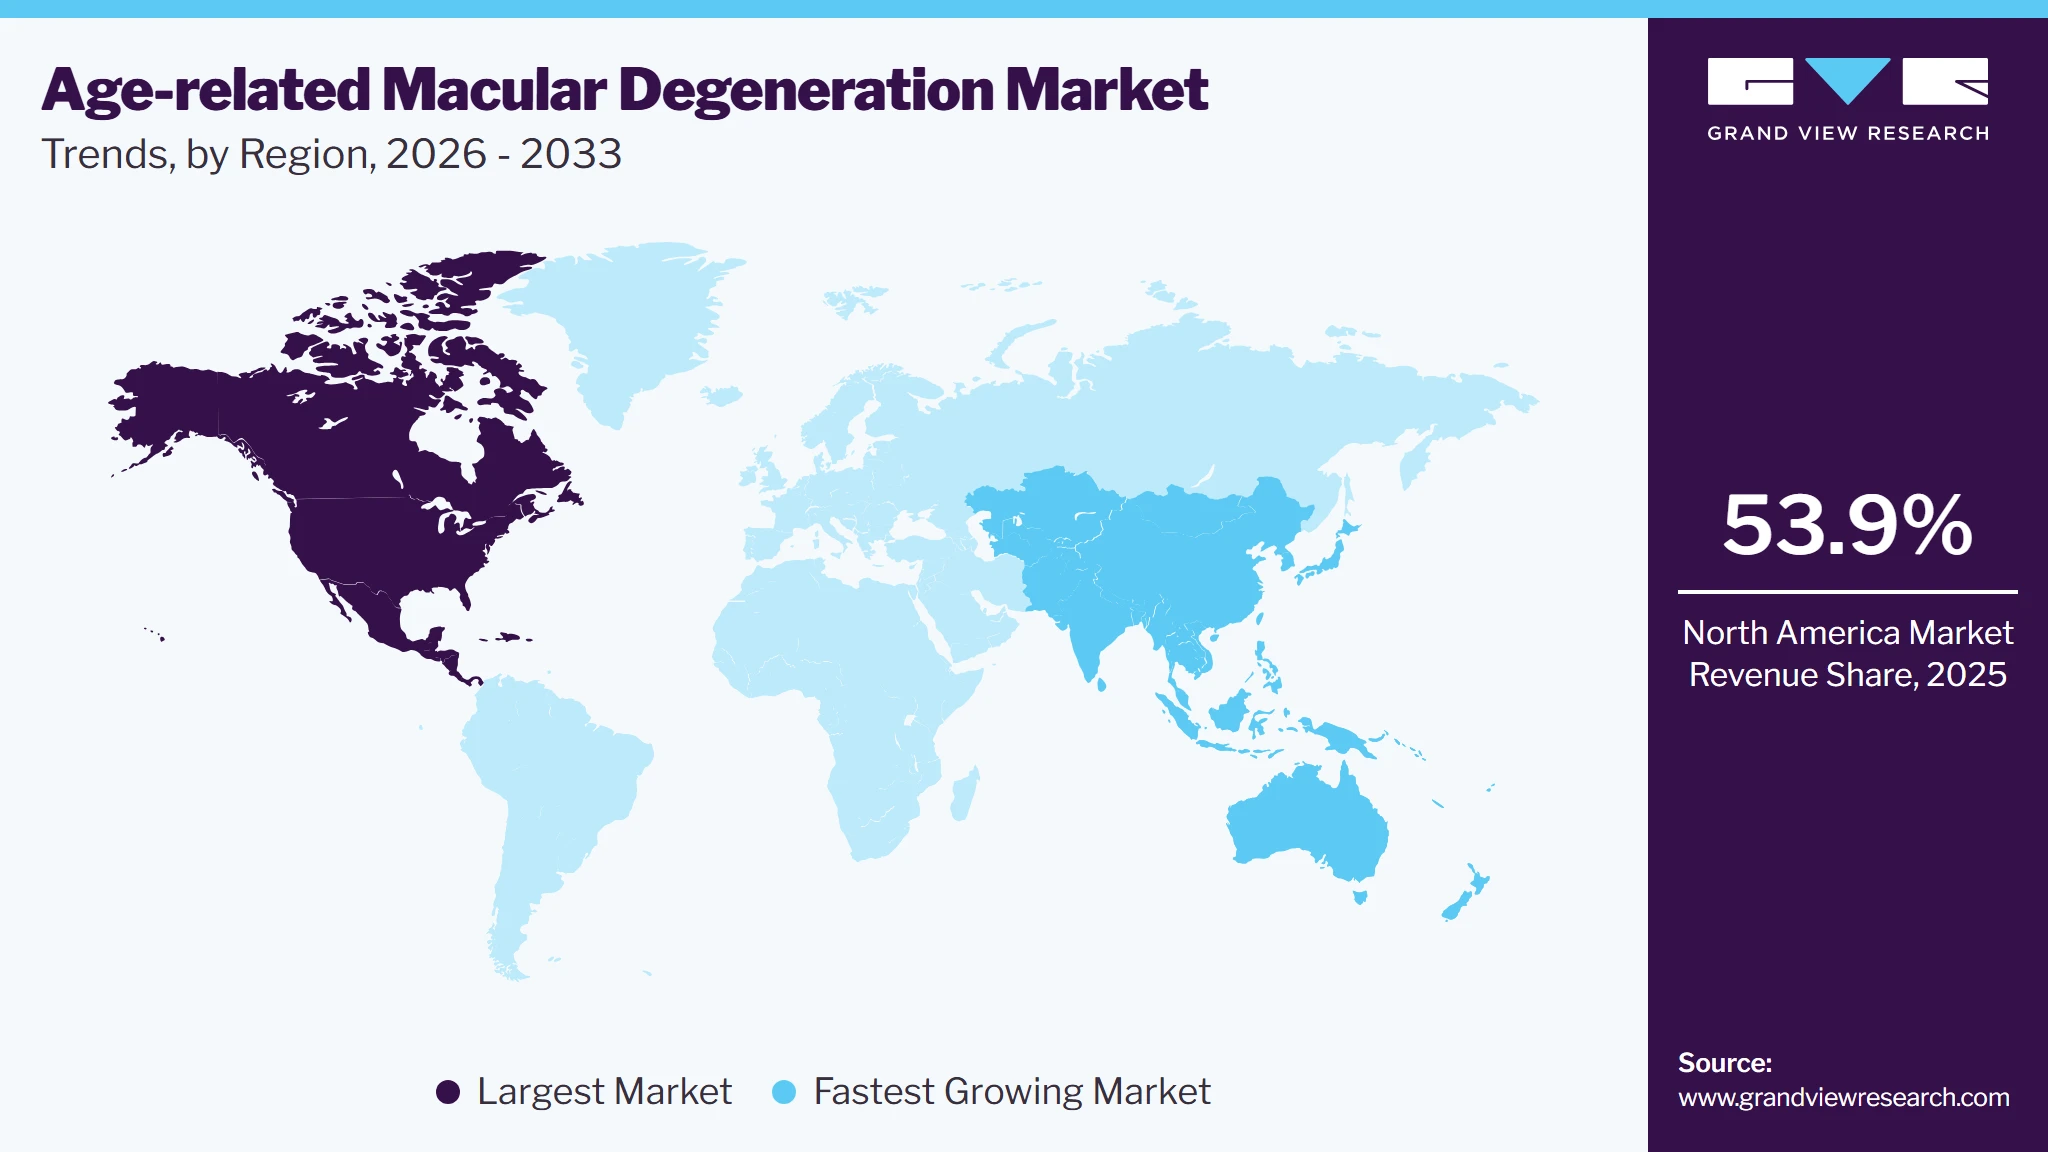
North America held the largest age-related macular degeneration market share of 53.9% in 2025, driven by the region's large aging population, high prevalence of retinal disorders, and well-established ophthalmology care infrastructure. The market benefits from the widespread adoption of advanced retinal imaging technologies, including optical coherence tomography (OCT) and fundus imaging, which enable early diagnosis and timely disease management. Strong utilization of anti-VEGF therapies and the increasing availability of new treatment options for geographic atrophy continue to support market growth across the region. In addition, favorable reimbursement coverage, high healthcare expenditure, and broad access to retinal specialists improve patient access to diagnosis and long-term treatment. The presence of leading pharmaceutical and biotechnology companies, ongoing clinical research, and continued investment in innovative therapies such as long-acting biologics, gene therapies, and sustained drug delivery systems further strengthen the regional market. Growing awareness of age-related vision loss and routine eye screening among older adults also contributes to sustained demand for AMD diagnosis and treatment across North America.
 To learn more about this report, Download Free Sample Report
U.S. Age-related Macular Degeneration Market Trends
The age-related macular degeneration market is driven by the country's strong clinical research ecosystem and rapid integration of innovative retinal therapies into routine ophthalmic practice. The U.S. is a primary site for pivotal clinical trials evaluating long-acting biologics, complement inhibitors, gene therapies, and sustained drug-delivery technologies, supporting the early availability of advanced treatment options. The market also benefits from the high concentration of academic medical centers and specialized retinal institutes, which facilitate the adoption of new treatment protocols and advanced retinal imaging techniques. Increasing collaboration between pharmaceutical companies, research organizations, and ophthalmology networks continues to accelerate therapeutic innovation and improve clinical outcomes. In addition, the growing use of personalized treatment approaches, supported by real-world evidence and evolving clinical guidelines, is optimizing long-term disease management. Continued investment in ophthalmic research, digital retinal imaging, and artificial intelligence-assisted disease monitoring further strengthens the U.S. market and supports sustained demand for age-related macular degeneration therapies.
Europe Age-related Macular Degeneration Market Trends
The age-related macular degeneration market in Europe is driven by the region's strong emphasis on integrated eye care services, standardized clinical management, and continuous adoption of innovative retinal therapies. The market benefits from established referral pathways that enable timely diagnosis and treatment through specialized ophthalmology centers across major European countries. The increasing availability of complement inhibitors for geographic atrophy, alongside the continued use of anti-VEGF therapies for neovascular AMD, has expanded treatment options for patients at different stages of the disease. Europe also has a well-developed regulatory and clinical research environment that supports the evaluation and adoption of advanced ophthalmic therapies, including long-acting biologics, sustained drug delivery systems, and gene therapies. In addition, collaborative research initiatives between academic institutions, healthcare providers, and pharmaceutical companies continue to accelerate innovation in retinal disease management. Growing investment in digital ophthalmology, artificial intelligence-assisted retinal imaging, and teleophthalmology services is further improving diagnostic efficiency and supporting sustained demand for age-related macular degeneration treatment across the region.
The UK age-related macular degeneration market is driven by the country's nationally coordinated ophthalmology services and standardized patient management pathways under the National Health Service (NHS). The market benefits from well-defined referral and treatment protocols established by the National Institute for Health and Care Excellence (NICE), enabling consistent access to evidence-based therapies across healthcare facilities. The UK has also expanded the use of community optometrists for early identification of retinal disorders, allowing patients with suspected AMD to be referred promptly to hospital eye services. In addition, the adoption of virtual monitoring clinics and shared-care models between community eye care providers and hospital-based retinal specialists has improved patient follow-up while reducing pressure on specialist services. Continuous workforce development, investments in modernizing ophthalmology services, and initiatives to improve capacity for retinal disease management further support sustained demand for age-related macular degeneration diagnosis and treatment across the UK.
The age-related macular degeneration market in Germany is driven by the country's strong network of office-based ophthalmologists and specialized retinal clinics that support timely diagnosis and long-term disease management. Germany has one of the largest outpatient ophthalmology systems in Europe, enabling broad access to retinal examinations and regular intravitreal treatment for patients with AMD. The market also benefits from the early adoption of innovative ophthalmic therapies following regulatory approval, supported by structured health technology assessments and efficient integration into clinical practice. In addition, Germany's well-established medical device and ophthalmic imaging industry facilitates the adoption of advanced diagnostic technologies that improve disease monitoring and treatment planning. Strong collaboration among university hospitals, retinal research centers, and industry partners continues to advance clinical studies and the generation of real-world evidence. Continuous investment in precision ophthalmology, digital healthcare solutions, and modern retinal care infrastructure further supports the sustained market growth in Germany.
France age-related macular degeneration market is driven by the country's strong public health focus on preventing vision impairment and preserving visual function among its aging population. The market benefits from an extensive network of hospital ophthalmology departments and private retinal specialists that support comprehensive diagnosis, treatment, and long-term monitoring of AMD. France has established structured care pathways that encourage multidisciplinary management of retinal diseases, improving coordination between ophthalmologists, primary care physicians, and community healthcare providers. In addition, the country's active participation in ophthalmology registries and observational studies contributes to the generation of real-world clinical data, supporting optimization of treatment strategies and long-term patient outcomes. Increasing investment in retinal disease research, expansion of ambulatory ophthalmology services, and broader implementation of digital health tools for patient follow-up are further strengthening the delivery of AMD care. These factors continue to support the sustained market growth in France while improving access to advanced retinal therapies.
Asia Pacific Age-related Macular Degeneration Market Trends
The age-related macular degeneration market in the Asia Pacific is projected to register the fastest CAGR of 10.5% during the forecast period, driven by the rapidly expanding elderly population, improving access to ophthalmic care, and increasing investment in retinal disease management across developing and developed economies. The market is benefiting from the expansion of specialized eye hospitals, greater availability of advanced retinal imaging technologies, and growing adoption of anti-VEGF therapies for neovascular AMD. Governments and healthcare organizations across the region are strengthening eye health programs and investing in initiatives that promote early detection of age-related vision disorders, supporting timely diagnosis and treatment. In addition, rising healthcare expenditure, expanding medical insurance coverage in several countries, and growing awareness of retinal diseases are expanding patient access to advanced ophthalmic therapies. The presence of rapidly developing healthcare infrastructure, expanding clinical research activities, and growing participation of global and regional pharmaceutical companies in ophthalmology are further supporting market growth. Continued investments in innovative retinal therapies and digital eye care solutions are expected to sustain the region's strong growth throughout the forecast period.
Japan age-related macular degeneration market is driven by the country's rapidly aging population and long-standing emphasis on preserving vision and quality of life among older adults. The market benefits from Japan's advanced ophthalmology ecosystem, where routine eye examinations and regular retinal screening are widely integrated into clinical practice. The country is also recognized for its strong ophthalmic pharmaceutical and medical technology industries, which support the continuous development and early adoption of innovative retinal therapies and diagnostic equipment. In addition, Japan has extensive experience in retinal disease research, with academic institutions and specialized eye centers actively participating in clinical studies evaluating next-generation treatments for age-related macular degeneration. Growing use of minimally invasive treatment approaches, improvements in retinal imaging technologies, and continued investment in regenerative medicine and gene therapy research are further strengthening the country's ophthalmology sector. These factors continue to support the sustained market growth in Japan while expanding access to advanced retinal care.
The age-related macular degeneration market in China is driven by the rapid expansion of ophthalmology services and increasing investment in specialized eye care infrastructure across urban and emerging healthcare centers. The country is strengthening its retinal disease management capabilities by establishing dedicated ophthalmology hospitals, expanding retinal specialty departments, and increasing the availability of advanced diagnostic technologies. China is also becoming an important location for ophthalmic clinical research, with domestic biotechnology companies and multinational pharmaceutical manufacturers increasing investments in innovative retinal therapies, including biologics, sustained drug delivery systems, and gene therapies. In addition, government initiatives aimed at improving healthcare accessibility, expanding medical insurance coverage, and modernizing hospital infrastructure are improving patient access to retinal diagnosis and treatment. Growing adoption of artificial intelligence-assisted retinal screening, teleophthalmology platforms, and digital healthcare technologies is further enhancing early detection and long-term management of age-related macular degeneration.
Latin America Age-related Macular Degeneration Market Trends
The age-related macular degeneration market in Latin America is projected to grow steadily during the forecast period, driven by improving access to ophthalmology services, rising awareness of retinal diseases, and the gradual modernization of healthcare systems across the region. The market is benefiting from the expansion of specialized eye care centers, greater availability of retinal imaging technologies, and increasing adoption of anti-VEGF therapies for the management of neovascular AMD. Governments and healthcare providers are investing in initiatives to improve the diagnosis and treatment of age-related vision disorders, particularly in major urban centers where access to specialized ophthalmology services continues to expand. In addition, the growing presence of multinational pharmaceutical companies, increasing participation in international ophthalmology clinical studies, and rising availability of innovative retinal therapies are strengthening the regional market. Continued improvements in healthcare infrastructure, broader medical insurance coverage in several countries, and increasing investment in digital ophthalmology and telemedicine services are expected to further support market growth.
Brazil age-related macular degeneration market is driven by the continuous expansion of ophthalmology services and increasing availability of specialized retinal care in major metropolitan regions. The country has a well-established network of public and private ophthalmology centers that are improving access to retinal diagnostics, intravitreal injection services, and long-term management of chronic retinal diseases. Brazil is also strengthening its position in ophthalmic clinical research, with increasing participation in multinational clinical trials evaluating innovative therapies for retinal disorders. In addition, the growing adoption of optical coherence tomography (OCT), expansion of private health insurance coverage, and rising investment in modern ophthalmic equipment are improving the diagnosis and monitoring of age-related macular degeneration. Collaboration between academic institutions, ophthalmology societies, and healthcare providers is supporting continuing medical education and wider implementation of evidence-based retinal care.
Middle East & Africa Age-related Macular Degeneration Market Trends
The age-related macular degeneration market in MEA is projected to grow steadily during the forecast period, driven by expanding ophthalmology services, improving healthcare infrastructure, and rising awareness of retinal diseases across several countries in the region. The market is benefiting from the establishment of specialized eye hospitals, wider availability of retinal imaging technologies, and growing adoption of anti-VEGF therapies for the treatment of neovascular AMD. Governments are investing in the modernization of healthcare systems and strengthening access to specialized ophthalmic care through national vision health initiatives and public-private partnerships. In addition, increasing healthcare expenditure, expanding private healthcare networks, and improving the availability of trained retinal specialists are supporting earlier diagnosis and long-term disease management. The region is also witnessing greater participation in international ophthalmology clinical research and increasing adoption of digital ophthalmology solutions, including teleophthalmology and artificial intelligence-assisted retinal screening.
Saudi Arabia age-related macular degeneration market is driven by the country's continued investment in healthcare modernization under Vision 2030, with a strong focus on expanding specialized medical services and improving access to advanced ophthalmic care. The country is strengthening its retinal disease management capabilities by expanding tertiary care hospitals, specialized ophthalmology centers, and modern diagnostic facilities equipped with advanced retinal imaging technologies. Increasing collaboration between public healthcare institutions and private providers is improving access to retinal specialists and intravitreal treatment services across major cities. In addition, Saudi Arabia is adopting digital health solutions, including electronic health records, teleophthalmology, and artificial intelligence-assisted retinal screening, to support earlier diagnosis and more efficient patient management. The country is also increasing participation in international clinical research and facilitating the introduction of innovative retinal therapies through an evolving regulatory environment.
Key Age-related Macular Degeneration Company Insights
The market is moderately concentrated, with F. Hoffmann-La Roche Ltd., Regeneron Pharmaceuticals Inc., Bayer AG, and Novartis AG accounting for a significant share of the global market through their established retinal disease portfolios, extensive ophthalmology commercialization networks, and continued investment in next-generation therapies. Roche maintains a strong position with Vabysmo (faricimab), while Regeneron and Bayer continue to strengthen their presence through Eylea (aflibercept) and its high-dose formulation, which supports extended dosing intervals. Novartis remains an important participant through its ophthalmology portfolio and strategic collaborations in retinal diseases. Emerging competition is intensifying as companies develop biosimilars, longer-acting biologics, gene therapies, and sustained drug-delivery technologies. Samsung Bioepis is strengthening its competitive position through biosimilar development, while Amgen Inc. and Biogen have expanded their ophthalmology capabilities through strategic collaborations and pipeline investments. Pfizer Inc. continues to evaluate opportunities in retinal therapeutics through research partnerships and innovation initiatives, whereas Bausch Health Companies Inc. maintains a presence through its ophthalmology business and established relationships with eye care providers. As innovation broadens beyond anti-VEGF therapy toward complement inhibitors, gene therapies, and durable treatment approaches, competition is gradually shifting from established biologics to differentiated technologies that improve long-term disease management.
Key Age-related Macular Degeneration Companies
The following key companies have been profiled for this study on the age-related macular degeneration market:
-
Novartis AG
-
Bayer AG
-
Pfizer Inc.
-
F. Hoffmann-La Roche Ltd
-
Bausch Health Companies Inc.
-
Regeneron Pharmaceuticals Inc.
-
Amgen Inc.
-
Biogen
-
Samsung Bioepis
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Hoffmann-La Roche Ltd.
- Mature players focus on strengthening retinal disease portfolios through lifecycle management, clinical research, long-acting therapies, and strategic collaborations. They invest in manufacturing capacity, regulatory approvals, physician engagement, and geographic expansion to improve treatment access while maintaining their position in the global age-related macular degeneration market.
- Mature companies maintain a competitive advantage through established ophthalmology brands, broad commercial infrastructure, extensive clinical evidence, strong regulatory expertise, and long-standing relationships with ophthalmologists and healthcare providers. Their financial resources, manufacturing capacity, and global distribution networks support consistent product availability and continued investment in retinal disease research.
- Mature players face challenges including high research and development costs, pricing pressure, strict regulatory requirements, increasing competition from biosimilars and emerging retinal therapies, and the need to continuously demonstrate long-term clinical value. Large organizational structures may also slow the adoption of new technologies and limit operational flexibility
Emerging Players: Samsung Bioepis
- Emerging players focus on expanding their ophthalmology presence through biosimilar development, strategic partnerships, pipeline expansion, targeted acquisitions, and investment in innovative retinal therapies. They emphasize cost-efficient manufacturing, clinical development, and technology collaborations to strengthen product portfolios and increase participation in the retinal disease market.
- Emerging players benefit from flexible development strategies, expertise in biologics and biosimilars, efficient manufacturing capabilities, and the ability to introduce competitive alternatives to established therapies. Their focus on innovation, strategic collaborations, and expanding research capabilities supports gradual growth in the AMD market.
- Emerging players often face limited commercial presence in ophthalmology, lower physician familiarity, fewer approved retinal products, and competition from established market leaders. They may also encounter challenges related to regulatory approvals, market access, reimbursement, and building specialized ophthalmology distribution and medical affairs capabilities.
Recent Developments
-
In April 2026, Regeneron Pharmaceuticals Inc. received U.S. FDA approval for an updated EYLEA HD dosing regimen, allowing treatment intervals of up to five months for patients with wet age-related macular degeneration following successful initial therapy.
-
In January 2026, Samsung Bioepis entered into a settlement and license agreement with Regeneron Pharmaceuticals and Bayer AG for SB15, an aflibercept biosimilar. The agreement enabled commercialization in the United Kingdom, across Europe, and in other international markets in accordance with the agreed launch schedule.
-
In January 2026, Samsung Bioepis began the direct commercialization of BYOOVIZ (ranibizumab), a biosimilar to Lucentis, across multiple European countries following the transfer of commercial rights from Biogen. The expansion strengthened the company's ophthalmology portfolio in Europe.
Age-related Macular Degeneration Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.6 billion
Estimated market size in 2026
USD 12.5 billion
Projected market size by 2033
USD 22.7 billion
Growth rate
CAGR of 9.0% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Product, disease, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key company profiled
F. Hoffmann-La Roche Ltd; Novartis AG; Bayer AG; Pfizer Inc.; Bausch Health Companies Inc.; Regeneron Pharmaceuticals Inc.; Amgen Inc.; Biogen; Samsung Bioepis
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Age-related Macular Degeneration Market Report Segmentation
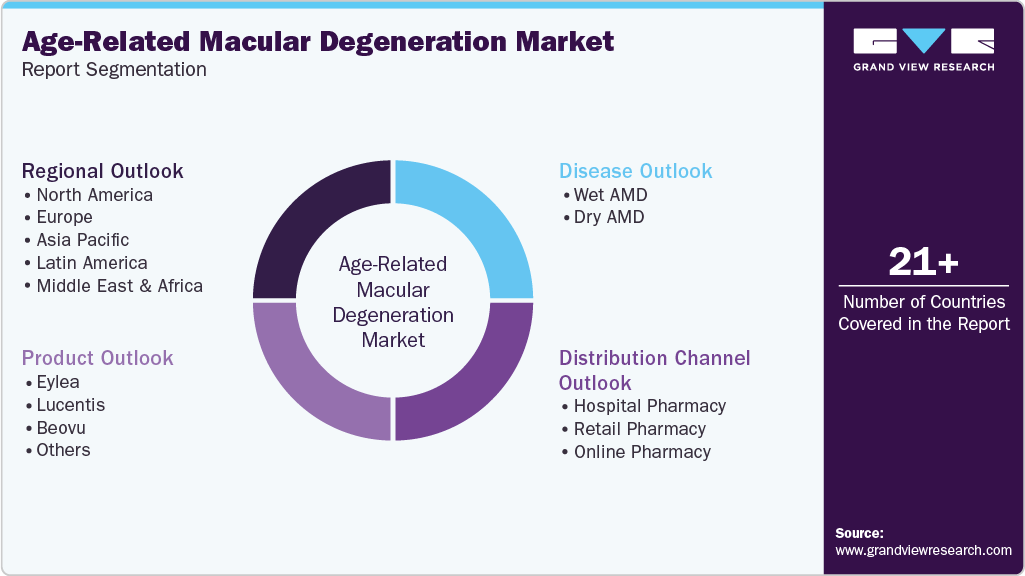
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global Age-related macular degeneration market report based on product, disease, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Eylea
-
Lucentis
-
Beovu
-
Others
-
-
Disease Outlook (Revenue, USD Million, 2021 - 2033)
-
Wet AMD
-
Dry AMD
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacy
-
Retail Pharmacy
-
Online Pharmacy
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The age-related macular degeneration market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each age-related macular degeneration segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Eylea
Covers Eylea (aflibercept), an anti-VEGF therapy approved for the treatment of neovascular (wet) age-related macular degeneration. The segment includes all approved formulations and presentations prescribed for AMD management.
Lucentis
Covers Lucentis (ranibizumab), an anti-VEGF therapy used to manage neovascular (wet) age-related macular degeneration by inhibiting abnormal blood vessel growth and preserving visual function.
Beovu
Covers Beovu (brolucizumab), an anti-VEGF therapy indicated for the treatment of neovascular (wet) age-related macular degeneration. The segment includes all approved product presentations used in routine clinical practice.
Others
Covers all other therapies used for age-related macular degeneration that are not classified under Eylea, Lucentis, or Beovu. This includes complement inhibitors, biosimilars, off-label therapies, and newly introduced products approved for AMD treatment.
Segment - Disease
Revenue capture definition
Wet AMD
Covers therapies indicated for the treatment of neovascular (wet) age-related macular degeneration, a form of AMD characterized by abnormal blood vessel growth beneath the retina that can lead to rapid central vision loss if left untreated.
Dry AMD
Covers therapies indicated for the treatment of dry age-related macular degeneration, including geographic atrophy. The segment includes products intended to slow retinal degeneration, preserve visual function, and manage disease progression.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Covers age-related macular degeneration therapies supplied through hospital pharmacies and ophthalmology centers where products are dispensed and administered under the supervision of healthcare professionals as part of clinical treatment.
Retail Pharmacies
Covers age-related macular degeneration therapies dispensed through licensed retail and community pharmacies based on physician prescriptions. The segment serves patients obtaining approved therapies outside hospital pharmacy settings.
Online Pharmacy
Covers age-related macular degeneration therapies supplied through licensed online pharmacy platforms that dispense approved prescription products and deliver them directly to patients while complying with applicable pharmaceutical regulations.
Estimation Model
 To learn more about this report, Download Free Sample Report
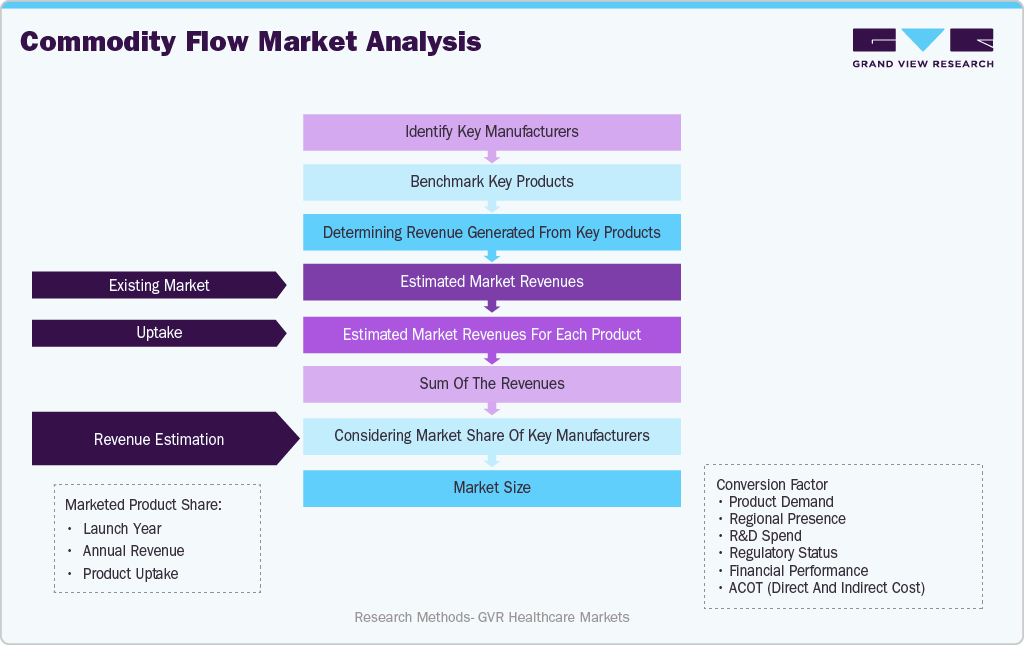
The global market was estimated using a commodity flow model by identifying leading manufacturers of anti-VEGF therapies, complement inhibitors, biosimilars, and other treatments for retinal diseases. Products were benchmarked against company revenues, product sales, pricing, regulatory approvals, geographic availability, and distribution networks, using annual reports, investor presentations, regulatory filings, and company disclosures. Revenue generated by leading AMD therapies was assessed across major regions to estimate the market's commercial value. Product utilization was validated through prescription trends, treatment frequency, patient compliance, and ophthalmology practice patterns. Market estimates were further verified using healthcare expenditure data, pharmaceutical sales databases, published literature, and government sources. Primary interviews with ophthalmologists, retinal specialists, distributors, and industry participants were conducted to validate product adoption, treatment patterns, pricing assumptions, and regional demand, ensuring consistent and reliable market estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Global Age-related Macular Degeneration Treatment Market Opportunity Assessment (U.S., Europe & Asia Pacific)
Conducted a detailed assessment of age-related macular degeneration treatment opportunities across the U.S., Germany, the U.K., Japan, and China. The study evaluated disease prevalence, patient diagnosis rates, treatment adoption, retinal care infrastructure, reimbursement frameworks, pricing trends, and physician prescribing patterns for anti-VEGF therapies, complement inhibitors, and emerging retinal treatments.
Helped the client identify regional growth opportunities, evaluate pricing and reimbursement scenarios, assess treatment adoption trends, and prioritize expansion strategies. The study also supported investment planning by identifying underserved patient populations, evolving treatment practices, and opportunities across established and emerging ophthalmology markets.
AMD Therapeutics Pipeline & Competitive Benchmarking
Delivered a comprehensive benchmarking analysis of approved and pipeline therapies for age-related macular degeneration. The assessment covered clinical development, strategic collaborations, licensing activities, long-acting biologics, gene therapies, complement inhibitors, sustained drug delivery technologies, manufacturing capabilities, intellectual property, and competitive positioning across the global AMD treatment market.
Enabled the client to identify licensing and partnership opportunities, evaluate technology platforms, prioritize research investments, and assess competitive positioning. The analysis also supported product portfolio planning, pipeline expansion strategies, and long-term decision-making in the evolving retinal therapeutics market.
Emerging Market Retinal Care Infrastructure Feasibility Study
Conducted a country-level feasibility assessment for retinal disease diagnosis and treatment infrastructure across Brazil, Saudi Arabia, South Africa, India, and Mexico. The study analyzed retinal imaging availability, ophthalmology workforce, healthcare accessibility, reimbursement systems, regulatory frameworks, and procurement practices supporting AMD diagnosis and treatment services.
Supported market entry planning by identifying regions with improving retinal care infrastructure, unmet diagnostic needs, and treatment access gaps. The study also helped optimize resource allocation, evaluate partnership opportunities, and strengthen long-term expansion strategies in developing ophthalmology markets.
Frequently Asked Questions About This Report
The global age-related macular degeneration market size was valued at USD 11.6 billion in 2025 and is estimated at USD 12.5 billion for 2026.
The global age-related macular degeneration market is expected to grow at a CAGR of 9.0% from 2026 to 2033, reaching USD 22.7 billion by 2033.
The hospital pharmacy segment held the largest 51.3% revenue share in 2025, while specialty pharmacy is projected to be the fastest-growing distribution channel, with a CAGR of 10.1% during the forecast period.
Key players include F. Hoffmann-La Roche Ltd., Regeneron Pharmaceuticals Inc., Bayer AG, Novartis AG, Pfizer Inc., Bausch Health Companies Inc., Amgen Inc., Biogen, and Samsung Bioepis.
The eylea segment led the market with a 42.4% revenue share in 2025, while beovu is projected to be the fastest-growing product segment, registering a CAGR of 19.4% during the forecast period.
The wet AMD segment accounted for the largest 91.0% revenue share in 2025, while dry AMD is expected to be the fastest-growing disease segment, with a CAGR of 25.3% over the forecast period.
Key factors include the growing aging population, increasing prevalence of retinal disorders, wider adoption of anti-VEGF therapies, expansion of complement inhibitors for geographic atrophy, advancements in retinal imaging technologies such as OCT, and ongoing development of long-acting biologics, gene therapies, and sustained drug delivery systems.
North America dominated the global age-related macular degeneration market with a 53.9% revenue share in 2025.
Asia Pacific is projected to be the fastest-growing regional market, expanding at a CAGR of 10.5% during the forecast period.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


