
- Home
- »
- Medical Devices
- »
-
Minimally Invasive Glaucoma Surgery Devices Market Size Report, 2033GVR Report cover

Minimally Invasive Glaucoma Surgery (MIGS) Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Valves, Glaucoma Drainage Implant), By Surgery Method, By End-use (Hospitals, Ophthalmic Clinics), By Region, And Segment Forecast
Market Size, 2025
$603.4MMarket Estimate, 2026
$635.3MMarket Forecast, 2033
$912.0MCAGR, 2026–2033
5.3%Minimally Invasive Glaucoma Surgery Market Summary
The global minimally invasive glaucoma surgery (MIGS) devices market size was valued at USD 603.4 million in 2025 and is projected to grow from USD 635.3 million in 2026 to USD 912.0 million in 2033, at a CAGR of 5.3% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of approximately 36.0% in 2025. The growing awareness of minimally invasive surgery, technological advancements, an aging population, and expanding healthcare infrastructure are the major factors driving market growth.
Key Market Trends & Insights
- By end-use: The hospitals segment held the largest market share of around 40.0% in 2025.
- By product: The glaucoma drainage implant segment held the largest market share of 33.0% in 2025.
- By surgery method: The trabecular meshwork bypass segment held the largest share of 35.0% in 2025.
Regional Highlights
- Largest regional market: North America (Approximately 36.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 603.4 Million
- Estimated market size in 2026: USD 635.3 Million
- Projected market size by 2033: USD 912.0 Million
- CAGR (2026-2033): 5.3%
Prism AI by Grand View Research Free to tryAsk a question about the minimally invasive glaucoma surgery (MIGS) devices marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The market is primarily driven by the rising global prevalence of glaucoma, increasing preference for minimally invasive ophthalmic procedures, and continuous advancements in glaucoma treatment technologies. MIGS procedures have gained widespread acceptance among ophthalmologists owing to their ability to reduce intraocular pressure while minimizing surgical trauma, shortening recovery time, and lowering the risk of postoperative complications compared with conventional glaucoma surgeries. According to the Bright Focus Foundation, approximately 80 million people worldwide are living with glaucoma, with the number expected to reach 111 million by 2040, highlighting the growing need for effective long-term glaucoma management.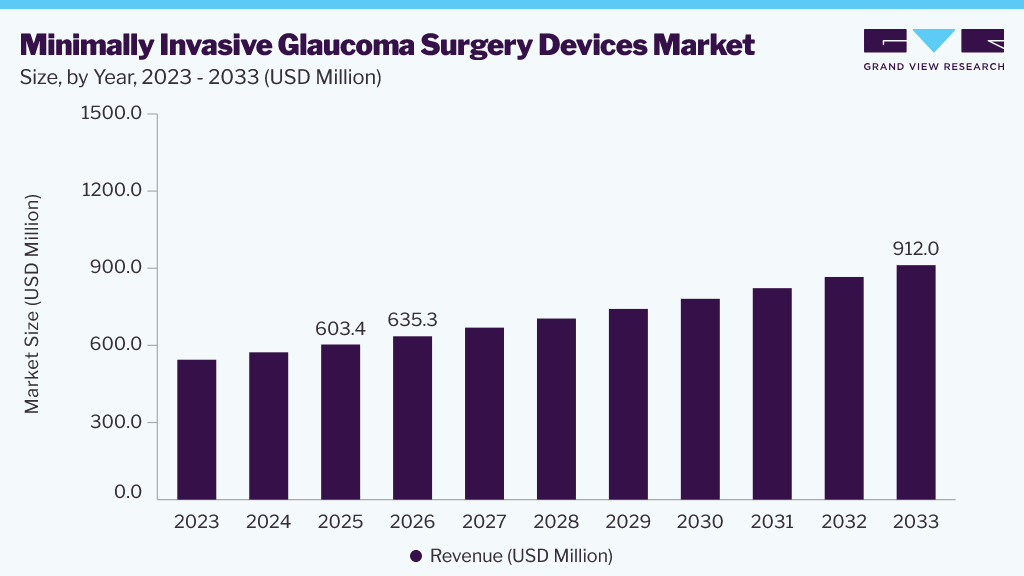 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Growing adoption of early glaucoma diagnosis, expanding access to specialized ophthalmic care, and increasing healthcare expenditure are further supporting market growth. Manufacturers continue to invest in next-generation implantable devices and laser-based technologies that improve procedural precision, clinical outcomes, and physician workflow. For instance, in February 2025, Alcon announced the U.S. commercial launch of Voyager DSLT, the first Direct Selective Laser Trabeculoplasty (DSLT) device. The launch expanded the company's glaucoma treatment portfolio and supported broader adoption of minimally invasive glaucoma therapies by improving access to advanced laser-based treatment.
Analyst Perspective
The increasing adoption of minimally invasive glaucoma surgery is changing the treatment approach for patients with mild-to-moderate glaucoma by providing safer alternatives to conventional surgical procedures. Manufacturers are focusing on developing advanced implants and laser-based technologies that improve intraocular pressure control while reducing postoperative complications and recovery time. Growing clinical acceptance, expanding surgeon experience, and continued product approvals are supporting wider commercialization of MIGS devices across developed markets. At the same time, improving ophthalmic infrastructure and increasing investments in specialized eye care are creating new opportunities in emerging economies. Continued innovation and expanding clinical evidence are expected to support long-term market growth.
End-use Insights
The hospitals segment held the largest market share of around 40.0% in 2025. Hospitals remain the primary setting for minimally invasive glaucoma surgery (MIGS) procedures owing to the availability of experienced ophthalmic surgeons, advanced surgical infrastructure, and comprehensive perioperative care. These facilities manage a large volume of glaucoma patients requiring surgical intervention while providing access to integrated diagnostic imaging, operating rooms, and postoperative monitoring. In addition, favorable reimbursement for hospital-based ophthalmic procedures and the ability to manage complex glaucoma cases continue to support segment dominance.
The ophthalmic clinics segment is expected to register the fastest CAGR during the forecast period. Growing preference for outpatient glaucoma treatment, shorter procedure times, and lower treatment costs are driving the expansion of specialized ophthalmic clinics. Increasing adoption of minimally invasive glaucoma procedures that require limited postoperative recovery has enabled more surgeries to be performed outside hospital settings. In addition, manufacturers are expanding commercialization across specialty eye care facilities. For instance, in September 2025, Glaukos Corporation announced the U.S. commercial launch of iDose TR, with adoption expanding across ophthalmology practices and ambulatory surgery centers (ASCs). The broader availability of the intracameral implant in outpatient settings supports greater access to minimally invasive glaucoma treatment and reflects the growing role of specialized ophthalmic centers in glaucoma care.
Product Insights
The glaucoma drainage implant devices segment held the largest market share of around 33.0% in 2025. The segment is driven by the widespread use of drainage implants for patients with moderate-to-severe glaucoma who require sustained intraocular pressure reduction when medications or laser therapies provide inadequate disease control. These devices offer long-term pressure management and are widely adopted in complex glaucoma cases because of their established clinical outcomes and broad acceptance among ophthalmic surgeons. Continuous improvements in implant design and surgical techniques are further supporting segment growth.
The stent segment is expected to register the fastest CAGR during the forecast period. Rising adoption of micro-invasive glaucoma surgery (MIGS), increasing preference for tissue-sparing procedures, and continuous innovation in micro-stent technologies are driving segment growth. Glaucoma stents enable effective intraocular pressure reduction through minimally invasive implantation while preserving ocular tissue and shortening patient recovery time. For instance, in June 2025, Glaukos obtained European Union Medical Device Regulation (EU MDR) certification for its iStent infinite and iStent inject W devices. The approval enables the company to expand the commercialization of its micro-invasive glaucoma surgery (MIGS) stent portfolio across European markets while improving access to minimally invasive glaucoma treatment.
Surgery Method Insights
The trabecular meshwork bypass segment accounted for the largest revenue share, at around 35.0%, in 2025. The segment is driven by the widespread adoption of trabecular bypass procedures as a first-line MIGS approach for patients with mild-to-moderate glaucoma. These procedures effectively lower intraocular pressure by improving aqueous humor outflow through the eye's natural drainage pathway while minimizing tissue disruption and postoperative complications. Growing surgeon familiarity, favorable clinical outcomes, and increasing use of trabecular bypass stents during cataract surgery continue to support segment growth.
The Schlemm's canal implant segment is expected to register the fastest CAGR during the forecast period. Growing clinical preference for procedures that restore the eye's physiological drainage pathway while minimizing surgical trauma is driving adoption of Schlemm's canal implant technologies. Continuous innovation in implant design, increasing clinical evidence supporting long-term intraocular pressure reduction, and expanding regulatory approvals are encouraging wider use of these devices across ophthalmic practices. Rising demand for minimally invasive glaucoma treatment with improved safety and faster patient recovery is expected to further support segment growth.
Regional Insights
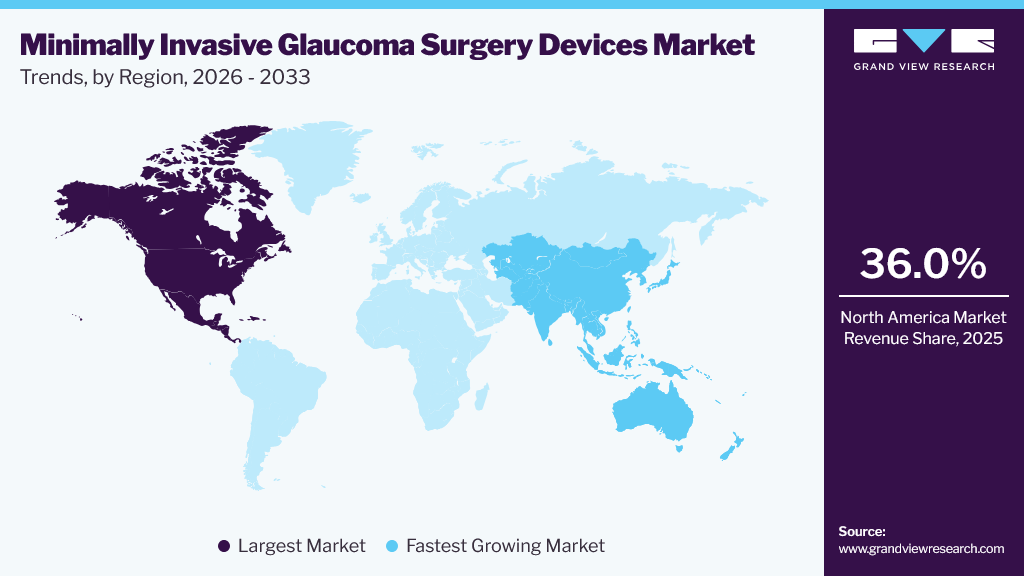
North America dominated the global minimally invasive glaucoma surgery (MIGS) devices market, accounting for approximately 36.0% of revenue in 2025. The region's leadership is supported by the high prevalence of glaucoma, strong adoption of minimally invasive ophthalmic procedures, advanced healthcare infrastructure, and favorable reimbursement policies. The presence of leading ophthalmic device manufacturers, increasing surgeon experience with MIGS procedures, and continuous product commercialization further support market growth. In addition, growing investments in glaucoma diagnosis and early surgical intervention continue to strengthen demand for advanced MIGS devices across hospitals and specialty eye care centers.
 To learn more about this report, Download Free Sample Report
U.S. Minimally Invasive Glaucoma Surgery Devices Market Trends
The U.S. accounted for the largest share of the North American market in 2025. Growth is driven by widespread adoption of minimally invasive glaucoma procedures, favorable reimbursement coverage, and strong availability of specialized ophthalmologists. Continuous regulatory approvals and commercialization of innovative glaucoma treatment technologies are further supporting market expansion, while increasing glaucoma screening programs and an aging population continue to expand the patient pool requiring surgical intervention.
Asia Pacific Minimally Invasive Glaucoma Surgery Devices Market Trends
Asia Pacific is expected to register the fastest CAGR during the forecast period. Rising glaucoma prevalence, rapid expansion of ophthalmic healthcare infrastructure, increasing healthcare expenditure, and growing awareness of early glaucoma diagnosis are driving regional market growth. Expanding access to specialized eye care services and increasing adoption of advanced minimally invasive ophthalmic procedures across countries such as China, India, Japan, and South Korea are further supporting demand for MIGS devices.
The China minimally invasive glaucoma surgery (MIGS) device market accounted for a significant share of the Asia Pacific market in 2025. The country's large glaucoma patient population, improving ophthalmic care infrastructure, and supportive regulatory environment continue to strengthen market growth. In 2025, China's National Medical Products Administration (NMPA) introduced measures to improve the quality and efficiency of medical device review and approval, including priority review pathways for innovative implantable medical devices and streamlined clinical evaluation processes. These reforms are expected to accelerate the commercialization of advanced ophthalmic devices, including minimally invasive glaucoma surgery technologies.
Key Minimally Invasive Glaucoma Surgery Devices Company Insights
The minimally invasive glaucoma surgery (MIGS) devices market is moderately consolidated, with leading companies focusing on product innovation, regulatory approvals, strategic acquisitions, clinical evidence generation, and geographic expansion to strengthen their ophthalmic portfolios and increase adoption of minimally invasive glaucoma treatment technologies across global healthcare markets.
Key Minimally Invasive Glaucoma Surgery Devices Companies
The following key companies have been profiled for this study on the minimally invasive glaucoma surgery (MIGS) devices market:
-
Alcon, Inc.
-
Glaukos Corporation.
-
Johnson & Johnson Vision
-
AbbVie Inc. (Allergan Plc.)
-
Corza Ophthalmology
-
Carl Zeiss Meditec AG
-
Lumenis Ltd
-
Ziemer Ophthalmic Systems AG
-
Iridex Corporation
Recent Developments
- In July 2024, Bausch + Lomb announced the acquisition of Elios Vision to expand its minimally invasive glaucoma surgery (MIGS) portfolio with the Elios procedure for open-angle glaucoma. The acquisition strengthened the company's surgical glaucoma portfolio and expanded its presence in the rapidly growing MIGS market.
Minimally Invasive Glaucoma Surgery Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 603.4 million
Estimated market size in 2026
USD 635.3 million
Projected market size by 2033
USD 912.0 million
Growth rate
CAGR of 5.3% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
End-use, product, surgery method, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; South Korea; Thailand; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Alcon, Inc.; Glaukos Corporation.; Johnson & Johnson Vision; AbbVie Inc. (Allergan Plc.); Corza Ophthalmology; Carl Zeiss Meditec AG; Lumenis Ltd; Ziemer Ophthalmic Systems AG; Iridex Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Minimally Invasive Glaucoma Surgery Devices Market Report Segmentation
This report forecasts revenue growth and provides an analysis on the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global minimally invasive glaucoma surgery (MIGS) devices market report based on product, surgery method, end-use, and region:
- Product Outlook (Revenue, USD Million, 2021 - 2033)
- Valves
- Glaucoma Drainage Implant
- Glaucoma Tube Shunts
- Stents
- Others
- Surgery Method Outlook (Revenue, USD Million, 2021 - 2033)
- Trabecular Meshwork Bypass
- By Stent Placement
- By Tissue Excision
- Suprachoroidal Space Implants
- Subconjunctival Space Implants
- Schlemm’s Canal Implants
- Gonioscopy-assisted Transluminal Trabeculectomy
- Endocyclophotocoagulation
- Trabecular Meshwork Bypass
- End-use Outlook (Revenue, USD Million, 2021 - 2033)
- Hospitals
- Ophthalmic Clinics
- Others Surgical Centers
- Regional Outlook (Revenue, USD Million, 2021 - 2033)
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Norway
- Denmark
- Sweden
- Asia Pacific
- Japan
- China
- India
- Australia
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa (MEA)
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
Frequently Asked Questions About This Report
Key players in the market include Alcon, Inc.; Glaukos Corporation.; Johnson & Johnson Vision; AbbVie Inc. (Allergan Plc.); Corza Ophthalmology; Carl Zeiss Meditec AG; Lumenis Ltd; Ziemer Ophthalmic Systems AG; Iridex Corporation., and others.
The global minimally invasive glaucoma surgery (MIGS) devices market is expected to grow at a CAGR of 5.3% from 2026 to 2033, reaching USD 912.0 million.
North America dominated with an approximately 36.0% revenue share in 2025.
The global minimally invasive glaucoma surgery (MIGS) devices market size was valued at USD 603.4 million in 2025 and is estimated at USD 635.3 million for 2026.
The hospitals segment in the minimally invasive glaucoma surgery (MIGS) devices segment accounted for the largest revenue share of around 40.0% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


