
- Home
- »
- Medical Devices
- »
-
Retinal Implants Market Size And Share Report, 2026-2033GVR Report cover

Retinal Implants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Retina Implant Alpha AMS, Implantable Miniature), By End Use (Hospitals, Outpatient Facilities), By Region, And Segment Forecasts
Market Size, 2025
$56.3MMarket Estimate, 2026
$61.0MMarket Forecast, 2033
$107.6MCAGR, 2026–2033
8.4%Retinal Implants Market Summary
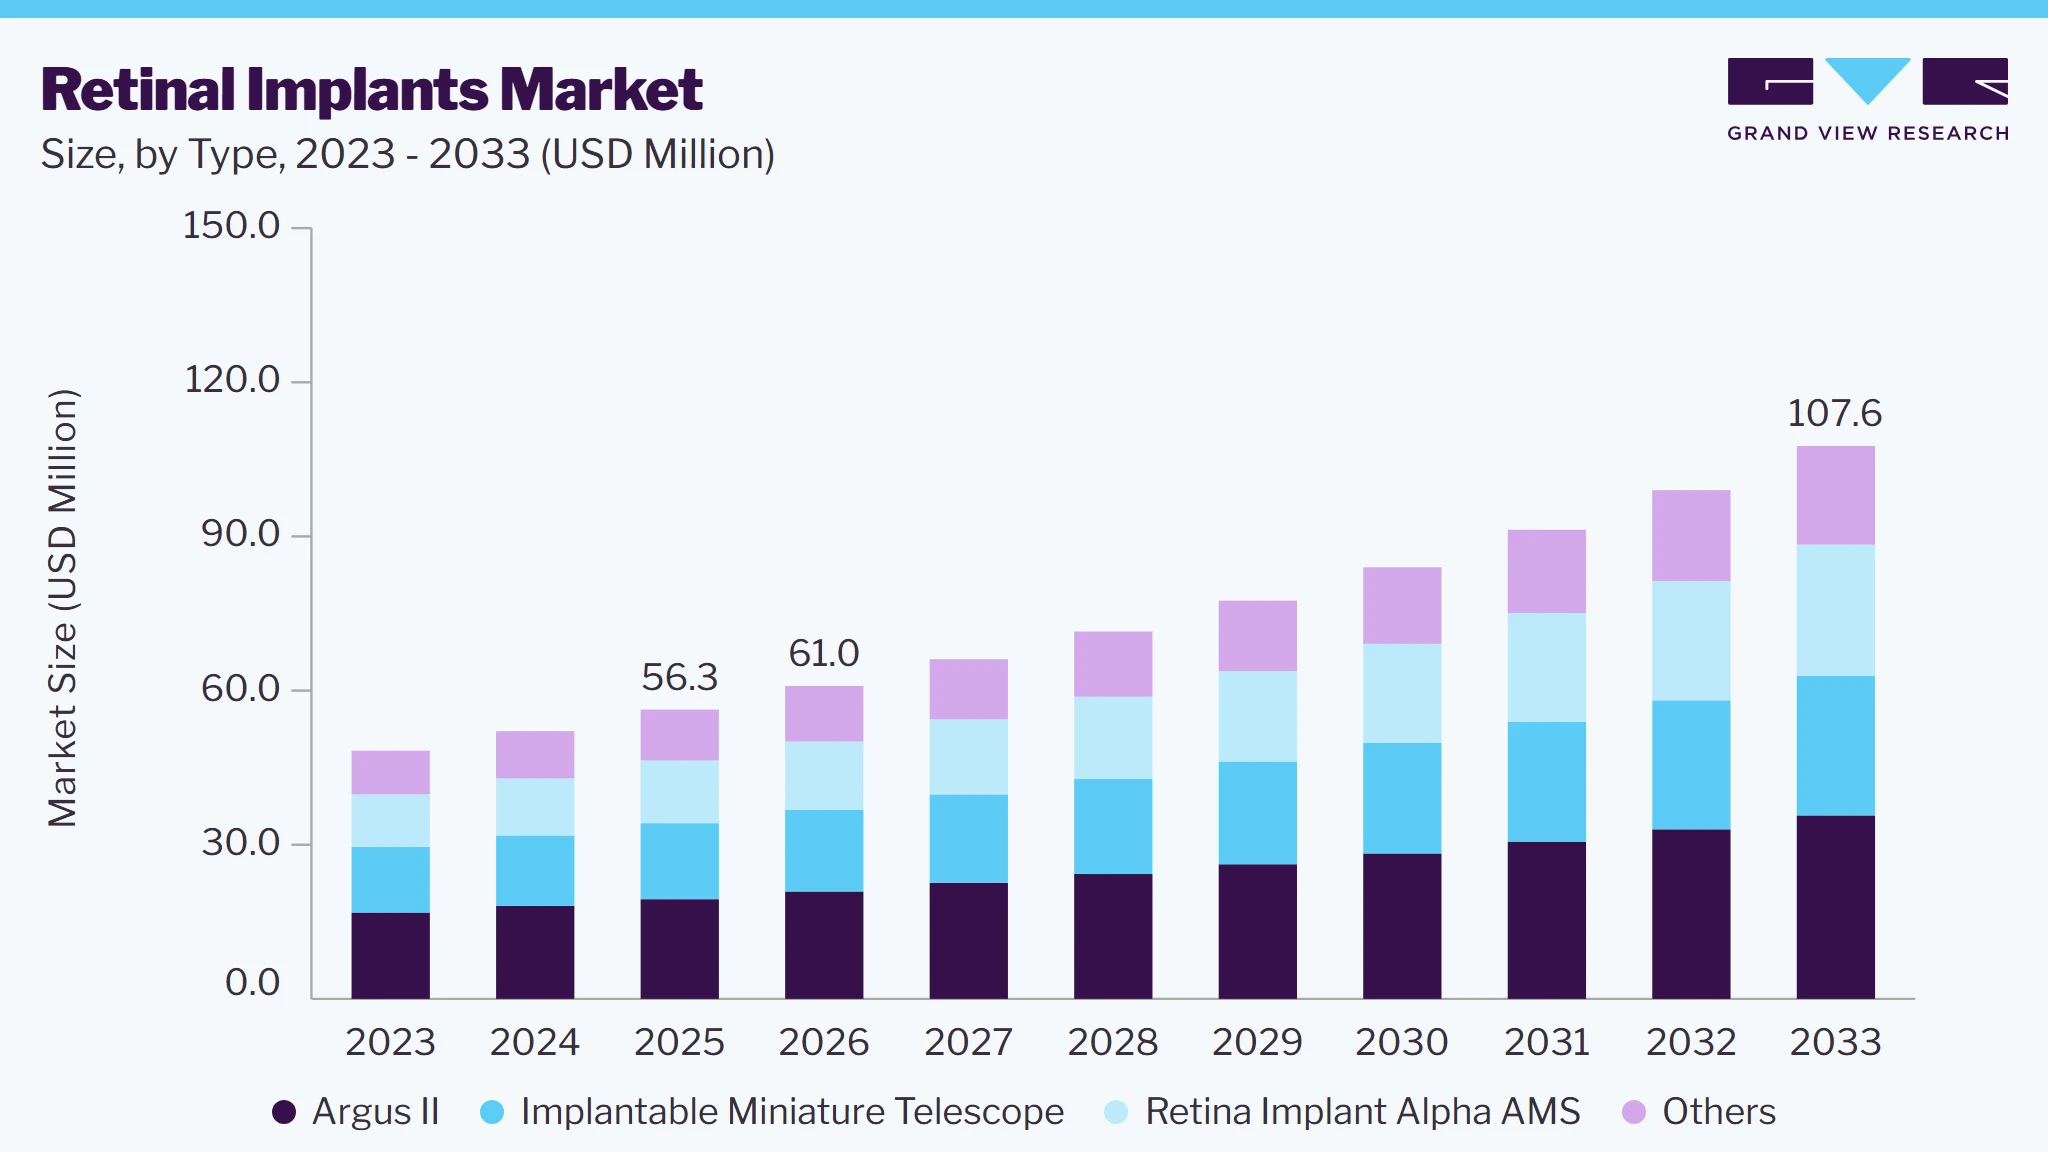
The global retinal implants market size was valued at USD 56.3 million in 2025 and is projected to grow from USD 61.0 million in 2026 to USD 107.6 million by 2033, at a CAGR of 8.4% from 2026 to 2033. North America dominated the retinal implants market with the largest revenue share of 37.4% in 2025. The ability to restore vision, the growing senior population, and the increasing prevalence of target illnesses are driving the demand for retinal implants.
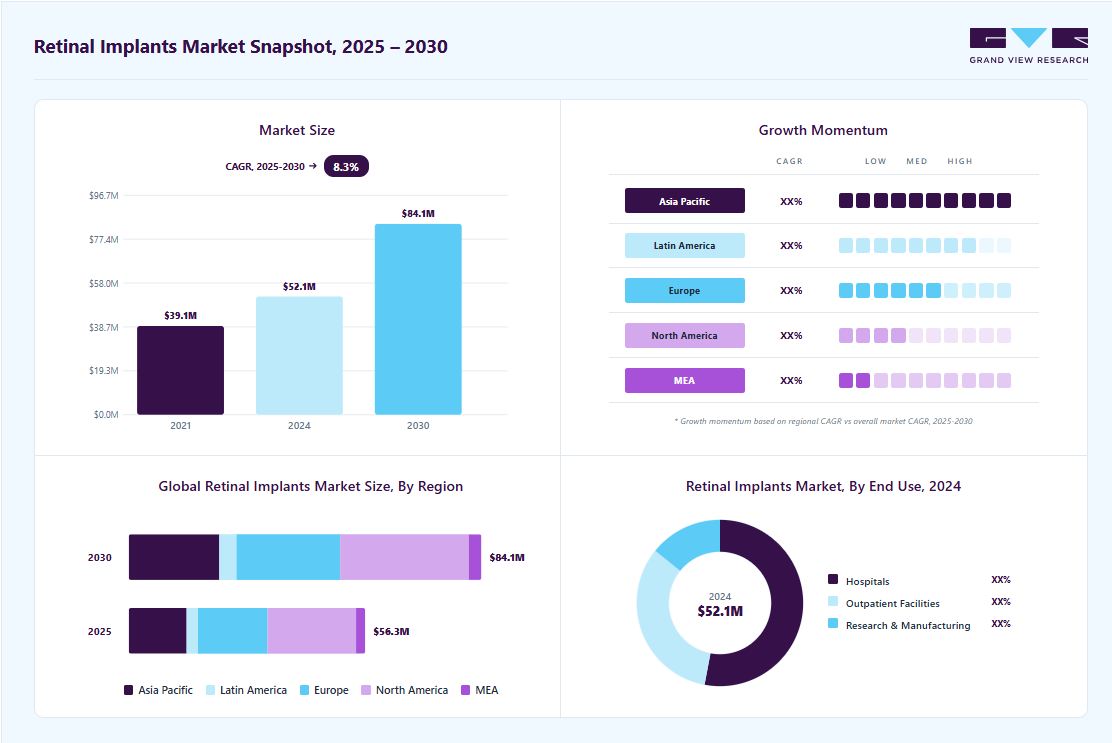 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Argus II segment held the largest market share of 34.5% in 2025.
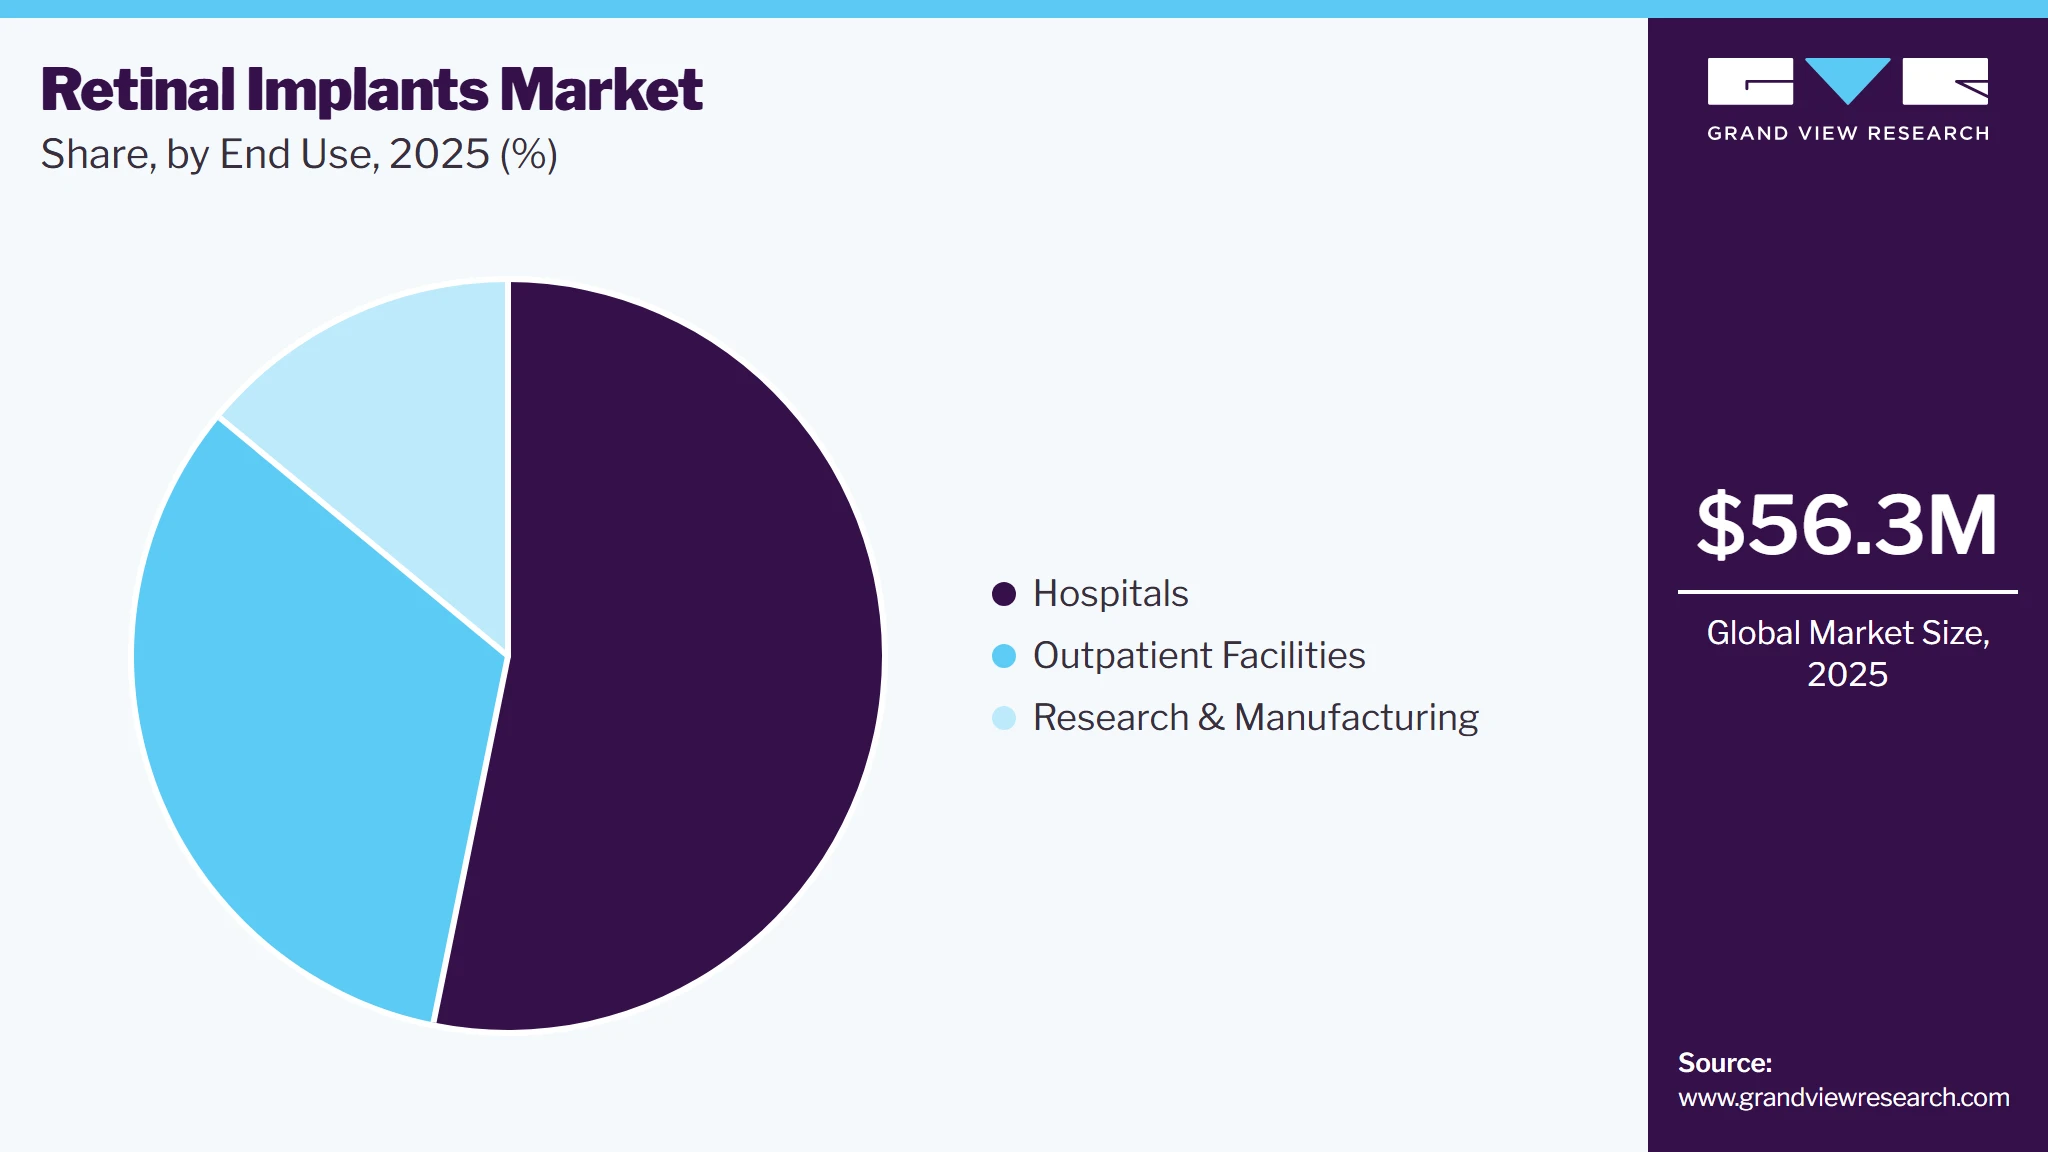
- By end use: Hospitals segment held the largest market share of 53.2% in 2025.
Regional Highlights
- Largest regional market: North America (37.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 56.3 Million
- Estimated market size in 2026: USD 61.0 Million
- Projected market size by 2033: USD 107.6 Million
- CAGR (2026-2033): 8.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is expanding owing to the rising frequency of retinal disorders worldwide. Blindness or loss of vision may result from many illnesses. Age-related macular degeneration (AMD), diabetic retinopathy, and retinitis pigmentosa are some of the most prevalent retinal disorders.
Retinitis pigmentosa (RP) remains one of the most debilitating retinal diseases, with no effective treatment currently available. RP is an inherited disorder that gradually destroys photoreceptor cells in the retina, ultimately leading to blindness. Around two million people worldwide are affected by RP, with no cure on the horizon. However, groundbreaking research from Johns Hopkins University in February 2024 may provide a solution. Researchers developed a biocompatible nanocomposite material that, when used in retinal implants and activated by laser illumination, has shown potential to acoustically stimulate cells in the damaged retina, sending signals to the brain's visual cortex. This material, containing palladium nanoparticles, converts light into sound waves, effectively stimulating retinal cells to restore some level of vision. The discovery represents a significant step forward in retinal implant technology, with the potential to change the course of treatment for RP patients.
 To learn more about this report, Download Free Sample Report
In addition to RP, diabetic retinopathy (DR) is another major contributor to the growing demand for retinal implants. Diabetic retinopathy is a microvascular complication of diabetes that can cause vision impairment or blindness if left untreated. According to the World Health Organization, DR accounts for approximately 4.8% of the 37 million blindness cases worldwide. In the United States, an estimated 4.1 million adults aged 40 and older have diabetic retinopathy, with nearly 900,000 individuals suffering from vision-threatening DR. The prevalence of DR is expected to rise significantly, particularly with the growing number of diabetic patients globally. By 2030, over 11 million people in the U.S. are expected to be affected by diabetic retinopathy, contributing to a substantial market for retinal implants that can mitigate the vision loss caused by this condition.
The global diabetic population is projected to reach 700 million by 2045, highlighting the scale of the problem. As the number of individuals at risk for diabetic retinopathy increases, so does the need for retinal implants and advanced treatment options. Diabetic retinopathy is the leading cause of blindness among adults with diabetes, and retinal implants may offer a critical solution to prevent vision loss in these individuals.
The advancements in retinal implant technology, particularly in terms of biocompatible materials and light-activated treatments, are crucial in addressing the growing demand for vision restoration. Furthermore, the integration of retinal implants with emerging technologies such as AI and machine learning will further enhance diagnostic accuracy and treatment effectiveness.
Market Dynamics
The retinal implants market is gaining significant traction within the field of advanced vision restoration technologies as it enables ophthalmologists, vitreoretinal surgeons, and neuro-ophthalmology specialists to provide partial visual rehabilitation for patients with severe vision loss caused by degenerative retinal disorders such as advanced retinitis pigmentosa and certain forms of inherited retinal dystrophies. These innovative implantable systems integrate sophisticated technologies including epiretinal or subretinal microelectrode arrays, implantable microchips, wireless power and data transmission, external camera-based visual processing units, and neurostimulation interfaces that electrically activate surviving retinal neurons to generate visual perception. Emerging next-generation retinal prostheses are further incorporating higher-density electrode arrays, biocompatible flexible materials, artificial intelligence (AI)-enabled image processing, and wireless communication platforms to improve image resolution, object recognition, contrast sensitivity, and overall functional vision. By restoring a degree of visual function in individuals with profound blindness, retinal impact technologies address the substantial unmet clinical need associated with irreversible retinal degeneration. They enhance patient independence, support orientation and mobility, facilitate daily living activities, and represent a major advancement in the convergence of ophthalmology, neuroengineering, and implantable medical device innovation.
The increasing prevalence of retinal degenerative diseases, particularly retinitis pigmentosa, age-related macular degeneration, and other inherited retinal dystrophies, is a major driver fueling growth of the global retinal implants market. As populations age and genetic retinal disorders continue to be diagnosed more frequently through advances in molecular testing, the number of individuals experiencing irreversible vision loss is steadily increasing. Millions of people worldwide suffer from retinal degenerative conditions that progressively destroy photoreceptor cells while leaving portions of the inner retinal neural network relatively intact, creating an opportunity for retinal prosthetic technologies to restore partial visual perception. Conventional treatment options provide limited benefit for patients with end-stage retinal degeneration, resulting in a significant unmet clinical need for innovative vision restoration therapies. Consequently, research institutions, medical manufacturers, and healthcare providers are increasingly investing in next-generation retinal implant systems featuring higher-density microelectrode arrays, wireless power transmission, miniaturized implant electronics, biocompatible flexible materials, and artificial intelligence (AI)-enabled image processing to improve visual outcomes and patient quality of life. The growing clinical demand for effective solutions that can restore functional vision and enhance patient independence is expected to accelerate the adoption of retinal implant technologies over the forecast period.
The growth of the retinal implants market is restrained by the complexity of surgical implantation procedures and the relatively limited pool of eligible patients. Retinal implantation requires highly specialized vitreoretinal surgery involving precise placement of epiretinal or subretinal electrode arrays, often performed only at advanced ophthalmic centers by experienced retinal surgeons. The procedures are technically demanding, require extensive preoperative assessment and postoperative rehabilitation, and may involve prolonged patient training to interpret artificial visual signals. Furthermore, retinal implants are generally suitable only for carefully selected patients with advanced retinal degenerative diseases who retain functional inner retinal neurons and an intact optic nerve, substantially limiting the addressable patient population. The high procedural costs, limited availability of specialized surgical expertise, and the need for multidisciplinary follow-up further restrict widespread clinical adoption, particularly in low- and middle-income countries. These factors continue to present significant barriers to the commercial expansion of retinal implants technologies despite ongoing advances in device design and neurostimulation capabilities.
Market Concentration & Characteristics
The retinal implants industry is characterized by rapid technological advancements and increasing demand due to rising cases of retinal diseases like retinitis pigmentosa and diabetic retinopathy. Key players are focusing on developing biocompatible, light-responsive materials and advanced retinal prosthetics. High research and development investments drive innovation, particularly in areas such as nanocomposite materials, AI integration, and gene therapy. The market is highly concentrated, with prominent players like Nidek Co., Ltd. and Pixium Vision leading the way. Regulatory approval, clinical trials, and cost-effectiveness remain crucial factors influencing market growth and widespread adoption, and increasing diabetic populations further fuel demand for vision restoration solutions.
The degree of innovation in the retinal implants industry is significant, driven by advancements aimed at improving patient comfort, safety, and ease of use. For instance, in July 2021, recent studies in Nature and Scientific American highlighted the development of an artificial eye featuring compact light-sensing nanowires, offering a promising breakthrough. Though these nanowires could be densely packed compared to natural photoreceptor cells, connecting the artificial eye to the optic nerve or directly to the brain's visual cortex will require years of further research.
 To learn more about this report, Download Free Sample Report
Regulations in the retinal implants industry play a crucial role in ensuring patient safety and the effectiveness of devices. Regulatory bodies like the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) establish stringent guidelines for clinical trials, product approval, and post-market surveillance. These regulations ensure that retinal implants, such as bionic eyes and retinal prosthetics, meet high standards for quality, safety, and performance. However, the evolving nature of this technology requires continuous updates to regulations, especially as innovations, such as advanced materials and nanotechnology, emerge. Regulatory hurdles can delay market entry, but they protect patient health.
Mergers and acquisitions (M&A) in the retinal implants industry have been growing as companies seek to expand their technological capabilities, product portfolios, and market presence. In April 2024, Science Corporation, a brain-computer interface company, acquired the intellectual property and assets related to Pixium Vision's Prima retinal implant. Founded by Neuralink co-founder Max Hodak, Science focuses on visual prosthetics for conditions like retinitis pigmentosa (RP) and dry age-related macular degeneration (AMD). The Prima System, already FDA breakthrough device-designated, uses a photovoltaic substitute for photoreceptors. Such strategic moves enable companies to improve operational efficiency and accelerate innovation, further driving competition and growth within the industry.
In the retinal implants industry, product substitutes are emerging in the form of non-invasive therapies, such as gene therapy, stem cell treatments, and retinal prosthetics. Gene therapies aim to restore retinal function by introducing genetic material into the retina, while stem cell treatments focus on regenerating damaged retinal cells. In addition, visual aids like wearable devices and smart glasses, which enhance vision for those with retinal degeneration, serve as alternatives to implants. These substitutes offer potential benefits, such as lower risk and broader patient applicability, although retinal implants remain a leading option for restoring sight in advanced cases of blindness.
The retinal implants industry is seeing substantial regional expansion, driven by advancements in medical technology and increasing healthcare investments. In North America, particularly the U.S., regulatory approvals and research funding are fueling growth, while Europe is witnessing the adoption of retinal implants through collaborations and clinical trials. In Asia-Pacific, countries like Japan and China are experiencing rising demand due to the aging population and increasing prevalence of retinal diseases. In addition, regions in the Middle East and Latin America are developing healthcare infrastructure, expanding access to advanced retinal treatments, thus enhancing the global reach.
Analyst Perspective
The retinal implants market is being driven by the increasing prevalence of retinal degenerative diseases and growing demand for vision restoration therapies. Conditions such as retinitis pigmentosa (RP), age-related macular degeneration (AMD), and inherited retinal dystrophies are creating demand for advanced treatment options capable of restoring functional vision. Retinal implant systems are increasingly being adopted for vision rehabilitation and improved quality of life. Innovations in AI-enabled image processing, wireless technologies, biocompatible materials, and minimally invasive surgical techniques are enhancing device performance and clinical outcomes. Growing investments in neurostimulation technologies, clinical research, favorable regulatory support, and industry collaborations are expected to accelerate the adoption of next-generation retinal implant technologies.
Type Insights
Based on type, the Argus II segment led the market with the largest revenue share of 34.5% in 2025. Based on the device type, the market is segmented into retina implant alpha AMS, implantable miniature telescope, Argus II, and others. The Argus II segment accounted for the largest revenue share of around 34.7% in 2024. The primary purpose of the epiretinal implant Argus II is to treat retinitis pigmentosa. A highly prevalent condition affecting the retina is retinal pigments. As per the National Institute of Health in Europe and the U.S., one out of every 4,000 to 4,500 persons suffer from this eye disorder.
The retina implant alpha AMS segment is expected to grow at the fastest CAGR during the forecast period. The high prevalence of AMD, a leading cause of blindness in older adults, creates a substantial patient pool seeking treatments such as IMTs. Ongoing technological advancements in IMT design and functionality can make these devices more effective and attractive to patients and healthcare providers.
End Use Insights
Based on end use, the hospitals segment led the market with the largest revenue share of 53.2% in 2025. The hospitals segment accounted for the largest revenue share of over 53.0% in 2024. This leadership is attributed to the availability of advanced surgical infrastructure and specialized ophthalmic care in hospitals, enabling successful implantation procedures. Hospitals are also preferred for their multidisciplinary expertise, ensuring comprehensive preoperative and postoperative care.
 To learn more about this report, Download Free Sample Report
The hospitals segment is expected to grow at the fastest CAGR during the forecast period. There is a rise in the number of independent eye hospitals across the globe. This trend is expected to continue during the forecast period owing to the availability of specialists, cost efficiency, and technologically advanced equipment.
Regional Insights
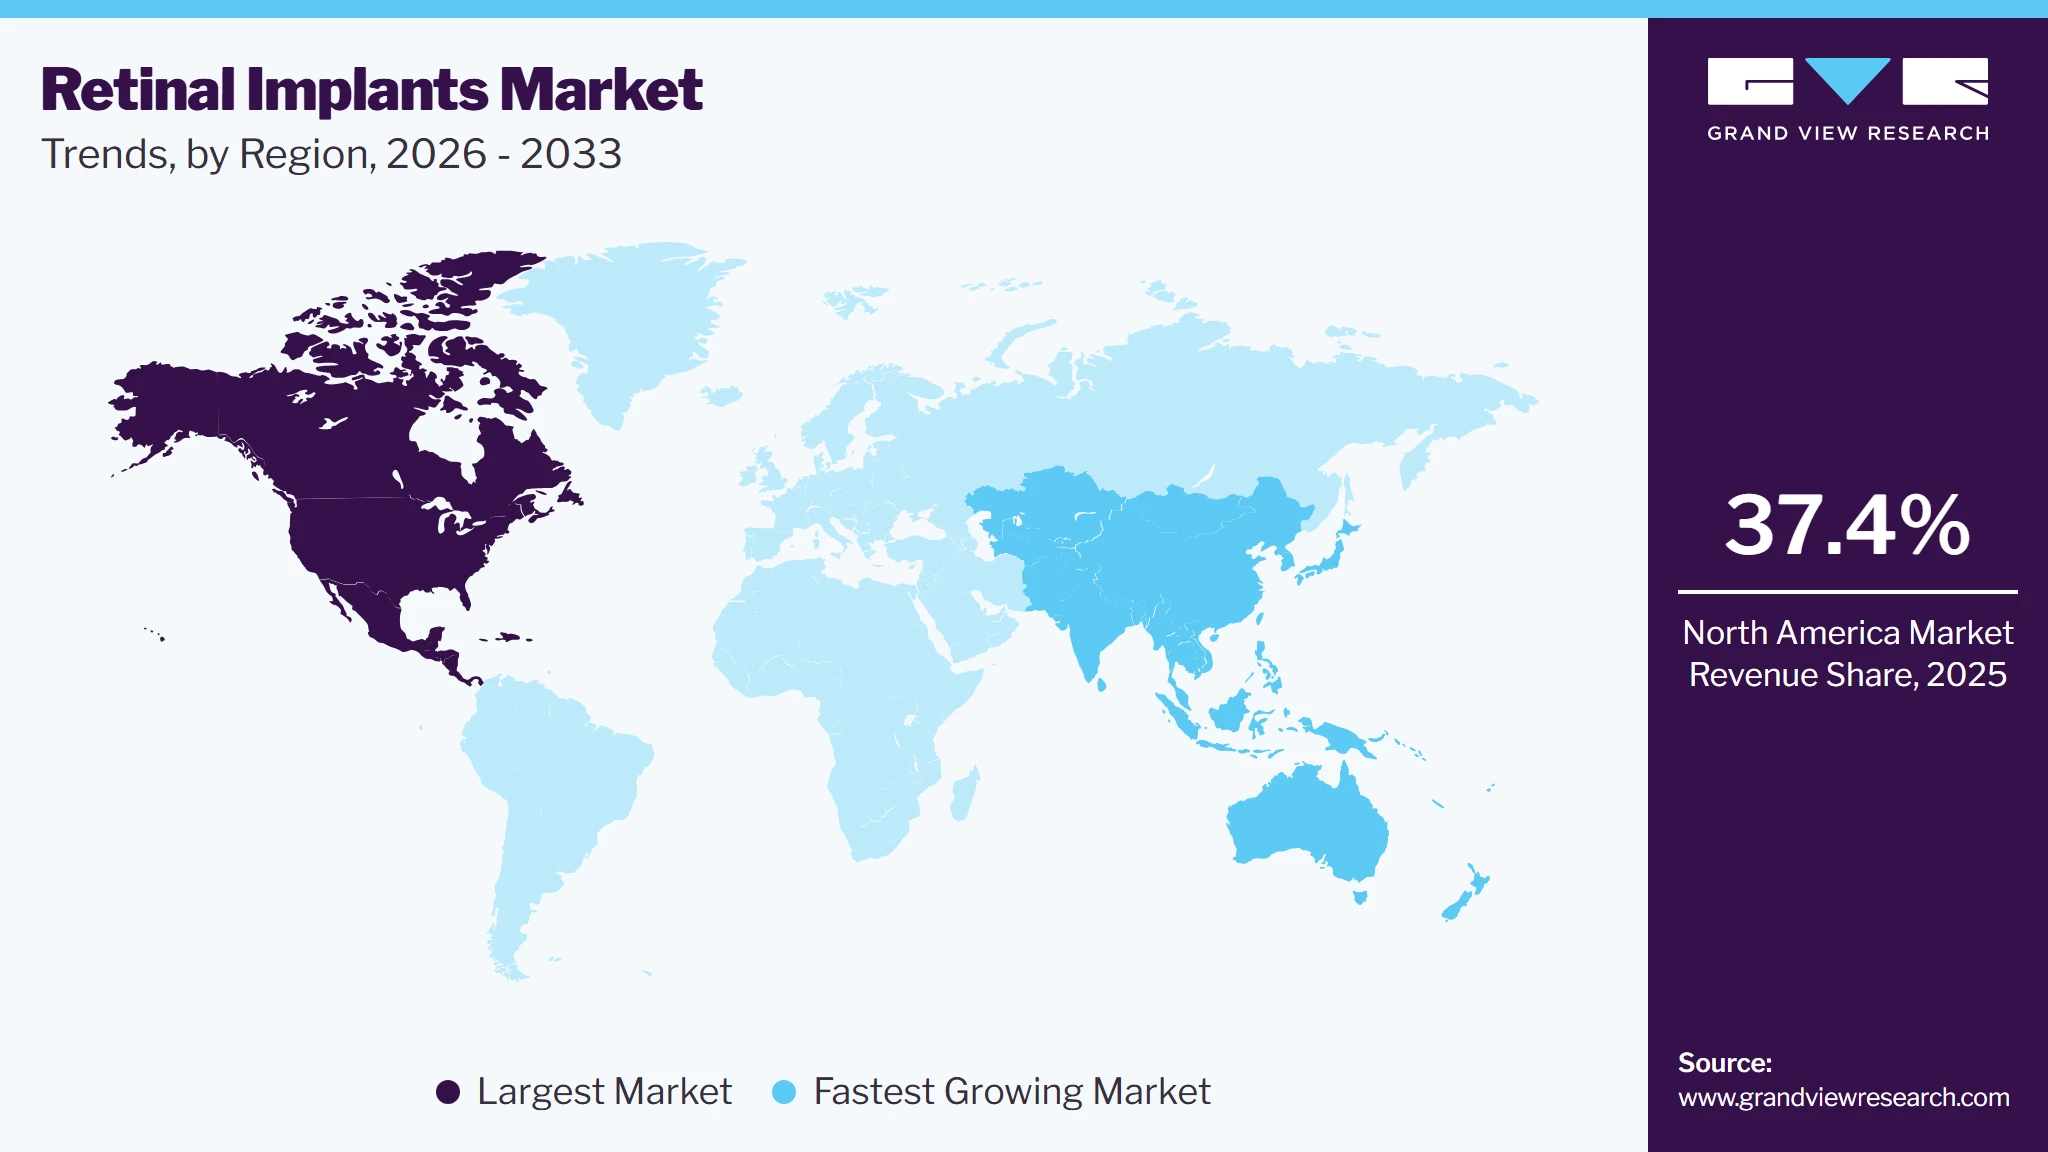
North America dominated the retinal implants market with the largest revenue share of 37.4% in 2025. Many leading pharmaceutical companies in the region are investing in the development of retinal implants, which is driving the growth of the market. The market is expanding because of the increasing number of product launches.
 To learn more about this report, Download Free Sample Report
U.S. Retinal Implants Market Trends
The retinal implants market in the U.S. held the largest share in the North America region in 2025. The U.S. plays a leading role in the retinal implants industry, supported by its robust healthcare infrastructure and extensive immunization programs. In this region, significant innovations, technological improvements, partnerships, and agreements are being made. For instance, on September 6, 2021, U.S.-based MedTech business Cirtec Medical and Bionic Vision Technologies (BVT) announced their strategic alliance. Because of this collaboration, Cirtec gained a strategic share in Bionic and is likely to help that company further create and refine its newest retinal implants.
Europe Retinal Implants Market Trends
Europe retinal implants market held a global revenue share of 29.5% in 2025 driven by advanced healthcare systems and strong public health initiatives. In October 2024, Science Corporation reported successful outcomes from a European clinical trial of the PRIMA retinal implant. This wireless device restores vision in patients with geographic atrophy (GA), enabling them to read and recognize faces post-implantation.
The UK retinal implants market is steadily growing, supported by a rise in diabetes-related eye diseases. An NHS Digital report indicates a 5% increase in cases over the past two years. Diabetic retinopathy affects about one-third of individuals with Type 1 diabetes and one in ten with Type 2 diabetes.
The retinal implants market in France is expanding, supported by advanced healthcare infrastructure and increasing adoption of innovative technologies. Clinical trials, such as the CALIPSO study, have demonstrated the potential of retinal implants in treating conditions like geographic atrophy and retinitis pigmentosa. French institutions are actively contributing to research and development, fostering innovation in vision-restoring devices. In addition, the government’s strong healthcare policies and public funding for ophthalmic treatments are driving market growth.
The German retinal implants market is anticipated to expand, driven by the rising prevalence of diabetes. Germany faces a significant healthcare challenge with high rates of undiagnosed type 1 and type 2 diabetes among adults. An aging population and unhealthy lifestyle choices are expected to further elevate type 2 diabetes cases in the next decade. Diabetic retinopathy, a major complication of diabetes, remains a critical health concern, impacting a substantial portion of the population. These factors underscore the growing demand for advanced retinal implant solutions to address vision-related complications associated with diabetes in Germany.
Asia Pacific Retinal Implants Market Trends
The Asia Pacific region retinal implants market is expected to register the fastest CAGR of 9.3% during the forecast period. The region has experienced significant growth in healthcare expenditure, resulting in a greater investment in R&D activities concerning retinal implants. This has helped in the development of new and innovative products and technologies, boosting market growth. Conditions such as age-related macular degeneration (AMD) and retinitis pigmentosa (RP) are becoming more prevalent globally. In addition, with the rapidly increasing aging population, consumers are becoming more aware of government policies. Furthermore, the healthcare infrastructure is undergoing modernization, while the medical tourism industry is rapidly expanding in developing economies such as China and India. Regional market expansion is also anticipated to be fueled by leading market participants spending more on healthcare in the public and private sectors to reach unexplored regions.
Japan's retinal implants market is poised for growth, driven by innovative advancements and successful clinical developments. In February 2024, Japan introduced a novel retinal implant system and completed a pilot clinical trial, showcasing its technological expertise. Additionally, Japanese researchers have successfully performed suprachoroidal retinal implantations on blind patients, marking a significant step in restoring vision.
The China's retinal implants market is advancing, highlighted by significant milestones. In July 2024, Samsara Vision successfully implanted a miniature telescope in a patient, with ongoing monitoring for visual rehabilitation as the patient adapts to their enhanced vision. In addition, the Shenzhen Institutes of Advanced Technology (SIAT) at the Chinese Academy of Sciences (CAS) is actively researching micro/nanotechnologies to develop high-density retinal implants, further driving innovation in the field.
The retinal implants market in India is experiencing significant growth, driven by increasing cases of diabetic retinopathy and advancements in healthcare technology. In May 2022, Chhattisgarh introduced OCT-guided coronary angioplasty, signaling a shift toward advanced ophthalmic care. The rising prevalence of diabetes, coupled with a growing geriatric population, has escalated demand for innovative retinal solutions. Government initiatives and increased healthcare funding are bolstering the adoption of retinal implants.
Latin America Retinal Implants Market Trends
The Latin American retinal implants market is expanding rapidly, supported by widespread vaccine distribution and increasing type 2 diabetes prevalence. Genetic predisposition and rising obesity rates have fueled a steady growth in diabetes cases over the past four decades, with approximately 10% of the global population affected. Key contributors to the market’s growth include Brazil, Mexico, Argentina, and Colombia. Investments by industry players, geographic proximity to North America, and free-trade agreements with countries like the U.S., Canada, Japan, and several European nations further boost market development. These factors position Latin America as a promising region for retinal implant advancements.
The retinal implants market in Saudi Arabia is set for rapid growth, fueled by the rising prevalence of diabetes and a rapidly aging population. The International Diabetes Federation (IDF) reports that the Middle East has the second-highest number of diabetes-related deaths in patients under 60. Additionally, IDF projects a 134% increase in the region's 24 million diabetic population by 2045.
Key Retinal Implants Company Insights
The market is very competitive, with several manufacturers holding a majority of the market share. For instance, in January 2018, Pixium Vision received approval from the U.S. FDA to initiate clinical trials for PRIMA, which is a sub-retinal implant. The implant was approved for practice in patients with atrophic dry age-related macular degeneration (AMD). Product launches, approvals, strategic acquisitions, and innovations are just a few of the critical business strategies market participants use to maintain and grow their global reach. The market participants are constantly working towards new product development, M&A activities, and other strategic alliances to gain market avenues.
Key Retinal Implants Companies:
The following key companies have been profiled for this study on the retinal implants market.
-
Vivani Medical
-
Pixium Vision
-
Boston Retinal Implant Project
-
Nano Retina
-
Labtician Ophthalmics, Inc.
-
LambdaVision, Inc.
-
Bionic Vision Technologies
-
Nidek Co., Ltd.
-
Retina Implant AG
-
Optobionics
-
VisionCare Ophthalmic Technologies
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Nidek Co., Ltd.; Retina Implant AG; VisionCare Ophthalmic Technologies; Labtician Ophthalmics, Inc.)
- Focus on commercializing clinically validated retinal implant and vision restoration technologies through specialized ophthalmic centers and tertiary hospitals. Companies emphasize expanding product portfolios across implantable miniature telescopes, subretinal prostheses, and low-vision rehabilitation solutions while strengthening physician education, post-implant rehabilitation programs, and long-term clinical evidence generation. Strategic collaborations with ophthalmic hospitals, academic institutions, distributors, and regulatory agencies support broader commercialization, reimbursement expansion, and geographic market penetration.
- Strong clinical credibility supported by years of ophthalmic expertise, established regulatory approvals, and extensive relationships with retinal surgeons and specialized eye hospitals. Mature quality management systems, manufacturing capabilities, and post-market surveillance programs enable reliable product commercialization while extensive clinical datasets strengthen physician confidence and facilitate reimbursement negotiations.
- High research, manufacturing, and regulatory compliance costs associated with implantable ophthalmic devices significantly increase operational expenditure. Limited addressable patient populations for retinal prostheses, lengthy commercialization timelines, and dependence on specialized surgical expertise constrain market expansion and slow revenue growth compared with larger ophthalmic device segments.
Emerging Players (Vivani Medical; Pixium Vision; Boston Retinal Implant Project; Nano Retina; LambdaVision, Inc.; Bionic Vision Technologies; Optobionics)
- Focus on developing next-generation retinal prostheses incorporating wireless power transmission, photovoltaic stimulation, higher-density microelectrode arrays, flexible biocompatible materials, AI-enabled image processing, and minimally invasive implantation techniques. Companies prioritize clinical research collaborations with universities, government-funded vision restoration programs, and neurotechnology institutes while actively pursuing breakthrough regulatory designations, strategic licensing agreements, venture capital funding, and technology partnerships to accelerate commercialization.
- Agile innovation models and strong research orientation enable rapid advancement of disruptive retinal neurostimulation technologies, bioelectronic implants, and next-generation visual restoration platforms. Close collaboration with academic institutions and research hospitals provides access to cutting-edge scientific expertise, early-stage clinical validation, and intellectual property that can differentiate products from existing retinal implant technologies.
- Limited financial resources, dependence on external funding, and early-stage product pipelines restrict large-scale manufacturing and commercial expansion. Extended clinical trial durations, stringent regulatory approval requirements, uncertain reimbursement pathways, and the technical complexity of demonstrating long-term safety and visual efficacy can significantly delay commercialization and increase development risk.
Recent Developments
-
In February 2024 , Yonsei University researchers developed a soft retinal prosthesis using ultrathin phototransistor arrays and liquid metal electrodes. Unlike rigid implants, this design, made with low-toxicity gallium-indium alloy, aligns with the retina's curved surface and reduces tissue damage, offering a safer, more adaptable solution for restoring vision in degenerative retinal diseases.
-
In February 2022 , Stanford researchers demonstrated that a retinal chip, combined with specialized glasses, restores central vision in macular degeneration patients. The prosthetic vision naturally integrates with patients' peripheral vision, creating coherent images without distortion. This breakthrough, published in Nature Communications, offers hope for restoring functional vision in the 200 million affected globally
Retinal Implants Market Report Scope
Report Attribute
Details
Market size in 2025
USD 56.3 million
Estimated market size in 2026
USD 61.0 million
Projected market size by 2033
USD 107.6 million
Growth rate
CAGR of 8.4% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Mexico; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
Vivani Medical; Pixium Vision; Boston Retinal Implant Project; Nano Retina; Labtician Ophthalmics, Inc.; LambdaVision, Inc.; Bionic Vision Technologies; Nidek Co., Ltd.; Retina Implant AG; Optobionics; VisionCare Ophthalmic Technologies
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Retinal Implants Market Report Segmentation
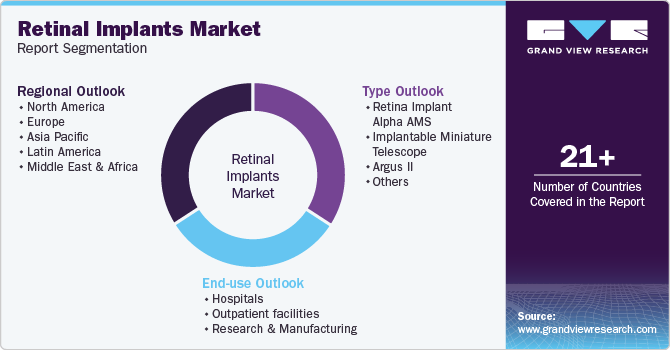
This report forecasts revenue growth at global, regional, and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global retinal implants market report based on type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Retina Implant Alpha AMS
-
Implantable Miniature Telescope
-
Argus II
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Outpatient facilities
-
Research & Manufacturing
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The retinal implants market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each retinal implants segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Retina Implant Alpha AMS
Revenue is generated through the sale of subretinal prosthetic systems designed to restore partial vision in patients with advanced retinal degeneration. Manufacturers capture value from implantable microchip systems, external power and control units, proprietary surgical implantation kits, post-implant device programming, rehabilitation services, and long-term technical support agreements.
Implantable Miniature Telescope (IMT)
Revenue is derived from implantable optical telescope systems intended to improve central vision in patients with end-stage age-related macular degeneration (AMD). Companies monetize through premium implant sales, dedicated ophthalmic surgical instruments, preoperative patient screening solutions, postoperative visual rehabilitation programs, and physician training and certification services.
Argus II
Revenue is generated from epiretinal prosthetic systems comprising implantable electrode arrays, external camera-equipped smart glasses, visual processing units, wireless communication modules, and specialized implantation accessories. Additional revenue is captured through software upgrades, replacement external components, clinical programming services, maintenance contracts, and patient rehabilitation programs aimed at improving functional vision.
Others
Revenue is captured from emerging retinal prostheses, next-generation retinal neurostimulation systems, photovoltaic retinal implants, cortical-retinal interface technologies, and investigational bioelectronic vision restoration platforms. Market participants generate income through prototype device commercialization, clinical trial supply agreements, research collaborations, custom implant components, and technology licensing arrangements.
Segment - End-use
Revenue capture definition
Hospitals
Revenue is secured through procurement of retinal implant systems by tertiary care hospitals, academic medical centers, and specialized ophthalmology departments performing vitreoretinal surgeries. Manufacturers generate income from implant sales, capital equipment for surgical planning and programming, operating room support systems, surgeon training, comprehensive service contracts, and postoperative patient management software.
Outpatient Facilities
Revenue is generated from specialized ophthalmic clinics and ambulatory surgical centers performing patient evaluation, follow-up care, device programming, and visual rehabilitation. Companies capture value through diagnostic equipment integration, external device components, software licensing, rehabilitation services, replacement accessories, and recurring maintenance and technical support.
Others
Revenue is derived from research institutes, universities, biotechnology companies, and medical device manufacturers engaged in retinal prosthesis development and translational research. Market participants monetize through prototype manufacturing, custom microelectrode arrays, research-use-only devices, technology licensing, collaborative development agreements, preclinical testing platforms, and contract manufacturing services supporting next-generation retinal implant innovation.
Estimation Model
01. Scope Definition
02. Build the Product Base
03. Estimate Penetration
04. Revenue Conversion
What is being sized?
How large is the total addressable market?
What portion of eligible patients in the market utilize retinal implant therapy?
How do procedure volumes and usage translate into market revenue?
Process Steps
Process Steps
Process Steps
Process Steps
Define retinal implant product categories and market scope.
Identify ophthalmology hospitals, retinal specialty centers, academic institutions, and referral networks performing retinal implant procedures.
Evaluate adoption rates among eligible patients suffering from severe vision impairment caused by retinal degenerative diseases.
Determine average selling price (ASP) by product type and technology.
Segment the market by type, end use, and geography.
Estimate the installed base of centers and annual retinal implant volumes.
Assess penetration based on clinical evidence, reimbursement availability, physician recommendations, and patient awareness.
Estimate revenue from implantable devices, associated procedures, and follow-up services.
Define target patient population, including individuals affected by retinal degenerative disorders and severe vision loss.
Assess procedure utilization rates and replacement cycles where applicable.
Evaluate regional differences in adoption and access to advanced ophthalmic care.
Account for revenue across hospitals, outpatient ophthalmology facilities, and specialized vision restoration centers.
Establish geographic coverage and forecast horizon.
Validate findings through primary interviews and secondary research.
Measure utilization across developed and emerging healthcare markets.
Triangulate and validate estimates using multiple data sources.
Data Sources: WHO, National Eye Institute (NEI), Foundation Fighting Blindness, regulatory agencies, company reports, clinical studies.
Data Sources: Hospital databases, ophthalmology associations, academic publications, company annual reports, reimbursement databases.
Data Sources: Primary interviews, physician surveys, company presentations, regulatory databases, clinical literature.
Data Sources: Company reports, procurement databases, distributor pricing data, primary interviews, and industry publications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive competitive landscape assessment for the global retinal implants market, covering leading companies developing retinal prostheses, implantable miniature telescopes, neurostimulation platforms, and next-generation technologies. The study evaluated company retinal implants market positioning, product portfolios (including epiretinal, subretinal, and suprachoroidal implants), strategic developments, regulatory approvals, clinical differentiation, commercialization planning, investment activities, strategic collaborations, licensing agreements, prioritization, regulatory strategy, and regional market expansion. It also assessed manufacturing capabilities, geographic commercialization strategies, intellectual property positions, identification of key technological advancements including higher-density retinal prostheses and AI-enabled image processing, microelectrode arrays, wireless power transmission, flexible-strengthened market penetration across advanced ophthalmology and electronic vision restoration applications.
Enables stakeholders to understand the competitive intensity, technology maturity, and innovation landscape shaping the retinal implants market. The study supports informed decision-making related to strategic partnerships, product and capital allocation, commercialization planning, investment prioritization, regulatory strategy, and regional market expansion.
Segment Analysis
Conducted a detailed segment-level assessment of the retinal implants market across product categories including retinal implants, implantable miniature telescopes, visual prostheses, and neurostimulation technologies. The study further evaluated adoption across end users including hospitals, retinal implant ecosystem participants, outpatient ophthalmic facilities, and research & innovation organizations. The assessment included market size and growth opportunities, reimbursement availability, premium versus economy positioning, investment outlook, adoption rates, technological advancements, regulatory criteria, and regional demand variations influencing segment growth globally.
Enables stakeholders to gain granular insights into high-growth product categories, end-user adoption patterns, and commercialization opportunities. The study supports portfolio optimization, investment planning, healthcare channel strategies, reimbursement assessment, and long-term market positioning aligned with advances in visual restoration technologies.
Key Market Driver Analysis
Conducted an in-depth driver analysis for retinal implants, assessing the increasing prevalence of retinal degenerative diseases including retinitis pigmentosa, age-related macular degeneration (AMD), and inherited retinal dystrophies, alongside the growing unmet need for vision restoration therapies. The study evaluated trends associated with advances in retinal neurostimulation technologies, wearable visual processing systems, high-resolution electrode arrays, wireless implant architectures, and biocompatible implant materials. It also assessed the impact of expanding clinical research, favorable regulatory designations for breakthrough ophthalmic devices, increasing investments in neurotechnology, and improvements in microsurgical techniques supporting retinal implant adoption.
Enables stakeholders to understand the key clinical, technological, and commercial factors accelerating demand within the retinal implants market. The study supports strategic forecasting, investment prioritization, product innovation planning, commercialization strategies, regulatory pathway assessment, and regional market expansion while identifying long-term growth opportunities in advanced vision restoration technologies and neuro-ophthalmic care.
Frequently Asked Questions About This Report
The global retinal implants market size was estimated at USD 56.3 million in 2025 and is expected to reach USD 61.0 million in 2026.
The global retinal implants market is expected to grow at a compound annual growth rate of 8.4% from 2026 to 2033 to reach USD 107.6 million by 2033.
By type, the Argus II dominated the retinal implants market with a share of 34.5% in 2025.
Some key players operating in the retinal implants market include Second Sight Medical Products, Inc.; Retina Implant AG; and VisionCare, Inc.
Key factors that are driving the market growth include rising prevalence of target diseases and growing demand for vision correction.
North America dominated the retinal implants market, accounting for 37.4% of the market in 2025. This is attributable to the high prevalence of degenerative conditions and technological advancements.
The hospitals segment dominated the retinal implants market in 2025, with a share of 53.2%.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


