
- Home
- »
- Organic Chemicals
- »
-
Electronic Materials And Chemicals Market Size, Growth Report, 2026-2033GVR Report cover

Electronic Materials And Chemicals Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Solid, Liquid), By Application (Silicon Wafers, Photoresists), By End-use (Semiconductors & Integrated Circuits, Printed Circuit Boards), By Region, And Segment Forecasts
Market Size, 2025
$78.5BMarket Estimate, 2026
$83.3BMarket Forecast, 2033
$127.3BCAGR, 2026–2033
6.2%Electronic Materials And Chemicals Market Summary
The global electronic materials and chemicals market size was estimated at USD 78.5 billion in 2025 and is projected to grow from USD 83.3 billion in 2026 to USD 127.3 billion by 2033, growing at a CAGR of 6.2% from 2026 to 2033. Asia Pacific accounted for 66.6% of the electronic materials and chemicals market revenue in 2025, making it the largest regional market. Increasing product demand for manufacturing semiconductors, flat panel displays, and photolithographic printing is expected to propel the growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Solid segment accounted for the largest share of the electronic materials and chemicals market, representing 54.0% of total revenue in 2025.
- By application: Silicon wafers dominated the application segment at a market share of 43.4% in 2025.
- By end-use: Semiconductors & integrated circuits dominated the market at a revenue share of 68.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (66.6% revenue share, 2025)
- By country: The China electronic materials and chemicals market is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 78.5 Billion
- Estimated market size in 2026: USD 83.3 Billion
- Projected market size by 2033: USD 127.3 Billion
- CAGR (2026-2033): 6.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Decreasing equipment prices and improved standards of living across various parts of the world is expected to be the key factor driving the consumer electronics industry’s growth, which in turn is likely to have a positive impact on this market. Growing demand for semiconductors for manufacturing mobile phones, electronic chips, and integrated circuits is expected to propel the growth.Advancements in the assembly technologies and miniaturization in these electronic products are achieved through innovation in new materials and associated process techniques. Increasing technological advancements in electronic products owing to rising consumer demand for high-tech products is expected to spur the product demand. The electronics materials and chemicals is a technology driven industry and are primarily influenced by the adoption of new product designs and specifications in the product field. Electronic materials are an essential part of the electronic hardware and are used in the development and design of electronic equipment. Growing demand for modern handheld gadgets such as iPod, cell phone, laptops, and portables measuring and testing equipment has resulted in miniaturization of electronic gadgets.
 To learn more about this report, Download Free Sample Report
The electronic materials & chemicals are an essential part of semiconductor manufacturing, as a result, as the need for semiconductor chips increases, demand for high purity chemicals and materials also increases. The market for electronic chemicals is directly influenced by the global demand for electronic products. The global consumer electronics market is anticipated to witness significant growth, especially in emerging economies such as China, Japan, Taiwan, and India. Increasing disposable income coupled with rising population in the region is expected to increase demand for electronic products, which in turn is likely to drive the industry growth over the forecast period.
Growing demand for electronic materials & chemicals for manufacturing consumer and industrial electronic products has been a major factor driving the growth. However, health and environmental hazards associated with the manufacturing and application of these products are expected to be key factors affecting the market negatively. Electronic equipment contains a wide range of toxic halogenated compounds, heavy metals, and radioactive substances. Initiatives taken by international organizations such as the U.S.EPA, the German Federal Ministry for the Environment, the National Institute of Environmental Health Sciences, and the World Health Organization (WHO) to address the global electronic waste trade and management concerns are likely to regulate various chemicals over the next eight years.
Market Dynamics
The Electronic Materials and Chemicals Market is witnessing robust growth driven by the rapid expansion of the semiconductor, consumer electronics, automotive electronics, and telecommunications industries. Electronic materials and chemicals, including specialty gases, photoresists, wet chemicals, CMP slurries, electronic-grade solvents, and advanced packaging materials, play a critical role in the manufacturing of integrated circuits, printed circuit boards, displays, and electronic components. Rising demand for advanced technologies such as artificial intelligence (AI), 5G infrastructure, electric vehicles (EVs), Internet of Things (IoT) devices, and high-performance computing is accelerating the consumption of high-purity electronic materials worldwide. Increasing investments in semiconductor fabrication facilities, ongoing miniaturization of electronic devices, and the growing emphasis on sustainable and energy-efficient manufacturing processes are further supporting market expansion. However, stringent purity requirements, supply chain complexities, and regulatory compliance challenges remain key concerns for manufacturers.
The Electronic Materials and Chemicals Market is experiencing significant growth driven by the rapid expansion of semiconductor manufacturing and increasing demand for advanced electronic devices. Electronic materials and chemicals are essential in the production of integrated circuits, printed circuit boards (PCBs), displays, sensors, and advanced packaging solutions. The growing adoption of artificial intelligence (AI), 5G networks, high-performance computing, consumer electronics, and data centers is increasing the demand for high-purity chemicals, specialty gases, photoresists, wet chemicals, and electronic-grade materials. Governments worldwide are also supporting domestic semiconductor production through investments and incentive programs, further strengthening market demand.
The impact of this trend extends across multiple industries, including telecommunications, automotive electronics, healthcare devices, and industrial automation. As semiconductor nodes continue to shrink and chip complexity increases, manufacturers require highly specialized materials that ensure precision, performance, and reliability. The continuous development of next-generation semiconductor technologies is expected to remain a key growth driver for the electronic materials and chemicals market over the forecast period.
Supply chain disruptions and stringent quality requirements present significant challenges for the Electronic Materials and Chemicals Market. The production of electronic materials relies on highly purified raw materials and complex manufacturing processes that must meet extremely strict contamination standards. Any disruption in the supply of critical materials, specialty gases, rare metals, or chemical precursors can impact semiconductor fabrication and electronics production.
Manufacturers face increasing regulatory requirements related to chemical handling, environmental protection, worker safety, and hazardous waste disposal. Maintaining ultra-high purity levels while complying with global regulations often requires substantial investments in production facilities, quality control systems, and environmental management technologies. These factors can increase operational costs and create challenges for new market entrants, particularly in highly regulated regions.
The growing adoption of advanced semiconductor packaging technologies, artificial intelligence infrastructure, and sustainable electronics manufacturing is creating substantial opportunities for the Electronic Materials and Chemicals Market. Advanced packaging solutions such as 2.5D and 3D integrated circuits require innovative materials, including advanced photoresists, dielectric materials, conductive chemicals, and specialty substrates. The expansion of AI servers, cloud computing facilities, and high-performance computing systems is further driving demand for sophisticated electronic materials.
Opportunities are also emerging from the industry's focus on sustainability and resource efficiency. Manufacturers are investing in environmentally friendly chemicals, recyclable materials, low-emission production processes, and water-efficient semiconductor manufacturing technologies. As electronics manufacturers seek to balance performance, reliability, and sustainability, suppliers that offer innovative and eco-friendly material solutions are expected to gain a competitive advantage and expand their presence across semiconductor, display, automotive electronics, and next-generation communication markets.
Analyst Perspective
The electronic materials and chemicals market is positioned for sustained growth, driven by increasing semiconductor production, rapid digitalization, and the expansion of advanced electronics applications worldwide. The growing adoption of artificial intelligence (AI), 5G infrastructure, cloud computing, electric vehicles (EVs), and Internet of Things (IoT) devices is creating strong demand for high-purity electronic materials, specialty gases, wet chemicals, photoresists, and advanced packaging materials. As semiconductor manufacturers continue to transition toward smaller process nodes and more complex chip architectures, the need for highly specialized materials that ensure performance, reliability, and manufacturing precision is expected to increase significantly.
Product Insights
The solid segment accounted for the largest share of the electronic materials and chemicals market, representing 54.0% of total revenue in 2025. Increasing product demand for manufacturing various consumer goods such as computers, laptops, and smartphones is expected to drive demand for solid electronic materials over the forecast period. The expansion of renewable energy technologies, particularly solar panels and electric vehicles, also contributes to this growing demand, as they rely on sophisticated electronic components from these specialized materials. Consequently, manufacturers invest heavily in research and development to create more effective and sustainable solid chemicals and materials, further driving the market's growth.
The gas segment is expected to grow at the fastest CAGR of 6.9% over the forecast period, owing to their rising penetration in semiconductor and PCB manufacturing. Increasing demand for gas materials for manufacturing LEDs, solar photovoltaic, and flat panel displays is expected to drive growth over the forecast period. Specialty gases are crucial in chemical vapor deposition (CVD) and etching. They create thin films, patterns, and structures on semiconductor substrates. Ongoing advancements in semiconductor technology and innovative fabrication technologies fuel the segment's growth.
Application Insights
Silicon wafers dominated the application segment at a market share of 43.4% in 2025. Increasing demand for PCB laminates in manufacturing various electronic products, including amplifiers and LEDs, is anticipated to positively impact the industry's growth over the projected period. Electronic device miniaturization and feature improvement require high-quality silicon wafers. These wafers play a crucial role in manufacturing semiconductors, which are utilized in manufacturing several electronic devices.
The photoresist is expected to be the fastest-growing application segment with the CAGR of 7.2% over the forecast period, owing to the growing demand for photoresists in microsystems and microelectronics. Photoresist involves the use of various chemicals for many imaging and non-imaging applications. In addition, ongoing advancements and enhanced manufacturing processes in the semiconductor industry drive the demand for high-performance photoresist materials to produce high-quality semiconductor gadgets.
End-use Insights
Semiconductors & integrated circuits dominated the market at a revenue share of 68.8% in 2025. The proliferation of advanced technologies such as artificial intelligence, the Internet of Things (IoT), and 5G communications requires increasingly sophisticated and miniaturized electronic components, driving the need for high-performance semiconductors and integrated circuits. Additionally, the automotive industry’s shift towards electric and autonomous vehicles demands robust electronic systems, further boosting this segment.
 To learn more about this report, Download Free Sample Report
The printed circuit boards (PCBs) segment is expected to grow at a CAGR of 5.8% from 2025 to 2030. Increasing demand for printed circuit boards as vital components of integrated circuit chip technology that is used in consumer appliances, including smartphones, computers, and laptops is expected to boost the growth. Increasing demand for semiconductors & integrated circuits for manufacturing computers and other consumer appliances is expected to be a key factor for the industry growth. Changing consumer lifestyles coupled with increasing consumer disposable income is likely to boost demand for consumer appliances, thereby driving the market’s growth.
Regional Insights
Asia Pacific accounted for 66.6% of the electronic materials and chemicals market revenue in 2025, making it the largest regional market. The region is anticipated to continue its dominance over the forecast period. Rapid industrialization and the presence of numerous electronic device manufacturers in Asian countries, including China, Taiwan, Japan, and South Korea, are expected to positively impact the industry’s growth.
 To learn more about this report, Download Free Sample Report
China Electronic Materials And Chemicals Market Trends
China held the largest share of the Asia Pacific electronic materials and chemicals market in 2025
North America Electronic Materials And Chemicals Market Trends
The electronic materials and chemicals market in North America held a significant market revenue share in 2024, owing to the large number of electronic device manufacturers in the region including Micron, Intel, Fairchild, Texas Instruments, and Avago. These players are engaged in the manufacturing of digital and analog semiconductor technologies for the end-users, thereby propelling product demand over the forecast period. North America is a key player in specialty gases and is expected to grow in near future owing to the increasing demand for plasma display panels and photovoltaic products.
The U.S. electronic materials and chemicals market dominated the North American market and accounted for the largest revenue share in 2024. Rapid technological advancements within the country's electronics industry significantly drive the electronic chemicals and materials market. The U.S. government's initiatives to bolster domestic semiconductor production and the expansion of 5G technology, electric vehicles, and renewable energy sectors significantly contribute to this growing demand.
Latin America Electronic Materials And Chemicals Market Trends
Latin America electronic materials and chemicals market is projected to grow at a CAGR of 6.4% over the forecast period. Increased demand from end-user industries, integration with global markets, policy reforms, and technological advancements are the main factors fueling the expansion of the electronic chemicals and materials market in Latin America. The development of the region is supported by its thriving electronics industry, abundance of natural resources, and skilled labor force. It is anticipated that the electronic chemicals and materials market in Latin America will grow in the upcoming period.
Europe Electronic Materials And Chemicals Market Trends
The electronic materials and chemicals market in Europe is expected to witness substantial growth over the forecast period, owing to rising applications across end-use industries such as electrical and electronics and automotive. The burgeoning production of hand-held gadgets is anticipated to bring about a surge in the manufacturing of electronic components, thereby propelling industry growth. The constantly increasing applications of electronic and chemical materials are anticipated to take the concerned market to newer heights in Europe.
Key Electronic Materials And Chemicals Company Insights
Some of the key companies in the electronic materials and chemicals market include Sumika Electronic Materials; Drex-Chem Technologies; EMD Performance Materials Corp.; EKC Technology; Fujifilm Electronic Materials; and others.
-
Sumika Electronic Materials, a subsidiary of Sumitomo Chemical, provides electronic materials such as polarizing film and OLED optical films, photoresists and wet chemicals for semiconductor lithography, lithium battery membranes, high purity alumina (HPA), and more.
-
FUJIFILM Electronic Materials portfolio includes photoresist products, processing chemicals, CMP slurries, thin film-forming materials, and cleaner products. Recently, they completed the acquisition of the electronic chemicals business from Entegris, rebranding it as FUJIFILM Electronic Materials Process Chemicals.
Key Electronic Materials And Chemicals Companies:
The following are the leading companies in the electronic materials and chemicals market. These companies collectively hold the largest market share and dictate industry trends.
- Bayer AG
- Albemarle Corporation
- Ashland
- BASF SE
- Air Liquide Electronics
- Merck KGaA
- Honeywell International Inc.
- Cabot Corporation.
- Linde PLC
- Dow
- Hitachi, Ltd.
- Sumitomo Chemical Co., Ltd.
- Monsanto Electronic Materials Co.
- EKC Technology
- FUJIFILM Holdings America Corporation
- HD Microsystems. Ltd.
- High Purity Products
- JSR Micro
- KANTO KAGAKU.
- Moses Lake Industries, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, Merck KGaA, Air Liquide, Linde plc, Dow, Honeywell International Inc., Cabot Corporation, Sumitomo Chemical Co., Ltd., JSR Micro, FUJIFILM Holdings Corporation)
- Focus on high-purity electronic materials and advanced semiconductor process chemicals.
- Invest heavily in R&D, manufacturing expansion, and next-generation semiconductor technologies.
- Establish long-term supply agreements with major semiconductor foundries and electronics manufacturers.
- Strengthen global manufacturing and distribution networks to support regional semiconductor ecosystems.
- Strong technological expertise and extensive intellectual property portfolios.
- Global production footprints with highly reliable supply chains.
- Ability to meet stringent purity and quality requirements demanded by advanced semiconductor manufacturing.
- Strong relationships with leading semiconductor and electronics companies.
- High capital investment requirements for maintaining advanced production facilities.
- Significant compliance costs related to environmental, safety, and chemical regulations.
- Complex organizational structures may slow responsiveness to niche market opportunities.
Category
Operating Strategies
Competitive Edge
Weakness
Emerging Players (EKC Technology, HD Microsystems Ltd., High Purity Products, Moses Lake Industries, KANTO KAGAKU, Monsanto Electronic Materials Co. and regional specialty chemical suppliers)
- Focus on niche electronic chemicals, specialty formulations, and customized solutions.
- Expand through strategic partnerships, technology licensing, and regional manufacturing capabilities.
- Target high-growth segments such as advanced packaging, specialty gases, and semiconductor process materials.
- Offer flexible production and customer-specific product development.
- Greater operational flexibility enables faster adaptation to customer-specific performance requirements.
- Competitive pricing strategies and strong relationships within regional markets.
- Ability to address specialized applications with tailored product offerings. Greater operational flexibility and faster response to customer requirements.
- Strong specialization in selected product categories and applications.
- Competitive pricing and closer engagement with regional customers.
- Ability to address emerging technology niches.
- Smaller production capacities and limited global reach.
- Lower R&D budgets compared with multinational industry leaders.
- Greater dependence on regional demand cycles and customer concentration.
- Limited ability to compete in large-scale supply contracts with leading semiconductor manufacturers.
Recent Developments
-
In August 2024, JSR Corporation announced the acquisition of all shares of Yamanaka Hutech Corporation, making YHC a wholly owned subsidiary. This strategic move aims to expand JSR's product portfolio in semiconductor materials, particularly in film-forming technologies. The acquisition aligns with JSR's growth strategy to enhance customer value and optimize the supply chain in the rapidly evolving semiconductor industry.
-
In May 2024, Air Liquide announced an expansion with its new diborane production facility at its advanced materials Center in Sejong, South Korea. This state-of-the-art plant, which utilizes advanced analytical and digital technologies, aims to provide high-quality diborane crucial for semiconductor manufacturing. The facility underscores Air Liquide's commitment to enhancing Korea's semiconductor ecosystem and aligns with its broader strategy to localize advanced material production.
Electronic Materials And Chemicals Market Report Scope
Report Attribute
Details
Market size in 2025
USD 78.5 billion
Estimated Market size in 2026
USD 83.3 billion
Projected Market size by 2033
USD 127.3 billion
Growth rate
CAGR of 6.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; Japan; India; South Korea; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Bayer AG; Albemarle Corporation; Ashland; BASF SE; Air Liquide Electronics; Merck KGaA; Honeywell International Inc.; Cabot Corporation; Linde PLC; Dow; Hitachi, Ltd.; Sumitomo Chemical Co., Ltd.; Monsanto Electronic Materials Co.; EKC Technology; FUJIFILM Holdings America Corporation; HD Microsystems. Ltd.; High Purity Products; JSR Micro; KANTO KAGAKU.; Moses Lake Industries, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Electronic Materials And Chemicals Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global electronic materials and chemicals market report based on, product, application, end-use, and region:
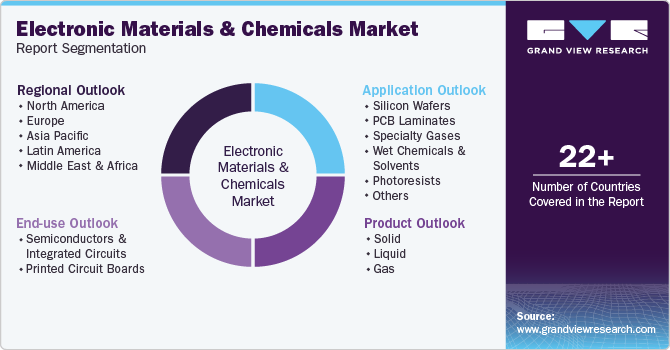 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Solid
-
Liquid
-
Gas
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Silicon Wafers
-
PCB Laminates
-
Specialty gases
-
Wet chemicals and solvents
-
Photoresists
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Semiconductors & Integrated Circuits
-
Printed Circuit Boards
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Latin America
-
Brazil
-
-
Middle East and Africa
-
Research Methodology
The electronic materials and chemicals market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each electronic materials and chemicals segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Solid
Revenue generated from solid electronic materials such as silicon wafers, photoresist materials, CMP pads, substrates, encapsulants, and advanced packaging materials used in electronic component manufacturing.
Liquid
Revenue generated from liquid electronic chemicals including wet chemicals, solvents, developers, etchants, cleaning agents, and slurry materials utilized in semiconductors and electronics fabrication processes.
Gas
Revenue generated from specialty and electronic-grade gases used in deposition, etching, doping, cleaning, and other semiconductor manufacturing applications requiring ultra-high purity standards.
Segment - Application
Revenue capture definition
Silicon Wafers
Revenue generated from materials and chemicals used in the production, processing, cleaning, and treatment of silicon wafers that serve as the foundation for semiconductor device manufacturing.
PCB Laminates
Revenue generated from materials and chemicals utilized in the production of printed circuit board laminates, including substrate materials, resins, and associated processing chemicals.
Specialty Gases
Revenue generated from high-purity gases used in semiconductor fabrication processes such as chemical vapor deposition (CVD), plasma etching, ion implantation, and chamber cleaning.
Wet Chemicals and Solvents
Revenue generated from acids, bases, solvents, cleaning chemicals, developers, etchants used in semiconductor and electronics manufacturing operations.
Photoresists
Revenue generated from light-sensitive materials used in photolithography processes for creating circuit patterns on semiconductor wafers and electronic components.
Other Applications
Revenue generated from electronic materials and chemicals used in display manufacturing, advanced packaging, sensors, MEMS devices, photovoltaics, and other electronics-related applications.
Segment – End Use
Revenue capture definition
Semiconductors & Integrated Circuits
Revenue generated from materials and chemicals used in the fabrication, assembly, packaging, and testing of semiconductor devices, integrated circuits, memory chips, processors, and related electronic components.
Printed Circuit Boards
Revenue generated from materials and chemicals utilized in the manufacturing, coating, etching, assembly, and finishing of printed circuit boards used across consumer electronics, automotive, industrial, and communication devices.
Estimation Model
Layer Name
Key Question
Description
Electronic Materials Production Layer
What forms is the supply base?
Identify global production capacity of electronic materials and chemicals, including semiconductor-grade silicon wafers, specialty gases, wet chemicals, photoresists, CMP materials, electronic-grade solvents, dielectric materials, and advanced packaging materials. Assess manufacturing infrastructure, purity standards, raw material availability, fabrication-support ecosystems, and regional production capabilities to establish the foundational supply base for the electronics industry.
End-Use Industry Adoption Layer
Where are electronic materials and chemicals utilized?
Estimate the proportion of electronic materials and chemicals consumed across semiconductors, integrated circuits, printed circuit boards (PCBs), displays, consumer electronics, automotive electronics, telecommunications equipment, industrial electronics, data centers, and renewable energy systems based on manufacturing requirements, technology adoption, and production volumes.
Consumption Intensity Layer
How much electronic material is used?
Analyze application-specific material consumption rates, wafer fabrication requirements, chemical utilization patterns, process node complexity, packaging technologies, PCB production standards, and regional electronics manufacturing trends to determine annual consumption across major end-use sectors.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of semiconductor materials, specialty gases, wet chemicals, photoresists, silicon wafers, CMP consumables, electronic-grade solvents, advanced packaging materials, and other high-purity electronic chemicals supplied to semiconductor manufacturers, PCB producers, display manufacturers, electronics assemblers, and industrial technology companies worldwide.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
Detailed cross-segmentation assessment evaluating the relationship between product types, applications, and end-use industries within the electronic materials and chemicals market. Analysis identifies consumption patterns, material intensity, purity requirements, technology adoption trends, and revenue contribution across intersecting segments such as specialty gases in semiconductor fabrication, photoresists in integrated circuit manufacturing, wet chemicals in wafer processing, and PCB laminates in electronics assembly.
Supports product portfolio optimization and market prioritization by identifying the most attractive product-application-end-use combinations, enabling improved resource allocation, sales targeting, production planning, and strategic growth initiatives.
Competitive Benchmarking
Comparative evaluation of leading electronic materials and chemicals manufacturers based on product portfolio breadth, semiconductor material capabilities, manufacturing capacity, geographic presence, purity standards, technology expertise, customer relationships, production footprint, innovation pipeline, and strategic developments across key regional markets.
Assists competitive intelligence, partnership evaluation, and supplier assessment by providing deeper visibility into market positioning, technological strengths, differentiation strategies, innovation capabilities, and areas of competitive advantage.
Opportunity Assessment
Comprehensive assessment of emerging opportunities associated with advanced semiconductor nodes, artificial intelligence infrastructure, advanced packaging technologies, electric vehicle electronics, 5G deployment, high-performance computing, display technologies, and sustainable electronic manufacturing processes. The analysis also evaluates opportunities in next-generation photoresists, specialty gases, electronic-grade chemicals, and advanced substrate materials.
Helps identify high-growth investment areas, emerging technology opportunities, product development priorities, and market expansion strategies, supporting long-term revenue growth and competitive positioning across the electronic materials and chemicals value chain.
Frequently Asked Questions About This Report
Key factors that are driving the market growth include increasing product demand for manufacturing semiconductors, flat panel displays, and photolithographic printing, along with decreasing equipment prices and improved standards of living.
Solid segment accounted for the largest share of the electronic materials and chemicals market, representing 54.0% of total revenue in 2025.
The silicon wafers dominated the application segment at a market share of 43.4% in 2025. Silicon wafers remain the foundational substrate for semiconductor device manufacturing, supporting their extensive use across integrated circuits, memory chips, sensors, and power electronics.
The semiconductors & integrated circuits dominated the market at a revenue share of 68.8% in 2025.. Rising demand for advanced chips in artificial intelligence, automotive electronics, consumer devices, data centers, and 5G infrastructure is fueling growth in this segment.
Electronic materials and chemicals are critical for the manufacturing of semiconductors, printed circuit boards, displays, and other electronic components. Growing digitalization, expanding AI applications, increasing chip complexity, and investments in semiconductor fabrication facilities are driving demand for high-purity materials and specialty chemicals worldwide.
The global electronic materials and chemicals market size was estimated at USD 78.5 billion in 2025 and is expected to reach USD 83.3 billion in 2026.
The global electronic materials and chemicals market is expected to grow at a compound annual growth rate of 6.2% from 2026 to 2033 to reach USD 127.3 billion by 2033.
Asia Pacific dominated the electronic materials and chemicals market with a share of over 66.6% in 2025. This is mainly attributed to rapid industrialization and the presence of numerous electronic device manufacturers in Asian countries, including China, Taiwan, Japan, and South Korea, are expected to positively impact the industry’s growth.
Some key players operating in the electronic materials and chemicals market include Bayer AG; Albemarle Corporation; Ashland; BASF SE; Air Liquide Electronics; Merck KGaA; Honeywell International Inc.; Cabot Corporation; Linde PLC; Dow; Hitachi, Ltd.; Sumitomo Chemical Co., Ltd.; Monsanto Electronic Materials Co.; EKC Technology; FUJIFILM Holdings America Corporation; HD Microsystems. Ltd.; High Purity Products; JSR Micro; KANTO KAGAKU.; Moses Lake Industries, Inc.
About the Author(s)
Organic Chemicals Research Team
Bulk Chemicals · Organic ChemicalsThis report was authored by the organic chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the organic chemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


