
- Home
- »
- Next Generation Technologies
- »
-
Fantasy Sports Market Size And Share Report, 2026-2033GVR Report cover

Fantasy Sports Market (2026 - 2033)
Size, Share & Trends Analysis Report By Sports (Individual Sports, Partner Sports), By Platform (Web-based, Application-based), By Sports Type, By Gameplay, By Device, By Demographics, By Region, And Segment Forecasts
Market Size, 2025
$27.8BMarket Estimate, 2026
$31.4BMarket Forecast, 2033
$75.1BCAGR, 2026–2033
13.3%Fantasy Sports Market Summary
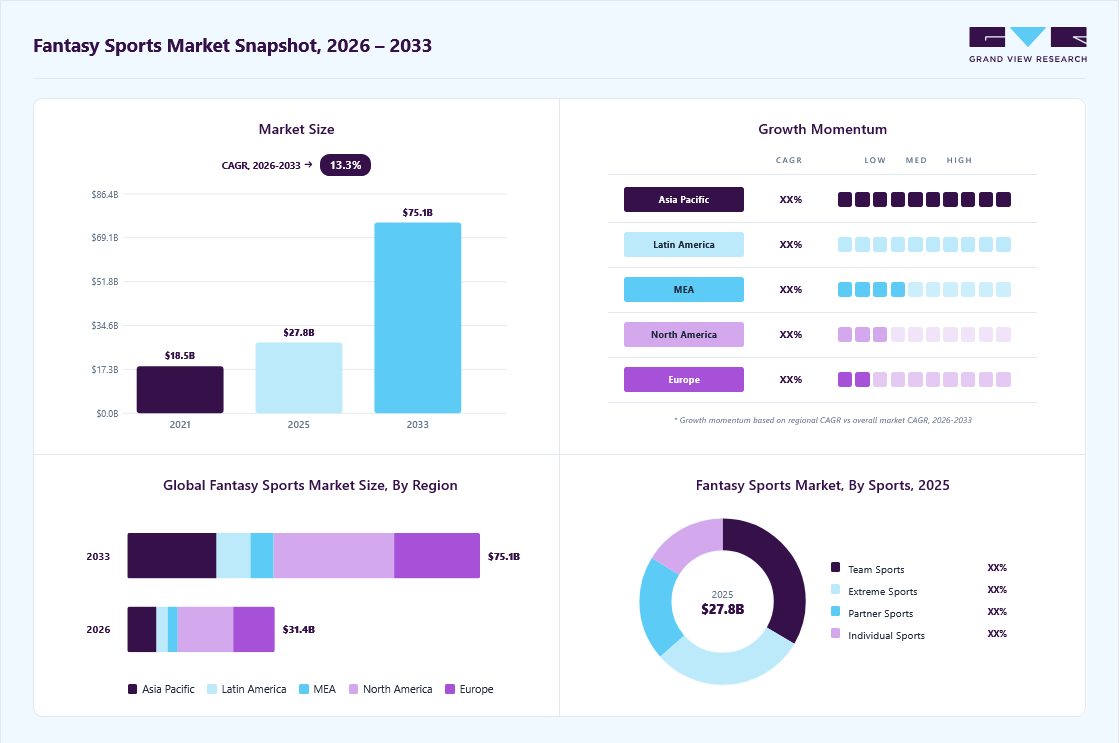
The global fantasy sports market size was valued at USD 27.8 billion in 2025 and is projected to grow from USD 31.4 billion in 2026 to USD 75.1 billion by 2033, at a CAGR of 13.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.2% in 2025. The fantasy sports market is primarily driven by the rapid growth of digital sports engagement, increasing smartphone and internet penetration, and the rising popularity of real-time, data-driven sports platforms that enhance user interaction and entertainment.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By sports: The individual sports segment accounted for the largest market share of 33.4% in 2025.
- By sports type: The football/soccer segment dominated the market, with a share of 21.1% in 2025.
- By platform: The application-based segment dominated the market, with a share of 78.1% in 2025.
- By gameplay: The team competition segment accounted for the largest market share of 68.3% in 2025.
- By device: The smartphones segment dominated the market, with a share of 50.6% in 2025.
Regional Highlights
- Largest regional market: North America (38.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR of 17.3%, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 27.8 Billion
- Estimated market size in 2026: USD 31.4 Billion
- Projected market size by 2033: USD 75.1 Billion
- CAGR (2026-2033): 13.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Growing fan engagement across major sports leagues is further accelerating user participation and monetization opportunities in fantasy sports ecosystems globally. This growth is largely driven by the expanding global fan base across both mainstream and niche sports.Increasing sports enthusiasm and awareness, particularly among younger demographics, is enhancing user engagement and participation. The widespread availability of internet access and smartphones further enables fans to interact with their favorite sports and athletes through fantasy platforms, encouraging social interaction and competitive play. In addition, rising disposable incomes and this demographic shift are expanding the market’s reach and supporting sustained long-term growth in the fantasy sports industry. Rapid advancements in mobile technology, high-speed internet, AI, machine learning, augmented reality (AR), virtual reality (VR), and blockchain are revolutionizing the fantasy sports industry. These technologies enable real-time data integration, personalized gaming experiences, enhanced user engagement through gamification, and secure payment systems. AI-driven recommendations and customization improve player retention, while AR/VR offer immersive experiences. Blockchain facilitates transparency and new monetization models such as NFT-based games, all contributing to a more interactive and dynamic fantasy sports industry expansion.
 To learn more about this report, Download Free Sample Report
In addition, the rapid adoption of smartphones and improved internet connectivity have made mobile apps the primary gateway for fantasy sports participation, driving market growth and innovation. Fantasy sports apps now offer real-time player performance tracking, live contests, and push notifications, allowing users to make instant decisions and stay engaged throughout live sporting events. The integration of gamification, social features, and seamless user interfaces on mobile platforms is expected to drive the fantasy sports industry growth in the coming years.
Furthermore, fantasy sports platforms are increasingly focusing on user engagement through interactive features such as live contests, social connectivity, player rankings, rewards, and virtual competitions. The adoption of freemium models, in-app purchases, premium subscriptions, and advertising generates diversified revenue streams. Integration with social media and brand promotion activities further amplifies user acquisition and retention. These strategies create immersive and rewarding experiences that attract and maintain a loyal user base, fueling market expansion.
Moreover, companies are focusing on user-centric innovation, strategic partnerships, and mobile-first platforms to drive growth in a competitive market. By leveraging advanced technologies such as AI and real-time analytics, they enhance personalization and engagement, while collaborations with sports leagues and media brands boost credibility and reach. Companies are also diversifying their offerings with new sports, daily fantasy formats, and digital monetization models, all while expanding into new regions and adapting to local regulations to capture a broader audience and thereby driving the fantasy sports industry growth.
Market Dynamics
The fantasy sports market is experiencing rapid growth, supported by advancements in data analytics, artificial intelligence, and personalized user experiences that enhance gameplay and user retention. Additionally, growing commercialization of sports leagues, integration with live streaming platforms, and expanding monetization models such as entry fees, subscriptions, and in-app advertising are strengthening the overall ecosystem.
The fantasy sports market is primarily driven by the rapid expansion of digital connectivity, including widespread smartphone adoption and affordable high-speed internet access. This has made fantasy sports platforms more accessible to a large and diverse user base, enabling seamless participation anytime and anywhere. As digital infrastructure improves globally, more users are engaging with mobile-based sports gaming applications.
In addition, growing fan engagement with live sports events is significantly boosting market growth. Users are increasingly seeking interactive, immersive experiences that enable them to leverage real-time match data and analytics. This shift from passive viewership to active participation is strengthening platform adoption and increasing overall user retention in the fantasy sports ecosystem.
The fantasy sports market faces significant restraints due to unclear and evolving regulatory frameworks across different countries and regions. In many jurisdictions, fantasy sports are classified differently, ranging from skill-based gaming to gambling, leading to inconsistent legal treatment. This lack of uniformity creates uncertainty for operators and limits large-scale market expansion.
Furthermore, strict regulations in certain regions impose licensing requirements, taxation policies, and operational restrictions, thereby increasing compliance complexity. These challenges raise operational costs for platform providers and restrict entry into potentially high-growth markets. As a result, regulatory challenges continue to act as a major barrier to sustaining global expansion.
The fantasy sports market presents strong growth opportunities through the integration of advanced technologies such as artificial intelligence, machine learning, and predictive analytics. These technologies enable personalized recommendations, real-time insights, and improved user experiences, making platforms more engaging and competitive. Enhanced data-driven features are also helping users make more informed gameplay decisions.
Additionally, the integration of live streaming, social features, and innovative monetization models such as subscription plans, in-app purchases, and advertising is expanding revenue streams for market players. As sports leagues increasingly collaborate with digital platforms, there is growing potential for immersive, interactive experiences that combine entertainment, analytics, and social engagement within a unified ecosystem, which is expected to generate substantial growth opportunities for fantasy sports equipment providers in the coming years.
Market Concentration & Characteristics
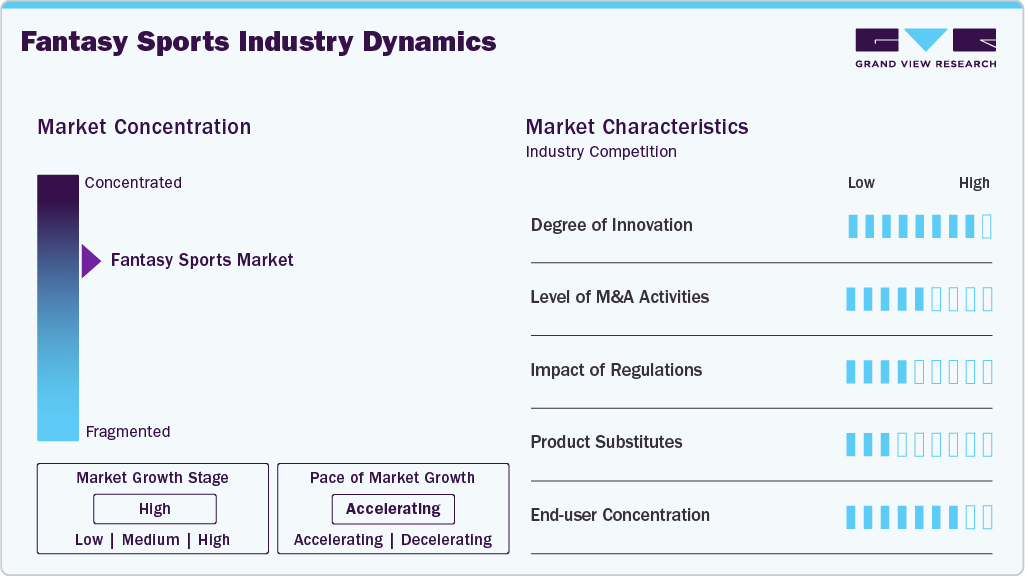
The fantasy sports market is moderately concentrated, with key players maintaining strong market positions through large user bases, advanced data analytics capabilities, and diversified fantasy gaming portfolios spanning multiple sports, including cricket, football, and basketball. The market is highly innovation-driven, supported by continuous advancements in real-time data integration, artificial intelligence, machine learning, predictive analytics, and personalized user experience technologies, which enhance engagement, retention, and monetization potential across digital platforms.
 To learn more about this report, Download Free Sample Report
The industry is evolving through strategic partnerships with sports leagues, media platforms, and streaming service providers, enabling deeper integration of live sports content and interactive gaming ecosystems. Regulatory frameworks governing online gaming, gambling classification, and digital payments significantly influence market operations, while licensing requirements and responsible gaming policies pose moderate barriers to entry. The threat of substitutes remains moderate due to the availability of alternative digital entertainment formats such as e-sports, sports betting, and casual mobile gaming. Moreover, demand is highly diversified across age groups and geographies, with growth closely linked to rising sports viewership, increasing smartphone penetration, and the expansion of global digital entertainment ecosystems.
Analyst Perspective
The fantasy sports market is gaining momentum owing to continuous technological advancements in mobile application development, real-time data streaming, artificial intelligence, and machine learning-based predictive analytics, cloud computing infrastructure, and API-driven sports data integration. These technologies enable seamless live scoring, personalized user experiences, and highly interactive contest formats, while improving platform scalability, security, and engagement. The integration of advanced payment gateways, gamification features, and cross-platform compatibility further enhances user participation and retention, driving sustained growth of the fantasy sports ecosystem globally.
Sports Insights
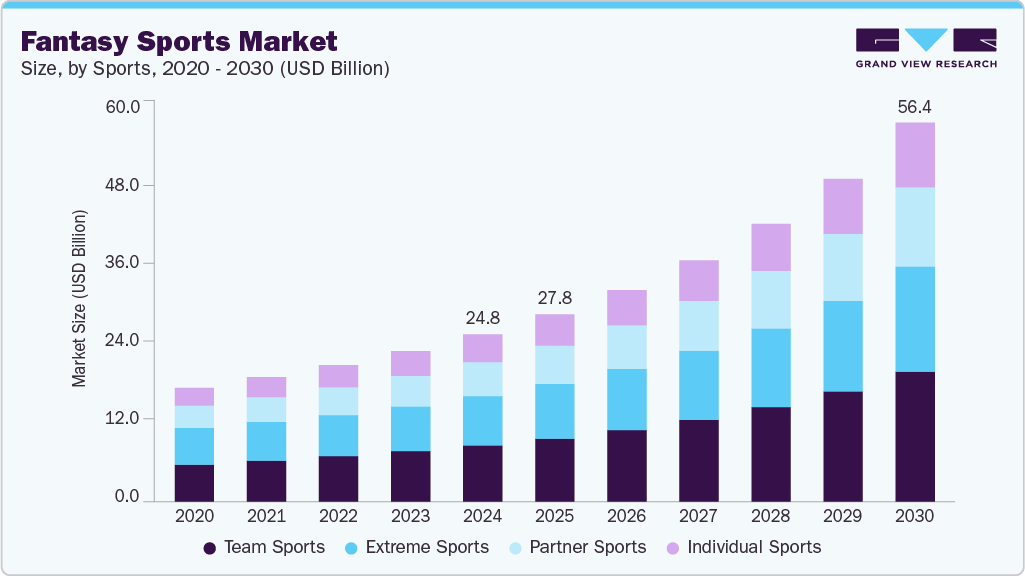
Based on sports, the individual sports segment led the market with the largest revenue share of 33.4% in 2025 and is expected to grow at a considerable CAGR over the forecast period, driven by the global popularity of traditional team-based sports such as football, basketball, and baseball. These sports have well-established leagues and tournaments that attract large fan bases, encouraging extensive participation in fantasy leagues. The social and competitive nature of team sports fantasy games, combined with live broadcasting and real-time data availability, enhances user engagement and retention, thereby driving the segmental growth.
The extreme sports segment is expected to witness the fastest CAGR of over 15% from 2026 to 2033, driven by growing global interest in adventure sports such as skateboarding, surfing, and snowboarding, especially among younger, tech-savvy users. The use of real-time data, immersive technologies (AR/VR), and AI-powered insights enhances fan engagement, while social media and streaming platforms boost visibility. Inclusion in major international events and rising demand for interactive, personalized fantasy contests are further expanding the user base and driving engagement in this segment.
Sports Type Insights
Based on sports type, the football/soccer segment dominated the market with the largest revenue share of 21.1% in 2025, supported by its massive global fan base and extensive league structures such as the English Premier League, La Liga, and FIFA tournaments. The sport’s year-round calendar and high media coverage foster continuous engagement in fantasy leagues. Integration with social media and mobile apps further enhances participation, allowing fans worldwide to connect and compete in real-time, thereby driving segmental growth.
The cricket segment is expected to witness the fastest CAGR from 2026 to 2033, driven by the sport’s surging popularity in emerging markets such as India, Southeast Asia, and the Middle East. Increasing smartphone penetration, affordable internet access, and the rise of T20 leagues have expanded the fan base, thereby driving the segmental growth. Mobile-based fantasy platforms tailored to cricket’s fast-paced format and regional preferences are attracting new users, boosting market growth.
Gameplay Insights
Based on gameplay, the team competition segment dominated the market with the largest revenue share of 68.3% in 2025, primarily driven by the social and interactive aspects of team-based fantasy contests. These competitions promote collaboration and rivalry among friends and communities, enhancing user engagement. The availability of diverse team formats and leagues across multiple sports also broadens appeal, making it a preferred choice for many fantasy sports enthusiasts and thereby driving segmental growth.
The individual competition segment is expected to witness the fastest CAGR from 2026 to 2033, driven by increasing demand for personalized, skill-based contests. AI and machine learning technologies enable real-time player performance tracking and customized game formats, appealing to users who prefer solo challenges. The rise of esports and other individual sports is further fueling the segment growth.
Device Insights
Based on device, the smartphones segment dominated the market with the largest revenue share of 50.6% in 2025, supported by widespread smartphone adoption, improved mobile internet connectivity, and the convenience of mobile apps that allow users to participate anytime and anywhere. Mobile platforms offer user-friendly interfaces, push notifications, and social sharing features, which significantly enhance user engagement and retention.
 To learn more about this report, Download Free Sample Report
The others segment is expected to witness a significant CAGR from 2026 to 2033, as cross-platform accessibility improves and users seek diverse ways to engage with fantasy sports. Enhanced web interfaces, tablet applications, and integration with smart TVs and wearable devices contribute to expanding the user base. This diversification caters to different user preferences and broadens market reach.
Demographic Insights
Based on demographics, the under 25 years segment dominated the market with the largest revenue share of 45.2% in 2025, primarily driven by the tech-savvy youth’s affinity for mobile gaming, social media integration, and interactive fantasy sports platforms. This demographic spends significant time on smartphones and online communities, making fantasy sports a popular avenue for social interaction, entertainment, and competition.
The 25 to 40 years segment is expected to witness a significant CAGR from 2026 to 2033, supported by rising disposable incomes, legalization of sports betting, and increasing interest in fantasy sports as a form of entertainment and social engagement. This age group values skill-based gaming and often participates in paid contests, contributing to market monetization and growth.
Platform Insights
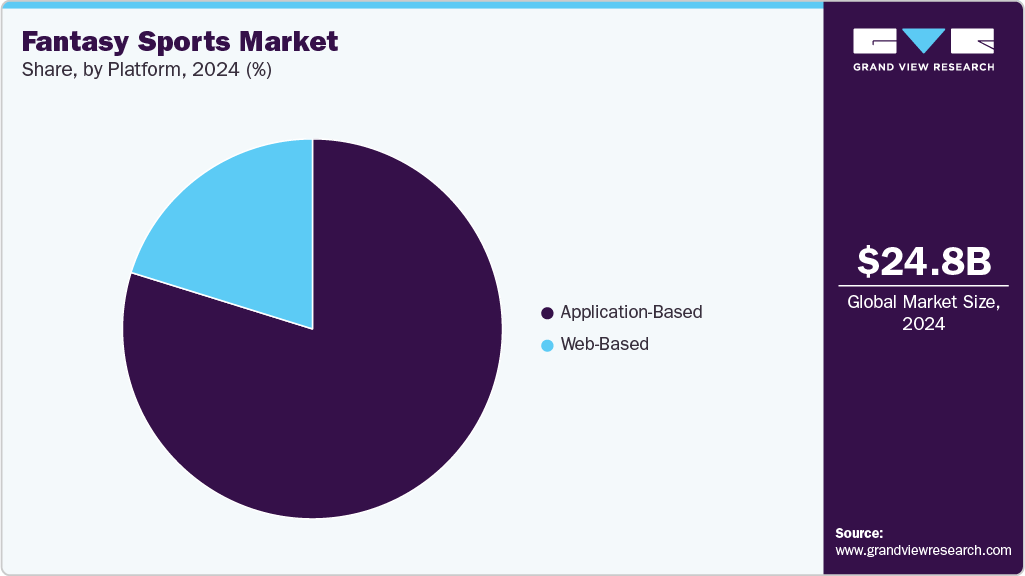
Based on platform, the application-based segment dominated the market with the largest revenue share of 78.1% in 2025, driven by the widespread adoption of smartphones, high-speed internet connectivity, and the demand for seamless, on-the-go user experiences. Advancements in AI and machine learning enable personalized recommendations, predictive analytics, and dynamic notifications, enhancing user engagement and retention. The rise of micro-transactions, multi-sport and niche league support, and enhanced social features further expands the user base, thereby driving the segmental growth.
The web-based segment is expected to witness a significant CAGR from 2026 to 2033, driven by its accessibility across multiple devices without requiring downloads, making it appealing for users who prefer desktop or cross-platform experiences. Web platforms often provide comprehensive interfaces with advanced analytics, real-time data visualization, and community forums, catering to serious fantasy sports enthusiasts and those managing multiple teams or leagues. The segment benefits from increasing internet penetration, cross-platform compatibility, and integration with social media, which enhances user interaction and sharing.
Regional Insights
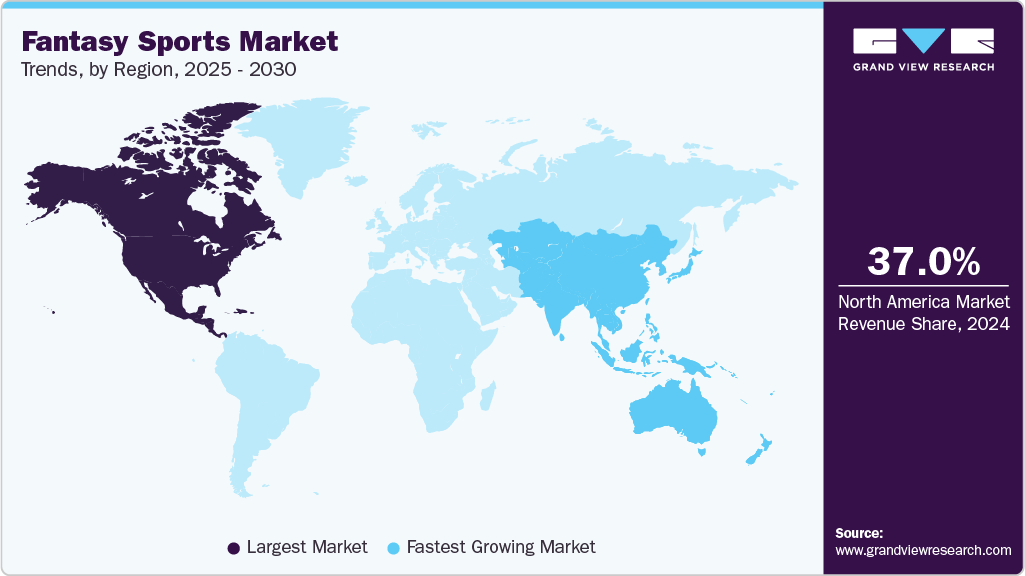
North America dominated the fantasy sports market, accounting for the largest revenue share of 38.2% in 2025, driven by the legalization and rapid expansion of sports betting across multiple states, with daily fantasy sports (DFS) dominating due to their shorter commitment and frequent play. The region benefits from high internet penetration, widespread smartphone adoption, and increasing consumer spending on fantasy sports, particularly in football, basketball, and baseball. Regulatory clarity and technological integration, including AI and mobile-first platforms, further fuel growth.
 To learn more about this report, Download Free Sample Report
U.S. Fantasy Sports Market Trends
The fantasy sports market in the U.S. held the largest share in the North America region in 2025, driven by technological advancements, such as AI-driven analytics and user-friendly interfaces, which enhance the gaming experience. Partnerships between fantasy platforms and professional leagues, along with engaging features like live drafts and rewards, continue to attract a diverse audience in the U.S.
Europe Fantasy Sports Market Trends
The European fantasy sports industry is expected to grow at a CAGR of over 12% from 2026 to 2033, owing to the growing legalization of sports betting, rising internet penetration, and increasing popularity of football and basketball fantasy leagues. Countries such as Germany, the UK, and France are key contributors, supported by strong sports culture and digital infrastructure. The market is further driven by innovations in AI, real-time data analytics, and immersive technologies like AR/VR, enhancing user engagement.
The UK fantasy sports industry is expected to grow at a significant rate in the coming years, driven by widespread sports enthusiasm, particularly for football and cricket, combined with a mature digital ecosystem and progressive regulatory environment for sports betting and fantasy gaming. Leading platforms integrate AI and machine learning for personalized user experiences, while partnerships with major sports leagues and broadcasters enhance content offerings. The rise of mobile gaming and social features also boosts participation and monetization opportunities.
The Germany fantasy sports industry is driven by increasing legalization of sports betting, strong football fandom, and rising adoption of mobile and online fantasy platforms. The market benefits from technological advancements in AI and data analytics, improving game formats and player engagement. Government initiatives to regulate and promote responsible gaming create a stable environment for market expansion.
Asia Pacific Fantasy Sports Market Trends
The Asia Pacific fantasy sports industry is expected to grow at a CAGR of over 17% from 2026 to 2033, fueled by a large, young, and tech-savvy population, rising smartphone penetration, and increasing disposable incomes. The market growth is further driven by increasing interest in cricket, football, and basketball fantasy leagues. The market also benefits from localized content, partnerships with sports leagues, and innovations such as AI and AR/VR integration.
The Japan fantasy sports industry is gaining traction, driven by the country’s strong sports culture, high smartphone usage, and increasing interest in fantasy leagues for baseball, soccer, and sumo wrestling. The market benefits from technological advancements such as AI-based player performance predictions and mobile app innovations. Regulatory frameworks are evolving to accommodate fantasy sports and sports betting, encouraging new entrants and partnerships with major sports leagues and media companies.
The China fantasy sports industry is rapidly expanding, driven by increasing internet and mobile device penetration and government initiatives to promote digital entertainment and sports engagement. However, regulatory restrictions on gambling and betting create challenges. The market focuses on social and casual fantasy games with an emphasis on basketball and football, supported by rising esports popularity. Integration of AI-driven analytics and partnerships with local sports organizations helps enhance user experience and market potential.
Key Fantasy Sports Company Insights
Some of the key players operating in the market are DraftKings, Inc., and FanDuel, among others.
-
DraftKings, Inc. is a U.S.-based sports technology company, initially launched as a daily fantasy sports platform. DraftKings expanded into sports betting and iGaming following the 2018 Supreme Court ruling that legalized sports betting in the U.S. The company offers a comprehensive suite of services, including daily fantasy sports, an online sportsbook, and casino games.
-
FanDuel is a premier mobile gaming destination in North America, offering a range of services including sports betting, iGaming, horse racing, and daily fantasy sports. The company was acquired by Flutter Entertainment in 2018 and operates FanDuel TV and FanDuel TV+, providing extensive sports content and live events. FanDuel is known for its user-friendly platforms and innovative features, such as Same Game Parlays, and maintains strong partnerships with major sports leagues such as the NFL, NBA, and MLB.
Dream Sports Group and MY11Circle are some of the emerging market participants in the fantasy sports industry.
-
Dream Sports Group operates a portfolio of brands, including Dream11, the world's largest fantasy sports platform with over 230 million users. Other brands under its umbrella include FanCode, a digital sports platform offering live streaming and merchandise, and DreamSetGo, a sports travel and experiences platform. Dream Sports aims to "Make Sports Better" by leveraging technology to enhance the sports ecosystem in India.
-
RotoWire is a U.S.-based provider of expert fantasy sports news and advice that offers comprehensive coverage across major sports, including MLB, NFL, NBA, NHL, college football, college basketball, esports, MMA, and more. In January 2022, RotoWire was acquired by Gambling.com Group Limited (NASDAQ: GAMB), a performance marketing company specializing in the online gambling industry. This acquisition has enabled RotoWire to expand its offerings into sports betting, including the launch of "Prop Points," a daily TV show on VSiN featuring RotoWire analysts discussing player props across fantasy sports and the betting market.
Key Fantasy Sports Companies:
The following key companies have been profiled for this study on the fantasy sports market.
-
Dream Sports Group
-
CBS Sports Digital
-
Realtime Fantasy Sports Inc.
-
Flutter Entertainment plc
-
Vauntek Inc. (Fantrax)
-
DraftKings
-
Pure Win (Sweetspot N.V.)
-
FanDuel
-
FantasyPros.com
-
MY11Circle
-
FANTACALCIO (Quandronica Srl)
-
RotoWire (GDC Media Limited)
-
NBC Sports Edge (NBC Sports Group)
-
MyFantasyLeague (Sideline Software Inc.)
-
Office Football Pool (OFP Hosting Inc.)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (DraftKings, FanDuel, Flutter Entertainment plc, CBS Sports Digital, NBC Sports Edge)
- Focus on large-scale daily fantasy sports (DFS), sportsbook-integrated ecosystems, real-time contest platforms, and subscription-based fantasy content services.
- Heavy investment in mobile-first platforms, live data integration, AI-driven recommendations, and cross-selling between betting, fantasy, and media.
- Strong brand recognition, massive user bases, high liquidity contests, advanced technology infrastructure, deep sports data partnerships, and strong monetization via DFS, ads, and betting convergence.
- High regulatory exposure across regions, high marketing costs, dependence on sports seasons, and rising customer acquisition costs.
Emerging & Specialized Players (Dream Sports Group, MY11Circle, Vauntek Inc. (Fantrax), FantasyPros.com, RotoWire (GDC Media Limited), Pure Win (Sweetspot N.V.)
- Focus on low-entry-cost fantasy contests, localized sports formats, micro-contests, and mobile-first engagement in developing markets.
- Strong emphasis on gamification, freemium models, and localized user engagement strategies.
- Fast user acquisition in emerging markets, high engagement via gamification, and strong appeal to first-time fantasy users.
- High agility, strong penetration in emerging markets, deep engagement in niche or sport-specific communities, strong content/analytics authority (for some players), and flexible product customization.
- Low scalability, weak global brand recognition, and limited capital for expansion.
- Limited mobile-first innovation, weaker monetization compared to DFS platforms, and slower adoption among younger, casual users.
Recent Developments
-
In May 2025, Dream Sports Group announced a strategic partnership with Microsoft at WAVES 2025 to publish Microsoft’s gaming portfolio in India and co-develop AI-driven gaming experiences tailored for Indian gamers. This collaboration aims to leverage Microsoft’s technical and AI expertise alongside Dream Sports’ 250 million user base to redefine the future of online gaming in India
-
In May 2025, CBS Sports announced a landmark multi-platform rights agreement with World Rugby, making Paramount+ the exclusive U.S. home for all men’s and women’s World Rugby events, including the next three Rugby World Cups and all USA national team matches. This deal significantly expands rugby’s visibility and fan engagement in the U.S. across streaming and linear platforms.
-
In March 2025, U.S. Soccer and CBS Sports reached a multi-year multimedia rights agreement, granting CBS Sports exclusive English-language coverage of the Lamar Hunt U.S. Open Cup. CBS Sports will stream every match live on Paramount+ and provide extensive ancillary content, boosting the tournament’s accessibility and popularity among U.S. soccer fans.
Fantasy Sports Market Report Scope
Report Attribute
Details
Market size in 2025
USD 27.8 billion
Estimated market size in 2026
USD 31.4 billion
Projected market size by 2033
USD 75.1 billion
Growth rate
CAGR of 13.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Sports, sports type, platform, gameplay, device, demographic, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; China; Japan; India; South Korea; Australia, Brazil; Mexico; UAE; Saudi Arabia; South Africa
Key companies profiled
Dream Sports Group; CBS Sports Digital; Realtime Fantasy Sports Inc.; Flutter Entertainment plc; Vauntek Inc. (Fantrax); DraftKings, Inc.; Pure Win (Sweetspot N.V.); FanDuel; FantasyPros.com; MY11Circle; FANTACALCIO (Quandronica Srl); RotoWire (GDC Media Limited); NBC Sports Edge (NBC Sports Group); MyFantasyLeague (Sideline Software Inc.); Office Football Pool (OFP Hosting Inc.)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Fantasy Sports Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest technological trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the fantasy sports market report based on sports, sports type, platform, gameplay, device, demographic, and region:
-
Sports Outlook (Revenue, USD Million, 2021 - 2033)
-
Individual Sports
-
Partner Sports
-
Team Sports
-
Invasion Game
-
Net Game
-
Field & Striking Game
-
Target Game
-
-
Extreme Sports
-
-
Sports Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Sports Type
-
American Football (Rugby)
-
Baseball
-
Basketball
-
Car Racing
-
Cricket
-
Football/Soccer
-
Others (MMA, Boxing, Golf, eSports, Etc.)
-
-
Platform Outlook (Revenue, USD Million, 2021 - 2033)
-
Web-Based
-
Application-Based
-
-
Gameplay Outlook (Revenue, USD Million, 2021 - 2033)
-
Individual Competition
-
Team Competition
-
-
Device Outlook (Revenue, USD Million, 2021 - 2033)
-
Smartphones
-
Computer
-
Others
-
-
Demographics Outlook (Revenue, USD Million, 2021 - 2033)
-
Under 25 Years
-
25 to 40 Years
-
Above 40 Years
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The fantasy sports market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each fantasy sports segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Sports
Revenue capture definition
Individual Sports
Revenue is generated through participation fees, contest entry charges, and microtransactions, with users competing in solo, athlete-based formats; monetization is driven by per-contest entries, premium analytics, and player-specific fantasy picks.
Partner Sports
Revenue is captured through team-based or paired participation formats where users collaborate or co-manage teams, generating income via shared contest entry fees, co-play subscription models, and referral-driven multiplayer engagement monetization.
Team Sports
Revenue is captured through entry fees, league participation charges, and recurring contest subscriptions in fantasy formats based on team-based real-world sports such as football, basketball, and cricket, supported by high-frequency contests and season-long leagues.
Extreme Sports
Revenue is captured through niche contest participation fees, event-based fantasy leagues, and premium predictive gameplay tied to high-engagement extreme or combat sports, often monetized via specialized tournaments and high-margin enthusiast communities.
Segment - Sports Type
Revenue capture definition
American Football (Rugby)
Revenue is captured through fantasy league entry fees, season-long contest subscriptions, and in-app purchases linked to player statistics, performance tracking tools, and premium match insights.
Baseball
Revenue is captured through daily and seasonal fantasy contest fees, data-driven subscription services, and monetization of advanced player analytics and matchup prediction tools.
Basketball
Revenue is generated through high-frequency daily fantasy contests, league entry fees, in-app boosts, and premium statistical insights driven by continuous match schedules.
Car Racing
Revenue is captured through event-based fantasy contests, race prediction pools, and premium participation fees tied to individual race weekends and championship seasons.
Cricket
Revenue is captured through high-volume contest entry fees, tournament-based fantasy leagues (especially T20 formats), and subscription-based premium insights and team optimization tools.
Football/Soccer
Revenue is generated through global league-based fantasy contests, season-long entry fees, and recurring subscription models, all driven by major tournaments and club competitions.
Others
Revenue is captured through niche fantasy contests, pay-per-event entry fees, and premium prediction tools across specialized sports categories with strong fan engagement.
Segment - Platform
Revenue capture definition
Web-Based
Revenue is captured through desktop-based contest participation fees, subscription plans, and advertising monetization from users engaging in fantasy sports via browser platforms.
Application-Based
Revenue is captured through in-app contest entry fees, in-app purchases (boosts, analytics, upgrades), push-driven engagement monetization, and subscription-based premium features.
Segment - Gameplay
Revenue capture definition
Individual Competition
Revenue is captured through single-user entry fees, one-on-one contests, and performance-based microtransactions, in which users compete independently with selected players.
Team Competition
Revenue is captured through group-based contest fees, league entry fees, and pooled reward systems in which users compete in structured team or league formats.
Segment - Device
Revenue capture definition
Smartphones
Revenue is captured through mobile-first in-app purchases, contest entry fees, real-time gameplay monetization, and high-frequency microtransactions driven by on-the-go participation.
Computer
Revenue is generated through web-based contest subscriptions, desktop entry fees, and access to premium analytical tools used by advanced or professional users.
Others
Revenue is captured through emerging or secondary devices such as tablets or connected platforms, monetized via cross-device subscriptions and synchronized gameplay features.
Segment - Demographics
Revenue capture definition
Under 25 Years
Revenue is captured through low-ticket entry fees, freemium upgrades, in-app purchases, and high-engagement microtransaction behavior driven by mobile-first and gamified experiences.
25 to 40 Years
Revenue is captured through higher-value contest participation fees, subscription-based premium analytics, and consistent spending on multi-league or professional-style fantasy engagement.
Above 40 Years
Revenue is captured through selective but high-value participation in premium contests, subscription services, and lower-frequency but higher-ticket fantasy sports investments driven by experience and disposable income.
Estimation Model
Layer Name
Key Question
Description
Addressable End-User Layer
Who are the potential fantasy sports users?
Represents the total addressable user base engaging with fantasy sports platforms. This includes sports fans across demographics, including casual viewers, passionate sports enthusiasts, and professional fantasy players. It spans users who follow cricket, football/soccer, basketball, baseball, and other sports across regions such as North America, Europe, Asia Pacific, Latin America, and MEA, with strong participation from mobile-first users and digitally engaged audiences.
Technology & Infrastructure Layer
What technologies enable fantasy sports capabilities?
Includes core enabling technologies such as mobile applications, web platforms, cloud computing infrastructure, real-time sports data feeds, APIs for live scoring, AI/ML-based predictive analytics, blockchain-based contest transparency systems, payment gateways, cybersecurity systems, and scalable backend infrastructure supporting high-traffic live sports events and microtransaction processing.
Application & Deployment Layer
How are fantasy sports solutions utilized?
Covers key application areas including daily fantasy sports contests, season-long fantasy leagues, head-to-head competitions, tournament-based gaming, predictive sports analytics platforms, esports fantasy formats, social gaming integrations, and gamified sports engagement platforms. This layer reflects how fantasy sports products are deployed to enhance fan engagement, retention, and monetization across sports ecosystems.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through multiple monetization streams, including contest entry fees, platform commissions, subscription-based premium features, in-app purchases (boosters, analytics, upgrades), advertising revenue, sponsorship and brand partnerships, data monetization, affiliate marketing, and transaction fees on prize pools. Additional revenue comes from premium analytics tools, VIP contests, and recurring memberships for advanced users.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Sizing, Competitive Landscape & Growth Opportunity Assessment
Assessed global fantasy sports market size, growth trends, segmentation by sports, platforms, and regions, along with competitive landscape and key player positioning across mature and emerging markets.
Supports market entry strategy, identifies high-growth regions and segments, improves investment prioritization, and strengthens competitive positioning.
Technology Roadmap & Innovation Opportunity Assessment
Evaluated key technologies, including AI/ML analytics, real-time sports data APIs, cloud infrastructure, blockchain-based transparency, and gamification systems shaping fantasy sports platforms.
Enables innovation planning, improves platform scalability and engagement, supports digital transformation, and enhances user experience capabilities.
Regional Market Demand & Deployment Opportunity Analysis
Analyzed regional adoption trends, regulatory environments, sports preferences, digital infrastructure, and monetization maturity across major global regions.
Supports geographic expansion, improves regulatory planning, enables targeted user acquisition, and identifies high-growth regional opportunities.
Frequently Asked Questions About This Report
The application-based segment dominated the market, accounting for the largest revenue share of 78.1% in 2025.
The team competition segment dominated the market, accounting for the largest revenue share of 68.3% in 2025.
The smartphones segment dominated the market with the largest revenue share of 50.6% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Key players operating in the fantasy sports market include Dream Sports Group; CBS Sports Digital; Realtime Fantasy Sports Inc.; Flutter Entertainment plc; Vauntek Inc. (Fantrax); DraftKings, Inc.; Pure Win (Sweetspot N.V.); FanDuel; FantasyPros.com; MY11Circle; FANTACALCIO (Quandronica Srl); RotoWire (GDC Media Limited); NBC Sports Edge (NBC Sports Group); MyFantasyLeague (Sideline Software Inc.); Office Football Pool (OFP Hosting Inc.)
Key factors that are driving the fantasy sports market growth include the rising affordability of high-speed internet services and the increased penetration of smartphones.
The global fantasy sports market size was valued at USD 27.8 billion in 2025 and is projected to grow from USD 31.4 billion in 2026
The global fantasy sports market is expected to grow at a compound annual growth rate of 13.3% from 2026 to 2033 to reach USD 75.1 billion by 2033.
North America dominated with a 38.2% revenue share in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


