
- Home
- »
- Homecare & Decor
- »
-
Real Estate Market Size, Share & Growth Report, 2026-2033GVR Report cover

Real Estate Market (2026 - 2033)
Size, Share & Trends Analysis Report By Property (Residential, Commercial, Industrial, Land), By Type (Sales, Rental, Lease), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$4,332.4BMarket Estimate, 2026
$4,557.7BMarket Forecast, 2033
$7,351.3BCAGR, 2026–2033
7.1%Real Estate Market Summary
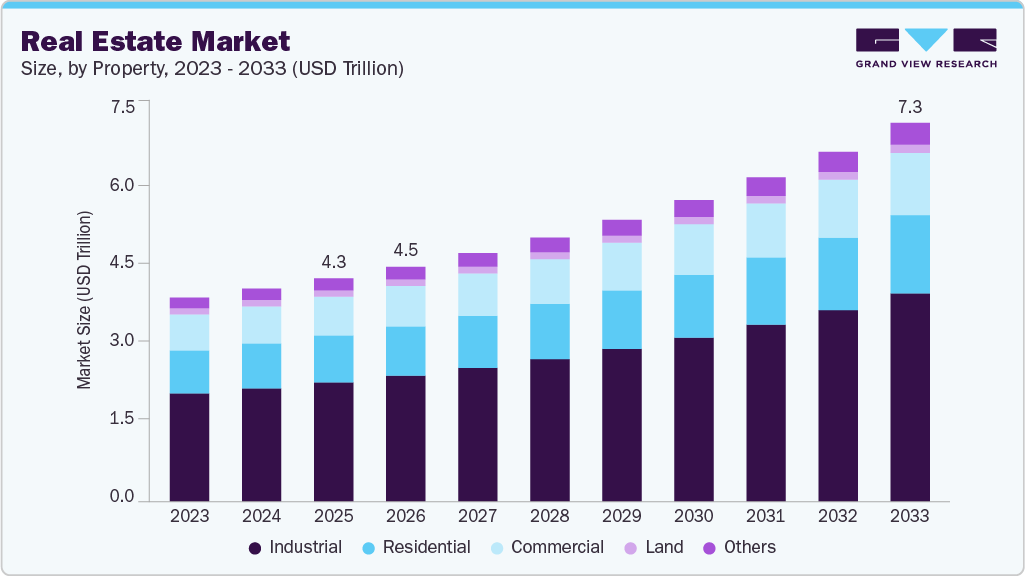
The global real estate market size was valued at USD 4,332.4 billion in 2025 and is projected to grow from USD 4,557.7 billion in 2026 to USD 7,351.3 billion by 2033, at a CAGR of 7.1% from 2026 to 2033. Asia Pacific dominated the global market, accounting for a revenue share at 53.4% in 2025. The market is undergoing structural changes as urbanization, demographic shifts, changing space requirements, and capital allocation patterns reshape demand across residential, commercial, industrial, and specialized property segments.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By property: Residential real estate segment held the largest market share of 35.5% in 2025.
- By type: Rental segment accounted for the largest market share of 51.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (53.4% revenue share, 2025)
- By country: China is projected to grow at a CAGR of 7.8% from 2026 to 2033
Market Size & Forecast
- Market size in 2025: USD 4,332.4 Billion
- Estimated market size in 2026: USD 4,557.7 Billion
- Projected market size by 2033: USD 7,351.3 Billion
- CAGR (2026-2033): 7.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In 2025, the United Nations reported that cities were home to 45% of the global population, underscoring the continuing expansion of urban real estate requirements. Institutional capital is increasingly being allocated across logistics, multifamily housing, data centers, healthcare properties, and other specialized real estate assets. In the U.S., Prologis has linked logistics demand to e-commerce expansion, supply-chain modernization, and the need for strategically located distribution facilities. Its 2025 annual report also identifies data centers as a growing development opportunity, supported by rising demand for cloud computing and AI infrastructure. This diversification is broadening the investment landscape beyond traditional office and residential properties and increasing interest in specialized infrastructure requirements.
 To learn more about this report, Download Free Sample Report
Capital allocation is also becoming more selective as investors reassess property performance in response to changes in interest rates, workplace utilization, and consumer behavior. In India, equity inflows into the real estate market exceeded USD 14 billion in 2025, with substantial investment directed toward land and development sites, built-up office properties, and warehousing. During the first quarter of 2026, built-up office assets accounted for a particularly significant portion of investment activity, while Real Estate Investment Trusts (REITs) remained active participants. Investors are therefore placing greater emphasis on income visibility, location, tenant quality, infrastructure access, and opportunities for operational improvement rather than evaluating properties solely by traditional asset categories.
Urbanization remains a fundamental source of long-term real estate demand, although the pace and form of urban growth differ considerably across regions. According to the United Nations World Urbanization Prospects 2025, cities were home to 45% of the global population of 8.2 billion in 2025, while two-thirds of global population growth through 2050 is projected to occur in cities. This concentration of population is supporting demand for housing, offices, logistics facilities, retail properties, healthcare assets, and related infrastructure. In emerging economies, urban expansion is closely associated with new residential construction and transport-linked development. In contrast, mature markets are placing greater emphasis on redevelopment, adaptive reuse, and improving the efficiency of existing buildings.
The commercial real estate market is consequently undergoing a broad repositioning. E-commerce continues to support logistics and distribution facilities, while changing workplace practices are influencing office occupancy, location preferences, and space configuration. Prologis has reported continued demand for logistics space around major population centers as delivery requirements intensify. At the same time, investors are allocating greater attention to alternative sectors such as data centers, healthcare, flexible workspaces, hospitality, and specialized living assets. India’s investment activity during 2025 and early 2026 reflects this wider diversification across office, warehousing, residential development, and emerging alternative segments.
Residential real estate is also changing in terms of product mix and buyer preferences. In India, residential sales and launches both exceeded 270,000 units during 2025, while high-end housing surpassed the mid-end segment in sales share, indicating stronger activity in higher-value residential products. Changes in household structures, affordability, mobility, and preferences for professionally managed housing are also encouraging developers and investors to consider build-to-rent, multifamily, senior housing, and other specialized residential formats. These trends are contributing to a more differentiated housing market rather than uniform expansion across all price categories.
Digitalization is reshaping how properties are developed, marketed, leased, and managed. Virtual property tours, digital transaction platforms, automated building management systems, IoT-enabled monitoring, and data analytics are becoming more integrated into real estate operations. For developers and brokers, these tools can extend the geographic reach of property marketing and streamline engagement with prospective buyers and tenants. For owners and operators, connected systems provide greater visibility into occupancy, energy consumption, maintenance requirements, and overall asset performance. Over time, this is supporting a shift toward real estate assets that combine physical infrastructure with digital operating capabilities.
Sustainability is becoming another important consideration in development and asset management. The International Energy Agency estimates that buildings account for around 30% of global energy demand, while its recent policy analysis emphasizes building energy codes, efficiency standards, and retrofit measures as important tools for improving building performance. As regulations and tenant expectations evolve, energy-efficient construction, electrification, renewable energy integration, green certifications, and building retrofits are increasingly influencing capital expenditure and property management decisions. This is particularly relevant for older commercial buildings, where improvements in energy performance can affect operating costs, regulatory compliance, tenant appeal, and long-term asset value.
Impact of U.S. Tariffs on Real Estate Construction
Trade policy changes in the U.S. during 2025 created additional uncertainty regarding construction costs and housing affordability, particularly for imported building materials. The impact varied by material and country of origin rather than resulting from a single uniform tariff regime. In April 2025, the National Association of Home Builders reported that Canadian and Mexican products remained exempt from the newly announced reciprocal tariffs, while existing duties on Canadian softwood lumber continued to affect builders. By September 2025, the U.S. Commerce Department had announced a 10% tariff on timber and lumber imports, as well as additional tariffs on kitchen cabinets and furniture. Canadian lumber was also subject to higher trade duties, increasing the cost pressure on U.S. homebuilders.
The effect extends beyond material prices because construction projects typically involve long planning and procurement cycles. In April 2025, NAHB reported that builders estimated recent tariff actions could add approximately USD 10,900 to the cost of a typical home, while more than 60% of surveyed builders reported higher costs attributable to tariffs. NAHB also estimated that imported goods represented about 7% of the materials used in new U.S. residential construction in 2025. These conditions can affect project budgets, pricing strategies, procurement decisions, and construction schedules, particularly for developers who depend on imported lumber, metals, electrical components, appliances, and other building inputs. For commercial real estate, the implications are similarly transmitted through construction and fit-out costs rather than through property demand alone. Higher prices for structural materials, electrical equipment, fixtures, and other imported inputs can increase development budgets and complicate fixed-price contracts. The effect is likely to vary considerably by asset type and project stage, with new construction generally more exposed than stabilized properties. As a result, developers and investors may place greater emphasis on domestic sourcing, procurement flexibility, cost contingencies, and phased development when trade conditions remain volatile.
Market Dynamics
The real estate market is influenced by a mix of demand factors, development challenges, and new investment opportunities in residential, commercial, and specialized property sectors. Rapid urbanization, housing shortages, and infrastructure development are driving the demand for built spaces. However, issues such as affordability pressures, financing costs, land availability, and regulatory requirements can slow down the pace of new development. Additionally, the growth of affordable housing programs, resilient construction practices, sustainable buildings, and technology-driven urban development is creating new opportunities for developers and investors.
Rapid urbanization is driving the demand for residential, commercial, and mixed-use properties. Currently, more than half of the global population lives in cities, and the World Bank projects that this figure will approach 70% by 2050. Growing urban populations will necessitate additional housing, transportation networks, commercial facilities, and public infrastructure, creating ongoing development opportunities in both established metropolitan areas and emerging cities.
Infrastructure investment is also influencing where real estate development takes place. Investments in mass transit, roads, utilities, digital networks, and other urban infrastructure can enhance connectivity and increase the development potential of surrounding areas. This is especially important in emerging markets, where urban expansion is creating new residential and commercial corridors. Rapid urbanization requires substantial investments in resilient infrastructure and affordable housing. Improved land-use planning and connectivity can further strengthen the economic role of cities.
High construction costs, elevated financing requirements, high land prices, and the limited availability of affordable housing can hinder real estate development and reduce purchasing power. Developers must increasingly balance project feasibility with affordability demands, as rising financing costs can impact both construction activities and mortgage affordability for end users. Additionally, regulatory requirements related to building standards, environmental performance, land use, and permitting can extend project timelines and increase development costs, especially for large-scale urban projects. These challenges are particularly significant in rapidly growing cities where the demand for housing is surpassing the available supply.
The shortage of adequate and affordable housing presents opportunities for developers, housing financiers, and infrastructure investors to expand supply through scalable residential models. The World Bank estimates that over one billion people live in slums and informal settlements. Its Global Urban Housing Program focuses on improving housing supply, access to land and infrastructure, developer capacity, innovative construction models, and sustainable housing finance. This program enables organized developers to participate in affordable and mid-income housing projects through public-private partnerships, housing finance initiatives, and transit-linked developments.
In addition, resilient, energy-efficient construction offers long-term opportunities in the real estate market. The demand for buildings that manage energy use, climate risks, and resource constraints is on the rise. Developers can differentiate their new projects by incorporating efficient building systems, renewable energy integration, smart infrastructure, climate-resilient materials, and digital building management. These features are becoming increasingly important to investors and occupiers as operating costs, environmental requirements, and resilience considerations play a significant role in property selection and asset management.
Analyst Perspective
The real estate market is being reshaped by urbanization, demographic shifts, evolving lifestyles, and changing business activity, driving demand across residential, commercial, and mixed-use properties. Developers are increasingly prioritizing well-connected locations, integrated projects, flexible spaces, and access to essential services. Construction costs, interest rates, land availability, regulations, and financing conditions continue to influence project feasibility and investment decisions. Digital platforms, data analytics, virtual tools, and smart building technologies are transforming property marketing and management, while sustainability is driving energy-efficient construction. Future competitiveness will depend on adapting to demand trends, controlling costs, leveraging technology, and delivering properties aligned with long-term market needs.
Property Insights
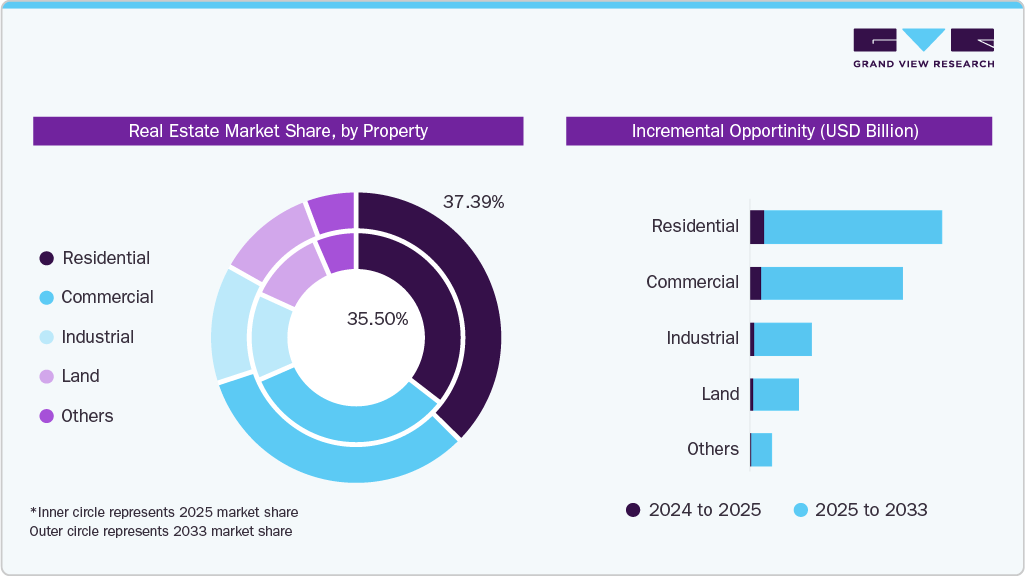
The residential real estate industry segment accounted for a revenue share of 35.5% in 2025, supported by demand across both homeownership and rental housing. Population growth, urbanization, and the formation of new households are driving an increased demand for residential space. Access to mortgage financing plays a crucial role in influencing homebuying activity. However, affordability and borrowing costs are significant factors affecting people's housing choices. A study by the IMF, published in 2025, found that higher mortgage rates have limited some renters' ability in the U.S. to transition to homeownership, putting additional strain on local rental markets. As a result, rental housing continues to be a vital part of residential demand, bolstered by workforce mobility, delayed homeownership, and affordability challenges in major urban centers.
 To learn more about this report, Download Free Sample Report
The commercial property segment is projected to grow at a CAGR of 6.9% from 2026 to 2033, driven by continued activity across office, retail, and hospitality assets. Office demand is being influenced by corporate expansion, professional services, and technology-driven services, as well as the gradual normalization of hybrid work. Recent global data shows a positive trend in office leasing activity. In the retail sector, demand for well-located, experience-oriented spaces is rising, especially in prime areas with high foot traffic. This demand, combined with limited new supply, is boosting leasing activity. Additionally, the hotel real estate market is benefiting from the resurgence of international, group, and business travel, which is enhancing occupancy rates and encouraging investment in hospitality assets.
Type Insights
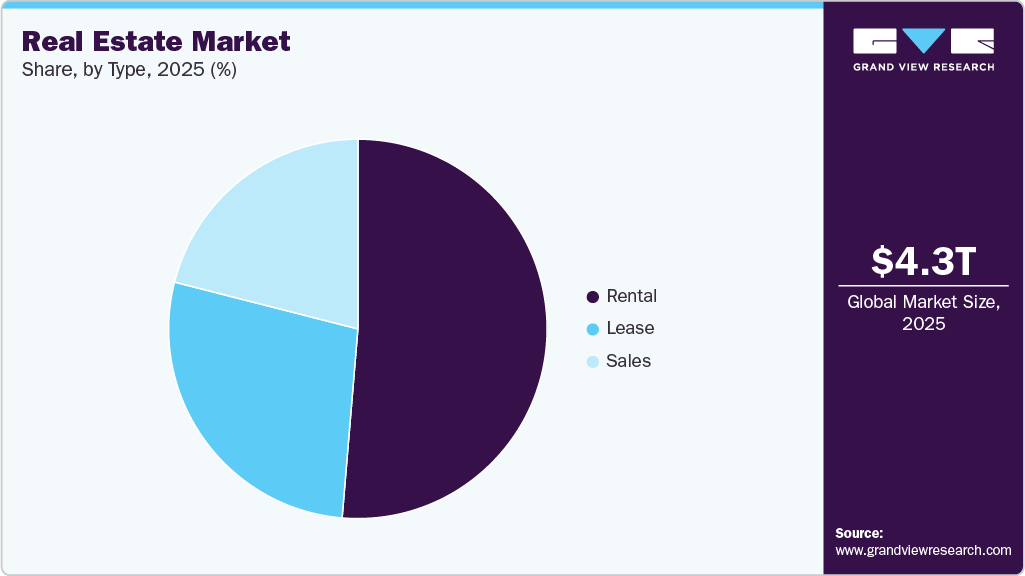
Rental properties dominated the real estate industry, accounting for approximately 51.3% revenue share in 2025, reflecting the substantial role of rental housing within the residential property segment. Demand remains supported by urban population growth, workforce mobility, delayed homeownership, and affordability constraints that make purchasing less accessible for some households. Higher mortgage costs can further extend rental tenure by limiting first-time buyers' ability to transition into ownership. An IMF study found that rising mortgage rates between 2021 and 2023 reduced the transition of U.S. renters into homeownership and added pressure to local rental markets. Remote and hybrid work arrangements have also influenced residential preferences in some markets, encouraging demand for homes that provide greater flexibility in location and space. These factors continue to support occupancy and investment across rental-focused residential developments, particularly in major employment centers and high-demand urban markets.
 To learn more about this report, Download Free Sample Report
The sales type segment is estimated to grow at a CAGR of 8.1% from 2026 to 2033, supported by continued urbanization, household formation, and demand for owner-occupied housing. Rising household incomes and access to mortgage financing can strengthen purchasing capacity, although affordability and borrowing costs remain important determinants of homebuying decisions. In emerging urban markets, population concentration around employment and economic centers is creating additional demand for new housing supply. India, for example, is expected to see its urban population reach 951 million by 2050, with more than 144 million additional homes required by 2070, illustrating the longer-term scale of housing demand associated with urbanization. Preferences for larger homes, better amenities, planned communities, and improved connectivity are also supporting demand across primary and secondary residential markets.
Regional Insights
 To learn more about this report, Download Free Sample Report
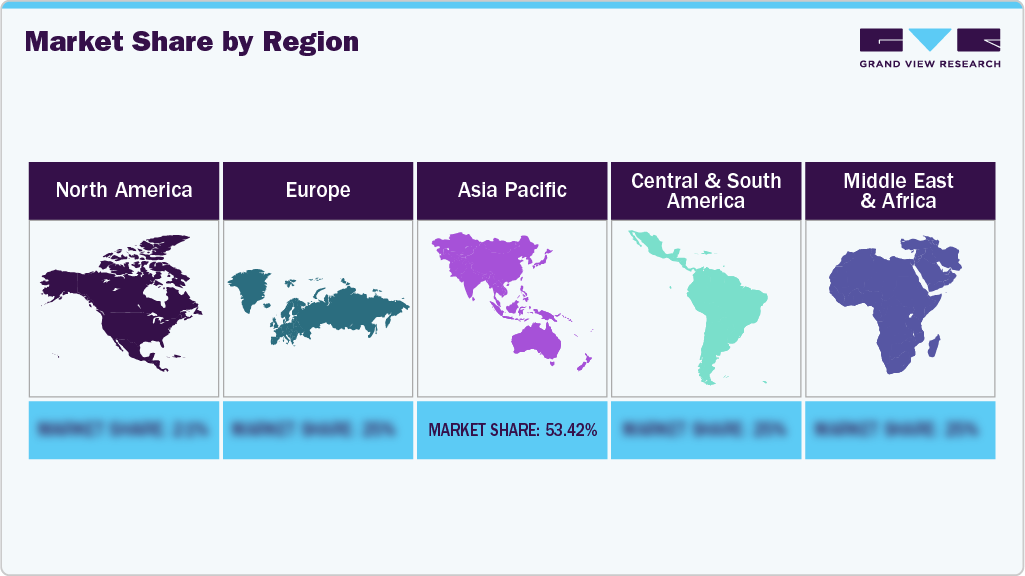
The North America real estate market accounted for a revenue share of 21.0% in 2025, supported by established housing markets, employment growth, household formation, and continued population shifts toward major metropolitan and suburban areas. In the U.S., residential demand is being shaped by housing affordability, mortgage costs, and migration toward employment centers, while commercial real estate activity is supported by improving capital-market conditions and demand for income-generating properties. Within the office real estate sector, occupiers and investors are increasingly selective, with demand concentrated in higher-quality and well-located buildings. Industrial and logistics properties continue to benefit from e-commerce, supply-chain restructuring, and demand for modern facilities that improve distribution efficiency and resilience.
The U.S. real estate market accounted for 62.6% of the North American market in 2025. Population and employment growth in sectors such as technology, healthcare, and professional services, together with migration toward high-growth metropolitan and Sun Belt markets, continues to support demand for housing and commercial property. The U.S. investment market also showed broader activity in 2025, with full-year net-lease investment reaching USD 51.4 billion, up 16% year over year. Industrial and logistics properties represented 55% of fourth-quarter net-lease investment, while office and retail accounted for 24% and 21%, respectively.
Europe Real Estate Market Trends
The Europe real estate industry accounted for 17.3% of global revenue share in 2025, supported by sustained housing demand, urban regeneration, rental activity, and investment in the modernization of existing property stock. Housing affordability remains an important market factor as house prices and rents continue to rise across the region. Eurostat reported that EU house prices increased 5.5% year over year in the fourth quarter of 2025, while rents rose 3.2%. Demand for rental housing remains particularly relevant in large metropolitan areas where high purchase prices and limited housing supply constrain homeownership. In addition, the aging building stock is creating opportunities for renovation, redevelopment, and energy-efficiency upgrades. Environmental requirements are also influencing investment decisions as property owners increasingly need to improve the energy performance of existing buildings.
The Germany real estate market accounted for 18.4% revenue share of Europe in 2025, supported by its large urban housing base and structurally high rental participation. Germany remains distinct in Europe because renting is more prevalent than homeownership; Eurostat reported that 53% of the population lived in rented housing in 2024, the highest rental share of any EU country. Housing availability remains a key issue, particularly in cities, where Destatis reported that 16.9% of the urban population lived in overcrowded housing in 2025. Policy measures, such as extending Germany's rent brake through 2029, are also shaping the rental market, while urban redevelopment and infrastructure investment continue to support housing development in major cities and surrounding areas.
The real estate market in the UK is estimated to grow at a CAGR of 6.2% from 2026 to 2033, supported by persistent housing requirements, limited availability in high-demand locations, and demand for both owner-occupied and rental properties. England had approximately 25.8 million dwellings as of March 2025, including 5.0 million private rented dwellings, while the total dwelling stock increased by 208,600 units year over year. Brownfield redevelopment is becoming an important component of new housing supply, with the UK Government's Platform4 initiative announced in July 2025, targeting up to 40,000 homes through the redevelopment of surplus railway land over the following decade. In commercial real estate, demand is increasingly concentrated in well-located logistics and industrial assets, while office activity remains focused on higher-quality buildings with modern infrastructure and strong transport connectivity.
Asia Pacific Real Estate Market Trends
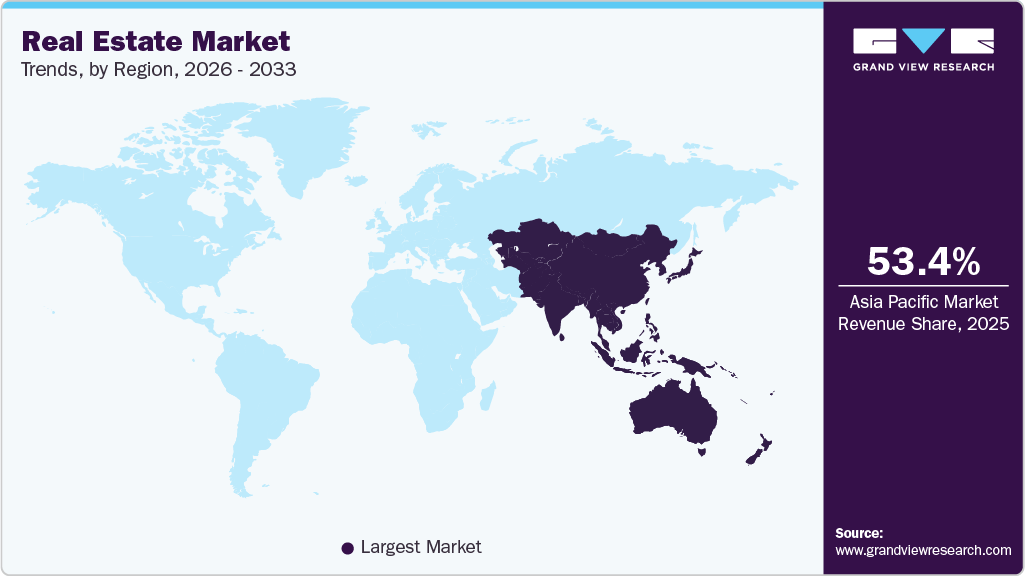
The Asia Pacific real estate industry accounted for 53.4% of global revenue in 2025, supported by rapid urban development, strong housing demand, infrastructure investment, and continued economic activity across developed and emerging economies. Urban migration is a significant driver of residential demand, as populations and jobs become increasingly concentrated in metropolitan and secondary cities. The expansion of infrastructure is also transforming development patterns by enhancing connectivity and creating new residential and commercial areas. Additionally, activities in manufacturing, domestic consumption, and services continue to fuel the demand for industrial, logistics, retail, and office properties in major economic centers. Investors are becoming more selective in their capital allocation, increasingly focusing on markets and asset classes that offer established infrastructure, income potential, and visibility into long-term demand.
 To learn more about this report, Download Free Sample Report
The China real estate market is projected to grow at a CAGR of 7.8% from 2026 to 2033. This growth will increasingly be driven by urban renewal, housing replacement, and the redevelopment of existing properties. Instead of focusing solely on new construction, policy initiatives are now directing investments toward upgrading older residential areas, enhancing urban infrastructure, and developing higher-quality housing. In 2025, China began constructing 1.21 million units of government-subsidized housing and initiated the renovation of 27,000 old urban residential communities, benefiting approximately 4.99 million households. In May 2026, the State Council released a 2026-2030 urban renewal plan that emphasizes the better use of underused land, higher-quality housing, improved municipal infrastructure, and greener, more resilient urban development. These initiatives are creating a steady source of activity for residential redevelopment, infrastructure-linked commercial projects, and the modernization of aging urban assets. However, the conventional real estate development market in China continues to face challenges. In 2025, investment in real estate development decreased by 17.2% year-over-year, while the value of residential sales fell by 13.0%.
The real estate market in India is estimated to grow at a CAGR of 8.1% from 2026 to 2033, driven by urbanization, household formation, rising employment, and expanding demand across metropolitan and emerging urban centers. Infrastructure investment is broadening the geography of real estate development by improving connectivity between established cities and developing urban corridors. As of 2025, India had more than 1,000 km of operational metro rail across 26 cities, while metro projects covering 84.57 km were sanctioned during 2025, strengthening the link between transport infrastructure and urban development. Government housing programs are also supporting residential supply across different income segments. Pradhan Mantri Awas Yojana-Urban 2.0 targets one crore urban poor and middle-income families over five years and includes support for home construction, home purchase, affordable rental housing, and housing finance. In addition, the Reserve Bank of India revised its affordable-housing lending limits in 2025, expanding the scope of eligible housing loans and property values. These measures, combined with rising incomes and the formalization of housing finance, are supporting demand for organized residential developments while infrastructure expansion is creating opportunities for commercial, logistics, and mixed-use projects beyond established metropolitan markets.
Latin America Real Estate Market Trends
The Latin America real estate industry is projected to grow at a CAGR of 3.3% from 2026 to 2033. Ongoing urbanization, rising housing needs, and investments in transportation and urban infrastructure support this growth. The region is already highly urbanized, and both population and employment growth are continually reshaping demand in major metropolitan and intermediate cities. Residential real estate demand is driven by household formation and the need for more formal housing; however, affordability and financing conditions remain significant constraints. The commercial sector is benefiting from growth in services, retail, logistics, and other urban-oriented industries. Additionally, infrastructure improvements are creating new development opportunities in emerging urban corridors.
In addition, tourism supports hospitality and mixed-use projects in well-established destinations, although investment conditions are sensitive to financing costs and the broader economic environment. The World Bank has projected economic growth in Latin America and the Caribbean at 2.1% for 2026, indicating relatively subdued investment conditions and ongoing elevated financing constraints.
Middle East & Africa Real Estate Market Trends
The real estate industry in the Middle East and Africa (MEA) is projected to grow at a compound annual growth rate (CAGR) of 8.1% from 2026 to 2033. Increasing urban populations, rising housing needs, infrastructure investments, and large-scale city development programs will drive this growth. In the Middle East, urban development is becoming increasingly connected to transport connectivity, job creation, housing availability, and economic diversification.
In 2026, the World Bank emphasized that better coordination between urban infrastructure, housing, land-use planning, and labor markets could enhance the economic contributions of cities in the MENA region. This alignment is creating opportunities across residential, commercial, logistics, retail, and mixed-use developments.
Tourism also plays a significant role in real estate activity within Gulf economies. In 2025, Saudi Arabia welcomed approximately 123 million domestic and inbound tourists, and total tourism spending reached around SAR 304 billion. This influx of tourism is driving investments in hotels, tourism facilities, retail, and destination-oriented developments.
Key Real Estate Company Insights
The global real estate market comprises large property developers, institutional investors, real estate investment trusts (REITs), private equity firms, regional developers, and specialized asset operators. These entities compete across various sectors, including residential, commercial, logistics, hospitality, and mixed-use properties. Competition in the market is increasingly driven by access to capital, development expertise, location intelligence, and the ability to manage complex assets efficiently. Additionally, investment strategies are expanding beyond traditional office and residential properties, with alternative real estate sectors now accounting for approximately 20% of global direct transaction volumes. This shift reflects a greater allocation of capital toward specialized and infrastructure-linked assets.
 To learn more about this report, Download Free Sample Report
Furthermore, technology and sustainability are becoming more integral to development and portfolio strategies. Developers and investors are leveraging data analytics and artificial intelligence (AI) to enhance site selection, asset management, and investment decisions. Features such as flexible building design, smart infrastructure, and energy-efficient systems are gaining significance in both new projects and redevelopments. According to JLL's 2025 report, 88% of surveyed real estate investors had started piloting AI across the real estate value chain.
Moreover, factors such as power availability, energy costs, building performance, and climate resilience are increasingly influencing site selection and asset valuation. These trends are encouraging market participants to diversify their portfolios across sectors such as housing, logistics, offices, retail, hospitality, data centers, and other specialized assets, and to expand into emerging urban centers and secondary cities.
Key Real Estate Companies
The following key companies have been profiled for this study on the real estate market.
-
Keller Williams Realty, LLC
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Player: Brookfield Corporation
- Mature players focus on portfolio diversification, large-scale acquisitions, asset development, and long-term investment strategies across multiple real-estate segments and geographic markets.
- They place importance on institutional capital access, strategic partnerships, redevelopment of existing assets, portfolio optimization, and expansion into high-growth markets through acquisitions and development projects.
- Established players maintain a competitive edge through large investment capacity, diversified property portfolios, extensive global networks, and strong relationships with institutional investors and tenants. Their scale also enables them to undertake large development and redevelopment projects while spreading risk across multiple asset classes and markets.
- High capital requirements, financing costs, and exposure to interest-rate and property-market cycles can pressure returns. Large and geographically dispersed portfolios can also increase operational complexity, while exposure to commercial real estate can create additional risks during periods of weak occupancy or reduced business investment.
Emerging Players: Keller Williams Realty, LLC
- Growth-oriented players adopt technology-driven, network-based, and customer-centric strategies to expand their presence without requiring the extensive physical asset base maintained by large property owners.
- They emphasize digital property platforms, agent recruitment and retention, data analytics, localized market expertise, and technology-enabled transaction processes to improve efficiency and expand market reach.
- Growth-oriented players can respond quickly to changing customer preferences and local market conditions. Technology adoption, flexible operating models, extensive agent networks, and localized expertise can help them compete with larger traditional real-estate organizations while supporting expansion into new markets.
- Dependence on transaction volumes, agent productivity, and local housing-market conditions can make revenues more variable. These companies may also have less direct ownership of income-generating property assets, limiting their exposure to recurring rental income compared with large real-estate investment and development companies.
Recent Developments
-
In January 2026, Compass completed its all-stock acquisition of Anywhere Real Estate, bringing the two residential real estate platforms under a single corporate structure. The transaction expanded Compass's brokerage, franchise, title, mortgage, and integrated-services businesses, while the company began integrating operations and technology platforms across the combined organization.
-
In July 2026, Prologis reported that it had acquired USD 1.9 billion of net real estate investments during the first half of 2026, including the acquisition of a partner's interest in an unconsolidated Asia co-investment venture. The activity reflects continued institutional capital deployment into logistics and industrial real estate assets.
-
In July 2026, Brookfield Corporation completed its acquisition of Oaktree, combining their investment platforms after a seven-year partnership. The integration expands Brookfield's capabilities across real assets and other investment strategies, including real estate-related credit and investment opportunities.
-
In July 2026, CBRE reported that equity capital inflows into India's real estate sector reached USD 8.5 billion during the first half of 2026, representing a 32% increase from H1 2025. The increase was supported by land and development-site acquisitions and investment in built-up office assets, highlighting continued institutional capital activity in the sector.
Real Estate Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4,332.4 billion
Estimated market size in 2026
USD 4,557.7 billion
Projected market size by 2033
USD 7,351.3 billion
Growth rate
CAGR of 7.1% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Property, type, region
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Spain; Italy; China; India; Japan; South Korea; Australia/New Zealand; Brazil; Saudi Arabia
Key companies profiled
Brookfield Corporation; ATC IP LLC; Prologis, Inc.; SIMON PROPERTY GROUP, L.P.; Coldwell Banker Real Estate LLC; RE/MAX, LLC.; Keller Williams Realty, Inc.; CBRE Group, Inc.; Sotheby’s International Realty Affiliates LLC.; Colliers
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Real Estate Market Report Segmentation
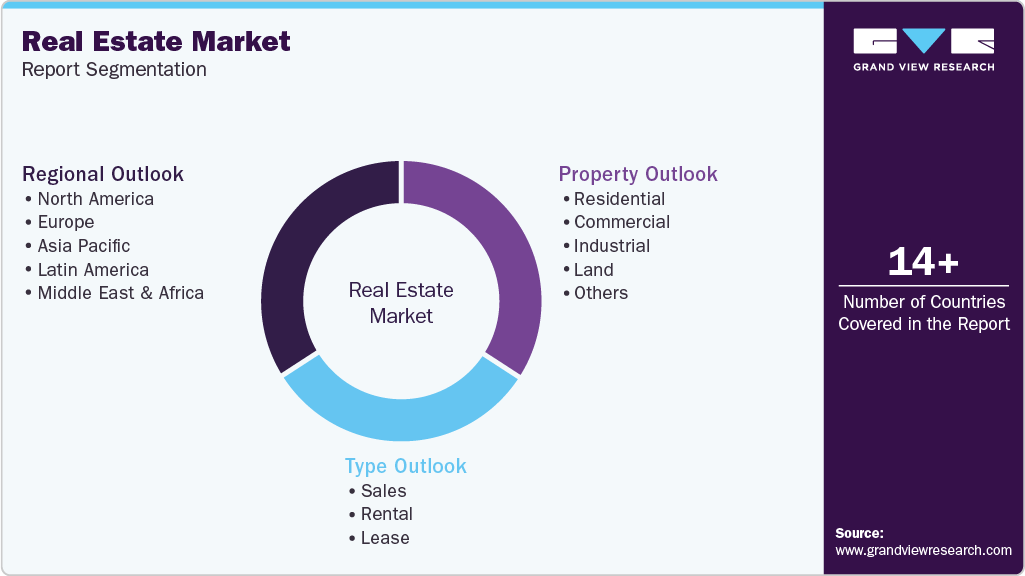
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the real estate market report based on property, type, and region:
 To learn more about this report, Download Free Sample Report
-
Property Outlook (Revenue, USD Billion, 2021 - 2033)
-
Residential
-
Commercial
-
Industrial
-
Land
-
Others
-
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Sales
-
Rental
-
Lease
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia/New Zealand
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
Saudi Arabia
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis of Real Estate Categories Across Regions
Detailed cross-segmentation analysis of the global real estate market across residential, commercial, industrial, and land properties, mapped against sales, rental, and lease formats across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The analysis also examines demand shifts by city tier, urbanization intensity, household formation, and investor activity.
Identifies the most attractive combinations of property type with transaction type and region. Highlights where rental housing, logistics assets, or residential development are outperforming, and helps prioritize markets where Asia Pacific’s scale, residential demand, and rental strength create the strongest near-term opportunities.
Competitive Landscape & Developer / Investor Benchmarking
Comprehensive assessment of the competitive ecosystem across developers, REITs, brokerages, institutional investors, and asset specialists. Coverage includes strategic positioning of companies such as Brookfield Corporation, Prologis, Simon Property Group, CBRE, RE/MAX, Keller Williams, Coldwell Banker Real Estate LLC, and Colliers, with analysis of portfolio focus, geographic exposure, and asset-class specialization.
It reveals which players are most exposed to residential, commercial, logistics, and mixed-use assets; identifies consolidation opportunities, partnership themes, and capital allocation patterns; and supports benchmarking of scale, diversification, and market resilience across core real estate segments.
Pricing, Rental Yield & Affordability Analysis
Analysis of pricing dynamics across owned housing, rental housing, and leased assets, with a focus on affordability trends, rent escalation, occupancy patterns, financing access, and income-generation potential. The study also evaluates how urbanization, interest-rate sensitivity, and the shift toward income-producing assets influence valuation and buyer behavior.
It will help identify markets where affordability pressure is sustaining rental demand, where rising disposable incomes and mortgage access are supporting sales activity, and where income-hedged assets are most attractive to investors seeking stable cash flows.
Frequently Asked Questions About This Report
Some of the key players operating in the real estate market include Brookfield Corporation; ATC IP LLC; Prologis, Inc.; SIMON PROPERTY GROUP, L.P.; Coldwell Banker Real Estate LLC; RE/MAX, LLC.; Keller Williams Realty, Inc.; CBRE Group, Inc.; Sotheby’s International Realty Affiliates LLC.; and Colliers.
The residential real estate segment led the market with a 35.5% revenue share in 2025.
The rental segment held the largest market share of 51.3% in 2025, while the sales segment is projected to grow at a CAGR of 8.1% during the forecast period.
Asia Pacific dominated the global real estate market with a 53.4% market share in 2025.
The key factors that are driving the global real estate market are the rising population and a desire for personal household space, the rapid rise of e-commerce, which drives demand for warehouses and logistics centers; the evolution of workplaces due to hybrid work models, prompting redesigns and upgrades of office spaces; and the recovery of retail and hospitality sectors in many regions.
The global real estate market size was valued at USD 4,332.4 billion in 2025 and is estimated at USD 4,557.7 billion for 2026.
The global real estate market is expected to grow at a CAGR of 7.1% from 2026 to 2033, reaching USD 7,351.3 billion by 2033.
Asia Pacific held the largest market share of 53.4% in 2025.
About the Author(s)
Homecare & Decor Research Team
Consumer Goods · Homecare & DecorThis report was authored by the homecare & decor research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the homecare & decor segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


