
- Home
- »
- Medical Devices
- »
-
3D Ultrasound Market Size, Share & Trends Report, 2033GVR Report cover

3D Ultrasound Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Handheld, Compact, Cart/Trolley), By Application (General Imaging, Obstetrics And Gynecology), By End-use (Hospitals, Diagnostic Imaging Centers), By Region, And Segment Forecasts
Market Size, 2025
$3.1BMarket Estimate, 2026
$3.3BMarket Forecast, 2033
$5.0BCAGR, 2026–2033
5.9%3D Ultrasound Market Summary
The global 3D ultrasound market size was valued at USD 3.1 billion in 2025 and is projected to grow from USD 3.3 billion in 2026 to USD 5.0 billion by 2033, at a CAGR of 5.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.9% in 2025. According to the World Health Organization, noncommunicable diseases (NCDs), such as cardiovascular diseases and cancers, account for approximately 41 million deaths annually, which represents 74% of all global deaths.
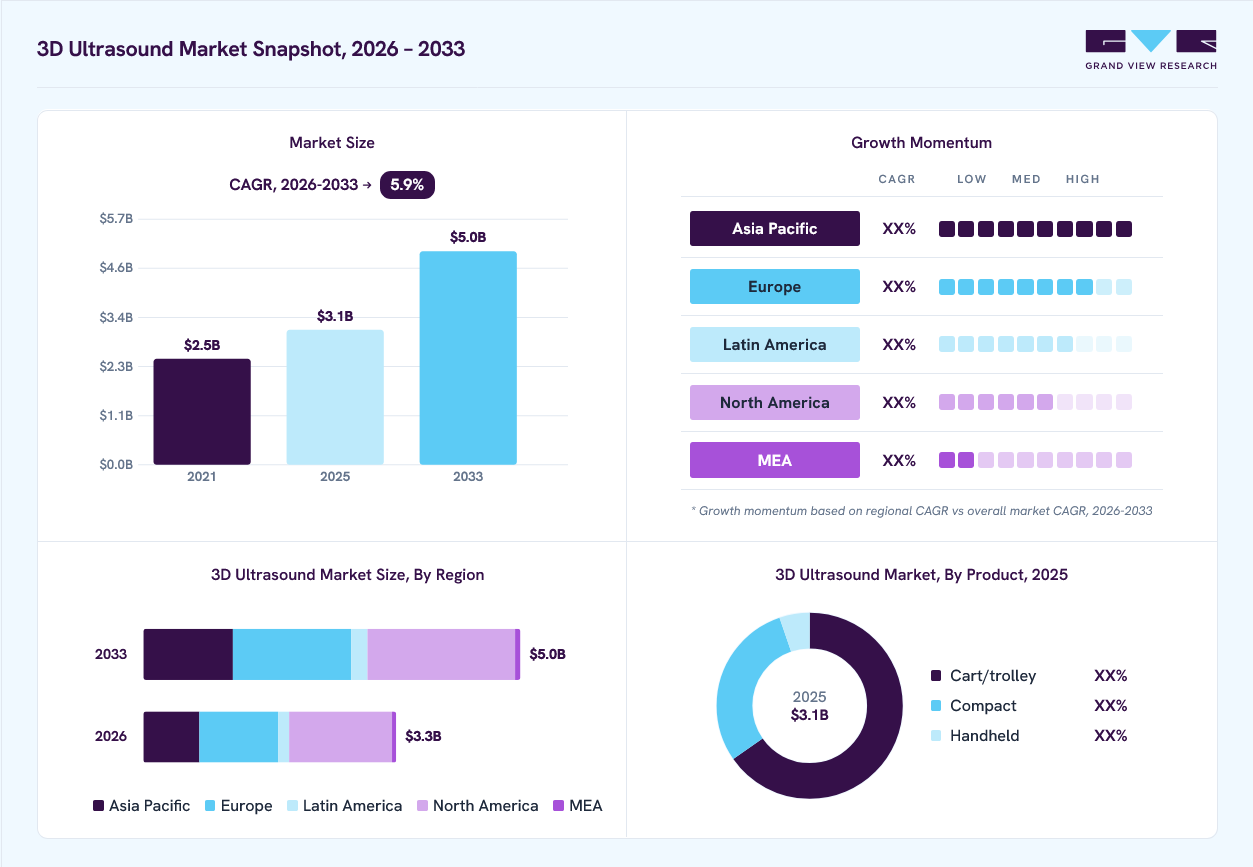 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Cart/trolley segment led the market with the largest revenue share of 65.2% in 2025.
- By application: Obstetrics and gynecology segment led the market with the largest revenue share of 33.4% in 2025.
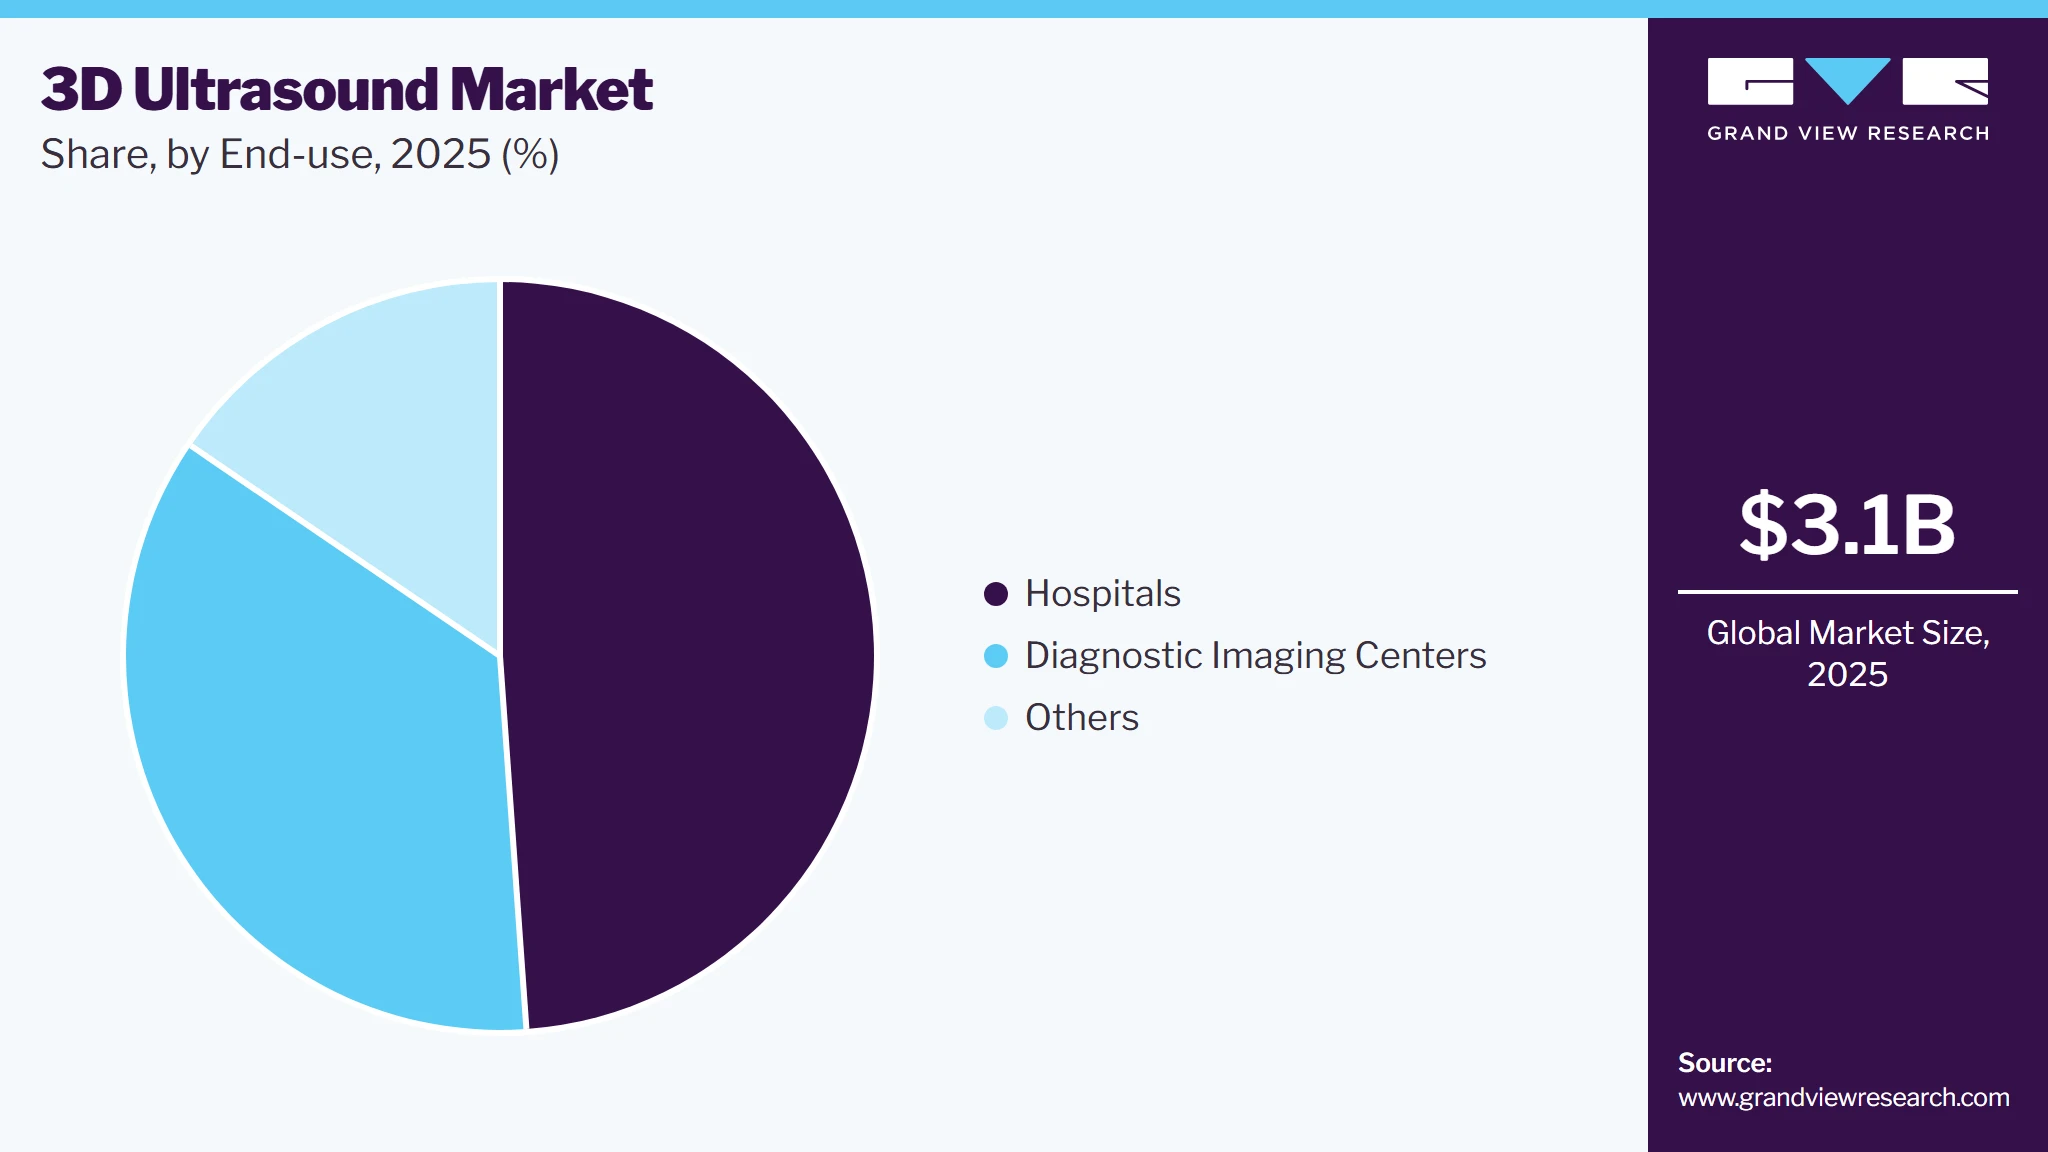
- By end-use: Hospitals segment led the market with the largest revenue share of 48.9% in 2025.
Regional Highlights
- Largest regional market: North America (40.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.1 Billion
- Estimated market size in 2026: USD 3.3 Billion
- Projected market size by 2033: USD 5.0 Billion
- CAGR (2026-2033): 5.9%
Prism AI by Grand View Research Free to tryAsk a question about the 3D ultrasound marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
This alarming statistic underscores the urgent need for effective imaging solutions such as 3D ultrasound technology, which provides detailed imaging crucial for accurate diagnosis and treatment planning. As these conditions rise, the demand for advanced imaging modalities grows correspondingly, positioning 3D ultrasound as a vital tool in modern healthcare.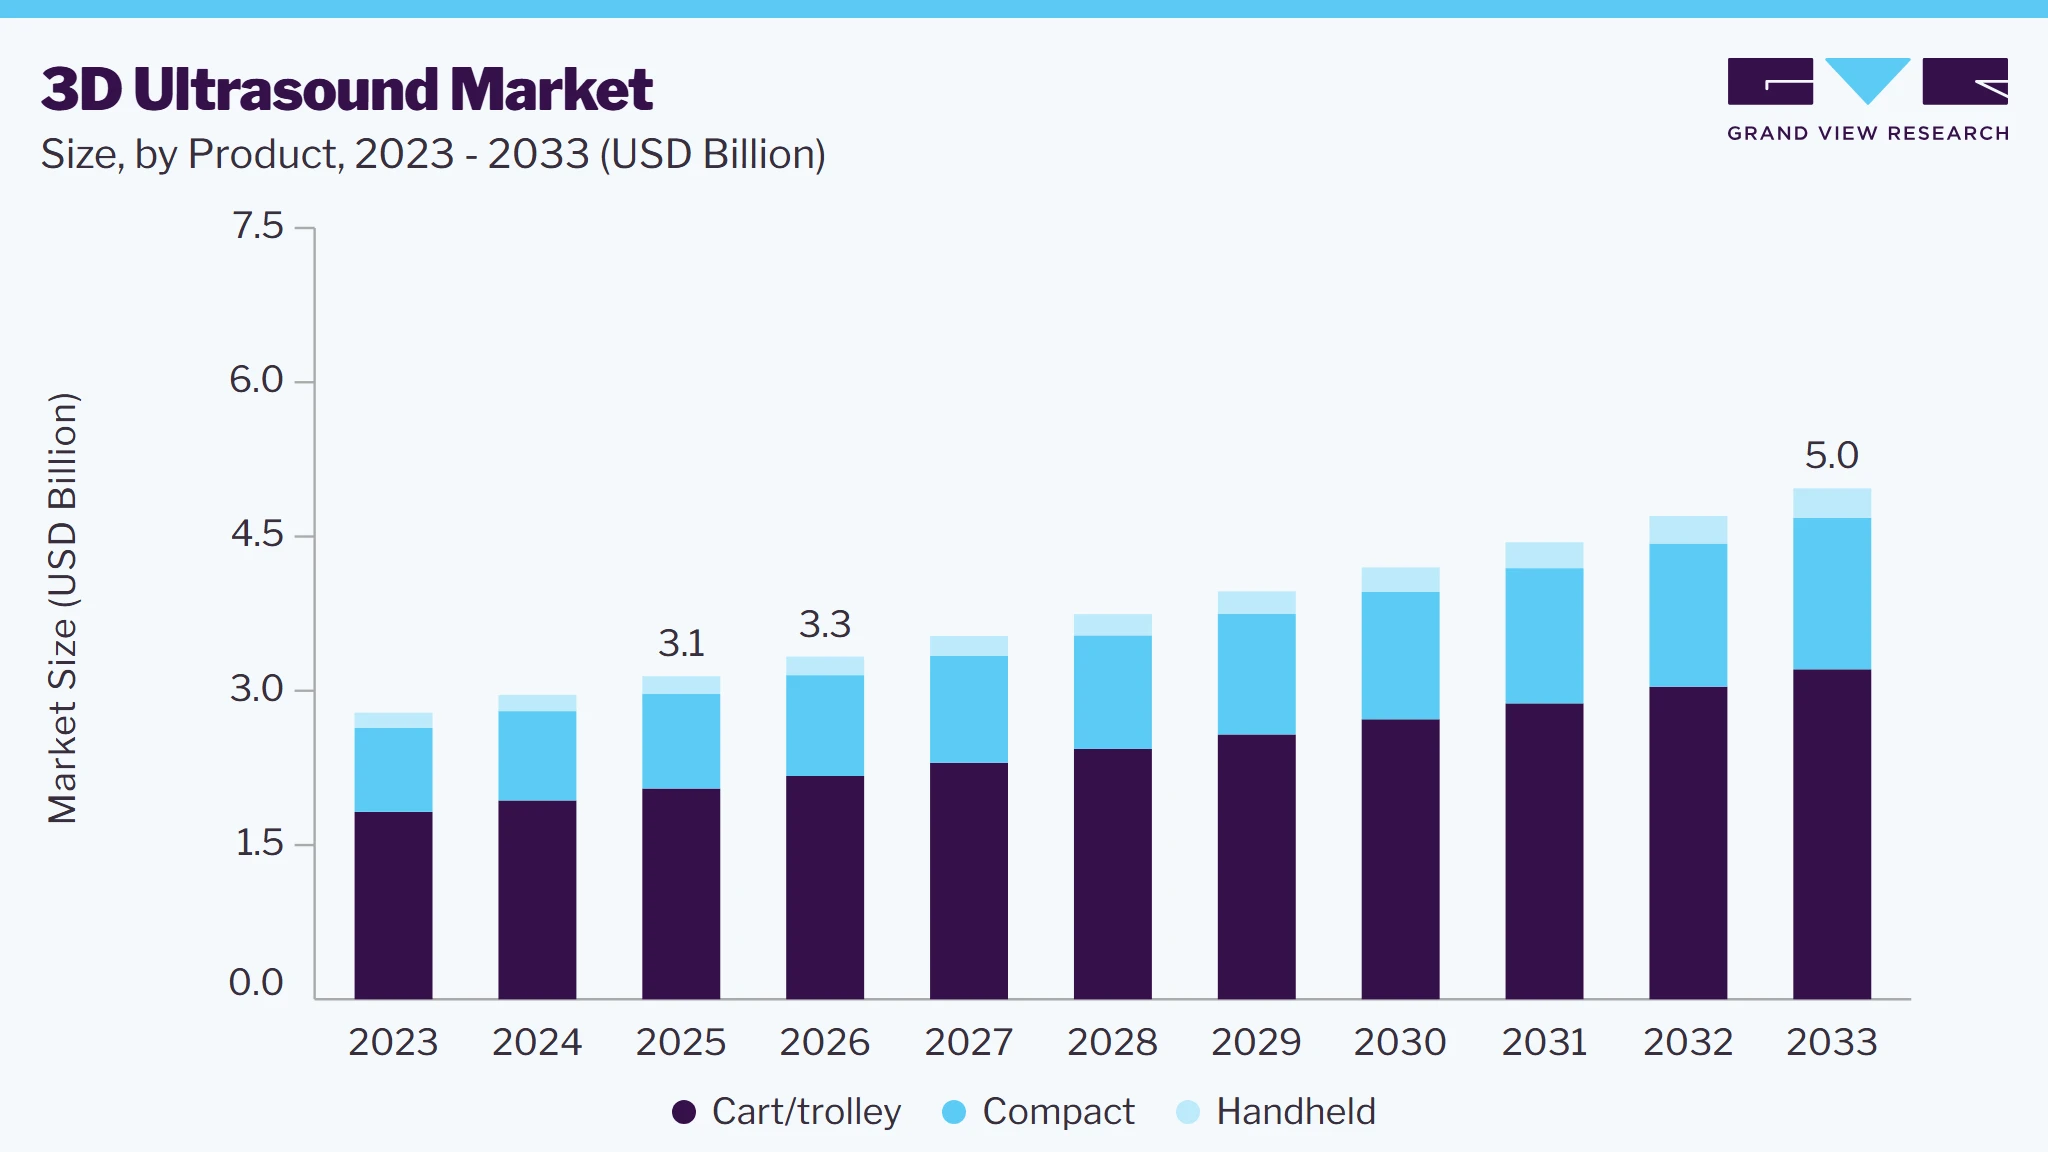 To learn more about this report, Download Free Sample Report
Technological advancements, including innovations such as enhanced image quality and real-time imaging capabilities, are significantly improving diagnostic accuracy and operational efficiency. A growing number of healthcare professionals are adopting these advanced systems, depicting a need for precise and timely healthcare solutions. The evolution of ultrasound technology is pivotal in addressing the increasing demand for effective diagnostic procedures while improving patient outcomes across various clinical settings.
Moreover, expanding diagnostic imaging facilities and healthcare infrastructure worldwide has cemented itself as a crucial factor in market growth. Increased healthcare spending enables investment in advanced medical technologies, including 3D ultrasound systems. The expansion of these facilities facilitates the widespread adoption of cutting-edge imaging tools, thereby meeting the rising demand for high-quality diagnostic services.
The increasing preference for minimally invasive procedures is significantly boosting interest in 3D ultrasound technology. A study indicated a 36% rise in total average residency case volumes across various procedures, with minimally invasive surgeries constituting a larger proportion. This trend is set to persist as healthcare providers increasingly adopt non-invasive techniques, underscoring the vital role of 3D ultrasound systems in advancing patient-centric care and enhancing recovery outcomes.
Market Dynamics
The 3D ultrasound market is witnessing robust growth due to the increasing adoption of advanced volumetric imaging systems that enable healthcare professionals to obtain highly detailed three-dimensional anatomical images for accurate diagnosis and treatment planning. 3D ultrasound systems generate volumetric datasets by reconstructing multiple 2D ultrasound images, allowing comprehensive visualization of organs, soft tissues, blood vessels, and fetal anatomy. These systems are available in handheld, compact, and cart/trolley-based configurations and are widely utilized across obstetrics and gynecology, cardiology, urology, musculoskeletal imaging, general imaging, and other clinical specialties. Rising demand for non-invasive, radiation-free diagnostic imaging, increasing prevalence of chronic diseases, growing maternal healthcare programs, and expanding adoption of point-of-care ultrasound (POCUS) are major factors driving market growth. Furthermore, continuous advancements in matrix-array transducers, artificial intelligence-assisted image acquisition, automated volume rendering, cloud-based image management, wireless connectivity, and portable ultrasound technologies are improving image quality, workflow efficiency, and diagnostic confidence, thereby accelerating adoption across hospitals, diagnostic imaging centers, ambulatory surgical centers, and outpatient healthcare facilities.
The increasing demand for advanced, real-time, and non-invasive diagnostic imaging is a major factor driving the global 3D ultrasound market. Healthcare providers are increasingly adopting 3D ultrasound systems because they provide superior spatial visualization, enhanced anatomical assessment, improved lesion characterization, and greater diagnostic accuracy compared with conventional 2D ultrasound. These capabilities are particularly valuable in obstetrics and gynecology for fetal anomaly detection, cardiology for structural heart assessment, urology for organ visualization, musculoskeletal imaging, and image-guided interventional procedures. The rapid expansion of point-of-care ultrasound (POCUS), increasing prevalence of cardiovascular diseases and pregnancy-related complications, growing awareness regarding early disease diagnosis, and rising preference for portable imaging solutions are further supporting market growth. Continuous technological innovations, including AI-assisted image optimization, automated measurements, advanced transducer technologies, and enhanced 3D/4D visualization, are improving clinical efficiency and expanding the use of 3D ultrasound across hospitals, emergency departments, ambulatory surgical centers, and primary healthcare settings.
Despite significant technological advancements, the 3D ultrasound market continues to face challenges associated with the high acquisition and operational costs of advanced imaging systems. Premium cart-based 3D ultrasound platforms equipped with high-performance volumetric transducers, AI-enabled software, and advanced visualization capabilities require substantial capital investment, making adoption difficult for smaller hospitals, diagnostic centers, and healthcare facilities in developing regions. In addition, ongoing expenses related to software upgrades, equipment maintenance, service contracts, and specialized accessories further increase the total cost of ownership. Accurate acquisition and interpretation of 3D ultrasound images also require experienced sonographers, radiologists, and specialized clinician training, creating workforce limitations in resource-constrained healthcare systems. Furthermore, limited reimbursement for advanced ultrasound procedures in certain countries, budget constraints among healthcare providers, and disparities in healthcare infrastructure may slow the widespread adoption of 3D ultrasound technologies, particularly in emerging markets.
Analyst Perspective
The 3D ultrasound market is positioned at the convergence of several transformative healthcare trends such as precision diagnostics, point-of-care imaging, maternal healthcare expansion, and digital transformation of medical imaging. Healthcare providers are increasingly investing in volumetric ultrasound technologies that improve diagnostic confidence while reducing dependence on ionizing radiation. Technological advancements in matrix transducer technology, AI-assisted image optimization, automated workflow solutions, cloud-based image management, and handheld ultrasound platforms are reshaping the competitive landscape. The growing adoption of portable imaging solutions across emergency medicine, critical care, obstetrics, cardiology, and primary healthcare settings is creating new growth opportunities for manufacturers. As healthcare systems continue to prioritize early diagnosis, decentralized care, and operational efficiency, demand for advanced 3D ultrasound is expected to increase steadily across hospitals, diagnostic imaging centers, and outpatient healthcare facilities worldwide.
Product Insights
Based on product, the cart/trolley segment led the market with the largest revenue share of 65.2% in 2025. These systems deliver superior image quality and functionality, making them ideal for diverse diagnostic applications. Their mobility enables healthcare providers to bring ultrasound equipment directly to patients in critical care settings, facilitating timely diagnosis and treatment. Cart-based systems often offer advanced capabilities, including integration with other imaging modalities, enhancing patient outcomes in hospitals and diagnostic centers.
Handheld products are expected to grow at the fastest CAGR of 8.8% over the forecast period. Handheld ultrasound devices enhance portability and accessibility, making them suitable for point-of-care and home healthcare environments. Their capability for immediate imaging results improves diagnostic efficiency in emergencies and remote settings. The increasing prevalence of chronic diseases and preference for minimally invasive procedures further accelerates the adoption of these devices across various medical fields.
End Use Insights
Based on end-use, the hospitals segment led the market with the largest revenue share of 48.9% in 2025. The rising prevalence of chronic diseases fuels the demand for precise imaging solutions. Integrating 3D ultrasound systems enhances clinical decision-making, improving patient outcomes and operational efficiency within hospitals.
 To learn more about this report, Download Free Sample Report
Diagnostic imaging centers are projected to grow at the fastest CAGR of 8.6% over the forecast period. These centers are vital for accurate diagnostics across multiple medical fields, driven by the increasing prevalence of chronic diseases and the demand for precise imaging techniques. Technological advancements further enhance image quality, reinforcing the reliance on specialized imaging services and boosting adoption.
Application Insights
Based on application, the obstetrics and gynecology segment led the market with the largest revenue share of 33.4% in 2025. 3D ultrasound offers enhanced imaging that greatly improves the visualization of anatomical structures, aiding in diagnosing conditions such as congenital uterine anomalies, fibroids, and endometrial polyps. With up to 100% accuracy in diagnosing congenital anomalies, its non-invasive approach and immediate results make it a favored option for clinicians, improving patient care in obstetrics and gynecology.
General imaging is expected to register the fastest CAGR of 8.7% over the forecast period. General imaging demonstrates versatility and advanced diagnostic capabilities. 3D ultrasound offers comprehensive visualization of anatomical structures, enhancing the assessment of conditions such as tumors and vascular abnormalities. Its real-time imaging supports surgical planning and guidance while being non-invasive and free of radiation, making it increasingly favored across various medical specialties, including cardiology and emergency medicine.
Regional Insights
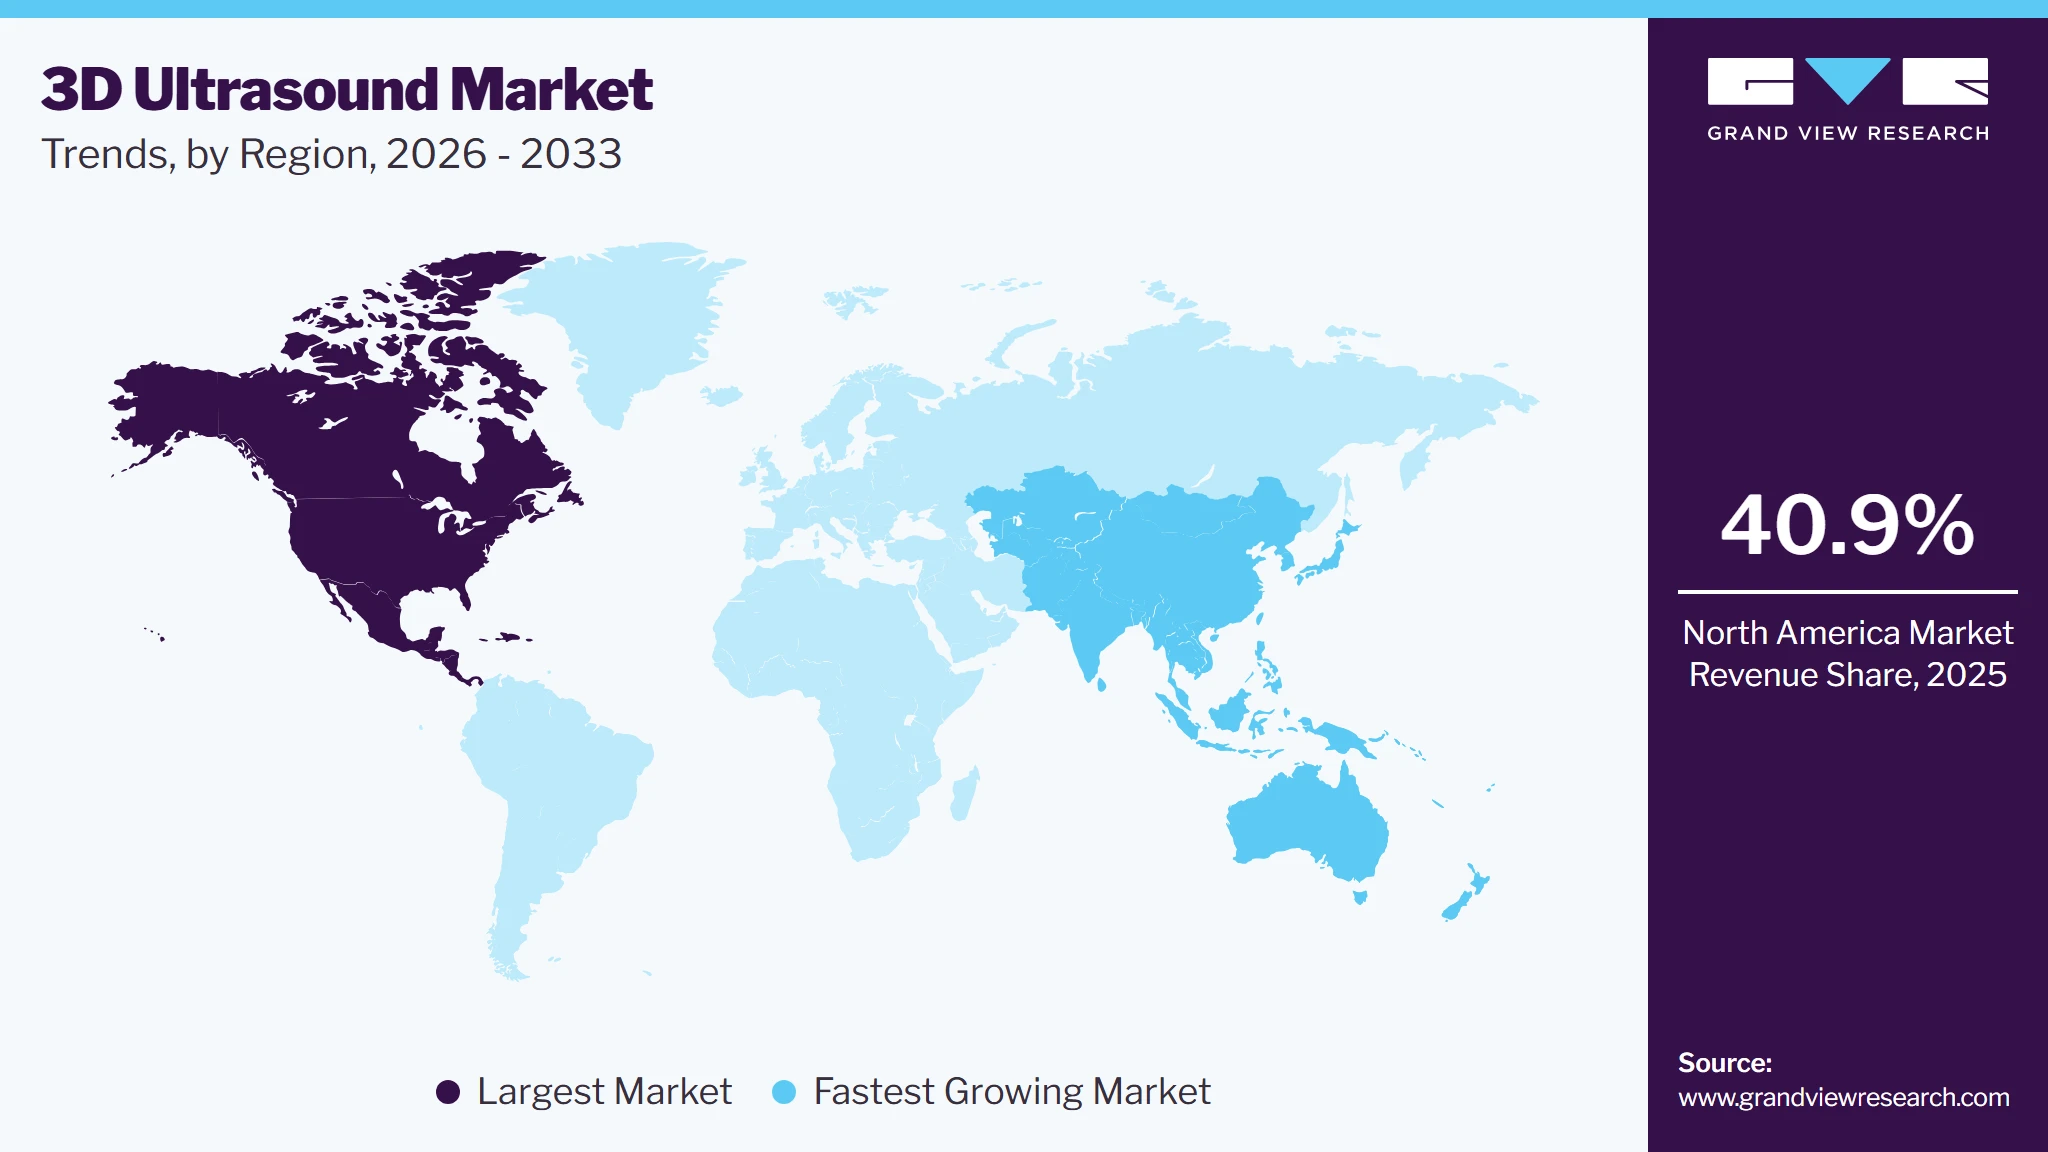
North America dominated the 3D ultrasound market with the largest revenue share of 40.9% in 2025. North America boasts a robust healthcare infrastructure, high adoption rates of innovative technologies, and a considerable number of product launches. Favorable reimbursement policies, heightened patient awareness of 3D imaging benefits, the rising prevalence of chronic diseases, and the demand for minimally invasive procedures significantly propel market growth. Continuous advancements in ultrasound systems further enhance diagnostic accuracy and efficiency.
 To learn more about this report, Download Free Sample Report
U.S. 3D Ultrasound Market Trends
The 3D ultrasound market in the U.S. held the largest share in the North America region in 2025. Significant investments in research and development drive innovation in advanced ultrasound devices. For instance, in May 2024, GE HealthCare and Tampa General Hospital expanded their partnership to enhance imaging and ultrasound technologies, improving diagnostic precision and patient outcomes across Florida’s outpatient facilities. The rising incidence of chronic diseases, demand for non-invasive diagnostics, and favorable reimbursement policies enhance accessibility to 3D ultrasound technologies, crucial for patient care across diverse U.S. medical specialties.
Europe 3D Ultrasound Market Trends
Europe 3D ultrasound market held substantial market share in 2024, owing to increased healthcare expenditures, technological advancements, and an emphasis on early diagnosis. Integrating AI and enhanced imaging software positions 3D ultrasound as a vital tool across multiple medical specialties, supported by favorable government policies and significant regional investments. For instance, in July 2023, Siemens announced an approximately USD 1.07 billion investment in Germany, establishing a Technology Campus in Erlangen to enhance innovation, research, and development in the industrial metaverse.
The UK 3D ultrasound market is expected to grow over the forecast period, fueled by enhanced government funding for healthcare and initiatives promoting early disease detection. Rising birth rates and emphasis on maternal health increase demand for obstetric ultrasound applications, while ongoing technological advancements improve accessibility and efficiency in imaging services across the UK.
Asia Pacific 3D Ultrasound Market Trends
Asia Pacific 3D ultrasound market is expected to register the fastest CAGR of 8.7% over the forecast period. The increasing prevalence of chronic diseases and a preference for minimally invasive procedures are driving demand for advanced imaging technologies. Enhanced healthcare infrastructure and accessibility and technological innovations such as portable ultrasound devices further promote adoption across diverse medical specialties.
The 3D ultrasound market in Japan is projected to witness the fastest growth of 10.0% in the Asia Pacific market over the forecast period. Outsourcing non-core services enables hospitals to concentrate on patient care while lowering operational costs. In Japan, the aging population increases the demand for specialized medical services, prompting hospitals to outsource functions such as radiology and laboratory services, thereby enhancing overall efficiency and solidifying Japan’s significance within the Asia Pacific region.
The 3D ultrasound market in Japan is projected to witness the fastest growth rate in Asia Pacific over the forecast period. Japan's established healthcare infrastructure provides widespread access to advanced medical technologies. In addition, its aging population is boosting demand for effective diagnostic tools, particularly in obstetrics and gynecology. Significant R&D investments and rising chronic disease prevalence are further driving market growth in the country.
Key 3D Ultrasound Company Insights
Some key companies operating in the market include GE HealthCare, Koninklijke Philips N.V., CANON MEDICAL SYSTEMS CORPORATION, and Hitachi, Ltd. Significant technological advancements and strategic collaborations drive product innovation, particularly in handheld devices, while partnerships and R&D investments enhance diagnostic accuracy and expand market offerings.
-
Koninklijke Philips N.V. provides advanced ultrasound systems that improve diagnostic capabilities across multiple medical specialties. Notable products such as the Epiq and Affiniti series offer high-quality 3D imaging for cardiology, obstetrics, and general imaging, prioritizing patient comfort and workflow efficiency.
-
Shenzhen Mindray Bio-Medical Electronics Co., Ltd. specializes in developing medical devices, including 3D ultrasound systems. Their solutions emphasize high-resolution imaging and user-friendly interfaces, supporting diverse clinical applications while enhancing diagnostic accuracy and maintaining affordability for healthcare providers.
Key 3D Ultrasound Companies:
The following key companies have been profiled for this study on the 3D ultrasound market.
-
GE HealthCare
-
Koninklijke Philips N.V.
-
CANON MEDICAL SYSTEMS CORPORATION
-
Hitachi, Ltd.
-
Siemens Healthineers AG
-
Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
-
FUJIFILM Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (GE HealthCare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Siemens Healthineers AG, FUJIFILM Corporation)
- Established companies focus on comprehensive ultrasound portfolios spanning handheld, compact, and premium cart-based systems. They emphasize AI-enabled imaging, advanced transducer technologies, integrated digital workflows, cloud connectivity, and continuous innovation in volumetric imaging. Their strategies include expanding installed bases, strengthening hospital partnerships, and offering long-term service agreements and software upgrades.
- Strong global distribution networks, extensive installed bases, comprehensive product portfolios, advanced R&D capabilities, and established relationships with hospitals and diagnostic imaging centers. Significant financial resources enable continuous innovation, regulatory compliance, and large-scale manufacturing.
- Dependence on capital equipment purchasing cycles and hospital budgets may affect sales. Large organizational structures may reduce agility in responding to niche clinical requirements and emerging technologies. Pricing pressures from healthcare cost-containment initiatives can impact margins.
Emerging Players (Shenzhen Mindray Bio-Medical Electronics Co., Samsung Medison, Esaote, SonoScape Medical, CHISON Medical)
- Emerging and expanding companies focus on delivering cost-effective, technologically advanced ultrasound systems with growing emphasis on portability, AI-assisted imaging, and expanding presence in emerging healthcare markets. They prioritize competitive pricing, regional expansion, and product innovation to increase market share.
- Agile product development, competitive pricing strategies, increasing investment in AI-enabled imaging, and strong growth across emerging economies. Ability to address underserved healthcare facilities and expand access to advanced ultrasound imaging supports market penetration.
- Comparatively smaller premium installed base in developed markets than leading multinational competitors. Brand perception in high-end volumetric imaging and dependence on distributor networks in certain regions may limit penetration.
Recent Developments
-
In May 2024, Royal Philips launched the VeriSight Pro 3D ICE catheter internationally, allowing hospitals in Hong Kong to utilize advanced imaging technology for enhancing procedural accuracy and patient care.
-
In February 2024, GE HealthCare launched its advanced LOGIQ ultrasound portfolio at the European Congress of Radiology, introducing features and AI tools to enhance imaging capabilities amidst rising global radiologist shortages.
-
In January 2024, CANON MEDICAL SYSTEMS CORPORATION launched the Aplio me ultrasound system, designed for routine users in high-throughput clinical environments, featuring advanced imaging capabilities, AI technologies, and user-friendly design to enhance workflow efficiency.
-
In January 2024, Olympus Corporation and CANON MEDICAL SYSTEMS CORPORATION announced a collaboration to develop and market advanced Endoscopic Ultrasound Systems to enhance diagnostic performance and quality in early disease detection worldwide.
3D Ultrasound Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 3.1 billion
Estimated market size in 2026
USD 3.3 billion
Projected market size by 2033
USD 5.0 billion
Growth rate
CAGR of 5.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Thailand; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
GE HealthCare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Siemens Healthineers AG, FUJIFILM Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Samsung Medison, Esaote, SonoScape Medical, CHISON Medical.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global 3D Ultrasound Market Report Segmentation
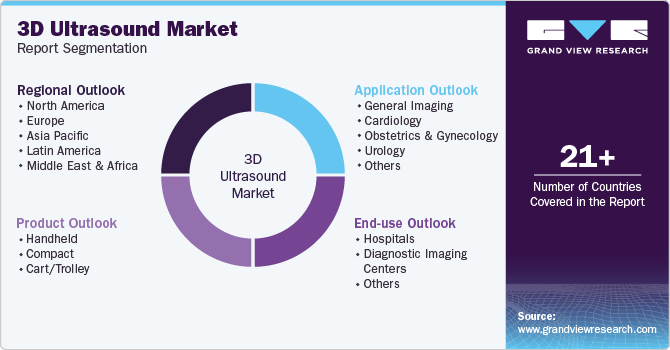
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global 3D ultrasound market report based on product, application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Handheld
-
Compact
-
Cart/Trolley
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
General Imaging
-
Cardiology
-
Obstetrics and Gynecology
-
Urology
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Diagnostic Imaging Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The 3D ultrasound market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each 3D ultrasound segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Handheld
Revenue is generated through compact handheld 3D ultrasound devices designed for point-of-care imaging across emergency medicine, primary care, obstetrics, cardiology, and remote healthcare settings. Manufacturers capture value through increasing adoption of portable diagnostics, wireless connectivity, and AI-assisted imaging capabilities.
Compact
Revenue is derived from portable compact ultrasound systems offering enhanced mobility while maintaining advanced imaging performance. Market participants benefit from growing demand among specialty clinics, ambulatory care centers, and outpatient diagnostic facilities requiring flexible imaging solutions.
Cart/trolley
Revenue is derived from portable compact Revenue is generated through premium cart-based 3D ultrasound systems utilized in hospitals and diagnostic imaging centers for comprehensive clinical examinations requiring advanced volumetric imaging, high-performance transducers, and sophisticated workflow capabilities.
Segment - Application
Revenue capture definition
General Imaging
Revenue is generated through utilization of 3D ultrasound devices for abdominal imaging, breast examinations, thyroid assessments, musculoskeletal evaluations, vascular imaging, and other routine diagnostic applications requiring enhanced anatomical visualization.
Cardiology
Revenue is derived from 3D echocardiography systems utilized for structural heart assessment, valve evaluation, congenital heart disease diagnosis, cardiac function analysis, and procedural planning. Manufacturers benefit from increasing adoption of advanced cardiac imaging technologies.
Obstetrics and Gynecology
Revenue is captured through 3D ultrasound imaging utilized for fetal development assessment, congenital anomaly detection, reproductive health evaluations, infertility management, and gynecological diagnostics. This segment represents one of the largest contributors to market revenue.
Urology
Revenue is generated through utilization of 3D ultrasound systems for prostate imaging, bladder assessments, kidney evaluations, biopsy guidance, and treatment planning for urological disorders.
Others
Revenue is derived from applications including emergency medicine, anesthesiology, pediatrics, oncology, critical care, rheumatology, and other specialty imaging procedures requiring volumetric ultrasound capabilities.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is generated through procurement and utilization of 3D ultrasound systems by public and private hospitals for routine diagnostics, specialty imaging, emergency medicine, surgical guidance, and comprehensive patient care. Manufacturers benefit from capital equipment sales, software upgrades, service contracts, and transducer replacement demand.
Diagnostic Imaging Centers
Revenue is derived from deployment of 3D ultrasound devices in independent imaging centers and outpatient diagnostic facilities providing specialized ultrasound services across multiple clinical applications. The segment benefits from increasing patient referrals and growing demand for advanced non-invasive imaging.
Others
Revenue is captured through adoption by ambulatory surgical centers, physician offices, specialty clinics, academic institutions, research organizations, military healthcare facilities, and mobile healthcare providers utilizing advanced ultrasound technologies.
Estimation Model
Step / Key Question
Process Steps
Data Sources
Scope Definition
What is being sized?
1. Define 3D Ultrasound Technology and radiosurgery Categories.
2. Scope Product, Application, End Use Segments.
3. Establish Geographic Coverage (Global/Regional).
4. Align on base year & forecast horizon (2026-2033).
FDA, EMA, PMDA, NMPA, Hospital Imaging Database
Build the Install Base
How large is total addressable market?
1. Collect Installed Base of 3D Ultrasound Systems by Country.
2. Assess Installed Base by Portability Type.
3. Evaluate New Equipment Shipments and Replacement Cycles.
4. Develop Installed Base and Shipment Forecasts.
Company Annual Reports, Hospital Procurement Databases, Distributor Sales Data
Estimate Utilization & Procedure
What portion of procedures use this technology?
1. Estimate Annual Ultrasound Examinations per Installed System.
2. Assess Utilization Across Clinical Applications.
3. Map Procedure Volumes by End User and Specialty.
4. Validate Through Industry Interviews.
Primary interviews, OECD Database, clinical surveys, industry experts
Revenue Conversion
How does volume become revenue?
1. Determine ASPs by Device Product and Region.
2. Estimate Revenue from Device Sales.
3. Apply Regional Pricing Variations.
4. Cross-validate with Company Revenues and Public Findings.
Company Annual Reports, Distributor pricing sheets, procurement data, expert interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive competitive assessment of the global 3D ultrasound market, evaluating leading manufacturers across handheld, compact, and cart-based systems. The study assessed product portfolios, volumetric imaging technologies, AI enabled imaging capabilities, transducer innovations, software ecosystems, pricing strategies, regulatory approvals, distribution networks, service offerings, and regional expansion initiatives. It also evaluated advancements in automation, cloud connectivity, workflow optimization, and portable imaging technologies.
Enables stakeholders to understand technology leadership, competitive positioning, pricing dynamics, and commercialization strategies shaping the global 3D ultrasound market. Supports procurement decisions, vendor benchmarking, investment planning, partnership evaluation, and regional market expansion.
Segment by Application Analysis
Conducted a detailed assessment across General Imaging, Cardiology, Obstetrics & Gynecology, Urology, and Other Applications. The study analyzed procedure volumes, utilization rates, disease prevalence, clinical workflow requirements, reimbursement trends, technology adoption, referral patterns, and forecast demand by application and portability segment.
Enables stakeholders to identify high-growth clinical applications, optimize product portfolios, prioritize commercialization strategies, align sales efforts with specialty demand, and identify emerging revenue opportunities driven by expanding use of volumetric ultrasound imaging.
Macroeconomic Analysis
Conducted an in-depth assessment of healthcare expenditure, diagnostic imaging investments, aging populations, maternal healthcare initiatives, cardiovascular disease prevalence, hospital capital budgets, reimbursement environments, healthcare infrastructure development, AI adoption, regulatory policies, and supply chain dynamics influencing 3D ultrasound adoption globally.
Enables stakeholders to understand the macroeconomic, demographic, regulatory, and healthcare system factors influencing demand within the global 3D ultrasound market. The study supports long-term strategic forecasting, pricing strategy development, investment prioritization, capacity planning, and regional expansion decisions amid increasing demand for advanced diagnostic imaging technologies.
Frequently Asked Questions About This Report
Key factors that are driving the 3D ultrasound market growth include increasing medicare reimbursement for telehealth services, reducing emergency room visits and hospitalization rate, and technological innovation in communication technology across the world.
The global 3D ultrasound market size was valued at USD3.1 billion in 2025 and is estimated at USD 3.3 billion in 2026.
The global 3D ultrasound market is expected to grow at a CAGR of 5.9% from 2026 to 2033 to reach USD 5.0 billion by 2033.
North America dominated the market, accounting for a revenue share of 40.9% in 2025.
Cart/trolley segment led the market with the largest revenue share of 65.2% in 2025.
The obstetrics and gynecology segment led the market with the largest revenue share of 33.4% in 2025.
The hospitals segment led the market with the largest revenue share of 48.9% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Some key players operating in the 3D ultrasound market include GE HealthCare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Siemens Healthineers AG, FUJIFILM Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Samsung Medison, Esaote, SonoScape Medical, CHISON Medical.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


