
- Home
- »
- Electronic Security
- »
-
Airborne Radars Market Size And Share Report, 2026-2033GVR Report cover

Airborne Radars Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component, By Mode, By Dimension, By Range, By Frequency Band, By Installation Type, By Technology, By Application, By Region, And Segment Forecasts
Market Size, 2025
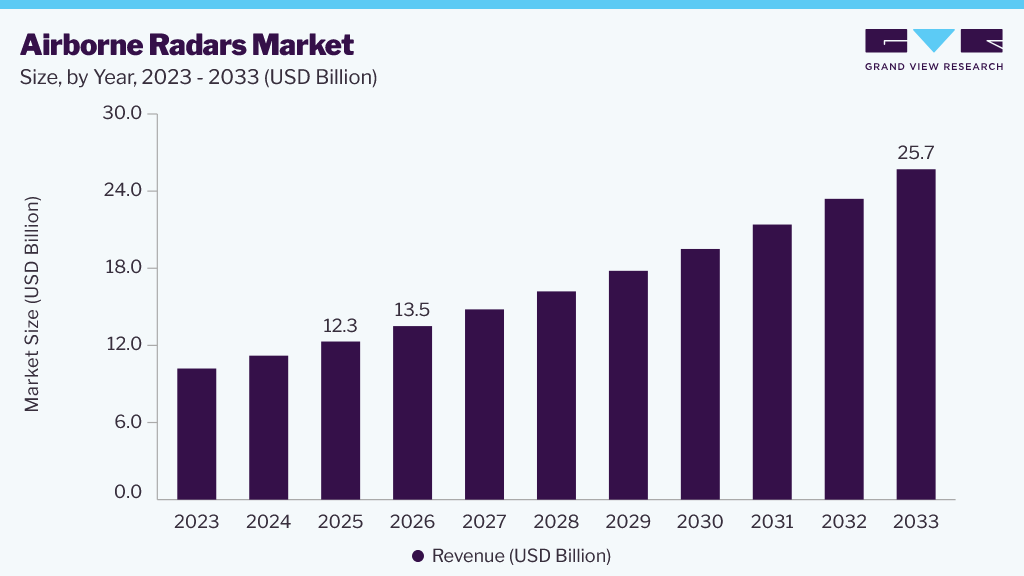
$12.3BMarket Estimate, 2026
$13.5BMarket Forecast, 2033
$25.7BCAGR, 2026–2033
9.6%Airborne Radars Market Summary
The global airborne radars market size was valued at USD 12.3 billion in 2025 and is projected to grow from USD 13.5 billion in 2026 to USD 25.7 billion by 2033, at a CAGR of 9.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 32.8% in 2025. Increasing penetration of unmanned aerial vehicles (UAVs) technology and the integration of radar systems on these platforms drive market growth.
Key Market Trends & Insights
- By component: The antennas segment held the largest market share of 23.0% in 2025
- By mode: The air-to-ground segment held the market with the largest revenue share of 46.0% in 2025.
- By dimension insights: The 2D segment held the largest market share of 55.0% in 2025.
- By range: The long-range segment held the market with the largest revenue share of 31.0% in 2025.
- By frequency band: The X-band segment led the market with the largest revenue share of 19.0% in 2025.
Regional Highlights
- Largest regional market: North America (32.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 12.3 Billion
- Estimated market size in 2026: USD 13.5 Billion
- Projected market size by 2033: USD 25.7 Billion
- CAGR (2026-2033): 9.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
UAVs equipped with radar systems play crucial roles in surveillance, reconnaissance, border patrol, and other applications. The demand for compact, lightweight, and efficient radar solutions suitable for UAVs drives innovation in the global market, meeting the requirements of unmanned aerial systems across military, civil, and commercial sectors.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Increasing investments in defense and aerospace modernization programs globally contribute to market growth. Governments and defense organizations allocate budgets for upgrading their airborne platforms with state-of-the-art radar systems to maintain a technological edge and ensure national security. The continuous development and procurement of new manned and unmanned aircraft propel the demand for advanced airborne radar systems, fostering market expansion.
Growing demand for advanced surveillance and reconnaissance capabilities is driving the market growth. Modern airborne radar systems play a crucial role in providing real-time situational awareness, detecting and tracking targets, and conducting intelligence, surveillance, and reconnaissance (ISR) missions. The increasing need for effective monitoring across diverse environments, including land, air, and maritime domains, drives the demand for airborne radar systems that offer enhanced detection, imaging, and target identification capabilities.
Increasing global security threats drive market growth. Airborne radar systems, with advanced features such as electronic scanning, multi-mode operation, and target discrimination, are essential for military forces and defense organizations. Their ability to provide early warning, track multiple targets simultaneously, and operate in complex electronic warfare environments addresses the evolving threat scenarios.
The increasing use of airborne radar in civilian and commercial applications also drives market growth. Beyond military use, airborne radar is used in weather monitoring, disaster management, and environmental monitoring. The versatility of airborne radar systems to provide valuable data for various non-military purposes drives adoption in civil aviation, meteorology, and scientific research, expanding the market beyond defense applications.
Analyst Perspective
The global airborne radars industry is expected to experience rapid growth owing to the growing investment by companies in the surveillance systems, early warning systems, and intelligence systems by major countries across the globe. Geopolitical instability and growing threats are further accelerating the demand for long-range and multi-domain sensing of airborne AEW&C systems. Technological advancements, including high-performing AESA radar technologies, enhance sensor integration, and network-centric defense systems are creating new growth opportunities. Moreover, defense modernization programs of several economies across the world are expected to grow this market.
Component Insights
The antennas segment led the market with the largest revenue share of more than 23.0% in 2025 and is expected to continue to dominate the industry over the forecast period. The advent of phased-array antennas and electronically scanned arrays (ESAs) has significantly enhanced the performance of airborne radar systems. Phased-array antennas enable rapid and precise beam steering, allowing for quick target acquisition and tracking. The demand for multi-function antennas (MFAs) is driving market growth. MFAs can perform various functions simultaneously, including surveillance, tracking, and communication. The integration of advanced MFAs enhances the versatility of airborne radar systems, allowing them to be applied in the military and defense.
The graphical user interface (GUI) segment is anticipated to witness at the fastest CAGR during the forecast period. The segment growth can be attributed to the need for increased situational awareness. Modern airborne radar systems generate vast datasets with information about air and ground targets, environmental conditions, and electronic warfare threats. The GUI segment addresses the challenge of presenting this information in an understandable format, enabling operators to make informed decisions rapidly. Intuitive graphical representations and interactive features facilitate rapid data assimilation, thereby enhancing situational awareness in military, defense, and surveillance applications.
Mode Insights
The air-to-ground segment led the market with the largest revenue share of over 46.0% in 2025. Increasing demand for integrated multi-role aircraft further propels the air-to-ground segment. Modern military aircraft are often equipped with versatile radar systems capable of performing a range of functions, including air-to-ground missions. This multi-role capability enables military forces to optimize their aerial assets, providing flexibility and adaptability in different operational scenarios. The versatility of air-to-ground radar systems is essential in the procurement decisions of defense organizations, supporting the overall market growth.
The air-to-air segment is expected to witness at the fastest CAGR during the forecast period. The increasing emphasis on fifth-generation fighter aircraft further propels the air-to-air segment. Modern fighter jets, including fifth-generation platforms, are equipped with advanced radar systems that offer superior performance in terms of range, stealth detection, and target engagement. The integration of highly capable air-to-air radar systems is critical to the overall effectiveness of these advanced fighter aircraft, supporting their role in air dominance and ensuring the success of air-to-air missions.
Dimension Insights
The 2D segment led the market with the largest revenue share of over 55.0% in 2025. The civilian sector benefits from 2D radar technology in air traffic control (ATC) and maritime surveillance. In air traffic control, 2D radar systems are employed to monitor the movement of aircraft, ensuring safe and efficient air travel. Similarly, these radar systems in maritime applications help monitor vessel movements, enhance navigation safety, and support search-and-rescue operations. The adaptability of 2D radar meets the diverse surveillance needs of military and civilian users.
The 3D segment is expected to witness at the fastest CAGR during the forecast period. The military sector relies heavily on 3D radar technology for air defense, early warning, and target tracking applications. 3D radar systems provide a more comprehensive understanding of the airspace by accurately determining the altitude of detected targets. This capability is crucial for identifying and tracking aircraft, drones, and missiles, particularly in scenarios where threats may approach from different altitudes. The ability to operate in three dimensions enhances the effectiveness of military operations, ensuring timely and precise responses to potential threats.
Range Insights
The long-range segment led the market with the largest revenue share of more than 31.0% in 2025. The growing need for early warning and monitoring in the face of emerging security challenges also influences the demand for long-range radar systems. Detecting and tracking potential threats from a considerable distance allows military and security forces to respond proactively, contributing to overall defense and security strategies.
The medium-range segment is anticipated to grow at the fastest CAGR during the forecast period. Medium-range radar systems are designed to provide adequate surveillance capabilities within a moderate range, making them versatile for various military and civilian applications. These radar systems play a crucial role in scenarios that require a combination of broad coverage and detailed target information. The medium-range airborne radar balances long-range detection and close-proximity target resolution, catering to diverse operational needs.
Frequency Band Insights
The X-band segment led the market with the largest revenue share of more than 19.0% in 2025. The X-band's advantages in weather penetration further enhance its significance. The X-band is less affected by adverse weather conditions, including rain and atmospheric interference, than lower-frequency radar bands. This weather-penetrating capability makes X-band radar systems reliable across various environmental conditions, ensuring consistent performance and operational effectiveness in adverse weather. This aspect is particularly crucial for military and civilian applications, where the ability to operate in challenging weather environments is paramount.
The multi-band airborne radar segment is expected to witness at the fastest CAGR during the forecast period. Improved resistance to electronic countermeasures (ECM) is driving the adoption of multi-band radar systems. These radar systems exhibit increased resilience against electronic warfare tactics, such as simultaneously jamming and spoofing using multiple bands. This resistance ensures that the radar remains effective in the face of evolving electronic threats, contributing to the overall survivability of airborne platforms. Moreover, image synthesis is being used to develop more realistic and immersive virtual worlds for entertainment and gaming.
Installation Type Insights
The retrofit segment led the market with the largest revenue share of over 67.0%. Cybersecurity enhancements are becoming increasingly important in the retrofit segment. As digital connectivity and data-sharing capabilities become integral to modern radar systems, retrofitting enables the incorporation of robust cybersecurity features. Upgraded radar systems can be equipped with advanced cybersecurity measures to protect against cyber threats, ensuring the integrity and confidentiality of critical mission data.
The new installation segment is expected to witness at the fastest CAGR during the forecast period. Government initiatives and defense modernization programs contribute to the new installation segment by fostering the adoption of advanced radar systems across military aircraft fleets. Governments and defense agencies worldwide are investing in upgrading their airborne capabilities to address emerging threats and challenges. These initiatives involve acquiring new aircraft or modernizing existing fleets, creating opportunities for installing state-of-the-art radar systems that align with the objectives of enhanced situational awareness, target identification, and overall mission success. For instance, in October 2025, L3Harris Technologies, Inc., announced it had secured a contract the deliver modified Bombardier Global 6500 airborne early warning and control (AEW&C) aircraft to the Republic of Korea Air Force. The aircraft is designed to provide combat-proven radar coverage at higher altitudes.
Technology Insights
The active electronically scanned array (AESA) segment led the market with the largest revenue share of over 24.0% in 2025. The military sector benefits significantly from AESA radar technology, especially in air-to-air and air-to-ground operations. AESA radars enhance detection, identification, and engagement of targets, providing a decisive advantage in combat scenarios. The ability to operate with high precision and to be immune to jamming makes AESA radar systems indispensable for modern military aircraft and missile defense platforms.
The digital beamforming segment is expected to witness at the fastest CAGR during the forecast period. The rise of network-centric warfare and the need for interoperability between different defense systems influence the adoption of digital beamforming technology. The ability of digital beamforming radar systems to seamlessly integrate into broader command-and-control networks enhances collaboration among various defense assets. This interoperability is crucial for achieving a unified defense and surveillance approach.
Application Insights
The commercial and business segment led the market with the largest revenue share of 61.0% in 2025. Another significant driver is the integration of radar technology into unmanned aerial vehicles (UAVs) for commercial and business applications. UAVs are increasingly used for aerial surveillance, mapping, and cargo delivery. Airborne radar systems enhance the capabilities of UAVs by providing obstacle detection, collision avoidance, and terrain mapping, enabling safe and efficient autonomous operations. The growth of the UAV market in industries such as agriculture, infrastructure inspection, and logistics amplifies the demand for radar systems tailored to the specific needs of commercial and business applications.
The defense and military segment is expected to witness at the fastest CAGR during the forecast period. Global geopolitical dynamics and new security challenges contribute significantly to the demand for advanced radar systems in the defense and military segment. Nations are investing in sophisticated airborne radar technologies to strengthen their defense capabilities, particularly in response to regional conflicts, geopolitical tensions, and the evolving nature of modern warfare. The need for robust radar systems operating in complex and contested environments is paramount, driving continuous research and development efforts.
Regional Insights
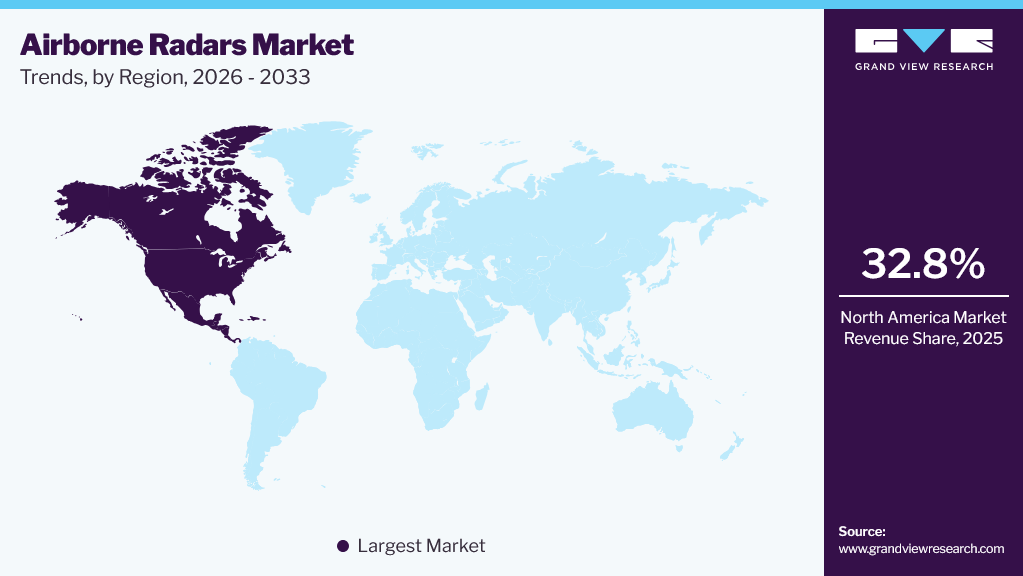
North America dominated the global airborne radars market with a revenue share of 32.8% in 2025 and is projected to grow at the fastest CAGR over the forecast period. The growing demand for intelligence, surveillance, reconnaissance (ISR), and border surveillance capabilities contributes to the momentum of the market growth in North America. The need to monitor vast territorial borders, coastal areas, and maritime domains drives investments in radar systems capable of long-range detection, tracking, and identification. This requirement addresses security challenges, including illicit trafficking, smuggling, and unauthorized border crossings.
 To learn more about this report, Download Free Sample Report
U.S. Airborne Radars Market Trends
The airborne radars market in the U.S. is expected to hold a significant revenue share in 2025 and grow at a significant CAGR over the forecast period. The U.S. military's focus on achieving multi-domain dominance further propels the demand for advanced airborne radar systems. These radar systems contribute to integrated air and missile defense, providing comprehensive situational awareness across land, air, sea, and space domains. The pursuit of interoperable and network-centric capabilities strengthens the role of airborne radar as a force multiplier, supporting joint military operations and enhancing the effectiveness of U.S. defense forces.
Asia Pacific Airborne Radars Market
The airborne radars market in the Asia Pacific is anticipated to grow at the fastest CAGR during the forecast period. The modernization and expansion of military capabilities across several countries in the Asia-Pacific are driving the rising demand for advanced airborne radar systems. Nations are investing heavily in upgrading their defense infrastructure, focusing on acquiring state-of-the-art technologies to maintain a competitive edge.
The China airborne radars market held a significant share in the Asia Pacific in 2025. The integration of airborne radar into China's broader military strategy, including the development of sophisticated fighter aircraft and naval vessels, further drives demand for advanced radar systems.
The airborne radars market in India is expected to grow at a significant CAGR over the forecast period. The persistent focus on border security and the need for continuous monitoring along India's extensive land and maritime borders further fuel the demand for advanced airborne radar systems.
Key Airborne Radars Company Insights
The airborne radars industry features a range of global, regional, and local players, making it a competitive market. The world’s leading companies are using partnerships, collaborations, acquisitions, mergers, and agreements as strategies to withstand the intense competition and increase their market share.
For instance, in January 2024, the Ministry of National Defense of the Republic of Lithuania signed a contract with the Dutch Command Materiel and IT (COMMIT) agency to acquire Thales Ground Master 200 Multi-Mission Compact radars. In collaboration with the Lithuanian partner ELSIS, Thales will be supported in the project, with a specific focus on integrating the radar system into vehicles. The compact radars boast the capability to simultaneously detect, track, and classify current and emerging threats, including drones.
Key Airborne Radars Companies
The following key companies have been profiled for this study on the global airborne radars market:
-
Lockheed Martin Corporation
-
Thales
-
Leonardo S.p.A.
-
Hensoldt
-
Honeywell Aerospace
-
L3Harris Technologies, Inc.
-
Elbit Systems Ltd.
-
Israel Aerospace Industries.
-
Indra
-
OPTIMARE Systems GmbH
-
Echodyne Corp.
Recent Developments
-
In December 2025, Saab announced that it had entered into a contract with the Directorate-General of Armaments of France to provide their GlobalEye airborne early warning & control system, consisting of two AEW&C aircraft, featuring extended range radar and a sensor suite to offer extended range and up-close surveillance of both airborne, maritime, and land threats, significantly enhancing French airborne surveillance and early-warning capabilities.
-
In January 2024, Lockheed Martin Corporation and Northrop Grumman collaborated to supply the U.S. Navy's E-2D Advanced Hawkeye with the 75th APY-9 radar. The latest iteration of the Advanced Hawkeye is equipped with Lockheed Martin's APY-9 radar system. The E-2, manufactured by Northrop Grumman, demonstrates exceptional proficiency in simultaneously monitoring air, land, and sea.
Airborne Radars Market Report Scope
Report Attribute
Details
Market size in 2025
USD 12.3 billion
Estimated market size in 2026
USD 13.5 billion
Projected market size by 2033
USD 25.7 billion
Growth rate
CAGR of 9.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, mode, dimension, range, frequency band, installation type, technology, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand; South Korea; Brazil; Argentina, South Africa; UAE
Key companies profiled
Lockheed Martin Corporation; Thales; Leonardo S.p.A.; Hensoldt; Honeywell Aerospace; L3Harris Technologies, Inc.; Elbit Systems Ltd.; Israel Aerospace Industries; Indra; OPTIMARE Systems GmbH; Echodyne Corp.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Airborne Radars Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global airborne radars market report based on component, mode, dimension, range, frequency band, installation type, technology, application, and region:
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Antennas
-
Receivers
-
Processors
-
Transmitters
-
Graphical User Interfaces
-
Stabilization Systems
-
Others
-
-
Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
Air-to-Ground
-
Air-to-Air
-
Air-to-Sea
-
-
Dimension Outlook (Revenue, USD Billion, 2021 - 2033)
-
2D
-
3D
-
4D
-
-
Range Outlook (Revenue, USD Billion, 2021 - 2033)
-
Long Range
-
Medium Range
-
Short Range
-
Very Short Range
-
-
Frequency Band Outlook (Revenue, USD Billion, 2021 - 2033)
-
X-band
-
C-band
-
KU-band
-
S-band
-
HF/VHF/UHF
-
KA-band
-
Multi-band
-
L-band
-
-
Installation Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
New Installation
-
Retrofit
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Active Electronically Scanned Array
-
Software-Defined Radar
-
Synthetic Aperture Radar
-
Digital Beamforming
-
Multistatic Radar Systems
-
Low Probability of Intercept
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Defense and Military
-
Combat Aircraft
-
Special Mission
-
Transport Aircraft
-
Helicopters
-
Unmanned Aerial Vehicles (UAVs)
-
Aerostats
-
-
Commercial and Business
-
Narrow Body Aircraft
-
Wide Body Aircraft
-
Jets
-
Helicopters
-
Urban Air Mobility (UAM)
-
Aerostats
-
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
Italy
-
France
-
Spain
-
Netherlands
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The global airborne radars market size was valued at USD 10.5 billion in 2023 and is estimated at USD 12.9 billion for 2026.
The global airborne radars market is expected to grow at a CAGR of 9.6% from 2024 to 2030, reaching USD 19.4 billion by 2030.
North America dominated the market with a revenue share of 32.8% in 2023 and is projected to grow over the forecast period. The growing demand for intelligence, surveillance, reconnaissance (ISR), and border surveillance capabilities contributes to the momentum of the airborne radar market in North America.
Some key players operating in the airborne radars market include Lockheed Martin Corporation; Thales; Leonardo S.p.A..; Honeywell Aerospace; L3Harris Technologies, Inc.; Elbit Systems Ltd.; Israel Aerospace Industries; Indra; Telephonics Corporation; OPTIMARE Systems GmbH and Echodyne Corp.
Factors such as increasing global security threats and the expanding commercial aviation sector and rising air travel demands are driving the market growth.
About the Author(s)
Electronic Security Research Team
Semiconductors & Electronics · Electronic SecurityThis report was authored by the electronic security research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic security segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


