
- Home
- »
- Organic Chemicals
- »
-
Aircraft De-icing Market Size And Share Report, 2026-2033GVR Report cover

Aircraft De-icing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Fluid Type (Type I, Type II, Type III, Type IV), By Method (Spray De-Icing, Chemical De-Icing, Infrared Heating), By Application (Military, Commercial), By Region, And Segment Forecasts
Market Size, 2025
$1.3BMarket Estimate, 2026
$1.4BMarket Forecast, 2033
$2.0BCAGR, 2026–2033
5.0%Aircraft De-icing Market Summary
The global aircraft de-icing market was valued at USD 1.3 billion in 2025 and is projected to grow from USD 1.4 billion in 2026 to USD 2.0 billion in 2033, at a CAGR of 5.0%from 2026 to 2033. The North America aircraft de-icing market held the largest revenue share of around 35.0% in 2025. The growth of the product market is attributed to the rising safety concerns, as the accumulation of snow and ice on the aircraft’s surface can significantly impact its performance. Moreover, regulatory requirements implemented by aviation authorities, such as the Federal Aviation Administration (FAA) necessitate being compliant with de-icing guidelines. Such factors are expected to advance the product demand over the forecast period.
Key Market Trends & Insights
- By fluid type: Type II segment held the largest revenue share of around 30.0% in 2025.
- By method: Spray de-icing segment held the largest revenue share of over 33.0% in 2025.
- By application: Commercial aviation segment held the largest revenue share of over 45.0% in 2025.
Regional Highlights
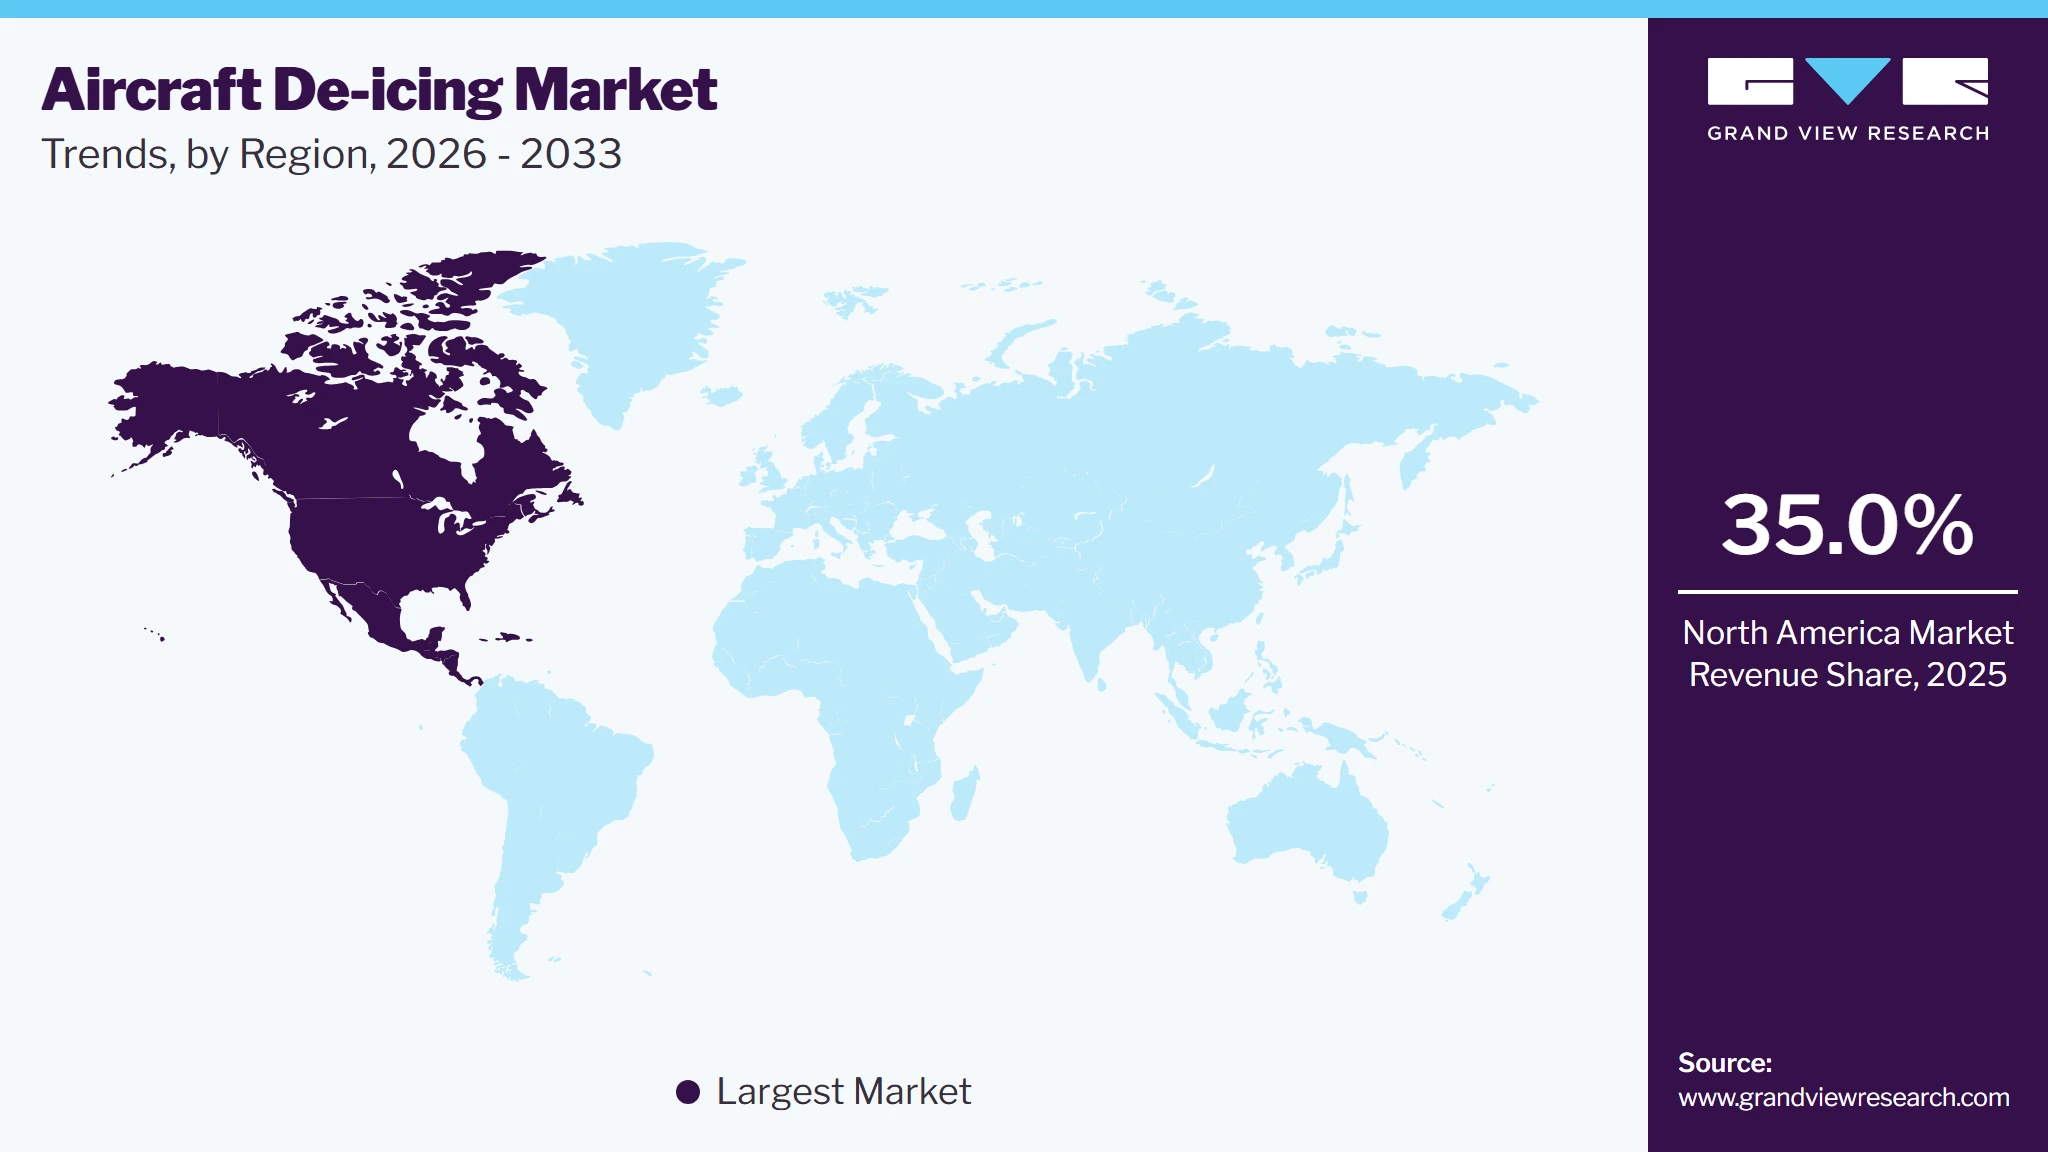
- Largest regional market: North America (35.0% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 1.3 Billion
- Estimated market size in 2026: USD 1.4 Billion
- Projected market size by 2033: USD 2.0 Billion
- CAGR (2026-2033): 5.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Regions with cold climates and frequent snowfall require aircraft de-icing solutions to ensure safe, uninterrupted flight operations, as ice accumulation on aircraft surfaces can significantly affect aerodynamics, visibility, and overall operational safety. Airports located in North America, Europe, and parts of Asia increasingly rely on de-icing procedures and fluids to prevent ice and frost buildup on wings, fuselage, engines, and runways during winter operations. In addition, the increasing number of commercial and cargo flights, coupled with the steady expansion of the global aviation industry, is significantly supporting market growth. Rising air passenger traffic, growing investments in airport infrastructure, and the expansion of airline networks into colder regions are further driving the need for efficient timely de-icing solutions.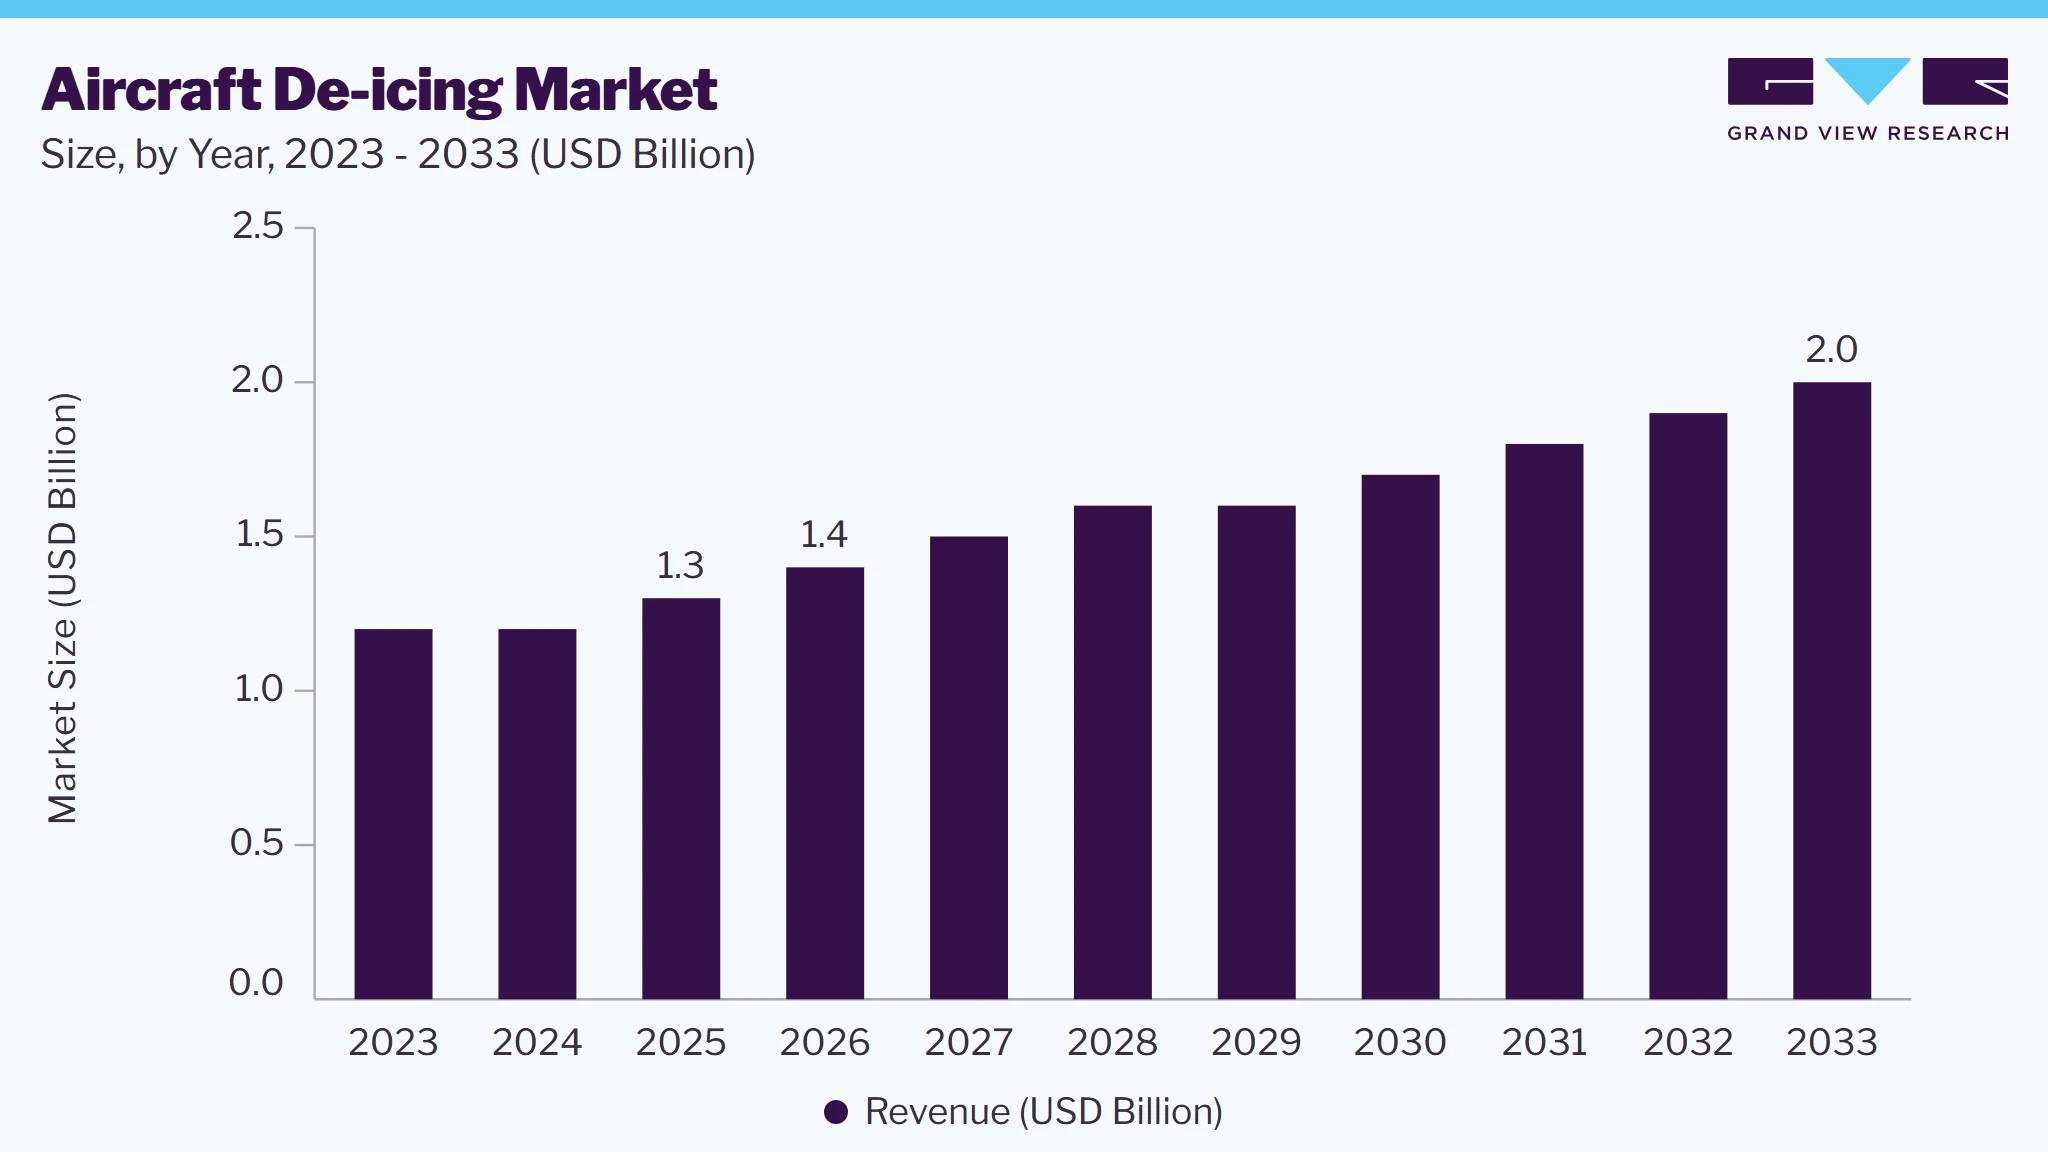 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The aircraft de-icing market is shifting toward sustainable, energy-efficient solutions as the aviation industry seeks to reduce operational costs, improve aircraft performance, and support environmental goals. Manufacturers and research institutions are investing more in new technologies that reduce energy use while ensuring flight safety and reliability. For instance, in December 2025, researchers at the Fraunhofer Institute for Structural Durability and System Reliability built a new de-icing system that works on vibration as part of the Clean Aviation initiative. This system removes ice from aircraft surfaces with the help of precise wing vibrations instead of traditional thermal methods. It can reduce de-icing energy use by up to 80% while also lowering aircraft weight and boosting overall efficiency. Such advancements demonstrate the industry’s growing focus on next-generation de-icing technologies that promote sustainability, reduce energy use, and support safer, more environmentally friendly aviation operations.
Market Dynamics
The aircraft de-icing market is primarily driven by the increasing volume of air traffic and the growing need to ensure safe flight operations during adverse winter weather conditions. According to International Air Transport Association (IATA), the full-year international traffic increased by 7.1% compared to 2024, while capacity grew by 6.8%. In December, international demand was up by 7.7% and capacity rose by 7.9%. Asia-Pacific airlines experienced a 10.9% increase in full-year international traffic for 2025 compared to 2024. Capacity rose by 10.2%, and the load factor improved by 0.5 percentage points to 84.4%. Ice and snow accumulation on aircraft wings, fuselage, and critical components can significantly affect aerodynamic performance, fuel efficiency, and operational safety, making de-icing procedures essential before takeoff. Rising investments in airport infrastructure, expansion of airline fleets, and increasing commercial and cargo flight operations in cold-climate regions are further strengthening demand. In addition, stringent aviation safety regulations and compliance requirements imposed by aviation authorities are encouraging airlines and airports to adopt advanced de-icing systems and high-performance de-icing fluids.
The aircraft de-icing market is restrained by the high costs associated with de-icing operations, including specialized equipment, fluid procurement, labor requirements, and infrastructure maintenance. De-icing fluids, particularly glycol-based formulations, require substantial quantities during peak winter seasons, increasing operational expenditure for airports and airlines. In addition, environmental concerns related to chemical runoff and contamination of nearby soil and water sources are creating regulatory pressures on airports to adopt costly containment and treatment systems. These factors can limit adoption, particularly among smaller airports and regional carriers operating with constrained budgets.
The Aircraft De-icing market presents significant growth opportunities driven by the development of environmentally sustainable de-icing fluids and advanced airport operational technologies. Growing regulatory focus on reducing the environmental impact of glycol-based chemicals is encouraging manufacturers to introduce biodegradable and lower-toxicity de-icing formulations. In addition, the integration of automated de-icing systems, weather monitoring technologies, and AI-driven operational planning helps airports improve efficiency, reduce aircraft turnaround times, and optimize fluid usage. Expanding airport modernization projects and increasing air connectivity in cold-weather emerging markets are further creating new opportunities for market expansion.
Analyst’s Perspective
The aircraft de-icing market is supported by strong long-term growth drivers, including rising global air traffic, increasing frequency of winter weather disruptions, and expanding investments in airport infrastructure across cold-climate regions. Airlines and airport operators are increasingly prioritizing operational safety and on-time performance, driving consistent demand for advanced de-icing fluids, automated spray systems, and emerging sustainable technologies, such as infrared heating solutions. However, the market is also influenced by challenges such as high operational costs, environmental concerns about glycol-based fluid runoff, and logistical constraints during peak winter demand periods, which can affect efficiency and scalability.
Fluid Type Insights
The type II segment dominated the aircraft de-icing market in 2025, accounting for around 30.0% of the market. This dominance is driven by its widespread use in anti-icing applications, particularly for protecting aircraft surfaces from ice formation during taxiing and takeoff delays in moderate to severe winter conditions. Type II fluids are widely preferred for their shear-thinning properties, which allow them to flow off aircraft surfaces during takeoff while still providing effective short-term ice protection. Their compatibility with a wide range of commercial aircraft and operational efficiency at busy airports further support strong adoption. In addition, increasing flight frequencies in cold-climate regions and stringent aviation safety requirements are reinforcing the use of Type II fluids across major international airports.
The Type I segment is expected to grow at a significant CAGR, driven by its critical role in rapid de-icing operations where immediate removal of ice, snow, and frost from aircraft surfaces is essential for safe flight departures. Type I fluids are widely preferred due to their low viscosity and fast-acting properties, which allow efficient clearing of contaminants during pre-takeoff procedures at busy airports experiencing frequent winter disruptions. The increasing need to reduce aircraft turnaround time and maintain operational efficiency in adverse weather conditions is further accelerating their adoption across commercial aviation hubs. In addition, rising air traffic volumes, expanding airport infrastructure in cold-climate regions, and strict aviation safety regulations are supporting consistent demand for Type I fluids as the primary de-icing solution before anti-icing application.
Method Insights
The spray de-icing segment dominated the aircraft de-icing market in 2025 with a share of over 33.0%, driven by its high efficiency, rapid application capability, and ability to ensure uniform coverage of aircraft surfaces under severe winter weather conditions. Spray de-icing systems are widely used at commercial airports as they enable quick removal of ice, snow, and frost from wings, fuselage, and control surfaces, thereby reducing aircraft turnaround time and minimizing flight delays. The method is particularly preferred in high-traffic airports where operational efficiency and safety are critical during peak winter operations. In addition, increasing adoption of automated and truck-mounted de-icing spray systems is further enhancing performance consistency and reducing manual intervention. Growing air traffic and stringent aviation safety regulations requiring effective pre-flight de-icing procedures are also supporting the dominance of this segment.
The infrared heating segment is expected to grow significantly during the forecast period, driven by its growing adoption as an efficient, environmentally friendly, and rapid aircraft de-icing solution that reduces reliance on chemical-based fluids. Infrared de-icing systems enable the removal of ice, snow, and frost from aircraft surfaces using controlled thermal radiation, eliminating the need for glycol consumption and significantly reducing environmental impact from runoff. The segment is gaining traction amid increasing pressure on airports to adopt sustainable ground-handling practices and comply with stricter environmental regulations on chemical de-icing fluids. In addition, infrared systems help reduce aircraft turnaround time by enabling centralized, automated de-icing operations, improving operational efficiency at high-traffic airports. Growing investments in airport modernization and green infrastructure development are further supporting the adoption of infrared heating technology across cold-climate aviation hubs.
Application Insights
The commercial aviation segment dominated the market in 2025, accounting for over 45.0% of revenue. The market growth can be attributed to the exceptionally high volume of passenger and cargo flight operations across global airport networks, particularly in regions exposed to frequent snow, frost, and freezing rain conditions. In addition, stringent aviation safety regulations mandate the complete removal of ice and snow from critical aircraft surfaces before takeoff, reinforcing the segment’s dominance. For instance, in January 2026, Amsterdam Schiphol Airport experienced widespread operational disruptions, with hundreds of commercial flights canceled and delayed as airlines such as KLM conducted continuous de-icing operations under extreme demand conditions, highlighting the heavy reliance of commercial aviation on de-icing services to sustain flight schedules.
The growth of the military segment is driven by increasing defense aviation modernization programs across major economies, including large-scale procurement of next-generation fighter aircraft, transport aircraft, and unmanned aerial vehicles (UAVs). As defense forces expand operations in high-altitude and Arctic/near-Arctic regions, the need for reliable, advanced ice-protection systems becomes increasingly critical to ensure uninterrupted mission readiness and operational safety. In addition, rising geopolitical tensions and increasing defense budgets are accelerating investments in advanced aviation capabilities, including all-weather operational readiness. This is further supported by the integration of next-generation ice protection technologies, such as electro-thermal systems, bleed-air optimization, and hybrid de-icing solutions, which improve efficiency, reduce weight, and enhance performance under extreme conditions.
Regional Insights
North America dominated the market with a share of around 35.0% in 2025. This growth is attributed to diverse and often harsh winter weather conditions, including snowstorms, freezing rain, and ice accumulation in the region. These weather conditions pose a significant challenge to the safe operation of aircraft, making effective de-icing procedures crucial. Regulatory compliance is another crucial factor leading to the strong demand for aircraft de-icing services. Regulatory bodies, such as the Federal Aviation Administration (FAA) in the U.S., have established specific guidelines concerning aircraft de-icing procedures. Airlines need to comply with these regulations to maintain their operating licenses and meet safety standards. A failure to follow these regulations can result in penalties and the potential grounding of aircraft.
 To learn more about this report, Download Free Sample Report
Key Aircraft De-icing Company Insights
The competitive environment of the aircraft de-icing market is moderately fragmented, with the presence of global chemical manufacturers, airport ground support equipment providers, and specialized aviation service companies. Key players compete based on de-icing fluid performance, operational efficiency, equipment automation capabilities, environmental compliance, and integration with advanced airport ground handling systems across commercial and military aviation networks. Increasing focus on eco-friendly de-icing fluids, automated spray systems, infrared-based de-icing technologies, and smart weather-responsive operations is intensifying competition.
-
In June 2025, Textron GSE introduced the Premier TT4000 tanker truck, designed to improve airport de-icing operations by enabling rapid refilling of active de-icing vehicles, significantly reducing downtime and increasing ramp efficiency during winter operations at busy commercial airports.
-
In September 2024, Vestergaard Company launched the OPTIM-ICE operator-assisted de-icing system, which uses LiDAR-based scanning to identify aircraft surfaces and automatically guide nozzle movements for more precise and efficient de-icing operations, improving safety and reducing operational complexity during winter conditions at airports.
Key Aircraft De-icing Companies
The following key companies have been profiled for this study on the aircraft de-icing market
-
CLARIANT
-
Dow
-
JBT Marel
-
Kilfrost Ltd.
-
LyondellBasell Industries Holdings B.V.
-
BASF SE
-
CRYOTECH
-
Vestergaard Company
-
Inland Group of Companies, LLC.
-
Textron Specialized Vehicles
Aircraft De-icing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.3 billion
Estimated market size in 2026
USD 1.4 billion
Projected market size by 2033
USD 2.0 billion
Growth rate
CAGR of 5.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in kilo tons, revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Fluid type, method, application, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; France; Italy; UK; Spain; China; India; Japan; South Korea; Brazil; Argentina; Saudi Arabia; South Africa;
Key companies profiled
CLARIANT; Dow; JBT Marel; Kilfrost Ltd.; LyondellBasell Industries Holdings B.V.; BASF SE; CRYOTECH; Vestergaard Company; Inland Group of Companies, LLC.; Textron Specialized Vehicles
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Aircraft De-icing Market Report Segmentation
This report forecasts revenue growth at the regional, and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global aircraft de-icing market report on the basis of fluid type, method, application, and region:
 To learn more about this report, Download Free Sample Report
-
Fluid Type Outlook (Volume, Kilo Tons; Revenue, USD Billion, 2021 - 2033)
-
Type I
-
Type II
-
Type III
-
Type IV
-
-
Method Outlook (Volume, Kilo Tons; Revenue, USD Billion, 2021 - 2033)
-
Spray De-Icing
-
Chemical De-Icing
-
Infrared Heating
-
Other Methods
-
-
Application Outlook (Volume, Kilo Tons; Revenue, USD Billion, 2021 - 2033)
-
Military
-
Commercial
-
Other Applications
-
-
Regional Outlook (Volume, Kilo Tons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The global aircraft de-icing market size was valued at USD 1.3 billion in 2025 and is estimated at USD 1.4 billion for 2026.
The global aircraft de-icing market is expected to grow at a CAGR of 5.0% from 2026 to 2033, reaching USD 2.0 billion.
Key players include CLARIANT; Dow; JBT Marel; Kilfrost Ltd.; LyondellBasell Industries Holdings B.V.; BASF SE; CRYOTECH; Vestergaard Company; Inland Group of Companies, LLC.; Textron Specialized Vehicles
North America dominated with a 35.0% revenue share in 2025.
Commercial aviation dominated the aircraft de-icing market with a share of 45.0% in 2025.
About the Author(s)
Organic Chemicals Research Team
Bulk Chemicals · Organic ChemicalsThis report was authored by the organic chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the organic chemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


