
- Home
- »
- Processed & Frozen Foods
- »
-
Alcoholic Beverage Market Size, Growth Report, 2026-2033GVR Report cover

Alcoholic Beverage Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Beer, Wine, Spirits), By Packaging (Aluminum Cans, Pouches, Glass Bottles, Plastic Bottles), By Distribution Channel (Food Service Channels, Retail), By Region, And Segment Forecasts
Market Size, 2025
$2,500.0BMarket Estimate, 2026
$2,600.0BMarket Forecast, 2033
$3,900.0BCAGR, 2026–2033
5.7%Alcoholic Beverage Market Summary
The global alcoholic beverage market was valued at USD 2,500 billion in 2025 and is projected to grow from USD 2,600 billion in 2026 to USD 3,900 billion in 2033, at a CAGR of 5.7% from 2026 to 2033. Asia Pacific held the largest market share of the global alcoholic beverage market. Alcoholic beverages such as beer, wine, spirits, and flavored drinks are still in high demand due to changing consumer lifestyles and more social occasions for drinking.
Key Market Trends & Insights
- By type: the beer segment held the largest market share in 2025.
- By packaging: the glass bottle segment held the largest market share in 2025.
- By distribution channel: the retail segment held the largest market share in 2025.
Regional Insights
- Largest regional market: Asia Pacific (2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 2,500 Billion
- Estimated market size in 2026: USD 2,600 Billion
- Projected market size by 2033: USD 3,900 Billion
- CAGR (2026-2033): 5.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The rising interest in premium and craft alcoholic beverages, along with increasing disposable incomes and the growth of online retail, is a major factor boosting market growth, especially in developing economies. The global alcoholic beverage market is experiencing healthy growth due to rising incomes, evolving consumption habits, shifting demographics, and growing demand for sophisticated, premium alcoholic beverages. This growing appetite for alcohol can be attributed to shifting consumer behaviors; individuals are increasingly opting for higher-priced, experience-oriented beverage selections, including premium alcoholic drinks, traditional-brewed beers, and quality wines.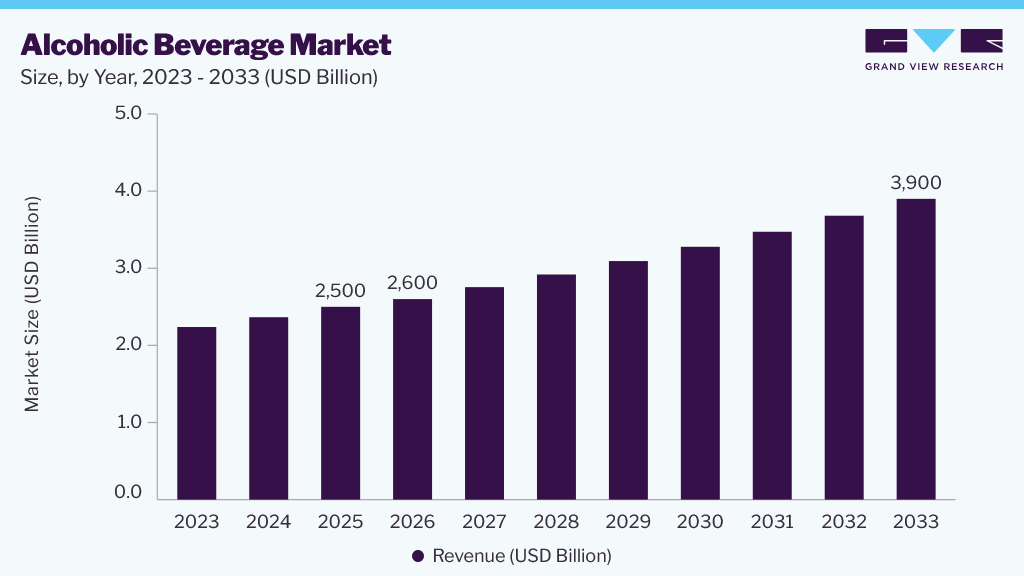 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The trend towards higher-priced beverages is particularly strong among Gen Z consumers, who are eager to discover new flavors and are willing to spend a bit more for unique blends and consumption experiences. In addition, rapid urbanization in emerging economies, along with the expansion of the middle class, has significantly boosted global beverage consumption. People frequently socialize and celebrate with drinks, further driving demand for alcoholic beverages around the world.
The ready-to-drink and flavored beverage segments, especially among young adults, are beginning to have a substantial impact on sales growth in the alcoholic products industry, both regionally and beyond. Online purchasing of alcoholic drinks is also gaining popularity among consumers worldwide, as e-commerce offers a wider variety of national and international brands along with the convenience of home delivery.
To attract more customers and meet the increasing demand for beverages from a health-conscious perspective, suppliers and retailers are developing lower-alcohol drinks, alcohol-free options, and organic and functional beverages.
Analyst Perspective
The global alcoholic beverage market has experienced healthy growth due to several factors, including premiumization, evolving consumer habits and lifestyles, and accelerated innovation in product development. There is a growing consumer preference for premium spirits, craft beer, and high-quality wine. In addition, the increased consumption of ready-to-drink (RTD) beverages, flavored alcoholic drinks, and low- and no-alcohol alternatives is expanding the existing consumer base. The rise of e-commerce and quick-commerce platforms, the proliferation of social drinking occasions, and rising consumer spending capacity in emerging economies, particularly in the Asia Pacific region, are also contributing to market growth. However, some factors pose challenges to the growth of the alcoholic beverage market. Stringent regulatory measures, rising tax duties, and bans on liquor advertising in various countries restrict market entry. Moreover, growing awareness of the negative effects of excessive alcohol consumption is leading more consumers to moderate their drinking habits, which is driving demand for low- and no-alcohol beverages. This shift could negatively impact revenue in traditional sectors. Furthermore, pricing pressures, supply chain complexities, and a highly competitive, both global and local, environment compound the challenges. Despite these factors, the alcoholic beverage market is expected to remain robust, with a shift toward innovation and premiumization to achieve a balanced approach.
Type Insights
The beer segment held the largest market share in 2025. Several factors contributed to this, including its strong brand equity, wide consumer base, and affordability in both developed and emerging markets. As a traditional alcoholic beverage, beer is distributed and easily accessible in many parts of the world through retail outlets, supermarkets, and venues serving alcohol. In addition, the rising demand for craft beers, premium varieties, and flavored beverages has further strengthened this segment's popularity, attracting a broader audience. For example, major brands such as Budweiser from Anheuser Busch InBev and Heineken continue to enjoy global appeal, with a strong presence in supermarkets, convenience stores, and bars, especially in both developed and developing markets. This underscores beer's status as the most popular form of alcohol consumption worldwide.
The spirits segment is projected to grow at the fastest CAGR during the forecast period from 2025 to 2033. This growth is driven by rising consumer preferences for premium and super-premium alcoholic beverages, the growing popularity of cocktails, and the expanding cocktail culture across all age groups. The emergence of craft distilleries, along with a diversification of flavor options and a growing interest in high-quality whisky, vodka, gin, and rum, has significantly contributed to the spirits market’s expansion. Moreover, as disposable incomes rise and product premiumization continues in developing regions, the spirits category is expected to experience substantial long-term growth. For instance, companies such as Diageo (with brands such as Johnnie Walker, Tanqueray, and Smirnoff) and Pernod Ricard are making significant investments in premium whiskies, gins, and ready-to-drink (RTD) cocktails. The rapid success of bottled and canned cocktails such as Smirnoff RTD showcases how spirits-based beverages are evolving beyond traditional consumption methods into more convenient formats.
Packaging Insights
The glass bottle segment held the largest market share in 2025. This is primarily due to its association with a premium image, product integrity, and long shelf life. Beer, wine, and spirits are predominantly packaged in glass because it effectively protects both taste and aroma, thereby enhancing the consumer experience. In addition, its high recycling rate and acceptance in both on-trade and off-trade sectors further contribute to its significant market share. Well-established branding strategies associated with glass also help maintain its "premium" positioning, ensuring it remains a staple on store shelves worldwide.
The aluminum cans segment is projected to grow at the fastest CAGR throughout the forecast period. The demand for convenience, portability, and environmentally friendly packaging has grown, particularly among younger consumers and urban populations. The use of aluminum packaging has surged due to the rising popularity of canned cocktails, craft beers, and ready-to-drink (RTD) alcoholic beverages. Moreover, aluminum cans are favored by both manufacturers and eco-conscious customers for their lightweight design, ease of transport, and high recyclability. Brands such as Cutwater Spirits and White Claw have significantly contributed to the widespread adoption of canned cocktails and flavored alcoholic beverages, which are commonly enjoyed during social gatherings, festivals, and at home due to their portability and convenience.
Distribution Channel Insights
The retail distribution channel segment dominated the global alcoholic beverage market in 2025, accounting for the largest share of overall revenue. This dominance is attributed to the widespread availability of alcoholic beverages in supermarkets, hypermarkets, convenience stores, and specialty liquor stores. Consumers prefer off-trade purchases as these retail settings offer a wide variety of brands, price points, and product categories all under one roof. This trend benefits the retail segment, making it the leading distribution channel in the alcoholic beverage market.
Moreover, organized retail formats and improved in-store promotions, along with strong brand visibility and easy accessibility, are further supporting segment growth in both developed and emerging economies. For example, large retail chains such as Walmart and Carrefour play a significant role in alcohol distribution by offering a diverse portfolio of beer, wine, and spirits across various price ranges. Their prominent shelf presence and effective promotional strategies establish retail as the primary channel of consumption.
The e-commerce segment is projected to grow at the fastest CAGR during the forecast period from 2025 to 2033. The rapid expansion of e-commerce platforms supports this growth. Consumer preferences are shifting toward convenient home delivery services, which greatly benefit the online segment. The rise of digital retail and quicker alternatives, such as quick commerce and alcohol specialists, is reshaping how consumers in urban and younger demographics purchase products. As more regions adopt alcohol e-commerce, with significant consumer incentives, a broad selection, and seamless buying processes, online retail is becoming one of the hottest and fastest-growing channels in the marketplace. For instance, platforms such as Drizly, now integrated with Uber Eats in some regions, and Uber Technologies have accelerated the home delivery of alcohol, especially in the post-pandemic period. Consumers are increasingly opting to order alcoholic beverages online for the convenience, variety, and doorstep delivery they offer.
Regional Insights
In 2025, the Asia Pacific held the largest market share of the global alcoholic beverage market, owing to key factors including an expanding consumer base, rising disposable incomes, and increasing urbanization in major economies such as China, India, and Japan. The growing acceptance of premium alcoholic beverages, such as craft beer, imported spirits, and flavored drinks, further enhances market penetration across the region.
In addition, the rise of modern retail formats and the rapidly developing e-commerce channels are facilitating greater product accessibility, particularly in urban centers. Consumers in the Asia Pacific are adopting a lifestyle approach to consumption, leading to a higher demand for high-end and branded alcoholic products. Notable consumption trends include the increasing popularity of international beer brands in China and the surge in whisky and ready-to-drink (RTD) beverage consumption in India, illustrating the evolving consumption patterns in the region.
North America Alcoholic Beverage Market Trends
North America plays a crucial and valuable role in the global alcohol industry. It is the oldest developed region, characterized by strong consumer spending, a deeply rooted drinking culture, and significant product innovation. The U.S. displays the highest demand, particularly for premium spirits, craft beer, and new alcoholic beverage formats with lower alcohol content.
The region is a hub for industrial innovation, with many multinational companies launching a variety of new alcoholic beverages and novel drinking experiences that align with evolving consumer tastes. The rise in popularity of craft beer and premium whiskey highlights North American consumers' preference for innovation and quality over mass-marketed options.
Although the region's growth may be moderate compared with that of some emerging economies, it remains strategically significant and generates substantial revenue. North America boasts strong brand equity and sophisticated distribution networks. For example, Constellation Brands has a solid presence in the U.S. market, especially with its premium beer offerings such as Corona and Modelo. The company's growth is largely fueled by strong demand for premium imported-style beers and a consumer shift toward high-quality, brand-driven alcoholic beverages. This trend reflects the market's maturity, where growth is driven primarily by premiumization, brand loyalty, and product innovation rather than mere volume expansion.
Key Alcoholic Beverage Company Insights
The global alcoholic beverage market is highly competitive, characterized by a strong presence of both multinational corporations and regional players. Companies are actively pursuing mergers, acquisitions, partnerships, and brand extensions as strategies to increase market share and thrive in a rapidly evolving industry.
A significant trend in this sector is the focus on "premiumization." Many companies are leveraging craft-based brands and ready-to-drink (RTD) alcoholic beverages, and offering lower-alcohol or alcohol-free alternatives to meet consumer demand.
Moreover, companies are innovating in packaging, implementing sustainability initiatives, and developing new flavors to attract younger consumers and enhance shelf visibility. For example, Heineken has been expanding its portfolio of premium beers and non-alcoholic beverages, while also promoting sustainable brewing practices and recyclable packaging. These efforts demonstrate how leading players are adapting to modern consumer trends while maintaining strong global brand positioning.
Key Alcoholic Beverage Companies
The following key companies have been profiled for this study on the alcoholic beverage market.
-
Anheuser-Busch InBev SA/NV
-
Bacardi Limited
-
Carlsberg Group
-
Constellation Brands, Inc.
-
Diageo plc
-
Heineken N.V.
-
Kirin Holdings Company, Limited
-
Molson Coors Beverage Company
-
Pernod Ricard SA
-
Suntory Holdings Ltd.
Recent Developments
-
In September 2025, Heineken N.V. expanded its Heineken 0.0 non-alcoholic beer portfolio in the U.S. through the nationwide relaunch of its limited-edition “L0VE.L0VE” cans following a successful 2024 debut. The launch was supported by the “0.0 Reasons, 0.0 Judgment” campaign during the US Open, reflecting the company’s focus on promoting alcohol-free social consumption and expanding its appeal among health-conscious and younger consumers seeking inclusive beverage options.
-
In 2024, Anheuser-Busch InBev expanded the global presence of Corona Cero, a zero-alcohol beer under its Corona brand, positioning the product within the rapidly growing non-alcoholic beer segment. The company promoted the brand through major international sponsorships, including the Olympic Games, strengthening product visibility and consumer awareness across multiple global markets.
Alcoholic Beverage Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2,500 billion
Estimated market size in 2026
USD 2,600 billion
Projected market size by 2033
USD 3,900 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, packaging, distribution channel, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; France; Germany; Italy; Spain; China; Japan; India; Australia; South Korea; Brazil; Argentina; South Africa
Key companies profiled
Anheuser-Busch InBev SA/NV; Bacardi Limited; Carlsberg Group; Constellation Brands, Inc.; Diageo plc; Heineken N.V.; Kirin Holdings Company, Limited; Molson Coors Beverage Company; Pernod Ricard SA; Suntory Holdings Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Alcoholic Beverage Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global alcoholic beverage market report based on type, packaging, distribution channel, and region:
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Beer
-
Wine
-
Spirits
-
Ciders and Flavored Alcoholic Beverages (FABs)
-
Others
-
-
Packaging Outlook (Revenue, USD Billion, 2021 - 2033)
-
Aluminum Cans
-
Pouches
-
Glass Bottles
-
Plastic Bottles
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Food Service Channels
-
Retail Channels
-
Hypermarkets & Supermarkets
-
Convenience Stores
-
E-commerce
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
-
Frequently Asked Questions About This Report
The global alcoholic beverage market size was valued at USD 2,500 billion in 2025 and is estimated at USD 2,600 billion for 2026
The global alcoholic beverage market is expected to grow at a CAGR of 5.7% from 2026 to 2033, reaching USD 3,900 billion
Asia Pacific dominated the global market in terms of revenue share in 2025
The beer segment accounted for the largest revenue share in 2025
Key players in the market include Anheuser-Busch InBev SA/NV; Bacardi Limited; Carlsberg Group; Constellation Brands, Inc.; Diageo plc; Heineken N.V.; Kirin Holdings Company, Limited; Molson Coors Beverage Company; Pernod Ricard SA; Suntory Holdings Ltd., and others
About the Author(s)
Processed & Frozen Foods Research Team
Consumer Goods · Processed & Frozen FoodsThis report was authored by the processed & frozen foods research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the processed & frozen foods segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


