
- Home
- »
- Pharmaceuticals
- »
-
Antacids Market Size, Share & Trends Report, 2026-2033GVR Report cover

Antacids Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Tablet, Liquid), By End Use (Retail Pharmacy, Hospital Pharmacy, Online Pharmacy), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$8.1BMarket Estimate, 2026
$8.4BMarket Forecast, 2033
$11.4BCAGR, 2026–2033
4.4%Antacids Market Summary
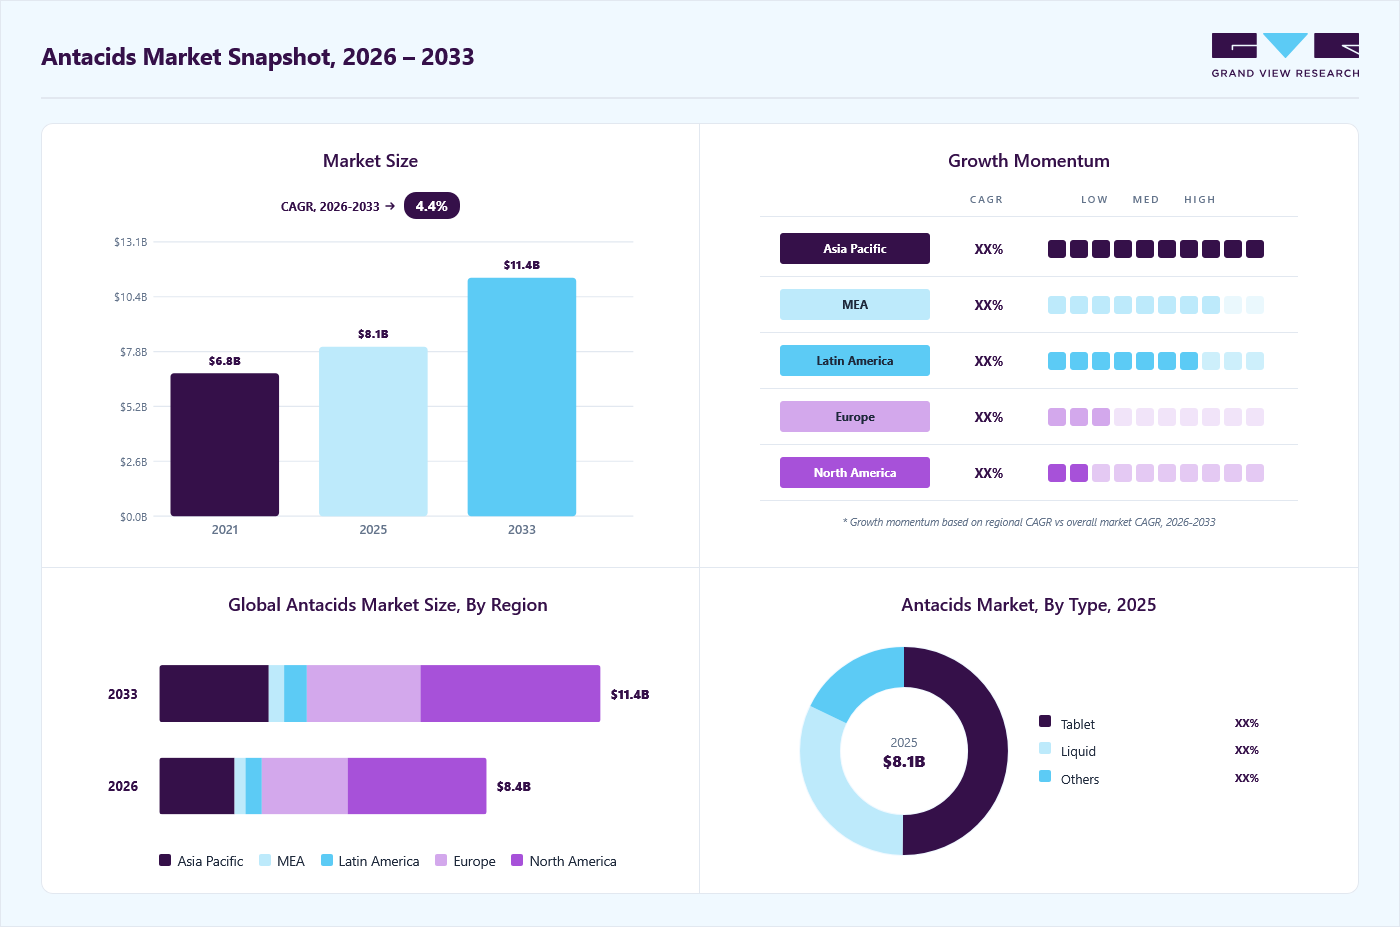
The global antacids market size was valued at USD 8.1 billion in 2025 and is projected to grow from USD 8.4 billion in 2026 to USD 11.4 billion by 2033, at a CAGR of 4.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 42.7% in 2025. Changing dietary habits are among the major factors expected to fuel the growth of the market during the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Tablet segment led the market with the largest revenue share of 50.2% in 2025.
- By end use: Retail pharmacy segment led the market with the largest revenue share of 72.2% in 2025.
Regional Highlights
- Largest regional market: North America (42.7% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.1 Billion
- Estimated market size in 2026: USD 8.4 Billion
- Projected market size by 2033: USD 11.4 Billion
- CAGR (2026-2033): 4.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The increasing prevalence of gastroesophageal reflux disease (GERD), peptic ulcers, and various other digestive disorders, which result in acidity, digestion problems, and heartburn are also expected to drive the market. According to a study published by the National Institutes of Health (NIH) in 2022, 783.95 million people were diagnosed with GERD globally in 2019. The total number of years of life lived with disability (YLD) increased by 77.19%, whereas the total number of prevalent cases increased by 77.53%, and the total number of incident cases increased by 74.79% from 1990 to 2019.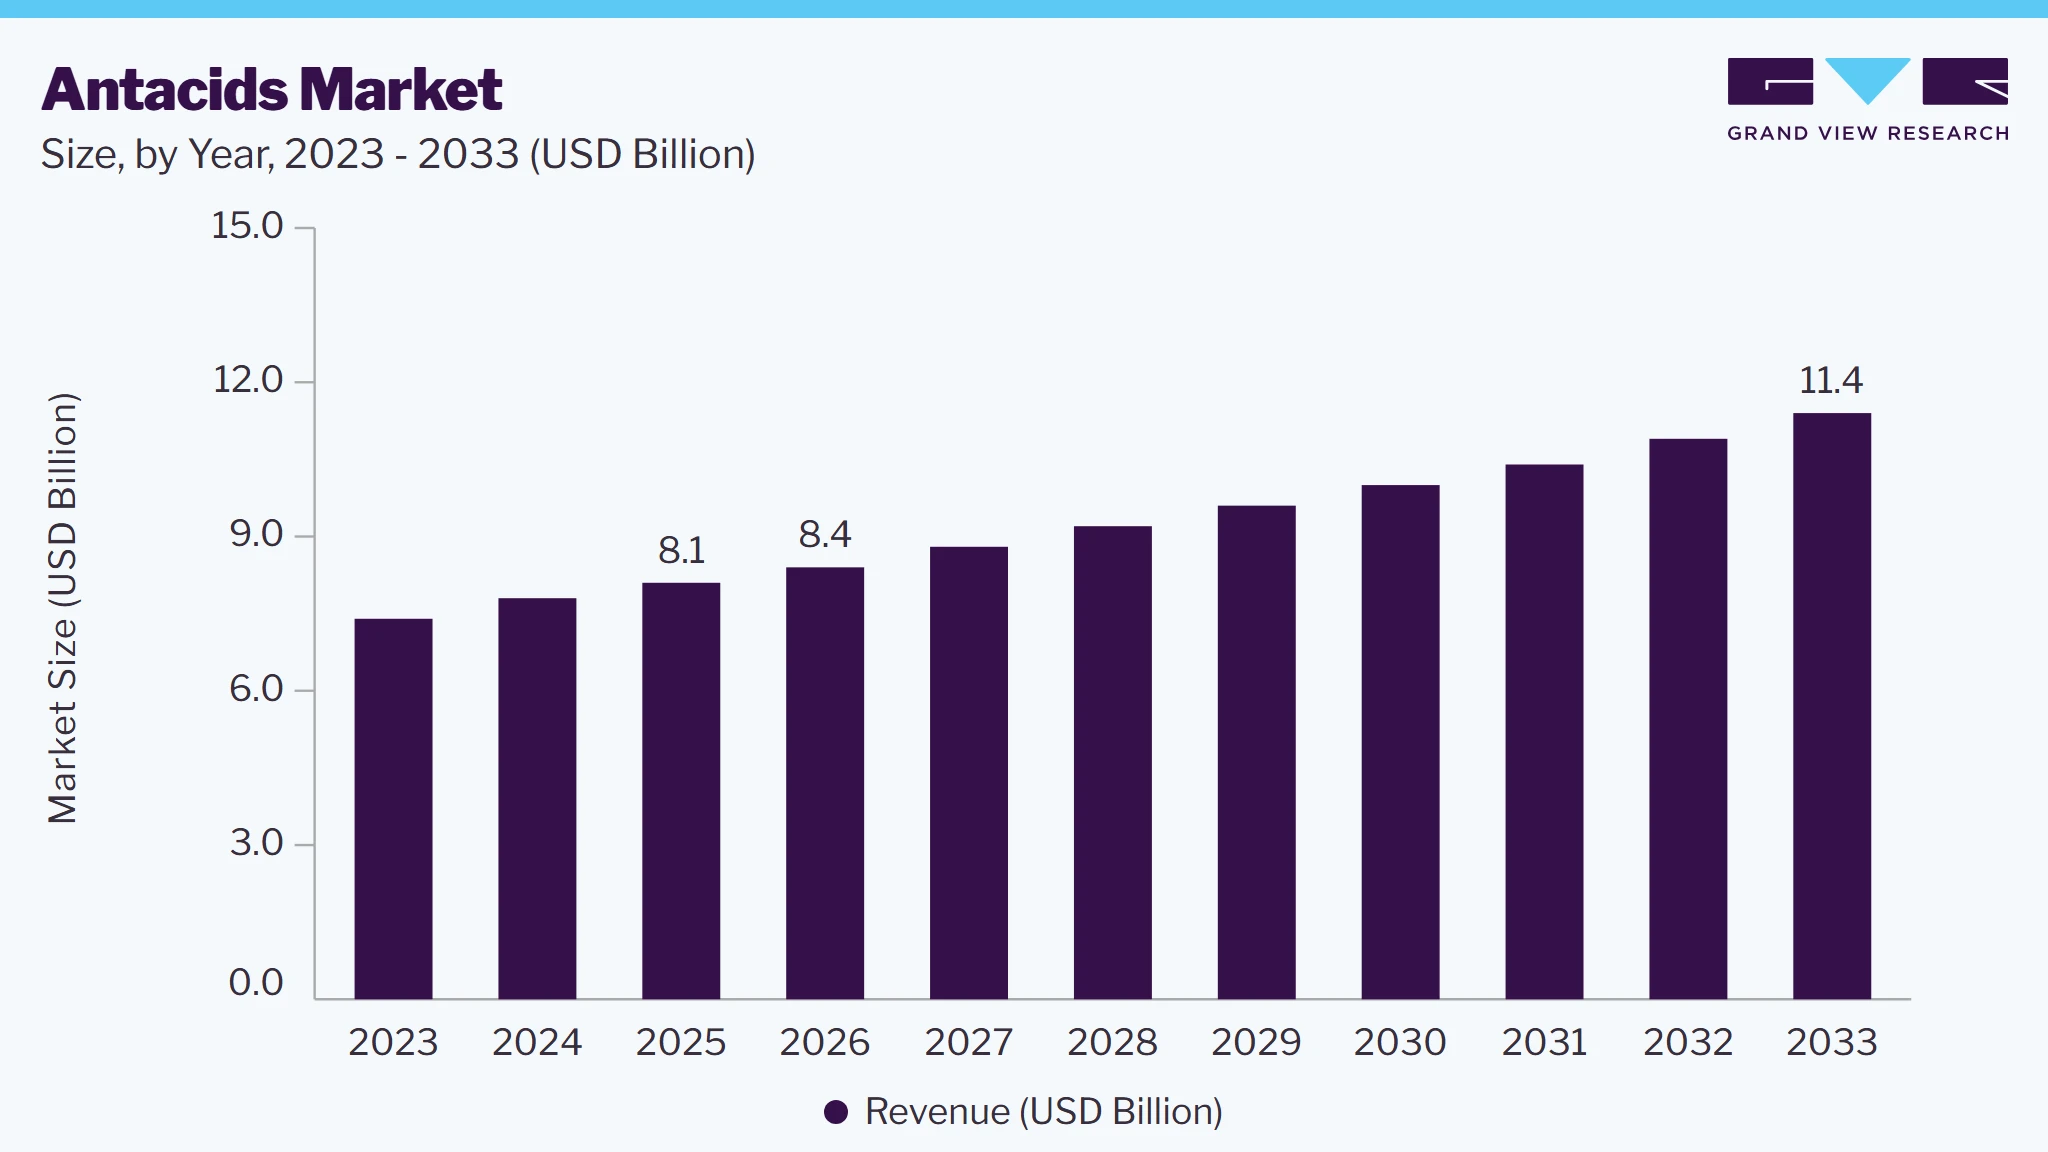 To learn more about this report, Download Free Sample Report
Furthermore, increasing awareness about GERD is anticipated to boost the market growth. According to an article published in the International Foundation for Gastrointestinal, the International Foundation for Functional Gastrointestinal Disorders (IFFGD) encourages patients suffering from GERD-related symptoms, to consult their physicians.
Other factors include rising awareness and availability of over-the-counter (OTC) antacids that offer quick and effective relief from these symptoms and the growing geriatric population that is more prone to digestive issues and requires frequent use of antacids. Changing dietary habits and lifestyle factors such as stress, smoking, alcohol consumption, and obesity that contribute to the development of acid-related disorders can also affect the growth of the market.
In the geriatric population, acid complications create a unique challenge for both general practitioners and gastroenterologists. Moreover, such patients often suffer from various symptomatic disorders such as Barrett's esophagus, and esophageal cancer. For the treatment of such disorders, a combination of treatments is used and the use of antacids in such cases has increased significantly, which is expected to drive the market growth over the forecast period.
Market Dynamics
The antacid market is characterized by sustained demand for over the counter gastrointestinal therapies used for the management of heartburn, acid indigestion, and mild gastroesophageal reflux symptoms. Market activity remains concentrated around calcium carbonate based antacids and alginate containing formulations, particularly in North America and Europe where self medication rates are high. Manufacturers are focusing on line extensions through sugar free variants, flavored formulations, and portable dosage formats to maintain brand competitiveness in a mature product category. The market is also experiencing increasing competition from proton pump inhibitors and H2 receptor antagonists, which are widely used for longer duration acid suppression. Retail pharmacies continue to account for a significant share of product distribution, while online pharmacy channels are gaining importance across developed markets. In emerging economies, expanding consumer access to self care medications and broader pharmacy penetration are supporting product consumption. Generic competition remains a key factor affecting pricing across multiple regional markets.
The increasing prevalence of gastroesophageal reflux disease, heartburn, dyspepsia, and indigestion continues to support demand for antacid products globally. Changes in dietary patterns, growing consumption of processed foods, rising obesity rates, and sedentary lifestyles have contributed to a larger population experiencing acid related gastrointestinal symptoms. Antacids remain among the most widely utilized self care treatments due to their ability to provide rapid symptomatic relief and broad availability through over the counter channels. Demand remains particularly strong among consumers seeking immediate management of occasional reflux and heartburn without requiring physician consultation. The market also benefits from increasing awareness of gastrointestinal health and expanding access to consumer healthcare products across emerging economies. Retail pharmacies, supermarkets, and online pharmacies continue to improve product accessibility, supporting consistent utilization across various demographic groups. In addition, the growing elderly population contributes to demand as older individuals frequently experience gastrointestinal discomfort associated with age related conditions and medication use. Manufacturers continue to focus on formulation improvements, flavor enhancements, and convenient dosage formats to maintain consumer preference. These factors collectively support stable demand for antacid products across both developed and emerging healthcare markets.
The antacid market faces limitations due to increasing utilization of proton pump inhibitors and H2 receptor antagonists for the treatment of chronic acid related disorders. While antacids provide immediate symptom relief, their relatively short duration of action makes them less suitable for long term management of gastroesophageal reflux disease and other persistent gastrointestinal conditions. Healthcare professionals often recommend alternative therapies that offer prolonged acid suppression and reduced symptom recurrence, particularly among patients requiring continuous treatment. The widespread availability of generic proton pump inhibitors has further increased accessibility and affordability, creating additional competition for traditional antacid products. In many developed healthcare markets, treatment approaches have shifted toward therapies that address disease progression rather than solely managing symptoms. The mature nature of the antacid category also creates pricing pressure due to the presence of numerous generic and private label products. Limited product differentiation among standard formulations can restrict premium pricing opportunities for manufacturers. Furthermore, increasing consumer awareness regarding long term disease management may encourage the use of alternative therapies for recurrent symptoms. These factors continue to moderate growth potential within the antacid market despite the sustained prevalence of gastrointestinal disorders and consistent demand for rapid symptom relief products.
The growing focus on digestive health within the consumer healthcare industry presents a significant opportunity for the antacid market. Manufacturers are increasingly expanding their gastrointestinal product portfolios through acquisitions, portfolio diversification, and consumer focused product development strategies. Demand for convenient self-care solutions continues to increase as consumers seek accessible options for managing occasional heartburn, acid indigestion, and reflux symptoms. Product innovation remains focused on improving convenience, taste, portability, and consumer experience through chewable formulations, gummies, liquid suspensions, and sugar free alternatives. The continued expansion of online pharmacy platforms and direct to consumer distribution channels is also improving product visibility and accessibility across both developed and emerging markets. Increasing healthcare awareness and broader availability of over the counter digestive health products further support category growth. In addition, strategic acquisitions are enabling larger consumer healthcare companies to strengthen their presence within digestive wellness segments and access newer consumer demographics. For instance, in January 2026, Procter & Gamble acquired Wonderbelly, a digestive health brand offering antacid products, expanding its Personal Health Care portfolio and strengthening its position within the digestive wellness category. Such strategic investments demonstrate continued industry interest in expanding digestive health offerings and support future opportunities for innovation, product differentiation, and broader consumer reach across global markets.
Analyst Perspective
The antacid market continues to be a mature segment of the gastrointestinal therapeutics industry, with demand supported by the consistent use of over the counter products for heartburn, acid indigestion, and reflux symptom management. Market competition is centered on established brands, generic alternatives, formulation differentiation, and distribution reach. Tablet formulations continue to account for a significant share of consumption due to convenience and broad availability, while liquid products maintain demand among specific patient groups. The market is witnessing increased emphasis on consumer friendly formats, including flavored, sugar free, and portable formulations. In addition, online pharmacy expansion and growing consumer engagement in self care are creating opportunities for broader product accessibility. Strategic investments in digestive health portfolios and brand expansion activities are expected to remain key competitive factors across major markets.
Type Insights
Based on type, the tablet segment led the market with the largest revenue share of 50.2% in 2025. The presence of chewable tablets in different flavors helps in improving patient adherence to the medication. In addition, tablets can provide the exact amount of dosage to the patients compared to other dosage forms and also they are easy to store compared to other counterparts. These factors can be attributed to the segment growth over the forecast period. Some well-known brands of chewable tablets include TUMS, manufactured by the Haleon Group of Companies; Alka-Seltzer, manufactured by Bayer AG; and Rolaids, manufactured by Sanofi Consumer Healthcare.
Strict regulations regarding formulations, labeling, and other elements associated with medicines have been stimulating reformulations, product relaunches, and enhanced R&D efforts in this market. For instance, in November 2025, the U.S. Food and Drug Administration announced approval for reformulated ranitidine tablets, which marked return of widely used acid-reducing medicine the U.S. industry. Such developments highlight the growth trends in this market.
The liquid segment is expected to grow at a significant CAGR over the forecast period. The presence of key players, such as Pfizer Inc., GlaxoSmithKline plc. and Dabur offering liquid antacids is estimated to boost the segment growth. Also, the liquid dosage form is one of the most favored choices for children and the elderly population due to its palatable taste. This factor is also anticipated to foster market growth.
End Use Insights
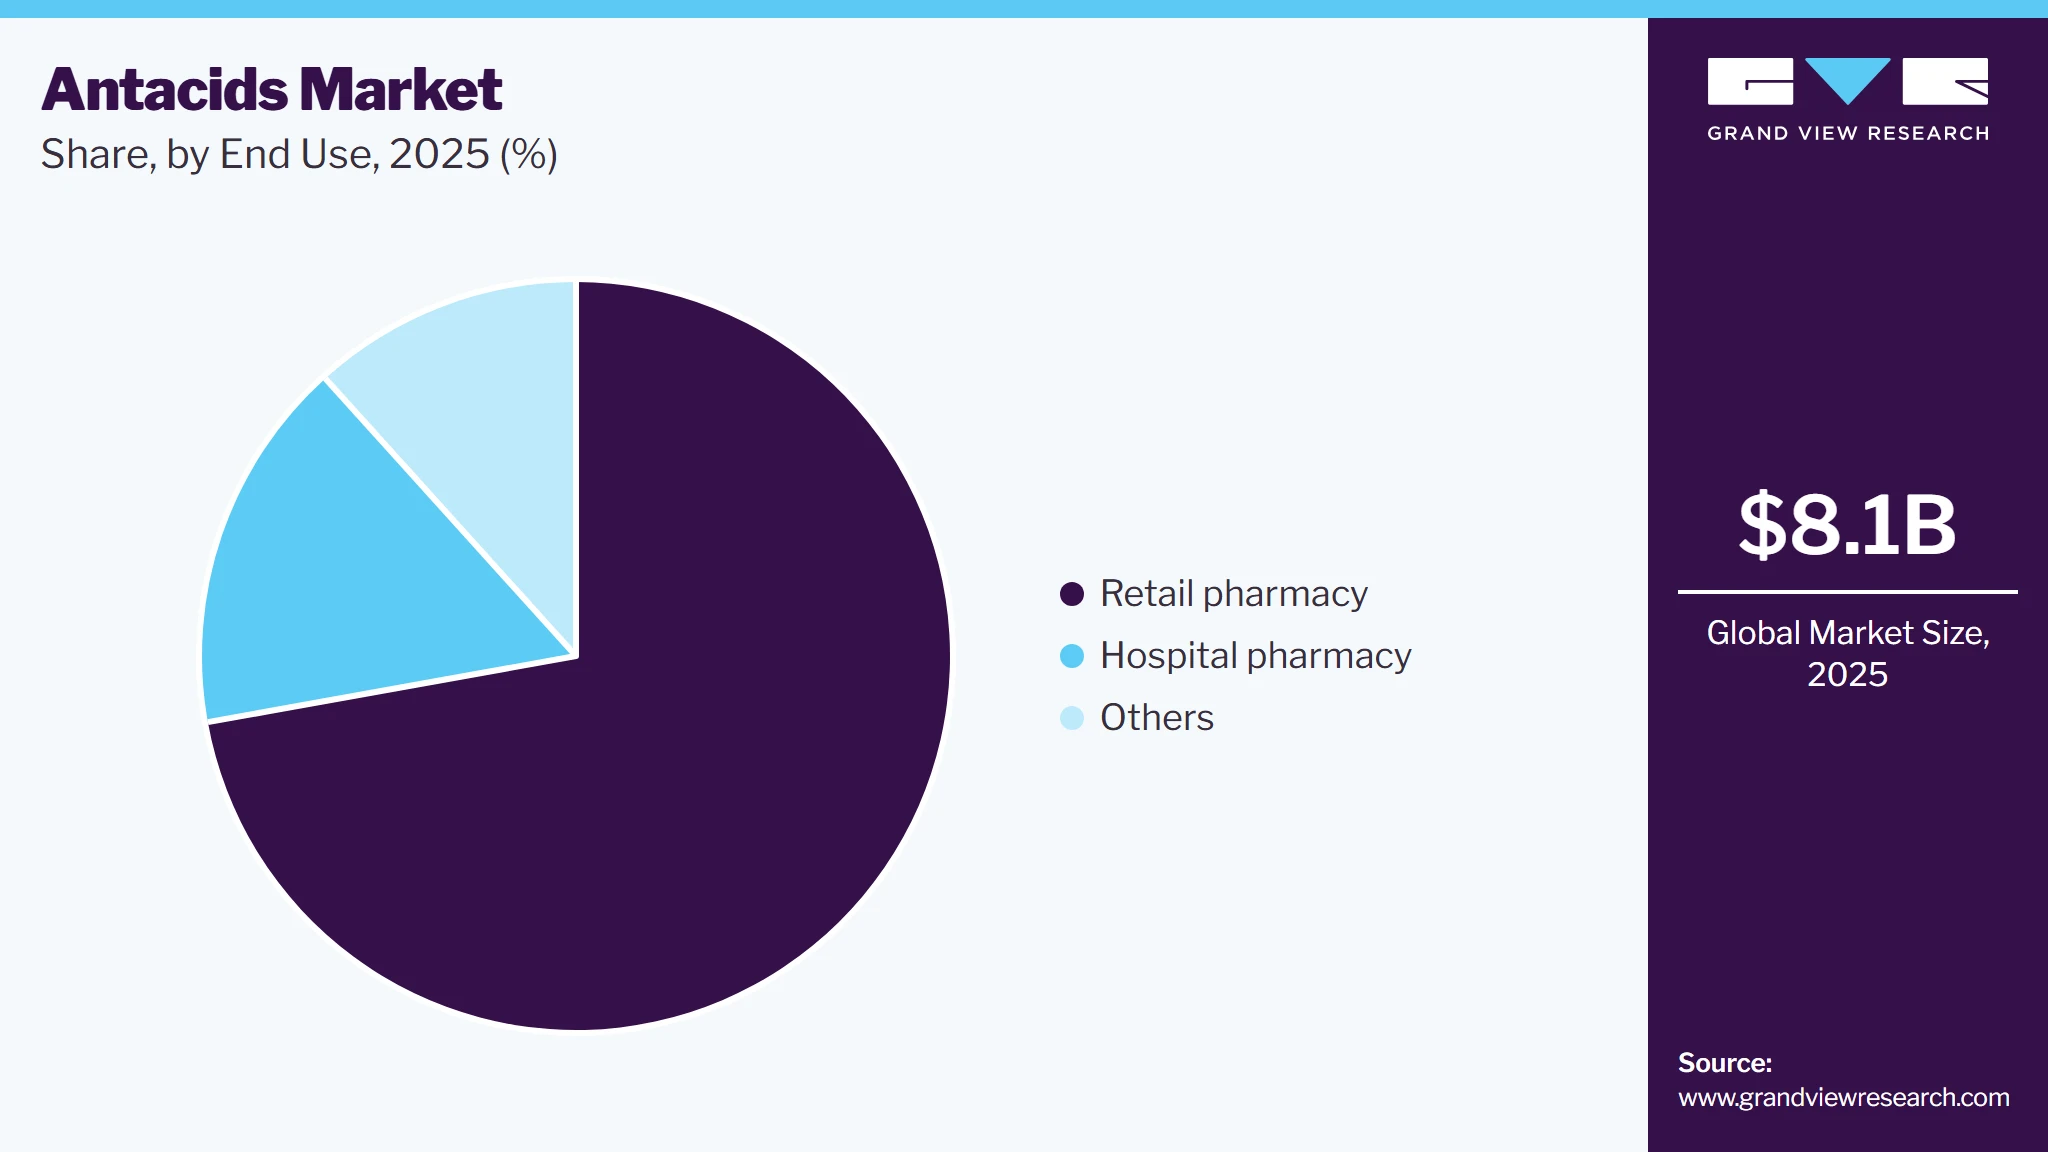
Based on end use, the retail pharmacy segment led the market with the largest revenue share of 72.2% in 2025. Easy accessibility, increasing number of retail pharmacies operated by organized retail businesses, and assistance provided by local pharmacist in making right choices for OTC medicines, are some of the key growth drivers for this segment. Retail pharmacies have been offering variety of products with similar symptom relief properties, which enables additional choices for the patients, leading to greater engagements.
 To learn more about this report, Download Free Sample Report
Presence of large retail businesses in this segment is anticipated to fuel growth in forecast period. Multiple large-scale operators in retail industry have been adopting automation and enhanced warehousing techniques to develop competitive advantage over others. For instance, in May 2025, Walmart announced opening of its centralized prescription processing facility, spanning across 102,000-square-foot, in Frederick, Maryland. The facility is developed to address 100,000 prescriptions each day, to facilitate seamless operational support for nearly 700 stores across multiple states. It also announced ongoing facility developments in Phoenix, Arizona and Republic, Missouri. Such advancements are likely to support growth of retail pharmacy segments in this market.
Online pharmacy is anticipated to grow at the fastest CAGR over the forecast period, owing to perks such as quick home delivery, diversity in options for goods, better pricing, and discounts. Some of the top online pharmacy companies in the U.S. include Sesame, Amazon Pharmacy, CVS, Pill Pack, Blink Health, and GeniusRx. In February 2026, Amazon announced its plans to expand same-day prescription delivery through Amazon Pharmacy to 4,500 U.S. locations by the end of 2026. Such developments are expected to support segment growth during the forecast period.
Regional Insights
North America Antacids Market Trends
North America dominated the antacids market with the largest revenue share of 42.7% in 2025. The antacids market in the U.S. held the largest share in the North America region in 2025. This is attributed to a well-established healthcare system and infrastructure, easy information availability, and a strong retail pharmacy presence in the region. In addition, the presence of multiple companies engaged in the manufacturing and marketing of antacids in the regions also contributes to the growth experienced by this regional industry.
 To learn more about this report, Download Free Sample Report
Asia Pacific Antacids Market Trends
Asia Pacific antacids industry is projected to register the fastest CAGR over the forecast period, which is attributed to high unmet clinical needs, increasing awareness about the immediate relief benefits offered by the antacids, and the growing network of retail pharmacies in countries such as India and China. The presence of various manufacturing organizations such as Haleon, Reckitt Benckiser, Sanofi, Bayer AG, Johnson & Johnson, Sun Pharmaceutical Industries, Dr. Reddy's Laboratories, and others also adds significant strength to the region’s growth potential.
Key Antacids Company Insights
The competitive environment of the market is highly fragmented, with the presence of several multinational players and small-scale companies, competing to gain higher market share. New product launches, geographical expansion, and joint ventures are some of the key strategies undertaken by key players in the market.
Key Antacids Companies
The following key companies have been profiled for this study on the antacids market.
-
GSK plc.
-
Bayer AG
-
Boehringer Ingelheim International GmbH
-
Dr. Reddy’s Laboratories Ltd.
-
Sanofi
-
Reckitt
-
Sun Pharmaceutical Industries Ltd.
-
Takeda Pharmaceutical Company Limited
-
Pfizer Inc.
-
Procter & Gamble
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Reckitt, Procter & Gamble, Sanofi, Bayer AG, Takeda Pharmaceutical Company Limited)
- Focus on strengthening digestive health portfolios through brand extensions, formulation improvements, consumer awareness campaigns, and expansion across retail and online pharmacy channels. Emphasize established antacid brands, broad geographic coverage, and integration of digestive health products within larger consumer healthcare portfolios.
- Strong brand equity, extensive distribution networks, significant marketing resources, and established relationships with retailers and pharmacy chains. Broad global presence enables efficient product availability and consumer reach across developed and emerging markets.
- High exposure to competition from generic and private label products. Mature product portfolios may limit opportunities for significant differentiation. Large organizational structures can slow response to changing consumer preferences and niche product trends.
Emerging and Regional Players (Dr. Reddy’s Laboratories Ltd., Sun Pharmaceutical Industries Ltd., GSK plc., Boehringer Ingelheim International GmbH, Pfizer Inc.)
- Focus on expanding regional market presence through cost competitive formulations, targeted distribution strategies, product portfolio optimization, and selective participation in gastrointestinal care categories. Emphasize accessibility, affordability, and penetration within high volume retail pharmacy markets.
- Strong manufacturing capabilities, competitive pricing strategies, and established presence in key regional pharmaceutical markets. Ability to address price sensitive consumer segments and capitalize on growing demand in emerging economies.
- Lower brand visibility within the antacid category compared with leading digestive health brands. Limited digestive health portfolio focus may restrict competitive positioning and investment relative to companies with dedicated consumer healthcare gastrointestinal franchises.
Recent Developments
-
In January 2026, Wonderbelly, one of the digestive health company, engaged in clean-label product developments, was acquired by Procter & Gamble. Becoming part of P&G’s personal health care portfolio, Wonderbelly is expected to strengthen P&G position in consumer health industry.
-
In July 2024, Phathom Pharmaceuticals, a biopharmaceutical company dedicated to the development and market launch of next-generation therapies for gastric acid disorders, announced the approval of the FDA for VOQUEZNA (vonoprazan) 10 mg tablets, which are used to reduce the heartburn related to Gastroesophageal Reflux Disease (GERD) in adults.
Antacids Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.1 billion
Estimated market size in 2026
USD 8.4 billion
Projected market size by 2033
USD 11.4 billion
Growth rate
CAGR of 4.4% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
GSK plc.; Bayer AG; Boehringer Ingelheim International GmbH; Dr. Reddy’s Laboratories Ltd.; Sanofi; Reckitt; Sun Pharmaceutical Industries Ltd.; Takeda Pharmaceutical Company Limited; Pfizer Inc.; Procter & Gamble.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Antacids Market Report Segmentation
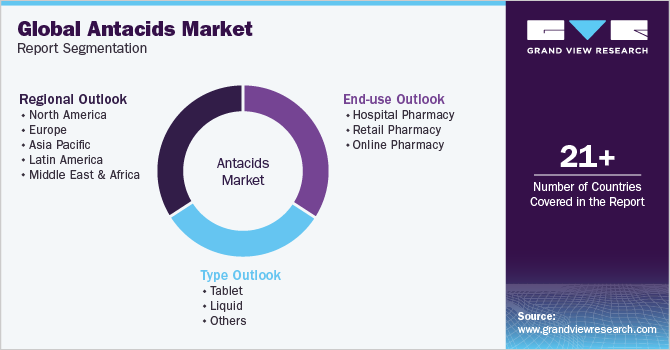
This report forecasts revenue growth at the regional and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global antacids market report based on type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Tablet
-
Liquid
-
Others
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Pharmacy
-
Retail Pharmacy
-
Online Pharmacy
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The antacids market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each antacids segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Tablet
Includes antacid products formulated and marketed in tablet form, including chewable tablets, swallow tablets, compressed tablets, and flavored tablet variants. Revenue is attributed to products sold in solid tablet dosage formats for the management of acid related gastrointestinal symptoms.
Liquid
Includes antacid products formulated as oral liquids, suspensions, syrups, and ready to consume liquid preparations. Revenue is attributed to products sold in liquid dosage formats for the management of heartburn, acid indigestion, reflux symptoms, and related gastric discomfort.
Others
Includes antacid products marketed in dosage forms other than tablets and liquids, including powders, granules, effervescent products, gummies, orally dissolving formulations, and other alternative delivery formats. Revenue is attributed exclusively to these non tablet and non liquid antacid products.
Segment - End Use
Revenue capture definition
Hospital Pharmacy
Includes antacid products procured and dispensed through hospital pharmacy channels for inpatient and outpatient use. Revenue is attributed to sales supplied directly through hospital affiliated pharmacy operations and excludes retail and online pharmacy transactions.
Retail Pharmacy
Includes antacid products distributed through community pharmacies, chain pharmacies, drug stores, supermarkets, and other physical retail outlets. Revenue is attributed to purchases completed through brick and mortar retail channels and excludes hospital and online pharmacy sales.
Online Pharmacy
Includes antacid products purchased through licensed online pharmacies, digital healthcare platforms, and e commerce pharmacy channels. Revenue is attributed to transactions completed through online ordering platforms and excludes sales occurring through hospital and physical retail pharmacy channels.
Estimation Model
 To learn more about this report, Download Free Sample Report
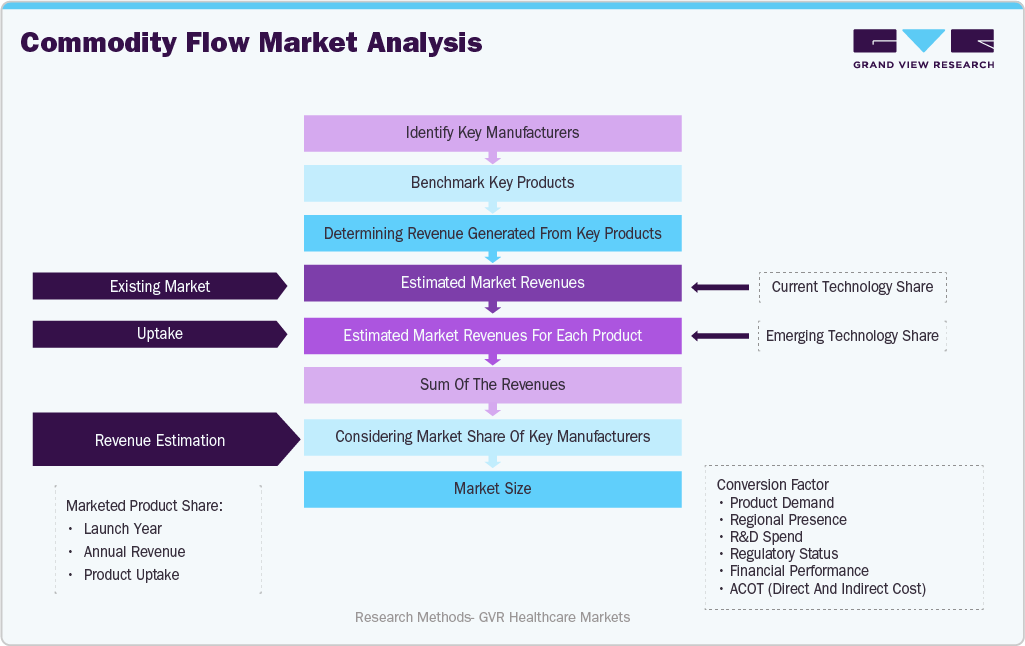
The Antacid Market was estimated using a commodity flow and revenue based market analysis approach. The methodology began with the identification of key manufacturers and commercially available antacid products across major markets. Leading brands and generic products were benchmarked based on product portfolios, sales performance, pricing, dosage forms, distribution reach, and geographic presence. Revenue generated from antacid products was assessed through company annual reports, investor presentations, regulatory filings, product catalogs, industry publications, and trade databases. Product level revenues were aggregated to estimate market revenues across tablet, liquid, and other dosage form segments.
The market estimates were further validated through an assessment of consumption patterns, retail sales trends, pharmacy channel distribution, and product utilization across key regions. Market shares of leading manufacturers were evaluated based on brand presence, distribution networks, and product availability. Data triangulation was performed by comparing company revenues, product sales, and channel level demand trends to ensure consistency across market estimates. Forecast projections incorporated changes in consumer purchasing behavior, generic competition, e commerce penetration, product innovation, and expansion of digestive health product portfolios.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Consumer Purchasing and Usage Pattern Analysis
Assessment of consumer purchasing behavior, product utilization frequency, brand preferences, and dosage form adoption across antacid products and major regional markets.
Helps identify key demand drivers, product adoption trends, and high consumption consumer segments.
Distribution Channel and Retail Landscape Assessment
Analysis of antacid sales across retail pharmacies, online pharmacies, hospital pharmacies, supermarkets, and other distribution channels, including channel level penetration and purchasing trends.
Supports channel wise revenue allocation and identification of high growth distribution opportunities.
Product Innovation and Formulation Assessment
Assessment of tablet, liquid, chewable, sugar free, flavored, and other formulation trends, including product differentiation strategies adopted by manufacturers.
Identifies product categories with higher commercial potential and evolving consumer preferences.
Competitive Benchmarking and Brand Portfolio Analysis
Comparative evaluation of leading manufacturers, brand portfolios, pricing strategies, geographic presence, and market positioning across the antacid category.
Supports market share estimation, competitive intelligence, and strategic positioning analysis.
Regional Consumption and Market Penetration Assessment
Analysis of antacid consumption trends, product accessibility, pharmacy penetration, and brand adoption patterns across developed and emerging markets.
Identifies regional growth opportunities, underpenetrated markets, and expansion priorities for market participants.
Frequently Asked Questions About This Report
Based on type, the tablet segment led the market with the largest revenue share of 50.2% in 2025.
The global antacids market size was valued at USD 8.1 billion in 2025 and is estimated at USD 8.4 billion for 2026.
The global antacids market is expected to grow at a CAGR of 4.4% from 2026 to 2033, reaching USD 11.4 billion.
Key players include GSK plc.; Bayer AG; Boehringer Ingelheim International GmbH; Dr. Reddy’s Laboratories Ltd.; Sanofi; Reckitt; Sun Pharmaceutical Industries Ltd.; Takeda Pharmaceutical Company Limited; Pfizer Inc.; Procter & Gamble.
North America dominated with a 42.7% revenue share in 2025.
Based on end use, the retail pharmacy segment led the market with the largest revenue share of 72.2% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


