
- Home
- »
- Medical Devices
- »
-
Anti-infective Agents Market Size & Share Report, 2026-2033GVR Report cover

Anti-Infective Agents Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Antibacterial, Antiviral, Antifungal & Antiparasitic), By Route Of Administration (Oral, Parenteral), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$133.8BMarket Estimate, 2026
$132.9BMarket Forecast, 2033
$153.2BCAGR, 2026–2033
2.0%Anti-Infective Agents Market Summary
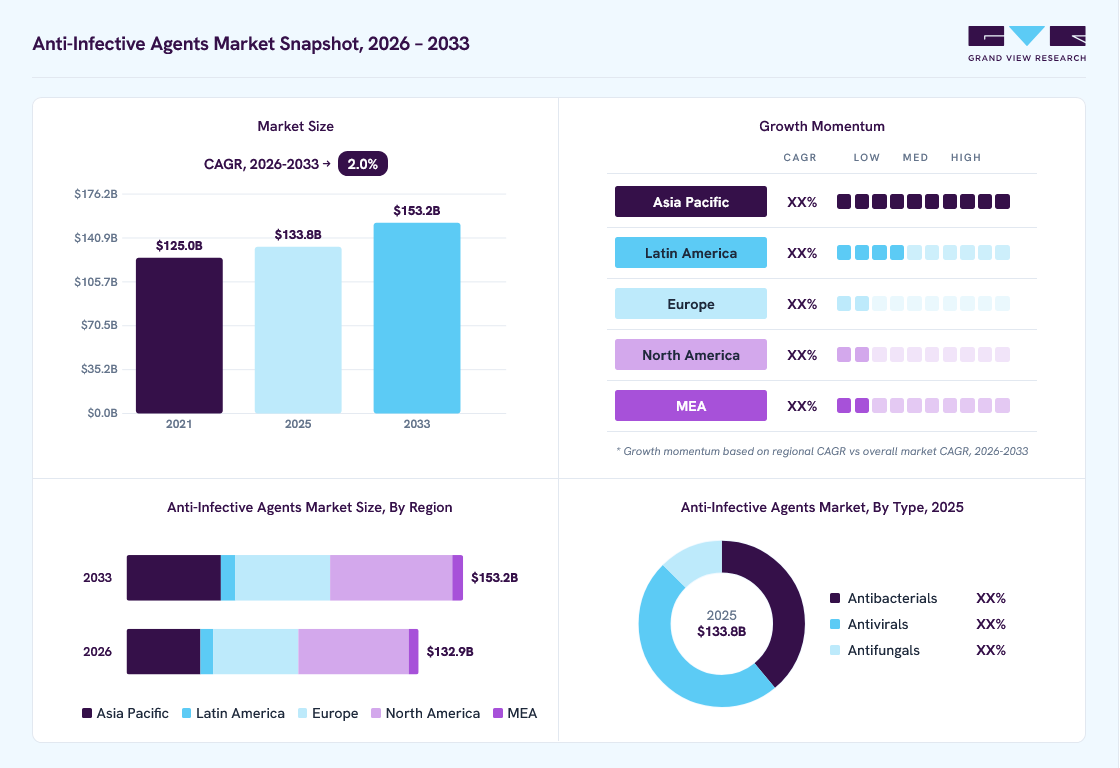
The global anti-infective agents market size was valued at USD 133.8 billion in 2025 and is projected to grow from USD 132.9 billion in 2026 to USD 153.2 billion by 2033, at a CAGR of 2.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.0% in 2025.The market growth can be attributed to the rising prevalence of infectious diseases, increased healthcare investments, and advancements in R&D.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Antivirals segment dominated the market, with a revenue share of 48.4% in 2025.
- By route of administration: Oral segment held the largest market share of 41.3% in 2025.
- By distribution channel: Hospital pharmacies held the largest revenue share of 48.5% in 2025.
Regional Highlights
- Largest regional market: North America (38.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 133.8 Billion
- Estimated market size in 2026: USD 132.9 Billion
- Projected market size by 2033: USD 153.2 Billion
- CAGR (2026-2033): 2.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market growth can be attributed to the rising prevalence of infectious diseases, increased healthcare investments, and advancements in R&D. Factors like the emergence of drug-resistant infections, government support, and expanding pharmaceutical industries are driving the demand for innovative treatments. Moreover, the growing focus on global health initiatives further fuels market expansion.The growing incidence of infectious diseases worldwide has led to a robust demand for effective anti-infective agents. Diseases caused by bacteria, viruses, and fungi continue to rise, fueled by factors such as global travel, urbanization, and climate change, which increase the spread of pathogens across regions. This global health challenge necessitates a proactive approach to developing anti-infective agents to combat new and re-emerging diseases. Notable examples include recent outbreaks of Ebola and Zika, reinforcing the need for quick-response treatments. The COVID-19 pandemic highlighted this urgency, underscoring the critical role of targeted antiviral therapies to contain and treat high-impact infections swiftly.
 To learn more about this report, Download Free Sample Report
Moreover, the demand for antiviral drugs surged in response to the pandemic as the healthcare sector aimed to curb the spread and impact of the novel coronavirus. Pharmaceutical companies and research institutions mobilized rapidly, leading to significant investments in the research, development, and repurposing of existing drugs to meet the global demand. This period saw accelerated timelines for drug approvals, with regulatory agencies streamlining processes to bring treatments to market faster than before. The urgency around COVID-19 also spurred innovations in the anti-infective space, driving the development of new therapeutic approaches, including mRNA-based therapies, which could serve as blueprints for tackling future infectious diseases. This rapid mobilization increased production and sales in the anti-infective agents market, underscoring their pivotal role in global public health.
Governments and global health organizations also play a key role in driving R&D for anti-infective drugs by offering pharmaceutical companies funding, grants, and incentives. Such support allows companies to mitigate the high costs and risks associated with R&D in this space, which has traditionally been challenging due to the complexity and time required to develop new anti-infective agents. For example, several initiatives were launched during the COVID-19 pandemic to fast-track the development of antiviral treatments and vaccines, demonstrating the positive impact of targeted R&D investment.
Public awareness campaigns have gained momentum, especially in light of recent outbreaks like COVID-19, Ebola, and Zika. These efforts highlight the need for preventive measures, including regular handwashing, vaccination programs, and proper use of medications. By increasing public understanding of these practices, health organizations are reducing the risk of spreading infections and ensuring that communities are better prepared to respond to outbreaks.
Market Dynamics
The anti-infective agents market continues to be supported by the ongoing burden of bacterial, viral, fungal, and parasitic infections across both developed and developing countries. Increasing antimicrobial resistance remains a key healthcare challenge, driving the need for effective treatment options and supporting investment in novel anti infective therapies. Demand remains consistent across hospital and outpatient settings, particularly for the management of respiratory infections, urinary tract infections, healthcare associated infections, and sexually transmitted diseases. Market growth is further supported by improvements in diagnostic capabilities that enable earlier pathogen identification and targeted treatment selection. In addition, expanding healthcare access and broader availability of essential medicines in emerging economies are contributing to treatment adoption. Government initiatives focused on infection control, surveillance, and antimicrobial resistance management also support the continued use of anti-infective therapies. Collectively, these factors sustain the importance of anti-infective agents within healthcare systems and support ongoing market expansion.
The increasing prevalence of antimicrobial resistance remains a major factor supporting growth in the anti-infective agents market. Resistance to commonly used antibiotics has reduced the effectiveness of several established therapies, creating a need for new treatment options capable of addressing multidrug resistant bacterial infections. Healthcare providers are placing greater emphasis on targeted anti-infective therapies that can improve clinical outcomes while limiting the spread of resistant organisms. Public health agencies and regulatory authorities are supporting the development of innovative anti-infective products through expedited review pathways and other regulatory initiatives. The burden of hospital acquired infections and complicated bacterial infections continues to create demand for therapies with activity against resistant pathogens. Pharmaceutical companies are expanding research efforts toward novel mechanisms of action and combination therapies designed to address unmet clinical needs. Recent product approvals reflect the industry's response to these challenges. For instance, in February 2025, AbbVie and Pfizer received U.S. FDA approval for EMBLAVEO (aztreonam and avibactam) for the treatment of adults with complicated intra-abdominal infections who had limited or no alternative treatment options. The approval was supported by a Phase III clinical study involving 422 patients. Complicated intra-abdominal infections affect approximately 3.5 million people annually in the United States, highlighting the continued need for new therapies that can address resistant Gram negative bacterial infections.
The widespread availability of generic anti-infective agents continues to limit growth opportunities for manufacturers of branded products. Many antibacterial, antiviral, and antifungal therapies have experienced patent expiry, resulting in pricing pressure across several treatment categories. Healthcare systems and payers increasingly favor lower cost generic alternatives, particularly for common infectious diseases where multiple treatment options are available. In addition, antimicrobial stewardship programs have become a standard component of healthcare practice in many countries. These programs promote the appropriate use of anti-infective therapies and encourage physicians to limit unnecessary prescribing in order to reduce the development of resistance. While these initiatives are important for public health, they can restrict prescription volumes for certain products. Developers of novel anti-infective agents also face challenges in achieving adequate commercial returns because newer antibiotics are often reserved for severe or resistant infections rather than routine use. Combined with lengthy development timelines and substantial clinical trial costs, these factors can reduce investment incentives and create barriers to broader market expansion.
Growing collaboration among pharmaceutical companies, biotechnology firms, research institutions, and public health organizations is creating opportunities across the anti-infective agents market. These partnerships help companies share development costs, access specialized expertise, and accelerate the advancement of therapies targeting resistant pathogens. Increasing attention toward antimicrobial resistance has also encouraged investment in novel anti infective approaches, including next generation antibiotics and treatments designed for difficult to treat infections. Supportive regulatory pathways and public funding initiatives are further contributing to product development activity. Recent approvals demonstrate the continued progress of innovation within the sector. For instance, in June 2026, GSK received U.S. FDA approval for Utebzi (tebipenem HBr), the first oral carbapenem antibiotic approved for complicated urinary tract infections, including pyelonephritis. The approval was based on a Phase III clinical trial involving 1,690 hospitalized adult patients. Complicated urinary tract infections affect more than 2.8 million people annually in the United States, and the availability of an oral carbapenem provides an alternative to intravenous treatment in eligible patients. Such advancements are expanding treatment options and supporting future opportunities in the anti-infective agents market.
Market Concentration & Characteristics
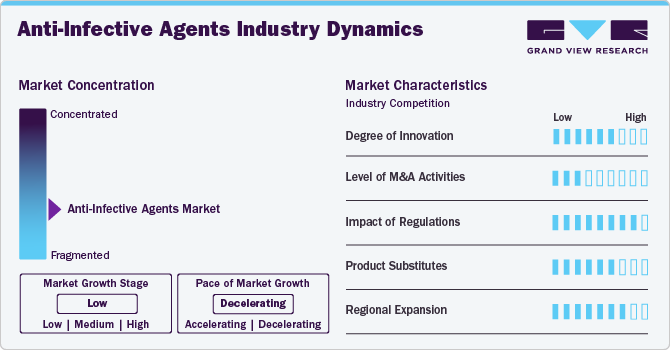
The market growth stage is low. The market is witnessing moderate innovation, focusing on developing targeted therapies and improving drug delivery systems, particularly in combating antimicrobial resistance. Novel drug classes like bacteriophage therapies and CRISPR-based anti-infectives are gaining traction but remain in the early stages of development.
The anti-infective market has seen an uptick in mergers and acquisitions, driven by larger pharmaceutical companies acquiring biotechs with promising pipelines. These activities are particularly concentrated in segments like antibiotics and antiviral drugs to expand portfolios and address resistance challenges.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks, such as FDA's GAIN Act and similar initiatives in Europe, are incentivizing R&D in antibiotics. However, stringent approval processes and post-market surveillance requirements for anti-infectives impact the speed of new product launches.
The emergence of biologics and non-pharmaceutical alternatives, such as probiotics, vaccines, and preventive measures, poses a potential threat to traditional anti-infective agents. However, these substitutes are often complementary rather than direct replacements.
Growth opportunities in emerging markets, especially in Asia-Pacific and Africa, are driving regional expansion. These regions are experiencing increased healthcare spending, improved infrastructure, and higher disease burden, making them lucrative markets for anti-infective agents.
Analyst Perspective
The anti-infective agents market remains a fundamental component of global healthcare, supported by the continued burden of bacterial, viral, and fungal infections and the growing challenge of antimicrobial resistance. The market is increasingly focused on the development of targeted therapies, novel antimicrobial mechanisms, and treatments for drug resistant pathogens. Gilead Sciences continues to maintain a strong position in antiviral therapies through its HIV and hepatitis portfolio, while Pfizer has strengthened its anti-infective presence through investments in antibacterial innovation and broad infectious disease capabilities. Similarly, Abbott, Bayer, AstraZeneca, and Boehringer Ingelheim are leveraging their global healthcare infrastructure and research expertise to support infectious disease management. Generic and specialty manufacturers such as Sandoz, Xellia Pharmaceuticals, B. Braun, and Mankind Pharma continue to play an important role in expanding access to essential anti-infective therapies, particularly in hospital and cost sensitive healthcare settings.
Type Insights
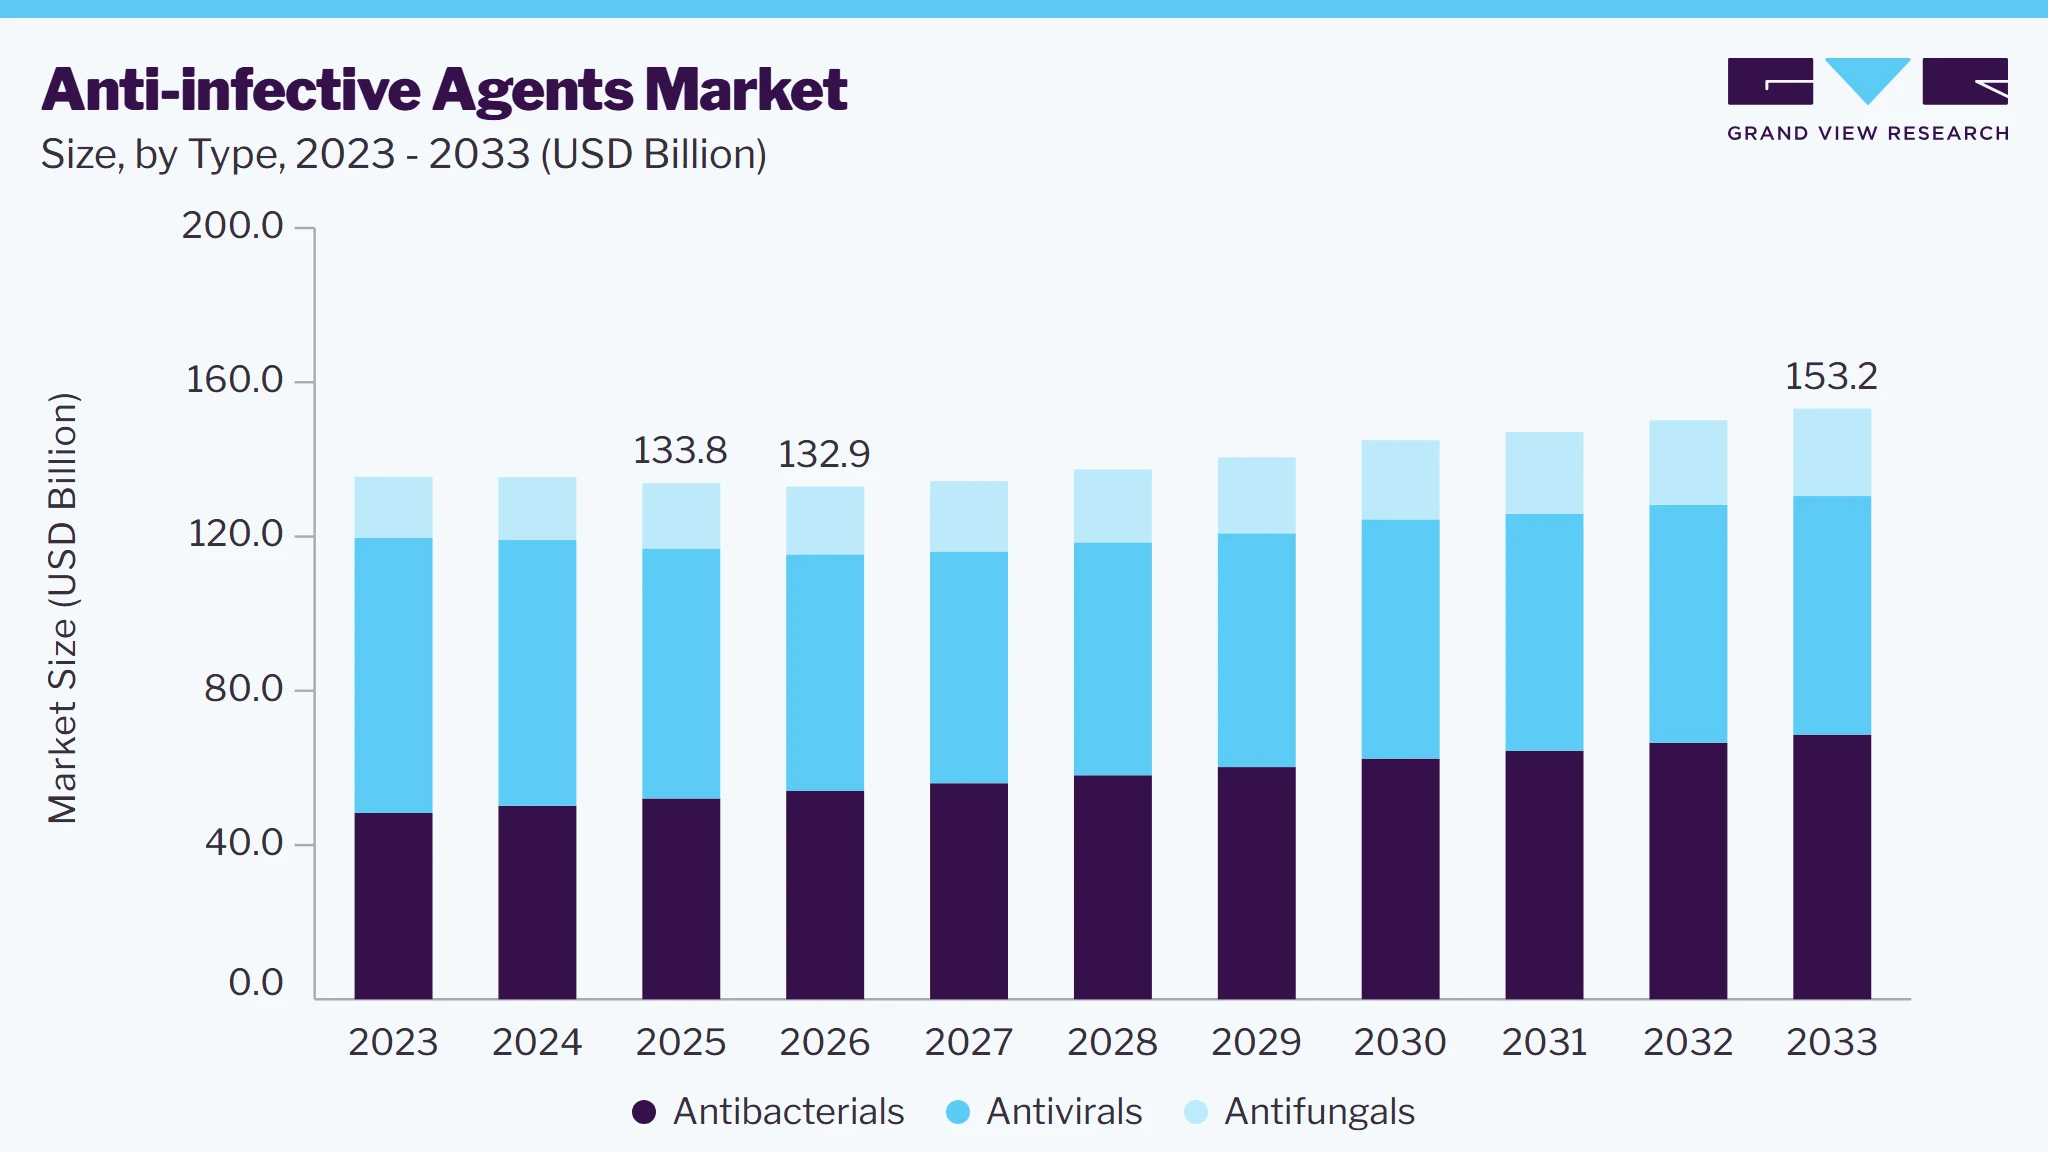
Based on type, the antivirals segment led the market with the largest revenue share of 48.4% in 2025. Antiviral drugs are crucial components of the anti-infective agents market, primarily used in the treatment and prevention of viral infections such as influenza, HIV, hepatitis, and more recently, COVID-19. The global increase in viral infections, particularly the emergence of new strains and pandemics, has driven significant growth in this segment. As a result, antiviral medications are seeing increased demand and innovation across various therapeutic areas.
The antifungal segment is expected to grow at the fastest CAGR during the forecast period.The antifungal market is witnessing substantial growth, driven by increasing prevalence of fungal infections and innovations in treatment options. In recent years, several new drug approvals have provided critical advancements, with drugs such as Fosmanogepix by Amplyx Pharmaceuticals and Vivjoa (oteseconazole) by Mycovia Pharmaceuticals offering promising results for treating fungal infections. These innovations, alongside increased funding for research and development, are expected to drive market growth. Public awareness campaigns, such as the CDC’s Fungal Disease Awareness Week, are also contributing to increased diagnosis rates, which are likely to spur the adoption of antifungal treatment.
Route of Administration Insights
Based on route of administration, the oral segment led the market with the largest revenue share of 41.3% in 2025, driven by new product developments and a robust pipeline. Oral antifungal medications are essential for treating systemic infections, such as throat and mouth yeast infections (e.g., thrush). These medications, including fluconazole (Diflucan) and terbinafine (Lamisil), are favored for their effectiveness in severe cases, as they target fungal cells throughout the body. However, they carry a higher risk of drug interactions compared to topical treatments. For instance, oral medications such as fluconazole can be effective with a single dose, while ibrexafungerp (Brexafemme) requires a twice-daily one-day regimen to address specific fungal strains.
 To learn more about this report, Download Free Sample Report
The parenteral segment is likely to grow at the fastest CAGR from 2025 to 2030. Intravenous anti-infectives are crucial for managing severe infections that require immediate systemic intervention, such as sepsis, meningitis, and severe bacterial and fungal infections. This route ensures 100% bioavailability, delivering the active ingredient directly into the bloodstream, critical for rapid therapeutic effects. Consequently, IV anti-infectives are extensively used in hospital settings, particularly in emergency departments and intensive care units, where quick and potent infection control can be life-saving. The growing incidence of hospital-acquired infections and the rise in invasive procedures and chronic conditions requiring hospitalizations support this market's growth.
Distribution Channel Insights
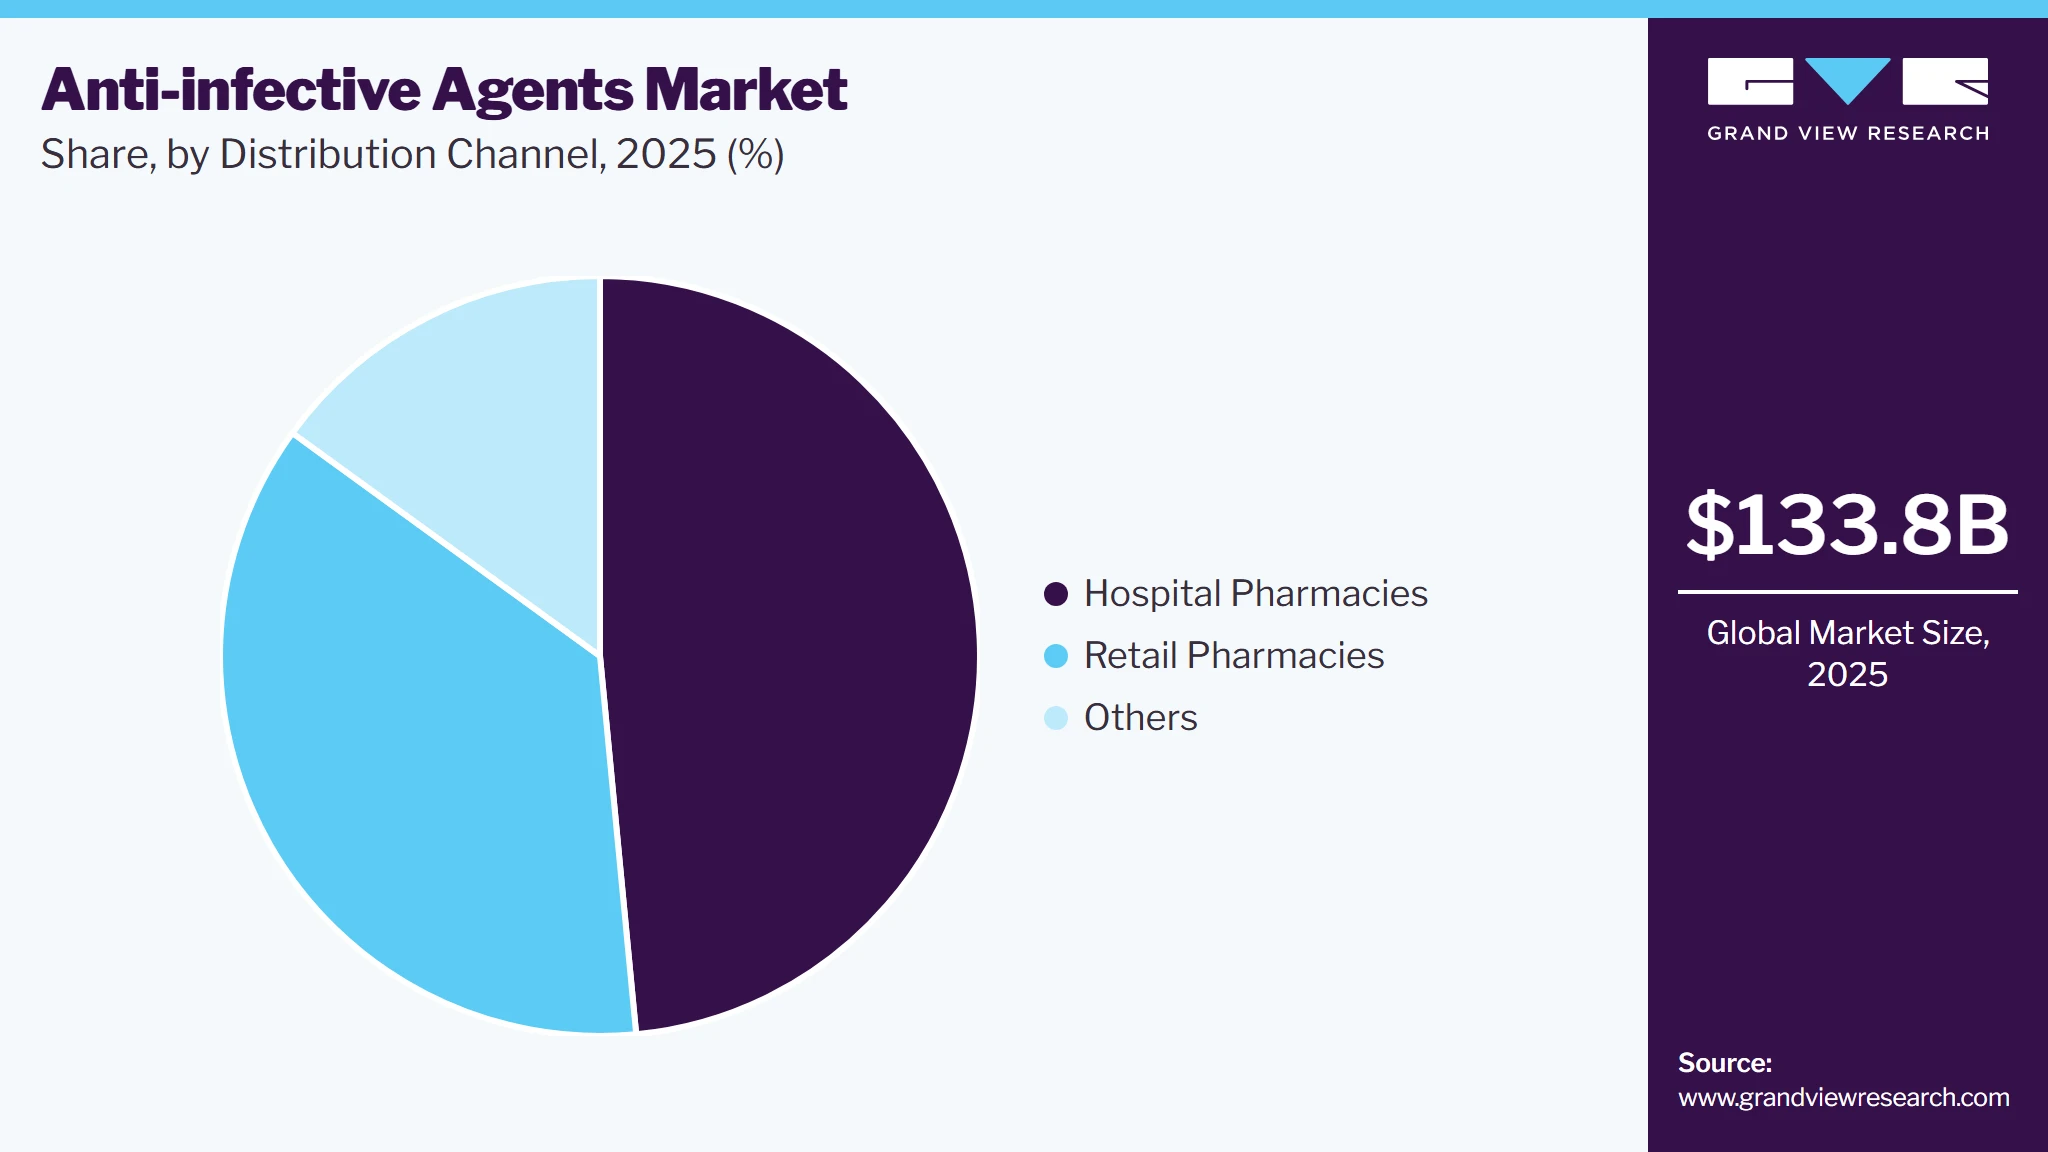
Based on distribution channel, the hospital pharmacies segment led the market with the largest revenue share of 48.5% in 2025, driven by the rising number of hospitalizations globally. Hospitals offer comprehensive patient care, prompt reimbursement, and favorable insurance policies, making them a preferred choice for patients. Hospital pharmacies are typically found in large medical institutions with advanced healthcare facilities, often including specialized departments such as infectious disease or intensive care units, where patients with severe infections receive treatment.
The other segment is expected to exhibit a fastest CAGR during the forecast period. The Others segment in the distribution channel for antiparasitic drugs, particularly online pharmacies, is growing rapidly. The convenience of purchasing medications online, especially for over-the-counter antifungal treatments, drives demand in regions seeking quick access to drugs. E-commerce platforms offer a variety of antifungal products, including generics, which may not be readily available in traditional retail pharmacies. This enhances consumer choice, offering cost-effective alternatives. The ability to order medications at any time and have them delivered directly to consumers' homes is particularly beneficial for those facing mobility issues, time constraints, or living in remote areas.
Regional Insights
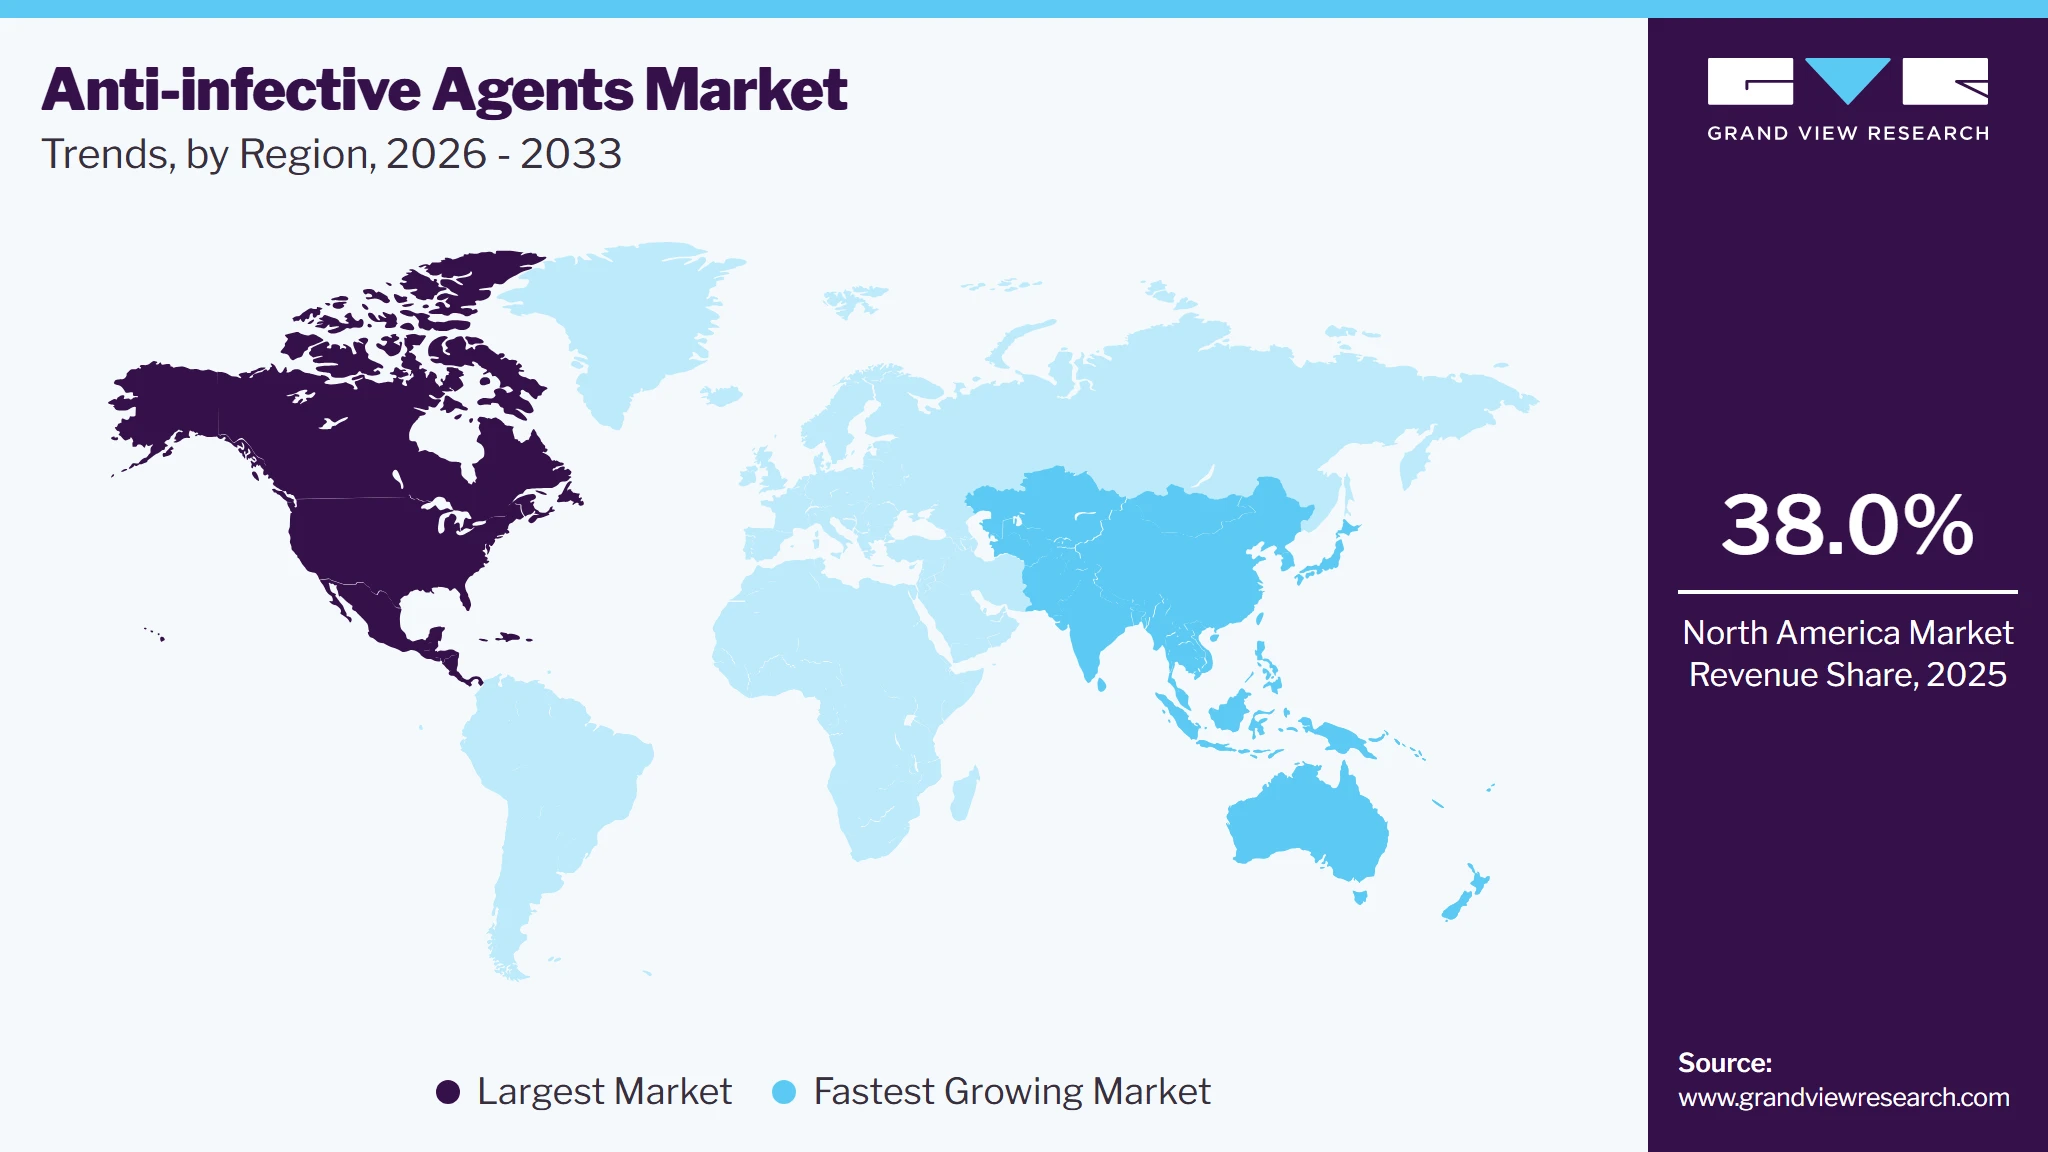
North America dominated the anti-infective agents market with the largest revenue share of 38.0% in 2025. Key drivers of regional market growth are advanced healthcare infrastructure and growing awareness among healthcare professionals and clinicians. In addition, strong government efforts to raise public health awareness, promote infection prevention, support vaccination programs, and encourage responsible antibiotic use, along with favorable reimbursement policies and high purchasing power for costly medications, are expected to further drive the market.
 To learn more about this report, Download Free Sample Report
U.S. Anti-Infective Agents Market Trends
The anti-infective agents market in the U.S. held the largest share in the North America region in 2025. The anti-infective agents market in the U.S. is expected to grow over the forecast period attributed to launch of projects and initiatives focused on improving the health of women is further anticipated to drive market. For instance, in April 2024, Cleveland Clinic announced the launch of new women’s health comprehensive health and resource center, with an aim to improve and address the unique health needs of women during their midlife period.
Europe Anti-Infective Agents Market Trends
Europe anti-infective agents market was identified as a lucrative region in this industry. The market is experiencing robust growth, driven by the rising prevalence of infectious diseases and increasing concerns about antimicrobial resistance. Government support plays a critical role in this expansion, with various initiatives to enhance the development and approval processes for new antibiotics. In April 2024, Pfizer Inc. announced that the European Commission (EC) had granted marketing authorization for EMBLAVEO to treat adult patients with complicated intra-abdominal infections, hospital-acquired pneumonia, including ventilator-associated pneumonia, and complicated urinary tract infections. Regulatory agencies are streamlining the approval pathway for innovative anti-infective agents to ensure timely access to effective treatments.
The Anti-Infective Agents market in UK is growing primarily due government's proactive action plan on antimicrobial resistance (AMR). In May 2024, UK health officials announced a new five-year national action plan on antimicrobial resistance (AMR) covering the period from 2024 to 2029. This action plan replaces the previous five-year strategy (2019 to 2024), during which the UK achieved significant reductions in the use of antimicrobials in both humans and food-producing animals. The earlier plan also led to the development of enhanced surveillance systems and the pilot implementation of a subscription-style antibiotic payment scheme within the National Health Service. This plan includes initiatives to enhance public awareness, improve surveillance of resistance patterns, and encourage better prescribing practices among healthcare professionals.
The Anti-Infective Agents market in Germany is growing steadily, supported by robust government funding and strategic collaborations to combat infectious diseases. The German government has allocated significant resources to advance research in antimicrobial resistance (AMR) and accelerate the development of new anti-infective therapies. In October 2022, the German Federal Ministry of Education and Research announced an additional USD 54.53 million in funding to support the essential work of the Global Antibiotic Research & Development Partnership (GARDP) for the next five years (2023-2027). This funding from Germany will enable GARDP to develop new treatments for drug-resistant infections and ensure they are accessible to everyone in need. Through initiatives such as the German Antibiotic Resistance Strategy (DART), the government promotes responsible antibiotic use, enhanced surveillance, and funding for innovation in anti-infectives.
The Anti-Infective Agents market in France is expanding, driven by collaborations between research institutions and companies to address infectious diseases and combat antimicrobial resistance. For instance, in March 2023, Nosopharm, a biotech firm focused on discovering antibiotics from unconventional sources, was selected for the French Tech Health20 program. This recognition supports the company’s innovative approach to tackling antimicrobial resistance, bolstering research and development efforts in the anti-infective space.
Asia Pacific Anti-Infective Agents Market Trends
The anti-infective agents industry in the Asia Pacific is anticipated to grow at the fastest CAGR from 2026 to 2033. The Asia-Pacific anti-infective agents market is experiencing robust growth driven by increasing infectious disease prevalence and significant investments in research and development by key market players. Companies are focusing on innovation to develop novel antibiotics and antiviral agents, addressing the urgent need for effective treatments against resistant pathogens. In July 2024, Eisai Co., Ltd. announced a license agreement with Sato Pharmaceutical Co., Ltd. for the development and commercialization rights of the antifungal agent fosravuconazole in the Asia/Oceania region. As part of this agreement, Eisai grants Sato Pharma exclusive rights to the intellectual property of fosravuconazole in the specified countries and regions.
The Anti-Infective Agents market in Japan is experiencing significant growth, driven by government funding and initiatives aimed at combating antimicrobial resistance (AMR) and supporting pharmaceutical innovation. In October 2023, the Government of Japan announced an increase in funding for the Global Antibiotic Research & Development Partnership (GARDP) to bolster its crucial efforts in developing new treatments for drug-resistant infections and ensuring these treatments are accessible to those in need.
Latin America Anti-Infective Agents Market Trends
The anti-infective agents market in Latin America is experiencing significant growth due to various factors, including the rising incidence of infectious diseases, increased healthcare investments, and ongoing research and development efforts. According to the World Bank, Haiti reported the highest incidence of tuberculosis (TB) in the region in 2021, with 159 new cases per 100,000 people. Peru followed closely with 130 new cases per 100,000 people. Notably, Brazil, Peru, and Mexico collectively account for over half of all TB cases in the Americas. This alarming trend highlights the urgent need for effective anti-infective treatments. In 2020, the highest incidence rates were recorded in Haiti, Peru, and Bolivia, with rates of 168, 116, and 105 cases per 100,000 population, respectively. These statistics underscore the critical demand for innovative solutions to combat infectious diseases and improve public health across the region.
The Anti-Infective Agents market in Brazil is experiencing significant growth, bolstered by the introduction of new drugs and substantial government support for research initiatives. In July 2024, GSK plc, in collaboration with Medicines for Malaria Venture (MMV), launched tafenoquine, the first single-dose medication designed to prevent the relapse of Plasmodium vivax malaria. Co-administered with chloroquine for radical cure, this breakthrough is a crucial step in Brazil’s efforts to eliminate malaria.
MEA Anti-Infective Agents Market Trends
The anti-infective agents market in the Middle East and Africa (MEA) is witnessing substantial growth, driven by an increasing prevalence of infectious diseases and heightened awareness of their impact on public health. Conditions such as tuberculosis, malaria, HIV/AIDS, and various bacterial infections are widespread in parts of the region, underscoring the urgent need for effective treatment solutions. The Middle East and North Africa (MENA) region is one of only two areas globally where HIV cases are increasing.
The Anti-Infective Agents market in Saudi Arabia is experiencing notable growth, driven by extensive government-led health initiatives and the expansion of the pharmaceutical sector. The Ministry of Health has implemented several key programs aimed at reducing infectious diseases, with a particular focus on tuberculosis (TB). Through its National Program to Combat Tuberculosis, the Ministry successfully lowered TB incidence by 21% in 2022 compared to 2015, underscoring the positive impact of these public health interventions.
Key Anti-Infective Agents Company Insights
Some of the key players operating in the market are undertaking various strategic initiatives to gain market share, such as mergers & acquisitions, technological collaborations, partnerships, and innovative product developments & launches. Some of the key major players are Pfizer Inc.; AbbVie.; Gilead Sciences, Inc.; Bristol-Myers Squibb Company; Merck & Co., Inc.; Sandoz International GmbH; and B. Braun SE. Some of the market players are adopting strategies such as acquisitions to strengthen their presence in other regional markets.
Key Anti-infective Agents Companies:
The following are the leading companies in the anti-infective agents market.
- Pfizer Inc.
- Merck & Co., Inc.
- Gilead Sciences, Inc.
- AbbVie
- Bristol-Myers Squibb
- AstraZeneca
- Sandoz International GmbH
- Bayer AG
- Xellia Pharmaceuticals
- Mankind Pharma
- B. Braun SE
- Boehringer Ingelheim
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Pfizer Inc., Abbott, Gilead Sciences, Inc., Bristol-Myers Squibb Company, Bayer AG, AstraZeneca, Boehringer Ingelheim International GmbH)
- Focus on expanding anti-infective portfolios through lifecycle management, strategic acquisitions, licensing agreements, and development of therapies targeting resistant and high burden infectious diseases. Strengthen market presence through broad geographic coverage, established hospital procurement channels, and collaborations with healthcare organizations and research institutions.
- Strong global brand recognition and extensive commercial infrastructure across developed and emerging markets. Diverse product portfolios spanning antibacterial, antiviral, and antifungal therapies supported by substantial research capabilities, regulatory expertise, and established relationships with healthcare providers and government agencies.
- High research and development costs associated with anti-infective drug discovery and regulatory compliance. Exposure to patent expirations, generic competition, pricing pressures, and antimicrobial stewardship initiatives that may limit product utilization and revenue growth.
Emerging and Specialized Players (Sandoz, B. Braun, Xellia Pharmaceuticals, Mankind Pharma)
- Focus on expanding access to anti-infective therapies through generic product development, competitive manufacturing cost, and targeted expansion in hospital and institutional care segments. Emphasize portfolio diversification across injectable antibiotics, essential anti-infective medicines, and region specific infectious disease treatment needs.
- Competitive pricing strategies and strong manufacturing capabilities support adoption in cost sensitive healthcare markets. Flexibility to address specific therapeutic niches and supply requirements within hospitals, retail pharmacy, and government procurement channels.
- Limited innovative product portfolios compared to multinational pharmaceutical companies. Dependence on generic products and institutional purchasing contracts may increase exposure to pricing pressure, procurement competition, and fluctuations in raw material and manufacturing costs.
Recent Developments
-
In August 2024, Shionogi & Co. announced that its New Drug Application (NDA) for cefiderocol, a novel siderophore cephalosporin antibiotic, has been accepted for review in China by the Center for Drug Evaluation. Cefiderocol targets gram-negative bacteria, including multidrug-resistant strains, and has demonstrated superior efficacy in a Phase III trial compared to imipenem/cilastatin. It is already approved in over 10 countries, including Japan, Europe, and the U.S., and is recognized on the WHO's Essential Medicines List. Shionogi aims to enhance global access to this treatment amid rising antimicrobial resistance (AMR) concerns.
-
IIn March 2024, Sandoz opened a new antibiotic production facility in Kundl, Austria, with a USD 53.81 million (EUR 50) investment. This expansion increases capacity by 20%, enabling the production of 240 million packages annually. The facility will produce an additional one billion penicillin tablets, doubling the output of key pediatric formulations. This move strengthens Sandoz's commitment to improving global access to antibiotics and addressing shortages, reinforcing its position as a key European supplier of penicillin. The facility is part of a broader EUR 200 million investment in the site. This expansion strengthens the global supply chain for penicillin, ensuring a steady and scalable supply to meet rising demand. By enhancing production and addressing market needs, the initiative helps improve access to affordable penicillin, fostering growth in the global market.
-
In January 2024, Basilea Pharmaceutica announced its acquisition of a preclinical antibiotics program from Spexis AG. The program targets multidrug-resistant Gram-negative bacteria using novel antibiotics that disrupt lipopolysaccharide transport, a key mechanism for bacterial survival. This novel approach has shown promising bactericidal activity in both in vitro and in vivo studies against resistant strains such as E. coli and K. pneumoniae. The strategic initiative contributes to penicillin market growth by fostering innovation in antibiotic treatments targeting drug-resistant bacteria, enhancing the industry's response to urgent bacterial threats. This approach strengthens the antibiotic portfolio, creating synergies that indirectly support penicillin demand and expand treatment options in infection management.
Anti-Infective Agents Market Report Scope
Report Attribute
Details
Market size in 2025
USD 133.8 billion
Estimated market size in 2026
USD 132.9 billion
Projected market size by 2033
USD 153.2 billion
Growth rate
CAGR of 2.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Pfizer Inc.; Abbott.; Gilead Sciences, Inc.; Bristol-Myers Squibb Company; Sandoz; B. Braun; Xellia Pharmaceuticals; Mankind Pharma; Bayer AG; AstraZeneca; Boehringer Ingelheim International GmbH.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Anti-Infective Agents Market Report Segmentation
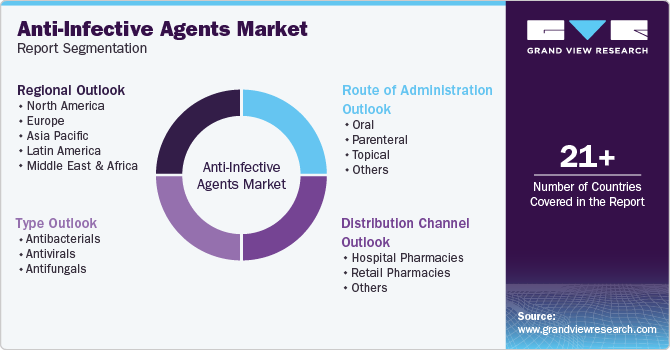
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global Anti-Infective Agents Market report on the basis of type, route of administration, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Antibacterials
-
Cephalosporins
-
Penicillin
-
Fluoroquinolones
-
Macrolides
-
Carbapenem
-
Others
-
-
Antivirals
-
Antifungals
-
Azoles
-
Echinocandins
-
Polyenes
-
Others
-
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Oral
-
Parenteral
-
Topical
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Others
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The anti-Infective agents market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each anti-Infective agents segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Antibacterials
Includes anti-infective agents indicated for the treatment, prevention, and management of bacterial infections. The segment covers therapies targeting Gram positive, Gram negative, and atypical bacterial pathogens across acute and chronic infectious disease indications and excludes antiviral and antifungal agents.
Antivirals
Includes anti-infective agents indicated for the treatment, prevention, and management of viral infections. The segment covers therapies used against human immunodeficiency virus, hepatitis viruses, influenza viruses, herpes viruses, coronaviruses, and other clinically relevant viral pathogens and excludes antibacterial and antifungal agents.
Antifungals
Includes anti-infective agents indicated for the treatment, prevention, and management of fungal infections. The segment covers therapies used against superficial, mucosal, systemic, and invasive fungal diseases and excludes antibacterial and antiviral agents.
Segment - Route of Administration
Revenue capture definition
Oral
Includes anti infective agents administered orally for the systemic treatment, prevention, and management of bacterial, viral, and fungal infections. This segment excludes injectable, topical, and other alternative route formulations.
Parenteral
Includes anti infective agents administered through intravenous, intramuscular, or subcutaneous routes for systemic management of infectious diseases. This segment excludes oral, topical, and other non injectable formulations.
Topical
Includes anti infective agents administered directly to the affected site for localized treatment and prevention of infections involving the skin, eyes, ears, and mucosal surfaces. This segment excludes systemic oral and parenteral therapies.
Others
Includes anti infective agents administered through routes not classified as oral, parenteral, or topical, including inhalational, intranasal, rectal, and vaginal formulations.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Includes anti infective agents supplied through hospital pharmacy networks for inpatient care and hospital administered treatment of infectious diseases.
Retail Pharmacies
Includes anti infective agents dispensed through community, chain, and independent pharmacies for outpatient treatment of infectious diseases.
Others
Includes anti infective agents distributed through channels outside hospital and retail pharmacies, including online pharmacies, specialty pharmacies, mail order services, and government procurement programs.
Estimation Model
 To learn more about this report, Download Free Sample Report
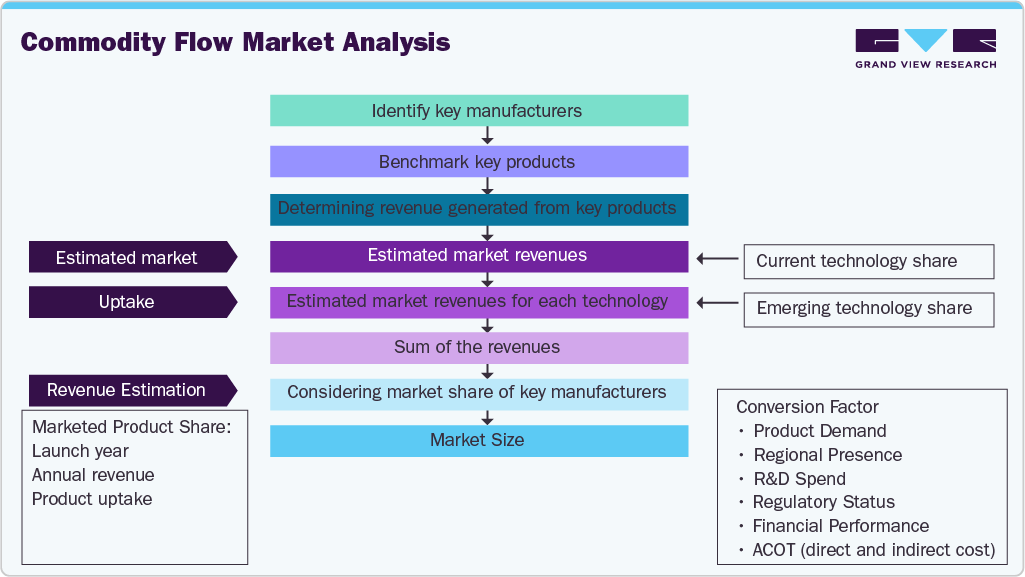
The anti-infective agents’ market was estimated using a commodity flow and revenue based market analysis approach. The methodology began with the identification of key manufacturers and commercially available anti-infective therapies used for the treatment and prevention of bacterial, viral, and fungal infections. Major product categories, including antibacterials, antivirals, and antifungals, were benchmarked based on annual sales, prescription volumes, treatment duration, pricing, distribution channels, and geographic presence. Revenue generated from leading branded and generic anti-infective products was assessed using company annual reports, investor presentations, regulatory filings, healthcare databases, hospital procurement records, pharmacy sales data, and industry publications. Product level revenues were aggregated to estimate market revenues across therapeutic classes, routes of administration, and distribution channels.
The market estimates were further validated through an assessment of the infectious disease burden associated with respiratory tract infections, urinary tract infections, skin and soft tissue infections, HIV, viral hepatitis, influenza, invasive fungal infections, and other infectious diseases. Treatment utilization rates, prescribing patterns, hospitalization trends, and anti infective consumption across hospitals, retail pharmacies, specialty pharmacies, and other healthcare facilities were analyzed to determine demand side dynamics. Data triangulation was performed by comparing manufacturer revenues, product sales volumes, prescription trends, and treatment rates to ensure consistency across market estimates. Forecast projections incorporated trends in infectious disease incidence, antimicrobial resistance, healthcare expenditure, generic penetration, product approvals, and the development of novel anti-infective therapies.
Customization Table
Client Request
Customization Delivered
Value Adds
Anti Infective Competitive Landscape & Portfolio Assessment
Conducted a targeted assessment of the global anti-infective agents market, evaluating approved products, late-stage pipeline assets, therapeutic categories, mechanisms of action, resistance-focused programs, clinical development progress, and competitive positioning. The study analyzed key participants including Pfizer, Gilead Sciences, Abbott, AstraZeneca, Bayer, Bristol Myers Squibb, Boehringer Ingelheim, Sanofi, Zella Pharmaceuticals, B. Braun, and Mankind Pharma, along with emerging developers advancing novel antibacterial, antiviral, and antifungal therapies.
Helped the client identify high-growth therapeutic segments, evaluate competitive threats, benchmark portfolio differentiation, and prioritize licensing, acquisition, and partnership opportunities within the anti-infective agents market.
Anti Infective Product & Technology Benchmarking Study
Delivered a comprehensive benchmarking analysis of anti-infective products and therapeutic technologies, focusing on antibacterial, antiviral, and antifungal portfolios, resistance targeting approaches, treatment efficacy, safety profiles, route of administration, and clinical performance. The assessment compared established therapies with next-generation anti-infective candidates and evaluated pipelines in terms of maturity, regulatory positioning, and product differentiation across leading manufacturers.
Enabled the client to assess product competitiveness, identify innovation opportunities, benchmark therapeutic performance, and prioritize investment in novel anti-infective development programs and differentiated treatment platforms.
Anti Infective Manufacturing & Supply Chain Feasibility Assessment
Conducted a strategic assessment of the anti-infective manufacturing ecosystem, evaluating active pharmaceutical ingredient production capabilities, formulation technologies, sterile manufacturing infrastructure, regulatory requirements, supply chain resilience, and outsourcing opportunities. The study analyzed manufacturing organizations, production networks, regional supply capabilities, and distribution networks supporting commercial-scale production of anti-infective therapies across global markets.
Supported strategic manufacturing planning by identifying qualified manufacturing partners, assessing supply chain risks, evaluating manufacturing scalability, and recommending actions for key manufacturing scalability and commercial readiness across key geographic markets.
Frequently Asked Questions About This Report
The global Anti-Infective agents market size was valued at USD 133.8 billion in 2025 and is estimated at USD 132.9 billion in 2026.
The global anti-Infective agents market is expected to grow at a CAGR of 2.0% from 2026 to 2033, reaching USD 153.2 billion by 2033.
Key factors include emergence of drug-resistant infections, government support, and expanding pharmaceutical industries are driving the demand for innovative treatments. Moreover, the growing focus on global health initiatives further fuels market expansion.
Some key players operating in the global anti-infective agents market include GlaxoSmithKline plc.; Pfizer Inc.; Bayer AG; Sanofi; Merck & Co., Inc.; Bristol-Myers Squibb Company; Abbott; Novartis AG; Johnson & Johnson Services Inc.; Gilead Sciences, Inc.; and Astellas Pharma Inc.
North America dominated with a 38.0% revenue share in 2025.
Antivirals segment dominated the market, with a revenue share of 48.4% in 2025.
Oral segment held the largest market share of 41.3% in 2025 while parenteral segment is expected to be the fastest-growing market.
Hospital pharmacies held the largest revenue share of 48.5% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


