
- Home
- »
- Specialty Polymers
- »
-
Anti-glare Glass Market Size And Share Report, 2026-2033GVR Report cover

Anti Glare Glass Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Coated, Etched), By Application (Consumer Electronics, Automotive Display, Architectural Glass, Industrial Displays), By Region, And Segment Forecasts
Market Size, 2025
$3.1BMarket Estimate, 2026
$3.3BMarket Forecast, 2033
$4.7BCAGR, 2026–2033
5.2%Anti-glare Glass Market Summary
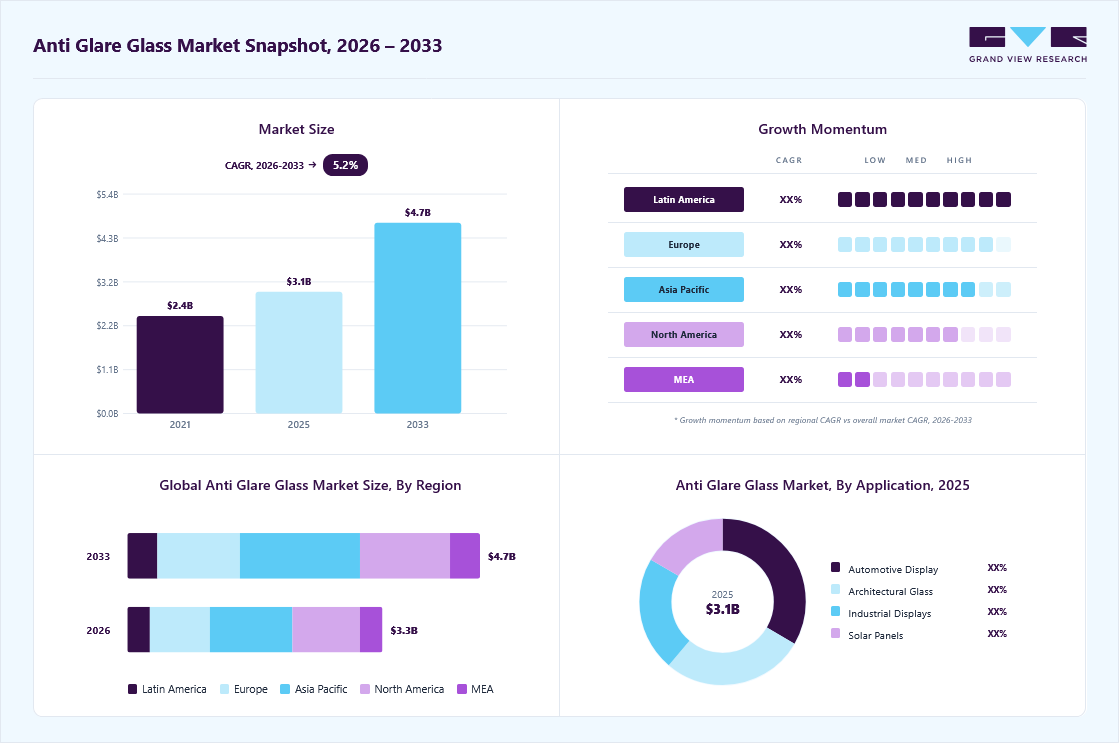
The global anti glare glass market size was valued at USD 3.1 billion in 2025 and is projected to grow from USD 3.3 billion in 2026 to USD 4.7 billion by 2033, at a CAGR of 5.2% from 2026 to 2033. The Asia Pacific held the largest share of 33.4% of the global market in 2025. This growth is largely driven by rising demand from consumer electronics, automotive displays, and solar photovoltaic applications, where improved visibility and light transmission are critical.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Etched anti-glare glass segment held the largest share of 57.8% in 2025.
- By applications: Automotive displays segment is expected to grow at the fastest CAGR of 5.5% from 2026 to 2033.
Regional Highlights
- Largest regional market: Asia Pacific (33.4% revenue share, 2025)
- Fastest-growing regional market: Latin America (highest CAGR, 2026-2033)
- By country: The China led the Asia Pacific market in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.1 Billion
- Estimated market size in 2026: USD 3.3 Billion
- Projected market size by 2033: USD 4.7 Billion
- CAGR (2026-2033): 5.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Increasing adoption of advanced coated glass in smart devices and energy-efficient architectural solutions is further supporting steady market expansion. The anti-glare glass industry is strongly aligned with global decarbonization and energy-efficiency goals, particularly through its use in solar energy systems and green buildings. For instance, in July 2025, the European Commission under its “REPowerEU” initiative emphasized accelerating solar deployment across member states, where high-efficiency solar glass with anti-reflective coatings is a key enabling material for improving module performance and energy yield. Similarly, in March 2025, the U.S. Department of Energy highlighted advanced solar materials in its Solar Energy Technologies Office roadmap, focusing on optical coatings to improve panel efficiency and reduce lifecycle emissions, reinforcing the role of anti-glare glass in sustainable energy systems.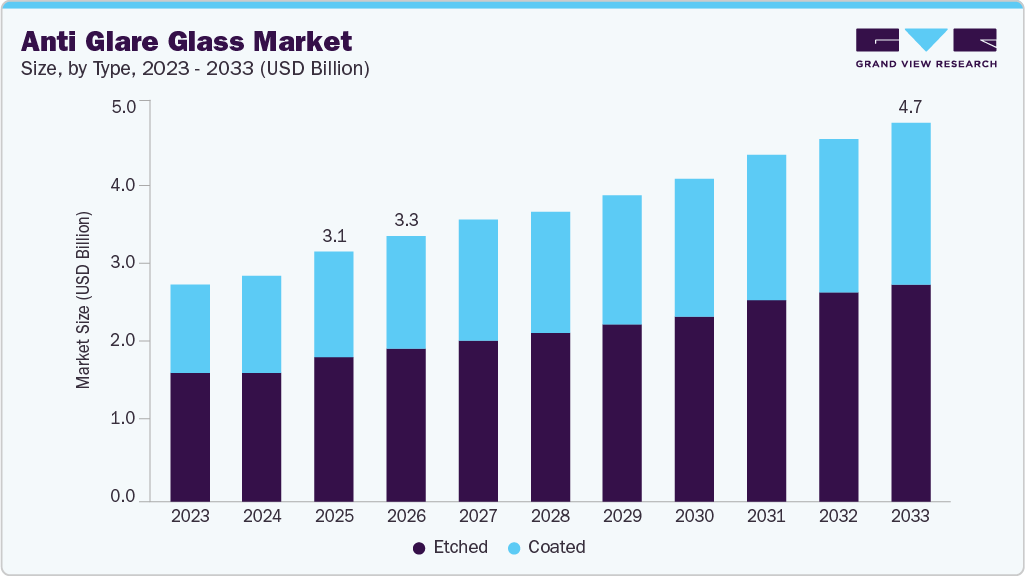 To learn more about this report, Download Free Sample Report
Technological advancements in anti-glare glass are being driven by innovations in nano-engineered coatings, magnetron sputtering, and multilayer optical film deposition, enabling ultra-low reflectance, higher durability, and improved scratch resistance. These technologies are increasingly being integrated into high-performance displays, automotive HUDs, and AR/VR devices. For example, in April 2025, Japan’s Ministry of Economy, Trade and Industry (METI) supported next-generation display materials research under its Green Innovation Fund, focusing on advanced optical coatings to enhance visibility and energy efficiency in electronic displays. In another instance, in February 2026, South Korea’s Ministry of Trade, Industry and Energy (MOTIE) highlighted advancements in semiconductor and display material ecosystems, including precision-coated glass for OLED and micro-LED applications, reflecting strong government-backed innovation momentum in the Asia-Pacific region.
Drivers, Opportunities & Restraints
The anti glare glass industry is primarily driven by rapid growth in consumer electronics manufacturing, automotive digitalization, and solar energy deployment, where high visibility and reduced surface reflection are essential for performance and safety. Increasing adoption of advanced display systems in vehicles and public infrastructure is further supporting demand. For instance, in February 2025, India’s Ministry of Heavy Industries reported continued strong growth in automobile production under the PLI scheme, supporting increased integration of digital dashboards and infotainment systems that rely on anti-glare display glass for improved visibility and safety.
Significant opportunities are emerging from government-led renewable energy expansion, smart city development, and digital infrastructure programs that require high-performance coated glass solutions. Solar energy expansion is a key driver for anti-reflective glass demand, especially in utility-scale installations. For example, in January 2026, India’s Ministry of New and Renewable Energy (MNRE) highlighted ongoing large-scale solar capacity additions under the National Solar Mission, where anti-reflective coated glass is widely used in photovoltaic modules to improve energy conversion efficiency by reducing reflection losses.
Market growth is restrained by high production costs associated with advanced coating technologies, energy-intensive manufacturing processes, and dependence on specialized raw materials and vacuum deposition equipment. In addition, performance degradation under extreme environmental conditions limits long-term application in some regions. For instance, in March 2025, the European Commission’s industrial materials sustainability review noted challenges in scaling advanced coated glass technologies due to high energy consumption in manufacturing and the need to improve durability standards for long-term architectural applications, which continues to affect wider adoption in cost-sensitive markets.
Type Insights
The Etched anti-glare glass segment led the market with the largest revenue share of 57.8% in 2025, due to its cost-effectiveness, durability, and widespread adoption across architectural and display applications. The mechanical or chemical etching process provides a permanent matte surface that reduces reflection without requiring additional coating, making it highly suitable for large-scale industrial use such as building facades, signage, and basic electronic displays. Its strong penetration in price-sensitive markets and ease of manufacturing have further strengthened its dominant position in the global market.
The coated anti-glare glass segment is expected to record at the fastest CAGR during the forecast period, driven by rising demand for high-performance applications requiring superior optical clarity and advanced functionality. Multi-layer anti-reflective coatings produced by vacuum deposition and nanotechnology enable significantly higher light transmission than etched alternatives, making them ideal for smartphones, AR/VR devices, automotive HUDs, and solar panels. Continuous technological advancements and increasing adoption in premium electronics and next-generation display systems are accelerating growth in this segment.
Application Insights
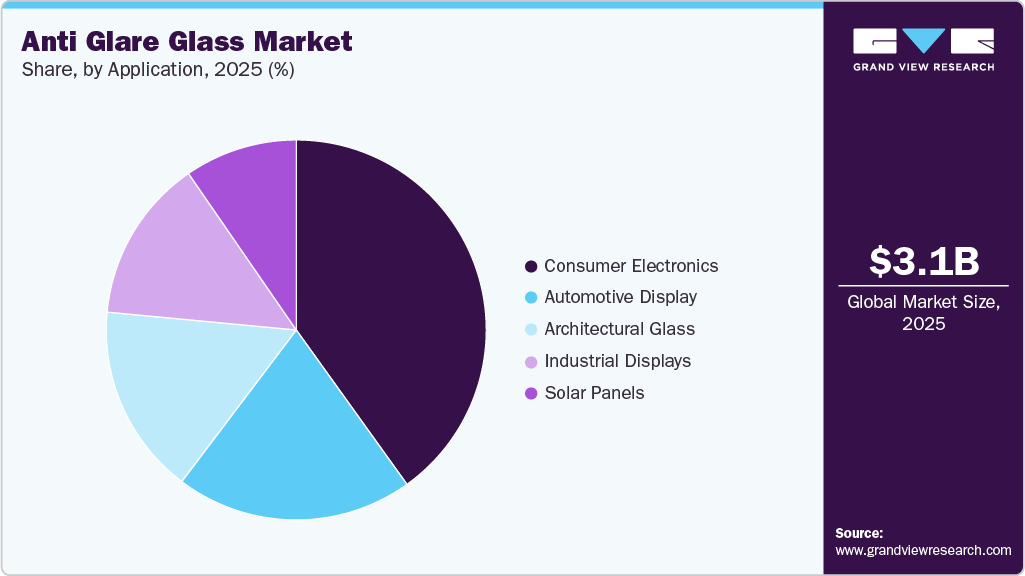
The consumer electronics segment led the market with the largest revenue share of 40.1% in 2025, supported by massive global production and consumption of smartphones, tablets, laptops, and televisions. The increasing need for improved screen visibility under varying lighting conditions and reduced eye strain has made anti-glare coatings a standard feature in modern display devices. Strong manufacturing ecosystems in the Asia Pacific, coupled with continuous product upgrades and high replacement cycles, continue to reinforce the dominance of this segment.
 To learn more about this report, Download Free Sample Report
The automotive display segment is expected to register at the fastest CAGR during the forecast period, driven by the rapid digitalization of vehicle interiors and the increasing integration of advanced infotainment systems, digital dashboards, and head-up displays (HUDs). As vehicles evolve toward electric and autonomous models, demand for high-clarity, anti-reflective display glass is rising to ensure safety and readability under direct sunlight. Growing investments in smart mobility and connected car technologies are further accelerating the adoption of anti-glare solutions in the automotive sector.
Regional Insights
The North America anti glare glass market is driven by strong demand from advanced consumer electronics, automotive display systems, and premium architectural applications. High adoption of AR/AG-coated glass in smartphones, laptops, and infotainment systems, along with steady investments in smart buildings and solar energy projects, continues to support market growth across the region. The region also benefits from strong R&D capabilities and early adoption of next-generation display technologies.
U.S. Anti Glare Glass Market Trends
The anti-glare glass market in the U.S. accounted for the largest market revenue share in North America in 2025, supported by the strong presence of leading technology companies and display manufacturers. The rising use of anti-glare coatings in high-end electronics, aerospace displays, and smart automotive systems, along with the increasing focus on energy-efficient architectural glass, is driving sustained demand. Continuous innovation in consumer electronics and defense-grade optical systems further strengthens market expansion.
Asia Pacific Anti Glare Glass Market Trends
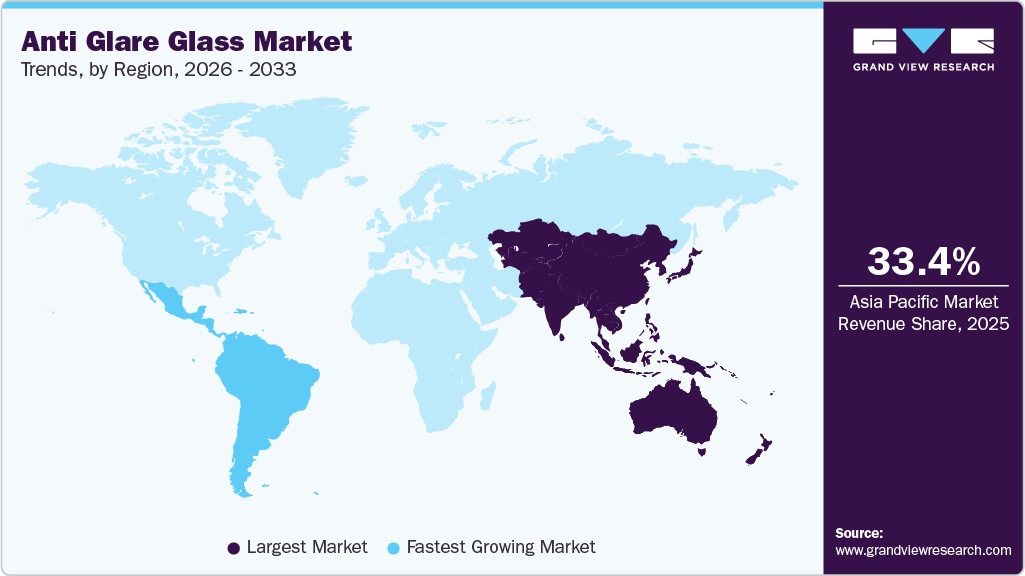
Asia Pacific dominates the global anti-glare glass market with the largest revenue share of 33.4% in 2025, due to large-scale electronics manufacturing, rapid urbanization, and expanding solar energy installations. Countries like China, Japan, South Korea, and India are key contributors, with strong demand from the display glass, photovoltaic modules, and automotive industries. Cost-efficient production capabilities and export-oriented manufacturing hubs further enhance regional dominance.
 To learn more about this report, Download Free Sample Report
The China anti glare glass market is driven by its large-scale electronics manufacturing ecosystem, extensive solar photovoltaic installations, and strong flat glass production capacity. The country is home to major players in display glass, architectural glass, and solar cover glass, enabling high-volume production of anti-reflective and anti-glare coated products at competitive costs. Rapid urbanization, continuous expansion of smart device manufacturing, and government support for renewable energy further strengthen China’s leadership position in the regional market.
Europe Anti Glare Glass Market Trends
The anti-glare glass market in Europe is supported by strict energy efficiency regulations and high adoption in automotive, construction, and optical applications. Demand is further strengthened by advanced architectural projects, museums, and luxury retail infrastructure requiring high-clarity, low-reflection glass solutions. Sustainability mandates across EU countries are accelerating the shift toward energy-efficient coated glass products.
Latin America Anti Glare Glass Market Trends
The anti-glare glass market in Latin America is anticipated to grow at the fastest CAGR during the forecast period, driven by increasing adoption of consumer electronics and growing investments in commercial construction projects. Rising awareness of energy-efficient building materials and solar energy deployment is also supporting moderate demand for anti-glare glass in the region. Infrastructure modernization in urban centers is expected to further stimulate future growth.
Middle East & Africa Anti Glare Glass Market Trends
The anti-glare glass market in the Middle East & Africa is witnessing steady growth due to increasing infrastructure development, smart city projects, and rising adoption of high-performance architectural glass. Demand is particularly driven by commercial buildings, luxury developments, and solar energy projects in Gulf countries. Extreme climatic conditions in the region also underscore the need for glare-reducing, heat-resistant glass solutions.
Key Anti Glare Glass Company Insights
Some of the key players operating in the market include Corning Incorporated, AGC Inc., and others.
-
Corning Incorporated, founded in 1851, is a leading global materials science company with a strong presence across North America, Europe, and Asia, specializing in advanced glass and ceramic-based technologies, including anti-reflective and specialty display glass solutions. The company operates through multiple business segments such as Display Technologies, Optical Communications, Environmental Technologies, Specialty Materials, and Life Sciences, supplying high-performance glass substrates and coatings for electronics, automotive displays, solar applications, and telecommunications. Its portfolio includes anti-glare and anti-reflective cover glass, Gorilla Glass, precision optical components, and engineered glass solutions designed for high durability, optical clarity, and scratch resistance.
-
AGC Inc., founded in 1907, is a major global glass and chemical company with a strong presence across Japan, Europe, and Asia, offering a broad range of glass and material solutions, including anti-reflective and coated glass products. The company operates through segments such as Glass, Electronics, Chemicals, and Ceramics, supplying architectural glass, automotive glazing, display glass substrates, and specialty coated glass for solar and electronic applications. Its portfolio includes anti-glare and anti-reflective glass, solar control glass, automotive windshield glass, and high-performance display substrates engineered for enhanced light transmission and reduced reflection.
-
Saint-Gobain, founded in 1665, is one of the world’s oldest and largest building materials companies with a strong global presence across Europe, North America, and Asia, providing high-performance glass and material solutions, including anti-reflective and anti-glare glass products. The company operates through multiple divisions, including Innovative Materials, Construction Products, and High-Performance Solutions, supplying architectural glass, specialty-coated glass, and industrial glass for construction, automotive, solar, and interior applications.
Key Anti Glare Glass Companies:
The following key companies have been profiled for this study on the anti glare glass market.
- AGC Inc.
- Abrisa Technologies
- AVIC Sanxin Co., Ltd.
- Corning Incorporated
- Flat Glass Group Co., Ltd.
- Guardian Industries
- Nippon Sheet Glass
- Saint-Gobain
- Schott AG
- Xinyi Glass Holdings
Recent Developments
-
In February 2026, Corning Incorporated announced the expansion of its advanced glass finishing facility in the United States to increase production capacity for anti-reflective and anti-glare display glass used in smartphones, automotive displays, and augmented reality devices. The expansion focuses on next-generation nano-textured coatings designed to reduce surface reflectance while improving durability and optical clarity for high-brightness environments, supporting rising global demand from electronics OEMs.
-
In January 2026, AGC Inc. introduced an upgraded version of its anti-reflective coated glass technology under its architectural and solar glass portfolio in Japan, targeting improved light transmission efficiency for photovoltaic modules and reduced glare in high-rise building façades. The development integrates advanced multilayer coating technology to enhance energy efficiency in solar applications while meeting stricter urban building illumination and sustainability standards.
-
In March 2026, Schott AG announced progress in scaling its AMIRAN anti-reflective glass production line in Europe, designed for premium architectural and display applications, including museums, luxury retail spaces, and high-end electronics. The upgraded production process incorporates improved magnetron sputtering technology to achieve ultra-low reflectance, enhancing visual transparency and supporting the growing demand for high-clarity glass in commercial infrastructure and specialty optics markets.
Anti Glare Glass Market Report Scope
Report Attribute
Details
Market definition
The market size represents the revenue generated from the sale of both coated and etched anti glare glass across various end-use industries in a given year.
Market size in 2025
USD 3.1 billion
Estimated market size in 2026
USD 3.3 billion
Projected market size by 2033
USD 4.7 billion
Growth rate
CAGR of 5.2% from 2025 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative Units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, competitive landscape, growth factors, and trends
Segments covered
Type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; China; India; Japan; South Korea; Brazil
Key companies profiled
AGC Inc.; Abrisa Technologies; AVIC Sanxin Co., Ltd.; Corning Incorporated; Flat Glass Group Co., Ltd.; Guardian Industries; Nippon Sheet Glass (NSG Group); Saint-Gobain; Schott AG; Xinyi Glass Holdings
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Anti Glare Glass Market Report Segmentation
This report forecasts global, country, and regional revenue growth and analyzes the latest trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global anti glare glass market report based on the type, application, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Coated
-
Etched
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Consumer Electronics
-
Automotive Display
-
Architectural Glass
-
Industrial Displays
-
Solar Panels
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Frequently Asked Questions About This Report
Asia Pacific dominated with a 33.4% revenue share in 2025.
Latin America is the fastest-growing region over the forecast period.
The consumer electronics segment led with a 40.1% revenue share in 2025, while automotive display is the fastest-growing applications.
The global anti glare glass market size was valued at USD 3.1 billion in 2025 and is estimated at USD 3.3 billion for 2026.
The global anti-glare glass market is expected to grow at a CAGR of 5.2% from 2026 to 2033, reaching USD 4.7 billion by 2033.
In terms of type, etched anti-glare glass held a 57.8% revenue share in 2025, owing to its strong adoption in large-scale architectural and display applications, supported by its durability, affordability, and consistent performance across varied end-use environments.
Key players include AGC Inc.; Abrisa Technologies; AVIC Sanxin Co., Ltd.; Corning Incorporated; Flat Glass Group Co., Ltd.; Guardian Industries; Nippon Sheet Glass (NSG Group); Saint-Gobain; Schott AG; Xinyi Glass Holdings.
The anti-glare glass market is primarily driven by rising demand from consumer electronics such as smartphones, tablets, laptops, and display panels that require high visibility and reduced reflection.
About the Author(s)
Specialty Polymers Research Team
Specialty & Chemicals · Specialty PolymersThis report was authored by the specialty polymers research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the specialty polymers segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


