
- Home
- »
- Medical Devices
- »
-
Arterial Cannula Market Size, Share & Trends Report, 2033GVR Report cover

Arterial Cannula Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (ECMO, Cardiopulmonary Bypass Surgery), By Size (20-22 Fr, 35-36 Fr), By End-use (Hospitals, Ambulatory Surgical Centers), By Region, And Segment Forecasts
Market Size, 2025
$23.3MMarket Estimate, 2026
$24.9MMarket Forecast, 2033
$40.9MCAGR, 2026–2033
7.3%Arterial Cannula Market Size & Trends
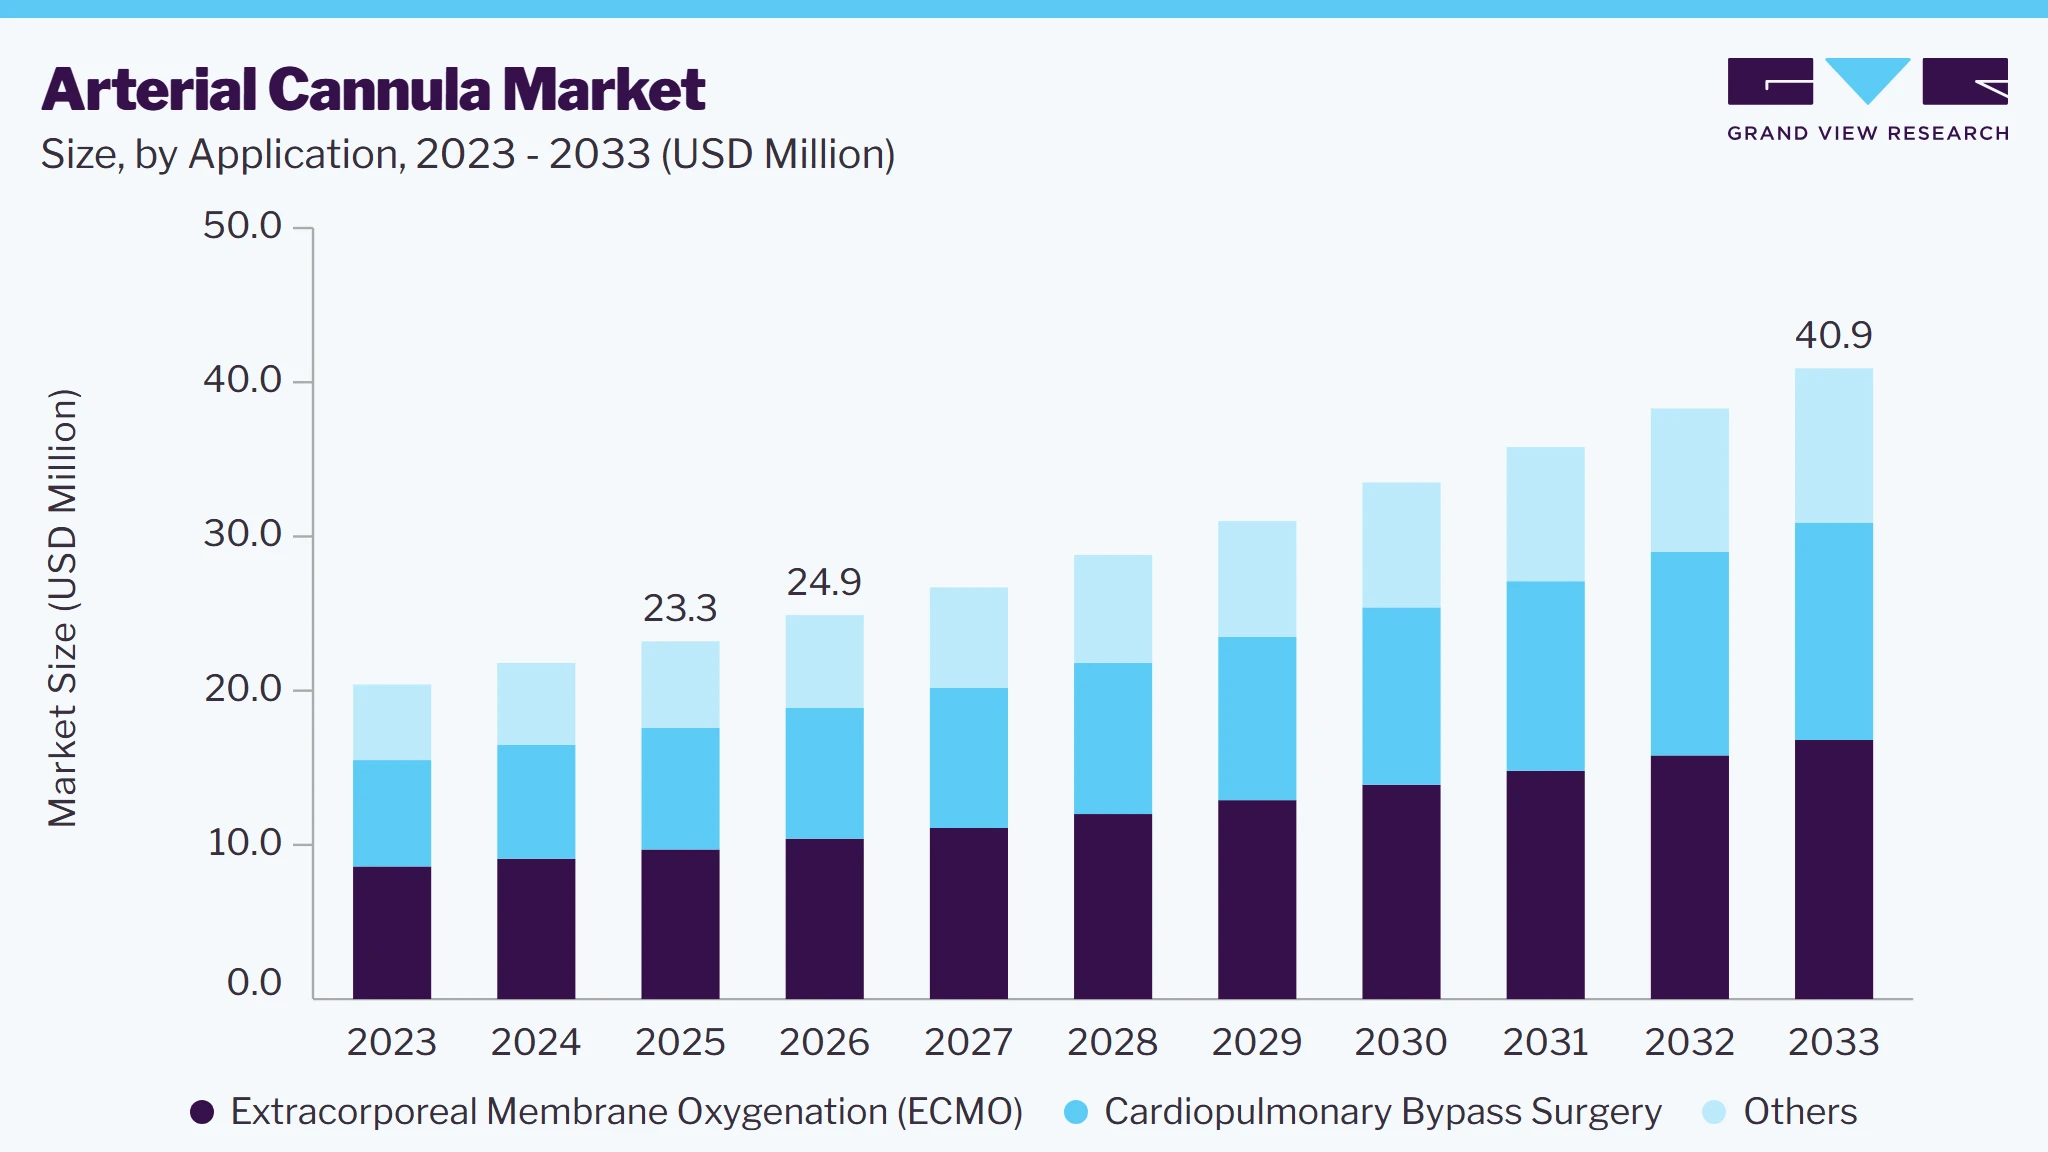
The global arterial cannula market size was valued at 23.3 million in 2025 and is projected to grow from USD 24.9 million in 2026 to USD 40.9 million by 2033, at a CAGR of 7.3% from 2026 to 2033. North America market dominated, with a revenue share of 40.3% in 2025. The growing incidence of chronic conditions necessitating procedures such as cardiopulmonary bypass surgery (CABG), dialysis, and Extracorporeal Membrane Oxygenation (ECMO) is a key factor driving arterial cannula demand.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Extracorporeal membrane oxygenation (ECMO) segment led the market with the largest revenue share of 41.8% in 2025.
- By size: 20-22 Fr segment led the market with the largest revenue share of 23.1% in 2025.
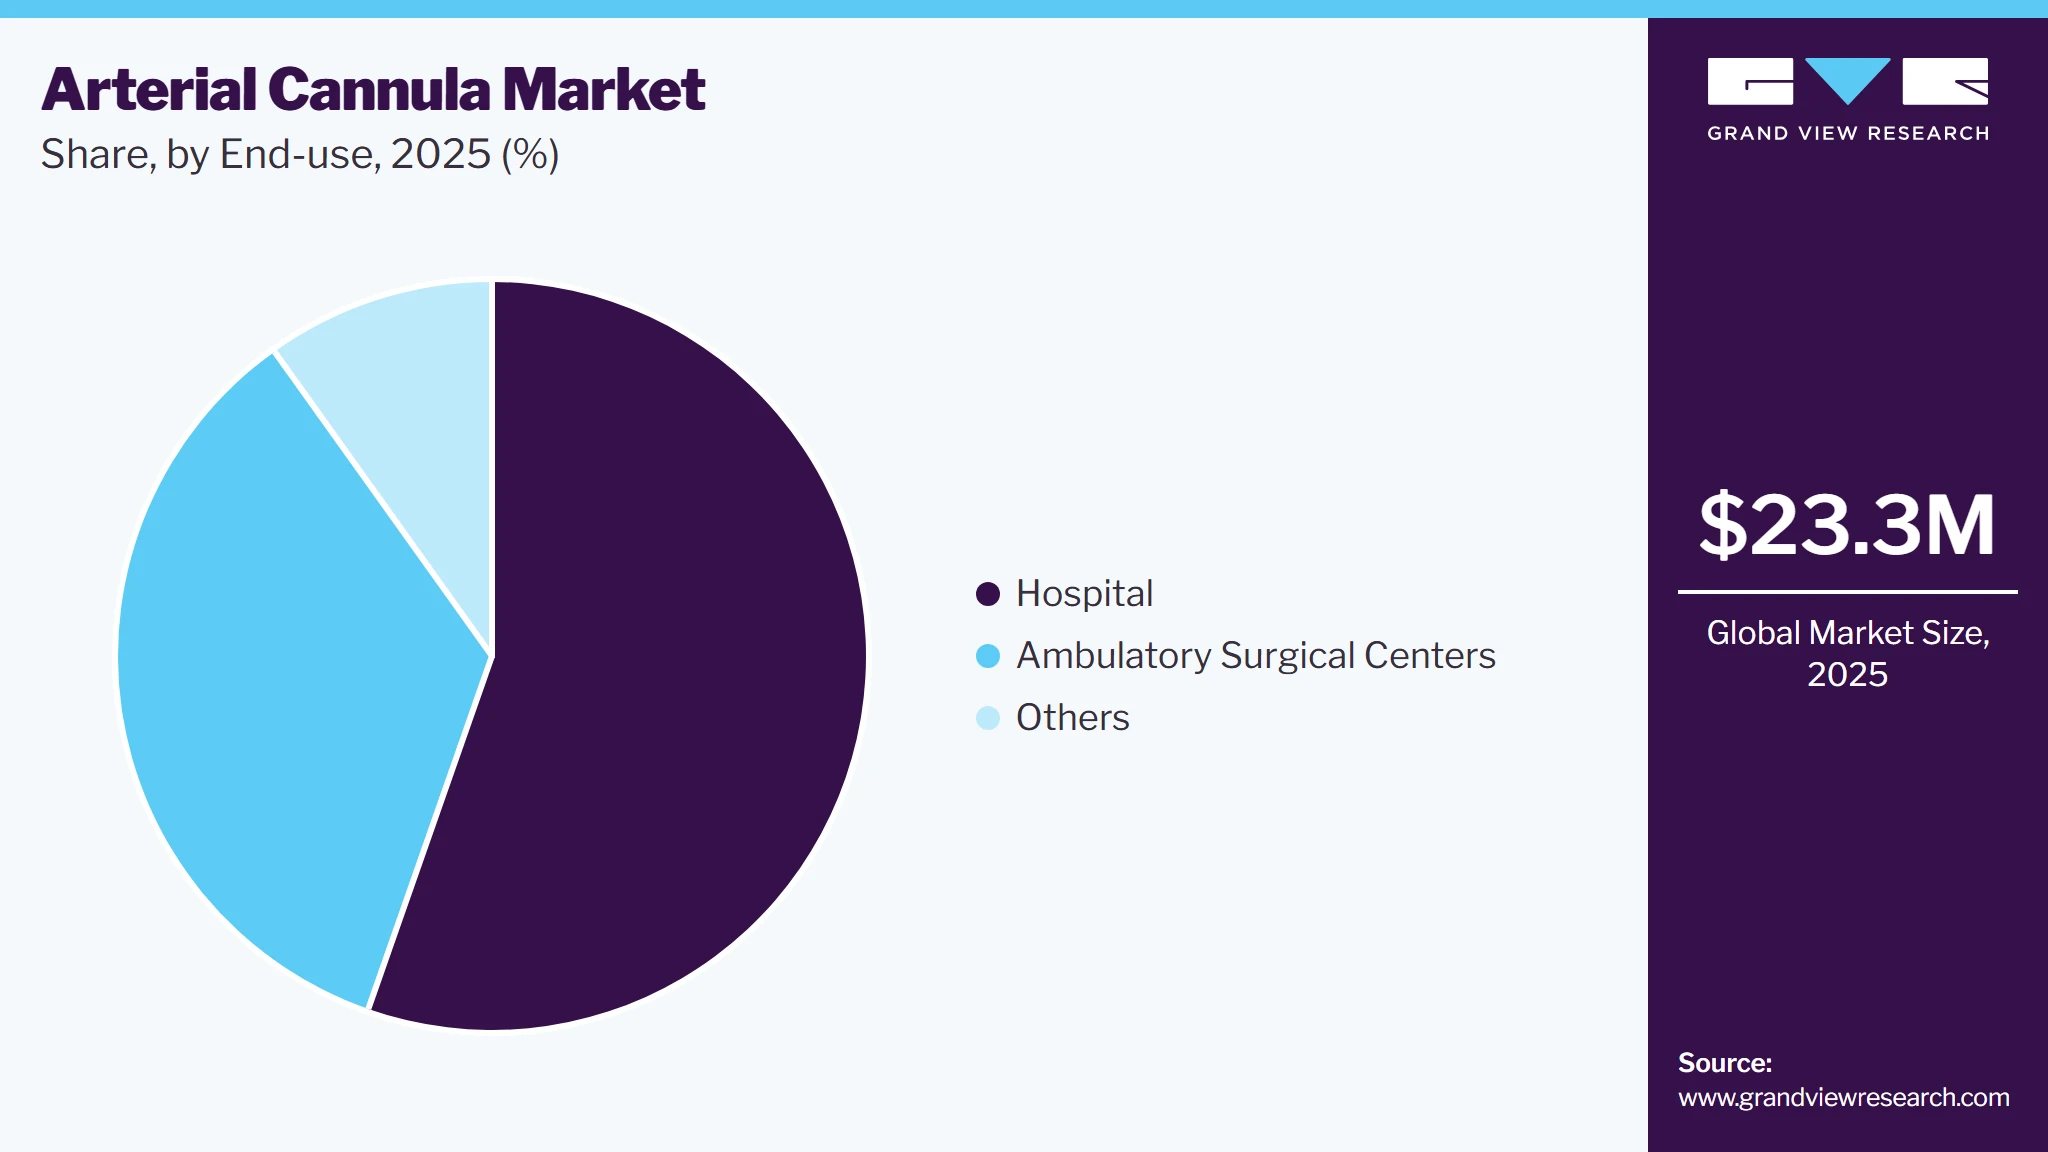
- By end-use: Hospital segment led the market with the largest revenue share of 55.3% in 2025.
Regional Highlights
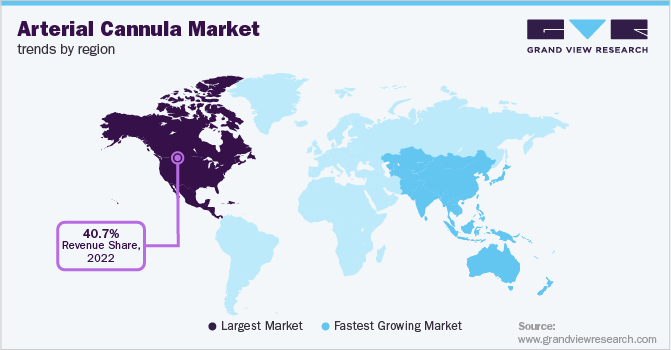
- Largest regional market: North America (40.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecasts
- Market size in 2025: USD 23.3 Million
- Estimated market size in 2026: USD 24.9 Million
- Projected market size by 2033: USD 40.9 Million
- CAGR (2026-2033): 7.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The preference for minimally invasive techniques is increasing due to benefits such as shorter recovery times and reduced pain. In addition, advancements in minimally invasive surgeries and the creation of innovative, biocompatible cannula materials further boost market growth. The rising prevalence of cardiovascular diseases significantly fuels demand for arterial cannulas. Cardiovascular conditions remain the leading cause of mortality globally, accounting for nearly 18.6 million deaths annually, according to the World Health Organization (WHO). Procedures such as CABG and ECMO have become increasingly common to manage severe cardiac and respiratory conditions. The COVID-19 pandemic further highlighted the importance of ECMO therapy, leading to a surge in arterial cannula usage for critically ill patients. Dialysis also contributes to market growth, driven by the growing incidence of end-stage renal disease and chronic kidney conditions.Minimally invasive techniques are gaining popularity due to their advantages, such as shorter recovery times, reduced scarring, and lower risks of complications. These procedures heavily depend on advanced arterial cannula designs, including biocompatible materials that minimize the risk of infection and enhance patient outcomes. Innovations in manufacturing have introduced arterial cannulas with improved flexibility and durability, further driving their adoption. Hospitals and cardiac care centers dominate the market as primary users, given the increasing number of surgeries and specialized care they provide.
 To learn more about this report, Download Free Sample Report
According to a research study published in the European Journal of Preventive Cardiology, the official journal of the European Association of Preventive Cardiology, more than 90 percent of people with type 2 diabetes (T2D) are at high risk of fatal heart disease or stroke within 10 years. Thus, an increase in risk factors, such as diabetes and hypertension, is likely to lead to a rise in the prevalence of Cardiovascular Diseases (CVDs), which will boost the product demand over the forecast period. An increasing geriatric population that is highly vulnerable to developing chronic diseases is also contributing to the growth of industry. According to the U.S. Census Bureau, there were about 40.3 million U.S. residents aged 65 years and older in 2010 and the number rose to 54.1 million in July 2019.
Geographically, North America leads the arterial cannula market due to advanced healthcare infrastructure, high prevalence of chronic diseases, and widespread adoption of innovative medical technologies. The U.S., in particular, represents a significant share of the market, with over 500,000 CABG surgeries performed annually. Europe follows closely, driven by similar factors and a growing elderly population that demands cardiovascular interventions. Meanwhile, the Asia Pacific region is emerging as a lucrative market due to improving healthcare facilities, increasing medical tourism, and rising awareness of advanced surgical techniques. Countries such as India and China are witnessing rapid growth as they expand healthcare access to broader populations.
Market Dynamics
The arterial cannula market is witnessing continuous growth owing to the increase in cardiothoracic surgical procedures, increasing adoption of extracorporeal life support systems, and growing need for minimally invasive procedures of the cardiovascular system. Arterial cannulas form an important part of the extracorporeal circulation system which allows blood to be returned to the arterial system during cardiopulmonary bypass, extracorporeal membrane oxygenation, and other temporary circulatory support procedures. The market for arterial cannulas consists of different types of arterial cannulas that come in varying French (Fr) sizes and can cater to the needs of different types of patients ranging from neonates to adults. Growing incidences of cardiovascular diseases, heart failures, respiratory disorders requiring ECMO support, increased incidences of cardiac surgeries, and opening of cardiac care centers drive market growth. In addition, technologically advanced products such as wire reinforced cannulas, thin-wall cannulas, heparin coated cannulas, kink resistant cannulas, and innovative tips have been developed.
The rising incidence of cardiovascular ailments and the expanding use of extracorporeal circulatory support treatments are some of the key determinants fueling the growth of the arterial cannula industry. The modern arterial cannulas are being used increasingly by healthcare professionals in cardiopulmonary bypass surgeries, ECMO treatment, and other types of cardiovascular surgery to facilitate efficient blood perfusion in the body and better patient results. Growing preference for minimal invasive heart surgery, development of heart transplantation and mechanical circulatory support programs, availability of ECMO treatments, and ongoing innovation in cannula technologies are propelling product adoption.
Despite continuous product innovation, market growth remains constrained by the risk of vascular complications associated with arterial cannulation, including bleeding, embolism, arterial dissection, limb ischemia, and infection. Successful arterial cannulation requires experienced cardiovascular surgeons, while manufacturers must comply with stringent regulatory standards governing cardiovascular medical devices. Additionally, high product validation requirements, reimbursement variability, and pricing pressure within healthcare systems may limit market expansion, particularly in cost-sensitive regions.
Market Concentration & Characteristics
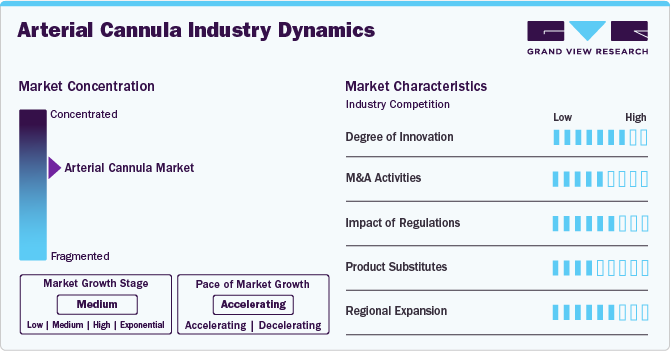
The arterial cannula industry is moderately concentrated, with key players such as Medtronic, Terumo Corporation, and Edwards Lifesciences dominating the market. These companies focus on innovation, offering advanced biocompatible materials and minimally invasive designs to enhance patient outcomes. The industry is characterized by high regulatory standards, requiring rigorous testing for safety and efficacy. Technological advancements and strategic collaborations drive competition, while emerging players contribute to market diversity.
The arterial cannula industry demonstrates a high degree of innovation, driven by advancements in materials, designs, and manufacturing technologies. Biocompatible materials enhance patient safety, while innovations in minimally invasive cannulas improve procedural efficiency and recovery times. Companies invest heavily in R&D to develop flexible, durable, and precision-engineered products for specialized applications, such as ECMO and CABG procedures. The integration of advanced coatings to reduce infection risks and advancements in catheterization techniques further highlight the sector's innovation. Collaborative efforts among manufacturers, healthcare providers, and research institutions accelerate innovation, ensuring the industry meets evolving clinical demands and enhances patient outcomes globally.
 To learn more about this report, Download Free Sample Report
Regulations significantly impact the arterial cannula industry by ensuring product safety, efficacy, and quality. Strict guidelines from agencies such as the FDA and European Medicines Agency (EMA) govern manufacturing, testing, and approval processes. Compliance with ISO standards for medical devices is essential, increasing production costs and timelines but enhancing reliability. Regulatory scrutiny over biocompatibility and infection risks drives innovation and improvements. Non-compliance can lead to recalls, impacting market reputation and revenue. Conversely, meeting regulatory requirements fosters consumer trust and global market access. Evolving healthcare policies and regional regulatory disparities present challenges, influencing market dynamics and driving continuous quality enhancement efforts.
The arterial cannula industry has witnessed a moderate level of mergers and acquisitions (M&A) activity, primarily driven by the need for market consolidation, technological advancements, and expansion of product portfolios. Leading players such as Medtronic and Edwards Lifesciences actively acquire smaller firms with innovative technologies to enhance their competitive edge. M&A activities enable companies to access advanced manufacturing capabilities, strengthen global distribution networks, and capitalize on emerging market opportunities.
In the arterial cannula industry, substitutes are limited but include alternative devices such as venous cannulas, percutaneous catheters, and advanced vascular access technologies. While these alternatives cater to specific procedures, they may lack the versatility and efficacy of arterial cannulas in critical applications such as ECMO, CABG, and dialysis. Emerging innovations, such as minimally invasive devices or bioengineered grafts, pose potential substitution threats but are not yet widely adopted. The preference for arterial cannulas remains strong due to their established clinical outcomes and compatibility with diverse procedures, limiting the impact of substitutes on market demand in the short to medium term.
The arterial cannula industry is expanding regionally, driven by rising healthcare investments and disease prevalence. In Asia Pacific, countries such as India and China see growing demand due to increasing cardiovascular and diabetes cases, alongside improving healthcare infrastructure. In Latin America, public health initiatives and access to advanced surgical tools fuel growth. Developed regions such as North America and Europe lead due to technological advancements and strong healthcare systems, while the Middle East sees demand rise from chronic disease management and healthcare modernization. Regional collaborations, favorable policies, and strategic market entries by global players further accelerate growth in emerging and underserved markets.
Analyst Perspective
The market for arterial cannulas continues to be a key part of the larger cardiovascular surgery and extracorporeal life support landscape. The increasing prevalence of cardiovascular ailments, increase in the number of procedures performed for open-heart surgery, increased use of ECMO, and improvements in perfusion technology will ensure consistent demand for high-quality arterial cannulas. Innovations in arterial cannulas include better biomaterials, wire reinforced cannulas, thin-walled cannulas, anti-thrombotic coating of cannulas, and specially designed anatomical cannulas to reduce complications and improve results from the procedure. With the healthcare industry continuing to develop their cardiac surgery facilities, critical care departments, and extracorporeal life support services, there is going to be a steady demand for technologically sophisticated arterial cannulas.
Application Insights
Based on application, the extracorporeal membrane oxygenation (ECMO) segment led the market with the largest revenue share of 41.8% in 2025. This can be attributed to the high prevalence of cardiac diseases and lung failures. According to the American Lung Association’s estimated data in 2022, around 37 million Americans live with chronic lung disease such as COPD and asthma, which includes chronic bronchitis and emphysema. About 15 million American adults have been diagnosed with COPD, an obstructive lung disease that over time makes it harder to breathe.
This suggests that the increasing burden of respiratory diseases that may eventually result in lung failure is the major factor contributing to the dominance of the ECMO segment. On the other hand, cardiopulmonary bypass surgery is expected to be the fastest-growing segment over the forecast period. This is due to the rising prevalence of cardiac diseases that require cardiopulmonary bypass surgery. According to a research article, published by the National Centers for Biotechnology Information published in May 2022, almost 400,000 CABG surgeries are performed annually making it the most commonly performed major surgical procedure.
Size Insights
Based on size, the 20-22 Fr segment led the market with the largest revenue share of 23.1% in 2025. The high share of the segment can be attributed to an increase in the adoption of cannulas of this size while carrying out ECMO procedures. The demand for these cannulas experienced a sudden rise during the pandemic as a higher number of patients required ECMO, especially those who were infected with the virus.
While selecting the size, the general rule that healthcare professionals need to abide by is to select the smallest possible size but the one which allows effective drainage. The 23-25 Fr size segment accounted for the second-highest revenue share of the global industry in 2024. This was due to the wide usage of these cannulas in cardiopulmonary bypass surgeries. On the other hand, the 35-36 Fr size segment is estimated to register the fastest growth rate during the forecast period.
End use Insights
Based on end-use, the hospital segment led the market with the largest revenue share of 55.3% in 2025. This was mainly attributed to a large number of surgeries being performed in these settings. In addition, the availability of all types of skilled professionals and surgical instruments is expected to fuel the segment's growth. The rising number of admissions due to an increasing number of chronic disorders is also expected to propel the segment growth over the forecast period.
 To learn more about this report, Download Free Sample Report
The Ambulatory Surgical Centers (ASCs) segment is anticipated to witness notable growth during the forecast period, driven by a rising preference for surgeries in ASCs. Key factors include lower overall costs and shorter post-surgery hospital stays. In addition, supportive government policies bolster this trend. For example, in early 2021, the Centers for Medicare and Medicaid Services expanded ASC coverage to include cardiac interventions such as endovenous ablation, catheterization, and pacemaker placements.
Regional Insights
North America dominated the arterial cannula market with the largest revenue share of 40.3% in 2025 due to advanced healthcare infrastructure, high surgical procedure rates, and a growing elderly population. Increasing adoption of minimally invasive surgeries and the prevalence of cardiovascular diseases have driven demand for arterial cannulas. The U.S. leads the market, supported by strong R&D investments and technological advancements. In addition, the presence of key manufacturers ensures innovation and accessibility. Favorable reimbursement policies and an emphasis on patient safety further enhance market growth. These factors position North America as a key player in the global arterial cannula market, maintaining its leadership in the segment.
 To learn more about this report, Download Free Sample Report
U.S. Arterial Cannula Market Trends
The arterial cannula market in the U.S. held the largest share in the North America region in 2025. The U.S. arterial cannula market is one of the largest and fastest-growing segments within the global market, driven by the increasing prevalence of chronic conditions such as diabetes. According to the CDC, there were 7,433 dialysis facilities in the U.S. in 2018, with 518,749 patients undergoing dialysis, averaging about 70 per facility. In addition, pulmonary diseases such as COPD and asthma, which can lead to lung failure, are notably prevalent in the region, further contributing to the demand for arterial cannulas.
Europe Arterial Cannula Market Trends
Europe arterial cannula market dominates driven by advanced healthcare infrastructure, high prevalence of cardiovascular diseases, and an aging population. With over 50 million people living with cardiovascular conditions in Europe, demand for arterial cannulas continues to rise.
The UK arterial cannula market is steadily growing, supported by government initiatives focused on investing in diabetes care and research to enhance treatment options for diabetic patients. The increasing number of diabetes cases in the region is a key factor driving market expansion. According to Diabetes UK, over 4.3 million people in the UK are affected by diabetes, with an additional 850,000 individuals potentially living undiagnosed.
The arterial cannula market in France is growing due to the rising prevalence of cardiovascular diseases and diabetes. Advancements in medical technologies and the increasing adoption of minimally invasive procedures further drive demand. In addition, France’s strong healthcare infrastructure and a focus on improving patient outcomes contribute to market expansion.
The German arterial cannula market is primarily driven by the growing prevalence of diabetes, with approximately 7.5 million people affected, according to the International Diabetes Federation. This increase in diabetic patients contributes to a higher demand for vascular procedures, boosting the need for arterial cannulas in medical treatments.
Asia Pacific Arterial Cannula Market Trends
The Asia Pacific arterial cannula market is expected to experience strong growth during the forecast period. Factors such as the rising prevalence of cardiovascular diseases, diabetes, and an aging population are driving demand for arterial cannulas. In addition, improving healthcare infrastructure, increasing access to advanced medical technologies, and a growing focus on minimally invasive procedures contribute to market expansion. Countries such as China, India, and Japan are witnessing significant adoption of arterial cannulas in both public and private healthcare sectors. The region's expanding healthcare access and rising awareness of advanced treatment options position it as a key growth area.
The arterial cannula market in Japan is experiencing growth, driven by continuous technological advancements in medical devices. Innovations in biocompatible materials and minimally invasive techniques enhance patient outcomes, while Japan's robust healthcare infrastructure and increasing demand for cardiovascular procedures further contribute to the market's expansion.
The arterial cannula market in China is anticipated to grow quickly, driven by the increasing number of diabetic patients in the region. According to the 2020 edition of the Guidelines for the Prevention and Treatment of Diabetes in China, the prevalence of diabetes among adults stands at 11.2%, with an estimated 141 million people affected. Furthermore, about 51.7% of these individuals remain undiagnosed. This growing diabetic population is a key factor fueling the expansion of the arterial cannula market in China.
India's arterial cannula market is growing significantly due to its high diabetes prevalence, with over 77 million affected individuals, ranking among the world's highest. This surge drives demand for vascular procedures, including arterial cannulation, supported by advancements in minimally invasive techniques and improving healthcare infrastructure across the country.
Latin America Arterial Cannula Market Trends
The Latin American arterial cannula market is growing rapidly, fueled by increasing diabetes prevalence, affecting nearly 32 million adults in the region (IDF, 2023). Diabetes-related complications drive demand for vascular procedures, including arterial cannulation, supported by expanding healthcare access and advancements in minimally invasive surgical techniques.
Middle East & Africa Arterial Cannula Market Trends
The arterial cannula market in the Middle East and Africa (MEA) is expected to grow significantly, driven by an increasing prevalence of chronic conditions such as cardiovascular diseases and diabetes. According to the International Diabetes Federation, the MEA region had 73 million adults living with diabetes in 2021, with numbers projected to rise. In addition, growing investments in healthcare infrastructure and the adoption of advanced medical technologies are supporting market growth. The demand for minimally invasive techniques further boosts the arterial cannula market in the region.
The arterial cannula market in Saudi Arabia is growing due to increasing cardiovascular disease prevalence, an aging population, and advancements in healthcare infrastructure. Rising adoption of minimally invasive surgeries and government investments in modern medical technologies further drive demand, positioning the country as a key market in the Middle East region.
Key Arterial Cannula Company Insights
The competitive scenario in the arterial cannula market is highly competitive, with key players such as Medtronic plc., Inc., Getinge AB and others. The major companies are undertaking various organic and inorganic strategies such as new product development, collaborations, acquisitions, mergers, and regional expansion to serve the unmet needs of their customers.
Key Arterial Cannula Companies
The following key companies have been profiled for this study on the arterial cannula market.
-
Medtronic, plc.
-
LivaNova plc
-
Edward Lifesciences
-
Getinge AB
-
Fresenius Medical Care
-
BD
-
Nipro Corp.
-
Andocor
-
Freelife Medical GmbH
-
Surgical Holdings
-
Kangxin Medical
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Medtronic plc; LivaNova plc; Edwards Lifesciences; Getinge AB; Fresenius Medical Care; BD; Nipro Corporation)
- Established manufacturers focus on comprehensive extracorporeal circulation product portfolios by offering arterial cannulas alongside cardiopulmonary bypass systems, ECMO platforms, perfusion accessories, and cardiovascular surgical consumables. They emphasize continuous product innovation, biocompatible materials, heparin-coated technologies, global regulatory compliance, strategic hospital partnerships, and expansion of manufacturing capabilities to strengthen market leadership.
- Strong global distribution networks, diversified cardiovascular product portfolios, extensive clinical validation, established relationships with cardiac surgery centers, advanced manufacturing capabilities, and broad regulatory expertise provide sustainable competitive advantages.
- Dependence on hospital procurement cycles, pricing pressure within healthcare systems, stringent regulatory requirements, and increasing competition from regional manufacturers may impact market growth.
Emerging Players (Andocor; Freelife Medical GmbH; Surgical Holdings; Kangxin Medical)
- Emerging companies prioritize development of cost-effective arterial cannulas, specialized perfusion products, customized sizing options, and region-specific commercialization strategies. They focus on product quality, manufacturing efficiency, distributor partnerships, and regulatory expansion to strengthen market presence across developing healthcare markets.
- Competitive pricing, manufacturing flexibility, specialized product offerings, responsiveness to customer requirements, and growing regional distribution capabilities support adoption across emerging cardiac surgery markets.
- Limited global brand recognition, smaller commercial infrastructure, restricted international distribution, lower manufacturing scale, and dependence on regulatory approvals and strategic partnerships may constrain global expansion compared with established multinational companies.
Recent Developments
-
In September 2024, Shockwave Medical has expanded its U.S. peripheral intravascular lithotripsy (IVL) portfolio by introducing an enhanced catheter, designed for treating calcified arterial lesions. This advancement underscores the growing innovation in vascular care, directly benefiting arterial cannula applications by supporting procedures requiring precision and addressing complex vascular conditions effectively.
-
In April 2024, The FDA has announced a recall of Arrow QuickFlash Radial Artery Catheterization Kits due to potential device malfunctions that could pose safety risks. This highlights the importance of stringent quality standards in arterial cannula manufacturing to ensure reliability and safety in procedures like arterial line placement and catheterization.
Arterial Cannula Market Report Scope
Report Attribute
Details
Market size in 2025
USD 23.3 million
Estimated market size in 2026
USD 24.9 million
Projected market size by 2033
USD 40.9 million
Growth rate
CAGR of 7.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, size, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Thailand; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Medtronic, plc; LivaNova plc; Edward Lifesciences; Getinge AB; Fresenius Medical Care; BD; Nipro Corp.; Andocor; Freelife Medical GmbH; Surgical Holdings; Kangxin Medical
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Arterial Cannula Market Report Segmentation
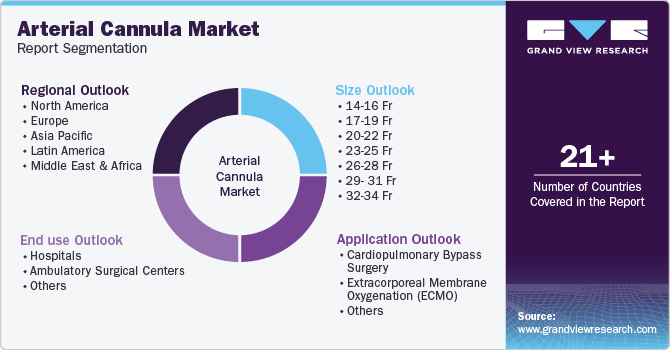
This report forecasts revenue growth at country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global arterial cannula market report on the basis of application, size, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Cardiopulmonary Bypass Surgery
-
Extracorporeal Membrane Oxygenation (ECMO)
-
Others
-
-
Size Outlook (Revenue, USD Million, 2021 - 2033)
-
14-16 Fr
-
17-19 Fr
-
20-22 Fr
-
23-25 Fr
-
26-28 Fr
-
29- 31 Fr
-
32-34 Fr
-
35-36 Fr
-
-
End use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The arterial cannula market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each arterial cannula segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Cardiopulmonary Bypass Surgery
Revenue is generated through the utilization of arterial cannulas during cardiopulmonary bypass procedures performed in open-heart surgeries, including coronary artery bypass grafting, valve replacement, congenital heart defect repair, and aortic surgery. Manufacturers capture revenue through arterial cannula sales, accessory components, customized product configurations, and recurring procurement by cardiac surgery centers.
Extracorporeal Membrane
Oxygenation (ECMO)
Revenue is derived from arterial cannulas utilized in veno-arterial ECMO procedures supporting patients with severe cardiac and cardiopulmonary failure. Manufacturers generate revenue through specialized ECMO cannulas, emergency perfusion products, disposable components, and customized cannulation solutions designed for adult, pediatric, and neonatal patient populations. Increasing adoption of ECMO therapy continues to support demand within this segment.
Others
Revenue is generated through arterial cannulas utilized in temporary circulatory support procedures, extracorporeal circulation during vascular surgery, organ transplantation, and other specialized cardiovascular interventions. Manufacturers benefit from sales of application-specific cannulas, accessory products, and customized perfusion solutions addressing diverse clinical requirements.
Segment - Size
Revenue capture definition
14-16 Fr
Revenue is generated through arterial cannulas designed primarily for neonatal, pediatric, and small adult patients requiring low-flow extracorporeal circulation. Manufacturers capture revenue through specialized cannula sales and pediatric cardiovascular surgery programs.
17-19 Fr
Revenue is derived from arterial cannulas supporting pediatric and smaller adult cardiac surgery and ECMO procedures. Increasing utilization across specialized cardiac centers contributes to recurring procurement.
20-22 Fr
Revenue is generated through medium-sized arterial cannulas commonly utilized in adult cardiopulmonary bypass procedures requiring moderate perfusion flow rates. Manufacturers benefit from routine procurement by cardiac surgery departments.
23-25 Fr
Revenue is derived from arterial cannulas supporting standard adult cardiac surgeries and extracorporeal circulation procedures. High procedural volumes continue to make this an important revenue-generating segment.
26-28 Fr
Revenue is generated through large-bore arterial cannulas designed for adult patients requiring higher perfusion flow during complex cardiovascular procedures and ECMO therapy.
29- 31 Fr
Revenue is derived from arterial cannulas supporting high-flow extracorporeal circulation during advanced cardiac surgery and mechanical circulatory support procedures. Manufacturers generate revenue through premium cannula designs and specialized product offerings.
32-34 Fr
Revenue is generated through extra-large arterial cannulas utilized in selected high-flow adult cardiovascular procedures requiring maximum circulatory support. Demand is driven by specialized tertiary cardiac centers.
35-36 Fr
Revenue is derived from highly specialized arterial cannulas designed for complex surgical procedures requiring maximum extracorporeal blood flow. Manufacturers capture revenue through customized products and limited-volume, high-value clinical applications.
Segment - Vector
Revenue capture definition
Hospital
Revenue is generated through procurement and utilization of arterial cannulas by tertiary hospitals, cardiovascular specialty hospitals, academic medical centers, and transplant centers performing cardiopulmonary bypass surgery and ECMO procedures. Manufacturers benefit from recurring disposable product sales, supply contracts, and long-term procurement agreements.
Ambulatory Surgical Centers
Revenue is derived from ambulatory surgical centers performing selected cardiovascular and vascular procedures requiring temporary extracorporeal circulation support. Increasing adoption of minimally invasive cardiovascular interventions continues to support market growth within this segment.
Others
Revenue is generated through specialized cardiac centers, military healthcare facilities, emergency care institutions, and research organizations utilizing arterial cannulas for clinical, educational, and investigational applications.
Estimation Model
Step / Key Question
Process Steps
Data Sources
Scope Definition
What is being sized?
1. Define Arterial Cannula Market Scope
2. Scope Application, Size, and End use Segments
3. Establish Geographic Coverage (Global/Regional)
4. Align on base year & forecast horizon (2026-2033)
FDA, CE MDR, Company Product Catalogs, ELSO Guidelines, STS Guidelines
Build Procedure Base
How large is total addressable market?
1. Estimate Annual Cardiopulmonary Bypass and ECMO Procedures
2. Segment Procedures by Application, Patient Population, and Cannula Size
3. Assess Cannula Utilization Across Healthcare Facilities
4. Forecast Procedure Growth Across Regions
Hospital Procurement Databases, Company Annual Reports, Academic Research Infrastructure Records
Estimate Product Utilization
What portion of procedures utilize arterial cannulas?
1. Assess Average Cannula Consumption per Procedure
2. Evaluate Utilization by Application and Size
3. Analyze Procurement Frequency and Product Replacement Trends
4. Validate Through Industry Interviews
Primary interviews, clinical surveys, industry experts
Revenue Conversion
How does volume become revenue?
1. Determine ASPs by Size
2. Estimate Revenue from Sales of Cannula
3. Apply Regional Pricing Variations
4. Cross-validate with Company Revenues and Public Findings
Company Annual Reports, Distributor pricing sheets, procurement data, expert interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive assessment of leading arterial cannula manufacturers by evaluating product portfolios across cardiopulmonary bypass and ECMO applications, cannula size offerings, biomaterial technologies, tip configurations, heparin-coated surfaces, regulatory approvals, pricing strategies, manufacturing capabilities, geographic presence, strategic partnerships, mergers and acquisitions, and research and development initiatives. Competitive benchmarking assessed both established and emerging participants to identify technology leadership and market positioning.
Enables stakeholders to benchmark technology leadership, identify product innovation trends, compare competitive positioning, evaluate product portfolios, assess purchasing opportunities, and formulate commercialization, procurement, and investment strategies within the cardiovascular surgery and extracorporeal life support market.
Segment by Application Analysis
Conducted a detailed assessment of arterial cannula adoption across cardiopulmonary bypass surgery, ECMO, and other applications, segmented by French size (14-16 Fr to 35-36 Fr) and end users including hospitals, ambulatory surgical centers, and other healthcare facilities. The study evaluated procedure volumes, cannula utilization rates, procurement patterns, replacement frequency, patient demographics, and technology adoption to estimate demand across each segment.
Enables stakeholders to identify high-growth application and product segments, optimize commercialization strategies, understand purchasing behavior, forecast product demand, prioritize product development, and support strategic planning across diverse cardiovascular care settings.
Macroeconomic Analysis
Conducted an in-depth assessment of cardiovascular disease prevalence, cardiac surgery volumes, ECMO adoption, healthcare expenditure, reimbursement policies, expansion of cardiac surgery infrastructure, regulatory developments, and investments in advanced cardiovascular care influencing demand for arterial cannulas. The study also evaluated demographic trends, aging populations, critical care capacity, expanded government healthcare initiatives shaping long-term market growth across developed and emerging healthcare markets.
Enables stakeholders to understand demographic, epidemiological, economic, regulatory, and healthcare system factors influencing demand within the arterial cannula market. The study supports long-term forecasting, manufacturing capacity planning, pricing strategy development, regional market expansion decisions, investment prioritization, and evaluation of future growth opportunities driven by advances in cardiovascular surgery and extracorporeal life support technologies.
Frequently Asked Questions About This Report
Some key players operating in the arterial cannula market include Medtronic, plc., LivaNova plc, Edward Lifesciences, Getinge AB, Fresenius Medical Care, BD, Nipro Corporation, Andocor, Freelife Medical GmbH, Surgical Holdings, and Kangxin Medical.
Key factors that are driving the arterial cannula market growth include an increasing number of surgical procedures, advancements in minimally invasive surgeries and increasing prevalence of chronic diseases.
Asia Pacific is the fastest-growing region over the forecast period.
Extracorporeal membrane oxygenation (ECMO) segment led the market with the largest revenue share of 41.8% in 2025.
The global arterial cannula market size was valued at USD 23.3 million in 2025 and is estimated at USD 24.9 million for 2026.
The global arterial cannula market is expected to grow at a CAGR of 7.3% from 2026 to 2033, reaching USD 40.9 million by 2033.
Hospital segment led the market with the largest revenue share of 55.3% in 2025.
20-22 Fr segment led the market with the largest revenue share of 23.1% in 2025.
North America market dominated, with a revenue share of 40.3% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


