
- Home
- »
- Medical Devices
- »
-
Australia & New Zealand Healthcare CROs Market Report 2033GVR Report cover

Australia & New Zealand Healthcare CROs Market (2025 - 2033 ) Size, Share & Trends Analysis Report By Type (Drug Discovery, Pre-clinical, Clinical), By Service, By Therapeutic Area, By End-use, And Segment Forecasts
Australia & New Zealand Healthcare CROs Market Summary
The Australia & New Zealand healthcare CROs market size was estimated at USD 1.33 billion in 2024 and is projected to reach USD 3.35 billion by 2033, growing at a CAGR of 11.02% from 2025 to 2033. Supportive regulatory and ethical frameworks, government incentives and investment in R&D and advanced infrastructure and diverse patient pool are some of the key factors driving market growth.
Key Market Trends & Insights
- The Australia & New Zealand healthcare CROs is expected to grow significantly over the forecast period.
- Based on type, the clinical services segment held the largest market share of 75.93% in 2024.
- Based on service, clinical monitoring segment held the highest market share in 2024.
- Based on therapeutic area, oncology segment held the highest market share in 2024.
Market Size & Forecast
- 2024 Market Size: USD 1.33 Billion
- 2033 Projected Market Size: USD 3.35 Billion
- CAGR (2025-2033): 11.02%
- Australia: Largest market in 2024
- New Zealand: Fastest growing market
Prism AI by Grand View Research Free to tryAsk a question about the australia & new zealand healthcare CROs marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The regulatory frameworks is anticipated to drive the clinical research activities in the Australia and New Zealand market. For instance, in New Zealand, it takes approximately 6.5 weeks to obtain regulatory approval and about 5 weeks for ethics approval. In Australia, the average time for regulatory approval is around 1 week, while ethics approval typically takes about 8 weeks, indicating the efficient yet different timelines for clinical trial governance in both nations. Swift ethics approval processes, standardized trial protocols, and well-recognized organizations such as the Therapeutic Goods Administration (TGA) and Medsafe help minimize start-up delays and improve adherence to ICH-GCP standards. This clear regulatory environment draws in global biopharmaceutical and medical device firms that are in search of consistent, high-quality research settings.In addition, New Zealand has become a preferred destination for early-phase and adaptive clinical trials due to its rapid regulatory timelines, high-quality data standards, and cost-efficient trial execution. As a result, these regions have become preferred destinations for early-phase and adaptive clinical trials. This supportive framework lowers development costs and strengthens partnerships between sponsors and CROs, thereby expanding the healthcare contract research organization outlook.
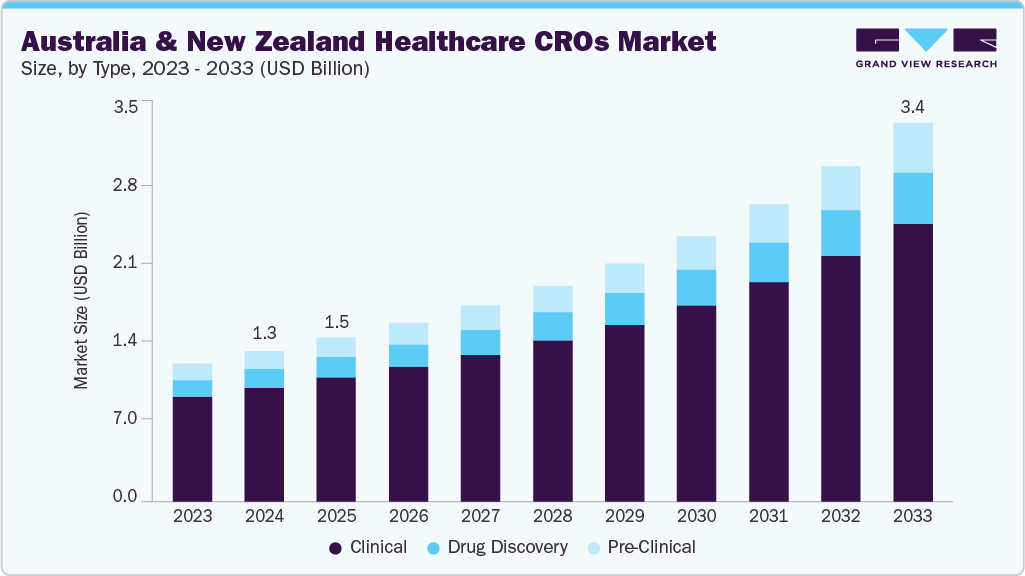 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Furthermore, increasing R&D tax incentives, research grants, and public-private collaborations across Australia and New Zealand have significantly boosted market growth. According to a report of September 2025, New Zealand offers strong healthcare infrastructure and easy access to clinicians and trial participants whereas Australia holds a competitive edge with a 43.5% R&D tax incentive for Phase 1 studies, compared to 15% in New Zealand. In addition, for instance, in May 2025, Cooperative Research Australia (CRA) supported collaborative research programs, emphasizing their vital role in industrial growth in healthcare, and alignment with health and biomedical research collaborations. Such tax incentives and government initiatives can help increase the number of industry-sponsored clinical trials, eventually boosting the demand among CRO clients, which have primarily U.S. and Asian sponsors, to perform clinical trials in Australia.
The regions’ advanced healthcare infrastructure and genetically diverse populations have created strong foundations for CRO market expansion. Modern hospitals, high-quality laboratories, and robust electronic health record systems facilitate accurate data collection and real-time patient monitoring. The ethnically diverse population supports inclusive clinical research, making results globally relevant. CROs leverage these assets to conduct complex, multi-phase trials efficiently, while telemedicine and decentralized trial models further streamline patient participation.
Opportunity Analysis
Australia and New Zealand Healthcare CROs market presents strong growth opportunities driven by favorable regulatory environments, government R&D incentives, and increasing global outsourcing of clinical research. Australia’s 43.5% R&D tax rebate and New Zealand’s streamlined ethics approvals make the region attractive for early-phase and adaptive trials. Expanding biotech ecosystems, rising investment in precision medicine, and growing regional integration with Asia Pacific further enhance market potential. In addition, the focus on decentralized trials, AI-driven data analytics, and patient recruitment technologies offers CROs avenues to deliver faster, more cost-effective solutions, positioning the region as a leading hub for global clinical research outsourcing.
Impact of U.S. Tariffs on Australia & New Zealand Healthcare CROs Market
The impact of U.S. tariffs on the Australia and New Zealand Healthcare CROs market remains notable. Increased costs for research equipment and medical devices may raise operational expenses for CROs. However, the region’s strong domestic R&D capabilities, streamlined regulatory systems, and favorable tax incentives continue to attract U.S. biopharma companies seeking cost-efficient clinical research. Exporters and CROs are advised to monitor tariff changes and diversify sourcing strategies. Thus, tough tariffs pose challenges in healthcare, but Australia and New Zealand remain resilient hubs for global clinical trials.
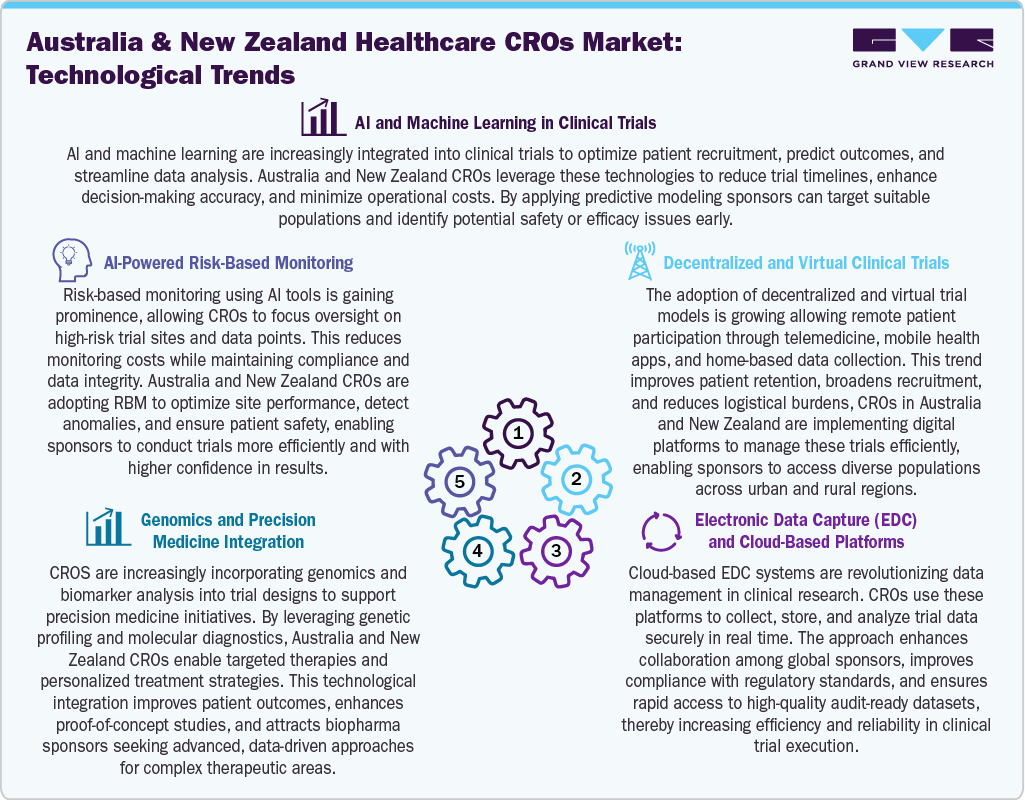 To learn more about this report, Download Free Sample Report
Australia and New Zealand’s healthcare CRO market is rapidly evolving through advanced technologies that enhance clinical trial efficiency and precision. AI and machine learning optimize patient recruitment, predict outcomes, and streamline data analysis, whereas decentralized and virtual trials expand access and retention. Cloud-based electronic data capture ensures secure, real-time collaboration, and genomics integration supports precision medicine and targeted therapies. In addition, AI-driven risk-based monitoring focuses oversight on high-risk sites, improving compliance and data integrity. In conclusion, these innovations reduce costs, accelerate timelines, and enable high-quality, patient-centric trials, positioning the region as a leading hub for global clinical research outsourcing.
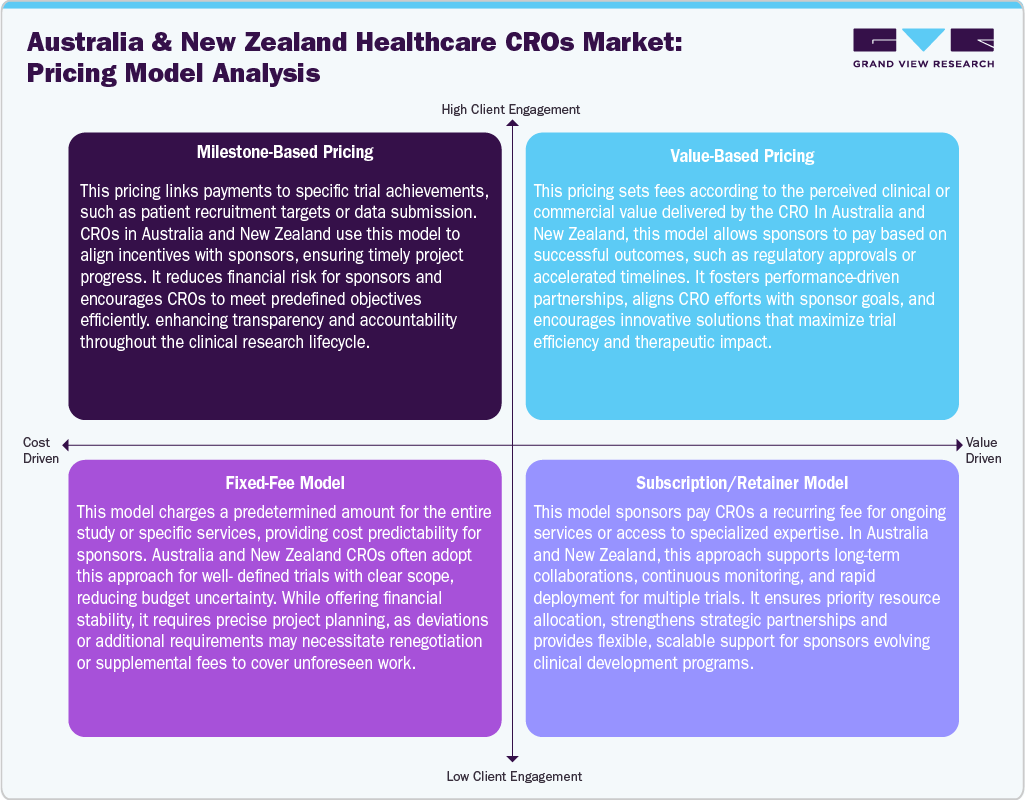 To learn more about this report, Download Free Sample Report
In the Australia and New Zealand healthcare CRO market, diverse pricing models cater to varying sponsor needs and project complexities. Milestone-based pricing links payments to specific trial achievements, ensuring timely progress and accountability. Value-based pricing aligns fees with clinical or commercial outcomes, incentivizing high-performance solutions. Fixed-fee models provide budget predictability for well-defined studies, while subscription or retainer models offer ongoing access to expertise and scalable support for multiple trials. Thus, these approaches enable flexible, transparent, and performance-driven partnerships, allowing sponsors to optimize costs, accelerate development timelines, and maintain strategic collaborations across early-phase and adaptive clinical research programs.
Market Concentration & Characteristics
The Australia & New Zealand healthcare CROs market growth stage is high, and growth is accelerating. The market is characterized by the degree of innovation, level of M&A activities, regulatory impact, service expansion, and regional expansion.
Australia and New Zealand CROs emphasize innovation through advanced technologies such as AI-driven patient recruitment, decentralized trials, and precision medicine integration. Adoption of digital platforms and data analytics enhances trial efficiency, accelerates timelines, and improves outcomes.
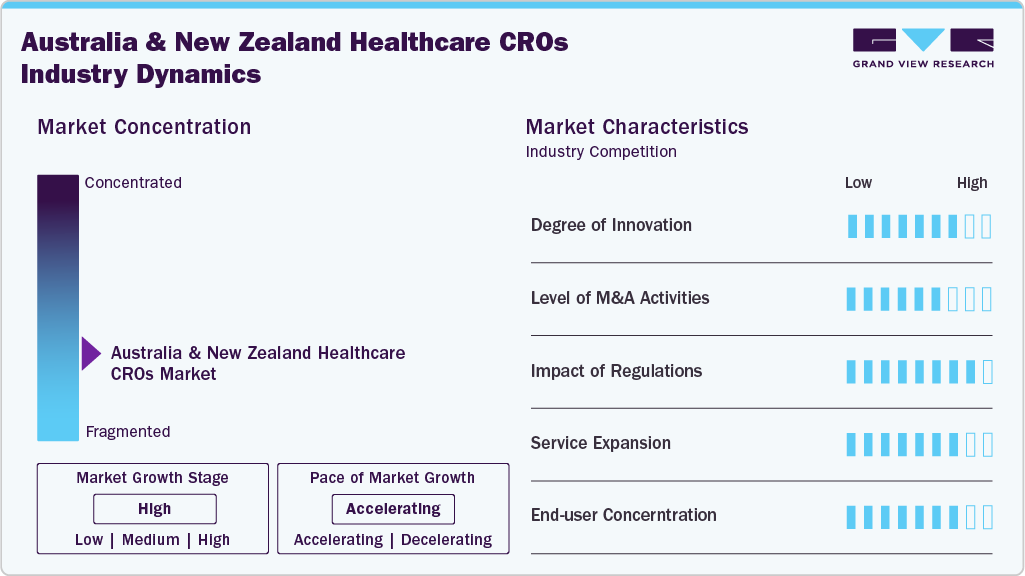 To learn more about this report, Download Free Sample Report
Mergers and acquisitions are reshaping the Australia and New Zealand CRO landscape, enabling consolidation of expertise, expansion of service offerings, and entry into new therapeutic areas. For instance, in September 2025, Momentum Clinical Research and PCRN have merged to form largest integrated clinical trial network, delivering seamless Phase 1–4 trial capabilities across Australia and New Zealand.
The effective regulatory systems in Australia and New Zealand, featuring faster ethics approvals and supportive tax incentives, enable faster study initiation and adherence to global standards. Organizations like TGA and Medsafe offer guidance that aligns with ICH-GCP, drawing interest from international sponsors.
CROs in Australia and New Zealand are broadening service portfolios to include early-phase trials, decentralized study models, patient recruitment, data analytics, and post-market surveillance. For instance, in June 2025, Novatrials launched Phase 1 facility in Australia, offering full-spectrum clinical trial services, advanced infrastructure, expert staff, and diverse participant access, delivering speed, quality, and value to global sponsors.
Pharmaceutical and biotechnology companies dominate the market, which account for the majority of clinical trial outsourcing. Academic institutions, government research agencies, and medical device manufacturers form a smaller segment. High reliance on a few large sponsors drives competition among CROs, encouraging specialized services, efficiency, and strategic partnerships to secure long-term contracts and repeat business.
Type Insights
On the basis of type, in 2024, clinical segment held the largest market share in the market, accounting for a revenue share of 75.93%. The segment is driven by the region’s growing number of clinical trials and increasing demand for cost-efficient outsourcing solutions. Rising investments by pharmaceutical and biotechnology companies to accelerate drug development, coupled with supportive government initiatives and strong regulatory frameworks have contributed to clinical research activities. For instance, in January 2025, Government of Australia launched the Clinical Trial Enabling Infrastructure grant, offering USD 23.39 million to support innovative and registry-based trials, strengthening national research collaboration and advancing medical innovation across Australia.
The drug discovery segment is anticipated to witness the fastest growth during the forecast period. Rising investments in innovative therapeutics, biopharmaceutical R&D, and precision medicine are the key factors driving the segment’s growth. Besides, increasing collaboration between biotech startups and academic research institutions, along with government supports are contributing to market growth. In addition, advanced technologies such as AI-based drug design, high-throughput screening, and biomarker discovery further accelerate the efficiency and success rates.
Service Insights
On the basis of service, the clinical monitoring segment dominated the market with the largest revenue share in 2024 owing to increasing number of clinical trials and rising trend of outsourcing clinical research to CROs. This trend has gained momentum over the past decade due to the cost-effectiveness and technical expertise provided by such services. Due to the advent of smart analytics and real-time data acquisition devices, clinical monitoring data in the healthcare sector is expected to improve. The early detection of trial errors related to drug safety and toxicity through real-time data acquisition enables timely rectifications such as trial re-design or termination further contributing to segment growth.
The regulatory/medical affairs segment is expected to witness highest growth in the Australia & New Zealand healthcare contract research organization market. The outsourcing of regulatory affairs has increased significantly due to the rise in R&D activities, clinical trial applications, product registration, and drug pipeline. Rising demand for expert guidance on drug registration, clinical documentation, and post-approval surveillance is boosting CRO engagement in this domain. The expanding biotechnology and pharmaceutical sectors require robust regulatory strategy support to ensure faster market access and compliance with international standards.
Therapeutic Area Insights
On the basis of therapeutic area segment, in 2024, the oncology segment held the largest market share and is the fastest growing segment over the forecast period. In recent years, the field of oncology has witnessed a rise in R&D activities, with a focus on discovering new and more effective treatments for cancer. According to Australian Cancer Trials, at present total 47 clinical trials taking place for oncology research. This has led to a growing demand for CROs that specialize in oncology research in Australia and New Zealand. Pharmaceutical and biotech companies are utilizing CRO expertise for complex oncology studies involving immunotherapies, targeted therapies, and combination drugs. The adoption of adaptive trial designs and biomarker-based research enhances trial efficiency, strengthening the segment’s growth.
The respiratory diseases segment is anticipated to witness a lucrative growth across the forecast period in the Australia & New Zealand healthcare contract research organizations market. The high prevalence of respiratory diseases such as asthma, chronic obstructive pulmonary disease (COPD), and respiratory infections in Australia and New Zealand is expected to drive the segment growth. One in three individuals suffers from respiratory conditions. According to the report of National Asthma Council August 2025, in Australia respiratory diseases account for 10% of the disease burden but receive only 2% of research funding, limiting healthcare progress. This emphasizes the need for effective management, healthcare resources, and targeted interventions for asthma and COPD patients.
End-use Insights
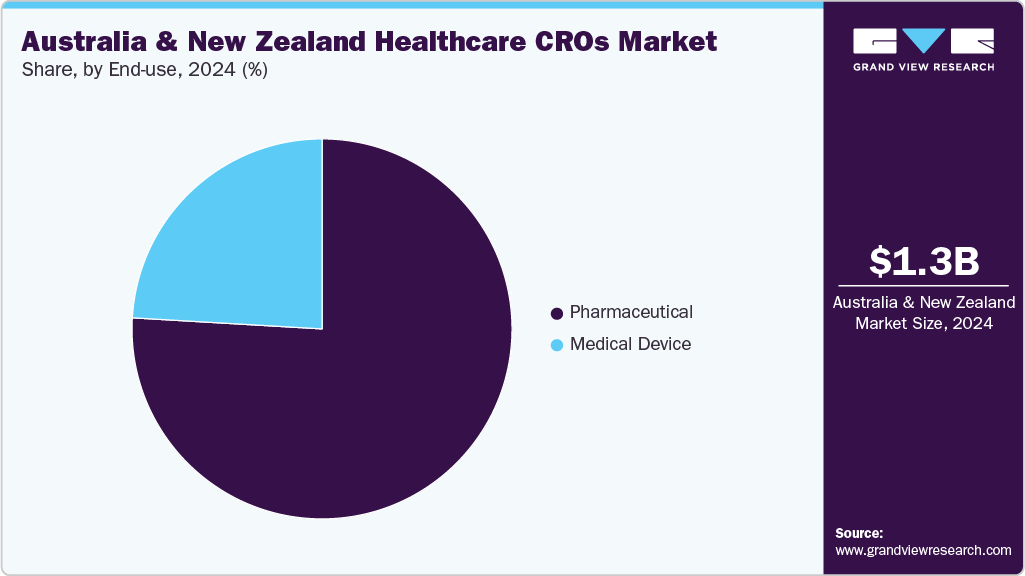
On the basis of end use, pharmaceutical companies segment accounted for the largest share in 2024. The segment is witnessing growth owing to rising R&D investments, increasing clinical trial complexity, and demand for innovative therapeutics. These companies increasingly outsource to CROs to optimize costs, accelerate timelines, and access specialized expertise in regulatory, bioanalytical, and clinical operations. The strong presence of multinational pharmaceutical firms, favorable government support for clinical research, and the region’s high-quality healthcare infrastructure further drives the segment growth.
 To learn more about this report, Download Free Sample Report
The medical device companies’ segment is anticipated to witness a steady growth rate over the forecast period, fueled by rising demand for advanced diagnostic and therapeutic technologies. The region’s strong regulatory framework, skilled workforce, and expanding clinical research infrastructure attract device manufacturers seeking efficient trial execution and compliance support. Increasing innovation in wearable health tech, implantable devices, and digital health solutions has boosted outsourcing to CROs for design validation, regulatory submissions, and post-market surveillance.
Key Australia & New Zealand Healthcare CROs Company Insights
Key players in the Australia and New Zealand healthcare CRO market include Novotech, Parexel, ICON, Syneos Health, and Covance, dominating with comprehensive clinical trial services. Strategic mergers, acquisitions, and technological investments enhance market share, enabling these companies to deliver end-to-end solutions, expand regional presence, and cater to growing demand from pharmaceutical and biotechnology sponsors. For instance, in June 2024, Novotech launched a dedicated Early Phase Strategic Delivery Unit in Australia and New Zealand, leveraging rapid start-up, streamlined regulations, and scientific excellence. This unit strengthens Phase I trial delivery, enabling biotech clients to accelerate early-phase development and seamlessly transition into later-phase global studies, reinforcing Novotech’s commitment to innovative clinical solutions.
Key Australia & New Zealand Healthcare CROs Companies:
- PAREXEL International Corporation
- Thermo Fischer Scientific, Inc.
- SGS SA
- ICON plc
- Medpace Australia Pty. Ltd
- Charles River Laboratories International, Inc.
- IQVIA
- Novotech
- Laboratory Corporation of America Holdings
- Syneos Health
Recent Developments
-
In March 2025, Novotech secured significant investment from GIC, Temasek, and reinvestment from TPG to accelerate global expansion. The funding will support organic growth, transformative M&A, and scaling operations in Asia Pacific, the US, and Europe. This positions Novotech to strengthen its leadership as a global biotech-focused CRO.
-
In November 2024, Novotech formed a long-term strategic partnership with Biostar Pharmaceuticals following Biostar’s HKEX listing, supporting oncology and synthetic biology clinical development in China. The collaboration leverages Novotech’s technical platforms to advance drug innovation, enabling both companies to accelerate research, expand international reach, and bring novel therapeutics to a global patient population
-
In January 2024, ClinChoice expanded its footprint in Southeast Asia, Australia, and New Zealand by acquiring CSI Medical Research, enhancing full-service capabilities across 30+ countries. The acquisition leverages CSI’s regional expertise, regulatory knowledge, and infrastructure, enabling ClinChoice to deliver innovative, cost-effective clinical research solutions and accelerate global trial execution.
Australia & New Zealand Healthcare CROs Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.45 billion
Revenue forecast in 2033
USD 3.35 billion
Growth rate
CAGR of 11.02% from 2025 to 2033
Actual data
2021 - 2024
Forecast period
2025 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2025 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, service, therapeutic area, end-use
Country scope
Australia & New Zealand
Key companies profiled
PAREXEL International Corporation, Thermo Fischer Scientific, Inc., SGS SA, ICON plc, Medpace Australia Pty. Ltd, Charles River Laboratories International, Inc., IQVIA, Novotech, Laboratory Corporation of America Holdings, Syneos Health
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Australia & New Zealand Healthcare CROs Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Australia & New Zealand healthcare CROs market report based on type, service, therapeutic area, and end-use.
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Drug Discovery
-
Target Validation
-
Lead Identification
-
Lead Optimization
-
-
Pre-clinical
-
Clinical
-
Phase I Trial Services
-
Phase II Trial Services
-
Phase III Trial Services
-
Phase IV Trial Services
-
-
-
Service Outlook (Revenue, USD Million, 2021 - 2033)
-
Project Management/Clinical Supply Management
-
Data Management
-
Regulatory/Medical Affairs
-
Medical Writing
-
Clinical Monitoring
-
Quality Management/ Assurance
-
Bio-statistics
-
Investigator Payments
-
Laboratory
-
Sterility Testing
-
Container/Closure Testing
-
Extractables and Leachable Testing
-
Environmental Monitoring (Including Microbiology Testing)
-
Disinfectant Efficacy Studies
-
Others
-
-
Patient And Site Recruitment
-
Technology
-
Others
-
-
Therapeutic Area Outlook (Revenue, USD Million, 2021 - 2033)
-
Oncology
-
CNS Disorders
-
Infectious Diseases
-
Immunological Disorders
-
Cardiovascular Diseases
-
Respiratory Diseases
-
Diabetes
-
Ophthalmology
-
Pain Management
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical
-
Small Molecules
-
Biologics
-
-
Medical Device
-
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


