
- Home
- »
- Advanced Interior Materials
- »
-
Automotive Polymer Composites Market Report, 2026-2033GVR Report cover

Automotive Polymer Composites Market (2026 - 2033)
Size, Share & Trend Analysis Report By Material, By Product, By Application, By End Use, By Manufacturing Process, By Region, And Segment Forecasts
Market Size, 2025
$11.4BMarket Estimate, 2026
$12.0BMarket Forecast, 2033
$16.9BCAGR, 2026–2033
5.0%Automotive Polymer Composites Market Summary
The global automotive polymer composites market size was valued at USD 11.4 billion in 2025 and is projected to grow from USD 12.0 billion in 2026 to USD 16.9 billion in 2033, at a CAGR of 5.0% from 2026 to 2033. Europe market held the largest revenue share of approximately 36.5% in 2025. The market is experiencing growth driven by rising demand for lightweight vehicles, increased adoption of electric vehicles, and advancements in manufacturing processes. This trend is fueled by the need for reduced vehicle weight, improved fuel efficiency, and enhanced safety features.
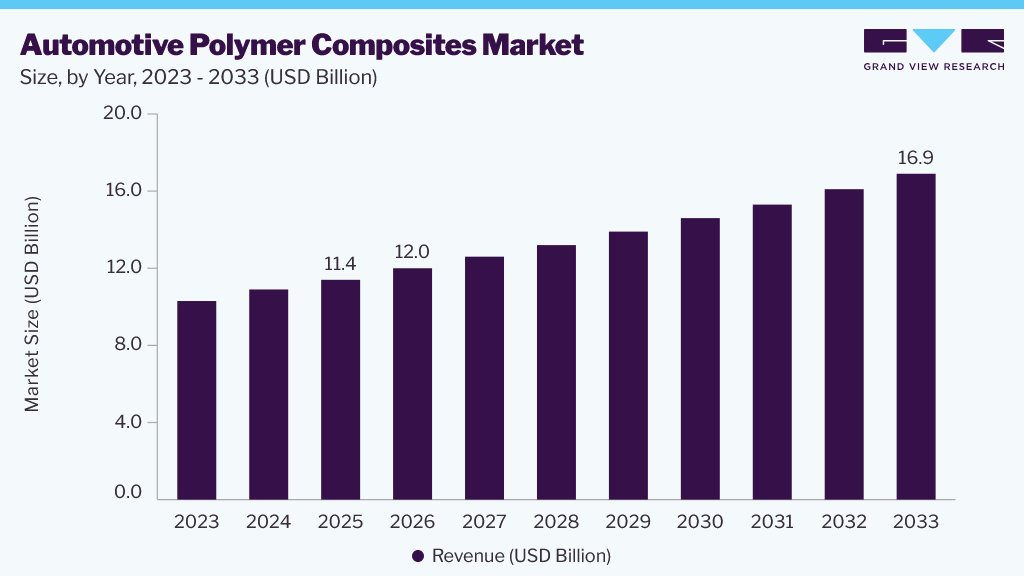 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The glass fiber reinforced polymer composite segment held the largest market share of around 65.0% in 2025.
- By material: The polyester segment held the largest market share of around 25.0% in 2025.
- By application: Exterior components led the market and accounted for a share of around 34.0% in 2025.
Regional Highlights
- Largest regional market: Europe (36.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 11.4 Billion
- Estimated market size in 2026: USD 12.0 Billion
- Projected market size by 2033: USD 16.9 Billion
- CAGR (2026-2033): 5.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The automotive industry is undergoing a significant transformation, with a strong emphasis on lightweight materials to enhance fuel efficiency and performance. As a result, polymers are playing a leading role in this shift, gradually replacing traditional materials such as steel and aluminum in lightweight vehicles. Car manufacturers are leveraging pre-pregs, a type of polymer composite, to substitute metals in both interior and exterior components, thereby reducing weight and improving performance and safety.
The increasing adoption of electric vehicles is also driving the demand for lightweight materials. By reducing the vehicle body's weight, electric cars can use smaller batteries without compromising driving range. Moreover, reducing the weight of the vehicle body and battery pack has a cumulative effect on overall vehicle weight, enabling the downsizing of other components, such as the brake system and drivetrain. In internal combustion engine vehicles, reduced weight leads to lower emissions and improved performance with the same power and torque levels.
Advancements in polymer composite production technology have also contributed to their growth, as manufacturing costs have decreased, making them more economical than traditional materials. Furthermore, governments worldwide are implementing stricter regulations on automakers regarding emissions and fuel efficiency, which is driving the adoption of lightweight materials such as polymer composites. As a result, the use of polymer composites is expected to continue to grow in the automotive industry, enabling manufacturers to meet evolving regulatory requirements while improving vehicle performance and safety. For instance, in August 2025, BMW Group announced that natural-fiber composite materials had reached series-production readiness and would be incorporated into future vehicle models. The company stated that these lightweight composite materials meet stringent automotive safety and homologation requirements while helping reduce vehicle weight and associated CO₂ emissions. BMW highlighted that the technology, developed through years of research and testing, supports the industry's efforts to comply with increasingly stringent environmental regulations while improving vehicle efficiency and sustainability.
Analyst Perspective
The market is projected to grow rapidly. Automakers are focusing on strategies to improve fuel efficiency, lower emissions, and boost vehicle performance. Polymer composites are becoming popular alternatives to traditional materials like steel and aluminum. They offer a high strength-to-weight ratio, design flexibility, and corrosion resistance. The fast growth of the electric vehicle (EV) market is increasing demand, as lightweight materials can extend driving range and improve battery efficiency. Ongoing improvements in polymer processing technologies are lowering production costs, making these composites more widely available for mass-market vehicles. Strict global rules on fuel economy and carbon emissions are also pushing manufacturers to use new lightweight materials. In the future, the growing emphasis on sustainable mobility, vehicle electrification, and performance improvement should continue to drive the use of automotive polymers in both conventional and electric vehicle markets.
Material Insights
The polyester segment held the largest market share of around 25.0% in 2025, due to its lightweight, high-strength, and durable properties, which enhance fuel efficiency and reduce emissions. Advancements in manufacturing processes have made polyester composites more cost-effective and suitable for various automotive applications, driving demand for sustainable materials.
Vinyl ester is expected to register the fastest CAGR over the forecast period, aided by its unique combination of properties, including high strength, corrosion resistance, and durability. Vinyl ester resins offer excellent adhesion to reinforcements, enabling the creation of lightweight yet strong composite materials, making them a popular choice for automotive applications.
Product Insights
The glass fiber reinforced polymer composite segment held the largest market share of around 65.0% in 2025. Glass fiber composites are a staple in the automotive polymer industry, boasting high strength, stiffness, flexibility, and chemical resistance. With a focus on lightweight materials to improve fuel efficiency and meet emission regulations, glass fiber composites are a popular choice due to their affordability compared to carbon and natural fibers, making them widely used in the automotive industry.
Carbon fiber-reinforced polymer composite is projected to grow at the fastest CAGR over the forecast period due to its strength and durability. Carbon fibers are manufactured through the precise alignment of carbon atoms along the fiber’s length, requiring specialized equipment and skilled labor. Despite their high production costs, carbon fibers offer exceptional durability and are often preferred for automotive applications. Crashworthiness is a critical consideration in material selection for lightweight automotive components. For instance, in November 2025, Land Rover unveiled the 2026 Range Rover Sport SV Carbon, featuring forged carbon accents, optional carbon-fiber wheels, and carbon-ceramic brakes. According to the company, the use of carbon-fiber components contributes to significant weight savings while maintaining structural performance and vehicle dynamics. This development highlights the growing adoption of CFRP materials in premium vehicles to improve performance and efficiency and reduce vehicle weight.
Application Insights
Exterior components led the market, accounting for around 34.0% in 2025. Automotive composites are widely used in exterior components, including headlamps and heat shielding parts. OEMs are increasingly incorporating composites into car bodies, with recent advancements showcasing the potential of reinforced thermoplastics. Notably, BMW’s i3 is the first mass-produced car to extensively use thermoplastic composites, particularly in exterior components, marking a significant milestone in the industry.
Interior components are expected to grow significantly during the forecast period. Composites offer a comprehensive solution to industry challenges, including lightweighting, design versatility, safety, cost-efficiency, sustainability, and regulatory compliance. By providing enhanced design flexibility, composites enable the creation of complex, customized interior components, allowing unique shapes and textures that enhance the overall visual appeal of vehicles.
End Use Insights
Conventional vehicles accounted for the largest market revenue share of about 48.5% in 2025. The growing demand for fuel-efficient, stylish, and safe vehicles aligns with the benefits of composite materials. As the automotive sector prioritizes innovation and sustainability, composites emerge as a compelling choice for car manufacturers. With technological advancements and shifting consumer preferences, the widespread adoption of composites in traditional vehicles is expected to increase. For instance, in August 2025, SGL Carbon supplied flax-fiber-based prepreg materials, developed in collaboration with the Swiss cleantech company Bcomp, to the Japanese motorsport firm Tras Ltd. for use in constructing a natural-fiber composite body for a Toyota Hilux rally vehicle competing in the Asia Cross Country Rally (AXCR) in Thailand. The lightweight composite components were developed to reduce weight while maintaining strength and durability, demonstrating how advanced composite materials are increasingly being adopted in conventional vehicle platforms to improve performance and efficiency.
The electric vehicles segment is expected to register the fastest CAGR during the forecast period. Electric vehicles, incorporating cutting-edge automotive technologies and lightweight components, rely heavily on composites in their manufacturing process. The electric vehicle sector demands distinctive features such as lightweight crash safety and seamless integration with the Internet of Things, making composites a crucial element in meeting these exacting requirements.
Manufacturing Process Insights
Compression molding dominated the market in 2025 with the largest revenue share of around 32.0%. Compression molding is a prominent manufacturing process for producing complex, robust fiberglass reinforcements in large volumes under high pressure. This technique offers the ability to produce intricate, sizable components with fewer knit lines and reduced fiber degradation compared to injection molding, making it a preferred method for industrial applications.
The injection molding segment is projected to grow at a notable CAGR over the forecast period. The process involves injecting hot plastic materials into a mold, allowing them to solidify and produce molded items. Primary raw materials include polyethylene, polypropylene, polyurethane, and others, which are used to create lightweight automotive components that offer significant advantages, including reduced weight and improved fuel efficiency.
Regional Insights
Europe automotive polymer composites market dominated the global market with a revenue share of approximately 36.5% in 2025. The European automotive industry is a significant sector, accounting for a substantial share of global production. The European Union’s member states collectively rank among the world’s top motor vehicle manufacturers, with the industry investing heavily in research and development. The need for automotive polymer composites has arisen from the increasing demand for fuel-efficient, lightweight vehicles.
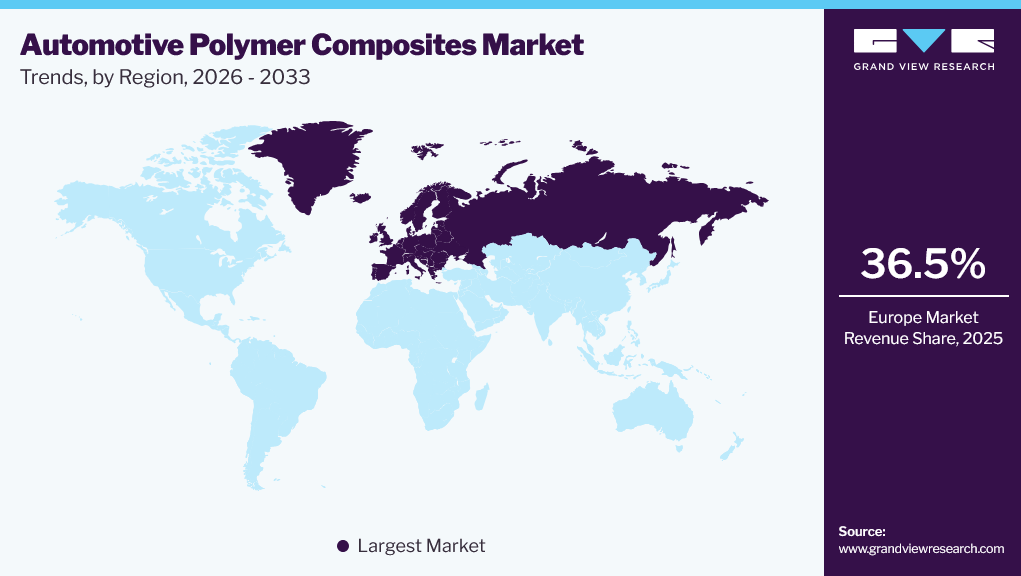 To learn more about this report, Download Free Sample Report
Germany Automotive Polymer Composites Market Trends
The automotive polymer composites market in Germany dominated Europe in 2025. Germany’s market is expected to remain robust, driven by growing consumer awareness of eco-friendly options. The market’s growth prospects are fueled by the increasing adoption of environmentally sustainable automotive composites. German OEMs are also aligning with government initiatives by focusing on natural composites.
North America Automotive Polymer Composites Market Trends
The automotive polymer composites market in North America was identified as a lucrative segment of the global market in 2025. Market growth in the region is driven by increased vehicle production, rising demand for lightweight materials, and the expansion of the electric vehicle sector. Technological innovations and government initiatives promoting sustainable materials also contribute to the market’s growth, creating a favorable environment for expansion.
The U.S. automotive polymer composites market is expected to grow rapidly in the coming years. The country’s automotive sector’s significant vehicle production demands substantial materials, including polymer composites. The presence of leading OEMs and suppliers fosters research and development in composite materials and applications. The U.S. is at the forefront of innovating composite materials and manufacturing techniques, such as CFRTP and AFP, driving industry advancements.
Asia Pacific Automotive Polymer Composites Market Trends
The automotive polymer composites market in the Asia Pacific is anticipated to witness the fastest growth over the forecast period. The Asia-Pacific region is driving market growth, with China, India, and Thailand leading the way due to their large vehicle populations. India and China are expected to dominate the four-wheeler market, fueling further growth. The North American market is also receiving government support for energy-efficient automotive composites, particularly natural-fiber composites.
China automotive polymer composites market held a substantial market share in 2025. China is the world’s largest automotive market, with substantial vehicle production, driving demand for materials such as polymer composites. The growing Chinese middle class fuels demand for new vehicles, while China’s competitive labor costs attract component manufacturers, including those producing polymer composites. A well-established supply chain network ensures efficient sourcing of raw materials and components.
Key Automotive Polymer Composites Company Insights
Some key companies in the market include BASF, Covestro AG, DuPont, Gurit Services AG, and Hexcel Corporation. Companies are focusing on expanding their customer base to gain a competitive edge, driving strategic initiatives such as mergers, acquisitions, and collaborations with industry leaders.
- Plasan is a specialist provider of composite-based survivability and protection solutions for defense and security vehicles. The company develops lightweight ballistic protection systems, composite armor solutions, and integrated survivability technologies that enhance vehicle safety without significantly increasing vehicle weight. While primarily focused on defense applications, Plasan’s advanced composite technologies demonstrate the broader use of high-performance materials in specialized mobility platforms requiring extreme durability and protection.
- Hexcel Corporation is a provider of advanced composites, offering a diverse range of products, including carbon fibers, reinforcements, prepregs, and matrix materials. Its solutions serve the commercial aerospace, space, defense, and industrial sectors, enhancing the performance, efficiency, and reliability of a range of applications.
Key Automotive Polymer Composites Companies
The following key companies have been profiled for this study on the automotive polymer composites market:
-
BASF
-
Covestro AG
-
DuPont
-
Gurit Services AG
-
Hexcel Corporation
-
Johns Manville. A Berkshire Hathaway Company.
-
KOLON Corp.
-
Mitsubishi Chemical Group Corporation
-
Owens Corning
-
Plasan
Recent Developments
-
In June 2026, Toray Performance Materials launched Stratex 2300r, a patent-pending carbon-fiber composite containing post-consumer recycled PET (rPET). The company stated that the material achieves performance parity with conventional virgin-material composites while improving sustainability. Such innovations are expected to support automotive manufacturers seeking lightweight materials that help meet increasingly stringent emissions and sustainability targets.
-
In April 2025, BASF showcased advanced material solutions for automotive applications at CHINAPLAS 2025, including circular and bio-based engineering plastics, polyurethane systems, and lightweight composites. These materials were demonstrated in collaboration with automotive OEMs such as Hyundai-Kia, including the Kia EV3 study car, in which multiple BASF materials contributed to reduced CO₂ emissions and enhanced performance.
Automotive Polymer Composites Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.4 billion
Estimated market size in 2026
USD 12.0 billion
Projected market size by 2033
USD 16.9 billion
Growth rate
CAGR of 5.0% from 2026 to 2033
Actual data
2021 – 2025
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, product, application, end use, manufacturing process, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; China; Japan; India; South Korea; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
BASF; Covestro AG; DuPont; Gurit Services AG; Hexcel Corporation; Johns Manville. A Berkshire Hathaway Company; KOLON Corp.; Mitsubishi Chemical Group Corporation; Owens Corning; Plasan
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Polymer Composites Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2023 to 2033. For this study, Grand View Research has segmented the global automotive polymer composites market report based on material, product, application, end use, manufacturing process, and region:
-
Material Outlook (Revenue, USD Million, 2023 - 2033)
-
Epoxy
-
Polyurethane
-
Polyamide
-
Polypropylene
-
Polyethylene
-
Polyester
-
Vinyl Ester
-
Others
-
-
Product Outlook (Revenue, USD Million, 2023 - 2033)
-
Glass Fiber Reinforced Polymer Composite
-
Natural Fiber Reinforced Polymer Composite
-
Carbon Fiber Reinforced Polymer Composite
-
-
Application Outlook (Revenue, USD Million, 2023 - 2033)
-
Interior Components
-
Exterior Components
-
Structural Components
-
Powertrain Components
-
-
End Use Outlook (Revenue, USD Million, 2023 - 2033)
-
Conventional Vehicles
-
Electrical Vehicles
-
Trucks & Buses
-
-
Manufacturing Process Outlook (Revenue, USD Million, 2023 - 2033)
-
Compression Molding
-
Injection Molding
-
Sheet Molding
-
Resin Transfer Molding
-
-
Regional Outlook (Revenue, USD Million, 2023 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
Europe dominated with a 36.5% revenue share in 2025.
Conventional vehicles accounted for the largest market revenue share of about 48.5% in 2025.
The global automotive polymer composites market size was valued at USD 11.4 billion in 2025 and is estimated at USD 12.0 billion for 2026.
The global automotive polymer composites market is expected to grow at a CAGR of 5.0% from 2026 to 2033, reaching USD 16.9 billion by 2033.
Key players include BASF, Covestro AG, DuPont, Gurit Services AG, Hexcel Corporation, Johns Manville. A Berkshire Hathaway Company, KOLON Corp., Mitsubishi Chemical Group Corporation, Owens Corning, Plasan, and others.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


