
- Home
- »
- Automotive & Transportation
- »
-
Automotive Seats Market Size, Share & Trends Report, 2033GVR Report cover

Automotive Seats Market (2026 - 2033)
Size, Share & Trends Analysis Report By Seat (Bench, Bucket) By Material (Genuine Leather, Synthetic Leather) By Technology, By Vehicle, By Sales Channel, By Region, And Segment Forecasts
Market Size, 2025
$65.6BMarket Estimate, 2026
$68.3BMarket Forecast, 2032
$98.5BCAGR, 2026–2032
5.4%Automotive Seats Market Summary
The global automotive seats market size was valued at USD 65.6 billion in 2025 and is projected to grow from USD 68.3 billion in 2026 to USD 98.5 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 46.1% in 2025. Rising integration of lightweight, modular, and smart seating technologies is fueling the growth of the automotive seats market.
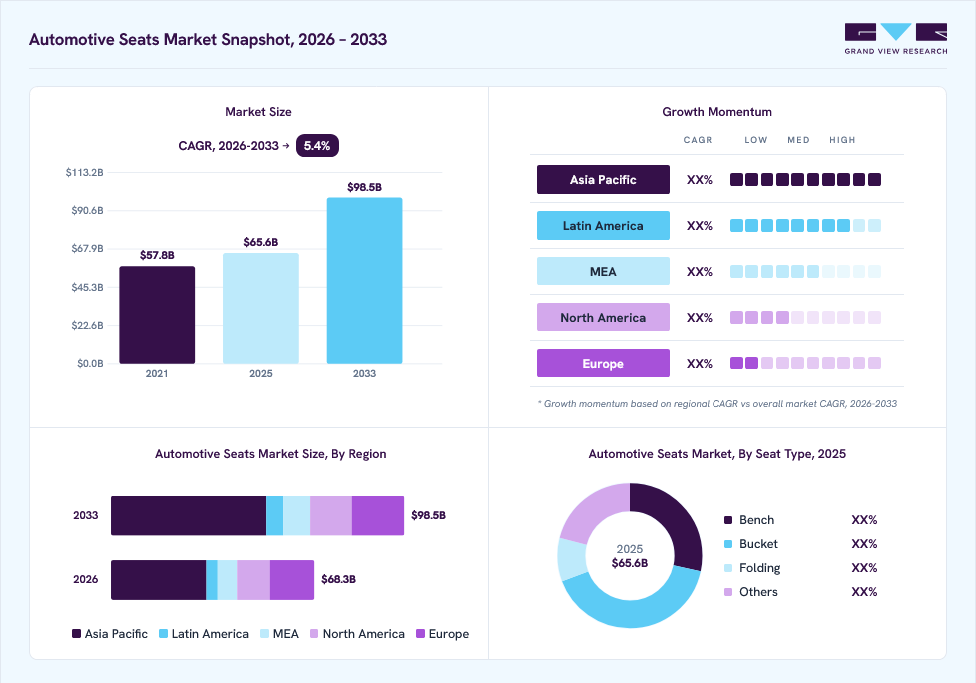 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By seat: Bucket segment led the market and accounted for 40.8% share in 2025
- By material: Fabric segment led the market and accounted for 44.5% share in 2025.
- By technology: Manual seats segment accounted for the largest share in 2025.
- By vehicle: Passenger cars segment accounted for the largest revenue share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (46.1% revenue share, 2025)
- By country: China held the largest share of Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 65.6 Billion
- Estimated market size in 2026: USD 68.3 billion
- Projected market size by 2033: USD 98.5 Billion
- CAGR (2026-2033): 5.4%
Prism AI by Grand View Research Free to tryAsk a question about the automotive seats marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The growing adoption of modular automotive seating systems is reshaping vehicle interior development. Automakers are increasingly adopting modular seat platforms to enable greater customization, improve manufacturing efficiency, and reduce development costs. These seating systems integrate advanced comfort features such as adaptive support, heating, ventilation, and massage while using lightweight, recyclable materials. Moreover, modular seating is emerging as a key trend supporting personalized mobility and sustainable vehicle interiors in the market.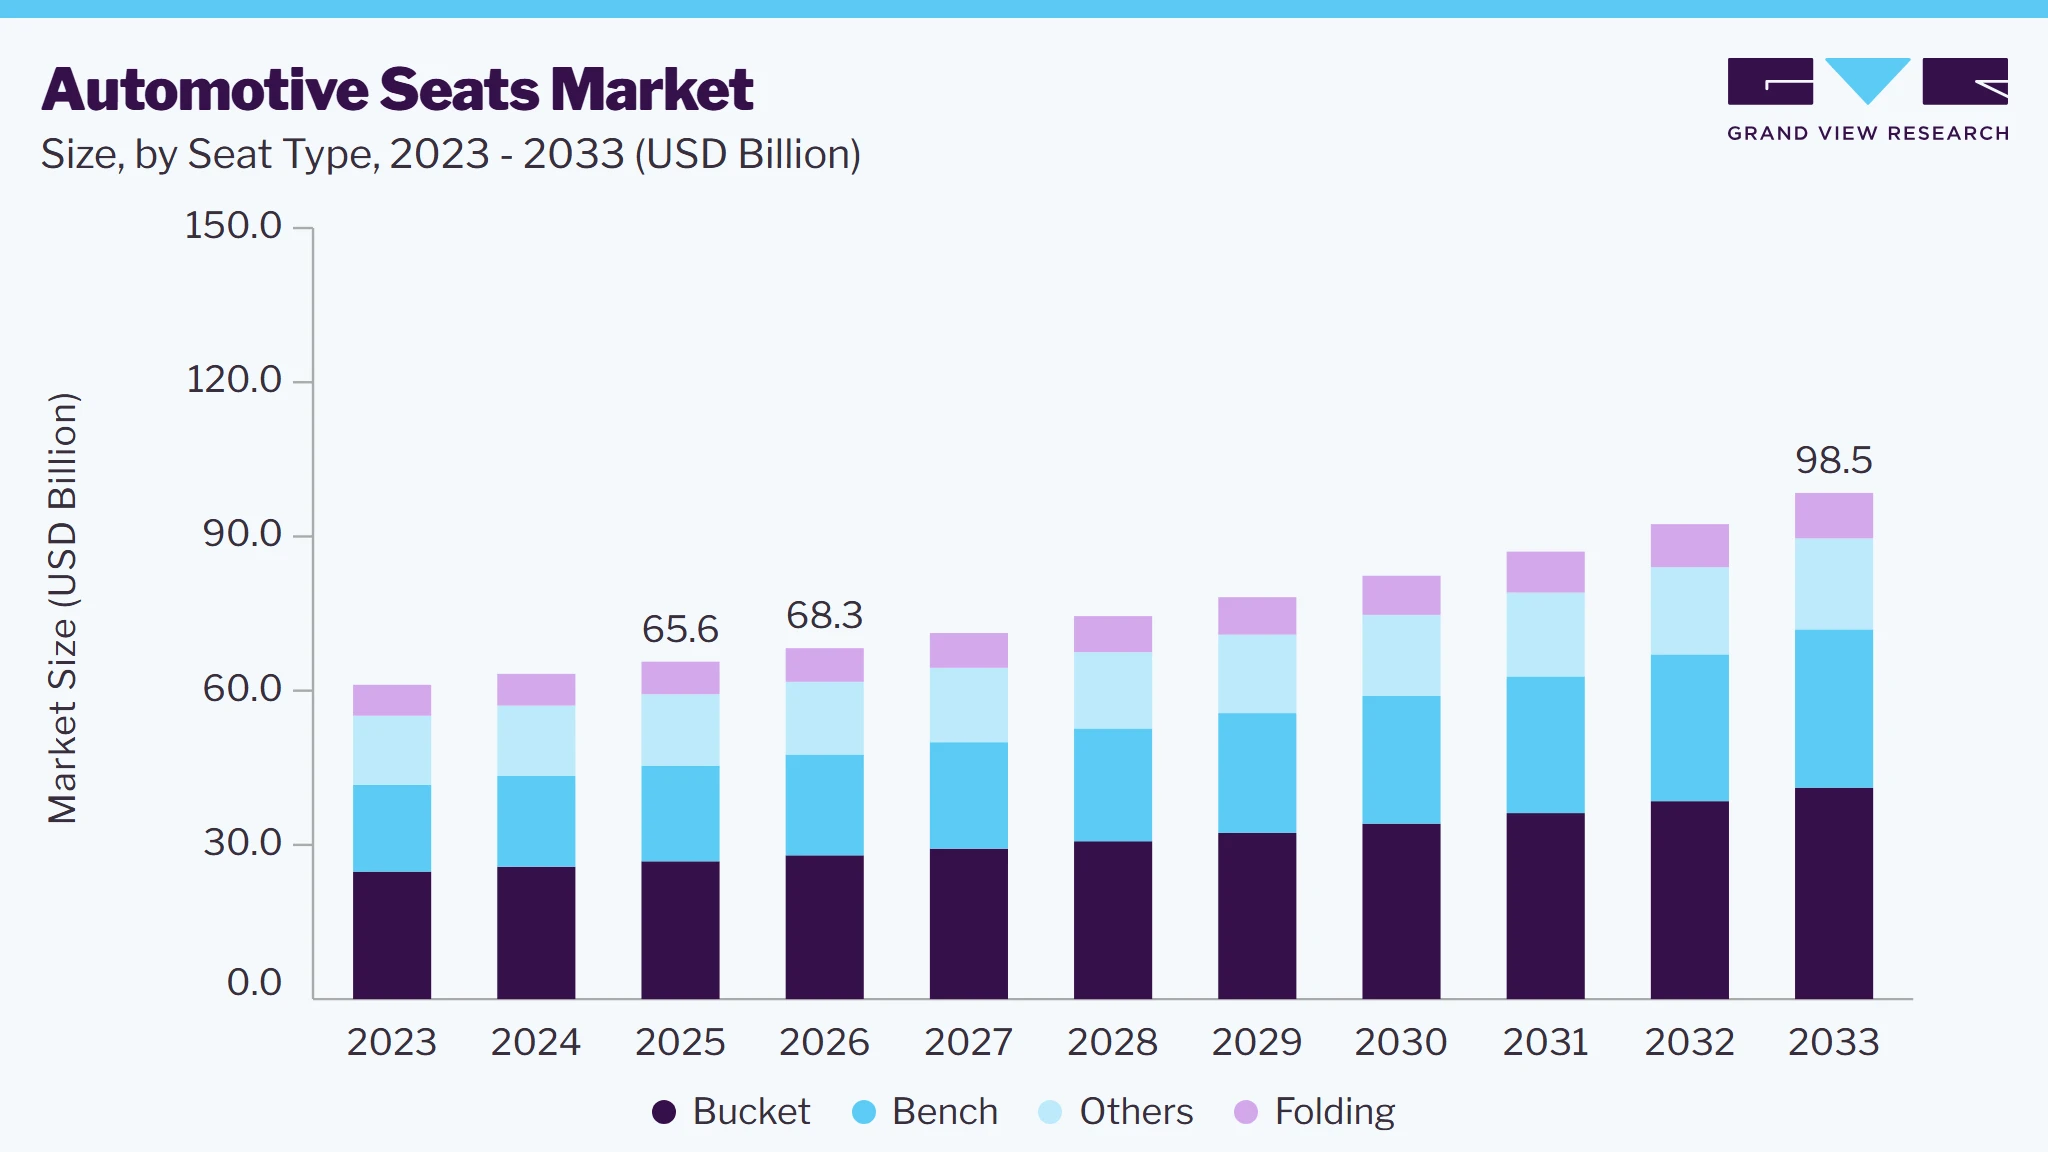 To learn more about this report, Download Free Sample Report
The increasing focus on child occupant safety is encouraging regulatory authorities to introduce stricter vehicle safety requirements. According to the NHTSA, FMVSS No. 213a was introduced to improve child safety in side-impact collisions. The regulation requires child restraint systems for children weighing under 40 pounds to pass a new 30 mph side-impact crash test. This requirement helps improve crash protection by reducing impact forces and preventing harmful contact with vehicle structures.
Automotive seat quality inspection is challenging due to the complexity of modern seating systems. As seating systems incorporate more complex components, advanced inspection processes are required to monitor test parameters and ensure consistent product quality. This complexity, combined with a shortage of skilled inspection personnel, increases manufacturing challenges and operational costs. Moreover, manufacturers must invest in automated inspection technologies to maintain product quality and comply with safety standards.
Market Dynamics
The automotive seats market is evolving as vehicle manufacturers increasingly prioritize occupant comfort, safety, lightweight construction, and intelligent cabin experiences. Growing production of passenger vehicles, rising electrification, premium-vehicle demand, and stringent safety regulations are driving continuous innovation in seating systems. At the same time, advancements in lightweight materials, integrated electronics, thermal comfort technologies, and smart seating functions are reshaping product development strategies. OEMs and seat manufacturers are investing in modular platforms and digitally integrated seating solutions to improve vehicle efficiency while enhancing passenger experience.
The automotive industry is experiencing growing consumer preference for vehicles that provide superior comfort, ergonomics, and premium interior features. Increasing disposable income, expanding SUV and luxury vehicle sales, and changing customer expectations have elevated vehicle seating from a basic functional component to a major purchasing consideration. Consumers increasingly evaluate vehicles based on long-distance comfort, seating flexibility, lumbar support, ventilation, and heating functions. This trend is particularly evident in electric vehicles, where cabin experience has become a key product differentiator.
Automotive seat manufacturers are responding by developing ergonomically optimized seats incorporating memory functions, massage systems, active climate control, lightweight structures, and intelligent adjustment mechanisms. OEMs are integrating premium seating technologies across mid-range vehicle platforms rather than limiting them to luxury segments. Modular seat architecture enables manufacturers to offer multiple comfort configurations while reducing production complexity. These innovations increase seat value per vehicle and support sustained revenue growth across global automotive seating markets.
Automotive seating systems increasingly utilize advanced foams, high-strength steel, aluminum alloys, genuine leather, synthetic materials, electronic actuators, sensors, and thermal comfort components. Fluctuating prices of metals, polymers, leather, semiconductors, and specialty textiles significantly increase manufacturing costs. At the same time, OEMs continue to exert pricing pressure on suppliers, reducing opportunities for cost recovery. The addition of smart seating electronics further increases component complexity and production expenses.
Higher production costs particularly affect entry-level vehicles, where affordability remains the primary purchasing criterion. Manufacturers serving emerging economies often delay adoption of premium seating technologies to maintain competitive vehicle pricing. Smaller suppliers face greater challenges investing in advanced manufacturing automation and lightweight material development. Moreover, cost pressures slow the penetration of technologically advanced seating systems in price-sensitive vehicle segments and limit overall market expansion.
Rapid digitalization of vehicle interiors is creating significant opportunities for intelligent seating systems to improve comfort, safety, and personalized user experiences. The increasing adoption of connected vehicles, software-defined vehicles, and advanced driver assistance systems is enabling seats to serve as integrated electronic platforms rather than passive components. Sensor technologies, biometric monitoring, occupancy detection, posture recognition, and AI-enabled personalization are expanding the functional scope of automotive seating.
Conducting seating manufacturers are investing in intelligent seating platforms that integrate health monitoring, adaptive comfort controls, memory profiles, and seamless communication with vehicle operating systems. Premium passenger vehicles and electric vehicles are expected to be the primary adopters of these technologies before they are widely deployed in mass-market vehicles. Suppliers with expertise in electronics integration, software capabilities, and modular seating platforms are well-positioned to capture this expanding market opportunity while strengthening long-term OEM partnerships.
Market Concentration & Characteristics
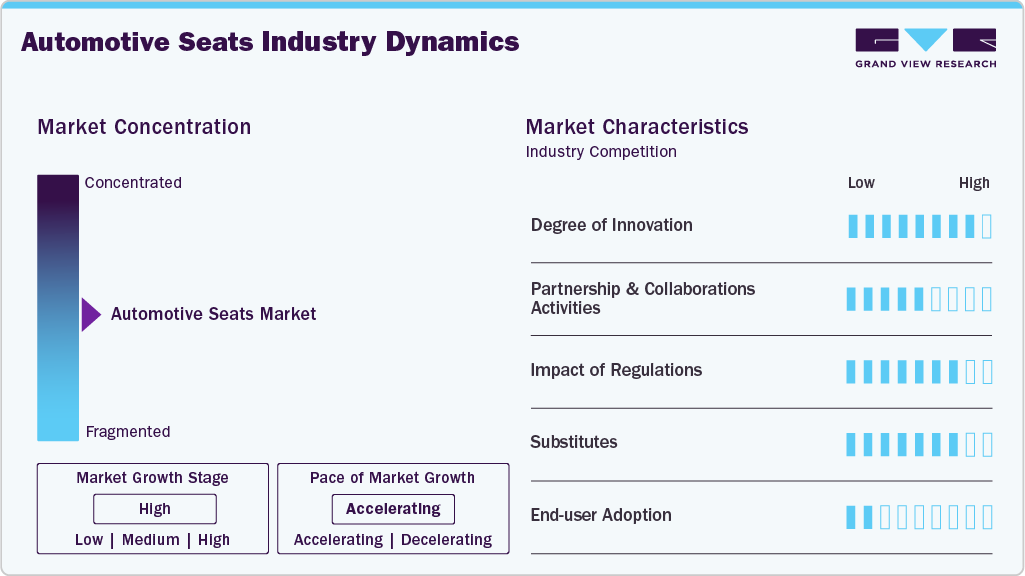
The automotive seats market is moderately fragmented due to the presence of numerous global and regional seating manufacturers offering standard passenger seats, premium seats, commercial vehicle seats, and customized seating solutions for passenger cars, SUVs, trucks, and other vehicles. Companies are focusing on expanding manufacturing capabilities, developing lightweight and comfortable seating systems, and investing in sustainable materials, modular designs, intelligent seating features, and advanced safety solutions. As vehicle production, SUV demand, and electric vehicle adoption continue to increase worldwide, manufacturers compete through product quality, customization capabilities, OEM partnerships, technological innovation, and cost-efficient manufacturing rather than market concentration.
 To learn more about this report, Download Free Sample Report
Moderate market concentration is further supported by the strong presence of established companies such as Lear Corp., Adient plc, FORVIA, Magna International Inc., TOYOTA BOSHOKU CORPORATION, and NHK SPRING Co., Ltd., which continue to strengthen their market positions through product development, strategic collaborations, manufacturing expansion, and global OEM relationships. At the same time, companies such as TS TECH Co., Ltd., and GENTHERM are expanding their presence by offering specialized seating solutions for passenger vehicles, SUVs, commercial vehicles, and electric vehicles. Market participants primarily compete on seating comfort, ergonomic design, lightweight construction, durability, safety, material quality, customization capabilities, smart seating features, after-sales support, and long-term supply agreements with vehicle manufacturers, thereby maintaining the moderately fragmented nature of the automotive seats market.
Analyst Perspective
The automotive seats market is transitioning from conventional seating production toward intelligent, lightweight, and highly integrated seating solutions that enhance both occupant comfort and vehicle efficiency. Rising vehicle electrification, growing demand for premium interiors, and stricter safety requirements continue to drive innovation in seating technologies. Smart seating equipped with sensors, climate control, and personalized adjustment capabilities is expected to become a major competitive differentiator during the forecast period. Investment is increasingly directed toward modular manufacturing platforms, sustainable materials, and software-enabled seating systems. Competition is also shifting toward strategic collaborations between OEMs and seating suppliers, with a focus on electronics integration, lightweight engineering, and advanced occupant-experience technologies.
Seat Insights
The bucket seats segment accounted for 40.8%, the largest share of global revenue in 2025. This dominance is driven by the increasing demand for enhanced seating comfort and ergonomic support in passenger vehicles. Compared to bench seats, bucket seats provide better individual support and feature a two-seat configuration with a center console, improving occupant comfort and convenience. As automakers continue to prioritize comfort-oriented vehicle interiors, the adoption of bucket seats is supporting the growth of the industry.
The bench seat segment is projected to grow at the fastest CAGR over the forecast period. The growth is driven by the increasing demand for higher passenger seating capacity and flexible interior configurations in family and commercial vehicles. To address these requirements, manufacturers are introducing bench seats with fold-down armrests, 60/40 split-folding backrests, and ski hatches that improve both passenger comfort and cargo flexibility. These functional seating configurations are increasing the adoption of bench seats and boosting the growth of the automotive seats market.
Material Insights
The fabric segment accounted for 44.5%, the largest share of global revenue in 2025. The segment is driven by the growing demand for comfortable, durable, and cost-effective seating materials, as consumers increasingly prefer practical and visually appealing vehicle interiors. Furthermore, automakers are expanding the availability of fabric seating solutions across multiple vehicle models to meet varied consumer preferences and price requirements. This continued focus on affordable and comfortable interior materials is supporting the growth of the automotive seats market.
The synthetic leather segment is projected to grow at the fastest CAGR over the forecast period. The rising adoption of sustainable and high-performance upholstery materials in automotive interiors is driving the growth of the segment. Synthetic leather offers durability, breathability, and improved tactile properties, making it a suitable alternative to conventional upholstery materials. Moreover, manufacturers are introducing water-based, solvent-free, and bio-based synthetic leather solutions that meet environmental standards while maintaining product performance. These innovations are accelerating the adoption of synthetic leather in automotive seating applications.
Technology Insights
The manual seats segment accounted for the largest share of global revenue in 2025. The growing demand for cost-effective and durable seating systems is driving the manual seats segment. Manual seats are increasingly adopted in entry-level passenger cars and commercial vehicles due to their low manufacturing cost, lightweight construction, and simple mechanical design. Automakers address this demand by offering mechanically adjustable seats that reduce maintenance requirements and minimize the risk of component failure. These advantages continue to support the adoption of manual seats and contribute to the automotive seats market growth.
The smart seats segment is projected to grow at the fastest CAGR over the forecast period. The increasing demand for occupant safety is driving the growth of the smart seats segment. As automakers prioritize advanced safety features to reduce injuries and improve passenger protection, smart seats are gaining wider adoption across new vehicle models. These seating systems use sensors and algorithms to monitor seat occupancy, verify seat belt usage, and integrate features such as smart headrests, wraparound airbags, and intelligent child restraint systems to enhance occupant protection.
Vehicle Insights
The passenger cars segment accounted for the largest market revenue share in 2025 and is projected to grow at the fastest CAGR over the forecast period, driven by the increasing production and sales of passenger vehicles, particularly SUVs and premium models, which require advanced seating systems. As consumers seek greater comfort, safety, and convenience through features such as power-adjustable, heated, and ventilated seats, manufacturers are developing lightweight, modular, and technology-integrated seating solutions for OEMs. The continued expansion of passenger car production is driving the adoption of advanced automotive seats and supporting market growth.
The commercial vehicle segment is projected to grow at the significant CAGR over the forecast period. The increasing adoption of electric buses and trucks is supported by government incentives and fleet electrification initiatives. As electric commercial vehicles require lightweight and ergonomic seating systems to improve energy efficiency and driver comfort, seat manufacturers are developing modular and durable seating solutions that reduce vehicle weight while maintaining safety and comfort. The rising production of electric commercial vehicles is increasing the adoption of advanced automotive seating systems and supporting market growth.
Sales Channel Insights
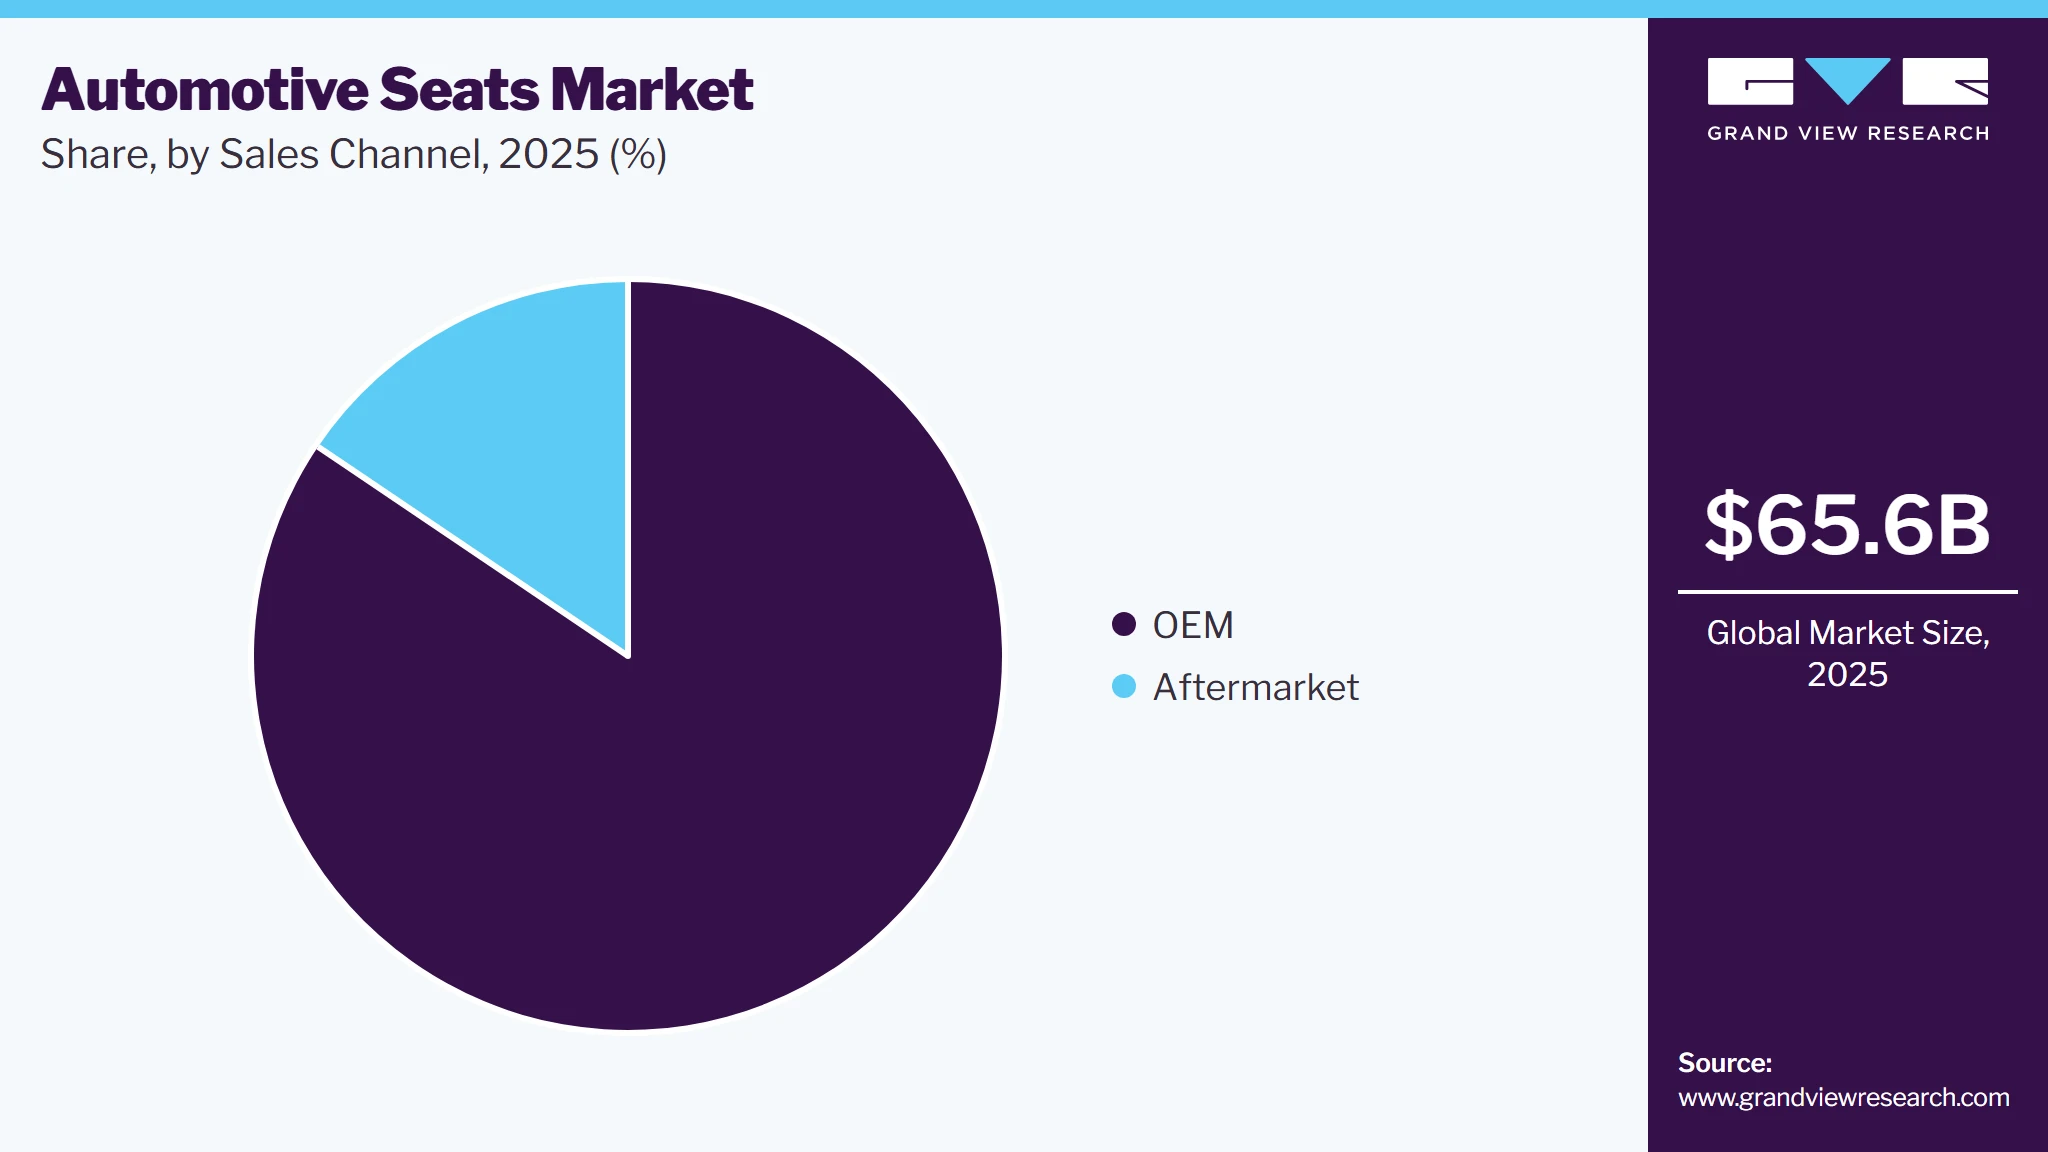
The OEM segment accounted for the largest market revenue share in 2025. The growth is driven by the rising production of new vehicles and the increasing integration of advanced seating systems by automakers. To meet the growing demand for enhanced comfort, safety, and technological features, automotive seat suppliers are developing innovative seating systems that meet OEM quality, design, and performance requirements. The continued expansion of global vehicle manufacturing is driving the demand for OEM automotive seats and supporting market growth.
 To learn more about this report, Download Free Sample Report
The aftermarket segment is projected to grow at a notable CAGR over the forecast period. Growth is driven by the continuous replacement and customization of automotive seats due to wear and tear of seat covers, foam cushions, and other seat components. To meet this demand, aftermarket suppliers offer cost-effective seat covers, upholstery, cushions, and replacement parts compatible with a wide range of vehicle models. Their affordability and broad availability are accelerating the adoption of aftermarket seating products and supporting market growth.
Regional Insights
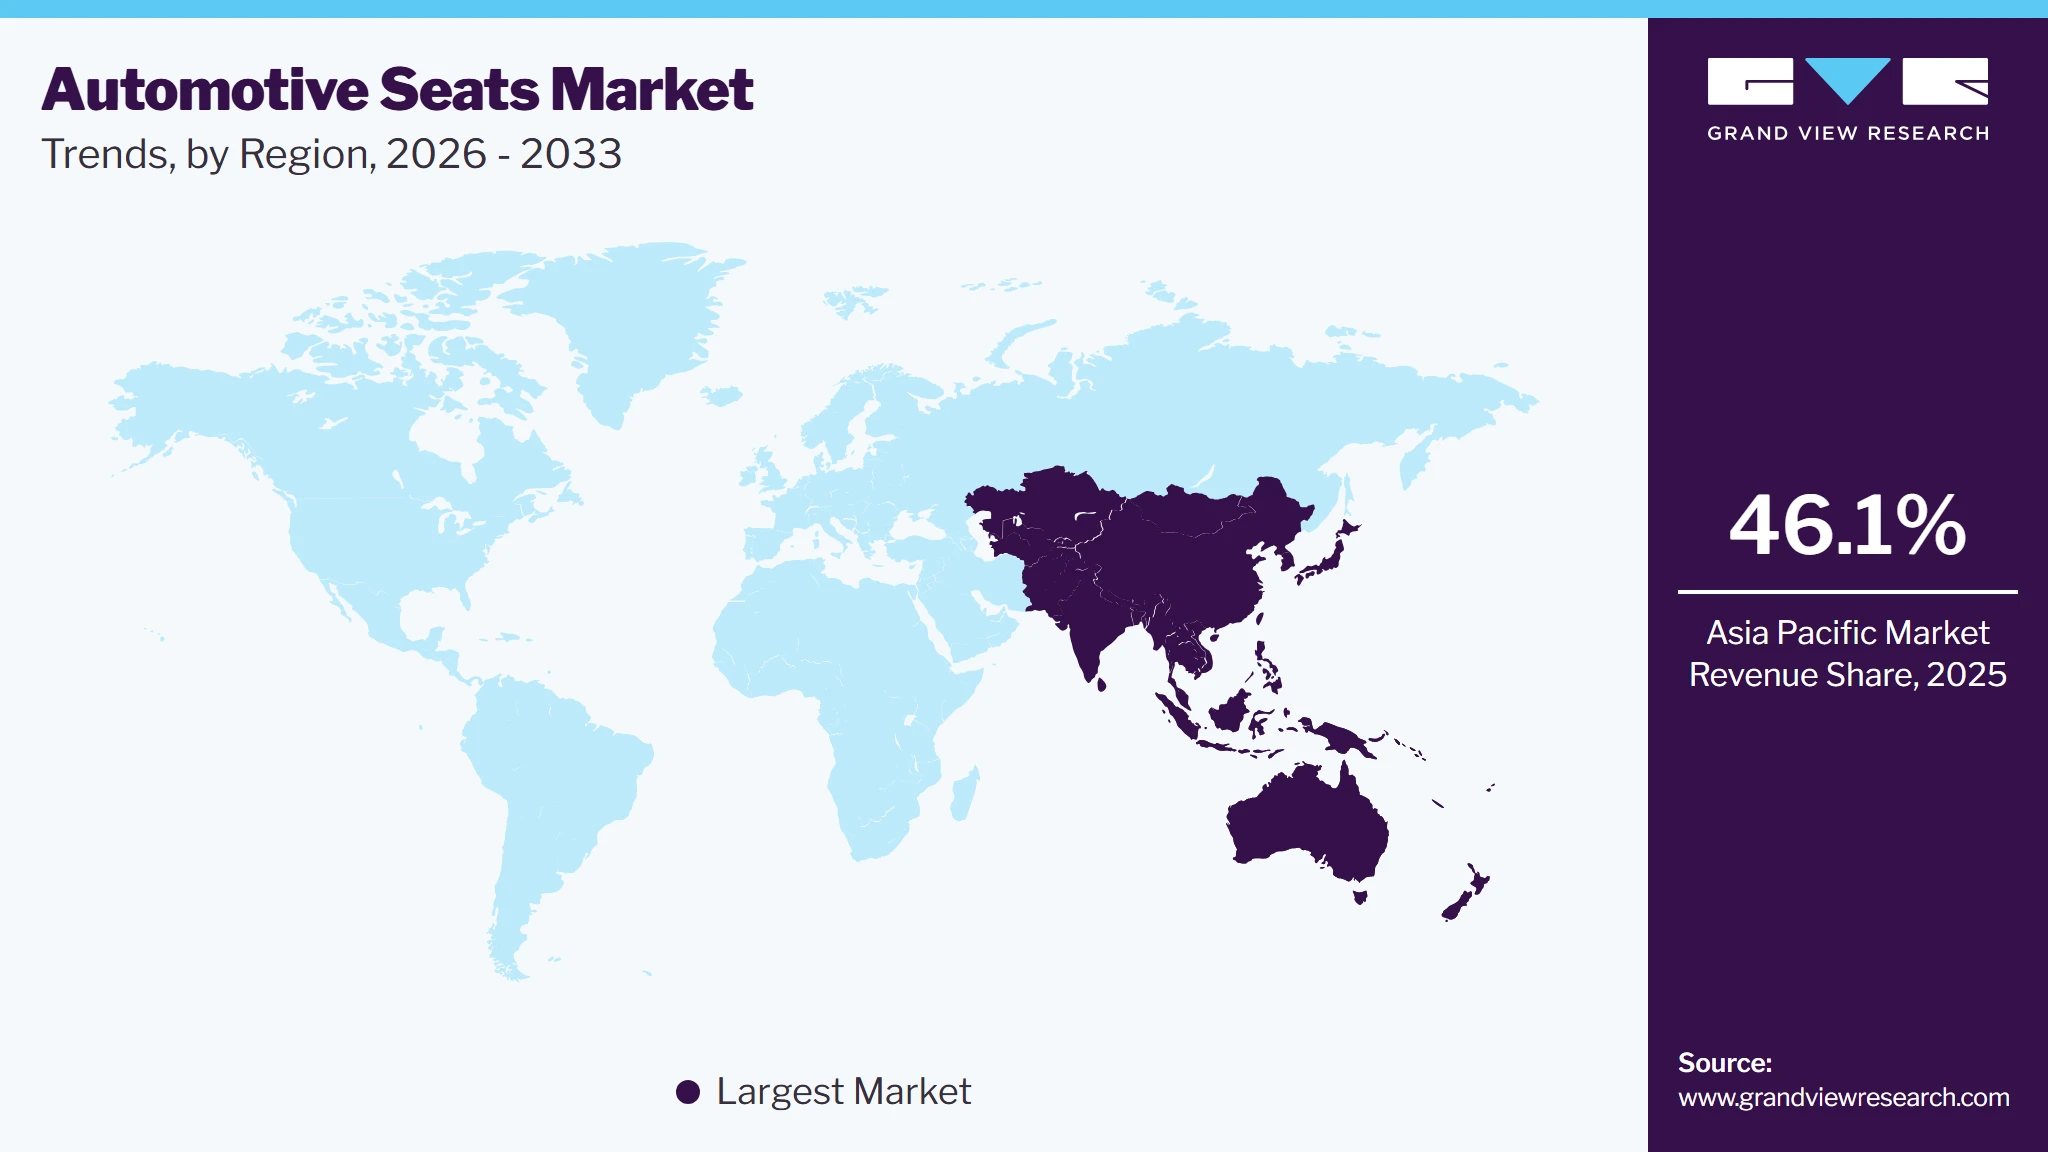
The Asia Pacific automotive seats marketled the global industry and accounted for 46.1% of the global revenue in 2025 and is expected to register the highest growth from 2026 to 2033. The dominance comes on the back of a strong automotive manufacturing ecosystem and high vehicle production. The region benefits from rising vehicle ownership, expanding middle-class populations, and increasing investments in automotive manufacturing. These factors continue to support demand for automotive seating systems across passenger and commercial vehicles.
 To learn more about this report, Download Free Sample Report
The automotive seats market in China has gained traction as the country is the largest automotive producer globally and the leading market for electric vehicles. Government support for new energy vehicles and the continuous expansion of EV production are accelerating demand for lightweight, smart, and sustainable automotive seating solutions. Domestic automakers are also increasing the adoption of advanced comfort and connectivity features.
The Japan automotive seats market is expected to grow at a significant CAGR over the forecast period. Japan's automotive seats market is driven by its leadership in automotive engineering and advanced manufacturing technologies. Automakers focus on developing ergonomic, lightweight, and high-quality seating systems that enhance safety, durability, and occupant comfort. Continuous innovation by Japanese OEMs and seat suppliers supports the adoption of next-generation seating technologies.
North America Automotive Seats Market Trends
The automotive seats market in North Americahasheld a significant position in the market, driven by strong vehicle ownership and sustained demand for SUVs, pickup trucks, and crossover vehicles. Consumers increasingly prefer vehicles with enhanced comfort and convenience features, encouraging manufacturers to develop advanced seating solutions. This continues to support the adoption of premium automotive seating technologies across the region.
U.S. Automotive Seats Market Trends
The automotive seats market in the U.S.is anticipated to register significant growth from 2026 to 2033, due to its high production and sales of light trucks and full-size SUVs. Automakers are increasingly equipping vehicles with powered, heated, ventilated, and memory seats to meet rising consumer expectations for comfort. The growing popularity of premium trims is further driving demand for technologically advanced seating systems.
Europe Automotive Seats Market Trends
The automotive seats market in Europeis poised for significant growth from 2026 to 2033. driven by stringent vehicle safety and environmental regulations that encourage the adoption of lightweight and sustainable seating materials. The region is also witnessing increasing demand for premium vehicle interiors and advanced comfort features. These factors are driving continuous innovation in automotive seating technologies.
The UK automotive seats market is supported by the growing adoption of electric vehicles and increasing consumer preference for premium vehicle interiors. Manufacturers are focusing on sustainable upholstery materials and lightweight seat designs to improve vehicle efficiency. This is encouraging the development of eco-friendly automotive seating solutions.
The automotive seats market in Germany held a substantial share of the Europe industry. Germany is a global center for luxury and premium vehicle manufacturing, creating strong demand for technologically advanced automotive seating systems. Leading automakers are integrating intelligent seating features such as power adjustment, memory, heating, ventilation, and massage functions to enhance the occupant experience. This continues to drive innovation in high-performance automotive seating.
Key Automotive Seats Company Insights
Key players operating in the automotive seats market include Lear Corp., Adient plc., FORVIA., Magna International Inc., TOYOTA BOSHOKU CORPORATION., NHK SPRING Co.,Ltd., TS TECH CO., LTD., Bharat Seats Limited, Martur Fompak International, and GENTHERM. These companies are expanding manufacturing capabilities, developing advanced seating technologies, and strengthening OEM partnerships. Companies are focusing on improving seating comfort, safety, and lightweight designs to support the growing demand for premium and electric vehicles.
-
Adient plc is a global automotive seating company. It designs engineers, manufactures, and delivers complete seating systems and seating components for passenger cars and commercial vehicles. The company focuses on developing lightweight, modular, and sustainable seating solutions. It also emphasizes innovation, manufacturing efficiency, and customization through close collaboration with global automotive OEMs.
-
FORVIA is a global automotive technology company formed through the combination of Faurecia and HELLA in 2022. The company provides a broad portfolio of solutions across seating, interiors, electronics, lighting, clean mobility, and lifecycle solutions for the automotive industry. FORVIA focuses on developing safe, sustainable, customizable, and cost-effective mobility technologies while leveraging innovation, industrial excellence, and close collaboration with automakers to shape the future of mobility.
Key Automotive Seats Companies
The following key companies have been profiled for this study on the automotive seats market.
-
Lear Corp.
-
Adient plc.
-
FORVIA
-
Magna International Inc.
-
TOYOTA BOSHOKU CORPORATION
-
NHK SPRING Co., Ltd.
-
TS TECH CO., LTD.
-
Bharat Seats Limited
-
Martur Fompak International
-
GENTHERM
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Lear Corp., Adient plc., FORVIA, Magna International Inc., TOYOTA BOSHOKU CORPORATION
- Mature players in the automotive seats market are focusing on global manufacturing footprint and long-term OEM partnerships Their strategies focus on continuously invest in R&D, modular seating platforms, and advanced seating technologies to improve comfort, safety, lightweight design, and strengthen competitive positioning.
- Mature players gain a competitive advantage through broad product portfolio and large-scale production capacity. Strong OEM relationships, advanced engineering capabilities, and economies of scale support continuous innovation, cost optimization, and long-term global market leadership.
- These companies often face challenges related to large organizational structures often require multiple approval processes, which can slow decision-making and delay the introduction of new seating technologies. Heavy dependence on major OEM contracts makes revenue vulnerable to changes in vehicle production volumes, production delays, or reduced OEM purchasing.
Emerging Players: Bharat Seats Limited, GENTHERM
- Emerging players in the automotive seats market are focusing on specialized seating technologies, regional expansion, strategic collaborations, and differentiated solutions for selected vehicle segments.
- Emerging players gain market traction through strong niche expertise, greater operational flexibility, faster innovation cycles, and the ability to address specific OEM requirements efficiently.
- Emerging players face limitations due to limited global operations and smaller manufacturing capacity make it difficult to meet the large-volume and multi-region supply requirements of global OEMs.
Recent Developments
-
In August 2026, Adient plc. introduced the ModuGo seat, a modular automotive seating solution designed to improve manufacturing efficiency and reduce costs. The seat offers customizable features, including heating, ventilation, massage, and adaptive lumbar support. It also uses 100% recyclable materials to support sustainability. Moreover, the innovation enhances occupant comfort while providing greater flexibility in vehicle interior design.
-
In February 2025, Lear Corp. partnered with General Motors, a multinational automotive manufacturing company, to introduce the ComfortMax Seat with integrated thermal comfort technologies. The system delivers up to 40% faster heating and ventilation while improving occupant comfort. Its modular design reduces seat components by up to 50%, enhancing manufacturing efficiency and supporting sustainable automotive seating solutions.
Automotive Seats Market Report Scope
Report Attribute
Details
Market size in 2025
USD 65.6 Billion
Estimated market size in 2026
USD 68.3 billion
Projected market size by 2033
USD 98.5 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Seat, material, technology, vehicle, sales channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
Lear Corp.; Adient plc.; FORVIA.; Magna International Inc.; TOYOTA BOSHOKU CORPORATION.; NHK SPRING Co., Ltd.; TS TECH CO., LTD.; Bharat Seats Limited; Martur Fompak International; GENTHERM
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Seats Market Report Segmentation
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive seats market report based on seat, material, technology, vehicle, sales channel, and region.
-
Seat Outlook (Revenue, USD Billion, 2021 - 2033)
-
Bench
-
Bucket
-
Folding
-
Others
-
-
Material Outlook (Revenue, USD Billion, 2021 - 2033)
-
Genuine Leather
-
Synthetic Leather
-
Fabric
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Manual Seats
-
Power Seats
-
Smart Seats
-
-
Vehicle Outlook (Revenue, USD Billion, 2021 - 2033)
-
Passenger Car
-
Commercial Vehicle
-
-
Sales Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
OEM
-
Aftermarket
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
UAE
-
Kingdom of Saudi Arabia (KSA)
-
South Africa
-
-
Research Methodology
The automotive seats market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automotive seats segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Seat
Revenue capture definition
Bench
The segment revenue is generated by manufacturing and supplying fixed or split bench seating systems for front or rear vehicle applications, including seat structures, cushions, upholstery, mounting hardware, and integrated safety components.
Bucket
The segment revenue is derived from individual bucket seats supplied for driver and passenger positions, including manual or powered adjustment mechanisms, headrests, lumbar support, heating, ventilation, and integrated electronics.
Folding
The segment revenue is captured from foldable seating systems designed for flexible cabin configurations, including split-fold seats, tumble seats, reclining mechanisms, locking systems, and associated structural assemblies.
Others
The segment revenue is generated from specialized seating products, including captain seats, removable seats, sports seats, modular seating systems, and customized seating solutions for niche vehicle applications.
Segment - Material
Revenue capture definition
Genuine Leather
The segment revenue is generated from automotive seats upholstered with natural leather materials, including premium finishing, stitching, surface treatment, and OEM-installed luxury seating applications.
Synthetic Leather
The segment revenue is derived from seats utilizing polyurethane, PVC, or other artificial leather materials supplied for cost-effective, premium appearance and durability across multiple vehicle categories.
Fabric
The segment revenue is captured from seats upholstered with woven, knitted, or textile-based materials, including foam lamination, seat covers, cushioning integration, and standard seating configurations.
Segment - Technology
Revenue capture definition
Power Seats
The segment revenue is generated from mechanically adjustable seating systems utilizing manual levers, sliders, recliners, and height adjustment mechanisms without electrical actuation.
Manual Seats
The segment revenue is derived from electrically adjustable seating systems incorporating motors, controllers, memory modules, wiring harnesses, and electronic positioning functions.
Smart Seats
The segment revenue is captured from intelligent seating systems integrating sensors, occupant monitoring, climate control, massage, memory, posture adjustment, biometric monitoring, and connected electronic features.
Segment - Vehicle
Revenue capture definition
Commercial Vehicle
The segment revenue is generated from seating systems supplied for hatchbacks, sedans, SUVs, MPVs, luxury vehicles, sports cars, and electric passenger vehicles.
Passenger Car
The segment revenue is derived from seating supplied for light commercial vehicles, trucks, buses, coaches, and specialty commercial vehicles, including driver and passenger seating solutions.
Segment - Sales Channel
Revenue capture definition
OEM
The segment revenue is generated from direct supply of complete automotive seating systems, components, and modules to vehicle manufacturers for factory installation in new vehicles.
Aftermarket
The segment revenue is generated from replacement seats, seat covers, cushions, repair kits, upholstery materials, retrofit upgrades, and accessory seating products sold after original vehicle production.
Estimation Model
Layer Name
Key Question
Description
Global Vehicle Production Assessment
How many vehicles require automotive seats?
The first layer estimates total addressable demand by evaluating global vehicle production across passenger and commercial vehicles. Production volumes are analyzed by region, vehicle category, and manufacturing trends. This establishes the baseline number of seating systems required annually.
Seat Configuration Analysis
What seating configurations are installed per vehicle?
This layer evaluates average seat count per vehicle, seating layouts, seat adoption, and premium seating penetration. Vehicle mix, seating architecture, and regional consumer preferences are incorporated to estimate demand for different seating configurations.
Technology and Material Penetration
Which seating technologies generate the highest value?
This layer measures adoption of manual, power, and smart seats along with genuine leather, synthetic leather, and fabric materials. Premium feature penetration, electronic integration, and lightweight material adoption determine average revenue per seating system across vehicle categories.
Revenue Validation and Market Forecast
What is the total market revenue over the forecast period?
The final layer combines production volume, seat configuration, technology penetration, and average selling prices to estimate market revenue. Historical trends, OEM procurement strategies, regional manufacturing expansion, and future technology adoption are incorporated to validate forecasts and long-term growth projections.
Delivered CustomizationThis report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Automotive Seats Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the Automotive Seats Market
Criss-cross market analysis by seat, material, technology, vehicle, sales channel
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted seat positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the Automotive Seats Market
Benchmarking of key competitors across seats, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global automotive seats market size was valued at USD 65.6 billion in 2025 and is estimated at USD 68.3 billion in 2026.
The global automotive seats market is expected to grow at a compound annual growth rate of 5.4% from 2026 to 2033, reaching USD 98.5 billion by 2033.
Bucket seats segment accounted for 40.8%, the largest share of global revenue in 2025. This dominance is driven by the increasing demand for enhanced seating comfort and ergonomic support in passenger vehicles
The Asia Pacific automotive seat market led the global market and accounted for 46.1% of the global revenue in 2025 and is expected to register the fastest growth from 2026 to 2033, Asia Pacific dominates the automotive seats market due to its strong automotive manufacturing ecosystem and high vehicle production
Rising integration of lightweight, modular, and smart seating technologies is fueling the growth of the automotive seats market.
Some key players operating in the automotive seats market include Lear Corp., Adient plc., FORVIA., Magna International Inc., TOYOTA BOSHOKU CORPORATION., NHK SPRING Co.,Ltd., TS TECH CO.,LTD., Bharat Seats Limited, Martur Fompak International, GENTHERM
Fabric segment accounted for 44.5%, the largest share of global revenue in 2025, while synthetic leather is projected to grow at the fastest CAGR over the forecast period
Manual seats segment accounted for the largest share of global revenue in 2025, while smart seats is projected to grow at the fastest CAGR over the forecast period.
Passenger cars segment accounted for the largest market revenue share in 2025 and is projected to grow at the fastest CAGR over the forecast period
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


