
- Home
- »
- Advanced Interior Materials
- »
-
Automotive Tire Market Size & Share Report, 2026-2033GVR Report cover

Automotive Tire Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Radial, Bias), By Application (Passenger cars, LCV, HCV), By Rim Size (Less Than 15 Inches, 15 to 20 Inches), By Season Type (Summer Tire, Winter Tire ), By Region, And Segment Forecasts
Market Size, 2025
$431.0MMarket Estimate, 2026
$462.5MMarket Forecast, 2033
$781.4MCAGR, 2026–2033
7.8%Automotive Tire Market Summary
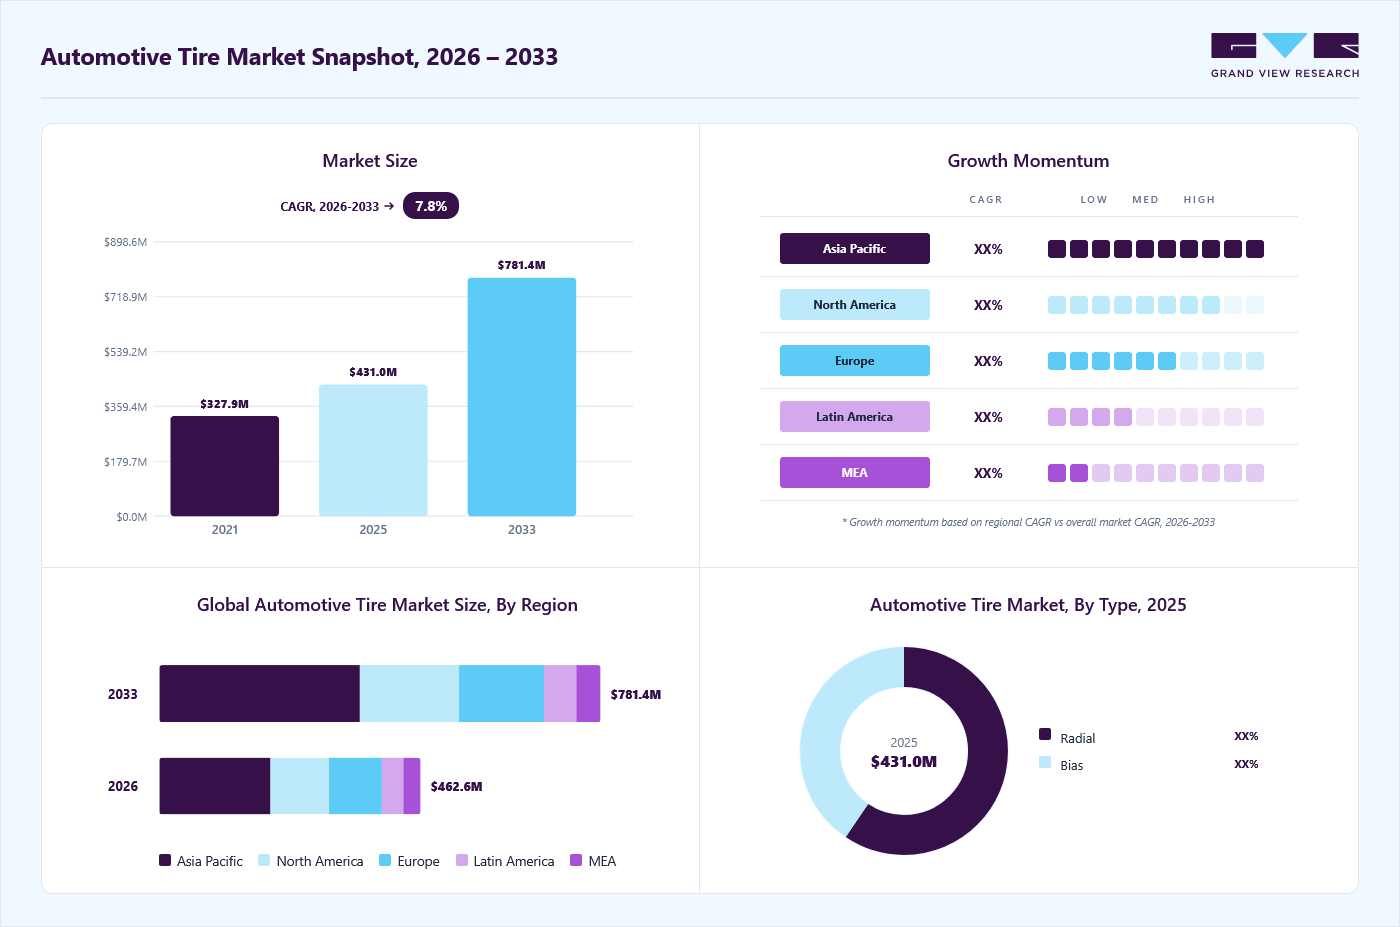
The global automotive tire market size was valued at USD 431.0 million in 2025 and projected to grow from USD 462.5 million in 2026 to USD 781.4 million by 2033, at a CAGR of 7.8% from 2026 to 2033. Asia Pacific dominated the global market with the largest revenue share of 42.2% in 2025, attributed toincreased vehicle production and sales, along with a rising demand for retreaded tires. As more vehicles hit the roads, the need for original and replacement tires escalates. Retreaded tires, offering cost-efficiency and sustainability, further boost the market by providing a viable option for commercial and fleet vehicles.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Radial segment led the market with the largest revenue share of 59.4% in 2025.
- By application: Passenger cars segment led the market with the largest revenue share of 56.1% in 2025.
- By season type: All-season Tire segment led the market with the largest revenue share of 52.2% in 2025.
- By rim: 15 to 20 Inches segment led the market with the largest revenue share of 64.9% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (42.2% revenue share, 2025)
- By country: China hold major share in Asia Pacific region.
Market Size & Forecast
- Market Size in 2025: USD 431.0 Million
- Estimated Market Size in 2026: USD 462.5 Million
- Projected Market Size by 2033: USD 781.4 Million
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
As more vehicles hit the roads, the need for original and replacement tires escalates. Retreaded tires, offering cost-efficiency and sustainability, further boost the market by providing a viable option for commercial and fleet vehicles. This dual demand fuels continuous market expansion, reflecting the critical role of both new and retreaded tires in meeting the evolving needs of a growing global automotive industry.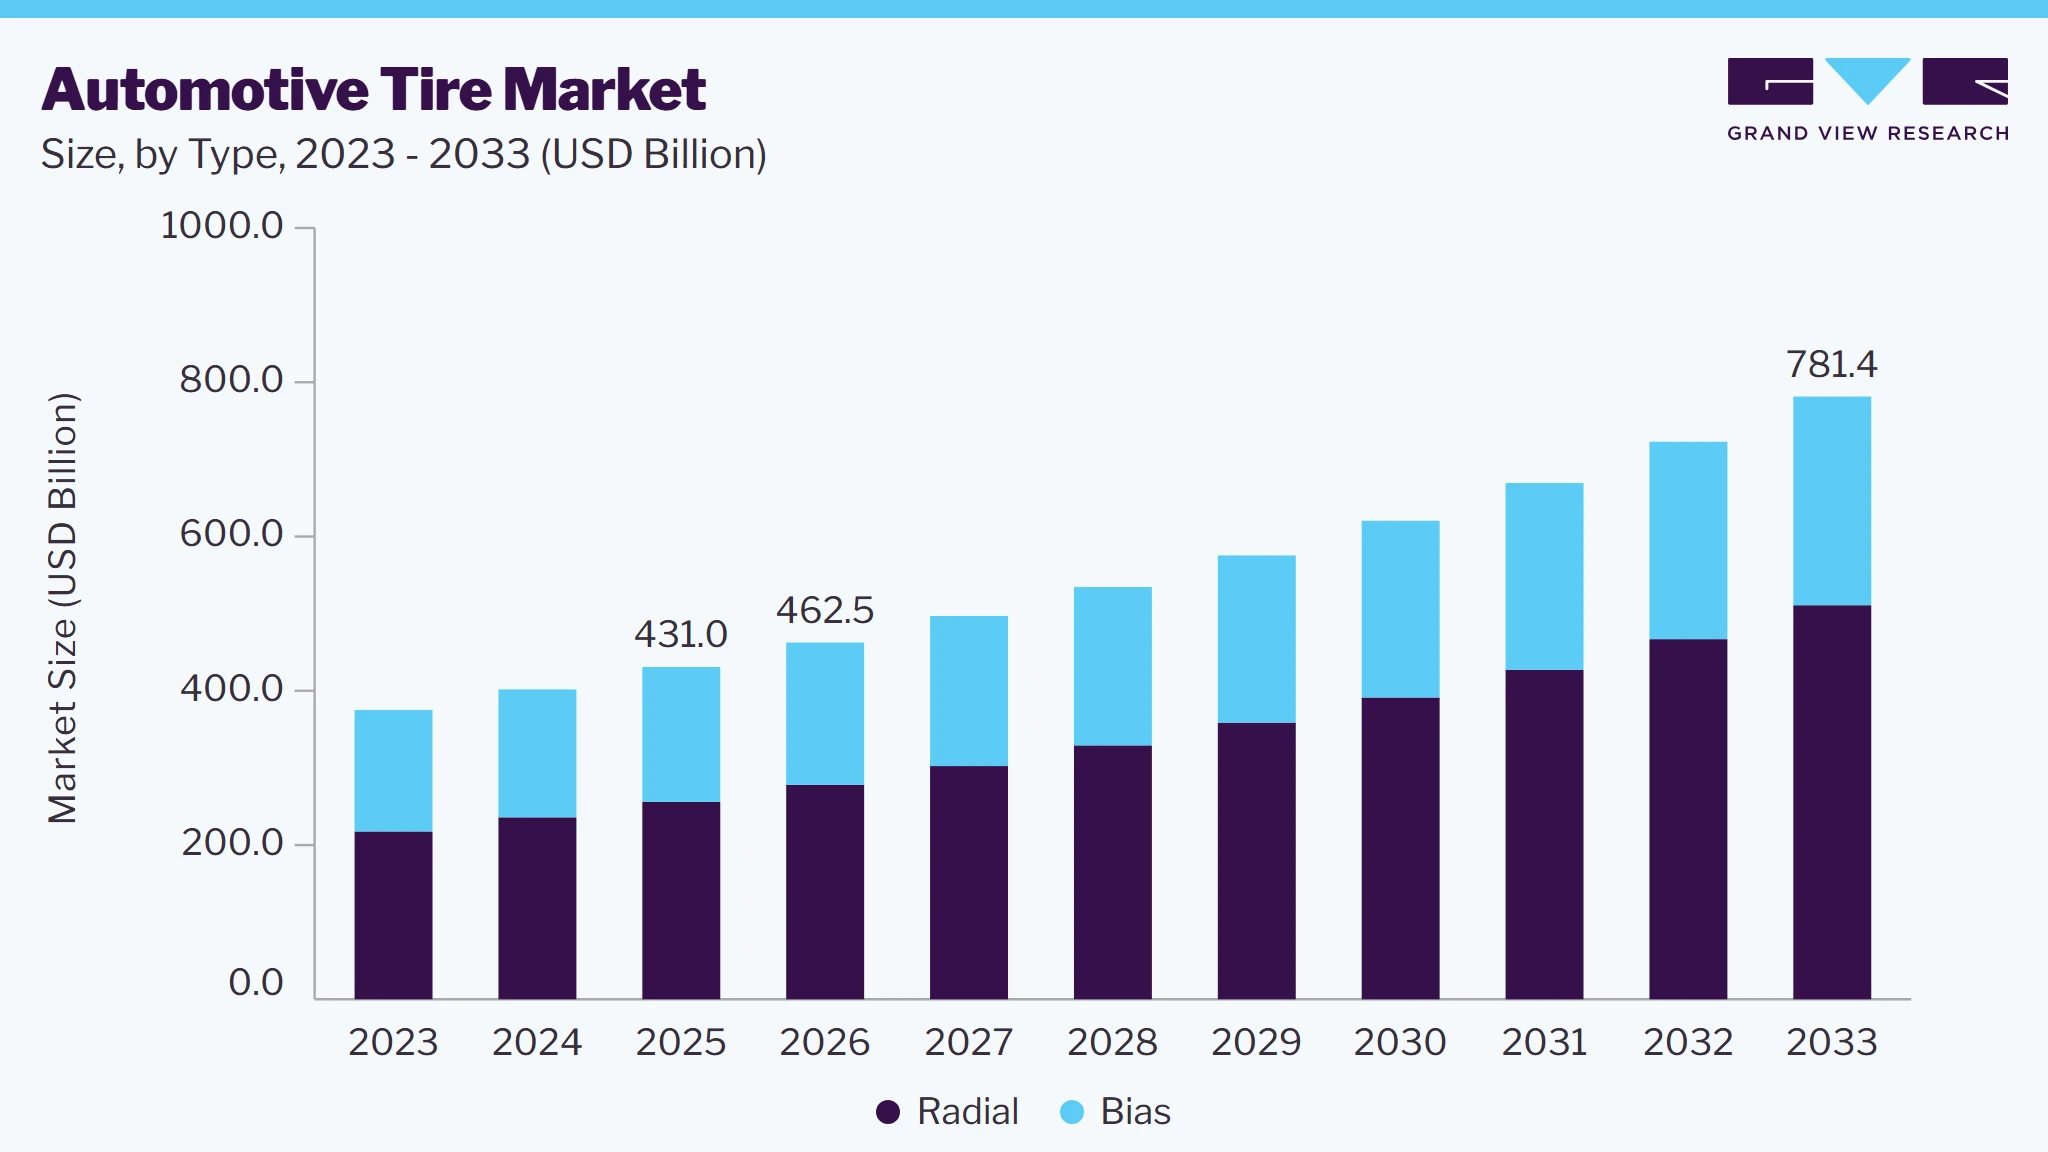 To learn more about this report, Download Free Sample Report
In addition, the adoption of smart technologies and the rise of electric vehicles (EVs) are poised to drive the size of the automotive tire industry significantly. Smart tires, equipped with sensors to monitor pressure, temperature, and wear, offer enhanced performance and safety, fueling demand for high-tech products. In addition, the growing EV market is increasing the need for specialized tires designed to handle the unique demands of electric vehicles, such as higher torque and weight. These trends are prompting tire manufacturers to innovate, expanding the market for both advanced tire technologies and EV-specific tires.
Market Dynamics
Growing vehicle ownership, rising replacement tire demand, and increasing production of passenger cars, SUVs, commercial vehicles, and electric vehicles are driving growth in the automotive tire market. Advancements in tire technologies, including low rolling resistance compounds, smart tire systems, run-flat tires, and EV-specific tire designs, are improving fuel efficiency, safety, durability, and overall vehicle performance. Manufacturers are also investing in sustainable materials, advanced tread designs, and digital tire monitoring solutions to enhance product differentiation and meet evolving customer requirements. However, fluctuations in raw material prices, including natural rubber, synthetic rubber, carbon black, and steel, along with high manufacturing and logistics costs, continue to pressure profit margins across the industry. Intense competition and pricing pressure further challenge market participants, particularly in highly fragmented replacement tire markets. Meanwhile, growing environmental concerns and increasingly stringent emission and sustainability regulations are creating opportunities for the development of eco-friendly tires, recycled materials, and circular economy initiatives. The accelerating adoption of electric vehicles is also opening new growth avenues for premium and high-performance tire manufacturers worldwide.
The increasing global vehicle production is a key factor driving the growth of the automotive tire market. Rising vehicle ownership across emerging economies, supported by urbanization, improving living standards, and expanding transportation infrastructure, continues to increase demand for both original equipment (OE) and replacement tires. Since tires are wear-and-tear components that require periodic replacement, the growing number of vehicles in operation creates a recurring and stable demand base for tire manufacturers.
The market is also benefiting from the rapid expansion of the SUV, crossover, and light commercial vehicle segments, which typically utilize larger and higher-value tires. Additionally, the growth of e-commerce and last-mile delivery services has increased vehicle utilization rates, particularly among commercial fleets, resulting in more frequent tire replacements. Fleet operators are increasingly prioritizing tire performance, durability, and fuel efficiency to reduce operating costs, further supporting demand for advanced tire solutions.
Furthermore, the accelerating adoption of electric vehicles (EVs) is creating new growth opportunities for tire manufacturers. EVs require specialized tires capable of handling higher vehicle weight, instant torque delivery, and lower rolling resistance requirements. Leading tire manufacturers are introducing EV-specific tire portfolios to address these evolving performance needs. As vehicle ownership continues to expand and mobility demand increases worldwide, replacement tire demand is expected to remain a fundamental growth driver for the automotive tire market throughout the forecast period.
Fluctuations in the prices of key raw materials remain a major challenge for the automotive tire market. Tire manufacturing relies heavily on natural rubber, synthetic rubber, carbon black, steel cord, and various petrochemical-based materials, all of which are subject to price volatility driven by changes in crude oil prices, supply-demand imbalances, weather conditions, and geopolitical developments. Sudden increases in raw material costs can significantly impact manufacturing expenses and profit margins, particularly for tire manufacturers operating in highly competitive markets.
The industry is also exposed to supply chain disruptions that can affect the availability and cost of essential materials. For example, adverse weather conditions in major natural rubber-producing countries such as Thailand, Indonesia, and Vietnam can reduce rubber output and create supply shortages. In addition, fluctuations in freight costs and trade restrictions can further increase procurement and transportation expenses.
The rapid adoption of electric vehicles (EVs) presents a significant growth opportunity for the automotive tire market. EVs have unique performance requirements due to their heavier battery packs, instant torque delivery, and the need for lower rolling resistance to maximize driving range. As a result, vehicle manufacturers are increasingly seeking specialized tire solutions that offer enhanced durability, energy efficiency, reduced noise levels, and improved traction.
Tire manufacturers are investing heavily in the development of EV-specific tire technologies to address these evolving requirements. Advanced tread designs, lightweight materials, and innovative rubber compounds are being introduced to improve tire lifespan and vehicle efficiency. As global EV production and sales continue to increase, demand for premium and high-performance tires is expected to grow alongside the expanding electric vehicle fleet.
In addition, government incentives supporting vehicle electrification and investments in charging infrastructure are accelerating EV adoption across major automotive markets. The growing penetration of electric passenger cars, electric buses, and electric commercial vehicles is creating new revenue opportunities for tire manufacturers in both OEM and replacement channels. Consequently, the transition toward electric mobility is expected to become a key growth avenue for the automotive tire market over the coming years.
Analyst Perspective
The automotive tire market is experiencing steady growth, driven by increasing vehicle ownership, expanding global vehicle parc, and rising replacement tire demand across both developed and emerging markets. Growth in SUVs, crossovers, and commercial vehicles is supporting demand for larger and higher-value tire products, while the rapid adoption of electric vehicles is creating opportunities for specialized tire solutions with enhanced durability, low rolling resistance, and noise reduction capabilities. Tire manufacturers are investing in advanced tread designs, sustainable materials, smart tire technologies, and EV-specific product portfolios to improve performance and meet evolving customer requirements. The replacement segment continues to account for the majority of market revenue, supported by increasing vehicle utilization and fleet operations worldwide. However, fluctuations in raw material prices, supply chain disruptions, and intense pricing competition remain key challenges impacting profitability. Despite these constraints, the market is expected to witness sustained growth as vehicle populations expand, mobility demand increases, and technological advancements continue to enhance tire performance, safety, and efficiency.
Type Insights
Based on type, the radial segment led the market with the largest revenue share of 59.4% in 2025, propelled by its superior performance and durability. Radial tires, featuring innovative construction, offer improved fuel efficiency, enhanced handling, and longer tread life than traditional bias-ply tires. These advantages have made them the preferred choice for various vehicles, from passenger cars to commercial trucks. The rising demand for better ride quality and increased vehicle safety has further cemented the importance and growth of radial tires in the industry.
Moreover, the bias segment is projected to grow significantly from 2025 to 2030 due to its cost-effectiveness and robust durability. Known for their strong sidewalls and capability to handle heavy loads, bias tires are becoming increasingly popular, especially in commercial and agricultural sectors. The expansion of transportation and logistics industries further boosts demand for these tires. Moreover, recent advancements in bias tire technology are improving performance and extending their lifespan, making them an attractive option for various vehicles.
Application Insights
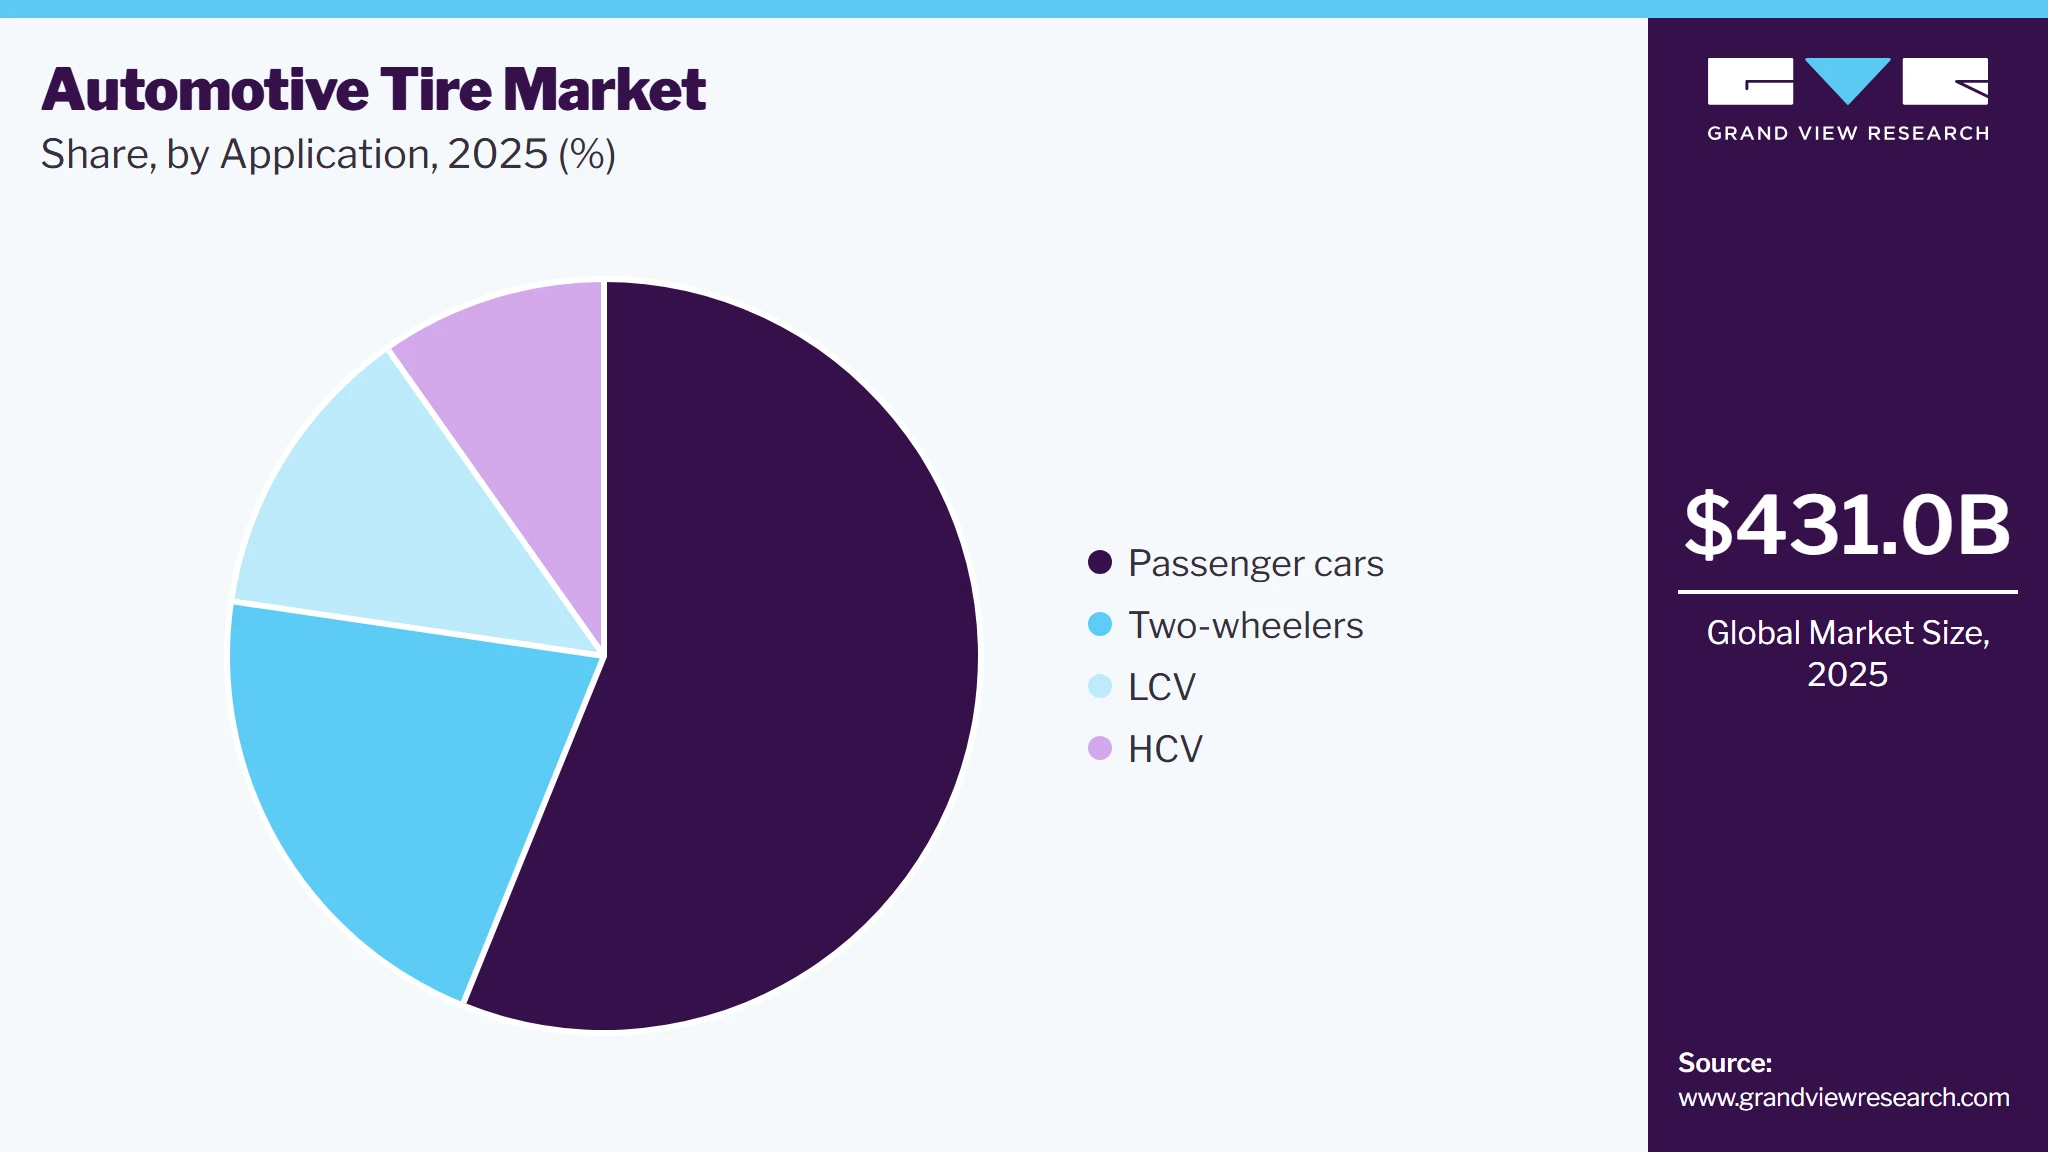
Based on application, the Passenger cars segment led the market with the largest revenue share of 56.1% in 2025, due to the significant number of vehicles in this category. With growing urbanization and increasing disposable incomes, more individuals are buying personal vehicles, which fuels the demand for passenger car tires. Besides, advancements in tire technology that improve safety, fuel efficiency, and performance have made these tires highly attractive to consumers, emphasizing the segment's critical role in the market.
 To learn more about this report, Download Free Sample Report
The LCV segment is expected to register a substantial CAGR over the forecast period. As e-commerce and logistics industries expand, the demand for LCVs, such as delivery vans and small trucks, is growing. These vehicles require specialized tires that offer durability, fuel efficiency, and load-carrying capacity, driving innovation in tire design. In addition, with the rise of last-mile delivery services and increased urbanization, LCVs are becoming essential for businesses, further boosting the demand for LCV-specific tires and contributing to market growth in this segment.
Season Type Insights
Based on season Type, the All-season Tire segment led the market with the largest revenue share of 52.2% in 2025, attributed to its versatility and year-round performance. These tires are designed to provide a balanced blend of traction, comfort, and durability, making them suitable for various weather conditions, including dry, wet, and light winter conditions. As consumers increasingly seek convenience and cost-effectiveness, all-season tires eliminate the need for seasonal tire changes. This demand for low-maintenance, multi-purpose tires has significantly contributed to the segment's dominance in the market.
The summer tire segment is set to witness a significant CAGR over the forecast period, spurred by increasing consumer demand for improved performance and fuel efficiency, especially in regions with warmer climates. Summer tires offer superior handling, enhanced braking, and better traction in dry and wet conditions, making them ideal for performance and luxury vehicles. With advancements in tire technology and growing consumer awareness of their benefits, such as reduced rolling resistance and better fuel economy, the summer tire segment is poised for substantial growth and market dominance in the coming years.
Rim Size Insights
Based on rim, the 15 to 20 Inches segment led the market with the largest revenue share of 64.9% in 2025, due to its widespread use in passenger vehicles, especially in mid-range and premium car models. These tire sizes balance performance, comfort, and fuel efficiency, making them highly preferred by consumers. In addition, the growing demand for versatile and durable tires that can handle diverse road conditions has driven the popularity of this segment. With increasing vehicle sales and the shift toward higher-performance models, the 15 to 20-inch tire segment continues to uphold a prominent share of the industry.
The more than 20-inch tire segment is projected to secure a significant share of the automotive tire market as consumer preferences shift towards larger, high-performance vehicles such as SUVs, crossovers, and luxury cars. These tires offer enhanced handling, stability, and performance, particularly for high-speed and off-road driving, making them increasingly popular in premium vehicle segments as automakers focus on offering larger wheels for aesthetic appeal and improved driving experience.
Regional Insights
North America is expected to witness the fastest growth rate over the forecast period, fueled by the region's robust automotive industry, increasing demand for passenger and commercial vehicles, and growing consumer preference for high-performance tires. Rising vehicle production and advancements in tire technologies, such as eco-friendly materials and improved fuel efficiency, further boost market growth. In addition, the region's strong infrastructure, high disposable income, and emphasis on safety and vehicle performance create a favorable environment for the tire market, ensuring North America's notable market share in the coming years.
U.S. Automotive Tire Market Trends
The U.S. held a remarkable position in the automotive tire industry in 2024, propelled by its robust automotive industry and high vehicle ownership rates. With a strong presence of leading tire manufacturers, the U.S. benefits from extensive research, innovation, and advanced manufacturing techniques. The diverse climate across the country also drives the demand for various types of tires, from all-season to specialized winter and off-road tires. Moreover, the emphasis on vehicle safety and performance has led to increased consumer preference for high-quality tires, reinforcing the dominant position of the U.S.
Canada is anticipated to record a noteworthy market share throughout 2030 due to its growing automotive sector, rising vehicle sales, and increasing demand for original equipment and replacement tires. The country’s expanding electric vehicle (EV) market is also driving demand for specialized tires designed to handle the unique needs of EVs. Furthermore, harsh weather conditions, particularly in winter, fuel the demand for high-performance and all-season tires. With a strong focus on sustainability and innovation, Canada automotive tire market is expected to grow substantially in the coming years.
Europe Automotive Tire Market Trends
Europe's prominence in the automotive tire industry is attributed to the region’s well-established automotive industry, a high rate of vehicle ownership, and a growing demand for eco-friendly tire solutions. The region is home to leading tire manufacturers such as Michelin, Continental, and Pirelli, who are at the forefront of tire innovation, particularly in terms of performance, safety, and sustainability. The rise of electric vehicles (EVs) has further spurred demand for specialized tires. In addition, stringent environmental regulations and consumer preferences for low-rolling resistance and energy-efficient tires continue solidifying Europe’s global tire market dominance.
The UK automotive tire market is expected to experience a significant growth rate over the forecast period, fueled by increasing vehicle sales, the rise of electric vehicles (EVs), and growing demand for eco-friendly tire solutions. With the UK’s commitment to reducing carbon emissions, there is a shift towards energy-efficient, low-rolling resistance tires. The expanding EV market, in particular, is creating a demand for specialized tires designed to handle the unique requirements of electric vehicles. Moreover, the country’s high vehicle fleet and replacement cycles further fuel growth in the tire market, positioning the UK for continued market expansion.
Germany is likely to witness a significant CAGR over the forecast period, driven by its strong automotive industry and increasing demand for high-performance and sustainable tires. As a hub for leading automakers such as Volkswagen, BMW, and Mercedes-Benz, the automotive tire market in Germany benefits from robust vehicle production and sales. The rise of electric vehicles (EVs) in the country further boosts demand for specialized tires that cater to EV needs. In addition, stringent environmental regulations and a focus on innovation in tire technology are propelling the growth of eco-friendly and energy-efficient tire solutions in Germany.
Asia Pacific Automotive Tire Market Trends
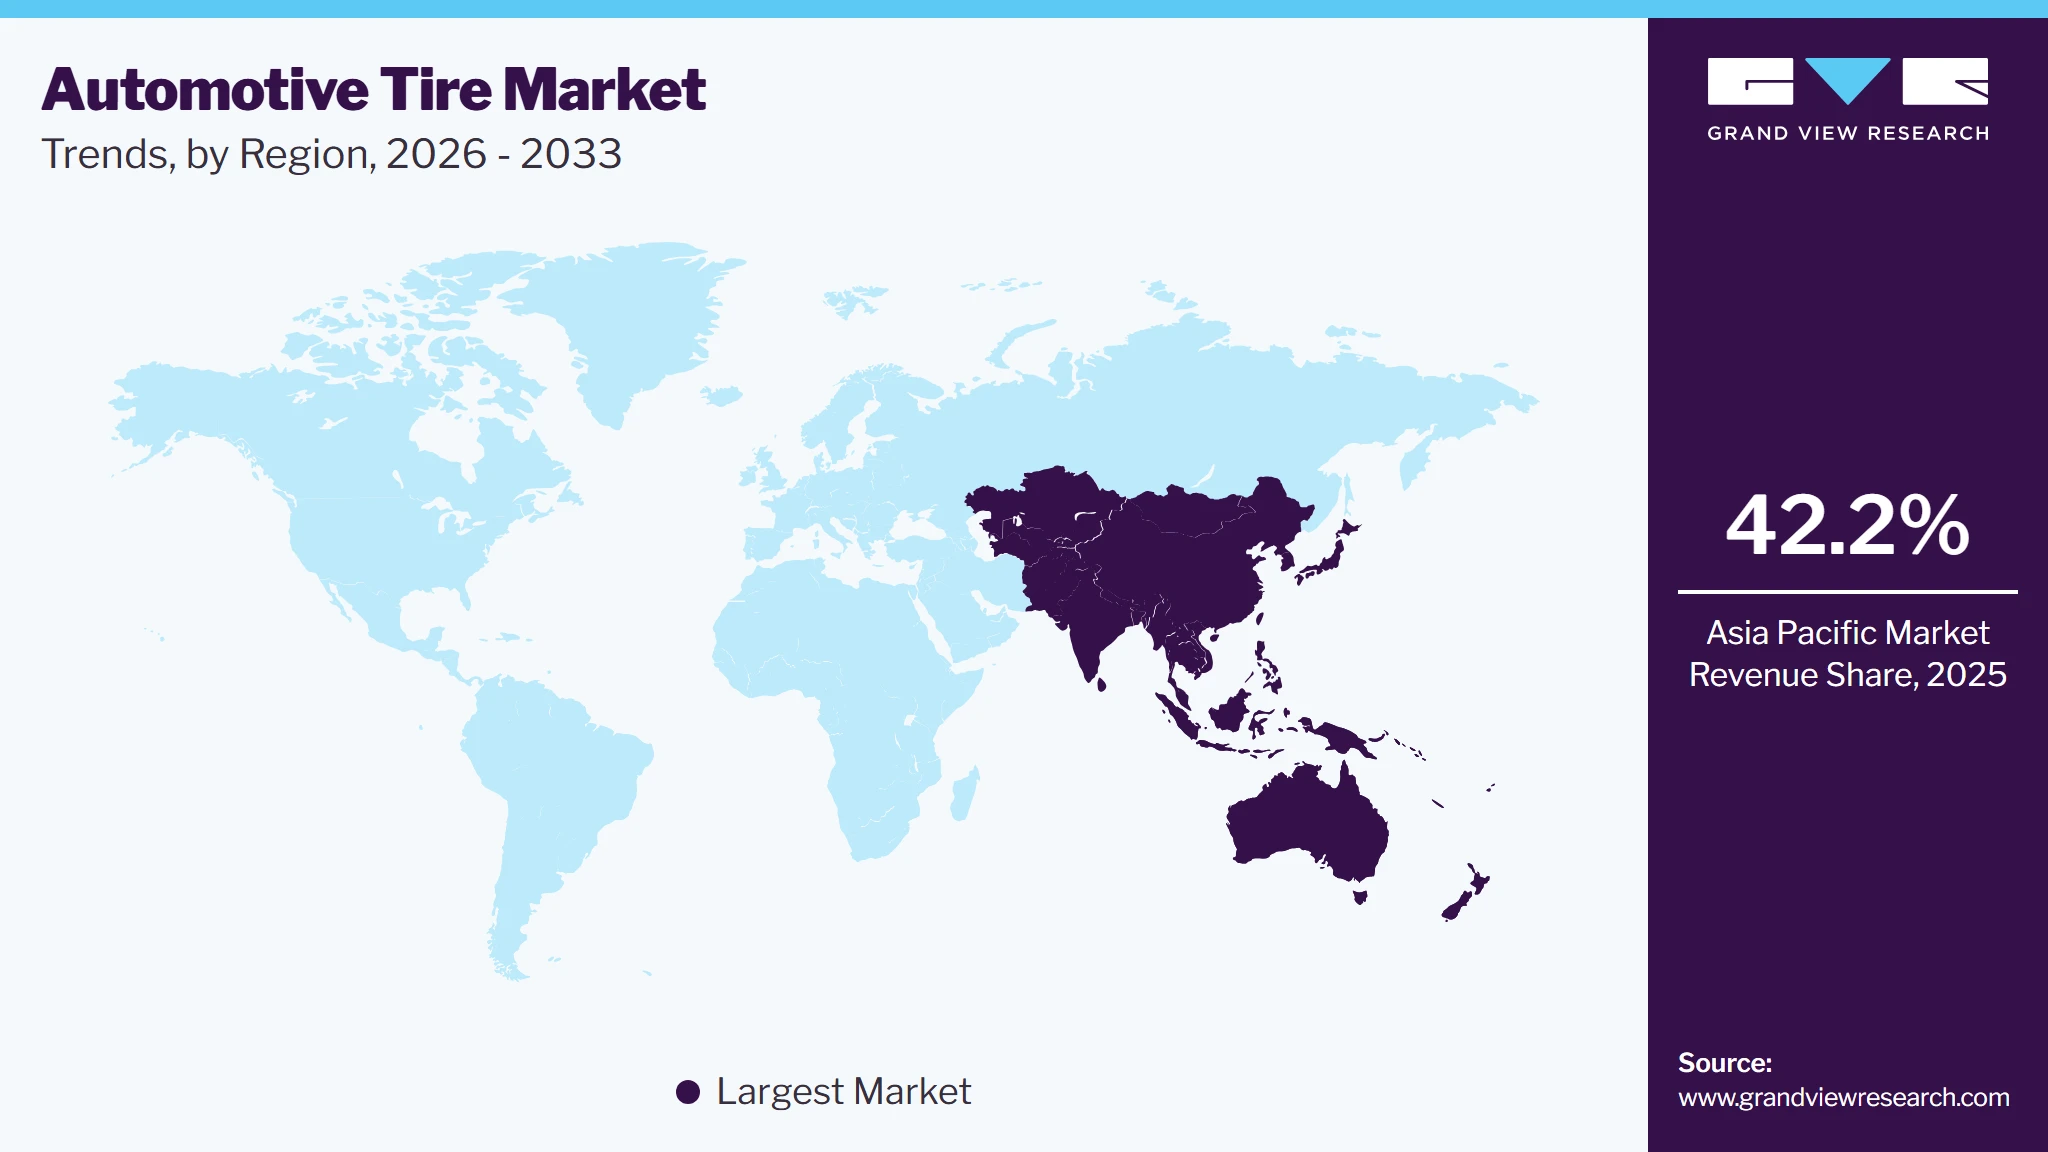
Asia Pacific dominated the global automotive tire market with the largest revenue share of 42.2% in 2025, driven by rapid industrialization, high vehicle production, and strong demand in countries such as China, India, and Japan. With a growing middle class and increasing vehicle ownership, tire consumption in the region has surged. Asia Pacific is home to major tire manufacturers such as Bridgestone, Michelin, and Goodyear, who have established extensive production facilities to meet local and global needs. Besides, the rising demand for electric vehicles (EVs) and light commercial vehicles (LCVs) further strengthens the region’s dominance in the global tire market.
Asia Pacific automotive tire market witnessed a substantial rise in 2024 due to the region's booming automotive industry, vast manufacturing infrastructure, and rising demand for vehicles in countries such as China, India, and Japan. The region, particularly China, India, and Japan, is home to major automotive manufacturing hubs, driving high demand for tires. The increasing number of vehicles on the road, coupled with rising disposable incomes and urbanization, fuels tire consumption. Besides, Asia Pacific's cost-effective manufacturing capabilities and investments in innovative tire technologies, such as fuel-efficient and eco-friendly options, have solidified its leading position in the global automotive tire industry.
 To learn more about this report, Download Free Sample Report
China hold major share in Asia Pacific region, attributed to its vast automotive industry and increasing vehicle production. As the world’s largest vehicle manufacturer and consumer, the demand for tires in China is surging, driven by the rapid increase in passenger and commercial vehicles. In addition, the rise of electric vehicles (EVs) and government initiatives supporting infrastructure development further stimulate tire demand. The government's push for electric vehicles and advancements in tire technologies, such as eco-friendly and fuel-efficient options, further bolster China’s prominence in the global market.
Japan held a considerable revenue share in 2024, spurred by its advanced automotive industry, innovation in tire technology, and focus on sustainability. As a major hub for automakers such as Toyota, Honda, and Nissan, Japan drives high demand for high-performance and eco-friendly tires. The growing adoption of electric vehicles (EVs) further spurs the need for specialized tires. Japan’s commitment to cutting-edge tire designs, improved fuel efficiency, and reduced environmental impact positions it as a crucial contributor to global tire market growth.
Key Automotive Tire Company Insights
Some of the key companies in the automotive tire market include Continental Group, Cooper & Rubber Company, Hankook Co. Ltd., Goodyear & Rubber Company, Michelin Group, Pirelli, Sumitomo Rubber Industries Ltd., The Bridgestone Group, Toyo & Rubber Co Ltd., and Yokohama Rubber Co. Ltd, and others.
- Continental Group offers many products and solutions, including premium car, truck, and motorcycle tires and advanced automotive technologies for safety, autonomous driving, and connectivity.
- Cooper & Rubber Company, now part of Goodyear, provides a comprehensive portfolio of replacement tires for automobiles and commercial vehicles, known for their quality and performance.
Key Automotive Tire Companies:
The following are the leading companies in the automotive tire market. These companies collectively hold the largest market share and dictate industry trends.
- Continental Group
- Cooper & Rubber Company
- Hankook Co. Ltd.,
- Goodyear & Rubber Company
- Michelin Group
- Pirelli
- Sumitomo Rubber Industries Ltd.
- The Bridgestone Group
- Toyo & Rubber Co Ltd.
- Yokohama Rubber Co. Ltd
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Michelin, Bridgestone, Goodyear, Continental, Pirelli)
- Focus on premium tire offerings, continuous innovation in EV-specific tires, smart tire technologies, sustainable materials, and fuel-efficient tire solutions.
- Maintain strong OEM partnerships with leading vehicle manufacturers while expanding premium replacement tire portfolios and digital fleet management services.
- Strong global manufacturing footprint, established brand reputation, broad product portfolios, and long-standing OEM relationships.
- Advanced technology capabilities, premium pricing power, extensive distribution networks, and strong aftermarket presence support market leadership.
- High manufacturing and operating costs, significant exposure to raw material price fluctuations, and dependence on mature automotive markets for a substantial portion of revenue.
- Large organizational structures may slow down responsiveness to rapidly changing regional market dynamics.
Emerging and Regional Players (Hankook Tire & Technology, Sumitomo Rubber Industries, Toyo Tire)
- Focus on balancing performance and affordability through expansion in OEM supply, replacement markets, SUV tires, and commercial vehicle tires.
- Competitive pricing, strong presence in high-growth developing markets, lower manufacturing costs, and ability to serve value-conscious customers.
- Limited premium brand recognition, weaker penetration in high-end OEM and performance tire segments, and comparatively lower investment in advanced tire technologies.
Recent Developments
-
In June 2023, Continental introduced the UltraContact NXT, its most sustainable tire series, designed to deliver optimal safety and performance while incorporating 65% renewable, recycled, and mass balance certified materials.
-
In June 2023, Michelin introduced the Air X SkyLight tire for commercial aviation, offering a 10-20% reduction in weight compared to previous generations. This lighter design contributes to a 15-20% improvement in long-term performance and lifespan.
Automotive Tire Market Report Scope
Report Attribute
Details
Market size in 2025
USD 431.0 million
Estimated Market Size in 2026
USD 462.5 million
Projected Market Size by 2033
USD 781.4 million
Growth rate
CAGR of 7.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, season type, rim, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; Italy; Spain China; Japan; India; Australia; South Korea; Brazil; Kingdom of Saudi Arabia (KSA); UAE; South Africa
Key companies profiled
Continental Group, Cooper & Rubber Company, Hankook Co. Ltd., Goodyear & Rubber Company, Michelin Group, Pirelli, Sumitomo Rubber Industries Ltd., The Bridgestone Group, Toyo & Rubber Co Ltd., and Yokohama Rubber Co. Ltd
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Tire Market Report Segmentation
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global automotive tire market report on the basis of type, application, season type, rim size, and region:
-
Type Outlook (Revenue, USD Million, 2021- 2033)
-
Radial
-
Bias
-
-
Application Outlook (Revenue, USD Million, 2021- 2033)
-
Passenger cars
-
LCV
-
HCV
-
Two-wheelers
-
-
Season Type Outlook (Revenue, USD Million, 2021- 2033)
-
Summer Tire
-
Winter Tire (Studded and Non-studded)
-
All-season Tire
-
-
Rim size Outlook (Revenue, USD Million, 2021- 2033)
-
Less Than 15 Inches
-
15 to 20 Inches
-
More than 20 Inches
-
-
Regional Outlook (Revenue, USD Million, 2021- 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
- South Korea
-
-
Latin America
-
Brazil
-
-
Middle East and Africa
-
Saudi Arabia
-
United Arab Emirates (UAE)
-
South Africa
-
-
Research Methodology
Segment Definition
Type
Revenue Capture Definition
Radial
Revenue is primarily captured through OEM supply agreements with passenger vehicle, SUV, commercial vehicle, and EV manufacturers, alongside replacement tire sales through dealer networks and retail channels. Premium radial tires generate higher margins due to advanced tread designs, fuel-efficiency benefits, longer lifespan, and EV-specific performance characteristics.
Bias
Revenue is generated mainly through OEM and replacement sales for agricultural equipment, construction machinery, mining vehicles, industrial vehicles, and select commercial vehicle applications. Demand is concentrated in cost-sensitive markets and off-road environments where durability and sidewall strength are prioritized over fuel efficiency. Revenue is largely driven by replacement demand and fleet procurement contracts.
Application
Revenue Capture Definition
Passenger Cars
Revenue is generated through the sale of tires designed for passenger cars, including sedans, hatchbacks, SUVs, and crossovers. This segment captures the largest share of market revenue due to the substantial global passenger vehicle parc and recurring replacement demand. Revenue is derived from both OEM fitments and aftermarket tire replacements, with premium, EV-specific, and high-performance tires contributing significantly to value growth.
LCV
Revenue is generated through the sale of tires used on light commercial vehicles such as vans, pickups, and small delivery trucks. Demand is supported by OEM installations and replacement purchases driven by commercial transportation, urban delivery services, and fleet operations. Higher vehicle utilization rates contribute to recurring replacement tire demand.
HCV
Revenue is captured through the sale of tires for heavy commercial vehicles, including trucks, buses, trailers, and specialized freight vehicles. Although vehicle volumes are lower than passenger cars, higher tire consumption per vehicle and frequent replacement cycles contribute significantly to segment revenue. Premium commercial tires and retread-compatible products further support revenue generation.
Two-Wheelers
Revenue is generated through the sale of tires used on motorcycles, scooters, mopeds, and electric two-wheelers. The segment benefits from large vehicle populations in Asia-Pacific and frequent replacement cycles. Revenue is derived from both OEM supply agreements and high-volume aftermarket sales.
Season Type
Revenue Capture Definition
Summer Tire
Revenue is primarily captured through OEM fitments and replacement sales in regions with predominantly warm climates. Premium and performance vehicle owners contribute significantly to revenue through purchases of ultra-high-performance summer tires that offer enhanced handling, braking, and fuel efficiency.
Winter Tire (Studded and Non-studded)
Revenue is generated through seasonal replacement purchases in regions experiencing snow and icy conditions. Demand is supported by regulatory requirements in several countries, with consumers often maintaining dedicated winter tire sets, creating recurring seasonal revenue opportunities for manufacturers and dealers.
All-season Tire
The dominant revenue segment globally, capturing income through OEM installations and replacement purchases by consumers seeking year-round tire performance. Revenue growth is supported by increasing adoption among passenger vehicles, SUVs, and crossovers due to convenience, lower ownership costs, and improved all-weather capabilities.
Rim Size
Correct Revenue Capture Definition
Less Than 15 Inches
Revenue is generated through OEM and replacement sales of tires designed for compact and entry-level passenger vehicles using wheel diameters below 15 inches. Demand is primarily volume-driven and concentrated in emerging markets where smaller vehicles maintain a significant share of the vehicle parc.
15 to 20 Inches
Revenue is captured through the sale of tires fitted on mainstream passenger cars, SUVs, crossovers, and light commercial vehicles. This segment generates the largest share of industry revenue due to its extensive OEM fitment base and substantial replacement tire demand across global vehicle fleets.
More than 20 Inches
Revenue is generated through premium, luxury, performance, and electric vehicle tire sales designed for larger wheel diameters exceeding 20 inches. Although unit volumes are lower, higher average selling prices and premium product positioning contribute disproportionately to segment revenue.
Estimation Model
Layer Name
Key Question
Description
Vehicle Population Layer
What creates tire demand?
Global vehicle parc and annual vehicle production by passenger cars, LCVs, HCVs, and two-wheelers.
Tire Consumption Layer
How many tires are required?
Tire fitment per vehicle, OEM tire demand, replacement demand, spare tire demand, and penetration of radial, bias, summer, winter, and all-season tires.
Tire Replacement Intensity Layer
How often are tires replaced?
Replacement frequency based on mileage, operating conditions, climate, vehicle age, fleet utilization, and regulatory standards.
Revenue Layer
How is revenue captured?
Revenue generated from the sale of tires across vehicle types, tire types, rim sizes, and seasonal categories through OEM and aftermarket channels, including premium and EV-specific tire solutions.
Customization Table
Client Request
Customization Delivered
Value Adds
Automotive Tire Market Assessment
- Structured evaluation of market dynamics including key drivers, restraints, and emerging opportunities across the tire value chain.
- Assessment of technology evolution across tire materials, tread designs, EV-specific tires, smart tire technologies, and sustainability initiatives.
- Clear visibility into growth drivers and market challenges.
- Strategic input for market entry, expansion planning, and investment decisions.
End-Use and Application Insights
- Analysis of demand distribution across passenger cars, LCVs, HCVs, and two-wheelers.
- Evaluation of shifting vehicle preferences toward SUVs, electric vehicles, commercial fleets, and mobility solutions influencing tire demand.
- Identification of high-growth and high-value vehicle segments.
- Support for targeted product positioning and portfolio optimization.
Technology and Competitive Landscape Review
- Benchmarking of key tire technologies including radial and bias tires, low rolling resistance tires, run-flat tires, all-season tires, and smart tire solutions.
- Analysis of major players' innovation focus, product differentiation, manufacturing footprint, OEM partnerships, and regional penetration.
- Competitive intelligence for technology positioning and market differentiation.
- Guidance for R&D prioritization, product development, and strategic partnerships.
Frequently Asked Questions About This Report
The global Automotive Tire market size was estimated at USD 430.9 million in 2025 and is expected to reach USD 462.5 million in 2026.
The global Automotive Tire market is expected to grow at a compound annual growth rate of 7.8% from 2026 to 2033 to reach USD 781.4 million by 2033.
Asia Pacific dominated the Automotive Tire market with a share of 42.2% in 2025. This is attributable to rapidly growing domestic consumption, evolving standards, cheap labor, and a large base of the population.
Some key players operating in the Automotive Tire market include Continental Group, Cooper & Rubber Company, Hankook Co. Ltd., Goodyear & Rubber Company, Michelin Group, Pirelli, Sumitomo Rubber Industries, Ltd., The Bridgestone Group, and Toyo & Rubber Co. Ltd.
Key factors that are driving the market growth include a growing number of commercial and passenger vehicles globally, and companies launching innovative products.
Based on type, the Radial segment led the market with the largest revenue share of 59.4% in 2025.
Based on rim size, the 15 to 20 Inches segment led the market with the largest revenue share of 64.9% in 2025.
Based on application, the passenger cars segment led the market with the largest revenue share of 56.1% in 2025.
All-season tire segment led the market with the largest revenue share of 52.2% in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


