
- Home
- »
- Pharmaceuticals
- »
-
Benzathine Penicillin G Market Size, Share Report, 2026-2035GVR Report cover

Benzathine Penicillin G Market (2026 - 2035)
Size, Share & Trends Analysis Report By Application (Syphilis, Rheumatic Fever), By Mode of Injection (Intramuscular, Intravenous), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$512.0MMarket Estimate, 2026
$542.7MMarket Forecast, 2035
$916.9MCAGR, 2026–2035
6.0%Benzathine Penicillin G Market Summary
The global benzathine penicillin G market size was valued at USD 512.0 million in 2025 and is projected to grow from USD 542.7 million in 2026 to USD 916.9 million by 2035, at a CAGR of 6.0% from 2026 to 2035. North America dominated the market, accounting for the largest revenue share in 2025. The market growth is driven by the rising prevalence of syphilis and rheumatic fever, increasing public health initiatives for infectious disease management, and growing demand for effective long-acting antibiotic therapies.
Key Market Trends & Insights
- By application: The rheumatic fever segment held the largest market share in 2025.
- By mode of injection: The intramuscular segment accounted for the largest market share in 2025.
- By end use: The hospitals & clinics segment dominated with the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2035)
Market Size & Forecast
- Market size in 2025: USD 512.0 Million
- Estimated market size in 2026: USD 542.7 Million
- Projected market size by 2035: USD 916.9 Million
- CAGR (2026-2035): 6.0%
Prism AI by Grand View Research Free to tryAsk a question about the benzathine penicillin g marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Expanding healthcare access and disease prevention programs are further supporting market growth, particularly across emerging regions.
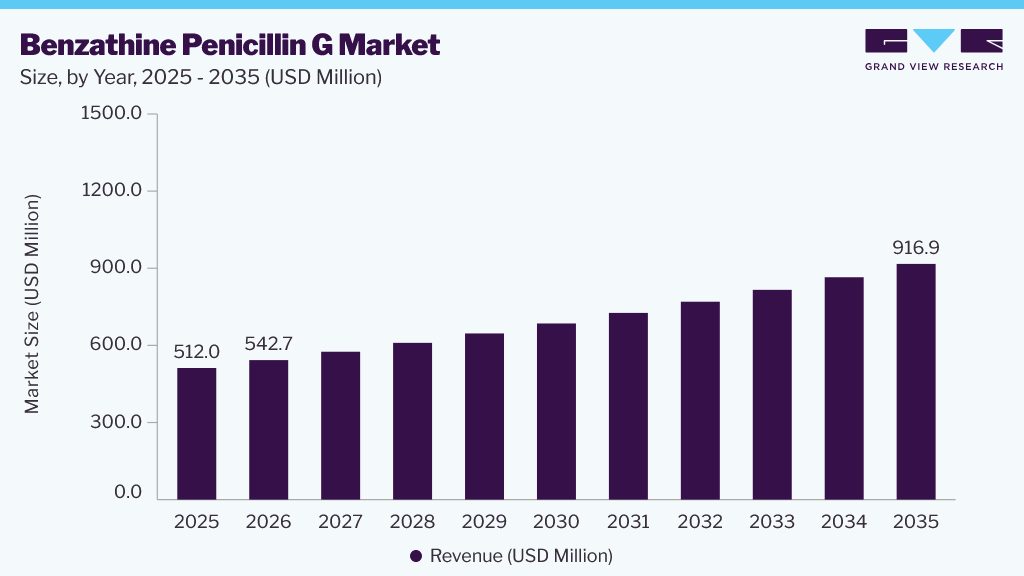 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The market is primarily driven by the increasing prevalence of syphilis and rheumatic fever, along with growing emphasis on infectious disease prevention and treatment programs worldwide. The continued recommendation of Benzathine Penicillin G as a first-line therapy for syphilis and as a preventive treatment for recurrent rheumatic fever is supporting consistent demand. Rising healthcare awareness, expansion of screening initiatives, and government-led public health campaigns aimed at controlling sexually transmitted infections are further contributing to market growth.
However, factors such as antibiotic resistance concerns, supply chain challenges associated with injectable drug manufacturing, and limited availability of trained healthcare professionals for injection-based treatments may restrain market expansion. The market presents significant opportunities through improving healthcare infrastructure in emerging economies, increasing access to essential medicines, and the expansion of national disease control programs.
Growing investments in maternal healthcare and syphilis prevention initiatives are expected to create new growth opportunities, particularly in developing regions. In addition, advancements in pharmaceutical manufacturing, improved supply reliability, and collaborations between healthcare organizations and drug manufacturers can support broader availability of Benzathine Penicillin G. Moreover, increasing focus on eliminating preventable infectious diseases and strengthening primary healthcare systems is expected to provide sustained growth opportunities during the forecast period.
Analyst Perspective
The benzathine penicillin G market is expected to witness steady growth, supported by its continued role as an essential antibiotic for syphilis treatment and rheumatic fever prevention. Increasing global efforts to control sexually transmitted infections and strengthen infectious disease management programs are likely to sustain demand. Healthcare systems are focusing on improving access to essential medicines, particularly in emerging economies with rising treatment needs. The market is also benefiting from increased awareness regarding early diagnosis and preventive care initiatives. However, supply constraints, limited manufacturing capacity, and challenges associated with injectable antibiotic administration may influence market growth. Companies are expected to focus on improving production reliability and expanding distribution networks to enhance accessibility. Growing investments in public health infrastructure and disease elimination programs will remain key factors shaping future market opportunities.
Application Insights
The rheumatic fever segment accounted for the largest market revenue share in 2025. Benzathine Penicillin G plays a crucial role in the long-term prevention of recurrent rheumatic fever and rheumatic heart disease through regular prophylactic treatment. The segment benefits from established clinical guidelines, continued demand for secondary prevention therapies, and the ongoing burden of streptococcal infections in developing regions. Government-led initiatives aimed at reducing rheumatic heart disease prevalence and improving access to essential antibiotics are supporting sustained adoption of Benzathine Penicillin G. The requirement for repeated long-acting injections over extended treatment periods further contributes to stable product demand in this application area.
The syphilis segment is expected to grow at the fastest CAGR over the forecast period. Increasing global incidence of syphilis, rising screening rates, and growing emphasis on maternal and congenital syphilis prevention are key factors driving segment expansion. Benzathine Penicillin G remains the preferred first-line therapy for syphilis, particularly among pregnant patients, due to its proven effectiveness and long-acting formulation. Expanding public health programs, improving disease surveillance, and efforts to strengthen access to essential medicines are expected to create significant growth opportunities. For instance, in August 2025, Pfizer issued an availability update for Bicillin L-A (benzathine penicillin G) prefilled syringes, announcing phased resumption of shipments while maintaining supply allocation due to ongoing demand pressures. This trend highlights the importance of maintaining access to Benzathine Penicillin G for syphilis treatment programs. This increasing focus on ensuring treatment availability is expected to support the growth of the syphilis application segment during the forecast period.
Mode of Injection Insights
The intramuscular segment accounted for the largest market revenue share in 2025 and is expected to grow at the fastest CAGR over the forecast period. Benzathine Penicillin G is predominantly administered through deep intramuscular injection due to its long-acting formulation, which allows gradual absorption and prolonged therapeutic activity compared with conventional antibiotic delivery methods. The segment’s leadership is supported by its established role in the treatment of syphilis and the secondary prevention of rheumatic fever, in which maintaining effective antibiotic levels over time is essential. Growing demand for long-acting injectable therapies, increasing focus on improving treatment adherence, and continued use of Benzathine Penicillin G in public health programs are expected to strengthen segment growth. In addition, the preference of healthcare providers for reliable and well-established administration methods further supports the widespread adoption of intramuscular formulations.
The intravenous segment is expected to grow at a steady CAGR during the forecast period. The segment accounts for a smaller share as Benzathine Penicillin G is specifically developed as a long-acting intramuscular formulation, making intravenous administration less common in clinical practice. However, increasing healthcare infrastructure development, advancements in antibiotic delivery approaches, and the need for alternative treatment options in specific clinical situations may provide gradual growth opportunities. Despite these factors, intramuscular administration is expected to remain the preferred route due to its proven efficacy, convenience, and alignment with established treatment guidelines.
End use Insights
The hospitals & clinics segment accounted for the largest market revenue share in 2025, and is expected to grow at the fastest CAGR over the forecast period. Hospitals and clinics are the primary healthcare settings for Benzathine Penicillin G administration due to their role in diagnosing and managing infectious diseases such as syphilis and rheumatic fever. The segment benefits from the availability of trained healthcare professionals, established treatment protocols, and better access to injectable antibiotic therapies. Increasing patient visits for infectious disease management, expansion of public health treatment programs, and growing emphasis on early diagnosis and prevention of complications are supporting the continued adoption of Benzathine Penicillin G in hospitals and clinical settings.
The ambulatory surgical centers segment is expected to grow at a significant CAGR during the forecast period. Increasing adoption of outpatient care models, improving healthcare accessibility, and the shift toward cost-effective treatment environments are supporting the expansion of ambulatory healthcare facilities. These centers provide convenient settings for administering injectable therapies while reducing the burden on hospitals. However, their adoption remains comparatively lower due to the requirement for specialized medical supervision and infrastructure for antibiotic administration. Diagnostic Centers and Research Centers are expected to account for smaller shares, with demand primarily driven by disease screening, clinical research activities, and development of improved treatment approaches.
Regional Insights
North America dominated the global benzathine penicillin G market with the largest revenue share in 2025, supported by advanced healthcare infrastructure, strong infectious disease surveillance systems, and established access to essential antibiotic therapies. Rising syphilis cases, increasing screening initiatives, and growing emphasis on maternal and congenital syphilis prevention are driving demand for benzathine penicillin G across the region. The presence of well-developed healthcare networks, regulatory support, and public health programs further strengthens regional market growth.
In October 2025, the Pan American Health Organization (PAHO) presented a regional agreement to eliminate syphilis and congenital syphilis in the Americas, introducing 15 key recommendations focused on improving diagnosis, treatment access, surveillance, and healthcare system response. The initiative highlighted the increasing burden of syphilis cases in the region and the need to strengthen access to effective treatments such as benzathine penicillin G.
Asia Pacific Benzathine Penicillin G Market Trends
The benzathine penicillin G market in the Asia Pacific is expected to grow at the fastest CAGR over the forecast period, driven by expanding healthcare access, a large patient population, and a growing focus on infectious disease control. Growing awareness of sexually transmitted infections, expansion of maternal healthcare programs, and improved availability of essential medicines are supporting market expansion across emerging economies. Countries such as India, China, and Southeast Asian nations are strengthening healthcare infrastructure and increasing investments in disease prevention and treatment programs. The growing presence of domestic pharmaceutical manufacturers and improving distribution networks are further creating opportunities for the adoption of Benzathine Penicillin G across the region.
Key Benzathine Penicillin G Company Insights
The benzathine penicillin G industry is characterized by a competitive landscape shaped by supply reliability, manufacturing capabilities, regulatory compliance, and distribution strength. Market participants are focusing on strengthening production capacity, optimizing supply chains, and improving access to long-acting antibiotic therapies to address rising treatment demand. The market dynamics are influenced by the need for consistent availability of essential medicines, particularly for treatment of syphilis and rheumatic fever.
Key Benzathine Penicillin G Companies
The following key companies have been profiled for this study on the global benzathine penicillin G market:
-
Pfizer Inc.
-
Sandoz Group AG
-
Viatris Inc.
-
Hikma Pharmaceuticals PLC
-
Novartis AG
-
Aurobindo Pharma Limited
-
Teva Pharmaceutical Industries Ltd.
-
F. Hoffmann-La Roche Ltd.
-
Atral Laboratories
-
Wockhardt Limited
Recent Developments
-
In June 2026, the U.S. FDA permitted the temporary importation of Lentocilin (benzathine benzylpenicillin), manufactured by Laboratórios Atral S.A., Portugal, and distributed through the Mark Cuban Cost Plus Drug Company Marketplace, to help mitigate the ongoing Bicillin L-A shortage in the U.S. and maintain access to long-acting benzathine penicillin therapy.
-
In June 2026, the Maine Center for Disease Control and Prevention (Maine CDC) issued a health advisory regarding the extended Bicillin L-A shortage in the U.S., highlighting continued efforts to manage Benzathine Penicillin G availability and prioritize treatment access for critical patient groups.
Benzathine Penicillin G Market Report Scope
Report Attribute
Details
Market size in 2025
USD 512.0 million
Estimated market size in 2026
USD 542.7 million
Projected market size by 2035
USD 916.9 million
Growth rate
CAGR of 6.0% from 2026 to 2035
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2035
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2035
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, mode of injection, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; Japan; India; Australia; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Pfizer Inc.; Sandoz Group AG; Viatris Inc.; Hikma Pharmaceuticals PLC; Novartis AG; Aurobindo Pharma Limited; Teva Pharmaceutical Industries Ltd.; F. Hoffmann-La Roche Ltd.; Atral Laboratories; Wockhardt Limited
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Benzathine Penicillin G Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2035. For this study, Grand View Research has segmented the global benzathine penicillin G market report based on application, mode of injection, end use, and region:
-
Application Outlook (Revenue, USD Million, 2021 - 2035)
-
Syphilis
-
Rheumatic Fever
-
-
Mode of Injection Outlook (Revenue, USD Million, 2021 - 2035)
-
Intramuscular
-
Intravenous
-
-
End use Outlook (Revenue, USD Million, 2021 - 2035)
-
Hospitals & Clinics
-
Ambulatory Surgical Centers
-
Diagnostic Centers
-
Research Centers
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2035)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The global Benzathine Penicillin G market size was valued at USD 512.0 million in 2025 and is estimated at USD 542.7 million for 2026.
The global Benzathine Penicillin G market is expected to grow at a CAGR of 6.0% from 2026 to 2035, reaching USD 916.9 million.
The rheumatic fever segment accounted for the largest revenue share in 2025.
North America dominated with the largest revenue share in 2025.
Key players in the market include Pfizer Inc., Sandoz Group AG, Viatris Inc., Hikma Pharmaceuticals PLC, Novartis AG, Aurobindo Pharma Limited, Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd., Atral Laboratories, and Wockhardt Limited.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


