
- Home
- »
- Medical Devices
- »
-
Biosensors Market Size, Share & Trends Report, 2026-2033GVR Report cover

Biosensors Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Electrochemical, Thermal, Piezoelectric), By Application (Medical, Bioreactor, Agriculture), By End Use (PoC Testing, Food Industry), By Region, And Segment Forecasts
Market Size, 2025
$32.2BMarket Estimate, 2026
$34.7BMarket Forecast, 2033
$64.0BCAGR, 2026–2033
9.1%Biosensors Market Summary
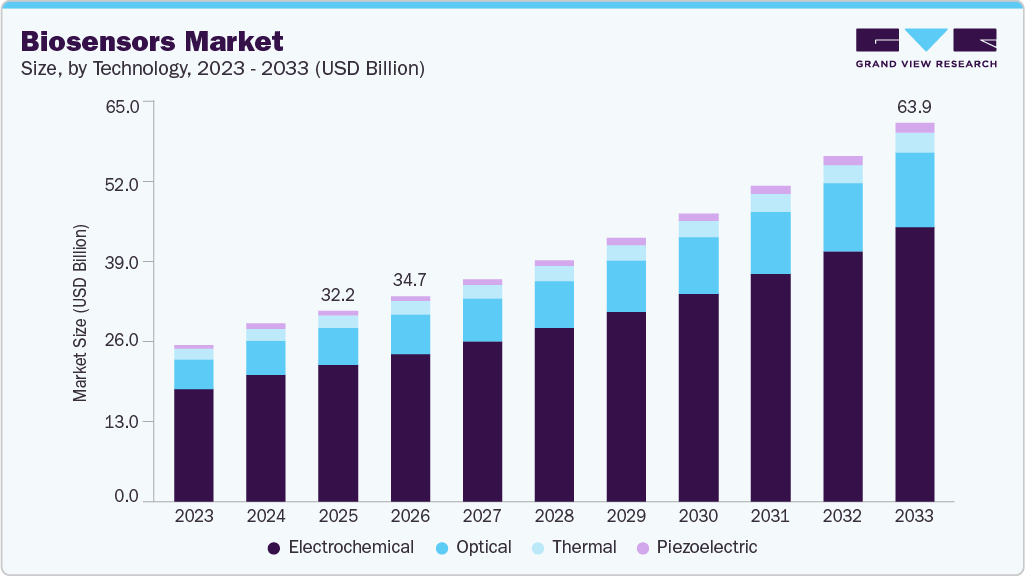
The global biosensors market size was valued at USD 32.2 billion in 2025 and is projected to grow from USD 34.7 billion in 2026 to USD 64.0 billion by 2033, at a CAGR of 9.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 42.6% in 2025. The demand for biosensors is increasing due to the diversity of medical applications, growing prevalence of chronic and non-communicable diseases such as diabetes and hypertension, high demand for compact diagnostic devices, and rapid technological advancements.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Electrochemical segment dominated the market, with a revenue share of 71.6% in 2025.
- By application: Medical segment held the largest market share of 66.8% in 2025.
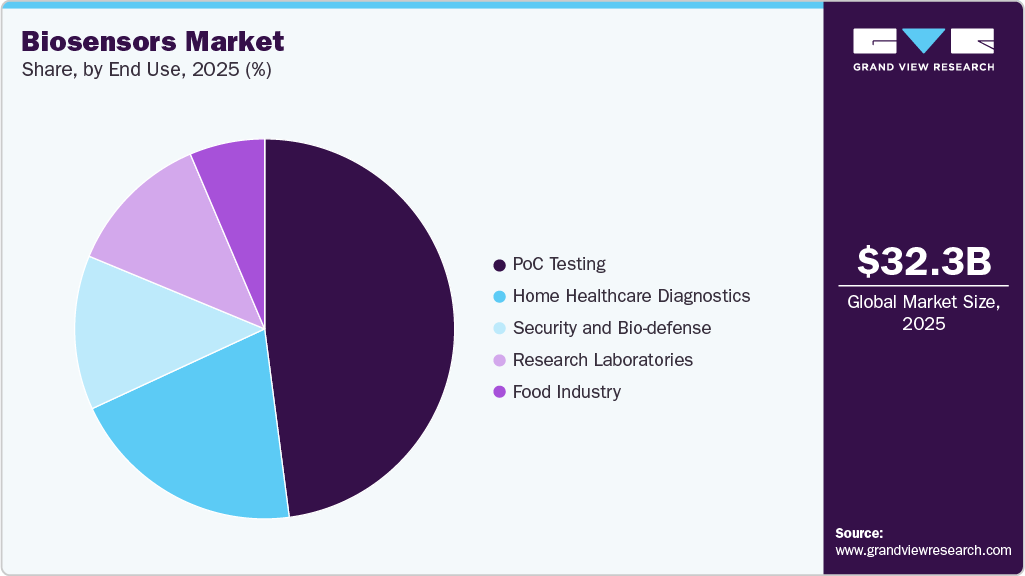
- By end use: Point-of-Care (PoC) segment accounted for the largest revenue share of 47.9% in 2025.
Regional Highlights
- Largest regional market: North America (42.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 32.2 Billion
- Estimated market size in 2026: USD 34.7 Billion
- Projected market size by 2033: USD 64.0 Billion
- CAGR (2026-2033): 9.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The increasing demand for health monitoring and fitness tracking, coupled with rising interest in personalized digital wellness, is a primary driver in the growth of the market. In addition, nanotechnology-based biosensors are expected to have wide application scope in various industries, such as food analysis, imaging, and microbial activity monitoring. The global market is consolidating due to the growing preference for non-invasive wearable biosensors, rising popularity of medical devices & specialty drugs, and increasing research collaborations between various manufacturers.Moreover, biosensors enable continuous, real-time monitoring of physiological metrics such as heart rate, sleep patterns, blood oxygen saturation, and steps taken, providing actionable data for consumers and healthcare professionals. For instance, according to an article published by the University of Arizona Health Sciences in June 2025, advanced sensor platforms use deep learning models to predict physiological events, including labor onset and stress response, from high-frequency biometric data. These devices serve as an early warning system to detect health risks prior to symptom onset. This approach transforms health management from episodic to proactive intervention, reducing the burden of late diagnoses and emergency care.
 To learn more about this report, Download Free Sample Report
Similarly, the Cardiosense CardioTag is a significant example of this trend. It is an FDA-cleared, multimodal wearable sensor for cardiac monitoring, combining ECG (electrocardiogram), PPG (photoplethysmogram), and SCG (seismocardiogram) signals. It leverages advanced AI algorithms to analyze these high-fidelity signals for early heart failure detection, comprehensive cardiac assessment, and personalized therapy guidance, enabling noninvasive measurement of cardiac mechanics, hemodynamics (such as left ventricular ejection time), and volume status in both clinical and home settings.
Furthermore, advances in artificial intelligence, machine learning, and sensor miniaturization have significantly enhanced the functionality and accuracy of wearable devices. Integration of AI algorithms enables real-time data processing, predictive analytics, and personalized feedback. In patient management, Medtronic’s edge AI-enabled insulin delivery systems demonstrate clinical-grade, real-time decision-making by fusing biosensor streams for dynamic insulin dose adjustment. This system highlights the capability of AI-enabled wearables to deliver responsive, personalized interventions without requiring external connectivity, thereby supporting precision medicine in ambulatory settings. In addition, smart rings are gaining traction due to improved measurement accuracy from finger-based sensors and enhanced comfort for 24-hour wear.
Furthermore, increasing partnerships and collaborations withing the industry contribute to market growth. For instance, partnerships between French firms and global startups, such as Livingston’s collaboration for biosensors and wearables in June 2025, enable scalable production and global market reach. This expansion supports personalized fitness, wellness, and lifestyle applications, reflecting increasing adoption among fitness enthusiasts and urban consumers.
“The diagnostics industry has changed post COVID, wearable technology has risen up the agenda, along with AI having an increasing impact, and we think the collaboration with Linxens will keep us ahead of the curve while significantly improving our market reach.”-Kevin Fallon, FlexMedical’s CEO and co-founder,
“This collaboration expands our biosensor portfolio by integrating functionalisation capabilities, enabling us to deliver end-to-end solutions - from flex-PCB or printed electrodes to fully functional sensor platforms. Together, we streamline the journey from R&D to mass production, accelerating the delivery of innovative diagnostic solutions.”
-Minh Le, vice-president of Linxens Healthcare
Market Dynamics
The market growth is driven by the increasing prevalence of chronic diseases, rising demand for point-of-care diagnostics, expanding adoption of wearable health-monitoring devices, and continuous advancements in biosensor technologies. Growing investments in personalized medicine, remote patient monitoring, and non-invasive diagnostic solutions are further driving market growth. The increasing use of biosensors in food safety, environmental monitoring, and bioprocessing also supports market expansion. However, stringent regulatory approval requirements, high development costs, limited stability of biological sensing elements, and challenges related to sensor accuracy and calibration may hinder market growth.
Rapid technological advancements are a key driver of the biosensors market, enabling the development of highly sensitive, accurate, and portable diagnostic devices. Innovations in nanotechnology, microelectronics, artificial intelligence (AI), and wireless connectivity have enhanced real-time monitoring capabilities and expanded biosensor applications across healthcare, environmental monitoring, and food safety. The growing adoption of wearable and point-of-care biosensors is further accelerating market growth by supporting continuous health monitoring and early disease detection. For instance, in April 2026, UltraGreen Cardiac Technologies partnered with LifeSignals to globally distribute advanced wearable cardiac monitoring biosensors, expanding access to remote cardiac diagnostics and strengthening digital health monitoring capabilities.
"This partnership reflects our commitment to building clinically relevant, data-driven platforms that address real capacity challenges in healthcare systems globally. In addition to addressing growing cardiology demand, wearable monitoring plays an increasingly important role in patient care."
- Ravi Sajwan, CEO, UltraGreen
High development and manufacturing costs remain a significant restraint for the biosensors market. The design and production of biosensors require advanced materials, sophisticated microelectronics, specialized fabrication processes, and extensive research and development investments. In addition, integrating technologies such as artificial intelligence, wireless connectivity, and miniaturized components increases overall production costs, making advanced biosensor devices more expensive for manufacturers and end users.
Moreover, stringent regulatory requirements, clinical validation procedures, and quality assurance standards increase the time and cost of bringing new biosensor products to market. Small and emerging companies often face challenges in securing sufficient funding for product development and commercialization, while high device costs can limit adoption in price-sensitive healthcare systems and developing regions, thereby restraining market growth.
The integration of artificial intelligence (AI) with multiplex and non-invasive biosensors presents a significant opportunity for the biosensors market. Advanced biosensors are increasingly capable of detecting multiple biomarkers simultaneously from non-invasive samples such as sweat, saliva, tears, and interstitial fluid. AI-powered analytics can process this data in real time to support early disease detection, personalized treatment decisions, and continuous remote patient monitoring. Growing demand for preventive healthcare, wearable medical devices, and decentralized diagnostics is expected to accelerate the adoption of these technologies, creating new growth opportunities for biosensor manufacturers.
For instance, in July 2025, Trinity Biotech plc unveiled CGM+, an AI-native continuous glucose monitoring (CGM) platform that combines wearable biosensor technology with real-time analytics and multi-sensor data integration. The platform is designed to enhance personalized diabetes management and reflects the industry's shift toward AI-enabled biosensors for continuous health monitoring.
Market Concentration & Characteristics
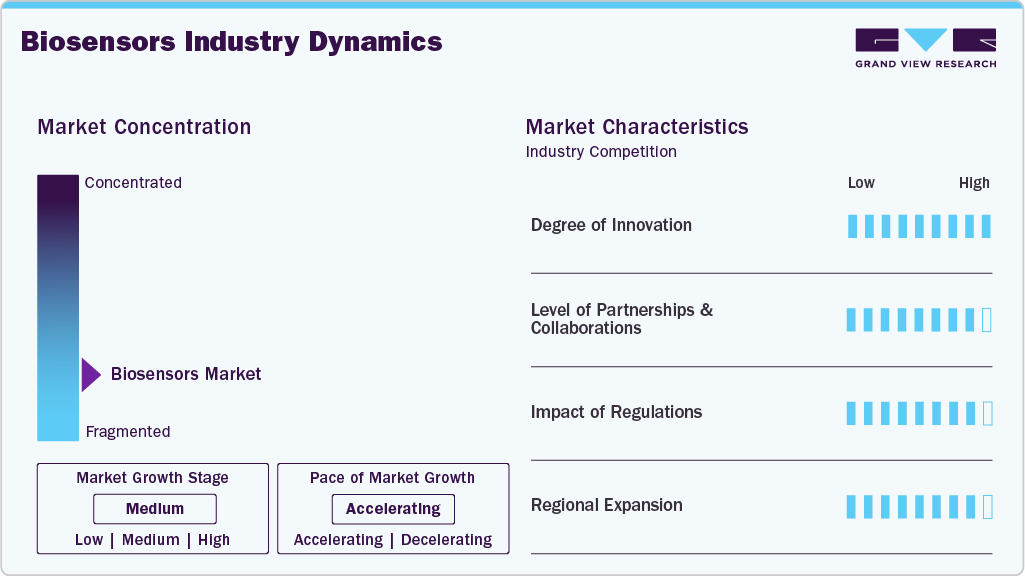
The chart below illustrates the relationship between industry concentration, industry characteristics, and industry participants. The x-axis represents the level of industry concentration, ranging from low to high. The y-axis represents various industry characteristics, including industry competition, level of partnerships & collaborations, degree of innovation, impact of regulations, and regional expansion. The biosensors industry is fragmented. Several emerging players are entering the market, thereby contributing to increased fragmentation within the market. The degree of innovation, the level of partnerships & collaborations, the impact of regulations, and the regional expansion of industry is high.
The biosensors industry is characterized by constant innovation. Biosensors have made rapid advances in the medical field due to their ability to meet various criteria through a combination of interdisciplinary approaches in chemistry, nanotechnology, and medicine. For instance, the Ring AIR by Ultrahuman Healthcare Pvt Ltd. is a sleek, lightweight health tracker, designed for continuous, passive biometric monitoring. Featuring advanced sensors including infrared photoplethysmography (PPG), non-contact medical-grade skin temperature sensors, and 6-axis motion sensors, the Ring AIR measures heart rate, heart rate variability (HRV), blood oxygen saturation, skin temperature, movement, and sleep quality.
 To learn more about this report, Download Free Sample Report
The industry is experiencing a high level of partnerships & collaborations undertaken by several key players. This is due to the desire to gain a competitive advantage in the industry, enhance technological capabilities, and consolidate in a rapidly growing market. For instance, in November 2024, Dexcom and ŌURA announced a strategic partnership to integrate Dexcom glucose biosensor data with vital sign, sleep, stress, and activity metrics from the Oura Ring.
Regulations, such as the HIPAA in the U.S. and the GDPR in Europe, establish standards for safeguarding patient data privacy and security. Compliance with these regulations is crucial for AI applications in healthcare to ensure the safe and secure handling of patient information, reducing the risk of data breaches and unauthorized access.
The industry is witnessing high geographical expansion. Companies within the biosensors industry seek geographic expansion strategies to maintain their foothold in emerging markets and attract customers from these regions. For instance, in June 2025, Huawei launched Band 10 in India, featuring advanced health and fitness tracking, AI-powered swim stroke and lap recognition (with 95% accuracy), Pro-Level sleep analysis, and an emotional well-being assistant.
Analyst Perspective
The biosensors market is experiencing strong growth, driven by the rising prevalence of chronic diseases, the growing demand for point-of-care diagnostics, and the increasing adoption of wearable health monitoring devices. The expansion of personalized medicine, remote patient monitoring, and non-invasive diagnostic technologies is increasing the demand for advanced biosensors across healthcare, food safety, environmental monitoring, and bioprocessing applications. Technological advancements in AI-enabled biosensors, continuous monitoring systems, microfluidics, nanotechnology, and multiplex sensing are further accelerating market growth. Market participants are focusing on developing next-generation wearable biosensors, expanding digital health capabilities, improving sensor accuracy, and pursuing strategic partnerships, product launches, and regulatory approvals to strengthen their competitive position and address the evolving needs of healthcare and industrial applications.
Technology Insights
Based on technology, the electrochemical segment held the largest market share of 71.6% in 2025, owing to its ubiquitous use in biochemical and biological processes for measurement and analysis. For instance, AccuChek SmartGuide by F. Hoffmann-La Roche Ltd. It is an advanced continuous glucose monitoring (CGM) system featuring real-time, AI-enabled predictive analytics for diabetes management. The sensor provides accurate glucose readings every five minutes for up to 14 days, connecting wirelessly to the SmartGuide apps (monitoring and prediction).
The optical segment is expected to grow at the fastest CAGR during the forecast period. Optical biosensors are increasingly adopted for point-of-care testing due to their ability to provide real-time results with high accuracy, making them essential in critical care and emergency settings. The segment is experiencing robust growth, driven by the rising prevalence of chronic diseases and the demand for efficient monitoring systems.
Application Insights
Based on application, the medical segment accounted for the largest revenue share of 66.8% in 2025. Biosensors are used in the fields of cholesterol testing, blood glucose monitoring, drug discovery, pregnancy testing, blood gas analyzer, and infectious disorders in the medical segment. These devices are critical for point-of-care diagnostics, chronic disease monitoring, and real-time health tracking, supporting early intervention and personalized care. For instance, Signos Inc.’s Signos is an FDA-cleared metabolic health platform that combines a continuous glucose monitor (CGM) and an AI-powered app, designed for weight management and personalized healthy living. It uses a 15-day Dexcom Stelo glucose biosensor to deliver real-time continuous glucose data directly to your smartphone, enabling round-the-clock monitoring.
The agriculture segment is anticipated to grow at the fastest CAGR from 2026 to 2033, driven by the need for precision farming, sustainable practices, and real-time monitoring of crop and soil health. Biosensors enable farmers to detect pathogens, monitor nutrient levels, optimize irrigation, and manage pesticide use, leading to improved yields and reduced environmental impact. These devices are also critical for ensuring food safety by detecting contaminants and toxins in agricultural produce. The integration of IoT and smart farming technologies further enhances the utility and scalability of biosensors in modern agriculture. In January 2025, Classiq and Florence Quantum Labs collaborated to develop quantum-enhanced biosensors and AI-quantum hybrid algorithms for precision agriculture. Their work focuses on real-time soil health diagnostics, nutrient management, and ecosystem modeling, aiming to advance sustainable farming and global food security through scalable, climate-smart solutions.
End Use Insights
Based on end use, the Point-of-Care (PoC) segment held the largest market share of 47.9% in 2025. In addition, this segment is anticipated to grow at the fastest CAGR during the forecast period. Key factors driving segment growth include technological advancements that create innovative products, such as ultra-sensitive printable biosensors for PoC applications that help detect or monitor organic fluids like urine, saliva, blood, and sweat. For instance, in August 2022, NanoDx, Inc., a developer of innovative medical diagnostic solutions, and SkyWater Technology announced the first commercially available protein-responsive nano biosensor.
 To learn more about this report, Download Free Sample Report
The research laboratories segment is anticipated register a significant CAGR from 2026 to 2033. The research laboratories segment is a key end use in the biosensors industry, driving demand for advanced analytical platforms for drug discovery, biomarker identification, and disease research. These labs utilize biosensors for high-throughput screening, monitoring cell cultures, and validating new diagnostic assays, which accelerates the pace of scientific innovation. For instance, in December 2025, Monod Bio and Gator Bio partnered to integrate Monod’s AI-designed NovoBody binding proteins into Gator’s biolayer interferometry (BLI) biosensor platform. This collaboration advances next-generation biosensors for life science research, offering enhanced stability and performance compared to traditional antibodies.
Regional Insights
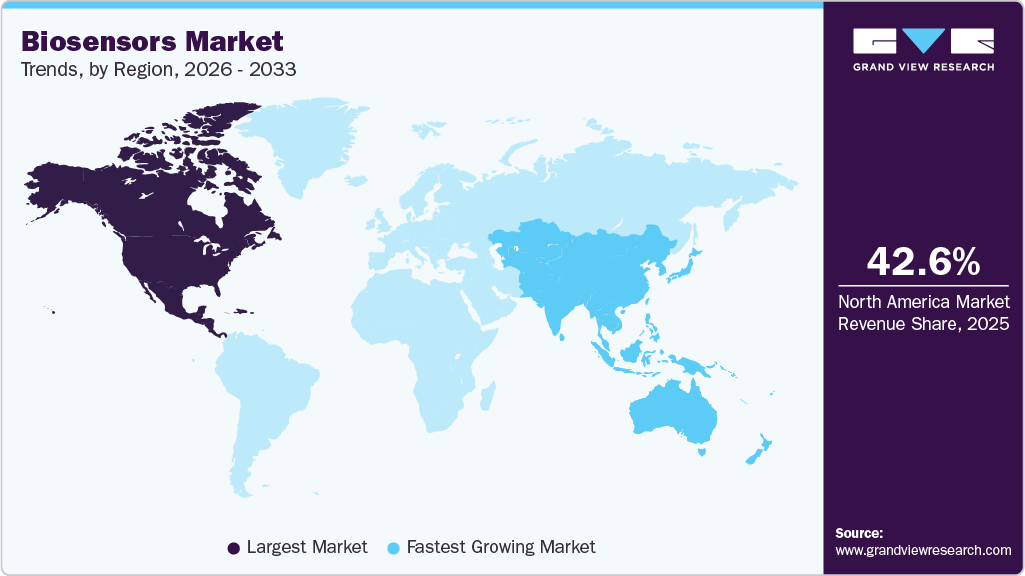
North America dominated the biosensors market with the largest revenue share of 42.6% in 2025. This is attributed to the high prevalence of chronic diseases, strong reimbursement frameworks, and rapid integration of advanced technologies such as AI and machine learning into digital health ecosystems. The U.S. leads with significant FDA clearances for AI-powered diagnostic and therapeutic devices, ensuring regulatory support for innovation. Moreover, rising collaborations between technology companies and healthcare providers further fuel innovation. For instance, in October 2024, Penn State received a USD 1.5 million NSF grant to develop AI-designed biosensors, aiming to systematically identify optimal materials for biosensing applications and accelerate device development.
 To learn more about this report, Download Free Sample Report
U.S. Biosensors Market Trends
The biosensors market in the U.S. held the largest share in the North America region in 2025. The country has witnessed a surge in approvals for wearable medical devices, reflecting robust innovation in healthcare technology. For instance, In May 2025, RingConn launched its Gen 2 Smart Ring for sleep apnea monitoring at Target.com, marking its U.S. retail debut. The slim, lightweight ring offers 10-12 days of battery life, real-time sleep health insights, and AI-driven personalized coaching. It tracks heart rate, SpO₂, skin temperature, activity, stress, and menstrual cycles, providing actionable recommendations to improve sleep and manage apnea.
Europe Biosensors Market Trends
Europe biosensors industry is expected to witness significant growth during the forecast period. This is attributed to the widespread adoption of biosensor technologies in healthcare and increasing investments by government and private organizations. Moreover, integrating 5G with healthcare drives Europe's market by enabling faster, more reliable connectivity for advanced sensor technologies.
The UK biosensors industry is expected to grow over the forecast period, owing to the robust healthcare infrastructure and increasing investments in AI technologies to enhance medical diagnosis and patient care. For instance, according to the two studies published in January 2023, researchers from University College London (UCL) used wearable motion sensors and AI to track progression in movement disorders, including Friedreich's ataxia and Duchenne muscular dystrophy. This technology identifies disease-specific movement patterns, predicts disease progression, and enhances trial efficiency and precision, enabling faster drug development, particularly for rare conditions with small patient populations.
Germany biosensors industry held the largest revenue share in 2025 in the European market, attributed to increasing investments in healthcare technology and robust healthcare infrastructure. In addition, favorable government initiatives, coupled with the country’s focus on integrating AI into nationwide healthcare, environmental, and agriculture systems, propel market growth further.
Asia Pacific Biosensors Market Trends
Asia Pacific biosensors industry is expected to grow at the fastest CAGR in the coming years. Rapid improvements in healthcare infrastructure, rising prevalence of chronic diseases, and increased demand for point-of-care diagnostics are key drivers of growth. Countries such as China, India, and Japan are making substantial investments in biotechnology, digital health, and medical device manufacturing, accelerating biosensor adoption in both clinical and consumer applications.
India biosensors industryis expanding rapidly. Rising prevalence of chronic diseases, demand for point-of-care diagnostics, and investments in healthcare infrastructure are key drivers of market expansion. The government’s focus on digital health initiatives and medical device manufacturing further accelerates adoption across hospitals, clinics, and research centers.
The Japan biosensors industry is driven by the country’s advanced digital infrastructure and rapidly aging population, creating demand for health monitoring and assisted living solutions. AI-enabled fitness bands, and medical-grade wearables are increasingly deployed for remote monitoring of elderly patients, fall detection, and chronic disease management.
Latin America Biosensors Market Trends
Latin America biosensors industry is anticipated to grow at a significant CAGR over the forecast period. This is attributed to the rising incidence of diabetes, cardiovascular disorders, and infectious diseases. Demand is concentrated in glucose monitoring, immunoassays, and point-of-care diagnostics. Improving healthcare access in urban centers supports adoption.
Middle East And Africa Biosensors Market Trends
Middle East and Africa biosensors industry is expected to grow at a significant CAGR over the forecast period. The market is characterized by a dynamic landscape driven by the growing adoption of technologically advanced medical devices, increasing healthcare expenditures and supportive government policies. Significant integration of AI in healthcare technology across the region contributes to market growth further.
Key Biosensors Company Insights
Key players operating in the biosensors industry are undertaking various initiatives to strengthen their market presence and increase the reach of their products and services. Strategies such as new product launches and partnerships play a key role in propelling market growth.
Key Biosensors Companies
The following key companies have been profiled for this study on the biosensors market.
-
Abbott Laboratories
-
Medtronic
-
Biosensors International Group
-
Pinnacle Technology, Inc.
-
Dupont.
-
Sensirion AG
-
Thermo Fisher Scientific, Inc.
-
F. Hoffmann-La Roche
-
Siemens Healthineers
-
Zimmer & Peacock AS
-
Metrohm AG
-
DexCom, Inc.
-
Universal Biosensors, Inc.
-
Johnson & Johnson Services, Inc.
-
Nix Biosensors
-
Cyrcadia Health
-
Lifescan
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Abbott Laboratories, Medtronic, Thermo Fisher Scientific, Inc., F. Hoffmann-La Roche, Siemens Healthineers, DexCom, Inc., DuPont,)
- Invest in wearable biosensors, AI-enabled diagnostics, product launches, regulatory approvals, and strategic partnerships.
- Strong brands, broad product portfolios, global distribution, advanced R&D, and regulatory expertise.
- High R&D costs, lengthy regulatory approvals, premium pricing, and complex manufacturing.
Emerging Players (Pinnacle Technology, Inc., Zimmer & Peacock AS, Nix Biosensors, Cyrcadia Health)
- Develop niche wearable and non-invasive biosensors, collaborate with healthcare providers, and expand through innovation.
- Specialized technologies, faster innovation, flexible product development, and focus on emerging applications.
- Limited global presence, smaller distribution networks, lower production scale, and limited financial resources.
Recent Development
- In June 2026, DexCom, Inc. announced that its Stelo Glucose Biosensor received FDA clearance for use in children aged 2 years and older not using insulin. The company also announced the rollout of a redesigned Stelo app in the U.S. beginning in July 2026 and plans to expand the glucose biosensing platform to the UK, Australia, New Zealand, and South Korea through 2027.
Biosensors Market Report Scope
Report Attribute
Details
Market size in 2025
USD 32.2 billion
Market size value in 2026
USD 34.7 billion
Revenue forecast in 2033
USD 64.0 billion
Growth rate
CAGR of 9.1% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Brazil, Argentina, Saudi Arabia, South Africa, UAE, Kuwait
Key companies profiled
Abbott Laboratories; Medtronic; Biosensors International Group; Pinnacle Technology, Inc.; Dupont; Sensirion AG; Thermo Fisher Scientific, Inc.; F. Hoffmann-La Roche AG; Siemens Healthineers; Zimmer & Peacock AS; Metrohm AG; DexCom, Inc.; Universal Biosensors, Inc.; Johnson & Johnson Services, Inc.; Nix Biosensors; Cyrcadia Health; Lifescan
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Biosensors Market Report Segmentation
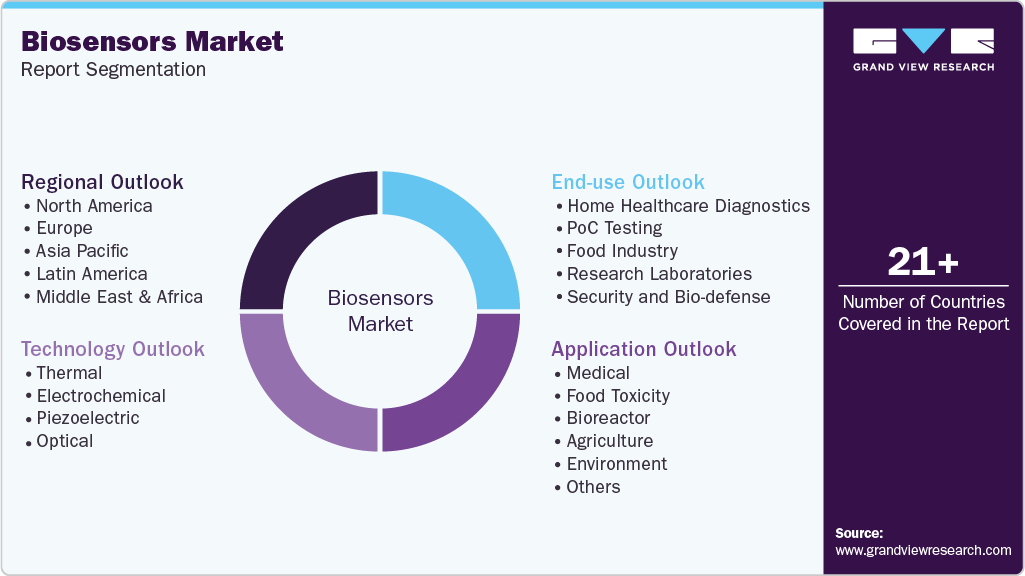
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global biosensors market report based on technology, application, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Thermal
-
Electrochemical
-
Piezoelectric
-
Optical
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Medical
-
Cholesterol
-
Blood Glucose
-
Blood gas analyzer
-
Pregnancy testing
-
Drug discovery
-
Infectious disease
-
-
Food Toxicity
-
Bioreactor
-
Agriculture
-
Environment
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Home Healthcare Diagnostics
-
PoC Testing
-
Food Industry
-
Research Laboratories
-
Security and Bio-defense
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The biosensors market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each biosensors segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Technology
Revenue Capture Definition
Thermal
Revenue generated from thermal biosensors that detect analytes by measuring heat changes produced during biochemical reactions. Includes thermal biosensor instruments, systems, and associated sensing components.
Electrochemical
Revenue generated from electrochemical biosensors that convert biochemical reactions into electrical signals for analyte detection. Includes amperometric, potentiometric, conductometric, and voltammetric biosensor systems and devices.
Piezoelectric
Revenue generated from piezoelectric biosensors that detect analytes through changes in mass or mechanical vibrations using piezoelectric materials. Includes quartz crystal microbalance (QCM) and related sensing technologies.
Optical
Revenue generated from optical biosensors that detect biological interactions using optical principles such as fluorescence, absorbance, luminescence, interferometry, and surface plasmon resonance (SPR).
Application
Revenue Capture Definition
Medical
Revenue generated from biosensors used in disease diagnosis, patient monitoring, and clinical testing across hospitals, clinics, diagnostic laboratories, and home healthcare settings.
This segment includes:
-
Cholesterol
-
Blood Glucose
-
Blood gas analyzer
-
Pregnancy testing
-
Drug discovery
-
Infectious disease
Food Toxicity
Revenue is generated from biosensors used to detect toxins, pathogens, allergens, pesticide residues, antibiotics, and other contaminants in food products for food safety and quality assurance.
Bioreactor
Revenue generated from biosensors integrated into bioreactors to monitor critical process parameters such as glucose, oxygen, pH, metabolites, and cell culture conditions during bioprocessing.
Agriculture
Revenue generated from biosensors used in agricultural applications for detecting plant diseases, soil nutrients, pesticide residues, pathogens, and other factors supporting precision farming.
Environment
Revenue generated from biosensors used to monitor environmental pollutants, heavy metals, toxins, microorganisms, and water or air quality across environmental testing applications.
Others
Revenue generated from biosensor applications not classified elsewhere, including veterinary diagnostics, forensic analysis, industrial process monitoring, and academic research.
End Use
Revenue Capture Definition
Home Healthcare Diagnostics
Revenue generated from biosensors used by individuals for self-monitoring and disease management in home settings, including personal diagnostic and health monitoring devices.
PoC Testing
Revenue generated from biosensors used in point-of-care testing to provide rapid diagnostic results at or near the site of patient care, including hospitals, clinics, physician offices, and pharmacies.
Food Industry
Revenue generated from biosensors used by food manufacturers and processors for quality control, contaminant detection, freshness monitoring, and regulatory compliance.
Research Laboratories
Revenue generated from biosensors used in academic institutions, government laboratories, contract research organizations, and pharmaceutical and biotechnology research facilities.
Security and Bio-defense
Revenue generated from biosensors used to detect biological threats, hazardous agents, toxins, and other substances for defense, homeland security, and public safety applications.
Estimation Model
Method
Approach
Description
01
Top-Down Analysis
Market size estimated by analyzing revenues from key biosensor manufacturers, supported by company annual reports, investor presentations, distributor insights, and premium databases. Private company revenues estimated using industry databases and validated through primary research to derive overall market value.
02
Segmentation Modeling
Market shares for technology, application, and end-use segments estimated using country-specific disease prevalence, healthcare infrastructure, adoption of point-of-care testing, wearable device penetration, regulatory environment, and industrial demand. Weighted averages applied to derive regional and global segment shares.
03
Validation Model
Market estimates validated through triangulation of secondary research, primary interviews, company-level revenue analysis, country-level demand assessment, and end-user adoption trends to ensure consistency and accuracy across segments and geographies.
04
Forecasting & CAGR Modeling
Market forecasts developed using historical adoption trends, chronic disease prevalence, demand for point-of-care diagnostics, wearable health monitoring adoption, technological advancements, healthcare expenditure, and regulatory developments. Regression-based analysis and trend modeling applied to project future growth and CAGR.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country-Level Volume Analysis
Detailed volume analysis of 23 countries for the biosensors market, including consumption, production (where applicable), import-export analysis, installed base, and application-wise demand across key countries.
Enables identification of high-volume countries, demand hotspots, and country-specific growth opportunities to support market entry and expansion strategies.
Company Market Share Analysis at the Region Level
Comprehensive market share analysis of leading biosensor manufacturers across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, including revenue contribution, competitive positioning, and regional presence.
Helps benchmark competitors, identify regional market leaders, and assess competitive intensity across key geographic markets.
Regional Average Selling Price (ASP) Analysis
Detailed analysis of the average selling price (ASP) of biosensors across major regions by technology and application, including pricing trends and key factors influencing regional price variations.
Supports pricing strategy, revenue forecasting, profitability analysis, and regional market positioning.
Frequently Asked Questions About This Report
The global biosensors market size was valued at USD 32.2 billion in 2025 and is estimated at USD 34.7 billion for 2026.
The global biosensors market is expected to grow at a CAGR of 9.1% from 2026 to 2033, reaching USD 64.0 billion by 2033.
The electrochemical segment dominated the global biosensors market and accounted for the largest revenue share of 71.6% in 2025.
The POC testing segment dominated the global biosensors market and accounted for the largest revenue share of around 47.9% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The medical segment dominated the global biosensors market and accounted for the largest revenue share of 66.8%.
Abbott Laboratories; Medtronic; Biosensors International Group; Pinnacle Technology, Inc.; Dupont; Sensirion AG; Thermo Fisher Scientific, Inc.; F. Hoffmann-La Roche AG; Siemens Healthineers; Zimmer & Peacock AS; Metrohm AG; DexCom, Inc.; Universal Biosensors, Inc.; Johnson & Johnson Services, Inc.; Nix Biosensors; Cyrcadia Health; Lifescan
North America dominated the biosensors market with the largest revenue share of 42.6% in 2025.
Key factors that are driving the market growth include the rapid technological advancements rising demand for health monitoring and fitness tracking, growing preference for non-invasive wearable biosensors, growing demand for early disease detection and preventive healthcare
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


