
- Home
- »
- Pharmaceuticals
- »
-
Blockbuster Oncology Brands Market Size Report, 2026-2033GVR Report cover

Blockbuster Oncology Brands Market (2026 - 2033)
Size, Share & Trends Analysis Report By Brands (Opdivo, Keytruda, Perjeta, Ibrance), By Treatment (Lung Cancer, Lymphoma), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$47.2BMarket Estimate, 2026
$51.0BMarket Forecast, 2033
$87.4BCAGR, 2026–2033
8.0%Blockbuster Oncology Brands Market Summary
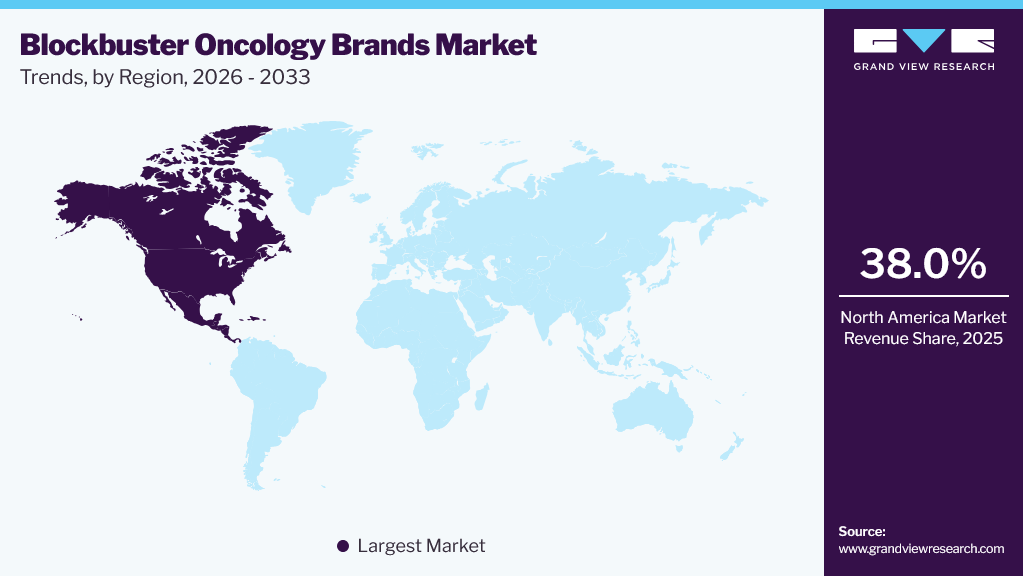
The global blockbuster oncology brands market size was valued at USD 47.2 billion in 2025 and is projected to grow from USD 51.0 billion in 2026 to USD 87.4 billion by 2033, at a CAGR of 8.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.0% in 2025. The rising prevalence of various cancer types across different age groups, coupled with ongoing advancements in oncology research, is driving market growth.
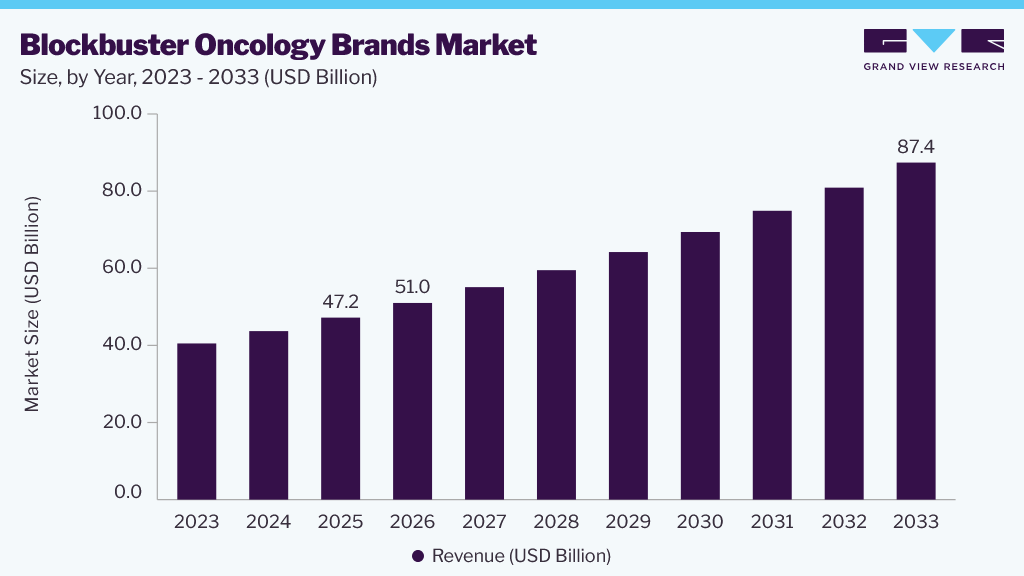 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By brands: The opdivo segment held the largest market share of around 15.0% in 2025.
- By treatment: The breast cancer segment accounted for the largest market revenue share in 2025.
- By distribution channel: The hospital pharmacies segment accounted for the largest market revenue share in 2025.
Regional Highlights
- Largest regional market: North America (38.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 47.2 Billion
- Estimated market size in 2026: USD 51.0 Billion
- Projected market size by 2033: USD 87.4 Billion
- CAGR (2026-2033): 8.0%
Prism AI by Grand View Research Free to tryAsk a question about the blockbuster oncology brands marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →In addition, the expanding availability of innovative treatment approaches, including immunotherapies, targeted therapies, and cellular therapies, is providing patients with a broader range of therapeutic options, further supporting market expansion.
A blockbuster drug is a highly sought-after drug that generates annual sales of USD 1 billion or more for a pharmaceutical company. Regulatory bodies worldwide have accelerated approval rates for new drug therapies as first-line treatments. In addition, companies have invested heavily in research and development efforts for new drug formulations. These factors have collectively contributed to the high growth trajectory of the global market for blockbuster oncology brands.
In January 2026, according to the American Cancer Society (ACS) in its Cancer Statistics, an estimated 2.1 million new cancer cases and 0.6 million cancer deaths are expected to occur in the United States. The most common types of cancer, according to IARC, were lung and prostate cancer for men and breast cancer for women. Such a large and expanding patient population encourages pharmaceutical companies to accelerate the development of innovative oncology therapies. These new drug therapies come at a high cost to patients; however, favorable reimbursement policies are supporting the commercial success of blockbuster oncology brands and contributing to overall market growth.
Regulatory bodies worldwide, such as the Food and Drug Administration (FDA), the European Medicines Agency (EMA), the Medicines and Healthcare Products Regulatory Agency (MHRA), and others, have fast-tracked their approval rates for the application of innovative drug therapies in cancer treatment, such as targeted immunotherapy, CAR-T cell therapy, monoclonal antibodies, and many others. Tailored treatment approaches employed by oncologists, based on genetic and molecular profiling of tumors, further enhance treatment efficacy and drive market demand.
Analyst Perspective
The global blockbuster oncology brands industry continues to expand, driven by the rising global cancer burden, accelerated regulatory approvals, and sustained investments in next-generation oncology therapies. Opdivo remains the leading revenue-generating brand owing to its broad range of approved indications, expanding label approvals, and strong adoption across multiple solid tumors. Breast cancer represents the largest treatment segment, supported by continuous innovation in targeted therapies and immuno-oncology, while lymphoma is emerging as the fastest-growing area due to increasing adoption of advanced cell and precision therapies. As competition intensifies, companies are focusing on strategic acquisitions, pipeline diversification, and the development of novel biologics and targeted therapies to address unmet clinical needs and sustain long-term blockbuster growth.
Brands Insights
The opdivo segment led the market with the largest revenue share of around 15.0% in 2025. Also known as Nivolumab, this drug has demonstrated clinical efficacy across a wide range of cancer symptoms, such as lung, melanoma, kidney, and other solid tumors. This broad therapeutic spectrum has expanded the drug's market potential and solidified its position as a preferred treatment option for oncologists. Furthermore, comprehensive clinical data supporting Opdivo's safety and efficacy have been instrumental in gaining its widespread adoption among healthcare professionals. This has resulted in increased prescription rates for Opdivo, leading to market dominance. For instance, in December 2024, the U.S. FDA approved Opdivo Qvantig, a subcutaneous formulation of Bristol Myers Squibb's blockbuster immunotherapy, reducing administration time from intravenous infusion to just a few minutes while enhancing patient convenience and treatment efficiency.
The zejula segment is expected to grow at the fastest CAGR from 2024 to 2030. Rising cases of cancer in women, such as ovarian cancer and fallopian tube cancer, along with the response of cancer to platinum-based therapy, have led to the increased adoption of Zejula by oncology professionals. According to the Ovarian Cancer Research Alliance, women have a 1 in 91 lifetime risk of developing ovarian cancer with a high mortality rate. Clinical trials for the drug have indicated that the use of Zejula is useful in delaying the progression of cancer up to a median of 14 months. These factors are expected to boost the adoption of Zejula among the medical community, accounting for its faster growth rate.
Treatment Insights
The breast cancer segment accounted for the largest market revenue share in 2025. Breast cancer is among the most common forms of cancer in 157 countries worldwide. According to an analysis published by the International Agency for Research on Cancer (IARC), 1 in 20 women globally is expected to be diagnosed with breast cancer during their lifetime, and annual new breast cancer cases are projected to reach 3.2 million, with 1.1 million deaths by 2050. Advancements in screening technologies and increased public awareness have led to earlier diagnosis of breast cancer. This has facilitated the timely initiation of treatment, contributing to improved patient outcomes and, consequently, higher drug utilization. In addition, there has been a concentrated focus on developing and commercializing innovative therapies for this patient population, further strengthening the market share of breast cancer-targeted blockbuster brands.
The lymphoma treatment segment is expected to grow at the fastest CAGR during the forecast period. A notable global surge in lymphoma incidence has driven demand for effective treatment options. For instance, in 2026, according to the American Cancer Society's Cancer Facts & Figures, an estimated 79,320 new cases of non-Hodgkin lymphoma and 8,920 new cases of Hodgkin lymphoma are expected to be diagnosed in the United States, and these numbers are expected to continue rising in the coming years. This epidemiological shift has created a substantial market opportunity for innovative therapies. Moreover, the introduction of high-priced and effective lymphoma treatments has contributed to the positive growth trajectory of this segment.
Distribution Channel Insights
The hospital pharmacies segment accounted for the largest market revenue share in 2025. This is attributed to a complex treatment regimen associated with oncology procedures, as well as the specialized expertise and continuous patient monitoring required for the administration of cancer therapies. For instance, in June 2025, Fox Chase Cancer Center opened a new oncology satellite pharmacy that tripled its capacity to prepare chemotherapy and intravenous medications, increasing it to more than 500 IV preparations per day, supporting the expansion of outpatient oncology services and increasing infusion capacity. Furthermore, a significant proportion of oncology drugs are administered via injection, requiring a controlled environment and medical professionals. Hospital pharmacies are uniquely equipped to handle these drug delivery modalities, which contributes to their strong market share.
The retail pharmacy distribution channel segment is expected to grow at the fastest CAGR during the forecast period. The increasing prevalence of cancer, advancements in precision medicine and targeted therapies, and the introduction of effective new oncology drugs collectively enhance the availability and appeal of innovative cancer treatments in the retail pharmacy sector. The introduction of novel oncology brands with blockbuster potential, such as Eli Lilly's Jaypirca, Genmab/AbbVie's Epkinly, and Johnson & Johnson's Talvey, has further contributed to the rising demand in retail pharmacies.
Regional Insights
North America dominated the global blockbuster oncology brands market with the largest revenue share of 38.0% in 2025. The region's leadership can be attributed to its substantial cancer burden, strong healthcare infrastructure, and rapid adoption of innovative oncology therapies. The U.S. Food and Drug Administration (FDA) continued to accelerate the availability of novel cancer treatments through multiple oncology approvals in 2025, including therapies for breast cancer, colorectal cancer, mantle cell lymphoma, pancreatic neuroendocrine tumors, gastric cancer, and other hematologic malignancies. A comparatively higher per capita healthcare spending in this region enables greater access to advanced oncology therapies for patients and facilitates market penetration for blockbuster drugs. Furthermore, a well-established ecosystem of pharmaceutical companies, biotechnology firms, and academic institutions nurtures the development of innovative oncology treatments.
 To learn more about this report, Download Free Sample Report
U.S. Blockbuster Oncology Brands Market Trends
The blockbuster oncology brands market in the U.S. accounted for the largest market revenue share in North America in 2025, supported by the country's huge cancer population and strong uptake of innovative cancer therapies. For instance, the American Cancer Society has estimated more than 2 million new cancer cases and over 600,000 deaths due to cancer in 2024 in the country. Effective formulation of regulatory frameworks from the FDA has expedited the market entry of novel oncology products, contributing to this country’s strong positioning. Additionally, rigorous intellectual property protection in the country safeguards the exclusivity of blockbuster oncology brands, allowing for substantial revenue generation.
Asia Pacific Blockbuster Oncology Brands Market Trends
The blockbuster oncology brands market in the Asia Pacific is expected to grow at the fastest CAGR during the forecast period. The region is witnessing a rapid increase in cancer incidence, creating significant demand for innovative and effective oncology therapies. According to a study published in The Lancet in January 2024, cancer has emerged as one of the most prominent public health threats in recent years. This poses a serious challenge for regional governments to tackle the growing incidence of cancer-related deaths. In recent years, significant investments in healthcare infrastructure, including hospitals, clinics, and research facilities, have improved access to advanced cancer treatments. Moreover, the development of specialized oncology centers and increased healthcare expenditure have boosted the adoption of innovative therapies. These factors have led to steady market growth in the region.
In 2024, according to the latest Health of the Nation report published by Apollo Hospitals, India experienced a sharp rise in cancer cases, with a growth rate of over 13.0% projected between 2020 and 2024. This has made India the cancer capital of the world. In addition, the median age for cancer diagnosis among Indians was less than the global average, leading to the occurrence of this disease at a younger age. This scenario presents a significant market opportunity for newer cancer therapies. Moreover, government initiatives for cancer treatment have enabled the low-income class to opt for high-priced immunotherapies, leading to a high patient base for new therapies.
Key Blockbuster Oncology Brands Company Insights
The blockbuster oncology brands industry features a range of global, regional, and local players, making it highly competitive. The world’s leading companies are using partnerships, collaborations, acquisitions, mergers, and agreements as strategies to withstand the intense competition and increase their market share. For instance, in March 2025, AstraZeneca completed the acquisition of EsoBiotec to strengthen its cell therapy capabilities and accelerate the development of innovative cancer treatments, further expanding its oncology portfolio.
Key Blockbuster Oncology Brands Companies
The following key companies have been profiled for this study on the global blockbuster oncology brands market:
-
Bristol-Myers Squibb Company
-
Merck & Co., Inc.
-
Pfizer Inc.
-
F. Hoffmann-La Roche Ltd
-
AstraZeneca PLC
-
GSK plc
-
Novartis AG
-
Johnson & Johnson Services, Inc.
-
AbbVie Inc.
-
Amgen Inc.
Recent Developments
-
For instance, in June 2026, GSK entered an agreement to acquire Nuvalent for approximately USD 10.6 billion to expand its precision oncology portfolio with late-stage targeted therapies for lung cancer, reinforcing its position in the blockbuster oncology market.
-
In July 2024, Bristol-Myers Squibb received validation for its Type II variation application from the European Medicines Agency (EMA) for Opdivo (nivolumab) plus Yervoy (ipilimumab) as a first-line treatment for unresectable or advanced hepatocellular carcinoma (HCC) in adult patients. The therapy is expected to improve treatment outcomes for European patients with HCC.
-
In July 2024, Merck announced its research partnership with Orion Corporation for the exclusive global licensing of the opevesostat investigational CYP11A1 inhibitor, and other drugs designed to treat prostate cancer. With financial assistance from Merck, Orion will accelerate its research toward developing a drug for patients with this form of cancer.
Blockbuster Oncology Brands Market Report Scope
Report Attribute
Details
Market size in 2025
USD 47.2 billion
Estimated market size in 2026
USD 51.0 billion
Projected market size by 2033
USD 87.4 billion
Growth rate
CAGR of 8.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Brands, treatment, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; Australia; South Korea; India; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Bristol-Myers Squibb Company; Merck & Co., Inc.; Pfizer Inc.; F. Hoffmann-La Roche Ltd; AstraZeneca PLC; GSK plc; Novartis AG; Johnson & Johnson Services, Inc.; AbbVie Inc.; Amgen Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Blockbuster Oncology Brands Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global blockbuster oncology brands market report based on brands, treatment, distribution channel, and region:
-
Brands Outlook (Revenue, USD Billion, 2021 - 2033)
-
Opdivo
-
Keytruda
-
Perjeta
-
Ibrance
-
Tecentriq
-
Gazyva
-
Tagrisso
-
Darzalex
-
Zejula
-
Revlimid
-
Imbruvica
-
Others
-
-
Treatment Outlook (Revenue, USD Billion, 2021 - 2033)
-
Lung cancer
-
Breast cancer
-
Multiple myeloma
-
Lymphoma
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Pharmacy
-
Retail Pharmacy
-
Other
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
India
-
China
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
Key players include Bristol-Myers Squibb Company, Merck & Co., Inc., Pfizer Inc., F. Hoffmann-La Roche Ltd, AstraZeneca PLC, GSK plc, Novartis AG, Johnson & Johnson Services, Inc., AbbVie Inc., Amgen Inc. , and others.
North America dominated with an approximately 38.0% revenue share in 2025.
The global blockbuster oncology brands market size was valued at USD 47.2 billion in 2025 and is estimated at USD 51.0 billion for 2026.
The global blockbuster oncology brands market is expected to grow at a CAGR of 8.0% from 2026 to 2033, reaching USD 87.4 billion by 2033.
The Opdivo brands segment accounted for the largest revenue share of approximately 15.0% in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


