
- Home
- »
- Clinical Diagnostics
- »
-
Blood Testing Market Size And Share Report, 2026-2033GVR Report cover

Blood Testing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Test Type (Glucose, Lipid, COVID-19, A1C, CRP, Vitamin-D, ALT, AST, Thyroid Stimulating Hormone, PSA, Cortisol), By Region, And Segment Forecasts
Market Size, 2025
$104.0BMarket Estimate, 2026
$112.4BMarket Forecast, 2033
$220.3BCAGR, 2026–2033
10.1%Blood Testing Market Summary
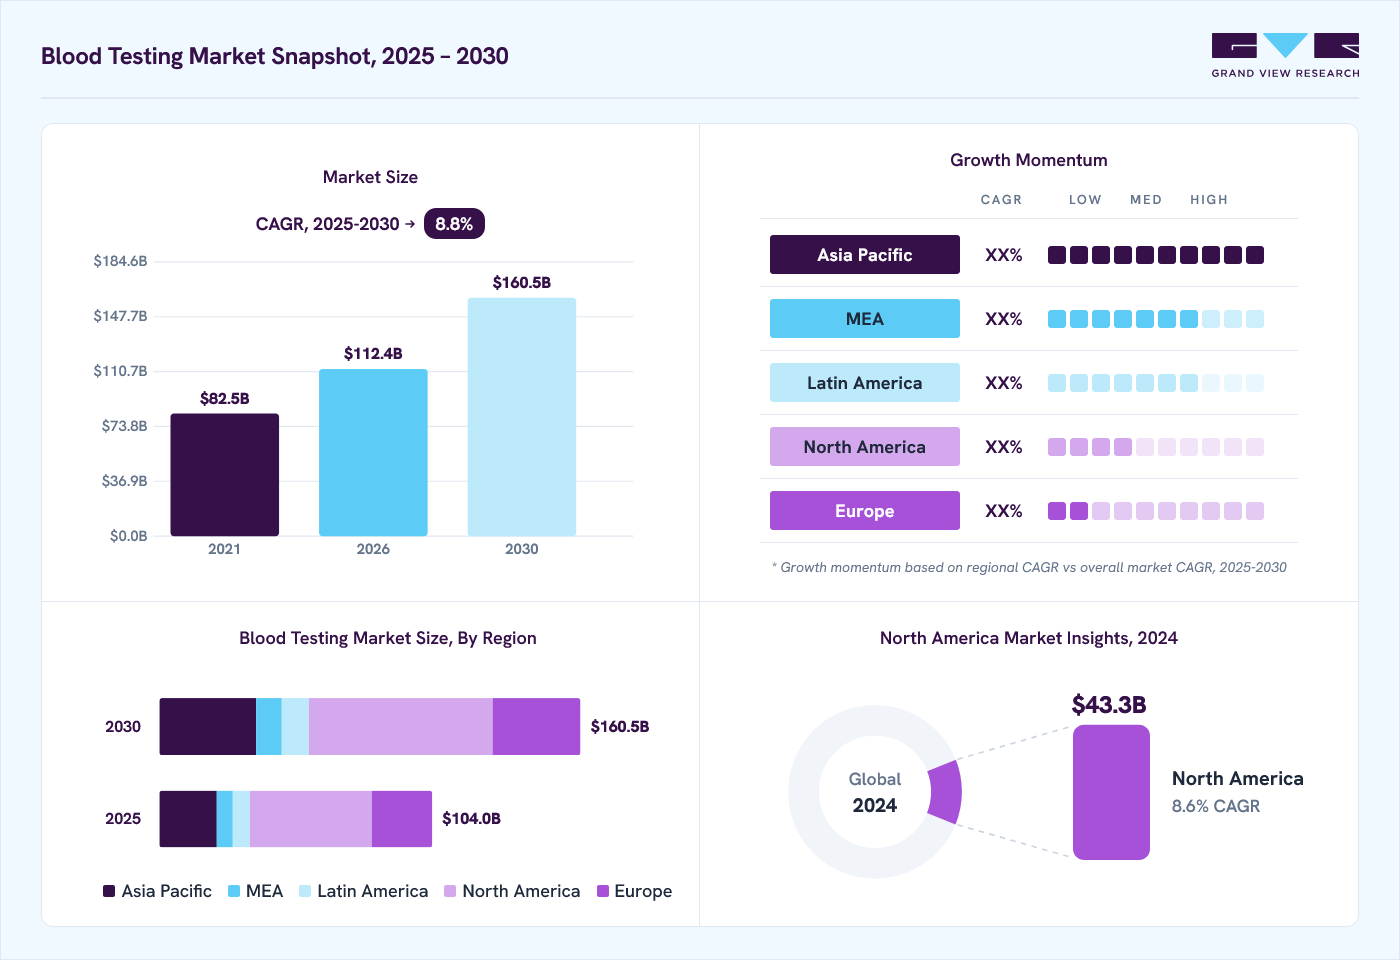
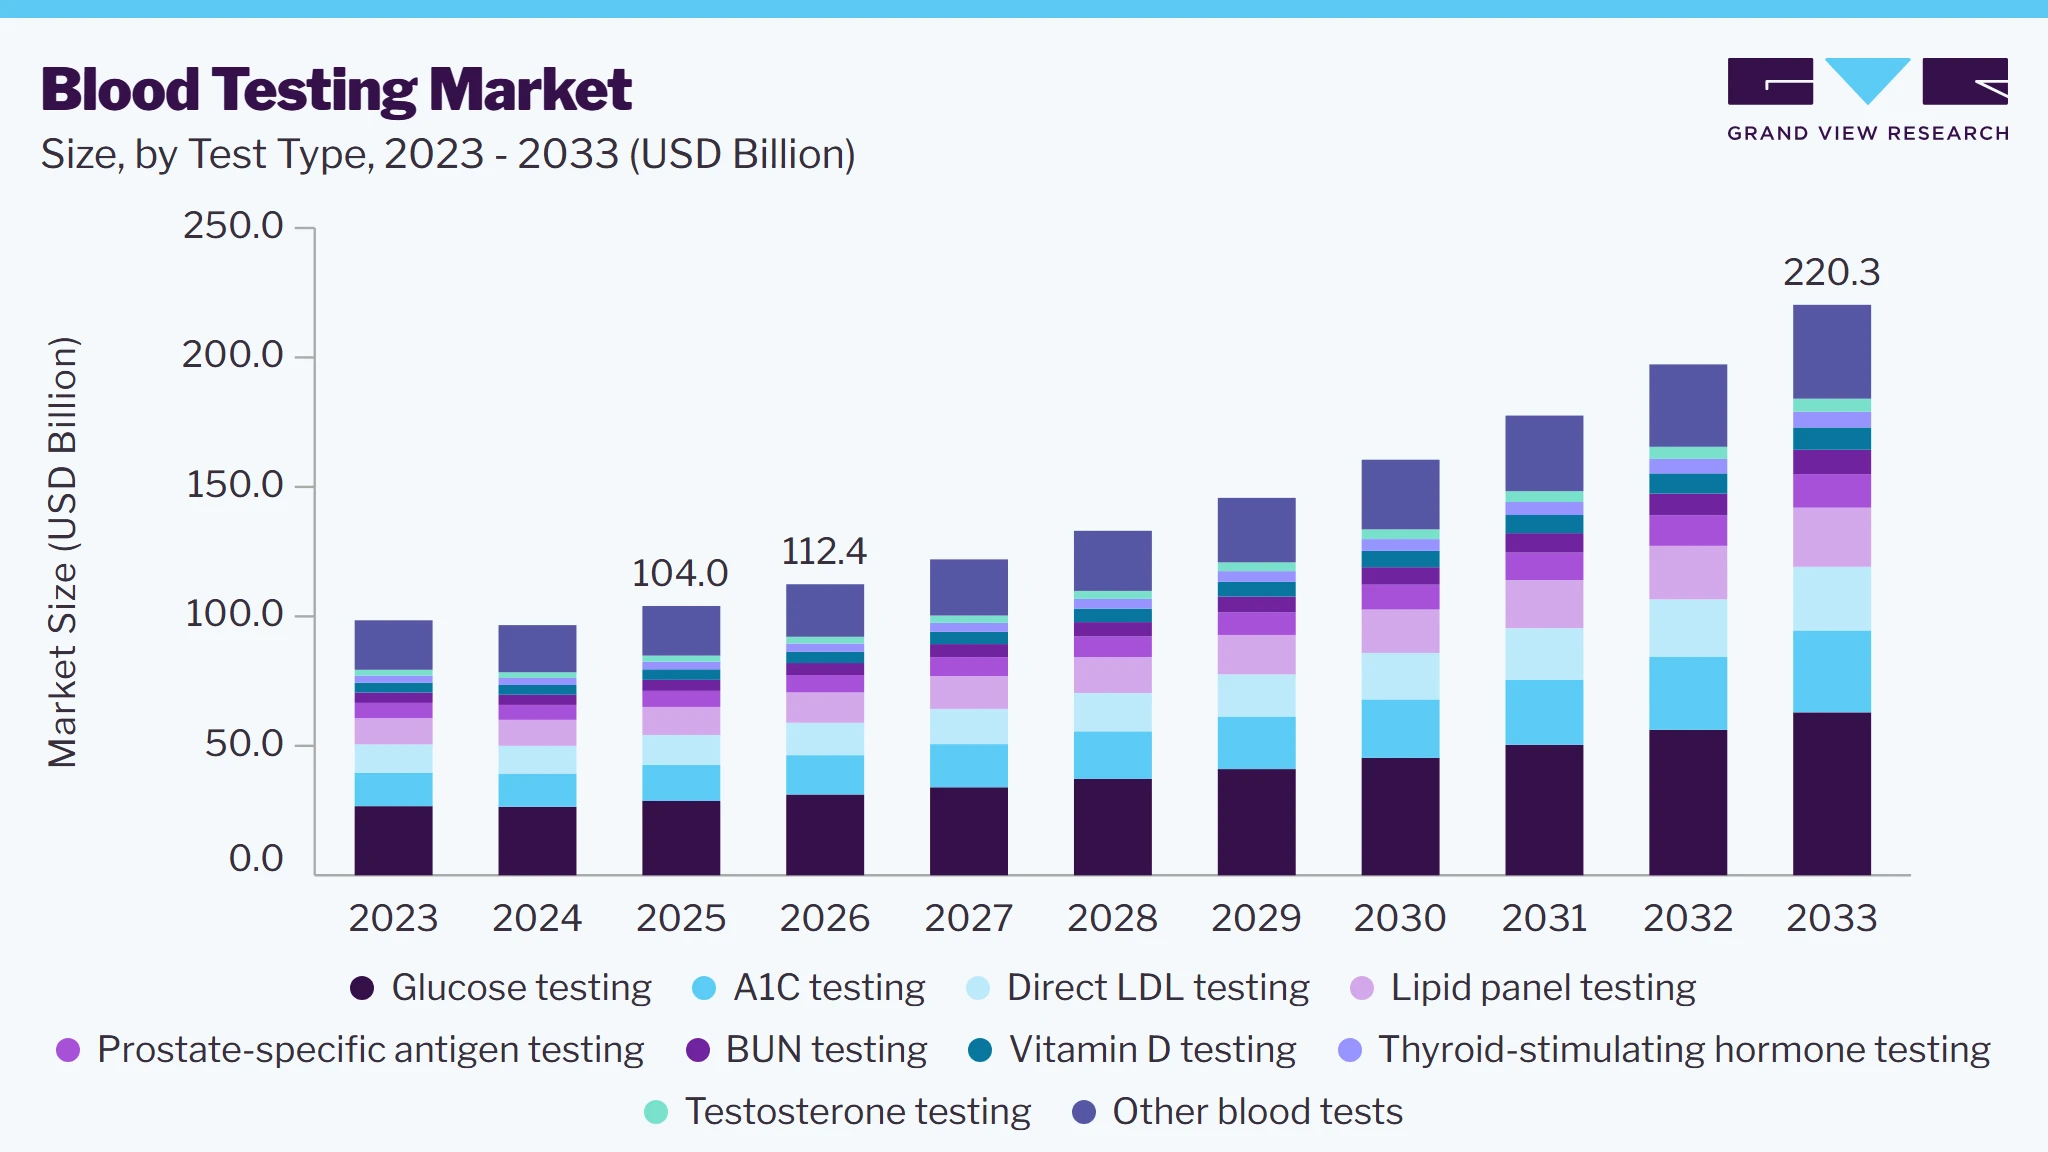
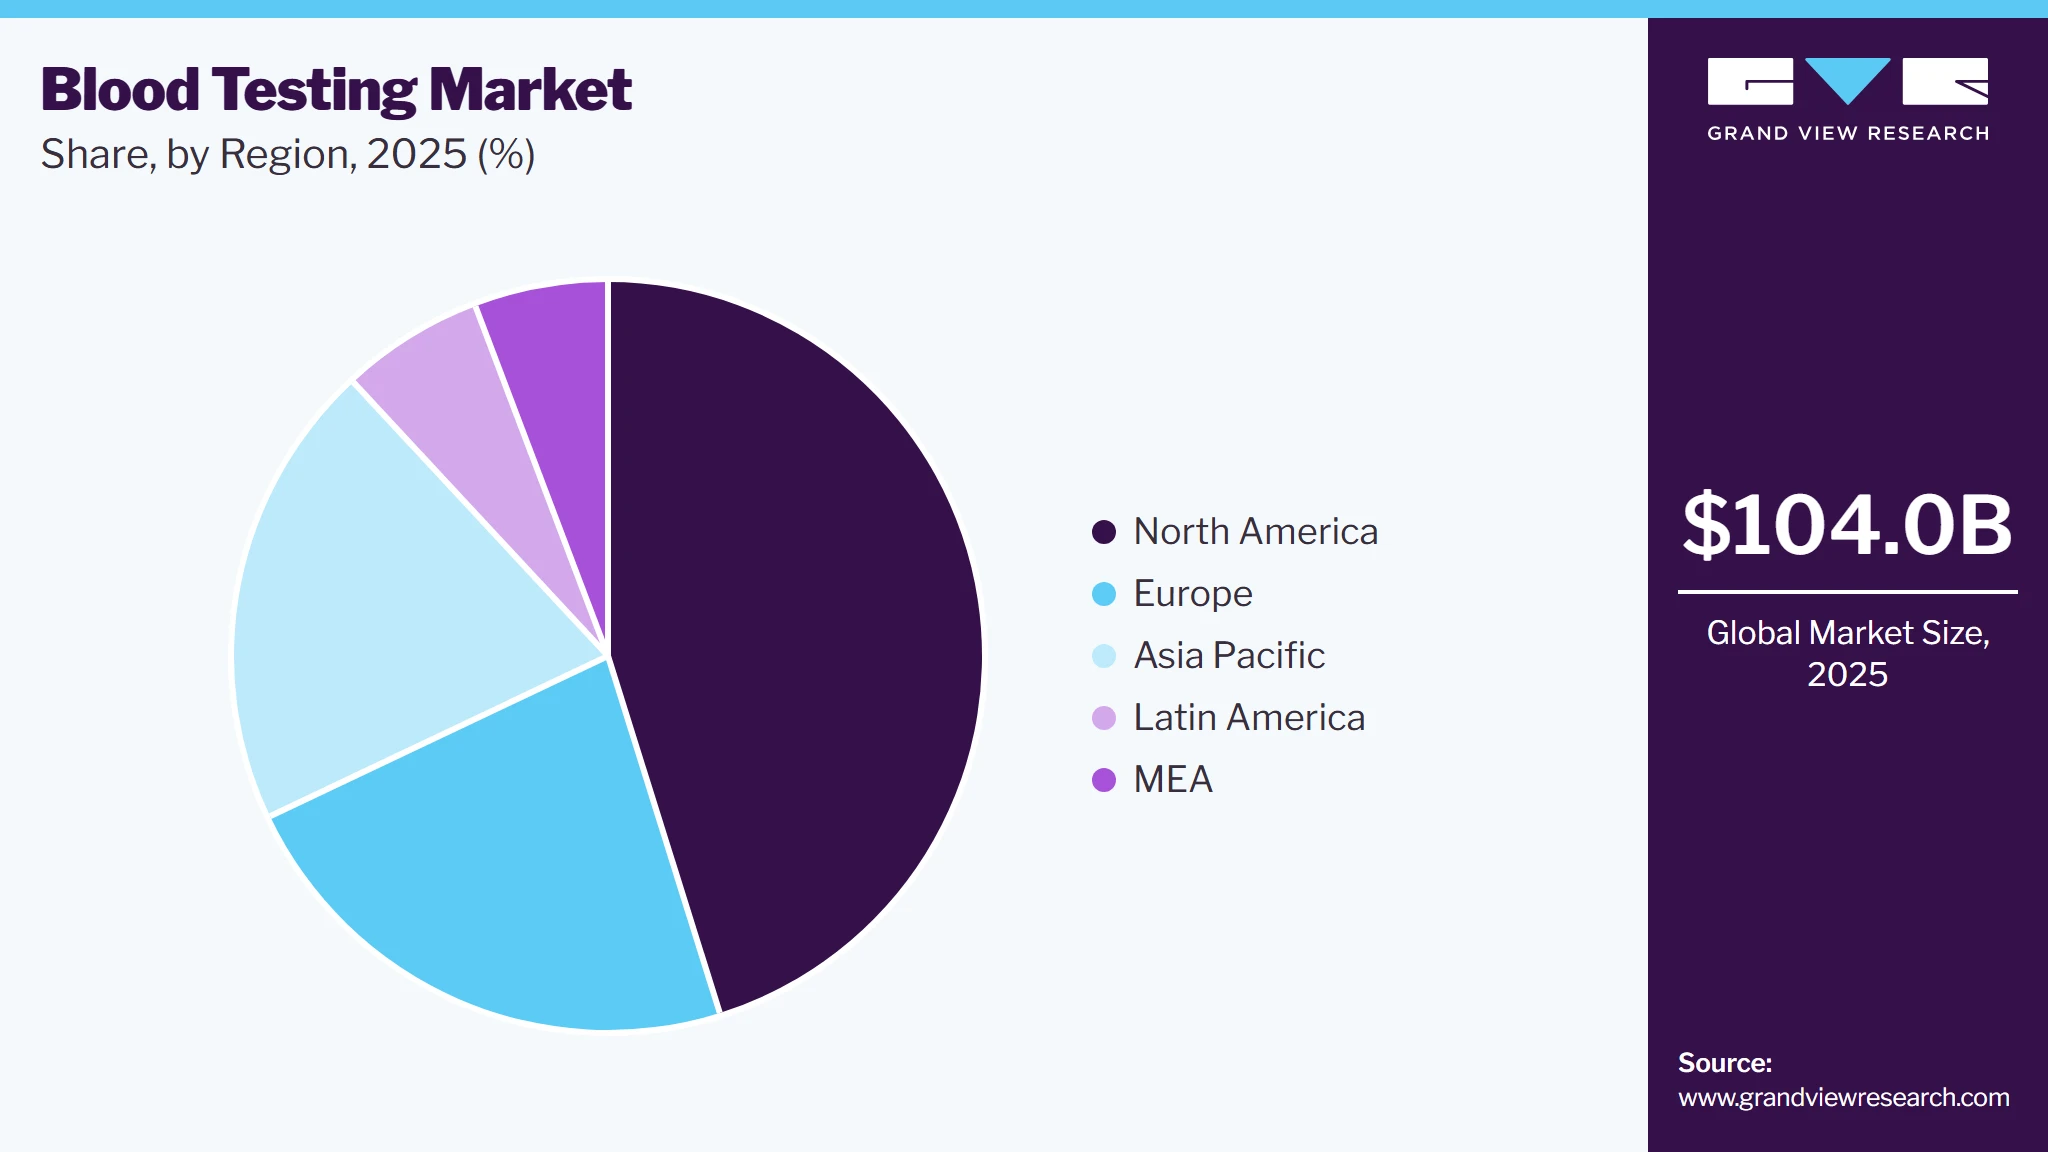
The global blood testing market size was valued at USD 104.0 billion in 2025 and is projected to grow from USD 112.4 billion in 2026 to USD 220.3 billion by 2033, at a CAGR of 10.1% from 2026 to 2033. The market in North America dominated with a revenue share of 45.2% in 2025. The market growth is attributed to rising awareness of preventative healthcare and advancements in testing technologies aided by an increasing healthcare expenditure by governments and regulatory bodies, which actively promote routine diagnostic testing to improve patient outcomes.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By test type: Glucose testing segment held the largest market share of 27.6% in 2025. The A1C testing segment is expected to grow at a significant CAGR during the forecast period.
Regional Highlights
- Largest regional market: North America (45.2% revenue share, 2025) Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033) By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 104.0 Billion
- Estimated market size in 2026: USD 112.4 Billion
- Projected market size by 2033: USD 220.3 Billion
- CAGR (2026-2033): 10.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
For example, developing advanced blood tests, such as those providing early detection for severe illnesses like COVID-19, demonstrates the growing focus on early detection and personalized care. These factors, combined with expanding healthcare infrastructure in emerging markets, are anticipated to drive market growth over the forecast period.
 To learn more about this report, Download Free Sample Report
The rising adoption of blood testing solutions is driven by increasing awareness of preventive healthcare and the growing need for accurate and early disease diagnosis. Healthcare providers are leveraging advanced technologies to detect chronic and infectious diseases, monitor health conditions, and personalize treatment plans. In addition, advancements in automation and point-of-care testing devices have made blood tests more accessible and efficient, reducing turnaround times and enhancing patient outcomes. The shift towards minimally invasive techniques and home-based blood kits further supports adoption by offering convenience and ease of use. These trends, coupled with growing healthcare spending and a focus on early detection, are propelling the widespread adoption across both developed and emerging markets.
The growing prevalence of target diseases such as diabetes, cardiovascular diseases, and cancer is a major driver for the market growth. As these chronic conditions continue to rise globally, the demand for diagnostic tools to monitor and manage these diseases has surged. For example, the International Diabetes Federation reports that approximately 537 million adults are living with diabetes worldwide, and this number is expected to increase to 783 million by 2045. In the U.S., nearly 122 million adults have hypertension, contributing to a greater need for blood pressure and cholesterol testing. In addition, the rise in cancer cases, with an estimated 19.3 million new cancer cases globally in 2020 according to the World Health Organization, further fuels the demand for early detection tools such as liquid biopsy tests. As more people are diagnosed with these conditions, regular and accurate blood testing becomes essential for effective disease management and prevention, driving the expansion of the industry.
The growing demand for point-of-care (POC) tests is propelling the growth, as they offer quick, accurate, and convenient diagnostic results outside traditional laboratory settings. POC tests are increasingly preferred for their ability to provide immediate results, reducing wait times and enabling timely medical interventions. This is particularly valuable in emergency situations, rural areas, or for patients seeking at-home solutions. For example, Abbott’s FreeStyle Libre system, a continuous glucose monitoring device, allows patients with diabetes to track their glucose levels in real time without needing a lab visit. Similarly, devices like Roche’s COBAS Liat System provide rapid molecular testing for various infectious diseases, such as COVID-19 and influenza, directly at the point of care. These innovations have made blood testing more accessible and efficient, driving the adoption of POC tests across healthcare facilities and homes, and fueling the overall growth of the blood testing industry.
The implementation of favorable government initiatives and external funding for research and development (R&D) activities is significantly driving the growth of the blood testing industry. Governments across various regions are recognizing the importance of early disease detection and preventive healthcare, which has led to increased funding for medical research and innovation in diagnostic technologies. For example, the U.S. government’s support for health initiatives like the National Institutes of Health (NIH) funding research in non-invasive diagnostic methods has accelerated the development of advanced solutions.
One key factor restraining the market growth is the complexity and cost associated with some advanced blood testing technologies, which can limit their accessibility, particularly in developing regions. In addition, stringent regulatory requirements, such as the FDA approval process for new diagnostic devices, can delay the market introduction of innovative testing solutions, slowing down the pace of advancement. Furthermore, reimbursement policies in certain regions, especially for home-based or non-invasive tests, can be restrictive, limiting patient access to these technologies. In many cases, insurance companies may not cover the full cost of certain blood tests, particularly for conditions that are still under research or are not yet widely recognized, further hindering market growth. These factors combine to create barriers to the widespread adoption of new technologies and services.
Market Dynamics
The blood testing market is experiencing sustained growth driven by the increasing emphasis on preventive healthcare, early disease diagnosis, and routine clinical monitoring across healthcare systems. The growing burden of chronic and infectious diseases, coupled with expanding access to diagnostic services, is supporting higher testing volumes across hospitals, diagnostic laboratories, and outpatient care settings. Advancements in laboratory automation, high throughput analyzers, and digital workflow integration are improving operational efficiency while enabling timely and accurate diagnostic outcomes. Reflecting these market developments, leading diagnostic companies continue to strengthen their preventive testing capabilities. For instance, in 2025, Labcorp expanded its preventive diagnostics portfolio by introducing more than 130 new diagnostic tests and enhancing its Labcorp OnDemand offerings, strengthening access to blood-based testing for preventive and specialty care. Such developments are expanding the availability of diagnostic services, supporting evidence based clinical decision making, and reinforcing the adoption of comprehensive blood testing across diverse healthcare settings.
The growing adoption of advanced blood screening and diagnostic technologies is a key driver of the blood testing market. Healthcare providers are increasingly implementing automated analyzers and nucleic acid testing platforms to improve the accuracy, efficiency, and safety of blood-based diagnostics. Rising demand for early disease detection, expansion of blood donation programs, and increasing emphasis on transfusion safety are encouraging healthcare institutions to modernize laboratory infrastructure. These investments are strengthening testing capacity while supporting faster clinical decision making. For instance, in 2026, AIIMS Mangalagiri deployed nucleic acid testing-based blood screening to enhance the detection of transfusion transmissible infections and improve blood safety standards. Such advancements are accelerating the adoption of advanced blood testing technologies and supporting the expansion of high-quality diagnostic services across healthcare systems.
The high cost of advanced blood testing technologies and laboratory infrastructure continues to restrain the growth of the blood testing market. Healthcare providers must invest significantly in automated analyzers, molecular diagnostic platforms, and high throughput laboratory systems, along with recurring expenses for reagents, maintenance, quality assurance, and skilled personnel. These financial requirements can be challenging for small hospitals, independent diagnostic laboratories, and healthcare facilities operating in resource constrained regions. In addition, reimbursement limitations for specialized blood tests and varying healthcare funding models may reduce the adoption of advanced diagnostic solutions. As a result, many healthcare providers continue to rely on conventional testing methods, limiting the broader implementation of innovative blood testing technologies and slowing market expansion across cost sensitive healthcare environments.
The expansion of advanced blood testing platforms presents a significant opportunity for the blood testing market. Healthcare systems are increasing investments in high throughput diagnostic technologies to strengthen transfusion safety, support preventive healthcare initiatives, and improve the early detection of infectious and chronic diseases. Growing demand for automated laboratory workflows and highly sensitive molecular testing is encouraging manufacturers to introduce innovative blood testing solutions that enhance diagnostic accuracy and operational efficiency. These advancements are also supporting broader adoption of standardized testing practices across blood banks and clinical laboratories. For instance, in 2026, Roche showcased its latest blood screening and diagnostic innovations at the ISBT Congress 2026, highlighting technologies designed to improve transfusion safety and laboratory performance. Such developments are expected to accelerate technology adoption, expand testing capabilities, and create new growth opportunities across global healthcare systems.
Analyst Perspective
The blood testing market is expected to maintain steady growth, supported by the increasing focus on preventive healthcare, routine health assessments, and early diagnosis of chronic and infectious diseases. Growing adoption of automated laboratory systems, high throughput analyzers, and advanced molecular and immunoassay technologies is improving diagnostic accuracy and laboratory efficiency. The market is also benefiting from expanding healthcare infrastructure and broader access to diagnostic services across developed and emerging economies. Future growth opportunities are expected to arise from decentralized testing, personalized medicine, and digital laboratory integration, supported by continued product innovation, regulatory approvals, and investments in advanced blood testing technologies by leading industry participants.
Test Type Insights
Based on test type, the glucose testing segment led the market with the largest revenue share of 27.6% in 2025 and anticipated to grow at fastest CAGR over the forecast period. The growth of the segment is driven by increasing global awareness of diabetes and the rising prevalence of the disease. Diabetes, both type 1 and type 2, has become a major public health concern, with the World Health Organization (WHO) estimating that approximately 422 million people worldwide suffer from the condition. As the incidence of diabetes continues to rise, there is a growing demand for glucose monitoring solutions to manage the disease effectively and prevent complications. Furthermore, the increasing shift towards home-based and point-of-care testing has significantly impacted the growth of glucose testing, as patients prefer convenient, at-home options for monitoring their glucose levels. This trend is reflected in the growth of blood glucose test strips, glucose meters, and wearable devices designed for continuous monitoring, positioning glucose testing as a key driver in the overall market growth.
 To learn more about this report, Download Free Sample Report
The A1C testing segment is expected to grow at a significant CAGR during the forecast period, due to the increasing global prevalence of diabetes, particularly type 2 diabetes, and the growing awareness of the importance of long-term glucose control. A1C tests, which measure the average blood sugar levels over the past two to three months, are a critical tool in managing diabetes and preventing complications, as they provide a more comprehensive picture of a patient’s glucose control than traditional fingerstick tests. The segment is further expanding as A1C testing becomes increasingly available at the point of care, allowing healthcare providers to quickly assess a patient's long-term glucose control. In 2020, Abbott received FDA approval for its Afinion 2, a device that provides A1C testing results in just 3 minutes, making it a convenient option for both healthcare professionals and patients. Similarly, devices like the A1CNow+ from PTS Diagnostics allow for at-home testing, offering individuals the flexibility to monitor their A1C levels regularly without needing to visit a clinic. These innovations are driving the growth by improving accessibility, reducing wait times for results, and enabling better patient engagement in managing their condition.
Regional Insights
North America dominated the Blood Testing Market with the largest revenue share of 45.2% in 2025. The market growth in North America is driven by factors such as the rising prevalence of chronic diseases, advancements in diagnostic technologies, and increasing healthcare awareness. Technological advancements in blood testing devices and procedures are another key factor contributing to the market's growth. Continuous glucose monitoring (CGM) devices, point-of-care testing systems, and molecular diagnostics innovations have revolutionized how diseases are detected and managed. Companies like Abbott, with their FreeStyle Libre system for glucose monitoring, and Roche, with their COBAS systems, are leading the market in bringing cutting-edge solutions to the market. These technologies not only improve the accuracy of tests but also reduce turnaround times, allowing healthcare providers to make quicker, more informed decisions, which is crucial for effective patient care.
U.S. Blood Testing Market Trends
The Blood Testing Market in the U.S. held the largest share in the North America region in 2025. The blood testing market in U.S.is expected to grow at the fastest CAGR over the forecast period, driven by the increasing prevalence of chronic diseases such as diabetes, cardiovascular conditions, and cancer. Technological advancements, including continuous glucose monitoring devices and point-of-care solutions, are enhancing diagnostic accuracy and accessibility. In addition, the increasing demand for home-based testing kits and the expansion of telemedicine have further fueled market expansion.
Europe Blood Testing Market Trends
The blood testing market in Europe accounted for a significant market share in 2024, driven by the increasing incidence of chronic diseases, an aging population, and rising healthcare awareness. Advancements in diagnostic technologies, including non-invasive blood tests and point-of-care devices, are driving demand for more efficient and accessible testing solutions.
The UK blood testing market is growing steadily, supported by the increasing prevalence of chronic conditions like diabetes, heart disease, and obesity. Advances in diagnostic technologies, including at-home kits and point-of-care devices, are making blood testing more accessible and efficient.
The blood testing market in France is expected to grow at a significant CAGR over the forecast period, due to the growing emphasis on early disease detection and personalized healthcare. As the prevalence of chronic conditions like diabetes and cardiovascular diseases rises, there is an increased demand for accurate and efficient diagnostic solutions. Technological advancements, such as point-of-care devices and automated systems, are improving the speed and precision of blood tests.
The Germany blood testing market is expected to exhibit at a significant CAGR during the forecast period, due to presence of strong healthcare infrastructure and increasing demand for advanced diagnostic solutions. The rising prevalence of chronic diseases, such as diabetes and cardiovascular disorders, is contributing to the higher adoption of blood testing technologies.
Asia Pacific Blood Testing Market Trends
The blood testing market in Asia-Pacific is expected to witness at the fastest CAGR over the forecast period, driven by rapidly expanding healthcare infrastructure, increasing awareness of chronic diseases, and rising healthcare expenditure. As the population ages and lifestyle-related diseases like diabetes, cardiovascular conditions, and cancer become more prevalent, there is a growing demand for diagnostic solutions. In addition, technological advancements in blood testing, such as point-of-care devices and affordable at-home kits, are driving market adoption. The rise of medical tourism in countries like India and China, along with the expansion of health insurance coverage, is also fueling demand for advanced diagnostic services. These factors, combined with government initiatives to improve healthcare access, position Asia Pacific as a key driver of market growth.
The China blood testing marketis expected to grow at the fastest CAGR over the forecast period, due to country's large population, increasing prevalence of chronic diseases, and significant investments in healthcare infrastructure.
The blood testing market in Japan is expected to grow at a significant CAGR over the forecast period, due to the high aging population and the increasing prevalence of chronic diseases such as diabetes and cardiovascular conditions. The country’s advanced healthcare system, high standards of medical research, and strong regulatory environment support the adoption of cutting-edge diagnostic technologies.
Latin America Blood Testing Market Trends
The blood testing market in Latin America was identified as a lucrative region in this industry due to increasing healthcare investments, rising awareness of chronic diseases, and expanding access to diagnostic services.
The Brazil blood testing market is expected to grow at the fastest CAGR over the forecast period. The prevalence of chronic diseases such as diabetes, hypertension, and cancer drives the market growth. As Brazil continues to expand its healthcare infrastructure, there is a growing demand for advanced diagnostic solutions, particularly in urban areas.
MEA Blood Testing Market Trends
The blood testing market in MEA was identified as a lucrative region in this industry. The market is witnessing significant growth opportunities driven by increasing healthcare investments and a rising burden of chronic diseases such as diabetes, cardiovascular diseases, and cancer.
The Saudi Arabia blood testing market is expected to grow at the fastest CAGR over the forecast period, attributed to the country’s expanding healthcare sector and increasing awareness of chronic diseases such as diabetes, hypertension, and cancer. With a growing population and a focus on improving healthcare services through Vision 2030, Saudi Arabia is investing heavily in advanced diagnostic technologies and healthcare infrastructure.
Key Blood Testing Company Insights
The blood testing industry is driven by major players who continuously innovate to enhance diagnostic accuracy and accessibility. Companies like Abbott, Roche Diagnostics, and Quest Diagnostics Incorporated lead the industry with advanced technologies, including point-of-care devices, automated analyzers, and high-sensitivity testing platforms. Emerging players such as Guardant Health and Bio-Rad Laboratories are gaining traction with novel solutions like liquid biopsy tests and specialized diagnostic tools for oncology and infectious diseases. These companies invest heavily in R&D, strategic collaborations, and regulatory approvals to expand their product portfolios and cater to the growing demand for early disease detection and personalized healthcare globally.
Emerging players in the blood testing industry are making significant strides with innovative technologies that cater to niche diagnostic needs and evolving healthcare trends. Companies like Guardant Health, with its cutting-edge liquid biopsy tests for cancer detection, and Everlywell, which focuses on at-home testing kits, are reshaping the market by offering convenient and accessible solutions for both patients and healthcare providers. Other notable players, such as Freenome and GRAIL, are pioneering advancements in genomic-based blood tests for early cancer detection, leveraging artificial intelligence and machine learning to improve diagnostic accuracy. These emerging companies are gaining attention through strategic partnerships, robust R&D, and the introduction of personalized healthcare solutions, contributing to rapid market growth by addressing unmet medical needs and driving innovation in non-invasive diagnostics.
Key Blood Testing Companies:
The following key companies have been profiled for this study on the blood testing market.
-
Abbott
-
F. Hoffmann-La Roche Ltd
-
Bio-Rad Laboratories, Inc.
-
bioMerieux
-
Quest Diagnostics Incorporated
-
Biomerica
-
BD
-
Siemens Healthineers AG
-
Danaher Corporation
-
Trinity Biotech Plc
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well Established Players (F. Hoffmann-La Roche Ltd., Abbott, Danaher Corporation, Siemens Healthineers AG, BD, Quest Diagnostics Incorporated, bioMérieux)
- Expand blood testing portfolios through clinical chemistry, immunoassays, hematology, molecular diagnostics, automated laboratory systems, and point of care testing solutions. Focus on product innovation, regulatory approvals, strategic collaborations, laboratory automation, digital health integration, and expansion of high throughput diagnostic capabilities to strengthen global market presence.
- Broad blood testing portfolios, extensive global distribution networks, advanced research and development capabilities, strong regulatory expertise, established laboratory infrastructure, and integrated diagnostic solutions. Ability to support hospitals, diagnostic laboratories, blood banks, and healthcare providers through comprehensive instruments, reagents, software, and technical support services.
- Premium pricing of advanced diagnostic systems, lengthy product development and regulatory approval timelines, and dependence on complex manufacturing operations may reduce operational flexibility. High capital investment requirements and reimbursement variability can limit adoption among smaller laboratories and healthcare providers.
Emerging and Specialized Players (Bio-Rad Laboratories, Inc., Biomerica, Trinity Biotech Plc)
- Focus on specialized blood testing solutions including immunodiagnostics, clinical chemistry assays, infectious disease diagnostics, niche biomarker testing, and decentralized diagnostic platforms. Emphasize product innovation, strategic partnerships, geographic expansion, regulatory approvals, and development of application specific blood testing solutions for targeted clinical needs.
- Strong expertise in specialized diagnostic assays, flexible product development, rapid innovation, and targeted testing solutions. Ability to address specific diagnostic applications through differentiated blood testing technologies, customized assay development, and responsive customer support for clinical and laboratory settings.
- Comparatively narrower product portfolios, smaller global commercial presence, and lower manufacturing capacity than multinational diagnostic companies. Greater dependence on selected diagnostic segments and regional distribution partnerships may limit competitiveness across the broader blood testing market.
Recent Developments
-
In July 2024, Guardant Health, Inc. announced that the U.S. Food and Drug Administration (FDA) had granted approval for its Shield blood test, designed for colorectal cancer (CRC) screening in adults aged 45 and older at average risk. Shield is the first blood test approved by the FDA as a primary screening option for CRC, enabling healthcare providers to offer it alongside other non-invasive methods recommended in screening guidelines.
-
In April 2024, Abbott's i-STAT TBI cartridge received FDA clearance for use with whole blood, enabling doctors to assess patients with suspected concussions directly at the bedside. This advancement provides lab-quality results within 15 minutes, eliminating the need for plasma or serum samples to be sent to a lab for processing, which was previously required for traumatic brain injury (TBI) assessments.
-
In May 2024, Roche announced that the Tina-quant lipoprotein Lp(a) RxDx assay received Breakthrough Device Designation from the U.S. Food and Drug Administration (FDA). This assay is designed to identify patients who may benefit from innovative Lp(a)-lowering therapies currently in development. Lipoprotein (a), or Lp(a), is increasingly recognized as a significant yet underappreciated risk factor for cardiovascular disease, a leading public health concern.
Blood Testing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 104.0 billion
Estimated market size in 2026
USD 112.4 billion
Projected market size by 2033
USD 220.3 billion
Growth rate
CAGR of 10.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Test type, Regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
Abbott, F. Hoffmann-La Roche Ltd., Bio-Rad Laboratories, Inc., bioMérieux, Quest Diagnostics Incorporated, Biomerica, BD, Siemens Healthineers AG, Danaher Corporation, Trinity Biotech Plc
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs.Explore purchase options
Global Blood Testing Market Report Segmentation
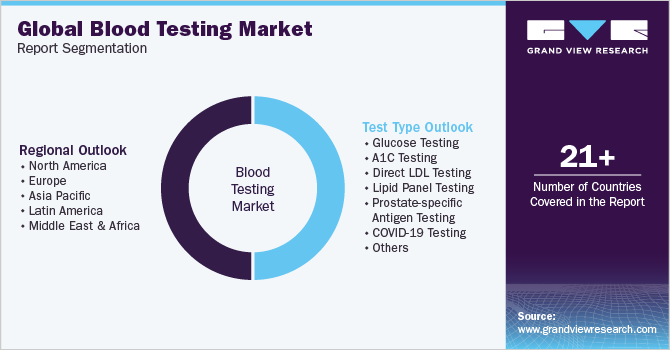
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global blood testing market report based on test type, and region:
 To learn more about this report, Download Free Sample Report
-
Test Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Glucose Testing
-
A1C Testing
-
Direct LDL Testing
-
Lipid Panel Testing
-
Prostate-specific Antigen Testing
-
COVID-19 Testing
-
BUN Testing
-
Vitamin-D Testing
-
Thyroid-stimulating Hormone (TSH)
-
Serum Nicotine/Cotinine
-
High sensitivity CRP Testing
-
Testosterone Testing
-
ALT Testing
-
Cortisol Testing
-
Creatinine Testing
-
AST Testing
-
Others Blood Tests
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
Russia
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
Singapore
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
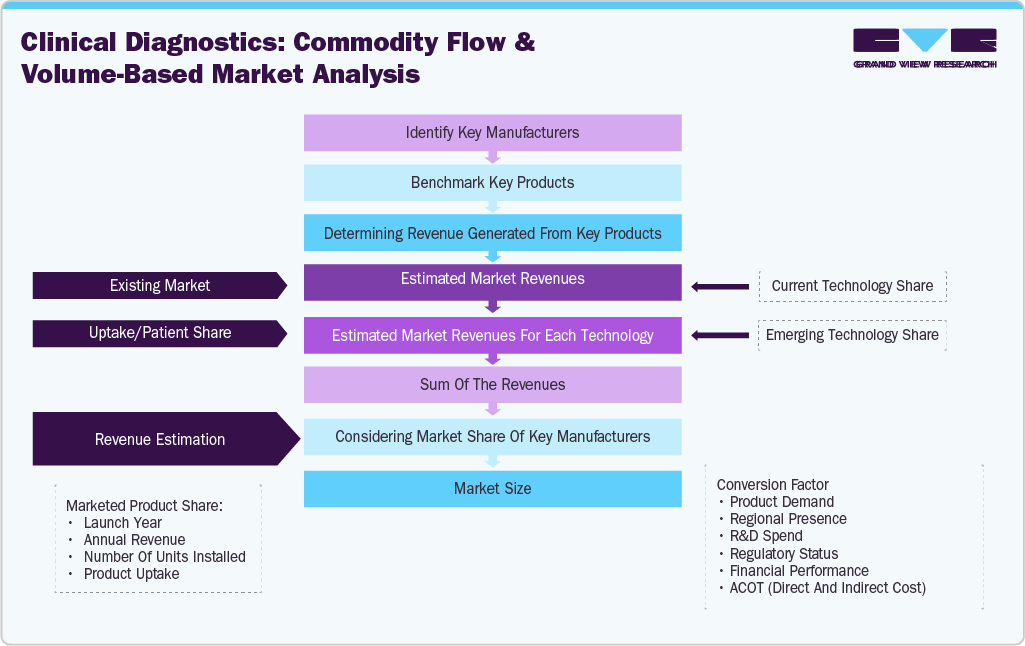
The blood testing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each blood testing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Test type
Revenue capture definition
Glucose Testing
Revenue is primarily captured through sales of blood glucose assay kits, reagents, analyzers, quality controls, calibrators, and laboratory consumables used for diabetes screening, diagnosis, and routine glycemic monitoring.
A1C Testing
Revenue flows from glycated hemoglobin assay kits, immunoassay and chromatography reagents, analyzers, calibrators, controls, and consumables utilized for long term diabetes management and treatment monitoring.
Direct LDL Testing
Revenue is derived from direct low density lipoprotein cholesterol assay kits, chemistry reagents, automated analyzers, calibrators, quality controls, and laboratory consumables used for cardiovascular risk assessment.
Lipid Panel Testing
Revenue is captured through sales of lipid profile reagent kits, clinical chemistry analyzers, calibrators, controls, and consumables used for measuring cholesterol and triglyceride levels in blood samples.
Prostate Specific Antigen Testing
Revenue flows from immunoassay reagent kits, PSA testing analyzers, calibrators, controls, and associated consumables used for prostate cancer screening, diagnosis, and patient monitoring.
COVID 19 Testing
Revenue is primarily captured through molecular assay kits, antigen tests, serology assays, laboratory reagents, automated analyzers, and consumables used for detecting SARS CoV 2 infection.
BUN Testing
Revenue is derived from blood urea nitrogen assay reagents, chemistry analyzers, calibrators, quality controls, and laboratory consumables used for evaluating kidney function and metabolic disorders.
Vitamin D Testing
Revenue flows from vitamin D immunoassay kits, reagents, analyzers, calibrators, controls, and laboratory consumables used for assessing nutritional status and bone health.
Thyroid Stimulating Hormone Testing
Revenue is captured through sales of TSH immunoassay kits, automated analyzers, reagents, calibrators, controls, and consumables used for thyroid function assessment and endocrine disorder diagnosis.
Serum Nicotine Cotinine Testing
Revenue is generated through nicotine and cotinine assay kits, laboratory reagents, analyzers, calibrators, controls, and consumables used for tobacco exposure assessment and smoking cessation monitoring.
High Sensitivity CRP Testing
Revenue is primarily captured through high sensitivity C reactive protein assay kits, immunoassay reagents, analyzers, calibrators, controls, and laboratory consumables used for cardiovascular risk evaluation and inflammation assessment.
Testosterone Testing
Revenue flows from testosterone assay kits, immunoassay reagents, analyzers, calibrators, controls, and laboratory consumables used for hormone evaluation and endocrine disorder diagnosis.
ALT Testing
Revenue is derived from alanine aminotransferase assay reagents, clinical chemistry analyzers, calibrators, controls, and consumables used for liver function assessment and disease monitoring.
Cortisol Testing
Revenue is captured through cortisol immunoassay kits, laboratory reagents, analyzers, calibrators, controls, and consumables used for adrenal gland function assessment and endocrine disorder diagnosis.
Creatinine Testing
Revenue flows from creatinine assay kits, chemistry reagents, automated analyzers, calibrators, controls, and laboratory consumables used for kidney function evaluation and chronic kidney disease monitoring.
AST Testing
Revenue is primarily captured through aspartate aminotransferase assay kits, clinical chemistry reagents, analyzers, calibrators, controls, and laboratory consumables used for liver and muscle injury assessment.
Other Blood Tests
Revenue is derived from assay kits, reagents, analyzers, controls, calibrators, and laboratory consumables used for additional blood based diagnostic tests including electrolyte, enzyme, protein, and biomarker analysis.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Blood Testing Market Competitive Landscape & Technology Assessment
Assessed the global blood testing market across clinical chemistry, immunoassays, hematology, molecular diagnostics, point of care testing, laboratory automation, and digital diagnostic solutions. Evaluated competitive positioning, product portfolios, technology advancements, regulatory approvals, strategic developments, and adoption trends across hospitals, diagnostic laboratories, blood banks, and outpatient healthcare settings.
Helped the client identify technology adoption opportunities, benchmark competitive capabilities, evaluate product differentiation, prioritize strategic investments, and assess market expansion opportunities across the blood testing and clinical diagnostics industry.
Blood Testing Product & Technology Benchmarking Study
Delivered comprehensive benchmarking of blood testing platforms including clinical chemistry analyzers, immunoassay systems, hematology analyzers, molecular diagnostic platforms, and point of care testing devices. Assessed analytical performance, workflow efficiency, automation capabilities, testing throughput, diagnostic accuracy, ease of integration, and product differentiation among leading market participants.
Enabled the client to evaluate technology competitiveness, identify innovation opportunities, benchmark product development strategies, and prioritize investments in laboratory automation, high throughput diagnostics, decentralized testing, and advanced blood testing technologies.
Blood Testing Adoption & Commercialization Assessment
Assessed healthcare infrastructure, blood testing utilization trends, preventive healthcare initiatives, laboratory modernization, reimbursement landscape, regulatory environment, procurement practices, and commercialization pathways influencing the adoption of blood testing technologies across major regional markets.
Supported commercialization planning by identifying market entry opportunities, evaluating customer adoption patterns, assessing operational and investment considerations, mitigating commercialization risks, and strengthening long term growth strategies across diagnostic manufacturers, healthcare providers, diagnostic laboratories, and blood banks.
Frequently Asked Questions About This Report
Some key players operating in the blood testing market include Abbott, F. Hoffmann-La Roche Ltd, Bio-Rad Laboratories, Inc., bioMerieux, Quest Diagnostics Incorporated, Biomerica, BD, Siemens Healthineers AG, Danaher Corporation, Trinity Biotech Plc.
Key factors that are driving the blood testing market growth include increasing patient awareness regarding self-testing, increasing demand for at-home diagnostic tests, and early detection of chronic ailments.
The blood testing market in Asia-Pacific is expected to witness at the fastest CAGR over the forecast period, driven by rapidly expanding healthcare infrastructure, increasing awareness of chronic diseases, and rising healthcare expenditure.
The A1C testing segment is expected to grow at a significant CAGR during the forecast period, due to the increasing global prevalence of diabetes, particularly type 2 diabetes, and the growing awareness of the importance of long-term glucose control.
The expansion of advanced blood testing platforms presents a significant opportunity for the blood testing market. Healthcare systems are increasing investments in high throughput diagnostic technologies to strengthen transfusion safety, support preventive healthcare initiatives, and improve the early detection of infectious and chronic diseases.
The global blood testing market size was valued at USD 104.0 billion in 2025 and is estimated at USD 112.4 billion for 2026.
The global blood testing market is expected to grow at a CAGR of 10.1% from 2026 to 2033, reaching USD 220.3 billion by 2033.
North America dominated the blood testing market with a share of 45.2% in 2025. Key factors attributing to the growth of the market include the rising prevalence of chronic diseases, advancements in diagnostic technologies, and increasing healthcare awareness.
The glucose testing segment dominated the global blood testing market and accounted for the largest revenue share of 27.6% in 2025.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


