
- Home
- »
- Homecare & Decor
- »
-
Books Market Size, Share & Trends Report, 2026-2033GVR Report cover

Books Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Science, Historical, Mystery, Fantasy, Literary), By Format (Hard Copy, E-book, Audiobook), By Distribution Channel (Online, Local Book Shops), By Region, And Segment Forecasts
Market Size, 2025
$134.9BMarket Estimate, 2026
$137.9BMarket Forecast, 2033
$172.4BCAGR, 2026–2033
3.2%Books Market Summary
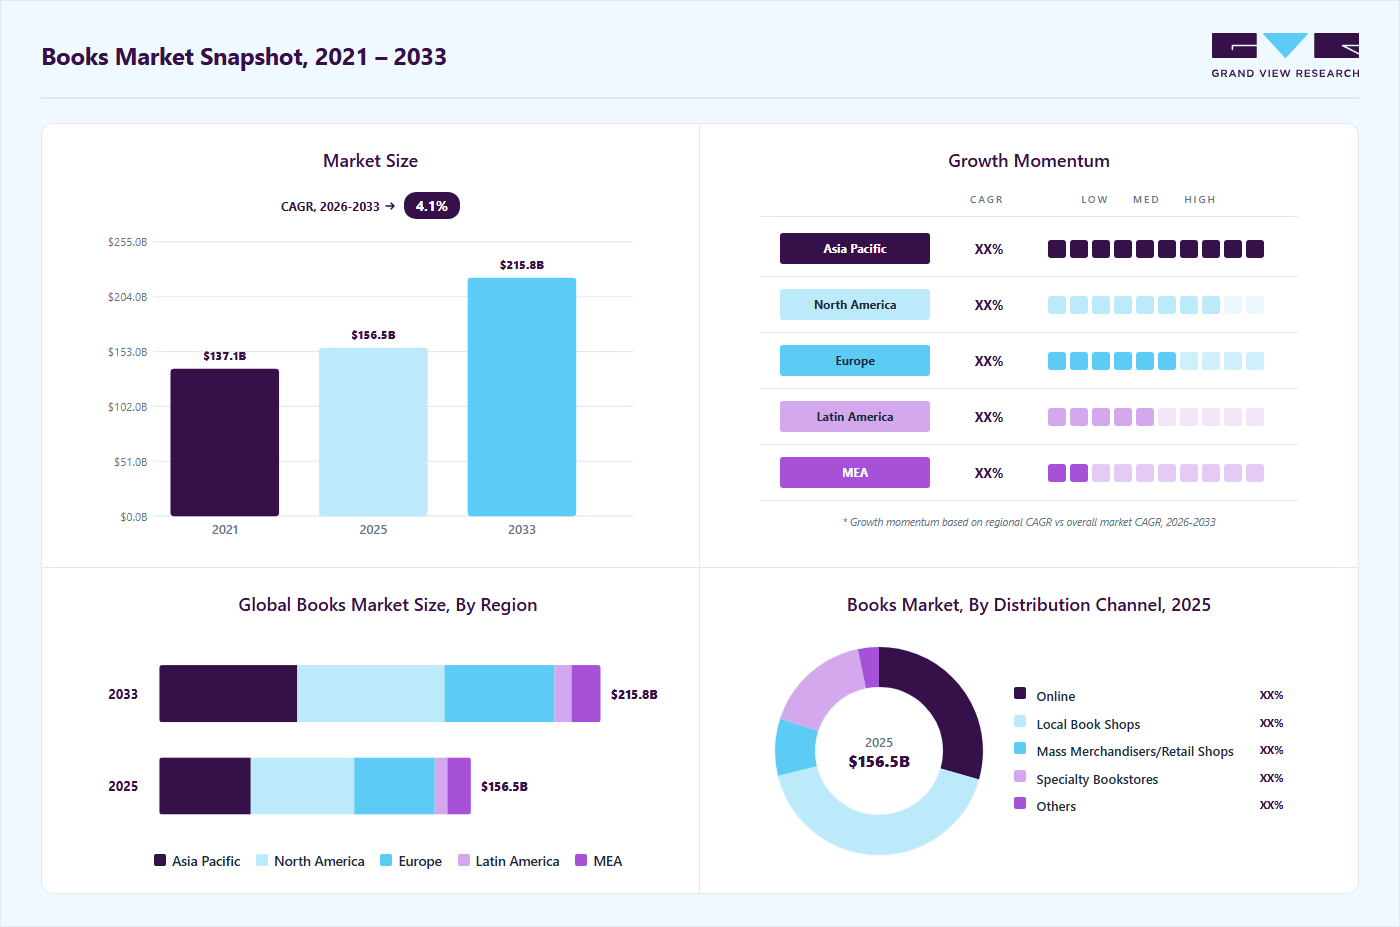
The global books market size was estimated at USD 134.9 billion in 2025 and is projected to grow from USD 137.9 billion in 2026 to USD 172.4 billion by 2033, at a CAGR of 3.2% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 35.9% in 2025. The global books industry is being shaped by changing consumer preferences across science, historical, mystery, fantasy, literary, contemporary/realistic, romance, educational, and comic books, alongside continued demand for both physical and digital reading formats.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Educational books held the largest market share of 32.4% in 2025.
- By format: Hard copy books held the largest market share of 75.8% in 2025.
- By distribution channel: Online segment held the largest market share of 40.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (35.9% revenue share, 2025)
- Fastest-growing regional market: Middle East & Africa (fastest CAGR, 2026-2033)
Market Size & Forecast
- Market Size in 2025: USD 134.9 Billion
- Estimated Market Size in 2026: USD 137.9 Billion
- Projected Market Size by 2033: USD 172.4 Billion
- CAGR (2026-2033): 3.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Increasing access to books through online platforms, local bookshops, mass merchandisers/retail shops, and specialty bookstores is expanding consumers' access to diverse titles and authors across regions. Demand for fantasy, romance, mystery, and contemporary/realistic books is supported by growing consumer engagement with genre-specific content and social-media-based book discovery, while educational and science books continue to benefit from demand for learning and knowledge-oriented content.The U.S. provides another indication of the scale of book consumption. According to the Association of American Publishers (AAP), 3.15 billion books were sold in the U.S. in 2025, representing a 0.4% increase from 2024, while publishing revenue was up 2.5%, and adult fiction revenue increased 3.9%, indicating continued consumer demand for several fiction-related categories within the broader books market. Meanwhile, the increasing adoption of e-books and audiobooks is expanding consumption beyond hard-copy formats, creating a more diversified global market across formats and distribution channels.
 To learn more about this report, Download Free Sample Report
The book market is evolving as preferences shift across book types, formats, and distribution channels, with digital formats and strong demand for select fiction categories supporting industry growth. In 2025, the U.S. publishing industry generated revenue, up 2.5% from 2024, while Trade publishing revenue increased 2.7%. Within Trade publishing, adult fiction revenue rose 3.9%, while hardback and paperback formats together accounted for 73.1% of Trade revenue, highlighting the continued importance of physical books alongside digital formats. Digital Audio revenue increased 5.3%, while e-book revenue rose 3.2%, demonstrating continued consumer adoption of digital reading and listening formats.
Consumer demand for audiobooks has also expanded substantially, strengthening the audiobook segment within the format category. According to U.S. audiobook revenue recorded an increase of 9% from the previous year the Audio Publishers Association, U.S. audiobook revenue an increase of 9% from the previous year, while publishers reported more than 750,000 active audiobook titles, up 43% from 2024. The growth in available titles is increasing the breadth of content across categories and giving consumers greater flexibility to access books through digital listening platforms.
Print books, however, continue to represent a significant part of the market. In the U.S., 762.4 million print books were sold in 2025, representing a 0.3% increase from 2024. Category-level performance varied considerably: romance sales increased by 3.9% to nearly 44 million units, while science fiction sales increased by 22.1% to more than 6 million units. Mystery- and thriller-related demand remained substantial, with suspense and thriller sales reaching approximately 25.5 million units despite a 2.2% decline. These patterns indicate that consumer demand remains distributed across specific book types rather than moving uniformly toward a single category.
The book market is being shaped by the coexistence of traditional print formats and expanding digital reading and listening options. Consumer preferences are becoming increasingly diverse across book types, while online platforms, physical bookstores, mass retailers, and specialty channels provide multiple avenues for discovery and purchase. At the same time, digital formats are creating greater accessibility and convenience, while physical books continue to appeal to consumers seeking tangible ownership and immersive reading experiences. These shifts are encouraging publishers and retailers to diversify content offerings, strengthen multichannel distribution, and adapt their strategies to changing consumer expectations across formats and purchasing channels.
Market Dynamics
Social media platforms, particularly TikTok and the #BookTok community, are increasingly influencing book discovery and purchasing behavior, especially among younger consumers. In 2025, more than 50 million #BookTok-recommended books were sold across key European markets. More than one-third of consumers aged 16-39 reportedly discovered new books through #BookTok, while around one in three young readers purchased books they had previously encountered or been recommended through digital media. The growing visibility of books through creator recommendations, reader discussions, short-form videos, and viral content is raising awareness of specific genres, particularly romance, fantasy, mystery, and contemporary titles. Publishers, authors, bookstores, and online retailers are consequently using social media communities to strengthen book discovery, engage younger audiences, and convert digital interest into purchases across online and physical distribution channels.
Counterfeit and pirated books continue to create revenue leakage for publishers, authors, and legitimate booksellers by diverting demand toward unauthorized copies and reducing returns from copyrighted content. The problem spans both physical counterfeiting and digital piracy, with online distribution making unauthorized copies easier to reproduce and circulate across websites, social platforms, and file-sharing channels. In 2025, the Italian Publishers Association estimated that book piracy resulted in €722 million in lost book sales in Italy, equivalent to approximately 30% of the country's book market excluding school books and exports. The broader economic impact was estimated at €1.95 billion, including related activities, while approximately 4,500 jobs in the book industry were estimated to be lost.
Physical piracy also remains a challenge in emerging publishing markets. In India, the Ministry of Education reported in June 2025 that more than 500,000 pirated NCERT textbooks had been seized over the previous 14 months, along with printing equipment and materials valued at more than INR 200 million; authorities also registered 29 FIRs against individuals involved in producing and distributing pirated textbooks. These activities increase enforcement and monitoring requirements for publishers while potentially reducing legitimate sales and making it more difficult to recover investments in content creation and distribution.
The emergence of local authors and language-specific content is vital in preserving cultural diversity and enriching the global literary landscape. Local authors capture the unique experiences, histories, and traditions of their communities, safeguarding cultural heritage and amplifying marginalized voices often overlooked in mainstream publishing. Their work introduces regional specificity, offering authentic stories, dialects, and perspectives that resonate deeply with readers. By championing these voices, the book industry promotes inclusivity and ensures that literature reflects the rich tapestry of global cultures, fostering a more diverse and representative literary world.
Analyst Perspective
The book market is increasingly shaped by the coexistence of print, e-books, and audiobooks, alongside evolving consumer preferences and changing book-discovery behaviors. Publishers are expanding multiformat offerings and strengthening online, physical, and direct distribution channels to improve accessibility and reach diverse reader groups. Social media and digital platforms are influencing how consumers discover authors, titles, and emerging content trends, while online retailers are making books more accessible across geographic markets. At the same time, physical bookstores and specialty retailers continue to support discovery and personalized purchasing experiences. These developments are encouraging publishers to diversify content portfolios, strengthen digital capabilities, and adopt flexible distribution strategies across formats and channels.
Brand Market Share Insights
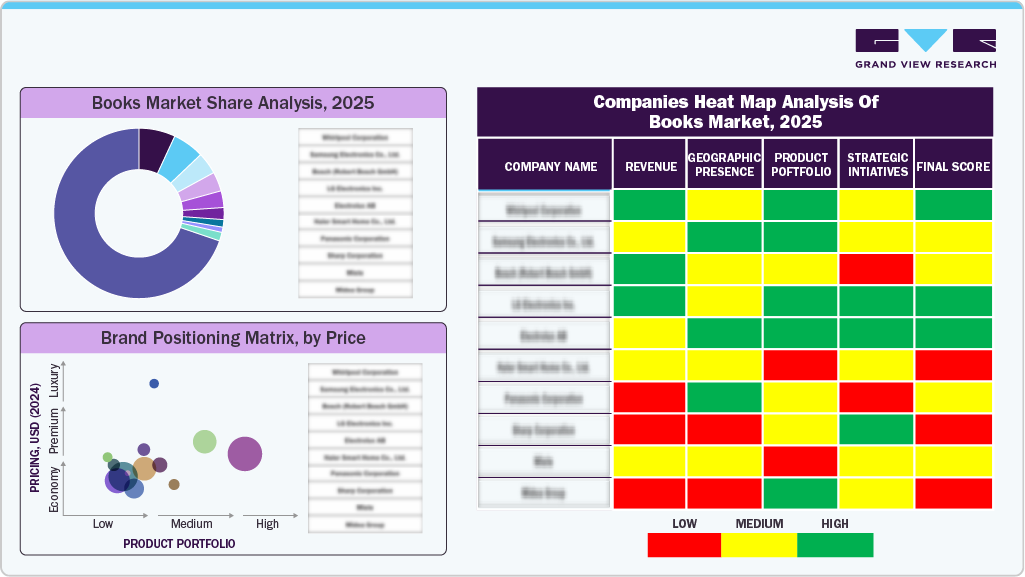
The global book market is characterized by a mix of large, established publishing groups and specialized publishers competing across diverse book types, formats, and distribution channels. Leading companies strengthen their market presence through extensive publishing catalogs, established author relationships, broad retail and distribution networks, and capabilities spanning print, e-books, and audiobooks.
 To learn more about this report, Download Free Sample Report
Major publishers are also expanding their digital capabilities and leveraging online retail platforms to improve accessibility and reach. At the same time, companies with specialized portfolios are differentiating themselves through distinctive content, recognizable intellectual properties, educational offerings, and targeted reader communities. Strategic acquisitions, licensing agreements, multimedia partnerships, and investments in digital and audio publishing are further enabling publishers to broaden their portfolios and strengthen consumer engagement across markets.
Consumer Insights
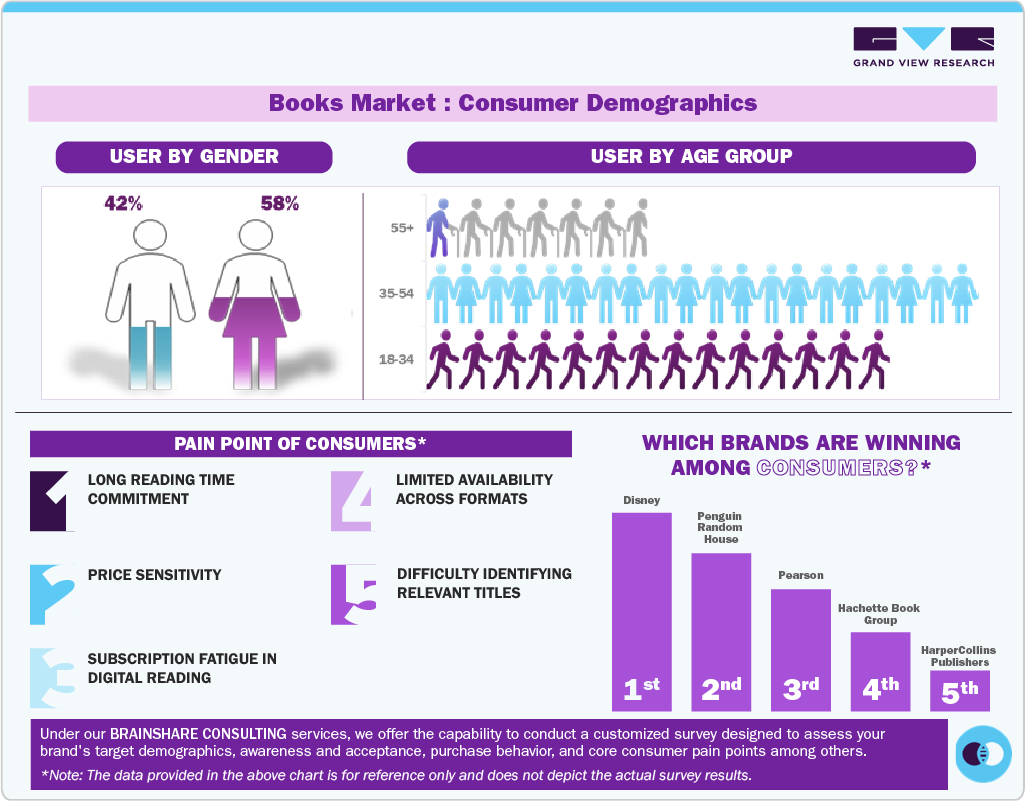
Consumer reading behavior in the U.S. reflects a continued preference for print books alongside growing adoption of digital formats. According to the Pew Research Center, 75% of U.S. adults read a book in any format during the previous 12 months, including 64% who read a print book, 31% who read an e-book, and 26% who listened to an audiobook. This indicates that print remains an important format, while e-books and audiobooks have become established alternatives that provide greater flexibility and accessibility.
 To learn more about this report, Download Free Sample Report
Age differences are also evident in format preferences. Among adults aged 18-29, 66% read print books, 41% read e-books, and 32% listened to audiobooks, compared with 65%, 23%, and 13%, respectively, among adults aged 65 and older. Education also influences reading participation, with 88% of college graduates reporting that they read a book in any format, compared with 60% of adults with a high-school education or less. These differences indicate that publishers and retailers need to address varied format preferences and reading behaviors across demographic groups.
Type Insights
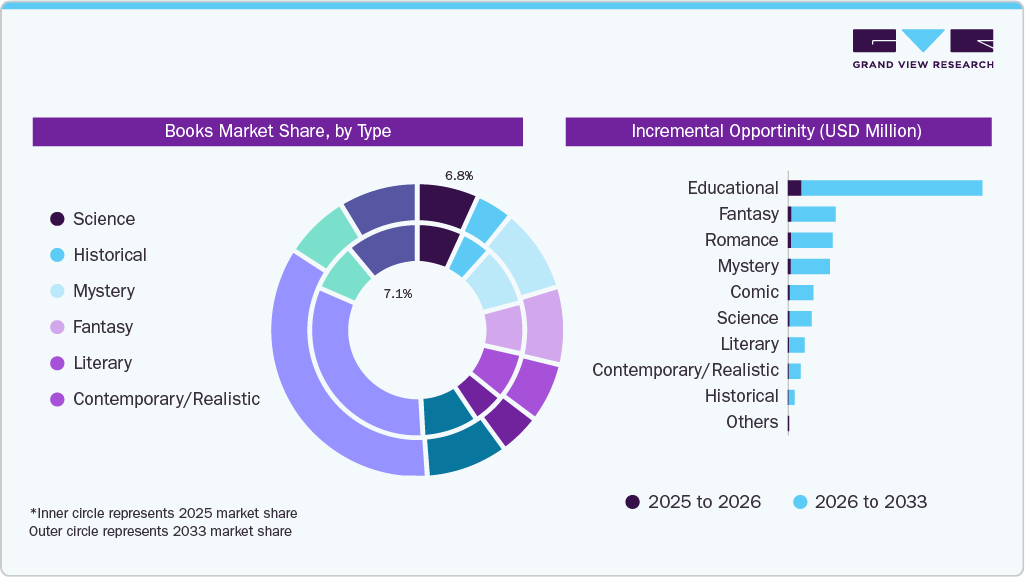
Educational books accounted for a revenue share of 32.4 % in 2025. Educational books remain an essential component of formal and higher education, supporting structured learning, academic instruction, examination preparation, and professional skill development. According to the Association of American Publishers (AAP), U.S. higher education course materials revenue increased by 8.5% in 2025, reflecting continued demand for textbooks and other learning materials used across colleges and universities. The segment is also adapting to changing student needs through print, digital, and affordable-access models, enabling learners to obtain course materials at lower costs while maintaining access to curriculum-aligned educational content.
 To learn more about this report, Download Free Sample Report
Fantasy books are projected to grow at a CAGR of 4.6% over the forecast period. Fantasy books continue to attract readers through immersive fictional worlds, adventure, supernatural elements, and fantasy-romance narratives. The popularity of contemporary titles such as Onyx Storm by Rebecca Yarros, the third installment in the Empyrean series, highlights the strong consumer interest in fantasy-romance content. Released in January 2025, Onyx Storm sold more than 2.7 million copies in its first week, making it the fastest-selling adult fiction title in two decades, according to reporting by The New York Times. The success of the title, following the popularity of Fourth Wing and Iron Flame, demonstrates the ability of high-profile fantasy series to generate substantial consumer demand and attract readers through a combination of fantasy, romance, and series-based storytelling.
Format Insights
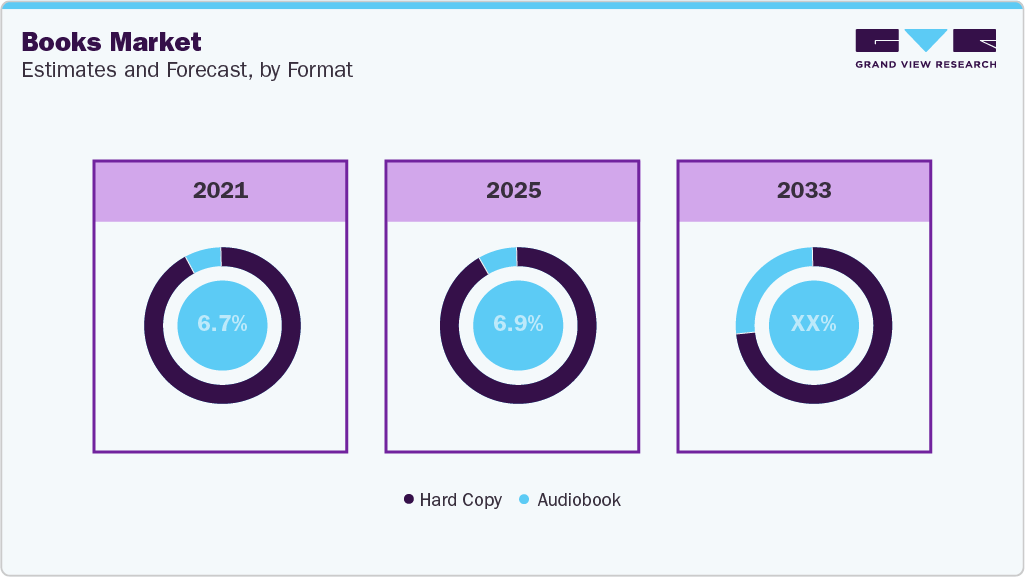
Hard-copy books dominated the books market, accounting for a revenue share of 75.8% in 2025. Hard-copy books continue to represent a major share of the book industry, supported by consumers' preference for tangible reading experiences, collecting, gifting, and screen-free reading. According to the Association of American Publishers (AAP), print formats accounted for 50.6% of U.S. publishers' total revenue in 2025, with hardback revenue increasing 3.9% and paperback revenue increasing 2.1%, highlighting the continued importance of physical formats despite the expansion of e-books and digital audio.
 To learn more about this report, Download Free Sample Report
Audio books are projected to grow at a CAGR of 8.4% over the forecast period of 2026-2033. Audiobook consumption is expanding as digital platforms increase the availability and accessibility of audio content. In June 2025, Spotify reported that its English-language audiobook catalog had nearly tripled to more than 400,000 titles since the launch of Audiobooks in Premium in 2023. Across the U.S., the UK, and Australia, the number of audiobook listeners increased by more than 30% year over year, while audiobook listening hours grew by more than 35%. The expansion of catalog size, combined with convenient access through smartphones and other connected devices, is enabling consumers to discover and listen to a wider range of books, supporting the growing adoption of audiobooks as an alternative format.
Distribution Channel Insights
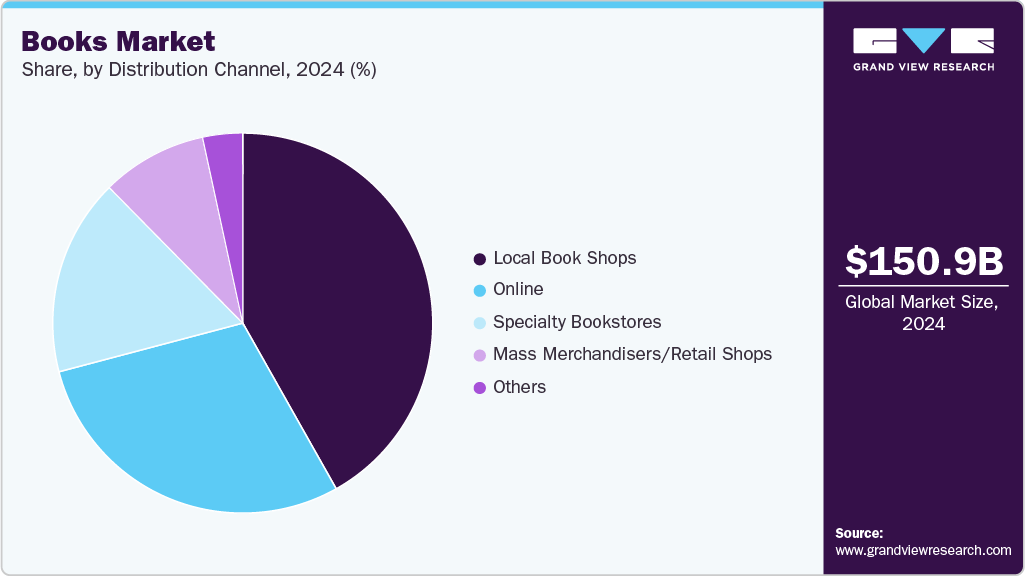
Online channels dominated the books industry, accounting for a revenue share of 40.5% in 2025. Online distribution channels are gaining importance in the books industry as consumers increasingly value convenient access to broad catalogs, easy price comparison, and home delivery. The growth of digital platforms is also enabling independent bookstores to participate in e-commerce without relying solely on physical store traffic. For instance, Bookshop.org reported revenue growth of nearly 55% from 2024. The platform now works with approximately 2,900 booksellers, while e-commerce sales among American Booksellers Association members increased 25% in 2025. These developments demonstrate how online channels are expanding the reach of booksellers while creating additional sales opportunities for independent bookstores.
 To learn more about this report, Download Free Sample Report
Specialty bookstores are projected to grow at a CAGR of 1.1% over the forecast period of 2026-2033. Specialty bookstores are expected to maintain steady growth over the forecast period, supported by consumers’ preference for curated book selections, knowledgeable staff, and personalized recommendations. These stores provide readers with opportunities to discover specialized titles across genres such as literary, fantasy, mystery, science, educational, and contemporary, which may receive less visibility through mass-market retail channels. In addition, author events, book clubs, reading communities, and local literary activities are strengthening customer engagement and encouraging repeat visits. The expansion of independent and specialty bookstores, combined with their ability to offer differentiated assortments and community-oriented experiences, is supporting their continued relevance within the books market.
Regional Insights
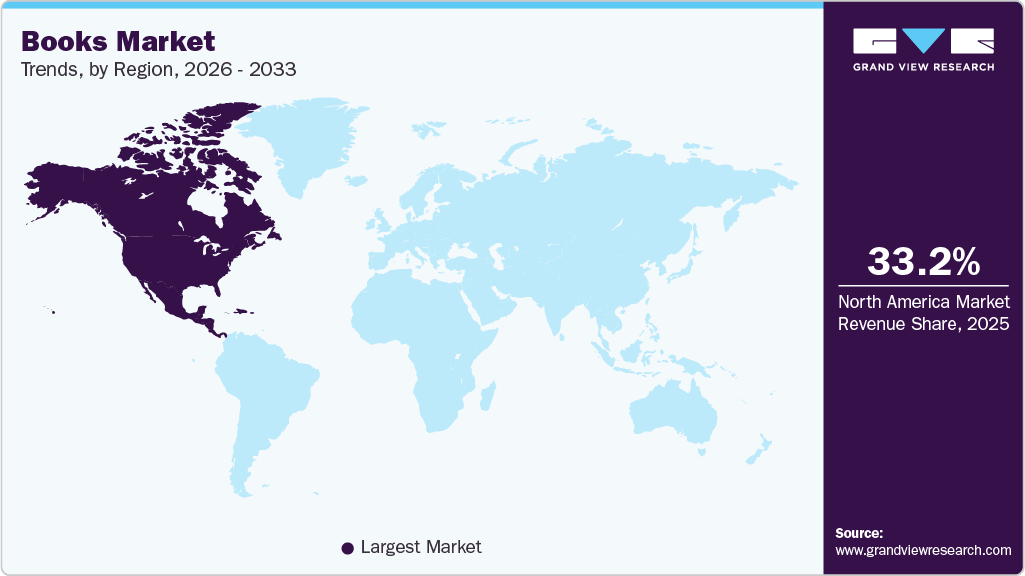
The Asia Pacific books market accounted for the largest global revenue share of 35.9% in 2025. The market is supported by continued growth in book sales, publishing activity, and demand for specific content categories across developed and emerging markets. Australia recorded 3.2% growth in book-market value and 1.4% growth in volume in 2025, with adult fiction increasing 4.9% and children’s, young adult, and educational books rising 7.4%. South Korea also showed continued publishing activity, with its book-publishing production index increasing 2.3% and the number of new titles published rising 1.1% during 2025. These developments indicate that demand for fiction, children's, and educational content, together with continued publishing activity and digital distribution, is supporting growth across the market.
 To learn more about this report, Download Free Sample Report
The China books market accounted for a revenue share of 31.7% in 2025. China’s reading market continued to expand in 2025, with the comprehensive reading rate among adults reaching 82.3%, up 0.2 percentage points from 2024. The average number of print and e-books read per adult was 8.39. Mobile reading also remained widespread, with the adult mobile reading rate reaching 79.0%, up 0.3 percentage points from the previous year, while the proportion of adults exposed to digital reading formats reached 80.8%. Among younger readers, the book-reading rate was 86.7%, with an average of 11.72 books per person. Digital reading also expanded, with the number of digital-reading works reaching up 11.87%, while the digital-reading user base reached 689 million, increasing 2.95% year over year.
The books market in India is projected to grow at a CAGR of 6.2% from 2026 to 2033. The market growth is strongly supported by educational publishing and the country's extensive demand for textbooks. According to India's Ministry of Education, textbooks account for nearly 96% of the total volume of book sales in the country. For the 2025-26 academic session, NCERT planned to publish 150 million textbooks, with availability targeted across nearly 20,000 PIN codes nationwide. The government also partnered with Amazon to make original NCERT textbooks available through major e-commerce platforms, helping address supply gaps, delayed availability, and regional shortages. NCERT has published approximately 2.2 billion books and journals since 1963, while its publishing program covers 23 languages, highlighting the scale and linguistic diversity of India's educational book ecosystem.
Europe Books Market Trends
The Europe books industry accounted for a revenue share of around 27.5% in 2025. The market continued to show mixed but resilient performance across individual countries in 2025. France, in contrast, recorded a 0.6% decline in publishing revenue and a 1.5% decline in book volumes in 2025, although school publishing revenue rebounded by 8.2% and book exports increased 5.7%. Across the wider European publishing industry, the Federation of European Publishers reported that publisher turnover increased 2.2% in 2024, with audiobooks accounting for approximately 4.2% of turnover and e-books around 13%. These developments indicate continued demand for books across European markets, while differences in economic conditions, format adoption, and content categories are creating varied growth patterns between countries.
The Germany books market accounted for a revenue share of 28.7% in 2025. The market growth is driven by a deeply embedded reading culture, a highly structured publishing ecosystem, and strong institutional support for books and literacy. Fiction sales increased by 1.3% in 2025, reflecting continued demand for fiction titles in the Germany book market. Meanwhile, specialist bookstores recorded a 3.0% decline in turnover, while average selling prices increased by 2.8% over the year. Consumers maintain consistent demand across educational, academic, professional, and leisure reading segments, supported by a nationwide network of independent bookstores, large retail chains, and public libraries. The market places strong emphasis on high production quality, editorial standards, and copyright protection, which sustains publisher confidence and long-term title availability.
The books market in the UK is projected to grow at a CAGR of 3.1% from 2026 to 2033. The growth is supported by a well-established reading culture, a diversified publishing ecosystem, and an extensive network of independent bookstores, retail chains, online platforms, and libraries. Consumers maintain demand for educational, academic, professional, and leisure reading, while publishers increasingly provide content in both print and digital formats. Recent industry performance highlights this continued demand: according to the Publishers Association, UK publishing revenue increased 3%, while consumer publishing revenue rose 3%. Fiction revenue increased 8%, and digital audiobook revenue grew 10%, reflecting continued demand for both leisure content and alternative formats. The physical retail ecosystem also remained active, with a record 739 independent bookshops participating in Independent Bookshop Week 2025, up from 716 in 2024. These developments demonstrate the continued importance of both physical and digital channels within the UK market.
North America Books Market Trends
The book industry in North America held a revenue share of 26.1% in 2025, due to the strong presence of independent publishers and an expanding audience of engaged readers. Major retailers like Amazon and Barnes & Noble dominate the region, while the rising popularity of e-books and audiobook formats reflects evolving consumer preferences. Although many brick-and-mortar bookstores face challenges from digital alternatives, the shift toward online purchasing and subscription-based reading platforms has stimulated market expansion. Canada also contributed to North America's book market, with 47.9 million physical books sold in 2025, valued at approximately CAD 1.15 billion, according to BookNet Canada. Juvenile and Young Adult books represented 39% of the Canadian market, followed by Non-Fiction at 30% and Fiction at 29%. Books by Canadian authors accounted for 14% of print book sales in 2025, up from 12% in 2024, indicating continued consumer demand for locally authored content.
U.S. Books Market Trends
The U.S. books industry accounted for a revenue share of 94.8% in the year 2025. It benefits from a broad and engaged readership, with demand spanning multiple formats and reader groups. According to the Pew Research Center’s October 2025 survey, 75% of U.S. adults had read at least one book in the previous 12 months. Print remained the most widely used format, with 64% of adults reporting having read a print book, 31% having read an e-book, and 26% having listened to an audiobook. Reading engagement was particularly high among younger and college-educated consumers, with 78% of adults aged 18-29 and 88% of adults with a college education or higher reporting having read a book in the previous year.
The Mexico books market is projected to grow at a CAGR of 3.5% from 2026 to 2033. The growth is supported by a broad publishing base and continued consumer demand for printed books. The Mexican book industry continued to benefit from demand across fiction, children’s, educational, and other book categories, while publishers and retailers increasingly combined traditional physical distribution with digital channels to reach readers. The market also benefits from the presence of established publishing groups, independent bookstores, retail chains, and online platforms, which provide consumers with access to diverse titles across different formats.
Central & South America Books Market Trends
The Central & South America books industry is projected to grow at a CAGR of 3.0% from 2026 to 2033. In Brazil, 18% of adults aged 18 and above purchased at least one book in 2025, representing approximately 3 million new book consumers compared with the previous year. Colombia recorded stronger industry-level momentum, with publishing-sector sales increasing 7.5% in 2025, while book volumes reached 39.4 million copies, up from 37.9 million in 2024. Argentina also expanded its publishing output, with 36,942 titles published in 2025, representing a 17% increase from 2024. These developments indicate increasing participation in the regional book ecosystem, supported by both consumer purchasing and continued expansion of local publishing activity.
The books market in Brazil accounted for a revenue share of 32.4% in 2025, supported by a broad consumer base, growing interest in diverse book types, and increasing integration of digital channels into book discovery and purchasing. Demand spans fiction, children’s and young adult titles, educational content, religious books, and adult nonfiction, while younger consumers are increasingly influenced by social media, online recommendations, and digital communities when discovering books. The market also benefits from the continued presence of physical bookstores alongside online retail platforms, providing consumers with multiple options for purchasing and discovery. Publishers are therefore expanding their catalogs across print and digital formats while strengthening online distribution, social-media engagement, and bookstore relationships to reach different reader groups and support sustained book consumption.
Middle East & Africa Books Market Trends
The Middle East & Africa books industry is projected to grow at a CAGR of 5.2% from 2026 to 2033. The market continues to reflect a combination of established print-reading habits and increasing adoption of digital and audio formats. For instance, the UAE National Reading Index 2025, released by the UAE Ministry of Culture in April 2026, found that residents read approximately six printed books annually, compared with seven in 2023, while digital and audio formats recorded an average of nine books annually. The survey also found that 54% of community members dedicate time to reading every day, while 40.7% own home libraries and 43.3% have designated reading spaces at home, indicating that reading remains embedded in household routines despite the shift toward digital formats.
The books market in Saudi Arabia accounted for a revenue share of 16.6% in 2025, supported by government initiatives promoting reading, cultural participation, and the development of the publishing ecosystem. Demand spans educational, literary, children’s, religious, and general-interest books, while digital formats and online channels are gradually expanding alongside established print consumption. The country’s growing cultural and literary event infrastructure is also strengthening opportunities for publishers, authors, and booksellers to engage with readers. Improvements in bookstores, online retail, and digital distribution are further increasing access to books, supporting the the market development.
Key Books Companies
The following key companies have been profiled for this study of the books market.
-
Disney
-
Penguin Random House
-
Pearson
-
Hachette Book Group
-
HarperCollins Publishers
-
Scholastic Inc.
-
Simon & Schuster, Inc.
-
McGraw-Hill
-
Macmillan
-
IDW Publishing
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Disney; Penguin Random House; Pearson; Hachette Book Group; HarperCollins Publishers; Scholastic Inc.)
- Mature players expand beyond traditional book sales by investing in digital content, audiobooks, educational platforms, licensing, and diversified publishing portfolios to strengthen revenue streams and reach broader reader segments.
- Mature players utilize established author relationships, extensive publishing catalogs, strong retail and distribution networks, recognizable brands, and multiformat capabilities to maintain broad market access.
- Large organizational structures, established workflows, and legacy publishing systems can make it more difficult to respond quickly to changing reader preferences, digital formats, and emerging content-consumption models.
Emerging & Niche Players (Simon & Schuster, Inc.; McGraw Hill; Macmillan; IDW Publishing)
- Strategically differentiated players leverage focused publishing portfolios, digital platforms, specialized educational or entertainment content, licensing, and multiformat publishing to strengthen their market presence and reach targeted audiences.
- These players can leverage specialized content expertise, recognizable franchises, strong author or creator relationships, and focused distribution and marketing strategies to address specific reader and learning segments.
- More focused portfolios and comparatively narrower distribution or brand reach can limit scale and make it challenging to compete with the extensive catalogs, resources, and retail relationships of the largest publishing groups.
Recent Developments
-
In February 2026, Penguin Random House Publisher Services (PRHPS) entered a multi‑year worldwide partnership with Oni Press, under which PRHPS will sell and distribute Oni’s comic books and graphic novels globally beginning August 1, 2026. This collaboration expands Oni Press’s reach by leveraging PRHPS’s international sales and distribution network for both frontlist and backlist titles.
-
In January 2026, HarperCollins India announced the special hardback edition launch of Prajakta Koli’s bestselling romance novel Too Good To Be True, set for publication in February 2026 to celebrate the title’s success and engage readers with a premium format. This edition underscores the continued popularity of the book and HarperCollins India’s commitment to presenting celebrated works in distinctive editions.
-
In March 2025, HarperCollins India launched Booktopus, a new imprint designed for preschoolers and early readers. This imprint aims to foster curiosity and learning through interactive and engaging books. The initial collection features a variety of formats, including board books, puzzle books, touch-and-feel books, sticker books, and lift-the-flap books. Tina Narang, Executive Publisher of HarperCollins Children's Books, emphasized the importance of providing creative and stimulating content for young learners.
-
In January 2025, Penguin Random House launched The Penguin Nehru Library, a collection of Jawaharlal Nehru’s writings, including his letters, essays, and other works. This initiative aims to provide readers with a deeper understanding of Nehru’s ideas, his vision for modern India, and his reflections on its cultural and political landscape.
Books Market Report Scope
Report Attribute
Details
Market size in 2025
USD 134.9 billion
Estimated market size in 2026
USD 137.9 billion
Projected market size by 2033
USD 172.4 billion
Growth rate
CAGR of 3.2% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, format, distribution channel, and region
Regional scope
North America; Europe; Asia Pacific; Central & South America; the Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Belgium; Netherlands; Luxembourg; China; India; Japan; Australia & New Zealand; South Korea; Indonesia; Thailand; Vietnam; Singapore; Malaysia; Brazil; Argentina; South Africa; UAE; Saudi Arabia
Key companies profiled
Disney; Penguin Random House; Pearson; Hachette Book Group; HarperCollins Publishers; Scholastic Inc.; Simon & Schuster, Inc.; McGraw-Hill; Macmillan; IDW Publishing
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Books Market Report Segmentation
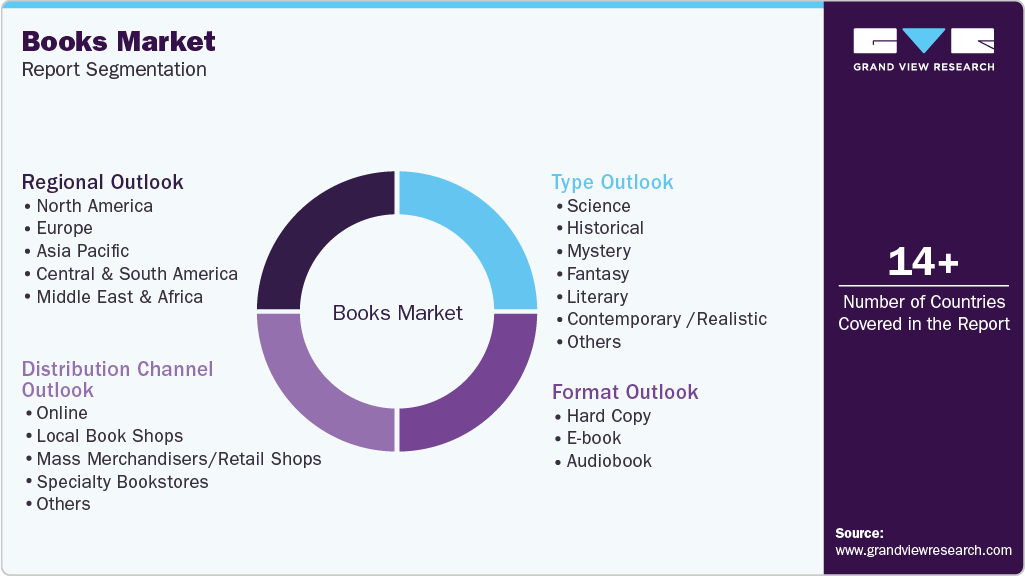
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the books market report based on type, format, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Science
-
Historical
-
Mystery
-
Fantasy
-
Literary
-
Contemporary /Realistic
-
Romance
-
Educational
-
Comic
-
Others
-
-
Format Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hard Copy
-
E-book
-
Audiobook
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Online
-
Local Book Shops
-
Mass Merchandisers/Retail Shops
-
Specialty Bookstores
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Belgium
-
Netherlands
-
Luxembourg
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia & New Zealand
-
South Korea
-
Indonesia
-
Thailand
-
Vietnam
-
Singapore
-
Malaysia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa (MEA)
-
South Africa
-
UAE
-
Saudi Arabia
-
-
Research Methodology
The books market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each books segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Format
Revenue capture definition
Hard Copy
This category includes books available in physical formats such as hardcover, paperback, and softcover editions. These formats are widely used across genres, including literary fiction, educational textbooks, and graphic novels. Examples include To Kill a Mockingbird (hardcover), The Catcher in the Rye (paperback), and The Great Gatsby (softcover).
E-book
This segment encompasses digital versions of printed books, accessible on computers, tablets, e-readers, and smartphones. E-books offer features such as adjustable text size and interactive content, making them a preferred format for academic texts and contemporary fiction. Notable examples include Sapiens: A Brief History of Humankind (Kindle edition) and The Handmaid’s Tale (ePub format).
Audiobook
This category includes professionally narrated recordings of books, available in various formats, including CDs, MP3 downloads, and streaming services. Audiobooks enhance accessibility and are popular for fiction, biographies, and self-help genres. Examples include Becoming by Michelle Obama (Audible), Atomic Habits by James Clear (CD format), and Harry Potter and the Sorcerer’s Stone (digital download).
Estimation Model
Consumer Need & Target Base Layer
Book Accessibility & Distribution Layer
Active Purchasing & Engagement Layer
Monetisation Layer
Who has a need or interest in reading books?
Who has access to books through relevant formats and channels?
Who actively purchases books?
How much revenue is generated?
Begin with the target population with an interest in reading across different book types, including science, historical, mystery, fantasy, literary, contemporary/realistic, romance, educational, and comic books. Consider readers across different age groups, education levels, and reading preferences.
Filter the potential reader base based on access to books through hard copy, e-books, and audiobooks, as well as online retailers, local book shops, mass merchandisers/retail shops, specialty bookstores, and other distribution channels. Consider availability across relevant book types and formats.
Apply reader awareness, purchase intent, willingness to pay, reading frequency, and book-purchase rates to identify active book buyers. Consider factors such as social-media and online recommendations, author awareness, bookstore discovery, educational requirements, gifting, and recurring reading habits.
Multiply the estimated number of active book purchasers by average selling price (ASP), purchase frequency, and format mix. Consider revenue generated across science, historical, mystery, fantasy, literary, contemporary/realistic, romance, educational, comic, and other book types, segmented by hard copy, e-book, and audiobook.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Books Market & Product Trend Analysis
Conducted a detailed assessment of the books market across science, historical, mystery, fantasy, literary, contemporary/realistic, romance, educational, comic, and other book types, evaluating format preferences across hard copy, e-book, and audiobook. The analysis also assessed reading behavior, publishing trends, book demand, pricing, and recent developments across major markets.
Helps stakeholders identify high-potential book types and formats, understand shifts in reader preferences, assess the transition between print and digital formats, and identify opportunities for portfolio expansion and content diversification.
Consumer & Distribution Channel Analysis
Evaluated consumer reading and purchasing behavior across online channels, local book shops, mass merchandisers/retail shops, specialty bookstores, and other distribution channels. The analysis assessed reading frequency, format preferences, purchase behavior, consumer demographics, book discovery, and the influence of digital platforms and social media on book purchases.
Provides insights into channel-specific opportunities, consumer purchasing patterns, format preferences, and book discovery behavior. Supports distribution strategy, channel expansion, pricing decisions, and targeted reader engagement.
Publishing, Distribution & Competitive Landscape Assessment
Assessed developments across the publishing ecosystem, including publishing portfolios, digital publishing, audiobook expansion, e-book adoption, physical bookstores, online distribution, publisher partnerships, new imprints, format innovation, and competitive strategies. The analysis also evaluated key publishers and their activities across different book types and formats.
Supports competitive positioning and publishing strategy by identifying emerging book formats, content opportunities, distribution strategies, publisher differentiation, and consumer-driven developments shaping the books market.
Frequently Asked Questions About This Report
The global books market size was estimated at USD 134.9 billion in 2025 and is expected to reach USD 137.9 billion in 2026.
The global books market is expected to grow at a compound annual growth rate of 3.2% from 2026 to 2033 to reach USD 172.4 billion by 2033.
The book market in the Asia Pacific accounted for a share of over 35.9% of the global market revenue in 2025, on account of the presence of a large number of independent publishers and publishing companies in the region, which is anticipated to boost the market.
Some key players operating in the books market include Disney; Penguin Random House; Pearson; Hachette Book Group; HarperCollins Publishers; Scholastic Inc.; Simon & Schuster, Inc.; McGraw-Hill; Macmillan; IDW Publishing
Rising consumer spending on books, driven by increasing incomes and growing interest in reading, along with innovations in format that enhance the reading experience, are key factors fueling market growth.
Hard copy dominated with a 75.8% revenue share in 2025.
Educational books type held the highest market share of 32.4% in 2025.
Online channels accounted for the highest market share of 40.5% in 2025.
Middle East & Africa is the fastest-growing region over the forecast period.
About the Author(s)
Homecare & Decor Research Team
Consumer Goods · Homecare & DecorThis report was authored by the homecare & decor research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the homecare & decor segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


