
- Home
- »
- Pharmaceuticals
- »
-
Breast Cancer Drugs Market Size, Growth Report, 2026-2033GVR Report cover

Breast Cancer Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Therapy (Hormonal Therapy, Targeted Therapy, Chemotherapy, Immunotherapy), By Cancer Type, By Distribution Channel, By Region, And Segment Forecasts,
Market Size, 2025
$40.3BMarket Estimate, 2026
$43.2BMarket Forecast, 2033
$69.7BCAGR, 2026–2033
7.1%Breast Cancer Drugs Market Summary
The global breast cancer drugs market was valued at USD 40.3 billion in 2025 and is projected to grow from USD 43.2 billion in 2026 to USD 69.7 billion by 2033, growing at a CAGR of 7.1% from 2026 to 2033. North America breast cancer market held the largest share of over 35.0% of the global market in 2025. The market is driven by several critical factors, including the increasing global incidence of breast cancer, advancements in diagnostic technologies, and a growing shift toward personalized medicine.
Key Market Trends & Insights
- By therapy: The targeted therapy segment held the highest market share of over 55.0% in 2025.
- By cancer type: The HR+/HER2- breast cancer segment held the highest market share in 2025.
- By distribution channel: The hospital pharmacies segment held the highest market share in 2025.
Regional Highlights
- Largest regional market: North America (over 35.0% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 40.3 Billion
- Estimated market size in 2026: USD 43.2 Billion
- Projected market size by 2033: USD 69.7 Billion
- CAGR (2026-2033): 7.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the American Cancer Society’s published data in May 2025, around 316,950 women in the U.S. will be diagnosed with breast cancer, which reflects a significant demand for novel therapies. The focus on early detection, facilitated by improved screening methods and genetic testing such as BRCA mutation testing, has led to earlier diagnoses, allowing for more effective treatment strategies. Personalized therapies, particularly those targeting HER2 and hormone receptors, are becoming increasingly vital in the treatment landscape. Moreover, the growing use of precision medicine, including biomarker-driven treatments and immunotherapies, is shaping the future of breast cancer care, making it a key driver of market expansion.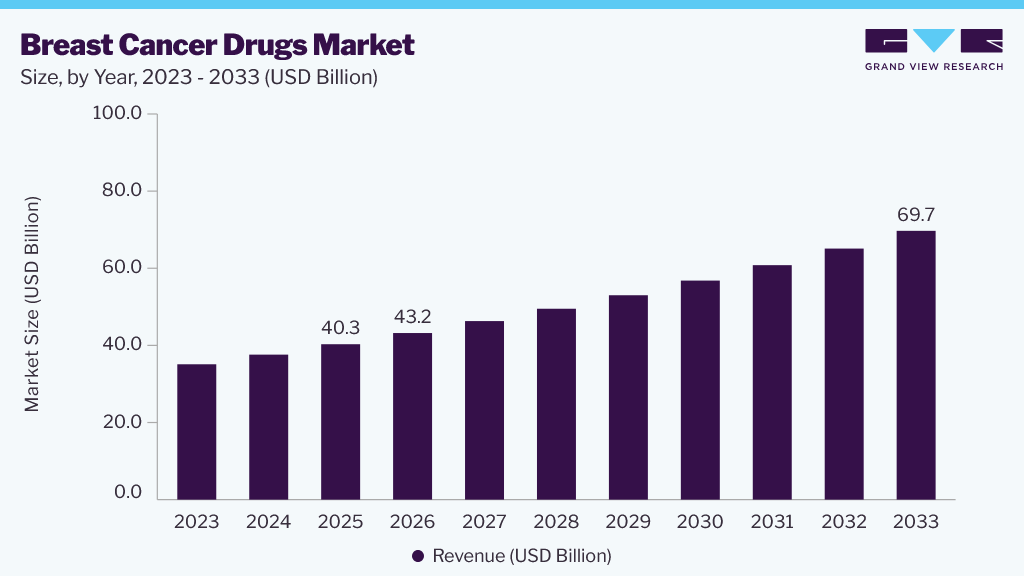 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The current market is marked by a shift away from traditional chemotherapy toward more targeted and less toxic treatments, such as monoclonal antibodies, hormone receptor-targeted therapies, and immunotherapies. Also, therapies such as Kadcyla (ado-trastuzumab emtansine) and Trodelvy (sacituzumab govitecan) have gained significant traction, particularly for treating HER2-positive and triple-negative breast cancer, respectively. These therapies have demonstrated greater efficacy and fewer side effects compared to traditional chemotherapy regimens. Keytruda (pembrolizumab), an immunotherapy currently being studied in combination with other treatments, shows promise in treating HER2-negative breast cancer. This growing reliance on advanced therapies is reshaping treatment paradigms, with a strong emphasis on combination therapies expected to enhance patient outcomes.
Business development in the breast cancer drugs market is also expanding rapidly, with numerous collaborations and pipeline advancements. By August 2025, over 300 drugs were under development, including antibody-drug conjugates (ADCs), small molecules, and novel mechanisms like proteolysis-targeting chimeras (PROTACs). According to Pfizer Inc., in April 2025, the company announced that its oncology portfolio will include data presentations on breast cancer, including a Phase 3 study (VERITAC‑2) in ER⁺/HER2⁻ metastatic breast cancer. It emphasized the development of next‑generation antibody‑drug conjugates (ADCs) in combination with immune checkpoint inhibitors.
In April 2024, the HERCESSI (trastuzumab‑strf) biosimilar to Herceptin(trastuzumab) was approved by the U.S. Food & Drug Administration (FDA) for the treatment of HER2‑overexpressing breast cancer and gastric or gastroesophageal junction adenocarcinoma. It is expected to drive down costs while improving access to critical treatments. These collaborations and new drug introductions highlight the ongoing evolution of the market, with major pharmaceutical companies seeking to enhance their portfolios and broaden treatment options, especially for complex subtypes such as HER2-low and triple-negative breast cancer.
Market Dynamics
The breast cancer drugs market is driven by the increasing global prevalence of breast cancer, supported by increasing incidence rates linked to aging populations, lifestyle changes, obesity, and improved disease awareness. Furthermore, expanding screening programs and early diagnostic initiatives are also contributing to higher detection rates, thereby increasing the patient pool eligible for treatment. This is further accelerating demand for advanced therapeutic options, such as hormonal therapies, targeted therapies, immunotherapies, and chemotherapy, while encouraging pharmaceutical companies to invest heavily in R&D for innovative, more effective treatments.
The rising global prevalence of breast cancer is a major driver of the breast cancer drugs market. Breast cancer remains one of the most commonly diagnosed cancers among women worldwide, and the number of new cases continues to increase due to factors such as population growth, aging demographics, changing lifestyles, obesity, and greater exposure to risk factors. For instance, according to the report published by Breast Cancer Org., in April 2026, in the U.S., every 1 in 8 women will develop breast cancer in their lifetime.
As the incidence of the disease rises, the demand for effective treatment options also increases, leading to higher utilization of breast cancer drugs across different stages of care. In addition, growing awareness of breast cancer and the expansion of screening programs are enabling earlier diagnosis, allowing more patients to access treatment. In February 2025, NHS England launched its first national breast cancer screening awareness campaign across England, U.K., to increase participation in routine mammography screening among eligible women. Healthcare providers are increasingly adopting targeted therapies, hormone therapies, immunotherapies, and chemotherapy drugs to improve patient outcomes and survival rates.
The high cost of treatment and targeted therapies is a major factor restraining the growth of the breast cancer drugs market. In recent years, significant advancements in breast cancer treatment have led to the development of targeted therapies, immunotherapies, and other innovative drugs that offer improved effectiveness and better patient outcomes. However, these advanced treatments are often associated with high costs, which can create barriers to their widespread adoption.
Targeted therapies are typically developed through extensive research and clinical trials, requiring substantial investment from pharmaceutical companies. As a result, these drugs are often priced significantly higher than traditional chemotherapy treatments. In addition, many targeted therapies require companion diagnostic tests to identify eligible patients and continuous monitoring throughout treatment. These additional requirements further increase the overall cost of care.
The financial burden of breast cancer treatment can be particularly challenging in developing and emerging economies, where healthcare budgets are limited, and reimbursement coverage may not be sufficient. High out-of-pocket expenses can make advanced therapies unaffordable for many patients, reducing access to effective treatment options. Even in developed countries, healthcare providers and insurance companies may face budget constraints that limit the use of high-cost therapies.
Market Concentration & Characteristics
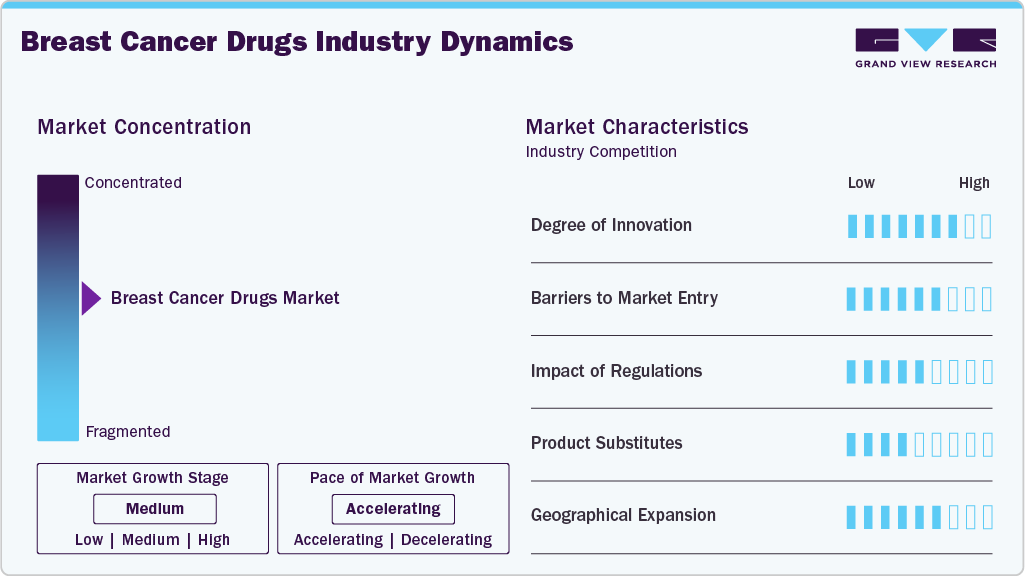
Innovation in the market is high and accelerating, driven by next‑generation modalities such as antibody‑drug conjugates (ADCs), proteolysis‑targeting chimeras (PROTACs) and biomarker‑driven small molecules. For example, in August 2024, a review noted that multiple oral selective estrogen‑receptor degraders, TROP2‑targeted ADCs and PI3K/mTOR inhibitors were in late‑stage trials in breast cancer. These innovations allow manufacturers to target previously unmet sub‑populations (e.g., HER2‑low, triple‑negative) and command premium pricing, especially when tied to companion diagnostics. The high level of R&D investment, the complexity of biologic manufacturing, and the need for robust clinical differentiation raise the innovation bar. This creates a competitive advantage for large specialty pharmaceutical firms with deep oncology portfolios and for‑purpose biotech players, reinforcing a premium structure to the market.
Entry into the breast cancer drugs segment is constrained by substantial barriers, including high R&D cost, long clinical development timelines, requirement for complex manufacturing (especially biologics/ADCs) and the need to access established distribution and reimbursement pathways. As noted in a general pharma industry review, the drug approval process can take 10‑12 years and cost billions of US dollars. For example, in January 2024, a regulatory study identified delays in approval timelines between the Food and Drug Administration and the European Medicines Agency, complicating market entry. New entrants must also overcome incumbents’ patent protections, established treatment protocols, and payer‑formulary inclusion. Consequently, this restricts significant market entry to firms with strong financing, established oncology experience, and strategic partnerships or licensing models.
 To learn more about this report, Download Free Sample Report
Regulatory oversight in the market plays a pivotal role in shaping product viability, time‑to‑market and reimbursement access. For instance, in November 2024, a regulatory decision in China placed the drug Enhertu (an ADC) on the national reimbursement list, triggering a price reduction of approximately 63 % as part of access negotiations. Regulatory frameworks require manufacturers to submit robust clinical outcomes, manage manufacturing quality standards (GMP/biologics) and adapt to region‑specific pricing and reimbursement mechanisms. A 2024 lifecycle study flagged that approval delays and divergent regional regulatory requirements form significant hurdles for breast cancer products. Overall, regulatory factors strongly influence commercial strategy, pricing design and geographic rollout sequencing.
Within the market, alternative therapies and generics/biosimilars form important substitute considerations, especially for older therapeutic classes. For example, biosimilars for the biologic Trastuzumab have become available and are increasingly used to reduce cost and expand access. While innovative agents such as ADCs offer differentiated benefits and command premium pricing, their uptake may be moderated by lower‑cost substitutes (chemotherapy, hormonal therapy generics) in cost‑sensitive markets. Thus, established branded therapies may face erosion as biosimilars and generics expand, pressuring pricing and margins for incumbent firms. For example, the availability of trastuzumab biosimilars supports substitution in HER2‑positive breast cancer and influences formulary dynamics.
Geographical expansion remains a key growth lever in the industry, with emerging markets such as Asia Pacific showing faster growth albeit with access and infrastructure constraints. Asia‑Pacific is the fastest‑growing region for breast cancer therapeutics, driven by increasing screening, rising incidence and improving infrastructure. Nonetheless, expansion into these regions is conditioned by regulatory, pricing and reimbursement challenges-as well as health‑care infrastructure limitations. For example, local manufacturing, pricing concessions, and partnering with regional distributors are often required. Strong uptake in North America remains tied to high healthcare spend and early adoption of novel therapies. In summary, geographic expansion offers a meaningful opportunity but demands region‑specific access strategies and competitive adaptation.
Therapy Insights
The targeted therapy segment accounted for the largest revenue share, over 55.0% in 2024, driven by several factors. The rise in personalized treatment options, including HER2-directed therapies and CDK4/6 inhibitors, is contributing significantly to its dominance. The growing focus on precision medicine, in which treatments are tailored to molecular profiles, supports the widespread adoption of these therapies. According to a March 2025 study in Frontiers in Oncology, 82 real-world studies found that CDK4/6 inhibitors conferred significant benefits in progression-free survival and overall survival among patients with HR-positive/HER2-negative advanced breast cancer. This highlights the growing focus on precision medicine, in which treatments are tailored to molecular profiles, and supports the widespread adoption of these therapies.
The immunotherapy segment is the fastest‑growing therapy segment in the market, driven by three key factors. Improved clinical outcomes of immune checkpoint inhibitors in subtypes such as Triple‑Negative Breast Cancer (TNBC) expand the eligible patient pool,further supported by ongoing regulatory momentum and the introduction of novel targeted oncology therapies that complement immuno-oncology treatment strategies.For instance, in May 2026, the FDA approved datopotamab deruxtecan-dlnk for unresectable or metastatic TNBC.
Cancer Type Insights
The HR+/HER2− Breast Cancer segment accounted for approximately 60.0% of revenue in 2025, as it is the most prevalent subtype and benefits from established treatment paradigms. For instance, in May 2024, an article in the Journal of the National Comprehensive Cancer Network reported that CDK4/6 inhibitors have “dramatically improved survival” in HR+/HER2− disease. Furthermore, regulatory approvals are driving growth in this segment. In December 2025, fam-trastuzumab deruxtecan-nxkir received approval from the FDA in combination with pertuzumab as a first-line treatment of metastatic HER2-positive or uresectable breast cancer.
The triple‑negative breast cancer (TNBC / HR-/HER2-) segment is the fastest‑growing in the breast cancer drugs market as it addresses an unmet clinical need with fewer established therapeutic options, leading to intensified research and innovation. Key drivers include the aggressive biology of TNBC, the expansion of immunotherapy and antibody‑drug‑conjugate regimens tailored to this subtype, and a high number of ongoing clinical trials reflecting investment in this area. For instance, according to the National Cancer Institute, more than 160 clinical trials are actively recruiting for TNBC treatments in the U.S. alone. In addition, according to Novotech, in January 2025, over 1,500 global TNBC‑focused clinical trials were initiated between 2019 and 2024.
Distribution Channel Insights
Hospital pharmacies held the largest revenue share of over 70.0% in 2025, driven by the administration of many breast cancer treatments, including injectable targeted therapies, biologics, and combination regimens, under supervision in hospital settings, which necessitates hospital pharmacy infrastructure. In addition, hospitals provide integrated oncology care and streamlined drug procurement and reimbursement pathways, thereby bolstering volume and revenue capture.
Other distribution channels are the fastest-growing for breast cancer drugs because they encompass emerging delivery models, such as online pharmacies and direct-to-patient channels, that expand access beyond traditional hospital and retail settings. Growth is driven by rising telemedicine adoption, increasing patient demand for convenience, and the wider availability of oral oncology agents suitable for non‑institutional settings.
Regional Insights
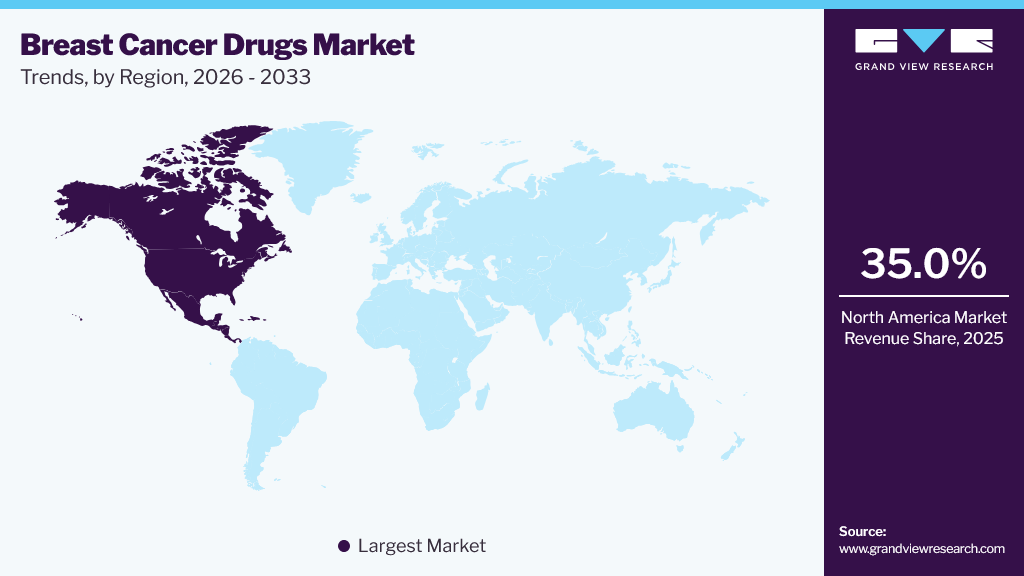
North America continues to dominate the global breast cancer drugs market with a revenue share of over 35.0% in 2025, driven by the high prevalence of breast cancer and the robust healthcare infrastructure present in both the U.S. and Canada. The region benefits from well-established reimbursement systems, with insurance providers typically covering the cost of breast cancer treatments, which facilitate widespread access to new therapies. In addition, healthcare spending is high in North America, particularly in the U.S., where there is significant demand for innovative and targeted treatments, such as HER2-targeted therapies, immunotherapies, and advanced chemotherapy alternatives.
 To learn more about this report, Download Free Sample Report
U.S. Breast Cancer Drugs Market Trends
The U.S. breast cancer drugs market is characterized by early adoption of cutting-edge therapies, particularly those driven by precision medicine. The U.S. market has a strong inclination toward biologics, including monoclonal antibodies and immunotherapies, which have revolutionized treatment paradigms, particularly for HER2-positive and triple-negative breast cancer. The U.S. is also a leader in clinical trial activity, providing the testing ground for many drugs that eventually reach global markets. In September 2024, the FDA approved Kisqali (ribociclib) in combination with an aromatase inhibitor for the adjuvant treatment of adults with hormone receptor‑positive, HER2‑negative stage II/III early breast cancer at high risk of recurrence, reinforcing the U.S.’s leadership in combination therapies for more comprehensive treatment approaches.
Europe Breast Cancer Drugs Market Trends
The Europe breast cancer drugs market is influenced by a unified regulatory environment and a mix of public and private healthcare systems. In most European countries, such as Germany and France, national health services provide a significant portion of funding for breast cancer treatments, ensuring that a large portion of the population has access to the latest therapies. In addition, Europe has a well-established network for early screening and diagnosis, which allows for the early identification of breast cancer, contributing to better patient outcomes. The European Medicines Agency (EMA) plays a central role in ensuring that novel therapies, including biologics and targeted treatments, meet rigorous safety and efficacy standards before being approved for use. For example, in April 2025, the European Commission approved Enhertu (trastuzumab deruxtecan) as monotherapy for adult patients with unresectable or metastatic hormone‑receptor‑positive, HER2‑low or HER2‑ultralow breast cancer (metastatic) who have received at least one endocrine therapy. This gives patients access to a novel antibody‑drug‑conjugate therapy after years of clinical trials.
The UK breast cancer drugs market is shaped by the National Health Service (NHS), which plays a dominant role in healthcare delivery and reimbursement. The NHS has been proactive in adopting innovative cancer therapies, especially those that have shown strong clinical efficacy in trials. However, drug pricing and cost-effectiveness assessments by bodies such as the National Institute for Health and Care Excellence (NICE) are crucial to the market. NICE reviews new therapies based on clinical effectiveness, cost-effectiveness, and long-term outcomes, often making recommendations that directly influence the availability of drugs within the NHS system.
Germany breast cancer drugs market is one of Europe’s largest markets, supported by a high standard of healthcare and significant healthcare expenditure. The country’s healthcare system combines public and private insurance, enabling broad access to new therapies, particularly innovative or breakthrough treatments. Germany has a well-developed infrastructure for breast cancer diagnosis and treatment, with advanced screening programs and specialized cancer centers that drive the demand for novel therapeutics.
The France breast cancer drugs market is largely influenced by the public healthcare system, which provides extensive coverage for cancer treatments through the Sécurité Sociale (social security system). The French healthcare system is known for its accessibility, with most patients receiving treatment for breast cancer through public hospitals, which are often equipped with the latest therapies. However, the decision to adopt new therapies depends on approval by the Haute Autorité de Santé (HAS), which assesses the clinical and economic value of new drugs.
Asia Pacific Breast Cancer Drugs Market Trends
The Asia Pacific region is emerging as a fast-growing market for breast cancer drugs, with countries such as Japan, China, and India showing rising demand for advanced cancer treatments due to an increasing incidence of breast cancer and improved healthcare infrastructure. One of the key drivers in this region is the rising adoption of targeted therapies and biologics, particularly in more developed markets such as Japan and South Korea.
Japan Breast Cancer Drugs Market
The Japan breast cancer drugs market is one of the leaders in the Asia-Pacific region for breast cancer treatment, driven by a strong healthcare system and high standards of oncology care. The country’s healthcare system, supported by universal health insurance, ensures broad access to breast cancer treatments, including innovative therapies such as targeted agents and biologics. According to Japanese business reports, Trodelvy (sacituzumab govitecan) was approved in Japan around late October 2024 for the treatment of triple‑negative breast cancer, marking an important step in expanding access to novel ADC therapies in the Japanese oncology market. This approval reflects Japan's rapid adoption of novel therapies, driven by both clinical efficacy and the country's efficient regulatory environment.
The breast cancer drugs market in China is driven by the increasing incidence of breast cancer and expanding healthcare access. The Chinese government has made significant investments in healthcare infrastructure and cancer care, which have contributed to better diagnosis and treatment. In February 2023, China’s NMPA approved Enhertu (trastuzumab deruxtecan) for adult patients with unresectable or metastatic HER2‑positive breast cancer who have received one or more prior anti‑HER2‑based regimens, a significant step in making this advanced therapy accessible to Chinese patients. This approval is a testament to China’s commitment to improving access to cutting-edge cancer treatments.
Latin America Breast Cancer Drugs Market Trends
The breast cancer drugs market in Latin America is growing steadily, driven by rising breast cancer incidences and improvements in healthcare access. The region has seen increasing demand for more advanced cancer treatments, particularly in countries such as Brazil, Mexico, and Argentina, where the healthcare infrastructure has improved significantly over the past decade. Governments are increasingly focusing on providing better access to screening and treatment programs for breast cancer, but disparities still exist in access between urban and rural areas.
Brazil market for breast cancer drugs is the largest in Latin America, driven by the country's significant population size and an increasing incidence of breast cancer. The Brazilian government has made notable strides in expanding healthcare coverage, with breast cancer treatments being widely available through the public healthcare system. However, disparities exist in access to newer, more expensive therapies, particularly in rural and underserved areas.
Middle East & Africa Breast Cancer Drugs Market Trends
The breast cancer drugs market in the Middle East and Africa is expanding due to increasing disease awareness and rising incidences of breast cancer, particularly in the Gulf Cooperation Council (GCC) countries. Countries such as Saudi Arabia, the UAE, and Qatar have significantly improved their healthcare systems, leading to better diagnosis and treatment availability for breast cancer patients. However, in sub-Saharan Africa, access to advanced cancer therapies remains a challenge due to underdeveloped healthcare infrastructure, limited access to screening, and financial barriers. Despite these challenges, there is a growing recognition of the importance of early detection and timely treatment, which is helping to drive market growth in more developed areas.
Saudi Arabia breast cancer drugs market plays a pivotal role in the Middle East's market, driven by strong government support for healthcare and cancer treatment. The country’s healthcare system has made substantial improvements, and the government has invested heavily in cancer research and treatment facilities. Saudi Arabia’s cancer treatment centers are among the best in the region, providing access to the latest breast cancer therapies, including targeted treatments and immunotherapies.
Key Breast Cancer Drugs Company Insights
Key players operating in the breast cancer drugs market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
-
In October 2025, the U.S. Food and Drug Administration (FDA) accepted the supplemental biologics license application (sBLA) for trastuzumab deruxtecan (brand name Enhertu) in combination with paclitaxel, trastuzumab, and pertuzumab for adult patients with HER2-positive stage II or III breast cancer, setting a PDUFA target action date of May 18, 2026.
-
In October 2025, the FDA granted Fast Track designation to ETX 636, a PI3Kα inhibitor and degrader, for the treatment of adult patients with PIK3CA mutant hormone receptor-positive, HER2-negative advanced breast cancer.
-
In January 2025, AstraZeneca PLC and Daiichi Sankyo Company, Limited received U.S. approval for datopotamab deruxtecan dlnk (brand name Datroway) for adults with unresectable or metastatic hormone receptor-positive, HER2-negative breast cancer who had received prior endocrine-based therapy and chemotherapy.
Key Breast Cancer Drugs Companies:
The following key companies have been profiled for this study on the breast cancer drugs market.
-
F. Hoffmann‑La Roche Ltd.
-
Pfizer Inc.
-
AstraZeneca
-
Novartis AG
-
Eli Lilly and Company
-
Merck & Co., Inc.
-
Sanofi
-
Bristol‑Myers Squibb Company
-
Eisai Co., Ltd.
-
AbbVie Inc.
-
MacroGenics, Inc.
-
Biocon
-
Takeda Pharmaceutical Company Limited
-
Kyowa Kirin Co., Ltd.
-
Johnson & Johnson
Breast Cancer Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 40.3 billion
Estimated market size in 2026
USD 43.2 billion
Projected market size by 2033
USD 69.7 billion
Growth rate
CAGR of 7.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Therapy, cancer type, distribution channel, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
F. Hoffmann‑La Roche Ltd.; Pfizer Inc.; AstraZeneca; Novartis AG; Eli Lilly and Company; Merck & Co., Inc.; Sanofi; Bristol‑Myers Squibb Company; Eisai Co., Ltd.; AbbVie Inc.; MacroGenics, Inc.; Biocon Takeda Pharmaceutical Company Limited; Kyowa Kirin Co., Ltd.; Johnson & Johnson
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Breast Cancer Drugs Market Report Segmentation
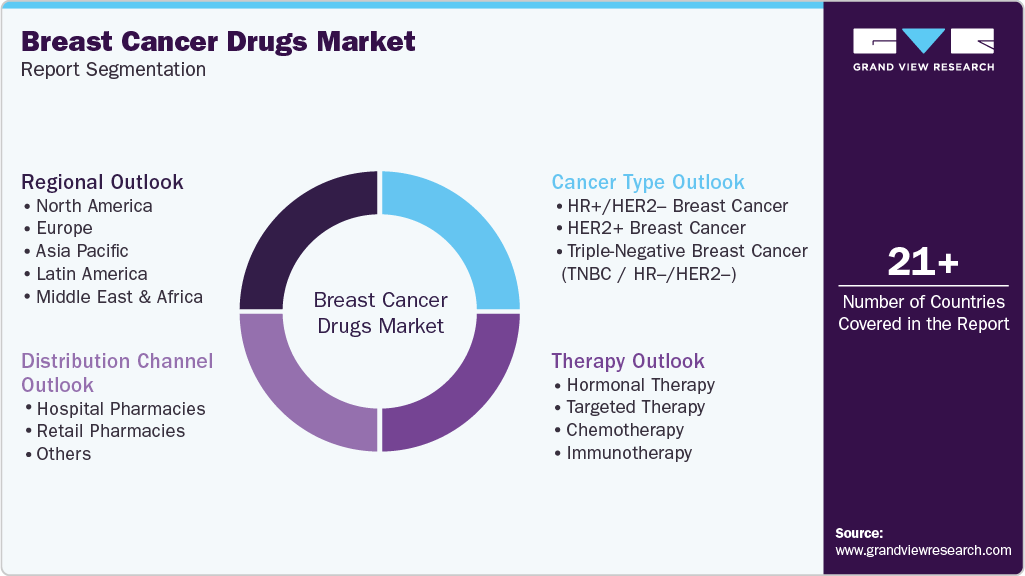
This report forecasts revenue growth at the regional and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global breast cancer drugs market report based on therapy, cancer type, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Therapy Outlook (Revenue, USD Million, 2021 - 2033)
-
Hormonal Therapy
-
Selective Estrogen Receptor Modulators (SERMs)
-
Aromatase Inhibitors
-
Selective Estrogen Receptor Degraders/Down-regulators (SERDs)
-
-
Targeted Therapy
-
HER2-Targeted Therapies
-
CDK4/6 Inhibitors
-
PARP Inhibitors
-
Antibody-Drug Conjugates (ADCs)
-
Other Targeted Therapies
-
-
Chemotherapy
-
Taxanes
-
Anthracyclines
-
Others
-
-
Immunotherapy
-
-
Cancer Type Outlook (Revenue, USD Million, 2021 - 2033)
-
HR+/HER2- Breast Cancer
-
HER2+ Breast Cancer
-
Triple-Negative Breast Cancer (TNBC / HR-/HER2-)
-
-
Distribution ChannelOutlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global breast cancer drugs market size was valued at USD 40.3 billion in 2025 and is estimated at USD 43.2 billion for 2026.
The global breast cancer drugs market is expected to grow at a CAGR of 7.1% from 2026 to 2033, reaching USD 69.7 billion by 2033.
North America dominated with a 35.0% revenue share in 2025.
Hospital pharmacies dominated the breast cancer drugs market with a share of 70.0% in 2025, while other distribution channels is the fastest-growing segment.
Key players include F. Hoffmann‑La Roche Ltd.; Pfizer Inc.; AstraZeneca; Novartis AG; Eli Lilly and Company; Merck & Co., Inc.; Sanofi; Bristol‑Myers Squibb Company; Eisai Co., Ltd.; AbbVie Inc.; MacroGenics, Inc.; Biocon Takeda Pharmaceutical Company Limited; Kyowa Kirin Co., Ltd.; Johnson & Johnson
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


