
- Home
- »
- Plastics, Polymers & Resins
- »
-
Breathable Films Market Size And Share Report, 2026-2033GVR Report cover

Breathable Films Market (2026 - 2033)
Size, Share and Trends Analysis Report By Raw Material (Polyester, Polyethylene, Polypropylene), By Film Type (Microporous, Microvoided, Non-porous), By End Use (Personal Care & Hygiene), By Region And Segment Forecasts
Market Size, 2025
$21.2BMarket Estimate, 2026
$22.3BMarket Forecast, 2033
$32.6BCAGR, 2026–2033
5.6%Breathable Films Market Summary
The global breathable films market size was valued at USD 21.2 billion in 2025 and is projected to grow from USD 22.3 billion in 2026 to USD 32.6 billion by 2033, at a CAGR of 5.6% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 30.5% in 2025. The market growth is being fueled by the increasing use of breathable films across Personal Hygiene & Consumer Goods, Healthcare & Medical Disposables, Food & Agricultural Packaging, Industrial Safety & Apparel industries.
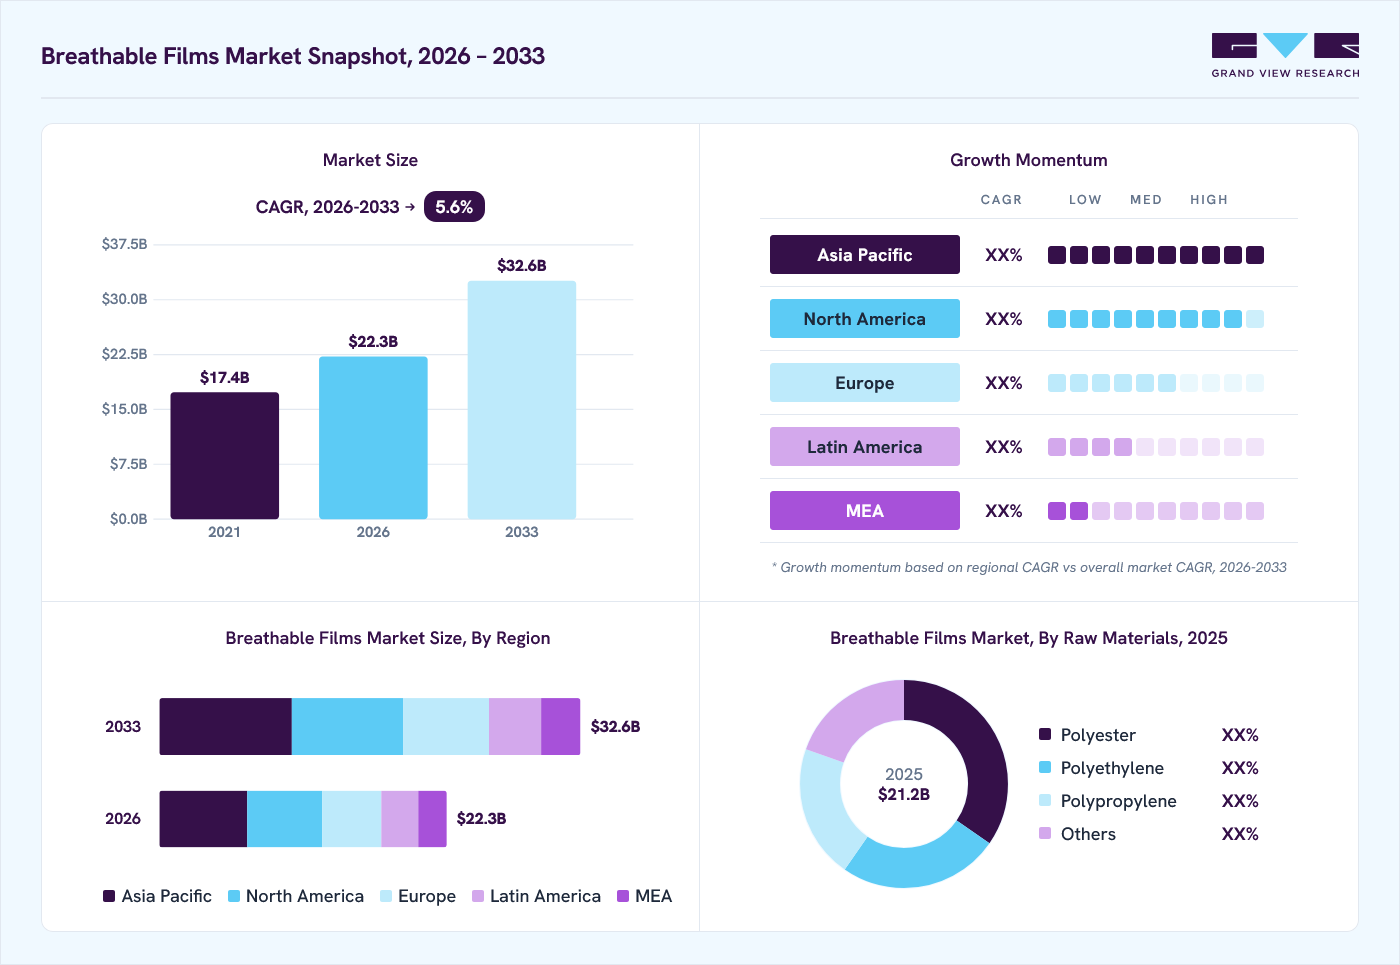 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By film type: Non-porous segment held the largest market share of 63.7% in 2025.
- By end use: Packaging segment held the largest market share of 40.6% in 2025.
- By raw materials: Polyester segment held the largest market share of 34.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (30.5% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 21.2 Billion
- Estimated market size in 2026: USD 22.3 Billion
- Projected market size by 2033: USD 32.6 Billion
- CAGR (2026-2033): 5.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Breathable films are mainly used in various applications such as feminine hygiene, adult incontinence products, surgical drapes, and diapers. It is used in various end-use industries such as food packaging, medical, construction, sports apparel, and others, owing to its properties, including UV stability, dispersion, extended shelf life, processability, and breathability levels. Moreover, the transition to sustainable packaging options is promoting the adoption of breathable films in both food and industrial packaging, especially for products sensitive to moisture. Innovations in film production technologies, including co-extrusion and microporous film technology, are also driving product development, improving breathability while maintaining barrier performance.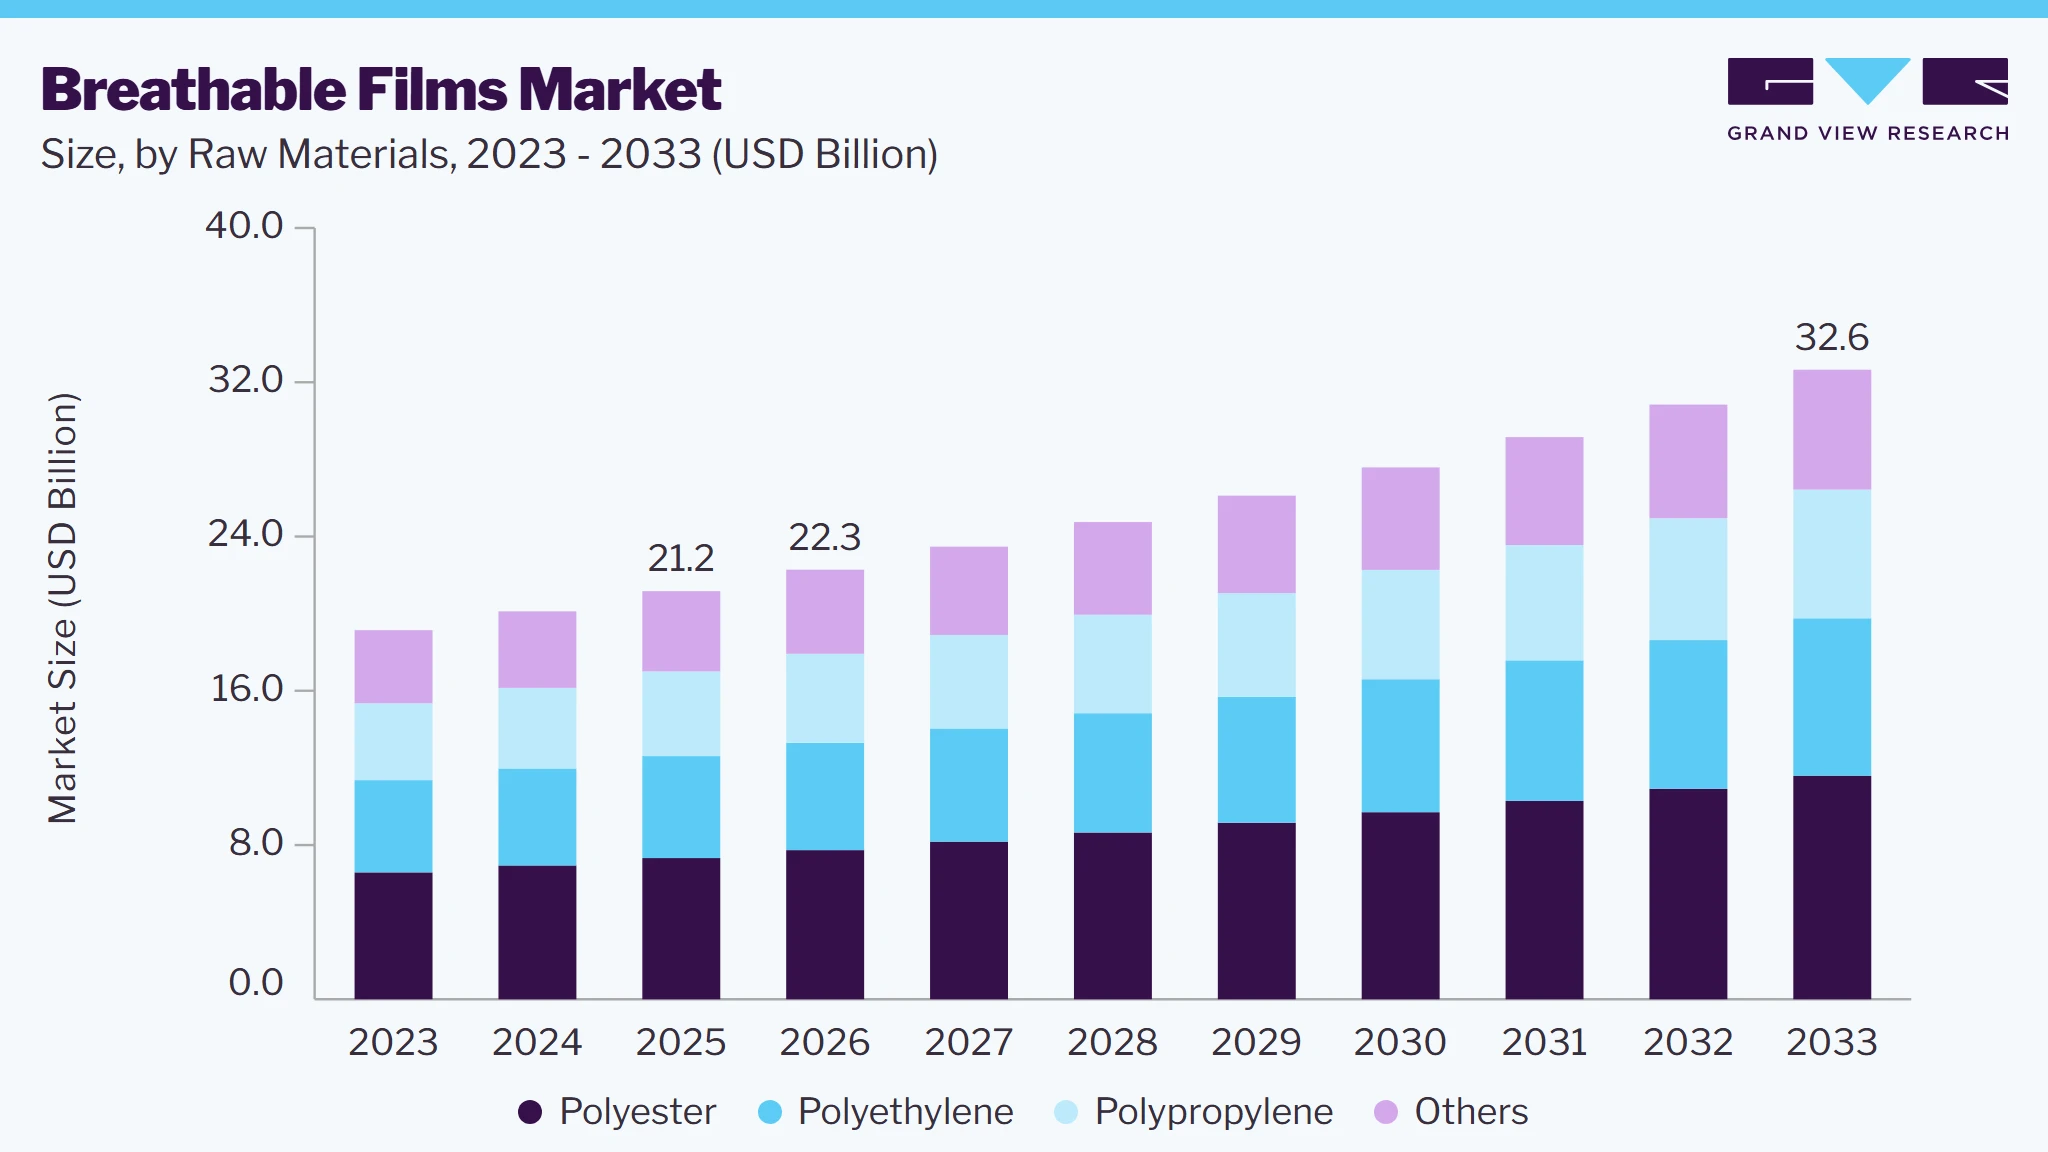 To learn more about this report, Download Free Sample Report
Breathable films are primarily produced using materials like polyethylene (PE), polypropylene (PP), and thermoplastic polyurethane (TPU), with PE holding a significant share due to its affordability and excellent moisture vapor transmission characteristics. Microporosity in the film structure is often achieved by adding calcium carbonate (CaCO₃) as a filler. Microporous PE films are prevalent in hygiene products because of their soft feel and high flexibility. Films made from TPU are increasingly popular in the medical and protective clothing industries due to their outstanding elasticity, water resistance, and breathability.
The availability, cost, and recyclability of these polymers and fillers play crucial roles in market trends. As sustainability becomes increasingly important, manufacturers are more frequently investigating bio-based and recyclable polyolefins to meet changing regulatory and consumer expectations.
Moreover, the increasing focus on comfort, infection prevention, and skin health in medical settings is boosting demand. Moreover, the trend towards breathable packaging materials that maintain product freshness while reducing condensation is promoting use in food and industrial sectors. Regulatory guidelines that advocate for product safety and skin compatibility are also driving innovation in film formulations worldwide.
Market Dynamics
Breathable films are evolving from conventional moisture management layers into advanced performance materials that support energy-efficient construction and durable building envelopes. Rising demand from residential, commercial, and industrial construction is increasing adoption due to their ability to allow water vapor transmission while preventing liquid water ingress. Applications in roofing membranes, wall wraps, protective apparel, and packaging are expanding as regulatory focus on indoor air quality and sustainable construction intensifies. Manufacturers are introducing multilayer structures, microporous technologies, and recyclable film solutions to enhance breathability, strength, and environmental performance. This shift is positioning breathable films as a critical material category for modern building efficiency, product protection, and long-term sustainability objectives.
The breathable films market is witnessing steady growth due to rising demand for advanced barrier materials in healthcare and personal protective applications. Breathable films provide an effective combination of liquid protection and moisture vapor transmission, improving wearer comfort while maintaining infection control standards. Their widespread use in surgical gowns, drapes, protective apparel, and disposable medical products is supporting market expansion. Increasing healthcare expenditure, growing awareness of hospital-acquired infections, and higher consumption of single-use protective products are further strengthening demand across both developed and emerging healthcare markets.
Healthcare remains a key end-use sector for breathable films, driven by the need for high-performance protective materials in medical and industrial settings. The growing prevalence of lifestyle-related diseases is increasing patient volumes and the use of medical consumables, sustaining demand for breathable barrier products. In addition, expanding healthcare infrastructure, rising surgical procedure volumes, and stricter hygiene regulations are accelerating adoption. Manufacturers are also focusing on lightweight, skin-friendly, and sustainable film technologies to meet evolving performance requirements and regulatory expectations.
High production costs remain a key restraint on the breathable films market. Manufacturing breathable films requires specialized machine-direction orientation stretching lines, precision extrusion systems, and strict process control to create the microporous structure needed for moisture vapor transmission. In addition, the use of high-quality precipitated calcium carbonate master batches and performance polymers increases raw material costs. These factors make breathable films considerably more expensive than conventional plastic films, limiting their penetration in price-sensitive applications. Cost pressures are particularly evident in emerging markets, where buyers often prioritize affordability over advanced functionality, despite growing demand from the hygiene, medical, and healthcare sectors driven by the rising prevalence of lifestyle-related diseases.
Opportunity - Growing Demand from the Construction Industry
The growing focus on energy-efficient and moisture-managed building envelopes is creating strong growth opportunities for breathable films in the construction sector. Increasing investments in residential housing, commercial buildings, and renovation projects are driving demand for advanced roofing membranes and house wraps. Breathable films enable water vapor to escape while preventing liquid water intrusion, helping improve structural durability and indoor air quality. Their lightweight design, ease of installation, and compatibility with modern insulation systems support wider adoption. Demand is further reinforced by stricter building performance standards and the need for long-term protection against moisture-related damage.
Market Concentration & Characteristics
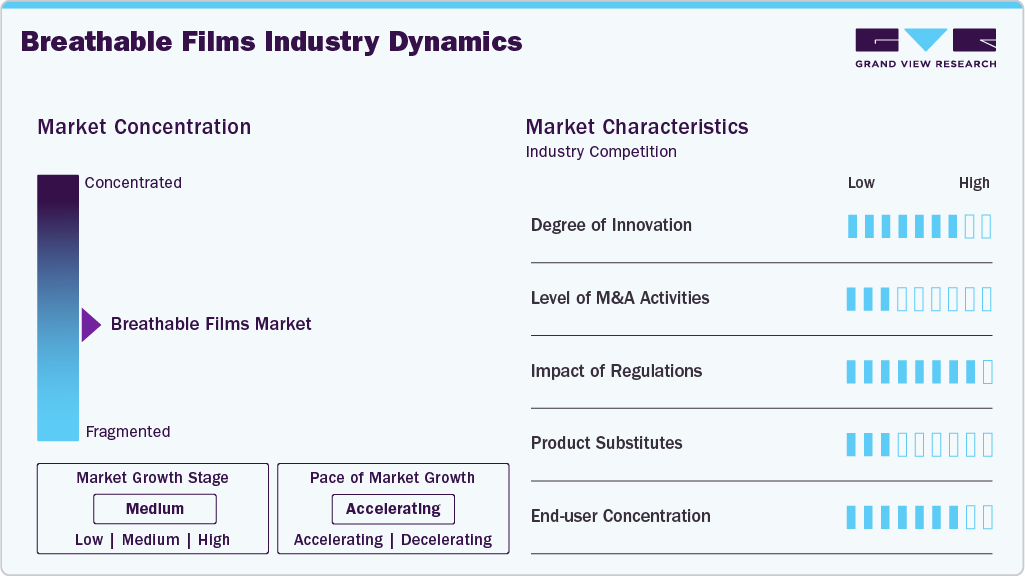
The market growth stage of the breathable films market is high, and the pace is accelerating. The market exhibits slight market fragmentation, with key players dominating the industry landscape. Major companies like Schweitzer-Mauduit International, Inc., Arkema, Berry Global, Inc., Fatra, a.s., Kimberly-Clark, Nitto Denko Corporation, Rahil Foam Pvt. Ltd., RKW North America, Inc., SILON s.r.o., and others play a significant role in shaping the market dynamics. These leading players often drive innovation within the market, introducing new products, technologies, and end uses to meet evolving industry demands.
The market for breathable films is projected to demonstrate a moderate-to-high level of consolidation, with significant strategic mergers and acquisitions (M&A) being crucial for enhancing geographic reach, diversifying product lines, and incorporating advanced film technologies. Major players are targeting niche manufacturers to bolster their presence in rapidly growing sectors such as medical and hygiene applications.
 To learn more about this report, Download Free Sample Report
Regulatory policies, particularly in North America and Europe, are majorly influencing the market, with stringent compliance requirements regarding skin sensitivity, recyclability, and chemical safety (such as REACH and FDA guidelines) fostering material innovation and sustainable practices. These regulations are anticipated to further spur the advancement of eco-friendly and biodegradable breathable films.
However, non-breathable films and woven/nonwoven fabrics may offer limited competition in applications focused on cost or lower performance; however, breathable films maintain a leading position where comfort, moisture control, and skin safety are paramount. The market shows a moderate level of concentration among end-users, especially in the hygiene and medical sectors, where a handful of major multinational companies and OEMs hold a significant portion of the demand. These buyers have a strong impact on supplier specifications, pricing, and sustainability criteria. Therefore, it is essential for suppliers to align with shifting end-user preferences and regulatory requirements to stay competitive in the long run.
Analyst Perspective
The breathable films market is experiencing consistent demand growth, driven by heightened usage in hygiene, medical, and protective packaging applications, where effective moisture vapor transmission and liquid barrier properties are essential. The expansion of the market is bolstered by the rising use of baby diapers, feminine hygiene items, adult incontinence supplies, and medical protective gear, especially in emerging markets that are enhancing healthcare access and undergoing demographic changes. Innovations in microporous and monolithic film designs are improving product performance and broadening the range of applications. Nonetheless, growth is still affected by fluctuations in raw material prices, which are primarily tied to polyethylene and polypropylene feedstocks, as well as mounting pressure to enhance sustainability and recyclability in disposable product categories.
Raw Materials Insights
Polyester dominated the overall market with a revenue share 34.6% of the total demand in 2025. Polyester exhibits moisture resistance, durability, and strength, making it suitable for use in the manufacturing of diapers, sanitary napkins, masks, and others.
Polyethylene (PE) is another segment that is expected to grow at a steady pace over the forecast period. Polyethylene films are mainly used in building and construction, medical, and sports apparel. Furthermore, advancements in the research and development (R&D) sector and manufacturing technology across the major regions of construction sites are expected to fuel the polyethylene (PE) demand in the breathable films market.
Another raw material majorly used is polypropylene (PP), which is mostly known for its properties including heat & fatigue resistance, rigidity, and low density, making it suitable for applications related to medical, industrial, and construction.
Film Type Insights
Based on film type, the non-porous segment led the market with the largest revenue share of 63.7% in 2025. Such significant consumption can be attributed to usage in products such as diapers, napkins, sanitary products, and clothing apparel. The properties of non-porous films, such as high permeability, strength, vapor transmission, and bacteria & virus resistance, make it widely preferable over microporous and micro-voided films.
Microporous film is predicted to witness a steady growth rate over the forecast period. Due to their versatile properties, such as low thermal connectivity and interconnected pores, there is an increasing demand for microporous film materials across industries such as consumer goods and medical. These materials are suitable for the manufacturing of sports apparel, gym wear, and hygiene products.
End Use Insights
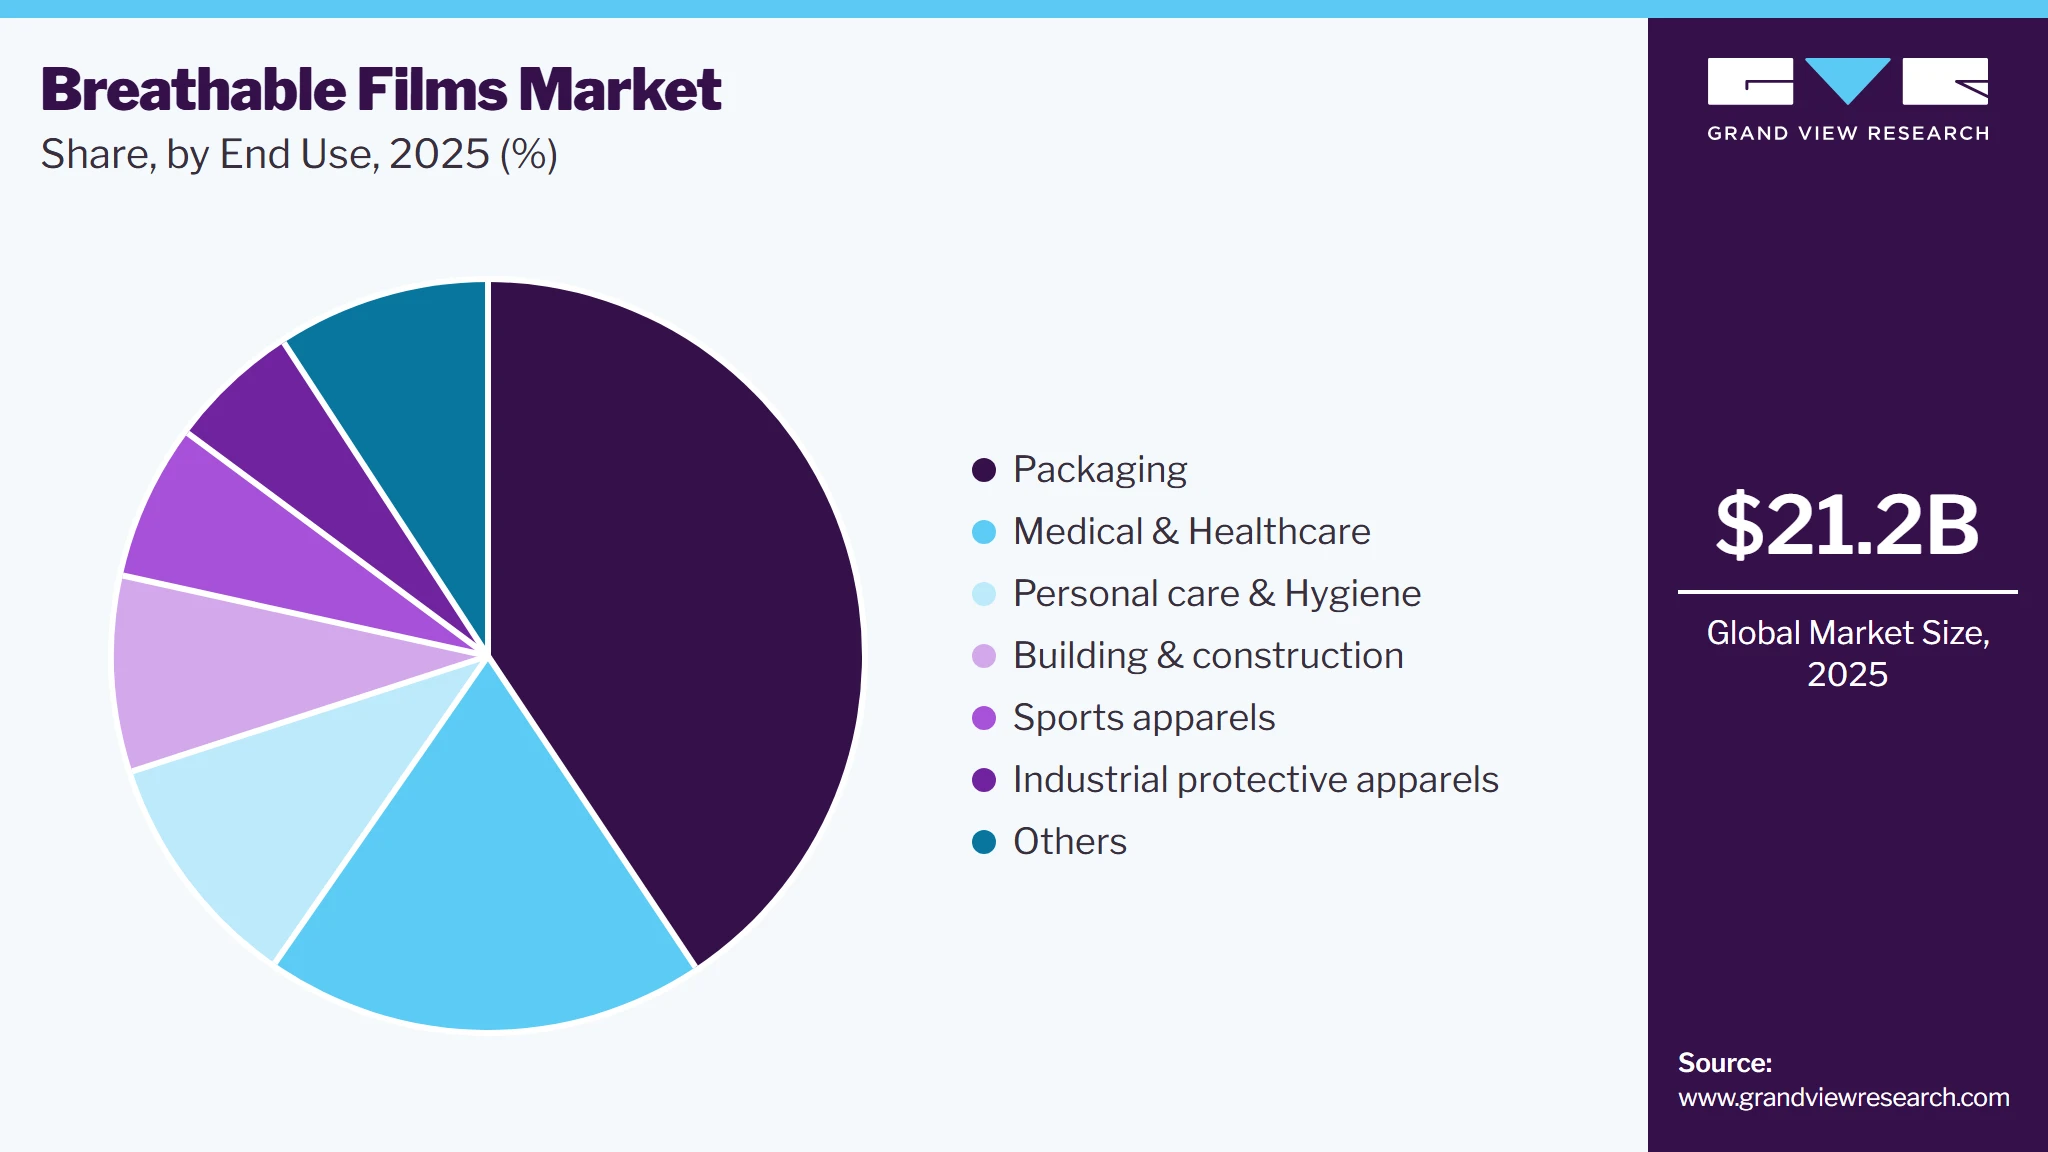
Based on end use, the packaging segment led the market with the largest revenue share of 40.6% in 2025. Breathable films find usage in food packaging, medical instruments, and consumer goods, among others. Breathable films are widely used in the packaging of beverage bottles, apparel, food preparations, electronic components, and other areas where moisture control is a requisite.
 To learn more about this report, Download Free Sample Report
Another end-use segment is the medical and healthcare industry, which is expected to grow at a steady pace over the forecast period. The market for breathable films in the medical and healthcare sector is anticipated to experience steady growth, propelled by a rising demand for innovative wound care, infection control, and solutions aimed at enhancing patient comfort. Breathable films are commonly utilized in surgical gowns, drapes, and wound dressings due to their capability to provide a barrier against liquids and pathogens while permitting moisture vapor transmission. An increase in surgical procedures, particularly among aging populations and those managing chronic diseases, is driving the need for high-quality medical films.
Furthermore, the heightened focus on preventing hospital-acquired infections (HAIs) is prompting healthcare providers to implement protective apparel and drapes that feature superior barrier properties. Advances in technology related to breathable film lamination and microporous film designs are enabling manufacturers to produce lightweight, skin-friendly, and hypoallergenic products that align with patient-centered care standards. In addition, rigorous healthcare regulations and product quality certifications are promoting the adoption of certified breathable films that comply with both safety and performance criteria.
Regional Insights
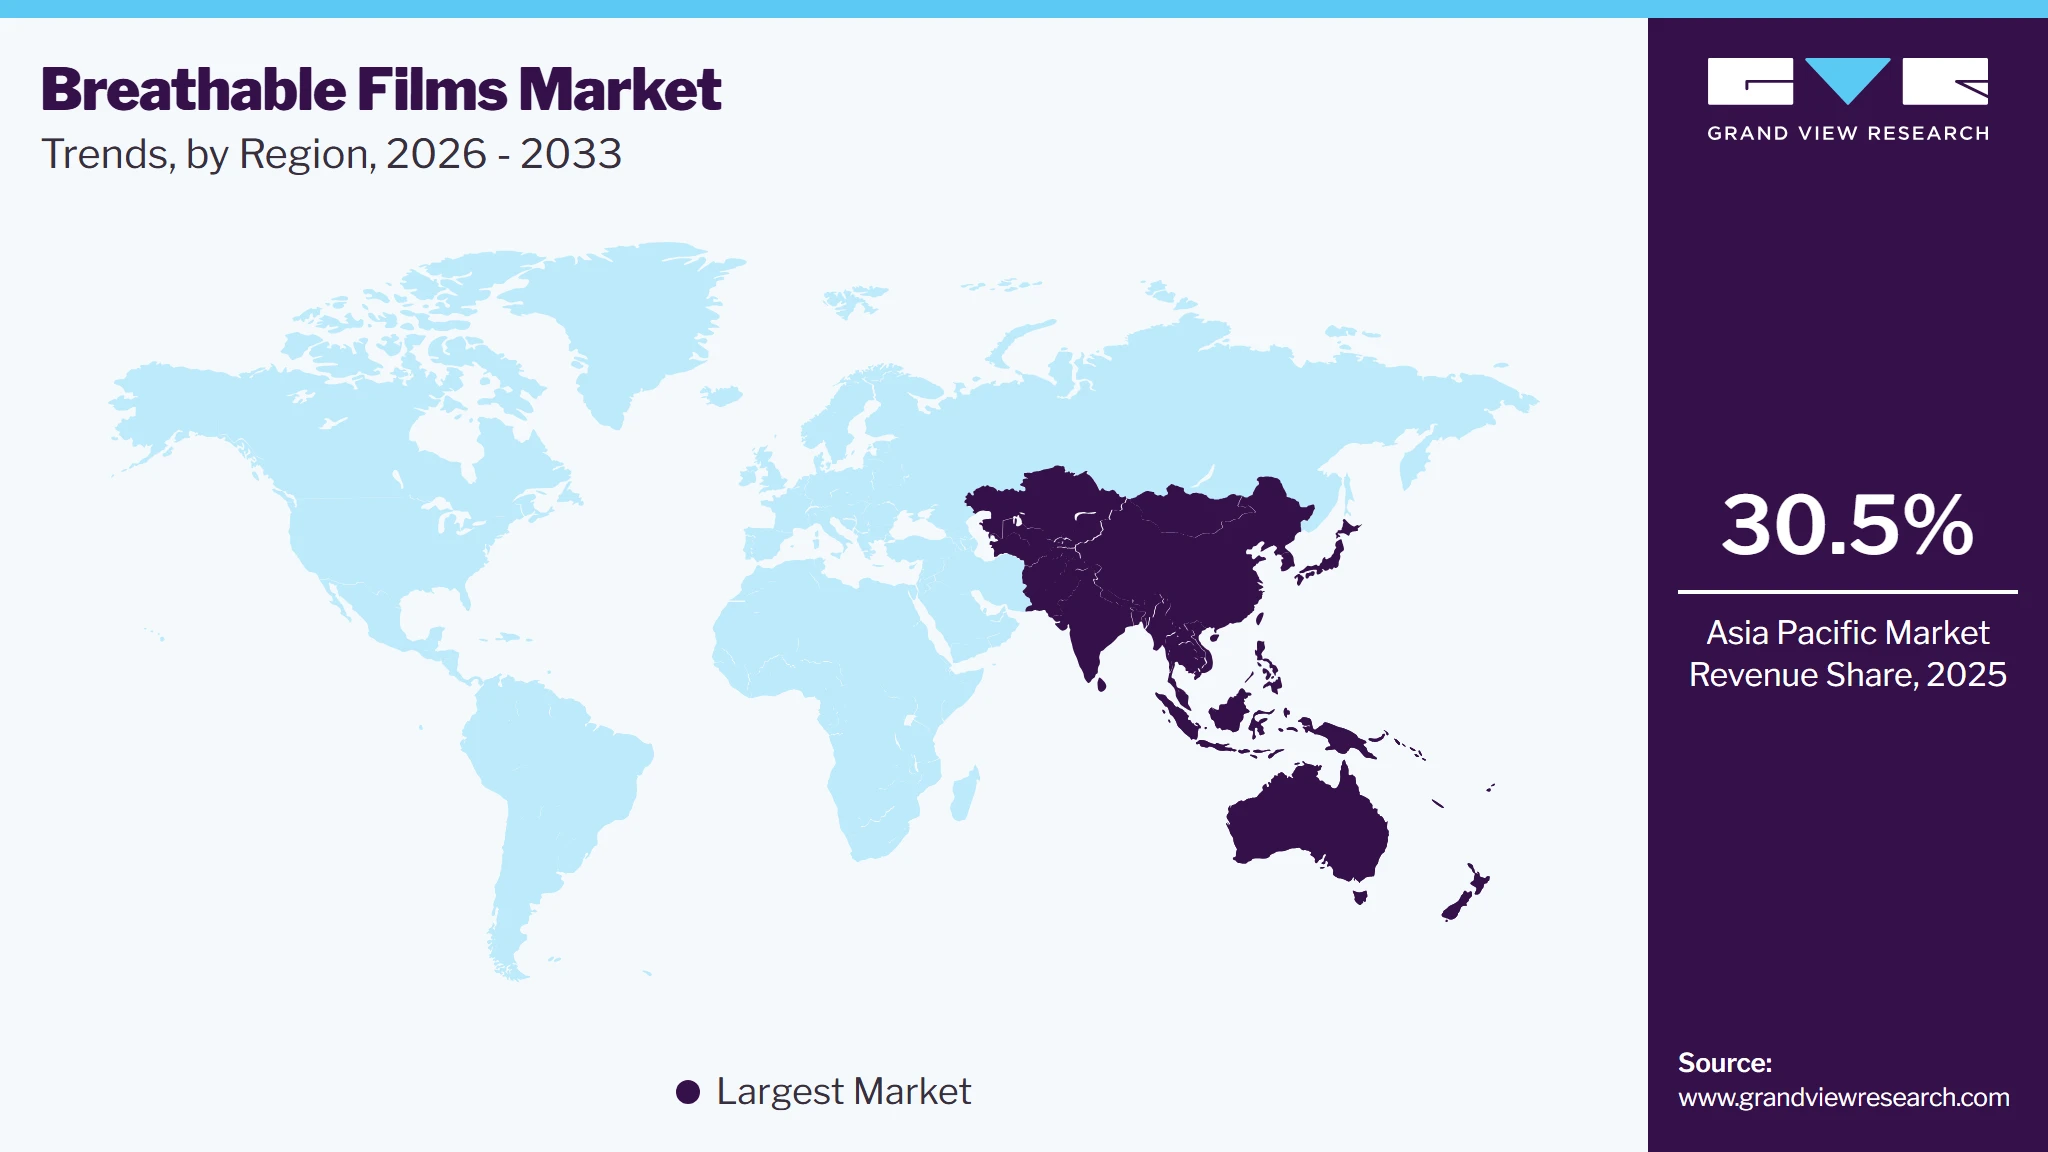
Asia Pacific is characterized by a rapidly evolving landscape for heavy manufacturing, food & beverages, clothing & apparel, and healthcare consumables. The region accounted for 30.5% of the global revenue share in 2025 and shall grow at a CAGR of 6.0% over the forecast period. Additionally, strengthening of supply chain logistics for various commodities in Southeast Asia shall provide impetus for the growth in demand for breathable films in packaging applications.
 To learn more about this report, Download Free Sample Report
China Breathable Films Market Trends
The breathable films market in China accounted for the largest market revenue share in the Asia Pacific in 2025. China's market for breathable films is expected to experience substantial growth, driven by rapid urban development, rising disposable income, and increased awareness of health and hygiene. The escalating consumption of disposable diapers for babies, feminine hygiene products, and adult incontinence supplies in both urban and rural areas is propelling demand. Moreover, improvements in China's medical infrastructure and the surge in surgical procedures are enhancing the need for breathable films in applications like wound care, gowns, and drapes.
North America Breathable Films Market Trends
The North American market for breathable films is expected to grow steadily, driven by strong demand in the hygiene, medical, and industrial sectors. This region demonstrates high per capita consumption of disposable hygiene products, such as baby diapers, feminine hygiene items, and adult incontinence solutions, which is bolstered by an aging population and increased consumer awareness of comfort and skin health. In the healthcare sector, the growing number of surgical procedures, stringent infection control regulations, and the demand for breathable barrier materials in gowns, drapes, and wound care products are propelling market expansion. Furthermore, compliance with FDA and EPA regulations ensures consistent quality and safety standards, encouraging the use of innovative breathable films.
The U.S. breathable films market dominated the North American region with over 62.0% revenue share in 2025. The market in the U.S. is anticipated to expand due to robust demand from the hygiene and medical industries, propelled by elevated healthcare expenditure, an older demographic, and a consumer inclination towards premium, skin-friendly options. The stringent regulatory landscape in the country, which includes FDA regulations for medical films and consumer safety, fosters the use of high-performance, breathable materials. Moreover, a growing emphasis on sustainability and domestic production is stimulating advancements in recyclable and bio-based film alternatives, which supports ongoing market development.
Europe Breathable Films Market Trends
The market for breathable films in Europe is projected to grow consistently, backed by robust regulatory measures that encourage safety, sustainability, and product effectiveness, especially in hygiene and healthcare sectors. The increasing need for environmentally friendly and skin-sensitive materials in baby diapers, adult incontinence items, and medical textiles is a major factor, influenced by consumer awareness and stringent adherence to REACH and CE certification standard.
Key Breathable Films Company Insights
The key players operating in the breathable films market include Schweitzer-Mauduit International, Inc., Arkema, Berry Global, Inc., Fatra, a.s., Kimberly-Clark, Nitto Denko Corporation, Rahil Foam Pvt. Ltd., RKW North America, Inc., SILON s.r.o, SKYMARK, Daika Kogyo, and others, owing to the presence of top regional players.
Governmental support in various countries focused on environmental concerns, as well as evolving consumer-enterprise transactions in the textiles, automotive, and packaging industries, has forced industry players to focus on consumer-specific positioning strategies for higher penetration in the local markets.
Key Breathable Films Companies:
The following key companies have been profiled for this study on the breathable films market.
- Schweitzer-Mauduit International, Inc.
- Arkema
- Berry Global, Inc
- Fatra, a.s.
- Kimberley - Clark
- Nitto Denko Corporation
- Rahil Foam Pvt. Ltd.
- RKW North America, Inc.
- SILON s.r.o
- SKYMARK
- Daika Kogyo
- American Polyfilm
- Innovia Films
- Mitsui Chemicals, Inc.
- Omya AG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Schweitzer-Mauduit International, Inc., Arkema, Berry Global, Inc., Fatra, a.s., Kimberly-Clark, Nitto Denko Corporation, RKW North America, Inc., SILON s.r.o., SKYMARK, Daika Kogyo, Innovia Films, Mitsui Chemicals, Inc., Omya AG)
- Diversified production of breathable films, nonwoven laminates, multilayer barrier films, and polymer-based functional coatings. Strong focus on extrusion, coating, and advanced film modification technologies.
- Continuous investment in sustainable materials, recyclable polymers, and high-performance membrane systems for construction, hygiene, medical, and packaging applications.
- Strategic collaborations with converters, OEMs, and infrastructure developers to expand application reach.
- Strong global manufacturing footprint with vertically integrated polymer and film capabilities. Advanced R&D in polymer chemistry, nanofillers, and breathable membrane engineering.
- High exposure to high-volume end-use sectors such as hygiene, construction membranes, and industrial protective films. Strong brand and technical service networks enabling long-term customer lock-in and specification-based demand.
- Exposure to cyclic demand in construction and consumer packaging markets.
- High sensitivity to raw material and energy price volatility affecting margins. Increasing regulatory pressure on plastic-based films and sustainability compliance.
- Intense competition from regional and low-cost manufacturers leading to pricing pressure and margin dilution.
Emerging Players (Rahil Foam Pvt. Ltd., American Polyfilm)
- Focus on niche and mid-volume production of breathable films, polymer films, and foam-based laminates. Emphasis on cost-efficient extrusion processes and flexible manufacturing setups.
- Gradual expansion into construction membranes, hygiene backing films, and protective packaging applications. Adoption of incremental upgrades in multilayer film technology and surface modification techniques. Selective partnerships with regional distributors and converters to improve market penetration and supply responsiveness.
- Cost-competitive manufacturing structure with flexible production lines enabling customization and short production runs. Strong regional supply capabilities supporting faster delivery cycles in domestic and nearby export markets.
- Ability to serve price-sensitive segments in construction underlayments, insulation wraps, and general-purpose breathable film applications. Growing agility in adapting product specifications based on customer requirements.
- Limited global scale and weaker brand recognition compared to established multinational players.
- Lower investment capacity in advanced R&D for high-performance multilayer and nanostructured films.
- Restricted product portfolio diversification and dependence on select regional markets. Higher vulnerability to raw material price fluctuations and competition from large integrated manufacturers with stronger pricing control.
Breathable Films Market Report Scope
Report Attribute
Details
Market size in 2025
USD 21.2 billion
Estimated market size in 2026
USD 22.3 billion
Projected market size by 2040
USD 32.6 billion
Growth rate
CAGR of 5.6% from 2026 to 2040
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2040
Quantitative units
Revenue in USD billion/million, Volume in kilotons/tons, and CAGR from 2026 to 2040
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Raw materials, film type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany, UK, France, Italy, China, India, Japan, Malaysia, Indonesia, Thailand; Brazil; Argentina; GCC countries; South Africa
Key companies profiled
Schweitzer-Mauduit International, Inc.; Arkema; Berry Global, Inc; Fatra, a.s.; Kimberley-Clark; Nitto Denko Corporation; Rahil Foam Pvt. Ltd.; RKW North America, Inc.; SILON s.r.o; SKYMARK; Daika Kogyo; American Polyfilm; Innovia Films; Mitsui Chemicals, Inc.; Omya AG
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Breathable Films Market Report Segmentation
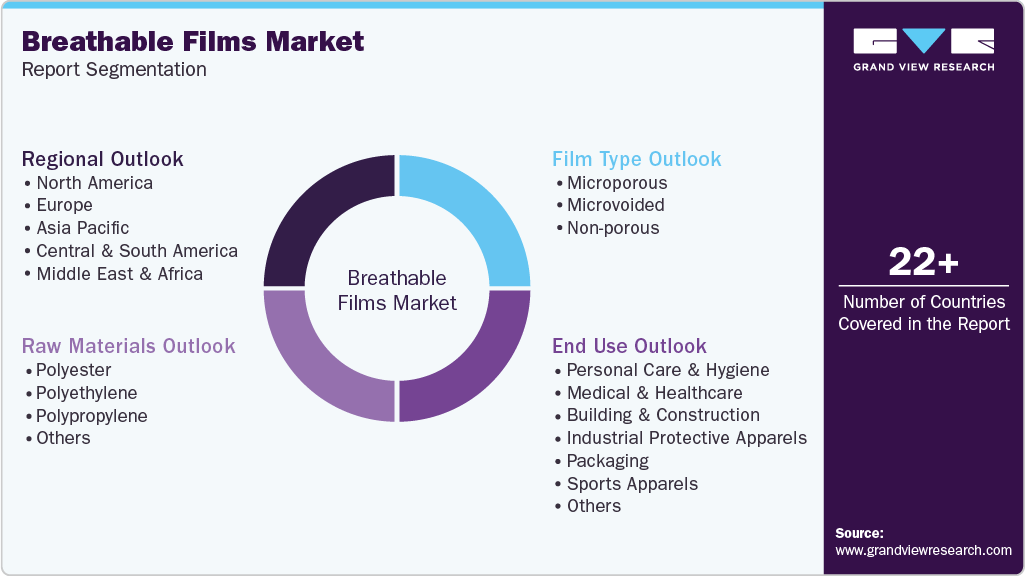
This report forecasts revenue and volume growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global breathable films market report based on the raw materials, film type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Raw Materials Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Polyester
-
Polyethylene
-
Polypropylene
-
Others
-
-
Film Type Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Microporous
-
Microvoided
-
Non-porous
-
-
End Use Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Personal Care & Hygiene
-
Medical & Healthcare
-
Building & Construction
-
Industrial Protective Apparels
-
Packaging
-
Sports Apparels
-
Others
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Malaysia
-
Indonesia
-
Thailand
-
-
Central and South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
GCC Countries
-
South Africa
-
-
Research Methodology
The breathable films market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each breathable films segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Raw Material
Revenue Capture Definition
Polyester
Revenue is captured through the sale of polyester-based breathable films used in high-performance construction, industrial, and protective applications. Demand is supported by strong tensile strength, dimensional stability, and good resistance to heat and mechanical stress. These films are preferred in roofing membranes, house wraps, building envelopes, and technical laminates where durability and long service life are important. Growth is also driven by their compatibility with multilayer structures and their ability to deliver consistent moisture management in demanding environments.
Polyethylene
Revenue is captured through the sale of polyethylene-based breathable films used in cost-sensitive and high-volume applications. Demand is driven by low material cost, good flexibility, lightweight properties, and ease of processing. These films are widely used in house wraps, moisture barriers, packaging-related protective layers, and general building protection systems. Their adoption is supported by strong demand for economical moisture control solutions in residential construction and other large-scale applications where performance and affordability must be balanced.
Polypropylene
Revenue is captured through the sale of polypropylene-based breathable films used in applications that require a balance of strength, chemical resistance, and lightweight performance. These materials are increasingly used in construction membranes, protective coverings, hygiene-related technical films, and industrial packaging applications. Demand is supported by their good moisture vapor transmission performance, processability, and competitive cost structure. Polypropylene films also benefit from wider adoption in applications where recyclability, durability, and lower material weight are important buying criteria.
Others
Revenue is captured through the sale of other specialty raw materials used in breathable films, including engineered blends and advanced polymer systems designed for niche performance needs. This category includes materials selected for enhanced breathability, barrier control, thermal stability, and application-specific functionality. Demand is concentrated in specialized end uses where standard polymers do not fully meet performance requirements. Growth is supported by custom formulations, product differentiation, and the need for films that address higher technical specifications in advanced construction and industrial applications.
Segment - Film type
Revenue capture definition
Microporous
Revenue is captured through the sale of microporous breathable films used in hygiene products, medical protective apparel, building materials, and packaging applications. Demand is driven by the film’s ability to allow water vapor transmission while preventing liquid penetration, supporting moisture management, comfort, and protection. Growth is further supported by increasing adoption in disposable hygiene products, healthcare applications, and energy-efficient construction materials requiring effective breathability and barrier performance.
Microvoided
Revenue is captured through the supply of microvoided breathable films manufactured using mineral-filled polymer structures that create interconnected pathways for moisture vapor transmission. These films are widely used in diapers, feminine hygiene products, medical disposables, and protective clothing. Sales are supported by cost-effective production, high breathability, lightweight properties, and growing demand for enhanced comfort and performance in personal care and healthcare applications.
Non-porous
Revenue is captured through the sale of non-porous breathable films that transport moisture vapor through molecular diffusion without the presence of physical pores. These films are utilized in premium medical textiles, protective garments, outdoor apparel, and specialized packaging applications where liquid barrier integrity is critical. Demand is driven by superior waterproof performance, contamination resistance, durability, and the increasing need for high-performance breathable materials in regulated and technically demanding end-use sectors.
Segment - End Use
Revenue capture definition
Personal Care & Hygiene
Revenue is captured through breathable films supplied for baby diapers, feminine hygiene products, adult incontinence products, and personal care disposables. Value is driven by moisture vapor transmission, liquid barrier performance, skin comfort, softness, and product durability. Demand is supported by rising hygiene awareness, growing aging populations, and increasing adoption of premium absorbent hygiene products that require effective breathability and leakage protection.
Medical & Healthcare
Revenue is generated through breathable films used in surgical gowns, drapes, wound care dressings, medical packaging, and protective healthcare products. Pricing is influenced by fluid resistance, microbial barrier properties, patient comfort, sterilization compatibility, and compliance with healthcare safety standards. Growth is supported by expanding healthcare infrastructure and increasing demand for infection prevention solutions.
Building & Construction
Revenue is captured through breathable films used in roofing membranes, house wraps, wall underlays, and moisture management systems for residential and commercial buildings. Value is driven by water resistance, vapor permeability, energy efficiency benefits, and protection against mold and structural deterioration. Demand is supported by growing construction activity, stricter building performance standards, and increasing adoption of sustainable building materials.
Industrial Protective Apparels
Revenue is generated through breathable films incorporated into protective garments used across manufacturing, chemical processing, pharmaceuticals, cleanrooms, and hazardous work environments. Pricing is supported by breathability, liquid and particulate barrier performance, wearer comfort, and compliance with occupational safety requirements. Demand is strengthened by rising workplace safety regulations and increased use of advanced protective clothing.
Packaging
Revenue is captured through breathable films used in food packaging, fresh produce packaging, pharmaceutical packaging, and specialty industrial packaging applications. Value is driven by controlled moisture transmission, product preservation, extended shelf life, contamination protection, and packaging efficiency. Growth is supported by increasing demand for high-performance packaging solutions and advancements in sustainable packaging technologies.
Sports Apparels
Revenue is generated through breathable films integrated into sportswear, outdoor clothing, footwear components, and performance apparel. Pricing is influenced by moisture management, comfort, lightweight construction, weather protection, and durability under active use conditions. Demand is supported by growing participation in sports and fitness activities and increasing consumer preference for high-performance apparel materials.
Others
Revenue comes from specialized applications including agriculture, automotive interiors, filtration systems, consumer goods, furniture, and technical textile products. Value is supported by application-specific performance requirements, customization capabilities, environmental resistance, and material innovation. These niche applications provide opportunities for premium product offerings and diversified revenue streams.
Estimation Model
Layer Name
Key Question
Description
Top-Down Breathable Films Demand Assessment Layer
What defines market boundaries?
This layer establishes global breathable films demand across construction, industrial protection, transportation infrastructure, energy assets, water management systems, and environmental containment applications. Demand is filtered through macro drivers such as infrastructure investment cycles, industrial maintenance intensity, urbanization trends, and wastewater treatment expansion. This defines the total addressable market based on end-use consumption intensity.
End-Use Demand Validation Layer
Where is demand generated?
This layer maps demand across roofing membranes, wall wraps, waterproofing systems, flooring protection, bridge decks, pipelines, marine structures, and containment linings. Market sizing is aligned with performance needs such as vapor permeability, waterproofing efficiency, chemical resistance, UV stability, and long-term durability under extreme environmental exposure conditions.
Consumption-to-Revenue Conversion Layer
Who captures market revenue?
This layer translates application area and project volumes into revenue potential using breathable films consumption rates, film thickness specifications, installation methods, substrate compatibility, and system type (pure or hybrid formulations). Pricing differentials across industrial, commercial, and infrastructure-grade applications are incorporated to estimate value realization across the supply chain.
Regional Demand Verification Layer
How are assumptions validated?
This layer validates demand distribution across Asia Pacific, North America, and Europe by assessing infrastructure development intensity, industrial refurbishment activity, regulatory standards for energy-efficient buildings, and environmental protection investments. Regional construction pipelines, climate exposure risks, and compliance-driven adoption are used to verify market penetration assumptions and forecast robustness.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
The breathable films market was segmented by key regions, including North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa. Demand patterns were reviewed by construction activity, hygiene consumption, industrial usage, and regulatory maturity.
Helped identify region-specific growth pockets, mature markets, and high-potential expansion zones. Enabled clearer prioritization of sales, production, and distribution strategies.
Cross-segmentation
The market was analyzed across regions, applications, material types, thickness, and end-use industries. Demand overlaps were mapped to show where specific product grades perform best.
Provided a more granular view of demand drivers. Improved understanding of product-market fit and helped identify high-value segment combinations.
Competitive benchmarking
Leading and emerging players were benchmarked on product portfolio, technology capability, manufacturing scale, sustainability focus, and geographic reach. Market positioning and strategic priorities were compared across competitors.
Clarified relative strengths and weaknesses across the competitive landscape. Supported identification of white spaces and differentiation opportunities.
Frequently Asked Questions About This Report
The packaging segment led with a 40.6% revenue share in 2025. This is attributed to rising demand for the product across various applications, such as food & beverages, pharmaceuticals, cosmetics, and others.
Key factors that are driving the market growth include breathable films application for convenience food & beverage packaging, sports, and protective apparels such as masks and gloves.
Asia Pacific dominated with a 30.5% revenue share in 2025.
China is the leading breathable films market and is expected to grow at a compound annual growth rate of 6.5%.
The global breathable films market is expected to grow at a CAGR of 5.6% from 2026 to 2033, reaching USD 32.6 billion by 2033.
The global breathable films market size was valued at USD 21.2 billion in 2025 and is estimated at USD 22.3 billion for 2026.
Some key players operating in the breathable films market include Schweitzer-Mauduit International, Inc.; Arkema; Berry Global, Inc; Fatra, a.s.; Kimberley-Clark; Nitto Denko Corporation; Rahil Foam Pvt. Ltd.; RKW North America, Inc.; SILON s.r.o; SKYMARK; Daika Kogyo; American Polyfilm; Innovia Films; Mitsui Chemicals, Inc.; Omya AG.
The polyester segment dominated the overall market with a revenue share of 34.6% in 2025.
Based on film type, the non-porous segment led the market with the largest revenue share of 63.7% in 2025.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


