
- Home
- »
- Advanced Interior Materials
- »
-
Calcined Anthracite Market Size & Share Report, 2026-2033GVR Report cover

Calcined Anthracite Market (2026 - 2033)
Size, Share & Trends Analysis By Calcination (Gas, Electrical), By Application (Pulverized Coal Injection, Basic Oxygen Steel Making), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
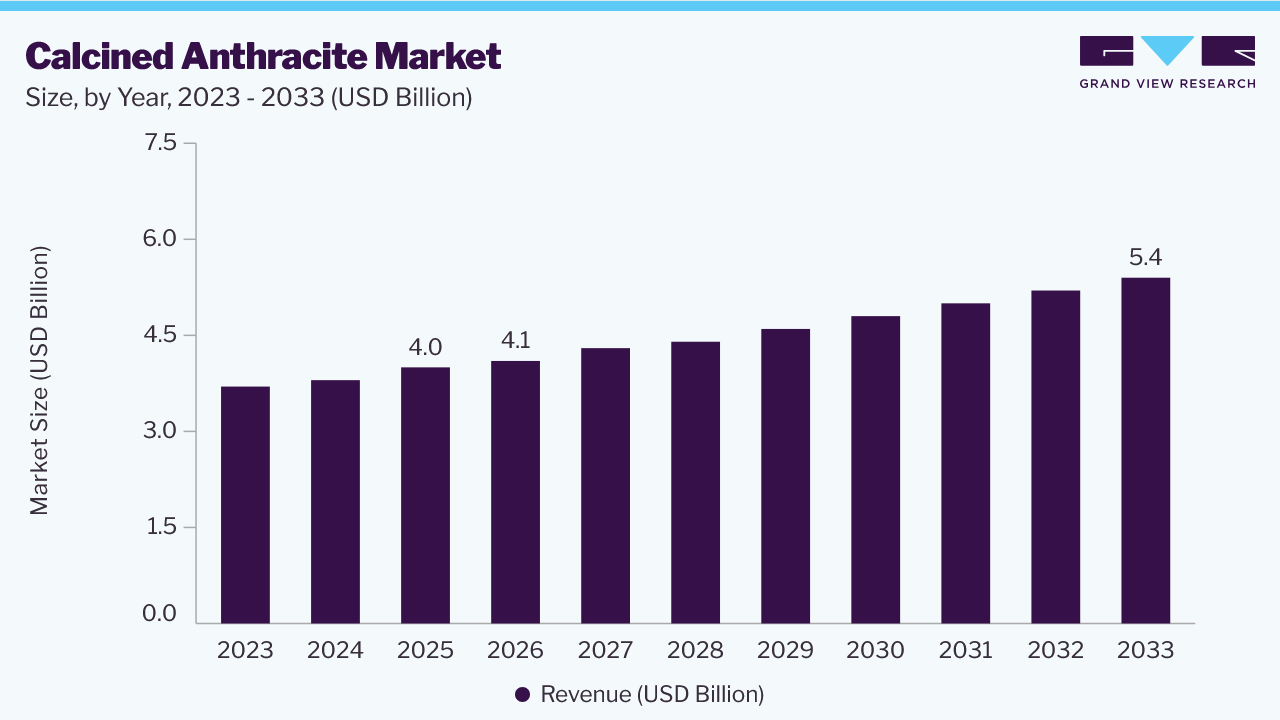
$4.0BMarket Estimate, 2026
$4.1BMarket Forecast, 2033
$5.4BCAGR, 2026–2033
4.0%Calcined Anthracite Market Summary
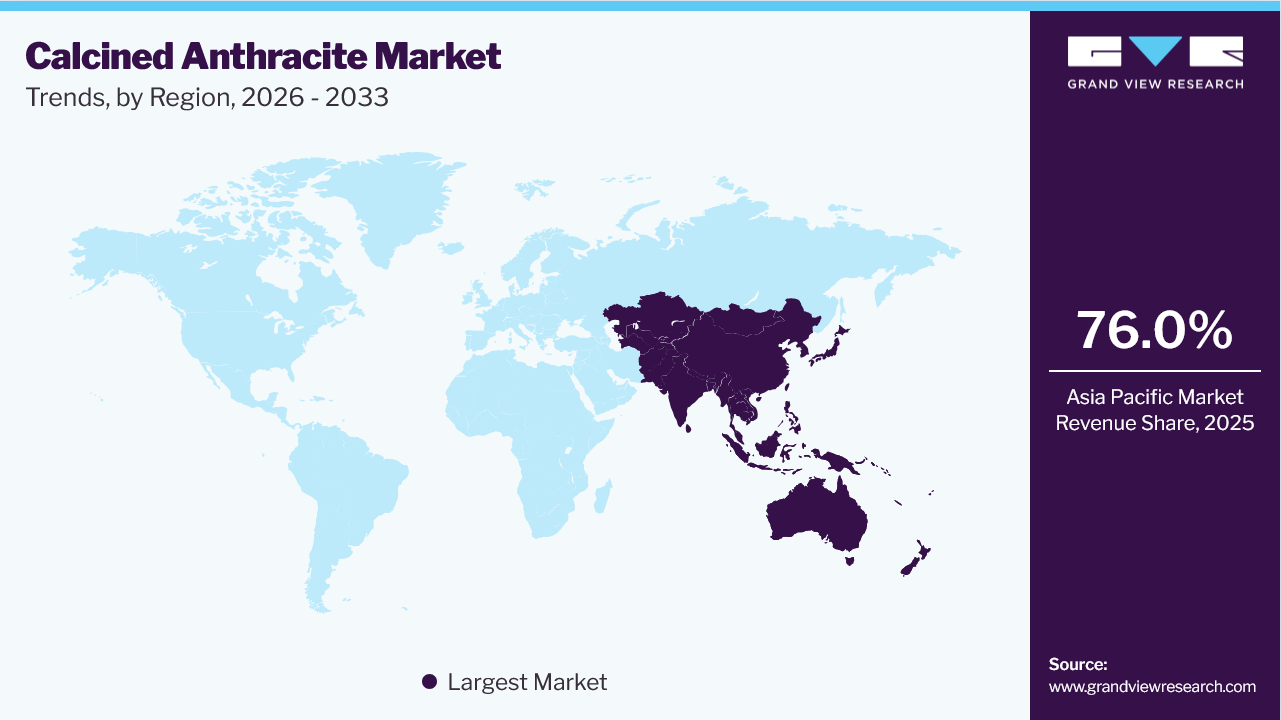
The global calcined anthracite market size was valued at USD 4.0 billion in 2025 and is projected to grow from USD 4.1 billion in 2026 to USD 5.4 billion in 2033, at a CAGR of 4.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 76.0% in 2025. Factors such as the increasing use of calcined anthracite in various applications, such as electric arc furnaces, pulverized coal injection, and steel manufacturing, are expected to push the market growth forward. It is used in the steel industry during the manufacturing process. The high carbon content with minimum impurities makes it an ideal material for various applications.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By calcination: The electric segment held the largest market share of around 75.0% in 2025.
- By application: The pulverized coal injection segment held the largest market share of approximately 44.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (76.0 % revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 4.0 Billion
- Estimated market size in 2026: USD 4.1 Billion
- Projected market size by 2033: USD 5.4 Billion
- CAGR (2026-2033): 4.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Calcined anthracite is an alternative to pet coke, as many countries impose pollution-control and environmental-sustainability regulations. Infrastructural developments in several countries lead to an increasing demand for steel, which influences the demand for calcined anthracite. Scientific and industrial literature commonly recognizes gas/electrically calcined anthracite as a high-carbon, low-volatile recarburizer used in cast iron and steel production due to its dense structure and high fixed-carbon content. Moreover, the growing dominance of steel in the construction and automotive sectors and the use of battery casings as an important filler component positively impact the market growth. Furthermore, continuous research and development for new applications contribute to market growth.
With the emerging trend of electric vehicles worldwide, the need for high-performance batteries drives the interest in electrically calcined anthracite. The demand for carbon content with high levels of conductivity, both electrical and thermal, has fueled the need for carbon electrode paste in the EV industry. In the steel industry, gas-calcined anthracite is an ideal component for applications involving cast iron or steel, primarily due to its dense properties. It is perceived as one of the best sources of high-quality carbon. Therefore, the calcined anthracite market is poised to grow steadily in the forecast period.
Analyst Perspective
The calcined anthracite market is expected to witness steady growth, driven by increasing demand from the steel, foundry, and aluminum industries, as it is widely used in these industries as a high-carbon recarburizer and carbon additive. The increased infrastructure development projects, along with industrial development, are contributing to its rapid adoption in the production of steel. This is resulting in an increase in the demand for calcined anthracite coal. Moreover, stringent government & environmental regulations are supporting the use of clean carbon material in place of petroleum coke. The new applications in batteries and conductive carbon products are providing additional growth avenues.
Calcination Insights
The electrical segment accounted for the largest market share of approximately 75.0% in 2025. Factors such as the increasing demand in the aluminum industry and electrically calcined anthracite are widely used as smelting additives due to their high purity and quality. The rising steel manufacturing and technological advancements have resulted in enhancements in battery technology, which is further poised to drive the segment growth. In addition, the increasing infrastructure developments are anticipated to contribute to the growth.
The gas segment is projected to witness the fastest-growing CAGR of approximately 4.0% in the forecast period. Gas applications in various industries are prominent due to the need for high-quality carbon materials, especially in the steel and aluminum industries. Technological advancements enhance the efficiency and effectiveness of gas-calcined anthracite. Gas-calcined anthracite is perceived as more environmentally friendly than its alternatives. In addition, the stringent government policies centered around clean technologies are further anticipated to encourage the use of eco-friendly gaseous chemicals.
Application Insights
The pulverized coal injection segment held the largest market share of approximately 44.0% in 2025. Pulverized coal reduces coke consumption and improves overall steel production efficiency. Pulverized Coal Injection (PCI) is a technique used in steelmaking where fine, talcum-like coal powder is pneumatically injected directly into the bottom of a Blast Furnace. Additionally, it reduces dependence on metallurgical coke and helps conserve energy, further enhancing steel and iron production. Owing to its efficiency, several steel manufacturers actively use these techniques for steel manufacturing. For instance, in September 2025, Jindal Steel commissioned a 5 MTPA blast furnace at its Angul facility in India, significantly increasing hot metal production capacity and reinforcing demand for pulverized coal injection and metallurgical carbon materials.
With the government’s support for clean energy, the authorities offer financial incentives and subsidies for implementing clean energy and systems. These factors are expected to catalyze the segment growth in the forthcoming years. In addition, the price stability of pulverized coal in the past few years has increased its demand.
The electric arc furnaces segment is expected to be the fastest-growing segment with a CAGR of approximately 4.5% over the forecast period. Increasing emphasis on sustainable manufacturing practices, as electric arc furnaces are more sustainable than traditional blast furnaces. The innovations and developments enhance operational efficiency and reduce energy consumption. Besides, the capital required to install an electric arc furnace is lower than that of its alternatives, resulting in cost efficiency. In addition, the increasing industrialization in countries such as India, Japan, and China will further drive market development. In March 2026, Tata Steel announced its journey toward sustainable steelmaking with the introduction of its scrap-based Electric Arc Furnace (EAF) facility at Hi-Tech Valley, Ludhiana. Built with an investment of approximately USD 340 million, the Ludhiana EAF has a capacity of 0.75 million tons per annum.
Regional Insights
The Asia Pacific calcined anthracite industry held the largest market share of approximately 76.0% in 2025. The increasing number of steel industries in India, China, and Japan supplements the regional market developments. In addition, the increase in aluminum production due to increasing investments in production facilities across the region, and the infrastructural developments, boost the regional developments. The increasing trend of lightweight materials in the automotive industry has increased the demand for calcined anthracite. For instance, in October, JSW Steel reported crude steel production of 6.77 million tons in Q2 FY25, reflecting strong steel manufacturing activity in India, which supports the consumption of carbon additives such as calcined anthracite in metallurgical processes.
 To learn more about this report, Download Free Sample Report
North America Calcined Anthracite Market Trends
The calcined anthracite industry in North America accounted for the global market share of approximately 8.5% in 2025. Factors such as the increasing emphasis on environmentally friendly practices in the U.S. and Canada have fueled the use of calcined anthracite. The shift in trend from traditional blast furnaces to electric arc furnaces has significantly contributed to the regional market growth. Other factors, such as the increase in steel consumption and emphasis on cleaner production practices, drive the market growth.
Europe Calcined Anthracite Market Trends
The calcined anthracite industry in Europe held a significant market share of approximately 11.5% in 2025. The growing demand for steel in the region has resulted in a surge in demand for calcined anthracite. Increasing environmental regulations are influencing the industries to adopt cleaner production practices and technological advancements that exhibit enhanced efficiency and reduce costs.
Key Calcined Anthracite Company Insights
Some of the key players in the calcined anthracite market are Rheinfelden Carbon Products GmbH., Asbury Carbons, and other companies. Organizations focus on increasing their customer base to gain a competitive edge in the industry. Therefore, the key players are undertaking several strategic initiatives, such as mergers and acquisitions, and partnerships with other major companies.
- Rheinfelden Carbon Products is a German multinational company among the leading manufacturers, especially in gas calcined anthracite.
- Asbury Carbons is a U.S.-based company offering diverse product offerings and has established partnerships with global suppliers to ensure a consistent supply of raw materials.
Key Calcined Anthracite Companies
The following are the leading companies in the calcined anthracite market. These companies collectively hold the largest market share and dictate industry trends.
-
Rheinfelden Carbon Products GmbH.
-
JH CARBON PTY LTD
-
RESORBENT, s.r.o.
-
Asbury Carbons
-
Rheinbraun Brennstoff
-
Ningxia Carbon Valley International Co., Ltd
-
Ningxia Coalician Carbon & Coke Co Ltd
-
Dev Energy
-
Carbon Resources
-
Singhania International Limited
Recent Developments
- In 2024, Petro Carbon and Chemicals Limited (PCCL), part of Atha Group, announced the installation of an Electrically Calcined Anthracite (ECA) facility in Haldia, India.
- In July 2024, Rio Tinto and Aymium formed the Évolys Québec joint venture to produce renewable metallurgical biocarbon as an alternative to anthracite in smelting applications.
Calcined Anthracite Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.0 billion
Estimated market size in 2026
USD 4.1 billion
Projected market size by 2033
USD 5.4 billion
Growth rate
CAGR of 4.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Calcination, application, region
Regional scope
North America; Europe; Asia Pacific
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India
Key companies profiled
Rheinfelden Carbon Products GmbH.; JH CARBON PTY LTD; RESORBENT; Asbury Carbons; Rheinbraun Brennstoff; Ningxia Carbon Valley International Co., Ltd; NingXia Coalician Carbon & Coke Co Ltd; Dev Energy; Carbon Resources; Singhania International Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Calcined Anthracite Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global calcined anthracite market report based on calcination, application, and region:
-
Calcination Outlook (Volume, Kilotons; Revenue, USD Billion, 2021- 2033)
-
Gas
-
Electrical
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021- 2033)
-
Pulverized Coal Injection
-
Basic Oxygen Steel Making
-
Electric Arc Furnaces
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021- 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Frequently Asked Questions About This Report
The global calcined anthracite market size was valued at USD 4.0 billion in 2025 and is estimated at USD 4.1 billion for 2026.
Key players in the market include Rheinfelden Carbon Products GmbH., JH CARBON PTY LTD, RESORBENT, Asbury Carbons, Rheinbraun Brennstoff, Ningxia Carbon Valley International Co., Ltd, NingXia Coalician Carbon & Coke Co Ltd, Dev Energy, Carbon Resources, Singhania International Limited, and others.
Asia Pacific dominated with an approximately 76.0% revenue share in 2025.
The electrical segment accounted for the largest revenue share of approximately 75.0% in 2025.
The global calcined anthracite market is expected to grow at a CAGR of 4.0% from 2026 to 2033, reaching USD 5.4 billion.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


