
- Home
- »
- Advanced Interior Materials
- »
-
Carbon Steel Market Size, Share & Trends Report 2026-2033GVR Report cover

Carbon Steel Market (2026 - 2033)
Size, Share & Trend Analysis Report By Type (Low Carbon Steel, Medium Carbon Steel, High Carbon Steel), By Application (Ship Building, Construction, Automotive), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$1,059.6BMarket Estimate, 2026
$1,107.2BMarket Forecast, 2033
$1,664.5BCAGR, 2026–2033
6.0%Carbon Steel Market Summary
The global carbon steel market size was valued at USD 1,059.6 billion in 2025 and is projected to grow from USD 1,107.2 billion in 2026 to USD 1,664.5 billion by 2033, at a CAGR of 6.0% from 2026 to 2033. Asia Pacific dominated the global market with the largest revenue share of 67.3% in 2025. Increasing focus on infrastructure development, particularly in Asia Pacific countries, is projected to drive the consumption of carbon steel products over the coming years.
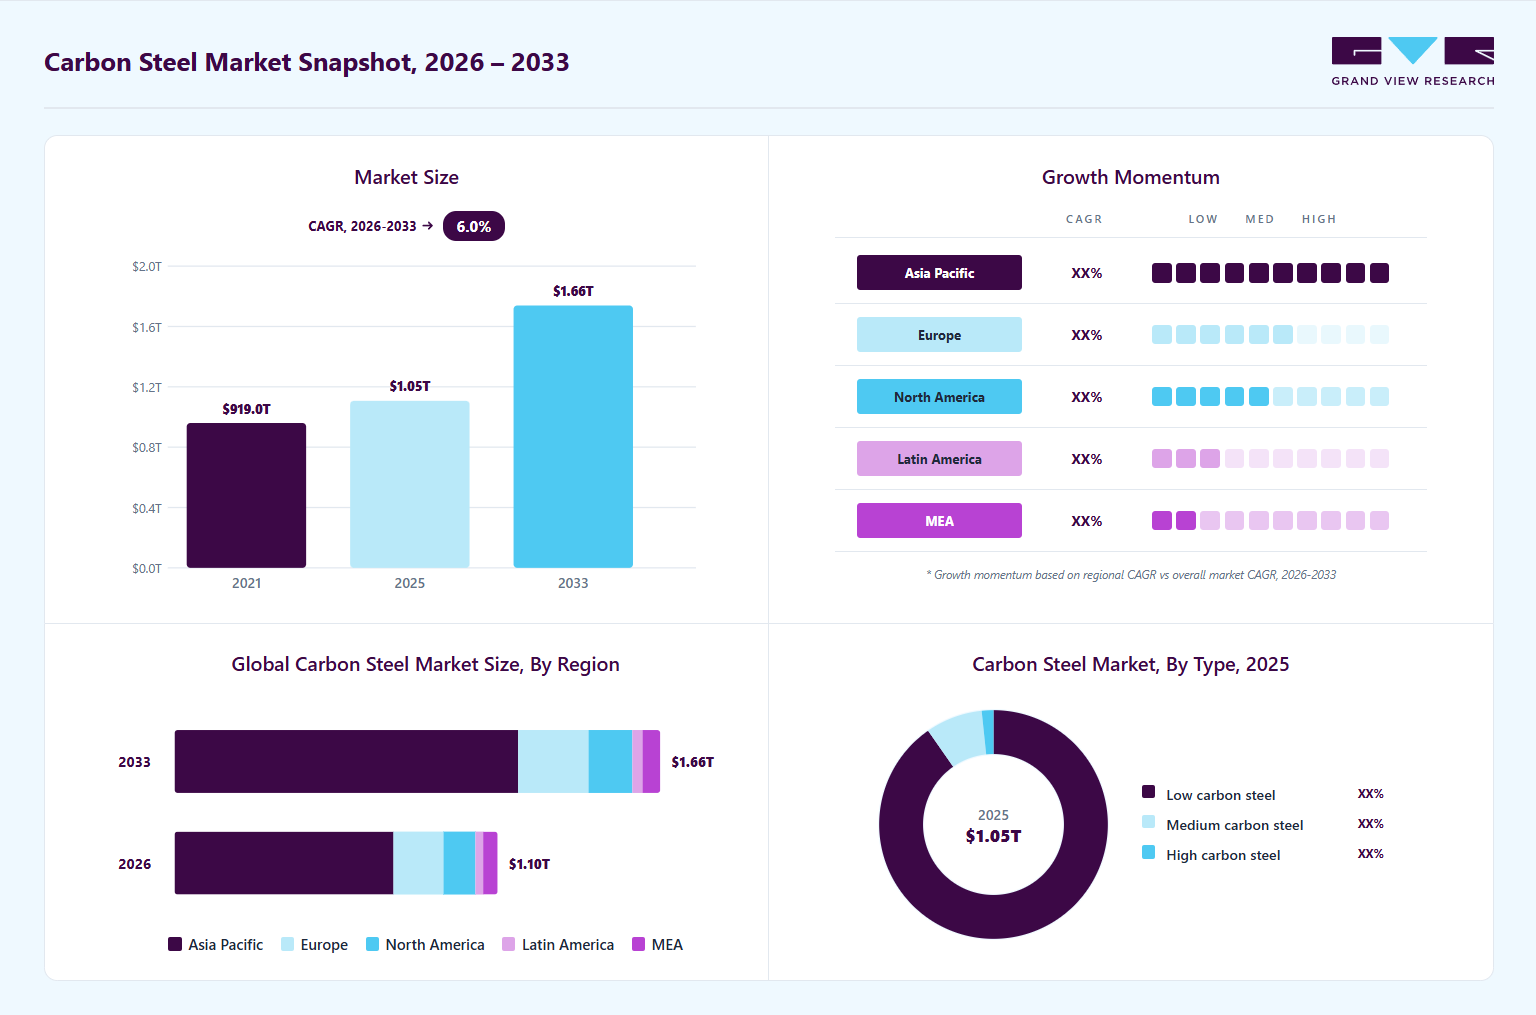 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Low carbon steel segment led the market with the largest revenue share of 90.3% in 2025.
- By application: Construction segment led the market with the largest revenue share of 40.7% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (67.3% revenue share, 2025)
- By country: The carbon steel market in the China held the largest share in the Asia Pacific region in 2025.
Market Size & Forecast
- Market size in 2025: USD 1,059.6 Billion
- Estimated market size in 2026: USD 1,107.2 Billion
- Projected market size by 2033: USD 1,664.5 Billion
- CAGR (2026-2033): 6.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The automotive industry plays a big role in boosting the consumption of carbon steel. Automakers use it to manufacture car bodies, exhaust systems, chassis frames, wheels, engine blocks, and many under-the-hood components. Its strength, formability, and cost-effectiveness make it ideal for mass production. As vehicle production rises, more carbon steel is needed, especially electric vehicles (EVs) in markets like China, the U.S., and Europe.For instance, in 2024, the global EV market surpassed 17 million units sold, marking a 17% year-on-year increase. China led this surge with 11 million EV sales, propelled by affordable pricing and robust domestic production. In EVs, carbon steel is also used for battery enclosures, structural frames, and undercarriage protection. Developing countries are witnessing a rising middle class and increasing car ownership, leading to the growth of local vehicle production. Moreover, many automakers are expanding or relocating their manufacturing plants to reduce supply chain risks. New machinery, stamping lines, and robotic arms are installed, mostly made using carbon steel.
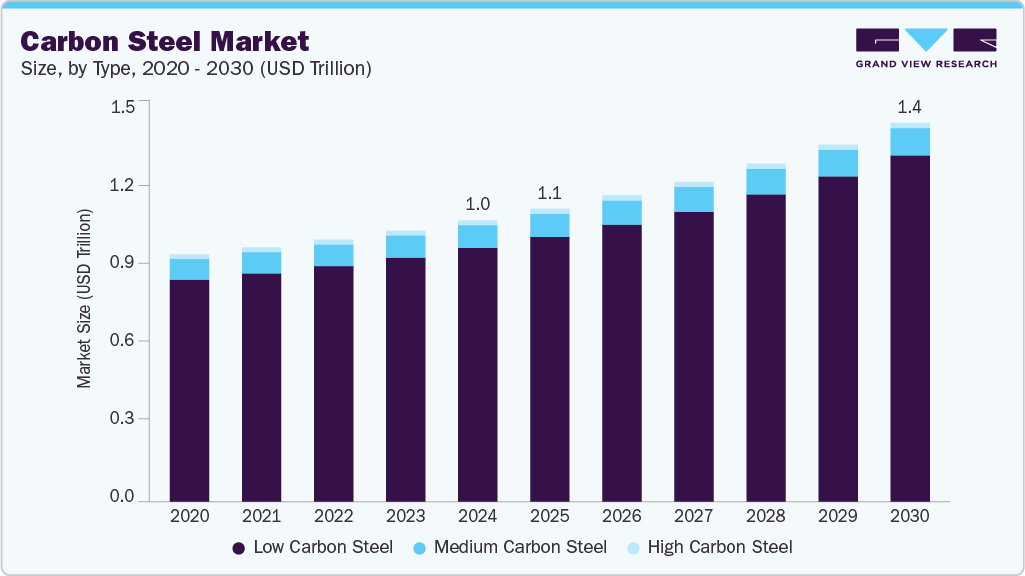 To learn more about this report, Download Free Sample Report
Manufacturing industries rely on carbon steel for its durability and ease of machining. The need for strong steel components rises as factories expand production lines and adopt automated systems. Sectors like mining, shipbuilding, chemicals, cement, and food processing use carbon steel in the form of tanks, conveyors, hoppers, gears, and shafts. Even basic industrial shelving, workbenches, and welding tables are made of carbon steel. In many regions, governments promote local manufacturing through incentives and policy reforms, such as “Make in India” and similar initiatives across Southeast Asia and Africa. These efforts are encouraging new investments in factories, which in turn increases the need for steel-based machinery and structures.
The oil and gas industry uses it for pipelines, drilling rigs, tanks, and refinery equipment due to its strength and resistance to high pressures. Natural gas transmission projects, including cross-border pipelines, are expanding across regions like the Middle East, Africa, and Central Asia. Meanwhile, the renewable energy sector is also using carbon steel extensively. Wind turbine towers, solar mounting structures, and hydroelectric dam components are all steel-intensive. Even in nuclear power plants, carbon steel is used for pressure vessels and structural applications. As countries strive to improve electricity access, reduce emissions, and upgrade energy grids, using carbon steel in conventional and renewable energy projects is gaining strong momentum.
Market Dynamics
The carbon steel market is experiencing strong growth driven by rising infrastructure investment and urbanization across emerging and developed economies. Carbon steel remains one of the most widely used construction materials due to its high strength, durability, cost-effectiveness, and versatility. Large-scale projects involving bridges, highways, rail networks, commercial buildings, residential housing, and industrial facilities continue to drive substantial demand for structural carbon steel products. Rapid urban expansion in countries such as India, China, Vietnam, and several Middle Eastern nations is further accelerating the consumption of carbon steel in construction and infrastructure applications. The construction sector alone accounts for the largest share of global carbon steel demand, underscoring its critical role in market expansion.
The rapid expansion of construction and infrastructure worldwide is a major driver of the carbon steel market. Carbon steel is widely used in residential, commercial, and industrial construction due to its high strength, durability, weldability, and cost-effectiveness. Structural beams, reinforcement bars, columns, roofing systems, and other building components extensively rely on carbon steel to ensure long-term structural integrity. As governments and private investors continue to fund large-scale housing projects, commercial complexes, and industrial facilities, the demand for carbon steel is increasing significantly across both developed and emerging economies.
Infrastructure development projects such as highways, bridges, railways, airports, ports, and urban transit systems are further contributing to market expansion. Many countries are implementing infrastructure modernization programs to support economic growth, improve connectivity, and accommodate rising urban populations. Carbon steel remains a preferred material for these projects because of its ability to withstand heavy loads and harsh environmental conditions, while offering a favorable cost-to-performance ratio. The growing emphasis on smart cities, transportation networks, and public infrastructure upgrades is expected to sustain strong demand for carbon steel throughout the forecast period.
Volatility in raw material prices remains a significant restraint for the carbon steel market, as key inputs such as iron ore, coking coal, and steel scrap are subject to frequent price fluctuations driven by supply chain disruptions, geopolitical tensions, mining output variations, and changing global demand patterns. Sudden increases in raw material costs can substantially raise production expenses for steel manufacturers, putting pressure on profit margins and reducing pricing flexibility. In many cases, producers are unable to fully pass these higher costs on to end users due to competitive market conditions, leading to financial challenges and operational uncertainties. Furthermore, unpredictable raw material pricing complicates long term planning, procurement strategies, and investment decisions, creating additional risks for market participants across the carbon steel value chain.
Advancements in green steel production technologies present a significant opportunity for the carbon steel market as governments, investors, and end-use industries increasingly prioritize sustainability and carbon reduction. Steel manufacturers are investing in innovative processes, such as hydrogen-based direct-reduced iron (DRI), electric arc furnaces powered by renewable energy, carbon capture systems, and enhanced recycling technologies, to lower greenhouse gas emissions associated with steel production. These developments enable producers to comply with evolving environmental regulations, reduce operational risks related to carbon pricing mechanisms, and strengthen their competitive positioning in global markets. As industries such as automotive, construction, and renewable energy seek low-carbon materials to meet their sustainability commitments, demand for environmentally responsible carbon steel products is expected to grow, creating new revenue streams and long-term market expansion opportunities.
Analyst Perspective
The carbon steel market remains one of the most fundamental pillars of global industrial development, supported by its extensive use across construction, automotive, shipbuilding, manufacturing, and energy sectors. Rapid urbanization, infrastructure expansion, and growing investments in transportation networks are continuing to drive strong demand, particularly in Asia Pacific, which remains the dominant consumption hub. The market is also benefiting from rising electric vehicle production, renewable energy installations, and industrial modernization projects that rely heavily on carbon steel for structural and mechanical applications.
Drivers, Opportunities & Restraints
The demand for carbon steel is largely supported by rapid infrastructure development, industrial expansion, and growth in the automotive and energy sectors. Carbon steel is extensively used in constructing bridges, highways, buildings, pipelines, and industrial machinery due to its strength and affordability. Emerging economies such as India, China, and Vietnam are witnessing a surge in urban development and manufacturing activity, increasing the need for construction-grade steel. The global shift towards electric vehicles and renewable energy systems is also boosting the demand for carbon steel components used in battery structures, wind turbine towers, and energy transmission systems.
There are several promising opportunities in the carbon steel industry, especially driven by green energy projects, infrastructure stimulus plans, and the trend of reshoring industrial production. The expansion of wind and solar energy installations across the U.S., Europe, and the Asia Pacific requires strong support structures, which often rely on carbon steel. Moreover, with many governments implementing infrastructure stimulus programs post-COVID, the demand for structural steel is expected to rise steadily. There is also growing interest in lightweight, high-strength variants of carbon steel for automotive applications, which could open up innovation-driven growth segments shortly.
Despite strong demand, the carbon steel industry faces several challenges. Volatility in raw material prices—particularly iron ore and coking coal, can impact profit margins and pricing stability. Environmental regulations related to carbon emissions from steel manufacturing are becoming stricter in regions like Europe and North America, putting pressure on producers to invest in cleaner technologies. In addition, the growing preference for stainless steel or aluminum in high-end or corrosion-sensitive applications can limit carbon steel’s usage in certain markets.
Type Insights
Based on type, low carbon steel segment led the market with the largest revenue share of 90.3% in 2025. Low-carbon steel, also known as mild steel, is witnessing strong demand due to its widespread use in construction, automotive, and consumer goods industries. Its properties, such as high ductility, ease of welding, and relatively low cost, make it ideal for manufacturing structural components, pipelines, metal sheets, and frames. Low-carbon steel is commonly used for reinforcing bars, light structural sections, and HVAC systems in the construction sector. Its machinability and formability make it a preferred material for parts that require bending, punching, or shaping.
The high carbon segment is anticipated to register at the fastest CAGR over the forecast period. It is gaining attention due to its superior hardness, strength, and wear resistance, making it suitable for specialized industrial applications. It primarily produces cutting tools, blades, springs, high-strength wires, dies, and rail tracks. The manufacturing sector, especially machinery, mining equipment, and automotive components, relies on high-carbon steel for parts that must withstand high stress, impact, and friction. For example, components like crankshafts, gears, and axles in heavy-duty vehicles often require high-carbon steel due to its durability under load. As global manufacturing recovers and industries modernize their equipment, the need for strong and wear-resistant materials is rising, benefiting this steel grade.
Application Insights
Based on application, construction segment led the market with the largest revenue share of 40.7% in 2025. This industry is one of the largest consumers of carbon steel, driven by its strength, versatility, and affordability. Carbon steel is extensively used in structural applications such as beams, columns, reinforcement bars (rebars), roofing materials, staircases, and frameworks for buildings, bridges, and tunnels. Its ability to withstand heavy loads and harsh weather conditions makes it ideal for residential and commercial construction.
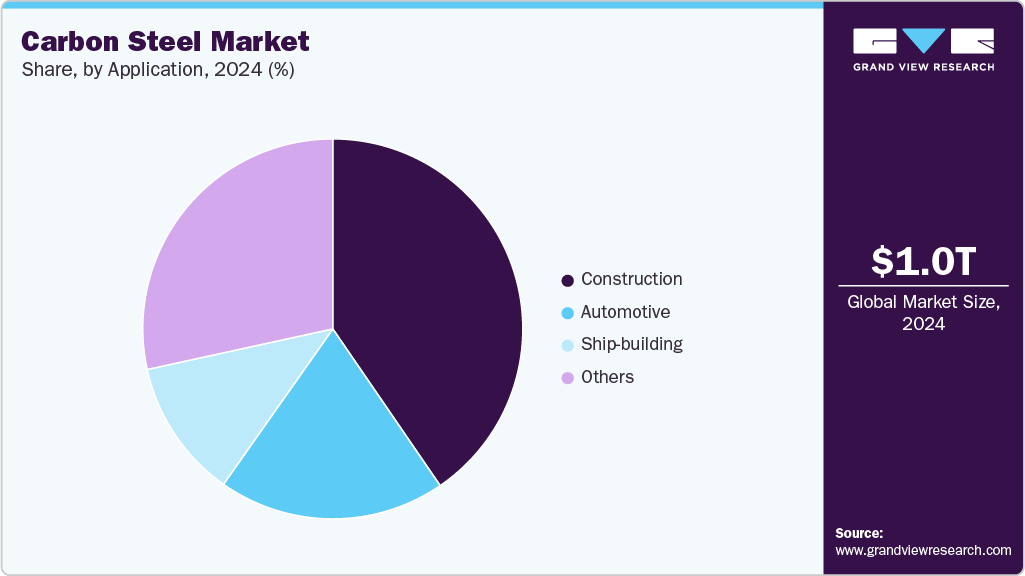 To learn more about this report, Download Free Sample Report
The automotive segment is anticipated to grow at a significant CAGR over the forecast period. Carbon steel is a key material in the automotive industry due to its excellent strength-to-weight ratio, cost-effectiveness, and suitability for forming and welding. It is widely used in manufacturing critical vehicle components such as chassis frames, body panels, engine parts, drive shafts, suspension systems, and exhaust pipes. As global vehicle production expands, particularly in emerging economies, this segment's demand for carbon steel has consistently grown.
For instance, in 2024, global vehicle production surpassed 93 million units, with China contributing over 30 million units, making it the largest vehicle manufacturing hub. In countries like India, Mexico, and Thailand, rising income levels and urbanization are driving up domestic automobile production, which fuels demand for carbon steel components due to their affordability and structural reliability.
Regional Insights
The carbon steel market in North America is supported by robust demand from the construction, automotive, energy, and manufacturing sectors. The U.S. leads the region in production and consumption, with carbon steel playing a key role in infrastructure development projects such as bridges, highways, pipelines, and public buildings. The passing of the U.S. Infrastructure Investment and Jobs Act, which allocates over USD 1.2 trillion for infrastructure upgrades over the next decade, is expected to boost demand for carbon steel across multiple applications significantly. Growing investments in commercial construction, transport networks, and energy transmission lines in Canada and Mexico further contribute to a steady demand for structural and low-carbon steel products.
U.S. Carbon Steel Market Trends
The carbon steel market in the U.S. accounted for the largest market revenue share in North America in 2024. In the U.S., carbon steel is widely used in construction, automotive, and energy industries. Large infrastructure projects such as roads, bridges, airports, and rail systems continue to support steady demand. The automotive industry is another major user of carbon steel in the U.S., especially for making vehicle frames, engine parts, and exhaust systems. In 2024, over 10 million vehicles were produced in the country, and production is expected to grow in 2025. Electric vehicle manufacturing is also rising, with carbon steel still playing a key role in structural and internal components. At the same time, steelmakers in the U.S. are investing in cleaner technologies like electric arc furnaces to meet environmental goals and reduce emissions, ensuring the long-term sustainability of the domestic carbon steel industry.
Asia Pacific Carbon Steel Market Trends
Asia Pacific dominated the carbon steel market with the largest revenue share of 67.3% in 2025, driven by rapid industrialization, urbanization, and infrastructure development across major economies such as China, India, Japan, and Southeast Asia. China, in particular, is the world’s largest producer and consumer of carbon steel, accounting for over half of global output. The country’s massive investment in infrastructure, including highways, high-speed rail, bridges, and smart cities, has kept demand for carbon steel consistently high. India also has strong momentum due to its National Infrastructure Pipeline (NIP), smart city initiatives, and expanding construction and manufacturing sectors. In addition, Japan and South Korea continue to use carbon steel extensively in automotive production and shipbuilding, supported by their advanced industrial bases.
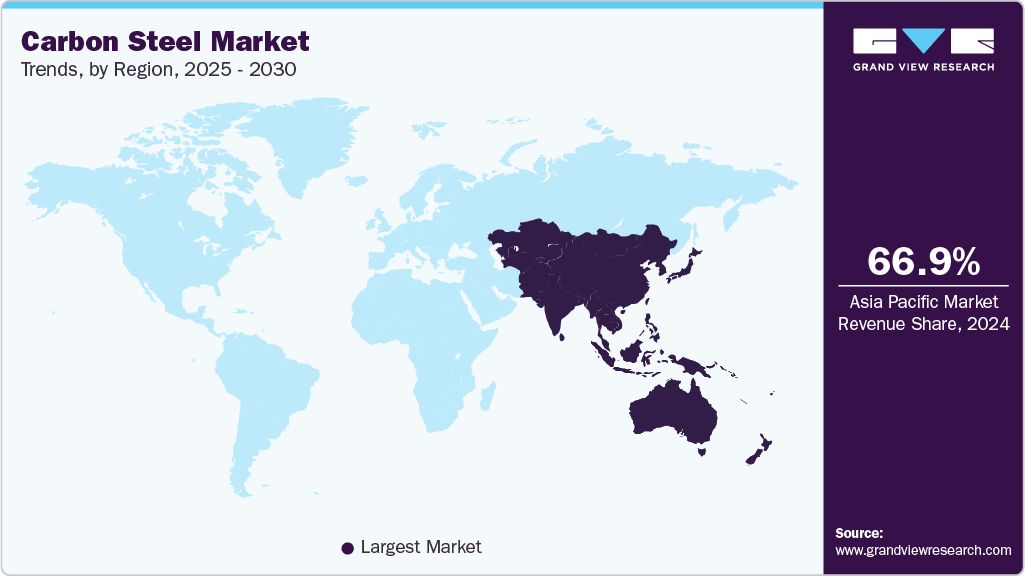 To learn more about this report, Download Free Sample Report
China Carbon Steel Market Trends
The carbon steel market in the China held the largest share in the Asia Pacific region in 2025.
Europe Carbon Steel Market Trends
The carbon steel market in Europe is anticipated to grow at the fastest CAGR during the forecast period. In the automotive sector, Europe is home to some of the world’s largest car manufacturers, including Volkswagen, BMW, Stellantis, and Renault. These companies continue to use carbon steel for vehicle chassis, structural parts, and engine components. The demand for strong yet affordable materials remains high with the ongoing shift toward electric vehicles. At the same time, European steel producers are under pressure to reduce emissions, leading to increased investment in green steel technologies and low-carbon production methods. These efforts are expected to shape the future of the carbon steel market in Europe while keeping it competitive and environmentally aligned.
Latin America Carbon Steel Market Trends
The carbon steel market in Latin America is seeing steady demand for carbon steel, mainly driven by infrastructure development, construction projects, and industrial expansion. Countries like Brazil, Mexico, Argentina, and Chile are investing in roads, bridges, railways, and public housing, which rely heavily on carbon steel for structural applications. Brazil, in particular, is the region's largest producer and consumer of carbon steel, supported by a strong domestic steel industry and major construction programs. Mexico also shows solid demand, especially with the growth of its automotive manufacturing sector and cross-border industrial exports to the U.S.
Middle East & Africa Carbon Steel Market Trends
The carbon steel market in the Middle East & Africa is witnessing a shift towards sustainable steel production. Countries like the UAE and Saudi Arabia are investing in green steel initiatives to reduce carbon emissions, leveraging their abundant renewable energy resources. For instance, in November 2023, Emirates Steel Arkan has partnered with international firms to develop green steel production facilities in Abu Dhabi. In addition, the automotive sector in Egypt and Morocco is expanding, increasing the demand for carbon steel in vehicle manufacturing. Despite challenges like fluctuating raw material prices and competition from alternative materials, the MEA carbon steel industry is poised for growth, supported by ongoing industrialization and infrastructure development.
Key Carbon Steel Company Insights
Some of the key players operating in the market include ArcelorMittal, AK Steel Corporation, and others.
-
ArcelorMittal, headquartered in Luxembourg City, is one of the world's leading steel and mining companies. With operations in over 60 countries and industrial footprints in 18 countries, the company produced approximately 58 million metric tonnes of crude steel in 2024, making it the second-largest steel producer globally. The company offers a diverse range of products, including flat and long carbon steel products, tailored to meet the needs of different industries. The company has also introduced the XCarb initiative, encompassing ArcelorMittal's reduced, low, and zero-carbon steelmaking activities.
-
AK Steel Corporation, now a subsidiary of Cleveland-Cliffs Inc., is a prominent producer of flat-rolled carbon, stainless, and electrical steel products. The company's operations are primarily in the U.S., with Indiana, Kentucky, Ohio, and Pennsylvania facilities. AK Steel specializes in producing hot and cold-rolled carbon steel products in the carbon steel segment, including coated and enameling steels. These products are essential for automotive manufacturers, especially for body panels and structural parts.
Key Carbon Steel Companies:
The following are the leading companies in the carbon steel market. These companies collectively hold the largest market share and dictate industry trends.
- AK Steel Corporation
- ArcelorMittal
- Baosteel Group
- Evraz plc
- HBIS Group
- JFE Steel Corporation
- Nippon Steel Corporation
- NLMK
- POSCO
- United States Steel
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g. ArcelorMittal, Baosteel Group, Evraz plc, HBIS Group)
- Mature participants in the carbon steel market primarily focus on large scale integrated steel production, supply chain optimization, and long term contracts with customers across construction, automotive, shipbuilding, energy, and industrial machinery sectors.
- These companies operate extensive facilities that encompass ironmaking, steelmaking, rolling, and finishing operations, allowing them to maintain cost efficiency and production consistency.
- Established players possess significant competitive advantages through their extensive production capacities, integrated operations, and strong raw material procurement capabilities.
- Their ability to achieve economies of scale enables lower production costs, stronger pricing competitiveness, and reliable supply to large industrial customers.
- Despite their market leadership, mature players face challenges related to high capital intensity, energy consumption, and environmental compliance requirements.
- Carbon steel production requires substantial investments in blast furnaces, rolling mills, emission control systems, and supporting infrastructure.
Emerging & Regional Players (e.g., AK Steel Corporation, NLMK)
- Emerging participants in the carbon steel market generally focus on regional demand opportunities, specialized product segments, and operational flexibility.
- Rather than competing directly with large integrated steel producers on scale, these companies often target niche markets requiring customized grades, smaller production volumes, or faster delivery schedules.
- Emerging companies benefit from operational agility and greater flexibility in responding to changing customer requirements.
- Their smaller organizational structures often allow faster decision making, quicker product development cycles, and more customized solutions compared to larger competitors.
- Emerging participants face significant challenges related to limited production capacity, lower economies of scale, and restricted access to financial resources.
- Competing against established steel producers with extensive manufacturing infrastructure and global distribution networks can be difficult, particularly in commodity grade carbon steel segments where pricing remains a key competitive factor.
Recent Developments
-
In February 2025, Gunung Raja Paksi Tbk (GRP), signed a multi-million-dollar deal with Primetals Technologies to become Asia's first supplier outside China of zero carbon endless hot rolled coil (HRC) for export to Europe. The new production line is expected to be operational by 2027, coinciding with the European Union's carbon border adjustment mechanism (CBAM) regime, positioning GRP as a leader in low-carbon steel manufacturing in Southeast Asia.
-
In July 2023, Hyundai Steel, a major South Korean steelmaker, launched its low-carbon steel brand, HyzeroSteel, under the new HyECOsteel initiative. This brand represents Hyundai Steel’s commitment to environmentally friendly steel production, aiming to reduce carbon emissions throughout its manufacturing process. As part of this initiative, the company plans to expand electric arc furnace (EAF) usage and adopt hydrogen-based steelmaking technologies. The launch aligns with Hyundai Steel’s broader sustainability strategy and goal of achieving carbon neutrality by 2050, reinforcing its position as a leader in green steel innovation in the Asia Pacific region.
Carbon Steel Market Report Scope
Report Attribute
Details
Market definition
The carbon steel market refers to the consumption of steel products primarily composed of iron and carbon, with limited alloying elements, used across a wide range of industrial applications.
Market size in 2025
USD 1,059.6 billion
Estimated market size in 2026
USD 1,107.2 billion
Projected market size by 2033
USD 1,660.5 billion
Growth rate
CAGR of 6.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, volume in kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; India; China; Japan; South Korea; Brazil; Saudi Arabia; UAE
Key companies profiled
AK Steel Corporation, ArcelorMittal, Baosteel Group, Evraz plc, HBIS Group, JFE Steel Corporation, Nippon Steel Corporation, NLMK, POSCO, United States Steel.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Carbon Steel Market Report Segmentation
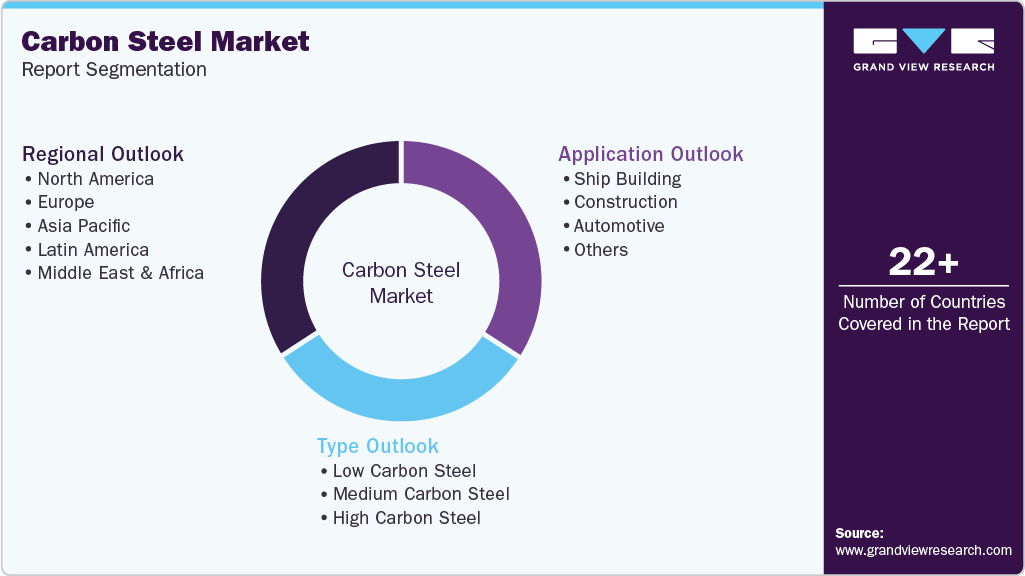
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global carbon steel market report based on type, application, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Low Carbon Steel
-
Medium Carbon Steel
-
High Carbon Steel
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Ship Building
-
Construction
-
Automotive
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Research Methodology
The carbon steel market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each carbon steel segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue Capture Definition
Low carbon steel
Low carbon steel contains typically up to 0.30% carbon and is known for its excellent ductility, weldability, and formability. It is widely used in construction, automotive body panels, pipes, and structural applications.
Medium carbon steel
Medium carbon steel contains approximately 0.30% to 0.60% carbon, offering a balance between strength, hardness, and ductility. It is commonly utilized in machinery components, railway tracks, gears, and automotive parts.
High carbon steel
High carbon steel contains around 0.60% to 1.0% carbon, providing superior hardness, wear resistance, and tensile strength. It is extensively used in cutting tools, springs, wires, and high strength industrial applications.
Application
Revenue Capture Definition
Ship-building
Carbon steel used in shipbuilding includes plates, sections, and structural components designed to provide strength, durability, and resistance to harsh marine environments. It is extensively utilized in the construction of cargo ships, tankers, naval vessels, and offshore structures.
Construction
Carbon steel in construction comprises structural beams, reinforcement bars, pipes, and sheets used in residential, commercial, and infrastructure projects. Its high strength, versatility, and cost effectiveness make it a key material for buildings, bridges, and industrial facilities.
Automotive
Carbon steel is widely employed in automotive manufacturing for chassis, body structures, engine components, and safety systems. It offers an optimal combination of strength, formability, and durability required for vehicle production.
Others
Others includes carbon steel consumption in power generation equipment, industrial machinery, household appliances, storage systems, and material handling equipment.
Estimation Model
Layer Name
Key Question
Description
Steel Demand Base Layer
What forms the demand base?
Identify global demand for steel across major end use industries including construction, automotive, machinery, shipbuilding, energy, transportation, and infrastructure. Assess industrial production and investment activities that drive carbon steel consumption. This layer establishes the total addressable demand for carbon steel products globally.
Carbon Steel Application Penetration Layer
Where is carbon steel utilized?
Estimate the penetration of carbon steel across key applications such as structural components, pipes and tubes, automotive parts, machinery, industrial equipment, shipbuilding materials, and construction products. Analyze usage patterns across developed and emerging economies based on industrialization and infrastructure development.
Carbon Steel Consumption Intensity Layer
How much carbon steel is consumed?
Analyze carbon steel consumption intensity by application and industry. Evaluate the utilization of low carbon steel, medium carbon steel, and high carbon steel based on performance requirements, mechanical properties, and end use specifications. Consumption intensity varies according to manufacturing output, construction activity, and capital investment trends.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the production and sale of carbon steel products including sheets, plates, bars, rods, structural sections, pipes, and wires. Revenue generation is driven by demand from construction, automotive, industrial manufacturing, energy, and transportation sectors. Market value is influenced by steel prices, raw material costs, production volumes, product grades, and regional supply demand
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Regional Segmentation
Detailed regional analysis of the carbon steel market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. Included evaluation of crude steel production, infrastructure investments, construction activity, automotive manufacturing, industrial output, government spending, and trade policies influencing carbon steel demand and supply dynamics.
Identified high growth demand centers and key steel producing regions. Enabled strategic expansion planning based on industrialization trends, infrastructure development, and steel consumption growth. Supported regional demand forecasting and supply chain optimization.
Cross Segmentation
Comprehensive cross segmentation analysis by product type and application, including low carbon steel, medium carbon steel, and high carbon steel consumption across construction, automotive, shipbuilding, and other industrial applications. Evaluated consumption patterns, product performance requirements, regional demand trends, and sector specific adoption across major end use industries.
Enabled identification of the most attractive product application combinations and growth opportunities. Supported product portfolio optimization, customer targeting, and investment prioritization strategies.
Opportunity Assessment
Identification of high growth opportunities across infrastructure development, commercial and residential construction, automotive manufacturing, renewable energy projects, shipbuilding activities, industrial machinery production, and advanced manufacturing sectors.
Enabled prioritization of high return growth segments and emerging regional markets. Supported long term investment planning, capacity expansion decisions, and strategic business development initiatives aligned with evolving industry requirements.
Frequently Asked Questions About This Report
The carbon steel market size was estimated at USD 1,059.6 billion in 2025 and is expected to reach USD 1,107.2 billion in 2026.
The carbon steel market is expected to grow at a compound annual growth rate of 6.0% from 2026 to 2033 to reach USD 1,664.5 billion by 2033.
The key factor that is driving the growth of the global carbon steel market is the growing demand for infrastructure development and construction activities across emerging economies, coupled with increasing application in automotive, energy, and manufacturing sectors due to its cost-effectiveness, strength, and recyclability.
Asia Pacific dominated the market with revenue share of 67.3% in 2025.
Based on type, low iron cast accounted for largest revenue share of 90.3% in 2025.
The key players operating in the carbon steel market are AK Steel Corporation, ArcelorMittal, Baosteel Group, Evraz plc, HBIS Group, JFE Steel Corporation, Nippon Steel Corporation, NLMK, POSCO, United States Steel.
Based on application, construction accounted for largest revenue share of 40.7% in 2025, while ship building registered a CAGR of 6.2% over the forecast period.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


