
- Home
- »
- Medical Devices
- »
-
Cardiovascular Ultrasound Market Size Report, 2026-2033GVR Report cover

Cardiovascular Ultrasound Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Transthoracic Echocardiography, Fetal Echocardiography), By Technology (2D, 3D/4D, Doppler), By Display (B/W, Color), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$3.2BMarket Estimate, 2026
$3.4BMarket Forecast, 2033
$4.7BCAGR, 2026–2033
4.7%Cardiovascular Ultrasound Market Summary
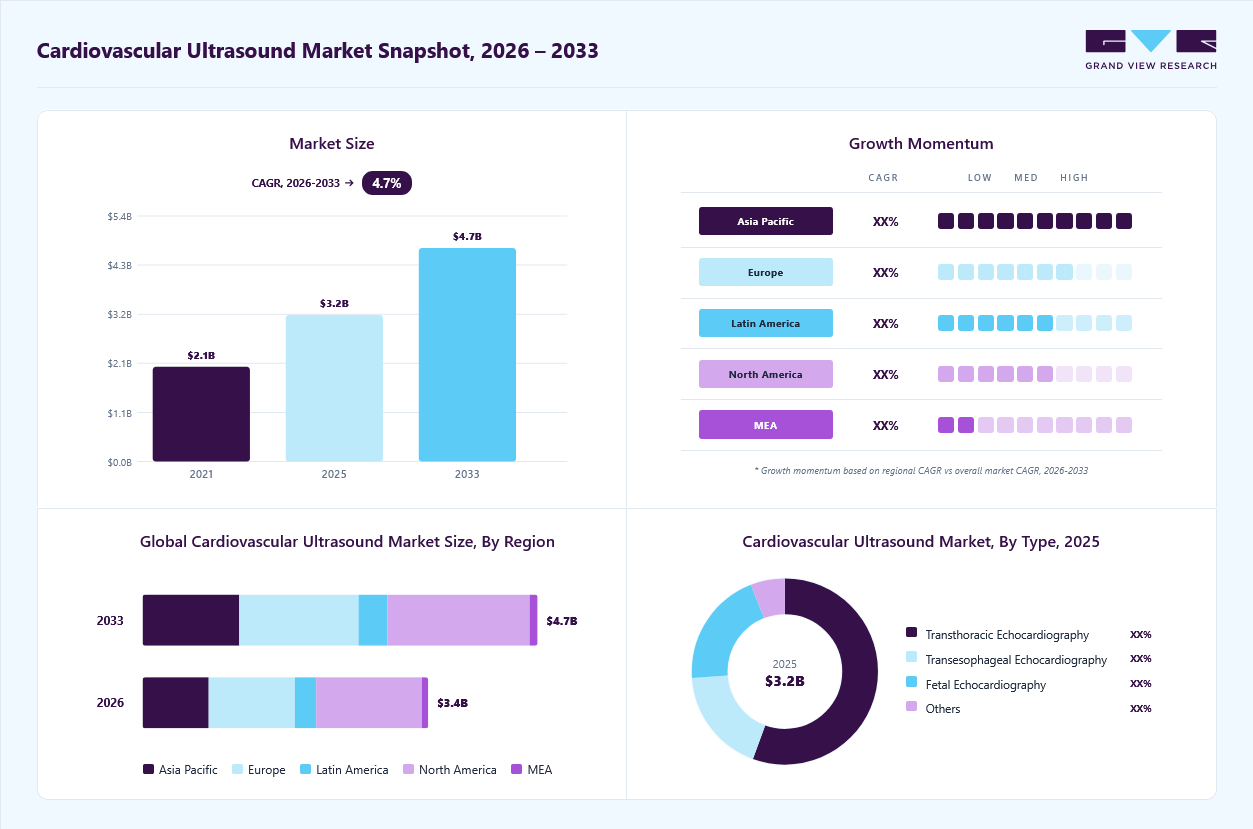
The global cardiovascular ultrasound market size was valued at USD 3.2 billion in 2025 and is projected to grow from USD 3.4 billion in 2026 to USD 4.7 billion by 2033, at a CAGR of 4.7% from 2026 to 2033. North America dominated the market with the largest revenue share of 37.1% in 2025. Major factors contributing to the market growth include the increasing prevalence of cardiovascular diseases (CVDs), which are among the leading causes of death globally.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Transthoracic echocardiography segment accounted for the largest revenue share of 55.5% in 2025.
- By technology: 3D/4D segment dominated the market with a revenue share of 36.9%in 2025.
- By display: Color segment led the market with a share of 83.8% in 2025..
- By end use: Hospitals segment accounted for the largest revenue share of 45.8% in 2025.
Regional Highlights
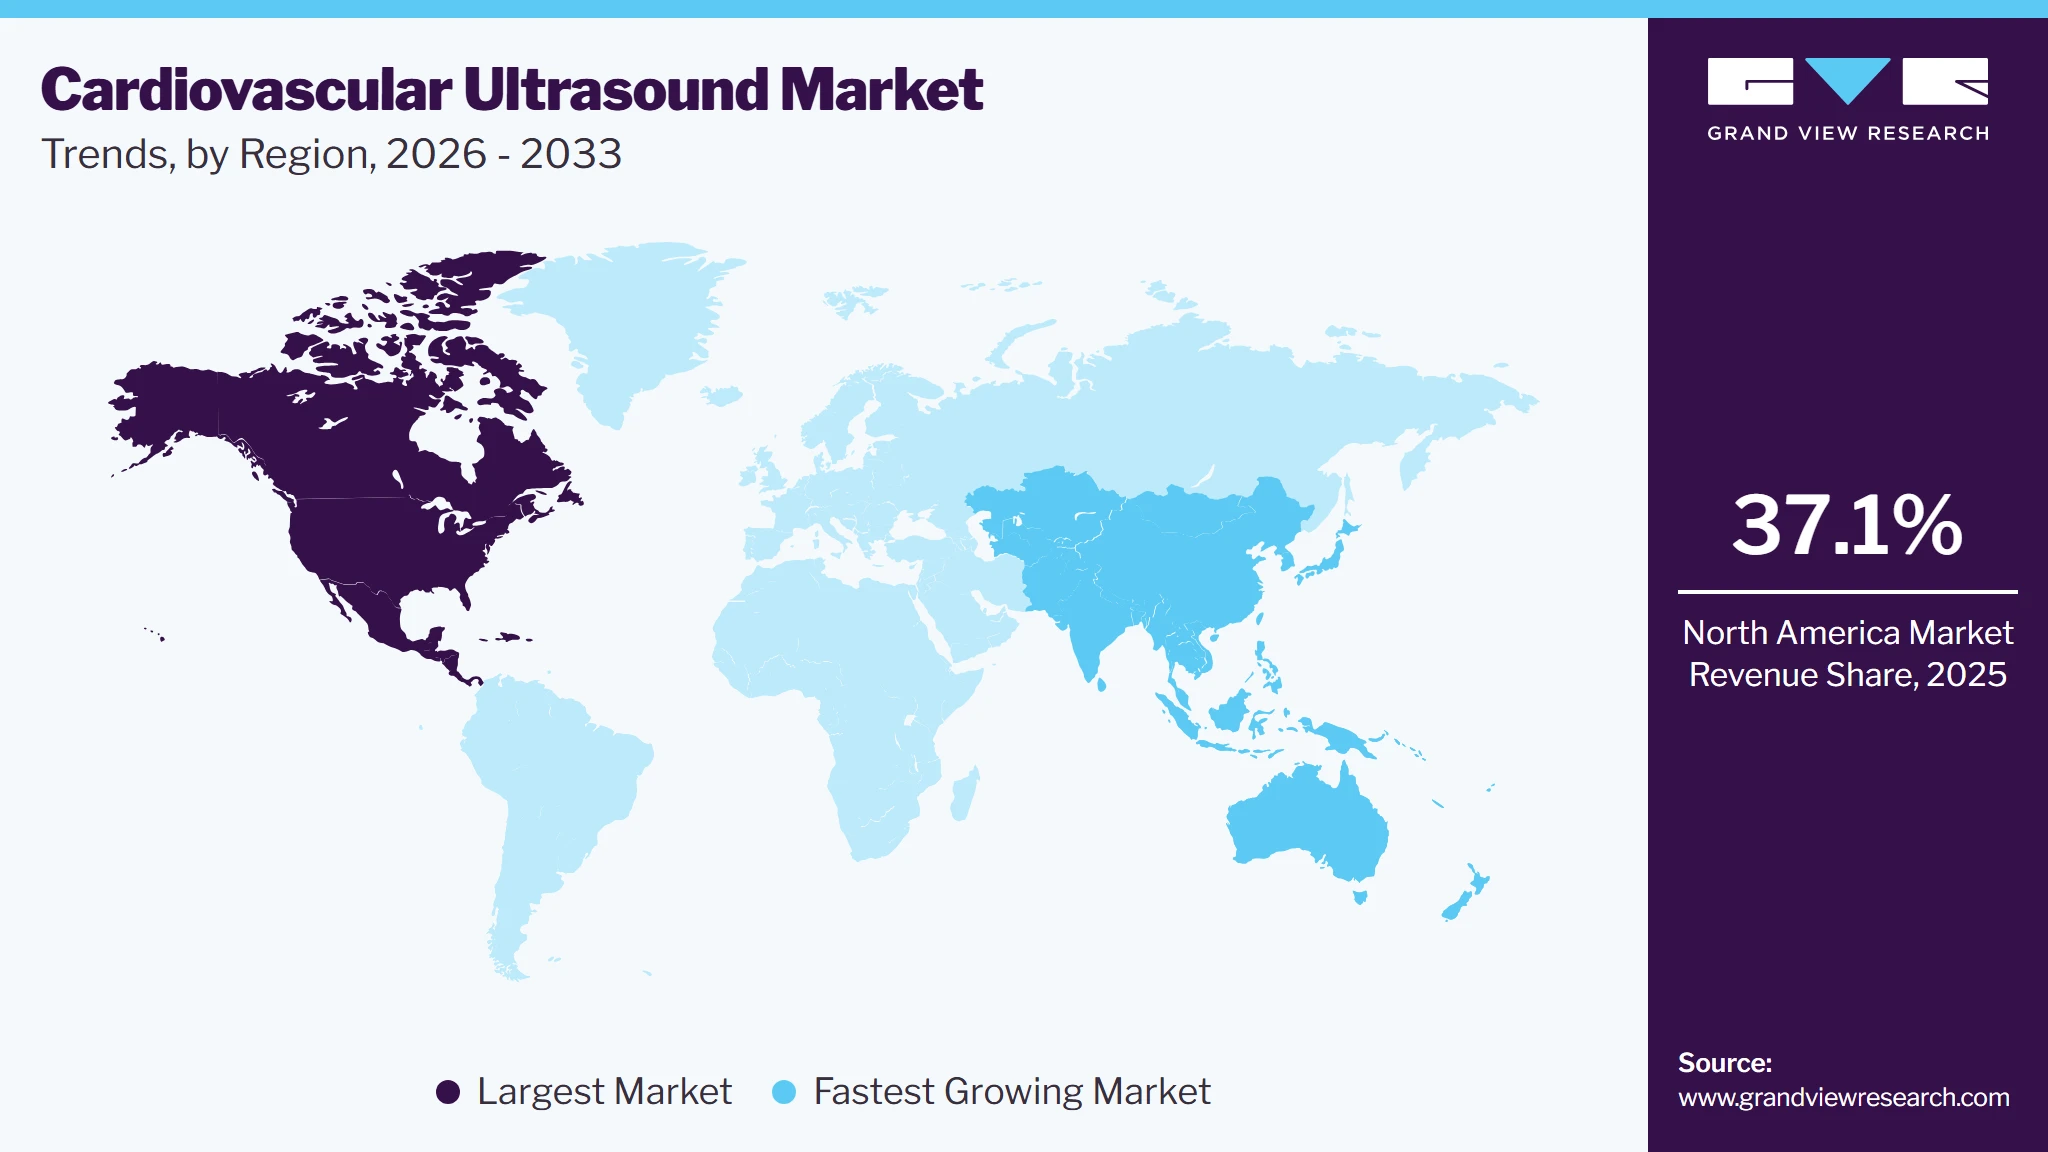
- Largest regional market: North America (37.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 3.2 Billion
- Estimated market size in 2026: USD 3.4 Billion
- Projected market size by 2035: USD 4.7 Billion
- CAGR (2026-2033): 4.7%
Prism AI by Grand View Research Free to tryAsk a question about the cardiovascular ultrasound marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Furthermore, the aging population, which is more susceptible to heart conditions, technological advancements in ultrasound imaging, growing awareness of early diagnosis and preventive healthcare, coupled with rising healthcare expenditures and government initiatives to improve healthcare infrastructure, are propelling market expansion. The increasing prevalence of cardiovascular diseases directly contributes to the growth of the ultrasound market as it increases the demand for effective, non-invasive diagnostic tools. Cardiovascular diseases are the leading cause of death worldwide, accounting for about 17.9 million deaths annually. Ultrasound, particularly cardiovascular ultrasound or echocardiography is essential for diagnosing and monitoring heart conditions, enabling early detection and intervention. As CVDs become more common, especially in aging populations, the demand for accurate, accessible, and cost-effective diagnostic methods rises. Ultrasound meets these needs by providing real-time images of the heart, helping clinicians assess heart function, detect abnormalities, and guide treatment options without the risks associated with more invasive procedures.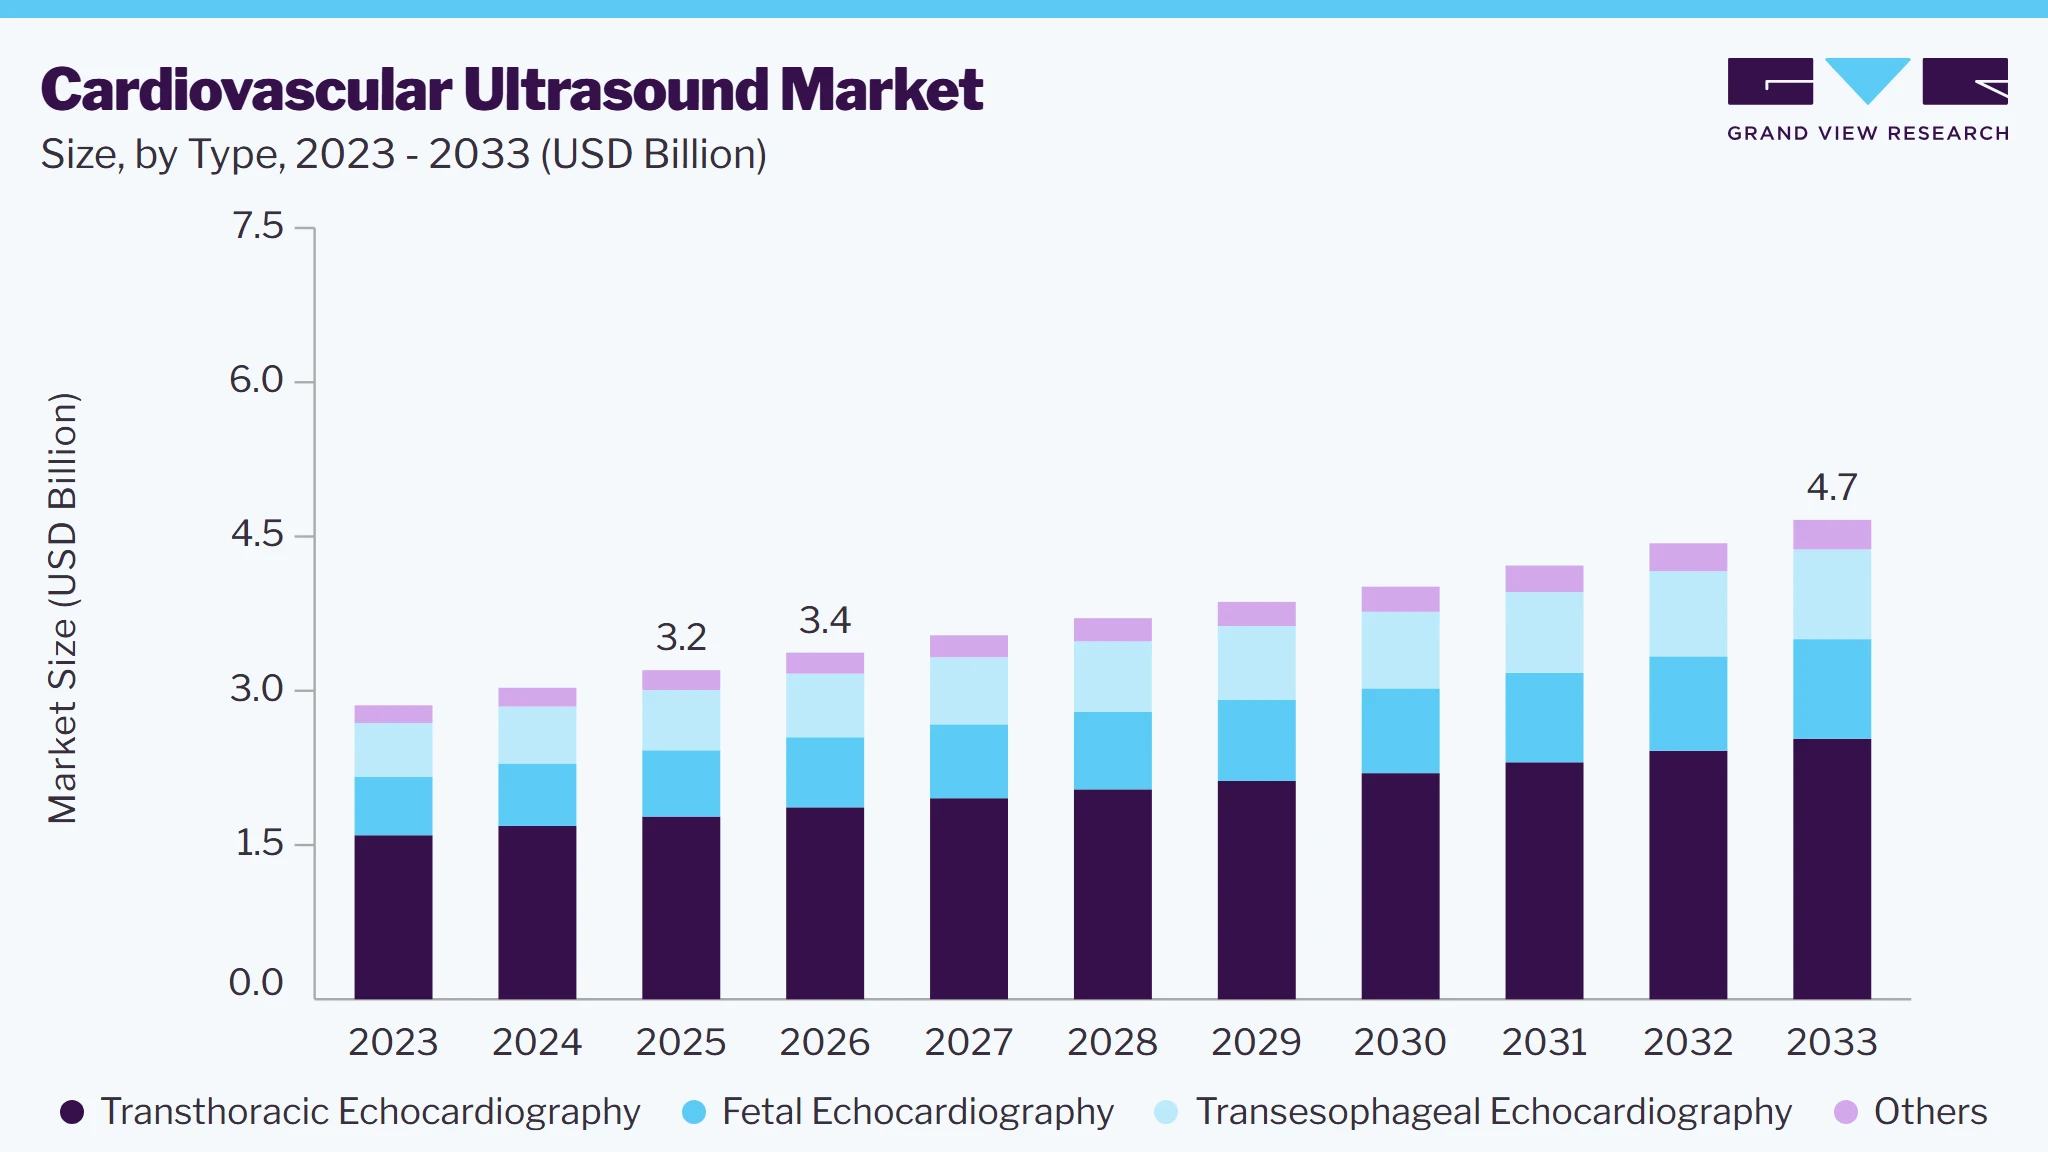 To learn more about this report, Download Free Sample Report
Technological advancements in cardiac ultrasound are further expected to significantly contribute to market growth by enhancing the capabilities and applications of cardiovascular ultrasound devices. Advancements such as 3D and 4D imaging, improved Doppler techniques, and the development of portable and handheld devices have revolutionized cardiac ultrasound, making it more accurate, efficient, and accessible. These advancements allow for better visualization of heart structures, improved assessment of cardiac function, and earlier detection of abnormalities. Additionally, the integration of artificial intelligence (AI) in ultrasound technology aids in more precise and automated interpretation of results. For instance, in June 2024, Philips unveiled its next-generation AI-powered cardiovascular ultrasound platform, designed to accelerate cardiac ultrasound analysis using advanced AI technology and alleviate the workload in echocardiography labs.
Market Dynamics
Cardiovascular ultrasound systems are gaining significant traction across diverse healthcare settings as they enable cardiologists, interventionalists, emergency physicians, and point-of-care clinicians to perform rapid, high-precision echocardiographic imaging through premium cart-based, compact portable, and specialized handheld platforms. These advanced diagnostic systems integrate cutting-edge technologies such as real-time 3D/4D volumetric imaging, multi-frequency matrix array transducers, high-frame-rate color Doppler, speckle-tracking strain analysis, and artificial intelligence (AI)-driven automated quantification to deliver exceptional structural and functional visualization of the heart and vasculature. By streamlining routine measurements and enhancing diagnostic accuracy, cardiovascular ultrasound technologies directly address the escalating global burden of cardiovascular diseases (CVDs) and structural heart conditions. They optimize clinical workflows, minimize inter-observer variability, and support critical interventional guidance.
The increasing prevalence of cardiovascular diseases (CVDs) such as ischemic heart disease, heart failure, arrhythmias, and structural heart disorders stands as a primary driver propelling the growth of the global cardiovascular ultrasound market. According to the American Heart Association 2025 report, as of 2025, approximately 612 to 640 million people worldwide were living with cardiovascular disease, highlighting the substantial global disease burden requiring ongoing diagnostic monitoring and imaging. As the leading cause of morbidity and mortality worldwide, the escalating burden of CVDs is heavily fueled by an aging global demographic and a rising incidence of lifestyle-related risk factors, including hypertension, diabetes, and obesity. This surge in patient volumes creates an unprecedented demand for reliable, non-invasive, and cost-effective diagnostic modalities. Echocardiography serves as the definitive frontline imaging tool for the early detection, comprehensive evaluation, and continuous monitoring of cardiac conditions. To keep pace with this growing clinical demand, healthcare facilities are rapidly adopting advanced cardiovascular ultrasound systems equipped with real-time 3D/4D volumetric imaging, automated strain analysis, and AI-driven quantification tools that enhance diagnostic accuracy while shortening throughout times.
The growth of the cardiovascular ultrasound market is restrained by the relatively longer examination and interpretation time associated with comprehensive echocardiography procedures. Cardiovascular ultrasound examinations, particularly advanced studies such as stress echocardiography, transesophageal echocardiography (TEE), and 3D/4D imaging, require skilled sonographers and cardiologists for image acquisition, analysis, and reporting. The procedure is often operator-dependent and can be time-consuming compared to some alternative diagnostic modalities, leading to workflow bottlenecks in high-volume healthcare settings. Additionally, increasing patient loads and shortages of trained cardiovascular imaging professionals may further limit throughput and reduce operational efficiency, thereby constraining the widespread adoption of cardiovascular ultrasound systems, especially in resource-limited healthcare facilities.
Market Concentration & Characteristics
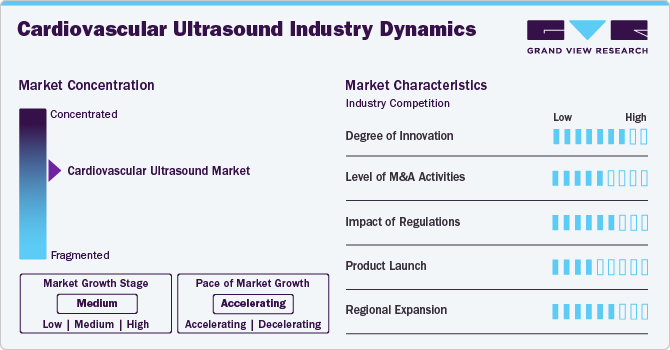
The cardiovascular ultrasound industry is experiencing moderate growth, propelled by a combination of technological advancements and increasing awareness of the importance of early diagnosis and preventive care in cardiovascular health. Innovations such as enhanced imaging techniques, portable devices, and AI integration are making ultrasound technology more accurate, efficient, and accessible, thereby expanding its clinical applications.
Leading companies in the industry are consistently involved to enhance their product portfolios to expand their customer base and capture a larger industry share. This effort includes upgrading their existing products, pursuing acquisitions, securing government approvals, and engaging in significant collaborative initiatives. For instance, in April 2024, GE HealthCare launched Caption AI on the Vscan Air SL wireless handheld ultrasound system to enable more clinicians to capture diagnostic-quality cardiac images.
 To learn more about this report, Download Free Sample Report
“With the increase of cardiovascular disease and shortage of sonographers around the globe, innovations like the Vscan Air SL with Caption AI are hugely transformative in cardiac care, supporting rapid and confident assessments at the point of care.”
"AI guidance has enormous potential in ultrasound due to its ability to guide experts and relatively new users in retrieving diagnostic-quality information to make timely and accurate decisions and get patients on the right path sooner."
- Cardiologist Jordan B. Strom, M.D., MSc.
The degree of innovation in cardiovascular ultrasound devices is remarkable, with advancements continually enhancing their capabilities. For instance, in May 2024, Siemens Healthineers introduced new cardiology applications incorporating artificial intelligence for the Acuson Sequoia ultrasound system and 4D transesophageal (TEE) transducer specifically designed for cardiology exams. These innovations hihglights the rapid progress in the field, improving diagnostic accuracy and expanding the range of clinical applications.
Companies in the cardiovascular ultrasound sector are actively pursuing mergers and acquisitions as a strategic move to strengthen their industry position, broaden their product offerings, and fuel growth. For instance, in July 2024, GE HealthCare announced an agreement to acquire Intelligent Ultrasound Group PLC’s clinical artificial intelligence (AI) software division for about USD 51 million. Intelligent Ultrasound is known for its advanced AI-driven image analysis tools that enhance the intelligence and efficiency of ultrasound imaging.
Regulations affecting cardiovascular ultrasound devices vary significantly across different regulatory agencies and regions. Key regulatory bodies, including the FDA in the U.S., the EMA in Europe, and other equivalent agencies globally, are essential in ensuring the safety, efficacy, and industry approval of these devices.
Manufacturers are actively involved in launching new products to meet evolving industry demands and technological advancements. For instance, in January 2024, Esaote introduced two new ultrasound systems at Arab Health: the MyLab A50 and MyLab A70. Featuring a compact footprint, lightweight and battery-operated design, these mobile systems are designed to meet the needs of a wide range of healthcare professionals.
The geographical reach of the cardiovascular ultrasound industry has been broadening due to population growth, increased healthcare investments, and evolving regulatory environments.
Analyst Perspective
The cardiovascular ultrasound market is positioned at the convergence of several long-term healthcare and medical imaging trends, including the rising global burden of cardiovascular diseases, increasing demand for non-invasive diagnostic procedures, and continuous advancements in ultrasound imaging technologies. Growing prevalence of conditions such as coronary artery disease, heart failure, valvular heart disorders, congenital heart defects, and hypertension is creating significant demand for accurate, real-time cardiac imaging solutions. Cardiovascular ultrasound systems, including echocardiography platforms and Doppler imaging technologies, are increasingly utilized across hospitals, cardiac centers, outpatient facilities, and emergency departments for disease diagnosis, treatment planning, and patient monitoring. Furthermore, ongoing innovations such as AI-assisted image analysis, 3D/4D echocardiography, portable ultrasound systems, and enhanced visualization capabilities are improving diagnostic accuracy and workflow efficiency.
Type Insights
Based on type, the transthoracic echocardiography segment led the market with the largest revenue share of 55.5% in 2025. TTE is a non-invasive imaging method that delivers real-time, high-quality images of the heart’s structures and functions, making it crucial for diagnosing and managing various cardiovascular conditions. Its widespread use is fueled by its user-friendliness, cost-effectiveness, and the convenience of performing it at the bedside, especially beneficial in critical care environments. Moreover, advancements in TTE technology, including enhanced image resolution and improved Doppler capabilities, have increased its adoption among clinicians.
The Fetal Echocardiography segment is expected to grow at the fastest rate over the forecast period. This is due to increasing awareness of the importance of prenatal cardiac screening and advancements in imaging technology. As more expectant parents and healthcare providers recognize the benefits of early detection of congenital heart defects, the demand for detailed and accurate fetal heart assessments rises. Advances in fetal echocardiography, such as enhanced imaging techniques and greater resolution, allow for more precise evaluations of fetal heart health. Additionally, guidelines and recommendations from medical practitioners now emphasize routine fetal echocardiography for high-risk pregnancies, further driving its adoption.
Technology Insights
Based on technology, the 3D/4D segment led the market with the largest revenue share of 36.9%in 2025. This is primarily attributed to its advanced capabilities in providing detailed blood flow and velocity measurements. Doppler imaging techniques, such as Doppler ultrasound, offer significant advantages in diagnosing and monitoring various cardiovascular and ophthalmic conditions by allowing precise visualization of blood flow dynamics. This increased diagnostic accuracy and efficiency have driven the widespread adoption of Doppler technology in medical imaging. Additionally, ongoing advancements in Doppler technology, including improvements in sensitivity and resolution, are further expected to contribute to the market growth.
The 3D/4D segment is also expected to grow at a significant level over the forecast period, this is primarily due to its ability to provide detailed and dynamic imaging of the heart's structure and function. Unlike traditional 2D ultrasound, 3D/4D imaging offers comprehensive three-dimensional views and real-time visualization of cardiac anatomy, which enhances diagnostic precision and aids in the assessment of complex cardiovascular conditions. The advanced imaging capabilities of 3D/4D technology facilitate more accurate evaluations of cardiac chamber volumes, valve function, and blood flow dynamics, leading to improved clinical decision-making and patient outcomes. Additionally, the increasing demand for non-invasive, high-resolution imaging techniques and technological advancements in 3D/4D ultrasound systems are driving segment growth.
Display Insights
Based on display, the color segment led the market with the largest revenue share of 83.8% in 2025 and it is expected to witness the fastest CAGR over the forecast period. This is primarily attributed to its superior ability to visualize and assess blood flow dynamics within the heart and vascular system. These devices provide real-time, color-coded images that represent blood flow direction and velocity, enhancing the accuracy and interpretability of cardiovascular assessments. This capability is essential for diagnosing and monitoring a range of cardiovascular conditions, from congenital heart defects to valvular diseases. The widespread adoption of color Doppler technology is driven by its effectiveness in delivering detailed, non-invasive insights that support precise clinical evaluations and treatment planning.
B/W cardiac ultrasound, commonly known as 2D echocardiography, is a fundamental tool in cardiology. It delivers detailed grayscale images that help clinicians evaluate various aspects of cardiac anatomy, including chamber sizes, wall motion, and overall heart function. Despite the advancements in color Doppler and 3D/4D imaging technologies, B/W cardiac ultrasound is known for its simplicity, speed, and effectiveness in providing clear, real-time images. Its ability to assess cardiac structures without the additional complexity of color flow information makes it a dependable option for initial evaluations, routine assessments, and certain clinical decisions.
End-use Insights
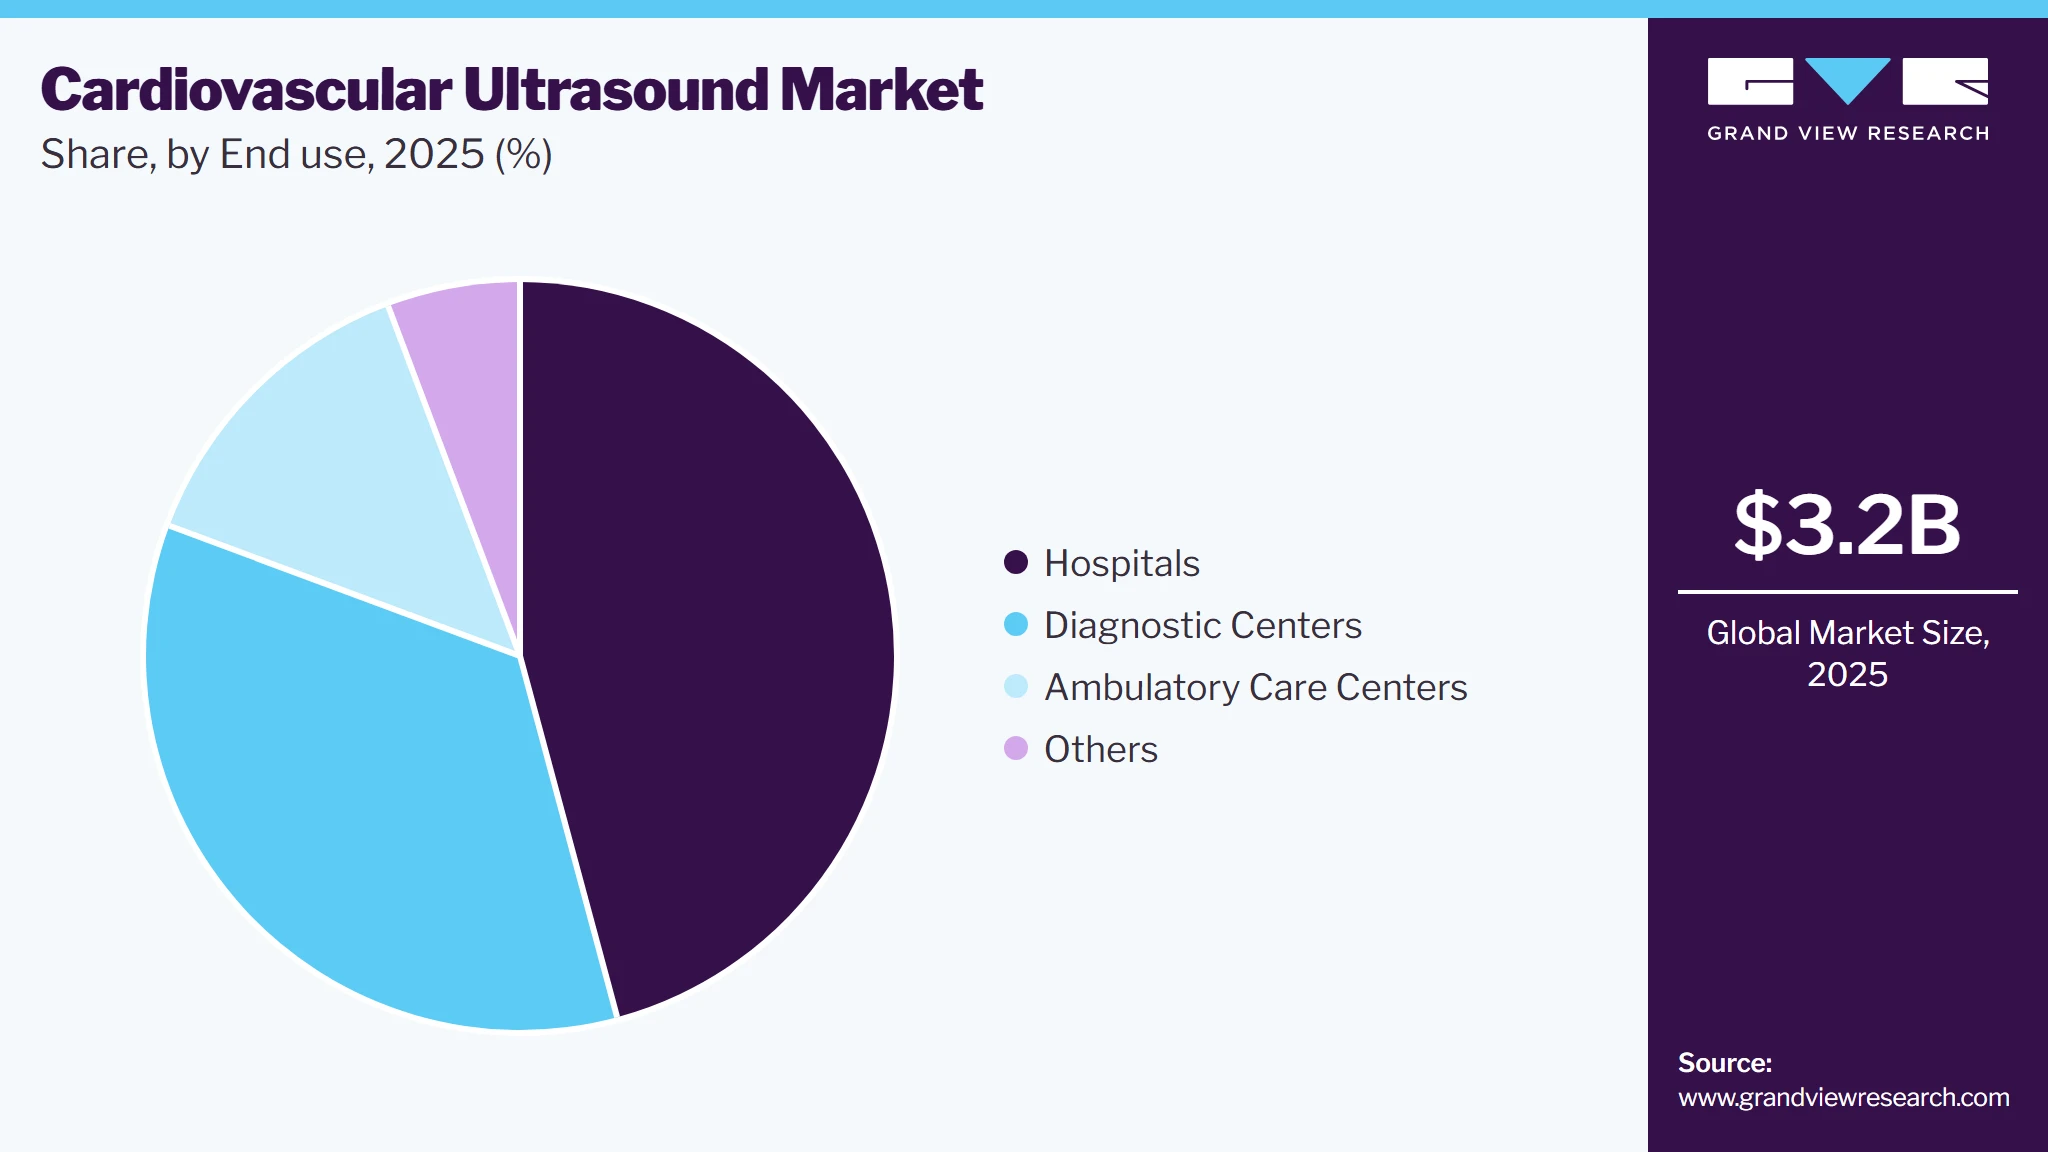
Based on end use, the hospitals segment led the market with the largest revenue share of 45.8% in 2025. This dominance is attributed to several factors, including the increasing number of outpatient department (OPD) visits and hospital admissions. Hospitals are central to cardiovascular care, offering a range of specialized diagnostic services that require advanced ultrasound technology. The growing prevalence of cardiovascular diseases, coupled with the rising demand for comprehensive diagnostic and monitoring services, has led to more frequent use of ultrasound imaging in hospital settings.
 To learn more about this report, Download Free Sample Report
The ambulatory care centers segment is expected to grow at the fastest CAGR over the forecast period, due to their ability to offer convenient, cost-effective diagnostic services in a less invasive setting compared to traditional hospitals. These centers are designed to provide specialized care with a focus on efficiency and patient convenience, allowing for quicker, outpatient-based procedures. The increasing preference for outpatient care, driven by its lower costs and reduced need for hospital admission, is fueling this growth. Additionally, advancements in portable and compact ultrasound technologies make it feasible for ambulatory care centers to perform high-quality cardiovascular imaging, further boosting their adoption.
Regional Insights
North America dominated the cardiovascular ultrasound market with the largest revenue share of 37.1% in 2025. This can be attributed to the presence of a robust healthcare infrastructure that facilitates the widespread adoption of advanced medical technologies, including cardiovascular ultrasound. Furthermore, market participants are introducing advanced cardiovascular ultrasound devices to address the increasing demand.
 To learn more about this report, Download Free Sample Report
U.S. Cardiovascular Ultrasound Market Trends
The cardiovascular ultrasound market in the U.S. held the largest share in the North America region in 2025. This is owing to the increasing prevalence of cardiovascular diseases, coupled with a strong focus on early diagnosis and preventive care. For instance, according to the CDC, in 2022, heart disease caused the deaths of 702,880 individuals in the U.S. The presence of major medical device manufacturers and ongoing innovation in cardiovascular ultrasound technology further contribute to the market growth.
Europe Cardiovascular Ultrasound Market Trends
The cardiovascular ultrasound market in Europe held a significant market share in 2025. Europe's aging population and the rising incidence of cardiovascular diseases are driving the growing demand for precise and early diagnostic devices. According to the WHO, cardiovascular diseases (CVDs) are the leading cause of disability and premature death in the European Region, accounting for over 42.5% of all deaths annually equivalent to around 10,000 deaths each day. This high burden of disease, combined with a strong focus on preventive healthcare and early detection, is accelerating the adoption of advanced diagnostic technologies throughout the region.
UK cardiovascular ultrasound market is anticipated to expand due to the increasing emphasis on early diagnosis and management of cardiovascular conditions, supported by advancements in imaging technology and growing healthcare investments.
The cardiovascular ultrasound market in France is expected to grow over the forecast period due to the technological advancements that enhance diagnostic capabilities and improve patient outcomes. Innovations such as high-resolution imaging, 3D/4D ultrasound, and advanced Doppler techniques are driving the adoption of more precise and efficient cardiovascular diagnostic tools.
Germany cardiovascular ultrasound marketis expected to grow over the forecast period this can be attributed to the country’s advanced healthcare infrastructure and strong emphasis on integrating innovative medical technologies into clinical practice. Government initiatives and funding aimed at improving cardiovascular care and enhancing diagnostic capabilities further support market growth.
Asia Pacific Cardiovascular Ultrasound Market Trends
The cardiovascular ultrasound market in Asia Pacific is estimated to witness the fastest CAGR of 5.5% during the forecast period, primarily due to the rapid expansion of healthcare infrastructure and increasing investments in advanced medical technologies across the region. The growing prevalence of cardiovascular diseases, driven by rising urbanization, lifestyle changes, and an aging population, is fueling demand for effective diagnostic tools. Additionally, the rising emphasis on improving healthcare access and quality, combined with the adoption of advanced ultrasound technologies and increasing healthcare expenditures, contributes to the market growth.
China cardiovascular ultrasound market is expected to grow over the forecast period, driven largely by the increasing incidence of cardiac diseases across the country. For instance, the World Heart Federation reports that approximately one in five adults in China suffers from cardiovascular disease. China has one of the highest rates of cardiovascular disease-related deaths globally.
The cardiovascular ultrasound market is expected to grow, over the forecast period. This growth is mainly driven by increasing awareness about cardiovascular disease and the benefits of cardiovascular ultrasound devices in the country.
Latin America Cardiovascular Ultrasound Market Trends
The cardiovascular ultrasound market in Latin America is expected to see moderate growth during the forecast period, largely due to rising investments in healthcare infrastructure throughout the region. This encompasses the expansion and modernization of hospitals and diagnostic centers, which improves access to advanced cardiovascular imaging services and drives demand for advanced ultrasound technology.
MEA Cardiovascular Ultrasound Market Trends
The cardiovascular ultrasound market in the Middle East and Africa (MEA) is anticipated to witness growth due to various factors. These include increasing investments in healthcare infrastructure, the expansion of medical facilities, and advancements in diagnostic technology across the region. Additionally, a growing focus on improving healthcare services and addressing the rising prevalence of cardiovascular diseases are contributing to the increased demand for advanced cardiovascular ultrasound solutions. The efforts to enhance healthcare accessibility and quality in MEA are further driving the market's growth.
Key Cardiovascular Ultrasound Company Insights
Major players in the cardiovascular ultrasound market are actively enhancing their product portfolios through various strategies to remain competitive and expand their market share. These strategies include continuous product upgrades to incorporate the latest technological advancements, strategic collaborations, and exploring opportunities for acquisitions. Additionally, obtaining government approvals for their products is crucial to ensure compliance with regulatory standards.
Key Cardiovascular Ultrasound Companies
The following key companies have been profiled for this study on the cardiovascular ultrasound market.
-
Koninklijke Philips N.V.
-
GE Healthcare
-
Siemens Healthineers AG
-
Canon Medical Systems
-
Mindray Medical International Limited
-
Samsung Medison Co., Ltd.
-
FUJIFILM SonoSite, Inc.,
-
Konica Minolta Inc.
-
Esaote
-
Trivitron Healthcare
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Koninklijke Philips N.V., GE Healthcare, Siemens Healthineers AG, Canon Medical Systems Player)
- Focus on expanding premium echocardiography portfolios including advanced cart-based 3D/4D volume systems, transesophageal echocardiography (TEE) probes, and AI-automated measurement solutions for structural heart diseases, heart failure, and coronary artery disease tracking.
- Emphasize strategic partnerships and enterprise-level contracts with major hospital networks, specialized cardiac centers, research institutes, and university clinics to secure long-term system replacements, multi-year servicing agreements, and continuous software licensing updates.
- Strong brand recognition, massive global distribution networks, and deep-seated institutional trust within cardiology departments worldwide support enduring market leadership.
- Extensive R&D investment capabilities and continuous software innovation help mature firms maintain premium market positioning across both high-resource and emerging healthcare markets.
- High manufacturing, compliance, and clinical trial costs associated with securing stringent global regulatory clearances (e.g., US FDA, EU MDR) for complex diagnostic and interventional cardiac imaging modalities increase operational overhead.
- Slower, bureaucratic innovation cycles mean larger, established corporations often take longer to pivot toward or integrate highly agile, niche point-of-care disruptions compared to smaller tech firms.
Emerging Players (Konica Minolta Inc., Trivitron Healthcare, Esaote)
- Focus on niche, highly portable, and cost-effective handheld cardiac ultrasound solutions targeting point-of-care ultrasound (POCUS) settings, emergency departments, intensive care units (ICUs), and ambulatory/remote cardiac clinics.
- Prioritize software-driven, AI-guided acquisition strategies featuring simplified, step-by-step user interfaces, cloud-based tele-echocardiography sharing, and automatic view recognition to enable non-cardiologist clinicians to perform rapid basic cardiac scans.
- Faster product iteration cycles and flexible, software-centric development models allow emerging firms to integrate new AI measurement features and deploy mobile application updates rapidly.
- The escalating global trend toward decentralized point-of-care medicine and remote cardiac monitoring opens significant commercial opportunities for highly accessible, technically differentiated, smartphone-compatible imaging devices.
- Limited financial reserves, minimal initial brand equity, and smaller specialized sales teams restrict their ability to scale rapidly, win large hospital enterprise tenders, or compete directly on massive global infrastructure projects.
- Complex clinical validation hurdles and lengthy regulatory approval processes for specialized automated cardiac measurement software can severely delay product launch timelines and slow down international commercial adoption.
Recent Developments
-
In August 2024, the FDA cleared UltraSight’s AI-powered cardiac ultrasound software. This real-time AI guidance tool helps medical professionals without sonography experience capture cardiac ultrasound images at the point of care across various settings. It enables broader detection of heart disease and offers patients improved access to cardiac monitoring.
-
In February 2024, FUJIFILM India announced the launch of the ALOKA ARIETTA 850 Diagnostic Ultrasound System in India, with its inaugural installation at Fortis Hospital in Bengaluru, Karnataka, a leading healthcare services provider in the state.
-
In April 2022, Trivitron Healthcare, a leading global manufacturer of medical devices, established its second ultrasound manufacturing facility in India, located in the Patalganga Industrial Area, Mumbai.
Cardiovascular Ultrasound Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 3.2 billion
Estimated market size in 2026
USD 3.4 billion
Projected market size by 2033
USD 4.7 billion
Growth rate
CAGR of 4.7% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, technology, display, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Mexico; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
Koninklijke Philips N.V.; GE Healthcare; Siemens Healthineers AG; Canon Medical Systems; Mindray Medical International Limited; Samsung Medison Co., Ltd.; FUJIFILM SonoSite, Inc.; Konica Minolta Inc.; Esaote, Trivitron Healthcare
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cardiovascular Ultrasound Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global cardiovascular ultrasound market report on the basis of type, technology, display, end-use, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Transthoracic echocardiography
-
Transesophageal echocardiography
-
Fetal echocardiography
-
Others
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
2D
-
3D/4D
-
Doppler
-
-
Display Outlook (Revenue, USD Million, 2021 - 2033)
-
B/W
-
Color
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital
-
Diagnostic centers
-
Ambulatory care centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
Segment Definition
Segment - Type
Revenue capture definition
Transthoracic Echocardiography
Revenue is generated through the sale of non-invasive ultrasound systems (both cart-based and premium portable consoles) used for standard chest-wall cardiac imaging. Manufacturers earn revenue from high-volume hardware sales, specialized adult and pediatric phased-array transducers, embedded automated measurement software (e.g., ejection fraction and strain imaging), and long-term service maintenance contracts.
Transesophageal Echocardiography
Revenue is derived from specialized, semi-invasive endoscopic ultrasound probes designed to visualize cardiac structures from within the esophagus. Market participants capture high-margin revenue from complex multiplane and 3D TEE probes, single-use disposable acoustic sheath consumables, dedicated automated valve-modeling software, and premium repair or replacement services due to the delicate mechanical nature of the probes.
Fetal Echocardiography
Revenue flows from high-resolution ultrasound systems optimized for detailed structural and hemodynamic evaluation of the fetal heart in utero. Income is driven by premium high-frequency curved-array or matrix volume probes, advanced early-gestation fetal cardiac software packages, spatial-temporal image correlation (STIC) technology licenses, and specialized maternal-fetal medicine clinical reporting tools.
Others
Revenue is captured from alternative or niche cardiac imaging modalities, including Intracardiac Echocardiography (ICE) and Stress Echocardiography. Providers generate income through high-value single-use disposable ICE catheters, specialized stress-test treadmill/bicycle hardware integrations, automated wall-motion scoring software, and contrast-enhanced ultrasound (CEUS) imaging licenses.
Segment - Technology
Revenue capture definition
2D
Revenue is generated through structural cross-sectional imaging systems that deliver fundamental grayscale, two-dimensional anatomical views of the heart chambers, walls, and valves. Revenue is sustained through entry-to-mid-tier console sales, basic multi-frequency transducers, and core image-optimization software packages.
3D/4D
Revenue is derived from premium, high-fidelity systems capable of capturing static three-dimensional (3D) structures or real-time moving (4D) volumes of the beating heart. Companies monetize via high-cost matrix-array transducers, heavy-compute processing hardware, advanced volumetric quantification software (e.g., automated 3D chamber quantification, structural heart intervention guidance), and recurring software sub-licenses.
Doppler
Revenue flows from systems integrated with Spectral, Continuous Wave (CW), Pulsed Wave (PW), and Tissue Doppler Imaging (TDI) to assess blood flow dynamics and myocardial tissue velocity. Value is captured through advanced hemodynamic calculation software bundles, multi-frequency Doppler-dedicated pencil probes, and specialized automated valvular regurgitation/stenosis assessment tools.
Segment - Display
Revenue capture definition
B/W
Revenue is derived from essential, cost-effective imaging platforms that rely purely on high-contrast structural grayscale displays for anatomical modeling. Revenue streams are concentrated on low-to-mid-tier hardware units, standard high-definition monitors, and core structural measurement tools primarily targeted at emerging markets or basic triaging clinics.
Color
Revenue is generated through advanced systems capable of real-time Color Flow Mapping (CFM) superimposed onto 2D or 3D anatomical structures to visually track blood flow direction and turbulence. Manufacturers maximize returns on high-performance graphics-processing hardware, high-end color-calibrated medical displays, and advanced color-Doppler software packages optimized for complex congenital and valvular heart disease analysis.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is secured through large-scale, high-value institutional procurement tenders, multi-year department fleet upgrades, and enterprise-level service level agreements (SLAs). Vendors capture steady income from premium cart-based installations in Echo Labs, ICUs, and Operating Rooms, alongside enterprise-wide PACS/Cardiovascular Information System (CVIS) data-integration software licenses.
Diagnostic Centers
Revenue is generated from high-throughput, dedicated imaging facilities prioritizing efficient patient turnover and diverse diagnostic capabilities. Revenue focus is placed on mid-to-premium tier systems, robust automated measurement software designed to reduce clinician scanning time, comprehensive digital reporting packages, and standard extended hardware warranties.
Ambulatory Care Centers
Revenue flows from outpatient surgical and diagnostic clinics requiring high-performance, compact, or space-saving systems. Income is driven by premium portable or laptop-style consoles, versatile multi-application probe bundles, scalable financing or leasing models, and cloud-based image storage and sharing subscriptions.
Others
Revenue is captured from decentralized or emerging care settings, including private cardiology practices, point-of-care emergency medical response (EMS), and academic/clinical research institutions. Market participants capitalize on highly tailored clinical software, direct-to-physician sales models, and specialized research-grade imaging software licenses.
Estimation Model
Step Title
Guiding Question
Process Steps
Data Sources
Scope Definition
What is being sized?
Define cardiovascular ultrasound product categories - Segment by technology - Define clinical applications - Establish geographic coverage and forecast period (2020-2030)
WHO, World Heart Federation, cardiovascular disease registries, healthcare statistics databases
Build the Product Base
How large is total addressable market?
Profile hospitals, cardiac centers, specialty cardiology clinics, and ambulatory care facilities - Estimate installed base of cardiovascular ultrasound systems by facility - Assess annual cardiovascular diagnostic procedure volumes - Model replacement cycles, equipment upgrade rates, and new facility additions
Healthcare facility databases, government ministries, company annual reports
Estimate Penetration
What portion is transitioning to advanced cardiovascular imaging systems?
Evaluate adoption of premium echocardiography platforms and AI-enabled imaging solutions - Assess penetration of portable and handheld cardiovascular ultrasound devices - Analyze transition from conventional 2D echocardiography toward 3D/4D and Doppler technologies - Measure utilization across developed and emerging markets
Physician surveys, company presentations, regulatory databases
Revenue Conversion
How do procedure volumes and equipment sales become market revenue?
Determine average selling prices (ASPs) by product type and technology tier - Estimate revenue from new equipment sales, upgrades, and service contracts - Allocate revenue across hospitals, cardiac centers, and outpatient facilities - Triangulate and validate
Annual reports, procurement databases, distributor pricing data, primary interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Added
Competitive Landscape Analysis
Conducted a comprehensive competitive landscape assessment for the global cardiovascular ultrasound market, covering major manufacturers offering premium cart-based systems, portable/handheld echocardiography devices, and advanced structural heart imaging solutions. The study visualized company profiling, product portfolios (including 2D/3D/4D trans-thoracic and transesophageal echocardiography systems), regulatory approvals, strategic collaborations, distribution partnerships, technological advancements in automated strain imaging, AI-assisted measurement, and expansion initiatives in hospitals, specialized cardiology clinics, ambulatory surgical centers, and emergency cardiac care units. The analysis also assessed innovation trends associated with cloud-based PACS integration, tele-echocardiography capabilities, and automation workflow optimization adopted by leading market participants.
Enables stakeholders to understand the competitive landscape, technological positioning, and strategic development shaping the cardiovascular ultrasound market. The analysis assists in benchmarking product portfolios, identifying opportunities for differentiation, innovation investments, and regional market expansion. Also helps stakeholders identify potential collaboration and innovation gaps (such as AI-driven automation, cloud integration) across diagnostic and interventional cardiology applications globally.
Segment Analysis
Conducted a detailed segment-level assessment of the cardiovascular ultrasound market across product categories including cart-based ultrasound systems, portable/handheld cardiovascular systems, and handheld echocardiography devices, alongside the technology types (2D, 3D/4D, and Doppler imaging). The study evaluated adoption trends among end users including hospitals, diagnostic imaging centers, specialized cardiac clinics, and ambulatory care centers. It further analyzed pricing trends, premium value tiers, strategic pricing strategies, software integration capabilities (such as automated strain, real-time calculation, virtual heart intervention alignment), premium vs. mid-tier product differentiation, procurement, and regional demand variations influencing segment growth globally.
Enables stakeholders to gain granular insights into high-growth market segments, open gaps, and opportunities for differentiation on monetization and product positioning. The analysis supports market expansion planning, targeted go-to-market strategies, business model optimization, and investment prioritization across diagnostic cardiology domains and the rising trend for specialized cardiac care.
Key Market Drivers Analysis
Conducted an in-depth driver analysis focused on the rising global prevalence of cardiovascular diseases (CVDs), the heart failure and coronary artery disease aging population, and the increasing volume of structural heart interventions (such as TAVR/MVR) requiring intraoperative guidance. The study evaluated trends associated with AI-based strain imaging, learning-based reproducible cardiac measurements, and the demand for minimally invasive procedures, rising adoption of 3D/4D volumetric imaging, and the growing preference for point-of-care cardiac assessment methods. Also evaluated the impact of ergonomic system designs, cloud-enabled cardiac image sharing, and clinician preference for advanced 4D volume imaging in complex diagnostic decision-making.
Enables stakeholders to understand the core clinical, technological, and economic drivers influencing market growth within the cardiovascular ultrasound market. The study supports product innovation strategies, regional market expansion, and cross-integration strategies aligned with evolving care networks, regulatory shifts, and global diagnostic adoption trends.
Frequently Asked Questions About This Report
The global cardiovascular ultrasound market size was estimated at USD 3.2 billion in 2025 and is expected to reach USD 3.4 billion in 2026.
Some of the key market players are Koninklijke Philips N.V.; GE Healthcare; Siemens Healthineers AG; Canon Medical Systems; Mindray Medical International Limited; Samsung Medison Co., Ltd.; FUJIFILM SonoSite, Inc.; Konica Minolta Inc.; Esaote, Trivitron Healthcare
Increasing cardiovascular diseases which has led to an increased demand for diagnostic tools, such as cardiovascular ultrasound, to detect and monitor cardiovascular disease
In 2025, North America dominated the market, accounting for 37.1% of revenue. The market's growth in the region is driven by rising cardiovascular disease rates.
Asia Pacific is the fastest-growing region over the forecast period.
3D/4D accounted for the largest revenue share of 36.9% in 2025.
The color segment led the market with the largest revenue share of 83.8% in 2025
Hospitals accounted for the largest revenue share of 45.8% in 2025, while ambulatory care centers segment are the fastest-growing sector.
The global cardiovascular ultrasound in healthcare market is expected to grow at a compound annual growth rate of 4.7% from 2026 to 2033 to reach USD 4.7 billion by 2033.
By type, the transthoracic echocardiography segment led with a 55.5% revenue share in 2025, while fetal echocardiography segment is the fastest-growing segment.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


