
- Home
- »
- Biotechnology
- »
-
Cell And Gene Therapy Manufacturing Market Report, 2033GVR Report cover

Cell And Gene Therapy Manufacturing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Therapy Type, By Scale (R&D), By Mode, By Workflow (Vector Production, Cell Banking), By Region, and Segment Forecasts
Market Size, 2025
$17.5BMarket Estimate, 2026
$21.0BMarket Forecast, 2033
$75.1BCAGR, 2026–2033
19.9%Cell And Gene Therapy Manufacturing Market Summary
The global cell and gene therapy manufacturing market size was valued at USD 17.5 billion in 2025 and is projected to grow from USD 21.0 billion in 2026 to USD 75.1 billion by 2033, growing at a CAGR of 19.9% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 47.0% in 2025. The emergence of advanced therapies has played a key role in transforming the treatment pattern of several life-threatening and rare diseases and in reshaping the biopharmaceutical industry.
Key Market Trends & Insights
- By workflow, Process development segment dominated the market, with a revenue share of more than 17.0% in 2025.
- By therapy type: Cell therapy manufacturing segment dominated the market, with a revenue share of more than 60.0% in 2025.
- By scale: Pre-commercial/R&D scale manufacturing segment dominated the market, with a revenue share of more than 70.0% in 2025.
- By mode: Contract manufacturing segment dominated the market, with a revenue share of more than 66.0% in 2025.
Regional Highlights
- Largest regional market: North America (47.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 17.5 Billion
- Estimated market size in 2026: USD 21.0 Billion
- Projected market size by 2033: USD 75.1 Billion
- CAGR (2026-2033): 19.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
A significant growth in demand is primarily driven by a shift in the approach of the healthcare industry, from managing symptoms to targeting the root cause of the condition or disease. The ability of CGTs to provide lasting results in a single administration, through editing, replacing, or augmenting genes, is highly preferred over the lifetime of medications. In addition, the growing prevalence of chronic diseases such as cancer and rare diseases has also contributed to increasing demand for targeted interventions.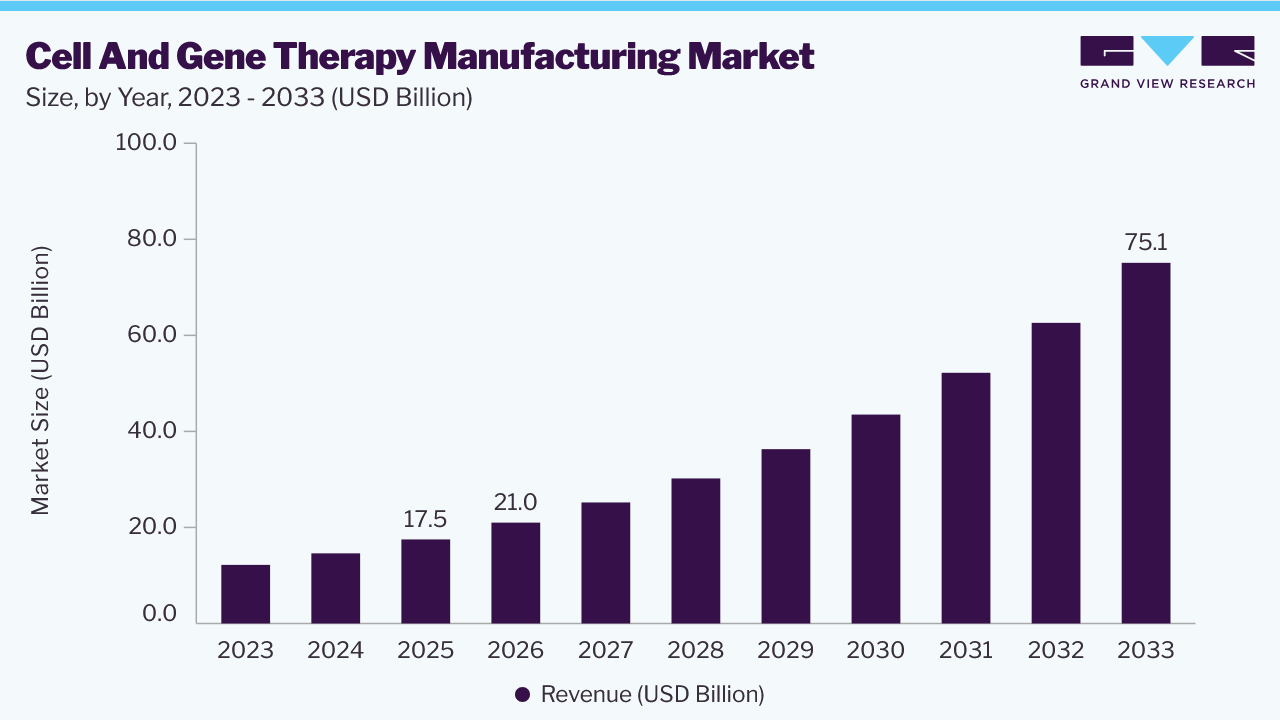 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The rapid growth of the advanced therapy landscape is a key driving factor for the growth of the cell and gene therapy manufacturing market. The COVID-19 pandemic also served as a driving factor for market growth. Several companies expanded their production capabilities for vector production as well as undertook various strategic initiatives to produce investigational therapies. For instance, in April 2022, BioCardia Inc. declared that the FDA approved the company’s IND applications for COVID-19 stem cell therapy for the treatment of patients recovering from Acute Respiratory Distress due to SARS-CoV-2.
Over the past few years, the healthcare industry has witnessed an improved ratio of clinical success to the number of clinical trials of cellular & gene-modified therapy products. This can be attributed to a better scientific and clinical understanding of safety risks related to the application of these products. As of May 2022, 329 cell and gene therapies are under clinical trial and are expected to increase significantly in the coming years.
Significant investments by government authorities and key market players are other factors fueling growth for cell and gene therapy manufacturing. Around USD 2.3 billion was invested in gene therapy companies over the last decade. This significantly high amount indicates that global pharmaceutical and biotechnology companies are investing in leading gene therapy companies. Major service providers, including CDMOs/CMOs, and in-house manufacturers consider gene & cell therapy as an active area of investment.
Market Dynamics
The transition of the healthcare industry from symptom management to interventions to address root cause, increasing demand for this approach and associated products in the treatment of chronic diseases such as cancer, spinal muscular atrophy, and others, and a massive active pipeline, mainly associated with aggressive cancers, are anticipated to drive market growth. According to an article published in CA: A Cancer Journal for Clinicians, Volume 76, Issue 1, in January 2026, by Wiley Periodicals LLC on behalf of the American Cancer Society, ACS estimated 2.1 million new cancer diagnoses in the U.S. in 2026. Such statistics indicate that demand for efficient cell and gene therapy manufacturing is expected to increase significantly in the coming years.
In recent years, improved scientific and clinical understanding of safety risks related to the application of gene and cell therapy products for various diseases has resulted in increasing number of approvals. Advancements in manufacturing such as enhanced accuracy of oligo synthesis, new chemistry, manufacturing, and control regulations has also been contributing to growing number of CGT approvals. According to the ASGCT 2025 Impact Report, by American Society of Gene & Cell Therapy (ASGCT), in 2025, pipeline of gene, cell, and RNA therapies had 4,164 therapies in development, including preclinical stage to pre-registration stage.
Approvals and new product launches may also contribute to the growing adoption of cell and gene therapies. For instance, in April 2026, the U.S. Food and Drug Administration announced approval for Otarmeni (lunsotogene parvec-cwha), which is dual adeno-associated virus (AAV) vector-based gene therapy. Considering published results of hearing restoration through the New England Journal of Medicine, the U.S. FDA granted a national priority voucher for specific accelerated review. After 61 days from BLA filing, the approval was issued under the Commissioner's National Priority Voucher (CNPV) pilot program. Such developments highlight a significant influence of strong pipeline and approvals and launches associated with new developments in cell and gene therapy.
Multiple factors associated with manufacturing, such as the availability of critical components, heavy reliance on skilled technicians, inability to scale Autologous (patient-specific) therapies, time durations for sterility, potency, and safety tests, and others, may develop bottlenecks in seamless operations for this industry. In addition, the scarcity of clinical-grade reagents and single-use bioreactor bags also contributes to the supply chain disruptions. For instance, the sourcing capabilities of manufacturers influence the accessibility to GMP-certified plasmids, which are essential in the manufacturing of cell and gene therapies.
Significant investments by government authorities and key market players are expected to present novel growth opportunities for this market. For instance, in February 2026, Johnson & Johnson, one of the key companies in the life sciences industry, announced an investment of more than USD 1 billion in a cell therapy manufacturing site located in Pennsylvania, U.S. Interests announced by major market participants with large investments highlight the growth potential of this industry.
The acquisitions and partnerships associated with companies engaged in the cell and gene therapy industry also signify the growing investments in the sector. In July 2025, Eli Lilly and Company, a global pharmaceutical company engaged in the discovery, development, manufacturing, and marketing of human health solutions, acquired VERVE THERAPEUTICS, INC., which has been developing a robust pipeline of gene editing medicines associated with atherosclerotic cardiovascular disease (ASCVD).
Analyst Perspective
The cell and gene therapy market is growing steadily, driven by rising demand for targeted treatments that address the root causes of diseases. Increased investments, government support through accelerated approvals, and strategic partnerships with CDMOs and CROs are fueling market expansion. Companies are also strengthening manufacturing and sourcing capabilities to improve supply reliability. Although challenges such as material shortages and a limited skilled workforce persist, ongoing collaborations and innovation are expected to support sustained market growth.
Therapy Type Insights
The cell therapy manufacturing segment dominated the market ad accounted for more than 60.0% in 2025. The higher market share is attributed to the increasing number of products entering the marketplace and the high number of ongoing clinical trials. More than 360 clinical trials focusing on CAR-T cell therapies and other cell-based therapies are being studied to decipher the potential of these therapies for the treatment of various disease indications. Thus, the demand for advanced therapy manufacturing services is expected to increase in the coming years. Entry of multiple companies in this market, backed with partnerships and collaborations indicates the growth potential of this segment. For instance, in December 2025, SCTbio, one of the major European CDMOs, with specialized capabilities associated with GMP manufacturing for cell-based products, announced a strategic collaboration agreement with Fortrea, a global contract research organization (CRO), aimed acceleration of cell and gene therapy developments.
The gene therapy segment is expected to expand by a significant CAGR during the forecast period. With a large number of products currently in clinical trials, production process improvement has become a major need for the gene therapy manufacturing market. With an increase in investments from players and the clinical success of more products, several gene therapy companies are focusing on manufacturing and commercialization. Evaluating the existing process and its scalability, as well as for deciding on in-house or outsourced manufacturing, are some of the major factors to be considered while designing the manufacturing process for gene therapy products. Some of the key global companies are undertaking various strategic initiatives to boost their presence in the gene therapy manufacturing market.
Scale Insights
The pre-commercial/R&D scale manufacturing segment dominated the market and accounted for more than 70.0% in 2025. Certain factors such as the robust and constantly growing pipeline of gene and cell therapies along with the rise in investments are expected to have a positive impact on the segment growth. Partnerships and collaborations influence this segment significantly, as tie-ups among academic organizations and companies engaged in healthcare industry enable availability of resource, technologies, and strong financial backing for R&D and associated activities. For instance, in February 2026, Cellares, an Integrated Development and Manufacturing Organization (IDMO) collaborated with Stanford Center for Definitive and Curative Medicine (CDCM) and Stanford Innovative Medicines Accelerator (IMA), which aimed at automating the manufacturing process of gene-edited hematopoietic stem cell (HSC) therapies, and assisting reduction in hands-on variability while developing scalable foundation to facilitate academic innovation.
The commercial-scale manufacturing segment is projected to have the highest CAGR during the forecast period. With the increasing number of regulatory approvals for gene and cell therapy products, the demand for commercial production of these therapies is increasing rapidly. The major market players such as Thermo Fisher Scientific and AGC Biologics are undertaking various strategic initiatives to fulfill the changing market demands.
Mode Insights
The contract manufacturing mode segment held the highest revenue share of more than 66.0% in 2025. With the growing demand for cell and gene therapies, the shortage of manufacturing capacity is creating growth opportunities for contract manufacturing service providers. As the market for cell and gene therapies is non-standardized and rapidly changing, outsourcing to a contract manufacturing service provider is expected to provide a competitive advantage in terms of experience and expertise.
The in-house manufacturing segment is likely to register a considerable CAGR during the forecast period. The academic institutes with personalized patient treatment programs, as well as the presence of a substantial number of entities with large capital, are the largest contributors to this segment. Moreover, advantages over contract manufacturing are also expected to boost segment growth. Small biotechnology companies developing cell and gene therapies lack resources, capacity, and infrastructure, leading to strategic partnerships with contract manufacturers. This factor is expected to boost segment growth in the coming years.
Workflow Insights
On the basis of workflow, the process development segment accounted for a significant revenue share of over 17.0% in 2025. With an increasing number of therapies advancing from clinical trials to regulatory approval, the development of well-characterized and robust methods for cell therapy production has become increasingly important. Process development strategies provide efficiency while improving the quality and safety profiles of candidate programs. Process development can be applied to all process elements, such as cell characterization, cell isolation, optimization of cell culture media, removal of impurities, and scale-up.
The vector development segment is estimated to register the fastest CAGR during the forecast period. The high penetration of manufacturing services in this space is the major factor contributing to the segment growth. With a growing market for gene therapies, the demand for viral vectors is increasing. Viral vectors have been used for the treatment of various disorders, such as metabolic, cardiovascular, muscular, infectious, hematologic, and ophthalmologic, as well as various types of cancer. The most widely used viral vectors are adenoviral, retroviral, AAV, lentivirus, and herpes simplex virus.
Regional Insights
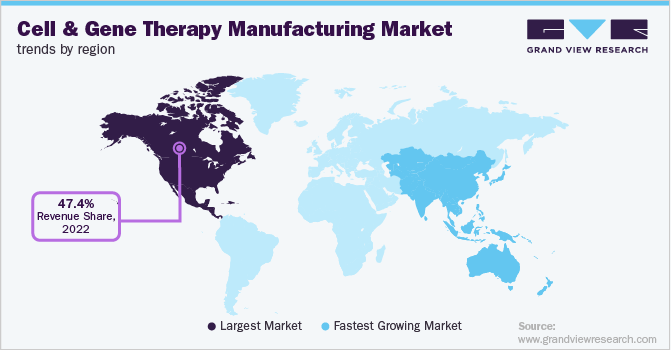
North America dominated the global market for cell and gene therapy and accounted for more than 47.0% in 2025. This is attributed to the growing engagement of entities in research and product development in gene and cell therapy, coupled with a substantial number of contract development organizations in the region. In addition, homegrown companies are expanding their manufacturing facilities in the region.
 To learn more about this report, Download Free Sample Report
U.S. Cell and Gene Therapy Market Trends
The cell and gene therapy manufacturing market in the U.S. has also been experiencing significant growth driven by increasing investments by government and private sector organizations, collaborations among companies and key institutes for pre-commercial/R&D scale manufacturing, accessibility to critical components, and strong healthcare infrastructural capabilities of the country.
Suitable strategic atmosphere for healthcare manufacturing and R&D, backed by the presence of multiple industry participants, infrastructure, and necessary government support, the U.S. has been attracting investments in the country. For instance, in July 2025, AstraZeneca, a global biopharmaceutical company originating from Europe, announced its plans to invest nearly USD 50.0 billion in the U.S. by 2030, including manufacturing facilities for cell therapy in Tarzana, California, and Rockville, Maryland.
Europe Cell and Gene Therapy Market Trends
Europe cell and gene therapy market is expected to experience significant growth during the forecast period. The growth of this market is primarily influenced by the factors such as expansion of clinical pipelines, growing investments in the market, favorable regulatory scenarios, and infrastructure capacity expansions initiated by major CDMOs in the region. Partnerships among companies also play key roles in growth of this market. For instance, in March 2026, Lonza, global CDMO announced extension of long-term commercial manufacturing partnership with a commercial-stage biotechnology company Genetix Biotherapeutics Inc.,including manufacturing capacity expansion focused on specialized support to FDA-approved gene therapy for pediatric and adult patients ZYNTEGLO. Such development highlight growth trends in this regional industry.
Asia Pacific Cell and Gene Therapy Market Trends
Asia Pacific is anticipated to experience fastest CAGR from 2026 to 2033. Over the past several years, the cell therapy market has gained momentum in Asia. This is attributed to the establishment of accelerated approval pathways, increasing healthcare needs, and growing private and government investments. Multiple companies have been focusing in development of expertise, technological capabilities, clinical excellence, and key strategic partnership to enter this market. For instance, in December 2025, Cipla, one of the global pharmaceutical companies with a strong presence across Australia, China, and parts of Southeast Asia, announced launch of its, innovation-based, Drug Controller General of India (DCGI) approved allogeneic mesenchymal stromal cell (MSC) therapy for Knee Osteoarthritis (Knee OA), Ciplostem. The offering was developed through partnership with Stempeutics Research.
Key Cell And Gene Therapy Manufacturing Company Insights
Key players operating in the cell and gene therapy manufacturing market are undertaking various initiatives to strengthen their market presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships play a key role in propelling market growth.
Key Cell And Gene Therapy Manufacturing Companies:
The following key companies have been profiled for this study on the cell and gene therapy manufacturing market.
-
Lonza.
-
Carlyle (bluebird bio)
-
Catalent, Inc
-
F. Hoffmann-La Roche Ltd
-
Samsung Biologics
-
Boehringer Ingelheim International GmbH
-
Cellular Therapeutics
-
Altaris, LLC
-
Takara Bio Inc.
-
Miltenyi Biotec
-
Thermo Fisher Scientific Inc.
-
Novartis AG
-
WuXi AppTec
Recent Development
-
In March 2026, the U.S. FDA approved a gene therapy developed for the treatment of severe-stage Leukocyte Adhesion Deficiency Type I (LAD-I), Kresladi. The accelerated approval is likely to provide a significant treatment for pediatric patients diagnosed with severe Leukocyte Adhesion Deficiency Type I.
-
In May 2025, CellFE, Inc., one of the market participants in microfluidics-based cell engineering and cell therapy CDMO, and Made Scientific, announced a strategic collaboration for the generation of credible pilot data on the CellFE High Volume Cyva System.
Cell And Gene Therapy Manufacturing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 17.5 billion
Estimated market size in 2026
USD 21.0 billion
Projected market size by 2033
USD 75.1 billion
Growth rate
CAGR of 19.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Therapy type, scale, mode, workflow, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; U.K.; France; Italy; Spain; Denmark, Sweden, Norway, China; Japan; India; Australia; Thailand; South Korea; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Lonza.; Carlyle (bluebird bio); Catalent, Inc; F. Hoffmann-La Roche Ltd; Samsung Biologics; Boehringer Ingelheim International GmbH; Cellular Therapeutics; Altaris, LLC; Takara Bio Inc.; Miltenyi Biotec; Thermo Fisher Scientific Inc.; Novartis AG; WuXi AppTec
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Cell And Gene Therapy Manufacturing Market Report Segmentation
This report forecasts revenue growth at the regional, and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global cell and gene therapy manufacturing market report on the basis of therapy type, scale, mode, workflow, and region:
-
Therapy Type Outlook (Volume, Number of Doses; Revenue, USD Billion; 2021 - 2033)
-
Cell therapy manufacturing
-
Stem cell therapy
-
Non-stem cell therapy
-
-
Gene therapy manufacturing
-
-
Scale Outlook (Volume, Number of Doses; Revenue, USD Million, 2021 - 2033)
-
Pre-commercial/ R&D scale manufacturing
-
Commercial scale manufacturing
-
-
Mode Outlook (Volume, Number of Doses; Revenue, USD Billion; 2021 - 2033)
-
Contract manufacturing
-
In-house manufacturing
-
-
Workflow Outlook (Volume, Number of Doses; Revenue, USD Billion; 2021 - 2033)
-
Cell processing
-
Cell banking
-
Process development
-
Fill & finish operations
-
Analytical and quality testing
-
Raw material testing
-
Vector production
-
Others
-
-
Regional Outlook (Volume, Number of Doses; Revenue, USD Billion; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global cell and gene therapy manufacturing market size was valued at USD 17.5 billion in 2025 and is estimated at USD 21.0 billion in 2026.
Some key players in the cell & gene therapy manufacturing market are Thermo Fisher Scientific, Lonza AG, Fujifilm, Bluebird Bio Inc., Samsung Biologics, Takara Bio Inc., Catalent Inc., and Merck KGaA.
North America dominated with a revenue share of 47.0% in 2025.
The global cell and gene therapy manufacturing market is expected to grow at a CAGR of 19.9% from 2026 to 2033, reaching USD 75.1 billion.
The cell therapy manufacturing segment dominated the market for cell & gene therapy manufacturing and accounted for the largest revenue share of 60.0% in 2025.
The pre-commercial/ R&D scale manufacturing segment dominated the market for cell & gene therapy manufacturing and accounted for the largest revenue share of 70.0% in 2025.
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


