
- Home
- »
- Advanced Interior Materials
- »
-
Chemical Anchors Market Size, Share, Industry Report, 2030GVR Report cover

Chemical Anchors Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Injectable Adhesive, Capsule Adhesive), By Resin (Polyester, Epoxy Acrylate, Pure Epoxy, Hybrid Systems, Unsaturated Polyester), By Application (Infrastructure, Industrial), By Region, And Segment Forecasts
Market Size, 2025
$1.0BMarket Estimate, 2026
$1.1BMarket Forecast, 2033
$1.6BCAGR, 2026–2033
5.1%Chemical Anchors Market Summary
The global chemical anchors market size was valued at USD 1.0 billion in 2025 and is projected to grow from USD 1.1 billion to USD 1.6 billion in 2033, at a CAGR of 5.1% from 2026 to 2033. Europe held the largest global revenue share of 33.2% in 2025. The demand for chemical anchors is increasing due to the growing need for high-strength fastening solutions in modern construction and infrastructure projects.
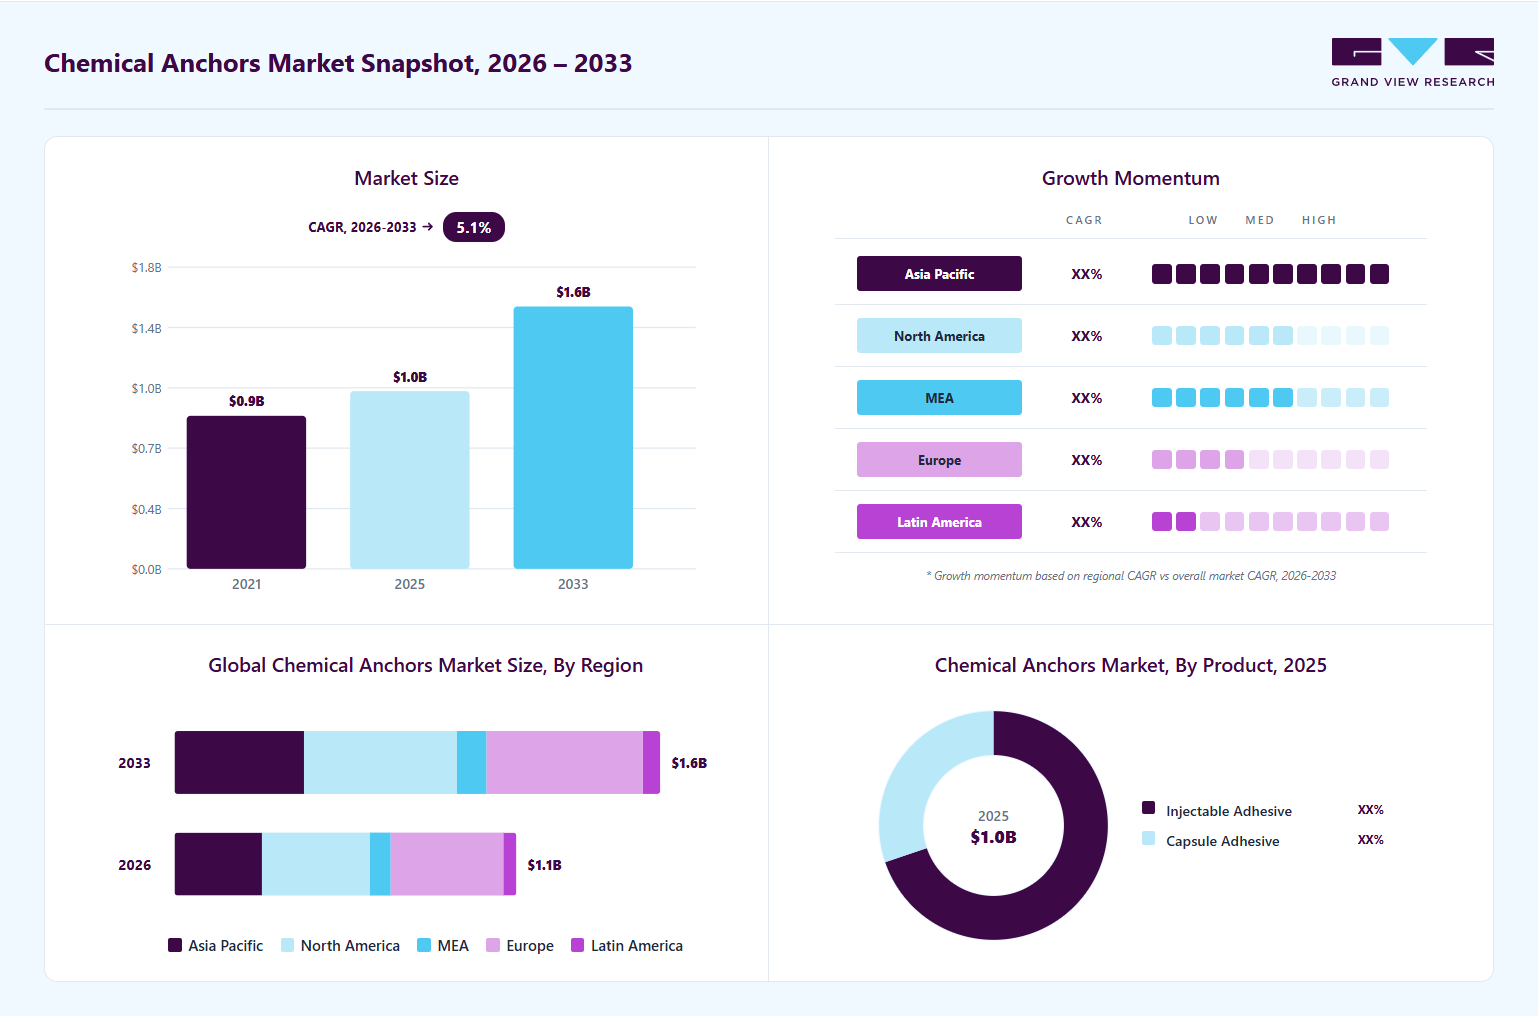 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Injectable adhesive anchors segment accounted for the largest revenue share of 69.8% in 2025.
- By resin: Epoxy acrylate segment dominated the market with a revenue share of over 35.2% in 2025.
- By application: Infrastructure segment led the market with a share of 40.0% in 2025.
Regional Highlights
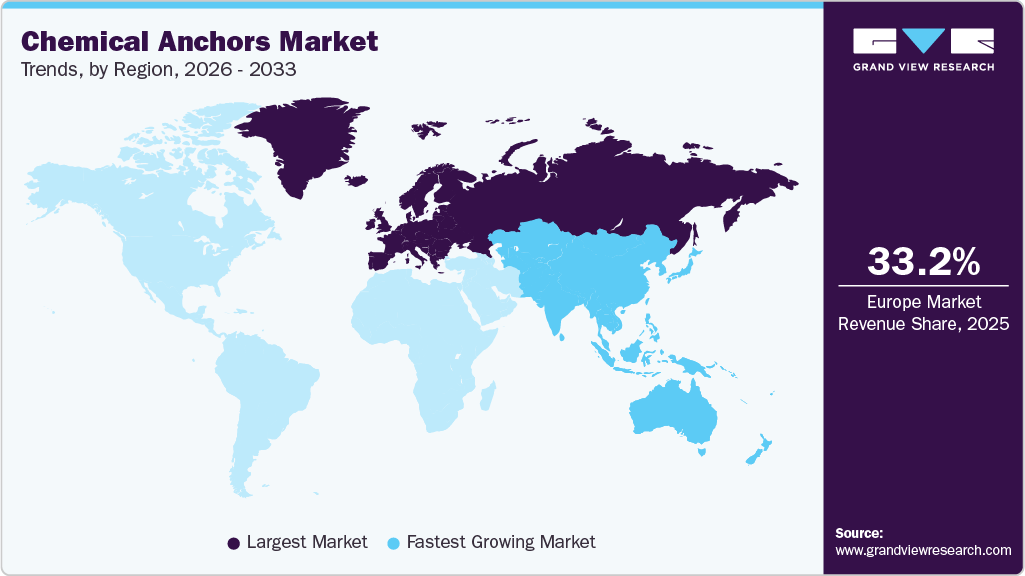
- Largest regional market: Europe (33.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- The chemical anchors industry in the Germany held the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.0 Billion
- Estimated market size in 2026: USD 1.1 Billion
- Projected market size by 2033: USD 1.6 Billion
- CAGR (2026-2033): 5.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Unlike mechanical anchors, chemical anchors provide superior load-bearing capacity and enhanced performance in cracked concrete, making them suitable for heavy-duty structural applications. Rapid urbanization and increasing investments in commercial and residential construction are further accelerating market demand.The expansion of transportation infrastructure, including bridges, tunnels, railways, airports, and highways, has significantly increased the adoption of chemical anchoring systems. These products are widely used for retrofitting, seismic strengthening, and structural reinforcement applications where reliability and long-term durability are critical. Aging infrastructure across developed economies is also driving replacement and rehabilitation activities.
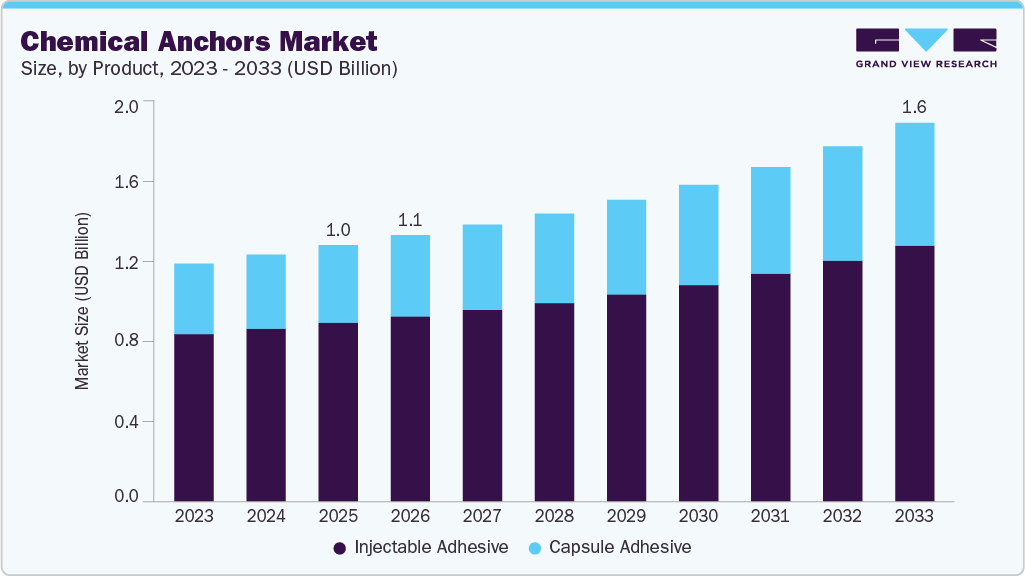 To learn more about this report, Download Free Sample Report
One of the primary demand drivers is the increasing adoption of renovation and retrofitting projects worldwide. Governments and private organizations are investing heavily in upgrading aging infrastructure, requiring reliable anchoring solutions for structural strengthening and extension projects. Chemical anchors provide flexibility and superior bonding strength in such applications.
The growth of high-rise buildings and complex architectural structures is another major demand driver. Modern construction designs require fastening systems capable of supporting substantial loads while maintaining structural stability. Chemical anchors offer enhanced load transfer, making them ideal for complex engineering projects.
Manufacturers are increasingly developing low-VOC and styrene-free chemical anchor formulations to address environmental and occupational safety concerns. These sustainable products help contractors comply with green building standards while maintaining strong bonding performance.
The market is witnessing significant innovation in epoxy, hybrid, and vinyl ester resin technologies. New-generation formulations offer faster curing times, improved load capacities, and enhanced performance under extreme temperature and moisture conditions, expanding their application range.
Market Dynamics
The increasing investment in infrastructure development worldwide is a major driver for the chemical anchors market. Governments and private investors are allocating substantial funds toward the construction of bridges, highways, rail networks, airports, commercial buildings, and industrial facilities. Chemical anchors are widely utilized in these projects due to their superior load-bearing capacity, strong bonding strength, and effectiveness in concrete and masonry substrates. Their suitability for heavy-duty structural applications makes them a preferred fastening solution in modern infrastructure projects.
In addition, the growing need to rehabilitate and retrofit aging infrastructure is significantly boosting demand. Many developed economies are focusing on extending the service life of existing structures through reinforcement and repair activities. Chemical anchors play a critical role in post-installed rebar connections, seismic strengthening, and structural upgrades, enabling engineers to enhance structural integrity without extensive reconstruction.
Fluctuations in the prices of key raw materials such as epoxy resins, vinyl ester resins, polyester resins, and specialty chemicals represent a significant restraint for the chemical anchors industry. These materials are derived largely from petrochemical feedstocks, making manufacturers vulnerable to changes in crude oil prices and supply chain disruptions. Rising input costs can increase product prices and compress profit margins, particularly in highly competitive construction markets where cost sensitivity remains high.
Market Concentration And Characteristics
The chemical anchors market is moderately consolidated, with several multinational companies holding significant market shares through extensive product portfolios and global distribution networks. Leading manufacturers focus on technological innovation, certification compliance, and strategic acquisitions to strengthen their market positions.
Regional players also maintain a strong presence in local markets by offering cost-effective solutions and customized products. Competition is driven by product performance, technical support capabilities, and adherence to international construction standards. Growing infrastructure investments continue to attract new participants, intensifying market competition while encouraging innovation.
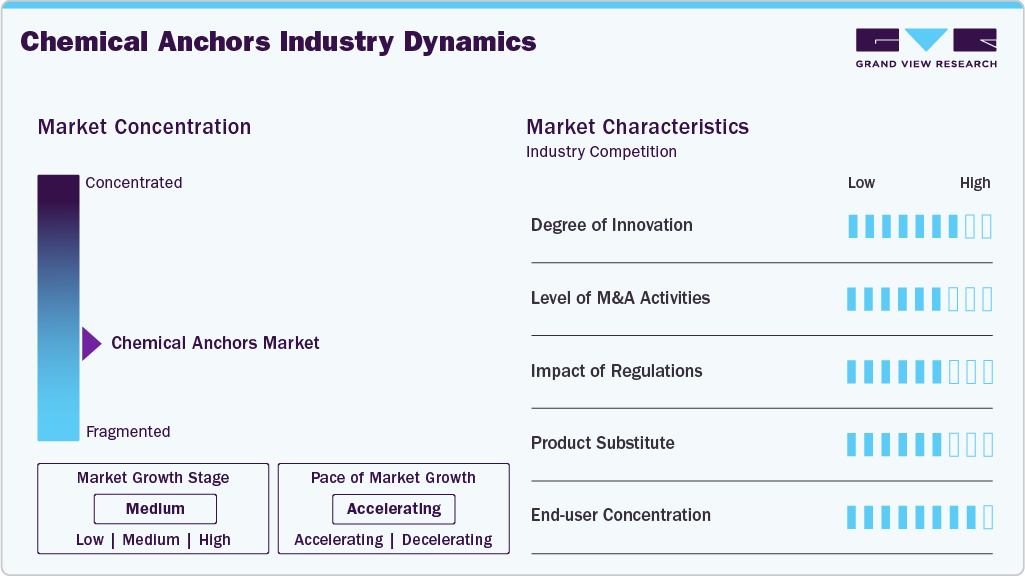 To learn more about this report, Download Free Sample Report
Mechanical anchors are the primary substitute for chemical anchors in construction applications. These alternatives offer easier installation and lower upfront costs, making them attractive for certain fastening requirements. However, mechanical anchors generally provide lower load capacities and reduced performance in challenging conditions compared to chemical anchors.
Other fastening technologies, including cast-in-place anchors and specialized fastening systems, also compete with chemical anchors in selected applications. Despite these alternatives, chemical anchors maintain a competitive advantage in heavy-duty structural projects requiring superior bonding strength, flexibility, and long-term durability. Consequently, the threat of substitutes remains moderate rather than high.
Product Insights
Injectable adhesive anchors dominated the chemical anchors industry, accounting for the largest revenue share of 69.8% in 2025. They are the most often used chemical anchors. Injection chemicals are widely used in masonry, natural stone, and rebar applications. They are commonly used to fix steel dowels, staircases, handrails, building facades, sound barriers, pipes, brackets, and post-installation rebar connections.
Injectable adhesive anchors require four times longer curing time than mechanical anchors. However, manufacturers are developing new resin formulations that will reduce curing time, making it a favorable option across applications and environmental conditions.
Capsule adhesive anchors are used on concrete surfaces and find application in industrial and commercial construction. These are primarily used in anchoring steel structures, cranes, elevators, and industrial machinery. Post-pandemic growth in industrial and commercial output is encouraging companies to expand their manufacturing capacity, thereby providing ample growth opportunities for capsule adhesive anchors.
Resin Insights
Epoxy acrylate dominated the chemical anchors market, accounting for the largest share of 35.2% in 2025. Key characteristics of the resin, including high strength, fast curing, suitability for high-load applications, and resistance to corrosive or moist conditions, promote its use across the construction sector.
Hybrid systems are expected to register the highest CAGR of 5.8% over the forecast period, owing to their ability to fill in any defects and make the hole airtight with 100% adhesion, thereby increasing load strength. It also strengthens the concrete walls and the area around the borehole, making them crack-resistant. Moreover, chemical anchoring enables the installer to make minor modifications to the stud alignment while the chemical combination cures.
Pure-epoxy chemical anchors are a two-part, 1:1-ratio, bonded anchoring system for use in cracked and uncracked concrete under normal and seismic conditions. These anchors are used in structural applications and rebar connections where high load-bearing capacity is required.
Furthermore, it is ideal for high-load applications, as the resulting bond is stronger than the base material. The system is centered on the adhesion principle, which results in no additional load stress being imparted to the base material. Thus, it is also ideal for reduced center, close-to-edge fixing, group anchoring, and low-compressive strength concrete.
Application Insights
The infrastructure segment accounted for the largest share, over 40.0%, in 2025 and is expected to witness the fastest growth over the forecast period. Chemical anchors are primarily used in this segment due to the need for robust and superior-performing products. Further, the cost factor of mechanical anchors has the least impact on this sector, owing to the scale of application.
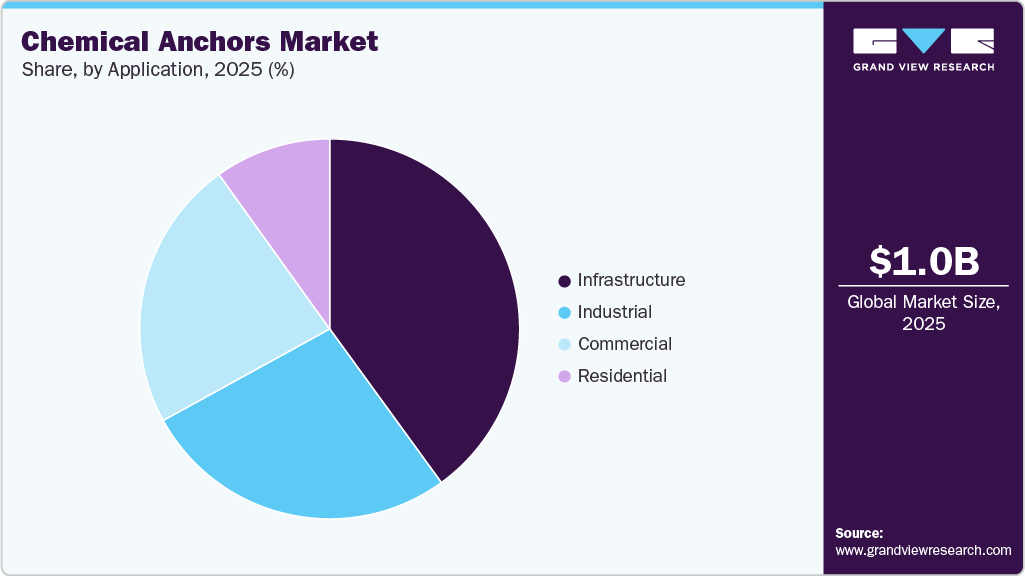 To learn more about this report, Download Free Sample Report
The residential and commercial sectors accounted for a significant revenue share in 2025. The rise in construction spending in emerging economies is expected to be the major driver for the market. The governments across these countries have made large investments in public infrastructures, such as offices, hospitals, and housing societies.
The emergence of various countries as upcoming manufacturing hubs can be attributed to the establishment of numerous industries and a large population migrating close to these facilities, resulting in the development of new cities and the expansion of existing cities. These factors have a major impact on the growth of the construction industry, including residential and commercial construction, resulting in increased demand for chemical anchors.
Regional Insights
Europe dominated the chemical anchors market, accounting for 33.2% of revenue in 2025, driven by extensive renovation activity and strict building regulations. The region's focus on sustainable construction and energy-efficient buildings supports the adoption of advanced anchoring technologies. Infrastructure refurbishment programs and transportation upgrades generate consistent demand. Growing investments in renewable energy projects further expand application opportunities. Technological innovation and regulatory compliance remain key market growth drivers.
 To learn more about this report, Download Free Sample Report
The Germany chemical anchors market is leading Europe, supported by its advanced construction industry and strong engineering standards. Infrastructure maintenance, industrial modernization, and commercial construction projects drive demand for chemical anchors. The country's emphasis on structural safety and sustainability promotes the use of certified anchoring systems. Renewable energy investments, particularly in wind power installations, contribute additional growth opportunities. Continuous innovation in construction technologies further supports market expansion.
Asia Pacific Chemical Anchors Market Trends
Asia Pacific is experiencing significant growth driven by rapid urbanization, large-scale infrastructure investments, and expanding industrial activity across the region. Countries such as China, India, Japan, and South Korea continue to invest heavily in transportation networks, commercial construction, and manufacturing facilities. Rising construction spending and growing adoption of advanced building materials are supporting market expansion. The presence of major construction projects and increasing demand for seismic-resistant structures strengthen Asia Pacific's position.
The China chemical anchors market is the largest contributor to regional demand, driven by extensive infrastructure development and urban construction activities. Government investments in railways, highways, airports, and industrial facilities continue to generate strong demand for chemical anchoring systems. The country's focus on structural safety and modernization supports the adoption of advanced fastening technologies. Growth in renewable energy installations also creates opportunities for anchor manufacturers. Domestic production capabilities further enhance market growth.
North America Chemical Anchors Market Trends
North America is a mature yet steadily growing market, driven by infrastructure rehabilitation and commercial construction. Aging bridges, highways, and public facilities require extensive retrofitting and strengthening solutions. Chemical anchors are increasingly utilized in renovation projects due to their reliability and load-bearing performance. Industrial expansion and renewable energy developments further support demand growth. Stringent construction regulations encourage the adoption of certified anchoring products.
U.S. Chemical Anchors Market Trends
The United States chemical anchors industry leads North America, owing to significant investments in infrastructure modernization and industrial development. Government funding programs focused on transportation upgrades and public infrastructure rehabilitation continue to create substantial demand. Commercial building construction and energy sector projects also contribute to market growth. Advanced engineering standards and seismic safety requirements encourage the use of high-performance chemical anchoring systems. The country's emphasis on resilient infrastructure supports long-term market expansion.
Central and South America Chemical Anchors Market Trends
The Central and South America market is experiencing gradual growth driven by increased investments in residential, commercial, and infrastructure development projects. Urbanization and population growth are creating demand for modern construction solutions. Governments are investing in transportation and public utility projects that require durable anchoring systems. Industrial expansion and mining activities also support market demand. Economic development initiatives are expected to create long-term growth opportunities across the region.
Middle East & Africa Chemical Anchors Market Trends
The Middle East & Africa chemical anchors industry is expanding due to large-scale infrastructure projects, urban development programs, and industrial investments. Countries in the Gulf region are investing heavily in smart cities, transportation networks, and commercial construction. Chemical anchors are increasingly used in high-rise buildings, energy facilities, and infrastructure projects that require high structural reliability. Growing construction standards and diversification initiatives support market adoption. Continued infrastructure spending is expected to drive sustained regional growth.
Key Chemical Anchors Company Insights
Some of the key players operating in the market are Hilti Group; Fisher Group; Illinois Tool Works Inc.; Sika AG; Simpson StrongTie Company Inc.; and Henkel AG & Company, KGaA:
-
Hilti Group offers several products and services, including anchor systems, cordless systems, construction chemicals, diamond corning and cutting, cutting, sawing, & grinding, direct fastening, drilling and demolition, screw fastening, firestop, accessories, measuring systems, modular support systems, façade systems, and ON!Track equipment management for the construction industry.
-
Fischer Group has five business divisions: Fischer fixing system, Fischer automotive, Fischertechnik, Fischer consulting, and LNT Automation. It distributes its products to more than 120 countries worldwide and has production facilities in Europe, North America, Central America, and South America.
EJOT, Ripple India, Koelner Rawlplug IP, Chemfix Products Ltd, and Leviat B.V. are some of the emerging participants in the chemical anchors market.
-
Leviat B.V. sells its products through its brands, namely Meadow Burke, HALFEN, Plaka, and Ancon. Halfen brand offers a wide range of anchoring, framing, façade technology, and reinforcing solutions for industrial and construction applications.
-
Chemfix Products Ltd specializes in the development of chemical anchoring, anchoring products, and repair solutions for construction, industrial, and DIY sectors. The company has four product lines, namely, chemical anchoring, metolux repair fillers, metolux adhesives, and timbabuild wood repair.
Key Chemical Anchors Companies
The following key companies have been profiled for this study on the chemical anchors market.
-
Hilti Group
-
MKT Fastening
-
Power Fasteners
-
FIXDEX Fastening Technology
-
Fischer Group
-
Leviat B.V.
-
Chemfix Products Ltd.
-
Mungo Befestigungstechnik AG
-
Koelner Rawlplug IP
-
Ripple India
-
EJOT
-
Illinois Tool Works Inc.
-
Sika AG
-
Simpson Strong-Tie Company, Inc.
-
Henkel AG & Company, KGaA
Company Categorization
Operating Strategies
Competitive Edge
Weakness
Mature Players: Hilti Group; Fischer Group; Illinois Tool Works Inc.; Sika AG
- Focus on large-scale infrastructure, commercial, and industrial projects through diversified anchoring product portfolios.
- Strong investment in R&D for seismic-certified, high-load-bearing, and environmentally compliant chemical anchoring systems.
- Strong global brand recognition with established relationships across the construction and engineering industries.
- Advanced manufacturing capabilities and broad product availability across multiple regions.
- Higher product pricing compared to regional and local competitors.
- Complex regulatory compliance requirements across different international markets.
Emerging Players: MKT Fastening; Power Fasteners; FIXDEX Fastening Technology
- Focus on regional expansion and competitive pricing to penetrate developing construction markets.
- Increasing investments in manufacturing capacity and localized distribution partnerships.
- Faster response to regional demand changes and customer-specific requirements.
- Growing presence in emerging economies supported by infrastructure and industrial development activities.
- Limited global brand visibility and smaller international distribution networks.
- Dependence on regional construction cycles and limited penetration in high-value infrastructure projects.
Recent Developments
-
In July 2025, Fischer Group introduced the world’s first HybridPower anchor, combining steel-anchor load capacity with polymer-anchor installation simplicity for structural fastening applications.
-
In October 2024, Hilti Group introduced Spec2Site, an integrated anchoring workflow solution combining anchor design, installation, and inspection processes for structural connections and post-installed rebar applications.
Chemical Anchors Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.0 billion
Estimated market size in 2026
USD 1.1 billion
Projected market size by 2033
USD 1.6 billion
Growth rate
CAGR of 5.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, resin, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Saudi Arabia
Key companies profiled
Hilti Group; MKT Fastening; Power Fasteners; FIXDEX Fastening Technology; Fischer Group; Leviat B.V.; Chemfix Products Ltd.; Mungo Befestigungstechnik AG; Koelner Rawlplug IP; Ripple India; EJOT; Illinois Tool Works Inc.; Sika AG; Simpson Strong-Tie Company, Inc.; Henkel AG & Company, KGaA
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Chemical Anchors Market Report Segmentation
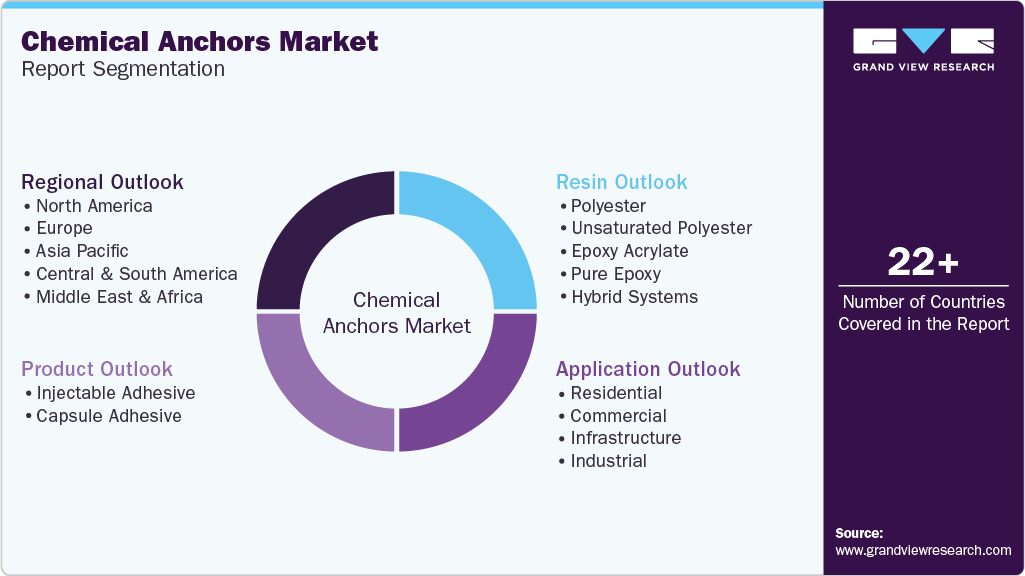
This report forecasts revenue growth at the global, regional, and country levels and analyzes the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global chemical anchors market report based on product, resin, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Injectable Adhesive
-
Capsule Adhesive
-
-
Resin Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Polyester
-
Unsaturated Polyester
-
Epoxy Acrylate
-
Pure Epoxy
-
Hybrid Systems
-
-
Application Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Residential
-
Commercial
-
Infrastructure
-
Industrial
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
lIndia
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regulatory Impact Analysis
Conducted a comprehensive assessment of building codes, anchoring standards, seismic regulations, construction safety requirements, environmental regulations, and certification frameworks affecting the chemical anchors market across major regions. Evaluated their impact on product development, market entry, installation practices, and compliance costs.
Helps stakeholders understand regulatory risks, ensure compliance with evolving standards, anticipate policy-driven market changes, and identify opportunities arising from stricter structural safety requirements.
Competitive Landscape Assessment
Performed an in-depth evaluation of leading chemical anchor manufacturers, including market positioning, product portfolios, pricing strategies, technological capabilities, distribution networks, certification strengths, and recent strategic developments such as mergers, acquisitions, partnerships, and capacity expansions.
Enables clients to benchmark against competitors, identify market gaps, assess competitive threats, formulate effective growth strategies, and uncover partnership or acquisition opportunities.
Sustainability & Low-VOC Product Trend Analysis
Assessed market adoption of styrene-free, low-emission, and environmentally friendly chemical anchor formulations driven by green building standards and sustainability goals.
Enables stakeholders to align product strategies with environmental regulations and growing customer preference for sustainable construction materials.
Frequently Asked Questions About This Report
The infrastructure segment accounted for the largest segment, with a revenue share of 40.0% in 2025.
Some of the key players in the chemical anchors market are Hilti Group, Illinois Tool Works Inc., Sika AG, Simpson Strong-Tie Company, Inc., and Henkel AG & Company, KGaA, MKT Fastening, Power Fasteners, FIXDEX Fastening Technology, EJOT, Ripple India, Koelner Rawlplug IP, Mungo Befestigungstechnik AG, Chemfix Products Ltd, Leviat B.V., and Fischer Group.
The key factors that are driving the chemical anchors market include the rising demand for the product in the construction industry owing to its superior performance as compared to mechanical anchors.
Epoxy acrylate accounted for the largest share of over 35.2% in 2025.
Unsaturated Polyester is the fastest growing resin segment over the forecast period.
Europe accounted for the largest revenue share in 2025.
Capsule Adhesive is the fastest growing product segment in the chemical anchors market.
The global chemical anchors market is expected to grow at a compound annual growth rate of 5.1% from 2026 to 2033, reaching USD 1.6 billion by 2033.
The global chemical anchors market size was estimated at USD 1.0 billion in 2025 and is expected to reach USD 1.1 billion in 2026.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


