
- Home
- »
- Renewable Chemicals
- »
-
Circular Economy Chemicals Market Size Report, 2026-2033GVR Report cover

Circular Economy Chemicals Market (2026 - 2033)
Size, Share & Trends Analysis Report By Chemical (Bio Based Chemicals, Recycled Chemicals), By Feedstock, By End Use (Packaging, Automotive, Building And Construction), By Region, And Segment Forecasts
Market Size, 2025
$225.5BMarket Estimate, 2026
$256.0BMarket Forecast, 2033
$621.1BCAGR, 2026–2033
13.5%Circular Economy Chemicals Market Summary
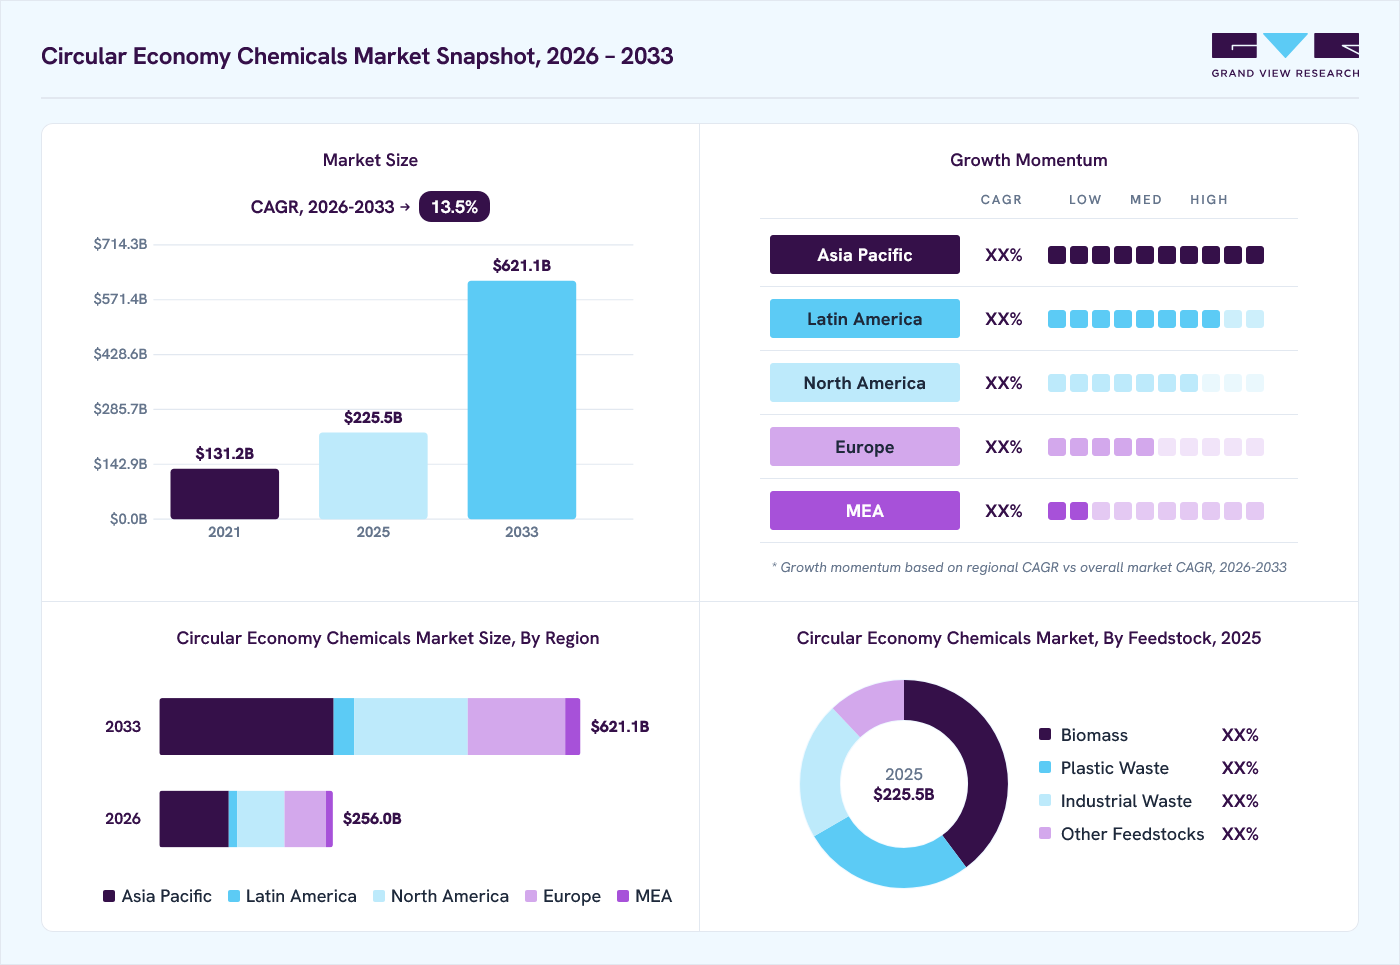
The global circular economy chemicals market size was valued at USD 225.5 billion in 2025 and is projected to grow from USD 256.0 billion in 2026 to reach USD 621.1 billion by 2033, at a CAGR of 13.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 39.8% in 2025. The market growth is driven by increasing adoption of bio based and recycled chemicals, growing utilization of waste derived feedstocks, and expanding demand for circular chemical solutions across packaging, automotive, building and construction, and chemical and petrochemical industries.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By chemical: The bio based chemicals segment held the largest revenue share of 35.0% in 2025.
- By feedstock: The biomass segment held the largest revenue share of 39.8% in 2025.
- By end use: The packaging segment led the market, accounted for the largest revenue share of 22.7% in 2025.
Regional Highlights
- Largest Region: Asia Pacific (39.8% revenue share, 2025)
- By country: China dominated the APAC market in 2025
Market Size & Forecast
- Market size in 2025: USD 225.5 billion
- Estimated market size in 2026: USD 256.0 billion
- Projected market size by 2033: USD 621.1 billion
- CAGR (2026-2033): 13.5%
Prism AI by Grand View Research Free to tryAsk a question about the circular economy chemicals market✓Every figure cited from GVR research Prefer the report? Download free sample →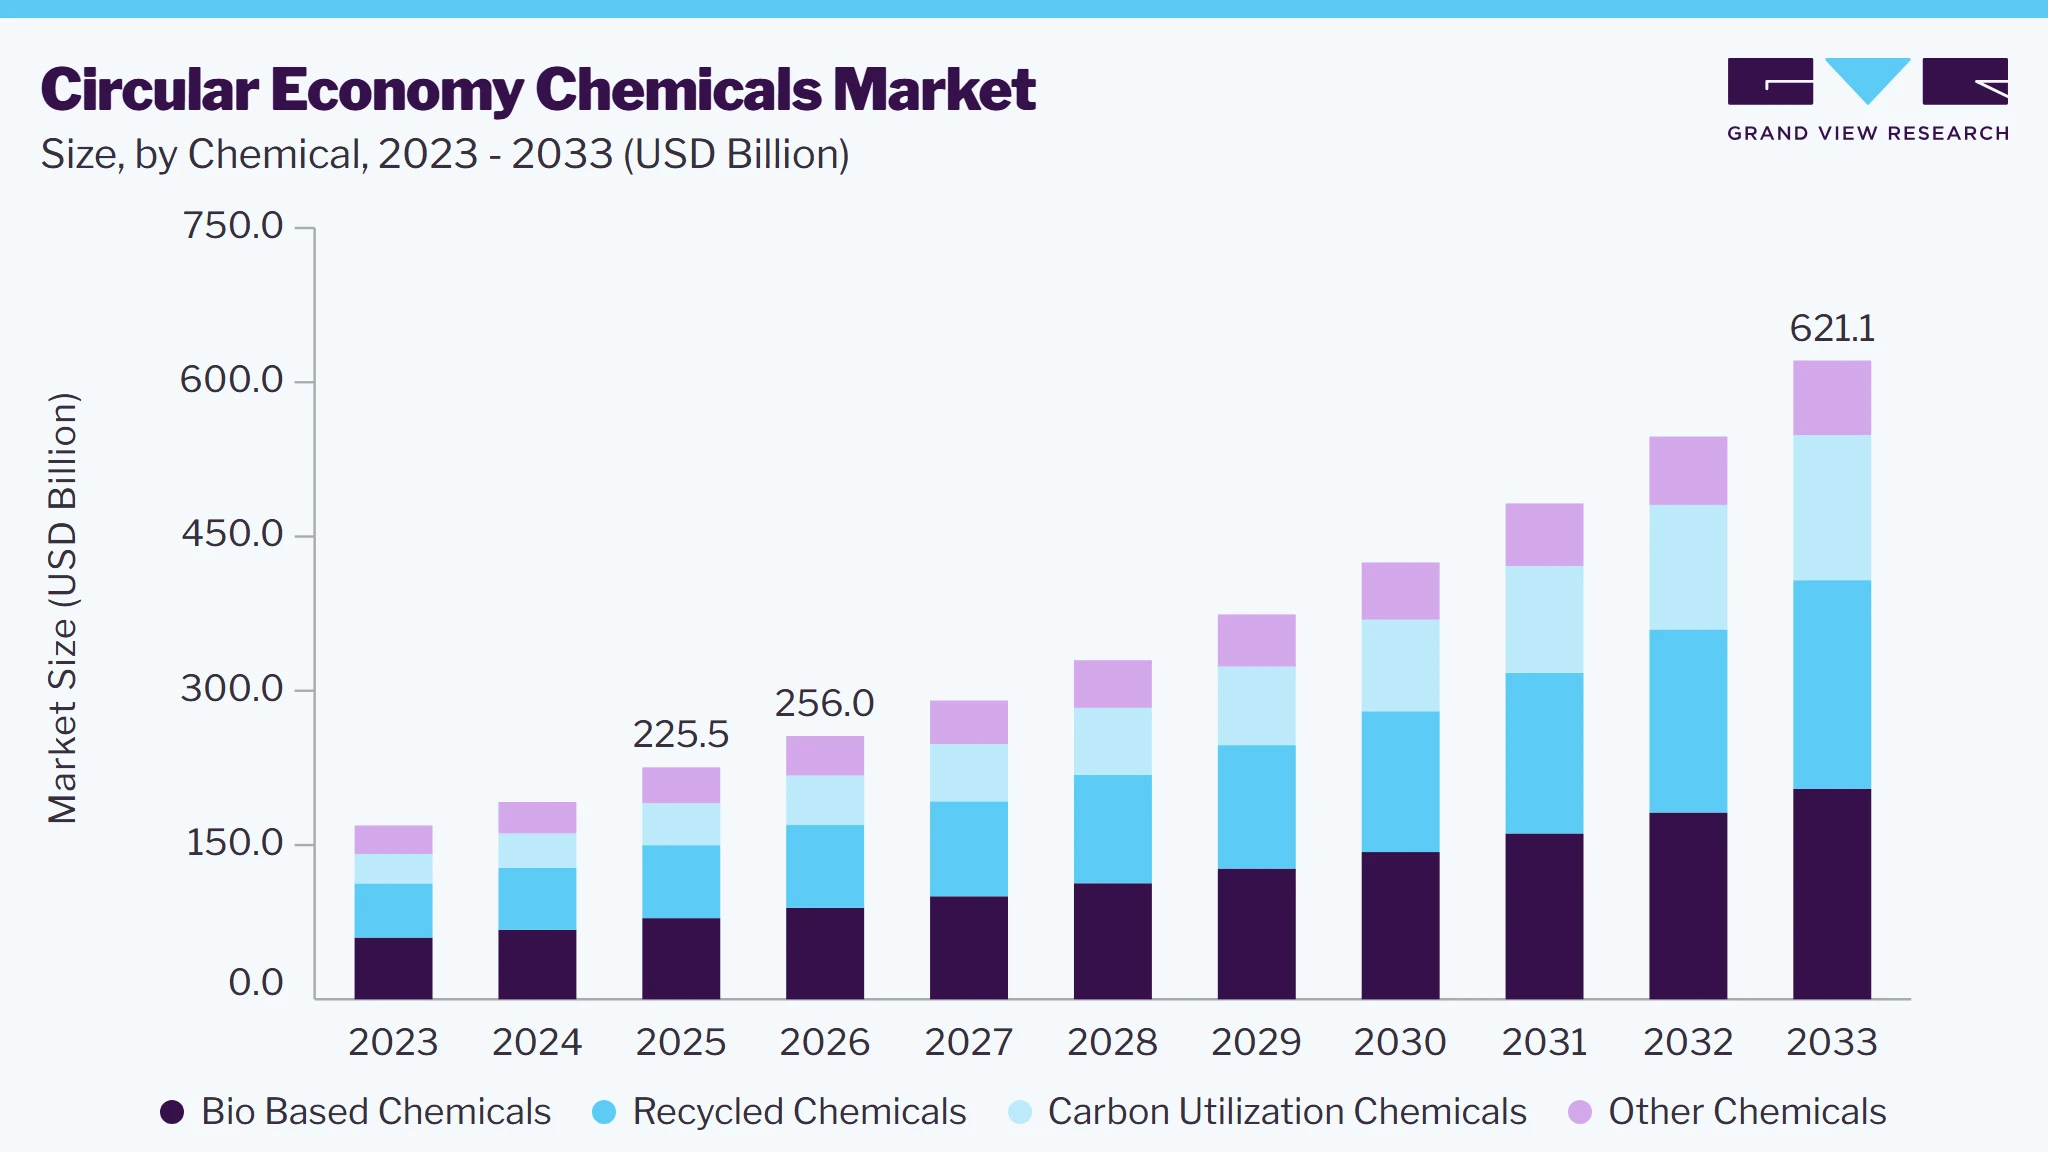 To learn more about this report, Download Free Sample Report
Growing environmental concerns and increasing emphasis on resource efficiency are driving the adoption of circular economy chemicals across multiple industries. Applications across packaging, automotive, building and construction, chemical and petrochemicals, consumer goods, electronics, healthcare and pharmaceuticals, and paper and textile are gaining traction as manufacturers seek to reduce waste, improve resource utilization, and integrate recycled, bio based, and carbon derived chemical solutions into their operations.
Market Dynamics
The global circular economy chemicals market is supported by increasing demand for sustainable chemical solutions across packaging, automotive, building and construction, chemical and petrochemicals, consumer goods, electronics, healthcare and pharmaceuticals, and paper and textile applications. Rising adoption of recycled and bio based chemicals, growing utilization of waste derived feedstocks, and increasing emphasis on resource efficiency are encouraging end users to integrate circular chemical solutions into their operations. Advancements in chemical recovery, recycling, biomass utilization, and carbon utilization are improving the efficiency and scalability of circular chemical production, enabling the development of solutions tailored to diverse industrial requirements. In addition, growing regulatory focus on waste reduction, resource conservation, and environmental sustainability is creating opportunities for manufacturers to expand their circular chemical portfolios.
The increasing focus on resource efficiency, waste reduction, and sustainable production practices is a primary factor driving the global circular economy chemicals market. Industries are increasingly adopting bio based, recycled, and carbon utilization chemicals to reduce dependence on conventional raw materials and improve resource utilization across packaging, automotive, building and construction, and chemical and petrochemical applications. Growing availability of biomass, plastic waste, and industrial waste as alternative feedstocks is further accelerating the transition toward circular chemical production. In addition, rising adoption across consumer goods, electronics, healthcare and pharmaceuticals, and paper and textile industries is expanding the application potential of circular economy chemicals.
In response to expanding sustainability requirements, manufacturers are increasing investments in product innovation, production capacity, and circular chemical technologies. Companies are developing chemical solutions based on recycled materials, renewable biomass, waste derived feedstocks, and carbon utilization pathways, enabling end users to improve material efficiency while supporting waste reduction objectives. Continuous advancements in circular production processes, coupled with growing demand for sustainable chemical solutions, are expected to support long term market growth and strengthen the adoption of circular economy chemicals across global industries.
Compliance with evolving environmental regulations and chemical management requirements represents a significant restraint for the global circular economy chemicals market. Circular economy chemicals produced from biomass, plastic waste, industrial waste, and other feedstocks must meet stringent requirements related to material quality, traceability, processing, environmental performance, and product safety established by regulatory authorities. Manufacturers must ensure compliance with applicable chemical regulations and industry standards, increasing the complexity of production, certification, distribution, and commercial operations across multiple end use industries.
The regulatory landscape also varies across global countries, requiring companies to adapt production processes, material specifications, documentation, and sustainability practices to meet country specific requirements. Circular economy chemicals manufacturers must invest in quality control systems, regulatory expertise, feedstock assessment, product testing, and certification processes to support market access and maintain customer confidence. These additional compliance costs and regulatory obligations can be particularly challenging for small and mid-sized manufacturers, potentially limiting production expansion and slowing the commercialization of new circular economy chemical products.
The increasing emphasis on resource efficiency, waste reduction, and sustainable production presents a significant opportunity for companies operating in the global circular economy chemicals market. Governments and industries are increasingly encouraging the adoption of recycled, bio based, and carbon utilization chemicals to reduce reliance on conventional feedstocks and improve resource efficiency. Growing utilization of biomass, plastic waste, and industrial waste as alternative feedstocks is creating opportunities for manufacturers to expand their customer base and strengthen their market presence across diverse end use industries.
Meanwhile, advancements in circular chemical production technologies are enabling the development of innovative solutions with improved material utilization, processing efficiency, and environmental performance. The development of application specific chemicals derived from renewable, recycled, and waste based feedstocks supports broader adoption across packaging, automotive, building and construction, electronics, consumer goods, and other industries. As demand for sustainable chemical solutions continues to increase, manufacturers investing in product innovation, capacity expansion, feedstock diversification, and circular production technologies are expected to capture significant long term growth opportunities.
Market Concentration & Characteristics
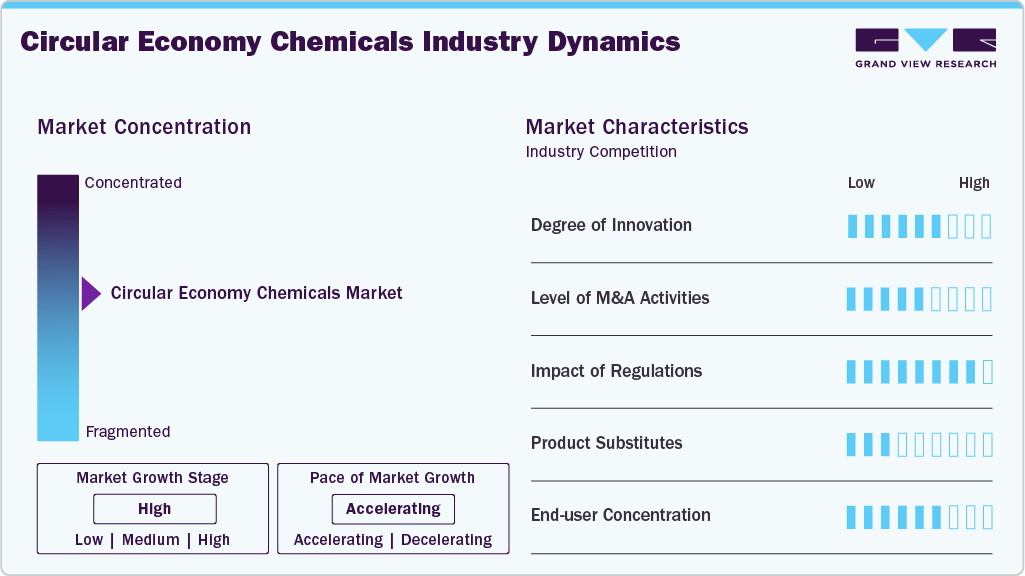
The global circular economy chemicals market is moderately consolidated, with competition centered on product portfolio, circular production capabilities, feedstock access, technology development, distribution networks, and long term partnerships with end use industries. Leading companies are expanding their bio based, recycled, and carbon utilization chemical portfolios to address growing demand across packaging, automotive, building and construction, consumer goods, electronics, and other applications. Investments in production capacity expansion, circular technology development, product innovation, feedstock diversification, and sustainability capabilities have become key competitive differentiators.
 To learn more about this report, Download Free Sample Report
Participants are also strengthening their position through strategic acquisitions, collaborative technology development, and expansion of regional manufacturing and distribution capabilities. Companies are increasingly working with end users to develop application specific circular chemical solutions tailored to packaging, automotive, building and construction, electronics, consumer goods, and chemical and petrochemical requirements. In addition, investments in circular production technologies, feedstock optimization, quality assurance programs, and research activities are enabling manufacturers to differentiate their offerings while meeting evolving sustainability requirements and customer expectations.
Analyst Perspective
The global circular economy chemicals market is driven by the increasing adoption of sustainable chemical solutions across diverse industrial applications. Growing demand for bio based and recycled chemicals, increasing utilization of alternative feedstocks, and rising emphasis on resource efficiency are supporting innovation across circular chemical production and applications. Advances in recycling, biomass utilization, and carbon utilization technologies are enhancing production capabilities and enabling broader market adoption. Companies that invest in product innovation, feedstock diversification, circular production technologies, and expanded manufacturing capabilities are expected to strengthen their competitive advantage and capitalize on evolving sustainability requirements.
Chemical Insights
Bio based chemicals segment held the largest revenue share of 35.0% in 2025. Increasing adoption of renewable raw materials, growing emphasis on reducing dependence on fossil based feedstocks, and rising demand for sustainable chemical alternatives are supporting the segment's market leadership. Their compatibility with circular production models and expanding use across packaging, consumer goods, automotive, and other end use industries continue to strengthen demand for bio based chemicals.
Carbon utilization chemicals segment is expected to grow at the fastest CAGR of 16.7% from 2026 to 2033. The growth is driven by increasing efforts to utilize captured carbon as a feedstock for chemical production, supporting resource efficiency and reducing reliance on conventional raw materials. Advancements in carbon utilization technologies and growing demand for lower impact chemical solutions are encouraging manufacturers to expand their offerings, while increasing adoption across diverse industrial applications is further supporting segment growth.
Feedstock Insights:
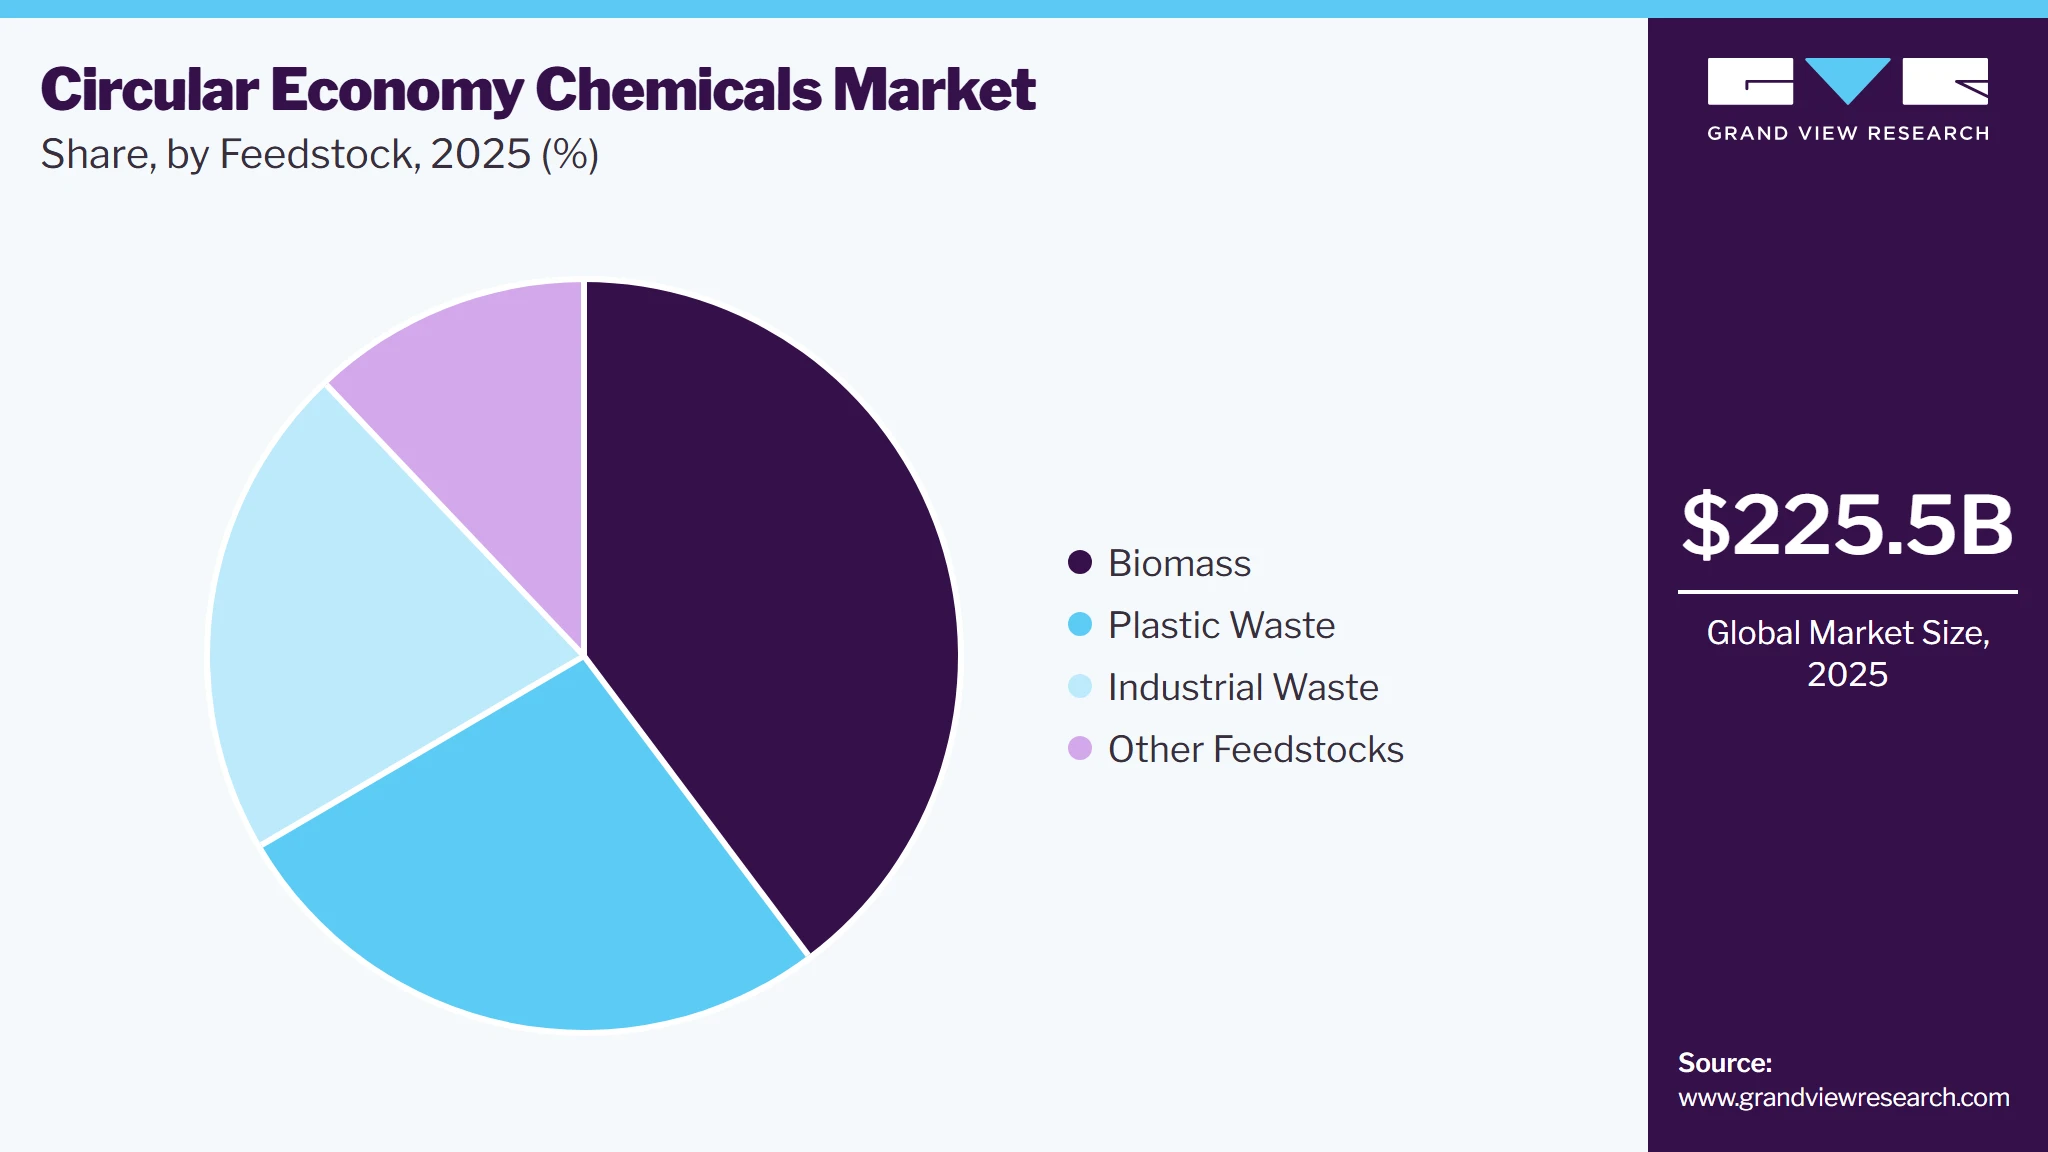
Biomass segment accounted for the largest revenue share of 39.8% in 2025, supported by its renewable availability and suitability as a feedstock for producing sustainable chemical solutions. Increasing efforts to reduce reliance on fossil based raw materials and growing adoption of renewable resources across chemical manufacturing are strengthening biomass utilization. Its expanding application in bio based chemical production and compatibility with circular production models are further supporting the segment's leading position.
 To learn more about this report, Download Free Sample Report
Plastic waste segment is projected to grow at the fastest CAGR of 16.1% from 2026 to 2033. Rising emphasis on plastic waste recovery, recycling, and conversion into valuable chemical feedstocks is accelerating segment growth. Advancements in chemical recycling technologies are improving the ability to convert waste plastics into usable chemical inputs, while increasing investments in waste management and resource recovery are creating further opportunities for plastic waste based chemical production.
End Use Insights
Packaging segment accounted for the largest revenue share of 22.7% in 2025, supported by increasing demand for sustainable materials and circular solutions across packaging production. Growing emphasis on resource efficiency, waste reduction, and the incorporation of recycled and bio based chemicals is encouraging packaging manufacturers to adopt circular chemical inputs. Rising sustainability requirements across the packaging value chain are further strengthening demand for circular economy chemicals within the industry.
Electronics segment is witnessing the fastest CAGR of 15.7% from 2026 to 2033. Increasing demand for resource efficient manufacturing and greater emphasis on waste recovery are supporting the integration of circular chemical solutions across electronics production. Growing adoption of recycled and bio based chemicals, together with advancements in circular material technologies, is creating opportunities for manufacturers to develop sustainable chemical inputs suited to evolving electronics industry requirements.
Regional Insights
Asia Pacific Circular Economy Chemicals Market Trends
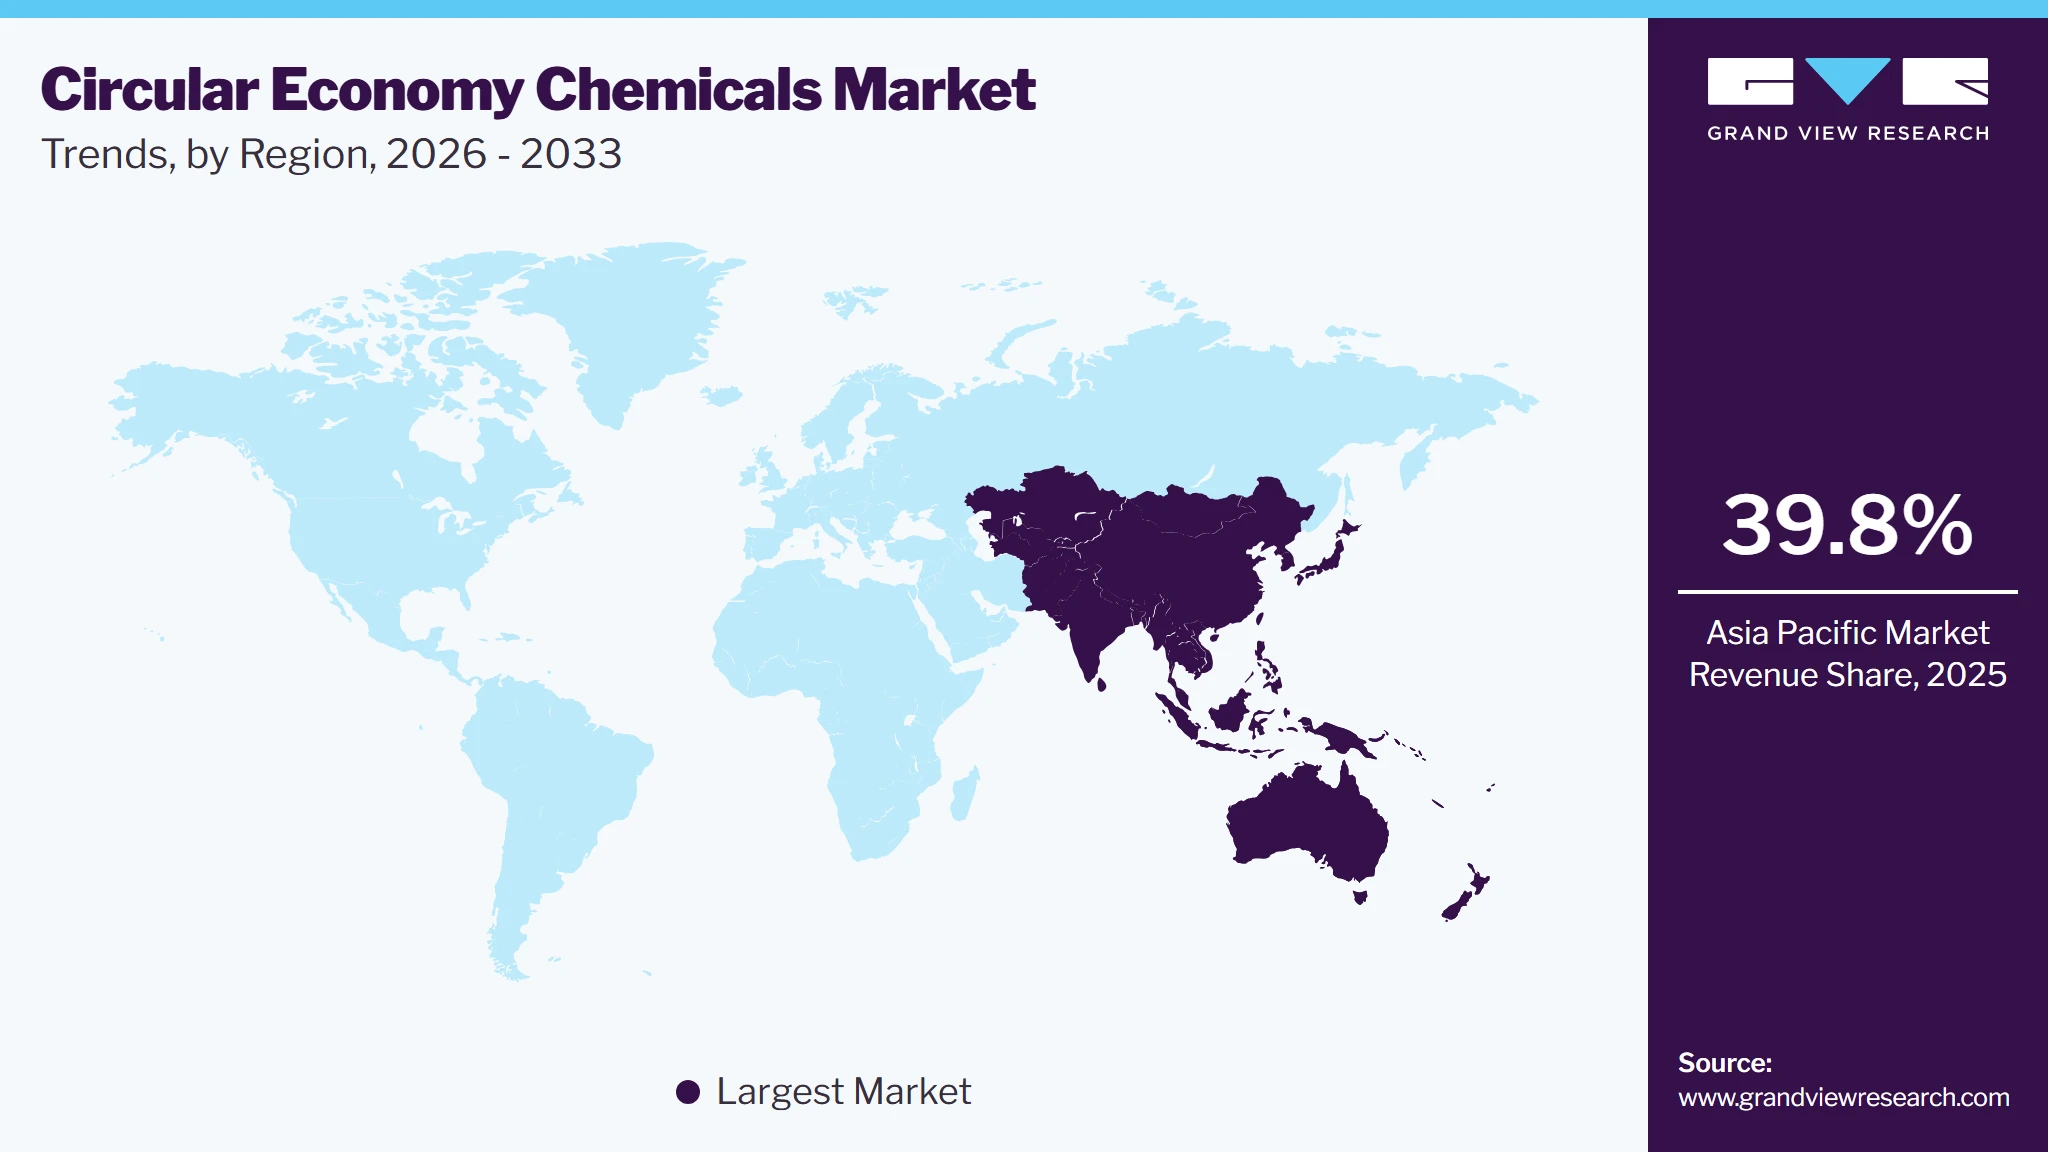
Circular economy chemicals market in Asia Pacific held the largest revenue share of 39.8% in 2025. The region's leading position is supported by expanding chemical manufacturing activities, growing availability of biomass, plastic waste, and industrial waste, and increasing adoption of circular production practices across major industries. Rising investments in recycling infrastructure, resource recovery, and sustainable manufacturing are supporting market development across the region. Growing demand for circular chemical solutions across packaging, automotive, electronics, and other industrial sectors continues to reinforce the region's market leadership.
 To learn more about this report, Download Free Sample Report
The China circular economy chemicals market represents a significant market within Asia Pacific, supported by its large chemical manufacturing base, substantial industrial activity, and increasing focus on resource efficiency. The country offers strong opportunities for circular chemical adoption due to the availability of industrial waste and plastic waste alongside growing emphasis on recycling and resource recovery. Increasing integration of recycled and bio based chemicals across packaging, automotive, electronics, and other manufacturing applications is supporting market growth.
North America Circular Economy Chemicals Market Trends
The North America circular economy chemicals market is supported by increasing emphasis on resource efficiency, waste reduction, and sustainable chemical production across major industries. The region represents a significant market due to established chemical manufacturing capabilities, growing investments in recycling and resource recovery infrastructure, and increasing adoption of circular production practices. Rising utilization of bio based, recycled, and carbon utilization chemicals across packaging, automotive, chemical and petrochemical, and consumer goods applications is supporting market growth.
U.S. Circular Economy Chemicals Market Trends
The U.S. circular economy chemicals market represents a leading market within North America, supported by advanced chemical manufacturing capabilities and growing emphasis on sustainable production practices. Increasing investments in recycling infrastructure, waste recovery, and circular chemical technologies are encouraging the adoption of alternative feedstocks and sustainable chemical solutions across the country. Growing demand from packaging, automotive, electronics, and other industrial applications is further contributing to market development.
Europe Circular Economy Chemicals Market Trends
The Europe circular economy chemicals market is supported by increasing emphasis on sustainable chemical production, resource efficiency, and waste reduction across major industries. The region represents a significant market due to established recycling infrastructure, strong environmental policies, and growing investments in circular production technologies. Increasing adoption of bio based and recycled chemicals, along with rising utilization of waste derived feedstocks across packaging, automotive, chemical and petrochemical, and consumer goods applications, is supporting market growth.
Latin America Circular Economy Chemicals Market Trends
The Latin America circular economy chemicals market is projected to grow at a CAGR of 13.5% from 2026 to 2033, driven by increasing adoption of sustainable chemical solutions, expanding waste recovery activities, and growing emphasis on resource efficiency. The region is witnessing greater utilization of biomass, plastic waste, and industrial waste as alternative feedstocks for chemical production. In addition, investments in recycling infrastructure, circular production capabilities, and sustainable manufacturing practices are creating new growth opportunities for circular economy chemicals across diverse industries.
Middle East & Africa Circular Economy Chemicals Market Trends
The Middle East & Africa circular economy chemicals market is supported by increasing focus on resource conservation, waste management, and diversification of chemical production practices. The region is witnessing growing interest in circular chemical solutions as industries seek to improve resource utilization and reduce dependence on conventional feedstocks. Increasing availability of industrial waste, investments in waste recovery and recycling infrastructure, and rising adoption of sustainable chemical solutions across packaging, construction, and other industrial applications are supporting market growth.
Key Circular Economy Chemicals Company Insights
Companies operating in the global circular economy chemicals market are adopting strategies centered on product innovation, circular production technologies, manufacturing expansion, feedstock diversification, and strategic collaborations to strengthen their competitive position. Leading chemical manufacturers are expanding their bio based, recycled, and carbon utilization chemical offerings to address growing demand across packaging, automotive, building and construction, electronics, consumer goods, and other industrial applications. They are also investing in advanced recycling technologies, resource recovery capabilities, and application specific solutions to improve resource efficiency and support evolving sustainability requirements across diverse end use industries.
-
BASF SE is a leading global chemical company offering a broad portfolio of chemical solutions across multiple industries. The company focuses on developing innovative and sustainable chemical solutions while leveraging its extensive manufacturing capabilities and research and development expertise. Its broad product portfolio, global presence, and focus on sustainable production enable the company to address evolving customer requirements and strengthen its position in the circular economy chemicals market.
-
SABIC is a global diversified chemicals company with a broad portfolio serving major industrial and consumer applications. The company focuses on developing sustainable chemical solutions and advancing circular approaches across its product portfolio, supported by its manufacturing capabilities and technical expertise. Its emphasis on resource efficiency, recycled materials, and innovative chemical solutions enables SABIC to address evolving sustainability requirements and strengthen its competitive position in the global circular economy chemicals market.
Key Circular Economy Chemicals Companies
The following key companies have been profiled for the study on the global circular economy chemicals market.
-
BASF SE
-
SABIC
-
LyondellBasell
-
The Dow Chemical
-
Eastman Chemical Company
-
Covestro AG
-
Mitsubishi Chemical Group
-
Evonik Industries
-
Arkema SA
-
LG Chem
Company Categorization
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: BASF SE, SABIC, LyondellBasell, The Dow Chemical, Eastman Chemical Company, Covestro AG, Mitsubishi Chemical Group, Evonik Industries, Arkema SA.
- Invest heavily in research and development to develop advanced circular chemical solutions using recycled, renewable, and alternative feedstocks.
- Expand through strategic collaborations, capacity expansion, acquisitions, and strengthening global manufacturing and distribution networks.
- Strengthen circularity initiatives and technology capabilities to address evolving sustainability requirements and regulatory standards.
- Extensive chemical manufacturing capabilities support large scale production and broad product availability.
- Strong technical expertise and diversified chemical portfolios enable solutions across multiple end use industries.
- Established global presence, financial strength, and long standing customer relationships reinforce competitive positioning.
- Large organizational structures can result in slower decision making and market responsiveness.
- High operational, manufacturing, technology development, and compliance costs can affect cost competitiveness.
- Complex global operations can increase supply chain and feedstock management challenges.
Emerging Players: LG Chem
- Focus on expanding sustainable and circular chemical product offerings and strengthening presence across global markets.
- Develop application specific solutions using recycled and renewable feedstocks to address growing demand for sustainable materials.
- Strengthen strategic partnerships, technology development, and circular production capabilities to improve market reach.
- Strong chemical manufacturing expertise and technical capabilities support product development and commercialization.
- Broad presence across major industrial applications provides opportunities to integrate circular chemical solutions across value chains.
- Investment in sustainable materials and technology development supports differentiation in emerging circular chemical applications.
- Relatively smaller circular economy portfolio compared with the most established global circular chemical leaders.
- Scaling new circular production technologies can require significant capital investment and technological development.
- Dependence on evolving feedstock availability, recycling infrastructure, and market adoption can create commercialization challenges.
Circular Economy Chemicals Market Report Scope
Report Attribute
Details
Market size in 2025
USD 225.5 billion
Estimated market size in 2026
USD 256.0 billion
Projected market size by 2033
USD 621.1 billion
Growth rate
CAGR of 13.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Chemical, feedstock, end use, region
Regional Scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
BASF SE; SABIC; LyondellBasell; The Dow Chemical; Eastman Chemical Company; Covestro AG; Mitsubishi Chemical Group; Evonik Industries; Arkema SA; LG Chem
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Circular Economy Chemicals Market Report Segmentation
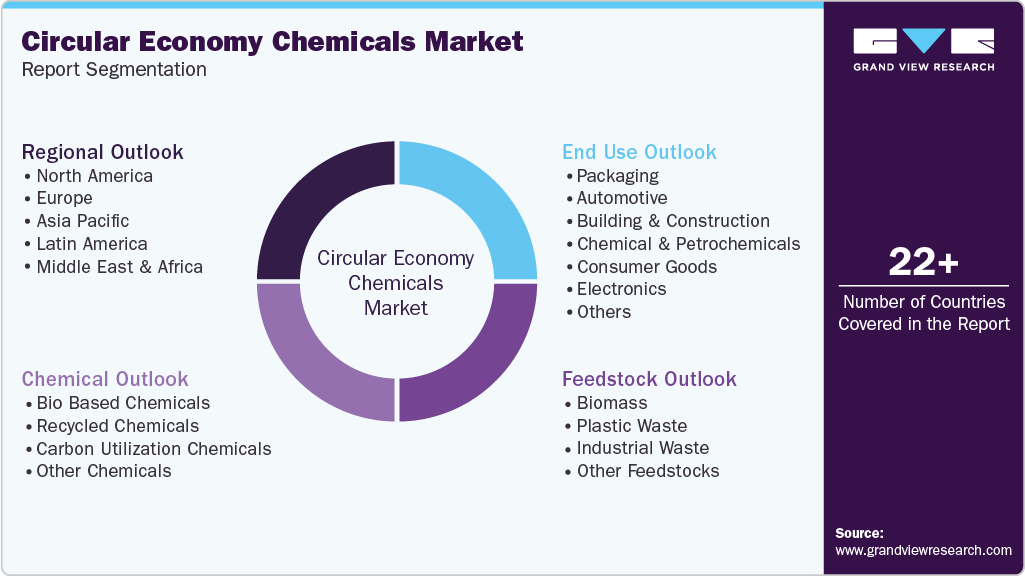
This report forecasts volume & revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global circular economy chemicals market report based on chemical, feedstock, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Chemical Outlook (Revenue, USD Billion; Volume, Kilotons, 2021 - 2033)
-
Bio Based Chemicals
-
Recycled Chemicals
-
Carbon Utilization Chemicals
-
Other Chemicals
-
-
Feedstock Outlook (Revenue, USD Billion; Volume, Kilotons, 2021 - 2033)
-
Biomass
-
Plastic Waste
-
Industrial Waste
-
Other Feedstocks
-
-
End Use Outlook (Revenue, USD Billion; Volume, Kilotons, 2021 - 2033)
-
Packaging
-
Automotive
-
Building and Construction
-
Chemical and Petrochemicals
-
Consumer Goods
-
Electronics
-
Healthcare and Pharmaceuticals
-
Paper and Textile
-
Other End Use Industries
-
-
Region Outlook (Revenue, USD Billion; Volume, Kilotons, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The circular economy chemicals market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each circular economy chemicals segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Chemical
Revenue capture definition
Bio Based Chemicals
Market value is generated through the commercial production and supply of chemicals derived from renewable biological resources such as biomass. Growing emphasis on reducing dependence on conventional fossil based raw materials and increasing adoption of renewable feedstocks across diverse industries support market demand.
Recycled Chemicals
Revenue is generated through the production and commercialization of chemicals recovered or manufactured from recycled materials and waste streams. Increasing emphasis on resource recovery, waste reduction, and material circularity is supporting adoption across packaging, automotive, consumer goods, and other industrial applications.
Carbon Utilization Chemicals
Market value is created through chemicals produced by utilizing captured or recovered carbon as a feedstock for chemical manufacturing. Growing focus on carbon utilization, resource efficiency, and development of alternative raw material pathways is supporting adoption and creating opportunities across diverse industrial applications.
Other Chemicals
Revenue is generated through circular chemical solutions that do not fall within bio based, recycled, or carbon utilization chemical categories. These products support resource efficiency and circular production objectives across various industrial applications and contribute to the broader transition toward sustainable chemical manufacturing.
Segment – Feedstock
Revenue capture definition
Biomass
Market value is generated through the utilization of renewable biological materials as feedstocks for chemical production. Growing availability of biomass and increasing efforts to replace conventional raw materials with renewable alternatives are supporting its use in the production of bio based and other circular chemical solutions.
Plastic Waste
Revenue is generated through the collection, processing, recycling, and conversion of plastic waste into chemical feedstocks and value added chemical products. Increasing focus on plastic waste recovery, resource conservation, and chemical recycling is supporting the adoption of plastic waste as a circular feedstock.
Industrial Waste
Market value is created through the utilization and recovery of industrial waste streams as alternative feedstocks for chemical production. Increasing emphasis on waste valorization, resource efficiency, and reduction of industrial waste disposal is encouraging manufacturers to integrate recovered industrial materials into circular chemical production processes.
Other Feedstocks
Revenue is generated through the utilization of feedstocks other than biomass, plastic waste, and industrial waste in circular chemical production. These alternative resources support feedstock diversification and enable manufacturers to improve resource utilization while developing sustainable chemical solutions for different industrial requirements.
Segment – End-Use
Revenue capture definition
Packaging
Market value is generated through the utilization of circular economy chemicals in packaging production and related processes. Increasing demand for sustainable packaging materials, greater incorporation of recycled and bio based chemical inputs, and emphasis on waste reduction support adoption across the packaging industry.
Automotive
Revenue is generated through the adoption of circular economy chemicals in automotive materials, components, manufacturing processes, and related applications. Growing emphasis on lightweight materials, resource efficiency, recycled inputs, and sustainable vehicle manufacturing is supporting the integration of circular chemical solutions across the automotive value chain.
Building and Construction
Market value is created through the use of circular economy chemicals across construction materials, building products, coatings, and related applications. Increasing focus on sustainable construction, material efficiency, recycled inputs, and reduction of resource consumption is supporting demand for circular chemical solutions within the industry
Chemical and Petrochemicals
Revenue is generated through the integration of circular economy chemicals into chemical and petrochemical manufacturing processes and product portfolios. Increasing efforts to diversify feedstocks, incorporate recycled and renewable inputs, and improve resource efficiency are supporting adoption across the chemical and petrochemical industry.
Consumer Goods
Market value is generated through the use of circular economy chemicals in consumer products and related manufacturing processes. Growing consumer and industry emphasis on sustainable materials, recycled content, renewable feedstocks, and waste reduction is encouraging manufacturers to incorporate circular chemical solutions across consumer goods applications.
Electronics
Revenue is generated through the utilization of circular economy chemicals in electronic components, materials, manufacturing processes, and related applications. Increasing emphasis on resource efficiency, recovery of valuable materials, and sustainable electronics production is supporting the adoption of recycled, bio based, and other circular chemical solutions.
Healthcare and Pharmaceuticals
Market value is created through the adoption of circular economy chemicals across healthcare products, pharmaceutical manufacturing, packaging, and related applications. Increasing focus on sustainable production, resource efficiency, and responsible material utilization is creating opportunities for circular chemical solutions within healthcare and pharmaceutical value chains.
Paper and Textile
Revenue is generated through the use of circular economy chemicals in paper, textile, fiber, and related manufacturing applications. Growing emphasis on sustainable production, recycled inputs, renewable feedstocks, and resource conservation is supporting the integration of circular chemical solutions across paper and textile value chains.
Other End Use Industries
Market value is generated through the utilization of circular economy chemicals across end use industries outside the major segments covered in this study. Increasing adoption of sustainable chemical solutions, alternative feedstocks, and resource efficient production practices is supporting market opportunities across additional industrial applications.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Feedstock & Production Layer
What forms the supply base?
Identify the sourcing, processing, and production of circular economy chemicals using biomass, plastic waste, industrial waste, and other feedstocks. Evaluate feedstock availability, sourcing practices, processing technologies, production capacities, material quality, supply chain dynamics, and key production hubs supporting the commercial availability of circular economy chemicals across global markets.
02
Chemical Adoption Layer
What types of circular economy chemicals are produced and utilized?
Assess the production and adoption of bio based chemicals, recycled chemicals, carbon utilization chemicals, and other circular chemical solutions. The assessment considers technology pathways, feedstock utilization, production capabilities, sustainability objectives, and increasing demand for alternative chemical inputs across diverse industrial applications.
03
End Use Consumption Layer
Where are circular economy chemicals consumed?
Analyze circular economy chemicals consumption across packaging, automotive, building and construction, chemical and petrochemicals, consumer goods, electronics, healthcare and pharmaceuticals, paper and textile, and other end use industries. The assessment considers industry production activity, adoption of circular chemical inputs, regional consumption patterns, and evolving sustainability requirements to estimate annual consumption across global markets.
04
Revenue Layer
How is market revenue generated?
Market revenue is generated through the production, processing, formulation, distribution, and commercial sale of circular economy chemicals derived from renewable, recycled, waste based, and carbon utilization feedstocks. Revenue growth is supported by increasing emphasis on resource efficiency, waste reduction, alternative feedstock utilization, and the adoption of sustainable chemical solutions across diverse end use industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
The assessment includes country level market size and forecasts; demand patterns by chemical type, feedstock, and End-Use; consumption trends across packaging, automotive, building and construction, chemical and petrochemicals, consumer goods, electronics, healthcare and pharmaceuticals, paper and textile, and other industries; regulatory developments; domestic production and trade dynamics; competitive landscape; distribution networks; industry trends; and investment opportunities shaping the circular economy chemicals market across each country.
Supports production planning, supplier evaluation, and market entry strategy development by providing visibility into feedstock availability, production capabilities, regional demand patterns, and supply chain dynamics. Helps identify high growth markets while improving sourcing decisions, distribution strategies, and long term investment planning.
Opportunity Assessment
Detailed evaluation of emerging growth opportunities across bio based chemicals, recycled chemicals, carbon utilization chemicals, and other circular chemical solutions. The assessment covers increasing utilization of biomass, plastic waste, and industrial waste as feedstocks, technological advancements in recycling and circular chemical production, evolving sustainability requirements, and opportunities created by expanding adoption across diverse end use industries.
Enables prioritization of high growth chemical, feedstock, and end use segments while identifying investment opportunities across the global circular economy chemicals value chain. Supports strategic expansion, product innovation, feedstock diversification, manufacturing investments, and sustainability initiatives through insights into evolving industry requirements, technology developments, and long term market demand.
Competitive Benchmarking
Comparative assessment of leading global circular economy chemicals manufacturers based on product portfolio, circular production capabilities, feedstock utilization, manufacturing footprint, technology expertise, regional presence, distribution network, strategic partnerships, sustainability initiatives, and expansion strategies. The benchmarking also evaluates capabilities across bio based, recycled, and carbon utilization chemicals and their applications across key end use industries.
Supports benchmarking against key competitors while identifying gaps in product portfolios, circular production capabilities, feedstock access, technology development, and market reach. Enables informed decision making related to strategic partnerships, capacity expansion, portfolio enhancement, feedstock sourcing, market expansion, and long term competitive positioning within the global circular economy chemicals market.
Frequently Asked Questions About This Report
The global circular economy chemicals market size was estimated at USD 225.5 billion in 2025 and is expected to reach USD 256.0 billion in 2026.
The circular economy chemicals market is expected to grow at a compound annual growth rate of 13.5% from 2026 to 2033, reaching USD 621.1 billion by 2033.
Bio based chemicals accounted for the largest share of the circular economy chemicals market, representing 35.0% of total revenue in 2025. Their leading position reflects strong adoption of bio based chemical solutions within the circular economy framework and increasing emphasis on sustainable chemical production.
Some of the key players operating in the circular economy chemicals market include BASF SE, SABIC, LyondellBasell, The Dow Chemical Company, Eastman Chemical Company, Covestro AG, Mitsubishi Chemical Group, Evonik Industries, Arkema SA, and LG Chem.
Asia Pacific dominated the circular economy chemicals market, accounting for 39.8% of total revenue in 2025. The region's leading position reflects its substantial chemical manufacturing base and growing adoption of circular economy practices across industries.
The circular economy chemicals market is driven by the growing adoption of sustainable chemical solutions, increasing utilization of alternative feedstocks, and rising focus on resource efficiency. The transition toward circular production models is also supporting demand for bio based chemicals, recycled feedstocks, and carbon utilization solutions.
The biomass segment held the largest revenue share of 39.8% in 2025.
The packaging segment led the market, accounted for the largest revenue share of 22.7% in 2025.
About the Author(s)
Renewable Chemicals Research Team
Specialty & Chemicals · Renewable ChemicalsThis report was authored by the renewable chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable chemicals segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


