
- Home
- »
- Automotive & Transportation
- »
-
Commercial Aircraft Landing Gear Market Size Report, 2033GVR Report cover

Commercial Aircraft Landing Gear Market (2026 - 2033)
Size, Share & Trends Analysis Report By Gear Position (Main Landing, Nose Landing), By Component, By Aircraft, By Arrangement (Tricycle, Tandem, Tailwheel), By Region, And Segment Forecasts
Market Size, 2025
$2.9BMarket Estimate, 2026
$3.1BMarket Forecast, 2033
$5.3BCAGR, 2026–2033
8.1%Commercial Aircraft Landing Gear Market Summary
The global commercial aircraft landing gear market size was valued at USD 2.9 billion in 2025 and is projected to grow from USD 3.1 billion in 2026 to USD 5.3 billion by 2033, at a CAGR of 8.1% from 2026 to 2033. North America dominated the market with the largest revenue share of 29.0% in the global market in 2025. The expansion in the fleet size of major airlines and the surging growth in the commercial aviation sector are expected to drive demand for new airliners and, consequently, for landing gear.
Key Market Trends & Insights
- By gear position: The main landing gear segment held the largest market share of around 64.0% in 2025.
- By aircraft: The narrow-body segment held the largest market share of approximately 59.0% in 2025.
- By arrangement: The tricycle segment held the largest market share of over 65.0% in 2025.
- By component: The landing gear steering system segment held the largest market share of around 39.0% in 2025.
Regional Highlights
- Largest regional market: North America (29.0% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Estimated Market size in 2026: USD 3.1 Billion
- Projected market size by 2033: USD 5.3 Billion
- Market size in 2025: USD 2.9 Billion
- CAGR (2026-2033): 8.1%
Prism AI by Grand View Research Free to tryAsk a question about the commercial aircraft landing gear marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The civil aviation sector is expected to grow significantly due to the rise in next-generation aircraft. Improvements in global economic conditions have led to an increase in air passenger traffic worldwide. There has been a steep increase in commercial airplanes to cater to the increasing demand for air travel. This growth in commercial aircraft is expected to drive demand for commercial aircraft landing gear systems.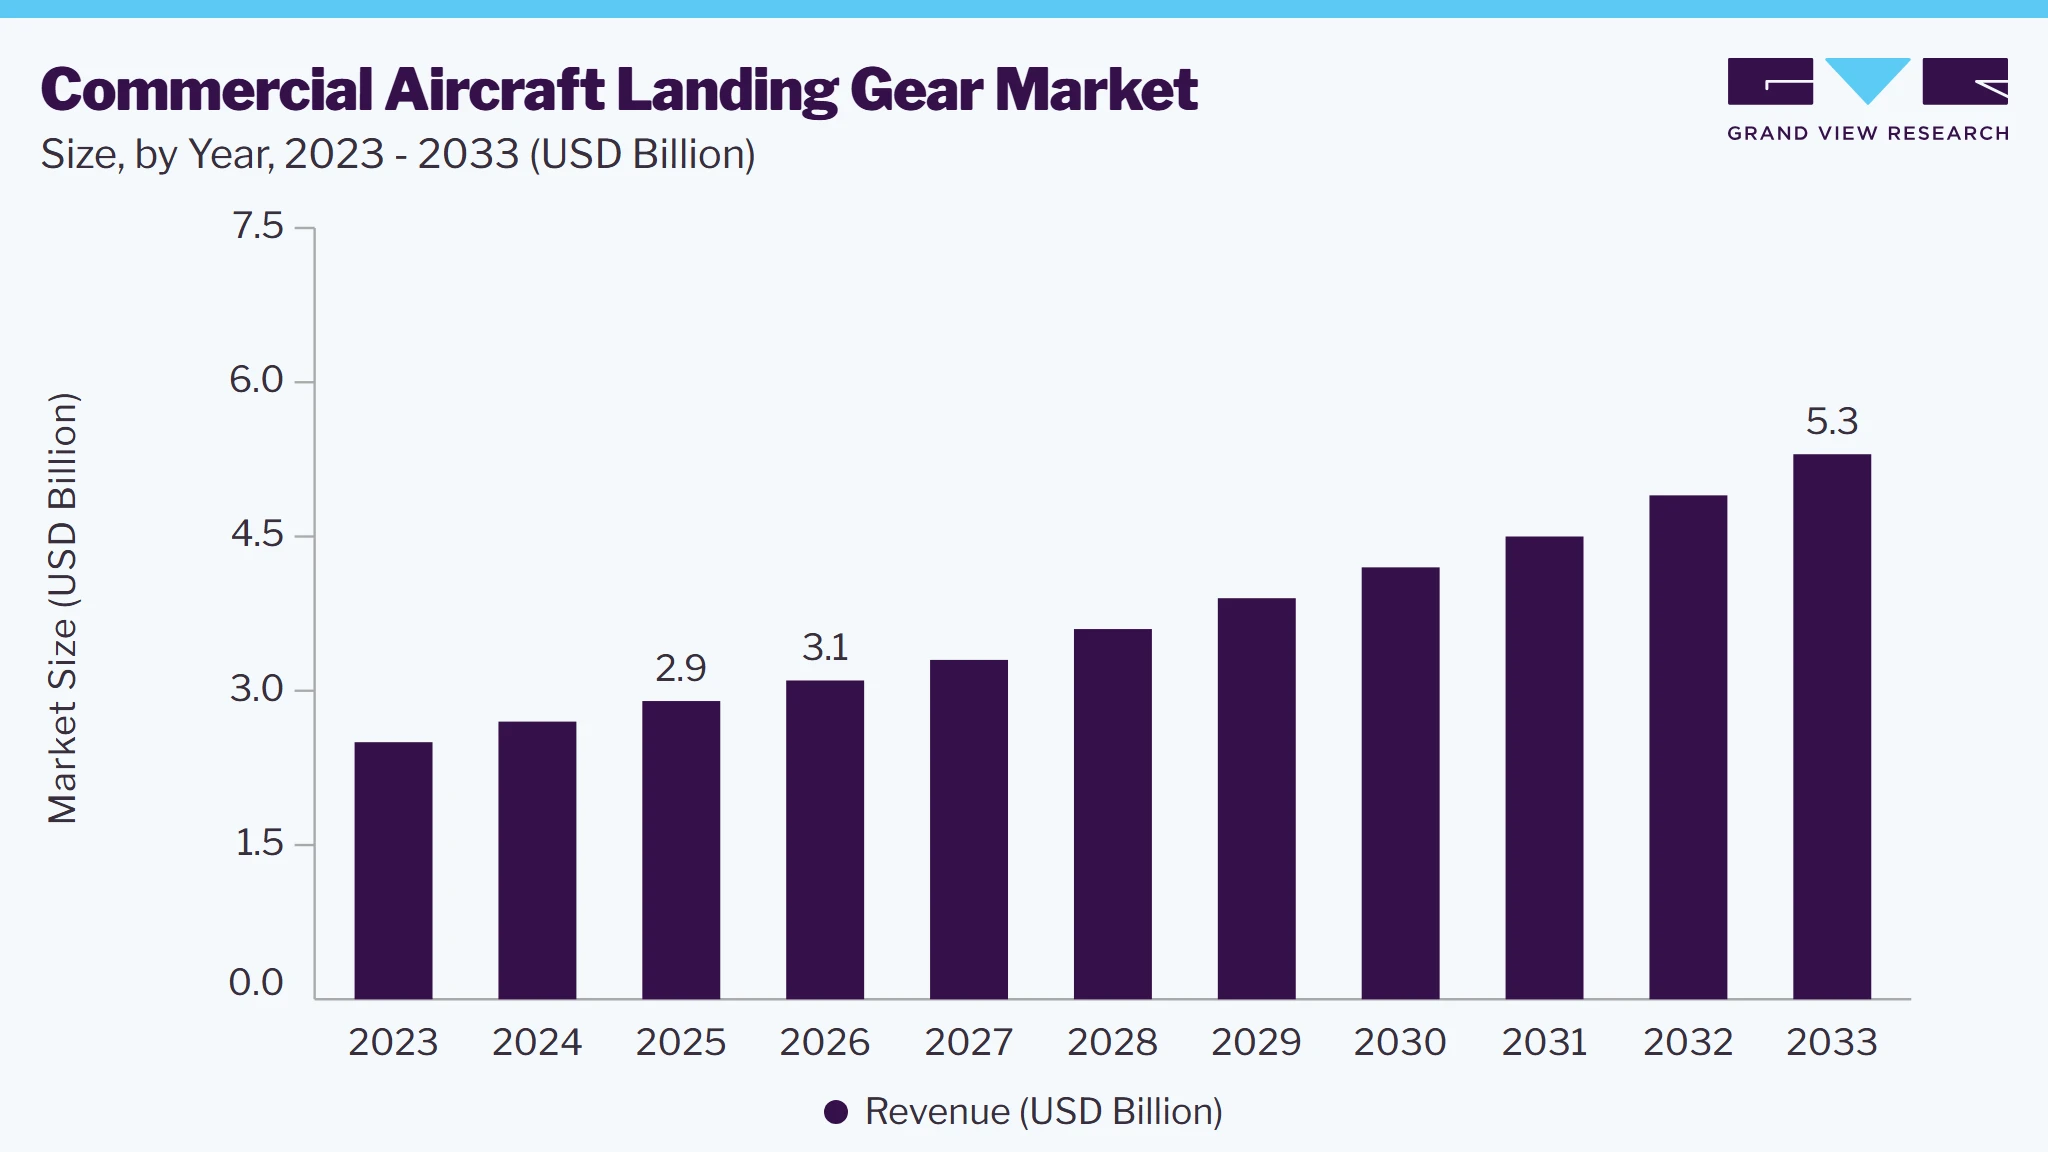 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Airplane manufacturers now use lightweight materials, electronic technologies, and innovative solutions to optimize overall aircraft performance during touchdowns and reduce aircraft downtime. These new systems require a lower degree of maintenance than their traditional counterparts. The increasing need for more fuel-efficient and eco-friendly airliners to replace the older ones is expected to drive the industry over the next eight years.
The global commercial aircraft landing gear industry is expanding rapidly. Technologically advanced control systems are increasingly replacing manually-controlled hydraulic and mechanical systems. Moreover, the competition among the industry incumbents across the value chain is increasing considerably.
The changing global economy transforms the global industry. However, challenges, such as increasing energy costs, expensive raw materials, and U.S. dollar inflation, are expected to challenge the industry's growth in the future. To overcome these obstacles, various players across the value chain, from OEMs to component & raw material suppliers, have started developing new business processes to benefit from the rapid globalization of the industry.
Market Dynamics
The increasing number of air travelers worldwide and the continuous expansion of commercial aircraft fleets are major factors driving the growth of the commercial aircraft landing gear industry. The ongoing increased demand for domestic and international air travel, especially in developing countries, has led airlines to spend large amounts on procuring new aircraft. The growing expansion of low-cost carriers, increasing tourist numbers, and increasing disposable incomes have led to increased aircraft deliveries throughout the world. Landing gear systems are integral parts of every aircraft, so an increase in aircraft production is favorable for the landing gear market. Aircraft manufacturers are developing new, fuel-efficient aircraft, leading to the demand for new generations of landing gear systems. Growing investments in airport infrastructure and fleet modernization programs are also expected to support the long-term growth of the market.
The high costs associated with the manufacturing, maintenance, and certification of landing gear systems remain a significant challenge for market growth. The landing gear of an aircraft is the most vital component of an aircraft, which needs to bear a considerable amount of stress during the process of taking off, landing, and moving on the ground. Therefore, aircraft manufacturers are obliged to employ highly durable materials, exacting engineering techniques, and rigorous testing practices for manufacturing safe and reliable landing gears. In addition, the imposition of aviation regulations and certifications adds to the time and cost associated with the production. These factors can create financial pressures for both manufacturers and operators, potentially limiting market growth.
The expansion of aircraft maintenance, repair, and overhaul (MRO) services and the rapid growth of the aviation sector in emerging economies present significant opportunities for the commercial aircraft landing gear industry. China, India, Indonesia, and many Middle Eastern countries are investing in airport expansions, aircraft fleets, and the development of air transportation facilities for passengers. A larger fleet of aircraft will continuously require maintenance, landing gear replacement, and overhaul due to high aircraft usage. These developments, combined with increasing aircraft deliveries and fleet modernization initiatives, are expected to create attractive growth opportunities for market participants over the forecast period.
Analyst Perspective
The commercial aircraft landing gear industry is expected to grow steadily, supported by rising global air passenger traffic, fleet modernization, and increasing demand for fuel-efficient and lightweight aircraft. Partnerships with OEMs, advanced manufacturing capabilities, adherence to safety regulations, and long-term service contracts play a crucial role. The competitive landscape will be dominated by the early adopters of lightweight materials, advanced composites, electric braking systems, and predictive maintenance technologies. Market leaders will differentiate through technological innovation, reliability, certification compliance, and integrated lifecycle support services. Electrification, digitalization, and sustainability-focused aircraft design requirements are likely to shape the future market growth across the globe.
Gear Position Insights
The gear position segment is categorized into main and nose landing gears. The main landing gear held the largest market share of around 64.0% in 2025. Main landing gear is estimated to dominate the market over the next eight years as they constitute one of the primary requirements for aircraft. The main landing gear bears most of the aircraft's weight during landing and takeoff. It is responsible for absorbing the impact forces and providing stability to the aircraft. The main gear typically consists of larger, more robust components than the nose gear, enabling it to handle higher loads and withstand the stresses of landing. This load-bearing component is crucial for ensuring the safe operation of commercial aircraft, making the main landing gear a critical component.
The nose landing gear segment is projected to register a significant CAGR over the forecast period. Advances in aircraft technology have led to the development of more efficient and capable aircraft models. These advancements often include improvements to landing gear systems, such as the nose landing gear. Upgraded nose landing gear offers enhanced reliability, durability, and performance, which can improve overall aircraft safety and efficiency.
Aircraft Insights
The narrow-body segment dominated the market with the largest revenue share of approximately 59.0% in 2025. The narrow-body segment is also expected to witness notable CAGR over the forecast period. Rising passenger traffic in Low-Cost Carriers (LCCs) and a growing number of high-density flights between major airports are expected to drive the demand for such aircraft. Airlines across developed economies, such as the U.S. and Germany, face growing competition from LCCs, as these carriers are transforming older, fuel-inefficient airplanes with new economic single-aisle models. Moreover, increased demand for replacing aging airliners, especially in emerging markets, is expected to further drive the need for commercial airplanes over the forecast period.
The wide-body segment is expected to witness a significant CAGR over the forecast period. Wide-body aircraft are designed to be more fuel-efficient, allowing airlines to operate long-haul flights with lower fuel consumption per passenger. They often incorporate advanced technologies, such as improved aerodynamics, lighter materials, and more efficient engines. By reducing fuel consumption and emissions, wide-body aircraft help airlines meet environmental regulations and reduce operating costs. The demand for these fuel-efficient wide-body aircraft leads to the expansion of the market as manufacturers develop landing gear systems that can handle the unique requirements of these larger and more efficient aircraft.
Arrangement Insights
The tricycle segment dominated the market with the largest revenue share of over 65.0% in 2025. The tricycle is the most widely used arrangement globally, providing better visibility from the flight deck during ground maneuvering. Such an arrangement provides a safe distance between the other aircraft's components, such as the fuselage and wings, when the airplane is on the ground.
The tandem segment is expected to grow at the fastest CAGR over the forecast period. The tandem segment is expected to grow over the forecast period as it allows for flexible wings with gears under the fuselage. The tail and main gears are aligned on the airplane's longitudinal axis in such an arrangement. Few airliners, including sailplanes, are designed with tandem gears. The tailwheels segment accounted for a considerable market share in 2025, and these landing gears are mostly used in traditional or small airplanes.
Components Insights
The landing gear steering system segment dominated the market, with the highest revenue share of around 39.0% in 2025. The dominance in the landing gear market is determined by load-bearing components, structural design, complexity, and overall performance rather than the steering system alone. The main landing gear, with its weight distribution, load-bearing components, and structural design, remains the primary factor in the market.
On the other hand, the actuation system segment is expected to grow at a significant CAGR over the forecast period. Actuation systems play a crucial role in the performance and safety of commercial aircraft landing gear. These systems are responsible for deploying and retracting the landing gear and providing stability and control during landing and takeoff. Advanced actuation systems offer improved reliability, precision, and responsiveness, which are highly valued in the aviation industry. The focus on safety and performance makes actuation systems a key component of commercial aircraft landing gear, driving their dominance in the market.
Regional Insights
North America Commercial Aircraft Landing Gear Market Trends
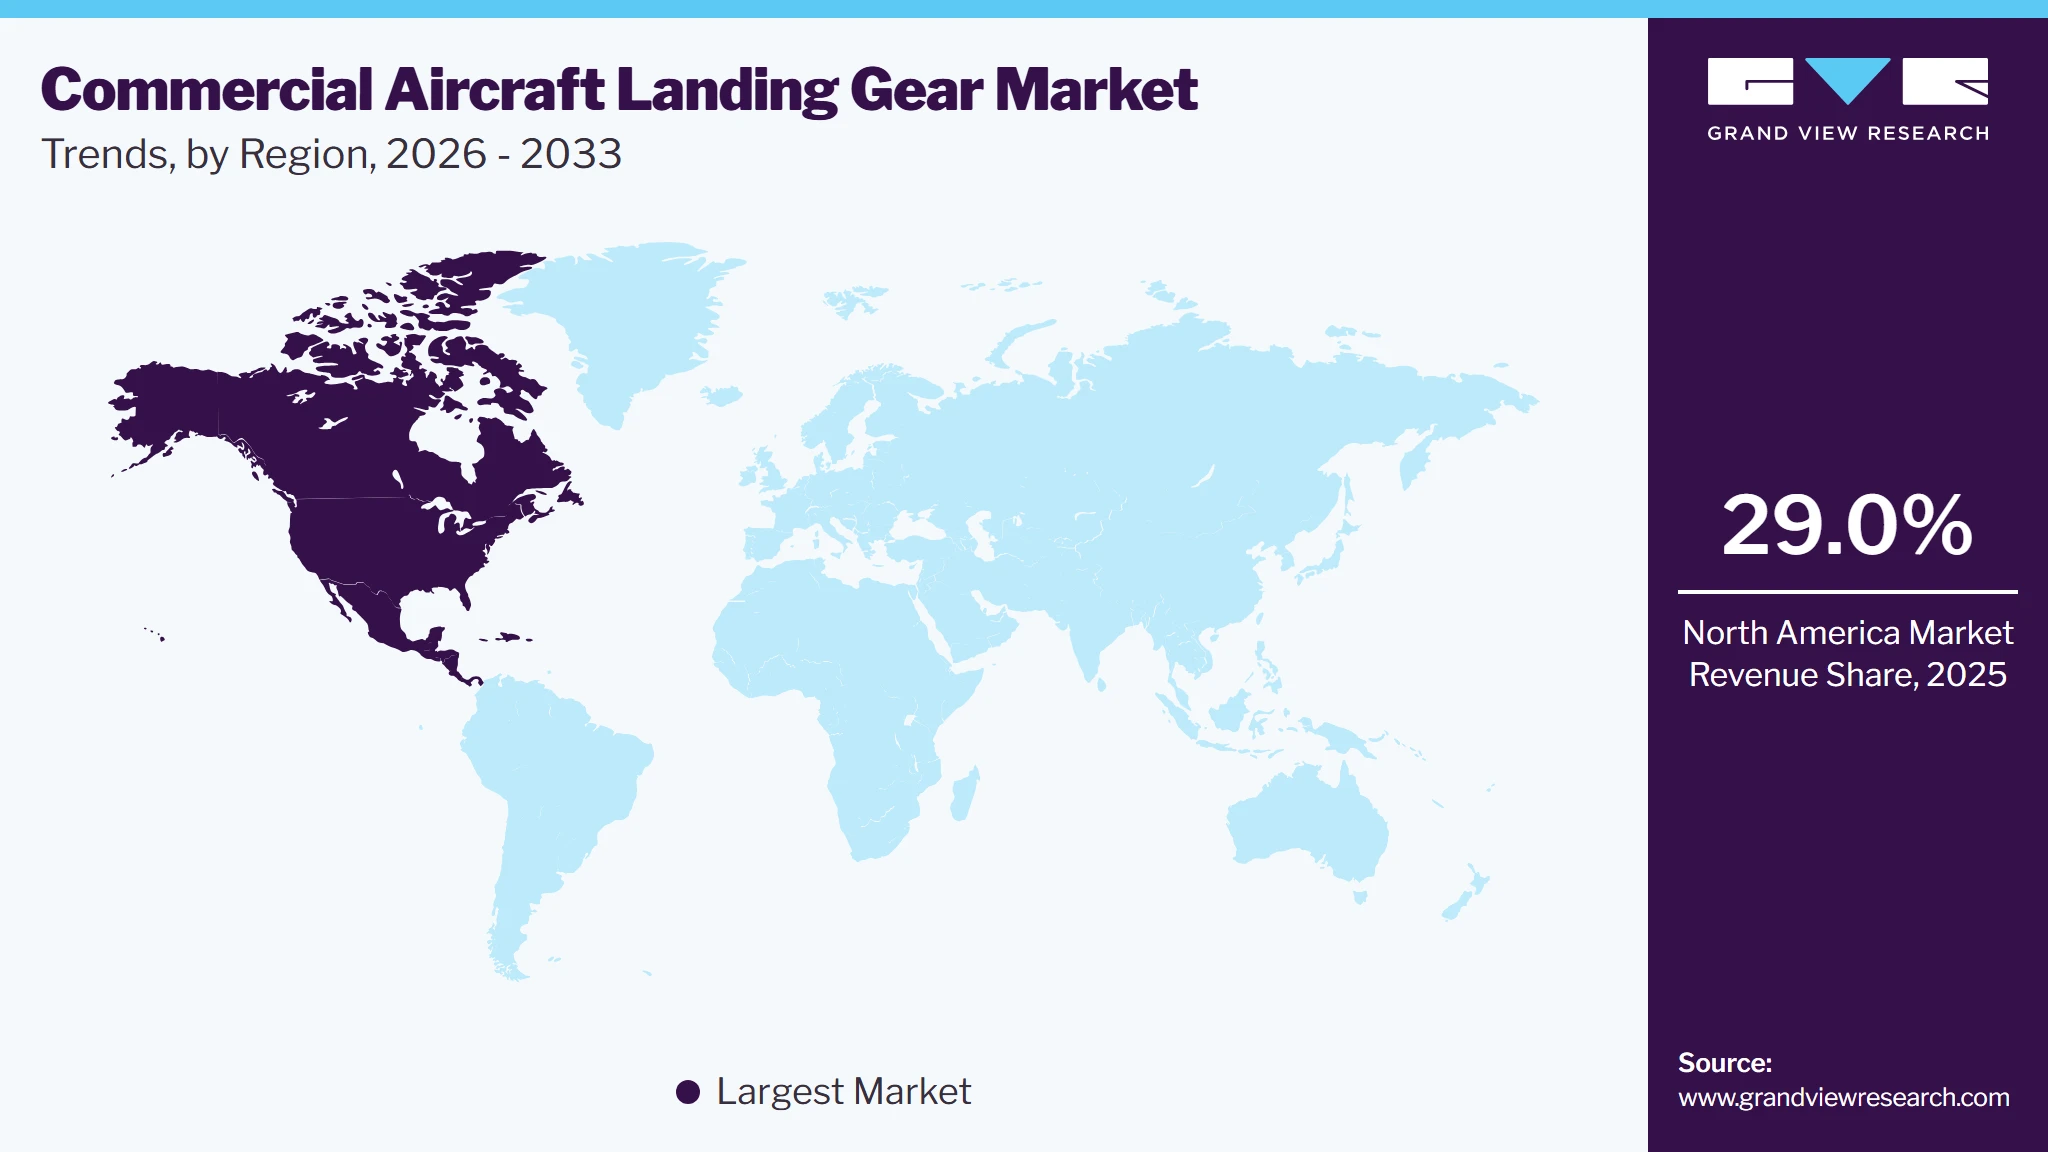
The North America commercial aircraft landing gear industry dominated, with the largest revenue share of around 29.0% in 2025. North America boasts a significant number of airlines and aircraft fleet operators. Major carriers, including American Airlines, United Airlines, Delta Air Lines, and Southwest Airlines, are headquartered in the region. These airlines operate extensive domestic and international networks, requiring many aircraft and corresponding landing gear systems. The demand generated by North American fleet operators drives the market for commercial aircraft landing gear, providing a favorable environment for North American manufacturers to thrive.
 To learn more about this report, Download Free Sample Report
Asia Pacific Commercial Aircraft Landing Gear Market Trends
The Asia Pacific commercial aircraft landing gear industry is expected to grow at the fastest CAGR during the forecast period. Asia Pacific is presumed to emerge as the dominant region over the forecast period due to the growing demand for commercial aircraft across developing countries, such as Japan and India. The demand for commercial aviation is increasing due to the growing income levels of the middle-class society, making flying more affordable. The region is expected to achieve unprecedented long-term growth in commercial aviation. This growth is anticipated to generate substantial economic contribution from commercial aerospace and facilitate general growth in developing economies through the catalytic effect of increased global connectivity.
Key Commercial Aircraft Landing Gear Company Insights
The global market for commercial aircraft landing gear is dynamic. Companies in the marketplace are transforming their gear positions and solutions to provide cost-effective systems to aircraft manufacturers. The key manufacturers are increasingly forming long-term agreements with suppliers to effectively manage their profit margins and inventory flow. Other strategies undertaken by key companies include developing new gear positions and service lines.
Key Commercial Aircraft Landing Gear Companies
The following key companies have been profiled for this study on the commercial aircraft landing gear market.
-
AAR
-
Advantage Aviation Technologies
-
CIRCOR AEROSPACE PRODUCTS GROUP
-
Eaton
-
Héroux-Devtek
-
Honeywell International Inc.
-
Magellan Aerospace Corporation
-
Liebherr
-
MAG Inc.
-
Sumitomo Precision Products Co., Ltd. (SPP)
-
Safran Landing Systems
-
UTC Aerospace Systems (United Technologies Corporation (UTC))
-
Triumph Group
-
Whippany Actuation Systems
Recent Developments
-
In August 2025, AAR Corp. acquired Aerostrat, a provider of aviation maintenance planning software, strengthening its maintenance, repair, and overhaul (MRO) capabilities. Improved maintenance planning can support more efficient scheduling of aircraft inspections and component overhauls, potentially contributing to demand for landing gear inspection, repair, and replacement services across the commercial aviation aftermarket..
-
In June 2025, Safran Landing Systems renewed and broadened its long-term cooperation with Revima through the conclusion of a new contract for the supply of spare parts and technical assistance. This cooperation, dedicated to landing gear MRO operations on the following Airbus aircraft - A320ceo, A320neo, A330, A330neo, A350 - is aimed at enhancing aftermarket support on the new-generation landing gear platforms and will take place at Revima's facilities in France and Thailand.
-
In April 2025, AAR finalized the divestiture of its Landing Gear Overhaul business to GA Telesis for a value of USD 51 million. This divestiture was part of AAR's portfolio optimization and strategy to focus on aviation aftermarket services. This sale passed a large commercial and military landing gear MRO business to GA Telesis.
Commercial Aircraft Landing Gear Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 2.9 billion
Market size value in 2026
USD 3.1 billion
Revenue forecast in 2033
USD 5.3 billion
Growth rate
CAGR of 8.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Gear position, component, aircraft arrangement, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; UK; Germany; France; Japan; China; India; Australia; South Korea; Brazil; Mexico; Saudi Arabia; South Africa; UAE
Key Companies Profiled
AAR; Advantage Aviation Technologies; CIRCOR AEROSPACE PRODUCTS GROUP; Eaton; Héroux-Devtek; Honeywell International Inc.; Magellan Aerospace Corporation; Liebherr; MAG Inc.; Sumitomo Precision Products Co., Ltd. (SPP); Safran Landing Systems; UTC Aerospace Systems (United Technologies Corporation (UTC)); Triumph Group; Whippany Actuation Systems
Customization scope
Free report customization (equivalent to up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Commercial Aircraft Landing Gear Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global commercial aircraft landing gear market report based on gear position, component, aircraft, arrangement, and region:
-
Gear Position Outlook (Revenue in USD Billion, 2021 - 2033)
-
Main Landing Gear
-
Nose Landing Gear
-
-
Component Outlook (Revenue in USD Billion, 2021 - 2033)
-
Landing Gear Steering System
-
Wheel & Brake System
-
Actuation System
-
Others
-
-
Aircraft Type Outlook (Revenue in USD Billion, 2021 - 2033)
-
Narrow-Body
-
Wide-Body
-
Regional Jet
-
Others
-
-
Arrangement Outlook (Revenue in USD Billion, 2021 - 2033)
-
Tricycle
-
Tandem
-
Tailwheel
-
-
Regional Outlook (Revenue in USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The global commercial aircraft landing gear market size was valued at USD 2.9 billion in 2025 and is projected to reach USD 3.1 billion in 2026.
Key factors that are driving the market growth include the expansion in the fleet size of major airlines and the surging growth in the commercial aviation sector.
The global commercial aircraft landing gear market is expected to grow at a CAGR of 8.1% from 2026 to 2033, reaching USD 5.3 billion by 2033.
Asia Pacific region is anticipated to register growth at a fastest CAGR owing to the growing demand of commercial aviation as a result of rising income levels of the middle-class society across the countries in the region.
Some key players operating in the commercial aircraft landing gear market include AAR, Advantage Aviation Technologies, CIRCOR AEROSPACE PRODUCTS GROUP, Eaton, Héroux-Devtek, Honeywell International Inc., Magellan Aerospace Corporation, Liebherr, MAG Inc., Sumitomo Precision Products Co., Ltd. (SPP), Safran Landing Systems, UTC Aerospace Systems (United Technologies Corporation (UTC)), Triumph Group, and Whippany Actuation Systems.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


