
- Home
- »
- Organic Chemicals
- »
-
Corrosion Inhibitors Market Size, Growth Report, 2026-2033GVR Report cover

Corrosion Inhibitors Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Organic, Inorganic), By Type (Water Based, Oil Based), By End Use (Oil And Gas, Chemical Processing), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$9.3BMarket Estimate, 2026
$9.6BMarket Forecast, 2033
$12.3BCAGR, 2026–2033
3.6%Corrosion Inhibitors Market Summary
The global corrosion inhibitors market size was estimated at USD 9.3 billion in 2025 and is projected to grow from USD 9.6 billion in 2026 to USD 12.3 billion by 2033, growing at a CAGR of 3.6% from 2026 to 2033. Asia Pacific dominated the corrosion inhibitors market with the dominating revenue share of 37.4% in 2025. This growth is attributed to the increasing demand from the oil and gas, automotive, and construction industries significantly contributes to this trend.
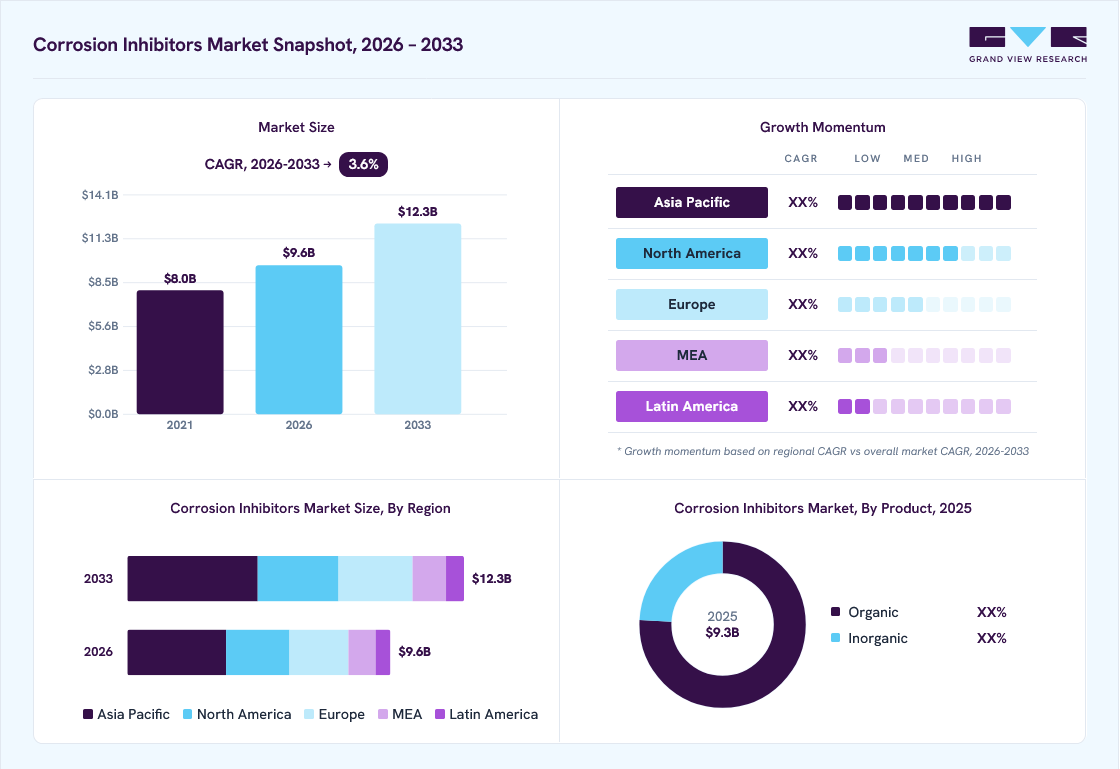 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Organic segment led the market with the largest revenue share of 75.7% in 2025.
- By type: In 2025, the oil-based segment by type accounted for the dominating revenue share of 55.6%.
- By end use: Oil & gas segment held the highest revenue share of 32.2% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (37.4% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 9.3 Billion
- Estimated market size in 2026: USD 9.6 Billion
- Projected market size by 2033: USD 12.3 Billion
- CAGR (2026-2033): 3.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, rising disposable incomes and the need for treated water in various sectors further propel market expansion. Furthermore, emerging economies are witnessing rapid industrialization, leading to heightened requirements for effective corrosion protection. Moreover, environmental concerns also drive the shift towards eco-friendly corrosion inhibitors, enhancing their acceptance across diverse applications globally.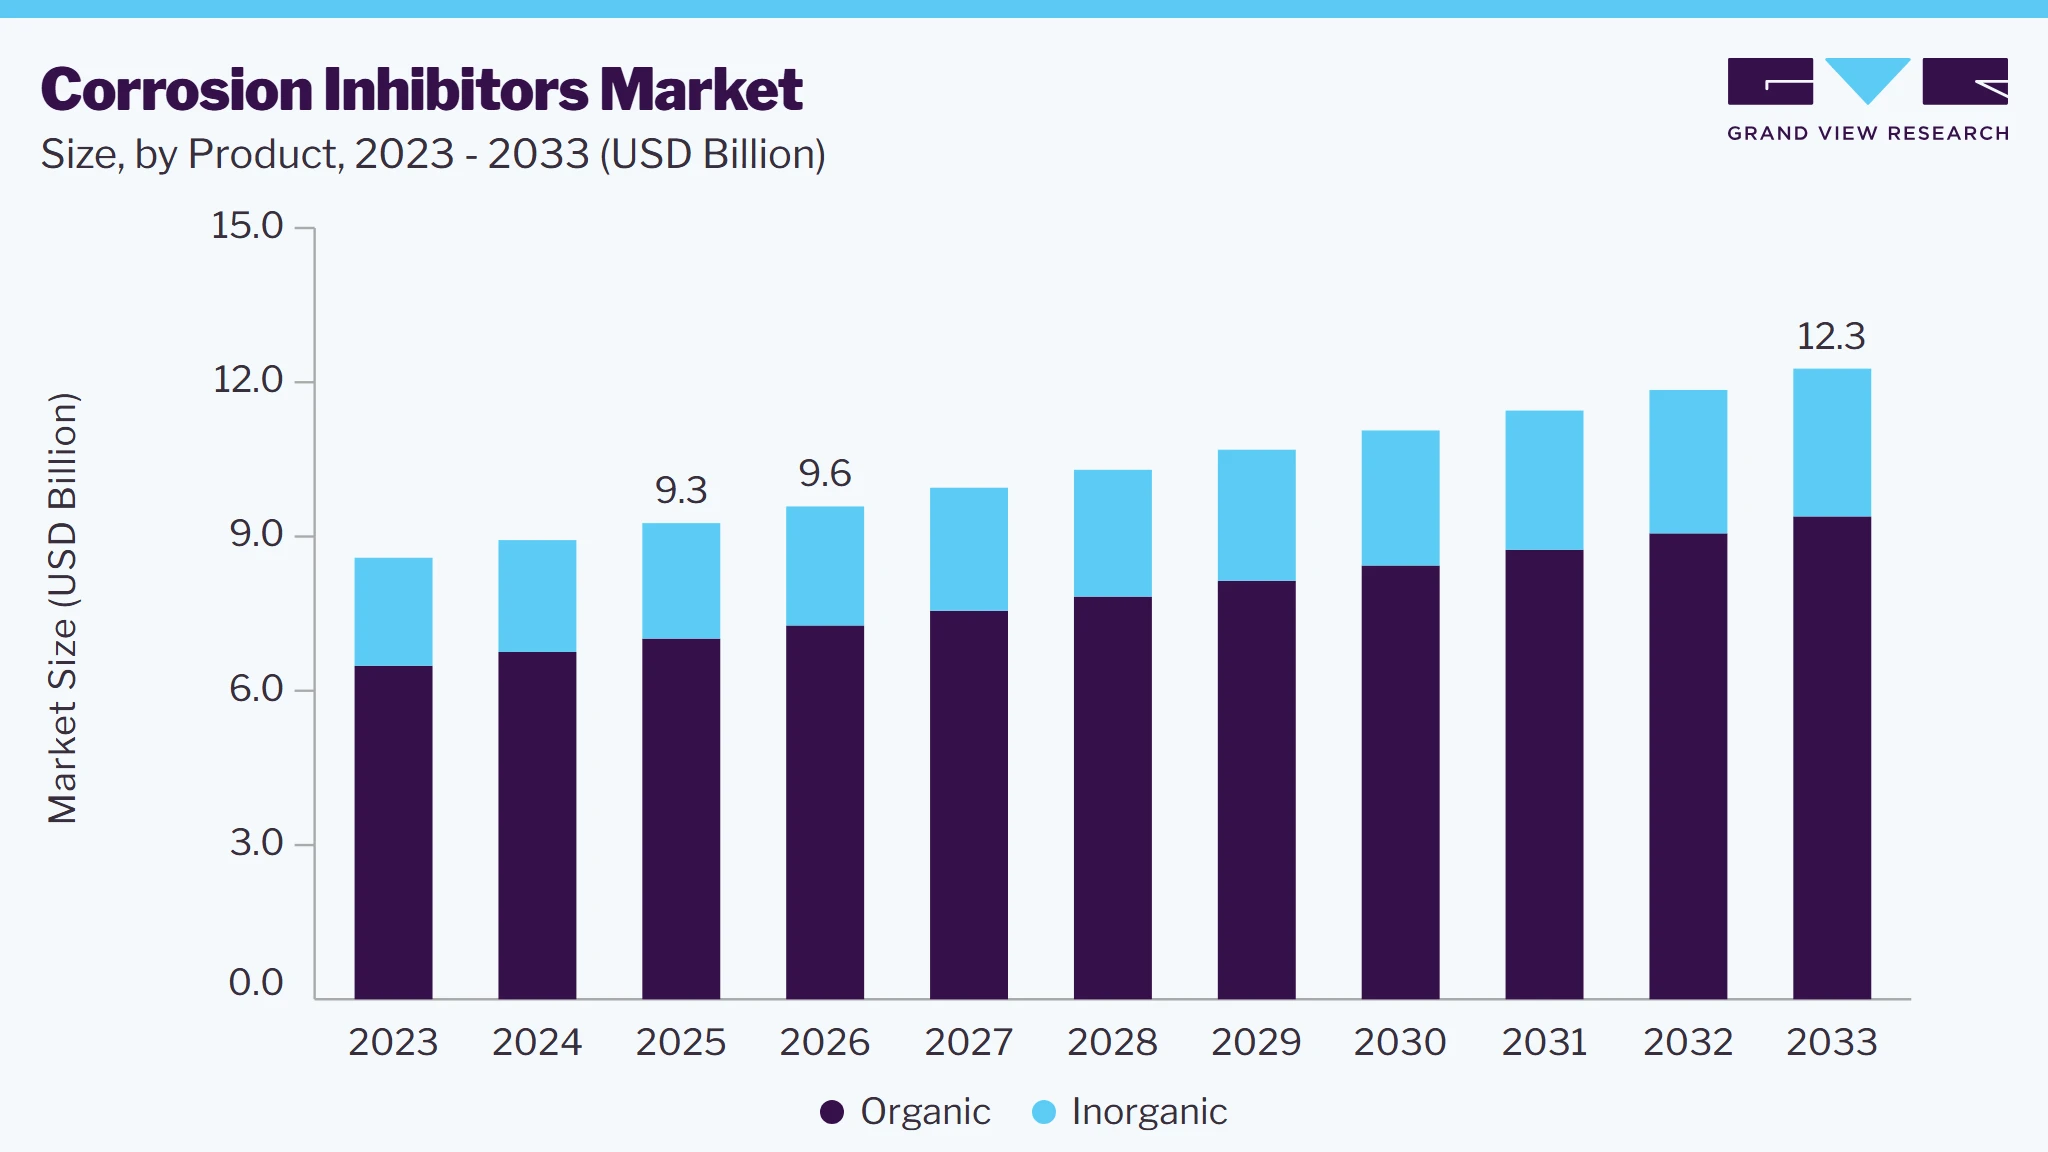 To learn more about this report, Download Free Sample Report
Corrosion inhibitors are essential chemical agents used to mitigate the deterioration of materials, particularly metals, caused by chemical or electrochemical reactions to their environment. These substances are vital in various industries, including oil and gas, construction, water treatment, and automotive manufacturing, as they help maintain the integrity and longevity of metals and alloys. Corrosion inhibitors function by forming a protective barrier on metal surfaces or modifying environmental conditions to decrease reactivity.
There are several types of corrosion inhibitors. Anodic inhibitors create a protective film on metal surfaces, effectively preventing oxidation and corrosion initiation. Cathodic inhibitors, such as zinc and magnesium compounds, slow down reduction reactions at the metal surface. In addition, mixed inhibitors comprise both anodic and cathodic properties for comprehensive protection against corrosion. Vapor phase inhibitors (VPIs) release volatile substances that form a protective layer in enclosed spaces, making them effective for hard-to-reach areas.
The economic implications of corrosion are significant; industries increasingly recognize that using corrosion inhibitors can lead to substantial cost savings. Stricter environmental regulations also push for adopting eco-friendly corrosion inhibitors, reflecting a shift towards sustainable practices. Moreover, advancements in nanotechnology have led to the development of more efficient nano-based corrosion inhibitors. However, challenges remain, including high initial costs for new technologies and limited awareness in developing markets about the benefits of these protective agents. Emerging technologies continue evolving, presenting opportunities and competition for traditional corrosion inhibition methods.
Market Dynamics
Corrosion inhibitors are specialty chemicals used to reduce or prevent the deterioration of metals and alloys caused by chemical or electrochemical reactions with their surrounding environment. These products are extensively utilized across oil & gas, power generation, water treatment, chemical processing, metal processing, and manufacturing industries to enhance asset lifespan, improve operational reliability, and reduce maintenance costs. Growing industrialization and increasing investments in infrastructure continue to support market demand globally.
The increasing need to protect critical industrial infrastructure from corrosion-related damage remains a major driver for the corrosion inhibitors market. Industries such as oil & gas, power generation, chemical processing, and water treatment operate equipment under harsh environmental conditions that can accelerate corrosion and lead to significant operational losses. Corrosion inhibitors help extend equipment life, reduce maintenance requirements, and improve process efficiency.
Rising investments in pipelines, refineries, power plants, industrial manufacturing facilities, and water treatment infrastructure are further supporting demand. As operators seek to minimize downtime and maximize asset utilization, the adoption of corrosion management solutions continues to increase across both developed and emerging economies.
Stringent environmental regulations governing the use and disposal of specialty chemicals remain a key challenge for market participants. Certain corrosion inhibitor formulations may contain substances subject to increasing regulatory scrutiny due to their environmental persistence or potential ecological impact. Compliance with evolving regulations often requires reformulation efforts and additional investment in product development.
Growing investments in industrial and municipal water treatment systems are creating significant opportunities for corrosion inhibitor manufacturers. Water infrastructure operators are increasingly adopting advanced treatment programs to improve system efficiency, reduce maintenance costs, and protect critical assets from degradation.
Analyst Perspective
The corrosion inhibitors market is increasingly evolving from a maintenance-focused industry toward a strategic asset protection market driven by reliability, sustainability, and operational efficiency objectives. While oil &s gas applications continue to account for a significant share of demand, emerging opportunities are developing across water treatment, power generation, infrastructure rehabilitation, and industrial manufacturing sectors. Growing emphasis on extending equipment lifespan and reducing unplanned downtime is encouraging adoption of high-performance and environmentally compliant inhibitor technologies.
Product Insights
Based on product, the organic segment led the market with the largest revenue share of 75.7% in 2025, primarily driven by the increasing demand for environmentally friendly solutions across various industries. As regulations tighten, particularly in regions such as Europe and North America, companies seek organic inhibitors derived from natural sources that minimize environmental impact while maintaining effectiveness. Furthermore, the oil and gas sector and construction and water treatment industries contribute to this growth, as organic inhibitors are favored for their ability to form protective layers on metal surfaces and lower toxicity compared to inorganic options.
The inorganic corrosion inhibitors segment is expected to grow at a CAGR of 3.2% over the forecast period, driven by their effectiveness in harsh conditions, such as high temperatures and pressures. These inhibitors, including chromates, phosphates, and nitrates, are widely used in critical infrastructure development and power generation applications. In addition, the ongoing growth in infrastructure projects, particularly in emerging economies, boosts demand for these robust solutions. Furthermore, advancements in secondary zinc-based and silicate-based inhibitors enhance the performance of inorganic options, making them more appealing for industries requiring reliable corrosion protection under challenging operational environments.
Type Insights
In 2025, the oil-based segment by type accounted for the dominating revenue share of 55.6%. This growth is attributed to the increasing oil and gas industry demand. In addition, these inhibitors provide superior protection for metal surfaces exposed to harsh conditions, such as high temperatures and corrosive chemicals, making them essential for exploration, extraction, and transportation equipment. The stability of crude oil prices also plays a crucial role in driving investments in this sector. Furthermore, the need for effective corrosion control solutions to minimize downtime and maintenance costs further propels the demand for oil-based inhibitors.
The water-based corrosion inhibitors are expected to grow at a CAGR of.3.7% from 2025 to 2030, owing to a growing emphasis on environmentally friendly solutions. These inhibitors are favored for their ease of application and effectiveness in protecting equipment in aqueous environments, such as cooling systems and pipelines. In addition, stricter environmental regulations push industries toward safer, non-toxic alternatives, enhancing the appeal of water-based formulations. Furthermore, the rising demand for treated water across various sectors, including manufacturing and water treatment, is contributing to the increased adoption of water-based corrosion inhibitors as industries seek to ensure the longevity and reliability of their assets.
End Use Insights
By end use, the oil & gas segment held the highest revenue share of 32.2% in 2025, driven by the increasing exploration and production activities. As global energy demands rise, effective corrosion protection solutions become critical to safeguard infrastructure and equipment from corrosive environments. In addition, aging pipelines and facilities and stringent safety regulations further amplify the demand for robust corrosion inhibitors. Furthermore, the high costs associated with corrosion-related failures motivate companies to invest in effective prevention strategies, ensuring operational efficiency and safety.
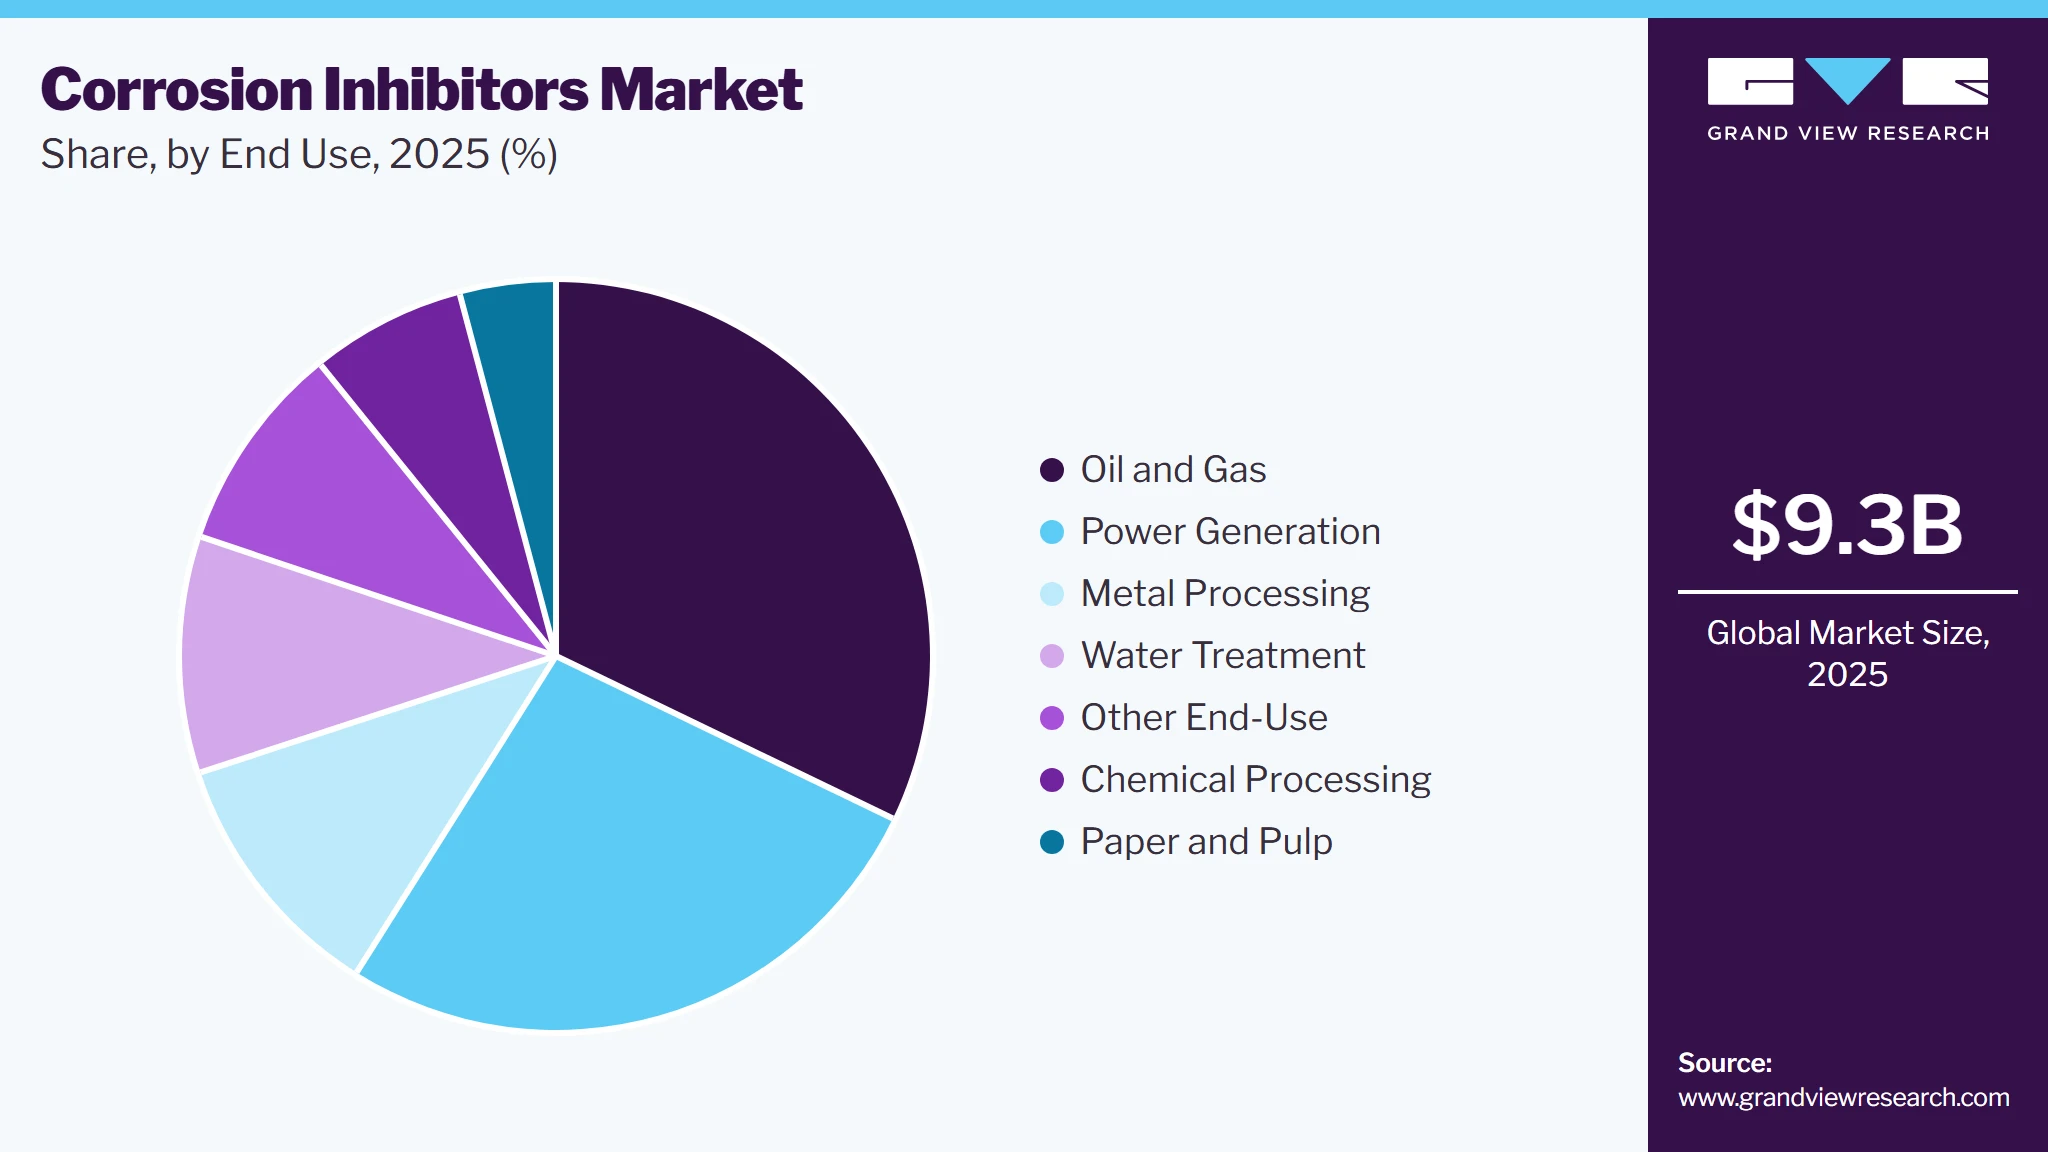 To learn more about this report, Download Free Sample Report
The water treatment segment is expected to grow at a CAGR of 4.3% over the forecast period, owing to the rising demand for treated water across various industries. As freshwater resources become increasingly scarce, efficient water recycling and treatment processes are essential. In addition, corrosion inhibitors play a crucial role in protecting metal machinery from deterioration caused by water flow. Furthermore, as the largest consumer of these inhibitors, the industrial sector seeks effective solutions to minimize equipment downtime and maintenance costs. Moreover, stricter environmental regulations are driving the adoption of eco-friendly corrosion inhibitors, enhancing their appeal in water treatment applications.
Regional Insights
The North America corrosion inhibitors market is expected to grow at a CAGR of 3.6% over the forecast period, owing to the growing oil and gas industry requiring effective solutions to protect pipelines and equipment from corrosion. In addition, the region's strong manufacturing base, particularly in the automotive and aerospace sectors, also contributes significantly to this growth as companies seek to enhance the durability of their products. Furthermore, ongoing infrastructure projects and stringent environmental regulations push industries towards advanced corrosion protection technologies to ensure compliance while minimizing maintenance costs.
The corrosion inhibitors market in the U.S. dominated the North American market and accounted for the largest revenue share in 2024, driven by high production rates in the automotive and aerospace industries. Furthermore, government investments in renewable energy projects require specialized corrosion inhibitors to protect critical components. This focus on enhancing energy efficiency and safety standards supports the overall growth of the corrosion inhibitors market in the country.
Asia-Pacific Corrosion Inhibitors Market Trends
Asia Pacific dominated the corrosion inhibitors market with the dominating revenue share of 37.4% in 2025 attributed to the increasing industrialization and urbanization in countries such as China and India. In addition, the rising demand for effective corrosion protection solutions is fueled by significant investments in infrastructure development across various sectors, including construction and manufacturing. Furthermore, this region's growing oil and gas industry necessitates advanced corrosion control measures to protect equipment from harsh operational environments.
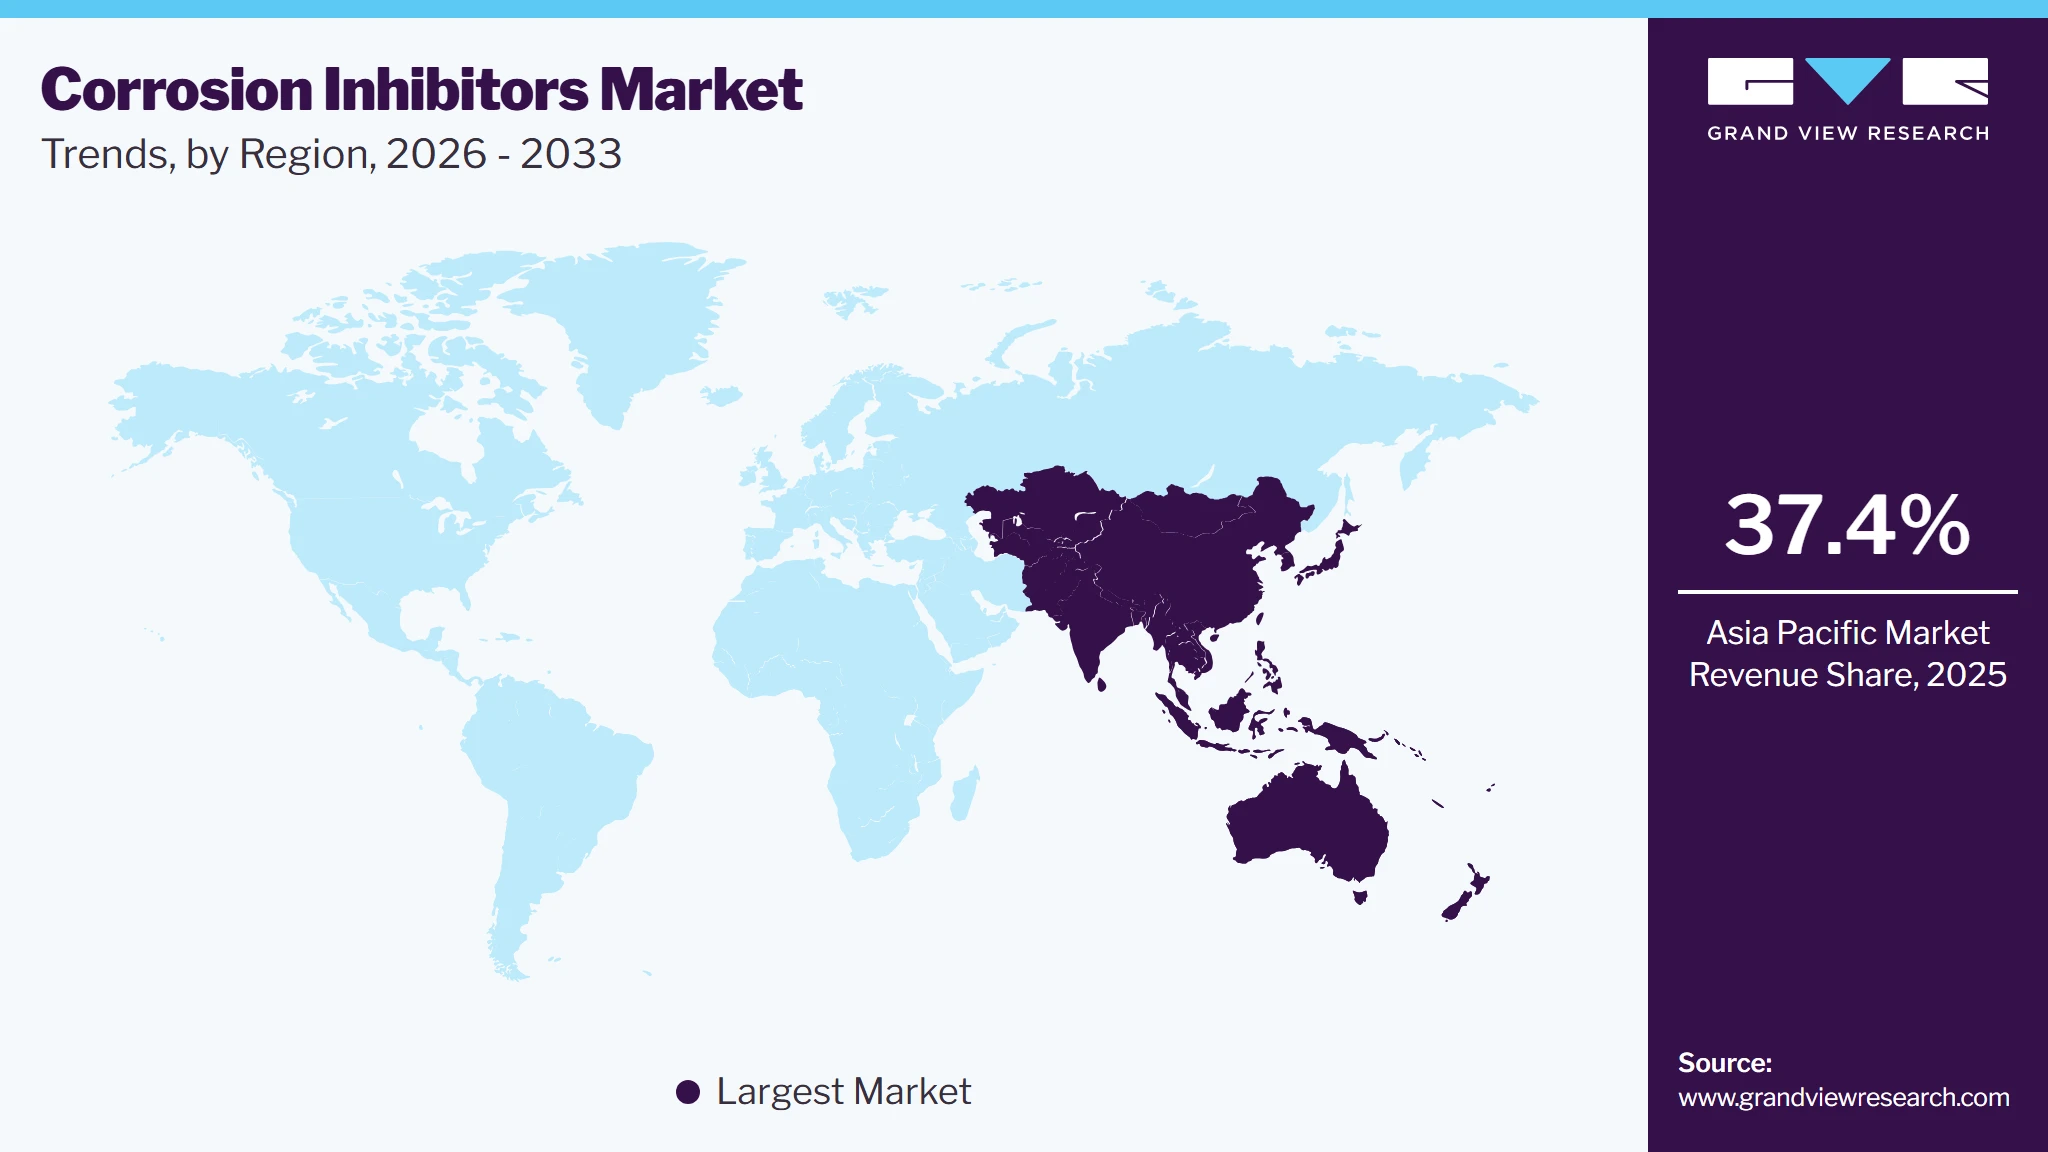 To learn more about this report, Download Free Sample Report
China accounted for a largest revenue share of 41.3% of the Asia Pacific corrosion inhibitors market in 2025, driven by its rapid economic growth and status as a leading energy consumer. In addition, the country's extensive industrial activities drive demand for corrosion inhibitors as industries seek to safeguard their infrastructure from deterioration. Moreover, China's focus on low-carbon initiatives and renewable energy projects further influences the need for effective corrosion protection solutions across various applications, positioning it as a critical market for growth in this sector.
Europe Corrosion Inhibitors Market Trends
Europe corrosion inhibitors market is expected to grow significantly, driven by strict environmental regulations that encourage the adoption of eco-friendly solutions. Furthermore, the region's strong industrial base drives demand for effective corrosion protection, especially in the automotive, manufacturing, and chemical processing sectors. Moreover, ongoing investments in infrastructure development and water treatment facilities further bolster market growth as industries seek reliable methods to mitigate corrosion risks while adhering to sustainability goals.
The growth of the corrosion inhibitors market in Germany is primarily driven by its advanced manufacturing capabilities and commitment to sustainability. In addition, the automotive sector is a major contributor to market growth as manufacturers seek innovative solutions for corrosion protection. Furthermore, Germany's focus on renewable energy initiatives is fueling demand for specialized inhibitors across various applications, ensuring that critical components remain protected against corrosion while supporting environmental objectives.
Key Corrosion Inhibitors Company Insights
Some of the key players in the global corrosion inhibitors industry include Nouryon, Cortec Corporation, Ashland, and others. These companies are adopting various strategies to enhance their competitive edge. These strategies include new product formulations, focusing on eco-friendly solutions to meet regulatory requirements, and expanding their product portfolios to cater to diverse industries. Furthermore, companies are forming strategic partnerships and collaborations to leverage technological advancements and enhance distribution networks, ensuring broader market reach and customer engagement while effectively addressing specific industry needs.
-
Ashland manufactures a range of products designed to protect metals from corrosion, particularly through its Ashland Water Technologies division. This segment provides process and utility chemistries that enhance operational efficiencies and protect plant assets across sectors such as food and beverage, pulp and paper, and industrial applications. The company’s corrosion inhibitors are essential for maintaining equipment integrity and ensuring compliance with environmental regulations.
-
Ecolab manufactures various chemical solutions to prevent corrosion in critical applications across various industries, such as oil and gas, food processing, and manufacturing. The company operates in the water treatment segment, offering innovative products that help manage water quality and protect infrastructure from corrosive damage. Their corrosion inhibitors are designed to enhance equipment lifespan and operational efficiency while addressing environmental sustainability concerns in industrial processes.
Key Corrosion Inhibitors Companies:
The following key companies have been profiled for this study on the corrosion inhibitors market.
-
Nouryon
-
Cortec Corporation
-
Ashland
-
Ecolab
-
Henkel Ibérica, S.A.
-
The Lubrizol Company
-
BASF SE
-
Dow
-
DuPont de Nemours, Inc.
-
Baker Hughes, a GE company LLC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Nouryon, Ashland, Ecolab, The Lubrizol Company, BASF SE, Dow, DuPont de Nemours, Inc., Baker Hughes, a GE company LLC)
Expanding specialty corrosion protection portfolios through innovation and application-specific product development initiatives.
Strengthening partnerships with industrial operators to deliver integrated asset protection and maintenance solutions.
Extensive global presence supports reliable product supply across diverse industrial and infrastructure sectors.
Strong research capabilities enable development of advanced formulations meeting evolving performance and environmental requirements.
Regulatory compliance requirements can increase product development costs and commercialization timelines significantly.
Dependence on industrial production activity exposes demand to economic and sector-specific fluctuations.
Emerging Players (Cortec Corporation, Henkel Ibérica, S.A.)
Focusing on environmentally friendly corrosion protection technologies and specialized industrial application segments.
Expanding regional distribution capabilities and customer support services to strengthen market penetration.
Strong specialization in corrosion management solutions enables targeted product differentiation within niche markets.
Flexible operational structures support rapid response to evolving customer and regulatory requirements.
Comparatively smaller global footprint may limit access to large multinational industrial contracts.
Lower economies of scale can impact competitiveness against larger diversified chemical manufacturers.
Recent Developments
-
In August 2024, PPG unveiled its latest innovation, PPG PRIMERON Optimal, a powder primer featuring optimized zinc for enhanced corrosion protection. This advanced primer is designed to improve adhesion and durability, making it ideal for various industrial applications. By incorporating effective corrosion inhibitors, PPG PRIMERON Optimal significantly extends the lifespan of coated surfaces, ensuring superior performance in challenging environments. This launch reflects PPG's commitment to providing high-quality solutions that meet customers' evolving needs in protective coatings.
-
In March 2023, Cortec announced a significant advancement in corrosion inhibitors by introducing VpCI-649 HP, certified to meet ANSI/NSF Standard 61 for hydro-testing drinking water systems. This innovative product offers effective corrosion protection during hydrostatic testing, which is crucial for ensuring the integrity of vessels and piping. With a low dosage requirement and minimal chloride impact, VpCI-649 HP not only safeguards metal surfaces but also expands opportunities for safe use in drinking water applications, enhancing industry standards for corrosion prevention.
Corrosion Inhibitors Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 9.3 billion
Market size value in 2026
USD 9.6 billion
Revenue forecast in 2033
USD 12.3 billion
Growth rate
CAGR of 3.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, Volume in Kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, Type, End-Use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Nouryon; Cortec Corporation; Ashland; Ecolab; Henkel Ibérica, S.A.; The Lubrizol Company; BASF SE; Dow; DuPont de Nemours, Inc.; Baker Hughes, a GE company LLC
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
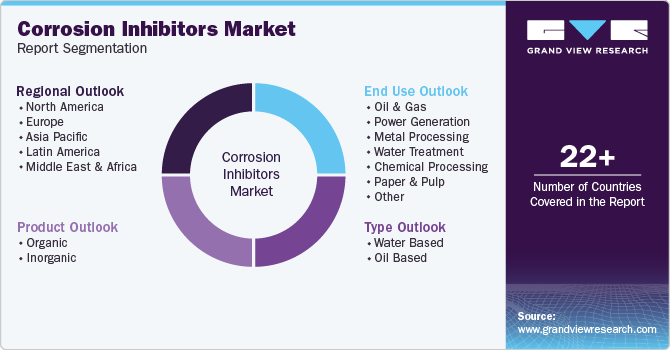
Global Corrosion Inhibitors Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global corrosion inhibitors market report based on product, type, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Organic
-
Inorganic
-
-
Type Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Water Based
-
Oil Based
-
-
End Use Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Oil and Gas
-
Power Generation
-
Metal Processing
-
Water Treatment
-
Chemical Processing
-
Paper and Pulp
-
Other
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
UAE
-
Iran
-
Iraq
-
Saudi Arabia
-
Kuwait
-
Oman
-
Bahrain
-
South Africa
-
-
Research Methodology
The corrosion inhibitors market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each corrosion inhibitors segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Organic
As the dominant product segment, revenue is generated through the widespread use of organic compounds that form protective films on metal surfaces. Extensive adoption across oil & gas, water treatment, power generation, and chemical processing industries supports substantial market value.
Inorganic
Revenue is supported by applications utilizing mineral-based corrosion inhibitors in cooling systems, boilers, water treatment facilities, and industrial equipment. Demand is influenced by operating conditions, treatment program requirements, and regulatory compliance considerations.
Segment - Type
Revenue capture definition
Water Based
Revenue is generated through corrosion inhibitor formulations designed for cooling water systems, boilers, water treatment facilities, and industrial process streams. Growing investments in water infrastructure and sustainability initiatives continue to support demand for water-based solutions.
Oil Based
As the dominant type segment, revenue capture is driven by extensive use in hydrocarbon production, pipelines, storage systems, and refinery operations. High-performance requirements in corrosive oilfield environments contribute significantly to commercial consumption and market value.
Segment - End Use
Revenue capture definition
Oil and Gas
As the largest end-use segment, revenue is generated through corrosion protection programs implemented across upstream, midstream, and downstream operations. Extensive pipeline networks, production facilities, and refining assets require continuous inhibitor usage to maintain operational integrity.
Power Generation
Revenue is supported by corrosion control applications in boilers, cooling systems, steam circuits, and power plant infrastructure. Asset reliability requirements and increasing electricity generation capacity continue to drive demand for specialized inhibitor formulations.
Metal Processing
Market value is derived from corrosion protection during metal manufacturing, finishing, storage, and transportation operations. Growing industrial production and quality control requirements support consistent adoption across metal processing facilities.
Water Treatment
Revenue capture is driven by inhibitor usage in municipal and industrial water treatment systems to prevent corrosion of pipes, tanks, and distribution infrastructure. Expanding water treatment investments and aging infrastructure replacement programs support segment growth.
Chemical Processing
Revenue is generated through applications protecting reactors, storage vessels, pipelines, and process equipment exposed to corrosive chemicals. Increasing chemical production capacity and process optimization initiatives continue to support demand.
Paper and Pulp
Market revenue is supported by corrosion management programs implemented in pulp mills, paper manufacturing plants, and associated process equipment. Harsh operating environments and asset maintenance requirements contribute to ongoing product consumption.
Other End-Use
This segment derives revenue from construction, marine, automotive, mining, and manufacturing industries utilizing corrosion inhibitors to protect critical assets and extend equipment service life under diverse operating conditions.
Estimation Model
Layer Name
Key Question
Description
Industrial Asset Layer
What forms the addressable base?
Identify global infrastructure, industrial equipment, pipelines, processing facilities, storage systems, and metal assets exposed to corrosive operating environments requiring protection and maintenance.
Protection Adoption Layer
Where are corrosion inhibitors utilized?
Estimate the proportion of industrial systems implementing corrosion management programs across oil & gas, power generation, water treatment, chemical processing, and manufacturing applications.
Consumption Intensity Layer
How much inhibitor is consumed?
Analyze treatment frequencies, operating conditions, fluid volumes, asset exposure levels, and maintenance schedules to determine annual corrosion inhibitor consumption across end-use industries.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of organic and inorganic corrosion inhibitors supplied to industrial operators, water treatment facilities, energy companies, and manufacturing sectors for ongoing asset protection and corrosion management programs.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study delivers detailed analysis across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, including key countries where industrial manufacturing, energy production, and infrastructure investments are driving corrosion inhibitor demand.
Enables stakeholders to identify high-growth regional markets, evaluate industrial activity trends, and prioritize geographic expansion strategies based on sector-specific demand and investment opportunities.
Pricing Analysis
The report delivers comprehensive pricing assessment covering historical price trends, raw material cost movements, formulation economics, and regional pricing variations influencing corrosion inhibitor market dynamics across major industrial sectors.
Supports procurement planning, cost optimization, margin management, and supply chain decision-making by providing greater visibility into pricing fluctuations and cost drivers affecting profitability.
Opportunity Assessment
The study delivers detailed evaluation of emerging opportunities across water treatment, renewable energy infrastructure, industrial manufacturing, power generation, and environmentally compliant corrosion protection technologies.
Helps companies identify future growth avenues, prioritize high-potential application sectors, and align product development strategies with evolving sustainability requirements and asset protection needs.
Frequently Asked Questions About This Report
The global corrosion inhibitors market size was estimated at USD 9.3 billion in 2025 and is expected to reach USD 9.6 billion in 2026.
The global corrosion inhibitors market is expected to grow at a compound annual growth rate of 3.6% from 2026 to 2033 to reach USD 12.3 billion by 2033.
Asia Pacific dominated the corrosion inhibitors market with a share of 37.4% in 2025. This is attributable to growing construction and steel manufacturing activities coupled with increasing product consumption in water treatment sector.
Some key players operating in the corrosion inhibitors market include Ashland Inc., AkzoNobel N.V., BASF SE, GE Water & Process Technologies, DuPont, Champion Technology Services, Inc., Renewable Lubricants, Inc., Ecolab Inc., Cytec Industries, Inc., Cortec Corporation, and Lubrizol Corporation.
Key factors that are driving the market growth include the development of organic corrosion inhibitor products and the growing necessity to increase the shelf life of metal equipment.
The Asia Pacific region led the corrosion inhibitors market in 2025, accounting for 37.4% of market revenue, owing to rapid industrialization, expanding manufacturing activities, and increasing demand for asset protection across key end-use industries.
The oil & gas segment dominated the corrosion inhibitors market in 2025, capturing 32.2% of market revenue.
The water treatment segment is projected to witness the fastest growth during the forecast period, registering a CAGR of 4.3% from 2026 to 2033.
The oil-based segment dominated the corrosion inhibitors market in 2025, accounting for 55.6% of market revenue, owing to its superior performance in harsh operating environments and widespread use across oil & gas and industrial applications.
About the Author(s)
Organic Chemicals Research Team
Bulk Chemicals · Organic ChemicalsThis report was authored by the organic chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the organic chemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


