
- Home
- »
- Medical Devices
- »
-
Cryoablation Devices Market Size And Share Report, 2033GVR Report cover

Cryoablation Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Tissue Contact Probe Ablators, Tissue Spray Probe Ablators), By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$540.3MMarket Estimate, 2026
$614.3MMarket Forecast, 2033
$1,179.0MCAGR, 2026–2033
9.8%Cryoablation Devices Market Summary
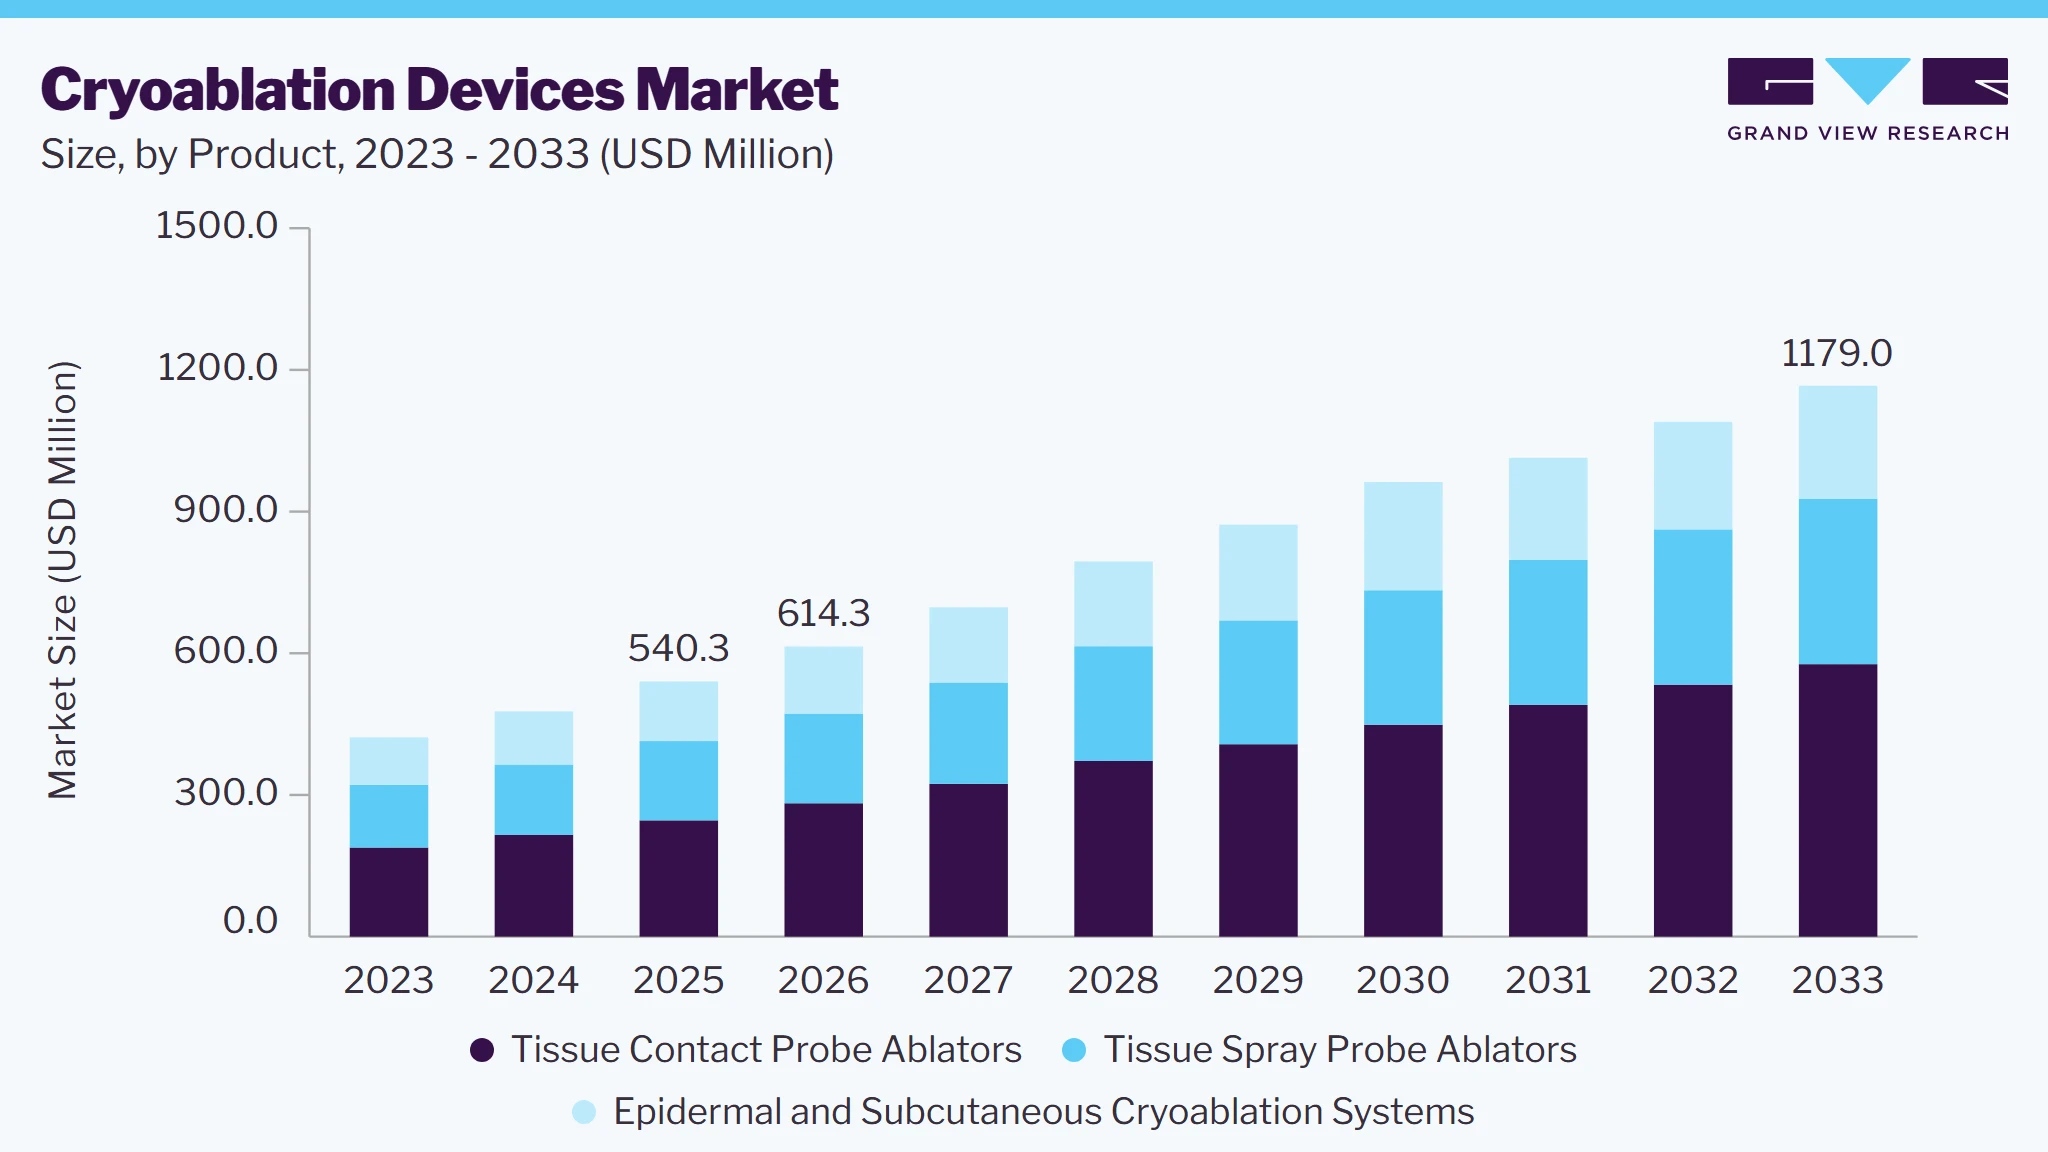
The cryoablation devices market size was valued at USD 540.3 million in 2025 and is projected to grow from USD 614.3 million in 2026 to USD 1,179.0 million by 2033, at a CAGR of 9.8% from 2026 to 2033. North America dominated the cryoablation devices market with the largest revenue share of 32.0% in 2025. Growth is driven by rising cancer prevalence, increasing adoption of minimally invasive procedures, and advancements in cryoablation technology.
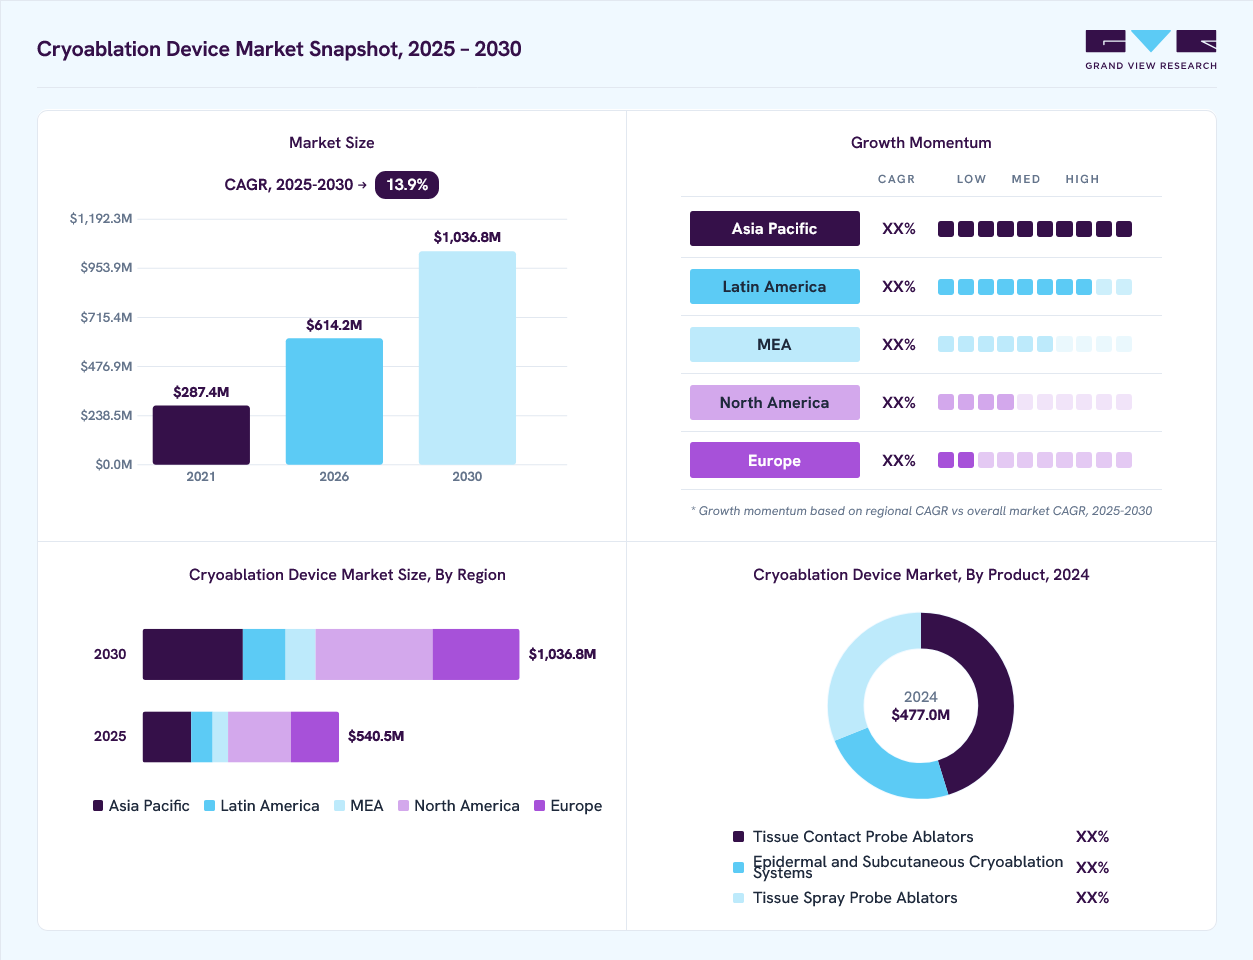 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Tissue contact probe ablators segment held the largest market share of 45.6% in 2025.
- By application: Cardiac arrhythmia segment held the largest market share of 38.0% in 2025.
- By end use: Hospital segment held the largest market share of 54.5% in 2025.
Regional Highlights
- Largest regional market: North America (32.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 540.3 Million
- Estimated market size in 2026: USD 614.3 Million
- Projected market size by 2033: USD 1,179.0 Million
- CAGR (2026-2033): 9.8%
Prism AI by Grand View Research Free to tryAsk a question about the cryoablation devices marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The expanding geriatric population and growing preference for targeted tumor therapies further boost demand. In addition, regulatory approvals and strategic collaborations among key players enhance market expansion. Increasing applications in cardiology, dermatology, and pain management contribute to market growth. Increasing inclination of the patients and surgeons towards non-invasion or minimal invasion treatment procedures due to the advantages such as patient comfort, speedy recovery, and minimized turnaround time are a few of the factors which are anticipated to fuel demand for cryoablation devices during the forecast period.
 To learn more about this report, Download Free Sample Report
Advanced cancer ablation procedures are mostly performed on an outpatient basis and do not require any hospital admission as compared to conventional therapies, resulting in a significant reduction in total healthcare expenses. Ablation therapy is the preferred surgery for cancer of small sizes. Hence, the procedural volume is indirectly reliant on the yearly tumor screening tests.
According to the CDC in October 2022, approximately 12 million U.S. individuals suffered from atrial fibrillation by 2033. Moreover, in 2019, around 183,321 deaths were caused in the U.S. Furthermore, approximately 450,000 hospitalizations were recorded with atrial fibrillation as the key diagnosis every year in the U.S. The rising prevalence of atrial fibrillation is predicted to enhance demand for the cryoablation devices industry during the forecast period.
A rise in the prevalence of tumors such as lung cancer, prostate cancer, breast cancer, and many more in several countries across the globe is anticipated to fuel the cryoablation devices industry growth. As per an article published by CDC in June 2022, nearly 221,097 new lung cancer cases were reported in the U.S., and 139,601 deaths were caused due to lung cancer. Furthermore, every year, in the U.S., approximately 25,000 men and 11,000 women get liver cancer, and around 9,000 women and 19,000 men die due to the same.
According to the survey conducted by NCI's Surveillance, Epidemiology, and End Results (SEER) Program, conducted in March 2021, the most common age for getting a tumor diagnosis is 66 years, that is, half of the tumor cases occur in individuals under this age. The geriatric population is held as the main target population for minimally invasive or noninvasive cryoablation techniques, due to the compromised body’s biological functions. Thus, the rising geriatric population base is expected to augment demand for cryoablation devices during the forecast period.
Market Dynamics
The cryoablation devices market is experiencing robust growth, driven by the increasing prevalence of cancer and cardiovascular disorders, rising demand for minimally invasive treatment procedures, growing adoption of image-guided interventional therapies, and continuous technological advancements in cryoablation systems. The market is further supported by the expanding geriatric population, increasing incidence of chronic diseases requiring localized tissue ablation, favorable clinical outcomes associated with cryotherapy, and improved access to advanced interventional healthcare services across both developed and emerging markets. Cryoablation devices enable hospitals, specialty clinics, ambulatory surgical centers, and interventional radiology and cardiology centers to precisely destroy diseased tissue through controlled freezing technology while minimizing damage to surrounding healthy structures. Cryoablation devices are extensively utilized for the treatment of a wide range of oncological and non-oncological conditions. In oncology, they are commonly used for the management of tumors affecting the kidney, liver, lung, breast, bone, and prostate, as well as selected soft tissue malignancies and metastatic lesions. In cardiology, cryoablation has become an established treatment option for cardiac arrhythmias, particularly atrial fibrillation and other supraventricular tachyarrhythmias.
The rising prevalence of cancer worldwide is one of the primary factors driving the growth of the cryoablation devices market. Increasing incidences of kidney, liver, lung, breast, prostate, and bone cancers have significantly boosted the demand for minimally invasive treatment options that provide effective tumor management while preserving healthy surrounding tissue. According to the World Health Organization (WHO) and the International Agency for Research on Cancer (IARC), an estimated 20 million new cancer cases and 9.7 million cancer-related deaths were reported globally, while approximately 53.5 million people were living within five years of a cancer diagnosis. Furthermore, global cancer incidence is projected to reach 35 million new cases annually by 2050, primarily driven by population aging, population growth, and increasing exposure to cancer risk factors. Cryoablation has emerged as a preferred therapeutic approach for patients with localized tumors, particularly those who are elderly, have multiple comorbidities, or are not suitable candidates for conventional surgery. The procedure offers several clinical advantages, including precise tissue destruction, reduced blood loss, minimal post-procedural pain, shorter hospital stays, faster recovery, and lower complication rates, contributing to its growing adoption across oncology centers. In addition, continuous advancements in cryoablation technology including improved cryoprobes, real-time imaging guidance, and enhanced temperature monitoring systems have improved procedural accuracy and clinical outcomes.
The high capital cost associated with cryoablation systems and the limited accessibility of advanced treatment infrastructure remain significant restraints to the growth of the cryoablation devices market. Cryoablation procedures require sophisticated capital equipment, including cryogenic consoles, cryoprobes or cryoballoons, argon and helium gas delivery systems, real-time monitoring software, and advanced imaging modalities such as computed tomography (CT), ultrasound, or magnetic resonance imaging (MRI) for precise probe placement. The substantial upfront investment required for procuring and maintaining these systems, coupled with the recurring costs of disposable cryoprobes, gas supplies, and service contracts, increases the overall cost of ownership for healthcare providers. Consequently, many small and mid-sized hospitals, ambulatory surgical centers, and healthcare facilities in emerging economies face financial constraints that limit the adoption of cryoablation technology. In addition to equipment costs, cryoablation procedures require highly skilled interventional radiologists, electrophysiologists, urologists, oncologists, or surgeons with specialized training to perform image-guided ablation safely and effectively. The limited availability of experienced specialists, particularly in low- and middle-income countries, restricts the widespread implementation of cryoablation procedures.
Market Concentration & Characteristics
The cryoablation devices industry is moderately concentrated, with key players like Medtronic, Boston Scientific, and IceCure Medical driving innovation. It is characterized by rapid technological advancements, increasing regulatory approvals, and expanding applications in oncology, cardiology, and dermatology. Market growth is fueled by rising demand for minimally invasive procedures and improved patient outcomes. The industry features strong R&D investments, strategic partnerships, and geographic expansions to enhance market presence. In addition, increasing awareness and favorable reimbursement policies support adoption. While barriers to entry include high development costs and regulatory hurdles, innovation and clinical efficacy continue to shape the competitive landscape.
The cryoablation devices industry has experienced significant advancements with AtriCure, Inc.'s announcement on October 2024 regarding the launch of its cryoSPHERE MAX cryoablation probe. This new probe features a larger ball tip to improve cryo nerve block therapy (cryoNB). It reduces freezing time by 50% compared to the original cryoSPHERE probe and over 30% compared to the cryoSPHERE+ probe.
 To learn more about this report, Download Free Sample Report
Regulations in the cryoablation devices industry are critical in ensuring patient safety and device efficacy. Regulatory bodies like the FDA and EMA oversee the approval and monitoring of cryoablation technologies, requiring rigorous clinical trials and safety testing before products reach the market. These regulations set standards for device performance, labeling, and post-market surveillance. In addition, regulatory frameworks help streamline the introduction of advanced devices while safeguarding public health.
Mergers and acquisitions (M&A) in the cryoablation devices industry are growing swiftly as companies seek to enhance their technological expertise and expand their market presence. A notable example is Boston Scientific Corporation's acquisition in July 2021 of the remaining 65% of Cryterion Medical Inc., a private firm developing a single shot cryoablation platform for atrial fibrillation (AF) treatment, for USD 202 million.
In the cryoablation devices industry, product substitutes include alternative treatment options for conditions like atrial fibrillation (AF) and chronic pain. Radiofrequency (RF) ablation is a common substitute, using heat to destroy tissue, offering a similar approach to cryoablation. Other alternatives are laser ablation, which employs light energy for tissue removal, and surgical procedures, such as catheter ablation, which can also target heart arrhythmias. In addition, pharmacological treatments and non-invasive therapies, like pharmaceutical drug management or electrical cardioversion, may act as substitutes in certain cases, depending on the patient’s condition and the physician's recommendations.
The cryoablation devices industry is experiencing notable regional expansion, driven by increasing demand for minimally invasive treatments for conditions like atrial fibrillation and chronic pain. Key markets such as North America and Europe are leading growth due to advanced healthcare infrastructure, rising patient awareness, and technological innovations. Meanwhile, emerging markets in Asia-Pacific and Latin America are seeing accelerated adoption of cryoablation therapies as healthcare systems improve and the demand for cost-effective treatments rises. This regional growth is supported by expanding clinical applications and regulatory approvals, fostering innovation and making cryoablation devices more accessible globally.
Analyst Perspective
The global cryoablation devices market is being driven by the rising prevalence of cancer and cardiovascular diseases, increasing preference for minimally invasive procedures, growing adoption of image-guided interventions, and advancements in cryogenic ablation technologies. The increasing incidence of liver, kidney, lung, prostate, and breast cancers, atrial fibrillation, chronic pain disorders, and other localized tumors is creating significant growth opportunities across healthcare settings. The market is further supported by the growing geriatric population, rising burden of chronic diseases, and increasing demand for organ-preserving treatment approaches that offer reduced procedural trauma, shorter hospital stays, and faster recovery. Growing adoption of advanced cryoablation systems, cryoprobes, and image-guided technologies is improving procedural precision, treatment efficacy, and patient outcomes, supporting continued market expansion.
Product Insights
Based on product, the tissue contact probe ablators segment led the market with the largest revenue share of 45.6% in 2025 and is anticipated to register the fastest CAGR during the forecast period. It is due to the developing healthcare infrastructure, adoption of changing trends in the healthcare system, and consumption patterns. The increasing focus of manufacturers in developing advanced cryoablation devices is expected to contribute towards market growth.
The ablation probe upon contacting the target, the tumor cells, uses freezing technology to destroy the abnormal tissues. For instance, cryoFORM Cryoablation Probe, a product of AtriCure, is among the latest generation, which features a thermal capacity to remove heat and increase the flexibility for various ablation treatments. The recent advancements in probe nanotechnologies assists healthcare professionals to detect and treat cancer. Nanoprobe biotechnology thus helps in discovering new cancer biomarkers, which have become a key part in early cancer diagnosis.
Tissue spray probe ablators held a considerable revenue share in 2025. Increasing preference and demand for tissue spray probes owing to their increasing advantages are anticipated to foster segment growth. The rising focus of manufacturers on developing advanced tissue probe ablators is estimated to contribute toward segment progression.
Application Insights
Based on application, the cardiac arrhythmia segment led the market with the largest revenue share of 38.0% in 2025. owing to the rising cardiovascular disorders that are anticipated to increase the risk of developing heart damage such as abnormal heart valves, cardiomyopathy, narrowed heart arteries, and many more. According to a WHO report of 2021, globally 17.9 million deaths occurred due to CVD annually. Moreover, it is anticipated that more than 3.6 million people will die from CVD, mainly from heart disease and stroke by 2033. The prevalence of getting cardiac arrhythmia is estimated to be between 1.5% to 5.0% in general. Thus, the increasing prevalence of cardiovascular disorders globally is expected to strengthen segment growth.
The breast cancer segment is estimated to expand at the fastest CAGR over the forecast period. According to the American Cancer Society article, published in January 2023, nearly 297,790 and 55,720 novel breast cancer cases and ductal carcinoma in situ (DCIS) cases, respectively, will be reported this year. Approximately, 43,000 deaths due to breast cancer in women are projected in the year 2023.
Furthermore, the median age estimated by the American Cancer Society is 62 years at which most women are most likely to be diagnosed with breast cancer. Although, breast cancer is mostly diagnosed in women, however, men get diagnosed too with breast cancer. According to a CDC article, published in September 2022, every 1 man out of 100 gets diagnosed with breast cancer. Moreover, according to the American Cancer Society, in 2023, around 2,800 novel breast cancer cases are expected to be diagnosed in men, and in that, 530 men are expected to die from cancer. The growing cases of individuals diagnosed with breast cancer are anticipated to propel the growth of the market for cryoablation devices.
End Use Insights
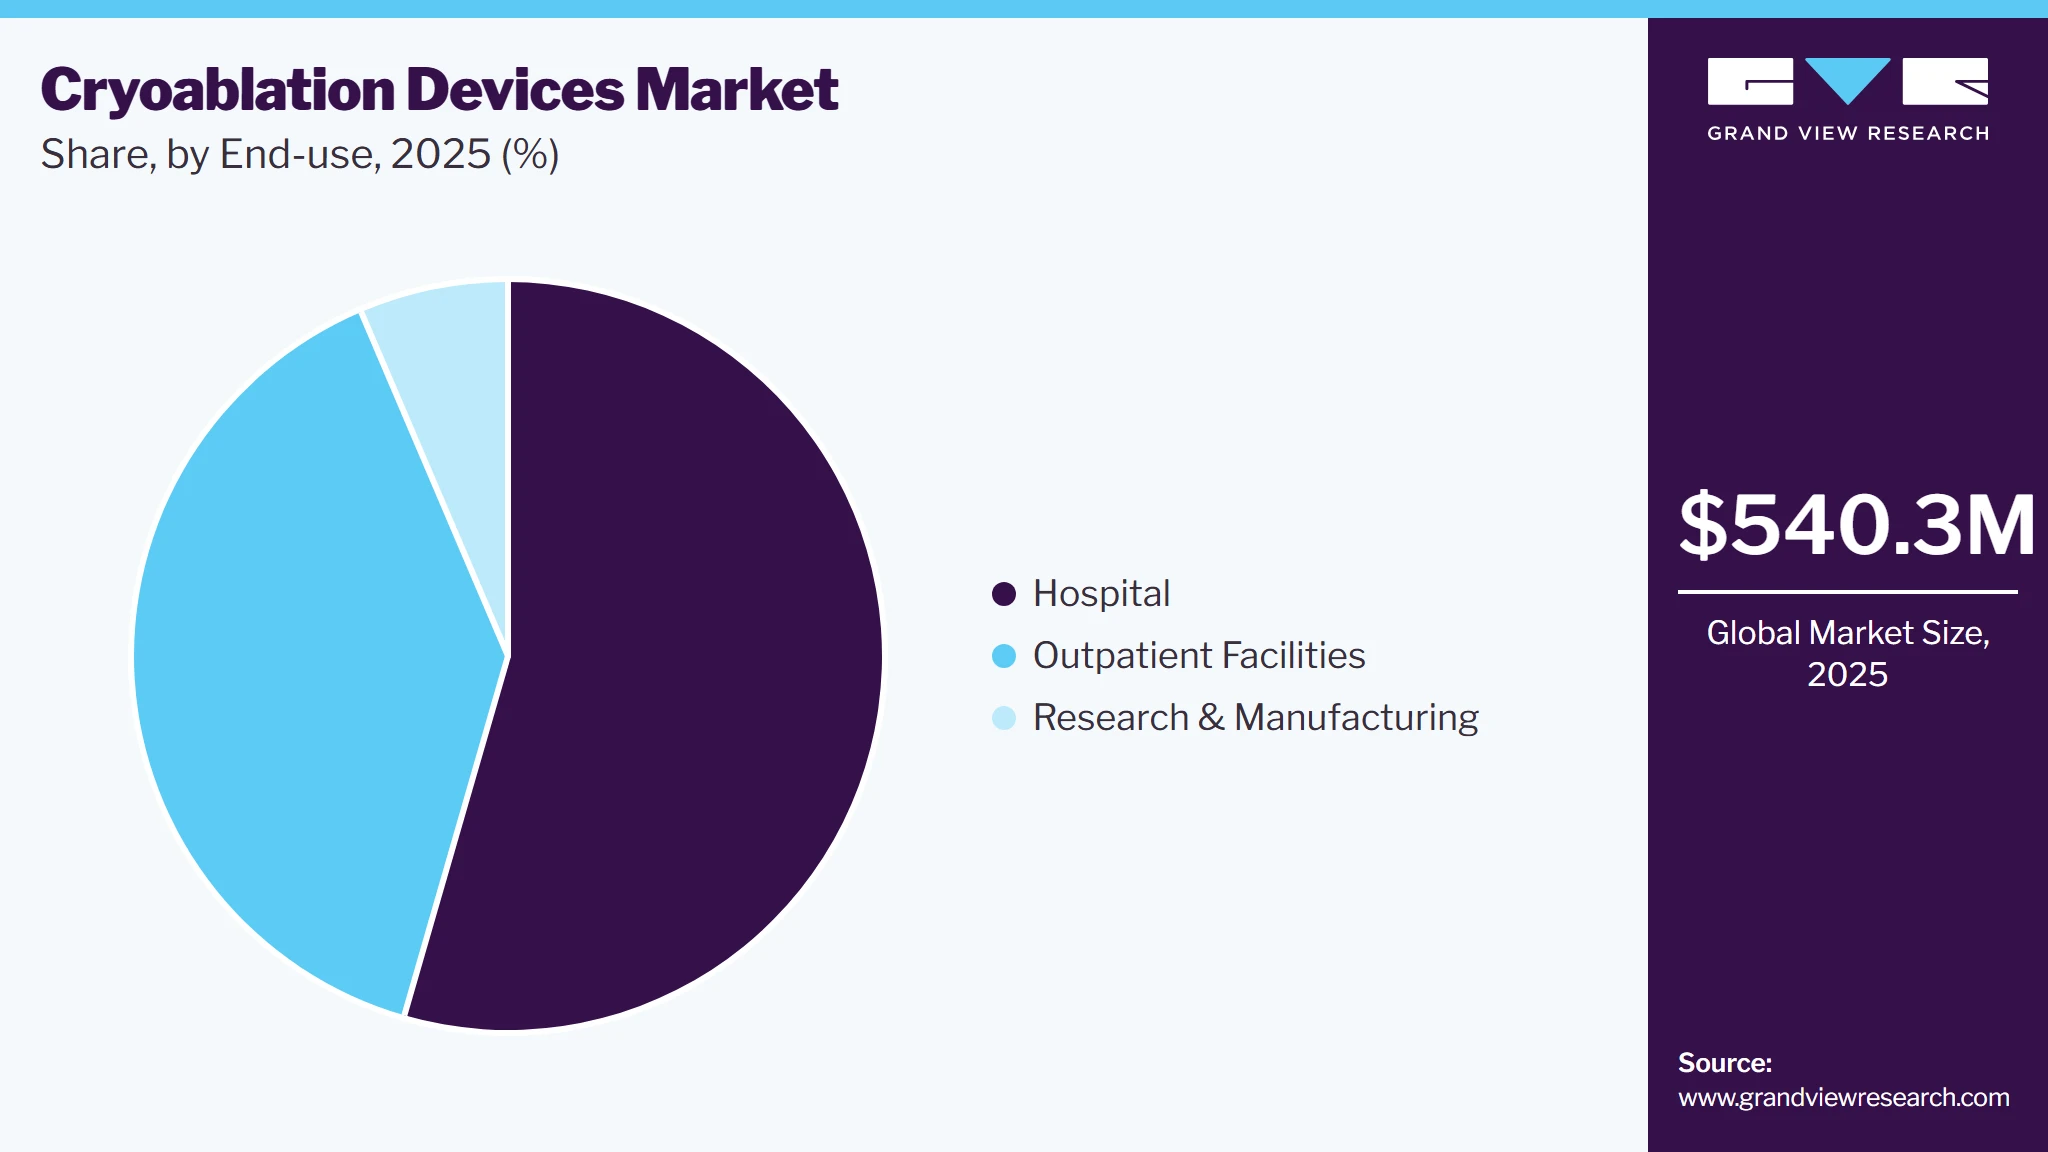
Based on end use, the hospital segment led the market with the largest revenue share of 54.5% in 2025. This is attributed to an increase in patients diagnosed with cardiovascular diseases leading to the increased number of cardiac arrhythmia surgeries performed, which is among the most common surgeries performed in hospitals worldwide. This type of surgery accounts for more resources used in the cardiovascular domain than any other procedure. In developed countries, insurance companies pay for medical expenditures that include ligature costs. Thus, an increase in the number of cancer cases contributes to the rising demand for cryoablation devices in this segment, which is expected to strengthen growth in future years.
 To learn more about this report, Download Free Sample Report
Outpatient facilities are expected to register the fastest CAGR during the forecast period. According to Definitive Healthcare’s platform, in 2022, there were over 11,815 active ambulatory surgical centers present in the U.S. and the number is most likely to rise in the coming years. This rapid growth trend reflects a rising preference for outpatient procedures. The kind of procedures performed in ambulatory centers have undergone substantial changes in recent years. Technological advancements in minimally invasive surgeries are contributing to the growing demand for ambulatory surgical centers.
Regional Insights
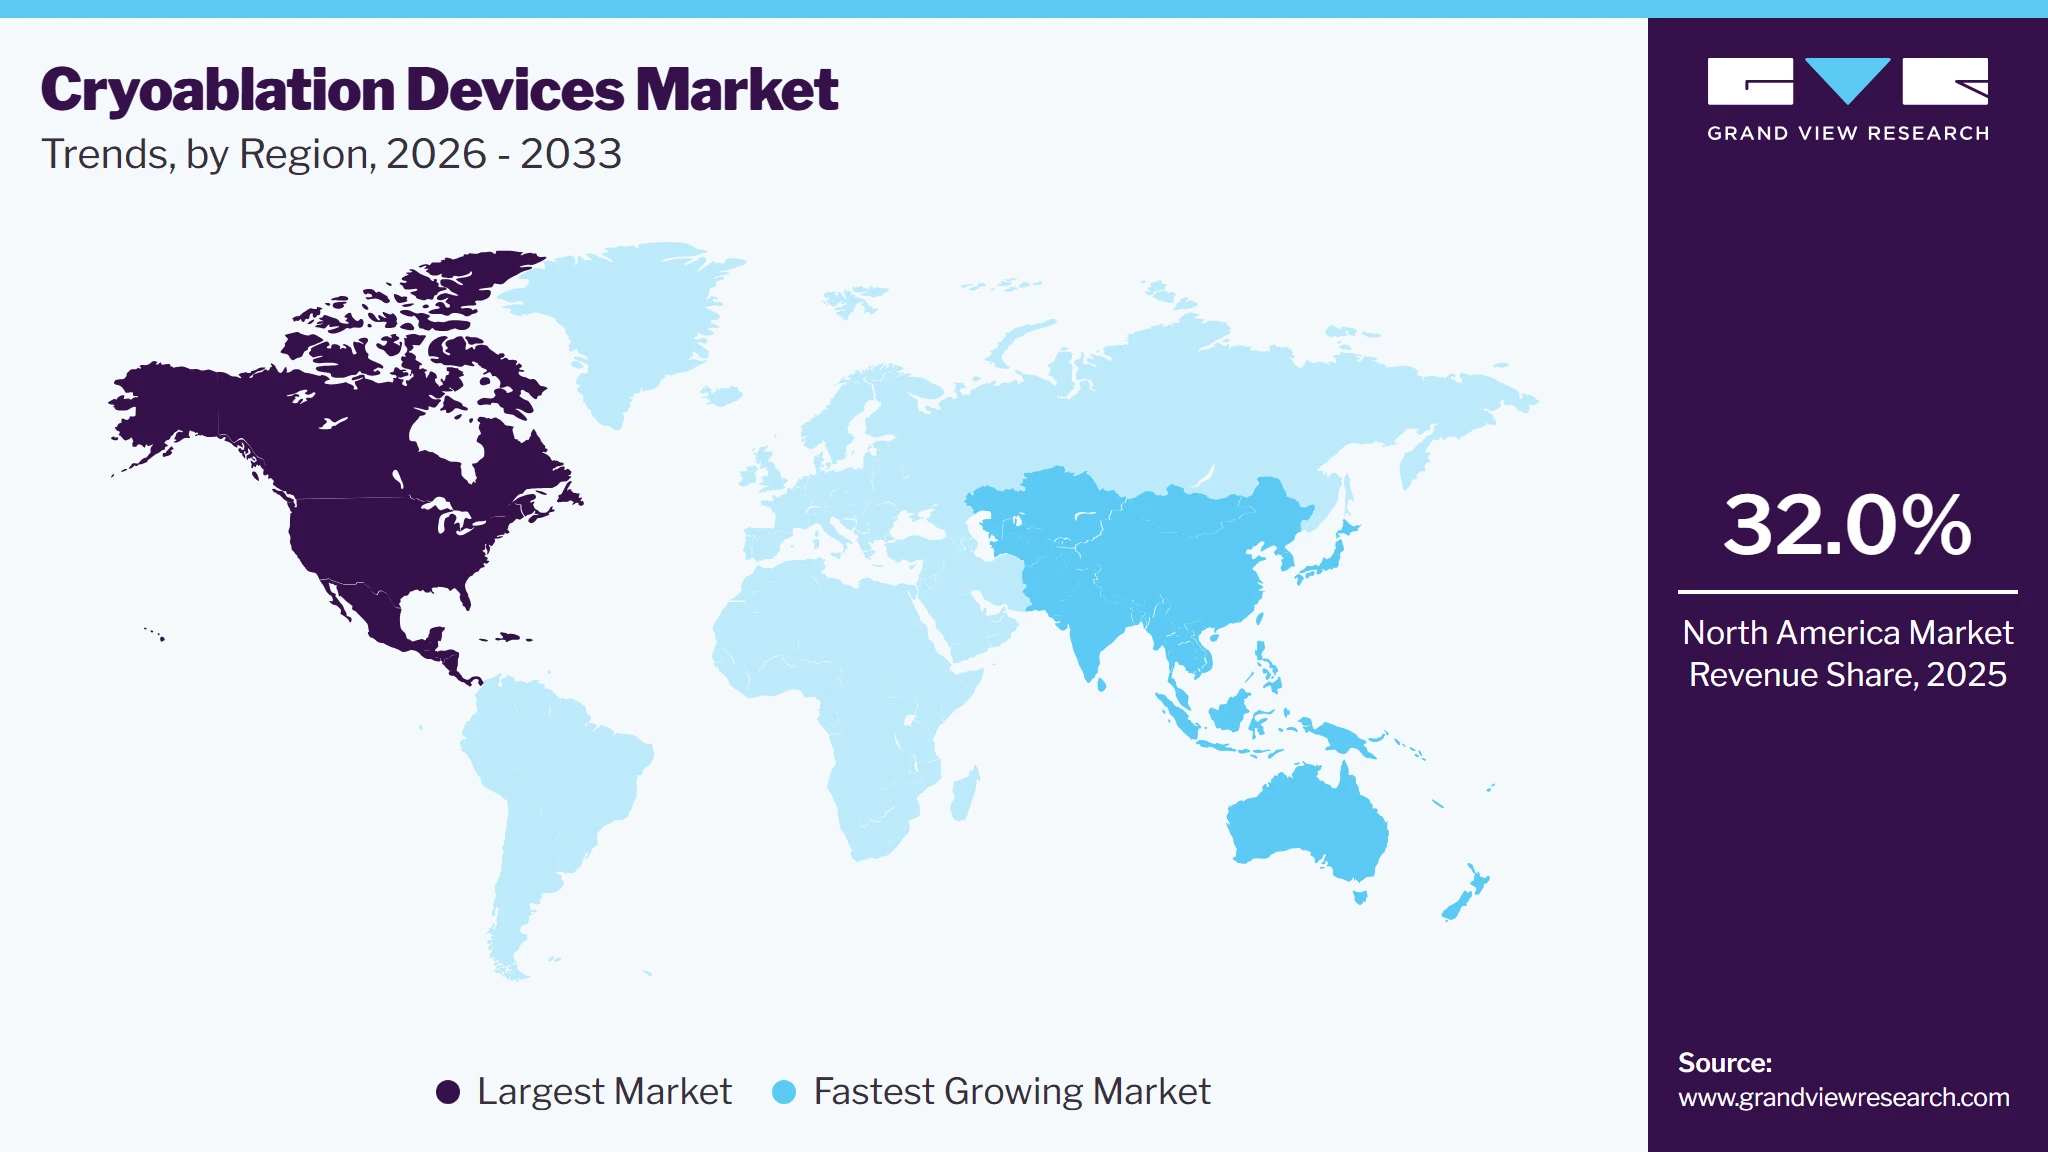
North America dominated the cryoablation devices market with the largest revenue share of 32.0% in 2025, cryoablation devices market held a dominant position, capturing 32.2% in terms of revenue owing to the rising prevalence of cancer, better healthcare infrastructure, availability of reimbursement, and growing geriatric population. These factors are driving the cryoablation devices industry growth in the region. For instance, the Patient Protection and Affordable Care Act (PPACA), a law passed by the U.S. government, promotes affordability along with the quality of healthcare through various health coverage policies, which helps in reducing the expenses of healthcare for individuals and governments.
 To learn more about this report, Download Free Sample Report
U.S. Cryoablation Devices Market Trends
The cryoablation devices market in the U.S. held the largest share in the North America region in 2025. The U.S. is home to key players and research institutions that drive innovation in cryoablation devices technology. The U.S. Food and Drug Administration (FDA) recently recalled catheters associated with Boston Scientific's POLARx Cryoablation System due to a higher risk of esophageal injury, which has been linked to seven patient injuries and four deaths. Approved by the FDA in August 2023, the POLARx Cryoablation System is used to treat recurrent symptomatic atrial fibrillation unresponsive to medical therapy contributing to the growth of the U.S. market.
Europe Cryoablation Devices Market Trends
The Europe cryoablation devices industry was the second largest globally in 2024, owing to the rising public funding in Europe’s healthcare infrastructure. Moreover, the growing geriatric population and growing number of initiatives by government to increase awareness for prevention of tumors is expected to propel market growth. For instance, the European Cancer Observatory aims to spread awareness about the various options available for treatments of tumor, such as advanced minimal invasive surgeries and early diagnostic techniques.
The cryoablation devices industryin the UK is witnessing significant growth due to the rising incidence of chronic diseases such as cancer and the rising elderly population. For instance, according to the Department of Health & Social Care in the UK, the population aged 85 and older is expected to increase by one million between 2021 and 2036.
France cryoablation devices industry is expanding, supported by substantial healthcare spending that guarantees access to quality, patient-focused services. According to World Bank data, in 2021, France allocated approximately 12.31% of its GDP to healthcare. Its robust healthcare infrastructure promotes the adoption of minimally invasive surgical instruments and devices.
The cryoablation devices industry in Germany is primarily fueled by advancements in medical procedures, such as the first intranasal cryotherapy performed at Landstuhl Regional Medical Center (LRMC) in April 2021. This procedure, a first in Germany, uses cryoablation to freeze nasal nerves, treating chronic rhinitis. U.S. Army Lt. Col. Jessica Peck highlighted its significance in addressing both allergic and non-allergic rhinitis. Previously performed in the U.S. for two years, it was only recently approved in Germany. With at least 20% of German adults suffering from allergies, this innovation offers new treatment options for long-term nasal inflammation relief.
Asia Pacific Cryoablation Devices Market Trends
The Asia Pacific cryoablation devices industry is anticipated to register the fastest CAGR over the forecast period. The growing presence of many healthcare providers and the rising patient population in developing countries such as India, Thailand, and China are the major factors estimated to foster market growth. Furthermore, with government assistance, the utilization of healthcare infrastructure in the region is expanding. For instance, the Indian government provides financial support for poor individuals suffering from tumors under the Health Minister Cancer Patient Fund (HMCPF) scheme. These government initiatives and other various factors are anticipated to boost the cryoablation device industry in the Asia Pacific during the period.
The cryoablation devices industry in Japan is growing, primarily driven by the country’s aging population, with approximately 30% aged 65 and older in 2023, according to World Bank data. Growth is further fueled by the introduction of advanced surgical tools and frequent product launches. Manufacturers are heavily investing in R&D to develop innovative instruments that enhance precision, efficiency, and patient care.
China cryoablation devices market held the largest revenue share in Asia Pacific in 2024. China's swiftly changing healthcare landscape and patient needs significantly contribute to the growth of the cryoablation devices industry. The country faces a rising prevalence of chronic diseases such as diabetes, cardiovascular conditions, and autoimmune disorders. For instance, the International Diabetes Federation (IDF) reported that in 2021, 537 million people globally had diabetes, with 206 million in the Western Pacific Region; this number is projected to increase to 260 million by 2045.
The cryoablation devices market in India is set for significant growth, driven by the increasing prevalence of gastrointestinal disorders and colorectal cancer. With colorectal cancer cases rising at an estimated 5% annually, the demand for minimally invasive procedures has increased. India's aging population, projected to reach 20% by 2050, further fuels this demand. Government initiatives, such as the Ayushman Bharat scheme, are enhancing access to advanced healthcare, boosting cryoablation devices.
Latin America Cryoablation Devices Market Trends
The Latin American cryoablation devices industry is primarily driven by Brazil and Argentina. The geriatric population in Latin America is increasing, leading to a higher demand for healthcare services & products. For instance, according to the World Bank, the adult population aged 65 and above in the Latin America and Caribbean region was around 9% of the total population in 2023, which is anticipated to double by 2050.
Middle East & Africa Cryoablation Devices Market Trends
The Middle East and Africa cryoablation devices industry is growing due to advancements in healthcare infrastructure, rising awareness of minimally invasive procedures, and the increasing prevalence of chronic conditions like atrial fibrillation and cancer. The adoption of cryoablation therapies is being driven by the growing demand for cost-effective, less invasive treatment options. In addition, improvements in medical technology, along with regulatory approvals for cryoablation devices, are fueling market expansion.
The cryoablation devices industry in Saudi Arabia is anticipated to grow over the forecast period. The growing geriatric population, which is highly susceptible to chronic diseases, is one of the major factors positively influencing the market growth in this country. For instance, as per Saudi Arabian Monetary Agency (SAMA), the proportion of the Saudi Arabian population aged 60 and above is estimated to reach 25% by the end of 2050.
Key Cryoablation Devices Company Insights
Companies are aiming at manufacturing new medical devices, developments, and technological advancements. Moreover, acquisitions and mergers for novel product development and solidification of the supply chain webs constitute some of the initiatives implemented by the major players. For instance, in August 2022, Medtronic plc announced the acquisition of Affera, Inc., which is a medical technology manufacturer. This acquisition helped Medtronic in expanding the company’s ablation portfolio by comprising the first cardiac navigation and mapping platform, thus introducing one of the most effective cryoablation technologies in the market.
Key Cryoablation Devices Companies
The following key companies have been profiled for this study on the cryoablation devices market.
-
Boston Scientific Corporation
-
Micro Port Scientific Corporation.
-
Medtronic
-
COOPERSURGICAL, INC.
-
ATRICURE, INC.
-
BVM Medical Limited
-
CPSI Biotech
-
Ice Cure Medical
-
METRUM CRYOFLEX Sp. z o.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Boston Scientific Corporation, Micro Port Scientific Corporation., Medtronic, COOPERSURGICAL, INC.)
Focus on expanding comprehensive cryoablation portfolios across oncology, cardiology, pain management, and gynecology applications.
Invest heavily in next-generation cryoprobes, imaging-guided navigation technologies, physician training programs, and strategic acquisitions to strengthen global market presence.
Strong global brand recognition, extensive distribution networks, and well-established relationships with hospitals and healthcare providers support market leadership.
Broad product portfolios integrated with advanced imaging modalities (CT, MRI, and ultrasound guidance) improve procedural precision, treatment outcomes, and physician confidence.
High R&D expenditure, stringent regulatory compliance requirements, and lengthy product approval timelines increase operational costs.
Large organizational structures often result in slower product development cycles and reduced flexibility in responding to niche clinical opportunities.
Emerging Players (CPSI Biotech, Ice Cure Medical, METRUM CRYOFLEX Sp. z o.)
Focus on niche clinical applications such as minimally invasive tumor ablation, office-based procedures, and specialized cryotherapy systems.
Prioritize innovation through compact cryoablation platforms, disposable cryoprobes, enhanced procedural efficiency, and collaborations with research institutes and specialty clinics.
Faster innovation cycles enable rapid introduction of specialized cryoablation technologies tailored to specific clinical indications.
Flexible organizational structures support quicker customization, improved physician engagement, and faster response to evolving market needs.
Limited financial resources, smaller commercial teams, and restricted global distribution networks constrain large-scale expansion.
Lower brand recognition compared with established multinational companies may reduce physician adoption and procurement opportunities.
Recent Developments
-
In December 2024, Boston Scientific revises usage guidelines for POLARx and POLARx FIT Cryoablation Balloon Catheters following an unexpectedly high number of atrio-esophageal fistula reports.
-
In November 2024, IceCure Medical has received a Notice of Allowance from Japan's Patent Office for its 'Cryogenic System with Multiple Submerged Pumps'. This innovation enables independent control of multiple cryoprobes, enhancing the treatment of larger tumors. The patent strengthens IceCure's intellectual property and product portfolio in cryoablation technology.
Cryoablation Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 540.3 million
Estimated market size in 2026
USD 614.3 million
Projected market size by 2033
USD 1,179.0 million
Growth rate
CAGR of 9.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Boston Scientific Corporation; Micro Port Scientific Corporation.; Medtronic; COOPERSURGICAL, INC.; ATRICURE, INC.; BVM Medical Limited; CPSI Biotech; Ice Cure Medical; METRUM CRYOFLEX Sp. z o.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cryoablation Devices Market Report Segmentation
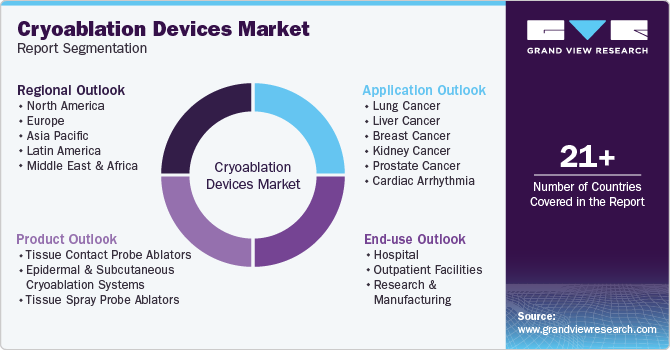
This report forecasts revenue growth at country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global cryoablation devices market report based on product, application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Tissue Contact Probe Ablators
-
Epidermal and Subcutaneous Cryoablation Systems
-
Tissue Spray Probe Ablators
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Lung Cancer
-
Liver Cancer
-
Breast Cancer
-
Kidney Cancer
-
Prostate Cancer
-
Cardiac Arrhythmia
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital
-
Outpatient Facilities
-
Research & Manufacturing
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The cryoablation devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each cryoablation devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Tissue Contact Probe Ablators
Revenue is generated through the commercialization of rigid or flexible percutaneous cryoprobes designed to deliver targeted cryogenic energy via direct contact with internal structures. Manufacturers earn significant income through the upfront capital sale of primary multi-channel gas consoles, supplemented by high-volume, recurring orders for specialized single-use cryoprobes that pull through gases to execute precise, real-time focal tissue necrosis.
Epidermal and Subcutaneous Cryoablation Systems
Revenue flows from the sale of specialized superficial and sub-surface cryotherapy workstations optimized for accessible, shallow target lesions. Market participants capture recurring product revenue from single-use dermatological applicators, localized micro-needling freeze arrays, and portable office-based consoles, driven by high-frequency treatment volumes for superficial carcinomas, keloids, and benign skin lesions.
Tissue Spray Probe Ablators
Revenue is captured through the production and distribution of open- or closed-system cryo-spray technologies that deploy a localized, non-contact stream of liquid nitrogen or argon gas across irregular, broad tissue surfaces. Companies derive income from specialized spray nozzles, flexible endoscopic delivery catheters, and high-frequency gas canister refills, utilized primarily across complex endoluminal oncology, gastroenterology, and advanced airway interventions.
Segment - Application
Revenue capture definition
Lung Cancer
Revenue is derived from the supply of high-precision, flexible cryo-catheters and percutaneous probes integrated with CT or endobronchial ultrasound (EBUS) navigation. Medtech companies capture value through the recurring utilization of ultra-fine probes to palliate central airway obstructions or ablate early-stage malignant pulmonary nodules in non-operative candidates.
Liver Cancer
Revenue flows from robust, multi-probe cryoablation setups engineered to treat primary hepatocellular carcinomas (HCC) and colorectal liver metastases. Income is driven by the utilization of multiple simultaneous probes per patient profile, which are required to form overlapping, large-diameter "ice balls" under real-time ultrasound or CT visualization to achieve clean oncological margins.
Breast Cancer
Revenue is captured through the commercialization of specialized, patient-friendly cryoablation kits marketed to outpatient breast care centers as a non-surgical option for early-stage fibroadenomas and low-risk luminal breast malignancies. Manufacturers maximize value by selling complete disposable procedural packs that bundle local anesthetic needles, thermal sensors, and high-conductivity localized freezing probes.
Kidney Cancer
Revenue is generated by marketing nephron-sparing cryoablation systems used to treat small renal masses. Income is secured through high-frequency percutaneous probe re-orders, sustained by established clinical guidelines favoring image-guided cryo-destruction over partial nephrectomies to preserve maximal renal biological function.
Prostate Cancer
Revenue streams develop from multi-probe percutaneous template systems and transrectal ultrasound (TRUS)-guided focal cryoablation packages. Manufacturers monetize this application through the concurrent sale of high-density arrays of active freezing probes, urethral warming safety catheters, and specialized pelvic template accessories designed to target localized prostate adenocarcinomas while protecting nearby nerve structures.
Cardiac Arrhythmia
Revenue is captured through premium electrophysiology (EP) lab device distribution, anchored on cryogenic balloon catheters and mapping-integrated console suites used for pulmonary vein isolation (PVI) in atrial fibrillation. Market participants earn substantial, high-margin revenue from advanced, single-use steerable balloon catheters and localized focal freezing tips that create uniform, transmural electrical isolation scars.
Segment - End Use
Revenue capture definition
Hospital
Revenue is generated through major capital equipment budget approvals, public or private medical group tenders, and institutional group purchasing organization (GPO) supply frameworks. Manufacturers secure bulk enterprise value via the deployment of multi-specialty, multi-channel capital cryo-consoles, multi-year clinical service warranties, and large-volume wholesale contracts for sterile, single-use percutaneous and catheter consumables.
Outpatient Facilities
Revenue flows from targeted, high-throughput commercial sales to ambulatory surgery centers (ASCs) and specialized specialty clinics. Income is driven by space-saving, portable cryo-consoles and rapid-turnaround single-use consumable configurations that align with the outpatient model's goal of accelerating patient turnaround, reducing overnight stay costs, and maximizing regional commercial volume.
Research & Manufacturing
Revenue is captured by distributing open-architecture cryo-consoles, custom micro-probe configurations, and specialized software modules to academic medical universities, pharmaceutical test groups, and pre-clinical contract research organizations (CROs). This niche segment commands high premium pricing tiers funded by institutional development grants and biotechnology corporate R&D allocations.
Estimation Model
01 - Scope Definition
02 - Build the Product Base
03 - Estimate Penetration
04 - Revenue Conversion
What is being measured in the Cryoablation Devices Market?
What is the total addressable market for cryoablation devices?
How rapidly are cryoablation technologies being adopted across clinical applications?
How do procedure volumes translate into market revenue?
Process Steps
Process Steps
Process Steps
Process Steps
1. Define cryoablation device product categories including
1. Assess disease prevalence and procedure-eligible patient populations
1. Measure penetration of cryoablation compared with alternative treatment modalities
1. Collect average selling prices (ASP) for cryoablation systems, and accessories
2. Segment the market by application
2. Estimate annual cryoablation procedure volumes by country
2. Assess adoption rates across hospitals, academic medical centers, specialty clinics, and ambulatory surgical centers
2. Estimate recurring revenue generated from disposable probes, consumables, maintenance contracts, and service agreements
3. Define end-user categories
3. Evaluate installed base of cryoablation systems and utilization rates across healthcare facilities
3. Evaluate technology diffusion driven by clinical evidence, physician preference, reimbursement policies, and availability of trained specialists
3. Segment revenues by product type, application, end user, and geography while accounting for capital equipment replacement cycles
4. Establish geographic scope and align on base year & forecast horizon (2026-2033)
4. Forecast future procedure demand considering disease incidence, technology adoption, expanding clinical indications, and healthcare infrastructure investments
4. Analyze regional adoption differences based on healthcare expenditure, regulatory approvals, availability of skilled specialists, and installed equipment base
4. Cross-check market estimates with import/export data and industry sales benchmarks
DATA SOURCES: Company annual reports, clinical guidelines, oncology & cardiology associations
DATA SOURCES: WHO, GLOBOCAN, CDC, hospital procedure databases, reimbursement agencies, physician interviews
DATA SOURCES: Primary interviews with interventional radiologists, electrophysiologists, oncologists, urologists
DATA SOURCES: Annual reports, distributor sales data, procurement databases, import/export statistics, hospital purchasing records
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country Specific Analysis
Conducted a comprehensive country-level assessment of the U.S. and Canada cryoablation devices market, covering market size, procedure volumes, adoption trends, healthcare infrastructure, reimbursement frameworks, regulatory landscape, and competitive positioning. The study evaluated market demand across major application areas including oncology, cardiology, pain management, dermatology, gynecology, and urology. It further analyzed leading manufacturers, product channel optimization, and investment prioritization. The study portfolios, pricing strategies, distribution networks, hospital penetration, physician adoption, and technological advancements in cryoablation systems and cryoprobes. High-growth application areas were identified, and country-specific assessments examined government healthcare initiatives, cancer prevalence, chronic disease burden, and investment in minimally invasive treatment technologies, along with regional growth opportunities influencing market expansion in both countries.
Enables stakeholders to gain a comprehensive understanding of market opportunities across the U.S. and Canada, supporting informed decisions regarding regional expansion, product positioning, commercialization strategies, distribution channel optimization, and resource allocation. The analysis helps stakeholders benchmark competitive performance, evaluate reimbursement and regulatory environments, identify high-growth application areas, and develop country-specific market entry and expansion strategies while minimizing commercial risks.
Market Dynamics Study
Conducted an in-depth assessment of the key factors influencing the global cryoablation devices market, evaluating major market drivers, restraints, opportunities, and emerging industry trends. The study analyzed the impact of increasing cancer incidence, rising adoption of minimally invasive procedures, expanding utilization of image-guided interventions, technological advancements in cryoablation systems, and growing preference for outpatient treatments. It also examined market restraints including high capital equipment costs, reimbursement challenges, procedural complexity, and competition from alternative thermal ablation technologies. Furthermore, the analysis identified emerging opportunities associated with expanding clinical applications, increasing healthcare investments, product innovation, and ongoing clinical research supporting cryoablation therapies.
Enables stakeholders to understand the underlying forces driving market growth and competitive evolution while supporting strategic business planning and long-term investment decisions. The study assists manufacturers in identifying growth opportunities, evaluating market risks, prioritizing R&D investments, strengthening product differentiation, developing commercialization strategies, and aligning product portfolios with evolving clinical requirements and future market demand.
Macroeconomic Analysis
Conducted a detailed macroeconomic assessment of the global factors influencing the cryoablation devices market. The study evaluated healthcare expenditure, government investments in cancer care infrastructure, inflationary trends, currency business fluctuations, manufacturing costs, international trade policies, supply chain dynamics, and regulatory developments affecting related healthcare spending and commercialization. It further assessed demographic trends including aging populations, increasing prevalence of chronic diseases and cancer, expansion of healthcare infrastructure, capital investments by hospitals, and economic conditions influencing procurement decisions and technology adoption across developed and emerging markets.
Enables stakeholders to assess external economic factors influencing market growth, operational efficiency, and long-term sustainability. The study supports strategic planning by identifying economic opportunities and potential risks related to healthcare spending, inflation, trade policies, supply chain resilience, and capital investments. It further assists organizations in optimizing pricing strategies, regional expansion plans, manufacturing investments, procurement planning, and resource allocation to strengthen competitiveness across global markets.
Frequently Asked Questions About This Report
By product, the tissue contact probe ablators segment held a leading market share of 45.6% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
North America dominated the cryoablation devices market with a share of 32.0% in 2025. This is attributable to the increasing prevalence of cancer such as lung and prostrate cancer and cardiac arrhythmia in North America.
The global cryoablation devices market size was valued at USD 540.3 million in 2025 and is estimated at USD 614.3 million for 2026.
The global cryoablation devices market is expected to grow at a CAGR of 9.0% from 2026 to 2033, reaching USD 1,179.0 million by 2033.
By application, the cardiac arrhythmia segment held a leading market share of 38.0% in 2025.
Some key players operating in the cryoablation devices market include Boston Scientific Corporation, MicroPort Scientific Corporation, Medtronic, COOPERSURGICAL, INC., ATRICURE, INC., BVM Medical Limited, CPSI Biotech, and IceCure Medical.
Key factors that are driving the market growth include Increasing preference for minimally invasive surgeries, new product launches, and rising prevalence of cancer.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


