
- Home
- »
- Organic Chemicals
- »
-
Cumene Market Size, Share And Trends Report, 2026-2033GVR Report cover

Cumene Market (2026 - 2033)
Size, Share & Trends Analysis Report By Production (Zeolite, Solid Phosphoric Acid, Aluminum Chloride), By Application (Phenol, Acetone), By Region (North America, Europe, Asia Pacific, CSA, MEA), And Segment Forecasts
Market Size, 2025
$27.1BMarket Estimate, 2026
$28.4BMarket Forecast, 2033
$39.4BCAGR, 2026–2033
4.8%Cumene Market Summary
The global cumene market size was valued at USD 27.1 billion in 2025 and is projected to grow from USD 28.4 billion in 2026 to USD 39.4 billion in 2033, at a CAGR of 4.8% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 48.0% in 2025. Its growing demand across applications such as laminates, composites, and plastics is expected to drive the market growth.
Key Market Trends & Insights
- By production: Zeolite segment held the largest market share in 2025.
- By application: Phenol segment held the largest market share of over 61.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (48.0% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 27.1 Billion
- Estimated market size in 2026: USD 28.4 Billion
- Projected market size by 2033: USD 39.4 Billion
- CAGR (2026-2033): 4.8%
Prism AI by Grand View Research Free to tryAsk a question about the cumene marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Cumene, also known as isopropylbenzene, is an organic compound. It is formed by an aliphatic substitution of aromatic compounds and is a constituent of refined fuels & crude oil. Isopropylbenzene is characterized by its colorless & flammable nature, and it boils at 152°C. For commercial use, it is manufactured by the Friedel-Crafts alkylation method.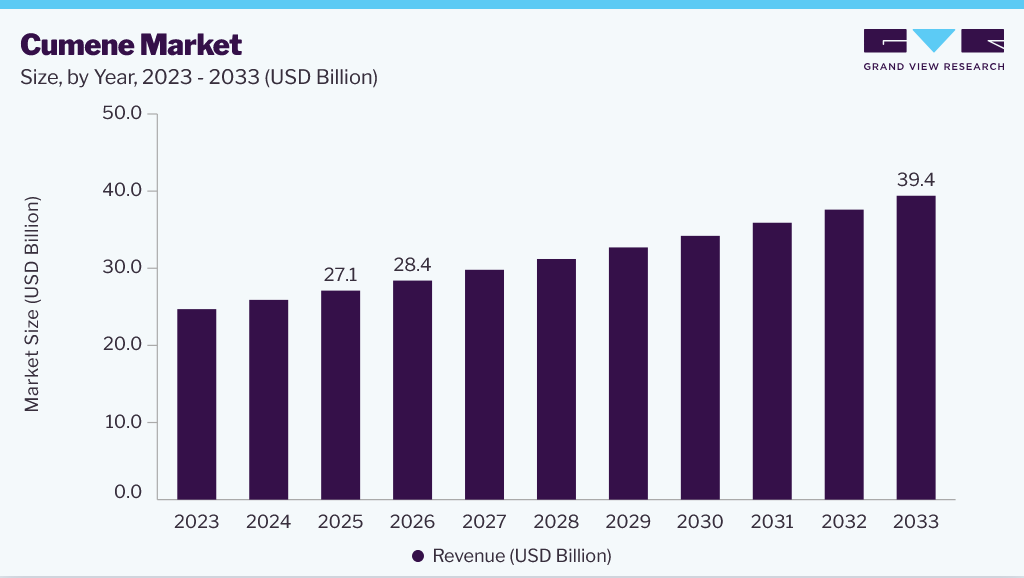 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The organic compound isopropylbenzene is also used the produce other chemicals, such as phenols and acetone. All the pure cumene compounds produced on an industrial scale are transformed into cumene hydroperoxide. This compound is used as an intermediate in the production of industrial chemicals such as acetone and phenol.
Cumene is a highly stable compound but tends to form peroxides when exposed to air. It is known to be incompatible with some reactions when coupled with strong oxidizing agents. Because of this, it is often tested for peroxide content before distillation or heat treatment.
Analyst Perspective
The global cumene market is experiencing steady growth, primarily driven by rising downstream demand for phenol and acetone, which are essential feedstocks for polycarbonate resins, epoxy resins, bisphenol A, and phenolic resins used in automotive, electronics, construction, and consumer goods. In addition, continuous improvement in production processes using zeolites helps to increase efficiency, reduce the environmental footprint, and cut down operational expenses, thus facilitating the capacity upgrade of petrochemical plants. Moreover, growth of manufacturing operations in the Asia Pacific region and increasing investments in high-quality plastics, composites, and specialty chemicals are likely to support the demand for cumene going forward.
Production Insights
The zeolite segment held the largest share of the cumene industry in 2025. Zeolite catalysts have largely replaced conventional catalyst systems owing to their superior selectivity toward cumene, higher conversion efficiency, longer catalyst life, and environmentally friendly operation. Unlike traditional homogeneous catalysts, zeolite-based processes minimize by-product formation, eliminate corrosive waste streams, and reduce operating and maintenance costs. Furthermore, increasingly stringent environmental regulations and ongoing investments in sustainable petrochemical manufacturing technologies are accelerating the adoption of zeolite catalysts in both new and existing cumene production facilities. For instance, in 2025, ExxonMobil Product Solutions highlighted that its Badger Cumene Process, powered by proprietary MCM-22 zeolite catalysts, delivers ultra-high cumene yields while replacing older aluminum chloride technologies with a more energy-efficient, lower-environmental-impact process, reinforcing the industry's growing preference for zeolite-based cumene production.
Cumene is manufactured primarily through the catalytic alkylation of benzene with propylene. The feedstocks are combined and introduced into a reactor, where they react to produce cumene. The resulting mixture is separated and purified to recover high-purity cumene, while unreacted benzene is recycled to improve process efficiency. The production process and catalyst technology influence raw material utilization, energy consumption, product yield, and operating costs.
The vaporized mixture is then mixed with solid phosphoric acid, which acts as a catalyst and helps to obtain a stable cumene product. Solid phosphoric acid, along with alumina, is used as a catalyst to obtain a highly stable and safe product. These reactions can be carried out in liquid or gaseous states. However, to obtain high conversion and stable products, a gaseous state is used.
The Friedel-Crafts alkylation method is also used to manufacture cumene. The method is obtained by the addition of aluminum chloride to aromatic benzene. This reaction takes place at around 130°C. Some of the disadvantages of the method include environmental hazards, high corrosion, and tedious washing for the removal of the catalyst.
Modern industrial processes employ the use of zeolites as a catalyst for the production of cumene. Zeolites have various advantages over aluminum chloride. The use of zeolites helps reduce the formation of olefin oligomers and polyalkylbenzenes, thereby enabling the attainment of a yield of 98%. The catalyst also enables alkylation at lower pressure and temperatures.
Application Insights
The global market for cumene is benefiting from increasing demand for phenol and acetone. Phenol emerged as the largest application segment and accounted for over 61.0% of the total market revenue in 2025.
Isopropylbenzene is used extensively for the production of phenols and their derivatives. Some of the phenol derivatives produced with the help of cumene include phenol resins, caprolactam, bisphenol A, and alkyl phenols. Bisphenol A is the largest derivative of phenol, which is further utilized for the production of polycarbonate and epoxy resins. The polycarbonate resins are mixed with glass and metals for use in the automotive sector.
The polycarbonate derived from Bisphenol A using cumene is used in security (sheets & glazing) and architectural applications. The polycarbonate is also utilized for the production of versatile and compact discs. Epoxy resins are utilized in high-performance adhesives, electrical laminates, coatings, paving, and flooring applications.
The phenol resins derived from isopropylbenzene find their usage in the home construction sector in the form of adhesives for structural wood panels, and in the production of mineral wool insulation as binders. Caprolactam is another derivative of phenol, which is primarily utilized for the manufacturing of nylon 6.
Acetone is another important chemical produced from cumene. The various acetone derivatives produced with the help of isopropylbenzene include methyl methacrylate, solvent, bisphenol A, and aldol chemicals. The methyl methacrylate derived from cumene is primarily used the produce copolymers and homopolymers. These polymers are used in the manufacturing of liquid crystal displays and flat-screen television sets.
Regional Insights
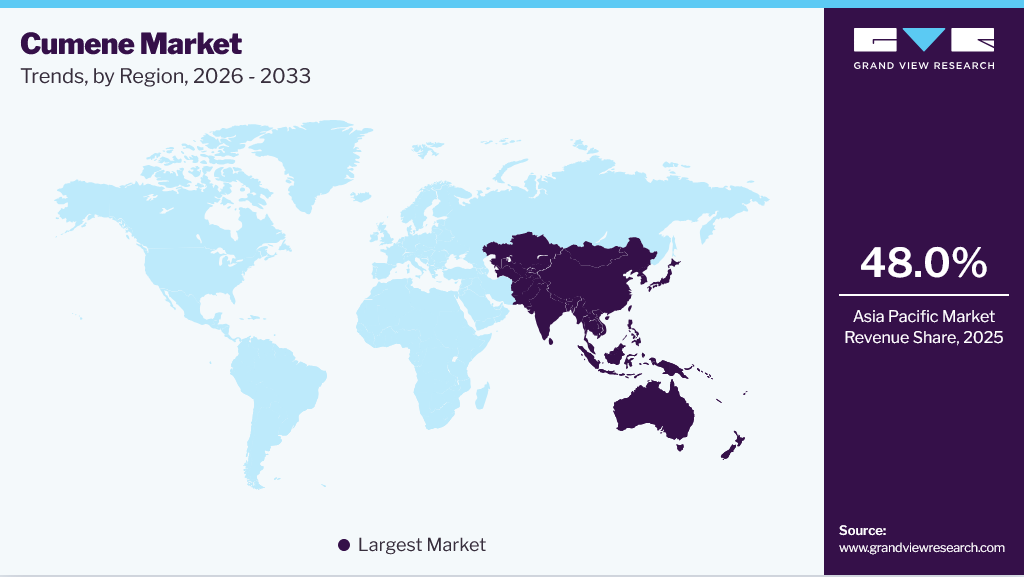
The Asia Pacific cumene market held the largest global revenue share of 48.0% in 2025 and is expected to grow at the fastest CAGR over the forecast period. This is attributed to rapid industrialization, expanding petrochemical production, and increasing demand for phenol and acetone from the plastics, electronics, automotive, and construction industries. Rising investments in integrated chemical complexes, coupled with growing consumption of polycarbonates, epoxy resins, and phenolic resins across China, India, South Korea, and Southeast Asia, are expected to accelerate regional market growth. Moreover, favorable government policies supporting domestic chemical manufacturing continue to strengthen the region's production capabilities. In addition, growing investments in capacity optimization and integrated production facilities are expected to drive market growth in the forecast period.
 To learn more about this report, Download Free Sample Report
For instance, in April 2025, Deepak Chem Tech Limited, a wholly owned subsidiary of Deepak Nitrite Limited, approved an investment of approximately USD 419 million to establish a new integrated manufacturing complex comprising a 300 KTPA phenol plant, a 185 KTPA acetone plant, and a 100 KTPA isopropyl alcohol (IPA) plant in Dahej, India. The project is designed to further integrate into polycarbonate resin production, highlighting the increasing investments in integrated petrochemical complexes across Asia Pacific to meet the growing regional demand for phenol, acetone, and downstream specialty materials.
North America Cumene Market Trends
The North America cumene industry accounted for a significant revenue share in 2025. Primarily supported by its well-established petrochemical infrastructure, abundant availability of benzene and propylene feedstocks, and the strong presence of integrated phenol and acetone manufacturing facilities. The region also benefits from robust demand from the automotive, construction, electronics, and coatings industries, where phenol and acetone derivatives are extensively utilized. In addition, continuous investments in capacity optimization and integrated production facilities are expected to strengthen the region's leadership in the global market.
For instance, INEOS Phenol has continuously invested in optimizing its integrated North American manufacturing network, increasing the production capacity of its Pasadena, Texas cumene plant to approximately 907,000 tonnes per annum through debottlenecking and process optimization. The facility, which supplies cumene to downstream phenol and acetone production units, is the world's largest standalone cumene plant, highlighting the company's continued investment in integrated production infrastructure and reinforcing North America's leadership in the global market.
The U.S. cumene industry dominated North America in 2025 and is projected to grow at a steady CAGR over the forecast period. Increasing demand for enamels, lacquers, and paints, along with the growing cumene usage for the manufacturing of steel, iron, and rubber in the country, is anticipated to boost the market growth.
Key Cumene Company Insights
The cumene market is characterized by the presence of a large number of established players. Major players in the industry include ExxonMobil Corporation, BASF, China Petroleum & Chemical Corporation, SABIC, INEOS AG, and others. The world’s leading companies are using partnerships, collaborations, acquisitions, mergers, and agreements as strategies to withstand the intense competition and increase their market share.
For instance, in April 2024, INEOS completed the acquisition of TotalEnergies' 50% interests in the Naphtachimie, Appryl, and Gexaro joint ventures at Lavéra, France, becoming the sole owner of these petrochemical assets. The acquisition strengthens INEOS' integrated aromatics and petrochemical production network, supporting the supply chain for key feedstocks used in downstream products such as cumene, phenol, and acetone.
Key Cumene Companies
The following key companies have been profiled for this study of the cumene market.
-
Versalis S.p.A.
-
Moeve
-
Exxon Mobil Corporation
-
BASF
-
China Petroleum & Chemical Corporation
-
SABIC
-
INEOS AG
-
TotalEnergies
-
Chang Chun Group
-
Braskem
Recent Developments
-
In January 2025, Versalis S.p.A. entered into a strategic partnership with Lummus Technology under which Lummus became the exclusive licensor of Versalis' phenolics technologies, covering the entire value chain from cumene to cyclohexanone oxime. The collaboration aims to expand the global commercialization of advanced technologies for cumene and phenol production while improving process efficiency and sustainability in future petrochemical projects.
Cumene Market Report Scope
Report Attribute
Details
Market size in 2025
USD 27.1 billion
Estimated market size in 2026
USD 28.4 billion
Projected market size by 2033
USD 39.4 billion
Growth rate
CAGR of 4.8% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Kilotons, Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Production, application, and region
Regional scope
North America, Europe, Asia Pacific, Central & South America, Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; France; Germany; Italy; Spain; China; India; South Korea; Japan; Australia; Brazil; Argentina; South Africa; UAE
Key companies profiled
Versalis S.p.A.; Moeve; Exxon Mobil Corporation; BASF; China Petroleum & Chemical Corporation; SABIC; INEOS AG; TotalEnergies; Chang Chun Group; Braskem
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Cumene Market Report Segmentation
This report forecasts volume and revenue growth at the global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global cumene market based on production, application, and region:
-
Production Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Zeolite
-
Solid phosphoric acid
-
Aluminum chloride
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Phenol
-
Phenol resins
-
Caprolactam
-
Bisphenol A
-
Alkylphenols
-
Others
-
-
Acetone
-
Solvent use
-
Methyl methacrylate
-
Aldol Chemicals
-
Others
-
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
France
-
Germany
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
South Korea
-
Japan
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
-
About the Author(s)
Organic Chemicals Research Team
Bulk Chemicals · Organic ChemicalsThis report was authored by the organic chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the organic chemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


