
- Home
- »
- Plastics, Polymers & Resins
- »
-
Dairy Packaging Market Size, Growth Report, 2026-2033GVR Report cover

Dairy Packaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Plastic, Glass, Metal, Paper & Paperboard), By Packaging Type (Cans, Bottles, Bags & Pouches, Films & Wraps), By Region, And Segment Forecasts
Market Size, 2025
$32.7BMarket Estimate, 2026
$33.5BMarket Forecast, 2033
$40.4BCAGR, 2026–2033
2.7%Dairy Packaging Market Summary
The global dairy packaging market size was valued at USD 32.7 billion in 2025 and is projected to grow from USD 33.5 billion in 2026 to USD 40.4 billion by 2033, at a CAGR of 2.7% from 2026 to 2033. The Asia Pacific dominated the market, accounting for a revenue share of 35.0% in 2025. This growth is driven by the increasing demand for dairy products, particularly in emerging economies.
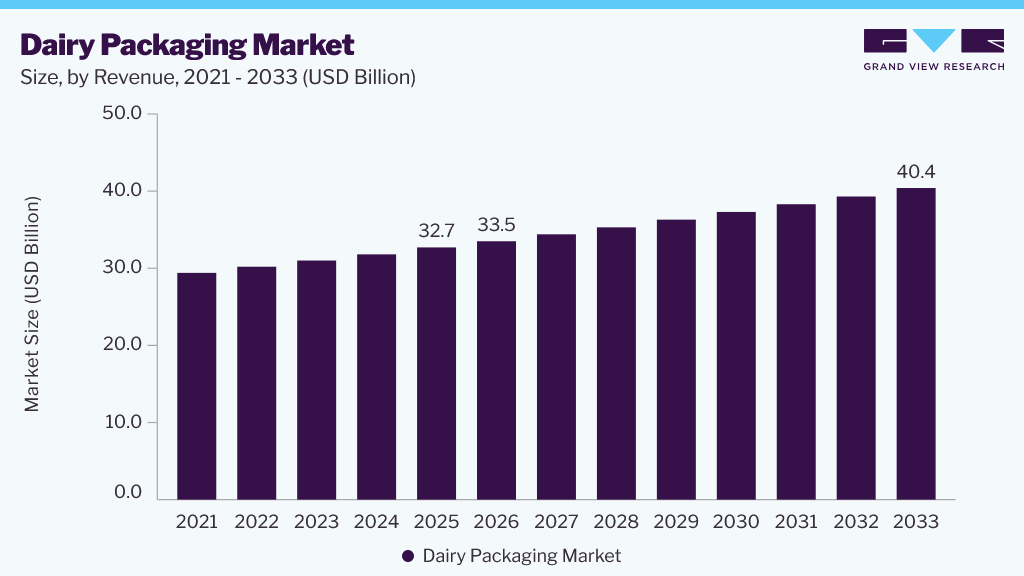 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: The plastic segment held the largest market share of around 45.0% in 2025.
- By packaging type: The bottles segment held the largest market share of over 15.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (35.0% revenue share, 2025)
- Fastest-growing regional market: Middle East & Africa (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 32.7 Billion
- Estimated market size in 2026: USD 33.5 Billion
- Projected market size by 2033: USD 40.4 Billion
- CAGR (2026-2033): 2.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Rising disposable incomes and a growing preference for healthier diets are expected to increase dairy consumption, driving demand for dairy packaging solutions. Additionally, the growing trend of convenience foods and ready-to-eat dairy products is boosting the need for efficient and attractive packaging.
The global dairy packaging market is currently experiencing a prominent shift towards sustainable and eco-friendly packaging materials, such as biodegradable plastics and recyclable paperboard, in response to increasing environmental concerns. Smart packaging solutions, which include features such as freshness indicators and QR codes for product information, are also gaining traction. Looking ahead, the market is expected to see further integration of advanced technologies such as modified atmosphere packaging (MAP) and aseptic packaging, which preserves the quality and extending the shelf life of dairy products. Moreover, the growing popularity of plant-based dairy alternatives is likely to influence packaging trends, requiring new solutions to cater to this expanding segment.
Analyst Perspective
The global dairy packaging market is experiencing steady growth driven by changes in consumer behavior and a shift towards sustainable products, and advancements in packaging technology. Increasing consumption of dairy products in emerging economies due to increasing disposable incomes and urbanization continues to generate demand for new packaging designs. Companies are focusing on lightweight, recyclable, and renewable materials to address environmental concerns and evolving regulatory standards. Additionally, the use of smart packaging, advance technologies, and extended shelf-life technology is improving product safety and logistics. The emergence of plant-based dairy substitutes is providing more opportunities to companies to innovate in the field of packaging.
Material Insights
The plastic segment accounted for approximately 45.0% of the market revenue in 2025, attributed to the versatility and durability of plastic materials widely used for dairy products such as milk, yogurt, and cheese. Plastics offer excellent barrier properties, protecting dairy products from contamination and extending their shelf life. Additionally, the lightweight nature of plastic reduces transportation costs and carbon emissions, making it a cost-effective and environmentally friendly option. Innovations in plastic packaging, such as the development of biodegradable and recyclable plastics, are further enhancing the appeal of this segment. For instance, in December 2024, Berry Global collaborated with Finnish dairy company Valio to introduce a customized CombiLight packaging solution for its PROfeel protein pudding range. The package combines a lightweight plastic structure with enhanced barrier properties to maintain product freshness and shelf life while reducing plastic usage. The development highlights ongoing innovation in plastic dairy packaging aimed at improving product protection, extending shelf life, and advancing sustainability objectives.
The paper and paperboard segment is expected to grow at a CAGR of approximately 3.0% from 2026 to 2033, driven by the increasing consumer demand for eco-friendly and sustainable packaging options. Paper and paperboard materials are biodegradable and recyclable, aligning with the global shift towards reducing plastic waste and promoting environmental sustainability. These materials are particularly popular for packaging products such as butter, cream, and other dairy items that do not require the same level of barrier protection as liquid dairy products. Additionally, advancements in paper and paperboard packaging technologies, such as improved moisture resistance and strength, are expanding their applications in the dairy industry. For instance, in April 2024, Mother Parkers Tea & Coffee partnered with Graphic Packaging International to introduce the Boardio fiber-based paperboard canister for retail coffee packaging. Made primarily from renewable paperboard, the packaging provides an alternative to plastic, glass, and metal containers while maintaining food safety and product freshness. The initiative highlights the growing adoption of recyclable paperboard packaging solutions across food and dairy-related applications as brands seek to reduce packaging waste and improve sustainability performance.
Packaging Type Insights
The bottle segment dominated the market in 2025 as bottles are particularly favored for liquid dairy products such as milk, yogurt drinks, and cream due to their durability, ease of handling, and ability to provide excellent protection against contamination. The use of materials such as PET (polyethylene terephthalate) in bottle manufacturing offers several advantages, including lightweight properties, recyclability, and the ability to maintain product freshness over extended periods. Additionally, bottles are often designed with user-friendly features such as resealable caps, which enhance convenience for consumers. The dominance of this segment is also driven by the increasing demand for single-serve and on-the-go dairy products, which are typically packaged in bottles. For instance, in April 2024, Nestlé upgraded the packaging of its Nesquik ready-to-drink dairy beverages by introducing fully recyclable shrink-sleeve labels on PET bottles. The development enhances bottle recyclability while maintaining product protection, reflecting the growing demand for convenient, single-serve dairy beverages packaged in lightweight PET bottles.
The bags and pouches segment is expected to grow the fastest over the forecast period from 2026 to 2033, attributed to the rising demand for flexible packaging solutions that offer convenience and cost-effectiveness. Bags and pouches are particularly popular for products such as cheese, butter, and powdered milk, where flexibility and space efficiency are crucial. These packaging types are lightweight, which reduces transportation costs and environmental impact.
Moreover, advancements in packaging technology have led to the development of high-barrier pouches that provide excellent protection against moisture, oxygen, and light, thereby extending the shelf life of dairy products. The increasing consumer preference for eco-friendly packaging options is also driving the adoption of bags and pouches, as they often use less material and are easier to recycle compared to rigid packaging.
Regional Insights
North America accounted for a significant share of the global dairy packaging market revenue in 2025, driven by the high consumption rates of dairy products such as milk, cheese, and yogurt in the region. The presence of advanced packaging technologies and stringent regulations regarding food safety and quality further bolsters the market. For instance, the U.S. Food and Drug Administration (FDA) enforces strict guidelines that ensure the safety and integrity of dairy packaging. The region’s well-established dairy industry and continuous innovation in packaging materials and designs contribute to its strong market position.
U.S. Dairy Packaging Market Trends
The U.S. held a substantial revenue share of the North American dairy packaging market in 2025, attributed to the large-scale production and consumption of dairy products in the country. The U.S. market is characterized by a high demand for innovative packaging solutions that enhance product shelf life and safety. For instance, the adoption of aseptic packaging, which allows dairy products to be stored without refrigeration, is gaining traction. Additionally, the growing trend of single-serve and on-the-go dairy products is driving the need for convenient packaging formats.
Asia Pacific Dairy Packaging Market
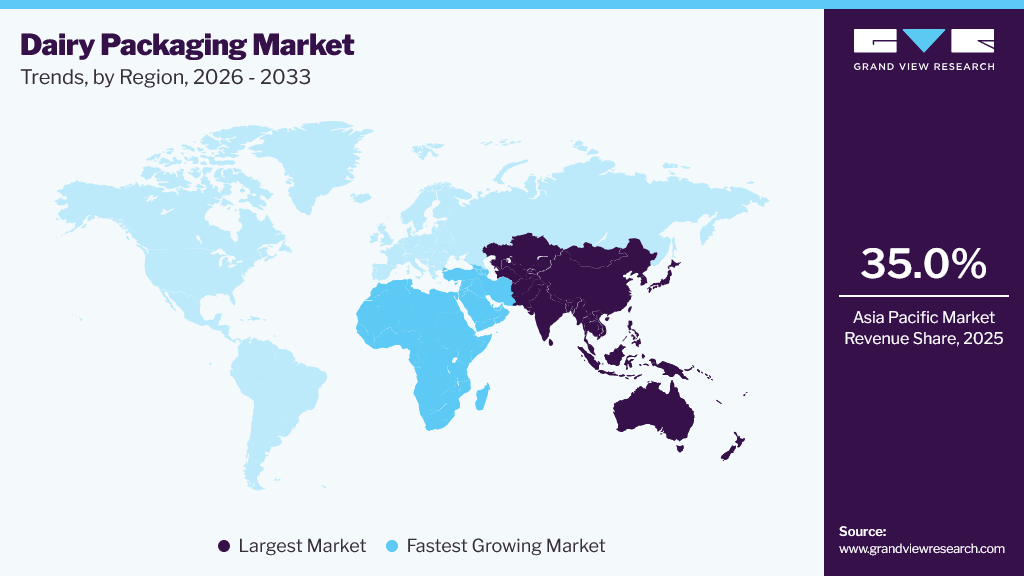
The Asia Pacific dairy packaging market held the largest revenue share of 35.0% in the global market in 2025, primarily due to the rapidly growing population, rising disposable incomes, and increasing consumption of dairy products in countries such as China and India. The region is witnessing a surge in demand for both traditional dairy products and plant-based alternatives, driving the need for diverse packaging solutions. The expansion of the retail sector and the growing popularity of e-commerce are contributing to market growth, as they require efficient and attractive packaging to appeal to consumers.
 To learn more about this report, Download Free Sample Report
China accounted for a significant market share of the Asia Pacific dairy packaging market, driven by its large population and the increasing consumption of dairy products, particularly among the urban middle class. The demand for high-quality and safe packaging solutions is rising, fueled by growing health awareness and stringent food safety regulations. For instance, the Chinese government has implemented strict standards for food packaging to ensure consumer safety. The National Mandatory Standard for Requirements of Restricting Excessive Packaging for Fresh Edible Agricultural Products (GB43284-2023) by the PRC State Administration for Market Regulation (SAMR), which aims to curb excessive packaging, is likely to drive dairy producers to adopt more sustainable and efficient packaging solutions. By limiting the interspace ratio and the number of packaging layers, the regulation encourages the use of minimal yet effective packaging materials.
Europe Dairy Packaging Market Trends
The European dairy packaging market is expected to grow at a CAGR of approximately 2.5% from 2026 to 2033, driven by the increasing interest in sustainable packaging solutions and stringent regulations on food safety and packaging sustainability. For instance, the European Union’s Circular Economy Action Plan aims to make all packaging recyclable or reusable by 2030. Countries such as Germany, France, and the UK are seeing a surge in demand for eco-friendly packaging materials such as biodegradable plastics and recyclable paperboard.
The dairy packaging market in the UK is projected to experience steady growth over the forecast period, supported by the increasing demand for sustainable and convenient packaging solutions. The UK market is also characterized by a strong focus on innovation, with manufacturers investing in new technologies and materials to enhance packaging efficiency and reduce environmental impact. For instance, the adoption of smart packaging solutions, which include features such as freshness indicators and QR codes for product information, is on the rise.
Middle East and Africa Dairy Packaging Market Trends
The Middle East and Africa dairy packaging market is expected to grow the fastest over the forecast period, driven by the increasing consumption of dairy products in the region, supported by rising disposable incomes and changing dietary preferences. The adoption of flexible packaging solutions such as pouches and bags is increasing due to their cost-effectiveness and convenience. In addition, the expansion of the retail sector and the growing popularity of e-commerce are contributing to market growth, as they require efficient and attractive packaging to appeal to consumers.
Key Dairy Packaging Market Company Insights
The global dairy packaging market is driven by several key companies, including Amcor plc, Sonoco Products Company, Greiner Packaging, Constantia Flexibles, and Tetra Pak.
- Amcor plc offers various innovative and sustainable packaging options tailored to dairy products such as cheese, yogurt, and butter. Amcor’s solutions include recycle-ready materials such as AmPrima and DairySeal, designed to meet the growing consumer demand for environmentally friendly packaging.
- Tetra Pak is renowned for its comprehensive dairy processing and packaging solutions. With over 70 years of experience, Tetra Pak provides end-to-end solutions that cover everything from milk and yogurt to cream and cheese. Their aseptic packaging technology, which includes the well-known Tetra Pak cartons, allows dairy products to be stored without refrigeration until opened.
Key Dairy Packaging Companies
The following key companies have been profiled for this study on the dairy packaging market.
-
Amcor plc
-
Greiner Packaging
-
Sonoco Products Company
-
Mondi
-
Berry Global Inc.
-
Constantia Flexibles
-
DS Smith
-
Tetra Pak
-
Winpak LTD
-
ProAmpac
-
Smurfit Kappa
-
Stanpac Inc.
-
Alfipa
-
Sealed Air
-
Graham Packaging
Recent Developments
-
In August 2024, Greatview Aseptic Packaging Company Limited firmly rejected an unsolicited takeover bid from Jingfeng Holding Limited. Jingfeng had made a pre-conditional voluntary general offer for Greatview, which the company deemed hostile. Greatview clarified that the proposed combination with Shandong NewJF is fundamentally incompatible and would not be beneficial to its shareholders.
-
In April 2024, Amul Dairy commissioned two advanced aseptic carton filling lines from SIG at its Kheda Satellite Dairy plant in Gujarat. The new filling systems increased packaging capacity and enabled the company to fill multiple pack sizes on the same production line, supporting growing demand for packaged dairy products and enhancing operational flexibility in the dairy packaging sector.
Dairy Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 32.7 billion
Estimated market size in 2026
USD 33.5 billion
Projected market size by 2033
USD 40.4 billion
Growth rate
CAGR of 2.7% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, packaging type, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand, South Korea; Brazil; Argentina, South Africa, UAE
Key companies profiled
Amcor plc; Greiner Packaging; Sonoco Products Company; Mondi; Berry Global Inc.; Constantia Flexibles; DS Smith; Tetra Pak; Winpak LTD; ProAmpac; Smurfit Kappa; Stanpac Inc.; Alfipa; Sealed Air; Graham Packaging
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Dairy Packaging Market Report Segmentation
This report forecasts revenue growth of the dairy packaging market and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global dairy packaging market report based on material, packaging type, and region:
-
Material Outlook (Revenue, USD Billion, 2021 - 2033)
-
Plastic
-
Glass
-
Metal
-
Paper & Paperboard
-
Others
-
-
Packaging Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cans
-
Bottle
-
Bags & Pouches
-
Films & Wraps
-
Boxes & Cartons
-
Jars & Containers
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The global dairy packaging market size was valued at USD 32.7 billion in 2025 and is estimated at USD 33.5 billion for 2026
The global dairy packaging market is expected to grow at a CAGR of 2.7% from 2026 to 2033, reaching USD 40.4billion.
Asia Pacific dominated with a 35.0% revenue share in 2025.
The plastic segment accounted for the largest revenue share of approximately 45.0% in 2025
Key players in the market include Amcor plc, Greiner Packaging, Sonoco Products Company, Mondi, Berry Global Inc., Constantia Flexibles, DS Smith, Tetra Pak, Winpak LTD, ProAmpac, Smurfit Kappa, Stanpac Inc., Alfipa, Sealed Air, Graham Packaging, and others
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


