
- Home
- »
- Medical Devices
- »
-
Dental Equipment Market Size And Share Report, 2026-2033GVR Report cover

Dental Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Dental Radiology Equipment, Laboratory Machines, Dental Lasers, Systems & Parts, Hygiene Maintenance Devices, Other Equipment), By Region, And Segment Forecasts
Market Size, 2025
$12.5BMarket Estimate, 2026
$13.2BMarket Forecast, 2033
$20.9BCAGR, 2026–2033
6.8%Dental Equipment Market Summary
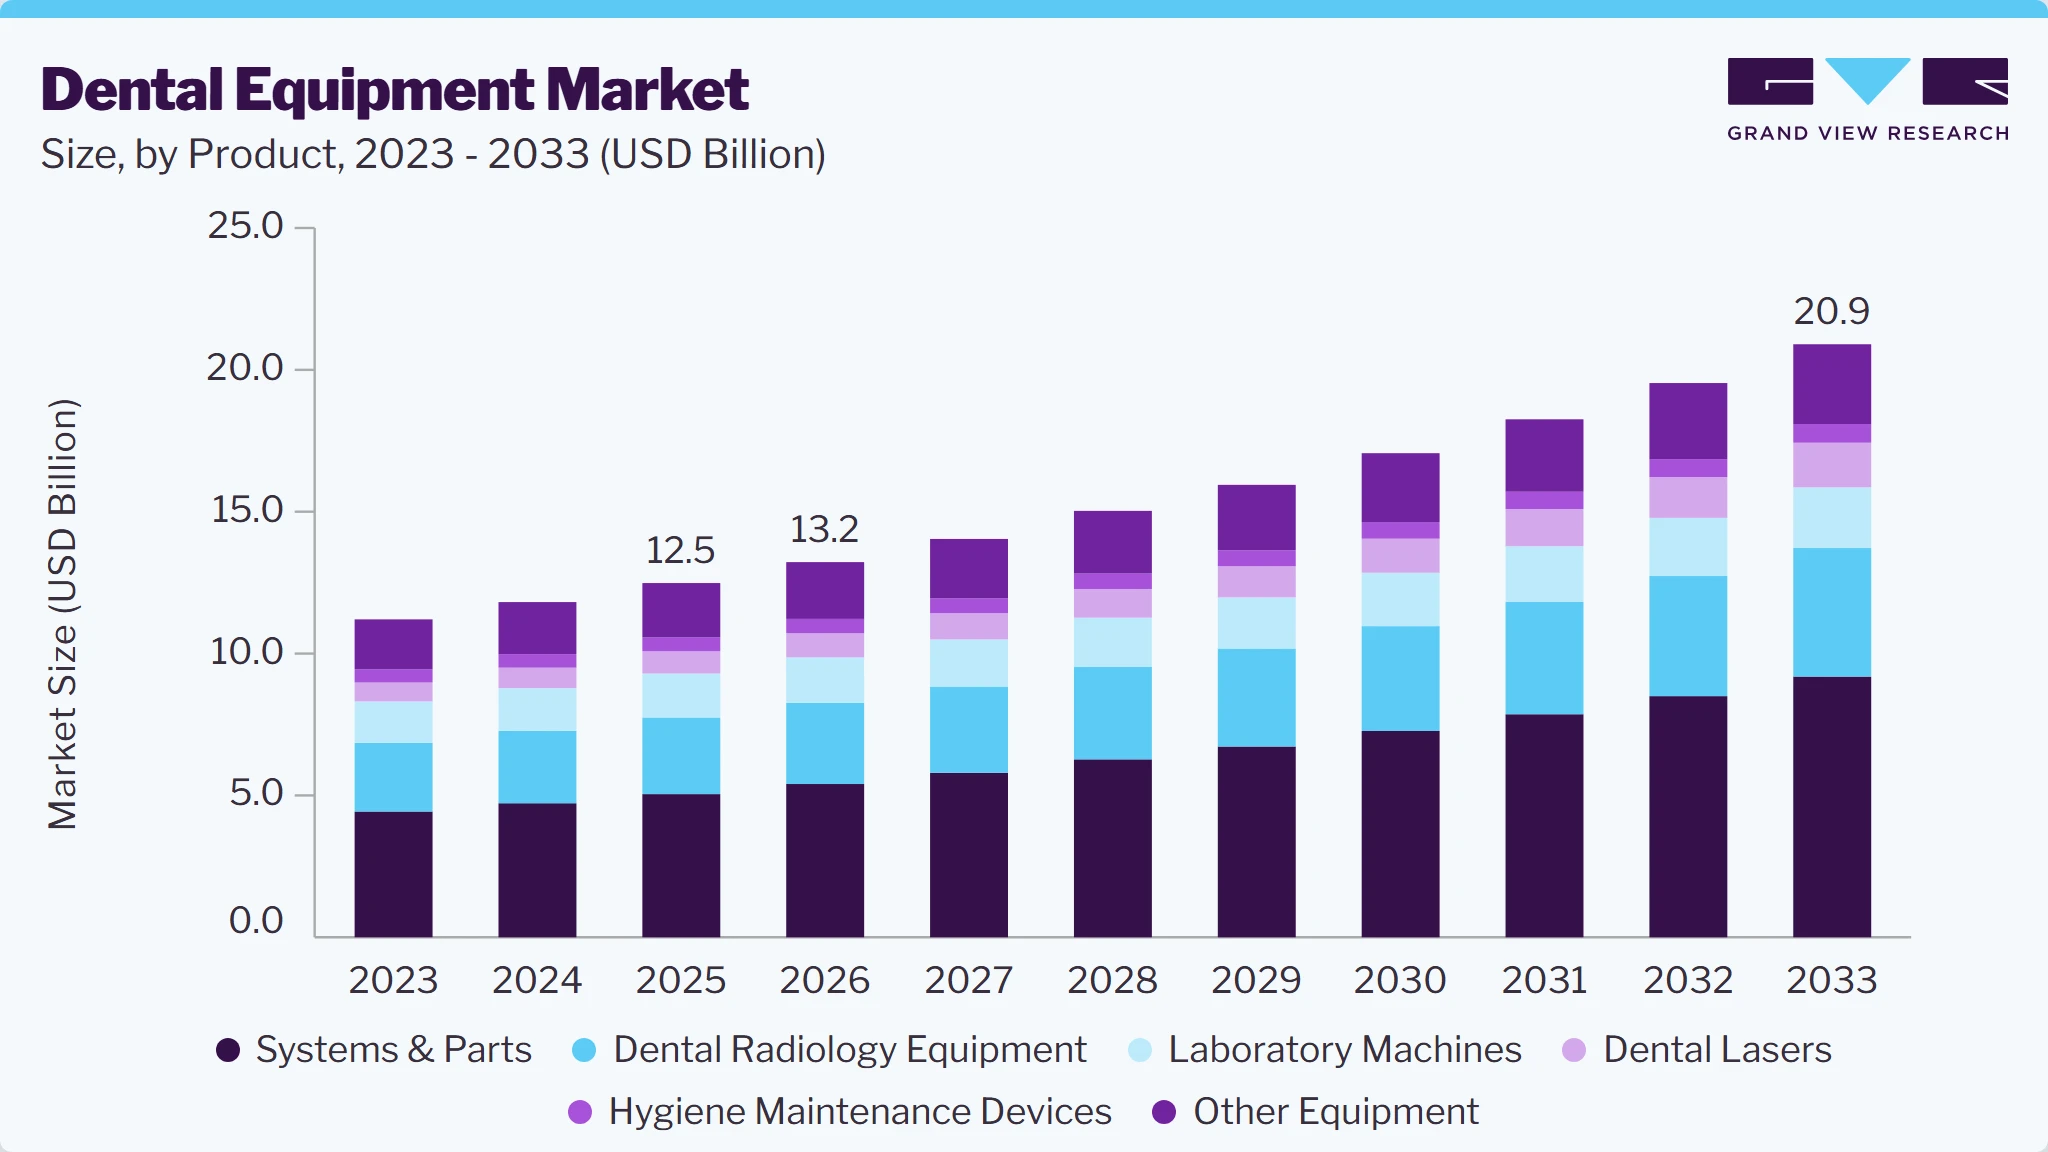
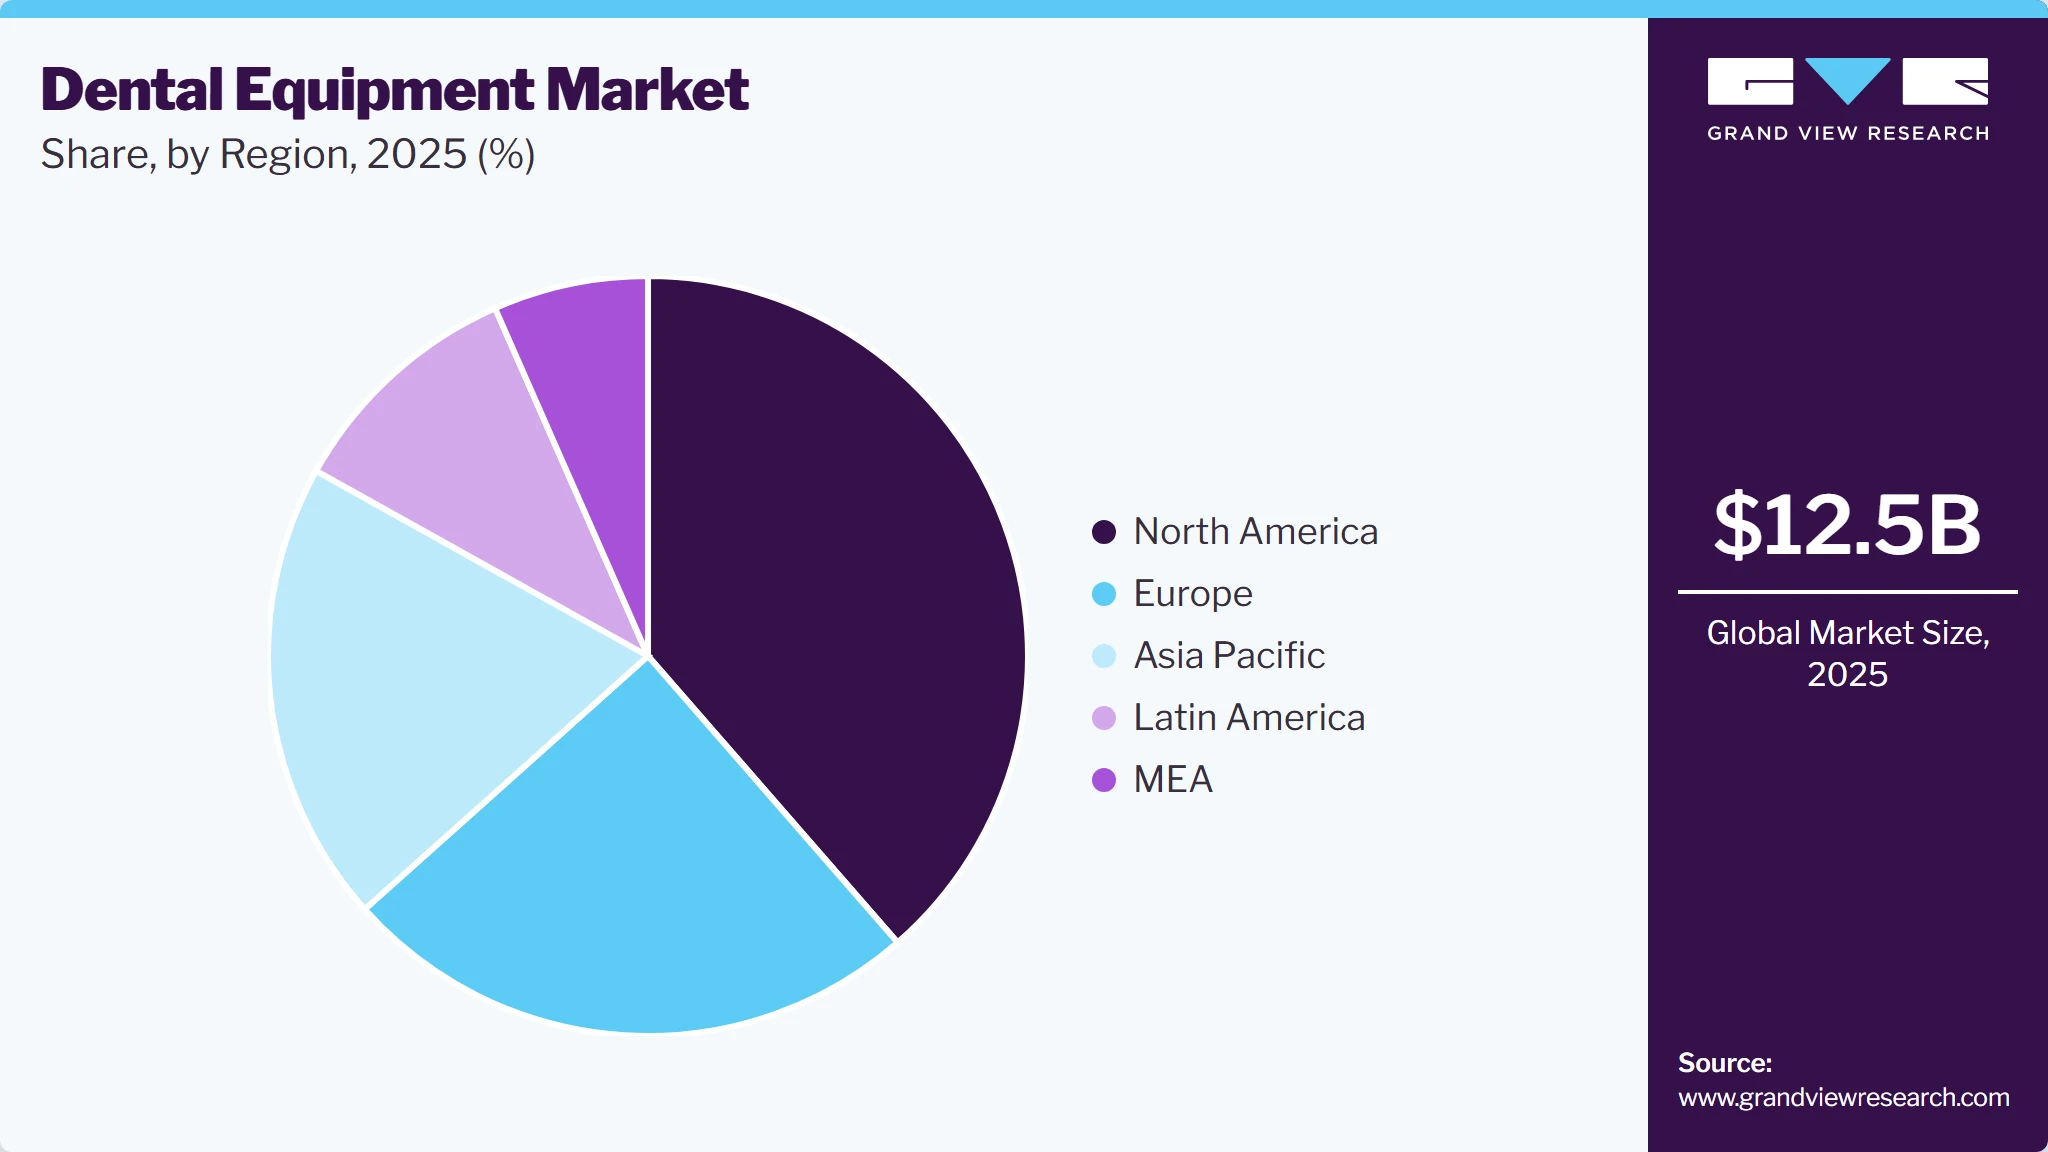
The global dental equipment market size was valued at USD 12.5 billion in 2025 and is projected to grow from USD 13.2 billion in 2026 to USD 20.9 billion by 2033, at a CAGR of 6.8% from 2026 to 2033. North America dominated the market, accounting for the largest share of 38.6% in 2025. Dental equipment includes a set of tools used to examine, manipulate, treat, and restore oral structures and function.
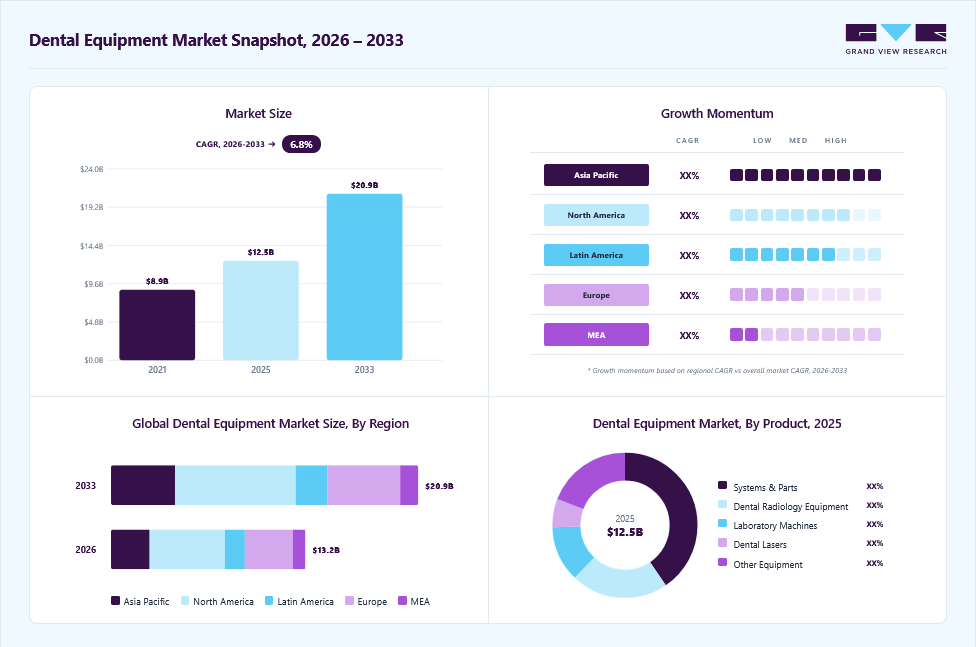 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Systems & parts segment led the market with the largest revenue share of 40.4% in 2025.
- By product: The dental lasers segment is anticipated to register the fastest CAGR of 9.2% over the forecast period.
Regional Highlights
- Largest regional market: North America (38.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market Size in 2025: USD 12.5 Billion
- Estimated Market Size in 2026: USD 13.2 Billion
- Projected Market Size by 2033: USD 20.9 billion
- CAGR (2026-2033): 6.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Factors such as the growing geriatric population suffering from oral diseases, evolving medical tourism for dental treatment, and the launch of multiple government initiatives for public oral health care are expected to drive industry expansion. Moreover, the introduction of advanced, efficient dental products by major companies is fueling market growth.Companies like DENTSPLY Sirona, Planmeca Oy, and Danaher Corp. are introducing advanced computer-aided imaging technology that will allow professionals to prepare a precise course of dental treatment. However, the COVID-19 pandemic has hugely affected the overall dental and oral hygiene industry. Routine dental care was largely unavailable during the pandemic, as many dental practices were forced to close because their services were deemed elective. The continuous operation and long-term survival of many dental practices are also threatened by the economic and social challenges arising from care restrictions, practice closures, and shortages of personal protective equipment (PPE), as well as the need to invest in new PPE and technology.
 To learn more about this report, Download Free Sample Report
While many practices and clinics worldwide reopened in 2021, the market recovered soon, as there were numerous concerns about the availability of dental services and ensuring the safety of dentists and dental teams. A review article published by The Journal of Contemporary Dental Practice stated that COVID-19 is expected to be a watershed moment in the field of dentistry. While the industry expected to see positive changes in the safe delivery of dental care, an increase in the cost of availing care is imminent. According to the FDI World Dental Federation, oral diseases affect 3.9 billion people worldwide, with untreated tooth decay (dental caries) affecting more than half of the global population (44%), making it the most prevalent of the 291 conditions included in the Global Burden of Disease Study.
The most frequently performed dental procedures during these visits include dental fillings, bonding, root canals, dental crowns, dental bridges, periodontal treatments, and oral & maxillofacial procedures. These showcase the existing potential dental procedures globally. Dental disorders such as periodontal disease, oral cancers, and environmental injuries resulting in oro-dental trauma are expected to further assist the overall market growth.
Furthermore, high consumption of tobacco & alcohol, unhealthy diet, and high intake of sugar are the leading causes of dental caries, which is the most common type of chronic disease prevalent globally. The rising geriatric population and their demand for dental services have also surged. According to the World Population Prospects, by 2050, 1 in 6 people in the world will be over the age of 65, up from 1 in 11 in 2019, providing a population pool of about 1.5 billion people above the age of 65 by 2050.
Market Dynamics
The dental equipment market is driven by the increasing prevalence of oral diseases and the growing awareness of oral health among people of all ages. Healthcare organizations and dental professionals are actively promoting preventive dental care and regular dental check-ups, encouraging greater adoption of advanced dental equipment. Improved access to dental care services, the expansion of dental clinics, and the growing availability of specialized dental treatments further support market growth. In addition, government initiatives and public health programs focused on improving oral healthcare, along with increasing investments in modern dental infrastructure, are driving demand for advanced dental equipment.
The rising prevalence of oral health disorders is a major driver of growth for the dental equipment market. Conditions such as dental caries (tooth decay), periodontal (gum) disease, tooth loss, oral infections, and oral cancer are becoming more common due to factors including poor oral hygiene, high sugar consumption, tobacco use, alcohol consumption, and aging populations. As the number of patients requiring diagnosis and treatment increases, dental clinics and hospitals must invest in advanced equipment, including dental chairs, imaging systems, intraoral scanners, sterilization units, dental lasers, and restorative treatment devices.
The high cost of dental imaging equipment remains a significant restraint for the dental equipment market. Advanced diagnostic systems such as cone beam computed tomography (CBCT) scanners, panoramic X-ray systems, cephalometric imaging units, and digital radiography systems require substantial upfront investment. In addition to purchase costs, dental practices must bear expenses for installation, software licensing, maintenance, calibration, radiation safety compliance, and staff training.
Dental practices are adopting digital technologies such as intraoral scanners, CAD/CAM systems, 3D printers, digital radiography, and practice management software to improve diagnostic accuracy, treatment efficiency, and patient experience. These technologies enable faster workflows, reduce manual errors, and support same-day restorations, making dental procedures more efficient and predictable.
Analyst Perspective
The dental equipment market is driven by the increasing demand for advanced dental care, growing awareness of oral health, and the rising adoption of digital technologies across dental practices. Market growth is supported by the increasing prevalence of dental disorders, expanding cosmetic dentistry procedures, and greater investments in modernizing dental clinics and hospitals. The most successful companies will be those that offer a comprehensive portfolio of diagnostic, treatment, imaging, and digital dentistry solutions while focusing on precision, workflow efficiency, patient comfort, and continuous technology integration. As dental professionals adopt CAD/CAM systems, intraoral scanners, AI-assisted diagnostics, and cloud-connected practice management platforms, market leadership will depend on continuous product innovation, strong clinical support, strategic partnerships, and the ability to deliver integrated digital ecosystems through robust global distribution networks.
Product Insights
Based on product, the systems & parts segment led the market with the largest revenue share of 40.4% in 2025. The global industry is segmented into dental radiology equipment, dental lasers, dental systems & parts, laboratory machines, and hygiene maintenance devices. The dental systems & parts segment is sub-segmented into instrument delivery systems, vacuums & compressors, cone beam CT systems, cast machines, furnaces and ovens, electrosurgical equipment, other systems and parts, and CAD/CAM. These devices are essential tools for performing any dental procedure.
The performance and functionality of these systems and parts are key factors for a successful dental treatment. The major driver for this segment is the technological advancement and rigorous R&D activities undertaken by key players to provide practitioner-friendly and highly efficient equipment to provide smooth procedures.
The dental lasers segment is anticipated to register the fastest CAGR of 9.2% over the forecast period due to the fact that it is being rapidly used in surgical and teeth whitening procedures. Dental lasers are also used to reshape gum tissue and remove inflamed tissue. The other benefit of using dental lasers is controlled blood loss during the procedures, thus lessening the need for sutures. The dental laser segment is further segmented into diode, carbon dioxide, and yttrium aluminum garnet lasers. Favorable technological adoption, satisfactory reimbursement scenario, increasing geriatric population, and growing awareness about oral care are the key factors assisting the market growth.
Regional Insights
North America dominated the global dental industry in 2025 with a market share of more than 38.6%, and it is anticipated to register a significant CAGR of 7.0% over the forecast period. The dental equipment market in the U.S. held the largest share in the North America region in 2025. This is attributed to the growing geriatric population, a strong medical infrastructure, well-established reimbursement policies, the presence of key players, and advances in preventive and restorative dental treatments. Moreover, according to the American Dental Association, 85% of individuals in the United States value dental health and consider it an essential aspect of overall care. The combination of all these factors will make North America the most promising regional market over the forecast period.
 To learn more about this report, Download Free Sample Report
APAC Dental Equipment Market Trends
The APAC region is anticipated to witness the fastest CAGR of 7.5% over the forecast period. China, Japan, and India are emerging economies with well-developed healthcare infrastructure & facilities, and they are now more focused on leading the basis of R&D activities. They have suitable infrastructure and funding for the same. A total of 43.6% of the spending is expected to emanate from Asia, with countries like China, Japan, and India being the topmost to spend on R&D activities.
Attributes like favorable government policies, a rising geriatric population, the presence of key players, and a rise in the demand for dental procedures are paving the way for the market in the Asia Pacific region. Moreover, medical tourism in the region is rapidly increasing due to shorter patient waiting times, low-cost treatment, availability of a large pool of skilled dental practitioners & high-end technology, and the presence of tourist destinations & quality accommodations. These aforementioned factors will assist in the market growth in the region.
Key Companies & Market Share Insights
The global industry is highly competitive. One of the key factors driving competitiveness among industry players is the rapid adoption of advanced technologies, such as computer-aided scanners, for precise imaging and diagnosis of dental disorders. Moreover, a significant number of companies are pursuing geographic expansion, strategic collaborations, and partnerships through mergers & acquisitions in emerging and economically favorable regions.
In June 2023, A-dec launched its digitally connected dental chair and transport system, marking a significant leap in dental technology. The A-dec 300 Pro and A-dec 500 Pro delivery systems are now accessible in the North American markets.
In March 2023, Planmeca revolutionized the dental industry with its fully integrated digital workflow solutions, spanning dental units, imaging devices, CAD/CAM, and software. At IDS 2023, the company is unveiling new products across these categories, thereby enhancing its portfolio of advanced digital dental equipment. The highlight is the Planmeca Pro50 dental care unit, a technological masterpiece with adaptability, sophisticated features, and exceptional ergonomics.
Key Dental Equipment Companies
The following key companies have been profiled for this study on the dental equipment market.
-
A-Dec Inc.
-
Planmeca Oy
-
Dentsply Sirona
-
Patterson Companies Inc.
-
Straumann
-
GC Corp.
-
Carestream Health Inc.
-
BIOLASE, Inc. (MegaGen Implant)
-
Danaher Corp.
-
3M
Recent Development
-
In June 2026, Planmeca expanded its dental unit portfolio with the Pro40 and Pro50 S models, featuring ergonomic designs, digital workflow capabilities, and enhanced infection-control features. The development strengthened Planmeca’s portfolio of integrated dental equipment and digital clinical solutions.
-
In May 2026, Dentsply Sirona launched Smart View-Detect, an FDA-cleared, AI-enabled diagnostic aid designed to identify teeth with periapical radiolucencies in cone-beam computed tomography (CBCT) scans. The launch expanded the company’s AI-assisted dental imaging and diagnostic capabilities, supporting the integration of advanced software into clinical workflows.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (3M, Dentsply Sirona Inc., Envista, Planmeca Oy, A-dec Inc., Institut Straumann AG)
- Invest heavily in R&D to develop advanced dental equipment, including digital imaging systems, CAD/CAM solutions, intraoral scanners, treatment units, and integrated workflow platforms.
- Expand market presence through acquisitions, strategic partnerships, training programs, and collaborations with dental clinics, hospitals, universities, and DSOs.
- Strong global brand recognition and extensive installed customer base across developed and emerging markets.
- Broad product portfolios covering diagnostics, restorative dentistry, implantology, orthodontics, and digital dentistry solutions.
- High R&D, manufacturing, and regulatory compliance costs.
- Dependence on replacement cycles and slower growth in mature markets, where equipment penetration is already high.
Emerging Players (AMD Lasers, Zolar Technology Mfg. Co. Inc., GIGAAMEDICAL)
- Focus on cost-effective, specialized dental equipment offerings for small- and mid-sized clinics.
- Strengthen regional distribution networks and expand market reach through local partnerships, competitive pricing, and customer support services.
- Competitive pricing and flexibility in addressing niche clinical requirements.
- Faster product development cycles and the ability to respond quickly to evolving customer needs and regional market demands.
- Limited global brand recognition and smaller distribution networks compared to multinational competitors.
- Lower marketing resources and limited participation in large-scale institutional procurement and training programs.
Dental Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 12.5 billion
Estimated Market size in 2026
USD 13.2 billion
Projected Market size by 2033
USD 20.9 billion
Growth rate
CAGR of 6.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark, Sweden, Norway, China; Japan; India; Australia; Thailand; South Korea, Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
3M, GC Corporation, Align Technology, Inc., Dentsply Sirona Inc., BIOLASE, Inc. (MegaGen Implant), LAZON, Fotona (Vitruvian Partners LLP), THE YOSHIDA DENTAL MFG. CO., LTD., Envista, Zolar Technology Mfg. Co. Inc., Institut Straumann AG, Planmeca Oy, A-dec Inc, GIGAAMEDICAL, CAO Group, Inc. (AMD Lasers, Inc.), Intense Medical & Dental System Pvt Limited, Wuhan Pioon Technology Co., Ltd., and Convergent Dental, Inc.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dental Equipment Market Report Segmentation
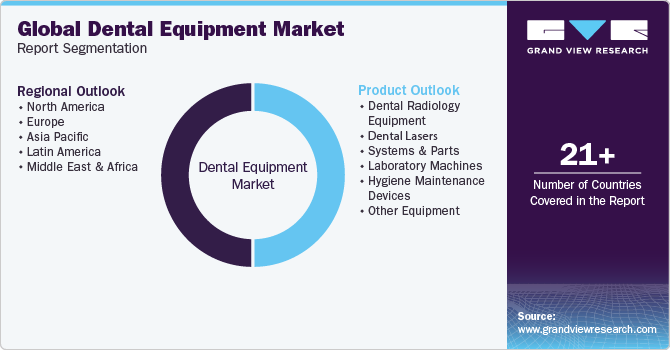
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global dental equipment market report based on product and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Dental Radiology Equipment
-
Intra-Oral
-
Digital X-ray Units
-
Digital Sensors
-
-
Extra-Oral
-
Digital Units
-
Analog Units
-
-
Dental Lasers
-
Diode Lasers
-
Quantum Well Lasers
-
Distributed Feedback Lasers
-
Vertical Cavity Surface-emitting Lasers
-
Heterostructure Lasers
-
Quantum Cascade Lasers
-
Separate Confinement Heterostructure Lasers
-
Vertical External Cavity Surface-emitting Lasers
-
-
Carbon Dioxide Lasers
-
Yttrium Aluminum Garnet Lasers
-
-
Systems & Parts
-
Instrument Delivery Systems
-
Vacuums & Compressors
-
Cone Beam CT Systems
-
Cast Machine
-
Furnace and Ovens
-
Electrosurgical Equipment
-
Other Systems and Parts
-
CAD/CAM
-
-
Laboratory Machines
-
Ceramic Furnaces
-
Hydraulic Press
-
Electronic Waxer
-
Suction Unit
-
Micro Motor
-
-
Hygiene Maintenance Devices
-
Sterilizers
-
Air Purification & Filters
-
Hypodermic Needle Incinerator
-
-
Other Equipment
-
Chairs
-
Hand Piece
-
Light Cure
-
Scaling Unit
-
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
Spain
-
Italy
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
India
-
Japan
-
China
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The dental equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dental equipment segment quantified using the revenue-capture definitions in the table below:
Segment Definition
Segment - Product
Revenue capture definition
Dental Radiology Equipment
Revenue includes sales of dental imaging systems used for diagnosis in dental clinics, hospitals, and diagnostic centers. This covers intraoral imaging equipment (intraoral X-ray systems, digital sensors, phosphor plate scanners) and extraoral imaging equipment (panoramic X-ray systems, cephalometric systems, and related imaging units). Revenue from installation, software bundled with equipment, and essential accessories supplied with the system are included.
Dental Lasers
Revenue includes sales of dental laser systems used for soft-tissue, hard-tissue, periodontal, endodontic, and cosmetic dental procedures. This includes diode, carbon dioxide (CO₂), and yttrium aluminum garnet (YAG) lasers, along with standard accessories supplied with the laser unit.
Systems & Parts
Revenue includes sales of core dental operatory systems and supporting equipment required for clinical workflows. This includes instrument delivery systems, vacuum and compressor systems, cone beam CT (CBCT) systems, and casting machines used in restorative and prosthetic dentistry. Revenue from integrated hardware and essential system components is included.
Laboratory Machines
Revenue includes sales of equipment used by dental laboratories the fabricate and process dental restorations and prosthetics. This includes ceramic furnaces, hydraulic presses, electronic waxers, and laboratory suction units, along with standard components delivered with the equipment.
Hygiene Maintenance Devices
Revenue includes sales of infection prevention and sterilization equipment used in dental practices. This includes sterilizers (autoclaves), air purification and filtration systems, and hypodermic needle incinerators designed to support clinical hygiene, sterilization, and biomedical waste management.
Other Equipment
Revenue includes sales of general-purpose dental equipment used during routine clinical procedures. This includes dental chairs, dental handpieces, light curing units, and ultrasonic scaling units, along with standard accessories and integrated components supplied with the equipment.
Estimation Model
Bottom-Up Estimation
Top-Down Approach
Supply-Side Analysis
Revenue is estimated by aggregating sales of dental equipment across hospitals, dental clinics, ASCs, academic institutions, and dental laboratories at the country, regional, and global levels. The analysis considers the number of dental facilities, patient treatment volumes, equipment replacement cycles, procedure volumes, and adoption rates of diagnostic, treatment, and digital dentistry systems to estimate total market revenue.
The overall healthcare and dental care market is identified first, and the share attributable to dental equipment is estimated using secondary research and expert validation. Factors such as oral disease prevalence, an aging population, demand for cosmetic dentistry, healthcare expenditure, dental clinic expansion, and adoption of digital dentistry technologies are analyzed to determine the category's contribution.
This approach evaluates the total production and sales of dental equipment by manufacturers, including diagnostic imaging systems, dental chairs, CAD/CAM systems, intraoral scanners, dental lasers, sterilization equipment, and treatment devices. Key parameters include manufacturing capacity, shipment volumes, product pricing, distribution networks, regional sales performance, and product portfolios.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Dental Equipment Technology & Application Assessment
Conducted a focused analysis of key dental equipment categories, including diagnostic imaging systems, dental chairs, CAD/CAM systems, intraoral scanners, sterilization equipment, dental lasers, and endodontic and implantology devices across general and specialty dental practices.
Helps stakeholders identify high-growth equipment segments, evaluate technology adoption trends, understand evolving clinical requirements, and assess commercialization opportunities across dental clinics, hospitals, and dental service organizations (DSOs).
Digital Dentistry Integration & Market Opportunity Assessment
Assessed demand for digitally connected dental equipment, including CAD/CAM workflows, intraoral scanning, 3D printing integration, imaging interoperability, AI-assisted diagnostics, cloud-based practice management connectivity, and emerging opportunities across clinics, hospitals, and DSOs.
Supports investment and expansion strategies by identifying technology readiness, digital adoption patterns, unmet clinical needs, opportunities for operational efficiency, and long-term growth potential within the digital dentistry ecosystem.
Dental Infrastructure & Equipment Procurement Analysis
Evaluated dental infrastructure expansion, equipment replacement cycles, procurement trends, modernization initiatives, and adoption patterns across private clinics, group practices, hospitals, and academic institutions.
Enables stakeholders to identify demand hotspots, optimize market entry strategies, prioritize high-potential customer segments, and align product portfolios with evolving purchasing requirements.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The global dental equipment market size was valued at USD 12.5 billion in 2025 and is estimated at USD 13.2 billion for 2026.
The global dental equipment market is expected to grow at a CAGR of 6.8% from 2026 to 2033, reaching USD 20.9 billion.
Based on product, the systems and parts segment held the largest share of 40.4% in 2025, while the dental lasers are the fastest-growing segment over the forecast period.
Key factors include the increasing demand for dental treatments, rapid adoption of digital dentistry technologies, and continuous investments in dental healthcare infrastructure globally. Rising cases of dental caries, periodontal diseases, tooth loss, and cosmetic dental concerns are encouraging patients to seek preventive, restorative, and aesthetic dental procedures, thereby increasing the demand for advanced dental equipment.
North America dominated with a 38.6% revenue share in 2025.
Key players include 3M, GC Corporation, Align Technology, Inc., Dentsply Sirona Inc., BIOLASE, Inc. (MegaGen Implant), LAZON, Fotona (Vitruvian Partners LLP), THE YOSHIDA DENTAL MFG. CO., LTD., Envista, Zolar Technology Mfg. Co. Inc., Institut Straumann AG, Planmeca Oy, A-dec Inc, GIGAAMEDICAL, CAO Group, Inc. (AMD Lasers, Inc.), Intense Medical & Dental System Pvt Limited, Wuhan Pioon Technology Co., Ltd., and Convergent Dental, Inc.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


