
- Home
- »
- Next Generation Technologies
- »
-
DevOps Market Size, Share & Growth Report, 2026-2033GVR Report cover

DevOps Market (2026 - 2033)
Size, Share, & Trends Analysis Report By Deployment Type (Cloud, On-Premise), By Enterprise Size (Large Enterprise, SME), By End-use (IT & Telecom, Manufacturing), By Region, and Segment Forecasts
Market Size, 2025
$16.2BMarket Estimate, 2026
$18.5BMarket Forecast, 2033
$74.1BCAGR, 2026–2033
21.9%DevOps Market Summary
The global DevOps market size was valued at USD 16.2 billion in 2025 and is projected to grow from USD 18.5 billion in 2026 to USD 74.1 billion by 2033, at a CAGR of 21.9% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 40.0% in 2025. The global market is shifting from rule-based automation toward AI-augmented and increasingly autonomous software delivery.
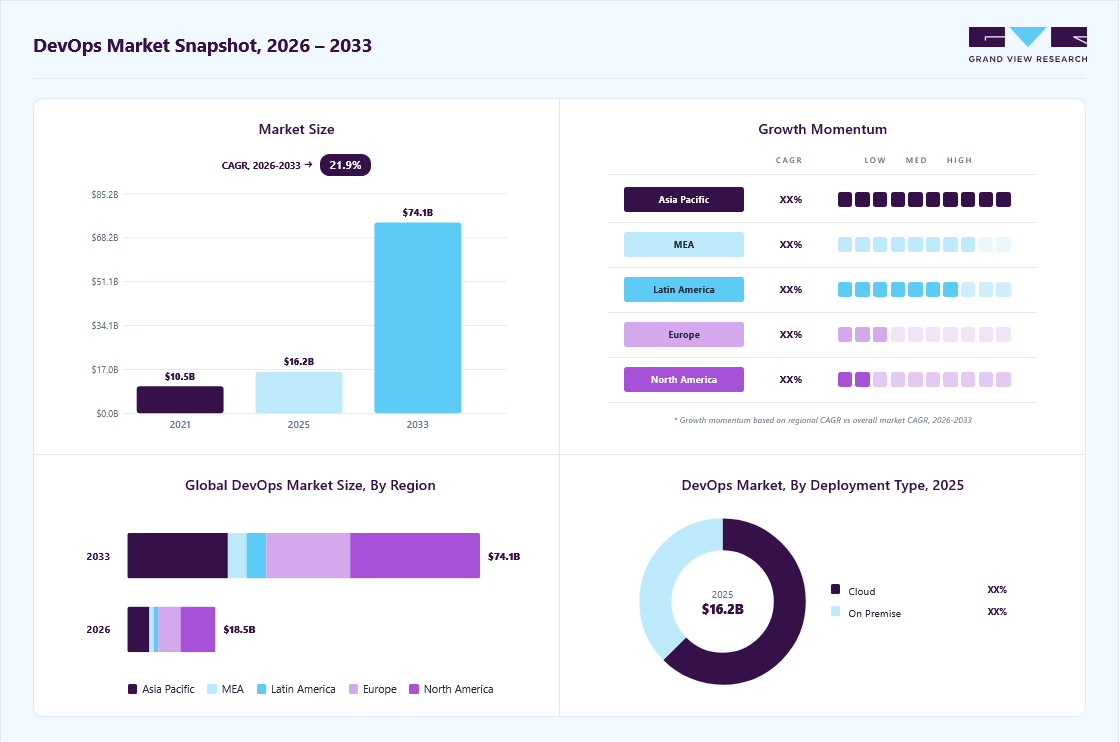 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By deployment type: Cloud segment held the largest market share of around 62.5% in 2025.
- By enterprise size: Large enterprise segment held the largest market revenue share in 2025.
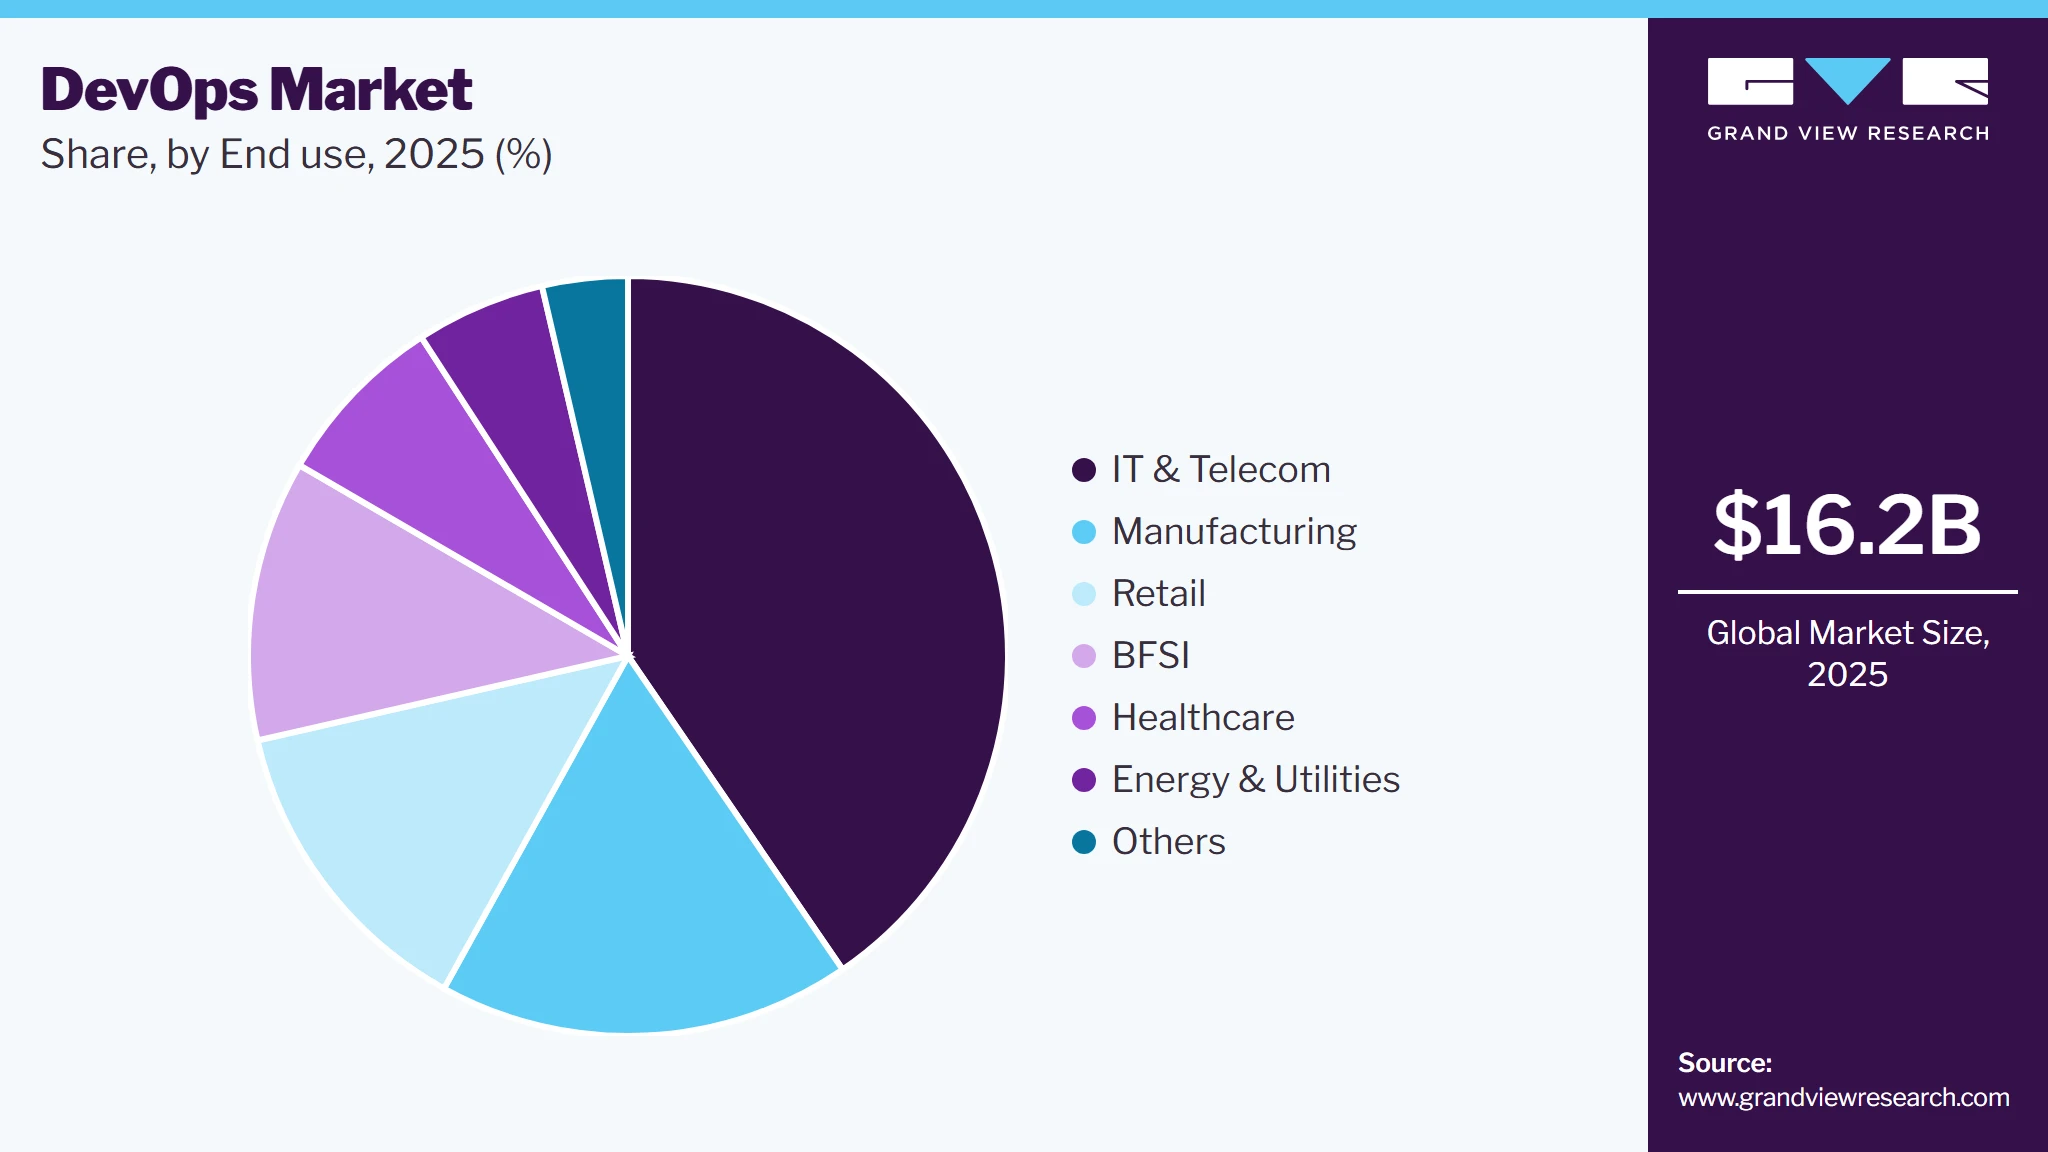
- By end use: IT & telecom segment led the market with the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- Leading country: The U.S. held the largest share in 2025
Market Size & Forecasts
- Market size in 2025: USD 16.2 Billion
- Estimated market size in 2026: USD 18.5 Billion
- Projected market size by 2033: USD 74.1 Billion
- CAGR (2026-2033): 21.9%
Prism AI by Grand View Research Free to tryAsk a question about the DevOps marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Agentic AI represents the most significant inflection point in this space, with AI agents now managing incident response, generating infrastructure-as-code, and optimizing cloud resource allocation rather than simply assisting developers through predefined scripts. This evolution is reinforced by the rapid expansion of AIOps and AI-augmented development practices, which embed generative AI capabilities directly within code creation, testing, and review workflows, fundamentally reshaping how engineering teams approach software delivery and operational decision-making.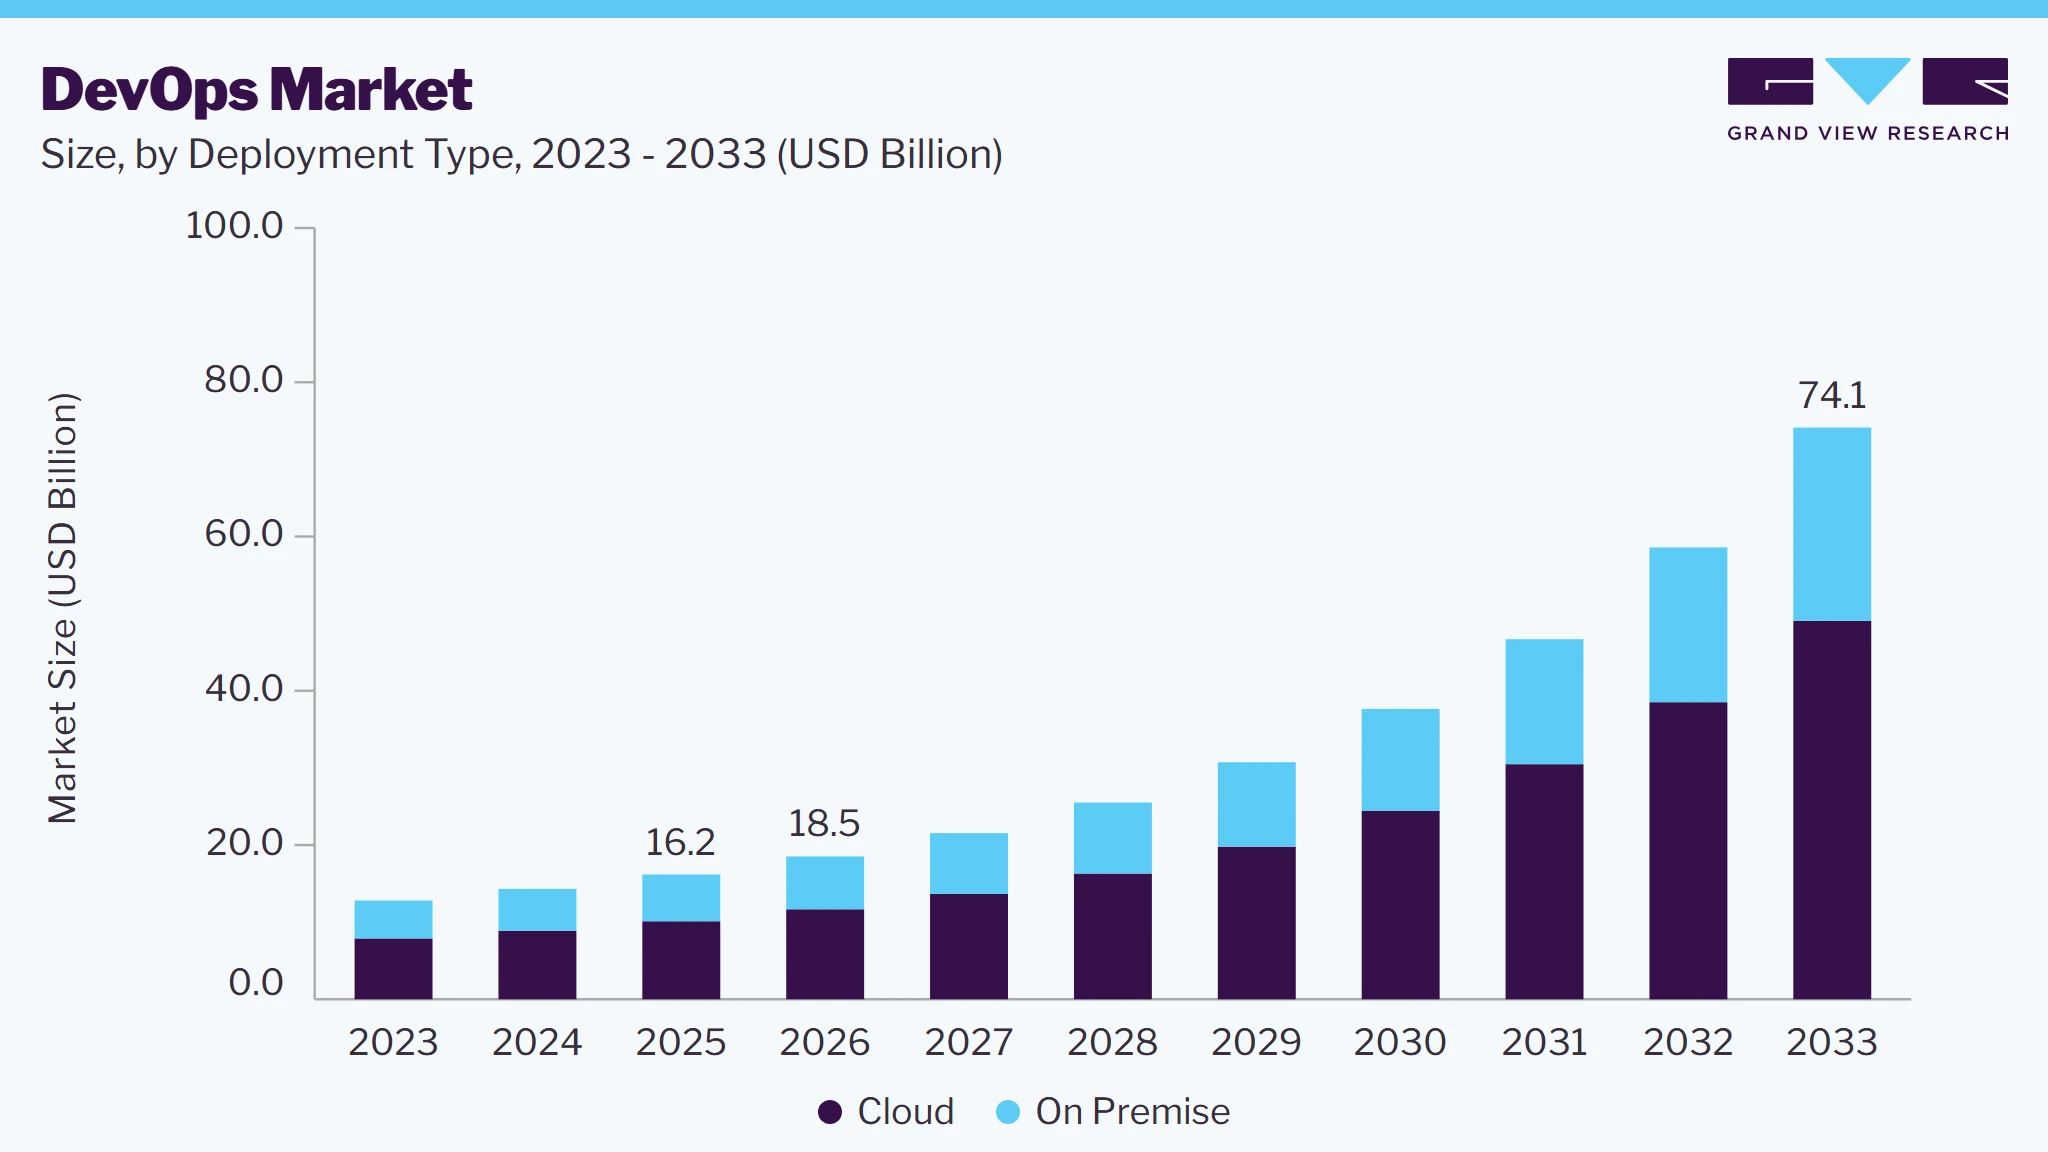 To learn more about this report, Download Free Sample Report
Platform engineering has concurrently emerged as a defining organizational and architectural paradigm within the market. Most large software engineering organizations are expected to establish dedicated platform engineering teams as internal providers of reusable services, components, and tools for application delivery, marking a sharp increase from prior adoption levels. This trend reflects a broader recognition that developer self-service platforms and Internal Developer Platforms (IDPs) reduce cognitive load on engineering teams, standardize delivery workflows, and allow organizations to abstract infrastructure complexity at scale. In parallel, the integration of DevSecOps, FinOps-aligned cloud cost management, and GitOps methodologies is extending DevOps principles beyond pure software delivery into governance, compliance, and cost-efficiency domains, as enterprises face mounting regulatory and operational resilience requirements.
Market Dynamics
The rising integration of artificial intelligence and machine learning across the software delivery lifecycle is a primary market growth driver. Organizations are increasingly embedding generative AI capabilities and, more recently, autonomous AI agents directly into CI/CD pipelines to manage tasks such as code generation, automated testing, incident response, and infrastructure provisioning. This shift from rule-based automation to agentic, intelligence-driven operations is compressing release cycles, reducing manual intervention, and enabling engineering teams to respond more rapidly to market demands, thereby reinforcing enterprise reliance on DevOps platforms and consulting partners to operationalize these capabilities at scale.
Despite strong growth momentum, the market faces a notable restraint in the form of integration complexity associated with legacy IT infrastructure and a persistent shortage of skilled DevOps and platform engineering talent. Many enterprises, particularly those with deeply entrenched on-premises systems or regulated operating environments, encounter significant challenges in migrating toward cloud-native, automation-first architectures without disrupting existing operations. Compounding this, the rapid pace of toolchain evolution—spanning GitOps, Kubernetes orchestration, and AI-driven observability—has outstripped the availability of professionals with the requisite cross-functional expertise, slowing full-scale implementation and increasing dependency on third-party consulting support.
A substantial opportunity for market participants lies in the accelerating adoption of platform engineering and Internal Developer Platforms (IDPs), as organizations seek to standardize delivery workflows and reduce cognitive load on development teams. With a large share of enterprise software organizations expected to establish dedicated platform engineering functions in the near term, vendors offering self-service infrastructure, reusable tooling, and unified developer experiences are well positioned to capture incremental demand. In addition, the convergence of DevOps with adjacent disciplines such as DataOps, MLOps, and FinOps presents a parallel growth avenue, enabling providers to extend their value proposition into cost governance, AI model deployment, and cross-functional data pipeline management.
Market Concentration & Characteristics
The global DevOps industry is moderately fragmented, comprising large, diversified technology and cloud vendors alongside specialized tool providers and consulting firms. Leading players such as Microsoft, AWS, IBM, and Broadcom compete across CI/CD, infrastructure automation, monitoring, and security segments, alongside a long tail of niche vendors and consulting firms serving specific industries. The landscape includes vertically integrated hyperscale cloud providers offering end-to-end DevOps toolchains within broader platform ecosystems, as well as specialized players competing on depth of functionality, open-source flexibility, and integration breadth. Growing partnerships among cloud providers, systems integrators, and independent software vendors are further shaping the market, with strategies increasingly centered on toolchain interoperability, API-driven integrations, and embedded AI capabilities.
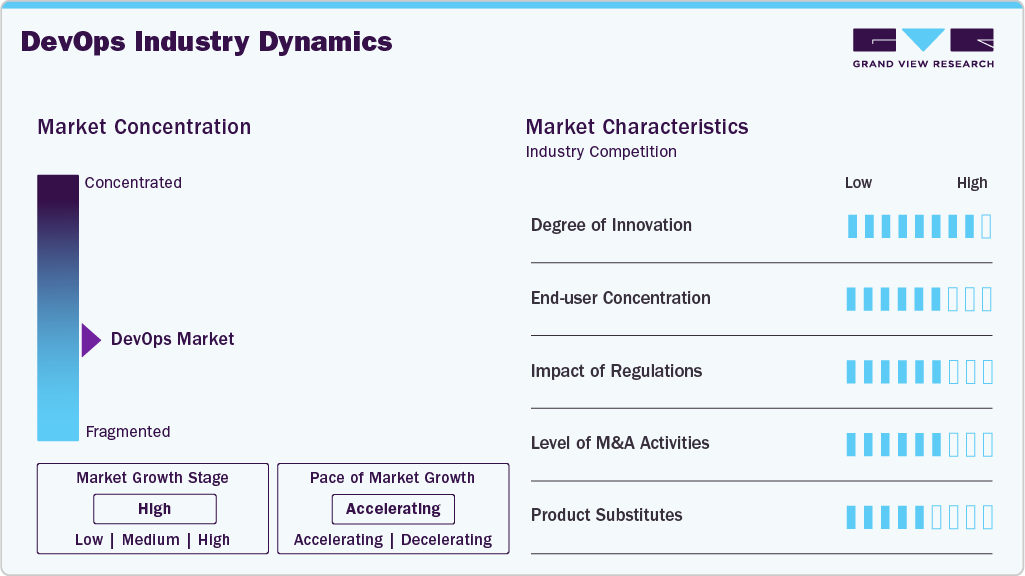 To learn more about this report, Download Free Sample Report
The market is characterized by rapid technological development centered on agentic AI and AIOps integration, platform engineering, GitOps, and container/Kubernetes-based orchestration. Vendors are expanding from standalone point tools toward unified, platform-based ecosystems—often termed Internal Developer Platforms (IDPs) that consolidate CI/CD, security, observability, and cost governance into a single developer experience. At the same time, software supply chain security, multi-cloud and hybrid interoperability, and the convergence of DevOps with adjacent disciplines such as DataOps, MLOps, and FinOps remain key areas of ongoing industry focus as the market matures from standalone automation tooling toward integrated, AI-native delivery platforms.
Analyst Perspective
The market is transitioning from a tools-centric phase toward an intelligence-driven, platform-based model, with agentic AI and platform engineering emerging as defining differentiators for vendors over the next five to seven years. Organizations that successfully embed autonomous AI agents into CI/CD workflows while maintaining governance and security rigor are likely to capture disproportionate value as enterprises prioritize both delivery velocity and compliance. We expect continued consolidation as hyperscale cloud providers deepen native DevOps capabilities, intensifying competitive pressure on standalone tool vendors to differentiate through specialization or ecosystem partnerships.
Deployment Type Insights
Cloud accounted for the largest market share, driven by the enterprise shift toward scalable, on-demand infrastructure that reduces capital expenditure while enabling faster, more flexible software delivery. This growth is further reinforced by the expanding ecosystem of certified partners and specialized service providers that help enterprises accelerate cloud-native DevOps adoption with validated expertise and reduced implementation risk. For instance, in February 2026, Softtek announced it had achieved the Amazon Web Services (AWS) DevOps Competency, recognizing its proven ability to support cloud application modernization through secure, automated, and scalable DevOps practices, including continuous integration and continuous delivery (CI/CD), Infrastructure as Code (IaC), and embedded security. Such competency validations strengthen collaboration between service providers and hyperscale cloud vendors, expanding co-sell opportunities and improving enterprise access to proven cloud DevOps frameworks. Consequently, the continued expansion of certified partner ecosystems and validated cloud-native delivery capabilities is expected to reinforce the cloud's dominant position within the deployment segment over the forecast period.
The on-premises segment is projected to witness significant growth, driven primarily by enterprise focus on data sovereignty, regulatory compliance, and operational control within highly regulated industries such as banking, healthcare, and government. This trend is reinforced by vendors increasingly expanding sovereignty-first deployment architectures that allow enterprises to retain AI and automation capabilities without relinquishing control over where sensitive data resides and how it is governed. For instance, in July 2026, Pega launched its EU Service Boundary (EUSB), an AWS-hosted offering based in Germany that ensures client data is stored, processed, and managed exclusively by EU-resident personnel, directly addressing strict regional compliance and data sovereignty requirements. Subsequently, as regulatory scrutiny over data residency intensifies globally, the on-premises segment is expected to sustain steady growth alongside cloud adoption, particularly among enterprises in regulated and security-sensitive sectors.
Enterprise Size Insights
Large enterprises accounted for the largest market share, driven by their greater financial and technical capacity to invest in comprehensive DevOps automation across security, infrastructure provisioning, and performance optimization. This dominance is further reinforced by the growing recognition among large organizations that DevOps automation has become a strategic imperative for managing increasingly complex, cloud-native technology stacks that exceed the scope of manual oversight. For instance, in September 2023, Dynatrace's global DevOps Automation Pulse Report, based on a survey of 450 IT practitioners across large organizations in the U.S., EMEA, and Asia Pacific, found that such automation investments delivered a 61% improvement in software quality, a 57% reduction in deployment failures, and a 55% decrease in IT costs, even though only 38% of organizations had a clearly defined automation strategy in place. These findings underscore that while large enterprises are leading DevOps automation adoption, the persistence of toolchain complexity and data silos continues to shape ongoing investment priorities within this segment. In conclusion, as large organizations continue to mature their automation strategies and address integration challenges, this segment is expected to retain its leading position within the enterprise size category throughout the forecast period.
SME accounted for the fastest-growing segment, driven by the increasing availability of affordable, cloud-based DevOps solutions purpose-built for organizations with limited technical resources and smaller IT budgets. This trend is further reinforced by DevOps vendors tailoring lightweight, cost-effective platforms specifically to lower the barrier to entry for smaller businesses seeking to accelerate release cycles without dedicated DevOps engineering teams. For instance, Copado announced that more than 10,000 users had implemented Copado Essentials, an easy-to-use, cost-effective release management solution purpose-built for small to mid-sized businesses on the Salesforce platform, positioning it as one of the fastest-growing SaaS DevOps solutions in the SMB segment. Such offerings enable non-technical teams to adopt structured, Git-based version control and streamlined release processes without the overhead traditionally associated with enterprise-grade DevOps toolchains. Therefore, as vendors continue to expand free-tier and low-cost offerings tailored to smaller organizations, the SME segment is expected to sustain the fastest growth rate within the enterprise size category over the forecast period.
End Use Insights
IT & Telecom accounted for the largest market share, owing to the sector's position at the forefront of digital infrastructure transformation, where telecom operators and IT service providers are under constant pressure to accelerate release cycles for software-defined, cloud-native networks while maintaining service reliability. This dominance is further reinforced by large-scale telecom automation initiatives that embed CI/CD practices directly into core network operations to support rapid technology transitions such as 5G rollout and virtualized network functions. For instance, in November 2021, Telefónica and Wipro announced an agreement to introduce Continuous Integration, Continuous Deployment, and Continuous Testing (CI/CD/CT) into Telefónica's German and Brazilian network operations, with plans for expansion into Spain and the UK, describing the framework as essential to enabling the robustness, reliability, and adaptability required under its 5G strategy. Such large-scale operator-vendor collaborations illustrate how deeply DevOps practices have become embedded in telecom network transformation, extending well beyond traditional software development into core infrastructure automation. Thus, as telecom operators and IT service providers continue to scale CI/CD-driven automation across increasingly complex, multi-cloud network environments, the IT & Telecom segment is expected to retain its leading position within the end-use category throughout the forecast period.
 To learn more about this report, Download Free Sample Report
Manufacturing is the fastest-growing segment, driven by the accelerating convergence of IT and operational technology (IT/OT) as manufacturers digitize the factory floor through smart manufacturing, Industrial IoT, and connected supply chain initiatives that demand continuous, reliable software delivery. This trend is further reinforced by leading industrial automation vendors increasingly embedding DevOps-aligned, autonomous operating capabilities directly into manufacturing execution and control platforms to support real-time, resilient production environments. For instance, in June 2026, Rockwell Automation unveiled FactoryTalk ResilientEdge, a platform designed to enable autonomous manufacturing operations, reflecting the industry's shift toward self-managing, continuously updated production systems that reduce downtime and strengthen operational resilience. Such platform launches underscore how manufacturers are extending CI/CD and automation practices beyond traditional IT environments into mission-critical plant-floor systems, where software reliability now directly impacts production continuity. Consequently, as manufacturers continue to adopt Industrial DevOps practices to support Industry 4.0 initiatives, digital twins, and edge-based automation, the manufacturing segment is expected to sustain the fastest growth rate within the end-use category over the forecast period.
Regional Insights
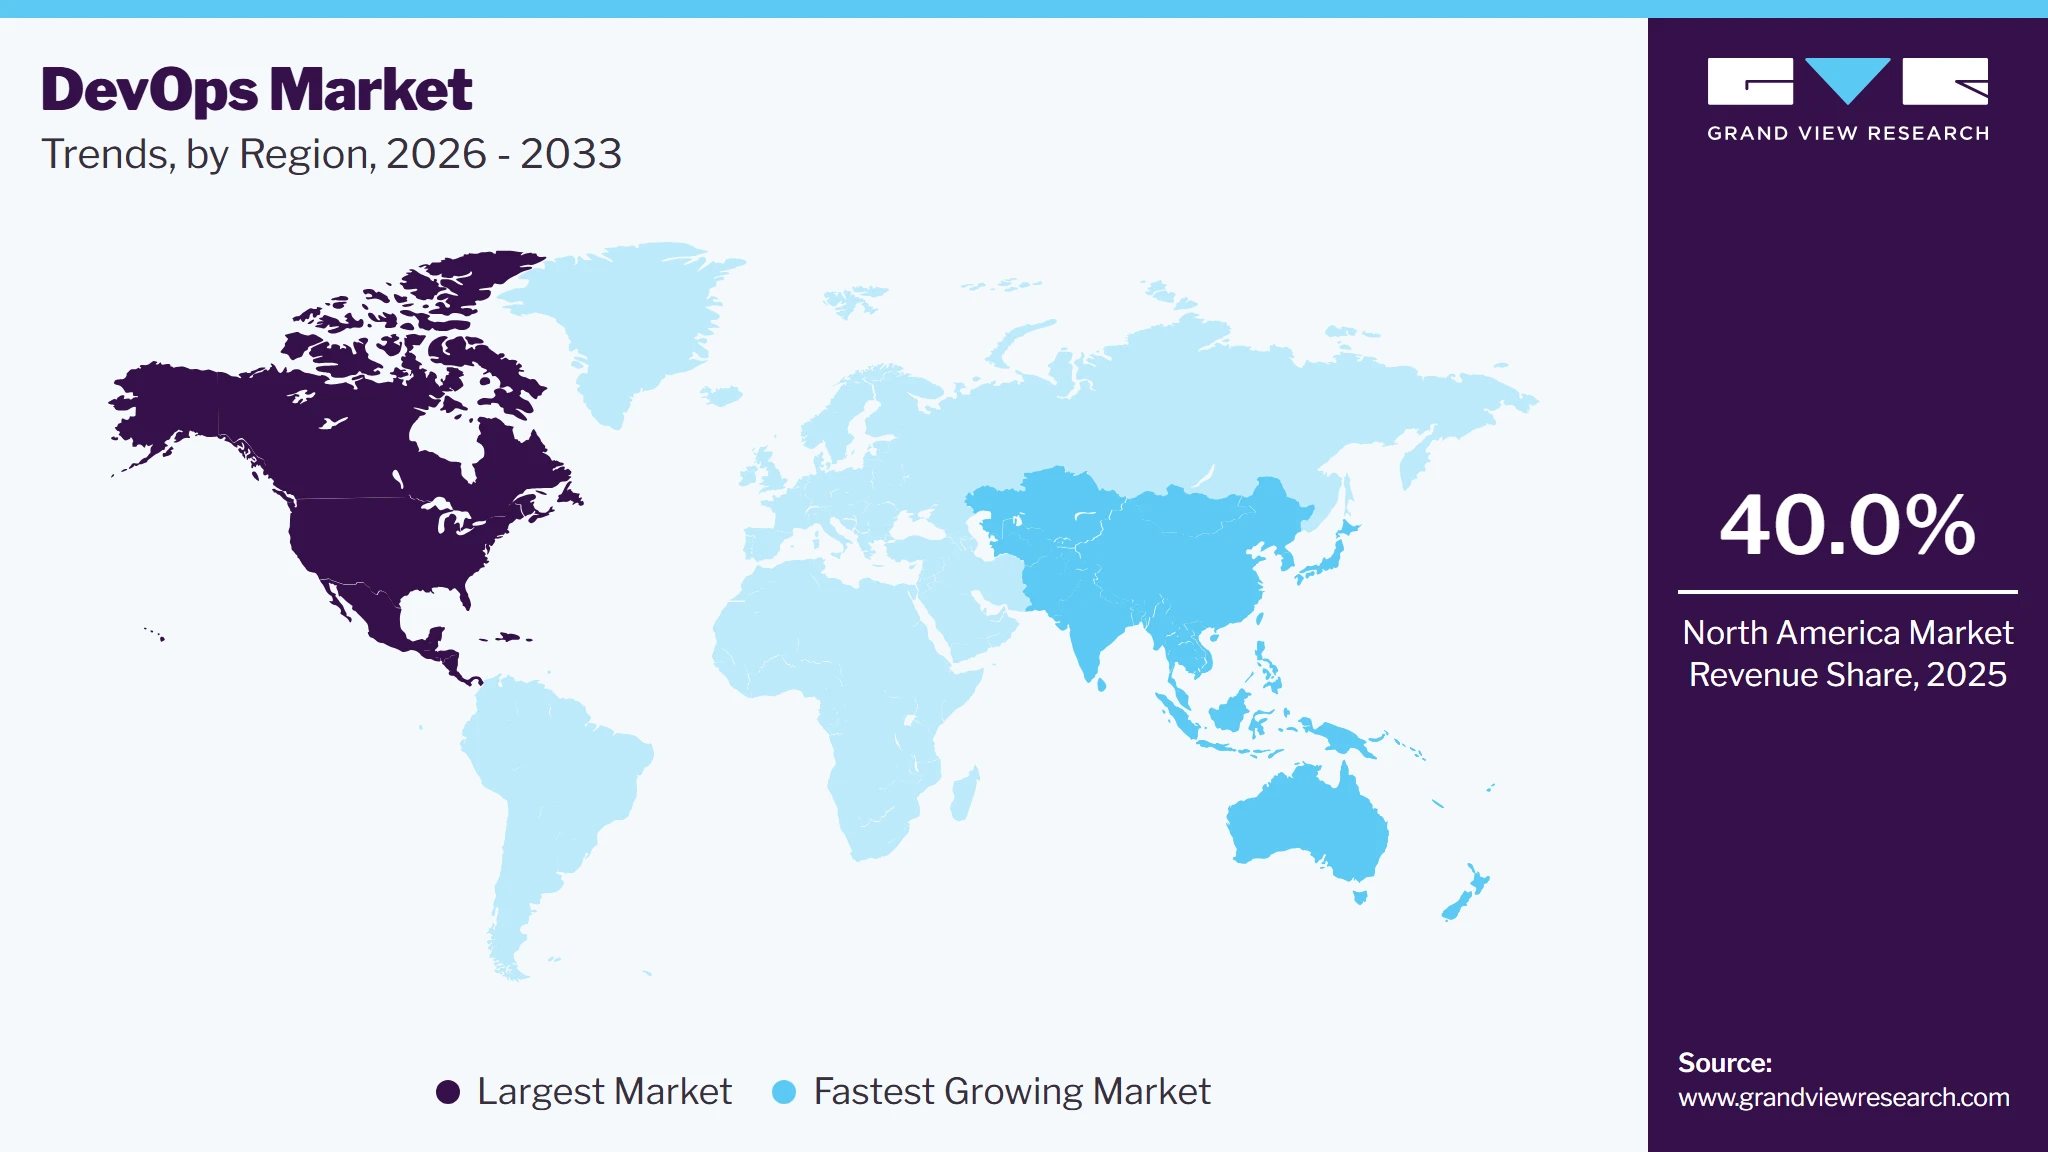
The North America dominated the market and accounted for 40.0% revenue share in 2025, shaped by deep enterprise reliance on hyperscale cloud ecosystems, with organizations increasingly embedding agentic AI and AIOps capabilities directly into CI/CD pipelines to manage incident response, infrastructure provisioning, and release automation with minimal manual intervention. Platform engineering has emerged as a dominant organizational trend, as U.S. enterprises accelerate the build-out of Internal Developer Platforms (IDPs) to standardize delivery workflows and reduce developer cognitive load across increasingly complex, multi-cloud environments. Canada's growing SaaS and fintech ecosystem and Mexico's nearshoring-linked IT investment are further diversifying regional demand beyond the historically dominant U.S. market. At the same time, rising DevSecOps adoption, software supply chain security requirements, and FinOps-aligned cloud cost governance remain key areas of focus as the region's DevOps practices mature from early automation toward integrated, AI-native delivery platforms.
 To learn more about this report, Download Free Sample Report
U.S. DevOps Market Trends
The DevOps market in the U.S. is experiencing robust growth, driven by its concentration of hyperscale cloud providers, enterprise IT budgets, and early, widespread adoption of CI/CD and DevSecOps practices across technology, financial services, and healthcare sectors. Enterprises are increasingly embedding agentic AI and AIOps capabilities into software delivery pipelines to automate incident response, testing, and infrastructure provisioning, while platform engineering has become a central organizational priority as large U.S. technology firms build Internal Developer Platforms to standardize delivery at scale. Growing regulatory emphasis on software supply chain security and data governance is further pushing organizations toward auditable, secure-by-design automation. Collectively, these dynamics continue to position the U.S. as the most mature and innovation-driving market within the broader North America region.
Asia Pacific DevOps Market Trends
The DevOps market in the Asia Pacific is experiencing rapid growth, driven by China's large-scale domestic cloud ecosystem investment and advanced manufacturing digitization, alongside India's expanding IT services and global capability center (GCC) base, which continues to be a major driver of cloud-native DevOps adoption and specialized engineering talent availability. Platform engineering and AI-augmented development are gaining traction across the region's technology hubs, while Southeast Asian markets are increasingly embracing serverless and cloud-first architectures to support rapid digital transformation. Japan's traditionally conservative, in-house IT culture is gradually shifting toward broader automation adoption as manufacturers integrate DevOps into smart factory and Industry 4.0 initiatives.
China DevOps market is witnessing steady growth, driven by large domestic technology firms such as Alibaba, Tencent, and Huawei advancing private and hybrid cloud-based automation to align with data governance and sovereignty requirements, while state-backed digital infrastructure investment continues to support broader enterprise adoption. Manufacturing remains a key growth driver, as China's extensive electronics, automotive, and industrial base increasingly integrates DevOps practices to support smart factory and Industry 4.0 initiatives. At the same time, large enterprises continue to dominate adoption given their scale and resources, though the growing availability of domestic cloud-native tooling is gradually extending DevOps practices to mid-sized organizations. Collectively, these dynamics position China as a key growth engine within the broader Asia Pacific market.
The DevOps market in India is at an emerging stage relative to more mature economies, yet it is scaling rapidly on the back of the country's vast IT services and global capability center (GCC) ecosystem, which continues to drive strong demand for cloud-native automation and DevOps engineering talent. Rapid SaaS adoption, a growing base of technology startups, and expanding enterprise digitization across the BFSI and retail sectors are further accelerating market momentum. While large enterprises and IT-services exporters currently lead adoption, the rising availability of affordable, cloud-based DevOps tooling is gradually extending practices to small and mid-sized businesses. Collectively, these dynamics position India as one of the fastest-growing markets within Asia Pacific, with substantial headroom for continued expansion as digital transformation deepens across industries.
Europe DevOps Market Trends
The DevOps market in Europe continues to be shaped by strong regulatory alignment around data protection, cyber resilience, and digital operational resilience, pushing enterprises toward auditable automation, secure software supply chains, and continuous compliance within CI/CD pipelines. Germany's Mittelstand-driven industrial base is increasingly integrating DevOps into manufacturing and Industry 4.0 initiatives, while the UK's dense fintech and SaaS ecosystem continues to drive cloud-native adoption and platform engineering maturity. France is advancing automation across its public sector and industrial base, and data sovereignty concerns are prompting growing interest in on-premises and sovereign cloud deployment options across the region, including offerings such as EU-resident data boundaries from major enterprise platform vendors. Collectively, these dynamics position Europe as a market where compliance-driven automation and platform consolidation are the primary growth catalysts.
Key DevOps Company Insights
The global DevOps market is characterized by a mix of large cloud and enterprise technology providers, integrated DevOps/DevSecOps platform vendors, and specialized CI/CD and automation providers. Competition is shifting from individual point tools toward integrated platforms. The 2025 Forrester Wave for DevOps Platforms evaluated 11 major participants, including AWS, Atlassian, CircleCI, CloudBees, GitLab, Google Cloud, Harness, IBM, Microsoft, Octopus Deploy, and Red Hat.
-
Microsoft has a broad DevOps ecosystem centered on Azure DevOps and GitHub, giving it strong positioning across enterprise software development and cloud environments. Azure DevOps integrates Boards, Repos, Pipelines, Test Plans, and Artifacts, covering project planning, source-code management, CI/CD, testing, and package management. Azure Pipelines also supports deployment across multiple languages, platforms, clouds, and on-premises environments.
-
GitLab follows an integrated-platform strategy, positioning its product as a single DevSecOps platform rather than a collection of disconnected DevOps tools. Its platform combines software development and delivery capabilities with security and compliance functions, including CI/CD, application security testing, dependency scanning, container security, infrastructure-as-code scanning, secret detection, and vulnerability management.
Key DevOps Companies
The following key companies have been profiled for this study on the DevOps market.
-
Amazon Web Services (AWS)
-
Atlassian
-
Broadcom
-
Chef (Progress Software)
-
Cisco
-
GitHub
-
Google Cloud
-
HashiCorp
-
IBM
-
JFrog
-
Microsoft
-
Oracle
-
Puppet
-
Red Hat
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Microsoft Corporation; Amazon Web Services, Inc.; International Business Machines Corporation (IBM); Broadcom Inc.; Oracle Corporation; Cisco Systems, Inc.
- Expanding integrated DevOps portfolios spanning CI/CD, infrastructure automation, observability, security, and AI-powered developer tooling within broader cloud and enterprise software ecosystems.
- Increasing investments in agentic AI, AIOps, and AI-assisted code generation to embed autonomous automation across the software delivery lifecycle.
- Large installed enterprise customer bases and deep, long-standing relationships with IT organizations across industries and geographies.
- Broad platform ecosystems enable integration across cloud infrastructure, security, and DevOps tooling, supporting bundling, cross-selling, and platform consolidation.
- Large, complex toolchains can result in higher implementation complexity and longer enterprise onboarding and migration cycles.
- Significant legacy and on-premise customer environments create challenges in migrating customers toward fully cloud-native, AI-enabled DevOps platforms.
Emerging Players: GitLab Inc.; HashiCorp, Inc.; JFrog Ltd.; Harness Inc.; CircleCI, Inc.
- Focusing on specialized DevOps capabilities such as GitOps, infrastructure-as-code, artifact management, and AI-native CI/CD pipelines tailored to cloud-native development teams.
- Increasing adoption of open-source-led, product-led growth, and usage-based pricing strategies to accelerate adoption among SMEs, startups, and mid-market engineering teams.
- Open-source roots and developer-first design reduce adoption barriers and foster strong community-driven engagement and trust.
- Greater organizational agility enables rapid incorporation of generative AI, agentic automation, and emerging delivery models into their platforms.
- Greater dependence on hyperscale cloud providers and third-party integrations increases ecosystem and platform dependency risk.
- Intense competition from hyperscale cloud vendors' native DevOps offerings and increasing feature convergence create challenges in maintaining long-term differentiation and customer retention.
Recent Developments
-
In September 2026, JFrog introduced DevGovOps capabilities within its AppTrust platform, automating regulatory compliance and governance for both human and AI-agent-driven software releases, addressing the growing need for continuous, machine-speed compliance as autonomous agents become integral to CI/CD pipelines.
-
In December 2025, AWS unveiled three "Frontier Agents": Kiro, AWS Security Agent, and AWS DevOps Agent, autonomous AI agents that independently write code, review security, and resolve/prevent incidents, marking a shift from AI-assisted to fully autonomous software development and operations workflows.
-
In June 2025, Cisco launched a new AI-ready network architecture featuring AgenticOps, an AI-driven operations layer with a new AI Canvas interface enabling NetOps, SecOps, and DevOps teams to collaborate and automate workflows, embedding DevOps-aligned automation directly into network infrastructure management.
DevOps Market Report Scope
Report Attribute
Details
Market size in 2025
USD 16.2 billion
Estimated market size in 2026
USD 18.5 billion
Projected market size by 2033
USD 74.1 billion
Growth rate
CAGR of 21.9% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company share, competitive landscape, growth factors, and trends
Segments covered
Deployment type, enterprise size, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; Japan; India; South Korea; Australia; Brazil; UAE; KSA; South Africa
Key companies profiled
Amazon Web Services (AWS); Atlassian; Broadcom; Chef (Progress Software); Cisco; GitHub; Google Cloud; HashiCorp; IBM; JFrog; Microsoft; Oracle; Puppet; Red Hat
Customization scope
Free report customization (equivalent to up to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global DevOps Market Report Segmentation
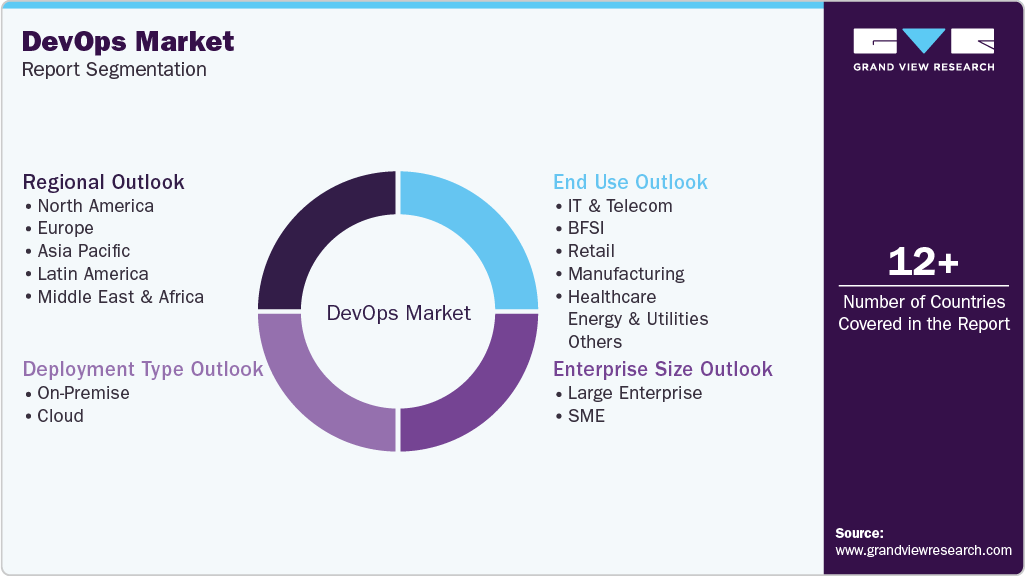
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global DevOps market report based on deployment type, enterprise size, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Deployment Type Outlook (Revenue, USD Million, 2021 - 2033)
-
On-Premise
-
Cloud
-
-
Enterprise Size Outlook (Revenue, USD Million, 2021 - 2033)
-
Large Enterprise
-
SME
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
IT & Telecom
-
BFSI
-
Retail
-
Manufacturing
-
Healthcare
-
Energy & Utilities
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa
-
UAE
-
KSA
-
South Africa
-
-
Research Methodology
The DevOps market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each DevOps segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Deployment Type
Revenue Capture Definition
On-Premise
Revenue generated from DevOps solutions deployed and hosted on an organization's own local servers or data centers, including tools for CI/CD, infrastructure automation, and monitoring installed and managed within internal IT environments.
Cloud
Revenue generated from DevOps solutions delivered via public, private, or hybrid cloud infrastructure, including SaaS-based CI/CD pipelines, infrastructure-as-code platforms, and managed DevOps services hosted by third-party cloud providers.
Enterprise Size
Revenue Capture Definition
Large Enterprise
Revenue generated from DevOps solutions purchased or subscribed to by large organizations for enterprise-wide software delivery automation, security integration, platform engineering, and large-scale CI/CD pipeline management.
SME
Revenue generated from DevOps solutions purchased or subscribed to by small and medium-sized enterprises for cost-effective, lightweight automation, release management, and software delivery processes.
End Use
Revenue Capture Definition
IT & Telecom
Revenue generated from DevOps solutions used by IT service providers, software companies, telecom operators, and digital technology organizations to support software delivery, network automation, and infrastructure management.
BFSI
Revenue generated from DevOps solutions deployed by banks, financial institutions, insurance companies, and other financial service providers to support secure, compliant, and rapid software release cycles.
Retail
Revenue generated from DevOps solutions supporting retail and e-commerce operations, including customer-facing application delivery, inventory systems, and digital commerce platform automation.
Manufacturing
Revenue generated from DevOps solutions supporting manufacturing operations, including software delivery for smart factory systems, industrial automation, IoT integration, and production management platforms.
Healthcare
Revenue generated from DevOps solutions used by healthcare providers, pharmaceutical companies, and life sciences organizations to support secure, compliant software delivery for clinical, administrative, and research applications.
Energy & Utilities
Revenue generated from DevOps solutions supporting energy and utility companies in automating software delivery for grid management, operational technology, and infrastructure monitoring systems.
Others
Revenue generated from DevOps solutions used across other industries, including media & entertainment, transportation & logistics, education, and professional services.
Estimation Model
Layer
Key Questions
Description
DevOps Infrastructure Layer (TAM)
Who might require DevOps solutions?
Organizations across industries, including large enterprises, SMEs, government bodies, and technology service providers, require tools and platforms for software development, continuous integration, continuous delivery, automation, monitoring, and security across their IT and software engineering functions.
DevOps Requirement Layer (SAM)
Who can technically and commercially adopt DevOps solutions?
Organizations operating software development teams, cloud or on-premise IT infrastructure, and application delivery pipelines where CI/CD automation, infrastructure-as-code, containerization, and observability tooling can address speed, reliability, security, and scalability requirements.
Active DevOps Adoption Layer (SOM)
Who actively uses or purchases DevOps solutions today?
Enterprises and SMEs currently subscribing to or deploying DevOps tools and platforms, including organizations adopting CI/CD pipelines, infrastructure automation, DevSecOps, platform engineering, and AI-augmented development workflows for core software delivery processes.
Revenue Realization Layer
How is revenue generated?
Revenue is generated through software subscriptions, usage-based and consumption-based pricing, per-user or per-seat licensing, tiered and enterprise plans, along with implementation, integration, managed services, training, and premium AI-powered or advanced automation feature add-ons where applicable.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
DevOps market strategy and enterprise technology assessment
Assessment of DevOps adoption across CI/CD, infrastructure automation, containerization, monitoring/observability, security (DevSecOps), and platform engineering tools.
Evaluation of DevOps demand across SMEs and large enterprises and key industries, including IT & telecom, BFSI, retail, manufacturing, healthcare, energy & utilities, and other sectors.
Developed a DevOps market strategy aligned with cloud-native adoption, AI-driven automation, agentic AI integration, platform engineering, and increasing demand for scalable, secure software delivery.
Identified growth opportunities across AI-augmented DevOps, DevSecOps, platform engineering, and industry-specific automation solutions.
DevOps technology and vendor benchmarking
Comparative assessment of leading DevOps providers based on product portfolio, AI/agentic capabilities, cloud architecture, integrations, scalability, security, pricing models, and enterprise functionality.
Benchmarking of established and emerging players across enterprise deployments, SMEs, cloud environments, and key industry verticals.
Delivered a structured vendor evaluation and technology benchmarking framework to support competitive positioning and DevOps tooling investment decisions.
Identified vendors based on product breadth, innovation capabilities, AI/agentic integration, customer base, ecosystem partnerships, scalability, and industry alignment.
DevOps use-case, technology, and adoption assessment
Assessment of key DevOps use cases across CI/CD pipelines, infrastructure-as-code, release automation, security integration, observability, and incident management.
Evaluation of adoption drivers and technology requirements, including cloud readiness, integration, data security, AI/agentic capabilities, interoperability, scalability, and developer experience.
Provided actionable recommendations for prioritizing DevOps opportunities based on enterprise adoption, AI maturity, digital transformation requirements, deployment preferences, and industry-specific needs.
Identified high-priority opportunities across DevOps tool categories, deployment models, enterprise sizes, and end-use industries.
Frequently Asked Questions About This Report
The global DevOps market is expected to grow at a CAGR of 21.9% from 2026 to 2033, reaching USD 74.1 billion by 2033.
North America dominated with a revenue share of 40.0% in 2025.
The global DevOps market size was valued at USD 16.2 billion in 2025 and is estimated at USD 18.5 billion for 2026.
The increasing adoption of cloud technologies, fast application delivery, advancements in artificial intelligence, and software automation is expected to drive the growth of the DevOps market.
The cloud segment led with a 62.5% revenue share in 2025 and is also the fastest-growing segment.
The large enterprise segment led with a 58.4% revenue share in 2025, while SME segment is the fastest-growing segment.
The IT & Telecom segment led with a 40.4% revenue share in 2025, while manufacturing segment is the fastest-growing segment.
Asia Pacific is the fastest-growing region over the forecast period.
Some key players operating in the DevOps market includeAmazon Web Services (AWS); Atlassian; Broadcom; Chef (Progress Software); Cisco; GitHub; Google Cloud; HashiCorp; IBM; JFrog; Microsoft; Oracle; Puppet; Red Hat
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


