
- Home
- »
- Bulk Chemicals
- »
-
Dewatering Pump Market Size And Share Report, 2026-2033GVR Report cover

Dewatering Pump Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drive Type (Electric, Diesel), By Pump Type (Submersible Pumps, Non-submersible Pumps), By End Use (Construction, Oil & gas), By Region, And Segment Forecasts
Market Size, 2025
$8.5BMarket Estimate, 2026
$8.8BMarket Forecast, 2033
$12.2BCAGR, 2026–2033
4.7%Dewatering Pump Market Summary
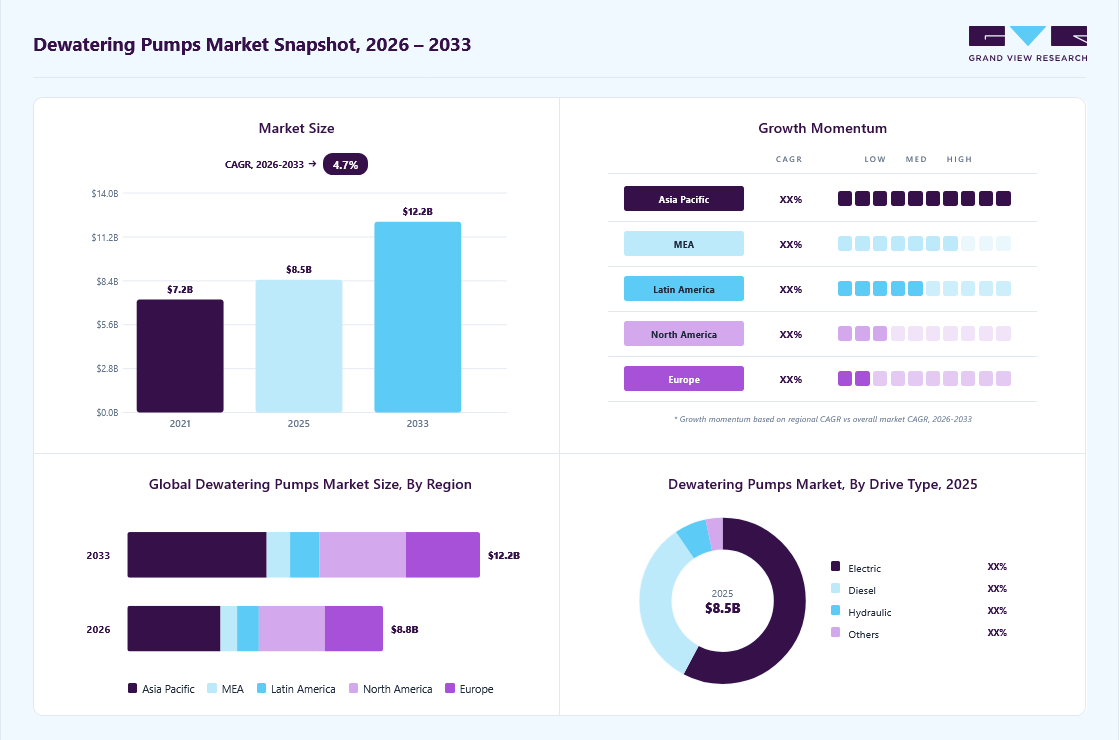
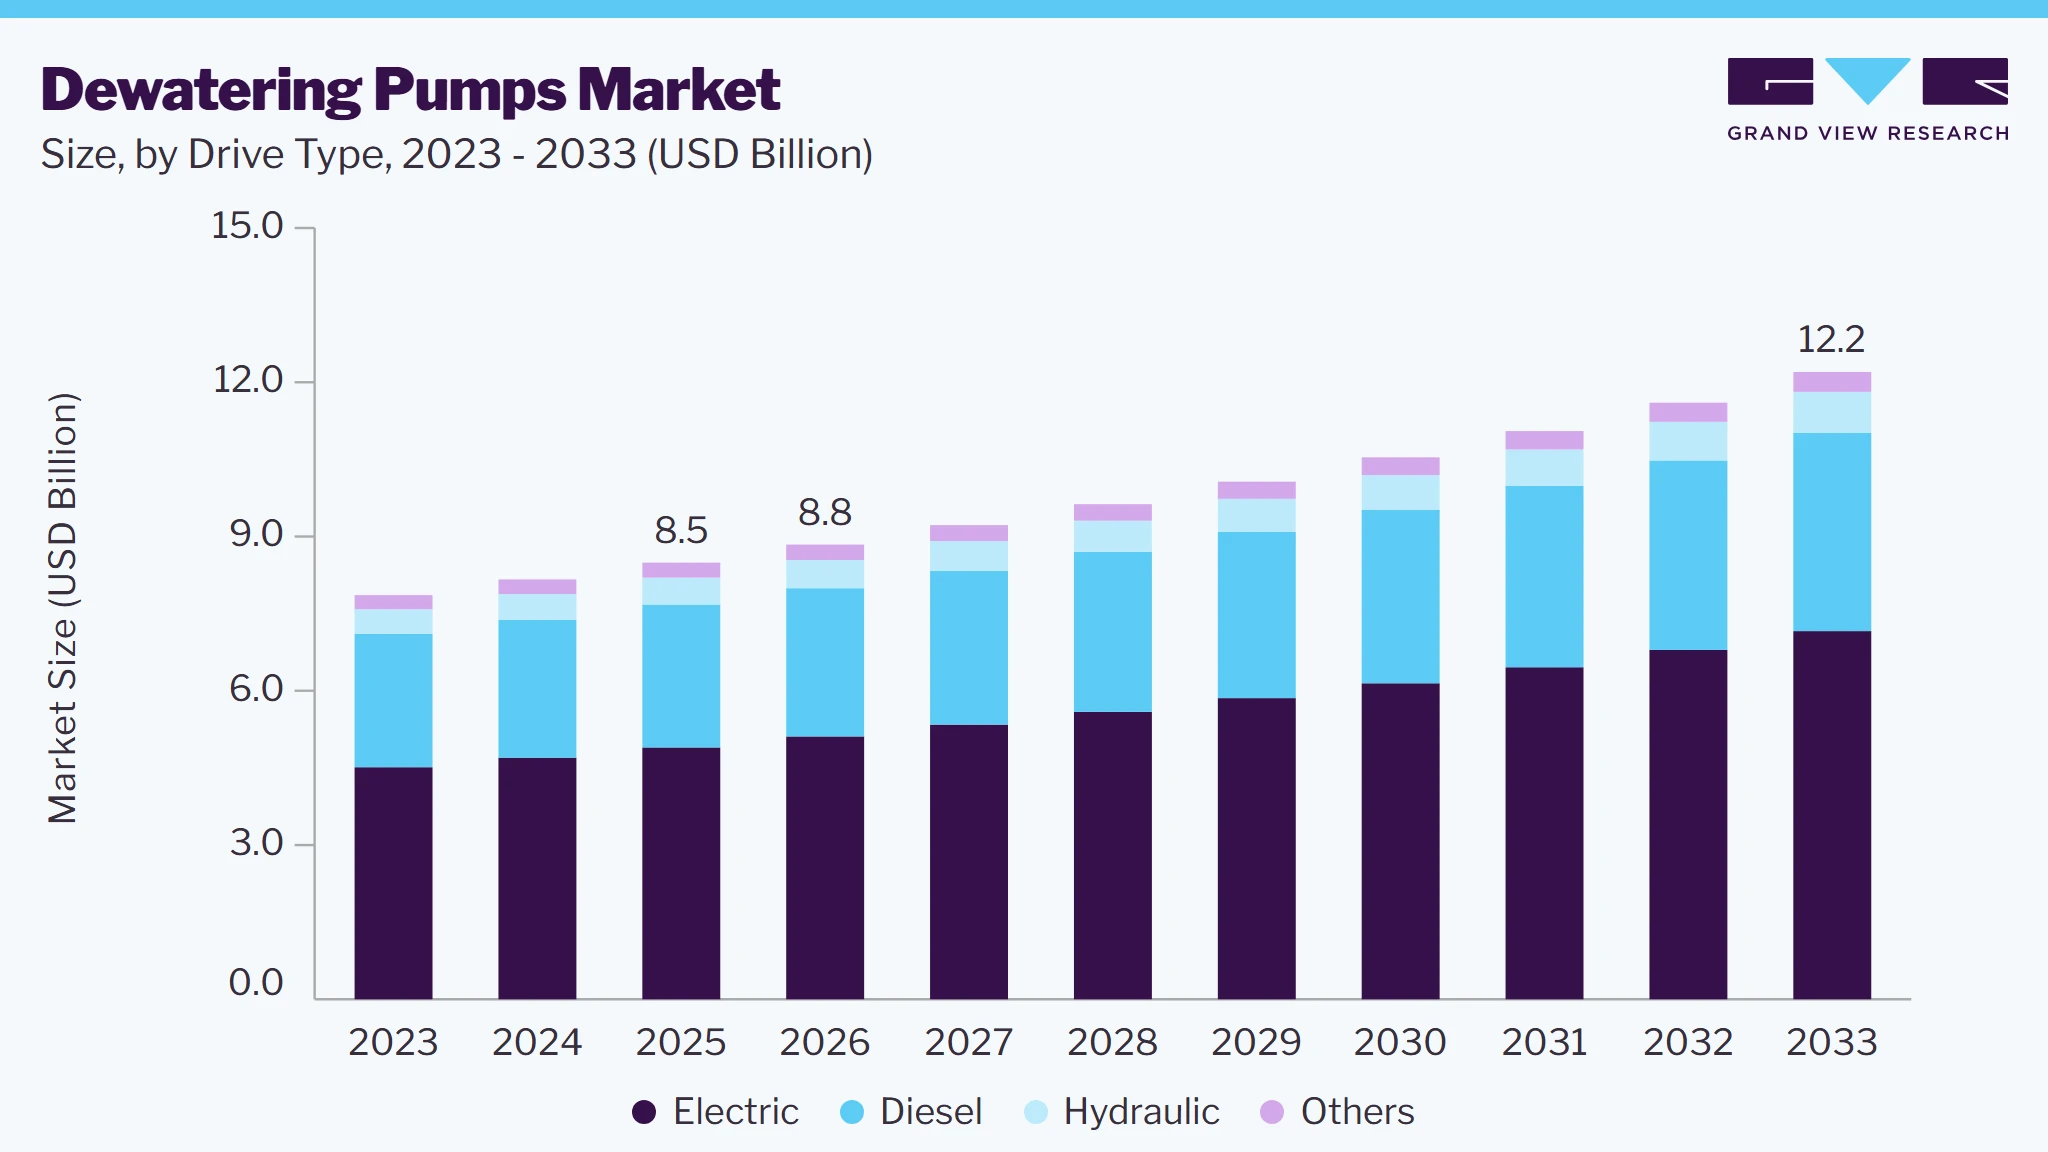
The global dewatering pump market size was valued at USD 8.5 billion in 2025 and is projected to grow from USD 8.8 billion in 2026 to USD 12.2 billion by 2033, at a CAGR of 4.7% from 2026 to 2033. Asia Pacific dominated the market with the largest revenue share of 36.0% in 2025. The market growth is driven by increasing construction, mining, and infrastructure activities that require effective water removal from excavations, tunnels, foundations, and mine sites.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drive type: Hydraulic segment is projected to grow at 5.5% CAGR from 2026 to 2033.
- By pump type: Submersible pumps segment held the largest market share of 58.9% in 2025.
- By end use: Municipal & utilities segment is expected to grow at a CAGR of 6.2% from 2026 to 2033.
Regional Highlights
- Largest regional market: Asia Pacific (36.0% revenue share, 2025)
- By country: China held the largest share of Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.5 Billion
- Estimated market size in 2026: USD 8.8 Billion
- Projected market size by 2033: USD 12.2 Billion
- CAGR (2026-2033): 4.7%
Prism AI by Grand View Research Free to tryAsk a question about the dewatering pump marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Expansion of underground projects and deeper mining operations is increasing the need for reliable pumping systems to manage groundwater ingress and maintain safe working conditions. Growing investments in drainage, flood-control, and municipal infrastructure are further supporting demand for portable and stationary dewatering equipment.
 To learn more about this report, Download Free Sample Report
Additionally, the replacement of aging pumping equipment and demand for application-specific systems are creating opportunities for manufacturers across different flow, head, and fluid-handling requirements. Rental-based access to dewatering equipment is also gaining relevance among contractors seeking flexible solutions for temporary projects without substantial capital expenditure. Manufacturers are incorporating features such as automated controls, remote monitoring, variable-speed operation, and improved wear resistance to address maintenance and operating-cost considerations.
Market Dynamics
The dewatering pump market is shaped by demand for equipment used to remove groundwater, surface water, and accumulated water from construction sites, mines, tunnels, excavations, and industrial facilities. Market requirements vary by pumping depth, flow, and head capacity, fluid characteristics, solids content, power source, and deployment conditions. Equipment selection is also influenced by portability, durability, energy consumption, and maintenance requirements.
The expansion of construction, excavation, tunneling, and mining activities is increasing the need for dewatering pump to maintain safe, workable operating areas. Deep foundations, underground structures, open-pit mines, and below-ground operations can encounter groundwater ingress or accumulated water that requires continuous or periodic removal. The growing scale and depth of these activities are therefore creating demand for pumps capable of operating under varying flow, head, and site conditions.
Dewatering pump used in construction and mining frequently handle water containing sand, silt, mud, and other abrasive particles. Prolonged exposure to such conditions can accelerate wear of impellers, seals, casings, and other components, increasing maintenance and replacement requirements. Higher operating and servicing costs can affect equipment utilization and purchasing decisions, particularly in applications involving continuous pumping.
The development of energy-efficient dewatering pump with variable-speed drives, automated controls, improved solids-handling capabilities, and remote monitoring offers opportunities for manufacturers to differentiate their products. These features can enable better adjustment to changing water levels and operating conditions while providing greater visibility into pump performance. Manufacturers can also expand their offerings through application-specific designs for deep excavation, high-solids pumping, and demanding mining environments.
Market Concentration & Characteristics
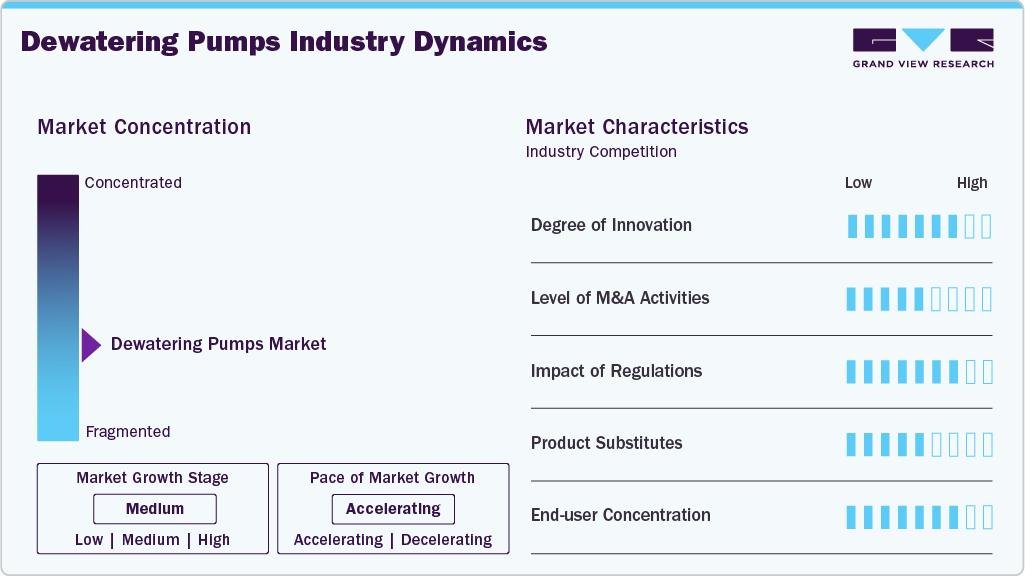
The dewatering pump market is moderately fragmented, comprising multinational manufacturers, regional suppliers, and specialized equipment providers serving construction, mining, industrial, municipal, and infrastructure applications. Competition varies across end-use sectors, with established companies offering diversified product portfolios while regional participants focus on customized solutions and localized distribution networks. Market participants compete through product performance, engineering capabilities, distribution reach, technical support, and after-sales services. The presence of equipment rental providers further broadens the competitive structure, particularly for temporary and project-based requirements.
Product offerings include submersible, centrifugal, and self-priming pumps designed for different water-handling conditions. Selection depends on pumping depth, flow rate, discharge head, water contamination, solids content, and installation environment. Manufacturers are developing energy-efficient systems with variable-speed drives, automated controls, and remote monitoring capabilities to address operating requirements across demanding applications. Portable and compact designs are also gaining relevance for temporary worksites, confined spaces, and projects requiring frequent equipment relocation.
 To learn more about this report, Download Free Sample Report
The dewatering pump industry is characterized by application-specific engineering, product development, and expanding lifecycle services. Companies are strengthening their offerings through preventive maintenance, replacement components, refurbishment, and technical assistance to support long-term equipment performance. Rental models are increasingly relevant for contractors requiring pumps for short-duration projects or emergency water removal. In mining and large industrial operations, equipment availability, maintenance response, solids-handling capability, and service coverage remain important considerations in supplier selection.
Analyst Perspective
The dewatering pump market is primarily influenced by the scale and complexity of excavation, mining, tunneling, and infrastructure projects, where water ingress can affect site continuity and equipment utilization. Pump selection is increasingly application-specific, with flow and head requirements, solids concentration, pumping depth, mobility, and available power sources determining the appropriate configuration. Electric systems are gaining relevance where reliable power infrastructure is available, while diesel-driven units remain suitable for remote and temporary sites. Competition is also shifting toward equipment with lower energy consumption, improved wear resistance, monitoring capabilities, and reduced maintenance requirements. Replacement of aging pump fleets and growing preference for rental-based equipment provide additional avenues for manufacturers beyond new project installations.
Drive Type Insights
The electric segment accounted for the largest revenue share of 57.7% in 2025. Its adoption is supported by the availability of electrical infrastructure across construction, mining, municipal, and industrial sites, where pumps are often required for extended operating periods. Electric systems offer consistent power delivery and can be integrated with automated controls, making them suitable for applications requiring stable and controllable water removal. Their use is particularly relevant for fixed and semi-permanent dewatering installations with reliable grid or generator access.
The hydraulic segment is projected to register the fastest CAGR during the forecast period. Growth is associated with the increasing use of hydraulically powered machinery at construction, mining, and infrastructure sites, enabling dewatering pump to operate through existing hydraulic systems. These pumps are suited to mobile applications, remote worksites, and environments where conventional electrical connections may be limited. Their ability to operate alongside excavators and other hydraulic equipment also supports deployment flexibility for project-specific dewatering requirements.
Pump Type Insights
The submersible pumps accounted for the largest revenue share in 2025, supported by their ability to operate directly within the water being removed and handle dewatering requirements across construction, mining, tunneling, and infrastructure sites. Their compact installation and direct pumping configuration reduce the need for separate suction arrangements, making them suitable for deep excavations, flooded areas, and confined worksites. Demand is also supported by their availability in configurations designed to handle sediment, slurry, and other solids commonly encountered in site dewatering.
The non-submersible pumps segment is projected to grow at a CAGR of 4.0% during the forecast period. These systems remain relevant where pumps need to be positioned outside the water source, particularly for surface drainage, excavation sites, and applications requiring accessible equipment for inspection and maintenance. Their suitability for high-capacity pumping and flexible deployment supports continued use across construction, mining, and industrial operations.
End Use Insights
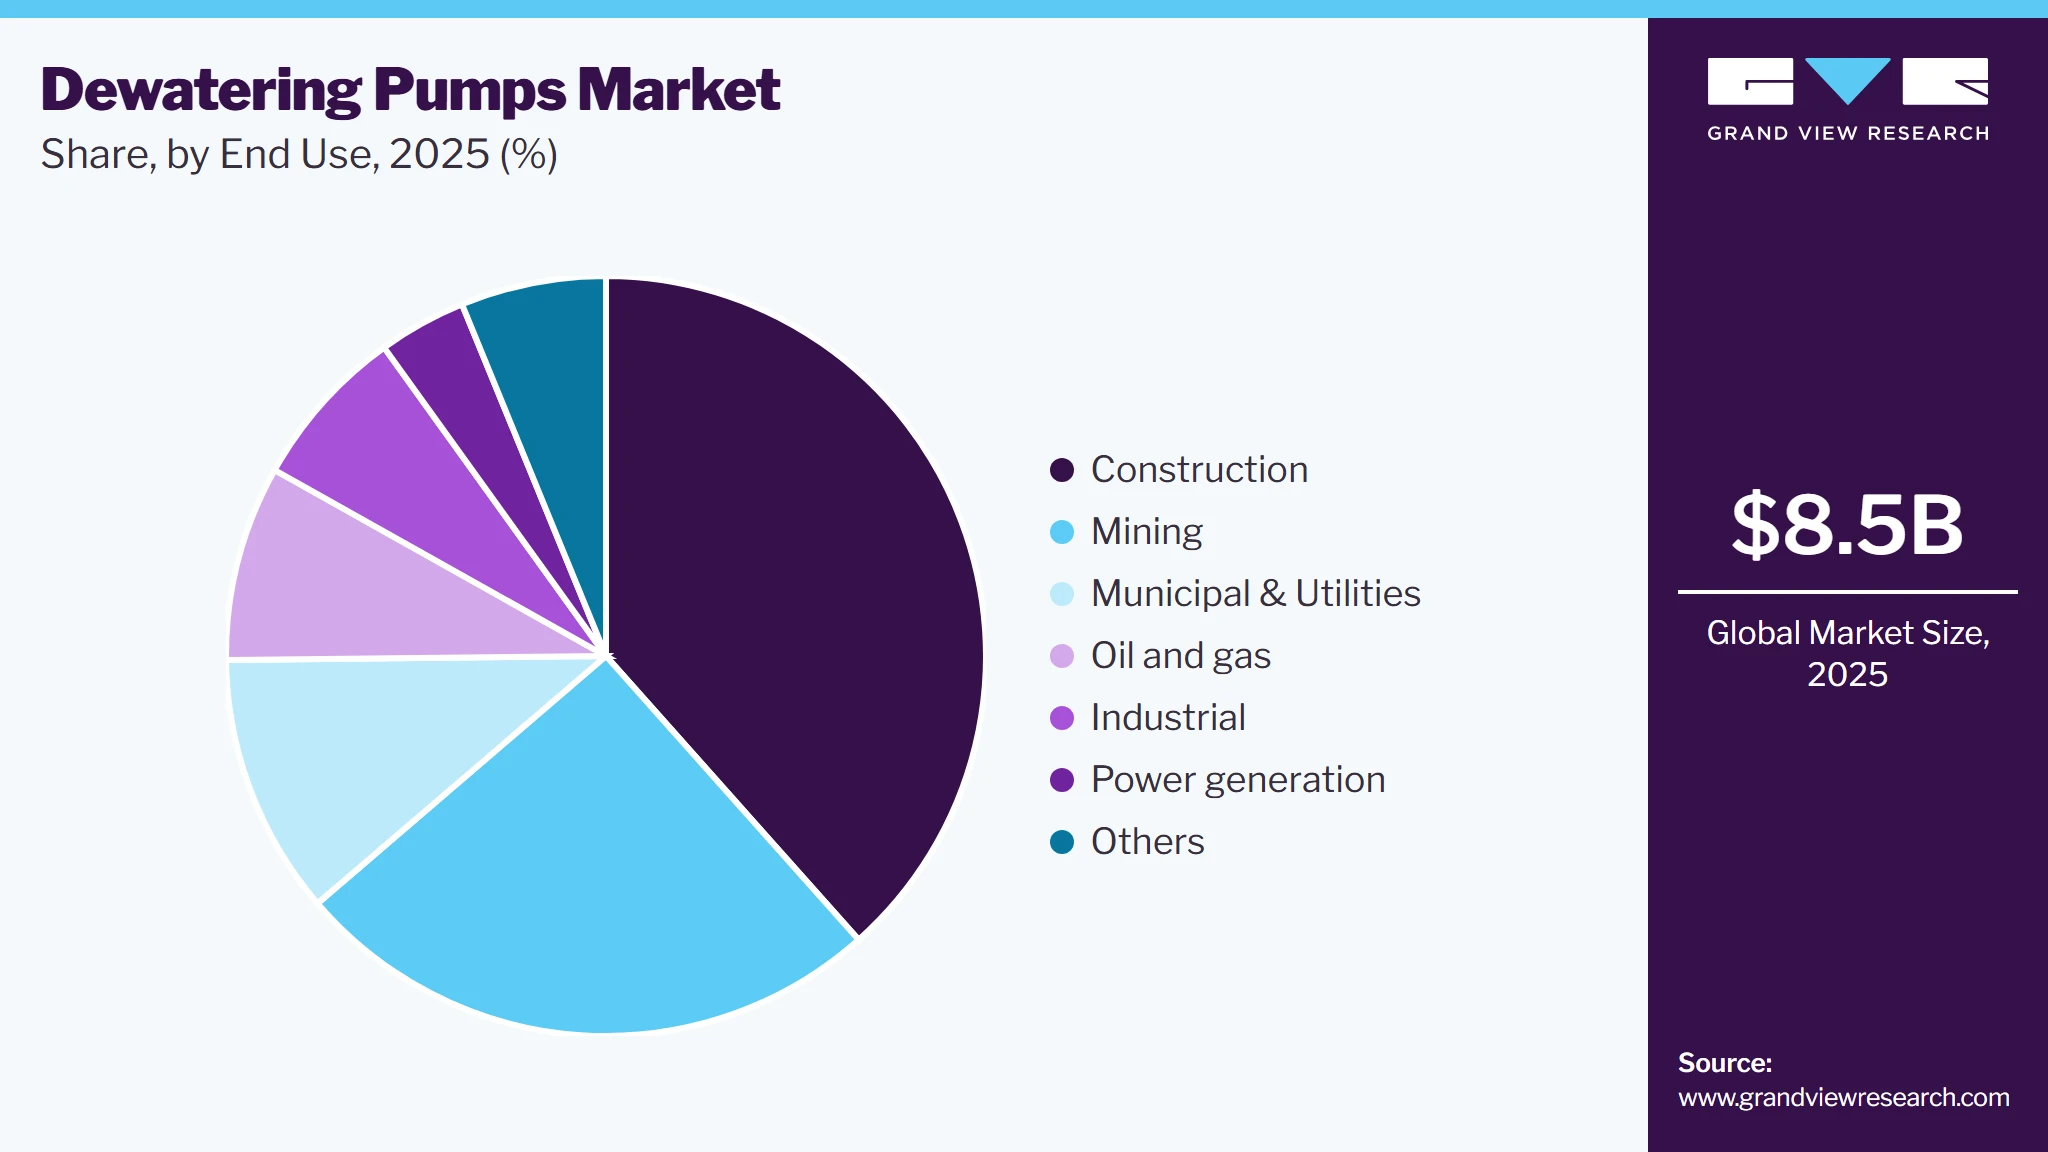
The construction segment dominated the dewatering pump industry, accounting for a revenue share of 38.4% in 2025. Demand is primarily associated with excavation, foundation construction, tunneling, road development, and other infrastructure projects where groundwater, seepage, and accumulated water must be removed from work areas. Project sites often require portable or temporary pumping equipment that can be deployed according to excavation depth, water volume, and site conditions. Continued development of underground and large-scale infrastructure projects is therefore supporting demand for dewatering pumps within the construction sector.
 To learn more about this report, Download Free Sample Report
The municipal & utilities segment is projected to grow at the fastest CAGR during the forecast period. Demand is being supported by the expansion and rehabilitation of drainage networks, flood-control infrastructure, utility projects, and municipal facilities requiring water removal during construction, maintenance, and emergency conditions. Aging drainage infrastructure and increasing requirements for higher pumping capacity are creating additional equipment needs. The use of mobile, high-capacity dewatering pumps for temporary water removal also offers scope for further adoption in municipal and utility applications.
Regional Insights
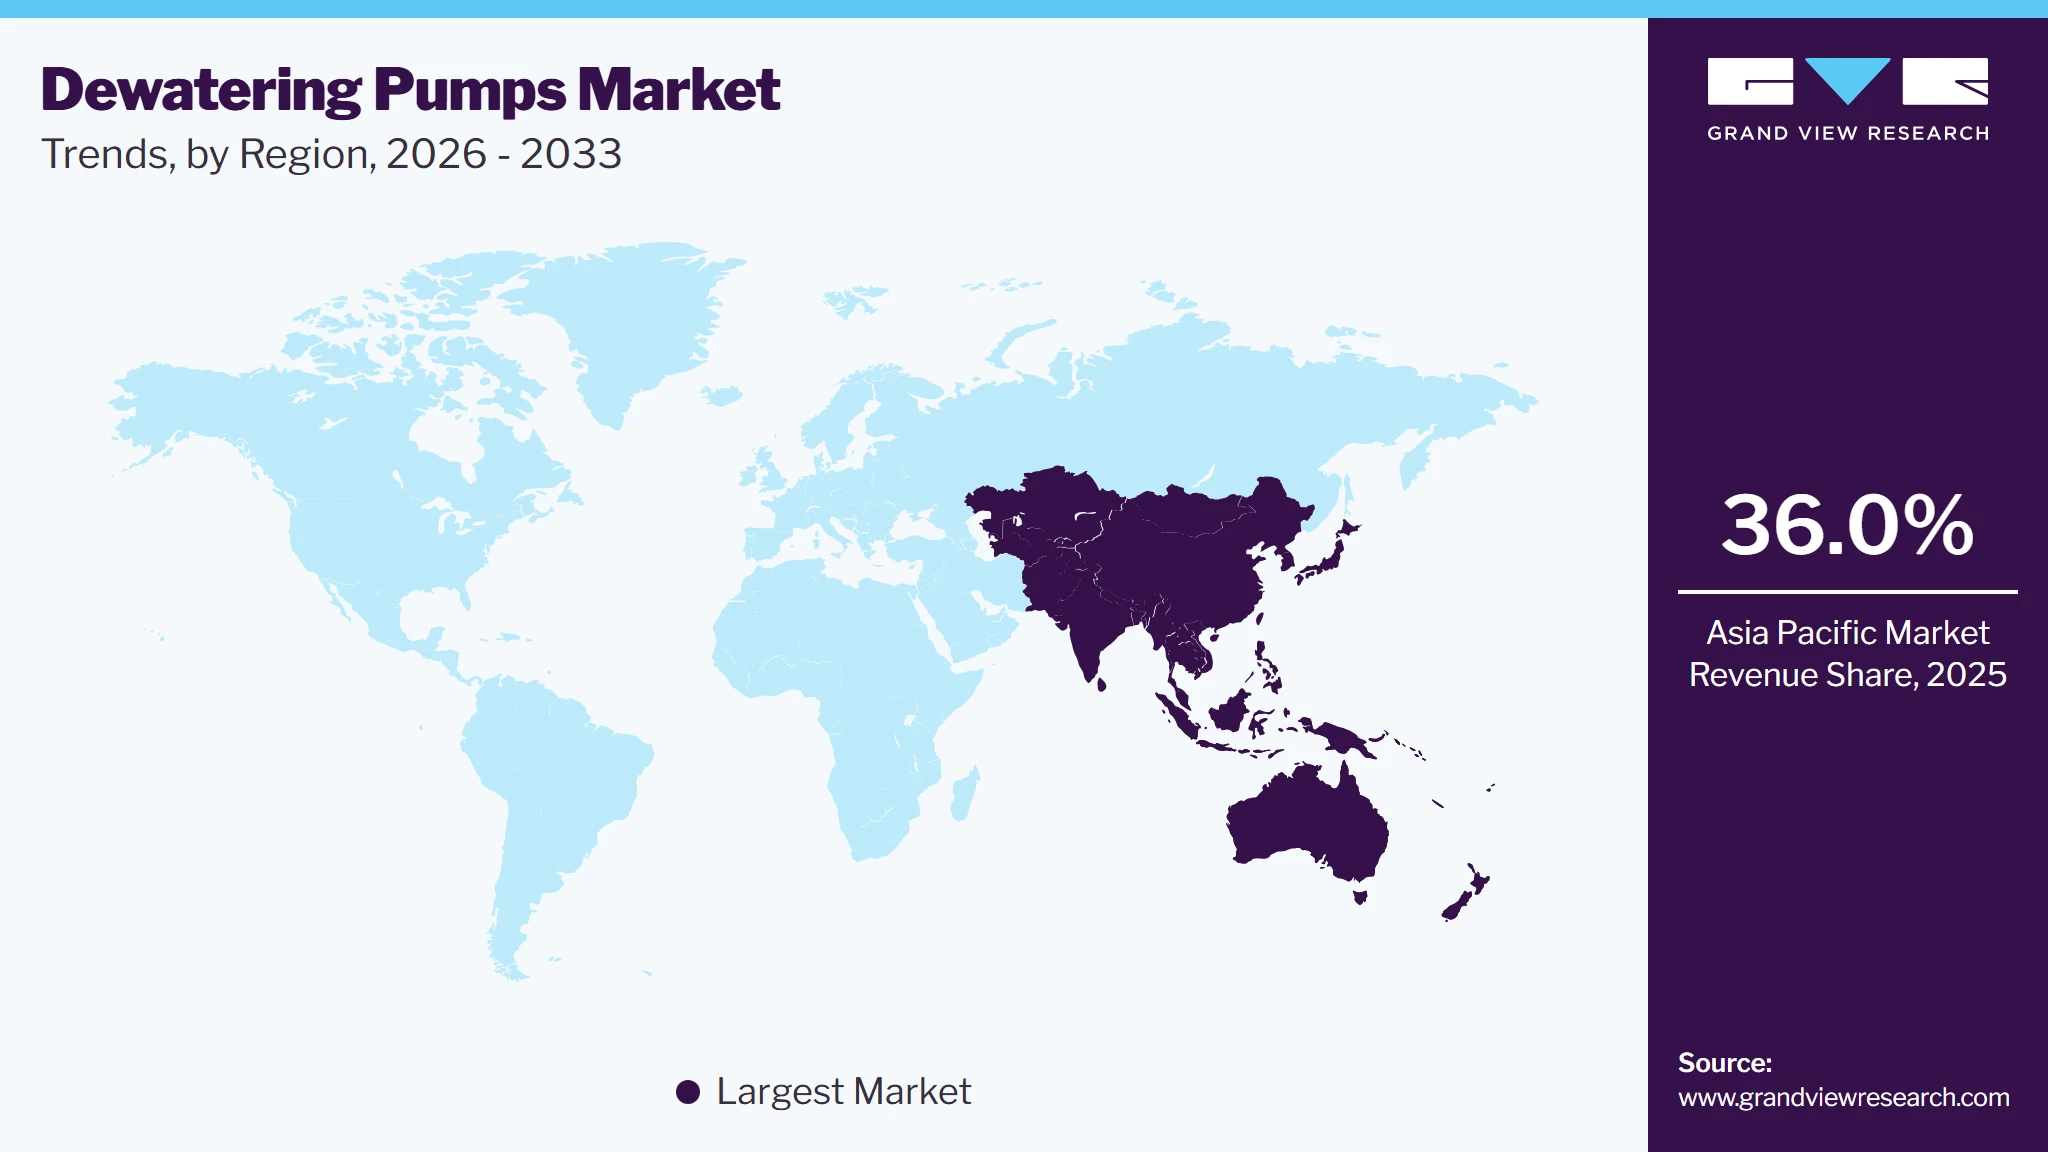
The Asia Pacific dewatering pumps market accounted for the largest revenue share of 36.0% in 2025. The regional market is characterized by a broad mix of construction, mining, tunneling, urban development, and water-management projects that require temporary or continuous removal of groundwater and accumulated water. Seasonal flooding and variations in groundwater levels also create requirements for mobile dewatering equipment across several markets. The diversity of project environments results in demand for submersible and non-submersible pumps across different flow, head, and solids-handling requirements.
 To learn more about this report, Download Free Sample Report
The dewatering pump market in China represents a substantial demand center in Asia Pacific, with dewatering requirements closely linked to underground transportation projects, large-scale urban construction, utility installation, and industrial development. Metro construction, deep excavations, and below-ground utility works require controlled removal of groundwater during different stages of project execution. Large civil projects also create requirements for high-capacity systems capable of handling sustained pumping duties. This application mix supports demand for equipment designed for extended operation and varying excavation depths.
The India dewatering pump market is projected to grow at the fastest CAGR of 9.7% during the forecast period. Market expansion is associated with metro rail development, highways, urban construction, mining projects, and the expansion of municipal infrastructure. Seasonal rainfall and groundwater accumulation can create short-duration but intensive pumping requirements at construction and excavation sites. Mining operations also require equipment capable of handling water containing suspended solids, creating demand for rugged submersible and high-capacity systems.
North America Dewatering Pump Market Trends
North America represents a mature dewatering pumps industry in which replacement demand and equipment utilization are important revenue contributors. The region has an established base of pumps deployed across construction, mining, municipal, industrial, and infrastructure applications. Equipment rental is also an important procurement option for contractors who require pumps for temporary projects, emergency water removal, or variable workloads. Consequently, product availability, replacement components, maintenance response, and equipment uptime influence purchasing decisions alongside pump specifications.
The U.S. dewatering pumps industry is characterized by demand from excavation, municipal drainage, industrial facilities, mining operations, and temporary construction requirements. Contractors frequently require equipment that can be deployed rapidly as site water conditions change during excavation or infrastructure work. Municipal applications create another demand stream through drainage projects, rehabilitation activities, and emergency water management. This application diversity creates demand for both permanently installed systems and readily deployable pumping equipment.
The Canada dewatering pump market has a more resource-oriented demand profile, particularly across mining and geographically dispersed construction projects. Dewatering requirements can arise at remote mine sites where pumping equipment must operate under demanding site conditions and limited access to supporting infrastructure. Equipment selection, therefore, places greater emphasis on mobility, durability, operating reliability, and service accessibility. Mining applications also create demand for systems capable of managing substantial water volumes and water containing abrasive solids.
Europe Dewatering Pump Market Trends
Europe is characterized by a relatively established installed base, making modernization and replacement an important part of market demand. Infrastructure rehabilitation, tunneling, urban redevelopment, industrial drainage, and municipal projects create requirements for temporary and permanent dewatering systems. Energy consumption and lifecycle operating costs are increasingly relevant when replacing older equipment, particularly where pumps operate for extended periods.
The Germany dewatering pump market has demand across civil engineering, industrial facilities, tunneling, and infrastructure maintenance, with equipment requirements shaped by technically demanding project conditions. Dewatering systems are used where excavation, underground construction, or industrial operations require controlled water removal without disrupting surrounding activities. Industrial users also require dependable pumping equipment for drainage and facility-level water management. The market, therefore, provides opportunities for technically engineered systems rather than relying solely on high-volume construction applications.
The dewatering pump market in France is influenced by urban redevelopment, transport infrastructure, tunneling, and municipal works. Temporary dewatering is relevant during excavation and below-ground construction where water accumulation can interfere with project execution. Rehabilitation of existing infrastructure also creates requirements for pumping systems that can be deployed within constrained urban worksites.
Middle East & Africa Dewatering Pump Market Trends
The Middle East & Africa dewatering pumps industry is characterized by project-based demand from construction, mining, oil & gas, industrial facilities, and municipal water management activities. Large excavation and infrastructure projects may require substantial pumping capacity during specific construction phases, whereas mining operations have more continuous water-removal requirements. Procurement conditions differ considerably across countries, making local equipment availability and technical support important considerations. Operating environments can also require pumps designed for heavy-duty use and straightforward field maintenance.
The Saudi Arabia dewatering pumps market is primarily influenced by large-scale urban development, transportation projects, commercial construction, and industrial infrastructure. Deep excavations and below-ground structures can require temporary dewatering throughout foundation and construction phases. The scale of individual projects can necessitate high-capacity pumping systems deployed as part of broader site-management arrangements. Demand is therefore closely linked to project execution schedules and the ability of suppliers, or contractors, to provide equipment for large, time-bound applications.
Latin America Dewatering Pump Market Trends
Latin America has a strong resource-sector component, with mining operations creating demand for dewatering systems across both surface and underground workings. Water accumulation, groundwater inflow, and process-related water management can require pumps capable of handling high volumes and abrasive fluids. Civil construction and infrastructure projects provide a separate source of demand, particularly where temporary water removal is required during excavation. The combination of resource extraction and project-based construction creates demand for both severe-duty and mobile pumping equipment.
The Brazil dewatering pump market is a key demand center in Latin America, driven by mining, infrastructure construction, industrial facilities, and urban development. Mining applications require water removal from pits and underground areas, while construction projects have temporary water removal needs during excavation and foundation work. Urban projects also create opportunities for pumps used in drainage and water-control activities. The coexistence of resource-sector and civil applications offers suppliers opportunities across a range of pump capacities and operating configurations.
Key Companies & Market Share Insights
Some of the key players operating in the market include Xylem Inc. and Grundfos Holding A/S.
-
Xylem Inc. is an Italy-based manufacturer specializing in machinery and automated systems for reinforcement steel processing. Its portfolio includes equipment for rebar cutting, bending, straightening, stirrup forming, and bar shaping, as well as systems for reinforcement mesh and cage production. The company also provides automated and robotic processing solutions that support continuous and high-volume rebar fabrication, positioning it across multiple stages of reinforcement steel processing.
-
Grundfos Holding A/S is a Germany-based manufacturer specializing in reinforcement steel processing machinery. Its portfolio covers rebar cutting, bending, stirrup forming, coil straightening, and reinforcement mesh processing, as well as equipment for automated rebar fabrication. The company offers both individual processing machines and integrated systems, addressing requirements across rebar bending operations and higher-volume reinforcement fabrication facilities.
Key Dewatering Pump Companies
The following key companies have been profiled for this study of the dewatering pumps market.
-
Xylem Inc.
-
Grundfos Holding A/S
-
Atlas Copco AB
-
Tsurumi Manufacturing Co., Ltd.
-
The Gorman-Rupp Company
-
The Weir Group PLC
-
KSB SE & Co. KGaA
-
Sulzer Ltd.
-
EBARA Corporation
-
Thompson Pump
-
Flowserve Corporation
-
WILO SE
-
Franklin Electric Co., Inc.
-
Cornell Pump Company
-
Wacker Neuson SE
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Xylem Inc.; Grundfos Holding A/S; Atlas Copco AB; Tsurumi Manufacturing Co., Ltd.; The Gorman-Rupp Company; The Weir Group PLC; KSB SE & Co. KGaA)
- Maintain broad portfolios covering submersible, centrifugal, self-priming, and high-head dewatering pumps.
- Invest in energy-efficient designs, automated controls, remote monitoring, and solutions for high-solids and abrasive water.
- Extensive product coverage supports diverse flow, head, depth, and site requirements.
- Established distribution, technical expertise, and service infrastructure strengthen support for large construction, mining, and infrastructure projects.
- Advanced systems may involve higher upfront and lifecycle costs.
- Specialized equipment can require greater technical expertise for installation and maintenance.
Emerging & Regional Players (e.g., Sulzer Ltd.; EBARA Corporation; Thompson Pump; Flowserve Corporation; WILO SE; Franklin Electric Co., Inc.; Cornell Pump Company; Wacker Neuson SE)
- Focus on selected pump configurations, portable units, and application-specific dewatering equipment.
- Compete through localized distribution, competitive pricing, faster equipment availability, and responsive field service.
- Flexible product configurations allow suppliers to address specific site and pumping requirements.
- Regional presence can provide faster service and support for construction, municipal, and industrial projects.
- Limited product breadth may limit participation in complex projects that require multiple pump types.
- Smaller geographic networks can constrain service coverage for large multi-location operations.
Recent Developments
-
In May 2025, Atlas Copco launched the new WEDA+ range of electric submersible dewatering pumps, comprising five models across normal-, high-, and super-high-head configurations. The redesigned pumps deliver up to 20% lower overall power consumption than previous models, with flow rates of 1,020-2,425 liters/minute and maximum heads of up to 69 meters. The range also incorporates rotation control, phase-failure protection, improved corrosion resistance, and simplified maintenance, strengthening Atlas Copco's offering for demanding construction and dewatering applications.
-
In February 2025, Franklin Electric acquired Australian-based PumpEng Pty Ltd., a manufacturer of submersible pumps focused on the mining sector. PumpEng offers a dedicated portfolio of dewatering pumps under the JetGuard, Guardian, and Raptor brands, with products assembled in Australia at certified manufacturing facilities. The acquisition strengthens Franklin Electric’s position in mining dewatering by combining PumpEng’s application expertise and Australian presence with Franklin Electric’s global water-systems capabilities.
Dewatering Pump Report Scope
Report Attribute
Details
Market size in 2025
USD 8.5 billion
Estimated market size in 2026
USD 8.8 billion
Projected market size by 2033
USD 12.2 billion
Growth rate
CAGR of 4.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Drive type, pump type, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; Italy; Spain; France; China; Japan; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Xylem Inc.; Grundfos Holding A/S; Atlas Copco AB.; Tsurumi Manufacturing Co., Ltd.; The Gorman-Rupp Company; The Weir Group PLC; KSB SE & Co. KGaA; Sulzer Ltd.; EBARA Corporation; Thompson Pump; Flowserve Corporation; WILO SE; Franklin Electric Co., Inc.; Cornell Pump Company; Wacker Neuson SE
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dewatering Pump Market Report Segmentation
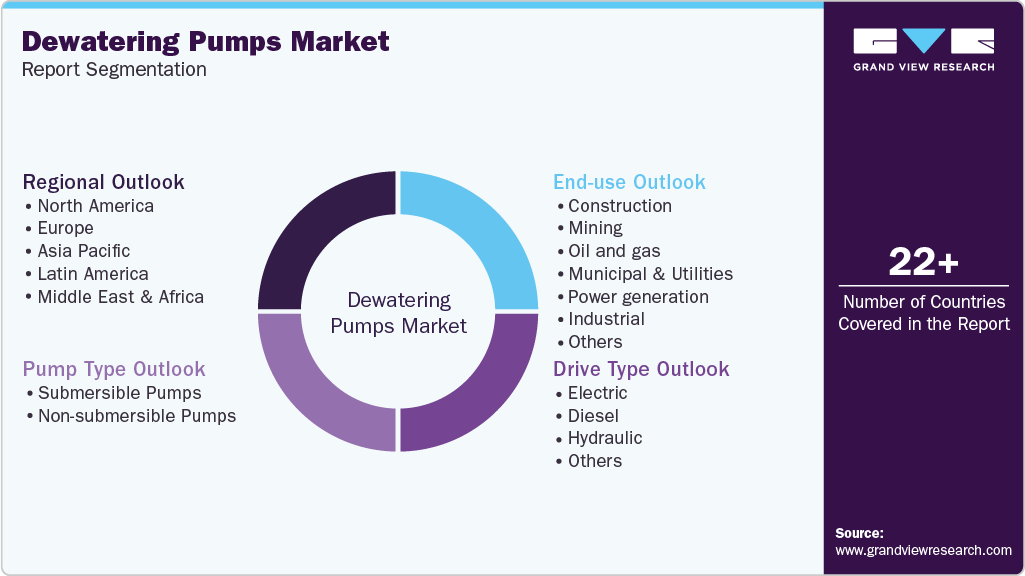
This report forecasts revenue growth at the global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global dewatering pumps market report based on drive type, pump type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Drive Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Electric
-
Diesel
-
Hydraulic
-
Others
-
-
Pump Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Submersible Pumps
-
Non-submersible Pumps
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Construction
-
Mining
-
Oil and gas
-
Municipal & Utilities
-
Power generation
-
Industrial
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The dewatering pump market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dewatering pump segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Drive Type
Revenue Capture Definition
Electric
Revenue generated from dewatering pumps powered by electric motors for water removal across construction, mining, industrial, municipal, and other applications.
Diesel
Revenue generated from dewatering pumps driven by diesel engines, primarily for applications requiring independent operation or deployment at sites with limited access to grid electricity.
Hydraulic
Revenue generated from dewatering pumps powered through hydraulic drive systems for applications requiring compatibility with hydraulic power sources and equipment.
Others
Revenue generated from dewatering pumps using drive configurations other than electric, diesel, or hydraulic systems.
Pump Type
Revenue Capture Definition
Submersible Pumps
Revenue generated from dewatering pumps designed to operate while submerged in the water or fluid being removed, including associated pump units sold for construction, mining, and other applications.
Non-submersible Pumps
Revenue generated from dewatering pumps installed outside the water source and used to transfer or remove accumulated water through suction and discharge arrangements.
End Use
Revenue Capture Definition
Construction
Revenue generated from dewatering pumps sold for construction activities, including excavation, foundation work, tunneling, infrastructure development, and site water removal.
Mining
Revenue generated from dewatering pumps sold for surface and underground mining operations to remove groundwater, seepage, and accumulated water from mine workings.
Oil & Gas
Revenue generated from dewatering pumps sold for water removal and fluid-handling requirements associated with oil and gas production, processing, and related field operations.
Municipal & Utilities
Revenue generated from dewatering pumps supplied for municipal drainage, wastewater infrastructure, flood management, utility projects, and related water-removal requirements.
Power Generation
Revenue generated from dewatering pumps used for water removal and drainage requirements at power generation facilities and associated infrastructure.
Industrial
Revenue generated from dewatering pumps sold for water removal and drainage applications across manufacturing, processing, chemical, and other industrial facilities.
Others
Revenue generated from dewatering pumps supplied to end-use applications not specifically classified under construction, mining, oil & gas, municipal & utilities, power generation, or industrial sectors.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Water Removal Demand Layer
What creates the fundamental need for dewatering pumps?
Analyze construction, mining, tunneling, infrastructure, municipal, industrial, oil & gas, and power generation activities that generate groundwater, seepage, stormwater, or accumulated water. Assess excavation conditions, project scale, mine depth, and site water conditions to establish the underlying requirement for mechanical water removal.
02
Dewatering Application Layer
Where and under what conditions are pumps required?
Evaluate the specific environments in which dewatering pumps are deployed, including excavations, foundations, tunnels, underground mines, open-pit mines, drainage areas, and industrial sites. Examine pumping depth, required flow, discharge head, operating duration, water quality, and solids content to determine equipment requirements across applications.
03
Pump Configuration & Technology Layer
Which pump configurations meet application requirements?
Assess adoption of submersible and non-submersible pumps across electric, diesel, hydraulic, and other drive types. Compare configurations based on portability, solids-handling capability, energy consumption, pumping capacity, installation requirements, and operating conditions. Evaluate adoption of energy-efficient designs, automated controls, remote monitoring, and other pump-level technologies.
04
Revenue Conversion Layer
How does equipment demand translate into market revenue?
Estimate annual dewatering pump shipments by pump type, drive type, end use, and geography. Apply pump-specific pricing benchmarks to shipment volumes to calculate market revenue. Account for new equipment purchases, replacement demand, project expansions, fleet additions, and upgrades to existing pumping equipment.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Leading dewatering pump manufacturers were compared across pump configurations, drive systems, pumping capacity, solids-handling performance, energy consumption, product durability, automation, monitoring capabilities, distribution reach, and aftermarket support. The assessment also considered differences in product specialization and application coverage.
Provides a clear view of competitor capabilities, product positioning, technical differentiation, and areas where portfolio expansion or service enhancement may strengthen market presence.
Regional Segmentation
Regional markets were analyzed based on construction and mining activity, tunneling and infrastructure development, municipal drainage projects, industrial operations, site water conditions, and equipment replacement requirements. Differences in pump selection, deployment conditions, and purchasing patterns were also evaluated.
Helps clients identify regional demand characteristics, assess geographic expansion opportunities, and align product offerings with local project and operating requirements.
Opportunity Assessment
Growth opportunities were evaluated across pump types, drive configurations, and end-use industries by examining new project installations, replacement of aging equipment, rental demand, fleet expansion, and requirements for high-flow, high-head, portable, and solids-handling pumps.
Helps clients prioritize commercially relevant applications, identify underserved product requirements, and direct product development, market expansion, and investment toward areas with stronger demand potential.
Frequently Asked Questions About This Report
The global dewatering pumps market is projected to grow at a CAGR of 4.7% from 2026 to 2033, reaching USD 12.2 billion by 2033.
Key factors include increasing construction and infrastructure activity, growing use of prefabricated reinforcement, demand for precise bar processing, expansion of organized rebar fabrication facilities, and increasing adoption of automated and CNC-based equipment.
Asia Pacific dominated the global dewatering pumps market with a revenue share of 36.0% in 2025, supported by extensive construction activity, a large reinforcement steel processing base, and increasing adoption of mechanized rebar fabrication.
China led the Asia Pacific dewatering pumps market in 2025, reflecting its extensive construction and infrastructure base, substantial reinforcement steel processing activity, and established manufacturing ecosystem for construction and metalworking machinery.
The hydraulic segment is projected to register the fastest CAGR during the forecast period.
The automatic/CNC segment dominated the market in 2025, accounting for a 58.9% revenue share. Its position reflects the growing use of programmable equipment offering controlled processing, repeatable output, and greater flexibility in handling different reinforcement configurations.
The construction & engineering contractors segment held the largest revenue share in 2025, supported by its extensive use of dewatering pumps market across building, infrastructure, and civil engineering projects requiring project-specific reinforcement preparation.
Key players include Xylem Inc., Grundfos Holding A/S, Atlas Copco AB, Tsurumi Manufacturing Co., Ltd., The Gorman-Rupp Company, The Weir Group PLC, KSB SE & Co. KGaA, Sulzer Ltd., EBARA Corporation, Thompson Pump, Flowserve Corporation, WILO SE, Franklin Electric Co., Inc., Cornell Pump Company, and Wacker Neuson SE
The global dewatering pumps market size was valued at USD 8.5 billion in 2025 and is projected to reach USD 8.8 billion in 2026.
About the Author(s)
Bulk Chemicals Research Team
Research · Bulk ChemicalsThis report was authored by the bulk chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the bulk chemicals segment of the research industry. All findings are based on proprietary research databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


