
- Home
- »
- Medical Devices
- »
-
Diabetic Foot Ulcer Biologics Market Size Report, 2026-2033GVR Report cover

Diabetic Foot Ulcer Biologics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Skin Substitutes, Growth Factors), By Indication (Neuro-ischemic Ulcers, Neuropathic Diabetic Foot Ulcer), By End-use (Hospitals, Clinics), By Region, And Segment Forecasts
Market Size, 2025
$2.1BMarket Estimate, 2026
$2.3BMarket Forecast, 2033
$3.8BCAGR, 2026–2033
7.6%Diabetic Foot Ulcer Biologics Market Trends
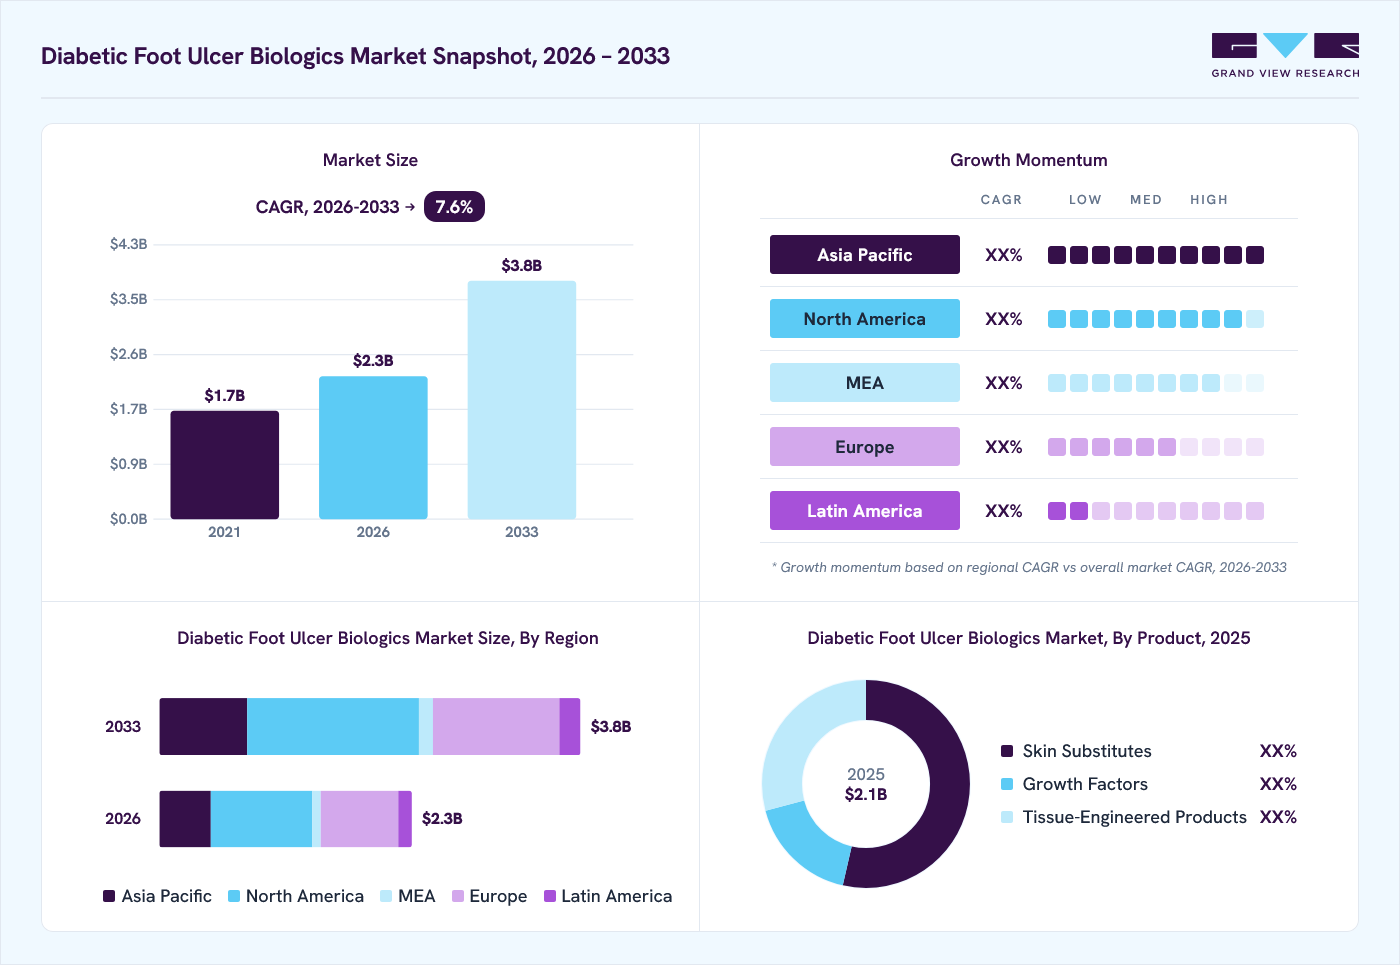
The global diabetic foot ulcer biologics market size was valued at USD 2.1 billion in 2025 and is projected to grow from USD 2.3 billion in 2026 to USD 3.8 billion by 2033, at a CAGR of 7.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.1% in 2025. The demand for diabetic foot ulcer biologics products is rising owing to the growing number of Diabetic Foot Ulcer (DFU) cases and the technological advancements in biologics to treat the disease. Moreover, the rising geriatric population, which is more prone to such infections, significantly contributes to market growth. For instance, a study published in the Journal of Diabetes Research in December 2024 found that most patients with DFUs were in the 50-to-59 age group, while the majority of deaths occurred in the 70-to-79 age group.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Skin substitutes segment led the market with the largest revenue share of 53.5% in 2025.
- By indication: Neuro-ischemic ulcers segment led the market with the largest revenue share of 53.2% in 2025.
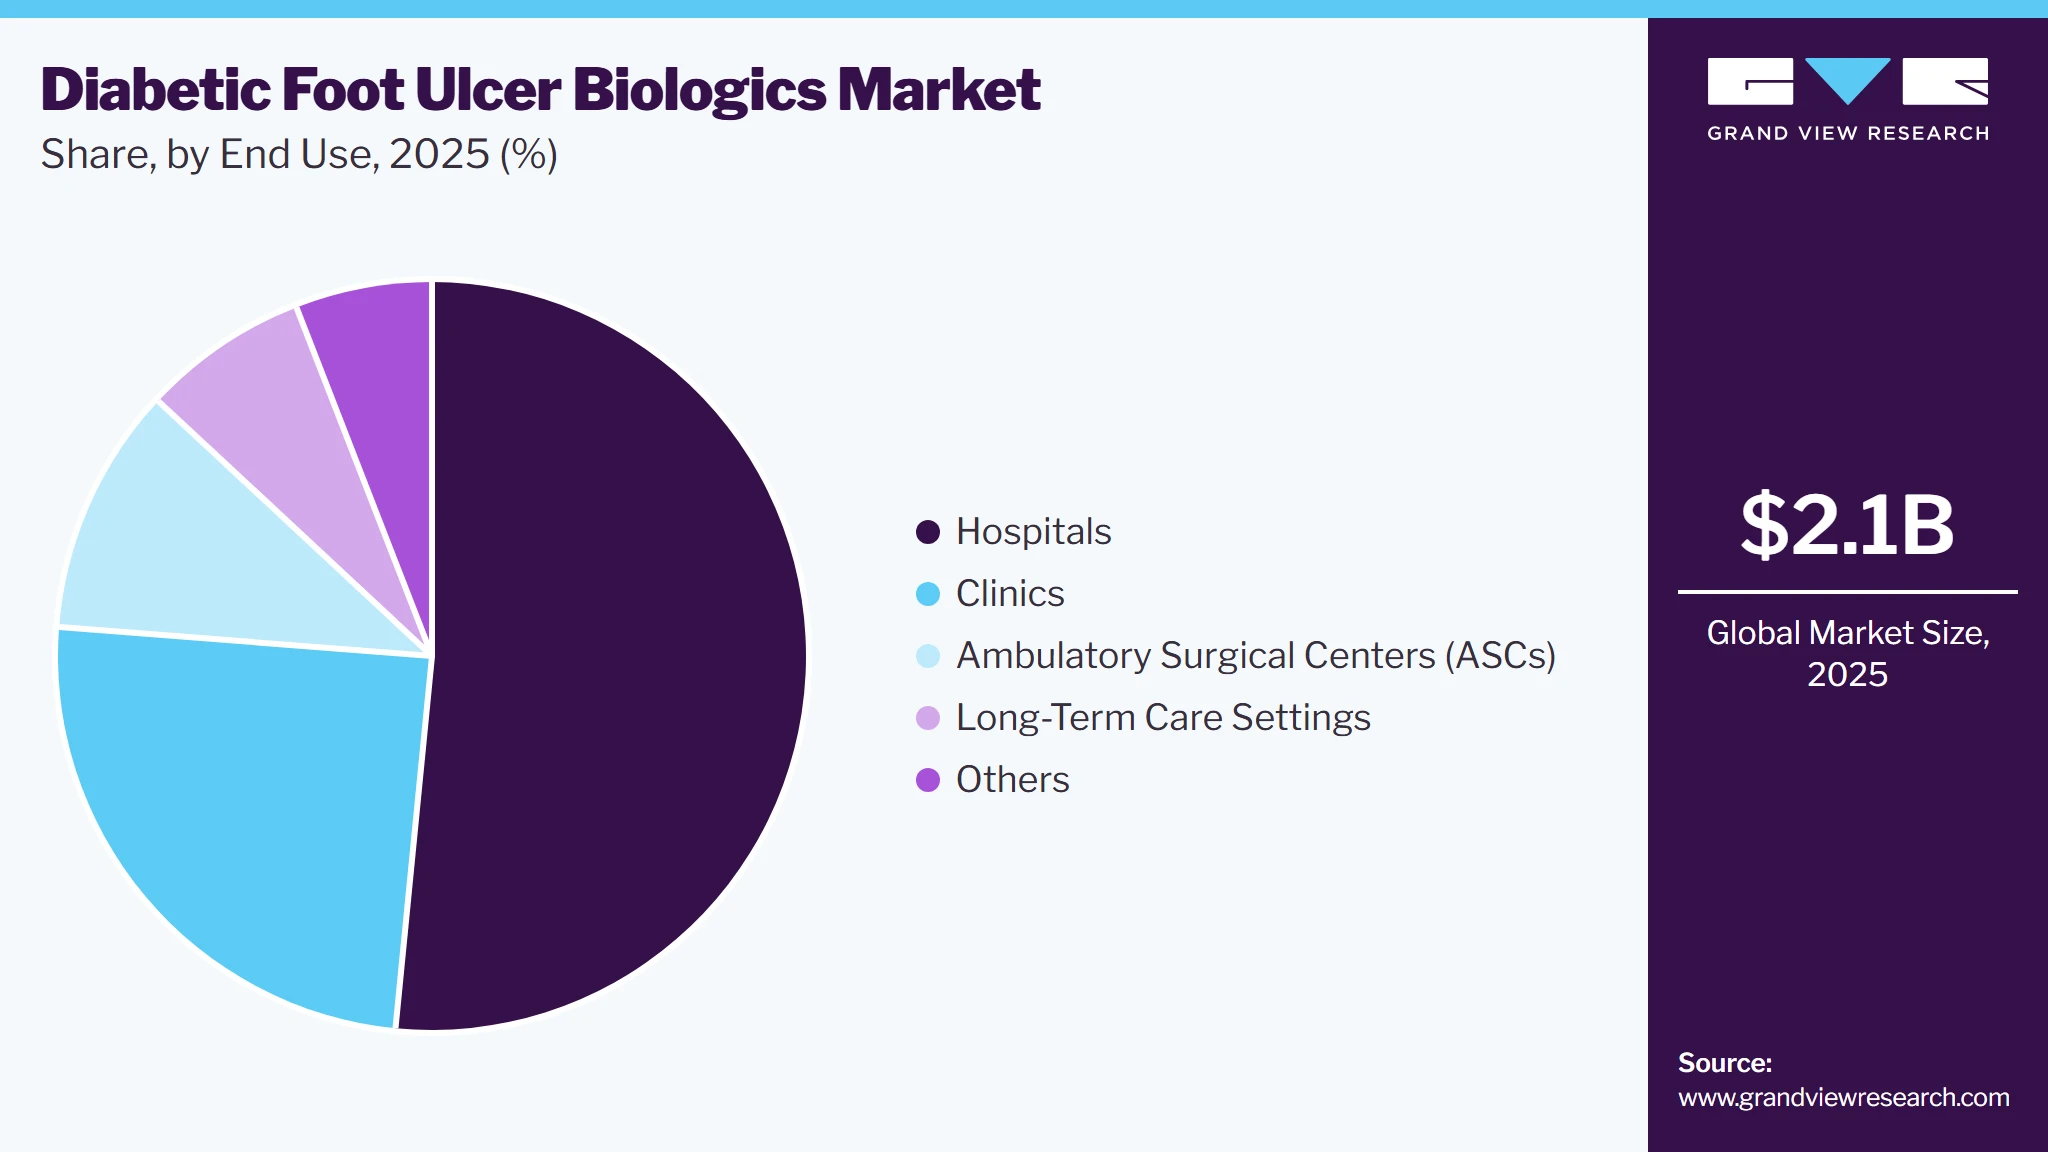
- By end use: Hospital segment led the market with the largest revenue share of 51.6% in 2025.
Regional Highlights
- Largest regional market: North America (40.1% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.1 Billion
- Estimated market size in 2026: USD 2.3 Billion
- Projected market size by 2033: USD 3.8 Billion
- CAGR (2026-2033): 7.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
A study published by Springer Nature Limited in January 2024 found that approximately 25% of individuals with diabetes will develop a diabetic foot ulcer at some point in their lives. The study also reported that the yearly incidence of DFUs worldwide ranges from 1.9 million to 26.1 million cases. In addition, the International Diabetes Federation reported that in 2021, around 10.7% of individuals aged 20 to 79 in the U.S. had diabetes, with this figure projected to rise to 12.1% by 2033 and 12.9% by 2045. As a result, the growing prevalence of diabetes in the U.S. is expected to increase the prevalence of diabetic foot ulcers. Biologics like NovoSorb BTM are available to treat diabetic foot ulcers. Thus, the increasing prevalence of diabetes and diabetic foot ulcers is anticipated to boost market growth over the forecast period.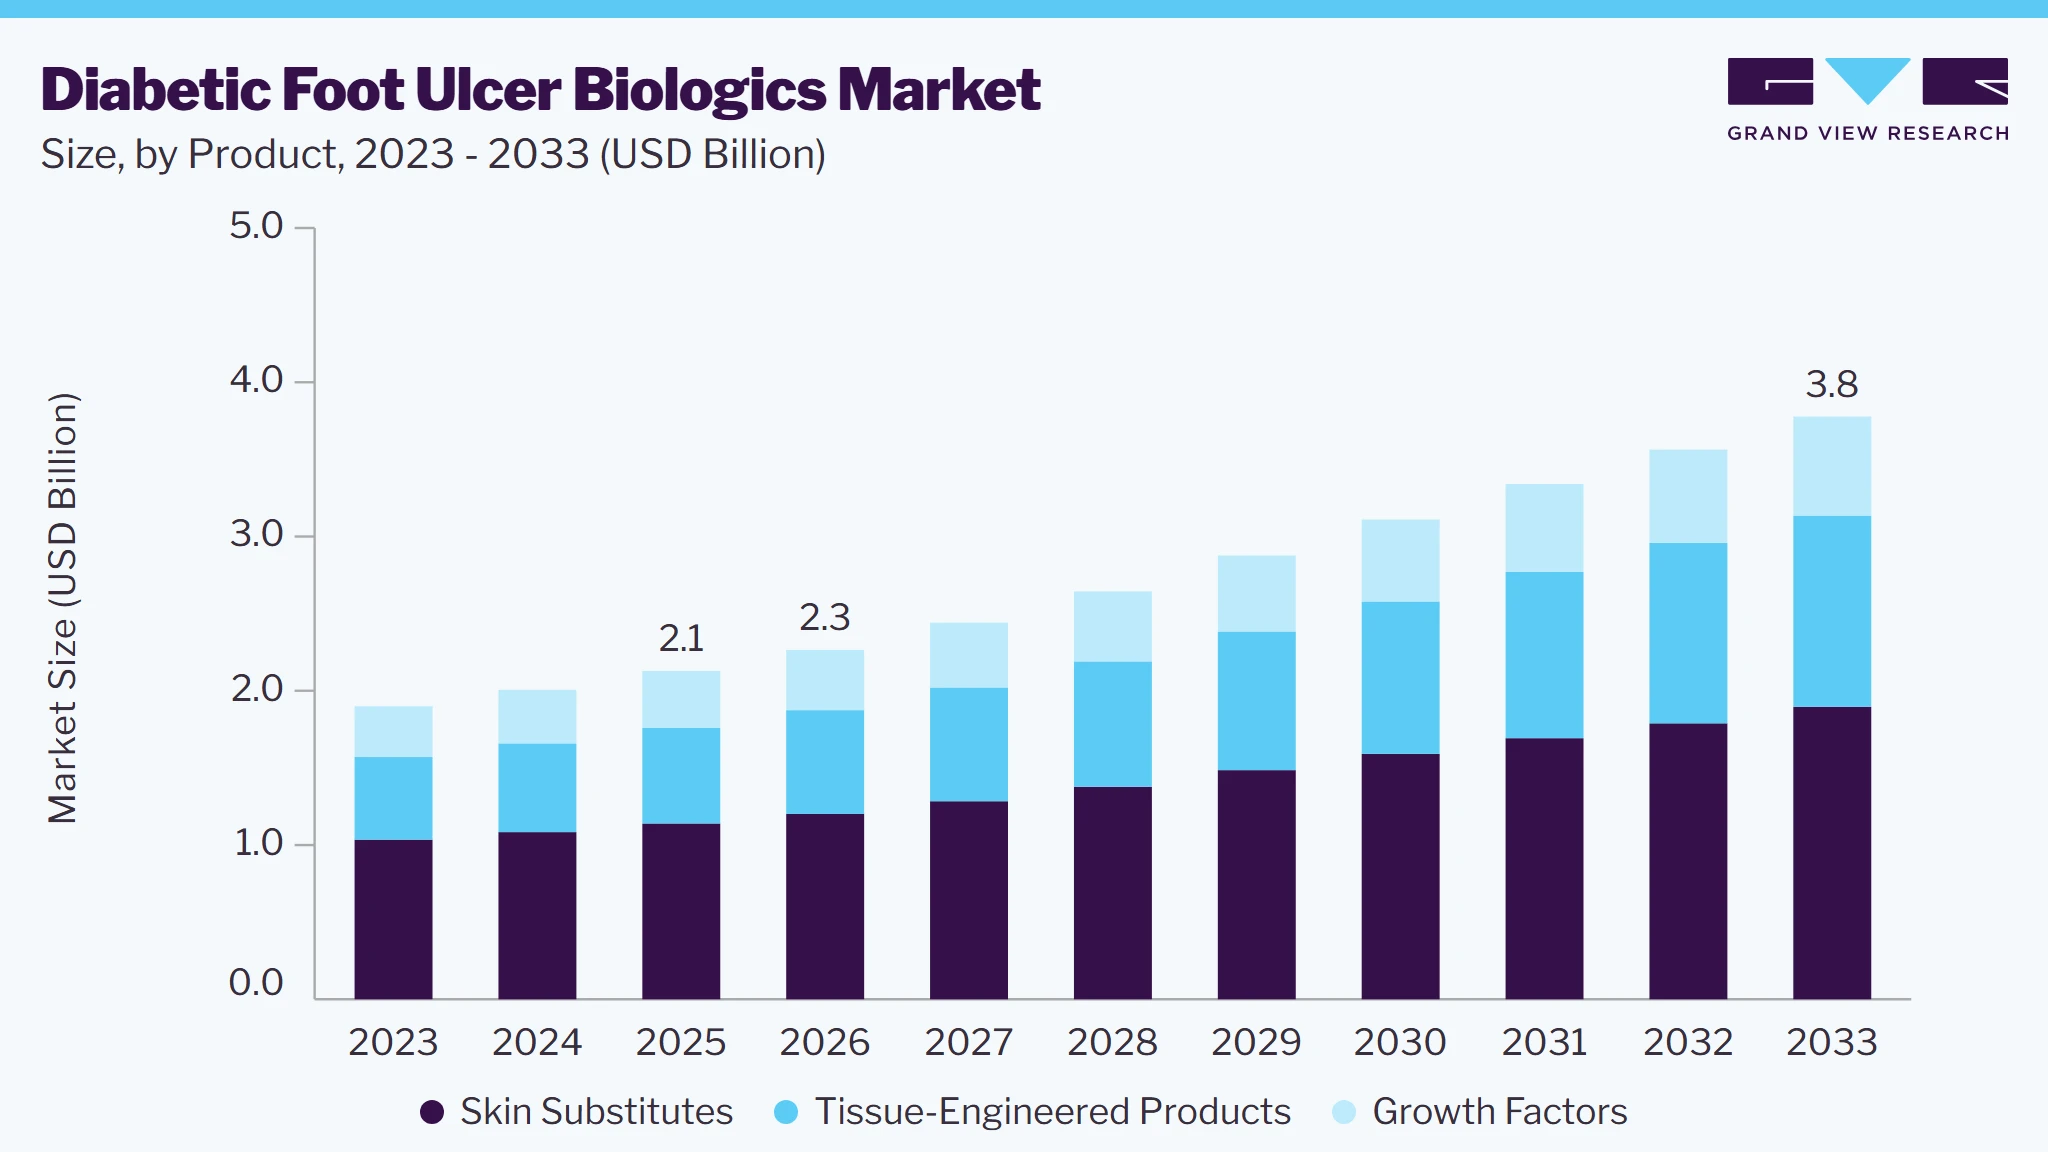 To learn more about this report, Download Free Sample Report
Technological advancements in biologics enhance the healing outcomes for patients suffering from diabetic foot ulcers. These advancements include a rising focus on bioengineered skin substitutes, 3D bioprinting, and the development of innovative biologics. In addition, numerous researchers are focusing on developing novel skin substitutes for managing chronic wounds such as diabetic foot ulcers. For instance, in May 2024, as per the article published by the European Patent Organization, Icelandic inventor Fertram Sigurjonsson & his team designed an innovative skin substitute utilizing fish skin, which offers numerous advantages over other wound-healing products. Fish skin can serve as a skin substitute and has been shown to aid in healing wounds, particularly those caused by diabetes, which can often lead to amputations. Such developments of advanced products are anticipated to drive market growth in the coming decade.
In addition, integrating 3D bioprinting technology into the development of biologics has been transformative. Several studies have evaluated the effectiveness of 3D bioprinted biologics in treating diabetic foot ulcers. For example, a study published by the National Library of Medicine in January 2023 examined the efficacy of 3D-bioprinted autologous minimally manipulated homologous adipose tissue (3D-AMHAT) on DFUs. This was a single-arm pilot study conducted at a tertiary hospital specializing in diabetic wound care. A total of 10 patients with DFUs were enrolled in the study. The findings indicated that 3D-AMHAT, combined with fibrin glue as a biodegradable scaffold, significantly enhanced the healing rates of chronic wounds in the lower extremities of patients with diabetes mellitus. As a result, these positive outcomes from clinical studies are expected to lead to the introduction of new 3D bioprinted biologics in the industry.
Market Dynamics
The diabetic foot ulcer biologics market is driven by the growing prevalence of diabetes, the increasing incidence of chronic wounds, and the rising demand for advanced wound-healing therapies. Adoption of biologic products such as skin substitutes, growth factors, and tissue-engineered solutions is increasing due to their ability to accelerate healing and reduce amputation risk. However, high treatment costs and reimbursement limitations continue to challenge broader market penetration. Ongoing innovations in regenerative medicine and expanding clinical evidence are expected to create significant growth opportunities for market participants.
The increasing prevalence of diabetes worldwide is a major factor driving demand for diabetic foot ulcer (DFU) biologics, as diabetic patients are more susceptible to chronic wounds and impaired healing. According to the International Diabetes Federation (IDF) Diabetes Atlas 11th Edition, approximately 589 million adults were living with diabetes in 2024, and this number is projected to reach 853 million by 2050. As the diabetic population continues to expand, the incidence of DFUs and related complications is expected to rise, increasing the adoption of advanced biologic therapies such as skin substitutes, growth factors, and tissue-engineered products for effective wound management and amputation prevention.
Stringent reimbursement reforms and cost-containment initiatives are emerging as key restraints in the diabetic foot ulcer biologics market. CMS reported that Medicare spending on skin substitutes surged from USD 256 million in 2019 to over USD 10 billion in 2024, prompting the agency to revise reimbursement policies and implement measures to reduce spending by nearly 90%. These changes are expected to increase pricing pressure on biologic manufacturers, limit the adoption of high-cost products, and create challenges for companies that lack strong clinical and economic evidence to support their therapies.
High Cost of Biologic Therapies
The high cost of biologic therapies remains a significant restraint in the diabetic foot ulcer biologics market, as advanced products such as skin substitutes, tissue-engineered grafts, and growth factor-based treatments are substantially more expensive than conventional wound care options. These elevated costs can limit patient access and place financial pressure on healthcare providers, particularly in developing regions and cost-sensitive healthcare systems. Inadequate reimbursement coverage for certain biologic products further restricts adoption, despite their potential to improve healing outcomes and reduce long-term complication rates.
Advancements in regenerative medicine and tissue engineering are creating significant opportunities in the diabetic foot ulcer biologics market by enabling the development of innovative therapies that enhance tissue repair, accelerate wound closure, and improve long-term healing outcomes. Emerging technologies such as bioengineered skin substitutes, stem cell-based therapies, extracellular matrix products, and regenerative tissue constructs are expanding treatment options for chronic and non-healing diabetic wounds. For instance, inFebruary 2025, the U.S. FDA granted Breakthrough Therapy Designation (BTD) to SkinTE, an autologous heterogeneous skin construct developed by PolarityTE, for the treatment of Wagner Grade 1 diabetic foot ulcers. The designation highlights SkinTE’s potential to regenerate functional skin tissue and accelerate wound healing by activating and repairing tissues surrounding chronic diabetic wounds.
“This designation underscores the unmet medical need for patients with DFUs, the potential therapeutic significance of SkinTE, as well as potentially facilitating timely access to patients,” Nik Sopko, chief operating officer and chief scientific officer of PolarityBio, said in a news release.
“Our ongoing COVER DFUS II Phase [3] Pivotal Trial evaluating the safety and efficacy of SkinTE to treat Wagner 1 DFUs is over 75% enrolled and we anticipate final results in Q1 2026, which will help us further understand the role SkinTE can play in treating this serious condition,” Sopko said in a news release.
Market Concentration & Characteristics
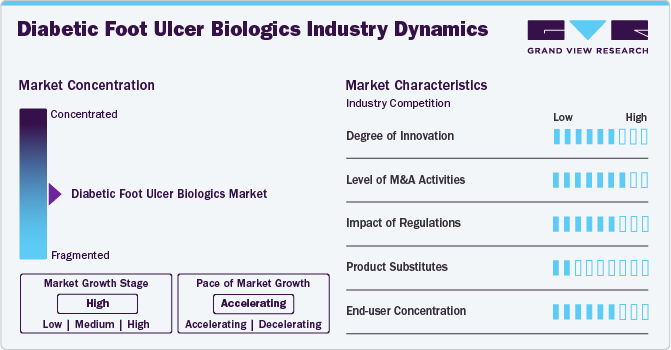
The market growth stage is high, and the pace of growth is accelerating. The diabetic foot ulcer biologics market is characterized by growth owing to the rising number of diabetic patients and robust advancements through clinical trials and strategic initiatives by industry players.
The diabetic foot ulcer biologics market is witnessing high innovation, driven by advancements in regenerative medicine, smart dressings, and exosome-based therapies. For instance, in January 2025, RION, a clinical-stage regenerative medicine company, completed patient enrollment for its Phase 2 trial of the Purified Exosome Product (PEP) for DFUs. PEP utilizes stabilized regenerative exosomes to enhance natural healing by promoting cellular growth and tissue repair, representing a cutting-edge approach to DFU treatment. Such novel biologics are revolutionizing wound healing strategies, offering more effective therapies to improve patient outcomes.
 To learn more about this report, Download Free Sample Report
Regulations play a crucial role in shaping the diabetic foot ulcer biologics market, influencing product development, approvals, and market entry. Stringent regulatory frameworks ensure that biologics meet high safety, efficacy, and quality standards before reaching patients. For instance, compliance with FDA regulations in the U.S., EMA guidelines in Europe, and MDR certification for medical devices can accelerate or delay market access depending on approval timelines.
The diabetic foot ulcer biologics market is experiencing a high level of mergers and acquisitions as companies seek to expand their product portfolios and strengthen market positions. For instance, in March 2024, MIMEDX Group, Inc. entered into an agreement with TELA Bio, Inc. to acquire exclusive rights to a supply and manufacturing deal with Regenity Biosciences. As part of this acquisition, MIMEDX added a 510(k) approved, bovine-derived matrix product designed for managing exudating wounds and controlling minor bleeding. Such strategic acquisitions allow companies to diversify their offerings, enhance wound care capabilities, and accelerate market growth in the DFU biologics sector.
The diabetic foot ulcer biologics market is highly fragmented due to the presence of multiple players offering diverse treatment solutions, including growth factors, skin substitutes, and gene therapies. Established pharmaceutical firms, biotechnology startups, and academic research institutions also contribute to the market's complexity by developing novel biologics with varying mechanisms of action.
The diabetic foot ulcer biologics market is witnessing significant regional expansion, driven by strategic partnerships, regulatory approvals, and increasing healthcare investments. Companies are actively entering new markets through distribution agreements, acquisitions, and collaborations to enhance accessibility to advanced biologics. For instance, Stedical Scientific, Inc. signed a distribution agreement with AVITA Medical, Inc. in January 2024 to market PermeaDerm products in the U.S., underscoring the trend of expanding product reach in high-demand regions. Emerging economies in Asia-Pacific and Latin America are also becoming key focus areas due to rising diabetes prevalence and improving healthcare infrastructure, further fueling regional market growth.
Analyst Perspective
The diabetic foot ulcer biologics market is witnessing strong growth driven by the increasing prevalence of diabetes, the rising burden of chronic wounds, and the growing demand for advanced therapies that promote faster healing and reduce the risk of complications and amputations. Biologic products such as skin substitutes, growth factors, and tissue-engineered therapies are gaining wider acceptance as healthcare providers shift toward regenerative wound care solutions with improved clinical outcomes. Although high treatment costs and reimbursement challenges may limit adoption in certain regions, continuous product innovation, expanding clinical evidence, and increasing investments in regenerative medicine are expected to drive sustained market growth over the forecast period.
Product Insights
Based on product, the skin substitutes segment led the market with the largest revenue share of 53.5% in 2025, in the product segment. The segment is driven by strong clinical evidence supporting their effectiveness in treating DFUs. For instance in October 2024, a study by Ker ecis published in NEJM Evidence, demonstrated that fish-skin grafts significantly outperformed standard care, with higher healing rates at both 16 and 24 weeks. Moreover, wounds treated with intact fish-skin grafts healed approximately two weeks earlier and had a 1.6 times greater chance of closure at any time, highlighting their superior regenerative properties. These positive outcomes are expected to increase the adoption of biological skin substitutes, fueling market growth by offering advanced wound healing solutions for severe DFUs, particularly those with exposed bone and tendons.
The tissue-engineered products segment is expected to grow at the fastest CAGR over the forecast period, especially diabetic foot ulcers, coupled with an increasing demand for innovative wound-healing treatments. Products like Apligraf have shown promising results in treating diabetic foot ulcers. According to Organogenesis Inc., Apligraf was evaluated against saline-moistened gauze, revealing that 56% of diabetic foot ulcers closed by week 12 with Apligraf compared to 38% for saline-moistened gauze. In addition, the median time to wound closure was 65 days for Apligraf versus 90 days against the saline-moistened gauze, indicating that Apligraf closed wounds 25 days faster. These positive outcomes drive the adoption of tissue-engineered products in the market, fueling segment growth.
Indication Insights
Based on indication, the neuro-ischemic ulcers segment led the market with the largest revenue share of 53.2% in 2025. An increasing focus on evaluating different types of biologics, such as skin substitutes and growth factors, for treating neuro ischemic ulcers significantly drives the segment’s growth. For instance, a study published by MDPI in February 2023 highlighted NovoSorb BTM as a safe and accessible option for treating moderate to severe neuro-ischemic ulcers, demonstrating its potential to improve wound healing outcomes. The positive clinical results from such studies are expected to fuel segment growth by increasing adoption of biologic therapies, addressing the challenges of impaired blood flow and nerve damage, and ultimately reducing the risk of severe complications, including amputations.
The ischemic diabetic foot ulcer segment is expected to grow at the fastest CAGR over the forecast period, primarily due to the increasing incidence of peripheral arterial disease among diabetic patients, which plays a major role in developing ischemic ulcers. According to a study published by WebMD LLC in August 2024, approximately 20% to 30% of individuals diagnosed with PAD also have diabetes. In addition, an article published by Omniamed Communications in July 2023 highlights that PAD is two to seven times more common in people with diabetes than in those without the condition, with estimated prevalence rates ranging from 9% to 55% among diabetic patients. Therefore, the increasing burden of PAD and diabetes is expected to drive growth in the ischemic diabetic foot ulcer segment in the coming years.
End-use Insights
Based on end use, the hospital segment led the market with the largest revenue share of 51.6% in 2025. Hospitals play a crucial role in the use of diabetic foot ulcer biologics, and their adoption is expected to drive segment growth in the future. Hospital settings are preferred over other healthcare settings as they provide comprehensive care to patients with complex medical needs. They have the essential medical expertise, infrastructure, and resources to effectively manage and monitor patients' conditions, ensuring optimal treatment outcomes. In addition, they can provide immediate access to advanced medical care in case of any complications or emergencies. These advantages associated with the hospital setting are expected to support segment growth in the coming years.
 To learn more about this report, Download Free Sample Report
Ambulatory surgical centers (ASCs) are expected to grow at the fastest CAGR over the forecast period. This increase can be attributed to several advantages, including cost-effectiveness and shorter recovery times. Additionally, the rising number of these centers and the growing volume of surgical procedures performed in outpatient settings are contributing to the segment's expansion.
Regional Insights
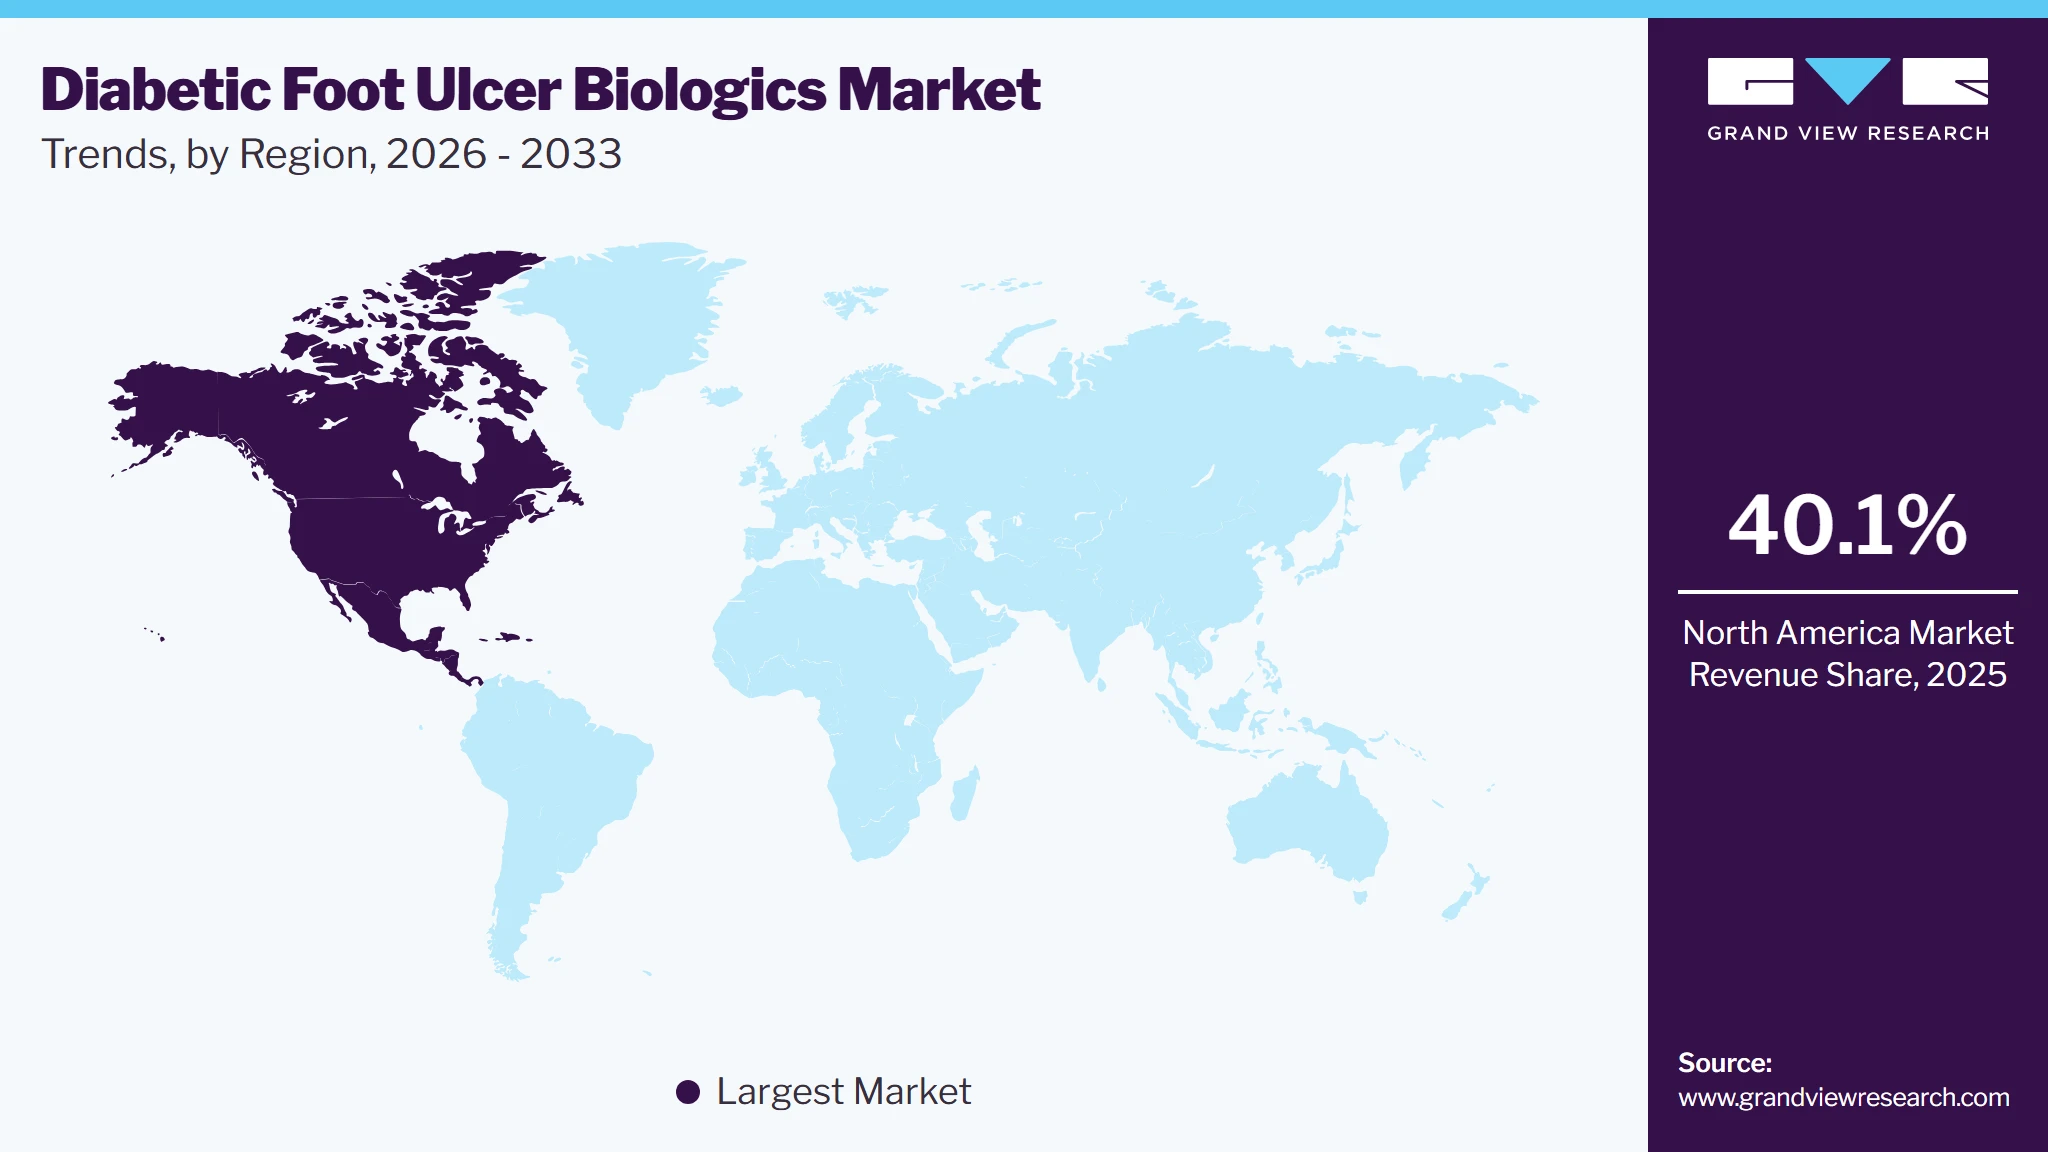
North America dominated the diabetic foot ulcer biologics market with the largest revenue share of 40.1% in 2025. The market is driven by the increasing awareness about the importance of timely and effective wound care, as well as the growing prevalence of chronic diseases such as diabetes, which can lead to diabetic foot ulcers. In addition, North America is home to leading pharmaceutical companies and research institutions that drive innovation in biologic treatments, such as growth factors and tissue-engineered products. For instance, in January 2025, BioStem Technologies announced the launch of the BR-AM-DFU (BioREtain Amniotic Membrane - Diabetic Foot Ulcers) clinical trial, which will assess the effectiveness of Vendaje in treating patients with non-healing diabetic foot ulcers. The innovative study will compare the standard of care treatment with and without Vendaje, with the goal of demonstrating its superiority in advanced wound care. Such studies is anticipated to support the regional market growth.
 To learn more about this report, Download Free Sample Report
U.S. Diabetic Foot Ulcer Biologics Market Trends
The diabetic foot ulcer biologics market in the U.S. held the largest share in the North America region in 2025, due to the increased government support, research funding, and healthcare initiatives to improve diabetes care. The National Institute of Diabetes and Digestive and Kidney Diseases has significantly invested in diabetes-related research, with substantial funding allocations in Alabama (USD 3.9 million), California (USD 32.3 million), Florida (USD 7.8 million), and Indiana (USD 4.3 million) in 2024. These investments are accelerating innovation, clinical research, and the availability of advanced biologic treatments for DFUs, thereby boosting market growth. As healthcare organizations continue to prioritize better DFU management, the demand for effective biologic therapies is expected to rise, leading to improved treatment options and patient outcomes.
Europe Diabetic Foot Ulcer Biologics Market Trends
The diabetic foot ulcer biologics market in Europe is projected to experience significant growth in the coming years, driven by the high prevalence of diabetes. For instance, according to the data reported by the WHO in July 2024, 64 million adults and 300,000 children and adolescents were affected by the disease. This growing patient population is prompting key industry players to invest in research and development to enhance biologic treatments for DFUs and expand their clinical applications. Advancements in wound care biologics, including growth factors, skin substitutes, and stem cell therapies, are improving treatment outcomes and driving market expansion across the region.
UK diabetic foot ulcer biologics market is driven by strategic partnerships, product innovations, and expansion of R&D and manufacturing facilities by key industry players. Companies are actively enhancing their market presence through collaborations, such as PolyNovo Ltd’s acquisition of exclusive distribution and sales rights for SUPRATHEL in May 2024, which expands access to advanced epidermal skin substitutes for wound healing. These partnerships are expected to increase the availability of innovative biologic treatments in the UK, improving DFU management and driving market growth. In addition, the focus on advanced wound care solutions and expanding healthcare infrastructure further supports the adoption of DFU biologics in the region.
The diabetic foot ulcer biologics market in Germany is driven by the rising prevalence of diabetes, which is expected to reach 12 million cases by 2040, according to DZG. With 8.5 million diagnosed and 2 million undiagnosed cases, the growing patient population increases the demand for advanced DFU treatments, including biologic therapies. As type 2 diabetes cases continue to surge, the need for effective wound healing solutions to prevent complications like foot ulcers and amputations is expected to boost market growth in the country.
Asia Pacific Diabetic Foot Ulcer Biologics Market Trends
The Asia Pacific diabetic foot ulcer biologics market is anticipated to witness the fastest growth over the forecast period, driven by the increasing demand for advanced wound care products and the rising prevalence of diabetic foot ulcers. Diabetic foot ulcer biologics, in particular, are gaining popularity due to their ability to promote tissue regeneration, improve wound healing, and reduce the risk of complications. The presence of developing economies, such as China, India, and Japan, is anticipated to boost the market in the region. In addition, technological advancements, an increasing geriatric population, a growing prevalence of chronic wounds, are anticipated to boost the regional diabetic foot ulcer biologics market.
China diabetic foot ulcer biologics market is expected to witness considerable growth over the forecast period due to rising burden of diabetes and increasing cases of chronic wounds. For instance, according to a report by the NIH in August 2024, the incidence of amputation among Chinese patients with diabetic foot ulcers (DFUs) is 22.4%. Moreover, a national survey conducted in 2024 among Chinese school students aged 3 to 18 years estimated that the prevalence of type 2 diabetes was 1.77 per 1,000 individuals during the years 2017 - 2019.
Diabetic foot ulcer biologics market in Japan is growing due to rising geriatric population. According to the data published by SPH Media Limited September 2024, the number of people in Japan aged 65 or older reached a record high of 36.25 million. As the aging population increases, the prevalence of chronic conditions such as diabetes also rises, which in turn leads to a higher incidence of diabetic foot ulcers among older adults. Older individuals often experience a slower healing process, decreased circulation, and higher rates of complications, making them more susceptible to DFUs. This growing demand for effective treatments has led to an increase in the adoption of biologic therapies, which are designed to accelerate wound healing and improve patient outcomes.
Latin America Diabetic Foot Ulcer Biologics Market Trends
The diabetic foot ulcer biologics market in Latin America is driven by affordable advanced treatments and improved healthcare infrastructure, making the region a growing hub for medical tourism. For instance, the availability of cost-effective biologic therapies attracts international patients seeking high-quality DFU treatments at lower prices. Governments are actively investing in healthcare development, and according to a May 2024 report by Fitch Solutions, Inc., Latin America is projected to have the second-highest growth in health expenditure globally from 2024 to 2032, further driving the adoption of innovative DFU biologics in the region.
The diabetic foot ulcer biologics market in Brazil is driven by a strong healthcare infrastructure and the growth of medical tourism, making advanced treatments more accessible. For instance, Brazil has one of the most well-established hospital networks in Latin America, with 7,191 hospitals, of which 62% are privately owned, according to 2023 data from the Brazilian Federation of Hospitals (FBH) and the National Confederation of Health (CNSaúde). This expansive private healthcare sector, combined with affordable advanced DFU treatments, is attracting both local and international patients, further boosting the adoption of biologic therapies in the country.
Middle East and Africa Diabetic Foot Ulcer Biologics Market Trends
Middle East and Africa (MEA) market is expected to grow considerably over the forecast period. The countries with significant growth rate in this region are South Africa, Saudi Arabia, UAE, and Kuwait. Factors that can be attributed to the growth of the MEA diabetic foot ulcer biologics market are the growing geriatric population and the rising prevalence of diabetic foot ulcers. In addition, with increasing government initiatives to develop healthcare infrastructure, the region is expected to witness a rise in the prevalence of diabetes, leading to an increase in demand for DFU biologics for postoperative care.
The diabetic foot ulcer biologics market in Saudi Arabia is anticipated to grow over the forecast period, driven by increasing healthcare demand due to the country’s high prevalence of diabetes. For instance, according to a report by the Journal of Diabetology in December 2024, diabetes has emerged as a significant public health issue in Saudi Arabia, with an estimated prevalence of 18.5% among adults in the country. Saudi Arabia has one of the highest rates of diabetes in the Middle East, which has created a growing need for advanced treatments for diabetic complications, including diabetic foot ulcers.
South Africa diabetic foot ulcer biologics market is driven by the rising prevalence of type 2 diabetes, largely influenced by changing dietary habits. For instance, according to a March 2024 report by the University of Pretoria, around one in nine adults in South Africa-approximately 4.2 million people-are living with diabetes, with numbers increasing due to the consumption of processed foods, sugary drinks, and high-calorie meals. This growing diabetic population is expected to increase the demand for advanced DFU biologic treatments, driving market expansion in the region.
Estimated Prevalence of Diabetes in U.S. states
States
Adults Diagnosed Diabetes
States
Adults Diagnosed Diabetes
Alabama
614,900
Indiana
666,400
Alaska
48,500
Iowa
287,500
Arizona
731,900
Kansas
256,500
Arkansas
367,300
Texas
3,127,800
California
3,520,500
Vermont
44,600
Colorado
377,300
Virginia
870,500
Connecticut
308,800
Washington
595,800
Delaware’
111,800
West Virginia
247,700
District of Columbia
44,100
Wisconsin
477,700
Florida
2,173,400
New York
1,779,200
Georgia
1,017,100
New Jersey
792,400
Hawaii
134,100
New Hampshire
111,300
Idaho
145,700
North Carolina
1,011,800
Illinois
1,185,700
South Carolina
533,300
Source: American Diabetes Association, Grand View Research
As higher diabetes cases lead to increased DFU incidence, complications like chronic wounds and infections are becoming more common among U.S. citizens affected by diabetes, necessitating advanced biologic treatments. The growing aging population and rising obesity rates further contribute to DFU cases, increasing demand for innovative wound care solutions. As a result, biologics such as growth factors, skin substitutes, and cell-based therapies are gaining traction, offering improved healing outcomes and reducing amputation risks.
Risk Factors Identified for DFU Development
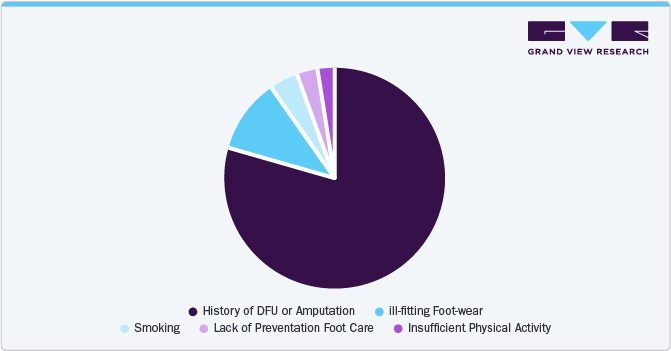
The diabetic foot ulcer biologics market is expanding due to the growing need for advanced wound care solutions, particularly as the prevalence of diabetes continues to rise globally. A recent study conducted in a university hospital in Iran, published in an NLM article in April 2024, followed 901 diabetic patients over two years to assess the incidence of DFU. The study reported a two-year cumulative incidence of 8%, highlighting the ongoing burden of DFUs among diabetic patients.
 To learn more about this report, Download Free Sample Report
Key risk factors identified for DFU development include a history of DFU or amputation (OR = 76.5), ill-fitting footwear (OR = 10.38), smoking (OR = 3.87), lack of preventive foot care (OR = 2.91), and insufficient physical activity (OR = 2.25). These findings underscore the urgent need for effective biologic treatments to promote wound healing and prevent severe complications such as infections and amputations. With advancements in growth factors, skin substitutes, and cell-based therapies, the biologics market is expected to witness significant growth, driven by increasing awareness, early diagnosis, and improved accessibility to innovative DFU treatments.
Key Diabetic Foot Ulcer Biologics Company Insights
Organogenesis Holdings Inc., Tissue Regenix, BioTissue, Integra LifeSciences, MIMEDX Group, Inc., Convatec Inc., Coloplast Group (Kerecis), Biocomposites, Smith+Nephew, Inc., Stedical Scientific, Inc., Zimmer Biomet, GUNZE LIMITED. are some of the major players in the diabetic foot ulcer biologics market. Companies are expanding their portfolios of diabetic foot ulcer biologics to gain a competitive advantage in the coming years. Moreover, industry players are also launching new products to meet the growing demand for biologics in treating diabetic foot ulcers.
Key Diabetic Foot Ulcer Biologics Companies
The following key companies have been profiled for this study on the diabetic foot ulcer biologics market.
-
Organogenesis Holdings Inc.
-
Tissue Regenix
-
BioTissue
-
Integra LifeSciences
-
MIMEDX Group, Inc.
-
Convatec Inc.
-
Coloplast Group (Kerecis)
-
Biocomposites
-
Smith+Nephew, Inc.
-
Stedical Scientific, Inc.
-
Zimmer Biomet
-
GUNZE LIMITED
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Organogenesis Inc., Integra LifeSciences Corporation, Smith + Nephew, Zimmer Biomet, MIMEDX Group, Inc.)
- Focus on expanding product portfolios across skin substitutes, growth factors, and tissue-engineered products.
- Invest heavily in clinical trials to strengthen product efficacy and reimbursement support.
- Strong brand recognition and established customer relationships.
- Extensive clinical data support product effectiveness and safety.
- Higher operational and manufacturing costs.
- Slower adoption of disruptive technologies due to complex organizational structures.
Emerging Players (Tissue Regenix Group, Stedical Scientific, Inc., BioTissue)
- Focus on innovative biologics, regenerative therapies, and next-generation tissue-engineered products.
- Target niche clinical applications and unmet wound care needs.
- Strong innovation capabilities and technological differentiation.
- Greater flexibility in responding to evolving market demands.
- Limited commercial reach and distribution infrastructure.
- Smaller clinical evidence base compared to established players.
Recent Developments
-
In March 2025, Novo Holdings and TA Associates have partnered to jointly invest in Biocomposites, a UK-based medical devices company specializing in bone and soft tissue infection management. This collaboration aims to accelerate Biocomposites' international expansion and product innovation.
-
In January 2025, BioStem Technologies, a MedTech company specializing in placental-derived biologics for advanced wound care, has initiated the BR-AM-DFU clinical trial to evaluate its product, Vendaje, in treating non-healing diabetic foot ulcers. Vendaje is a human placental allograft developed using BioStem's proprietary BioREtain technology. It is designed to support wound healing in chronic, non-healing wounds by providing a natural scaffold that facilitates tissue regeneration.
-
In November 2024, Geistlich Pharma North America, Inc. entered into an exclusive national distribution partnership with StimLabs, a regenerative medicine company based in Roswell, Georgia. StimLabs will immediately oversee all commercial activities for Geistlich's Advanced Wound Matrix, Derma-Gide, in the U.S. The agreement also aligns with recent developments in healthcare coverage. Derma-Gide has been included in the U.S. Centers for Medicare & Medicaid Services' Local Coverage Determination for treating DFUs
Diabetic Foot Ulcer Biologics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.1 billion
Estimated market size in 2026
USD 2.3 billion
Projected market size by 2033
USD 3.8 billion
Growth rate
CAGR of 7.6% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, indication, end-use region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Organogenesis Inc., Tissue Regenix Group, BioTissue, Integra LifeSciences Corporation, MIMEDX Group, Inc., Kerecis (Coloplast Group), Stedical Scientific, Inc. , Zimmer Biomet, GUNZE LIMITED, Smith+Nephew
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Diabetic Foot Ulcer Biologics Market Report Segmentation
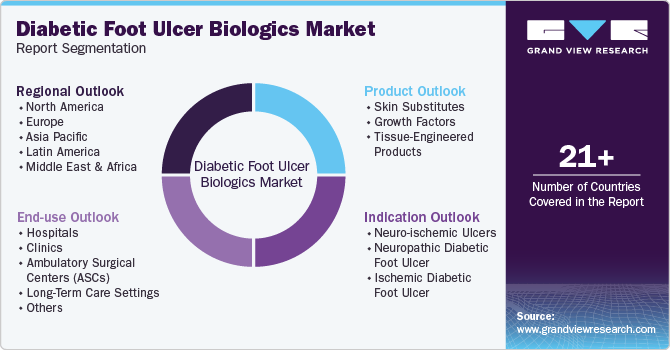
This report forecasts revenue growth at global, regional, and country levels and provides an analysis on the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global diabetic foot ulcer biologics market report based on product, indication, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Skin Substitutes
-
Biological
-
Synthetic
-
Bio-Synthetic
-
-
Growth Factors
-
Tissue-Engineered Products
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Neuro-ischemic Ulcers
-
Neuropathic Diabetic Foot Ulcer
-
Ischemic Diabetic Foot Ulcer
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Clinics
-
Ambulatory Surgical Centers (ASCs)
-
Long-Term Care Settings
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The diabetic foot ulcer biologics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each diabetic foot ulcer biologics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Skin Substitutes
Revenue capture includes sales generated from biologically derived and bioengineered skin replacement products used to promote healing and tissue regeneration in diabetic foot ulcers. The segment covers cellular and acellular grafts, tissue matrices, and other advanced skin repair solutions.
Tissue-Engineered Products
Revenue capture includes sales generated from tissue-engineered products designed to stimulate tissue repair, regeneration, and wound closure in diabetic foot ulcers. This segment covers bioengineered cellular constructs, regenerative scaffolds, and advanced biologic therapies used in chronic wound management.
Growth Factors
Revenue capture includes sales generated from growth factor-based biologic therapies used to accelerate diabetic foot ulcers by promoting cell proliferation, angiogenesis, and tissue regeneration. The segment covers topical and injectable formulations used in advanced wound care.
Estimation Model
Layer Name
Key Questions
Description
Bottom-Up Procedure Volume Modeling
How is the addressable patient and procedure volume estimated?
Models total diagnosed diabetes prevalence, active DFU incidence, and the subset of chronic, non-healing wounds failing standard care. Maps biologic treatment adoption rates, average units consumed per patient cycle, and penetration rates across specific ulcer severity grades.
Top-Down Revenue Triangulation
How is the total market revenue validated?
Aggregates supplier-side revenues from leading and emerging advanced wound care and biologic manufacturers (e.g., skin substitutes, placental tissue grafts, growth factors) through corporate financial reports, investor presentations, regulatory disclosures, and distributor-level sales tracking.
Demand-Side Care-Setting Modeling
How is demand distributed across healthcare settings?
Tracks localized purchasing patterns, procurement budgets, and order volumes across key healthcare channels. Segments demand by clinical environment based on patient acuity, treatment protocols, institutional budgets, and specialty physician alignment.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Healthcare Facility Analysis
Developed a granular utilization model assessing DFU biologic demand across Hospitals, Wound Care Centers (WCCs), Ambulatory Surgical Centers (ASCs), and Home Healthcare Settings. Included facility-level purchasing volumes, product rotation cycles, and setting-specific delivery preferences.
Identifies high-volume distribution channels, enables site-of-care targeting strategies, and optimizes field-force allocation between outpatient centers and home health networks.
KOL & Physician Insights
Conducted extensive primary research interviews with podiatrists, vascular surgeons, endocrinologists, and wound care specialists. Mapped explicit treatment preferences, clinical protocols, and quantified specific adoption barriers(e.g., handling complexity, tissue shelf-life, clinical trial data requirements).
Provides a direct understanding of clinician mindshare, flags hidden hurdles to technology adoption, and informs targeted clinical marketing and product development strategies.
Country-Level Market Assessment
Delivered country-level market sizes and forecasts integrated with regional epidemiology metrics (diabetes prevalence, DFU incidence, and amputation rates). Evaluated local healthcare expenditures and mapped the nuanced reimbursement landscape (graft size restrictions, bundled payment impacts).
Mitigates regulatory and financial risk by pinpointing regions with the most favorable reimbursement pathways, allowing for optimized market entry and localized pricing models.
Frequently Asked Questions About This Report
North America dominated the diabetic foot ulcer biologics market with the largest revenue share of 40.1% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The skin substitutes segment led the market with the largest revenue share of 53.5% in 2025.
The neuro-ischemic ulcers segment led the market with the largest revenue share of 53.2% in 2025.
The global diabetic foot ulcer biologics market size was valued at USD 2.1 billion in 2025 and is expected to reach USD 2.3 billion in 2026.
The global diabetic foot ulcer biologics market is expected to grow at a compound annual growth rate of 7.6% from 2026 to 2033 to reach USD 3.8 billion by 2033.
Some of the key players operating in the diabetic foot ulcer biologics market include Organogenesis Inc., Tissue Regenix Group, BioTissue, Integra LifeSciences Corporation, MIMEDX Group, Inc., Kerecis (Coloplast Group), Stedical Scientific, Inc. , Zimmer Biomet, GUNZE LIMITED, Smith+Nephew.
The hospital segment led the market with the largest revenue share of 51.6% in 2025.
The demand for diabetic foot ulcer biologics products is rising owing to the growing number of Diabetic Foot Ulcer (DFU) cases and the technological advancements in biologics to treat the disease.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


