
- Home
- »
- Medical Devices
- »
-
Dura Substitutes Market Size, Share & Trends Report, 2033GVR Report cover

Dura Substitutes Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Biological Dura Substitutes, Synthetic Dura Substitutes), By Region (North America, Europe, APAC, Latin America, Middle East And Africa), And Segment Forecasts
Market Size, 2025
$240.7MMarket Estimate, 2026
$251.8MMarket Forecast, 2033
$360.7MCAGR, 2026–2033
5.3%Dura Substitutes Market Summary
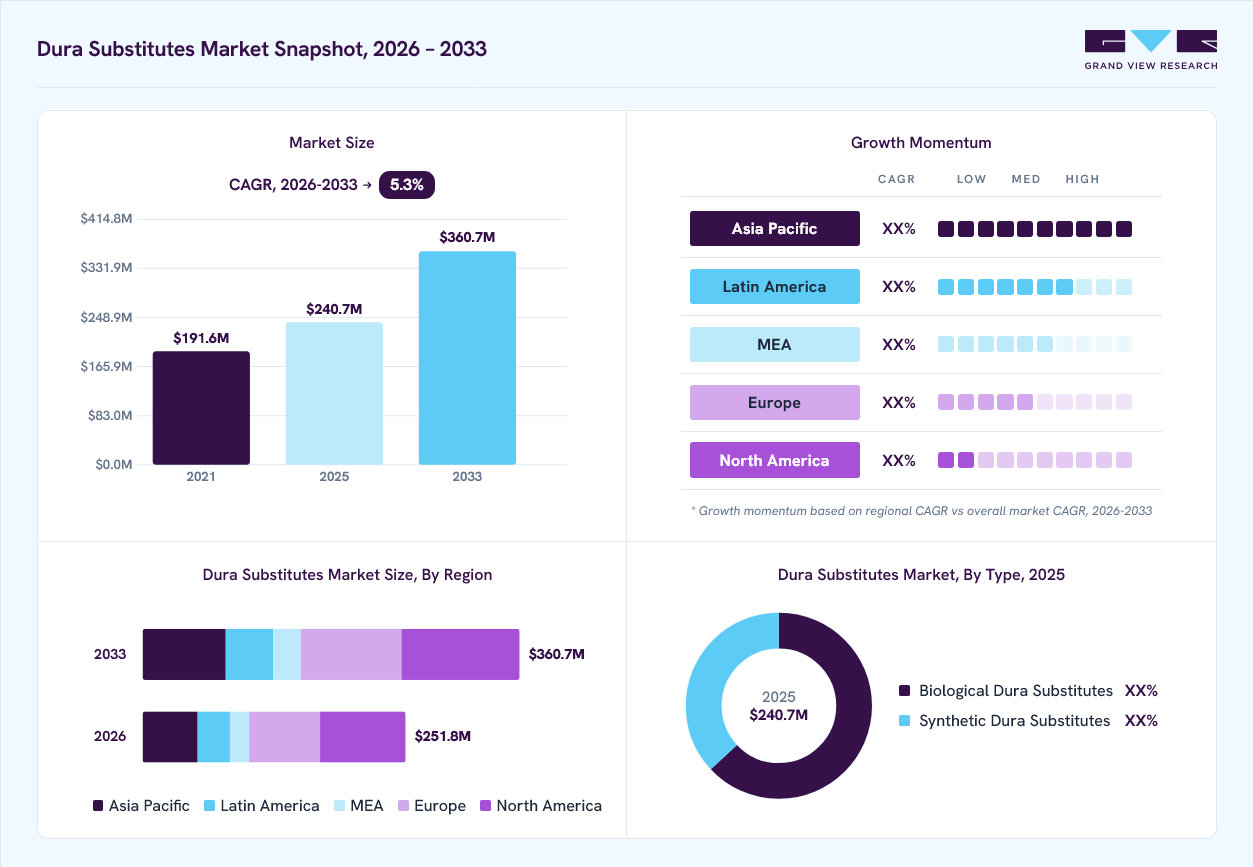
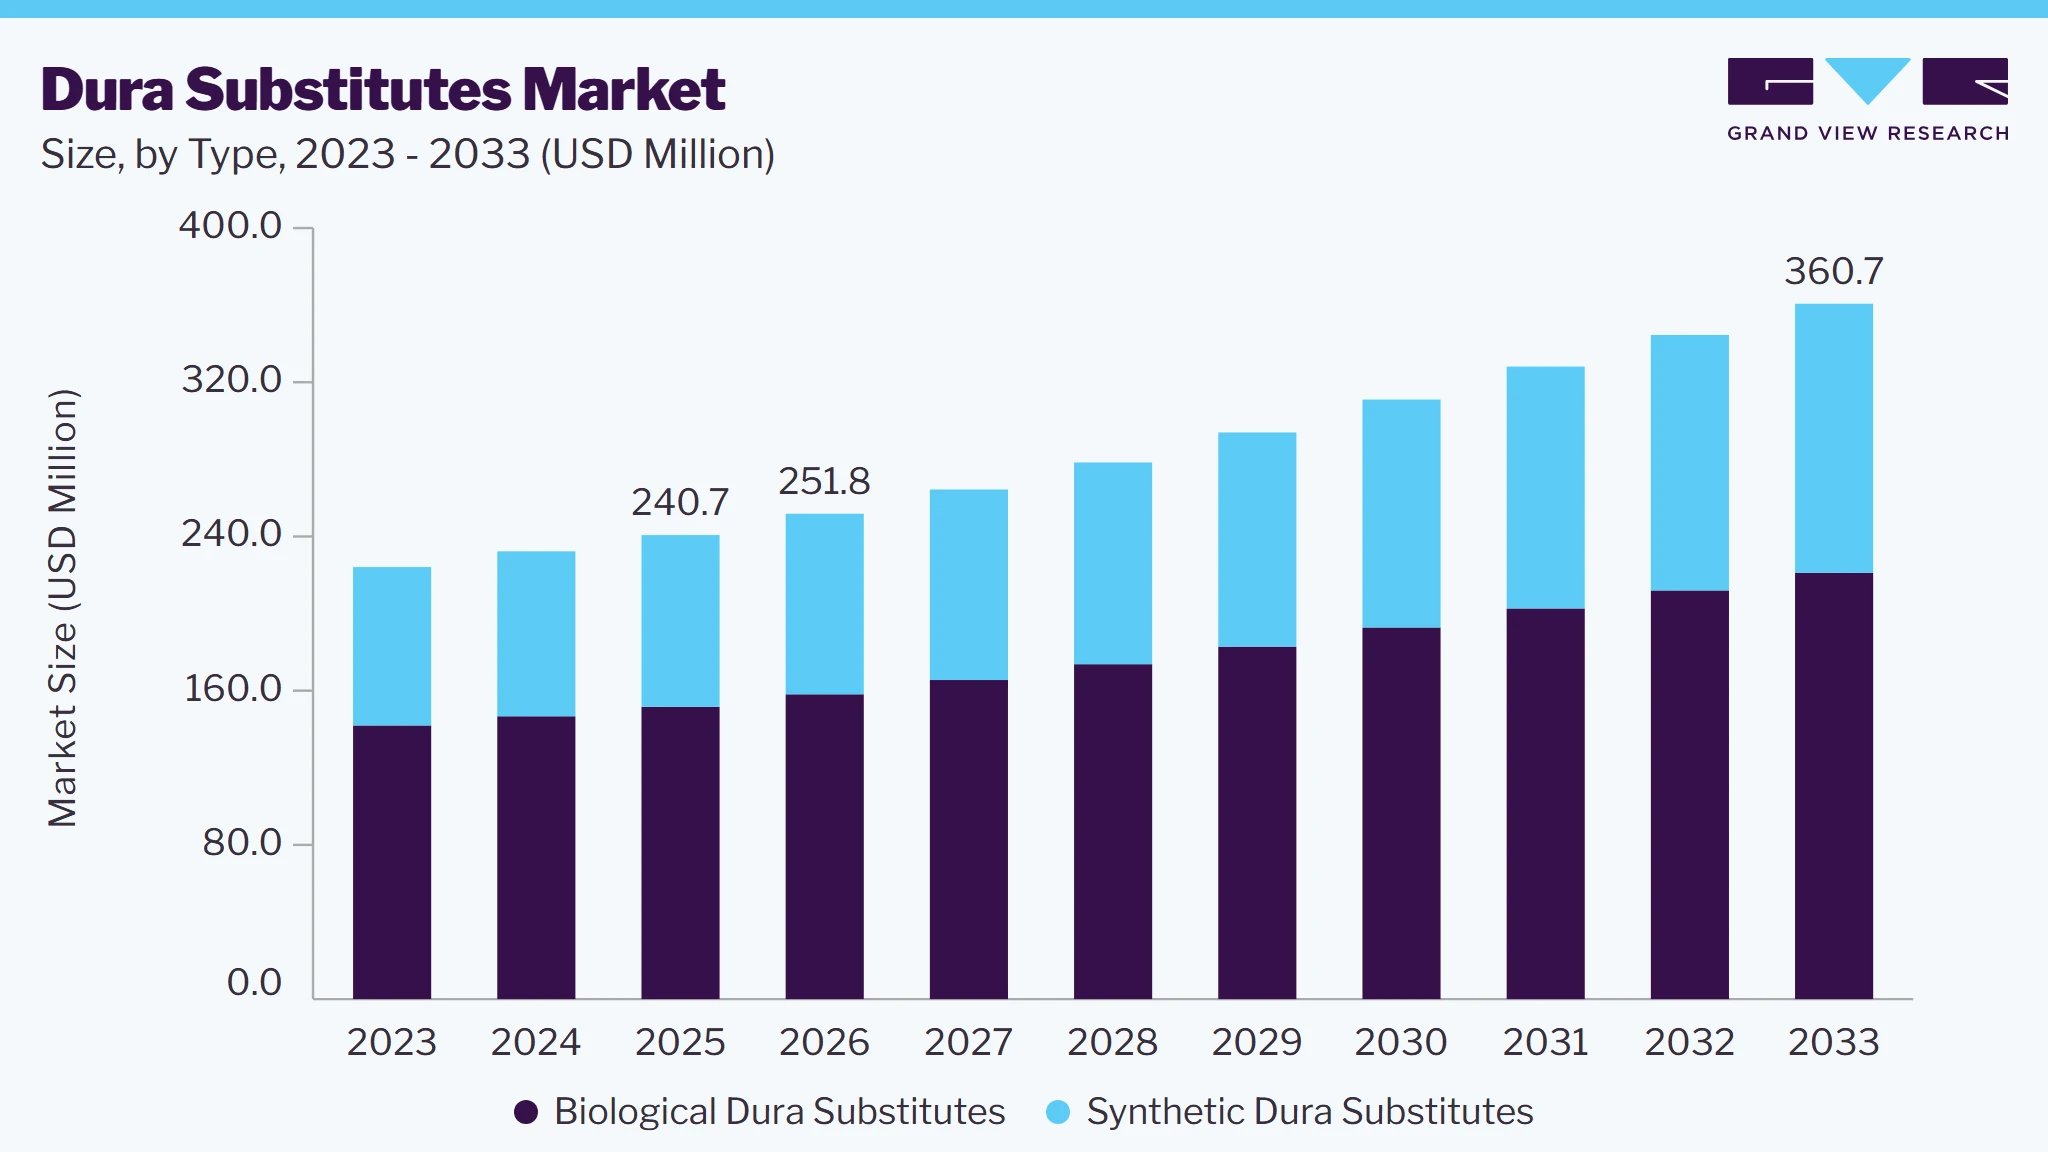
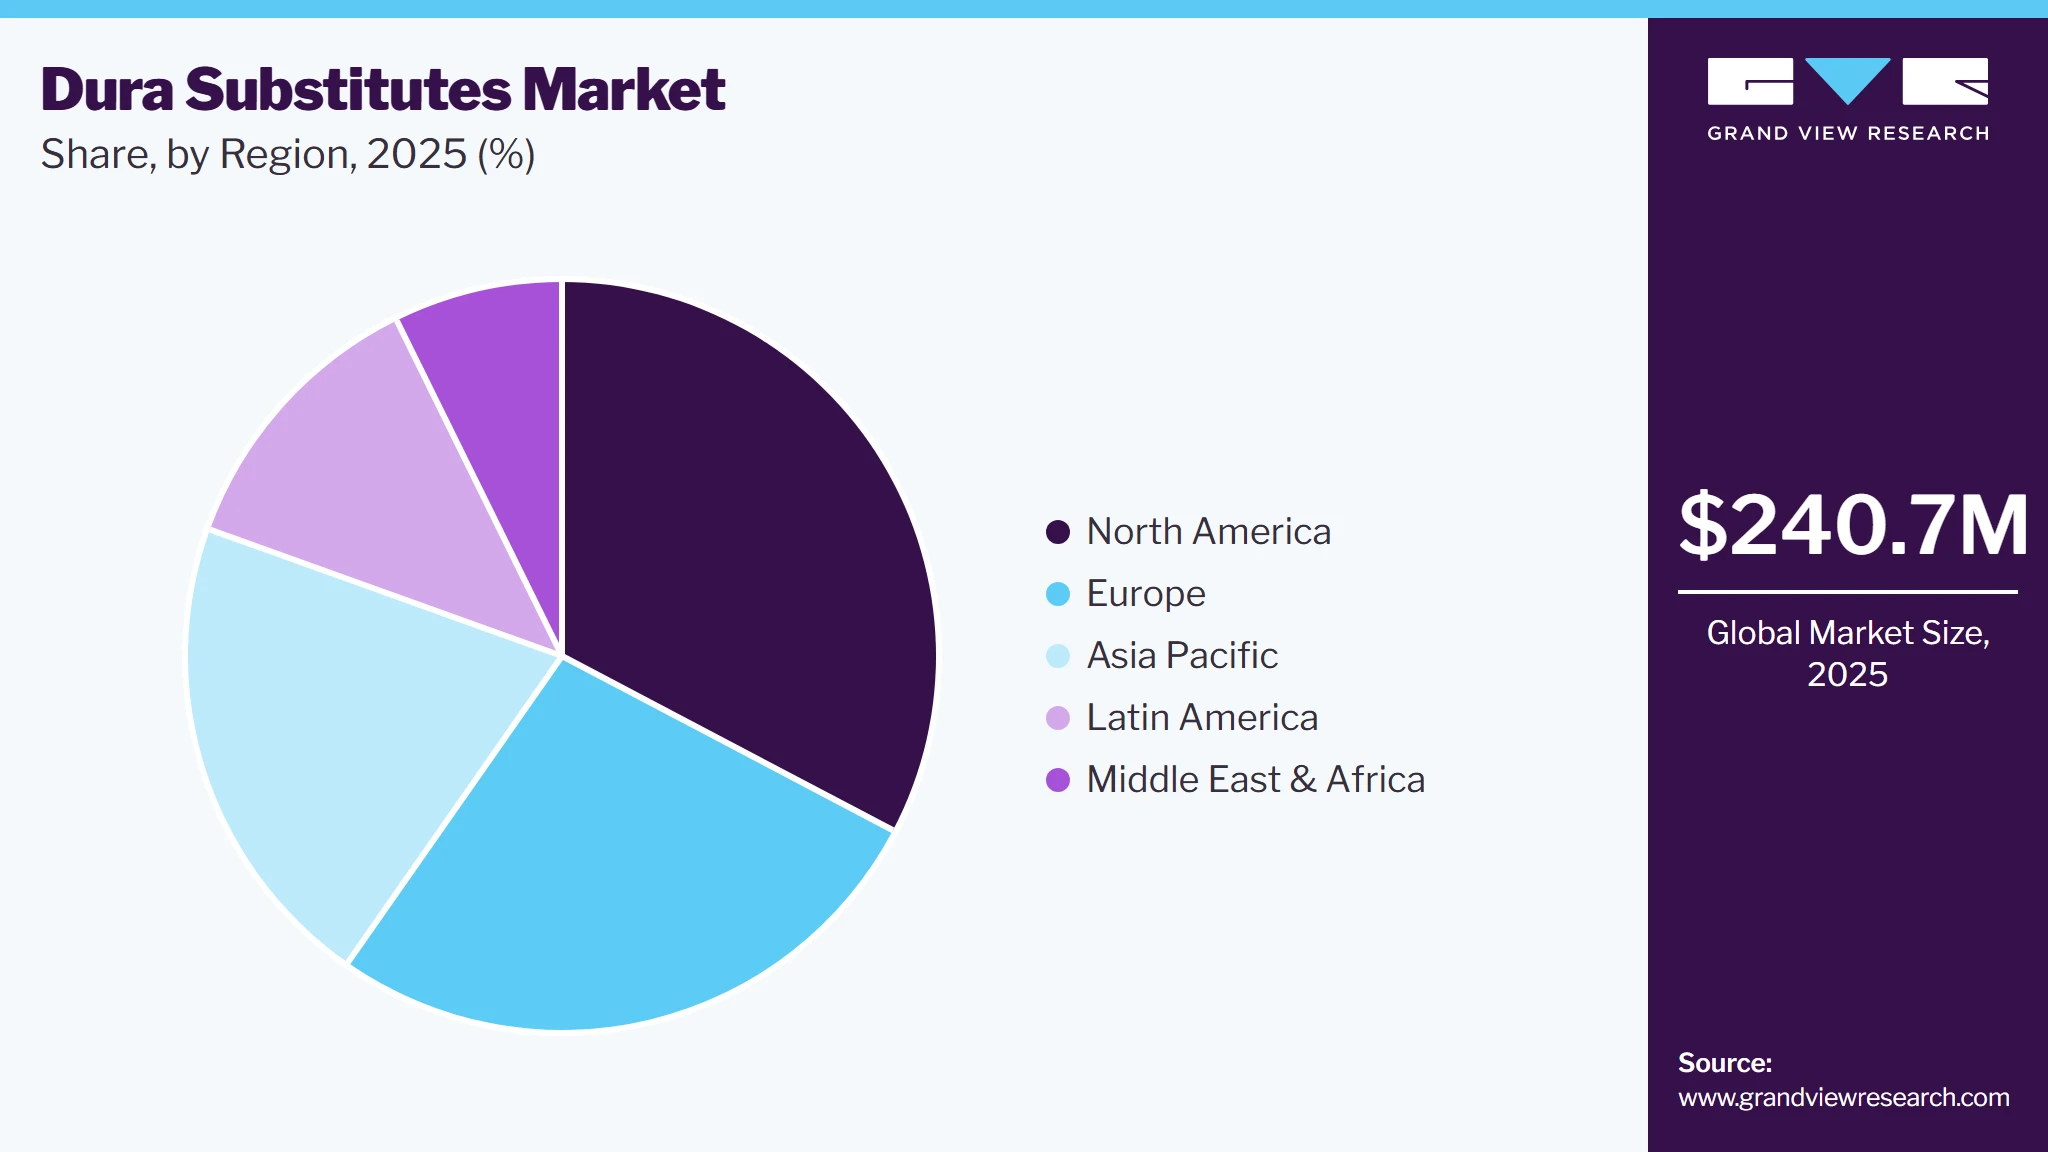
The global dura substitutes market size was valued at USD 240.7 million in 2025 and is projected to grow from USD 251.8 million in 2026 to USD 360.7 million by 2033, growing at a CAGR of 5.3% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 32.7% in 2025. The market growth is driven by advancements in neurosurgical techniques and the increasing prevalence of conditions requiring cranial or spinal surgeries, such as traumatic brain injuries, meningiomas, and chiari malformations.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Biological dura substitutes segment held the largest revenue share of 63.0% in 2025.
Regional Highlights
- Largest regional market: North America (32.7% revenue share, 2025)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 240.7 Million
- Estimated market size in 2026: USD 251.8 Million
- Projected market size by 2033: USD 360.7 Million
- CAGR (2026-2033): 5.3%
Prism AI by Grand View Research Free to tryAsk a question about the dura substitutes marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Moreover, an increasing focus on minimally invasive neurosurgical techniques has increased the demand for dura substitutes optimized for small incisions and endoscopic procedures. Dura substitutes, used to repair or replace the dura mater, are essential in cases of traumatic injuries, tumor resections, or congenital abnormalities. According to a report published by UpToDate, Inc. in May 2023, Traumatic Brain Injury (TBI) represents a critical global health challenge, contributing significantly to both disability and mortality. It is estimated that annually, between 27 and 69 million individuals worldwide experience a TBI. Such a high prevalence of TBIs is expected to increase the demand for advanced solutions offering better patient outcomes, which is expected to fuel the market growth over the forecast period.
 To learn more about this report, Download Free Sample Report
The aging population faces a higher risk of neurological disorders, which often require surgical interventions that utilize dura substitutes. According to UN population projections, the global population aged 65 and over is rapidly aging. Between 1974 and 2024, this demographic doubled, rising from 5.5% to 10.3% of the global population. By 2074, this figure is projected to double again, reaching 20.7%. In addition, the aging global population, coupled with a rising prevalence of neurological disorders, has increased the overall surgical volumes, thereby contributing to the rising need for effective dura substitutes. For instance, according to data from the CDC in May 2024, there were approximately 5,676 TBIs in the U.S. Furthermore, the same source reported over 69,000 TBI-related deaths in the U.S. in 2021, equating to 190 TBI deaths per day. In addition, according to data published by the Cleveland Clinic in May 2024, more than 75% of all TBIs are mild. Therefore, the increasing incidence of traumatic brain injuries is expected to drive market growth in the forecast period.
Market Dynamics
The dura substitutes market is growing significantly, driven by the increasing prevalence of neurological disorders, traumatic brain injuries, brain tumors, and the rising number of cranial and spinal surgeries worldwide. Technological advancements in biological and synthetic graft materials, coupled with growing demand for watertight dural closure and reduced postoperative complications, are accelerating product adoption. In addition, expanding healthcare infrastructure in emerging economies and continuous product innovation are creating new growth opportunities, although stringent regulatory requirements and the high cost of advanced grafts remain key challenges.
The primary driver of the dura substitutes market is the growing number of neurosurgical procedures performed for traumatic brain injuries, brain tumors, cerebrovascular disorders, and spinal conditions. The increasing demand for effective dural repair to prevent cerebrospinal fluid (CSF) leakage and postoperative infections is driving the adoption of biological and synthetic dural substitutes. Furthermore, advancements in neurosurgical techniques and greater access to specialized healthcare services are supporting sustained market growth.
Rising Global Burden of Neurological Disorders
- More than one in three people globally are expected to experience a neurological or psychiatric disorder during their lifetime, affecting approximately 3.4 billion individuals.
- Neurological disorders are a leading cause of disability and reduced quality of life worldwide.
- Around 11 million deaths each year are attributed to neurological conditions.
- The number of people living with dementia is projected to reach 78 million by 2033 and 139 million by 2050.
- The burden of brain-related disorders exceeds that of cancer and cardiovascular diseases combined.
Furthermore, the rising geriatric population, which is more susceptible to neurological disorders requiring surgical intervention, is further contributing to market demand. In addition, increasing awareness among neurosurgeons regarding the clinical benefits of advanced dural grafts, including improved biocompatibility and reduced revision surgeries, is driving higher product adoption globally.
The growth of the dura substitutes market is restrained by the high cost of advanced biological and synthetic graft materials, which can limit adoption in cost-sensitive healthcare settings. In addition, stringent regulatory approval processes and extensive clinical evidence requirements increase product development timelines and commercialization costs. Concerns regarding graft-related complications, such as infection, immune reactions, or cerebrospinal fluid leakage, also contribute to cautious adoption, particularly for newly introduced products.
Advancements in biomaterials and regenerative medicine are creating significant growth opportunities in the dura substitutes market. Manufacturers are developing next-generation absorbable, tissue-integrating, and bioengineered dura substitutes that offer improved biocompatibility, enhanced tissue regeneration, and reduced risk of cerebrospinal fluid leakage. Increasing investment in neurosurgical research, coupled with the adoption of minimally invasive surgical techniques, is accelerating demand for innovative dural repair solutions. Furthermore, expanding healthcare infrastructure and improving access to specialized neurosurgical care in emerging economies are expected to unlock substantial market potential over the coming years.
Market Concentration & Characteristics
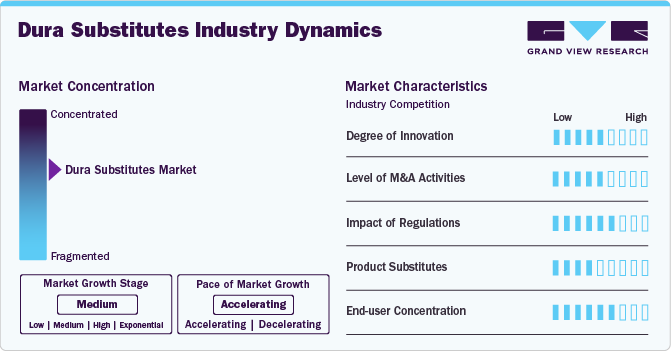
The market growth stage is medium, with an accelerating pace. The market is characterized by the rising prevalence of neurological disorders, the aging population, the rising preference towards minimally invasive surgical procedures, and the rising acceptance of dura substitutes as an effective solution for improving patient outcomes.
The market is experiencing a moderate degree of innovation. Limited research into novel biomaterials offers challenges to innovation, as several companies rely on established synthetic options. However, the increasing prevalence of various neurological conditions and the rise in surgeries are expected to drive innovation in dura substitutes over the forecast period.
 To learn more about this report, Download Free Sample Report
Regulatory bodies play a significant role in shaping the dura substitutes industry. Compliance with regulatory standards, such as those set by the FDA and EMA, is crucial for product approval and market entry. These regulations require stringent preclinical and clinical testing of dura substitutes. The complexity of regulatory processes can offer challenges for manufacturers, potentially impacting timely access to advanced dura substitutes for healthcare providers and patients. However, these regulations ensure that the dura substitutes are safe and effective for end users.
The level of M&A activities in the dura substitutes industry is moderate. Market players use this strategy for several reasons, including increasing market presence, enhancing product offerings, regional expansion, and others. Major players are acquiring smaller firms to enhance their product portfolios and expand market reach. Strategic mergers and acquisitions also enable companies to leverage advanced technologies and research capabilities.
The threat of product substitutes in the dura substitute industry is moderate but significant, as alternative materials such as autografts or allografts can serve similar purposes. While these traditional options may be preferred for certain applications due to their established efficacy, advancements in synthetic substitutes are significantly reducing this acceptance gap for the dura substitutes.
The dura substitutes industry is characterized by a moderate level of end user concentration. The end user concentration in the market primarily involves hospitals and surgical centers specializing in neurosurgery. As the number of neurosurgical procedures rises, driven by an aging population and increased incidence of neurological disorders, manufacturers need to meet the evolving needs of these facilities.
Analyst Perspective
The dura substitutes market is witnessing significant growth, driven by increasing volumes of neurosurgical procedures, the rising incidence of traumatic brain injuries, brain tumors, and spinal disorders, and the growing preference for advanced dural repair materials. Manufacturers are developing biocompatible, watertight, and easy-to-handle biological and synthetic grafts to reduce cerebrospinal fluid leakage and improve surgical outcomes. Continued product innovation, expanding regulatory approvals, and the adoption of minimally invasive neurosurgical techniques are expected to support long-term market expansion. In addition, increasing investments in biomaterials research and regenerative medicine are accelerating the development of next-generation absorbable and tissue-integrating dura substitutes. Emerging markets are also presenting significant growth opportunities as healthcare infrastructure improves and access to specialized neurosurgical care continues to expand.
Type Insights
Based on type, the biological dura substitutes segment led the market with the largest revenue share of 63.0% in 2025 owing to their superior biocompatibility, reduced risk of immunogenic reactions, and ability to integrate effectively with native tissue. These substitutes are primarily derived from human or animal tissues, such as bovine or porcine sources, which undergo rigorous processing to remove cellular components and reduce antigenicity. This process ensures that biological dura substitutes copy the natural properties of the human dura master, providing enhanced structural and functional support for neural tissue repair. Furthermore, their biodegradable nature eliminates the need for secondary removal surgeries, a significant advantage in neurosurgical procedures.
 To learn more about this report, Download Free Sample Report
The synthetic dura substitutes segment is expected to grow at the fastest CAGR over the forecast period due to several key advantages that these materials offer over other alternatives. Synthetic dura substitutes, made from advanced polymers such as polytetrafluoroethylene (PTFE), polyester, and silicone, provide a high degree of customization and reliability. These materials can be designed to meet specific mechanical and physical requirements, ensuring consistent performance in neurosurgical applications. Moreover, their properties, including flexibility and strength, make them suitable to withstand the biomechanical stresses in various surgeries, such as cranial and spinal surgeries, thereby increasing their demand.
Regional Insights
North America dominated the dura substitutes market with the largest revenue share of 32.7% in 2025. This can be attributed to the combination of increasing neurological procedures, advancements in biomaterials, and rising awareness among healthcare providers regarding effective post-surgical healing. North America has witnessed a steady rise in the prevalence of neurological conditions such as brain tumors, traumatic brain injuries, and spinal disorders. For instance, according to the American Cancer Society, in 2023, around 25,400 cases of malignant tumors of the brain or spinal cord were estimated to be diagnosed in the U.S. Furthermore, brain and spinal cord tumors were estimated to cause around 18,760 mortalities in the U.S. in 2023. This rising prevalence of neurological conditions has increased the demand for various neurosurgical procedures.
U.S. Dura Substitutes Market Trends
The dura substitutes market in the U.S. held the largest share in the North America region in 2025, owing to the advancements in neurosurgical techniques and the rising prevalence of neurological disorders requiring surgical intervention. Moreover, the increasing adoption of minimally invasive neurosurgical procedures, which often require the use of precise and adaptable dura substitutes, has further contributed to this rising demand. In addition, the presence of several key market players and access to advanced dura substitute products has further allowed healthcare providers to adopt these solutions, thereby driving their demand in the country.
The Canada dura substitutes market is experiencing steady growth driven by advancements in neurosurgical procedures, increasing prevalence of cranial injuries, and a robust healthcare infrastructure supporting innovation. In recent years, Canada has experienced a rise in traumatic brain injuries and neurological disorders, such as tumors requiring cranial surgery, which has created a sustained demand for effective dura substitutes. For instance, according to the Government of Canada, around 127,460 TBI-related hospitalizations were reported in Canada between 2021 and 2023.
Europe Dura Substitutes Market Trends
The Europe dura substitutes market is experiencing significant growth, driven by factors such as an aging population and the increasing adoption of synthetic biomaterials. Over the past decade, Europe has seen a surge in brain and spinal surgeries due to an aging population and higher diagnostic rates of conditions such as traumatic brain injuries and spinal tumors. This has increased the demand for effective dura substitutes, as repairing dura mater defects is crucial for preventing cerebrospinal fluid leakage and post-operative complications.
The dura substitutes market in the UK is expected to grow significantly over the forecast period. The growing number of patients requiring dural repair, particularly due to head and spinal injuries, is a key factor pushing this market. Moreover, the UK’s commitment to advancing healthcare technology, coupled with an aging population and the rise of neurological diseases, has created significant demand for durable, cost-effective dura substitutes.
The Germany dura substitutes market is witnessing a significant growth driven by the country’s developed healthcare infrastructure and growing focus on medical research. In addition, German hospitals have increasingly adopted minimally invasive techniques, which rely on advanced materials for dura repair, thereby contributing to the market growth in the country.
Asia Pacific Dura Substitutes Market Trends
Asia Pacific dura substitutes market is anticipated to grow at the fastest CAGR over the forecast period. Several factors, including rising incidences of neurological disorders, developing healthcare infrastructure, and increased awareness of brain surgeries, are attributed to the anticipated growth. In recent years, countries such as Japan, China, and India have seen a growing demand for dura substitutes, driven by an aging population and an increase in traumatic brain injuries. The region's healthcare infrastructure has also improved, with more specialized hospitals and surgical centers offering advanced treatments that involve dura mater repair, a process critical for patients undergoing cranial surgeries.
The dura substitute market in China is expected to witness significant growth over the forecast period. China has witnessed significant development in the country’s healthcare infrastructure, which has also allowed for the adoption of advanced healthcare solutions offering better patient outcomes in the country. Moreover, the country’s aging population, coupled with rising awareness towards minimally invasive procedures, has further contributed to the market growth in the country.
Latin America Dura Substitutes Market Trends
The Latin America Dura Substitutes Market is experiencing significant growth, driven by advances in neurosurgery and an increasing demand for effective treatments for conditions involving the dura mater, such as traumatic brain injuries, spinal cord surgeries, and brain tumor resections. Latin American countries have increasingly invested in advanced medical technologies and training, leading to more efficient use of these substitutes in complex surgical procedures. Additionally, as healthcare systems in the region evolve, regulatory bodies are expected to streamline approval processes for dura substitutes, making them more accessible for the end user in the market.
Middle East And Africa Dura Substitutes Market Trends
The dura substitutes market in MEA is experiencing growth driven by the increasing focus on healthcare infrastructure development, rising healthcare expenditure, and an increasing focus on improving patient outcomes following brain and spinal surgeries. Over the past decade, the demand for effective dura substitutes has risen as the region's healthcare infrastructure improves, with more hospitals and clinics specializing in neurosurgery. Moreover, countries such as the UAE and Saudi Arabia have witnessed a rise in medical tourism, with patients seeking advanced surgical treatments, further increasing demand for dura substitutes.
The dura substitutes market in Saudi Arabia is expected to witness significant growth over the forecast period. Saudi Arabia has made significant investments in the country’s healthcare infrastructure, including the field of neurosurgery, where dura substitutes are essential for treating dural defects resulting from trauma, surgery, or congenital conditions. The Saudi government’s Vision 2033 initiative has accelerated this development, with a focus on improving the quality of healthcare services and reducing reliance on international medical providers.
Neurological Health Awareness Initiatives
In November 2024, the National Center for Neurological Disorders launched a series of books aimed at increasing awareness of neurological disorders in China. The publication addresses common and major disorders, increasing the need for better understanding and support for affected individuals and their families.
In June 2024, the Società Italiana di Neurologia launched the Italian Brain Health Strategy 2024-2031, which aims to enhance awareness and combat mental and neurological diseases. It aligns with the WHO's Global Action Plan and emphasizes collaboration among patients, healthcare professionals, and policymakers to improve brain health across all demographics in Italy.
In May 2022, the WHO announced the adoption of the Intersectoral Global Action Plan on Epilepsy and Other Neurological Disorders (2022-2031) plan to enhance treatment access and improve the quality of life and access to treatment for individuals with neurological disorders. It outlines strategic objectives addressing governance, diagnosis, prevention, research, and public health responses to epilepsy and related conditions.
Key Dura Substitutes Company Insights
Key market players are adopting various strategies such as product launches, approvals, and others to increase their market presence and get a competitive advantage over other market players. These advancements in the dura substitutes industry are anticipated to boost market growth over the forecast period.
Key Dura Substitutes Companies:
The following key companies have been profiled for this study on the dura substitutes market.
-
Integra LifeSciences Corporation
-
Aesculap, Inc. (B. Braun SE)
-
DePuy Synthes (Johnson & Johnson)
-
W. L. Gore & Associates, Inc.
-
GUNZE LIMITED
-
Acera Surgical Inc. (Solventum)
-
Nurami Medical Nanofiber Technology
-
Stryker
-
Baxter
-
Severn Healthcare Technologies Limited (GBUK Group)
-
Biosynth Lifesciences
-
Medprin Biotech
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Integra LifeSciences Corporation, Aesculap, Inc. (B. Braun SE), DePuy Synthes (Johnson & Johnson)
Expand product portfolios across biological and synthetic dura substitutes.
Invest heavily in R&D to improve biocompatibility and watertight sealing performance.
Strong brand recognition and surgeon trust.
Broad product portfolio with established reimbursement and regulatory approvals.
High operating and manufacturing costs.
Slower product development due to complex organizational structures.
Emerging Players (Nurami Medical Nanofiber Technology, Severn Healthcare Technologies Limited (GBUK Group), Medprin Biotech)
Develop innovative biomaterials and next-generation absorbable grafts.
Target niche neurosurgical applications and unmet clinical needs.
Faster innovation cycles and greater flexibility in product development.
Adoption of advanced biomaterials and regenerative technologies.
Limited brand recognition and clinical adoption.
Smaller sales and distribution networks.
Recent Developments
-
In August 2023, NURAMI MEDICAL announced that its ArtiFascia Dura Substitute received FDA 510(k) clearance. This innovative graft, made from electrospun nanofibers, is designed for dural repair in neurosurgery. It offers several benefits, including promoting tissue regeneration, preventing cerebrospinal fluid (CSF) leakage, and providing ease of handling. The ArtiFascia Dura Substitute represents a significant advancement in soft tissue repair technology, enhancing surgical outcomes for patients undergoing neurosurgical procedures.
Dura Substitutes Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 240.7 million
Market size value in 2026
USD 251.8 million
Revenue forecast in 2033
USD 360.7 million
Growth rate
CAGR of 5.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type & region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Integra LifeSciences Corporation, Aesculap, Inc. (B. Braun SE), DePuy Synthes (Johnson & Johnson), W. L. Gore & Associates, Inc., GUNZE LIMITED, Acera Surgical Inc. (Solventum), Nurami Medical Nanofiber Technology, Stryker, Baxter, Severn Healthcare Technologies Limited (GBUK Group), Biosynth Lifesciences, Medprin Biotech
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dura Substitutes Market Report Segmentation
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global dura substitutes market report based on type and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Biological Dura Substitutes
-
Synthetic Dura Substitutes
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Thailand
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The dura substitutes market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dura substitutes segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Biological Dura Substitutes
Revenue is generated from the sale of biological dura substitute grafts derived from human allograft or animal-derived (bovine/porcine) tissues used for dural repair in neurosurgical and spinal procedures. It includes revenue from sterile grafts sold in various sizes and configurations to hospitals, ambulatory surgical centers, and specialty clinics.
Synthetic Dura Substitutes
Revenue is generated from the sale of synthetic dura substitute grafts made from biocompatible materials such as polyurethane, polyester, PTFE, silicone, and bioresorbable polymers for dural repair in neurosurgical and spinal procedures. It includes revenue from sterile grafts sold in various sizes and configurations to hospitals, ambulatory surgical centers, and specialty clinics.
Estimation Model
Bottom-Up Estimation
Top-Down Revenue Triangulation
Demand-Side Procedure Modeling
Regional market size is derived using country-level data such as the annual volume of cranial and spinal surgeries requiring dural repair, adoption rates of biological and synthetic dura substitutes, average selling price (ASP) of grafts, and manufacturer revenues across major regions.
The dura substitutes market is estimated by analyzing the neurosurgical biomaterials segment within the broader neurosurgery and surgical sealants market. Revenue contributions from leading manufacturers are assessed through annual reports, product portfolios, investor presentations, and regulatory filings to determine market share.
Market demand is estimated by evaluating the annual number of neurosurgical procedures (brain tumor resections, trauma surgeries, vascular procedures, and spinal surgeries), incidence of dural defects, surgeon adoption rates of dura substitutes, and hospital procurement patterns to calculate total market demand and revenue potential.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive landscape and benchmarking
Company-wise benchmarking covering product portfolio, pricing, regulatory approvals, pipeline, market share, and strategic initiatives.
Enables identification of key competitors, partnership opportunities, and competitive positioning.
Regional and country-level market assessment
Detailed analysis of market size, growth trends, reimbursement scenario, regulatory framework, and procedure volume across key countries.
Supports market entry, expansion planning, and regional investment decisions.
ASP and volume analysis
Comprehensive analysis of average selling prices (ASP) by product type and region, along with procedure volume, unit sales, and demand forecasting.
Enables accurate revenue forecasting, pricing strategy optimization, and volume-based market opportunity assessment.
Frequently Asked Questions About This Report
Key factors that are driving the market growth include the increasing prevalence of neurological and spinal disorders, including traumatic brain injuries, tumors, and degenerative conditions, which often necessitate neurosurgical interventions. Advances in biomaterial science have also fueled growth, with the development of biocompatible and synthetic dura substitutes that enhance surgical outcomes and minimize complications such as infections.
Asia Pacific is the fastest-growing region over the forecast period.
The biological dura substitutes segment led the market with the largest revenue share of 63.0% in 2025.
North America dominated the dura substitutes market with the largest revenue share of 32.7% in 2025.
North America dominated the dura substitutes market with a share of 32.7% in 2025. This can be attributed to increasing neurological procedures, advancements in biomaterials, and rising awareness among healthcare providers regarding effective post-surgical healing.
Some key players operating in the dura substitutes market include Integra LifeSciences Corporation, Aesculap, Inc. (B. Braun SE), DePuy Synthes (Johnson & Johnson), W. L. Gore & Associates, Inc., GUNZE LIMITED, Acera Surgical Inc. (Solventum), Nurami Medical Nanofiber Technology, Stryker, Baxter, Severn Healthcare Technologies Limited (GBUK Group), Biosynth Lifesciences and Medprin Biotech.
The global dura substitutes market size was valued at USD 240.7 million in 2025 and is estimated at USD 251.8 million for 2026.
The global dura substitutes market is expected to grow at a CAGR of 5.3%from 2026 to 2033, reaching USD 360.7 million by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


