
- Home
- »
- Medical Devices
- »
-
Durable Medical Equipment Market Size Report, 2026-2033GVR Report cover

Durable Medical Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Personal Mobility Devices, Bathroom Safety Devices And Medical Furniture), By End Use (Hospitals, Nursing Homes, Home Healthcare), By Region, And Segment Forecasts
Market Size, 2025
$246.0BMarket Estimate, 2026
$260.8BMarket Forecast, 2033
$379.8BCAGR, 2026–2033
5.5%Durable Medical Equipment Market Summary
The global durable medical equipment market size was valued at USD 246.0 billion in 2025 and is projected to grow from USD 260.8 billion in 2026 to USD 379.8 billion by 2033, at a CAGR of 5.5% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.3% in 2025. The industry is driven by the rising prevalence of chronic diseases, an aging population, and increasing demand for long-term and home-based care.
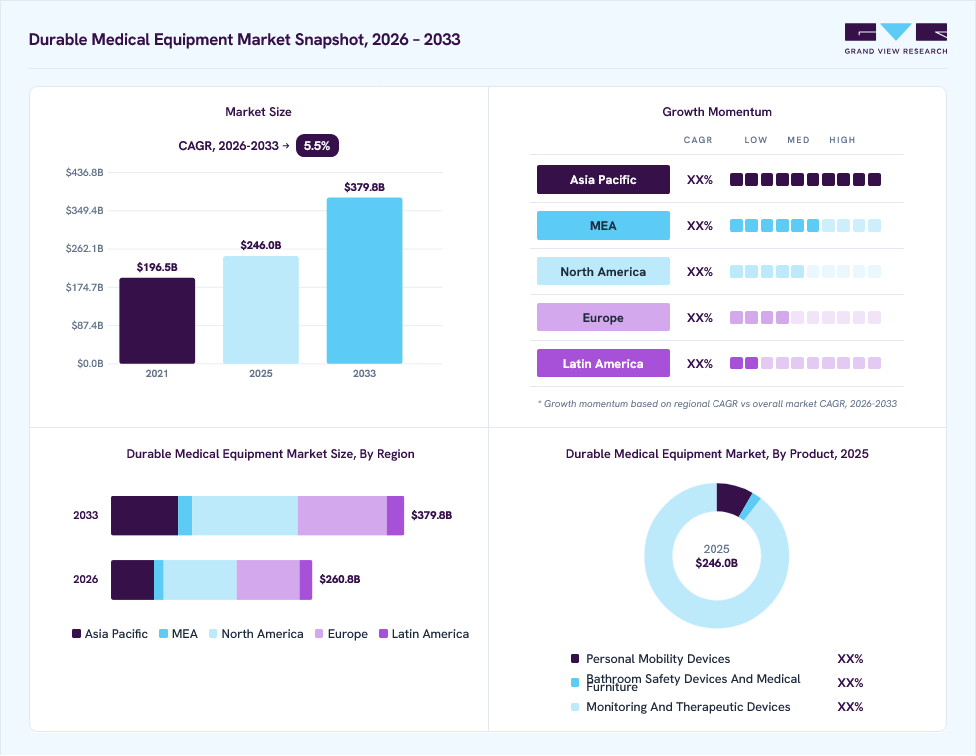 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Monitoring and therapeutic devices segment led the market with a 89.5% revenue share in 2025.
- By end-use: Hospitals segment led the market, accounting for 34.1% of revenue in 2025.
Regional Highlights
- Largest regional market: North America (36.3% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 246.0 Billion
- Estimated market size in 2026: USD 260.8 Billion
- Projected market size by 2033: USD 379.8 Billion
- CAGR (2026-2033): 5.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Technological advancements such as smart, connected, and lightweight medical devices further enhance patient convenience and treatment efficiency. Furthermore, growing healthcare awareness and supportive reimbursement policies are accelerating market adoption. According to the World Health Organization (WHO), chronic obstructive pulmonary disease (COPD) and asthma are the most common chronic respiratory diseases (CRDs), with COPD accounting for nearly 80% of CRD-related deaths. With an aging global population and multiple health challenges, COPD cases are projected to rise by 23% worldwide by 2050, disproportionately affecting women and individuals in low- and middle-income countries.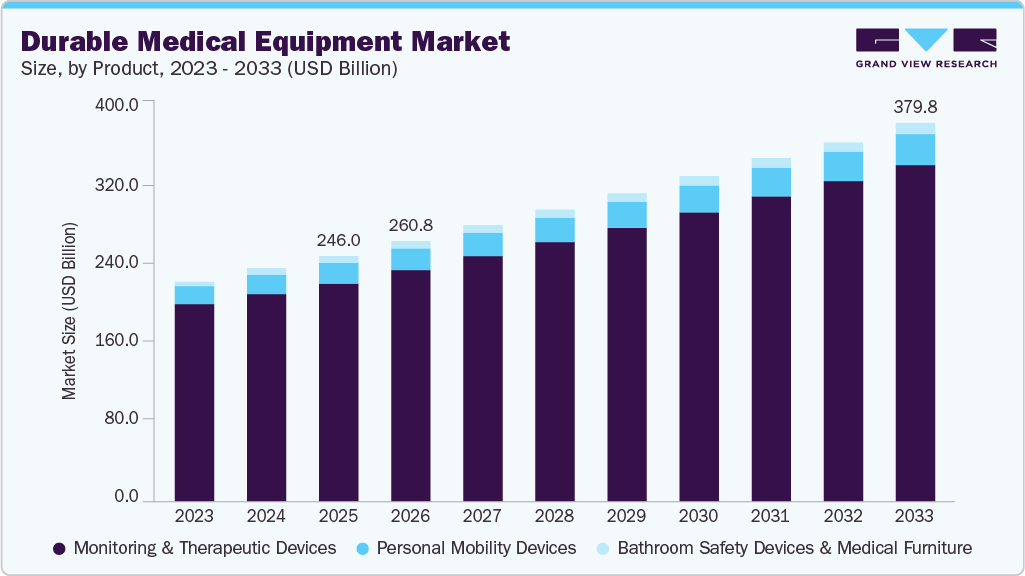 To learn more about this report, Download Free Sample Report
The growing prevalence of chronic diseases such as diabetes, cardiovascular disorders, respiratory conditions, and mobility-limiting illnesses is a major driver of the DME market. These conditions often require long-term management, continuous monitoring, and supportive care, increasing demand for equipment such as glucose monitors, oxygen concentrators, mobility aids, and therapeutic devices. As the global prevalence of chronic diseases rises, patients depend on DME to manage symptoms, improve quality of life, and reduce hospital visits. This sustained need for ongoing care solutions continues to fuel growth in the DME market.
Cardiovascular disease cases are increasing due to this rising demand for long-term monitoring and therapeutic devices, such as blood pressure monitors, oxygen concentrators, and mobility aids. The need for continuous care, rehabilitation, and home-based management of CVD patients supports DME adoption.
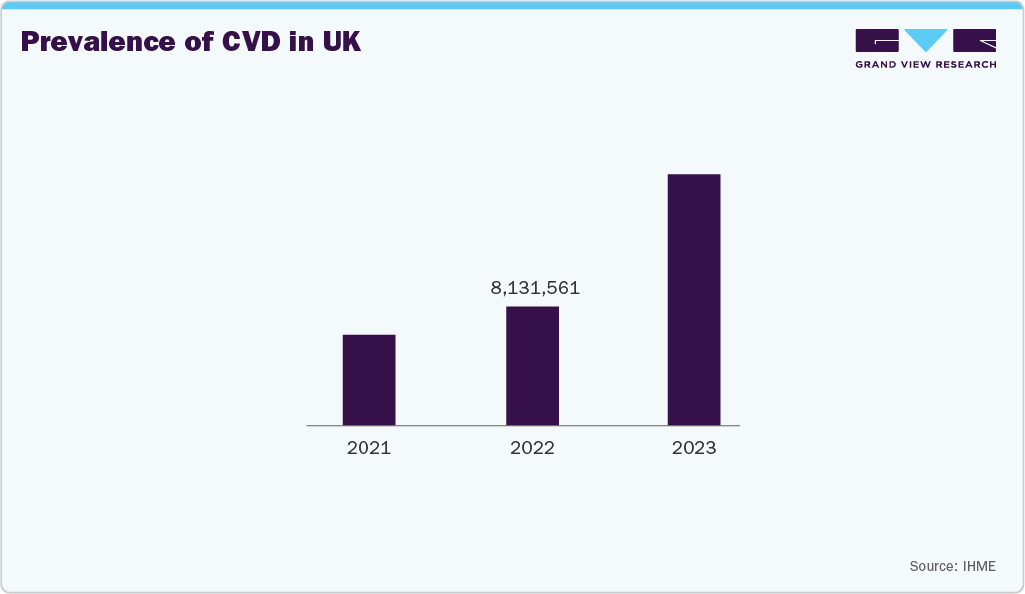 To learn more about this report, Download Free Sample Report
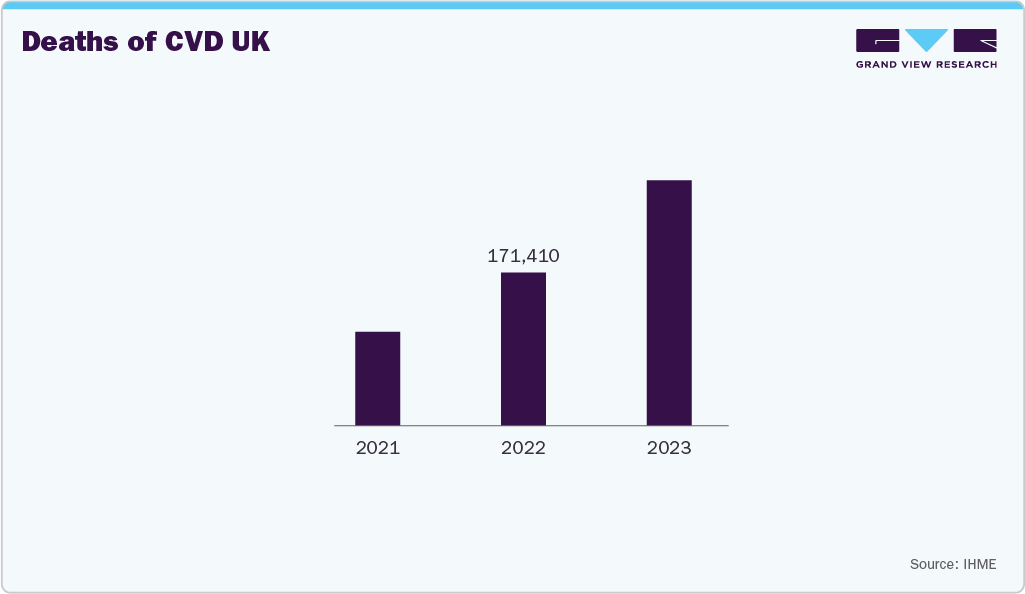 To learn more about this report, Download Free Sample Report
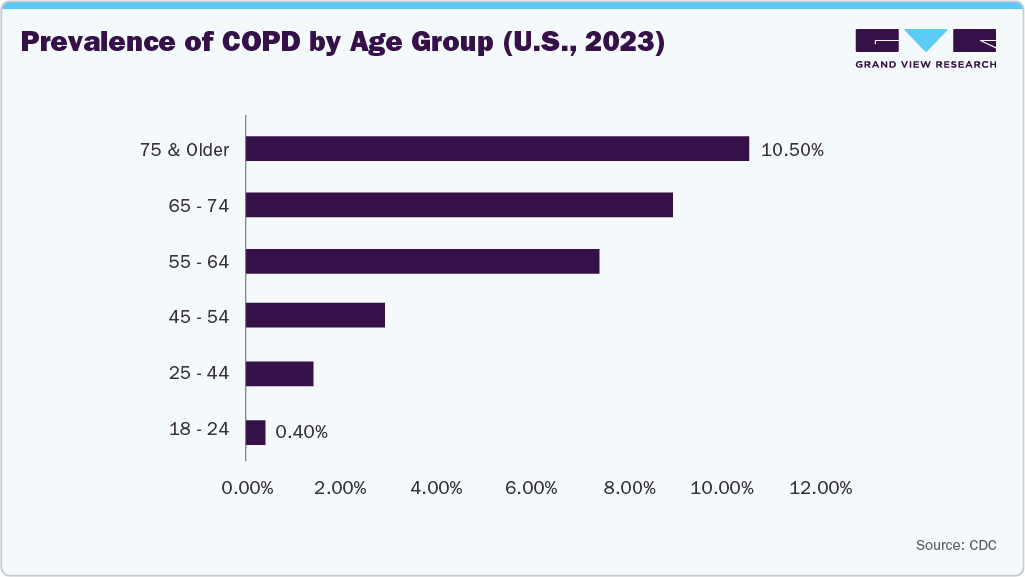
Similarly, COPD drives demand for DME, including oxygen concentrators, nebulizers, and ventilators. The need for ongoing home-based care and symptom management in COPD patients further accelerates the adoption of these medical devices. According to the CDC, in 2023, the age-adjusted prevalence of diagnosed chronic obstructive pulmonary disease (COPD) among adults aged 18 and older was 3.8%, with a higher prevalence in women (4.1%) compared to men (3.4%).
 To learn more about this report, Download Free Sample Report
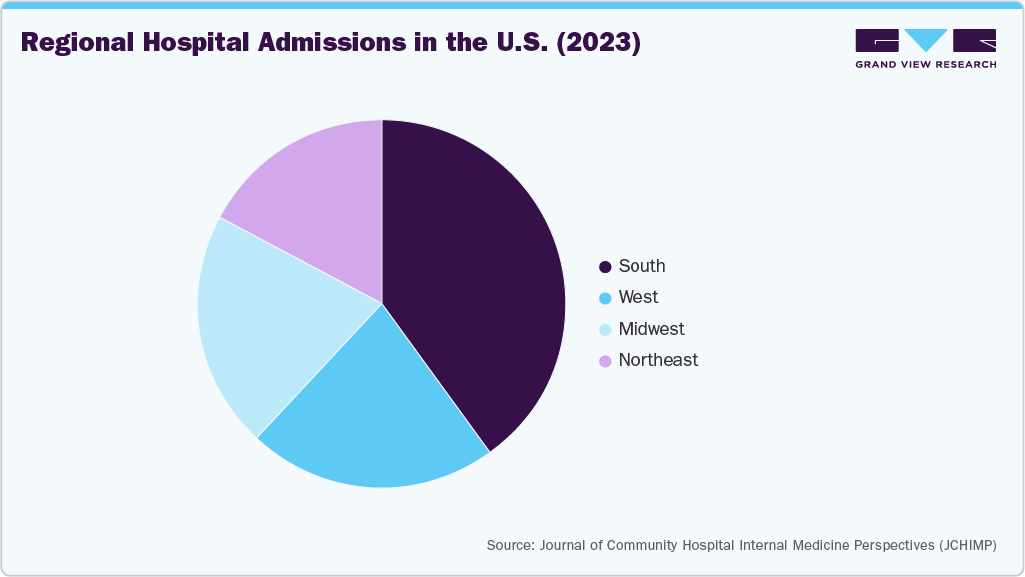
As a result, the rising prevalence of cardiovascular diseases and COPD, along with the growing geriatric population, is driving increased demand for durable medical equipment (DME), such as mobility aids, oxygen concentrators, ventilators, and home monitoring devices. This surge in demand for such equipment is fueling significant growth in the DME market.
Furthermore, post-surgery and rehabilitation care are major drivers of the durable medical equipment (DME) market, as patients require specialized support to recover safely and effectively. Equipment such as wheelchairs, hospital beds, walkers, and therapeutic devices is essential for mobility, pain management, and physical rehabilitation. The growing focus on early discharge and home-based recovery programs further increases demand for DME, enabling patients to regain independence while reducing hospital stays and healthcare costs.
 To learn more about this report, Download Free Sample Report
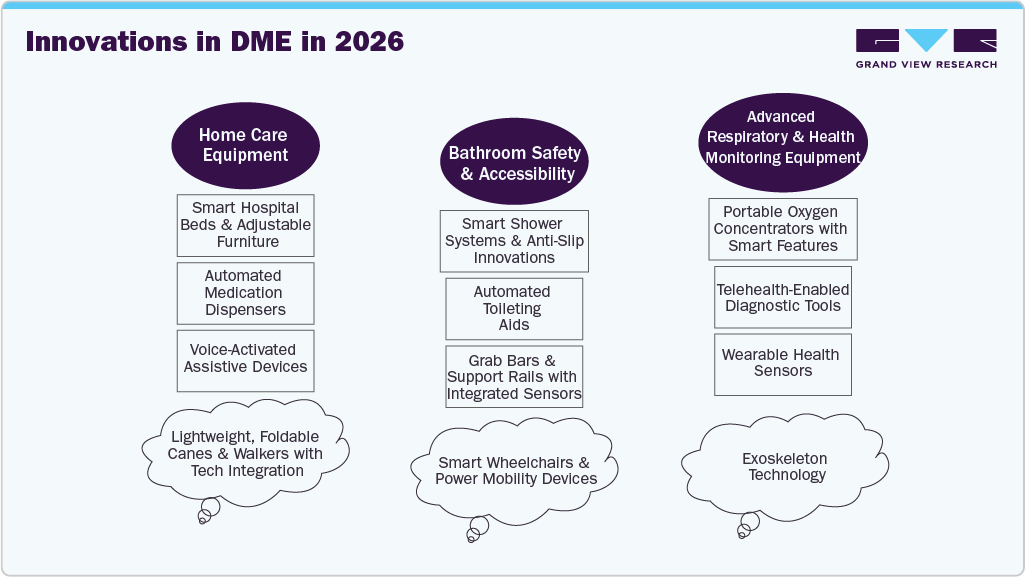
Technological advancements and product innovation are key drivers of the DME market, as manufacturers develop smarter, more efficient, and user-friendly devices. Innovations such as AI-powered monitoring systems, telehealth-integrated equipment, lightweight wheelchairs, and advanced respiratory devices enhance patient care, safety, and convenience. These improvements expand home healthcare adoption and increase demand for customized, high-performance DME solutions, supporting the market growth.
 To learn more about this report, Download Free Sample Report
As a result, technological innovations such as AI-enabled devices, telehealth-compatible equipment, and smart mobility solutions are driving growth in the DME market. These advancements enhance patient outcomes, expand access to care, and create new opportunities for market expansion.
Furthermore, reimbursement policy plays a vital role in strengthening the DME market by ensuring consistent payment for approved equipment and encouraging provider participation. Supportive reimbursement frameworks reduce financial risk, promote adoption of new technologies, and help sustain long-term market growth.
According to the All-Seniors Foundation, in 2026, Medicare expanded coverage for select innovative devices, including AI-enabled mobility aids and telehealth-compatible equipment. However, coverage continues to require documentation of medical necessity and compliance with supplier standards. Furthermore, Medicaid programs in several states have increased funding for home-based durable medical equipment, further supporting patient access to advanced care solutions. Many private insurers now offer supplemental DME plans that include coverage for advanced technology devices that are often not included in standard plans. Reviewing policy terms closely is essential, along with confirming any pre-authorization requirements for newer or emerging equipment.
Pricing in the DME market is influenced by reimbursement rates, regulatory controls, and competitive bidding programs. Cost pressures from payers and manufacturers drive variability across product categories while encouraging efficiency and value-based offerings. The table below shows the pricing analysis of some key manufacturers, their products, and respective categories:
Pricing Analysis of DME
Company Name
Product Type
Sub-product Type I
Product Name
Manufacturer Price (USD)
Invacare Corporation
Bathroom Safety Devices and Medical Furniture
Hospital Beds & Support Surfaces
CS600 Bed, Standard width 36"W x 80"L (CS600-36)
2,335.0
Mattress & Bedding Devices
Invacare microAIR MA800 48" Mattress only (MA800M48)
3,700.0
Sunrise Medical
Bathroom Safety Devices and Medical Furniture
Patient Lifts & Transfer Equipment
Nuprodx MC6200Tilt
6,458.0
Nuprodx MC4024 - User-Propelled Shower Commode Chair
3.029.6
Arjo
Bathroom Safety Devices and Medical Furniture
Mattress & Bedding Devices
AtmosAir Velaris Alternating Pressure Mattress System
2,993.7
Hospital Beds & Support Surfaces
Arjo Evenda Moveno Long-term Care Medical Bed
5,465.0
GF Health Products, Inc.
Bathroom Safety Devices and Medical Furniture
Commodes and Toilets
Drop Arm Commode with Lid, Steel, 300 lb.
365.0
Hospital Beds & Support Surfaces
Liberty Bed
1,833.7
Medline
Bathroom Safety Devices and Medical Furniture
Commodes and Toilets
Medline XW 24in Steel Bariatric Commode, 650lb Capacity 1Ct
102.5
Mattress & Bedding Devices
Medline Premium Gel Foam Overlay
269.5
Source: Company Websites, Product Brochure, Distributor, and third-party websites
(Note: A similar pricing analysis has been applied across all the mentioned companies and for all products.)
Market Dynamics
The Durable Medical Equipment (DME) market is experiencing growth driven by a combination of demographic, clinical, and technological factors. A key market dynamic is the rising prevalence of chronic diseases such as diabetes, cardiovascular disorders, respiratory conditions, and mobility impairments, which increases long-term demand for equipment like mobility aids, respiratory devices, monitoring systems, and home care products. In addition, the rapidly aging global population is significantly expanding the patient base requiring continuous and assisted care, further strengthening market demand. Another major dynamic is the growing shift toward home healthcare, as patients and providers prefer cost-effective, convenient, and remote care solutions supported by portable and user-friendly medical devices. Technological advancements such as smart, connected, and AI-enabled equipment are also transforming the market by improving patient monitoring, treatment efficiency, and data-driven care delivery.
The rising prevalence of chronic diseases is a key factor driving growth in the durable medical equipment market. Among these conditions, cancer is contributing significantly to the demand for a wide range of medical equipment used during treatment, recovery, and long-term care. Cancer patients require durable medical equipment, including hospital beds, mobility aids, wheelchairs, patient lifts, oxygen therapy devices, infusion pumps, and monitoring equipment, to manage symptoms and improve quality of life. As advances in diagnosis and treatment continue to improve survival rates, an increasing number of patients require ongoing supportive care in healthcare facilities and at home. In addition, cancer-related fatigue, reduced mobility, respiratory complications, and post-surgical recovery needs increase the use of durable medical equipment for extended periods. The increasing shift toward home-based care and outpatient treatment further supports demand for these products. As the number of individuals living with cancer and other chronic diseases continues to rise, there is a need for reliable and long-lasting medical equipment. According to the data published by the American Cancer Society in 2026, excluding non-melanoma skin cancers, approximately 2.1 million new cancer cases are expected to be diagnosed in the U.S. in 2026, leading to over 626,000 deaths, an equivalent of about 1,700 deaths per day.
The high cost of advanced durable medical equipment significantly restrains market growth by limiting affordability and adoption among patients, healthcare providers, and care facilities, especially in cost-sensitive and developing regions. Modern DME products, such as advanced ventilators, powered mobility devices, remote patient monitoring systems, and smart, connected rehabilitation equipment, require substantial upfront investment, and ongoing maintenance and training costs. These financial barriers make healthcare providers hesitant to upgrade to newer technologies, particularly when budget constraints exist or reimbursement coverage is insufficient. For individual patients, especially those without comprehensive insurance coverage, out-of-pocket costs can be prohibitive, leading them to opt for basic or outdated alternatives rather than advanced solutions.
Technological advancements are creating significant opportunities for the Durable Medical Equipment (DME) market by enhancing product capabilities, improving patient outcomes, and expanding access to care. The integration of IoT-enabled devices enables real-time patient monitoring, allowing healthcare providers to track health conditions remotely and respond quickly to changes. Artificial intelligence and data analytics further support predictive healthcare, personalized treatment plans, and improved decision-making. The development of smart, connected, and wearable medical devices is increasing patient convenience and encouraging wider adoption, particularly in home healthcare settings. In addition, advancements in lightweight materials, battery efficiency, and portable designs are making equipment more user-friendly and suitable for long-term use outside clinical environments.
• In June 2025, Stryker launched the APAISER X1 advanced ICU air mattress at ANEiCON 2025 in Kochi, India, designed specifically for the Indian healthcare market. The system integrates with Stryker’s SmartMedic platform and aims to improve patient comfort, reduce pressure injury risk, and enhance caregiver efficiency in critical care settings. It features low-air-loss technology, a 3-in-1 alternating pressure system, multiple care modes, and added features such as auto-Fowler detection, quiet operation, and pressure retention during patient transport or power outages, supporting continuous and efficient ICU care.
Market Concentration & Characteristics
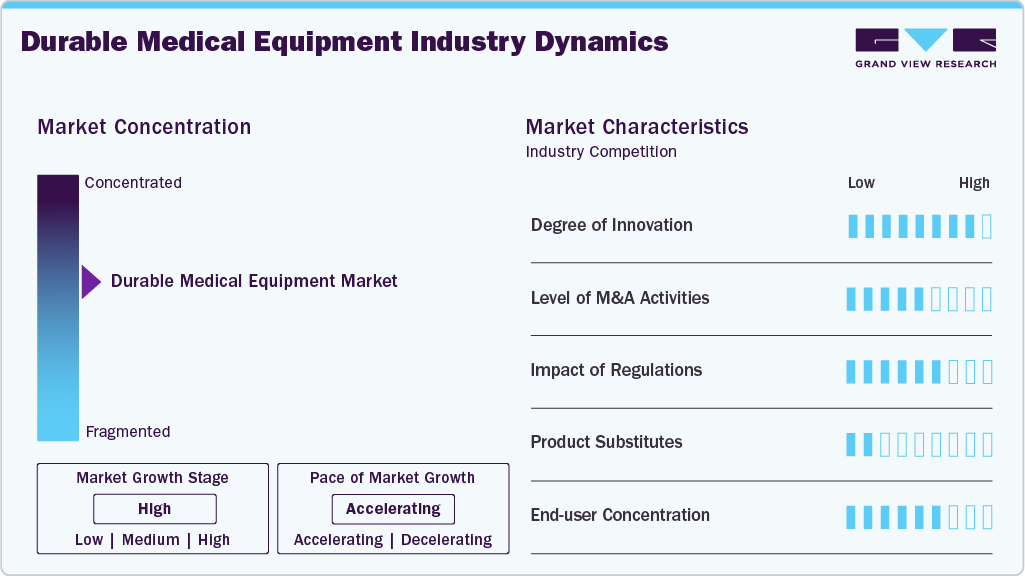
The industry is experiencing significant innovation, driven by advances in technology and patient-centered design. Companies are integrating smart features, IoT connectivity, and AI-driven monitoring into wheelchairs, beds, and home care devices, enhancing functionality and patient safety. Lightweight materials, modular designs, and customizable solutions further improve usability and accessibility. This continuous innovation meets evolving healthcare needs and opens new opportunities for growth in home and clinical care settings. For instance, in January 2026, Graham-Field, a leading provider of healthcare equipment and resident-centered solutions, announced the launch of the AmeriLux Extended Care Bed, a breakthrough in safe patient handling, comfort, and modern caregiving efficiency. Designed to meet the evolving needs of senior living communities, rehabilitation centers, and long-term care facilities, the AmeriLux sets a new standard for resident care.
"We designed the AmeriLux with one mission: to create a bed that not only improves safety and comfort for residents but meaningfully enhances the workflow of caregivers. This bed represents the next evolution of thoughtful, evidence-based long-term care design." said Peter Loope, President.
Similarly, in August 2025, Sunrise Medical introduced the Empulse M90 with a groundbreaking wheel add‑on that redefines assisted mobility by blending sleek design, superior functionality, and high performance. Its integrated, lightweight build delivers discreet power assist without the bulk, wires, or external components commonly found in similar devices.
 To learn more about this report, Download Free Sample Report
The DME industry has witnessed a significant number of mergers and acquisitions, driven by the need to expand portfolios, integrate technology, and expand geographic reach. Leading players are acquiring niche companies to gain access to innovative products, advanced technologies, and established distribution networks. For instance, in June 2025, Invacare America, a global provider of home and long-term care medical products, announced a strategic partnership between its Freedom Designs and Matrx, by Motion Concepts, divisions. This collaboration brings together Freedom Designs’ custom manual wheelchair expertise with Matrx’s advanced seating technology to deliver integrated, on-chair wheelchair and seating solutions that enhance personalized comfort and support for customers.
“When crafting wheelchairs, the goal is not only to provide solutions to people with mobility challenges - it is to enhance their lives. Through this partnership, we can more effectively get products to customers that help empower individuals to move freely and comfortably in their daily lives.” said Gavriela Guerrero, managing director of Freedom Designs.
“This collaboration reinforces our commitment to delivering advanced, comprehensive mobility solutions that place users’ needs first. By increasing access to our innovative products, we can reach and support even more people who could benefit from these products.” said Judy Rowley, vice president of Matrx.
Rowley added, “We invite clinicians, providers, and stakeholders to explore these new integrated offerings and join us in maximizing patient outcomes through better mobility and seating care.”
The industry is significantly influenced by regulations that ensure the safety, quality, and efficacy of medical devices. Stringent government standards, certification requirements, and compliance protocols can increase product development time and costs for manufacturers. While these regulations protect patients and build trust in the market, they also pose challenges for new entrants and smaller companies trying to innovate. Regulatory frameworks shape market dynamics by balancing patient safety with industry growth.
The industry faces competition from various product substitutes, including non-device therapies, outpatient care, and over-the-counter medical aids. For example, physical therapy, home exercise programs, or rental equipment can replace certain mobility or rehabilitation devices. These substitutes can limit demand for high-cost or specialized DME products, encouraging manufacturers to innovate, differentiate, and focus on value-added features to maintain market share.
The Durable Medical Equipment (DME) industry exhibits high end-use concentration, with significant demand coming from hospitals, rehabilitation centers, long-term care facilities, and home healthcare settings. Hospitals and clinics drive the adoption of advanced monitoring and therapeutic devices, while home healthcare relies on mobility aids and patient care equipment. This concentration highlights the critical role of institutional buyers in shaping market trends, purchasing decisions, and product development strategies.
Analyst Perspective
The durable medical equipment market is experiencing growth driven by the rising prevalence of chronic diseases, aging population, and increasing demand for long-term patient care solutions across homecare and hospital settings. Market participants are focusing on technologically advanced, patient-centric equipment such as mobility aids, respiratory devices, monitoring systems, and rehabilitation equipment to enhance clinical efficiency and patient comfort. The shift from conventional equipment to smart, connected, and energy-efficient devices is supporting improved care delivery and operational effectiveness. In addition, the expansion of home healthcare services, growing preference for outpatient care, and increasing healthcare infrastructure investments are further strengthening market penetration. Continuous innovation in device design, portability, and remote monitoring integration is expected to create sustained long-term growth opportunities in the durable medical equipment market.
Product Insights
Based on product, the monitoring and therapeutic devices segment led the market with a 89.5% revenue share in 2025 and is expected to grow at the fastest CAGR over the forecast period. Devices such as blood sugar monitors, continuous passive motion (CPM), infusion pumps, and therapeutic aids are widely used in hospitals, rehabilitation centers, and home healthcare settings. Their essential role in improving patient outcomes, ensuring safety, and enhancing clinical efficiency makes this segment the largest contributor to market revenue. For instance, in April 2025, DexCom, Inc., a global provider of glucose biosensing, announced that the FDA cleared the Dexcom G7 15-Day Continuous Glucose Monitoring System for adults aged 18 and older with diabetes in the United States. Featuring an overall MARD of 8.0%, the Dexcom G7 15-Day builds on the proven performance of Dexcom CGM, which has been clinically shown to lower A1C, reduce hyper- and hypoglycemia, and increase time in range.
“The approval of Dexcom G7 15 Day marks another major innovation for Dexcom. By listening to the needs of our users, we’re proud to offer the longest-lasting, wearable and most accurate CGM, giving people the knowledge to better control their diabetes with our best-in-class technology. This milestone sets a new standard in CGM and is a testament to our continued leadership in glucose biosensing. We look forward to bringing it to market in the second half of this year, but in the meantime, we encourage our users to upgrade to our current G7 system to gain the benefits of the most connected CGM brand in the world.” said Jake Leach, executive vice president and chief operating officer at Dexcom.
“Dexcom G7 15 Day makes managing diabetes even easier with its extended wear and greater accuracy. Data recently released during the 18th international Advanced Technologies and Treatments for Diabetes conference in Amsterdam supports that G7 15 Day is the most accurate CGM for adults.” said Satish Garg, MD, from Barbara David Center for Diabetes at the University of Colorado School of Medicine.
The bathroom safety devices and medical furniture segment is expected to grow the fastest in the DME market during the forecast period, driven by the rising aging population and increasing focus on home safety and fall prevention. Growing awareness of injury prevention, coupled with demand for ergonomic, supportive, and accessible furniture, is fueling adoption. Innovations in design, comfort, and portability are further accelerating growth in this segment.
Increasing awareness around intimate hygiene, rising adoption of bidet technology, and the shift toward premium smart home sanitation products are expected to drive strong demand for such differentiated offerings in the coming years. For instance, in January 2026, Kohler introduced the KOHLER PureWash E860 Dual-Wand Elongated Bidet Toilet Seat - a first-to-market solution featuring both front and rear bidet wands. The product is specifically designed to support women’s health and hygiene needs across different life stages, including menstruation, pregnancy, postpartum recovery, and menopause. The launch reflects the growing demand for advanced, hygiene-focused smart bathroom solutions, particularly those tailored to women’s wellness.
"Wellness is at the heart of what we do, and this innovation addresses a gap in the home wellness market that has been neglected for a long time," said Emma Felty, Senior Product Analyst - Smart Toilets and Bidet Seats. "We are proud to offer this first to market solution that is focused on the unique needs of women of all ages, and look forward to continuing to innovate, by expanding this dual-wand experience to additional bidet products moving forward."
End Use Insights
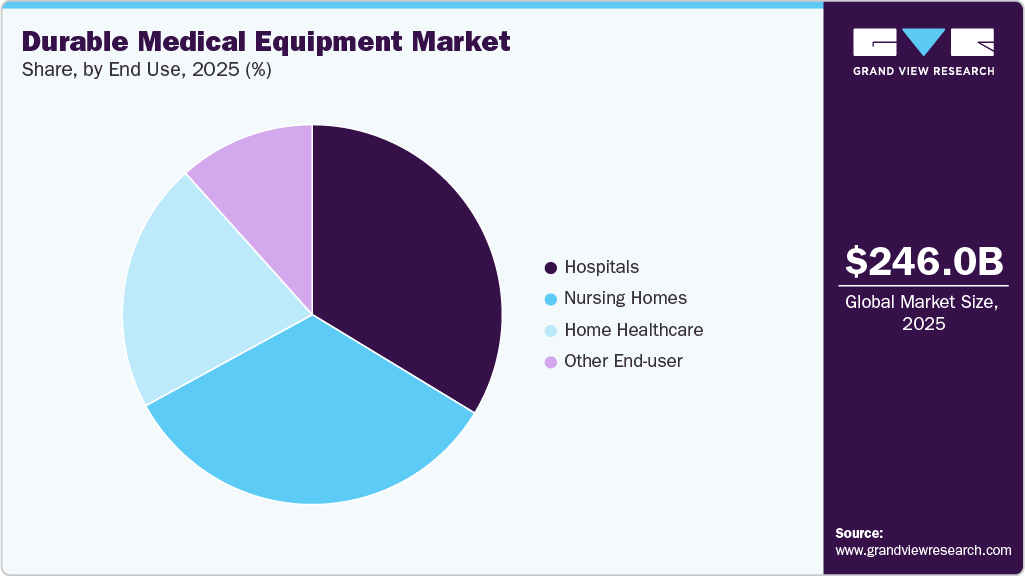
Based on end-use, the hospitals segment led the market, accounting for 34.1% of revenue in 2025, driven by the growing need for advanced patient care, surgical support, and critical care equipment. Hospitals continue to invest heavily in mobility aids, monitoring devices, and therapeutic equipment to improve patient outcomes and operational efficiency. Their large-scale procurement and preference for high-quality, technologically advanced devices make this segment a key revenue driver in the market.
 To learn more about this report, Download Free Sample Report
Home healthcare is expected to grow at the fastest CAGR over the forecast period, driven by rising patient preference for home care and an aging population. Demand for mobility aids, home monitoring systems, and portable therapeutic devices is driving this growth. In addition, advancements in lightweight, user-friendly, and connected devices are making home care more accessible and efficient, increasing market adoption.
Regional Insights
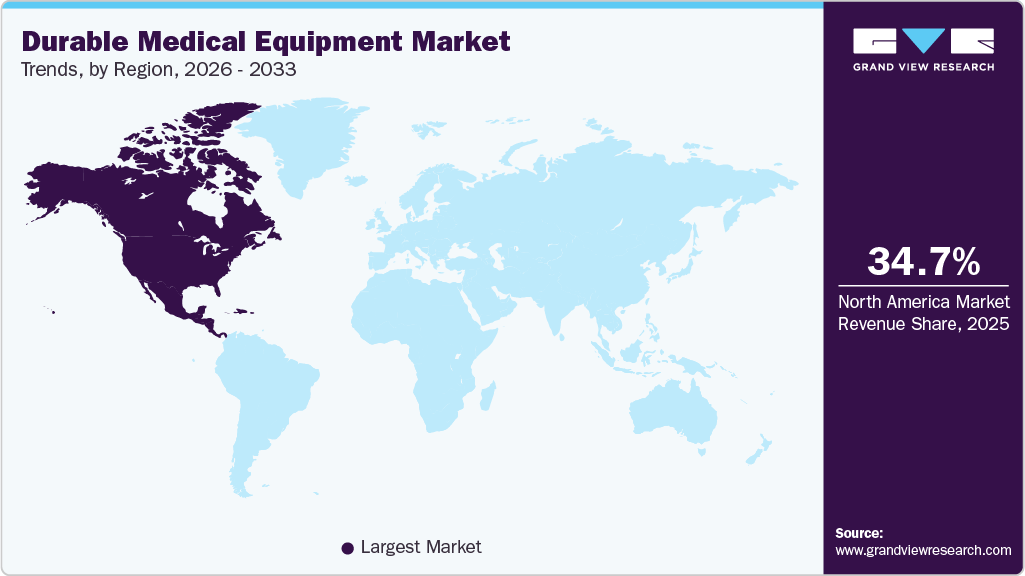
North America dominated the durable medical equipment market, accounting for the largest revenue share of 36.3% in 2025. This can be attributed to an aging population and a rising number of patients with chronic diseases who need long-term care. There is increasing demand for home healthcare devices, including mobility aids and remote monitoring equipment, as patients prefer receiving care outside hospitals. Technological advancements, such as smart and connected devices, are improving patient outcomes and driving adoption. Strong healthcare spending and supportive insurance coverage further encourage the use of durable medical equipment across hospitals and home settings.
 To learn more about this report, Download Free Sample Report
U.S. Durable Medical Equipment Market Trends
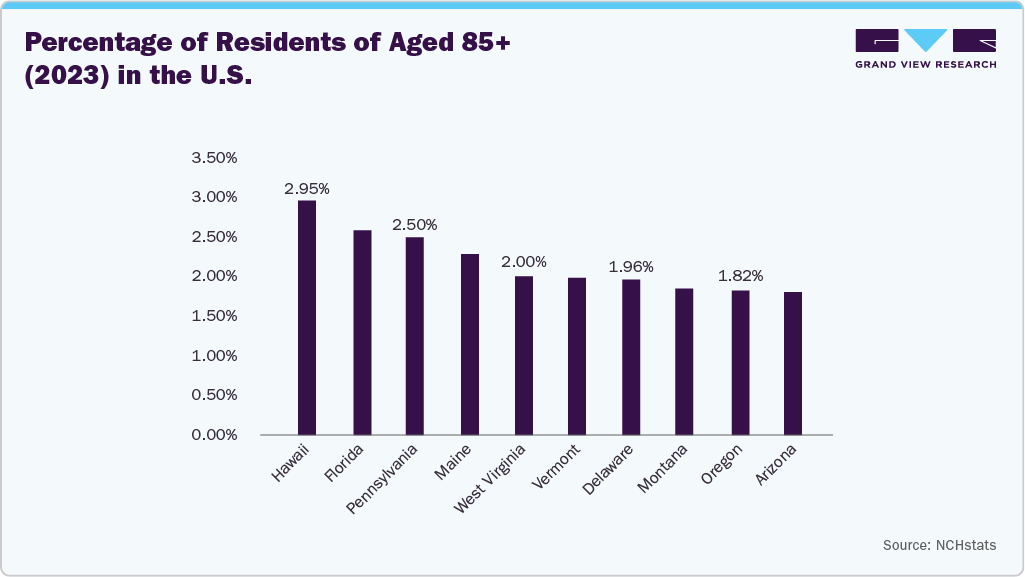
The durable medical equipment market in the U.S. held the largest share in the North America region in 2025. The durable medical equipment market in the U.S. is expanding as more patients choose home-based care and long-term management of chronic conditions. There is strong uptake of advanced, connected devices that help monitor health remotely and support independent living for the elderly. Hospitals and outpatient facilities continue to invest in durable equipment to improve care efficiency and reduce readmissions. Growing healthcare spending and broader insurance coverage also support increased adoption of these medical devices.
 To learn more about this report, Download Free Sample Report
Europe Durable Medical Equipment Market Trends
The durable medical equipment market in Europe is witnessing significant growth as healthcare systems across the region place greater emphasis on aging care and chronic disease management. There is increasing adoption of home healthcare solutions and portable monitoring devices, supported by government initiatives to reduce hospital stays and lower costs. Technological innovations, such as connected and user‑friendly equipment, are improving care quality and patient engagement. In addition, rising healthcare expenditure and reimbursement support in key European countries are driving wider use of durable medical equipment.
The UK durable medical equipment market is growing as healthcare providers and patients adopt home‑based care and long‑term support solutions. The rising prevalence of chronic illnesses and an aging population are boosting demand for mobility aids, respiratory devices, and home monitoring systems. There is also strong interest in smart, connected equipment that can share data with clinicians and improve remote care. Government healthcare policies and funding for community care continue to support wider use of durable medical equipment across the country.
The durable medical equipment market in France is evolving as healthcare systems focus on supporting aging patients and managing chronic diseases outside hospitals. Demand is rising for home‑use devices like mobility aids, respiratory equipment, and monitoring systems that help improve patient independence. There is also growing interest in connected, digital‑enabled equipment that enables remote tracking and better care coordination. Public healthcare initiatives and reimbursement policies in France continue to encourage wider adoption of durable medical devices across clinical and home settings.
Asia Pacific Durable Medical Equipment Market Trends
The durable medical equipment market in Asia Pacific is growing quickly as more countries improve their healthcare infrastructure and access. There is a growing demand for home healthcare devices, mobility aids, and patient monitoring equipment, driven by an aging population and the rise in chronic diseases. Adoption of smart, portable, and connected medical devices is helping hospitals and patients manage care more efficiently. Emerging economies in the region are also driving growth as healthcare spending and awareness continue to increase.
The China durable medical equipment market is expanding as the country invests heavily in healthcare modernization and improving access to care. There is a growing demand for home healthcare devices, rehabilitation equipment, and digital monitoring systems driven by an aging population and rising chronic disease rates. Chinese manufacturers are also focusing on innovation and cost‑competitive products, increasing domestic availability. Strong government support and improvements in reimbursement policies are further boosting market growth across both urban and rural areas.
Latin America Durable Medical Equipment Market Trends
The durable medical equipment market in Latin America is gradually growing as healthcare systems strengthen and focus more on long‑term patient care. There is increasing demand for basic home healthcare devices, mobility aids, and monitoring equipment as chronic diseases and aging populations rise across the region. Adoption of cost‑effective and easy‑to‑use equipment is expanding, particularly in urban healthcare facilities and private clinics. Continued investment in healthcare infrastructure and improved insurance coverage are supporting broader use of durable medical devices.
MEA Durable Medical Equipment Market Trends
The durable medical equipment market in the Middle East & Africa is gradually expanding as healthcare systems invest in modern medical infrastructure and services. Demand is increasing for basic mobility aids, respiratory devices, and home healthcare equipment due to rising rates of chronic disease and greater awareness of long‑term care needs. The adoption of affordable, easy‑to‑use devices is becoming more common, especially in urban centers with better healthcare access. Public and private sector efforts to improve insurance coverage and healthcare funding are further supporting market growth across the region.
According to Saudi Arabia’s Vision 2023, the country aims to increase local reserves of essential medicines, supplies, and medical devices, while developing key components of primary care, telemedicine, and virtual healthcare. This strategy directly impacts the DME market by increasing demand for home care equipment, remote monitoring devices, and technology-enabled medical solutions, thereby driving market growth and innovation.
Key Durable Medical Equipment Company Insights
The durable medical equipment market is dominated by a combination of major healthcare corporations and specialized manufacturers that offer a wide range of home care and mobility equipment. Market share is largely driven by strong distribution capabilities, product reliability, and alignment with reimbursement policies, while smaller players gain support through targeted and innovative offerings.
Key Durable Medical Equipment Companies
The following key companies have been profiled for this study on the durable medical equipment market.
-
Invacare Corporation
-
Arjo
-
Stryker Corporation
-
Hill Rom, Inc. (Baxter)
-
Drive Medical
-
GF Health Products, Inc.
-
Sunrise Medical
-
Medline Industries
-
Carex Health Brands, Inc
-
BD
-
GE HealthCare
-
Medtronic
-
Compass Health Brands
-
Getinge AB
-
ResMed Inc.
-
Cardinal Health
-
Drive DeVilbiss Healthcare (Kingswood Capital Management)
-
NOVA Medical Products
-
Kaye Products, Inc.
-
Karman Healthcare, Inc.
-
Numotion
-
Pride Mobility Products Corporation
-
Inogen, Inc.
-
CAIRE, Inc. (Niterra Group)
-
Portable Oxygen Solutions
-
Rhythm Healthcare, LLC
-
MedaCure Inc.
-
Thermo Fisher Scientific, Inc.
-
Abbott
-
F. Hoffmann-La Roche Ltd.
-
Biotronik
-
Ascensia Diabetes Care Holdings AG
-
Byram Healthcare Centers, Inc. (Owens & Minor)
-
Novo Nordisk
-
Insulet Corporation
-
B. Braun SE
-
Micrel Medical Devices SA
-
Boston Scientific Corporation
-
Tandem Diabetes Care, Inc.
-
Moog, Inc.
-
IRadimed Corporation
-
Koninklijke Philips N.V.
-
Siemens Medical Solutions USA, Inc.
-
Essity
-
Coloplast Corporation
-
Paul Hartmann AG
-
Hollister Incorporated
-
Convatec Group PLC
-
Enovis Corporation
-
Zynex, Inc.
-
ZOLL Medical Corporation (Asahi Kasei Corporation)
-
Össur (Embla Medical)
-
Breg, Inc.
-
Bauerfeind USA, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BD, GE HealthCare, Medtronic, Getinge AB, ResMed Inc., Cardinal Health)
- Focus on large-scale manufacturing, integrated supply chains, and long-term hospital contracts to ensure stable demand and efficient distribution networks.
- Expand rental models, service contracts, and reimbursement optimization strategies to increase recurring revenue and improve patient access consistently.
- Strong brand reputation, regulatory expertise, and broad product portfolios create high customer trust and significant switching barriers globally.
- Economies of scale reduce production costs, enabling competitive pricing while maintaining profitability across large-scale global operations and procurement systems.
- Heavy dependence on reimbursement policies exposes revenue to regulatory changes, reducing stability in uncertain healthcare funding environments globally.
- Slower innovation cycles compared to agile startups limit responsiveness to digital health trends and rapidly evolving homecare needs.
Emerging Players (Carex Health Brands, Inc (Compass Health Brands), NOVA Medical Products, Kaye Products, Inc., Karman Healthcare, Inc., Portable Oxygen Solutions, Rhythm Healthcare, LLC, MedaCure Inc.)
- Focus on niche product innovation, targeting homecare and ambulatory care segments with affordable, technology-enabled, durable medical equipment solutions that are globally scalable.
- Adopt asset-light manufacturing models and outsource production while partnering with contract manufacturers to reduce costs and scale international expansion quickly.
- High agility enables rapid innovation, allowing the customization of products and the faster adoption of new technologies in healthcare markets globally.
- Lower-cost structures and lean operations help compete aggressively on pricing, especially in emerging and price-sensitive healthcare markets worldwide.
- Limited brand recognition and weaker trust compared to established players restrict large hospital adoption and long-term contracts at the early stage.
- Dependence on external funding and venture capital creates financial instability and limits long-term, sustainable expansion during competitive market growth cycles.
Recent Developments
-
In January 2026, Graham-Field, a leading provider of healthcare equipment and resident-centered solutions, launched the AmeriLux Extended Care Bed, a breakthrough in safe patient handling, comfort, and caregiving efficiency. Designed to meet the evolving needs of senior living communities, rehabilitation centers, and long-term care facilities, the AmeriLux sets a new standard for resident care.
"We designed the AmeriLux with one mission: to create a bed that not only improves safety and comfort for residents, but meaningfully enhances the workflow of caregivers, This bed represents the next evolution of thoughtful, evidence-based long-term care design," said Peter Loope, President.
-
In January 2026, All Star Wheelchairs released its annual report analyzing trends in electric wheelchair use across the U.S. The 2025 report explores changing consumer preferences, demographic shifts, accessibility challenges, and the role of technology in advancing mobility solutions for people with disabilities and age-related mobility limitations.
-
In December 2025, Baxter International Inc., a provider of infusion therapies and technologies, announced collaborative data with The University of Texas Medical Branch (UTMB Health) showing that integrating smart infusion pumps with hospital electronic medical records (EMRs) positively impacts patient safety, clinicians’ bedside productivity, and programming compliance. The analysis, covering over one million infusions using Baxter’s Spectrum IQ large-volume infusion pumps (LVPs) at UTMB, was presented at the American Society of Health-System Pharmacists (ASHP) 2025 Midyear Clinical Meeting, held from December 7-10, 2025.
“Health systems face mounting challenges, from resource shortages to staff fatigue, yet remain committed to delivering the highest standards of care,” said Jay Ehrlich, MD, vice president of global patient safety and clinical research at Baxter. “Baxter is proud to provide technologies that help address these priorities and foster ongoing quality improvement initiatives to help advance patient safety and address cognitive overload for clinicians. The findings presented at ASHP, developed in collaboration with the University of Texas Medical Branch, reinforce the potential broad impact of, and opportunities associated with, smart infusion pump EMR integration.”
“Integrating smart infusion pumps with our EMR is more than a technology upgrade-it’s a commitment to safer, more efficient care at the bedside. This collaboration helps our clinicians spend less time troubleshooting and more time focusing on patients,” said Juanita Norton, PhD, MBA, MSN, CPHQ, RN-BC, CPN, CLSSBB, program manager, quality improvement, The University of Texas Medical Branch.
-
In November 2025, Abbott initiated a medical device correction in the United States for certain FreeStyle Libre 3 and FreeStyle Libre 3 Plus sensors after internal testing revealed that some sensors might produce inaccurate low-glucose readings.
-
In August 2025, Sunrise Medical introduced the Empulse M90 with a groundbreaking wheel add‑on that redefines assisted mobility by blending sleek design, superior functionality, and high performance. Its integrated, lightweight build delivers discreet power assist without the bulk, wires, or external components commonly found in similar devices.
-
In August 2025, Sunrise Medical, a global provider of advanced assistive mobility solutions, launched the Voice Activation feature for its Switch-It CTRL+5 power seating control module, becoming the first company in the industry to offer a voice-activated power seating system.
-
In June 2025, Invacare America, a global provider of home and long-term care medical products, announced a strategic partnership between its Freedom Designs and Matrx, by Motion Concepts, divisions. This collaboration brings together Freedom Designs’ custom manual wheelchair expertise with Matrx’s advanced seating technology to deliver integrated, on-chair wheelchair and seating solutions that enhance personalized comfort and support for customers.
-
In April 2025, DexCom, Inc., a global provider of glucose biosensing, announced that the FDA cleared the Dexcom G7 15-Day Continuous Glucose Monitoring System for adults aged 18 and older with diabetes in the U.S. Featuring an overall MARD of 8.0%, the Dexcom G7 15-Day builds on the proven performance of Dexcom CGM, which has been clinically shown to lower A1C, reduce hyper- and hypoglycemia, and increase time in range.
“The approval of Dexcom G7 15 Day marks another major innovation for Dexcom. By listening to the needs of our users, we’re proud to offer the longest-lasting, wearable and most accurate CGM, giving people the knowledge to better control their diabetes with our best-in-class technology. This milestone sets a new standard in CGM and is a testament to our continued leadership in glucose biosensing. We look forward to bringing it to market in the second half of this year, but in the meantime, we encourage our users to upgrade to our current G7 system to gain the benefits of the most connected CGM brand in the world.” said Jake Leach, executive vice president and chief operating officer at Dexcom.
-
In March 2025, Airchair, a wheelchair manufacturer, launched the Airchair II, specifically designed to comply with US DOT Regulation 14 CFR Part 382.65. Its innovative design addresses aircraft space constraints while meeting the needs of passengers with reduced mobility. Airlines and cabin crew benefit from a lightweight (6.8 kg / 15 lb) aisle chair that is easy to stow, deploy, and maneuver throughout the aircraft.
-
In March 2025, Graham-Field introduced the Hausted 5B800ST All-Purpose Bariatric Electric Stretcher, engineered to meet patient management needs while offering the versatility to support every phase of care, from pre-op treatment to post-op recovery.
"As the number of bariatric patients increases, healthcare facilities need proper equipment to safely care for these patients while ensuring staff safety. Our new All Purpose Bariatric stretcher not only provides patient comfort but also enhances efficiency with features like the optional Navigator Power Drive System- an improvement that every hospital seeks," said Cynthia Counts, Chief Product Officer for Graham-Field.
-
In October 2024, Permobil is launching two new aluminum ultra-lightweight manual wheelchairs, the TiLite X and TiLite Z, offering best-in-class performance, over 1 billion configuration options, and industry-leading 5-day lead times.
“We have taken everything you know and love about our TiLite products and made them even better. With a tremendous focus on end user and customer insights, we have improved functionality, simplicity, weight, weight capacity and lead times - all while keeping our industry-best configurability and durability. I couldn’t be prouder of what our team has accomplished,” said Chuck Witkowski, president of Permobil Americas.
“Our goal with the TiLite X and Z was to deliver the quality, performance, durability, and customizability of TiLite chairs to as many people as possible. We are proud to say we have delivered on that and are excited to expand TiLite to more users.” said Cody Verrett, VP and general manager of Permobil Americas.
-
In June 2024, Invacare employees from 20 countries participated in a global fundraising campaign, raising more than USD 28,000. With each wheelchair costing USD 96, the funds raised will provide 294 wheelchairs through Free Wheelchair Mission to people with disabilities in under-resourced countries, helping transform lives by improving mobility, independence, and quality of life.
“The Move for Mobility global fundraiser was a very successful effort of the Invacare team. This campaign illustrates our company’s commitment to accessibility and inclusion across communities worldwide.” said Geoff Purtill, our Invacare’s President and CEO, spent the last week in the Dominican Republic distributing wheelchairs with Free Wheelchair Mission.
-
In April 2024, GF Health Products, Inc. announced the acquisition of substantially all assets of Transfer Master Products, Inc. (“TMP”), a company with over 30 years of experience designing and manufacturing high-quality hi-low adjustable beds for home and healthcare settings.
Durable Medical Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 246.0 billion
Estimated market size in 2026
USD 260.8 billion
Projected market size by 2033
USD 379.8billion
Growth rate
CAGR of 5.5% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use & region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Invacare Corporation; Arjo; Stryker Corporation; Hill Rom, Inc. (Baxter); Drive Medical; GF Health Products, Inc.; Sunrise Medical; Medline Industries; Carex Health Brands, Inc; BD; GE HealthCare; Medtronic; Compass Health Brands; Getinge AB; ResMed Inc.; Cardinal Health; Drive DeVilbiss Healthcare; NOVA Medical Products; Kaye Products, Inc.; Karman Healthcare, Inc.; Numotion; Pride Mobility Products Corporation; Inogen, Inc.; CAIRE, Inc. (Niterra Group); Portable Oxygen Solutions; Rhythm Healthcare, LLC; MedaCure Inc.; Thermo Fisher Scientific, Inc., among others.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Durable Medical Equipment Market Report Segmentation
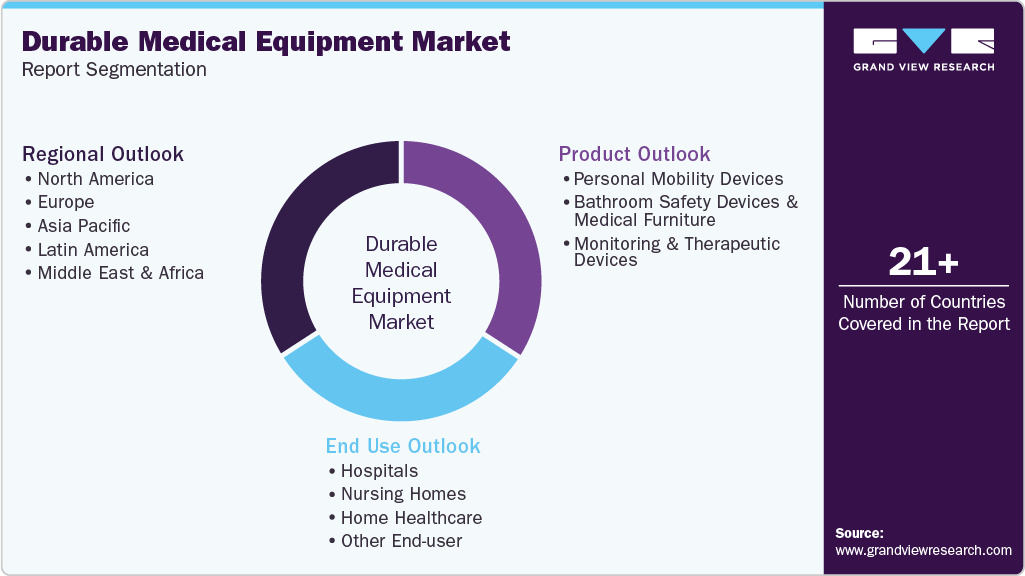
This report forecasts revenue growth at global, regional, and country levels and provides an analysis on the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global durable medical equipment market report on the basis of product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million; 2021 - 2033)
-
Personal Mobility Devices
-
Wheelchairs
-
Scooters
-
Walker and Rollators
-
Canes and Crutches
-
Door Openers
-
Other Devices
-
-
Bathroom Safety Devices and Medical Furniture
-
Commodes and Toilets
-
Mattress & Bedding Devices
-
-
Monitoring and Therapeutic Devices
-
Blood Sugar Monitors
-
Continuous Passive Motion (CPM)
-
Infusion Pumps
-
Nebulizers
-
Oxygen Equipment
-
Continuous Positive Airway Pressure (CPAP)
-
Suction Pumps
-
Traction Equipment
-
Others Equipment
-
-
-
End Use Outlook (Revenue, USD Million; 2021 - 2033)
-
Hospitals
-
Nursing Homes
-
Home Healthcare
-
Other End-user
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The durable medical equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each durable medical equipment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Personal Mobility Devices
This segment tracks total global sales and rental revenues generated from long-term assistive movement equipment. It includes standard and motorized wheelchairs, mobility scooters, walkers, rollators, canes, and crutches, specifically capturing expenditures by hospitals, care facilities, and retail consumers, while excluding short-term consumer fitness aids.
Bathroom Safety Devices and Medical Furniture
Market revenue for this category encompasses the total spending on specialized patient care support structures and fall-prevention equipment. It measures the financial value of hospital beds, lift chairs, commodes, shower chairs, grab bars, and transfer benches across clinical settings and private residences, excluding standard consumer home furnishings.
Monitoring and Therapeutic Devices
Revenue for this division includes durable, long-term non-disposable home healthcare equipment. It aggregates the market value of oxygen concentrators, CPAP machines, nebulizers, infusion pumps, continuous glucose monitors, and patient telemetry units, isolating hardware sales and leasing fees from recurring software subscription costs.
Estimation Model
Market Estimation Approach
Brief Content
Bottom-Up Epidemiological Modeling
DME patient population estimation across conditions and care settings using prevalence, incidence, and progression rates. Incorporates modality uptake, prescription rates, treatment duration, and regional demographic adjustments.
Top-Down Revenue Triangulation
Analyzing total DME market revenues reported by key manufacturers, distributors, payers, and CMS sources, allocating shares by product categories, end users, and regions based on price and utilization trends.
Demand-Side Care-Setting Modeling
Assessing DME volumes across care settings (home care, hospitals, long-term care), factoring in patient preferences, clinical suitability, reimbursement policies, and insurance coverage levels.
Supply-Side Capacity & Utilization Modeling
Evaluating installed manufacturing capacity, utilization rates, and supplier density to estimate achievable production, identifying capacity constraints vs. underutilized regions.
Data Triangulation & Market Reconciliation
Synthesizing outputs from multiple models with claims data, regulatory filings, hospital procurement data, and expert insights to ensure robust, validated DME market size estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
ASP and volume analysis (historical and forecast)
Comprehensive ASP (Average Selling Price) and volume analysis for Durable Medical Equipment (DME) products across 2021-2033, segmented by product category (mobility devices, respiratory equipment, patient monitoring devices, hospital beds, rehabilitation equipment, bathroom safety devices, diabetic care equipment, pressure relief devices, and home care products), care setting (home healthcare, hospitals, long-term care facilities, ambulatory care centers), and geography. Includes historical pricing trends, procurement patterns, reimbursement dynamics, and forward-looking forecasts based on utilization rates, technological advancements, and demographic trends.
Enables long-term revenue forecasting, pricing optimization, identification of high-growth product categories, and supports strategic planning through visibility into ASP trends, reimbursement changes, and volume-driven market expansion opportunities.
Patient population and disease burden analysis
Detailed assessment of the patient population requiring DME, including prevalence and incidence of chronic respiratory diseases, diabetes, cardiovascular diseases, musculoskeletal disorders, neurological conditions, obesity, aging-related disabilities, and post-operative recovery. Includes patient segmentation by age group, disease severity, homecare eligibility, and regional demand patterns.
Supports accurate demand forecasting, product utilization estimation, reimbursement strategy development, healthcare resource planning, and long-term market sizing across major DME categories.
Market share analysis by manufacturer and product category
Revenue- and volume-based market share estimation by manufacturer across mobility aids, respiratory devices, hospital beds, patient lifts, wheelchairs, walkers, CPAP/BiPAP systems, oxygen concentrators, diabetic care devices, and rehabilitation equipment, segmented by product category, distribution channel, and geography. Includes competitive benchmarking, pricing analysis, portfolio comparison, and innovation assessment.
Provides insights into competitive positioning, procurement trends, product leadership, distribution strength, and growth opportunities across institutional and home healthcare markets.
Frequently Asked Questions About This Report
The global durable medical equipment market size was valued at USD 246.0 billion in 2025 and is estimated at USD 260.8 billion for 2026.
Key factors that are driving the durable medical equipment market growth include the rising prevalence of chronic disease, increasing geriatric population base across the globe, and better coverage and reimbursement policies for DME products.
The global durable medical equipment market is expected to grow at a CAGR of 5.5% from 2026 to 2033, reaching USD 379.8 billion.
North America dominated with a 36.3% revenue share in 2025.
The monitoring and therapeutic devices segment held the largest market share of 89.5% in 2025, and it is the fastest-growing segment.
The hospitals segment held the largest market share of 34.1% in 2025, and it is the fastest-growing segment.
Key players include Invacare Corporation, Arjo, Stryker Corporation, Hill Rom, Inc. (Baxter), Drive Medical, GF Health Products, Inc., Sunrise Medical, Medline Industries, Carex Health Brands, Inc, BD, GE HealthCare, Medtronic, Compass Health Brands, Getinge AB, ResMed Inc., Cardinal Health, Drive DeVilbiss Healthcare (Kingswood Capital Management), NOVA Medical Products, Kaye Products, Inc., Karman Healthcare, Inc., Numotion, Pride Mobility Products Corporation, Inogen, Inc., CAIRE, Inc. (Niterra Group), Portable Oxygen Solutions, Rhythm Healthcare, LLC, MedaCure Inc., Thermo Fisher Scientific, Inc., Abbott, F. Hoffmann-La Roche Ltd., Biotronik, Ascensia Diabetes Care Holdings AG, Byram Healthcare Centers, Inc. (Owens & Minor), Novo Nordisk, Insulet Corporation, B. Braun SE, Micrel Medical Devices SA, Boston Scientific Corporation, Tandem Diabetes Care, Inc., Moog, Inc., IRadimed Corporation, Koninklijke Philips N.V., Siemens Medical Solutions USA, Inc., Essity, Coloplast Corporation, Paul Hartmann AG, Hollister Incorporated, Convatec Group PLC, Enovis Corporation, Zynex, Inc., ZOLL Medical Corporation (Asahi Kasei Corporation), Össur (Embla Medical), Breg, Inc., and Bauerfeind USA, Inc.
Rising demand for home healthcare services, a growing aging population, and an increasing prevalence of chronic diseases requiring long-term care. Technological advancements in smart, connected devices and remote patient monitoring further enhance adoption and expand market penetration globally.
Key restraints in the durable medical equipment market include high upfront costs of advanced devices, limited reimbursement coverage in several regions, and affordability challenges in low-income populations. In addition, complex regulatory approval processes and maintenance requirements can slow adoption and restrict market expansion.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


