
- Home
- »
- Medical Devices
- »
-
ENT Devices Market Size, Share And Report, 2026-2033GVR Report cover

ENT Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Hearing Aids, Hearing Implants, Diagnostic ENT Devices, Surgical ENT Devices, Nasal Splints), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$29.0BMarket Estimate, 2026
$30.8BMarket Forecast, 2033
$47.0BCAGR, 2026–2033
6.2%ENT Devices Market Summary
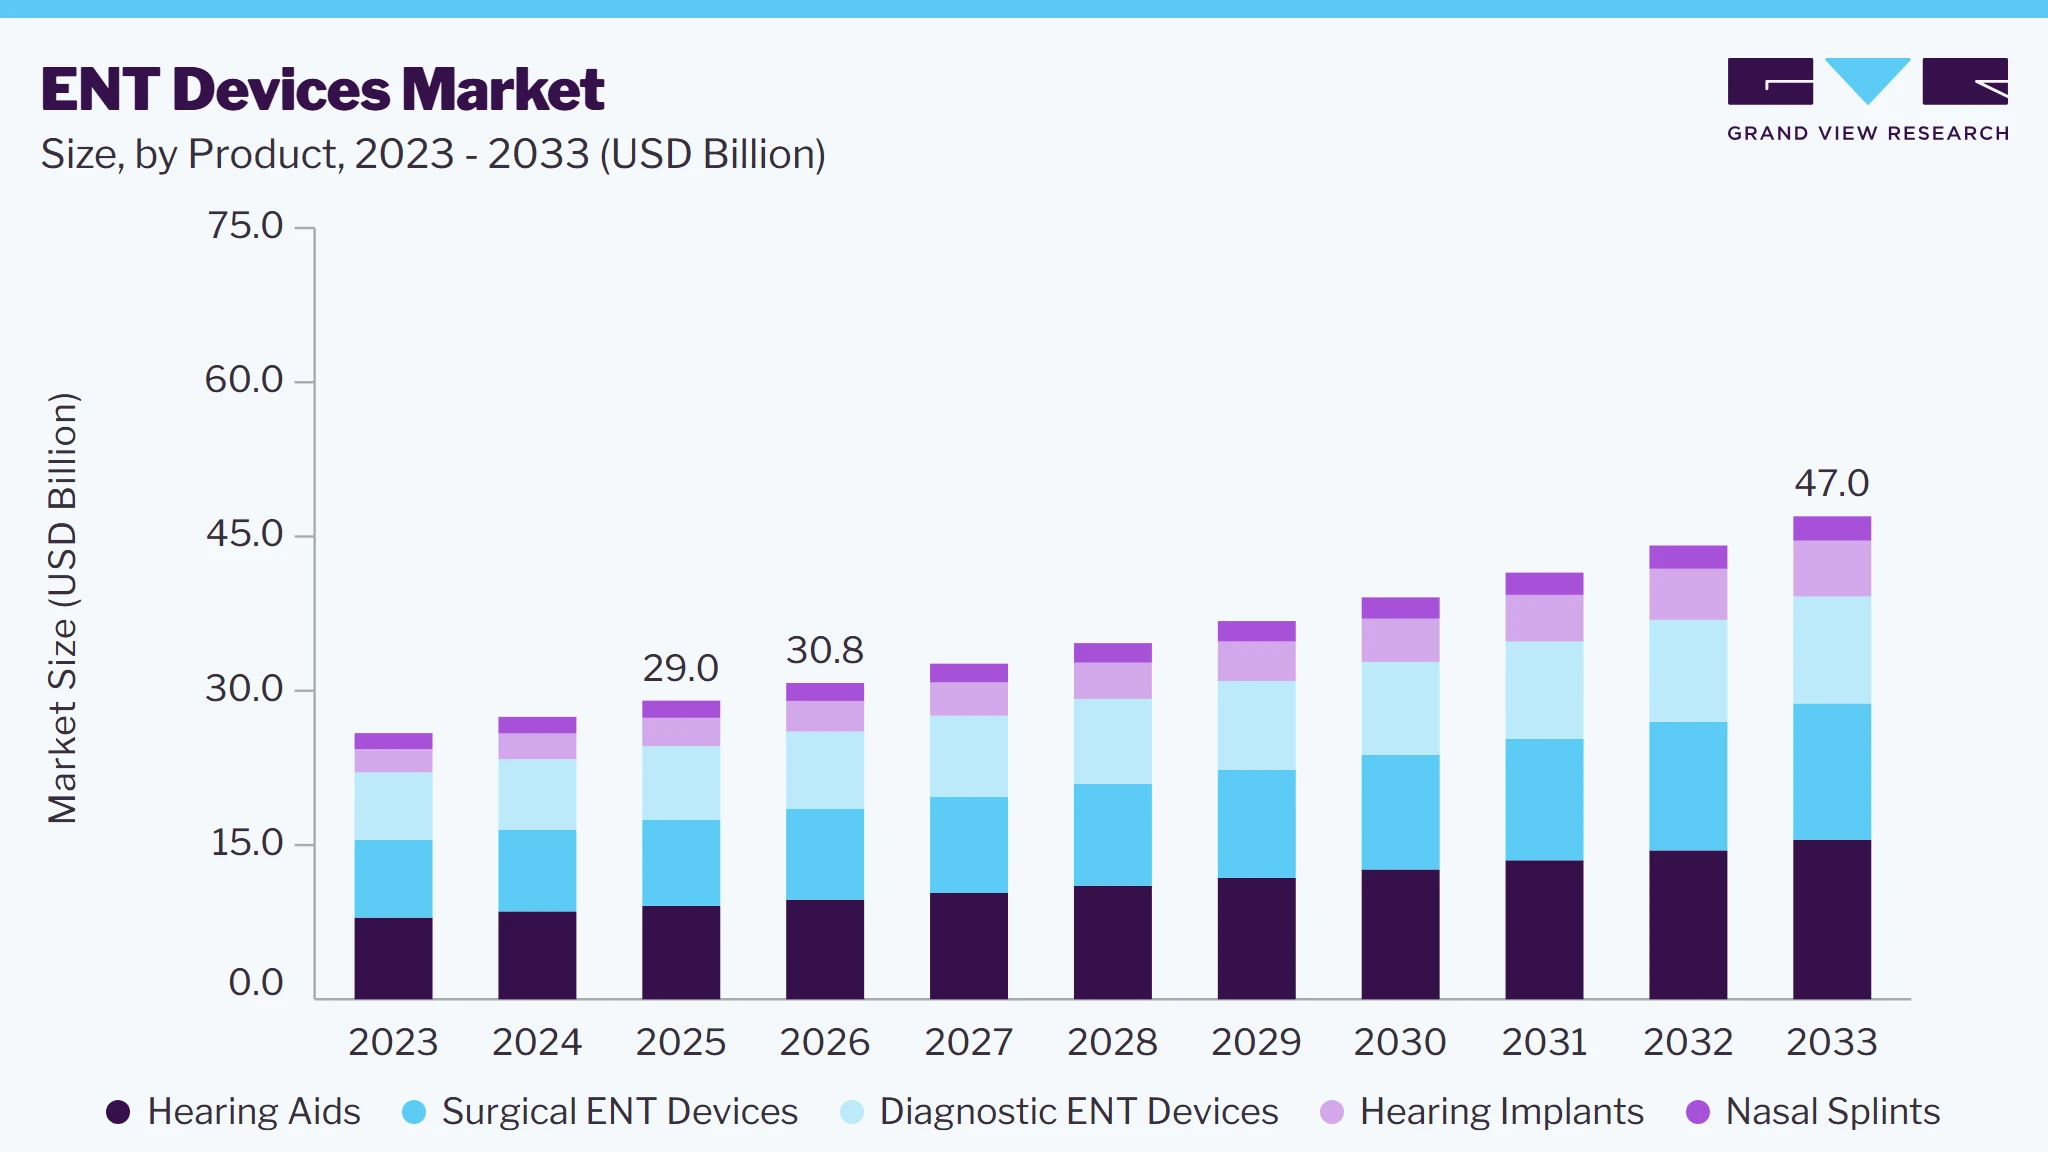
The global ENT devices market size was valued at USD 29.0 billion in 2025 and is projected to grow from USD 30.8 billion in 2026 to USD 47.0 billion by 2033, at a CAGR of 6.2% from 2026 to 2033. North America dominated the global market with the largest revenue share of 36.4% in 2025. Hearing loss and impairment have become a significant public health concern, particularly in developed economies.
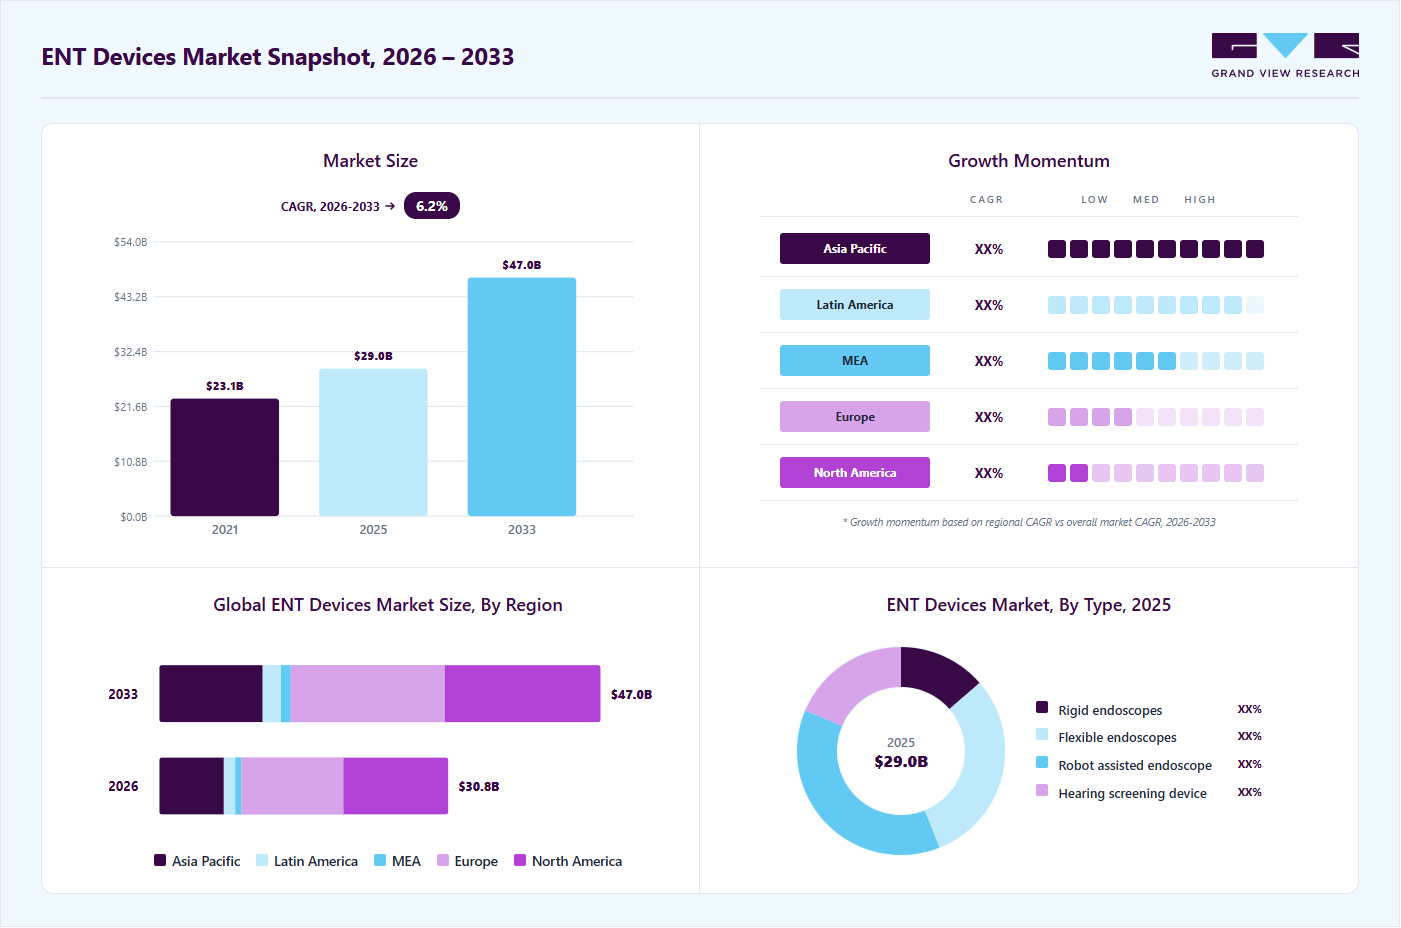 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Hearing aids segment led the market with the largest revenue share of 31.3% in 2025.
Regional Highlights
- Largest regional market: North America (36.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The ENT devices market in the U.S. held the largest share in the North America region in 2025.
Market Size & Forecast
- Market Size in 2025: USD 29.0 Billion
- Estimated Market Size in 2026: USD 30.8 Billion
- Projected Market Size by 2033: USD 47.0 Billion
- CAGR (2026-2033): 6.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The prevalence of hearing loss is increasing; it is considered one of the most common conditions affecting patients globally. According to WHO factsheet of February 2024, around 5% of the global population requires rehabilitation to address their hearing loss.Moreover, around 2.5 billion individuals are projected to have some hearing loss by 2050, and around 700 million are expected to require hearing rehabilitation by 2050. Primary factors expected to contribute to the rise in age-related hearing loss are the increasing life expectancy and the growing noise pollution. In low-income countries, common causes of hearing impairment include infections such as measles, middle ear infections, and meningitis.
 To learn more about this report, Download Free Sample Report
Chronic inflammation, exposure to loud noises, vascular issues, natural aging processes affecting the ear, and genetic predispositions can further contribute to the increasing prevalence of hearing impairment or loss. According to the European Hearing Instrument Manufacturers Association (EHIMA), hearing aid unit sales by its members increased by around 4.7% to reach 20.25 million units in 2022. Thus, the rise in hearing aid sales and the high prevalence of hearing loss are expected to drive the market.
Global hearing aids unit sales, 2017-2022
Year
Hearing Aid Unit Sales (Million)
Percent Growth
2017
15.05
+5.7%
2018
16.04
+6.6%
2019
17.06
+6.4%
2020
14.12
-17.2%
2021
19.34
+37.0%
2022
20.25
+4.7%
Source: European Hearing Instrument Manufacturers Association (EHIMA)
The demand for ENT devices is high among the elderly, driven by the increasing prevalence of hearing loss, the growing geriatric population, and the rising adoption of minimally invasive ENT procedures. In addition, geriatric patients often require specialized ENT devices for hearing aids, implants, and other related treatments, contributing to this demographic group’s high demand for ENT devices. Hearing impairment is a partial or total inability to hear. It is one of the most common conditions affecting the geriatric population. According to the National Institute on Deafness and Other Communication Disorders (NIDCD), about one out of every three people aged 65 to 74 years are affected by hearing loss, and 50% of people older than 75 years have difficulty hearing.
Furthermore, increasing penetration of minimally invasive ENT procedures is fostering market growth. Minimally invasive surgeries are gradually replacing traditional surgical methods in advanced countries, such as the U.S., UK, and Japan. Minimally invasive ENT procedures offer benefits such as reduced tissue damage, shorter operation times, and quicker patient recovery, resulting in improved patient outcomes. Traditional surgeries typically necessitate incisions to access internal body parts, requiring precision and expertise. On the other hand, minimally invasive ENT procedures offer advantages such as lower blood loss, reduced anesthesia requirements, lower infection risks, smaller incisions, shorter hospital stays, and faster recovery, often leading to better results.
Market Dynamics
The ENT devices market is driven by the rising prevalence of hearing loss, sinus disorders, sleep apnea, and throat-related conditions, coupled with a growing aging population that is more susceptible to ENT diseases. Healthcare providers are investing in advanced ENT equipment to improve diagnostic accuracy and treatment outcomes.
The increasing burden of hearing loss continues to be one of the major factors supporting growth in the ENT devices market. Hearing impairment is widely recognized as one of the most common health conditions globally, with a particularly high impact among older adults. According to the WHO’s February 2024 factsheet, more than 5% of the global population requires rehabilitation for disabling hearing loss. The burden is expected to rise further, with nearly 2.5 billion people projected to have some degree of hearing loss by 2050, including around 700 million who may require hearing rehabilitation.
Several factors are contributing to this increase, including longer life expectancy, higher exposure to occupational and environmental noise, chronic ear infections, genetic factors, and age-related changes in the auditory system. In low- and middle-income countries, conditions such as measles, meningitis, and untreated middle ear infections also remain important contributors to hearing impairment. As a result, demand for hearing aids, cochlear implants, audiology diagnostics, and other ENT treatment solutions is expected to remain strong over the forecast period.
The aging population is an especially important demand group for ENT devices. Hearing difficulty increases significantly with age, creating a steady need for hearing assessment, rehabilitation, and long-term device support. According to the National Institute on Deafness and Other Communication Disorders, nearly one in three people aged 65 to 74 years has hearing loss, while almost half of those aged above 75 years experience hearing difficulty. This age-linked demand is expected to support broader adoption of hearing aids, implantable hearing devices, and related ENT products. In line with this trend, the European Hearing Instrument Manufacturers Association reported that hearing aid unit sales by its members increased by around 2.1% to reach 23.16 million units in 2025.
Recent service expansion by ENT providers also reflects this shift toward advanced and less invasive care models. For instance, in March 2026, Integrative Ear, Nose & Throat opened a new facility in Lindenhurst, New York, offering minimally invasive sinus care, balloon sinuplasty, sleep apnea treatment, pediatric ENT services, and hearing evaluations. Such developments indicate increasing investment in accessible, procedure-based ENT care and are expected to support demand for diagnostic, surgical, and therapeutic ENT devices.
Stringent regulatory requirements remain a key restraint for the ENT devices market, particularly for manufacturers of advanced diagnostic, surgical, implantable, and digitally enabled devices. Products such as hearing implants, endoscopes, surgical navigation systems, and minimally invasive ENT devices must undergo detailed regulatory review before commercialization. Regulatory bodies, including the U.S. FDA, European authorities under the EU Medical Device Regulation, notified bodies, and national health agencies, require evidence related to device safety, clinical performance, quality, and reliability.
These approval processes often involve preclinical testing, clinical evaluation, risk assessment, quality management review, and post-market safety planning. While necessary to ensure patient safety, they can increase product development costs and delay market entry. The impact is particularly high for smaller and emerging manufacturers with limited regulatory and financial resources.
The challenge is further intensified by variation in approval pathways across countries. Companies targeting multiple markets must comply with different documentation, labeling, quality system, and clinical evidence requirements, which adds operational complexity. In addition, connected and software-enabled ENT devices are facing greater scrutiny around cybersecurity, software validation, data protection, and real-world performance monitoring. As a result, manufacturers must continue investing in regulatory expertise and compliance systems, which may slow the introduction of new ENT technologies.
The development of robotic-assisted surgery and artificial intelligence-enabled diagnostic systems is creating new growth avenues for the ENT devices market. AI algorithms assist clinicians in disease detection, image interpretation, hearing assessment, and treatment planning, improving diagnostic accuracy and clinical efficiency. Robotic technologies are also enhancing surgical precision in complex ENT procedures involving delicate anatomical structures. For instance, in March 2026, Medtronic received FDA clearance for its Stealth AXiS surgical system for cranial and ENT procedures. The platform combines planning, navigation, and robotics to improve workflow and surgical precision, providing anatomy-specific visualization for the sinuses and skull base.
“The Stealth AXiS surgical system represents the next era of navigation for ENT surgery. Building on 25 years of navigation leadership, this system is designed to help surgeons move with greater clarity, confidence, and control in the OR, while creating a powerful platform for the next generation of ENT innovation.”
- Sean Haag, president of the Ear, Nose, & Throat business at Medtronic.
These innovations support personalized treatment approaches, reduce procedural variability, and improve patient outcomes. Healthcare providers are increasingly interested in technologies that enhance clinical decision-making and operational efficiency. As research and development efforts continue to advance AI and robotic applications within otolaryngology, manufacturers have significant opportunities to introduce next-generation ENT devices that address evolving clinical needs and strengthen their competitive position.
Market Concentration & Characteristics
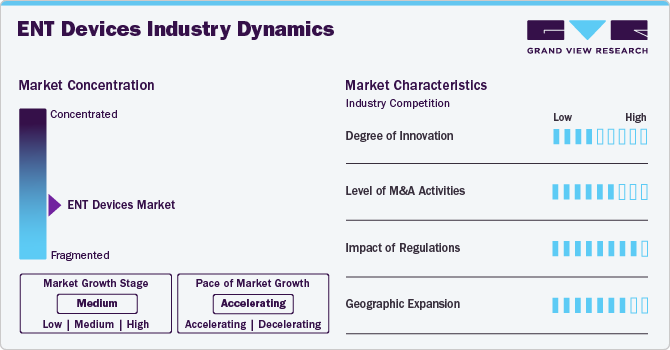
The chart below illustrates the relationship between industry concentration, industry characteristics, and industry participants. The x-axis represents the level of industry concentration, ranging from low to high. The y-axis represents various industry characteristics, including industry competition, degree of innovation, impact of regulations, level of merger & acquisition activities, and geographic expansion.
The degree of innovation is notably high, driven by continuous technological advancements, growing patient demand for minimally invasive procedures, and the need for improved diagnostic accuracy and therapeutic outcomes. Companies are investing heavily in research and development to introduce products that are smaller, more precise, and integrated with digital technologies such as AI, robotics, and image-guided systems. Innovations such as 3D-printed implants, balloon sinuplasty devices, and advanced hearing aids with wireless connectivity show the shift toward personalized and efficient care. In February 2024, GN Store Nord A/S expanded its existing portfolio of ReSound Nexia hearing aids with a new range of styles and connectivity.
 To learn more about this report, Download Free Sample Report
Several key market players are devising business growth strategies in the form of mergers and acquisitions. Through M&A activity, these companies can expand their business. For instance, in January 2024, Karl Storz acquired Innersight Labs Ltd., which is based in London. It is a manufacturer of innovative software.
Regulations play a critical role in shaping the ENT devices market by ensuring the safety, efficacy, and quality of products. Regulatory frameworks, such as the FDA in the U.S. and the MDR (Medical Device Regulation) in Europe, govern the approval, classification, and monitoring of ENT devices. These regulations establish strict guidelines for pre-market approvals, post-market surveillance, and adverse event reporting, ensuring that devices meet safety standards before they reach patients.
Several market players are expanding their business by entering new geographical regions to strengthen their market position and expand their product portfolio. In April 2024, Karl Storz expanded its business in Belgium, Luxembourg, and the Netherlands, with the acquisition of related business of distributor Stöpler.
Analyst Perspective
The global ENT devices market is characterized by the presence of diversified medical technology companies and specialized ENT-focused manufacturers competing through innovation, clinical effectiveness, and portfolio expansion. Established players such as Cochlear, Sonova, Demant, GN Store Nord, Olympus, Karl Storz, Stryker, and MED-EL maintain strong market positions through extensive product portfolios that cover hearing care, diagnostic endoscopy, and surgical ENT applications. Their investments in digital hearing technologies, minimally invasive surgical solutions, advanced visualization systems, and AI-enabled diagnostic capabilities continue to strengthen competitive differentiation.
Moreover, specialized companies such as Ambu, PENTAX Medical, Richard Wolf, Starkey, Rion, and Nemera are leveraging focused expertise to address specific segments within the ENT ecosystem. These companies often compete through innovation in single-use endoscopy, specialized hearing solutions, and niche diagnostic technologies. As healthcare providers increasingly seek minimally invasive procedures, improved diagnostic accuracy, and personalized hearing care solutions, competition is expected to intensify around technological advancements, clinical outcomes, product usability, and cost-effectiveness. Strategic partnerships, product launches, and geographic expansion initiatives are likely to remain key growth strategies across the market.
Product Insights
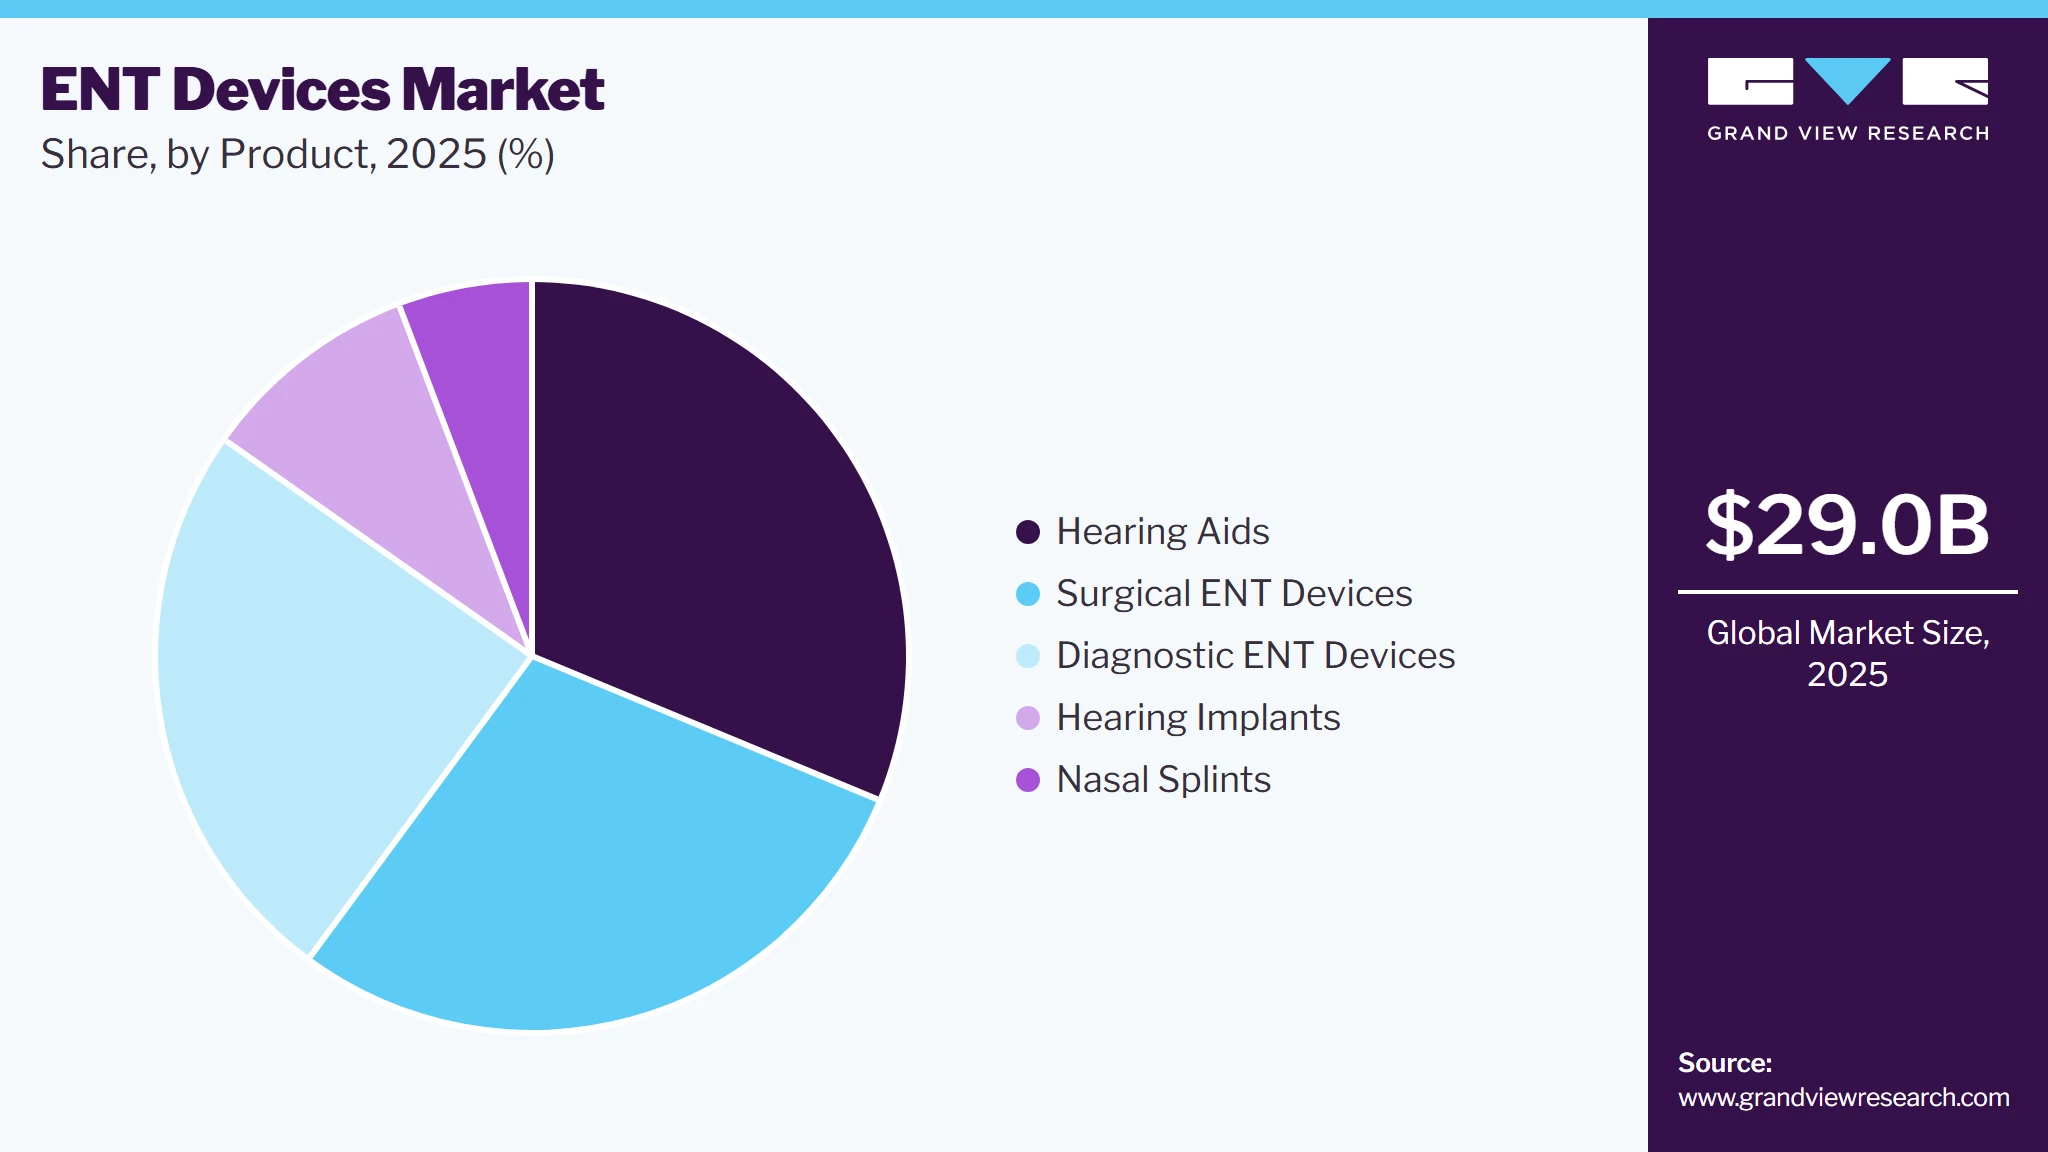
Based on product, the hearing aids segment led the market with the largest revenue share of 31.3% in 2025. However, the hearing implants segment is expected to grow at the fastest CAGR over the forecast period. Factors expected to contribute to market growth include increasing investments, new product launches, acquisitions, & technological advancements aimed at improving hearing and accurately diagnosing ear disorders. For instance, in March 2023, EssilorLuxottica acquired Nuance Hearing, an Israel-based start-up. This acquisition was expected to help EssilorLuxottica expand its presence in the hearing aids business by developing lenses fitted with acoustic technology, aiming to gain access to new technologies and establish its position in a rapidly growing market.
 To learn more about this report, Download Free Sample Report
The surgical ENT devices segment is anticipated to register a considerable growth rate over the forecast period. The increasing prevalence of ENT disorders, technological advancements in surgical devices, and rising demand for minimally invasive procedures are expected to drive market growth during the forecast period. In addition, efforts to promote the adoption of cochlear implants are likely to positively impact market growth. According to the World Health Organization (WHO), approximately 5% of the global population suffers from hearing loss, affecting nearly 432 million adults and 34 million children. By 2050, it is estimated that 2.5 billion people will suffer from hearing loss, with 700 million requiring hearing aids or surgery, thereby increasing the demand for cochlear implant devices.
Regional Insights
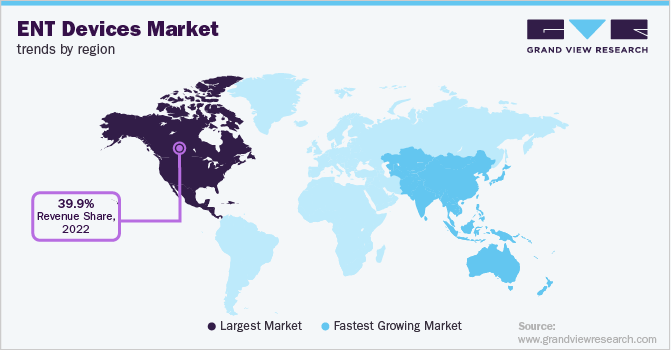
North America dominated the ENT devices market with the largest revenue share of 36.4% in 2025. Key factors contributing to growth of this region are growing geriatric population and increasing prevalence of hearing loss. Furthermore, approval and launch of advanced, next generation hearing devices in the U.S. & Canada and high adoption of hearing aids are likely to boost the market growth.
 To learn more about this report, Download Free Sample Report
U.S. ENT Devices Market Trends
The ENT devices market in the U.S. held the largest share in the North America region in 2025, due to technological advancements and recent approvals received for several hearing devices. Manufacturers are investing in R&D to obtain approvals for new products for commercialization. For instance, in December 2020, Advanced Bionics, in collaboration with Phonak, received FDA approval for Marvel hearing technology. This includes Sky CI Marvel, New Naída, and New Advanced Bionics Remote app for easy adjustments via smartphone.
Canada ENT devices market is anticipated to register the fastest growth during the forecast period. Canada's medical device market is ranked 8th in the world, and most establishments in the medical devices industry are located in British Columbia, Quebec, Ontario, and Alberta. The Canadian ENT devices market is expected to witness growth during the forecast period, which can be attributed to growing preference for minimally invasive surgical procedures, technological advancements, and increasing geriatric population suffering from ENT-related diseases.
Europe ENT Devices Market Trends
Europe ENT devices market is anticipated to register considerable growth during the forecast period. The UK, Germany, Italy, France, and Spain are the main markets in this region. Increasing geriatric population in developed countries, such as the UK, Germany, Italy, and France, are some of the factors anticipated to drive growth over the forecast period.
Germany ENT devices market is anticipated to register a significant growth rate during the forecast period. Germany is one of the countries with the fastest aging population. Factors such as increasing adoption of minimally invasive surgeries, introduction of advanced products, and other business activities, such as mergers & acquisitions, will contribute to growth of ENT devices market in Germany. For instance, in February 2023, a Germany-based company, KARL STORZ, acquired 100% of AventaMed DAC, an Irish medical technologies company, to strengthen its ENT Portfolio. AventaMed specializes in developing single-use medical devices and has created the Solo+ TTD, which is a new method of treatment addressing the current issues with ENT surgical tympanostomy procedures.
The ENT devices market in UK is anticipated to register a considerable growth rate during the forecast period. ENT UK is actively involved in developing new initiatives such as a virtual reality training simulation based on pediatric emergency national guidelines. These initiatives aim to enhance training and improve patient care in the field of ENT surgery. Thus, such factors are expected to drive the demand for technically advanced ENT devices in the country.
Asia Pacific ENT Devices Market Trends
Asia Pacific is anticipated to be the significantly growing region in the market. Technological innovations, such as real-time monitoring, wireless technology, increase in healthcare spending in the Asia Pacific region, and support from regulatory bodies are anticipated to promote growth of the ENT devices market. In addition, increasing geriatric population, coupled with growing prevalence of conditions affecting the ears, nose, and throat, are anticipated to drive the growth of ENT devices market
Japan ENT devices market held the largest share in 2024. This can be attributed to technological advancements, rising inclination for minimally invasive surgeries, increasing penetration of endoscopes for treatment & diagnosis, investment by global players, ongoing R&D, and presence of key manufacturers. According to GSK’s regulatory submission, chronic sinusitis in Japan is estimated to affect around 2 million people.
The ENT devices market in India is anticipated to register a significant growth during the forecast period. The Central Drugs Standard Control Organisation (CDSCO) in India recently issued a list of 67 ENT medical devices requiring registration and approval, including ear canal lights, ear wicks, ENT chairs, & audiometers. This is part of India's efforts to regulate the medical device industry better.
Latin America ENT Devices Market Trends
Latin America ENT devices market is anticipated to register significant growth during the forecast period. Latin America ENT devices market is primarily driven by Mexico, Brazil, Argentina, and Colombia. Growing investments by market players in the region, proximity to North America, and free-trade agreements with major countries such as the U.S., Canada, Japan, & several European countries are among the factors anticipated to boost the Latin America market during the forecast period.
Brazil ENT devices market accounted for a major share of Latin America in 2024. A large population suffering from mild-to-moderate hearing loss, coupled with rapid development of technologically advanced devices, is expected to increase the market penetration of hearing aids in the coming years.
MEA ENT Devices Market Trends
MEA ENT devices market is anticipated to register considerable growth during the forecast perioddue to the increase in the prevalence of hearing loss and the rapidly aging population, as well as the growing demand for technologically advanced devices. According to The World Bank, around 26.9 million people were aged 65 and above in 2022.
The ENT devices market in UAE is experiencing fastest growth during the forecast period. This growth is primarily driven by the increasing prevalence of ENT disorders such as sinusitis, hearing loss, and tonsillitis in the country. The UAE's high prevalence of hearing loss, sinus, and allergy-related disorders contributes to the demand for ENT equipment such as sinus irrigation devices and nasal sprays.
Key ENT Devices Company Insights
Key participants in the ENT devices market are focusing on devising innovative business growth strategies in the form of product portfolio expansions, partnerships & collaborations, mergers & acquisitions, and business footprint expansions.
Key ENT Devices Companies
The following key companies have been profiled for this study on the ENT devices market.
-
Ambu A/S
-
Cochlear Ltd.
-
Demant A/S
-
Sonova
-
GN Store Nord A/S
-
Karl Storz
-
Olympus Corporation
-
PENTAX Medical
-
Richard Wolf GmbH
-
Rion Co., Ltd.
-
Smith & Nephew plc
-
Starkey Laboratories, Inc.
-
Stryker
-
MED-EL Medical Electronics
-
Nemera
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Cochlear Ltd., Demant A/S, Sonova, GN Store Nord A/S, Karl Storz, Olympus Corporation, Smith & Nephew plc, Stryker, MED-EL Medical Electronics)
- Expand ENT device portfolios through continuous product innovation, strategic acquisitions, global distribution network expansion, and partnerships with hospitals, audiology centers, and ENT specialists.
- Invest in advanced hearing implants, hearing aids, endoscopic visualization systems, minimally invasive surgical technologies, digital health platforms, AI-enabled diagnostics, and robotic-assisted ENT solutions to strengthen market leadership.
- Strong global brand recognition, extensive clinical validation, broad product portfolios spanning hearing care, endoscopy, and ENT surgery, and well-established relationships with healthcare providers.
- Significant R&D capabilities, regulatory expertise, large-scale manufacturing infrastructure, and comprehensive sales networks enable broad market penetration and support for complex healthcare systems worldwide.
- High product development and regulatory compliance costs can impact profitability and pricing flexibility.
- Premium-priced technologies and sophisticated product platforms may face adoption challenges in cost-sensitive healthcare markets and smaller healthcare facilities with limited budgets.
Emerging & Specialized Players (Ambu A/S, PENTAX Medical, Richard Wolf GmbH, Rion Co., Ltd., Starkey Laboratories, Inc., Nemera)
- Focus on specialized ENT product categories such as single-use endoscopes, diagnostic devices, hearing solutions, customized surgical instruments, and targeted ENT treatment technologies.
- Leverage niche expertise, flexible product development, customer-focused innovation, and regional market expansion strategies to strengthen competitive positioning and address specific clinical needs.
- Greater agility in responding to evolving clinical requirements and technological trends within specialized ENT segments.
- Ability to introduce innovative products more rapidly, provide focused customer support, offer specialized clinical solutions, and address unmet needs in specific diagnostic, surgical, and hearing care applications.
- Limited global scale, narrower product portfolios, and lower financial resources compared to large multinational competitors.
- Reduced bargaining power, smaller distribution networks, and lower brand visibility may restrict penetration into large hospital systems and multinational procurement contracts.
Recent Developments
-
In April 2024, PENTAX Medical launched Digital Capture Module 9380, designed for medical recording in ENT and speech-language settings.
-
In February 2024, Sonova opened a new operations facility in Mexico to expand its cochlear implants and hearing instruments businesses.
-
In February 2024, Sonova launched the Stride V-UP Ultra Power BTE hearing aid to expand its Vivante portfolio.
-
In February 2024, HANSATON, a brand of Sonova, launched a beat FS RT675 UP power hearing aids as an extension to its existing portfolio.
ENT Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 29.0 billion
Estimated market size in 2026
USD 30.8 billion
Projected market size by 2033
USD 47.0 billion
Growth rate
CAGR of 6.2% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Ambu A/S; Cochlear Ltd.; Demant A/S; Sonova; GN Store Nord A/S; Karl Storz; Olympus Corporation; PENTAX Medical; Richard Wolf GmbH; Rion Co., Ltd.; Smith & Nephew plc; Starkey Laboratories, Inc.; Stryker; MED-EL Medical Electronics; Nemera
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global ENT Devices Market Report Segmentation
This report forecasts revenue growth at global, regional, and country level and provides an analysis on industry trends in each of the sub segments from 2021 to 2033. For the purpose of this study, Grand View Research, Inc. has segmented the global ENT devices market report on the basis of product and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue USD Million, 2021 - 2033)
-
Diagnostic ENT Devices
-
Rigid Endoscopes
-
Sinuscopes
-
Otoscopes
-
Laryngoscopes
-
-
Flexible Endoscopes
-
Bronchoscopes
-
Laryngoscopes
-
Nasopharyngoscopes
-
-
Robot Assisted Endoscope
-
Hearing Screening Device
-
-
Surgical ENT Devices
-
Radiofrequency handpieces
-
Otological Drill Burrs
-
ENT Hand Instruments
-
Sinus Dilation Devices
-
Nasal Packing Devices
-
Others
-
-
Hearing Aids
-
Hearing Implants
-
Nasal Splints
-
-
Regional Outlook Revenue USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Spain
-
Italy
-
France
-
Denmark
-
Norway
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
Segment Definition
Segment - Product
Revenue capture definition
Diagnostic ENT Devices
Diagnostic ENT devices are used to examine, visualize, assess, and diagnose disorders affecting the ear, nose, throat, and related anatomical structures. These devices assist healthcare professionals in identifying infections, structural abnormalities, hearing disorders, airway conditions, and other ENT-related diseases.
Rigid Endoscopes
Rigid endoscopes are non-flexible optical instruments used to provide high-definition visualization of ENT structures during diagnostic and surgical procedures. They are commonly used in nasal, sinus, laryngeal, and otologic examinations.posting, denial management, and accounts receivable follow-up on behalf of healthcare providers. This model helps organizations reduce administrative burdens, access specialized expertise, and improve operational efficiency.
Sinuscopes
Sinuscopes are specialized rigid endoscopes designed for examining the nasal cavity and paranasal sinuses. They enable detailed visualization of sinus anatomy and are widely used in the diagnosis and management of sinus disorders.
Otoscopes
Otoscopes are handheld diagnostic instruments used to inspect the external auditory canal and tympanic membrane. They are commonly utilized for diagnosing ear infections, hearing-related conditions, and structural abnormalities of the ear.
Laryngoscopes (Rigid)
Rigid laryngoscopes are used to examine the larynx, vocal cords, and upper airway structures. They support the diagnosis of throat disorders, voice abnormalities, tumors, and airway obstructions.
Flexible Endoscopes
Flexible endoscopes utilize a flexible insertion tube that allows physicians to access and visualize difficult-to-reach ENT structures. They provide greater maneuverability and patient comfort during examinations.
Bronchoscopes
Bronchoscopes are flexible endoscopic devices used to examine the trachea, bronchi, and lower respiratory airways. They assist in diagnosing airway abnormalities, infections, tumors, and pulmonary conditions.
Laryngoscopes (Flexible)
Flexible laryngoscopes are used to visualize the throat, larynx, vocal cords, and upper airway. They are frequently employed for diagnosing swallowing disorders, voice disorders, and laryngeal diseases.
Nasopharyngoscopes
Nasopharyngoscopes are flexible instruments designed to examine the nasal passages, nasopharynx, and upper throat. They help diagnose nasal obstruction, tumors, infections, and other upper airway conditions.
Robot-Assisted Endoscope
Robot-assisted endoscopes combine endoscopic visualization with robotic technologies to improve maneuverability, precision, and control during ENT examinations and surgical procedures. These systems support minimally invasive interventions and enhanced surgical accuracy.
Hearing Screening Device
Hearing screening devices are diagnostic tools used to evaluate hearing function and identify hearing impairments. These devices are commonly utilized in newborn hearing screening, audiology clinics, hospitals, schools, and occupational health programs.
Surgical ENT Devices
Surgical ENT devices are instruments and technologies used during ENT procedures to treat diseases and disorders affecting the ear, nose, throat, head, and neck regions.
Radiofrequency Handpieces
Radiofrequency handpieces deliver controlled radiofrequency energy to targeted tissues for cutting, coagulation, ablation, or tissue reduction. They are commonly used in procedures involving nasal obstruction, sleep apnea, tonsil reduction, and turbinate treatment.
Otological Drill Burrs
Otological drill burrs are precision surgical instruments used during ear surgeries to remove bone and diseased tissue. They are frequently employed in mastoidectomy procedures, cochlear implant surgeries, and other otologic interventions.
ENT Hand Instruments
ENT hand instruments include a broad range of manual surgical tools such as forceps, scissors, retractors, curettes, elevators, and suction instruments used in diagnostic and surgical ENT procedures.
Sinus Dilation Devices
Sinus dilation devices are minimally invasive tools used to enlarge blocked sinus openings and restore normal sinus drainage. They are commonly utilized in balloon sinuplasty procedures for chronic sinusitis treatment.
Nasal Packing Devices
Nasal packing devices are used to control bleeding, support healing, and stabilize nasal structures following surgery or trauma. These devices help prevent postoperative complications and promote recovery.
Others (Surgical ENT Devices)
This category includes additional ENT surgical devices such as powered surgical systems, microdebriders, electrosurgical instruments, suction-irrigation systems, navigation platforms, and tissue removal devices used across various ENT procedures.
Hearing Aids
Hearing aids are electronic amplification devices designed to improve hearing by enhancing sound signals for individuals with hearing impairment. Modern hearing aids often incorporate digital processing, wireless connectivity, and personalized sound adjustment technologies.
Hearing Implants
Hearing implants are surgically implanted medical devices that improve hearing in patients with severe or profound hearing loss. These devices include cochlear implants, bone conduction implants, and middle-ear implants that bypass damaged portions of the auditory system to provide auditory stimulation.
Nasal Splints
Nasal splints are medical devices placed inside or outside the nose following nasal surgery or trauma. They help stabilize nasal structures, maintain airway patency, minimize tissue adhesions, and support postoperative healing after procedures such as septoplasty and rhinoplasty.
Market-specific Research Models
Consensus-Based Estimates & Forecasting
The ENT devices market presents dominant opportunities, featuring global key players such as Ambu A/S; Cochlear Ltd.; Demant A/S; Sonova; GN Store Nord A/S; Karl Storz; Olympus Corporation; PENTAX Medical; Smith & Nephew plc; Starkey Laboratories, Inc.; Stryker. To ensure a holistic approach, the GVR research team adopted a comprehensive methodology, considering multiple companies worldwide and utilizing various variables for data accuracy.
Our methodology included
Model 1: Commodity Flow Analysis - For public players, annual reports were referenced. For private players, premium paid data sources such as S&P Global, Crunchbase, ZoomInfo, RocketReach, etc., were used for the latest revenue insights.
Model 2: Parent Market Analysis
Model 3: Country-level Multivariate Analysis Assumptions
Model 4: Segment-level Multivariate Analysis Assumptions
Model 5: ENT Devices Market CAGR Calculations
Commodity flow analysis was employed to track the movement of ENT devices through the value chain, from technology providers to end users. This analysis provided insights into demand generation points, intermediary roles, and ultimate consumption patterns.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
ENT Device Adoption & Procedure Volume Analysis
Developed a tailored analysis of the global ENT devices market focused on diagnostic ENT devices, surgical ENT devices, hearing aids, hearing implants, endoscopic systems, and nasal care products. The study assessed adoption trends across hospitals, ambulatory surgical centers, ENT specialty clinics, and audiology centers, while evaluating disease prevalence, procedural volumes, technology advancements, and healthcare infrastructure investments influencing market growth.
Enables stakeholders to understand evolving ENT treatment trends, identify high-growth product categories, assess procedure-driven demand patterns, and evaluate the impact of technological innovation on clinical outcomes, patient access, and long-term market expansion.
Diagnostic, Surgical & Hearing Care Technology Assessment
Delivered a customized evaluation of utilization trends across endoscopes, hearing screening devices, hearing aids, cochlear implants, sinus dilation systems, radiofrequency surgical devices, and robotic-assisted ENT technologies. The analysis assessed clinical adoption, reimbursement considerations, treatment effectiveness, minimally invasive procedure trends, and demand for advanced diagnostic and therapeutic solutions across key healthcare settings.
Provides actionable insights into emerging technology adoption, commercially attractive product segments, evolving treatment pathways, and opportunities associated with hearing restoration, sinus disease management, surgical efficiency, and enhanced patient outcomes.
Healthcare Infrastructure, Regulatory Environment & Competitive Landscape Assessment
Conducted a focused assessment of the global ENT devices ecosystem, including healthcare infrastructure development, regulatory frameworks, reimbursement policies, distribution networks, technology integration, and competitive positioning. The analysis evaluated market entry barriers, product innovation strategies, specialist workforce availability, procurement trends, and competitive differentiation initiatives among leading manufacturers.
Supports strategic planning for product development, geographic expansion, distribution partnerships, investment decisions, and market entry strategies by identifying growth drivers, operational challenges, regulatory considerations, revenue opportunities, and competitive advantages across the global ENT devices value chain.
Frequently Asked Questions About This Report
The global ENT devices market size was estimated at USD 29.0 billion in 2025 and is expected to reach USD 30.8 billion in 2026.
The global ENT devices market is expected to grow at a compound annual growth rate of 6.2% from 2026 to 2033 to reach USD 47.0 billion by 2033.
The hearing aids segment dominated the market with the largest revenue share of 31.3% in 2025.
Some key players operating in the ENT devices market are Ambu A/S; Cochlear Ltd.; Demant A/S; Sonova; GN Store Nord A/S; Karl Storz; Olympus Corporation; PENTAX Medical; Richard Wolf GmbH; Rion Co., Ltd.; Smith & Nephew plc; Starkey Laboratories, Inc.; Stryker; MED-EL Medical Electronics; Nemera
Key factors that are driving the ENT devices market growth include the increasing prevalence of hearing loss, the growing geriatric population, increasing penetration of minimally invasive ENT procedures, and technological advancements in this field.
North America dominated with a 36.4% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


